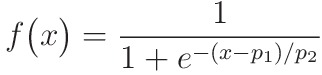Of Phaetons, Coupés, Shooting Brakes, Broughams, Hackneys, Cabriolets, Landaus and Limousines. Horace and Jim step back in time to revisit the raison d’être for carriages and the emerging “horseless” carriage. We explore how evolution rather than revolution of networks influenced the technologies of transportation.
The question of foothold markets comes up and we explore which jobs-to-be-done affected early car design. The leap from these early jobs to the modern segmentation of the market is observed through the contrast between Henry Ford’s approach to the then agrarian market compared with Alfred Sloan’s portfolio strategy at General Motors.
The discussion morphs into a brief infrastructure review where the development of roads is compared to today’s telco operator business and regulatory models.
Finally, Horace and Jim drift into insurance and discuss the risk pooling implications of driverless cars.
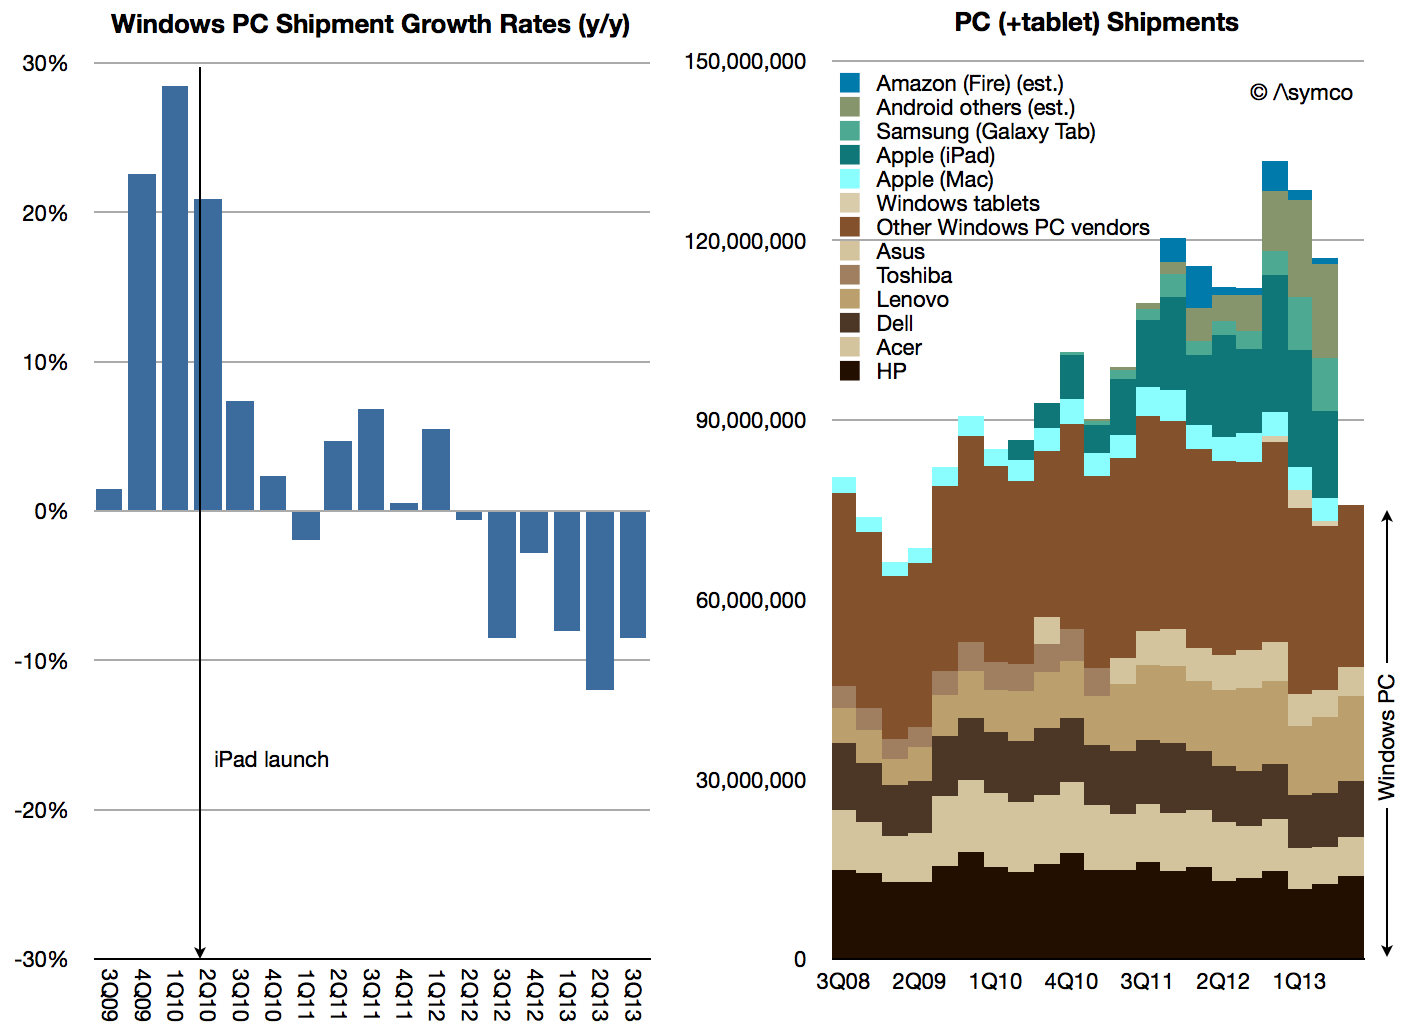
Gartner reported that PC shipments totaled 80.3 million units in Q3. Subtracting an estimated 4.4 million Macs yields an estimated 75.9 million Windows PCs. ((The total will be less than this as some PCs will not ship with Windows))
This total is lower than the total shipped in the same period of 2008.
The graphs above show the Gartner data and the split between tablets and PCs. ((Tablet and Mac data for Q3 is not yet available))
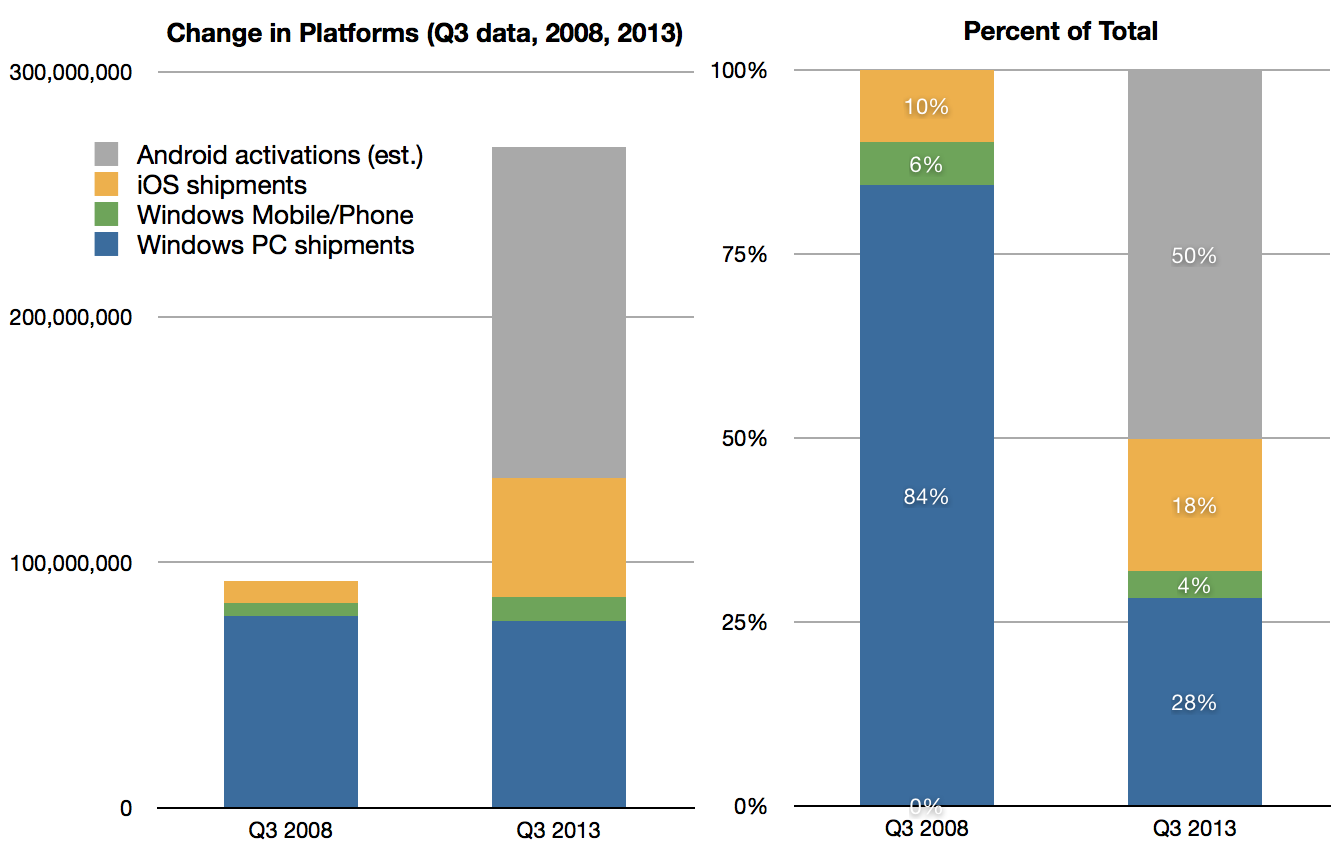
If we include all iOS and Android devices the "computing" market in Q3 2008 was 92 million units of which Windows ((Windows including Windows Mobile or Windows Phone)) was 90% whereas in Q3 2013 it was 269 million units of which Windows was 32%.
Any guesses on what this market will look like in 2018?
In yesterday's post forecasting smartphone penetration I neglected to mention the exact subset of the US population being sampled. The analysis is based on comScore's sampling which covers only those devices which are the "primary phone" for users over 13 years old and not provided by an employer.
In other words, the population being sampled is not meant to identify how many phones will be in use but rather what is the primary phone for those non-children who choose their own phones.
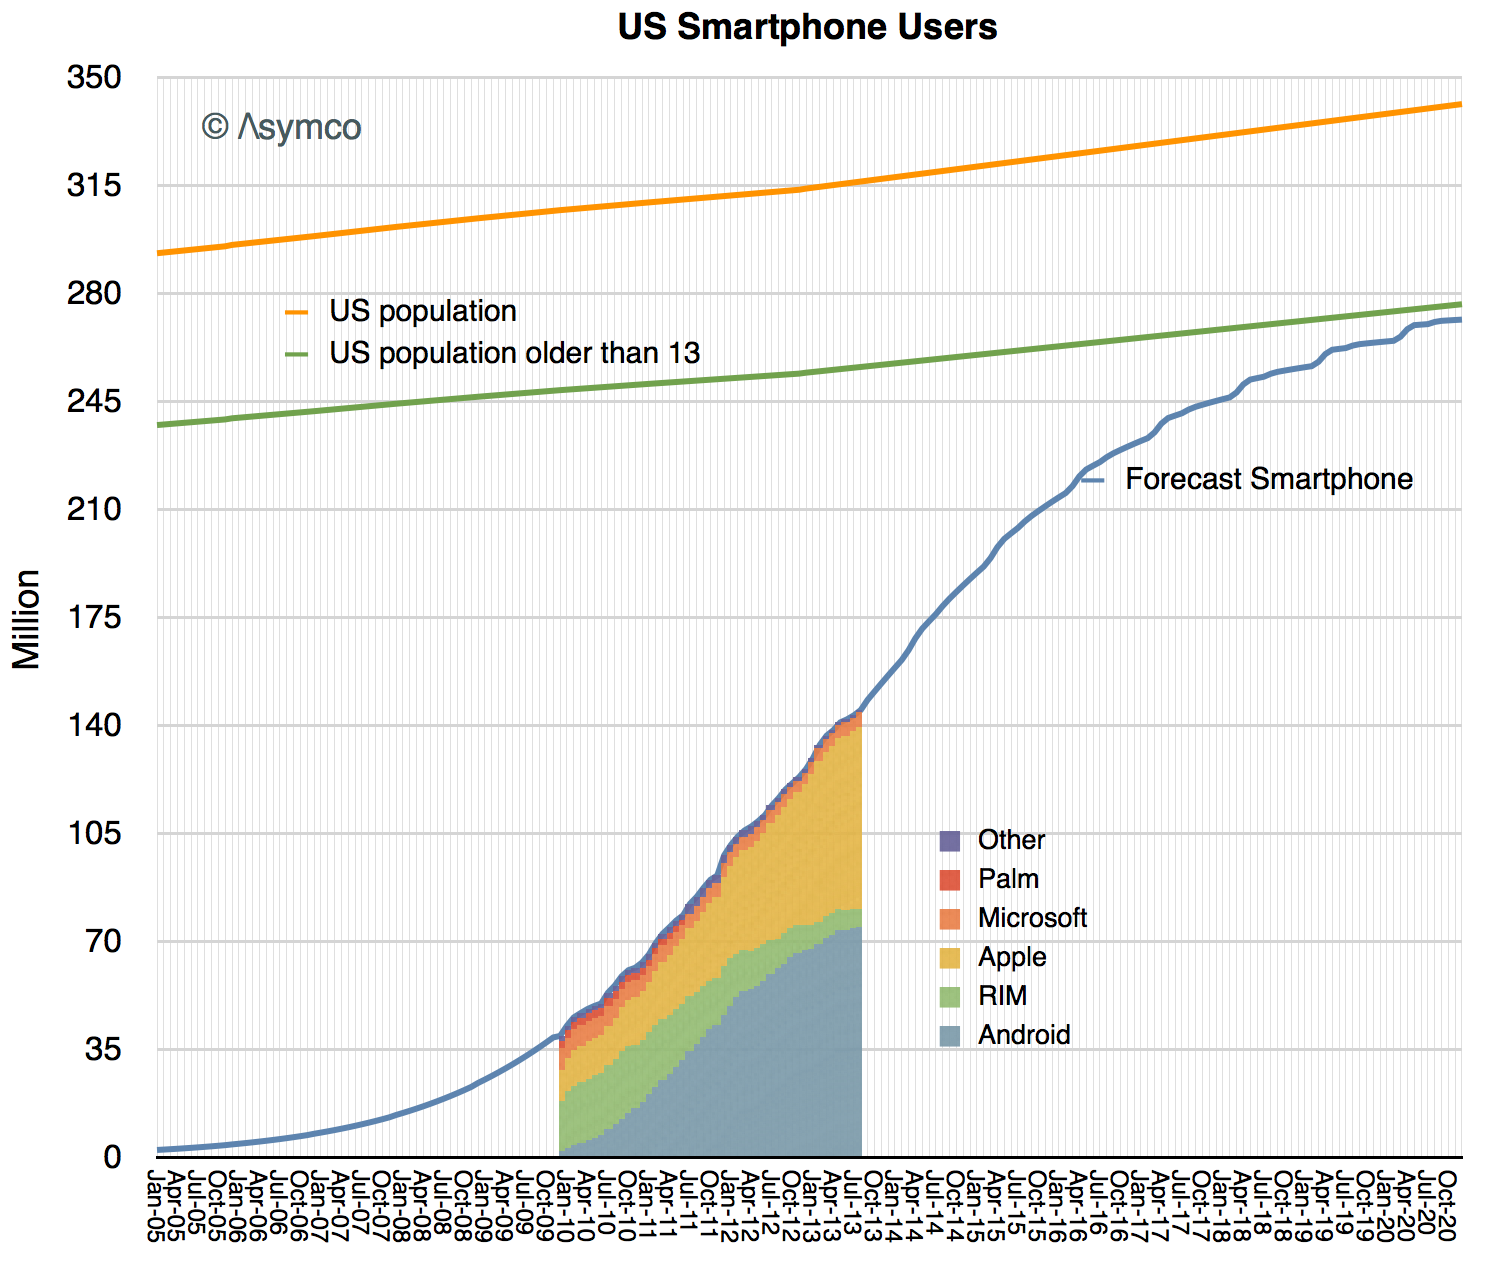
So the measurement that can be obtained from the S curve analysis is a subset of all phone users and will not identify exactly how many phones will be in use. Given that, this is what that subset looks like:
I drew a line showing the census data (and projection) for the US population and estimated what percent of that population might be older than 13 years ((I estimate 19% of the population is 0 to 13 years of age.))
Of the remaining population, I expect smartphones will be used by nearly all by end of 2020.
That means about 270 million users. It also means that about 125 million more than are using smartphones today. Note also that a significant number of those under 13 will also use smartphones and that the metric is "primary phone" and insofar as there are more than one phone for some users they are a multiplicative factor. Finally this measure does not account for company assigned devices.
So although this measures how many users will use smartphones, the total number of such phones in use is likely to be significantly higher.
Finally, when considering the market's potential size it's important to have an accurate estimate of how frequently these phones are replaced. So, for instance, if we guess that 300 million smartphones will be in use and that they get replaced every 2 years then it follows that the US market for smartphones would be about 150 million units per year in 2020.
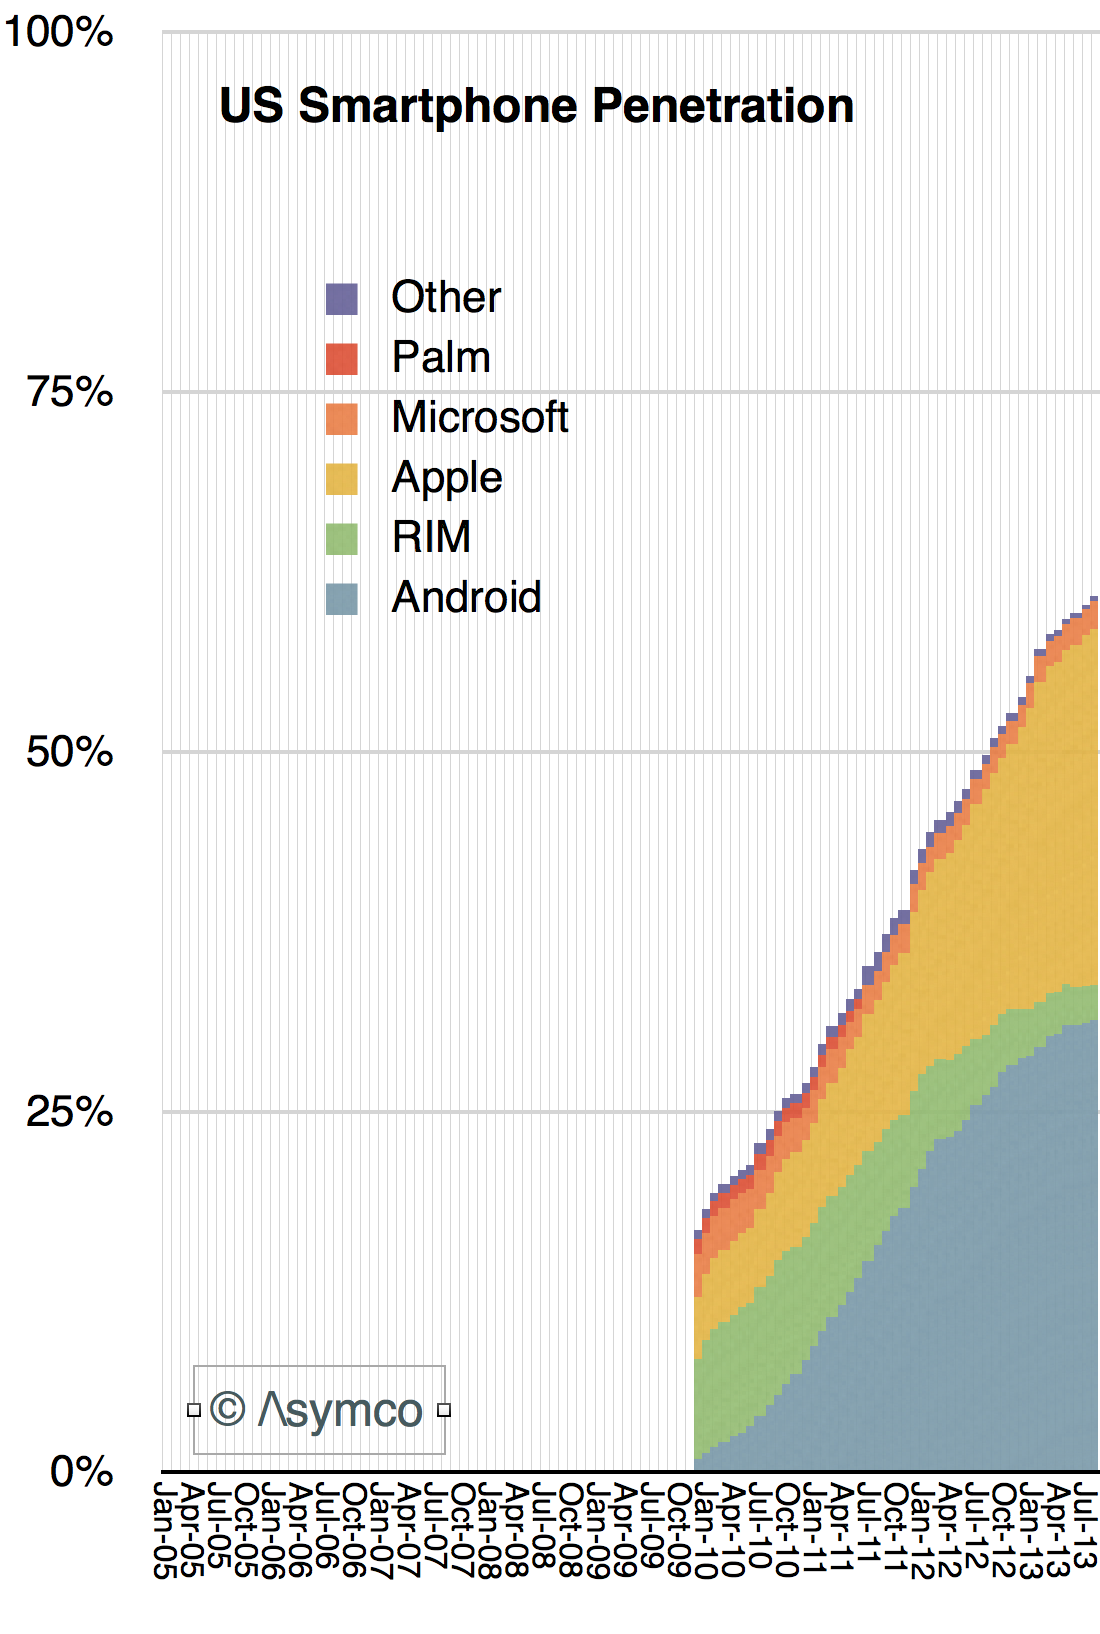
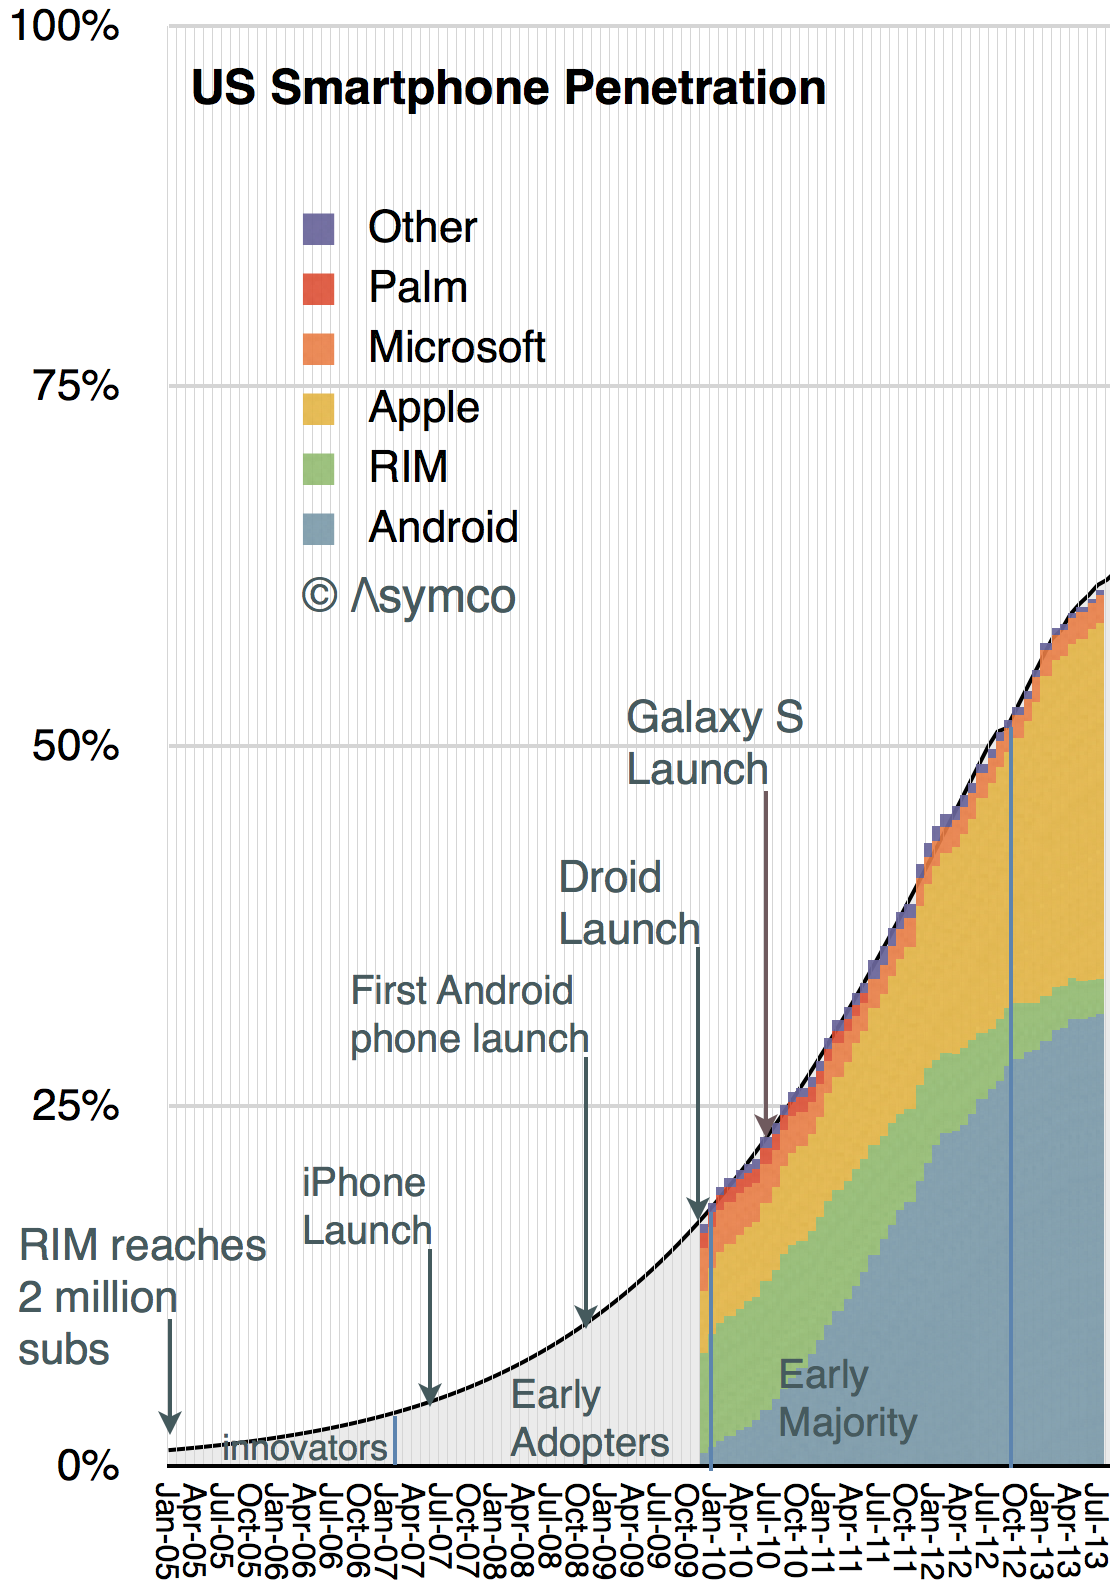
The latest comScore data places penetration at about 61%, up over 10 percentage points from the same time last year. The 50% last year is itself up nearly 14 percentage points from the same time in 2011. This progress in the diffusion of smartphones is shown the following graph:
I set the time frame for the graph to start in 2005 because there was still a market at the time. We can estimate the number of users from data supplied by RIM. They had about 2 million subs in 2005, the majority of whom were in the US.
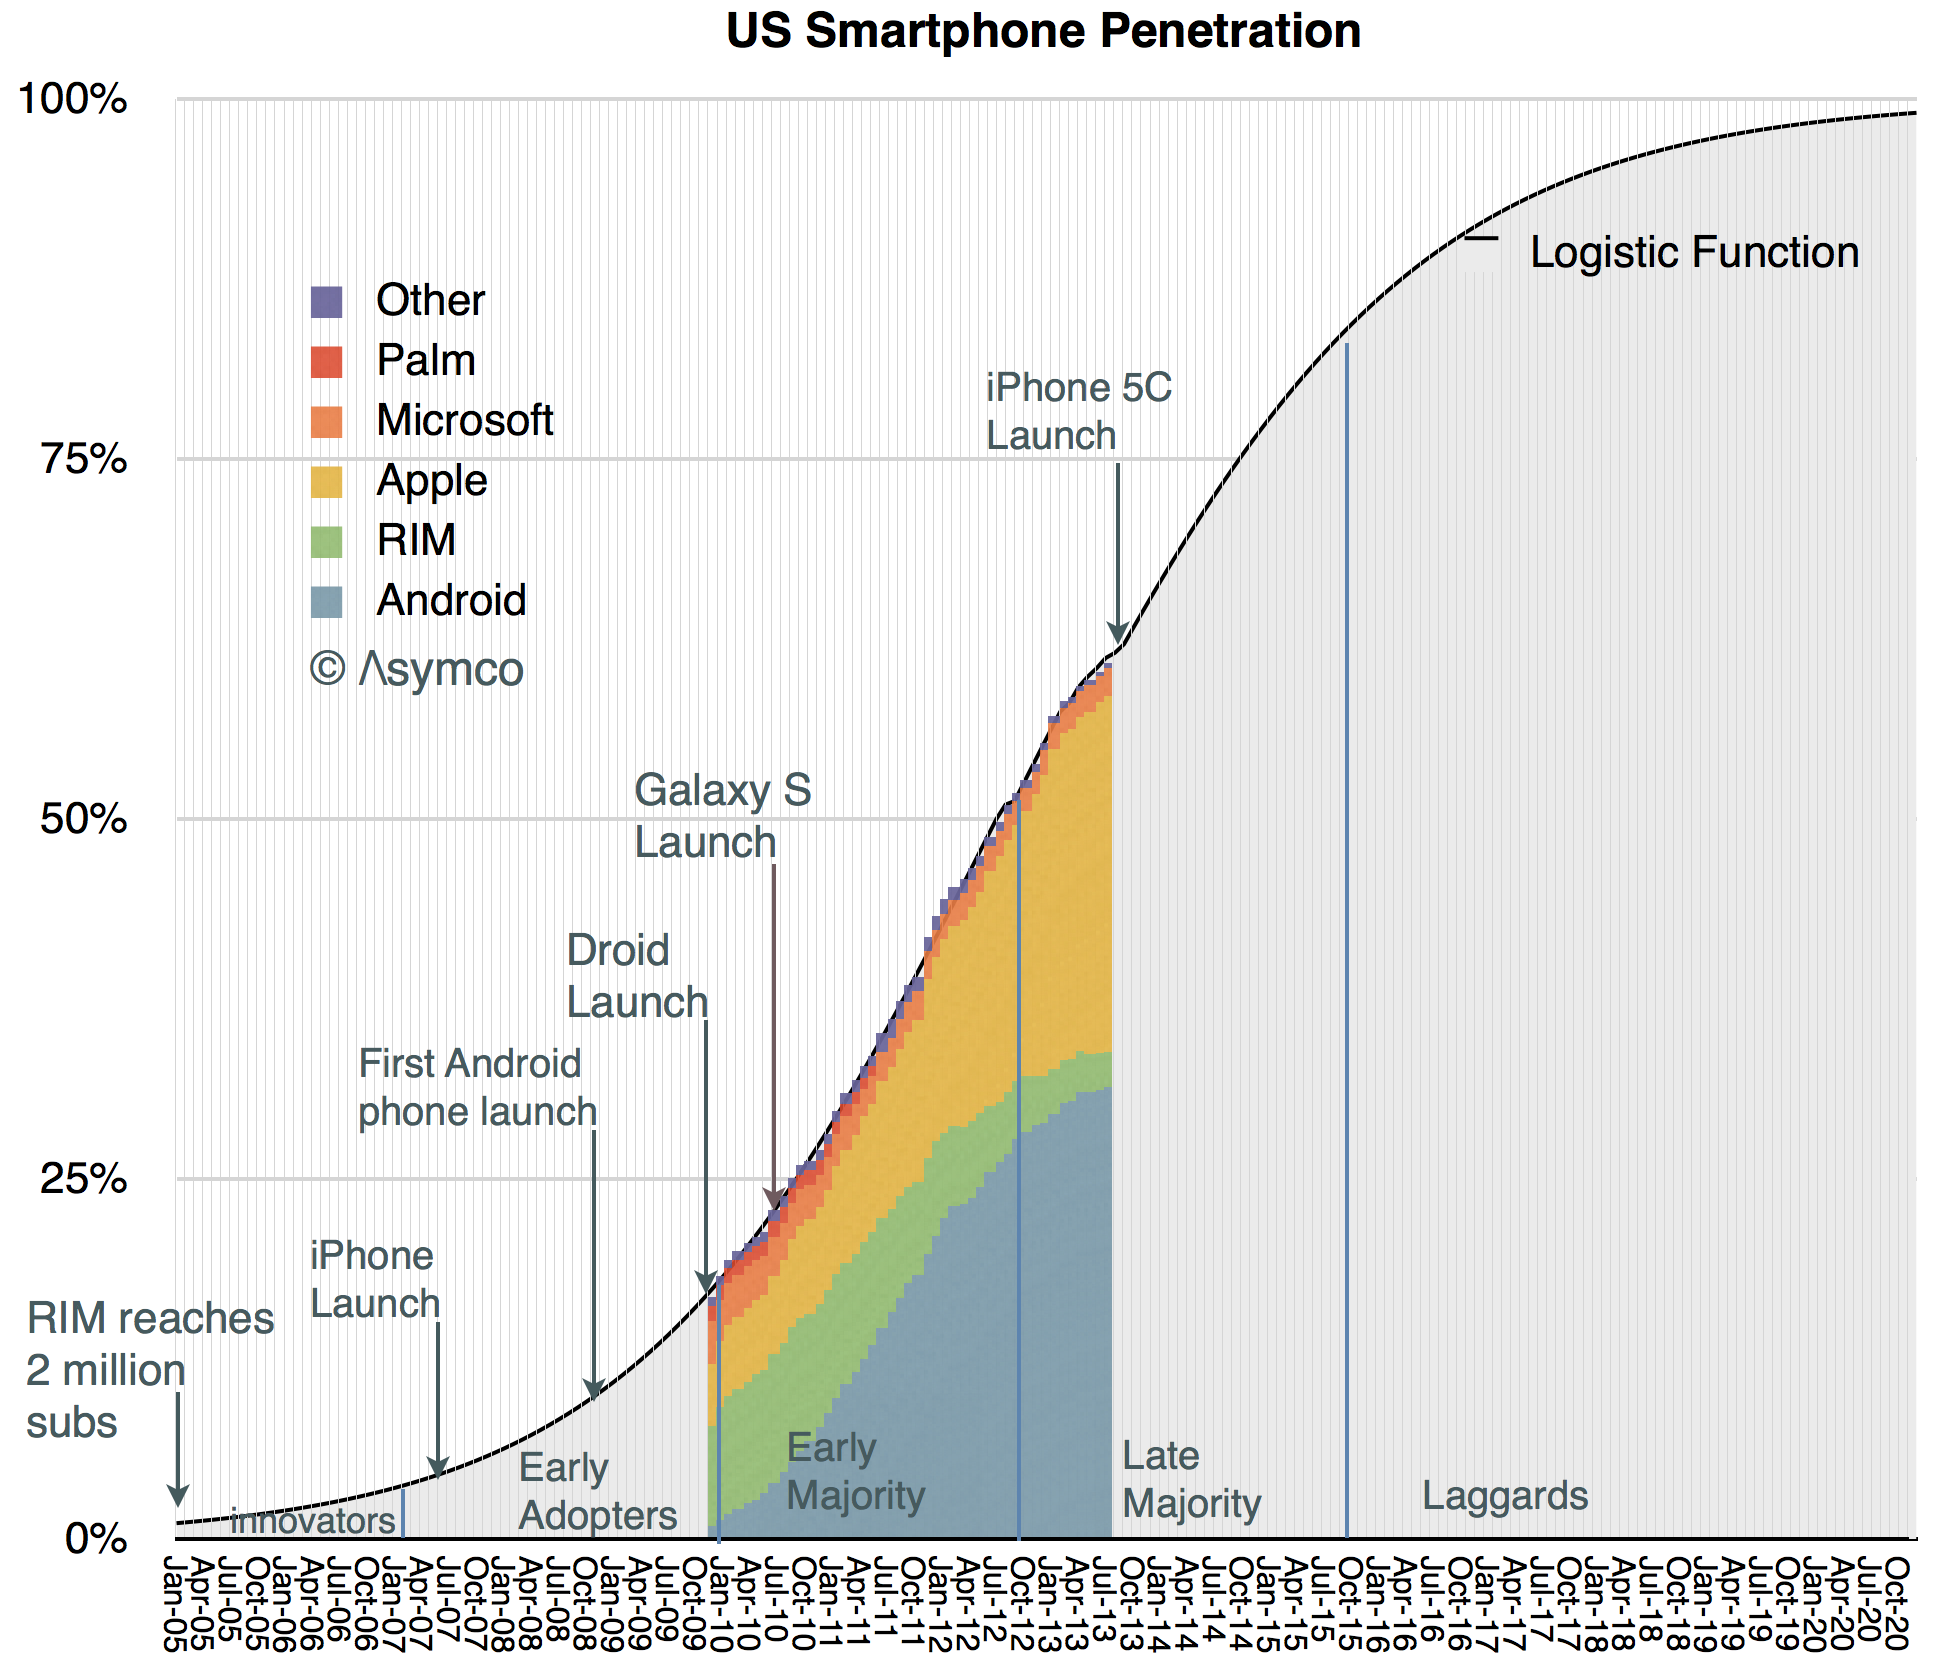
Given these data points we can draw a new penetration graph extrapolating to the complete date range.
I added a few events that mark some of the product launched during this period.
The penetration curve shown happens to be defined as the "Logistic Function" whose equation is well known:
p1 is the number of periods (in months) that it took for the market to reach 50% penetration and p2 is an index of which can be adjusted for this market.
Note that I also identified successive groups of consumers adopting smartphones as defined by Rogers in his Diffusion of Innovations. This is easily done since the formula for penetration gives us the answer (as the integral):
The Innovators (first 2.5% of the market) were recruited by February 2007, one month after the iPhone was announced. They were almost all BlackBerry users
The Early Adopters (the 13.5% which followed the innovators) were all using smartphones by the beginning of 2010. They were served mainly by iPhone 3GS and BlackBerries
The Early Majority were on board by October 2012, just in time for iPhone 4, Droid, Galaxy.
We are now in the Late majority which will run out by November 2015. The iPhone 5S came out about one third of the way through this period.
The next few years are shown in the following extrapolation.
The laggards will adopt smartphones from late 2015 until late 2020.
As this is the diffusion curve for the US, most other large regions are going to be shifted to the right and the global total can probably be estimated.
What remains to be done is to estimate the way the platform colors will fill in over this time frame for the US and to do the same analysis on a global level.
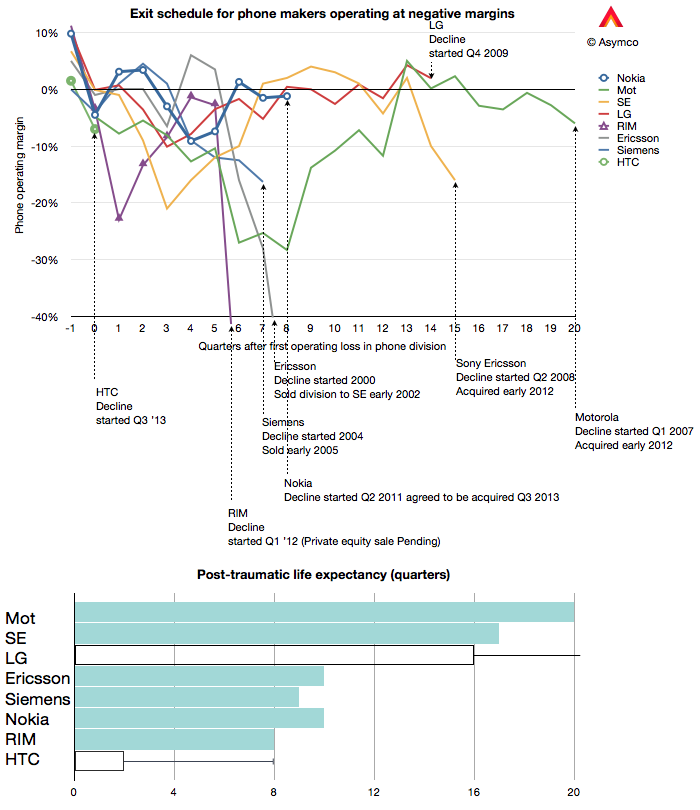
The pattern may be that companies either have short post-trauma lives of about two to three years or relatively long post-trauma lives lasting 4 to 5 years. What determines this life expectancy and how long do RIM, Nokia and LG have?
These comments came right after BlackBerry (then RIM) announced a loss and thus entered what I called the "post-traumatic" phase of its existence. ((The analysis began earlier, in June 2011)) The observation I have been making is that once a company begins to generate negative operating margins from phone sales, that phone business never recovers.
The question then becomes one of gauging how long they have before the business is sold, dissolved or merged. Since that update, both Nokia and RIM have tentatively agreed to be sold. If the sales go through then we can update the graphs as follows:
[Graph note: solid bars in the second graph indicate companies which exited and thus the duration of life post-trauma. Hollow bars indicate the companies have entered post-tramuatic period but have not yet exited. Lines extending from the hollow bars indicate life expectancy henceforth.]
It turns out that Nokia and RIM did indeed have "two to three years" of life left under the same ownership. Two years to be precise. But as Nokia and RIM change hands (and are thus re-classified in the graph above) HTC enters the schedule. ((Note that there are many companies not listed which also exited. I simply did not have data for Palm, Panasonic, NEC, BenQ, Alcatel, Hitachi, Casio, Fujitsu, Handspring or Danger or many other asian brands which are no longer in this business.))
HTC has just confirmed that they have lost profitability for the first time since going public in 2002. As the clock begins running the alarm is now set to a much tighter 2 years. The implication being that HTC will change ownership or control no later than mid 2015.
But there is a post-script to this story. LG, you may note, has not exited phones. In fact, it seems to be recovering nicely. Doesn't that give hope to HTC?
I don't believe it should. The caveat to this short post-tramuatic life expectancy hypothesis is that it applies mostly to companies which derive the bulk of their sales from phones. Companies which are conglomerates or which can offset losses from phones with cash flows from other businesses tend to live longer.
This does not mean however that LG's survival is assured. The factors at work in the phone business place continuing stress on the weakened while favoring the strong only temporarily. The dynamics are nothing like those in consumer electronics or in the computer industries. Reversals of fortunes are breathtaking.
Publicly, Mr. Lazaridis and Mr. Balsillie belittled the iPhone and its shortcomings, including its short battery life, weaker security and initial lack of e-mail. […]
Internally, he had a very different message. “If that thing catches on, we’re competing with a Mac, not a Nokia,” he recalled telling his staff.
The whole article is worth reading, detailing as it does the decision process inside BlackBerry during the painful disruption of its core business.
What struck me most however was how similar their decisions were to those of Nokia at about the same time. Consider:
The engineering priorities placed on optimization around constrained hardware. Although engineers knew how to build the right products, the business priorities caused them to be deployed in the wrong direction.
The delays these misdirected efforts caused. Mobile phones have narrow windows of opportunity but long lead times. A strategic mistake is very costly and most probably impossible to remedy. In the case of BlackBerry, buying QNX came too late while for Nokia the deprecation of Symbian was catastrophically managed.
The feedback loop from network operators which shut down any initiatives for improved user experiences. Your best customers provide all the wrong information when the market is being disrupted. Ignoring them is impossible while complying is a strategic mistake.
The demand from network operators to develop "killers" to competing platform-based products ((Ironically, Nokia was asked to do a BlackBerry killer)) and the subsequent "jumping at the opportunity".
Listening to large buyers at the expense of users. While BlackBerry was guided to omit consumer features from its enterprise buyers, Nokia never secured enterprise buyers of any significance ((though they tried very hard to get them)). Nevertheless it created the "E series" business-friendly phones which suppressed features like cameras and music.
The celebrity sponsorships and wasted promotional efforts in the face of structural failures. This is manifested today by HTC as well.
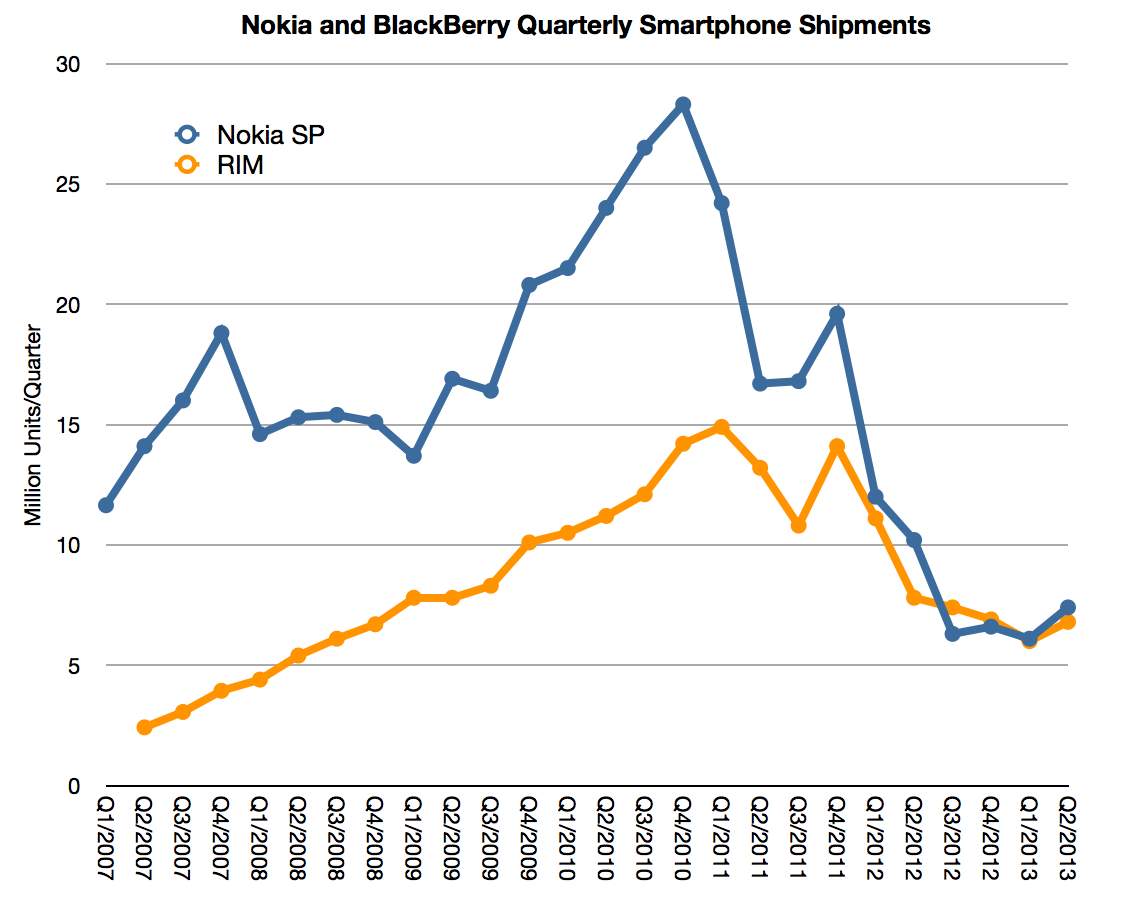
The parallelism of this synchronized failure can be seen in the following graph showing smartphone volumes.
The striking thing is how the two companies peaked are almost precisely the same time and how that moment (end of 2010) was not related to the entry timing of their nominal disruptor.
Recall that both companies cite the iPhone as the factor which caused a shift in the basis of competition. But the iPhone launched in mid 2007 (at the beginning of the graph's date range.) BlackBerry had 16 quarters of growth after the iPhone and Nokia nearly the same. The stock prices of the companies also prospered for a period long after the iPhone entered the scene validating a do-nothing approach. So this is the crux of the incumbent's dilemma: how do you rally a response when you don't feel any pain? It's worse actually: how do you embark on a painful course of action while feeling comfortable and safe?
The reason the companies did not suffer immediately from the iPhone was because it (and its Android equivalents) took time to reach the core customer bases. Remember that the iPhone was not "good enough" to be an enterprise product at launch and Android was not the first to serve the low end of the market, where Nokia was dominant.
Vision is worth exactly nothing without timing.
But enough about ancient history. The crucial question is what does it teach us. It's tempting to suggest that this disruption is happening again with the iPhone today.
There is one big problem with this. The iPhone was not a low-end disruption. It was exactly the opposite. The BlackBerry and the Nokia products were striving for the low end. They observed the discipline of constrained resources. They were expanding into emerging markets. They watched every fraction of a penny on the bill of materials. The low end was manna for the whole industry. Even Microsoft with Windows Mobile was better positioned for the low end than Apple.
Instead, what Apple did was unthinkable. It entered with a high end product. It even promoted its high price ($500, subsidized!) This is why it was laughed at.
Theirs was "the Mac in a phone" idea. The reason it worked was that it was not a phone. The reason it worked is because it was the hardest disruption to spot:
A new market disruption ((The reason Clayton Christensen and his disruption consulting black belts could not spot it is mostly because new market disruption requires deep industry domain knowledge))
Disruption is not a process that merely rewards breaking convention. Any fool can rebel against the status quo. To change it requires a process that rewards asymmetric competition. Finding a way to be seen as irrelevant and yet conquering at the same time. Being disruptive is, above all, being imperceptibly valuable.
For iPhone the core asymmetry was that it was a computing product and not a telecommunications product. Every decision thereafter flowed from the calculus of computing and not the compliance with telco convention. The ecosystem, the rapid rate of improvement, the rich user experience, the tie into other product lines.
It was this asymmetry which confused every observer. Predicting how a high end product can conquer the low end is fiendishly counterintuitive.
In contrast, spotting low end disruption is a parlor game. There is little challenge in observing a cheaper alternative competing as a commodity. For evidence look at how markets react. Whereas they could not understand the value of the iPhone (or iPod or iPad) they reacted instantly to the whiff of a commoditization play. Angst surrounding cheaper alternatives pervades. ((The contrarian should note that commoditization plays are hard bets to win since everybody can spot them.))
The problem with the low end disruption thesis is that low end is also much easier to respond to, especially now that everyone read the book. The incumbent simply needs to have a flexible cost structure and a vast margin to dip into. Most failures to respond to a low end disruption come from companies stuck in a high cost structure not from a failure to see a low end alternative. ((Christensen case studies almost always cite how the low end disruption was perceived easily but the response was felt to be marginally worse than not responding or fleeing upmarket.))
Apple's costs are mostly variable and their fixed (R&D and SG&A) are growing far slower than sales. There are huge margins and more cash being spun out than anyone can figure out what to do with it.
The distressed response to the low end tends to be a retreat into the higher margins and an abandonment of existing customers.
I don't see Apple doing either. Rather, it is gradually adjusting its portfolio toward lower end alternatives. Note that demand for the lower end product is far less than for the high end. Instinct would suggest that they should have stuck with the 5S alone. But it moved down anyway. It also did so with the iPod, iPad and Mac mini.
The idea that Apple is vulnerable to the low end is a relic of an idea. It goes back to the Mac of the 1990s, at a time when the world-wide computing market was orders of magnitude smaller than today and where purchasing and development decisions centralized in the hands of a few large companies ((essentially B2B as Ben Thompson points out)). And even when looking at that competition, the Mac somehow managed to survive.
That's not likely to be the case for those who found themselves in competition with the Mac in its pocketable re-incaration.
The most interesting juxtaposition in market data happened this week.
Apple announced 9 million units of the iPhone 5s/c sold in their opening weekend while BlackBerry recognized 3.7 million smartphones sold in the three months ended August 31.
I will state these data points with a different emphasis: while Apple explicitly reported, both in a press release and in an SEC filing, Sales of 9 million units, BlackBerry reported recognition of revenues on 3.7 million units. At the same time BlackBerry also reported sales to end users of 5.9 million units.
So, did Apple sell 9 million iPhones in three days? What about units ordered and not delivered? Which of these units will show up in the company's income statement? Conversely, did BlackBerry sell 3.7 million or did it sell 5.9 million smartphones in three months?
The answer is dependent on what constitutes a sale. I suggest re-reading the Sold and Shipped: A Brief Introduction post from last year. Understanding is complicated by many factors, not least of which could be intentional signaling by management. We may never come to a perfectly matched comparison of the two companies' situations but our job as analysts is to see through the signals and obfuscating language and interpret a pattern. A pattern that extends over a time and helps us learn.
My observation is one of contrast. The juxtaposition this time is that Apple emphasized sold and not shipped while BlackBerry sold more units to end users than it recognized revenue. These signals reflect precisely the inverted fortunes of the two companies.
For BlackBerry the higher sold than shipped recognition was due to a product launch failure. Units which were shipped (and recognized as revenue) last quarter did not sell and the company is not only writing off the inventory but has drastically reduced its deliveries of new units in order to drain inventory. The company explains:
During the second quarter the company recognized hardware revenue on approximately 3.7 million BlackBerry smartphones. Most of the units recognized are BlackBerry 7 devices, in part because certain BlackBerry 10 devices that were shipped in the second quarter of fiscal 2014 will not be recognized until those devices are sold through to end customers. During the quarter, approximately 5.9 million BlackBerry smartphones were sold through to end customers, which included shipments made prior to the second quarter and which reduced the Company's inventory in the channel.
The company is essentially saying that due to the unusual circumstances of a product launch failure, they will change how they account for their business. They don't have the confidence that units shipped will actually sell and will not recognize them since they fear they will have to write some off. They are signaling: They are being far more conservative, not reporting shipments alone because those shipments could essentially be value free.
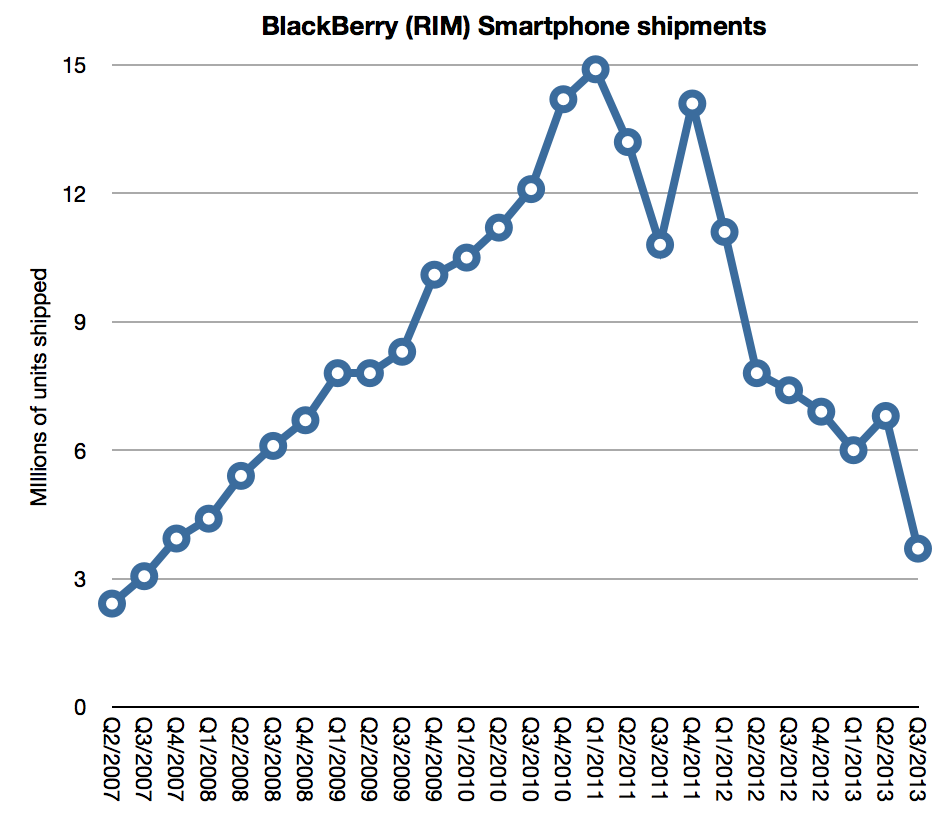
When seen as a pattern, the new figure on recognized revenue units needs to be shown relative to the history of recognized revenue units.
You can see the instability in volume recognition in the graph as a clue. Product launches cause erratic changes in what was previously a seasonally stable business. This is, essentially, the company being thrown onto its back foot. It is staggering from an unexpected blow and resetting expectations.
Now note the contrast with Apple. Apple provides every quarter shipment data on all its products. This is consistent with generally accepted accounting principles and consistent with reporting from other companies. ((Though many, e.g. Samsung, Google, refrain from reporting shipments any shipment data at all.))
Apple also offers "channel inventory" data on select products. This inventory data, when coupled with shipment data, offers insight into how many units are actually purchased by end users. If Apple runs a tight ship then its inventory is relatively low but if it has a reliable customer base that of its channel is also low. Moreover, if it can predict sales well then it avoids overfilling the channel and having to take a hit while draining it.
In that context the way the company reported the 5c/s launch is signaling optimism:
On September 23, 2013, Apple Inc. […] announced that it has sold over nine million new iPhone 5s and iPhone 5c models, just three days after the launch of the new iPhones on September 20.
Apple expects total company revenue for the fourth fiscal quarter to be near the high end of the previously provided range of $34 billion to $37 billion, and expects gross margin to be near the high end of the previously provided range of 36% to 37%.
The SEC filing language above refers to the following press release:
Apple® today announced it has sold a record-breaking nine million new iPhone® 5s and iPhone 5c models, just three days after the launch of the new iPhones on September 20
“This is our best iPhone launch yet―more than nine million new iPhones sold―a new record for first weekend sales,” said Tim Cook, Apple’s CEO. “The demand for the new iPhones has been incredible, and while we’ve sold out of our initial supply of iPhone 5s, stores continue to receive new iPhone shipments regularly. We appreciate everyone’s patience and are working hard to build enough new iPhones for everyone.”
The reporting of sales after a launch weekend has been a staple of Apple's communications about product for a long time. Therefore the evaluation of this performance should be made in comparison with previous launches.
But it's not necessarily a statement of end user purchases. Nor is it a statement purely of shipments. The term "sold" as used in a press release is not an accounting term and it is not something which is meant to be audited.
However, none of that matters. The signal is what should be observed. By deliberately and repeatedly using the word "sold" Apple is expressing confidence that demand for its products is strong. Sure, there is channel inventory in that 9 million unit number but there are also ordered devices which have not been shipped and thus are not counted as sales. There are also depleted store shelves and people angry about not getting their desired phone model. Apple knows this, Tim Cook is making it clear they know this. They have excellent visibility into the distribution of their products. They have excellent inventory management. They are typically conservative in their financial reporting.
So why would anyone interpret Apple's release as a negative signal? If you want an example of a negative signal, look at how BlackBerry reported its launch performance.
When interpretation of a signal is very different from the literal statement, it says more about the interpreter than about the company.
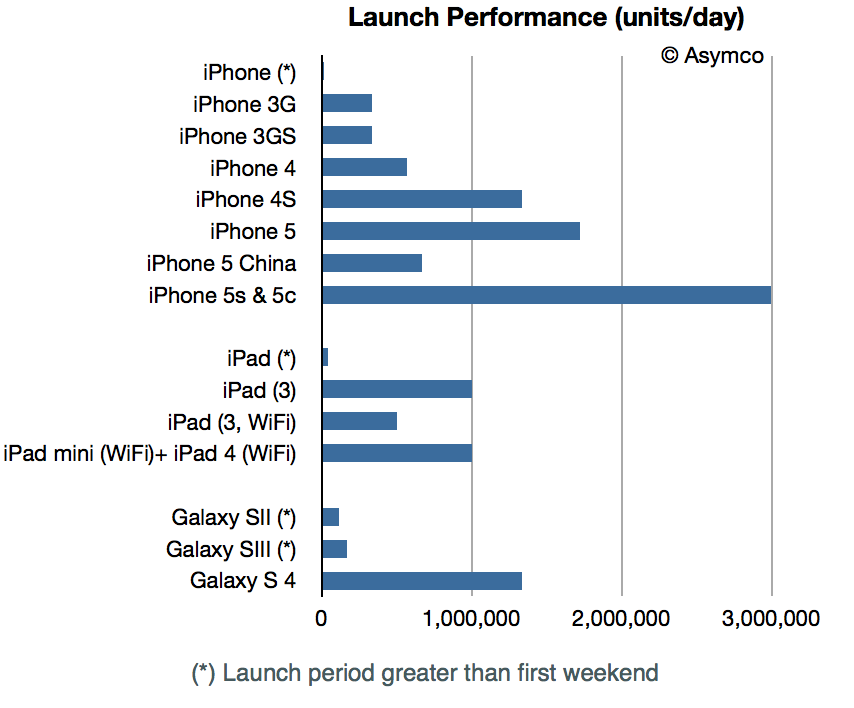
Apple today announced it has sold nine million new iPhone 5s and iPhone 5c models in the first three days after their launch. This performance is illustrated in the following graph:
Note that the data is normalized to units/day.
The launch countries this year differed from last year in that they include all of China whereas last year only Hong Kong was included. ((I am assuming that this year China includes Hong Kong. It would be good to confirm this.))
The absolute number of 5x devices sold (not just shipped) seems to be an 80% increase from the 5 launch (9 million vs. 5) but accounting for China the increase is a more modest 29%. ((The China launch event last year may have had a different dynamic as it occurred later and nearer to holiday season, but I'll go with the unqualified data.))
However, perhaps the more relevant comparison is between different "S" generations of phones.
The data shows that the 3GS was 3x more rapidly purchased on launch than the original iPhone. The 4S was 4x more rapidly purchased on launch than the 3GS and now the latest 5s/c are 2.3x more rapidly purchased than the 4S.
The growth is certainly lower but from a much higher base. This should not be surprising.
UPDATE: Galaxy S 4 launch data is updated to show weekend performance. Previous graph showed performance over the first 27 days.
Horace: Apple is an interesting company to study because its success comes from being a serial disruptor. This is a very rare type of success formula. I am trying to "reverse engineer" its operating model and I hope that such a model is one which others might learn from if they were to emulate it. The trouble is that very few others seem to want to emulate Apple. Why that is is also an interesting question.
Niaz: […] Do you think apple has lost its image that it has created over the years as a center of innovation and building excellent products?
Horace: I cannot comment on how Apple's image is measured by people in the industry. I have been listening to commentary on Apple for about a decade and I have never seen any change in pattern. The company has always been perceived as a failure by a majority of observers. With respect to its products, I also do not see a change in the pattern established over the last decade.
Niaz: Are you optimist about the future success of Apple? Like after 10 years and then 20 years?
Horace: Let me put it this way: if there were no Apple then somebody will have to invent an Apple to do the same thing Apple does. In that sense I'm optimistic that there will be an Apple in some way in perpetuity.
Niaz: What will be the next big innovation from Apple?
Horace: I have no idea but it's likely to involve refining new user interaction methods. Similar to the breakthroughs that came from the use of a mouse, a scroll wheel and a touch screen. It means making computers better at gleaning our intentions without our getting involved in explaining them.
Niaz: Will Apple, Google and Samsung be the major player for the future of computing? Or we can hope to see some new faces?
Horace: I am fairly sure Samsung will not be because they have not yet grafted software and services to their operating structure. I would give Amazon a higher probability in being a successful platform alternative.
Niaz: In 2011 you’ve written a blog post ‘Steve Jobs’ Ultimate Lesson for Companies’ on Harvard Business Review Blog and you have cited ‘A leader should aspire to do more. A leader should claim to have left a legacy not just on their company but on all companies.’ As you know Google, Amazon, Samsung, Facebook … all have learnt lifetime lessons from Steve Jobs. What do you think about the impact that Steve Jobs have created?
Horace: He led by example and like all great leaders sacrificed much as a way to inspire others to follow him. He also spent time in the wilderness and chose asceticism. This gave him authority. Many historical figures had the same quality. The problem is that few business leaders have it but I don't see why they shouldn't.
Much more on evaluating Tim Cook's performance, the iPhone portfolio, the rise of Android, Microsoft/Nokia, wearable technology and disrupting Google. Check it out on eTalks.
Are cars sold or purchased? Horace Dediu and Jim Zellmer discuss automotive “ecosystems” vis-à-vis Apple and Tesla’s direct sales model. We further dive into the rigidity and risk of such value chains and divert a bit into automakers' attempts at aviation. Finally, we consider the potential monetization of automotive metadata and what that might mean for new, perhaps “over the top” style entrants.
Also history lessons: Ford Trimotor, Ford production system, The Kaiser people’s car.