Asymco

Asymmetric Intelligence

Research

  1. Think local, act global

    Research · 113 comments

    One of the curiosities of the mobile phone market is how vast it is but also how heterogeneous it has always been. I wrote about this in 2010:  Smartphone parochialism: How operator policies prevent or promote platform adoption. This observation was influenced by my time at Nokia where I became amazed at how differently users behaved in different countries.

    There were many causes. Some cultural, some historical, some economic and some policy-driven. The result was that it presented a challenge to any company with global ambitions and indeed it was rare to see the same company do well in every market. Japanese companies did well in Japan, European companies did well in Europe and US (and Korean) companies did well in the US. Nokia was most successful because it was able to apply an European model more broadly (but not in the US). Samsung succeeded by simply adapting to each and every market with hundreds of products. But it was a particularly "provincial" market.

    My assumption was that when smartphones would become the majority of phones in use there would be a normalization of behavior and thus a homogeneity of preferences. This is, after all, what happened in other platform games. PC form factors are globally consistent, PC operating systems are equally preferred around the world, FaceBook, Google and Twitter are also, unless censored, uniformly popular. Apple's iPod eventually also became a global phenomenon with no material difference in preference by market. Likewise for game consoles. ((Although Japanese do seem to prefer Japanese platforms more.))

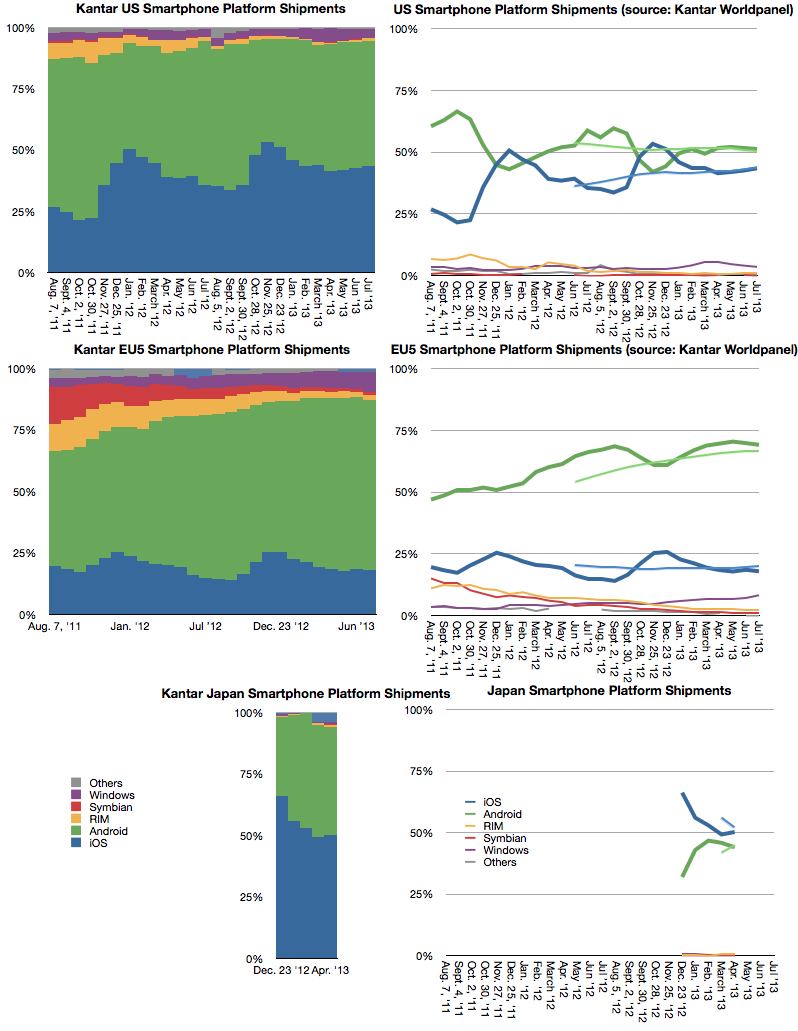
    However, a decade after the broad adoption of smartphones, the relative popularity of various platforms is still unevenly distributed. Prior to the iPhone, Symbian was strong everywhere but the US and BlackBerry was very strong in the US but weak elsewhere. Windows Mobile had footholds in some markets but little traction in others. Today the picture has changed but it's still a patchwork of preferences. Consider the following graphs.
    Screen Shot 2013-09-18 at 9-18-12.57.15 PM

    They are the most detailed sets of data on platform phone purchases but they not the only data: We also know that Android is vastly more popular in India from web usage statistics. We know that BlackBerry is sensationally popular in Latin America and the Middle East. We know that within Europe there is a gap between North and South in iOS vs. Android and even more pronounced between East and West. We know that whereas iPhone was a huge hit in Korea upon its launch there, Samsung and LG swamped it in the last two years.

    But the data shown above is the story of iOS being very popular in Japan and increasing its share in the US while being flat in EU5. Again these three markets are different but each contradicts the global picture.

    Note the differences in trend not just absolute performance. This is what is puzzling. There seems to be a divergence between markets: Markets are become more islands onto themselves rather than one whole. This contradicts all the theories of how computing markets should behave (network effects, ecosystems, monopoly power, etc.) It implies that there is still a great deal of friction in the market; friction which I suspect to be due to the peculiar nature of telecom economics.

    I wonder if this observation is, as usual, late on my part and that Apple's iPhone product marketing has seen it years ago.
  2. An Interview by Eric Jackson: On Blogging, Apple And What's Next

    Research · 19 comments

    My thanks to Eric Jackson for his thoughtful questions and post on Forbes.com. You can read full interview here but I repeat a few non-biographical questions and answers here for discussion:

    An Interview With Horace Dediu: On Blogging, Apple And What's Next

    Q: Turning to Apple, where is it at right now as a company in this post-Steve Jobs period?

    A: Still too early to tell. They seem to be cooking a lot of things and the great experiment of whether a company can be Jobsian without Jobs is still going on. I have been trying to put together a picture of how it operates. It’s hard because that’s their biggest secret. It’s also a picture that few people have ever seen, even those who worked there a long time. The glimpses so far are tantalizing but there is so much we don’t know and thus can’t assess how robust it is. One thing that is clear to me is that there is no absorption by mainstream observers of what makes Apple tick. It’s hiding in plain sight because what it is isn’t anything anyone can recognize. Case in point is the functional and integrated dimensions. It’s the largest functional organization outside the US Army and more integrated than Henry Ford’s production system. Just describing it sounds medieval and it’s so far outside convention that it’s not something reasonable people are willing to believe actually exists.

    Q: Is Tim Cook the right CEO for the company at this time?

    A: I hold the belief that he’s been CEO for much longer than it seems. Jobs was not a CEO in any traditional sense. He was head of product and culture and all-around micromanager. He left the operational side of the company to Cook who actually built it into a colossus. Think along the lines of the pairing of Howard Hughes and Frank William Gay. What people look for in Cook is the qualities that Jobs had but those qualities and duties are now dispersed among a large team. The question isn’t whether Cook can be the “Chief Magical Officer” but rather whether the functional team that’s around Cook can do the things Jobs used to do.

    Look at it another way: I subscribe to the idea that any sufficiently large company is a system and needs to be analyzed using a lost art called “Systems Analysis”. This is a complete review of all parts and the way they inter-relate. However, since for most of its life Apple was personified as an individual, what came to pass for Apple analysis was actually the psychoanalysis of that individual. It makes for great journalism and best selling books. It’s also banal and almost certainly wrong. The proof is in the vastness of complexity and number of people involved. Engineers tend to think about constraints and the constraints on companies are innumerable.

    Q: You’ve written extensively on the post-PC period, when will we come to the post-phone period – if ever?

    A: I think less than 10 years. Maybe even five. A wristband today can have more processing power than the original iPhone. An iPhone has more power than a desktop did 4 years ago. The speed of change is incredible.

    Q: What’s going to be the “next big thing” for Apple? Watches, TVs, something else?

    A: I segment along “jobs to be done” which are basically unstated and unmet needs. Unstated because they are usually so deep and so pervasive that they’re taken for granted. We have the need to feel good about our lives, to be healthy and to be connected in meaningful ways to others. These jobs are very poorly served by technology today and there are many non-technology products that are hired as poor proxies to help. The speed with which technology changes means that the trajectory of improvement will undoubtedly intersect that of the job. Even a small job like losing weight and eating well is probably worth as much as half the mobile phone market. Imagine if someone gives us a magic tool that does that for us. How much would you pay? How many of us would pay? There are so many next big things that I cannot choose. (By the way think of the job Facebook is hired to do: make me feel good about myself because I can show others how good I am. Boom!)

    Q: What’s your take on how they’re handling their expansion into China, India, and other emerging markets?

    A: It’s depressing how slow things are moving on that front. We can draw lines on a graph but we don’t know the constraints. Again, the issue with adoption is that the timing is so damn hard. I was expecting smartphones to take off in mid 2004 and was disappointed over and over again. And then suddenly a catalyst took hold and the adoption skyrocketed. Cook calls this “cracking the nut”. I don’t know what they can do to move faster but I suspect it has to do with placement (distribution) and with networks which both depend on (corrupt) entities.

    Q: As you look at the rest of the mobile internet competitive landscape, do you expect any big surprises from other players (good or bad) in the next 5 years?

    A: The big question in my mind is the sustainability of the arbitrage models which underpin pretty much every internet business plan. Essentially we have two markets: one where everybody consumes but pays in metadata and another where everybody consumes aggregated analytics but pays in cash. An internet business is the arbitrageur who takes advantage of the inability of each market to price the other. History shows that arbitrage markets tend not be stable as information begins to leak across markets. Therefore what would blow the internet up is if consumers could become wiser about what they are giving up and advertisers would become wiser about aggregating consumer data. I imagine a system where each individual would allow bids on their consumption and a market mechanism where bidders competed for that data. This of course depends on users taking control and ownership of their own data. What might help is the realization of what mass state surveillance can do and the realization that internet giants have more information about us than the government could ever hope to possess.

    It would create a new era which will have political dimensions. I imagine we’ll need an internet citizen’s bill of rights or some such movement which will reset expectations. Economically, could bode well for those who position themselves as protectors of the individuals and be a crisis for those who take advantage of consumer ignorance.


  3. M is for Mystery

    Research · 87 comments

    I recently tweeted that any discussion related to wearable technology needs to begin with a description of the job it would be hired to do. Without a reason for building a product, you are building it simply because you can.

    The reason a product deserves to exist is that it can do a job that needs doing and that few, if any others can also do it. This happens when the job is unstated and difficult to perceive. Put another way, the difficulty behind jobs-to-be-done based design is that jobs are never plainly evident. In contradiction to invention, where the problem being solved must be as clearly stated as its solution, value-creating innovation meets new and unarticulated needs. Even when created, the value is more subtly perceived, often only after prolonged use.

    Which brings me to the M7. Apple chose to highlight a component (curious in itself) which it bills as a "motion coprocessor". It claims to be measuring motion data via accelerometer, compass and gyroscope and processing the information in some way. By bundling the sensors and their management into one integrated chip battery consumption is reduced and these motion monitoring functions are performed more efficiently.

    But what for? The examples given during the presentation for an iPhone with M7 don't add up to a lot of benefit. An iPhone could be used as a fitness companion but it would not a very good one. Compared with, for example, a Nike FuelBand, an iPhone could not track your activity well. It's often not moving, sitting on a desk or in a purse or pocket while you are doing exercise. It's too big to take into a basketball game. It can't "observe" your activity because it's not worn during many activities and if it is worn it is in a position which does not inform much about what you're doing. Phones are too big to be used as physical activity monitors.

    Hence the question of what is the M7's job to be done. As part of an iPhone, it does not seem to have one. Saving a bit of battery life is not a job, and certainly not one that needs to have billing in a media special event. The answer must be that the M7 was developed for some other, as yet unstated reason.

    When the A series chips were created Apple leveraged the in-house design and cost reduction to make a wide range of products with more than 700 million examples built. Designing a chip needs a broad application domain.

    Perhaps this is why Apple chose to describe the iPhone 5s as "forward-thinking". The M7 and the Touch ID are like research projects whose actual value will be realized at some future time, in probably different contexts. The M series of chips may become Apple's "low end" microprocessor as the A series climbs the trajectory into core computing tasks (read: phone, tablets, TV, laptops).

    M might be the chip for the wearable segment, woven into a whole new fabric of uses and jobs to be done.

  4. A new platform classification

    Research · 35 comments

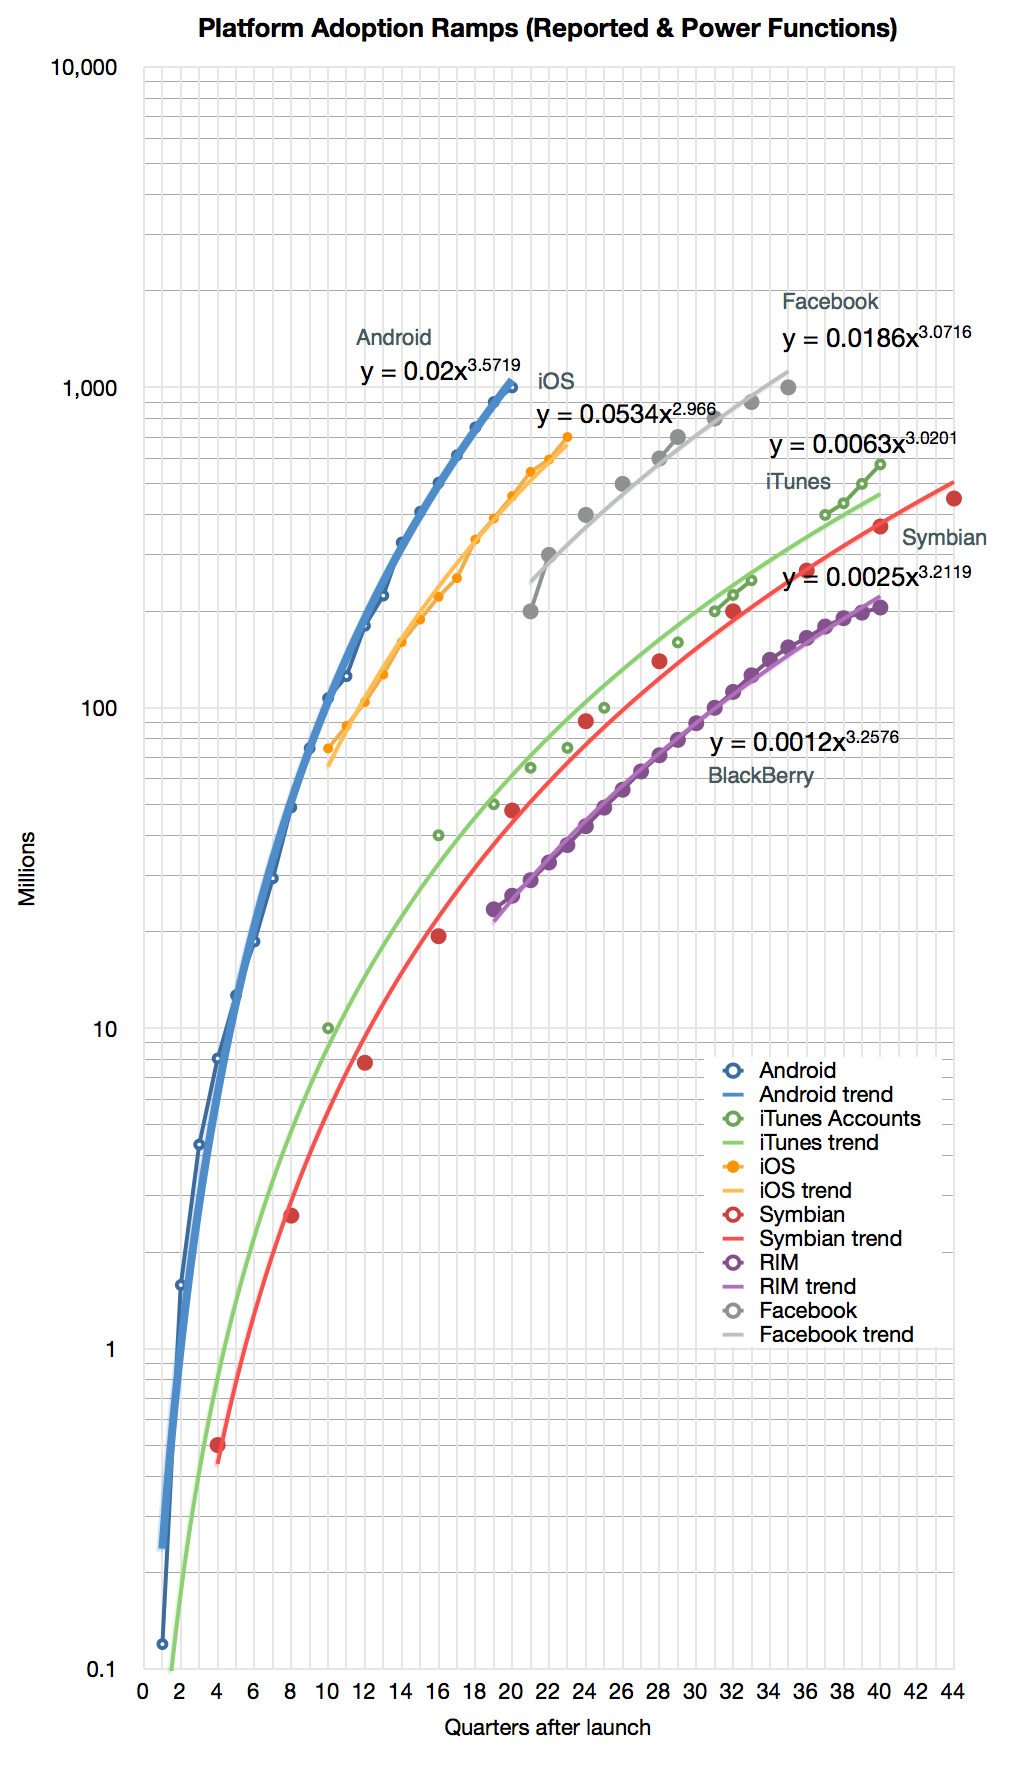
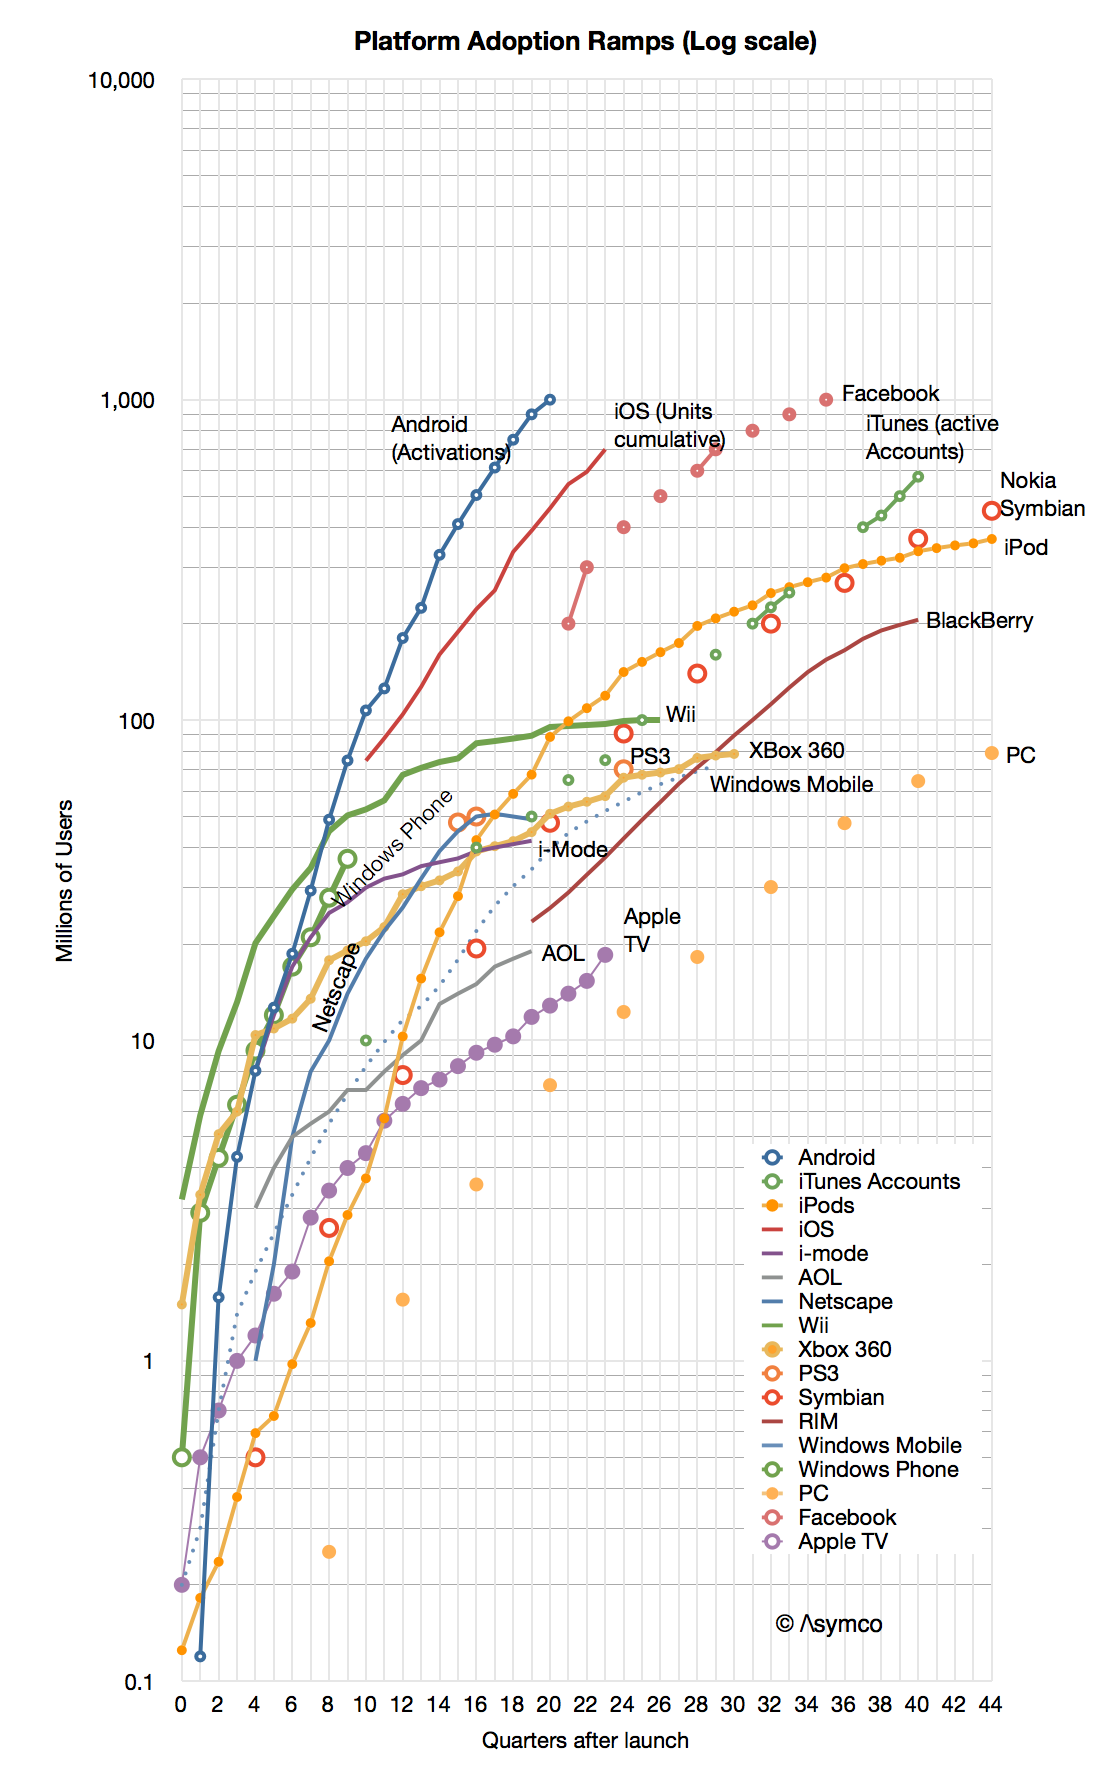
    When looking at the Race to a Billion data I noticed that some platform adoption ramps look quite different from others. It's not just a matter of "slope" or rate of growth but a distinctly different shape.

    If you look at the graph below you might see the difference yourself.

    Screen Shot 2013-09-12 at 9-12-4.41.13 PM

    First, note that the graph is logarithmic. A straight line on a log chart implies exponential growth (the y values are a constant to the power of the x value). However, none of the graphs show straight lines. None of the platforms follow exponential growth ((Except perhaps in the very early periods)).

    Second, we can eliminate linear or logarithmic functions. They simply do not fit.

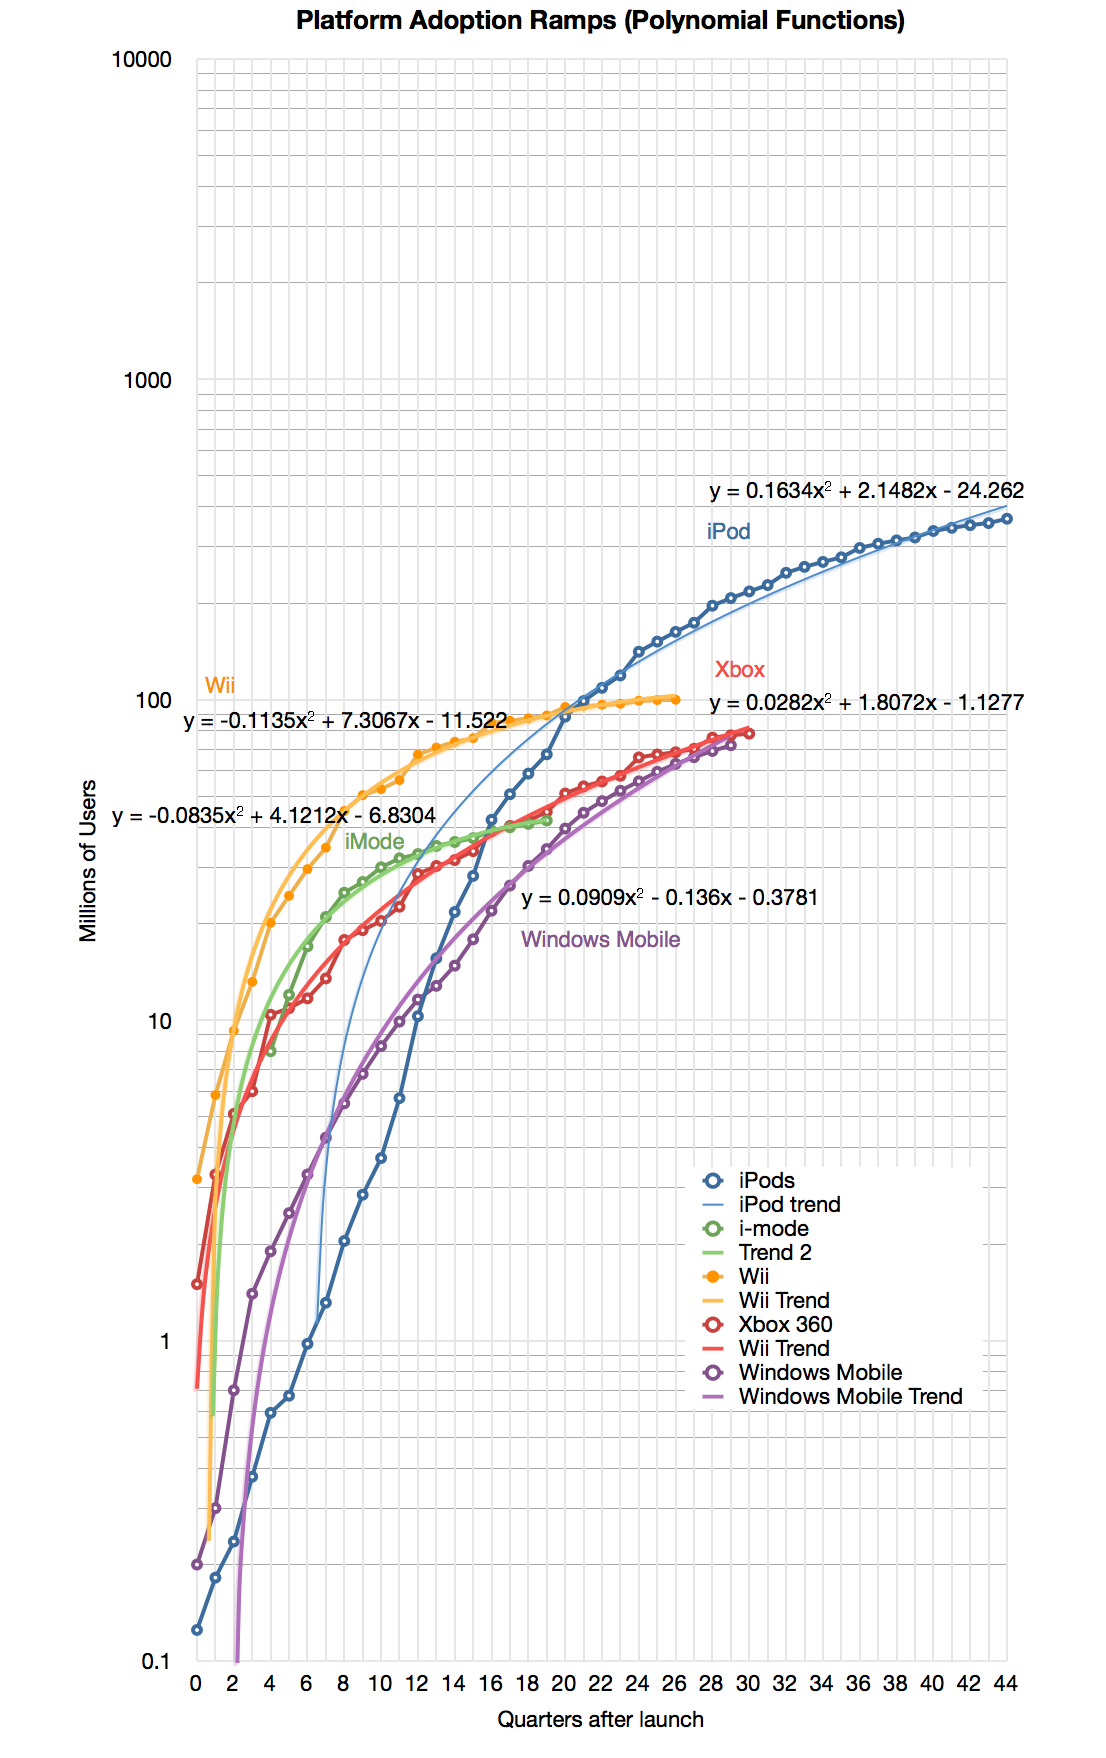
    That leaves: polynomial or power. It's easy to test these alternatives for all the functions and it becomes clear that most of the platforms split into one of these two classes.

    Here are the classes ((Some of the platforms had to be dropped because there was no easy fit. My observation is that some of these platforms went through some crisis or change in strategy during their history which caused the pattern of growth to change)):

    Screen Shot 2013-09-12 at 9-12-4.43.43 PM
    Screen Shot 2013-09-12 at 9-12-4.44.58 PM

    Note that I added the formulas for the selected platforms.

    I named these classes after their function types: "Power platforms" or "Second Order platforms" ((Note that all Polynomial functions found above are second order)).

    This classification has two benefits:

    1. It allows a clearer distinction in scope. Both may exhibit signs of network effects, but Power platforms seem to exhibit "global" or unlimited reach while Second Order platforms may have a strong upper bound on reach.
    2. It allows more reliable forecasting. If a platform classifies as Power, the forecast could be created with fewer data points.
    3. It allows us to guess at the causes of entry into each class for any potential platform challenger.

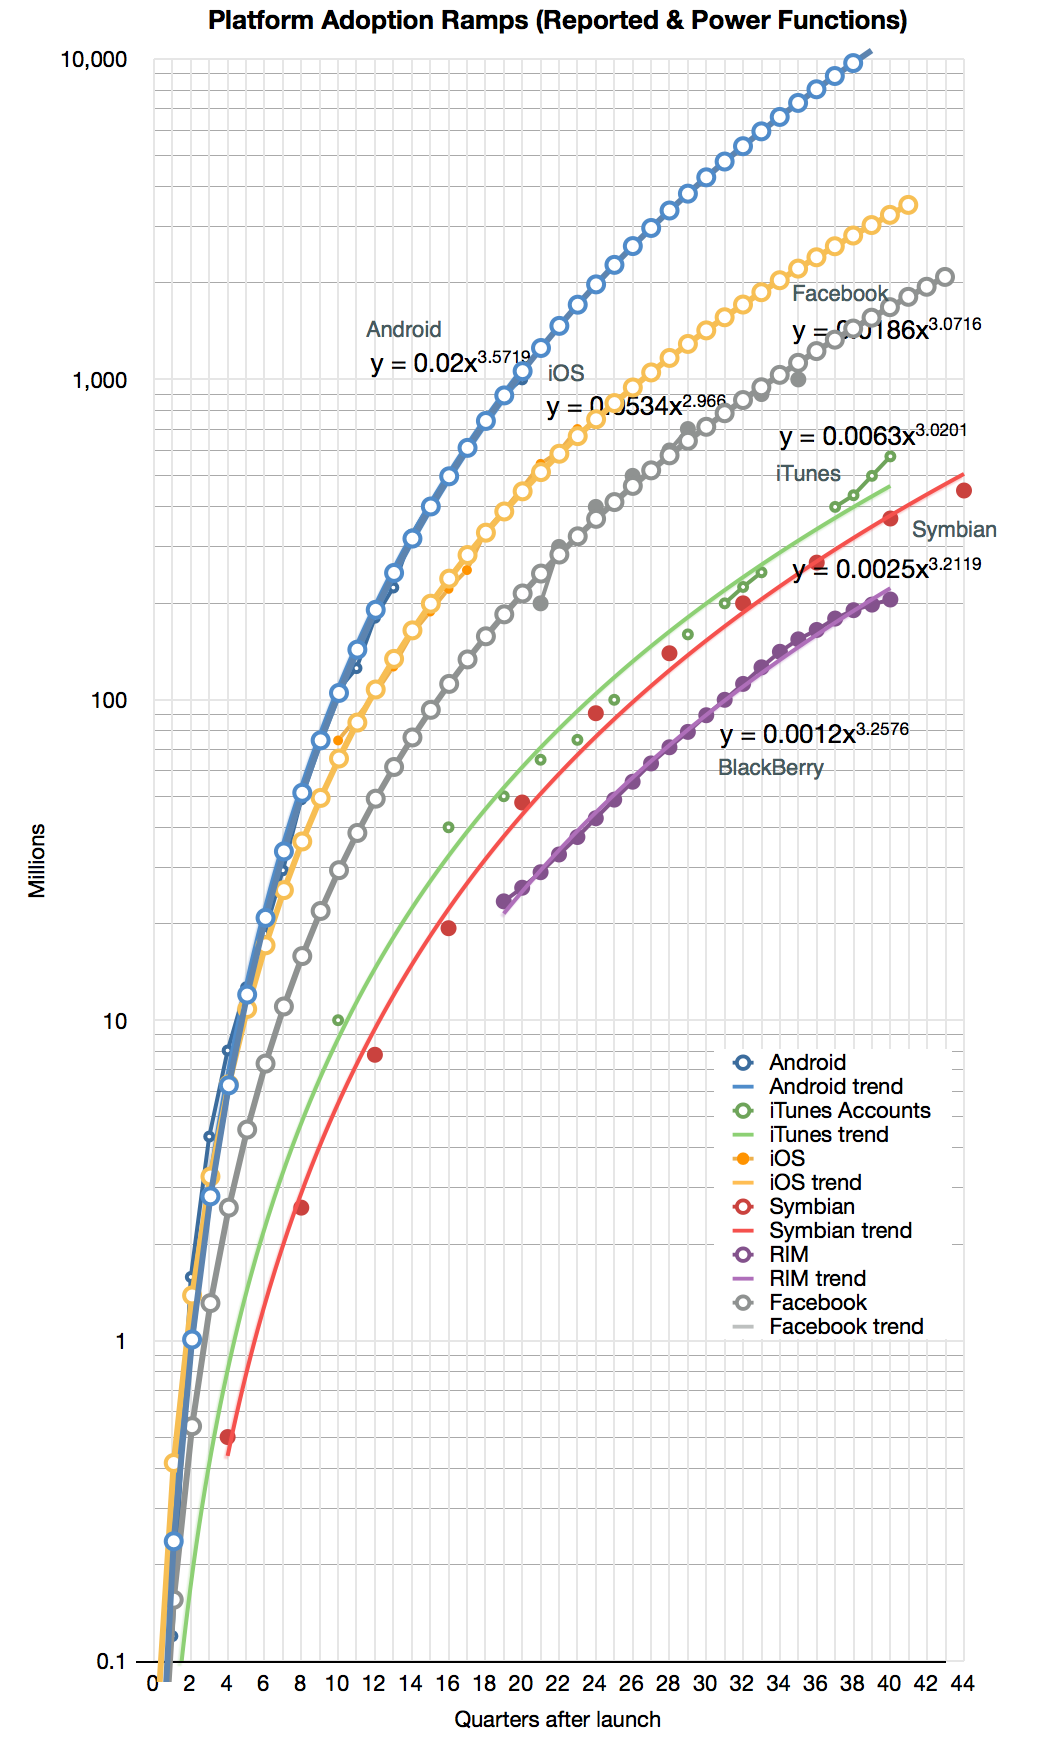
    To illustrate the second benefit, I took the Android, iOS and Facebook power functions and modeled (i.e. extrapolated) them for a few quarters into the future. The result is shown below:

    Screen Shot 2013-09-12 at 9-12-4.46.01 PM

    The forecast shows the following:

    • Android will reach 10 billion activations 10 years after its release (mid 2018)
    • iOS will reach 1 billion units sold by end of next year and 3 billion units by its 10th anniversary in 2017.
    • Facebook will reach 2 billion users by 2015 after the end of its 10th year.
  5. S is for Service

    Research · 96 comments

    One of the enduring mysteries of the iPhone has been its lack of a portfolio. After six years it seems that Apple has finally acquiesced that there should be one, albeit currently limited to two items. The second enigma is related to the price, namely why does Apple ask so much for its phones? At an average sales price of $600 it's a shocking premium to the average phone, and with a six year run, a shocking resistance to the corrosive effects of competition.

    The obvious answer to why Apple asks so much is because it can. Anybody would if they could. That's a poor question. So the right question should be: why does anybody pay this much? One could answer that few do and it's not a mystery that some feel better paying more simply because they can. But those who pay Apple's prices are, mainly, not consumers. They are operators. Exactly 270 of them.

    So then let's re-ask the question: Why do so many operators pay so much for Apple's phones? We can't answer that with the psychological slurs usually directed at the brand. Surely Operators aren't competing in beauty contests or need to soothe their collective egos. The decisions operators make on whether to range a phone are driven by hard economic realities: ARPU, churn, network costs, depreciation, ROI, etc. Some clearly can't make the iPhone fit their economic models and indeed about two thirds of them don't. But the most prominent ((Arguably the most important)) do. DoCoMo, the largest in Japan just did after holding out for five years. Verizon held out for years, as did T-Mobile. China Mobile's acceptance also seems imminent.

    But that still leaves the question of why are those operators who do carry the iPhone willing to pay so much for it? I only assume that their decision process is likely to be rational. Mainly because we have a large enough sample but also because there is a lot of money at stake requiring quite a bit of internal consensus and vetting before committment. We have to conclude that operators place the orders because they obtain value from the iPhone even when it's priced at a premium to the average alternative.

    The question which follows then is how do they obtain value? I've argued that this follow-the-money process leads one to conclude that the iPhone helps in moving users to higher revenue data services. These are more profitable services for operators and the subsidy model creates more loyalty and thus reduces churn and creates a stable cash flow which can then be leveraged through debt to upgrade networks and attract yet more loyal iPhone users.

    Therefore the iPhone is "a data service salesperson" receiving a large commission (in the form of a price- and hence margin premium) for doing what few others can do. In that sense the iPhone is hired by the operator to do a unique and valuable job and is paid well for doing it.

    This answers the question of why Apple can get away with charging so much for its phone: because operators love it. The entire product depends on a reward system and for years we've heard fears that it's going to end. But it hasn't. Operators love subsidies and they've been honing them for long before the iPhone showed up. ((Recall that the first iPhone was sold without subsidy and with a separate, secret revenue sharing plan. It did not last because it was cumbersome and because operators convinced Steve Jobs that their way was better.))

    But this is not the end of the money trail. The premium is initially paid by the operator but they tend to get most of that payment back from the consumer. In other words the subsidy that inflates the iPhone price is at least partly if not mostly paid by the consumer in the form of a higher phone bill.

    You won't see it itemized on your bill, but it's likely that $10 to $15/month from a subsidized phone service plan goes toward paying for your phone.

    So in a way, Apple has managed to place itself on many people's monthly phone bills. It's a nice place to be. It's nice for the same reasons operators like post-paid customers: predictability. It's also nice because recurring services are a better business model than products; they have higher levels of loyalty and are more "sticky".

    But this placement is not transparent. It smacks of misdirection. The link is not made in the mind of the consumer that they are paying for a phone through their service plan and many see it as a thinly veiled con. The value of the iPhone to the user may be evident through its use but the payment for that value is not.

    But in many ways this is similar to how many services are valued: through bundling. We pay for the value of a great retail experience through a higher price on items purchased. But we still associate that price with the good sold not with the place where it was bought. We get great value from Google's services but don't know how to quantify the cost of their peering into our minds. In fact the whole Internet and all business plans that are built on it depend on a subtle "something for nothing" type of misdirection. The Internet runs on the arbitrage between a consumer service market where everybody consumes but nobody pays and a separate data market where nobody consumes and everybody pays.

    The iPhone could thus be finally understood as a complex service business. It captures value through the phone bill but delivers value through a screen. A misdirection magic trick which many have tried to pull off. It's essentially tapping into the $1.3 trillion communications market, skimming profits by delivering the "content" which lights up the wires.

    It's great except it does not work everywhere. Not yet at least. The complexity of services means that they are usually found in more advanced so-called service economies and rare in less developed so-called goods economies.

    Economists have observed this process and even have a name for it: servitization: The process whereby almost all sufficiently advanced products are indistinguishable from services.

    As a service, the iPhone's strengths are easier to understand. Its weaknesses as well. Services simply don't work in economies which don't have robust institutions of credit, capital intensive infrastructure and distribution networks.

    It's also the reason why Apple is so slow to penetrate all markets. It's not in the business of selling phones. It's in the business of enabling and creating services.

  6. C is for Cognitive Illusion

    Research · 192 comments

    My assumption going into this, sixth iteration, of the iPhone was that we would see the expansion of the iPhone into two distinctly positioned products: a low-end C and a high-end S. The assumption was based on what what we saw with the iPad: the regular iPad and the mini iPad.

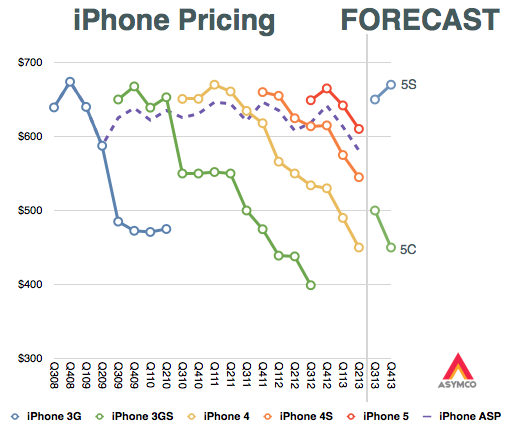
    By using the iPad as a template, my exercise in August was to forecast what the pricing ((Revenue/unit to be more precise)) might turn out to be for such a split-personality product.

    I expected the 5C would replace the "low end" n-2 variant ((Older by two generations as the iPad mini replaced the iPad 3)) and the 5S would continue as the core product. This is reflected in the original graph as devised in mid-August:

    Screen Shot 2013-08-12 at 8-12-11.44.05 AM

    The surprise was that the 5C was not "low end" in any way other than having a plastic case. It has a minor spec increase over the 5 but is otherwise a 5 feature set in a plastic skin. It also is priced as if it was the continuation of the 5, with a modest reduction in ASP.

    In addition, the continuation of the 4S and 4 (in China at least) means that the old strategy continues more-or-less unchanged.

    Knowing the line-up and pricing all that remains to understand is the positioning, or how the products are defined relative to each other.

    This is where there might be a shift happening. Under the old model the n-1 variant was meant to be a modest volume contributor to the portfolio, being essentially a cognitive illusion which encouraged buyers to stick with iPhone n at the expense of competitors. However, the new n-1 product (the 5C) has a distinct positioning that makes it seem fresh and not a lesser, stale version of the flagship. It is designed to appeal as a legitimate upgrade for iPhone 4/4S users.  It is, in other words, not meant as an illusion, and not focusing attention on the flagship ((It might still be an illusion for many but I'm suggesting that it won't be for most.)). Rather, it is meant to be a genuine, core product.

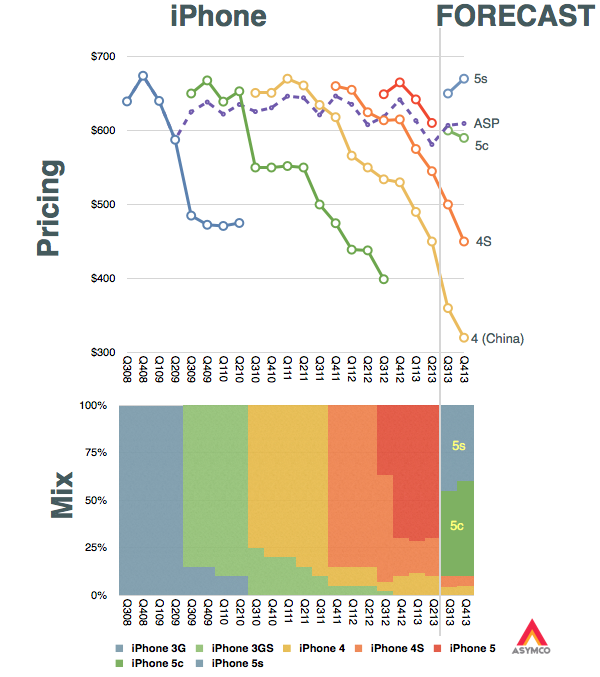
    As a result, I expect the mix of iPhones to be more evenly split between the C and S variants. I expect the C to even become the most popular version in the mid-term. My expectations are shown in the following graphs.

    Screen Shot 2013-09-11 at 9-11-11.57.11 AM

    There are several implications for this shift in positioning:

    1. Apple is recognizing that the market is actually "segmentable". This is the notion that one size does not fit all--a radical idea for the brand. Its mechanism to address it is a "good+better" portfolio. Note that this is not at all like the iPad where the Mini is actually suited to different tasks. The iPad can be thought of as a "small+big" portfolio. The iPhone shows a clear delineation within the same product.
    2. It is signaling that the premium may be more than what the mainstream needs. This is a corollary to the segmentation implication above but stands on its own because it also implies that the iPhone C is "good enough" and the S is more than good enough (or, to spin it another way, it is for "more demanding" customers.) It also implies that the premium "S" version will be a lower volume contributor.
    3. The third implication is that the basis of competition is shifting. ((It has always been expected to shift, but the timing is where all the value is captured)) The shift is toward competing for late adopters in advanced markets and with early adopters in trailing markets. The new C model is still not suitable for trailing markets as it still over-serves and is over-priced ((This post deals with the iPhone portfolio structure or the placement of iPhone models relative to one another. It does not deal with a separate question of why the overall pricing is so high. That question needs to be dealt with as a discussion about the jobs iPhone is hired to do and by whom. I'll re-visit this job-based segmentation of the market in a future post.)), but it is at least signaling the "end of the beginning" phase in the smartphone market.

    In summary I'd say that the C signals the beginning of the "good enough" phase which was also evidenced by the increasing mix of the older models during the last year. Financially it shows up as lower ASP, which, as the graph above implies, I expect to drop to $600 and lower during the next year.  Margins may not be affected much as the C is still very highly priced relative to its cost of production.

    Finally, if the good enough alternative is being "pinned" by Apple as the mid-range it also begs the question of why there isn't a specific "low end" version. It took six years for Apple to fork the product into two variants. Maybe it will take another year for it to stretch to a third. ((For more on the subject see S is for Service.))


  7. My interview with Chloe Cho on CNBC Asia's Cash Flow show

    Research · 3 comments

    My thanks to Kirk Burgess for providing this transcript:

    Horace Dediu interview on CNBC Asia Cash Flow show - 10th September 2013

    Chloe Cho (CNBC): Take us through what Apple is exactly trying to do?

    Horace Dediu: Well, this is the first time in the six years of this competition in the smartphone market that Apple has broadened its portfolio. We have seen only a single product launch every year--this is very unorthodox in the industry. Normally each competitor [ranges] dozens of devices. Apple's entry has been asymmetric from the start, and now in its sixth year we are expecting to see, finally, a broadening perhaps into two separate products. The question will be whether [there will be] a significantly lower price point for the so-called 5C and whether that will change the average selling price overall for the portfolio. The average selling price has been remarkably steady, and remarkably high, typically around $600 for the duration of this products life. Something, again, unprecedented. My expectation is the new price point will be quite a bit lower than $600, starting with about $450, it might drop a bit further, [which] would cause the overall price range to come down as we have seen with the iPad; [where we] also had a price erosion happen as the smaller version came out.

    Q: Horace, do you think they have got the timing right? Should they have done this a little bit earlier when the market wasn't so saturated and filled with cutthroat competition?

    A: Indeed, I think. As I said, as a product with six years in the market it's a bit late; I expected this to happen last year. I think a lot of the momentum that has been lost in the past year in terms of sales growth has been because of the lack of low end. To note also will be whether they indeed expand their carrier footprint. We are expecting something new in Japan and possibly China Mobile. There is a second announcement happening with a few hours delay in China. This is again the first time that has ever happened.

    Q: Horace, do you think they didn’t move down the value chain fast enough largely because they didn’t have a deal with China Mobile?

    A: Well that's always a good question whether they are driven more by carrier channels or are they driven more by consumer market expectations. I think it's a bit of both. We do have this hybrid approach where they continue selling this older product for one or two years after the new product is launched--so the 4 and 4S are still available while the 5 is being ranged. This strategy is hybrid I say because this isn't truly a low end product, it is a stale product that is being put out there. This [strategy] may be driven more by consumer demand, not so much what operators are asking for. With the 5C we might be looking at a solution for operators in particular.

    Q: Horace, how much do some these incumbents like Apple and Samsung need to be worried about Microsoft approaching their space?

    A: I believe Microsoft will not be competitive in the near term. I don't think [during] the next year we are going to see a very impactful entry from Microsoft. What Microsoft is likely do is lower prices significantly on Nokia's portfolio and their pipeline as it is. That might cause more pressure on the pricing, but the problem has been that consumers have not really been taking up the Windows Phone platform very aggressively. It has been somewhat successful in Europe but not taking off elsewhere. I think Microsoft will be in an integration mode with the Nokia assets into 2014, but I would expect in a year from now we might see some new entry product that would be exciting. I think 2-3 years down the road we might see something from Microsoft that would excite consumers as well.

    Q: There has been a lot of focus on which companies have a more integrated house, Apple or Samsung. In light of the fact that they are having to move into lower price points, in your view which is doing the better Job, Apple or Samsung?

    A: Well Samsung is a great industrial enterprise and they are doing very well by broadening as much as possible their portfolio, even before the smartphone race started for them, which was in 2010, they were known for being one of the most prolific product creators out there. They actually had over 100 different mobile phones, not smartphones, just regular mobile phones that they would range, and Nokia were extremely concerned by this pressure they were getting from Samsung.

    What they have seen since 2010 is the same thing, except with smartphones, and so they’ve been really prolific and covering the spectrum of price and screen and every other possible variant that could be made. I think however that Samsung hasn’t got a software platform under its belt. They could become a software player by taking over some of the control of Android as we have seen Amazon do, and thus really establish themselves as a platform player. They are doing so to some degree with the "Gear" product, and they might be doing something like this by launching their development conference this year.

    But they aren't yet a platform player whereas Apple is, but then again we just don’t know what the politics of Android are with respect to forking it by an OEM as large as Samsung.

  8. Game over

    Research · 235 comments

    In the "Race to a Billion" there is a graph showing Android reported activations and iOS cumulative unit sales alongside cumulative console sales. The contrast between mobile phone platforms and game consoles is striking, with an order of magnitude difference in consumption. The best performing console to date is the Wii with about 100 million units sold so far.

    [UPDATE: Thanks to Danny Nemer cumulative sales of Sony's PlayStation 2 (using production shipments from FY 2000-05 and recorded sales for FY 06-12) is 155.81 million units]

    However, that is an incomplete picture of the game platform business primarily because consoles are not the entirety of the business. Mobile (but dedicated) gaming platforms have been sold for some time.

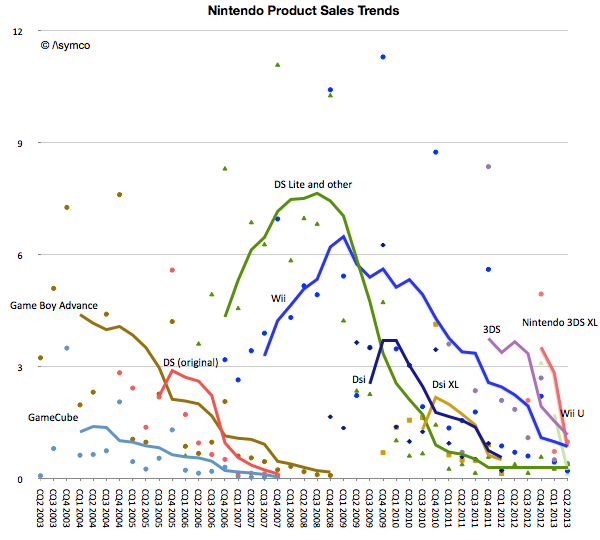
    To give a better picture of the game business we prepared the following graphs. The first shows Nintendo's product lines with actual unit shipments (shown as colored dots in millions of units per quarter) and the trend (shown as trailing twelve months' average trend lines).

    Screen Shot 2013-09-09 at 9-9-4.45.30 PM

    Note that fixed and mobile products are both shown on the same graph. The picture that emerges is that for Nintendo, its mobile platforms combined are more popular than its fixed consoles with a total of 186 million mobile devices sold since 2003.

    There is also a pattern of generational change. The GBA, DS and GameCube era was superseded by the DS Lite, DSi, Wii era. The Wii era (or generation) was significantly more popular than the GameCube generation. If there is a problem however, it seems to be that the new generation devices or consoles are not forming a new era. The Wii U and 3DS are not growing nearly to the level of the previous generations and have faded quickly.

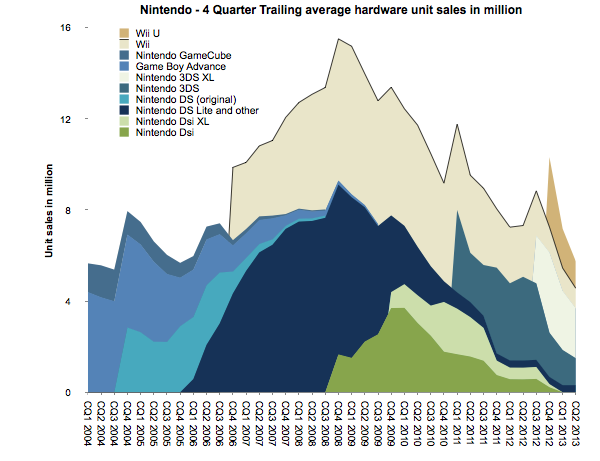
    To summarize, the unit volume graph for Nintendo is below. ((This is a smoothed graph showing what sales would have been if they had been evenly spread out over a 12 month period. The actual sales would total to the same area but would be much more seasonal and thus noisy.))

    Screen Shot 2013-09-10 at 9-10-10.25.23 AM

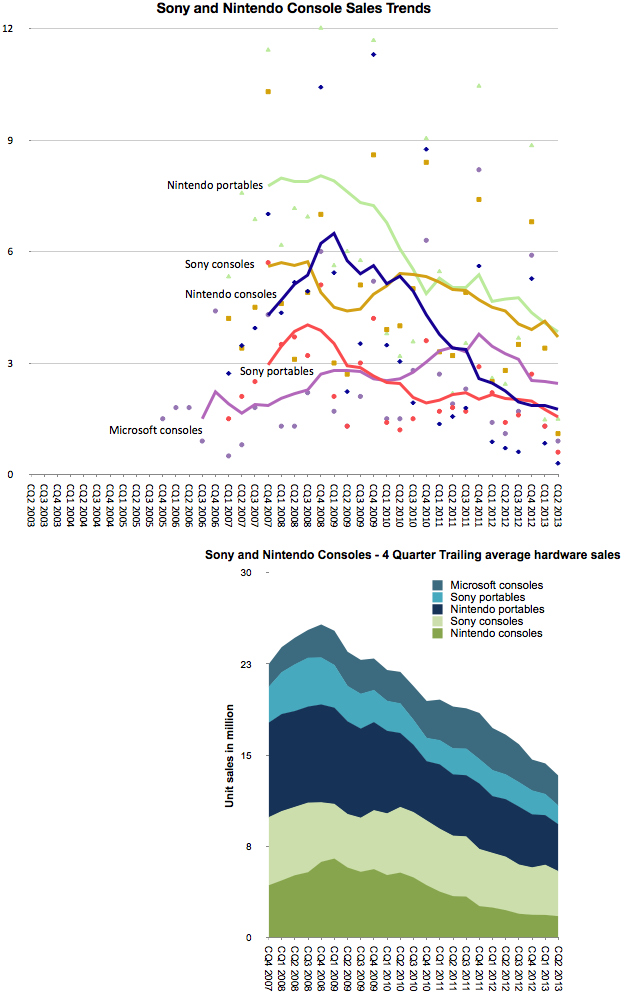
    To confirm that this is indeed disruption we should look at the pattern for another competitor in the console market: Sony. ((We would like to show the pattern for Microsoft but there is no regularly reported Xbox shipment data.))

    Screen Shot 2013-09-10 at 9-10-11.09.16 AM

    The graphs above combine both Nintendo portable/consoles and Sony portable/console sales. Note the similarity in patterns of growth. It's one thing to suggest that Nintendo consoles have "failed", it's another to show that Nintendo consoles and portables have failed, and yet another to show that two competitors in the games business seem to be failing in unison across all their product lines.  The cyclicality is also over a long period of time: The peak for the combined Sony/Nintendo was in 2008, five years ago.

    The chief criticism to the industry-wide view of decline is that there is a new generation of consoles right around the corner. This is the eighth generation of consoles which, it is presumed, will bring growth back to the industry.

    But the Nintendo 3DS, launched two years ago, was meant to kick off the eighth generation, and the PlayStation Vita was Sony's response. Then the Wii U was also billed as the successor to the Wii. They have so far failed to re-ignite growth. One might reply that they were merely appetizers and that the main  course of the next gen are the PS4 and Xbox One.

    Will they create growth again? Surely not for Nintendo, but I would argue that not for Sony or Microsoft either. There might be a burst of sales at launch as the hard core gamers upgrade, but they are unlikely to recruit new gamers the way the Wii did. In other words the PS4 and Xbox One are unlikely to win against non-consumption.

    That is where mobile is the clear winner. More people will hire mobile devices for their primary gaming activity.  And as mobile devices get inexorably better, they will be hired for use in the setting where consoles have been king: the living room.

    The implications are that Nintendo, Sony and Microsoft are beyond the point of no return in this industry. Gaming, as a business, cannot be sustained as a platform independent of a general purpose computer. Like other "applications" that used to have systems built around them conforming to their needs (( Applications such as word processing, financial calculation, media editing, music playback, etc.)) the dedicated-purpose solutions came to be absorbed into the general-purpose platforms. And the modern general purpose computer is the smartphone. (( One interesting question is why didn't the general purpose personal computer absorb console gaming. My answer is that personal computers could not conform to the experiences around the "10 foot" interface and still function well at their main jobs. In contrast, mobile devices through screen sharing have the ability to be much more malleable.))

    UPDATE: I added Microsoft console shipment data which became available after 2008.

  9. Third to a billion

    Research · 166 comments

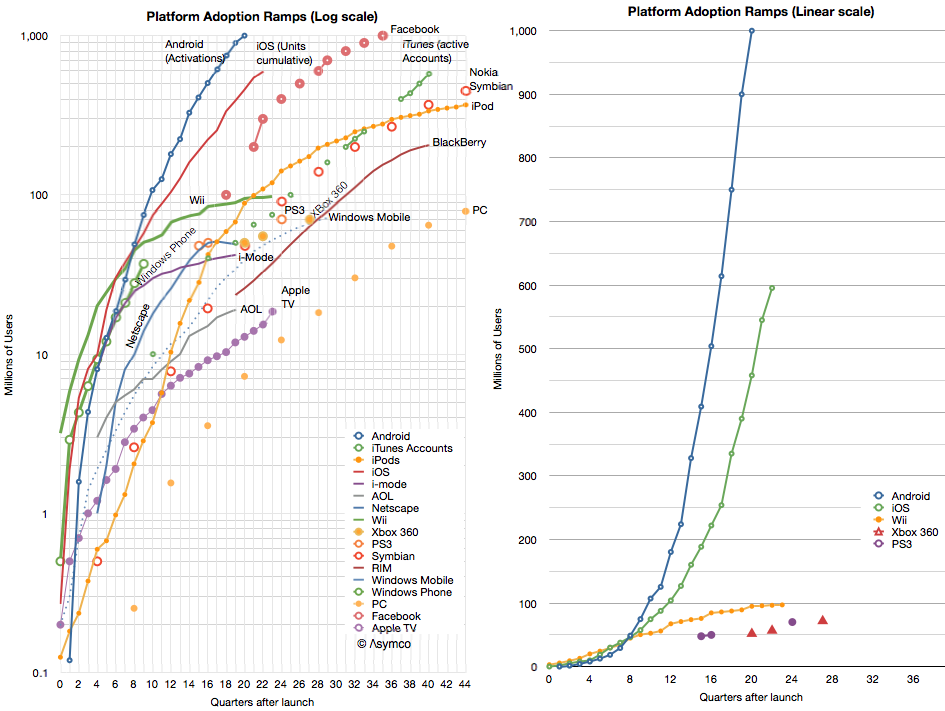
    Android is the third platform to reach a billion users ((Although activations are not users, I'm assuming that usage is not far behind and the cumulative sales figures I gather are roughly comparable.)) .  The first was Windows and the second was Facebook. Apple sold around 650 to 700 million iOS and is expected to be the fourth to a billion sometime next year. ((Separately, iTunes reports 575 million account holders.))

    If we define the Race To a Billion to be bounded by a time limit of 10 years, then Windows does not qualify and Android is actually second. The race is shown in the following graphs (the one on the left is logarithmic scaled, the one to the right includes only a few contenders for illustrative reasons).

    Screen Shot 2013-09-06 at 9-6-4.06.29 PM

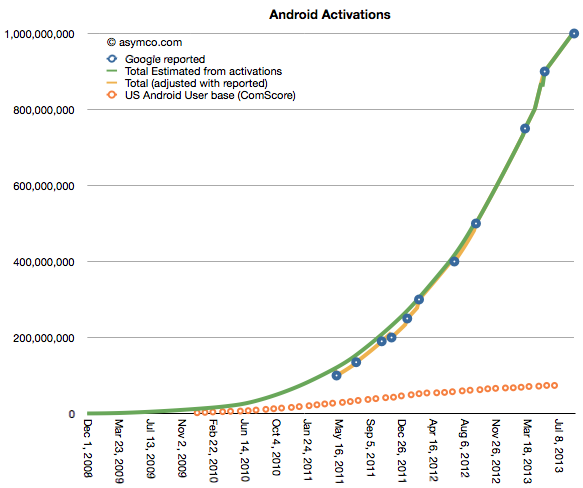
    Android's activations as reported are shown in the following graph:

    Screen Shot 2013-09-04 at 9-4-1.15.38 PM

    Without qualification, Android has been a viral success story. It reached one billion activations in about five years, almost half the time it took FaceBook and far faster than Windows.

    However, Android growth can be qualified. I added another set of data which is the number of US Android phone users as deduced from measurements by ComScore. ((ComScore surveys users on their primary phone. Survey includes only those aged over 13 years and excludes phones issued by businesses.))

    One way to read the two graphs is: Between March and August, of the 250 million Android devices activated, 4 million were to new Android consumers in the US. In other words, In the last six months, 1.6% of Android activations went toward new usage in the US. The equivalent figure for iOS is about 6%. Note that these are new users, not included are upgrades. It's likely that more of the US buying goes toward upgrades because iOS has been in use longer.

    So whereas Android is growing very rapidly, there is a question of reliability of that audience. Engagement is one thing, but in the market which shows highest penetration (and deepest distribution of an alternative) Android is peaking.


  10. Who's next?

    Research · 166 comments

    In February I asked Why doesn't anybody copy Apple?

    Put another way: Why is it that everyone wants to copy Apple’s products but nobody wants to copy being Apple?

    Being Apple means, at least:

    • Insourcing all aspects of operations which affect the customer experience. Increasingly that has meant insourcing everything, a toxic idea to every MBA-trained professional since forever.
    • Organizing functionally and having no product level P/L responsibility. That also means removing almost all incentives for employees to climb ladders and thus prove their worth.
    • Developing products using integrated "heroic" efforts which shun  every best (or even adequate) process for product development.

    I asked somewhat rhetorically because it's an open question. Apple's operating model and devotion to integration have been asymmetric to technology dogma for decades. To the casual (read: naïve) observer, pursuing the Apple way seemed also to be tied to one individual. You could not "be Apple" unless you were also Steve Jobs and there was only one of him.

    But it seems I did not give enough credit to other observers.

    According to Microsoft, they began negotiating the buying of Nokia assets in earnest (coincidentally) in February. It has, also since February, been planning a massive re-organization along functional lines. Thus, by owning significant hardware operations and organizing functionally, Microsoft might go about two thirds toward "being Apple-like". The development process is the final hurdle and it may be a bridge too far, but my thesis that nobody wants to copy Apple is now in tatters.

    And it gets worse. We can see a similar, though far weaker, example in Google's approach to integration. Their purchase of Motorola did not result in an integrated business, with Motorola being kept at arm's length and allowed to wither on the vine. Crucially, while Google bought Motorola's IP, Microsoft only licensed Nokia's. Microsoft clearly valued Nokia for something different than  what Google valued Motorola for.

    Nevertheless there is a semblance of similarity. We can generalize enough and say that Apple (iOS), Google (Android/Chrome) and Microsoft (Windows (Phone)) are all becoming near facsimiles of each other. They are all producers of Software, Services and Hardware. Each came from a different basis but expanded into areas which were missing.

    • Google started with a service, expanded into systems software and bought into hardware.
    • Apple started with hardware running its own software, expanded into application software and is developing services.
    • Microsoft started with software, expanded organically into services and bought into hardware.

    All three major platform companies are now racing to offer that which completes them as an integrated producer and eliminates the dependencies on others as a modular producer.

    This is re-integration of the computing industry--a reversal of the dis-integration brought about by the personal computer. Mobility, it turns out, was as important to the evolution of the computing value chain as microprocessors were to the previous era. It just had the opposite effect.

    I should point out that Apple was more lucky than enlightened through this sea change. Having always been integrated, Apple was out of favor during one period of the computing epoch, but, simply by surviving, its model came back into favor in the next. I don't think anybody there foresaw just how dramatic the shift would be and how important their structure was to being successful.

    But there is one company which seems left out of this discussion. Samsung is absorbing a large part of the available profits in computing today and it's not an integrated hardware/software/services player. Does this mean that there is room to be a module in an interdependent world?

    I argue that no, there isn't. Samsung must either stretch into becoming one of the ecosystem contenders or be relegated to a commodity hardware company--a path clearly visible when looking at Chinese entrants. Samsung itself benefited from disrupting from below and should be aware of the threat it faces as it races up-market. More importantly though there is the ability of creating new markets altogether. This new market creation and rapid iteration due to integration is what the Google/Microsoft/Apple trio are seeking.

    Without the components of software (ecosystems included[1]) and services, Samsung will depend on the good graces of suppliers. They may not be as keen to share when profits accrue to the whole rather than the part.


    ---

    Note:

    [1] e.g. BlackBerry

  11. Who's buying whom?

    Research · 115 comments

    When a prosperous company buys a struggling company you have to wonder what they're really buying.

    Here's how to think about it. A company is defined as the sum of three values: resources, processes and priorities (RPP). Everything of value can be classified into these three categories.

    When one company buys another it's the equivalent of one set of RPPs trying to engulf or swallow another set of RPPs. The simplest (naïve) interpretation is that an acquisition is the purchase of Resources in terms of customers, sales, profits, etc. It might be of assets like employees, intellectual properties, brand etc. I say this is naïve because Resources are the easiest to value because they can be measured and valuing only what can be measured while ignoring what can't be measured is deeply mis-pricing.

    So most people look for the "R" value or the value of Resources in an acquisition. It's may be naïve but it is what markets typically value because it's what they can price. But what happens when the "R" is flimsy or fleeting?

    The answer has to be that it's  the processes or even priorities which are valued by the acquirer.

    These are difficult to value which, as I've argued in The Innovator's Curse, is why they are not reflected in a share's price. When there is a price paid for these fuzzy assets, they are often interpreted as a "premium" to the market price. But that may not be the way a buyer sees it.

    When buying a set of Processes, a buyer may see a bargain because their costs for building a similar process could be enormous, even infinite. In the case of Nokia, the process of building hardware may be infinitely valuable to Microsoft as they have had dreadful luck doing it themselves. But they're seen as value free to the market because it seems that there are many others who are building hardware.

    The trickiest thing to perceive though is the value of a set of Priorities. Priorities are the answers to the "Why" question as much as Resources are the answers to the "What" and processes are to the "How." If you were to think in terms of software engineering Priorities are the "Specifications" where the Resources are the data and Processes are the algorithms. They determine the direction and reasoning of why a company even exists. If you have bad specs, it never matters whether the algorithm is efficient and you have all the data: you are building the wrong thing.

    Acquiring Priorities is also fundamental in that they are usually exclusive. A company typically only has room for one set. If there are conflicting priorities, they need to be sorted out else the company can end up in a state of internal conflict and dysfunction. So if you're acquiring a set of Priorities, it's likely that you'll have to discard your own. It makes most sense when a company which might otherwise be prosperous needs to change direction.

    So, in a way, an acquisition of Priorities is almost a reverse acquisition. The acquired is actually "buying" the acquirer. The acquired company's Priorities (and hence Processes and Resources) become the guiding principles in the acquirer. It's what happened when Apple bought NeXT and may have happened when Disney bought Pixar.

    Some companies are "Resource-heavy", some are "Process-heavy" and some are "Priority-heavy". Great companies tend to have great sense of priority. They may also have greatness in the other asset classes but it's rare to find a great company without a great sense of purpose.

    So the question for the Microsoft Nokia deal is what is Microsoft buying?

    Resources? Sure, there is IP and a team. But the chances are that not all the team members will be kept on. See what happened to Motorola after it was acquired by Google.

    Processes? Absolutely. Microsoft needs device development processes desperately.  They may seem a commodity but it turns out that running great hardware businesses is hard, very hard.

    Priorities? Here we have to pause. To acquire Nokia's priorities means acquiring its business model; its belief system. Perhaps they will be discarded and they're not valued. Perhaps, as is often the case, the acquirer becomes allergic to the new priorities.

    But Microsoft has made it clear that they are now a "Devices and Services" company. As much as Apple changed its name to exclude "Computer," Microsoft is almost changing its name to exclude "software". It will still make software, to be sure, but for it to get paid it needs to integrate that software into hardware and services.

    My first thought on this is that Nokia's priorities are not sufficient for the company that Microsoft wants and needs to become, but there are some priorities which are necessary and which it values.

    It may be too much to say that with respect to Priorities, Nokia acquired Microsoft, but insofar as Microsoft is having to transform its business model, what Nokia devices brings is an integral component of the new.