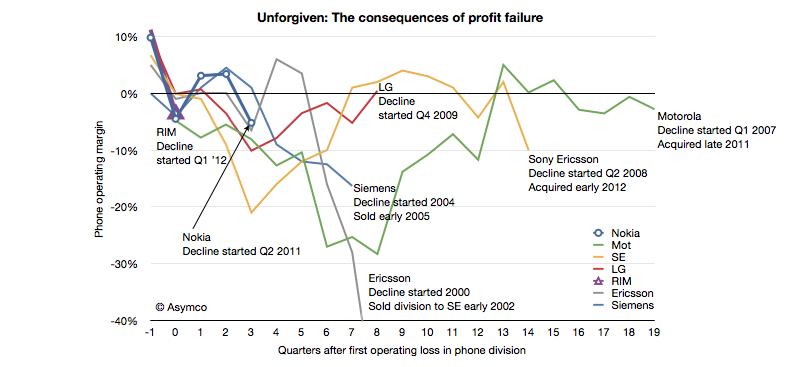
In June of last year I wrote a post titled "Does the phone market forgive failure?" It was written on the eve of Nokia's Q2 2011 report highlighting the historic consequences of a dip into negative operating margins for a phone vendor.
I listed 13 phone vendors who were either merged, liquidated or acquired. There are no examples of vendors who recovered from a position of loss making.
I was prompted to follow-up by a note Charter Equity Research analyst Edward Snyder wrote illustrating the effect of negative operating margins on phone vendors. I took his illustration and expanded it with additional data.
Since my post in June last year Sony Ericsson and Motorola were acquired making the victims list total 14 companies, with Nokia, LG and RIM having joined the "endangered species list". If the pattern repeats, then RIM and Nokia are in early phases of what promises to be an extended period of pain followed by an exit.
What the analysis does not answer is when a vendor loses its independence after beginning loss making. Motorola took 20 quarters; Sony Ericsson 14, Ericsson 8 and Siemens only 7. We cannot tell if or when LG, which is still operating after 8 and Nokia, which is now in its fourth and RIM, now in its second quarter post-loss, will lose independence.
The rumors swirling around RIM and LG are centered around exits and some suggest Nokia will follow. Many also argue that these companies will recover. The conditions they each face are different in details but broadly they are the same. Earlier last decade the exits were prompted by loss of brand value and subsequent loss of distribution. This decade disruption brought upon by mobile computing brings with it new business models centered on ecosystems and value captured through software and services.
Until and unless these endangered companies solve the dilemma of having the wrong business model at the wrong time, the chances are that they will not be forgiven for market failure.
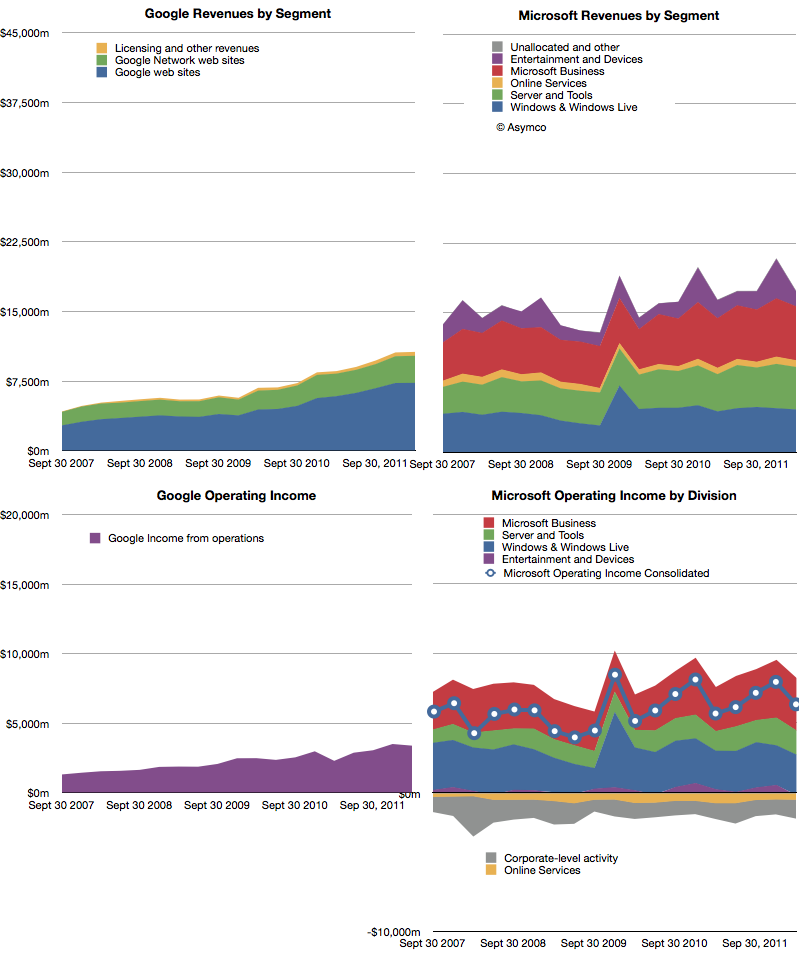
The following charts show Google and Microsoft revenues and operating income:
Both companies showed healthy growth. Revenues: Microsoft 6%, Google 24%. Operating Income: Microsoft 12%, Google 48%. Google had a particularly weak margin Q1 2011 so its income growth appears very strong.
The surprise in Microsoft's performance was the 4.8% increase in Windows revenue at a time when PC sales were expected to be declining or flat. Final PC numbers are not yet out so we'll have to check back on this figure to see whether Microsoft has been able to get higher pricing for Windows or whether the market did expand. (Average revenues per PC sold have been quite steady for years). Overall, Microsoft's business shows consistency. Of course, that should not be cause for comfort. Nokia had remarkable consistency until it jumped from a burning platform and RIM grew more rapidly until its platform imploded.
As Google still obtains 96% of its income from advertising, it's quite remarkable that it is now at 61% of Microsoft's revenues. Google is also growing more rapidly than Microsoft so the possibility exists that the top ad service will overtake the top software company in revenue, establishing a new benchmark for how software can be monetized.
The curious thing about both of these companies' financial performance is that mobility does not appear to have had any impact on either top or bottom lines[1]. There is no business division or income statement line that can be attached to mobile revenues. Microsoft placed Windows Phone under Entertainment and Devices but that division is dominated by Xbox and accessories. Google bundles everything under Advertising and has never broken out mobile, much less Android-derived income.
The surge in valuation for mobile-focused startups seems to leave investors in both these companies unaffected. The damnation for both companies lies in mobility being non-core businesses whose strategies center on reaction and defense.
---
Notes:
Google does not answer specific questions about the impact of mobile on their business but they do acknowledge that there are traffic acquisition costs (TAC) associated with OEMs and Carriers who deploy Android. This means that there are costs of mobile sales (i.e. Search) but not to any measure of specific value.
Our agreement with Microsoft includes platform support payments from Microsoft to us as well as software royalty payments from us to Microsoft. In the first quarter 2012, we received a quarterly platform support payment of USD 250 million (approximately EUR 189 million). We have a competitive software royalty structure, which includes minimum software royalty commitments. Over the life of the agreement, both the platform support payments and the minimum software royalty commitments are expected to measure in the billions of US Dollars. The total amount of the platform support payments is expected to slightly exceed the total amount of the minimum software royalty commitments.
The figure of $250 million for Q1 is the same as the amount Nokia received for "platform support" in Q4 2011. This means Microsoft has paid $500 million over two quarters. During the same time frame Nokia shipped approximately three million Windows Phone devices. The average cost to Microsoft to acquire a Nokia Windows Phone user is therefore $167 per user. This is down from $250/user in the last quarter.[1]
If the royalty is equivalent to a license fee then the more interesting question is how and when will the royalty payments nearly match the platform support payments as expected. This might give us an estimate of what both parties are expecting from the relationship.
If the payment schedule of $250 million per quarter is maintained through 2014, Microsoft will have paid $3.25 billion to Nokia. This is well within the "billions of US dollars" range that is cited above. (The minimum would be $2 billion which would mean payments through the end of 2013).
We also need to estimate the royalty payment structure. One figure that has been circulating for a long time is that Microsoft prices Windows Phone (and its antecedent Windows Mobile) at $15/unit. It's an aggressive price point for a mobile software license and should be subject to volume discounts but let's assume it's correct. If it is correct then the only remaining question is how quickly will Windows Phone units grow at Nokia?
One way to begin is to calibrate WP growth to iPhone growth. For the first two quarters iPhone and Lumia have sold at rough parity.[2] iPhone sold 1.4 million in its first quarter (including opening weekend sales of 270k in previous quarter) while Nokia sold "approximately" one million Lumias in its first quarter[3]. In the second quarter Nokia cited 2 million Lumia units and Apple had 2.3 million iPhone sold in Q4 07. So far Lumia is slightly under the iPhone ramp, but let's give it the benefit of doubt.
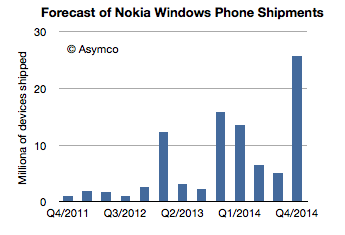
If we apply iPhone growth rates to Lumia then we have the following sales forecast for Nokia's Windows Phones:
This looks like healthy growth, as was the iPhone's. However, this "iPhone growth" pattern only results in about $1.4 billion in payments in exchange for $3.25 billion from Microsoft, leaving a deficit of $1.9 billion in the "platform support" balance.
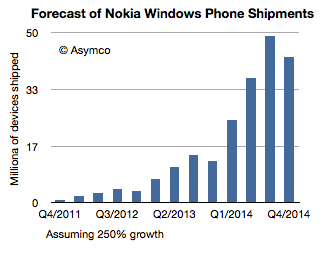
To erase the deficit, I tried an approach where I assigned 3 million and 4 million for Q2 and Q3 shipments respectively then applied a constant (y/y) growth rate thereafter. Solving for a figure of growth which results rough parity with platform support payments gives us about 250% growth. The resulting sales profile looks like this:
This ramp would result in 210 million Windows Phones shipped over about three years. It would also generate nearly $3.2 billion in "royalties" for Microsoft offsetting $3.25 billion in "platform support" payments by Microsoft to Nokia.
There are many assumptions in this, royalty rate and length of contract chief among them, but the key question should be a sanity check: is this a feasible product ramp. It's certainly far faster growth than Apple has been able to achieve. On average Apple obtained about 160% quarterly y/y growth. It also exceeds the growth rate that Samsung has been able to achieve (165 to 170 million smartphones shipped from a standing start three years ago). It implies 150 million units shipping in the third year of sales and nearly 50 million in a peak quarter. It assumes perhaps as much as 20% market share in smartphones in 2014. It's certainly ambitious.
But even if it's achieved, it's only a break-even point for Microsoft's relationship with Nokia. It would imply that payments to and payments from Nokia would be in balance. The road to (dare one say it?) profitability for Microsoft in mobile would just begin to be visible at that point.
---
Notes:
What the quote above also reveals is that Nokia is also expecting to pay back some of these "support payments" in the form of "royalty payments" for the software. That's an interesting word choice as usually an OEM would pay a license rather than a royalty for software. I'm not sure if this implies anything but it may.
See also Charles Arthur's analysis of comparable growth ramps for mobile phone platforms here.
This figure was cited "to date" in a March statement so actual calendar Q1 may have been less, perhaps 650k.
Nokia reported Q1 results following very closely the warning issued last week.
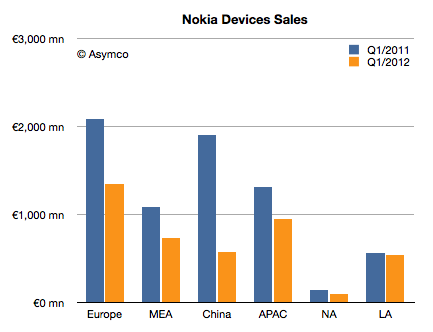
There were few surprises. There is much more detail in terms of regional performance which might be a better indicator of how the smartphone strategy is playing out. I plotted the data in three charts.
Regional Sales Value
A year ago Europe and China were nearly equally valuable as regions to Nokia (€2.1 billion and €1.9 billion, respectively). Even though sales fell across all regions, China fell so much that it has become the fourth in value and nearly the same value as Latin America (€577 million for China vs. €542 million for Latin America). This is a significant reversal for a very important market. The drop in value is a staggering 70%. Is there some clue as to what caused this?
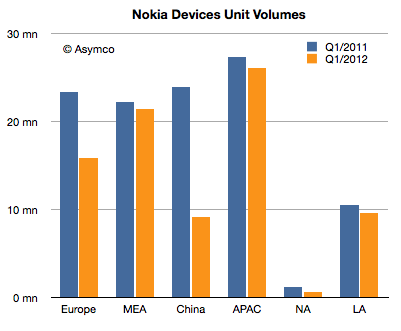
Regional Unit Volumes
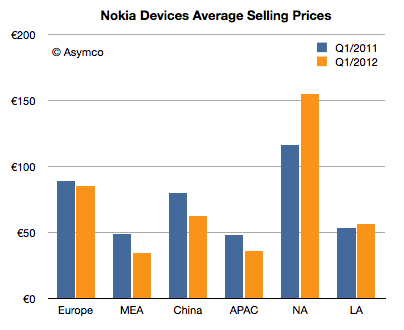
The data on volumes shows that Europe's drop is consistent (35% drop in value coupled with 32% drop in units). This implies an erosion in pricing but not a very large drop. However, in China the volumes fell less rapidly than sales (70% drop in value and 62% drop in volume). The pricing story was significantly worse. This story repeats in Middle East, Africa and Asia Pacific where volumes held but value dropped. This implies significant change in pricing in those regions. That's borne out by the chart below:
Regional Selling Prices
Prices in Europe dropped by about 4% but in China they dropped by 21% (from €80 to €63). In APAC the drop in price was 25% and in Middle East and Africa it was 30%. In the Americas prices increased with North America up by one third and Latin America by about 6%.
This uplift in NA is primarily due to the Lumia launch as channel was being filled. However, note that North American volumes were extremely small: only 600,000 units sold (inclusive all models).
As the Lumia line was not available in many markets, and as only 2 million were sold, it's hard to see its impact. The only clear effect was on North America prices and that overall smart devices ASP held the line (down only 2% y/y and up 2% sequentially). The €220 average price for Lumia was well above the €143 for all smart devices sold. Nevertheless, smart device volumes were down 50% to about 12 million units--nearly the same as RIM's pitiful results.
What these data points add up to is that Nokia cut pricing aggressively while losing volumes. The price cuts were "forced" by conditions and probably were designed to slow the drop in demand. Emerging markets, once Nokia's core growth area, showed dramatic value contraction due to price pressure. Nokia's brand value, which normally allows for price premiums regardless of functional value, is clearly evaporating in its last bastions.
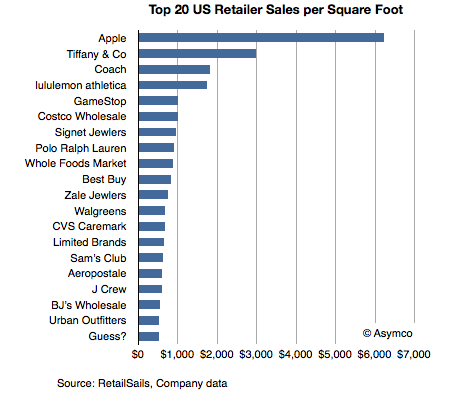
Thanks to RetailSails we have some data on retailers in the US which can be used to calibrate the performance of Apple retail. RetailSails compiled a table of the top 20 chains by sales per square foot (annual basis). The total sample was 160 American retailers (excluding restaurants) that publicly report results.
Sales per unit area is a standard and usually the primary measurement of store success. Here are some benchmark figures:
Annual store sales in the range of $300 per square foot is considered respectable in the US.
The US national average for regional malls is $341.
The average for specialty apparel retailers is $400 per square foot.
The average for jewelers is in the range of $600 per square foot.
The median for the best 20 US retailers is $787/sq. ft.
The data for the top 20 is shown in the following chart:
The data shows Apple leading by a significant margin. It's more than twice as efficient as the second place Tiffany and Co. It's also more than seven times the median of the top 20 and seventeen times better than the average mall retail space.
Note also that this data includes only physical retail and excludes e-commerce, catalog or services revenues. It should only be used to compare physical retail performance.
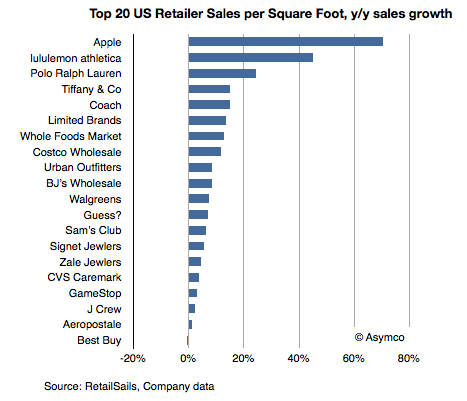
The achievement is also remarkable when measuring growth in overall sales.
Apple leads in absolute performance but also in growth.
Note also the performance of electronics retailers that might be comparable to Apple. Only Best Buy and GameStop are on the list, but their growth is among the poorest, with Best Buy going in the wrong direction (data was current as of August 2011).
We'll be getting an update on Apple retail at the next earnings call in a few days. To read more about Apple retail see:
The first Asymconf was conducted on Friday, April 13th, 2012 in Amsterdam. Here are some statistics from the show:
155 registered participants and over 1000 participation hours
Over 500 tweets generated during the day (#asymconf)
Eight hours of conference executed on schedule
Three iPads used to facilitate: one as a whiteboard, one as a slide presenter and one as an interactive motion chart.
Seven video cameras used to capture over 1 terabyte of video data.
Four cases conducted with majority of time spent on audience participation
Overall, feedback has been very positive. We will now edit the video to make it available for download. We will also analyze all aspects of the event to understand how it can be improved and post our findings.
We plan to hold Asymconf 2.0 in approximately six months somewhere on the West Coast of the US. We are already scouting for locations.
If you have photos or additional comments regarding the event that you'd like to share, please post them below.
Nokia currently estimates that Devices & Services net sales in the first quarter 2012 were EUR 4.2 billion, comprised of Mobile Phones net sales of EUR 2.3 billion (71 million units), Smart Devices net sales of EUR 1.7 billion (12 million units),
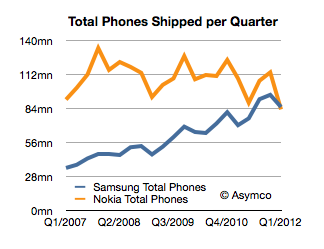
We don't have the total number of Samsung shipments, however estimates exist. They range between 41 and 44 million smartphones and 44 and 47 million feature phones. The low end of that range would imply Samsung shipped 85 million phones.
Nokia's press release indicates that it shipped 83 million.
This would be the first quarter that Samsung beat Nokia in total phone shipments. It had already overtaken Nokia in sales volume and profitability last year but this is the most cited metric of market performance: being the biggest in volume. Here is the tale of the shipments:
How did this happen?
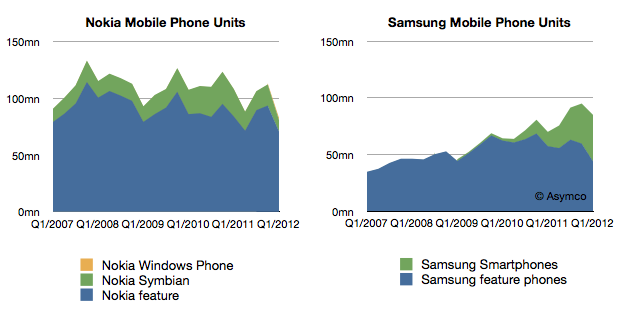
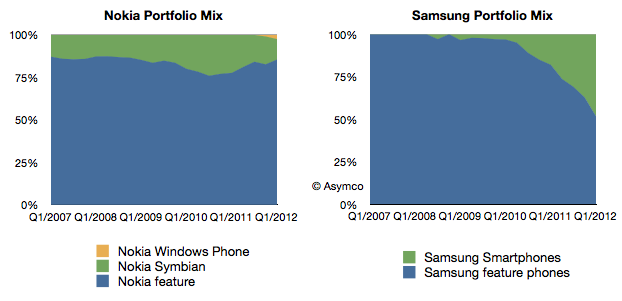
The answer should become visible when we look at at another set of data. If we split the smartphones from feature phones the charts look like this:
Looking at product mix, Samsung growth is shown to be almost entirely due to smartphones while Nokia's stagnant growth seems to be a failure to have any smartphone traction.
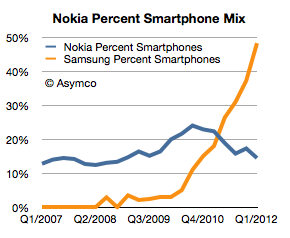
It's even more clear when showing the above mixes of devices as percents of total.
As a percent of total, Nokia has shrunk its smartphone business from a peak of 24% in Q3 2010 to 14% last quarter. In the same time frame Samsung's smartphone share of portfolio has exploded from 10% to nearly 50%.
Note that both companies have seen non-smart device volumes contracting. Samsung's level is approximately the same as it had in late 2007 and Nokia's is lower than at any point in the last six years (perhaps longer).
So the answer to the question of how Samsung beat Nokia is told in the following chart:
Samsung was able to convert its portfolio to smartphones while Nokia failed to do so. This is the sort of transition that can only come about from an explicit strategic intention on the part of management. Market demand can steer you in any number of directions, but a vision of a future should provide the compass for making the big bets.
The bet Nokia made many years ago was that there would be a continuing, substantial business in the "low end". And low end meant feature phones. This strategy was still in evidence last year under the moniker "the next billion" users. The decisions were not driven by whether the products would be hired for different jobs, but that they would hit different price points. In other words, segmentation of customers by their ability to pay for devices rather than categorization of the jobs they hired mobile devices to do.
Perhaps Samsung was no wiser, but they were more pragmatic. Being non-dogmatic meant being flexible. They ran with off-the-shelf technologies and managed a transition to smart devices faster than anyone expected. It may not be a perfect strategy but it beat a bad strategy.
Nielsen has already noted that more than half of US consumers have smartphones. comScore's data seems to point to that threshold being crossed sometime this year.
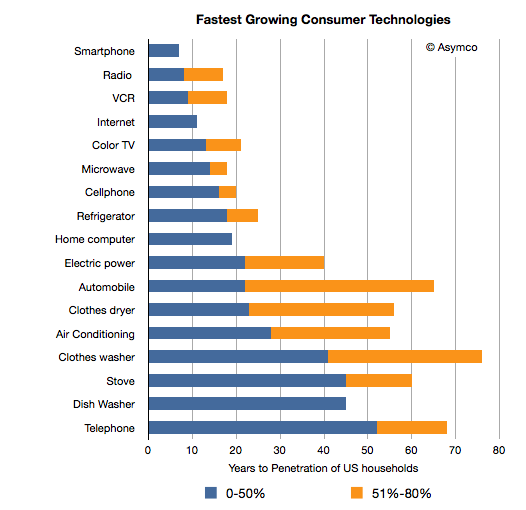
If that point is crossed then it would mark the smartphone as one of the most rapidly adopted consumer technologies of all time. I plotted the time it took for a set of technologies to reach 50% penetration of US households.
I also showed the time it took for some of the technologies to reach 80% penetration.
The obvious question is how long will it take for smartphones to reach saturation in the US. Saturation level would be above 80% for individuals but closer to 100% for households. A conservative estimate would be another seven years. An aggressive estimate would be five years. That implies that between 2017 and 2019 smartphones will be the only mobile phones Americans will use. That would be equivalent to a user population of about 300 million.
Note that some like Internet and home computers have not reached 80% penetration in the US.[1] [2] When or whether smartphones will overtake computer penetration in the US is an open question. I believe that, like cellphones have in other markets, smart devices will overtake computer consumption and thus penetration and even bandwidth consumption.
There are significant technical and marketing challenges for reaching the "second half" of the market, but, as in all the other technologies listed above the incentives are in place to overcome these challenges. What's most remarkable about smartphones is the speed with which obstacles are overcome. For such a complex and inter-dependent technology, the speed of adoption and value creation is unprecedented.
The value network creation rate is also staggering. The App Industry went from inception to billion dollar valuations in a matter of three years. Entirely new business models and experiences are being created almost daily. What used to be a glacial process of innovation diffusion can now be observed in near real-time.
---
Notes:
The question of when smartphones began penetrating the US is somewhat debatable. I contend it was either 2004 or 2005 when the BlackBerry and Treo brands began to be widely available. Although there were smartphones in production as early as 2001 (or even 1998 if we choose to include the GeOS based Nokia Communicator) their availability to US consumers was very limited.
One of the arguments made for the cause of the increase in Apple's share price of late has been that dividends would attract more institutional investors and provide more liquidity to Apple's shares. Can we test this argument?
We're not dealing with speculation. The decision to start paying dividends was made three weeks ago. It makes sense to assume that this new information has been absorbed by the markets and market participants have adjusted their positions. Funds that were previously restricted in their investment in Apple due to its lack of dividend policy, could now go ahead.
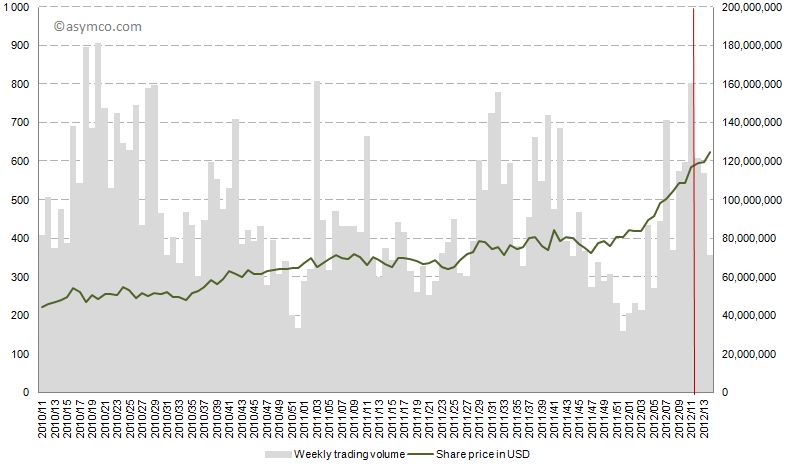
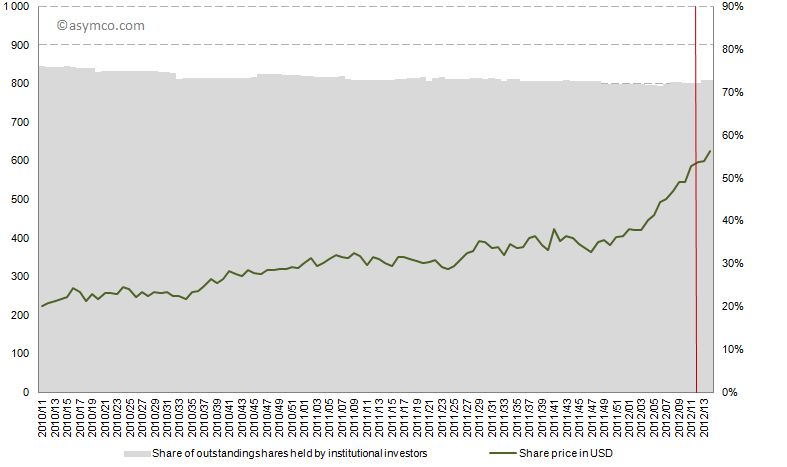
However, as the following chart shows, the share price climbed continuously before and after the dividend declaration of March 19th (shown in red). Trading patterns did not show unusual highs or lows. In fact, after March 19th the trading volume decreased on a weekly basis.
The other indicator is institutional holdings. The share of institutional investors as percentage of all outstanding shares did not increase significantly, and has been in an overall decline since late 2010.
But this lack of visible response to the decision should not be surprising.
Dividends are a tool to adjust capital structure based on optimal investment decisions. Dividends do not add value. The value of a company reflects the perceived net present value of all free, future cash flows. Whether the cash is in or out of the company is immaterial to its value. In either case the cash belongs to shareholders.
What the market is reflecting is fundamentals, not any change in liquidity due to "more buyers" available. For a long time the fundamentals were not accepted as sustainable. The best explanation for the rise in the share price is therefore that the company's future is now becoming clearer and a cloud of doubt is being lifted.
In August 2007, during the HD format wars between HD-DVD and Blu-ray format, Toshiba offered Paramount and Dreamworks $150 million to produce HD versions of their movies exclusively as HD-DVD.[1]
This type of deal is equivalent to an "advance" offered to a book author. The DVD manufacturer pays studios up-front cash for the right to make its DVDs. From an accounting point of view this is treated as an advance that the manufacturer recovers by selling the DVDs back to the studio's video division in the same way a publisher earns back the advance it gives an author.
In this case, the payment was so large and the sales of HD-DVDs so small that Toshiba was unlikely to earn back the entire advance. The way the deal made any sense for Toshiba was that it was exclusive: the studios could not continue to release their movies in Blu-ray. The deal was done explicitly to hobble a competitor and create "critical mass" of content for its own format.
But then in March 2008, Toshiba threw in the towel and abandoned the HD-DVD format. The way the deal worked, the studios got to keep almost all of the $150 million. They then re-released all their movies in the Blu-ray format. The only "cost" to the $150 million windfall was that there was a nine month delay in the eventual release to Blu-ray--a small price to pay for an emergent format without a large install base.[2]
Platform owners go to great lengths to ensure "content" for their platform. They will, essentially, finance an ecosystem when there are barriers to entry or when competing ecosystems are far more lucrative.
This scenario for movies is being played again with Netflix, Hulu and other distributors who need to fill their pipelines. Netflix's content acquisition costs are exploding and putting the whole company's future in doubt.
But this scenario is also being played out with app developers. Most recently, news broke that developers are receiving payments from Microsoft for Windows Phone ports of popular apps. In mobile platforms, apps are the new content and developers are the new studios. It's also a practice that is not without precedent[3].
This is as it should be. The value of the platform lies mainly in what is built on top of it just like a foundation is not much use without a house on it. However, the practice of "priming the pump" with cash payments for porting is not ideal. Like spiffs, those who receive payments may become used to it and withhold development if there is no payment. Also, those who did not get payment offers may feel shunned and retaliate in kind. Those who receive payment may become cynical about it and may not put in the extra effort (or, more probably, outsource) to make the work spectacular.
Or, like Paramount, they may just take the money and run if/when the platform fails.
Paramount made $250 million more from three "replication output" deals: $50 million from Toshiba for agreeing to release Titanic on DVD in time for Christmas sales, $150 million from Panasonic for agreeing to allow them to take over video replication from Thompson, and $50 million from the law firm Ziffrin, Brittenham and Circuit City stores for agreeing to support the DIVX format. Paramount got to keep the money even though DIVX never launched.
Although it's never been reported that Apple pays developers for building iOS apps, some developers do benefit from promotional placement and visibility during launch events and from early access to devices or SDKs under development.
Canaccord Genuity analyst Mike Walkley writes in a note to clients today. “In fact, we believe iPhones are outselling all other smartphones combined at Sprint and AT&T and selling at roughly equal volume to all Android smartphones at Verizon.”
That's useful data. Mainly because we can use it in combination with comScore data that tracks a different market measure. comScore's MobiLens service tracks US mobile installed base. By measuring the difference between their stats one month to the next, one can measure the gain in a particular platform.
Comparing that gain with the sell-through rate in the same period can yield a figure for the number of units sold as upgrades vs. those sold to new users.
The latest comScore data (period ending February) shows that Android added 2.87 million users to its base while iPhone added 1.52 million. If we assume that Android sold a minimal number of replacements (due to the limited time in use of bulk of units) and round up to 3 million for February, and if we assume that Apple sells as many iPhones as Android (which is what Walkley suggests) then we can conclude that in the US roughly half the iPhones are bought as replacements for existing iPhones.
Extrapolating this to global markets may be risky but already we can begin to form a picture of how the iPhone franchise is becoming an annuity-based business.
Apple likes to point out that "half of Mac buyers are first time buyers." In the case of the iPhone perhaps they could also say "half of iPhone buyers are repeat customers." At this stage in the platform, that's a powerful statement. If the repeat customer rate is high then it suggests strong loyalty but it also may suggest poor competitive position vs. non-consumption or alternate platforms. If the repeat customer rate is very low it may suggest competition vs. non-consumption but it may also suggest low loyalty. It all depends on the overall growth in the market and size of installed base.
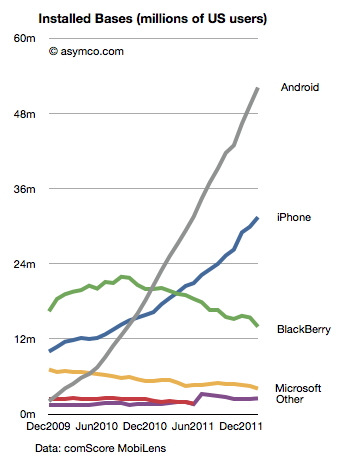
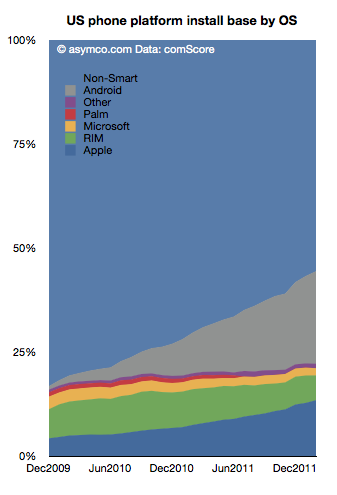
The following chart shows the overall market growth and the position of the various platforms within that growth.
Note the time scale is slightly more than two years. This suggests that the vast bulk of Android units in use (grey area) consists of first use units. New purchases are going to first time buyers. In contrast, the shrinking RIM total implies extremely low sales as the age of the base is far older than the time scale. iPhone base is both growing and being upgraded.
As we reach 50% penetration of smartphones, platform churn will become a significant component of market performance. The loyalty and "stickiness" of Android will begin to be tested. Current surveys show reasonably good satisfaction ratings for Android phones (around 60%) while iPhone's are even higher. But let's keep in mind that RIM's satisfaction and the loyalty of their customers was exceptionally high a few years ago. The rate of evaporation of goodwill toward the brand is breathtaking.
The longer term test of mobile platform performance will be in the recurring purchase rates. Loyalty must be earned and preserved. I.e. "You come for the product, you stay for the ecosystem."
So far, the iPhone seems to be getting a passing grade while Android has yet to face the test.