Asymco

Asymmetric Intelligence

Research

  1. The Bank of Apple: Using capital to ensure additional capacity and supply

    Research · 73 comments

    When I wrote suggesting that the "best use of cash" was not acquisition but integration of manufacturing under the Apple control umbrella, the rumor that set off that discussion was that Apple was financing new facilities for its suppliers.

    Those rumors were quashed, but we now know there is something to them.

    During the September and December quarters, we executed long-term supply agreements with three vendors through which we expect to spend a total of approximately $3.9 billion in inventory component prepayments and capital expenditures over a two-year period. We made approximately $650 million in payments under these agreements in the December quarter, and anticipate making $1.05 billion in payments in the March quarter.

    Apple Management Discusses F1Q11 Results - Earnings Call Transcript - Seeking Alpha [my emphasis]

    So Peter Oppenheimer confirmed that Apple is using its cash as a loan facility for its manufacturing partners. It's not for the first time either. Apple used the same leverage to ensure the supply of flash memory for the iPod line in 2005.

    Philip Elmer-DeWitt reminds us Tim Cook confirmed:

    The deal, he said, is similar to the one Apple cut five years ago:

    "As you probably remember," he began, "we signed a deal with several flash [memory chip] suppliers back at the end of 2005 that totaled over $1 billion because we anticipated that flash would become increasingly important across our entire product line and increasingly important to the industry. And so we wanted to secure supply for the company.

    Partly as a result was a dominant position in the music player market that is still paying off today.

    The use of capital to pre-pay for production is not therefore new. What we saw last quarter however is that it's using capital to ensure there is additional capacity.

    In other words, Apple Inc. pre-buys additional capacity by using Bank of Apple capital as a loan facility to bring more capacity online. How to judge this use of capital depends on your perspective:

    • From a fiscal perspective, Apple is acting like a trade lender (with moderate to low returns on capital.)
    • From the operational perspective Apple is acting as a limited manufacturing partner, just short of an equity holder.
    • From a strategic perspective, the Bank of Apple lends only to suppliers that commit to producing for Apple Inc. Thus locking out competitors.

    This strategy is not without risk. Those loans are forward contracts on production. The risk is that production is unneeded and hence the loans won't be "paid back". But Apple knows demand and supply in this market better than anyone else, so it has an unfair advantage over the market. So the rewards are probably out of proportion to the risk.

    By buying an option on production, not production itself Apple has a clever way to "own factories" without actually owning them: gain control over marginal increase in production without the impact from CapEX or depreciation.

    The return on that option will never be seen on the OI&E line in the income statement and the cash once recycled back into the balance sheet will seem to be sitting unrewarded. But the return on that capital will show up in the bottom line by way of margin and top line expansion for years to come.

    The committed capital is still tiny, but a proper analysis of Apple's cash management would be to look at the return on cash as more than the return on treasury bills.
  2. Estimates for Apple’s second quarter earnings (ending March)

    Research · 39 comments

    Apple's CFO guidance statement:

    We expect revenue to be about $22 billion, compared to $13.5 billion in the March quarter last year. We expect gross margins to be about 38.5%, reflecting approximately $50 million related to stock-based compensation expense. We expect OpEx to be about $2.35 billion, including about $250 million related to stock-based compensation. We expect OI&E to be about $50 million, and we expect the tax rate to be about 25.5%. We are targeting EPS of about $4.90.

    via Apple Management Discusses F1Q11 Results - Earnings Call Transcript - Seeking Alpha.

    This is a particularly aggressive revenue growth forecast of 63% (note again that Apple's P/E has dropped to 18 and 14 ex cash and 10 on a forward basis) . Since Apple always guides very conservatively, the likely figures for the top and bottom lines are likely to be higher.

    How much higher? Here are my estimates (growth in parentheses is year over year).

    • iPhone units: 18.4 million (110%)
    • Macs: 3.62 million (23%)
    • iPads: 6 million
    • iPods: 10.1 million (-7%)
    • Music (incl. app) rev. growth: 25%
    • Peripherals rev. growth: 23%
    • Software rev. growth: 23%
    • Total sales: $24.5 billion (82%)
    • GM: 38.8%
    • EPS: $5.89 (77%)

    Looking a bit further ahead, earnings suggest the company is now trading at a forward P/E of about 9.5.

  3. The end of exclusivity doesn't change the price operators pay for the iPhone

    Research · 55 comments

    AT&T does not pay a higher price for iPhone exclusivity | asymco.

    At the risk of repetition, there are three instances in conference calls that Apple management has stated that the iPhone has a fixed price for all operators and resellers.

    The first was in October 20, 2009:

    “So when you go from exclusive to multiple, you don’t change the charge to the carrier?”

    Cook answered: “Correct.”

    The second was a year later, October 18, 2010:

    Chris Whitmore – Deutsche Bank:  And what is your experience then when you’ve gone non-exclusive from a subsidy and margin standpoint on the phone, have you had to give anything up in the past?

    Tim Cook: We don’t give specific information out on the margins. But I think you can look at our ASPs and see that they’ve generally stayed above $600, and that’s despite opening up several markets from an exclusive market to a non-exclusive market.

    And the third was a few days ago on January 8, 2011:

    Toni Sacconaghi - Bernstein Research:  You've said on previous earnings calls that the move to iPhone non-exclusivity in regions of the world has had no impact on your ASPs. Can you comment on whether that is it still the case today and whether we should expect any impact in the migration away from U.S. exclusivity?

    Timothy Cook: I don't envision the overall iPhone ASP decreasing from the December quarter that we just completed to the March quarter that we're currently in.

    But, as always, we can confirm and validate using the data on pricing we have available.

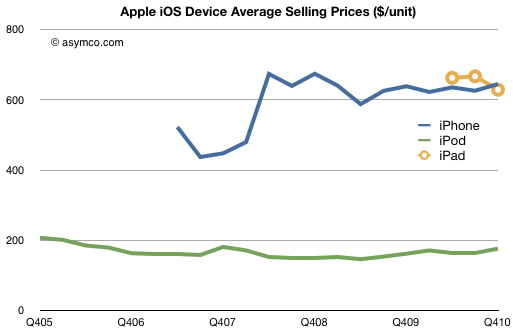
    In this case in the financial reports (take iPhone revenue and divide by units sold):

    You can see that after the first iPhone "2G" which had a peculiar pricing that included revenue sharing with the operator and which showed up differently in the accounting, the iPhone has had a steady price slightly above $600 for over two years[1].

    This is despite having more than 60% sales outside the US and being non-exclusive multi-operator in many countries. Despite being available locked, unlocked and everything in-between.

    We can even confirm what one particular operator paid exactly. In October 2008 AT&T reported that they had paid $900 million for 2.4 million iPhones. That's $375 per phone. Assuming a mix of $199 and $299 3G phones that gives something around $600--below the global ASP for that quarter of about $676. Here exclusivity would imply a discount to average price! The reason for the discount is most likely volume as AT&T was by far the largest buyer of iPhones globally.

    Still unconvinced? Try shopping for an unlocked iPhone at any of various retail locations where it's available unlocked. Accounting for VAT or other taxation, the price is always the same and is a slight mark-up to the operator ASP due to retail margins.

    Judging from comments on this site, the myth that loss of exclusivity in the US will change profit margins for Apple still persists no matter how many times I repeat this story.

    -----

    Notes:

    1. The steadiness of the price should give another huge clue as to the effect of competition on the product.
  4. How exclusivity distorted the US smartphone market

    Research · 69 comments

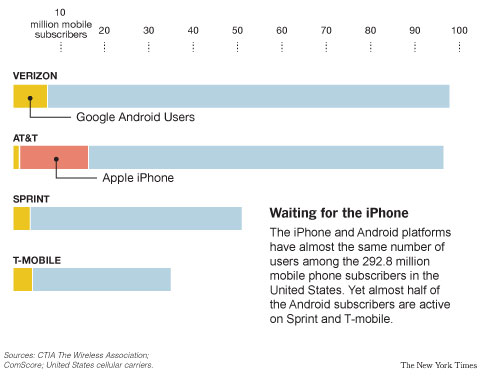
    Here's a wonderful chart from The New York Times:

    Will Apple Put the iPhone on Other Carriers? - NYTimes.com.

    Although the population of Android users is near in size to the population of iPhone users, the concentration in one carrier shows how distribution agreements hamstring platform choice.

    The chart also shows how the iPhone had a huge effect on smartphone adoption at AT&T and how it sucked the oxygen out of the segment for competitors.

    It is possible that we'll see more Android at AT&T and a lot more iPhone everywhere else, but on balance, the chart shows how exclusivity distorted the market.

    It sounded like Tim Cook was really relieved to announce in the earnings conference call that:

    We are not under a contractual exclusivity now in any country in the world. The last one was the United States. We have moved away from those.

    ...

    What I've said before and we have seen this in every case, literally, that we've done, is where we've moved from an exclusive carrier arrangement to a dual- or multi-carrier arrangement, our growth has changed significantly and our market share has increased.

  5. 65% of Apple's sales came from iOS powered devices

    Research · 46 comments

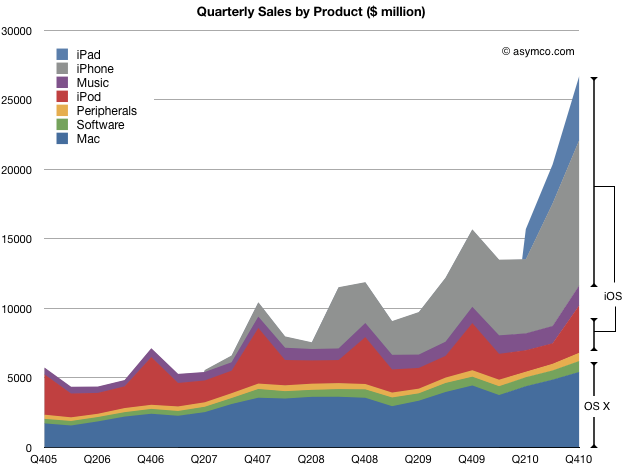
    The iPhone and iPad generated $15 billion of revenue last quarter. In addition, iPod touch generated about $2.3 billion, implying that iOS based devices were responsible for sales of $17.3 billion.

    To put that in perspective I drew this chart which shows not only the sales by products but a rough representation of share of the two OS variants Apple uses to power its products.

    iOS powered products (which did not exist three and a half years ago) generated 65% of all sales in the last quarter. OS X powered products generated 20% of sales. That's a noteworthy combined total of 85%.

    But software is even more important for Apple.

    The sale of OSX software (both the operating system and applications for it) accounted for another $786 million or 3% of total. In addition, I've put forward some evidence to suggest that the proportion of sales due to Apps in the Music store is nearly half, or another $600 million (a bit more than 2%).

    Therefore only 10% of Apple's sales were for products not directly powered by its vengeful operating system. That speaks volumes not only for the importance of software to Apple but for the cohesion of an extensible, flexible architecture that allows it to inhabit a portfolio spanning from a music player and an enterprise server.

    I recently answered a question on Quora on whether Apple is a Software, Hardware or Media company by saying it's all three.

    With 90% of sales dependent on a unique, proprietary operating system[1], perhaps the answer should have been different.

    ---

    1. I know that OS X has a large amount of open source. Proprietary, like Open is a partial definition.
  6. Why Eric Schmidt had to go: Google's innovation dilemma

    Research · 48 comments

    Charles Arthur provides a convincing back-story to the Google exec re-shuffle.

    Google shuffle: why Eric Schmidt had to be pushed from the top | Technology | guardian.co.uk.

    There is evidence of execution failure and indecision or muddled messages to stakeholders. Shared leadership arrangements never end well.

    But in this forum I've been critical of their strategy. Though I'll be the first to admit that such criticism is not founded on data but on intuition, strategy is always made in a vacuum of data. It is just an unfortunate fact of life that we don't have data about the future.

    But what data we do have is about the past and it shows the contrast between Apple and Google.

    As a sample, let's look at the performance in the last quarter:

    [nohang]

    GrowthGoogleApple
    Revenue26%70%
    Earnings29%75%
    P/E24.1318.57

    [/nohang]
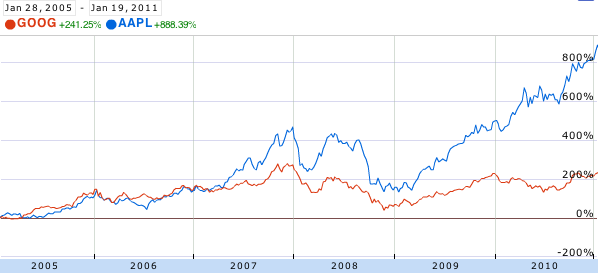
    Apple grew about 2.5x faster. The companies are in very different businesses, but the money they make is the same color. The investors have been paying attention:

    Source: Google Finance.

    In 2005 and 2006, Apple and Google were neck-and-neck in terms of returns to shareholders. However, with the iPhone's arrival in 2007 the stocks diverged. Google gained 38% since January 2007 while Apple gained 300%.

    However, going forward, the market is kinder to Google than to Apple, punishing Apple's 75% growth with a P/E of 18 (ex-cash 15) and rewarding Google's 29% growth with a P/E of 24 (22.5 ex-cash) . Although Google's P/E is proportionate relative to its growth, Apple's P/E implies deep pessimism.

    But does Google's performance suggest management failure? Certainly not. It's been a great performance. Google is arguably at the top of its game. Market share of search has never been better.

    Cracks in strategy are hard to spot. One hint is that most of Google's R&D efforts are defensive. Building browsers and mobile operating systems are methods to ensure they have distribution of search to as many screens as possible. These are expensive means to ensure channels are available for distribution. Expensive not only in terms of engineering costs but also in terms of relationships and opportunity costs.

    But even a defensive posture is not sufficient for management change.  What I think is the most serious failure is that for the past five years Google has not addressed the possibility of search itself becoming commoditized. Social media and app economies are asymmetric to search. They make money in different ways and appear to be less efficient or effective means to reach users, but they are growing. Facebook has overtaken Google in terms of page views and apps are a new interaction model for cloud-based content that does away with the indexing model Google champions.

    The real condemnation of the leadership at Google is that there has been a failure to create entirely new disruptions. As the stock chart above confirms, Android and Chrome are, if successful, sustaining technologies for Google. That's not going to be enough.

  7. Reminder: @asymco on Twitter

    Research · 2 comments

    There are many thoughts which are not substantial enough to be posted as blog entries. There are also questions that need to be asked or answered which are not yet 'baked' enough to be cast into a permanently linked posting.

    For these reasons and for the simple fact that it's fun, I am using Twitter more frequently. Since I know not everyone has or wants an account, my twitter feed is now shown in the second (right-most) sidebar. It's limited to the last eight tweets.

    For those who would like to keep the discussion going in this new medium, my Twitter app (from the Mac apps store) is always running.

  8. Apple's Growth Scorecard: 63% average earnings growth over 16 quarters

    Research · 30 comments

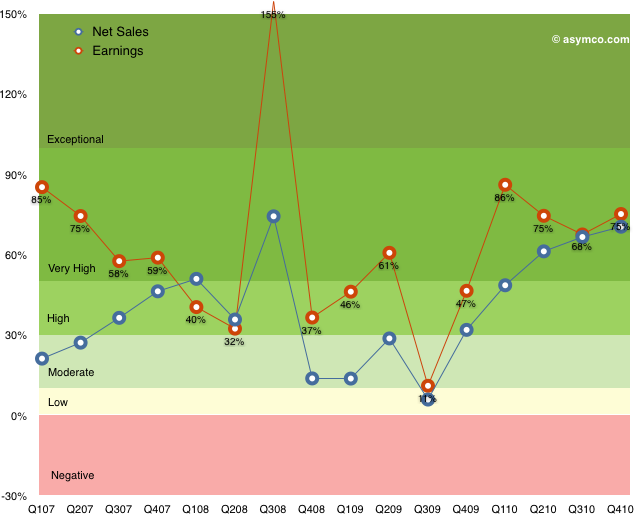
    In the last quarter Apple's top line grew by 70% and the bottom line by 75%.

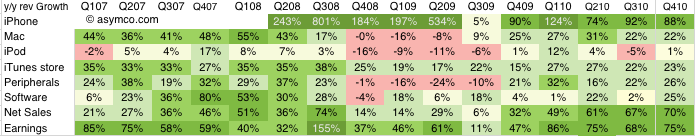
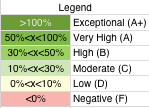
    For a historical perspective, the following table shows year-on-year growth for products[1] and sales/earnings color coded with an arbitrary scoring range.

    The major changes from the last quarter were the acceleration in software sales and the return to growth in iPod sales. iPod benefited from the continuing shift to iOS as the mix is now 50% touch in the portfolio.

    Software growth reached a level not seen since 2008. It's not clear to me yet  which products drove this increase.

    Overall the growth is both wide and deep. I'm most impressed with the iPod as it was a surprise to hear such a high mix of touch.

    The following chart shows the top and bottom lines plotted over time with color bands corresponding to the score system in the table above.

    Note how earnings growth has been in the high or very high or exceptional range for all but one quarter over in the last four years[2].

    Apple transcends the mythical "rule of large numbers"[3]. It's not only a mega-cap, but the second largest company in the world by market cap. Not only has this enormously valuable asset just grown in intrinsic value creation by 75% but it has maintained a growth of 70% for the last five quarters.

    If that weren't enough, the average earnings growth has been 63% for the last sixteen quarters.

    ------------

    Notes:

    1. The iPad is not included since we don't have more than one year of sales and this is year-on-year not sequential growth.
    2. The low growth for Q3 '09 was due to the corresponding spike the year before when the iPhone 3G was launched. That launch quarter in 2008 was a seminal turning point in the history of the phone industry when it became clear that the iPhone was not a passing fad. Steve Jobs famously participated in the conference call calling attention to the data which was obfuscated by subscription accounting. Alas, the news was lost in a sea of credit crunch panic.
    3. I have an aversion to this rule as "large" is never defined except in relative terms. For example a $1 trillion market cap may be large because it's unprecedented, but it may be a trifle if the company is priced at book value.
  9. A new era in financial analysis is dawning

    Research · 43 comments

    The story of amateur out-performance has been getting more attention lately and that's a good thing. Success emboldens more amateurs to try their hand at financial analysis. Transparency of methods and data demystifies a practice that is not as complex, and a skill that is not as hard to obtain, as it's often assumed.

    While, quarter after quarter, the gap between the two cohorts is calibrated, what we haven't heard much of is a defense from the professionals.

    That's a bit strange given the negative impact some of the attention must be having on their reputations. This is why I was glad to see that Adam Satariano's well-written piece finally got some reactions from the professionals.

    Professional analysts tend to be more conservative. That’s partly because they’re closely monitored and regulated, said Shaw Wu, an Apple analyst at Kaufman Brothers LP in San Francisco. He and his colleagues must pass a series of tests administered by the Financial Industry Regulatory Authority before becoming certified.

    “I have to be careful of everything that I do because it’s scrutinized,” said Wu, who has recommended buying Apple shares since joining Kaufman in 2008.

    Alexander Peterc, an analyst for Exane-BNP, said professionals are “very wary” of putting out aggressive estimates because of institutional memory of past technology booms and potential backlash from clients if they’re wrong.

    “They got it right on the way up, but we’ll see what happens after that,” Peterc said. “Often bloggers and amateur investors are very good in bull markets, but get lost in bear markets. If some of these guys call the moment at which Apple’s fortunes begin to turn I will be impressed.”

    via Apple's `Underdog' Analysts Outperform Wall Street From Helsinki, Caracas - Bloomberg.

    However, neither answer satisfies.

    Wu cites regulation and scrutiny but that does not prevent one from being intellectually honest. What matters is not avoidance of conservatism or exuberance. What matters is rigor; being impartial to everything but the data. One must keep one's convictions in proportion to one's valid evidence not to regulatory oversight (which is there to prevent abuse, not balance).

    Peterc cites pressure from clients (hence the obligations of employment). That implies that professionals are under pressure to say something other than what they believe, which is a sinister form of self-censorship. Not only is that less valuable as an opinion, but it's likely to be less accurate as well.

    But more fundamentally, the issue for the pros is that the institution of analysis risks becoming de-professionalized. In the same way many jobs that took specialized skills became commoditized by the use of new tools or access to information, the era of DIY financial analysis is dawning.

    The difference between professionalism and amateurism isn't whether one is well paid or not or whether one is anointed with credentials. It's whether one is consistently out-performing randomness (note emphasis on the consistency).

    Amateurs can get lucky and pros can get unlucky. But in the end it's about hitting that home run over and over again.

    So the question remains why, in bull markets or bear markets, the professionals are consistently wrong on Apple. The evidence has always been anecdotal and data was fragmented, but now the data is being diligently compiled and it will serve as testament to a shift that I think will be permanent.

    Stay tuned.

  10. Unforeseeable growth: Analyst failure on iPad as indicator of disruptive change

    Research · 156 comments

    Professional analysts' first year iPad unit forecasts (sourced from TMO Finance Board)

    • Brian Marshall, Broadpoint AmTech   7.0
    • David Bailey, Goldman Sachs           6.2
    • Kathryn Huberty, Morgan Stanley     6.0
    • Shaw Wu, Kauffman Bros.              5.0
    • Mike Abramsky, RBC Capital Markets   5.0
    • Gene Munster, Piper Jaffray           3.5
    • Ben Reitzes, Barclays Capital           2.9
    • Keith Bachman, BMO Capital         2.5
    • Jeff Fidacaro, Susquehanna           2.1
    • Chris Whitmore, Deutsche Bank       2.0
    • Scott Craig, Merrill Lynch               1.2
    • Peter Misek, Canaccord Adams       1.2
    • Doug Reid, Thomas Weisel             1.1
    • Yair Reiner, Oppenheimer             1.1

    Here are the predictions from Tech Bloggers:

    • Clayton Morris: 9
    • John Gruber: 8
    • Horace Dediu: 6
    • Natali Del Conte: 5
    • Ross Rubin: 5
    • Mike Rose: 4.5-5
    • Jason Snell: 3
    • Andy Ihnatko: 3

    Apple sold 14.8 million iPads in 2010.

    I sometimes use the phrase "unforeseeable growth" to describe the kind of growth that not even the most knowledgeable observers of a market can predict. It's usually an indicator that fundamentally transformational change is taking place.

    It's not a sufficient condition, but it's clear that "nobody saw it coming" is a common refrain when disruptions are seen in the rear-view mirror.

    If analysts, to a man, fail, you can be sure that competitors are no wiser. This collective shrug amounts to the greatest competitive advantage any entrant could ever hope to obtain.

  11. Having added $20 billion last year, Apple's cash growth suggests total could top $100 billion next year

    Research · 42 comments

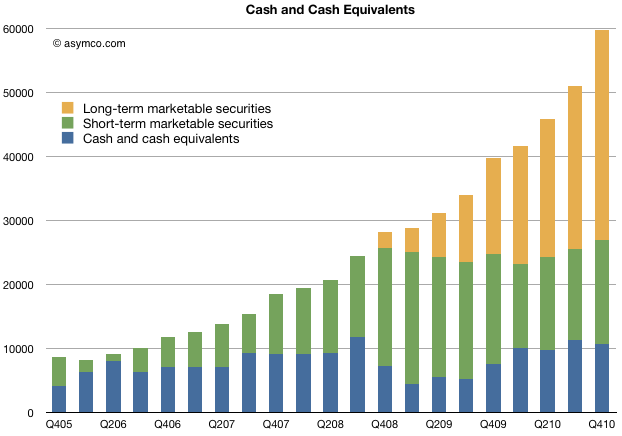
    The following chart shows the value of Apple's cash and cash equivalents for end of 2010:

    This represents $64/share (current price per share is about $340, making the enterprise value about $276).

    The company was trading at $64 per share in July 2006.

    Here is a list of iconic companies whose market cap is less than Apple's cash.

    • Visa Inc. $59.63b
    • American Express Company $55.8b
    • The Boeing Company $53.16b
    • Morgan Stanley $43.5b
    • The Dow Chemical Company $41.8b
    • NIKE, Inc. 40.22b
    • Eli Lilly & Co. $40.12b
    • Texas Instruments Inc. $40.92b
    • Nokia $39.92b
    • News Corporation 37.72b

    I would also make note of the trajectory of the cash. Growth is accelerating. The last quarter Apple added $8.7 billion in cash. A year earlier it added 5.8 billion and the year before that $3.6 billion.

    The amount of cash added is more than the amount of cash the company had five years ago.

    In 2010 the company added $20 billion to its cash reserves. In 2009 the company added about half that amount.

    If the trend continues, Apple could see $100 billion in cash by this time next year. That's about what HP is worth now.