Asymco

Asymmetric Intelligence

Research

  1. Google Nexus S

    Research · 52 comments

    Google Nexus S is real, gets leaked by Best Buy [U] | Electronista.

    Can you imagine Microsoft launching a Microsoft branded phone to compete with its Windows Phone licensees? When Microsoft launched the Zune, their licensing model (PlaysForSure) was quietly folded up.

    A Google phone makes little sense, but then again Google does not seem to care much about its ecosystem or relationships with Android device vendors. They even claim that they have no idea how many phones are being built using Android and, except for activations, have no way of measuring the number sold.

    From their point of view, if Motorola feels it's unfair to have to compete with a Google branded Samsung (or HTC) designed phone then too bad. There's lots of white label vendors lined up to make these with or without anyone's blessing.

    In fact, the biggest opportunity for Android growth seems to be the large unlicensed (and illegal) grey market which seems to be rapidly expanding.

  2. 20% vs 33% for "Others": Why are Gartner and IDC so far apart on mobile phone market estimates

    Research · 39 comments

    The latest mobile phone estimates from Gartner made a startling claim that "Others" vendors increased share from 16% a year ago to 33%. Doubling share in a year is possible if you're at 1% share but to double from a base of 16% is sounding improbable. They allege that the "Others" now sell more phones than Nokia. And Others don't even include ZTE and Huawei, the prototypical low end challengers.

    They emphasize this point in their discussion and state that the incumbent vendors are being pressured by these low end entrants. They go on to explain that the same set of vendors will probably use Android to enter the smartphone space.

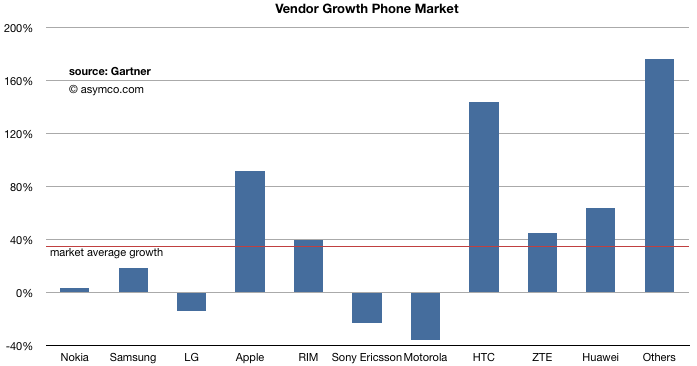
    To illustrate, the growth of individual companies is shown here (all phones).

    Also puzzling is that ZTE and Huawei did not share in this boom. They barely beat market growth and were growing at half of "Others". Until recently ZTE and Huawei were themselves Others, so the new vendors are truly unbranded "white box" vendors.

    To put it in perspective, their year-on-year growth is astronomical: 176%, selling 87 million more phones this third quarter than last year's. This is equivalent to saying that a new company was born in the last year and has already become the second largest in the world. The growth in volumes is higher than the total units Samsung sold!

    Mind the gap

    Extraordinary claims require extraordinary evidence. Can we check what other analysts estimated and do some form of validation of the claims?

    Yes we can.

    IDC reports the same data and they only reported 340.5 million phones sold (vs. Gartner's 417 million). Excluding ZTE and Huawei the total share for "Others" in IDC would be about 20%.

    20% share vs. 33% share is a big gap.

    IDC and Gartner both agree on smartphones, so the difference is even more glaring when you consider the "non-smart" comparisons:

    Non-smart phones:

    Total Market: millions of units sold____3Q2009______3Q2010
    Gartner268337
    IDC244260

    For added emphasis, I added a comparison of last year's quarter. Last year the Gartner total estimate was about 10% higher than IDC. This year they are 30% higher.

    How could the difference in the total phones sold be so big: 77 million phones?

    If Gartner is right, how could IDC miss 77 million phones. If IDC is right how did Gartner conjure up 77 million phones in one quarter? That number is nearly as big as all the smartphones sold (81 million). This is not within any margin of error for whatever sampling method they use.

    Perhaps they need to clarify this because until they do, neither is credible.

    --

    Note: My own models are built from individual company public reports. The only data I depend on from IDC and/or Gartner is this total market size which allows me to back out what the "Others" are doing. If the total market estimates disagree so much, I'll be forced to throw out the "Others" all together.

  3. Visualizing smartphone platform growth

    Research · 55 comments

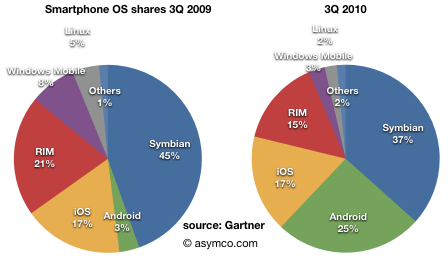
    None of this should come as major surprises, but Gartner's data allows for a bit more granular detail in the overall view of the market. Here are new points derived from Gartner's sell-through data:

    • The smartphone market is growing at nearly 100% (96%).
    • The overall market is growing at 35%.
    • The non-smartphone market is growing at 25%.
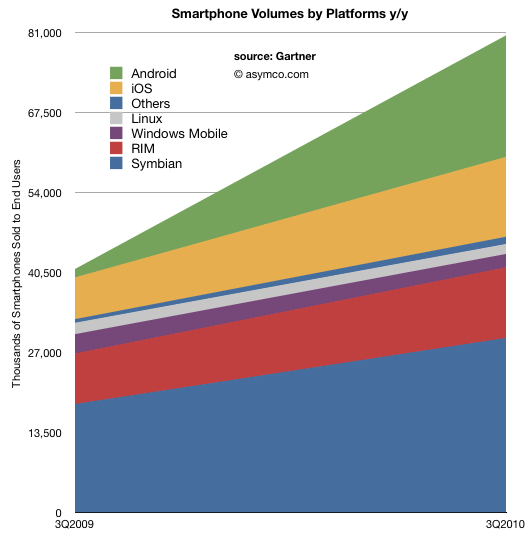
    • Android grew at 1,340% y/y. iOS grew at 92%, Symbian at 61% and RIM at 40%.
    • Platform market shares (below) shows a more even distribution of platform volumes between four main platforms:
    • Non-branded mobile phones grew to 33% of the market, with 141% unit growth. This is an alarming figure for the low-end of the market. The unbranded market excludes ZTE and Hauwei which grew below the overall market growth (9.8%, 27% respectively). The implications were most dire for Motorola (-36% units growth), Sony Ericsson (-23%) and LG (-14%). Nokia grew but, at 3.5%, well below market growth.
    • In 3Q 2009 41 million smartphones were sold. In 3Q 2010 80.5 million were sold. If we were to split the growth among platforms, nearly half the growth was Android. 27% of the additions were Symbian and 16% were iOS. Only 8.3% of the growth was RIM devices.
    • Windows Mobile and Linux were the only smartphone platforms to shrink volumes. However, even though the platform is deprecated, 2.2 million Windows Mobile devices were still sold last quarter -- more than Android sold a year earlier.
  4. The largest Android vendors

    Research · 8 comments

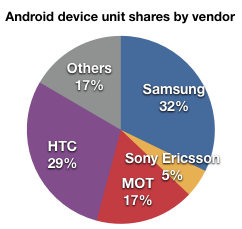
    Gartner released sell-through data for the handset market. In the release appears an estimate of total Android 3Q Smartphone sales (20.5 million). Combining this with what some of the vendors have reported in terms of units sold, we can estimate the share of Android by vendors.

    Note that this is a rough estimate. We don't have data on Sony Ericsson's smartphone units sold and we don't know the mix of HTC's Windows Mobile vs. Android.  I'm also assuming LG as part of Others. The data from Gartner is claimed to be sell-through whereas vendors report sell-in so there is more roughness about each vendor.

    Regardless of these potential sources of error, it's a very safe bet that Samsung and HTC are the largest Android vendors by a fairly large margin.

    It's perhaps noteworthy that both are also committed Windows Phone vendors. According to pdadb.net here is the count of Windows Phone SKUs by vendor:

    • HTC 12
    • LG 5
    • Samsung 2
    • Dell 2
    • Toshiba 1

    Motorola is keeping its Windows Phone options open, leaving "Others" as the only likely exclusive Android vendors.

  5. Were Nokia and Symbian always inter-dependent?

    Research · 8 comments

    Several readers pointed out that in my discussion on the market share of modular vs. inter-dependent market shares for smartphones, Nokia was incorrectly classified as having an inter-dependent software architecture since the Symbian platform is/was a modular component.

    The problem is that the relationship between Symbian and Nokia is not that of independent modules. Nominally, the two are independent and mutually exclusive, but, in practice, Symbian has always been so heavily dependent and influenced by Nokia that it's never been possible to declare its governance fully independent.

    I won't describe the full history since there are many other sources (good example here.) But I will point out that since Nokia licensed Symbian exclusively and Symbian obtained the vast bulk of license fees from Nokia, the relationship was one similar to a bilateral monopoly.

    Nokia's bargaining power over Symbian was always high enough to affect its operations. "Ownership" does not only infer a formal control over equity, and many would agree that Nokia "owned" Symbian even when it held less than 50% of the equity. The relationship was so tight, that even though there were other members of the consortium with board seats, the licensing by Nokia's competitors was always very limited. The only significant non-Nokia revenue for Symbian came from Japan where Nokia did not have a presence.

    After Symbian was effectively acquired by Nokia, the ownership became both de jure and de facto. The open sourcing of the Symbian code made it no less a Nokia operation than the open sourcing of Android makes it no less a Google operation.

    So for all intents and purposes, the relationship between Symbian and Nokia makes Nokia's smartphone hardware inter-dependent on Symbian's software.

    Now, given that the way the products are built in practice may be far from integrated, it would seem that Nokia's management captured the worst of both worlds: Modular implementation of an inter-dependent business. Nokia captured all the downside of modularity (poor integration and polish) without any of the benefits (e.g. flexible supply chain or lower R&D.)

  6. Android remains the only mobile OS still patterned after Microsoft's 2002 vision of the mobile value chain

    Research · 52 comments

    Belfiore wasn’t shy about criticizing Google’s Android OS. Even though Google currently dominates the mobile OS market, its strategy of licensing the Android OS to manufacturers is similar to Microsoft’s previous approach with Windows Mobile: It’s open-ended, and there are few restrictions on how manufacturers can use or modify the OS.

    As a result, Android is suffering from some of the same issues as Windows Mobile did: Android works better on some phones than others, manufacturers are shipping different versions of the OS on different phones, some Android phones are shipping with bloatware made by carriers, and some app developers complain that it’s difficult to make software because of the hardware and OS fragmentation.

    via How Microsoft Hit CTRL+ALT+DEL on Windows Phone | Gadget Lab | Wired.com.

    Android was initially an attempt to commoditize Windows Mobile with a symmetric but "free" alternative. The idea was to conform to OEMs and operator business models. This was directly copied from Microsoft's early 2000's playbook for entry into mobile.

    Trouble is that Microsoft realized their purely modular, operator and OEM centric approach was failing to be competitive on the user experience and decided to move into a more integrated approach, closer to Apple's integrated model.

    But while Microsoft dropped their vision, Android was still patterned after their approach.

  7. HTC to re-bone Android?

    Research · 10 comments

    Peter Chou, chief executive of HTC, had previously said he saw “little value” in HTC running its own application store. But he has also said that it was no longer enough for HTC to simply customise the standard Android user interface with its own “skin”: “It is not enough to be skin-deep. We need to go bone-deep.”

    via FT.com / Technology - HTC to target online app store.

    HTC was the world's biggest Windows Mobile vendor, at one time claiming to have sold over 80% of all WinMo phones ever made.

    I always considered them to be the natural leaders in the Android licensing cohort. First, because they are the most agile and second because they had the operator relationships that allowed white-label operator phones.

    HTC aspired to differentiate itself by "skinning" Windows Mobile and have carried their Sense UI over to Android offering a brand image distinct from competitors.  However, HTC's branded strategy may have upset their operator partnerships (no evidence of this, just hypothesis). In the event, HTC, though prosperous, is not the largest single Android vendor.

    Now the comment above from Peter Chou indicates that HTC is going to integrate the experience further. Building its own APIs, store and perhaps more. Not satisfied with "re-skinning" perhaps it will "re-bone" as well.

    Going "bone-deep" sounds a lot more integrated and inter-dependent than modular to me.

  8. Citizen Publisher

    Research · 11 comments

    In March this year Richard Stengel, managing editor of Time magazine, was speaking about the iPad.

    For a while many movies were more like filmed plays, until directors really learned to take advantage of the opportunities of the medium. For the iPad “The medium is waiting for its Orson Welles.”

    The idea that a new medium needs a new media is not novel. The implication that the new media needs a new genius to define it also follows naturally. However, the implications of new media for the creative industries that are built around them are more difficult to perceive. How are the structures of these industries shaped by disruptive innovations?

    Disrupting theater

    To see just how disruptive cinema was, consider the plight of acting talent. In the early years of the cinema (1890s–1900s), performers were not even identified in films. In other words, they were not in the "credits" and far from being "billed". The reason was that stage performers were embarrassed to be in film. Silent film was considered pantomime and since one of actors' main skills was their voice, they were concerned that appearing in films would ruin their reputations.

    Early film was also designed for the working classes, not for intellectuals. With peep shows as the original presentation format, followed by nickelodeons, film was seen as only a step above carnivals and freak shows. Clearly not something that an aspiring actor would want to be associated with.

    So here we have a classic disruption: The new medium was of a far lower quality than live theater. Even lower than the Vaudeville and Burlesque shows. It was, as many other disruptions are pronounced, a toy.

    However, it had a market--a profitable market. Over time, the product improved and within a few decades completely drained the profits from theater, leaving it to serve only the most demanding customers willing to pay high ticket prices and satisfying only their high brow tastes.

    So going from Theater to Cinema involved more than technological or technique innovation. It required business model innovation. Specifically, Cinema technology brought about the "Hollywood" industry, or more specifically, the Star System and the Studio System.

    The Star System was a branding technique designed to signal quality to the public. It remains a basic and fundamental innovation: celebrity as product. The Studio System was a production and value chain innovation.

    The integrated producer

    By the 1930s technological change led to a new value chain: vertical integration, ownership and effective control of distribution and theaters.

    During the Golden Age (early 20s to early 60s) eight companies constituted the Hollywood studio system. Of these eight, five were fully integrated conglomerates, combining ownership of a production studio, distribution division, and substantial theater chain, and exclusive contracting with performers and filmmaking personnel.

    The studios’ efficient, top-down control over all stages of their product enabled a new and ever-growing level of lavish production and technical sophistication.

    Readers may recognize this as the "inter-dependent" business architecture model.

    The studio system allowed iteration and innovation and factory-like efficiency in production. This architecture held sway as the technology remained relatively stable and the market for content expanded to cover most of the world's population.

    In the late 60s and 70s, modularity emerged as a more practical alternative and control over production was separated from distribution. (Theater ownership was removed by anti-trust action). The system that emerged gave more power to producers and directors (e.g. Kubrik) and the talent became independent of the studios.

    The new Welles

    Which brings me back to Orson Welles. Welles' masterpieces were the product of an industry that allowed innovation to happen. They were the product of an era. An era defined by integrated innovation and inter-dependent value-creating business with common ownership and control.

    So when print publishers today think about their future in the era of the iPad, they should consider their value chains and business architectures. Could the new Welles create the new iPad genres to jump off the screen if he worked in a regular publishing firm that outsources practically everything? Or will he emerge from a firm that operates an integrated value chain. A firm like Amazon that owns the device, the publishing system, the retail store and maintains direct relationships with readers?

    It's my opinion that before there is an Orson Welles of iPad there needs to be a Studio System and a Star System for iPad apps. The Star System is nearly there with the current App Store, but it needs discovery and a systematic way of promoting talent. The Studio System has yet to emerge.

    This does not bode well for traditional publishing houses aspiring to embrace the iPad. They are not in a position to create these Systems around this new media and hence to nurture the next Orson.

    It's perhaps ironic that Orson Welles' masterpiece "Citizen Kane" (1941) was the story of a publisher.
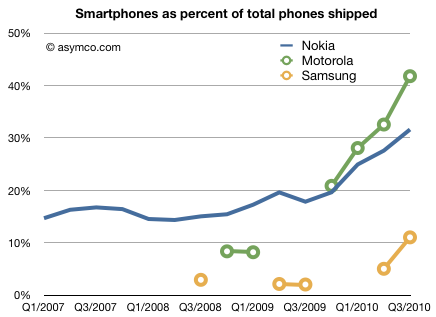
  9. Samsung's smartphones make up 10% of total sold. Nokia is at 30% and Motorola is over 40%.

    Research · 14 comments

    Today's chart: the percent of smartphones as part of the total phones sold for three vendors vendors that have traditionally sold a large portion of voice-oriented phones.

    As these vendors switch to a higher mix of smartphones, their distribution network will ensure a continuing surge in overall smartphone penetration.

    Most of Samsung's increase has come in the last two quarters. Note also the rate of growth in Nokia's mix. Motorola and Samsung owe it all to Android.

  10. 14 Percent of App Store apps target the iPad

    Research · 9 comments

    From Distimo (registration required):

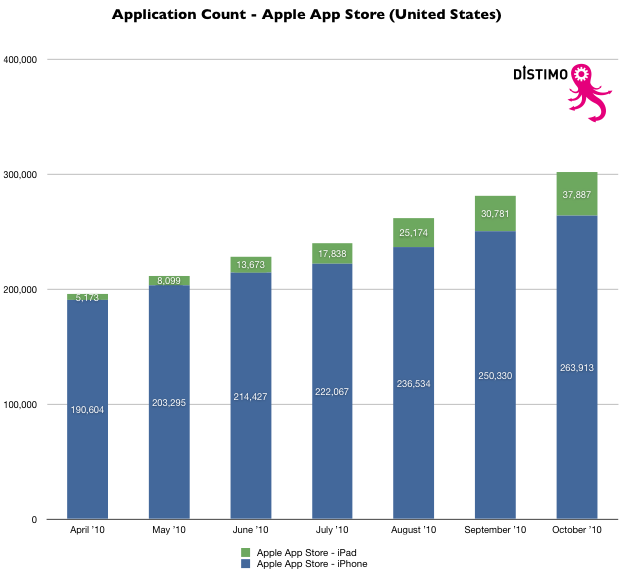
    • The number of applications in the Apple App Store has grown from just under 200,000 in April 2010 to over 300,000 in October 2010.
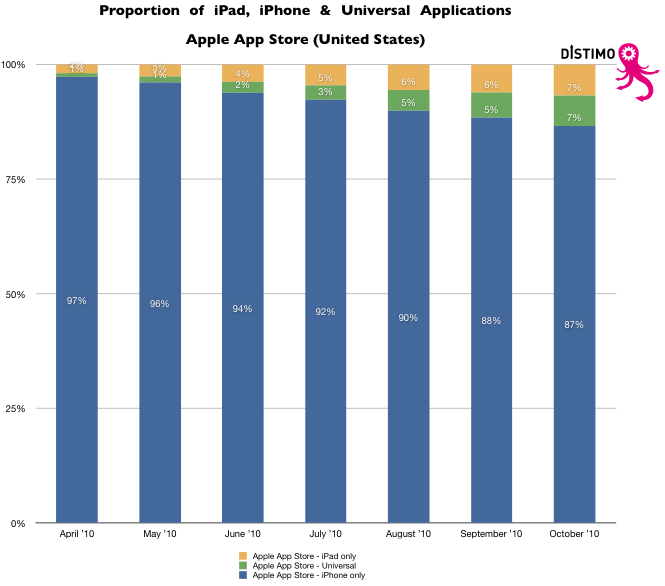
    • The proportion of iPad only applications outgrew the proportion of universal applications during the second quarter of 2010.This trend reversed in July 2010 with the proportion of iPad and universal applications in November being equal (7%).
    • The average price for an application in the Apple App Store for iPad increased from $4.34 in April 2010 to $4.97 in October 2010 (+14.5%). During the same period, the average price of an application in the Apple App Store for iPhone increased only slightly from $3.94 to $4.03 (+2.3%).
    • The average price of the top 100 paid applications in October 2010 is 171% higher in the Apple App Store for iPad than in the Apple App Store for iPhone; $5.80 compared with $2.14, respectively.
    • The lower average price of applications in the Apple App Store for iPhone is due to the fact that a large portion of paid applications are priced at $0.99 (45%), while only 24% of applications are priced at this price-point on the iPad.
    • Angry Birds was the top paid application in both the Apple App Store for iPhone and Palm App Catalog in September 2010. Angry Birds HD was the number three paid application in the Apple App Store for iPad.