An Office Hours question asked by Dave Emery, June 9, 2026.
Q: Are we heading for an AI bustfor the large hyperscalers? Or will the spending eventually produce the revenue the advocates promise? And if it's a bust, how does Apple adjust?
There is already revenue — there’s just not much profit, and not much free cash flow, because everything’s being reinvested. This feels like the early days of Amazon, another infrastructure play, when CapEx was huge, margins were thin, and the P/E looked absurd because earnings were almost nothing. Eventually they recorded earnings, and AWS became the savior. Remember: earnings are an opinion, cash flow is a fact. You can declare software development as R&D and manage the earnings opinion. Cash you cannot.
Is there a bust coming? Look at the hyperscalers — their P/E ratios are fairly modest, lower than Apple’s, and their top lines are growing fast. They’re so hungry for cash that some are doing private placements, diluting investors. But if they raise equity, I don’t worry. Equity is non-contagious. If you get hurt, it only hurts you.
My concern is debt. Almost every crash has come from debt, not equity, being mispriced. The dot-com crash was an overvaluation with no earnings and no revenue behind it, and it was short-lived. A debt-fueled crisis takes a long time to unwind, with repercussions across the economy. So far, AI hasn’t become a debt story. The bubble only bursts if people stop using it, run out of money to pay for it, or decide it’s a productivity mirage. Every indicator I see is the opposite: we wish we had more compute. That doesn’t scream crisis.
There is a subtler issue, though. The old machines of capital — looms, mills, lathes — compounded value and ran for years. These new machines are fragile. Unlike dark fiber that sits in the ground, this compute capital has an unpredictable lifespan and real externalities: cooling, energy, water, and popular opposition to data centers, an unrealized liability that planners are only now confronting. The economics of industrial capital took a century to understand. We’re trying to figure this one out in three years. But as far as Apple is concerned, all of this is an externality.
Overall smartphone shipments in Africa dropped 12%
According to Counterpoint Research, overall smartphone shipments in Africa dropped 12% year-over-year in Q1 2026. Factors like rising fuel prices, memory cost-driven price increases, and the region’s extreme price sensitivity contributed to the slowdown. Yet, iPhone sales bucked the trend, growing a robust 44% year-over-year.
NB: Apple does not adapt to markets. Markets evolve to become Apple markets. It's only a matter of time.
It's a myth that poor countries do not consume quality products. The cost of poor products is borne more severely by those who cannot afford quality. When the chance presents itself to escape to quality, it's taken.
This chance is helped by expanding availability through authorized resellers and carrier partnerships. Also trade-in programs and financing options making premium phones more accessible.
"Africa represents a massive long-term opportunity for smartphone makers, with a young, increasingly connected population. Apple’s ability to grow significantly faster than the market suggests its strategy of focusing on premium segments is paying dividends, even if overall volume share remains small for now."
20 more years at 24%? If we use the rule of thumb that long-term investments in Apple have yielded about 24% then the rule of 72 means you double your money in three years, every three years.
The question has always been about sustainability.
This is the question at the heart of Warren Buffett’s investment thesis. He called it a moat. It’s at the heart of management theory and it’s called sustainable competitive advantage. And it’s at the heart of Apple investment. Especially as the company was known as a hit-driven business. Hits are nice but they are not likely to be consistent. It’s why it’s had a low P/E ratio even though it was booming. →
Exponential increase in performance at a flat price. Is the formula about to change? The iPhone price structure is very carefully constructed. One could even say it’s engineered. It has operated under many constraints: segmentation, margin, scale and market windows. The balance between these and other constraints has been managed for 19 years. Until 2021 inflation was not a major factor but following the Covid perturbation the iPhone pricing fell dramatically. To see the →
Nota Bene
Only one in eight smartphone users uses a smartwatch. What’s the problem? → Counterpoint has Apple Watch shipments up 21 percent, the fastest among the top ten, yet pegs the whole category at 3 percent growth through 2030. That treats the market as mature when only one in eight smartphone users wears a watch. With roughly 650 million users against nearly 6 billion phones, the constraint is non-consumption, not demand. The catalyst that finally unlocks that headroom will be a health and wellness killer app, cheaper than GLP-1 drugs and far better at changing habits. →
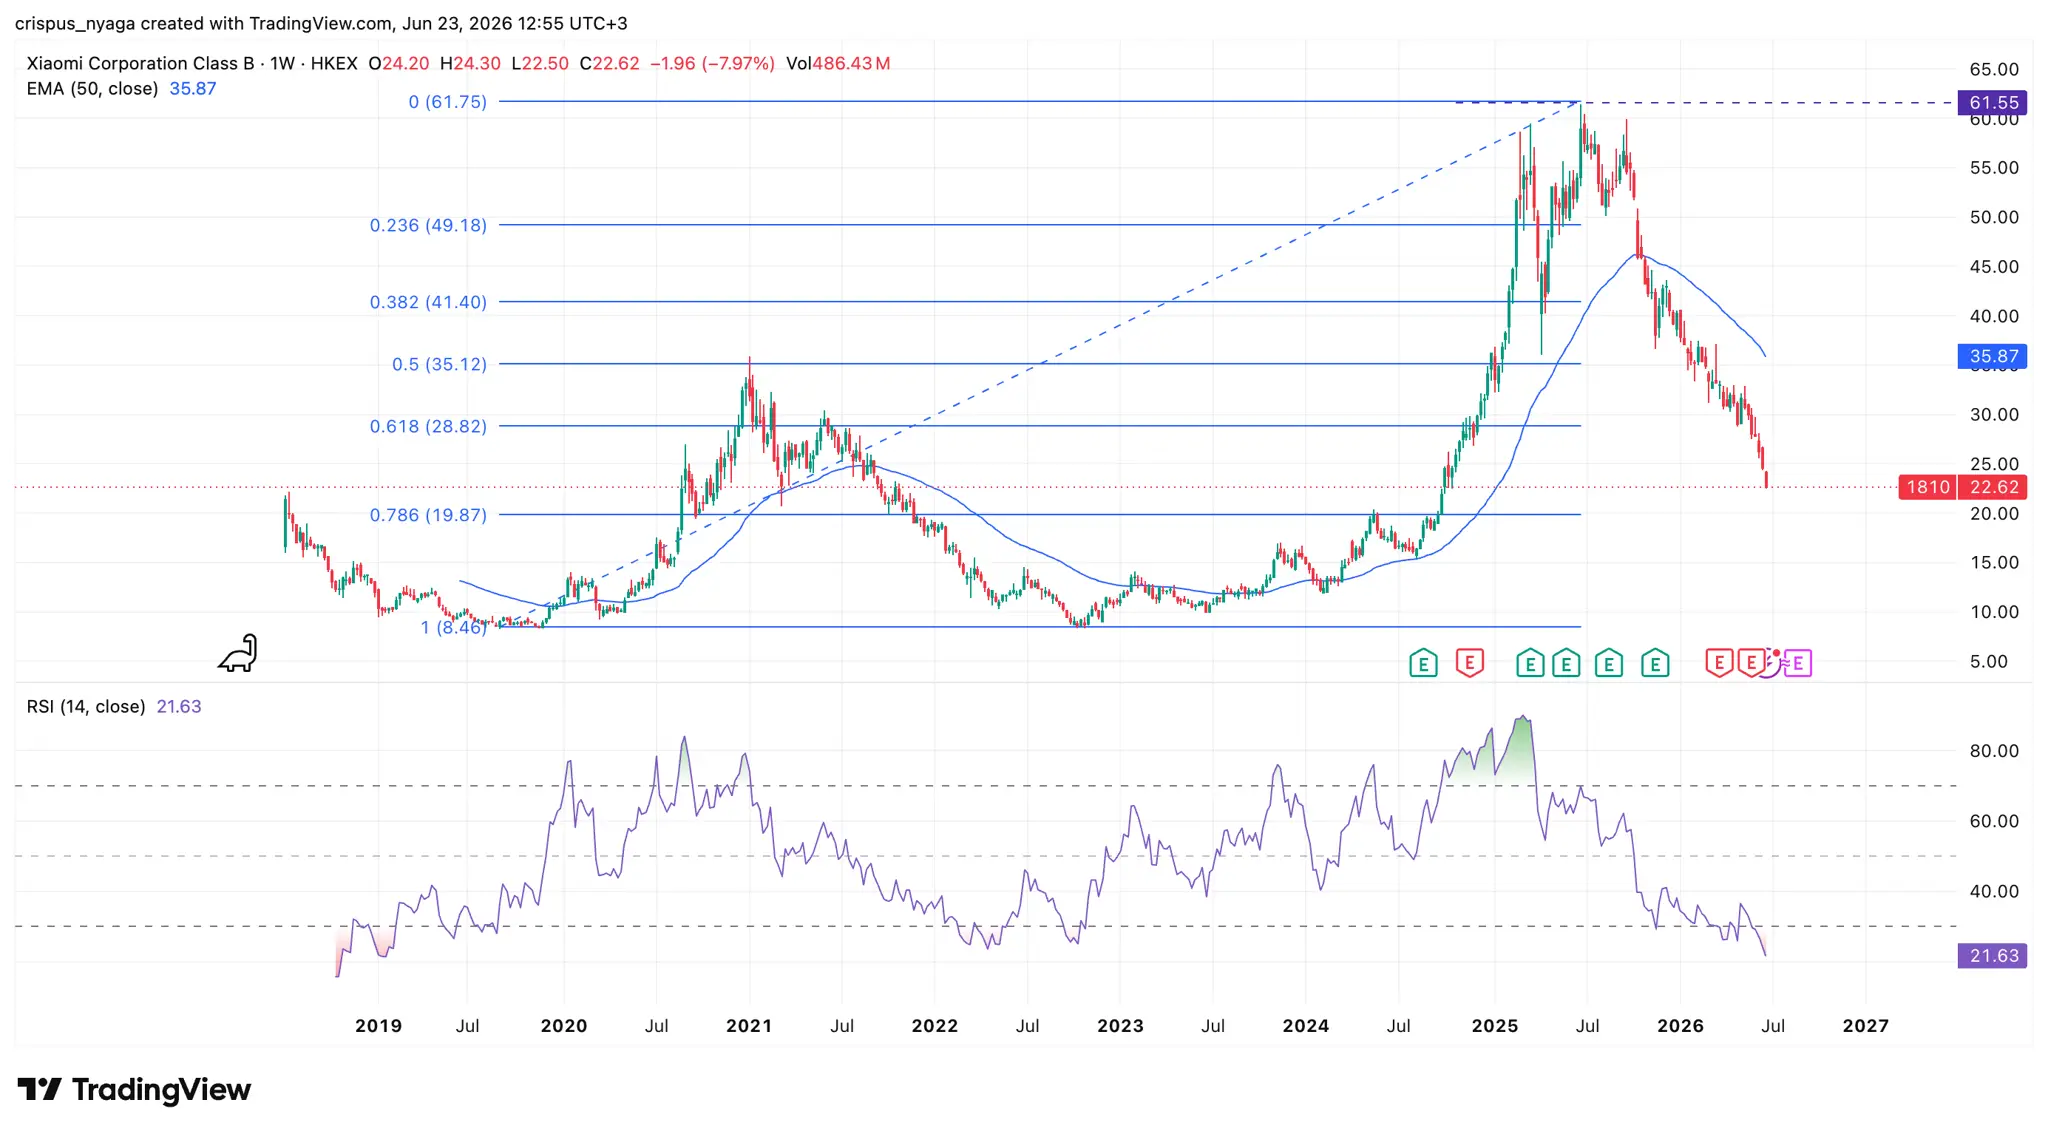
‘China’s Apple’ is in free-fall → Xiaomi, the company everyone insists on calling China’s Apple, is down 63 percent in a year, with revenue off 11 percent and profit cut by more than half. The market blames memory prices and the EV selloff, but the real cause is a lack of discipline. Xiaomi fast-followed Apple into cars and then refused to follow Apple back out when the project was cancelled. Phones and cars overlap in nothing, and a century of carmakers trying to diversify shows every version of this mix fails. →
The Memory Shock: Six Readings from a Supply-Chain Conversation → Singling out memory as strategic makes little sense when the supply chain is a global train, and qualifying an alternative supplier takes a year or two, not months. Apple’s old leverage of prepaying for hundreds of millions of devices is being undermined by data-center buyers who commit the same cash for a fraction of the units, so suppliers took the money and ran. Tim Cook calling this a hundred-year flood he has not seen in forty years told me he was shaken and out of his element. The phone market may fall 12 to 20 percent this year, the worst on record, but if Apple sneezes everyone else gets the flu and Apple quietly gains share. →
Office Hours
Why is the most expensive thing you own the dumbest? → Home has waited years for its missing ingredient, which is inference, because setting up a smart home today turns you into a programmer and it still fails. Apple TV is the hub only by convenience, and as an appliance you replace like a refrigerator it withers, so whatever comes next has to be a software object that keeps evolving. The real embarrassment is that the most expensive thing you own, a house worth millions, is the dumbest thing you own, with less intelligence than a $300 watch. The answer is not a humanoid robot that unsettles people but a little speaker with a screen that turns to greet you. →
Here is a summary of wide-ranging conversation about the 2026 memory-price shock and its consequences for Apple. Six of my answers worth separating out.
1. Why pick on memory? The politics of a commodity
My estimate is that Apple will increase by about $100 the average price of iPhones. Beyond that, I can’t analyze politics. What I do know is there are plenty of suppliers, and the memory is sourced from Asia anyway, which raises the question of why it matters so much that it not be Chinese. The memory makers are in South Korea, Taiwan supplies the processors, Japan is in there with lenses and batteries and camera modules, and there’s plenty of US content too. It’s a global train. If the decision is to pick memory out and call it "strategic", I don’t see the logic, because the penalty for not doing something is simply that there’s no supply. How does that benefit Americans? Apple is a multinational with good customers everywhere, and of all the components you could single out, memory is a peculiar one to choose.
2. How long it takes to qualify a memory supplier
When people ask how long it would take Apple to qualify a new memory supplier at meaningful volume, the answer isn’t months. Apple works on a two-year cycle for its own products. The camera lens, the battery system, the screen are all planned that far out, with targets set for suppliers to hit the quality and scale for a launch window two years away. Memory is a slightly different case, because there’s on-chip memory and there’s storage; files versus DRAM. The on-chip part has to be designed together with the system-on-a-chip, so that’s at least a year in advance. The storage memory can wait a little longer, but not much less than a year. Pricing might not freeze until six months out, which is exactly what we’re seeing now: the prices have come up because of what they’re going to be shipping late in the year.
3. Apple’s purchasing power, undermined
Apple’s strength was always that it prepaid, bought years in advance, and bought in enormous quantity, with contracts spanning hundreds of millions of devices. Nobody came close, not even Samsung [due to their far broader mix of products]. That leverage is now being undermined by new buyers willing to commit the equivalent amount, except they aren’t serving hundreds of millions of devices, they’re serving data centers measured in the single tens of millions of processing units. Orders of magnitude fewer devices, but far more memory per device. It’s been a lot of money dangling in front of a few suppliers, who decided it was better to take the cash and run. But this may pass. Two years from now, the ones who screwed Apple may find that Apple has a long memory and a grudge.
4. The hundred-year flood
Tim Cook said he’s never seen anything like this in forty years. A hundred-year flood. So when his warning came through the Wall Street Journal, it surprised me, because it suggested things may not be lining up into next year. His phrasing was careful: running out of options. Part of that could be cover for John Ternus, framing the trouble as on Tim’s watch so John can take over in the fall and look like the hero, though I won’t read it that far. What I will say is that Tim is the man who works on exactly this, the planning and predictability and negotiating in advance, and it’s his forte. It felt like he was shaken. It sounded unprecedented to him, and he wasn’t in his element.
5. Memory is the new gold
Price-insensitive buyers are purchasing everything in sight and skewing the entire market. This was supposed to be a settled issue, a commodity nobody worried about, and yet here we are. It belongs in the same family as the battery and rare-earth and quality crunches we’ve weathered before. It’s a moving target, and the memory case shocked everyone precisely because we thought it was long gone. Even Tim said he hasn’t seen anything like it in forty years. A hundred-year flood, and we’re all out of our element.
6. If Apple sneezes, everyone else catches a cold
The analysts watching the whole industry think the phone market collapses 12 to 20% this year, which would be the worst year for smartphones on record. We’ve never seen a double-digit decline, not even during COVID. Profits will evaporate. The number-three vendor globally is already down around 60% on the year, and Oppo and Vivo will almost certainly be in the red. That leaves Samsung, who happens to be a huge memory maker and whose stock has actually benefited. If Apple sneezes, everybody else has the flu. The silver lining is that Apple may gain share in a shrinking market, which has already happened in the first half, helped by the supplier inventory it carried over.
An Office Hours question asked by Lalit, June 9, 2026.
Q: Could some future Apple TV morph into a data center for the family? And what about all the talk about Home and AI?
I’ve anticipated the Home story for years, and maybe this is the year. Home needed a big upgrade in intelligence, because today it’s constrained by configuration. Anyone who’s set up a smart home feels like they have to be a programmer — set up events, triggers, scenes — and then it doesn’t work. I don’t want to tell it every single thing to do. I need it to be aware of my needs. The missing ingredient was always inference.
Where it gets interesting is the rumor of a new device type — think of a HomePod with a screen, a display that follows you and creates eye contact, something more anthropomorphic, more like the Pixar lamp. Right now Apple TV is the hub by convenience: it has a display, enough horsepower to act as a gateway, and the security to do the integration. The question is whether it stays the hub, or whether a new home hub arrives, or the two split the job.
Here’s my worry. With AI, the hardware will get obsoleted faster, so you’d need to upgrade more often — but the Apple TV withers, because it’s tied to the TV, and a TV is an appliance, like a refrigerator which you replace only when it breaks. I still have a TV from 2008. Nobody rushes out for a new Apple TV because it’s cool. So whatever they build has to have a reason to be a software object that evolves, not a static box.
Step back and the real problem is this: the most expensive thing you own is a house, possibly three million dollars, and it’s the least intelligent thing you own. We put more intelligence in a $300 wristwatch than in our homes. Cars are the second-worst offender — stupid by every metric, and they resist software, partly because many people don’t want them to be smart. Home and health are the great holdouts, unpenetrated by software for decades, and AI is the chance to take another run at them. And by the way, the dream of humanoid robots in the home baffles me. People don’t want a robot that freaks them out and does the job worse. We like approachable, single-purpose appliances. A little speaker with a screen that turns to greet you beats a faceless robot every time.
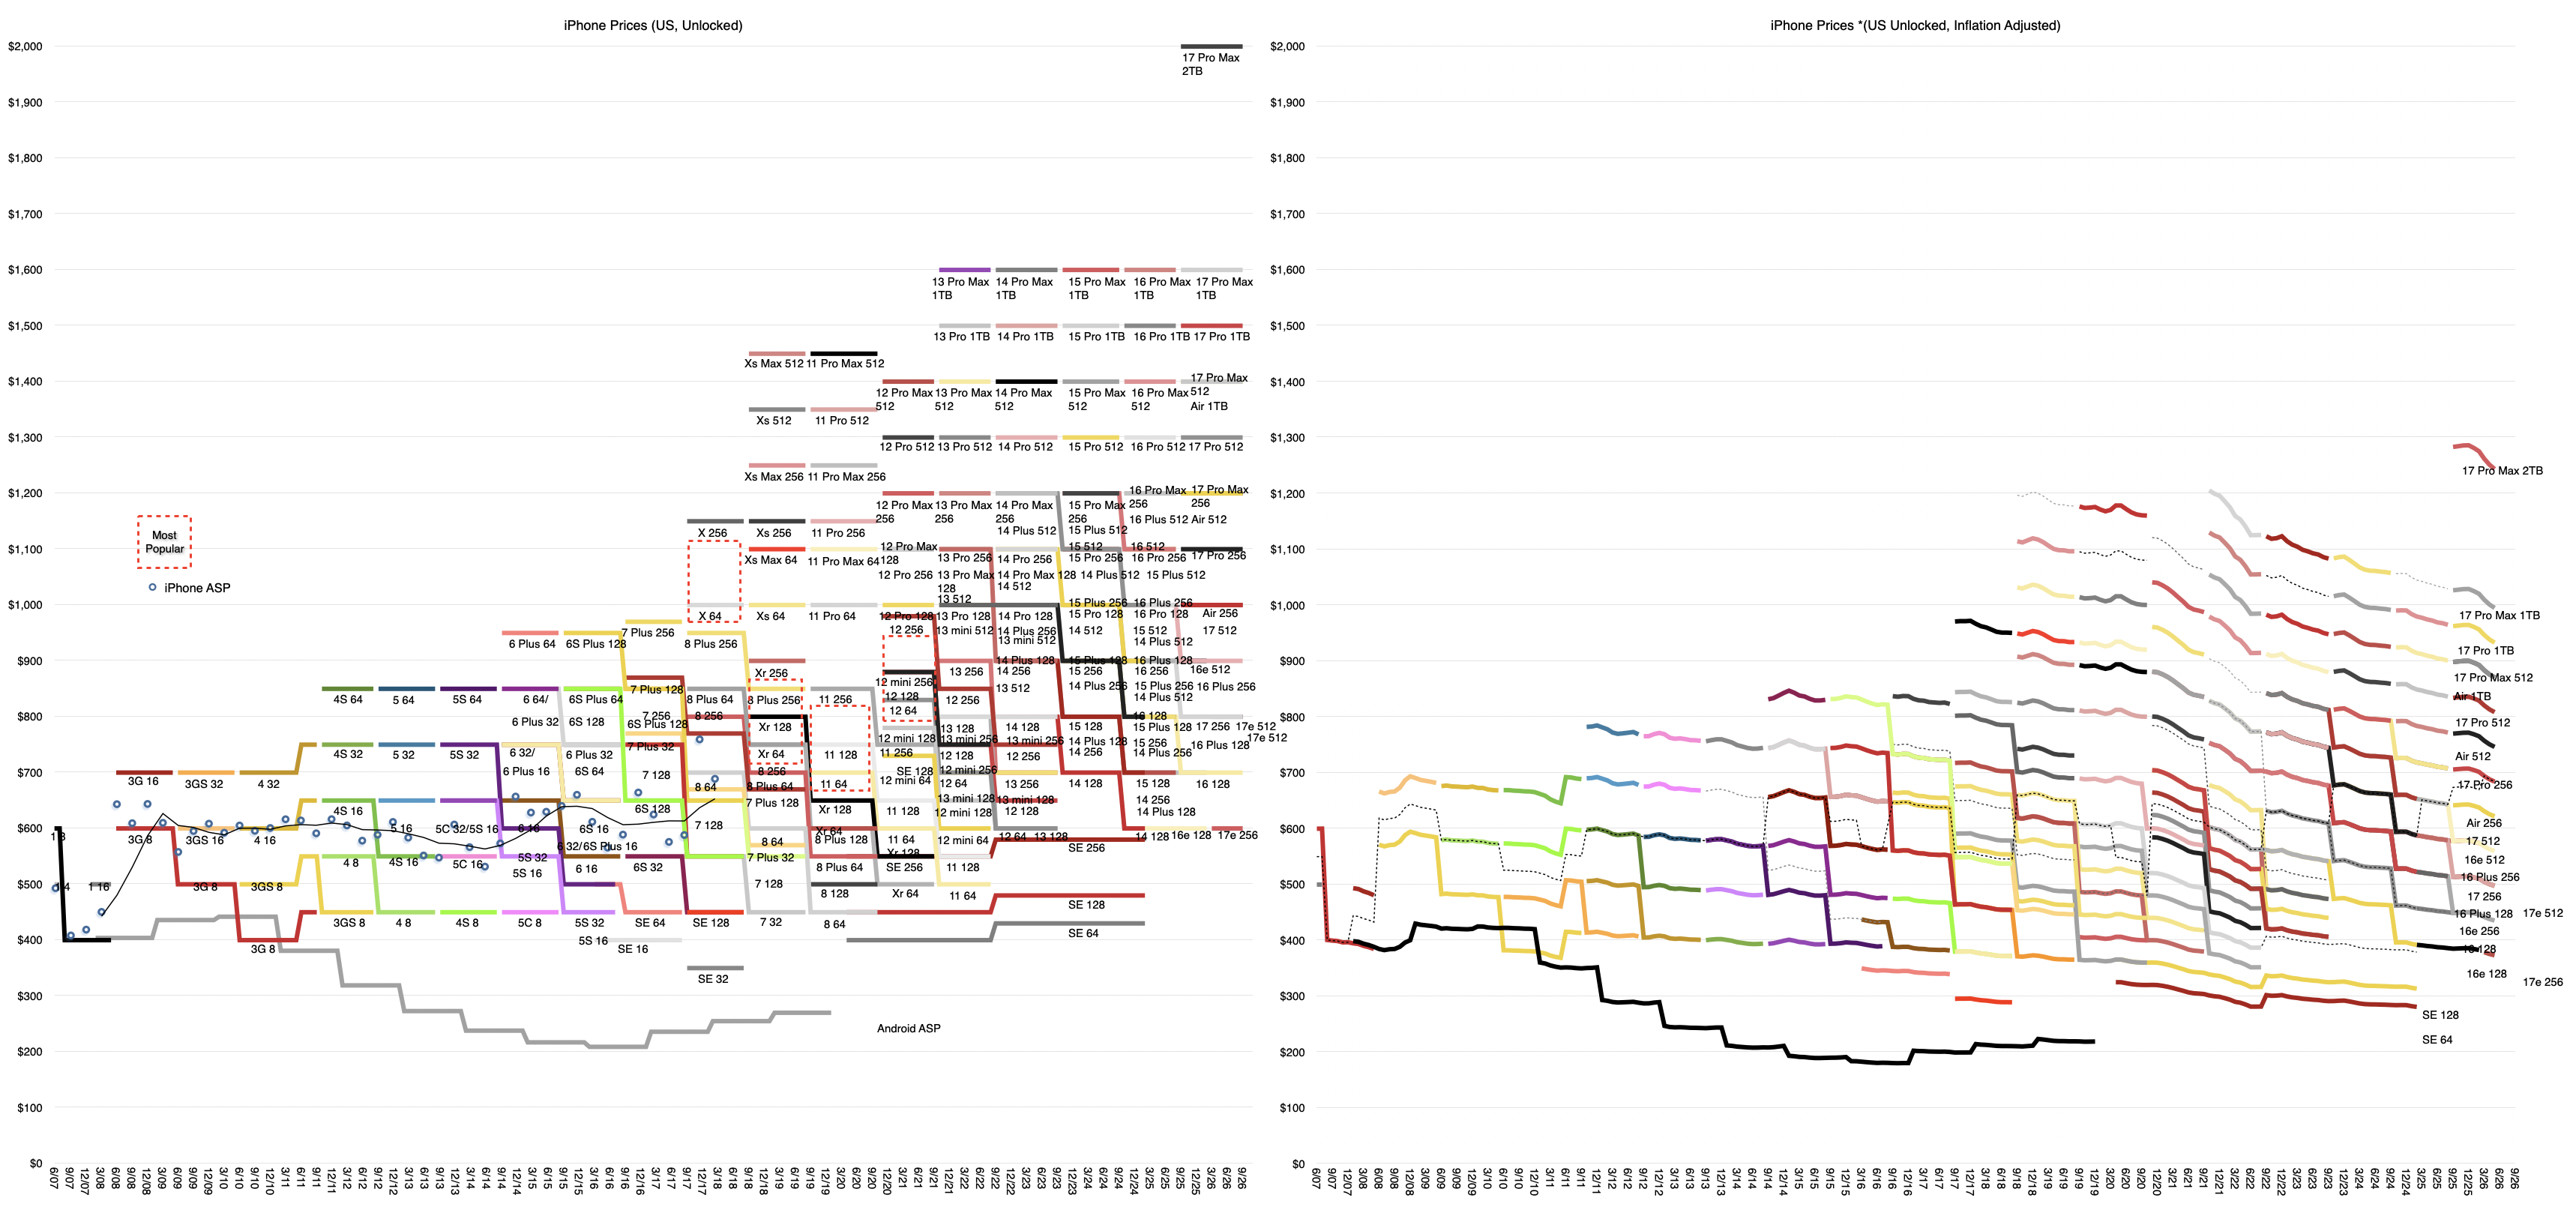
Exponential increase in performance at a flat price. Is the formula about to change?
The iPhone price structure is very carefully constructed. One could even say it's engineered. It has operated under many constraints: segmentation, margin, scale and market windows. The balance between these and other constraints has been managed for 19 years. The left-hand graph above shows the pricing of all iPhones ever sold in constant dollars. The right-hand graph shows the pricing adjusted for US (CPI) inflation.
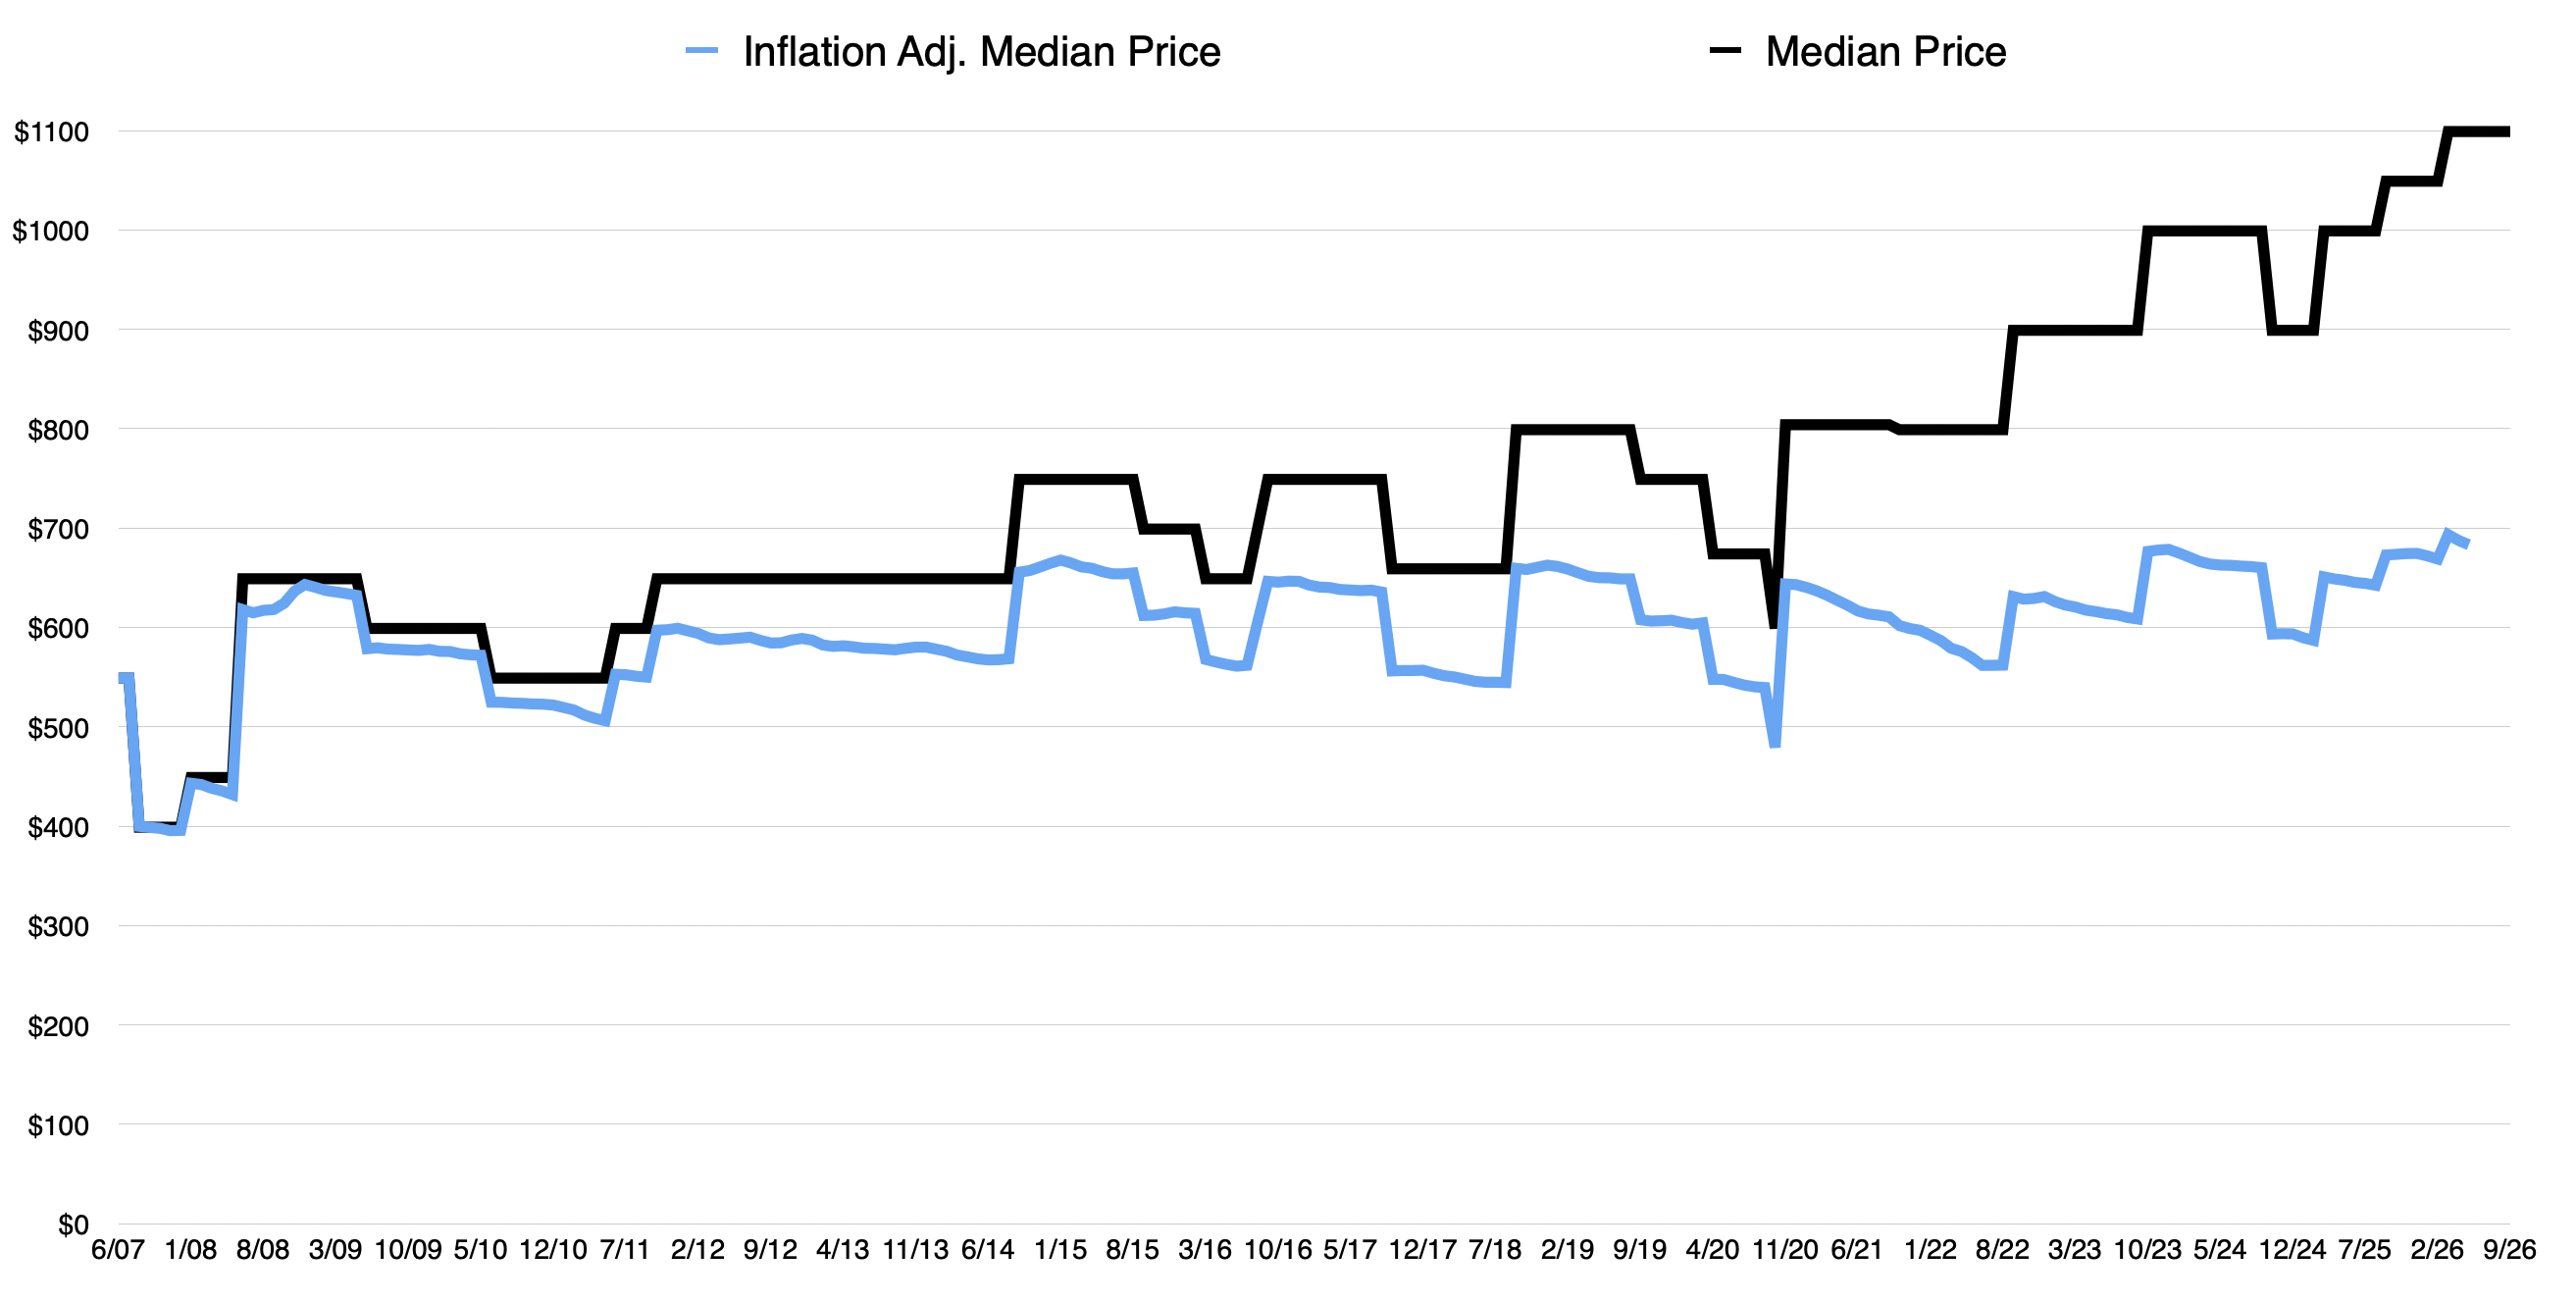
Until 2021 inflation was not a major factor but following the Covid perturbation the iPhone pricing fell dramatically. To see the picture more clearly, I show the median price below:
The median is the point where half the prices are above and half are below. It's not the average selling price (ASP)1. The black line is the constant dollar median and the blue is the inflation-adjusted median.
Note that the inflation-adjusted median has remained in the $500 to $700 point since 2012. In fact the average median is $597 over the entire 19 years.
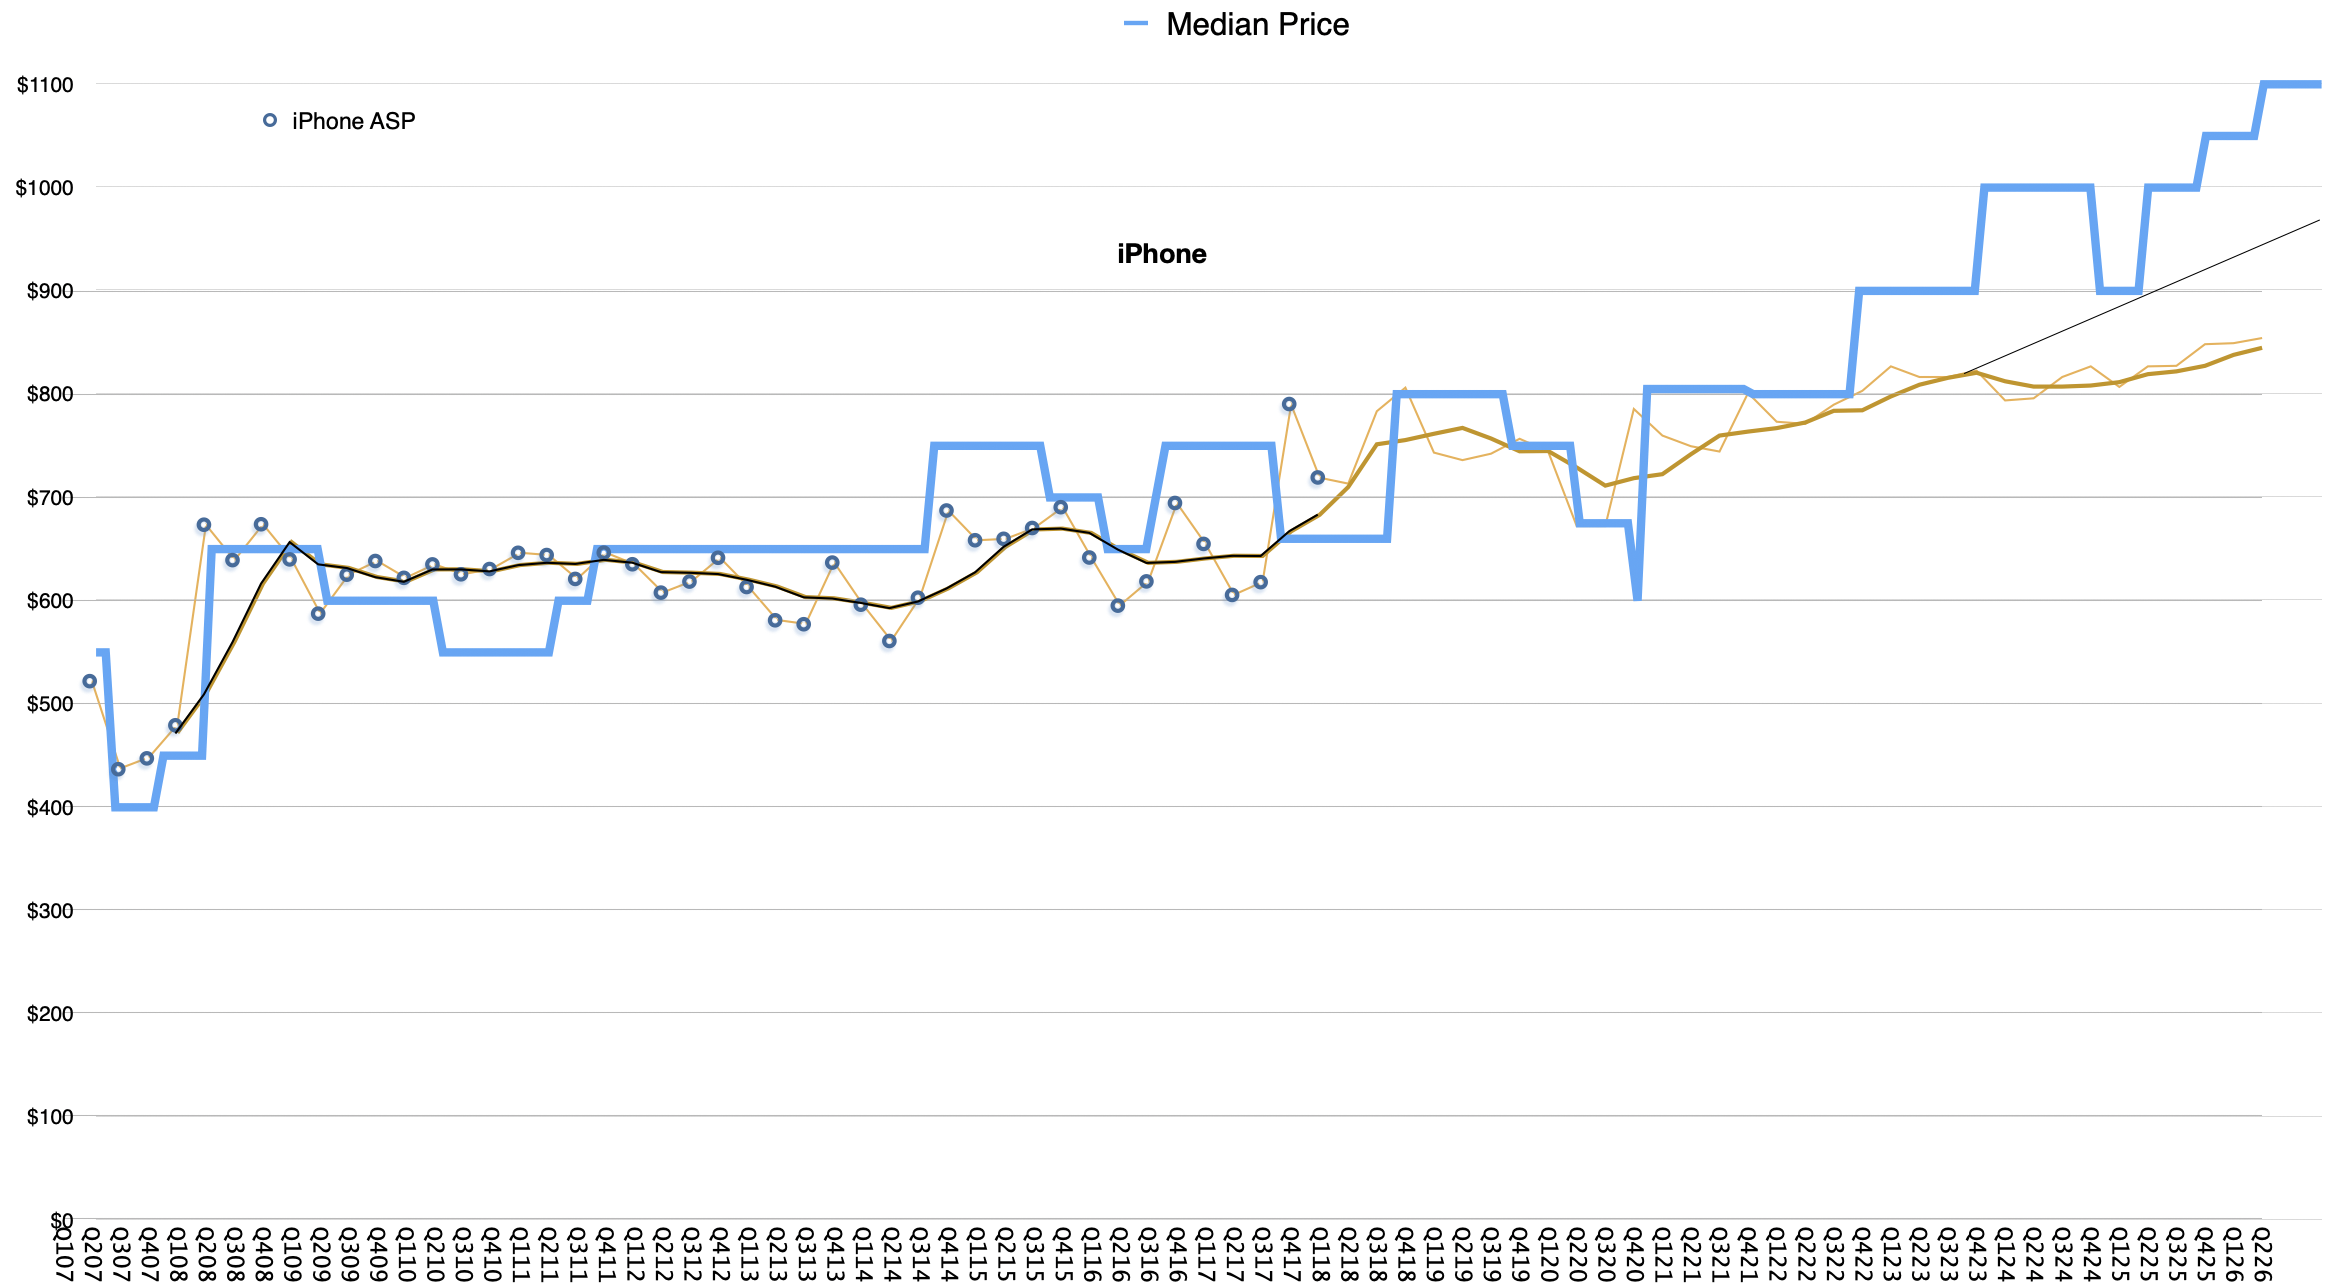
But what does the median represent? It's the midpoint of the price range. It's not adjusted by volume. If more people buy the expensive models then the ASP is higher and vice versa. To test this, I compared the known ASP data with the median to see the relationship.
The dotted line represents actual data and the un-dotted yellow line is my own approximation of the ASP since then. Clearly the data shows that until 2018 the median was a good proxy for the ASP. Perhaps since then the ASP has been lower than the median price but it's predictable.
But if adjusting for inflation, the ASP should be also quite flat over the entire period. It's a remarkable observation.
The iPhone has grown in capabilities exponentially but the price has remained the same.
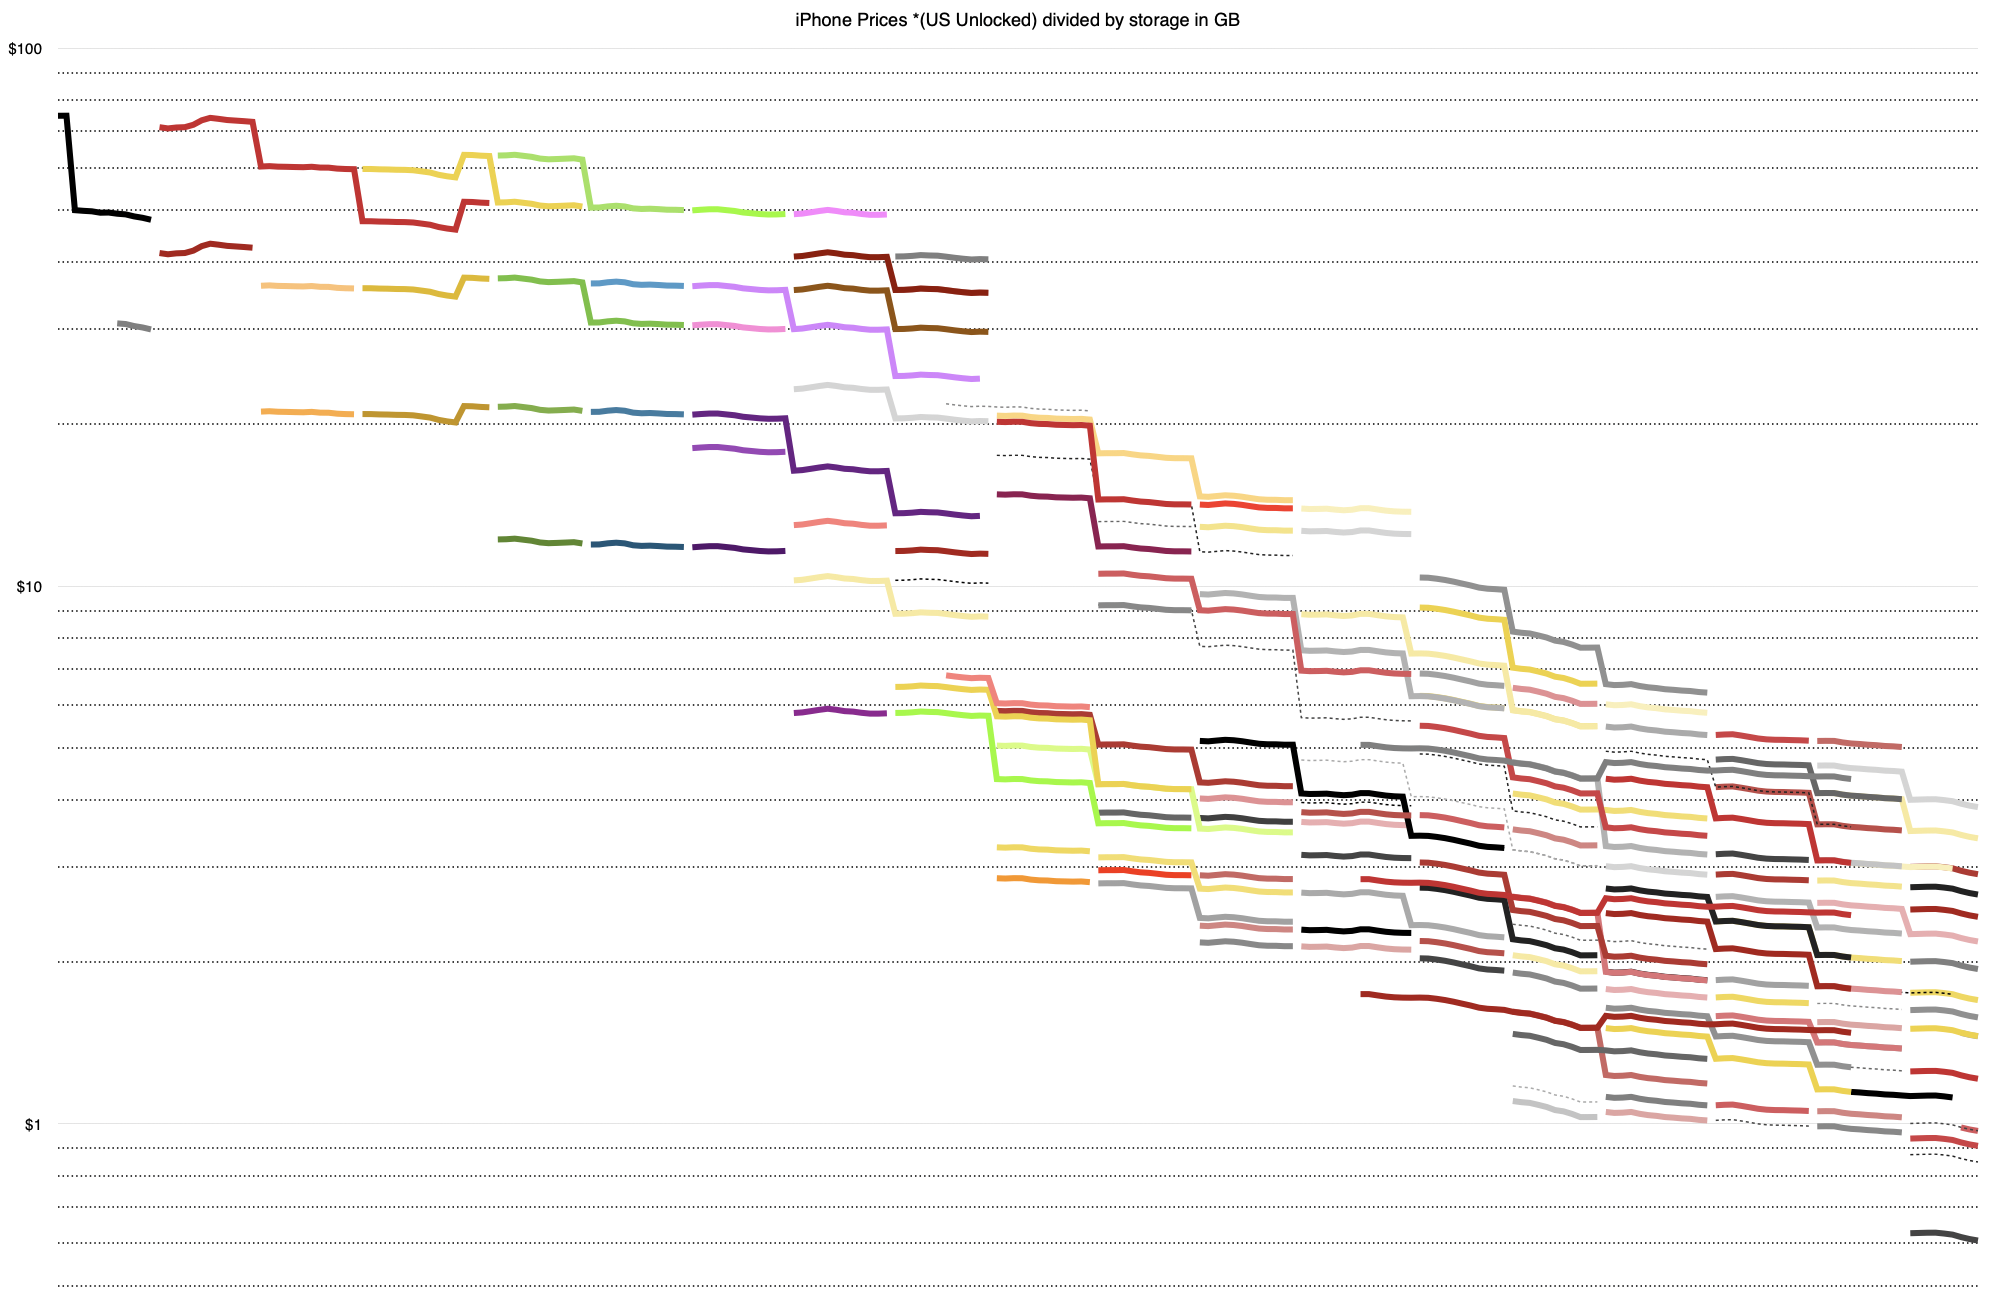
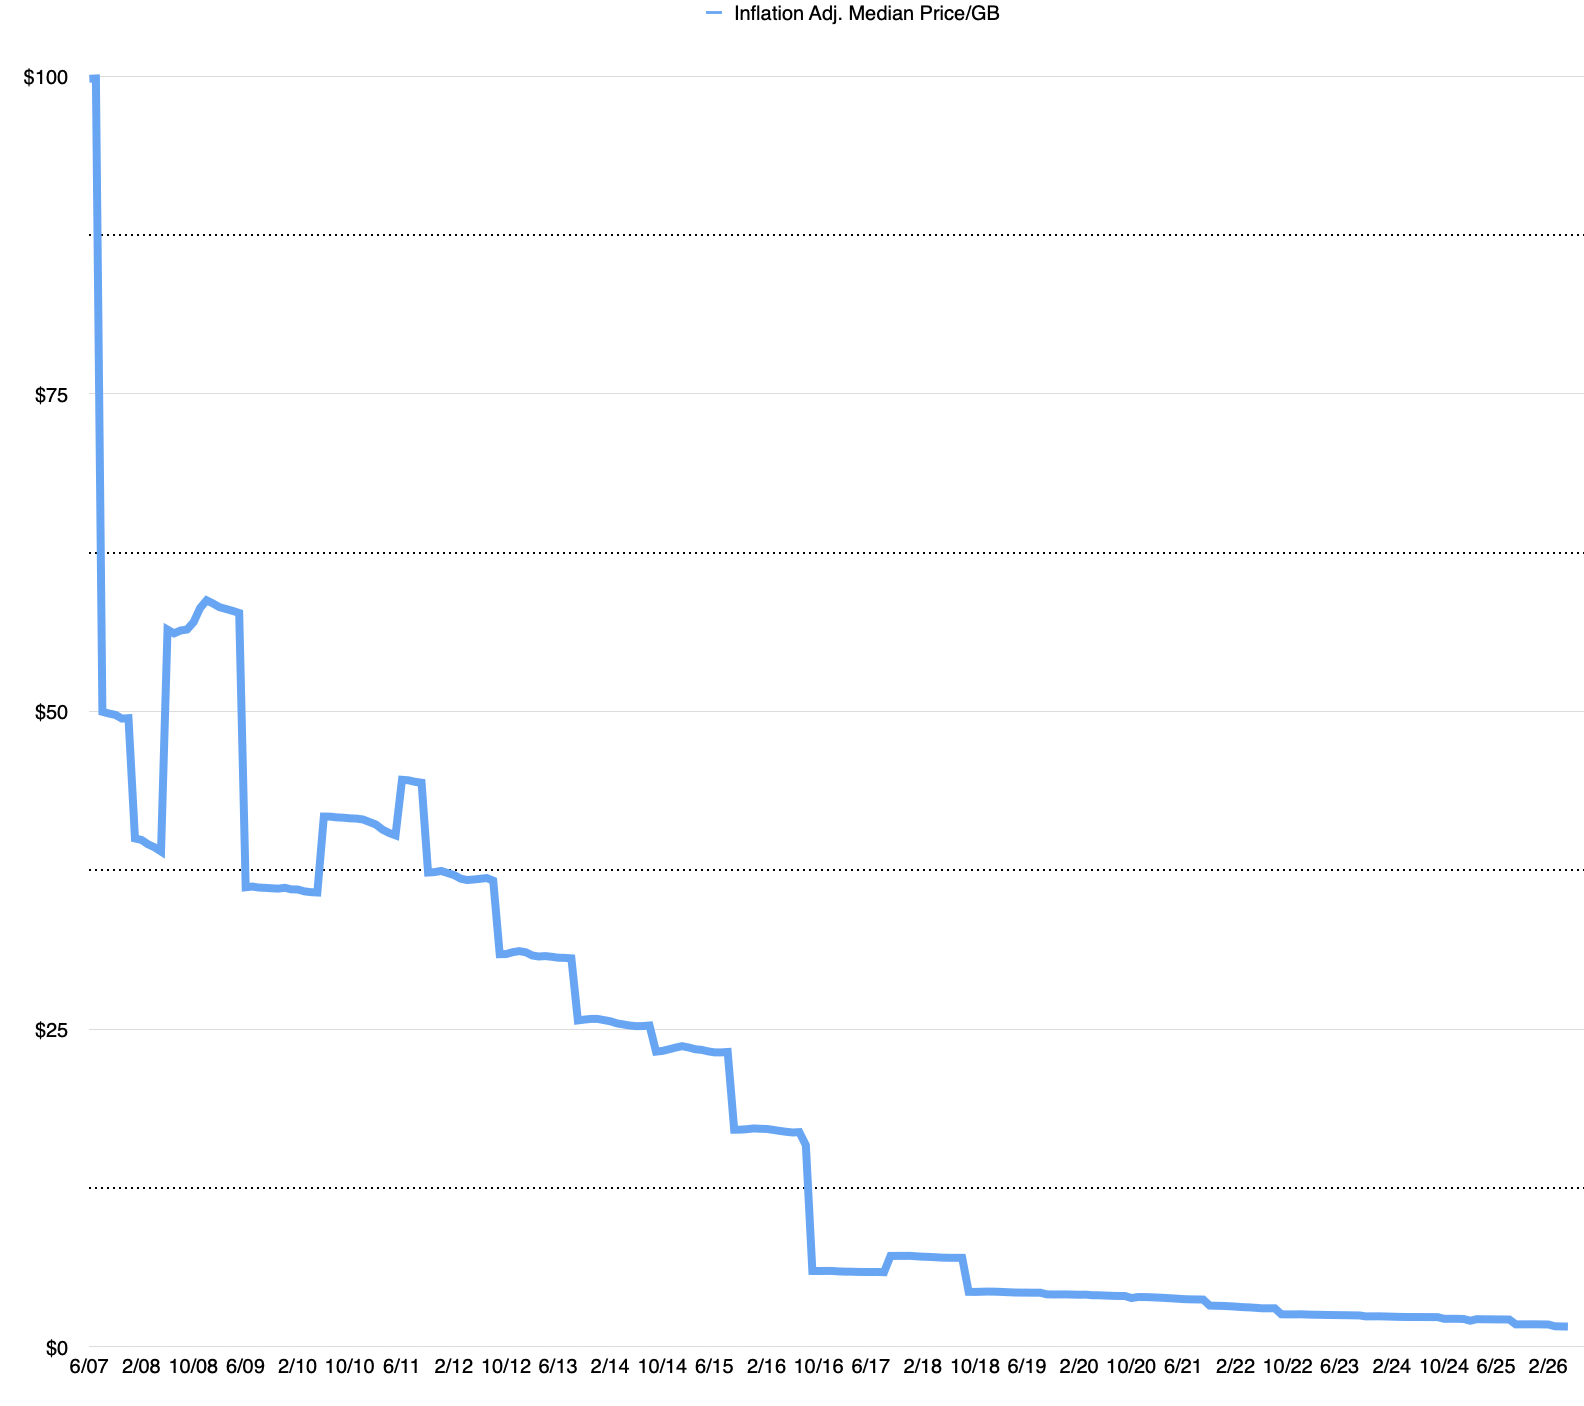
To illustrate, I considered the storage provided by each iPhone in the list (all 160 models). They span 4GB to 2048GB. If we divide the inflation-adjusted price by the storage we get adjusted dollars/GB and the graph for all iPhones is shown below
Note that this is a logarithmic scale. The pricing went from $75/GB with the iPhone (1) to about $1/GB with iPhone 17. A two-orders-of-magnitude reduction.
Taking the median of these prices per GB and plotting on a linear scale gives the following picture.
One of the accusations against Apple is that the iPhone is not much more than a storage device and Apple just charges a mark-up on memory. The higher prices are just deeper gouging of not-much-more expensive memory. The graph above shows how improbable this is. Though storage is one measure of performance, there are many others and the increases in density are passed through to the consumer.
The appetite for memory has grown exponentially and fortunately the pricing has dropped exponentially, yielding essentially a flat price for an exponentially improving product.
Which brings me finally to the point.
The latest warning from Tim Cook is that pricing on many Apple products will "inevitably" increase because memory costs are going through the roof.
The increases are likely to be in the 10% to 15% ($100 to $150 on the median price). But even if they are 30%, the pricing will only begin the deviate from inflation for the first time. I believe there is a reason why the pricing has been so consistent. Apple is pricing at what consumers are valuing (think cost/day including resale value) and are "marking their territory" with a price point few competitors can match.
Over the medium term. the supply/demand crisis in memory will be dealt with as with any economic imbalance: capital allocation chasing returns. Over the long term I believe Apple will expand their footprint to capture more Android users. This means more aggressive packaging (think Mac Neo) and, yes, pricing.
What might be visible in the long term is a blip in the historic "stairway to heaven" graph at the top of this post. The disturbance in the force is that a price might cause a product to change price mid-cycle and do so in a more significant way.
There is a precedent. In June 2011 there was a $50 increase across-the-board on all iPhones. This was because U.S. customers could then buy an iPhone 4 directly from Apple that was free of any carrier lock. Because Apple wasn't guaranteed a share of monthly carrier fees, they passed the true, unsubsidized cost of the device on to the buyer.
This even is almost completely forgotten. The transitions from subsidized to unsubsidized and from carrier-focus to Apple-focus on brand and retail distribution and global expansion are far more profound.
The iPhone has succeeded even though it's the most expensive phone brand. That is because it's more than a phone. It's the portal to one's life. A forced increase in price won't affect this.
Xiaomi stock price has suffered a major reversal in the last 12 months, moving from a high of H$61.55 to H$22.62 today, its lowest level since September 2024, with its market cap falling from H$1.53 trillion ($192 billion) to $74 billion. This retreat has happened amid the soaring memory prices and the ongoing retreat in EV stocks.
Xiaomi has also struggled because of its electric vehicle business. While its EV sales are rising, there are concerns that demand will wane after Beijing ended its subsidies earlier this year. All EV stocks have plunged sharply this year.
The most recent results showed that Xiaomi’s business is going in reverse gear. Its revenue dropped by 10.9% to RMB99.14 billion in the first quarter from the previous year’s RMB111.2 billion.
Its profitability metrics were worse. Its profit for the period declined by 56.5% to RMB4.7 billion, while the operating profit fell by 60% to RMB5.3 billion. These declines were mostly driven by the smartphone segment whose shipments dropped to 33.8 million units from 41.8 million in the same period last year.
The same slowdown is happening across its other segments. Vehicle deliveries dropped to 80,856 from 145,115 in the fourth quarter.
NB: Selling cars, eh? 19% phone unit sales drop contributed to the story but cars are a disaster. A phone maker selling cars is a bad idea. Almost as bad as a car maker building robots.
Xiaomi is being dubbed "China's Apple" but unlike Apple Xiaomi is undisciplined about what segments to enter. Xiaomi initially decided to "fast follow" Apple into cars but when Apple cancelled their project, Xiaomi either could or would not do the same. So they plunged into a capital intense, slow to evolve, highly regulated and indefensible market.
Of course, the phone business is not great for them but they had a chance to differentiate with design for those who would insist on a Chinese phone.
Mixing phones and cars means mixing two completely orthogonal businesses. There is zero overlap in design, manufacturing, distribution, capital allocation, cycle time of product launch, and brand risk/reward.
Car makers have had more than a century to diversify. Every attempt failed.
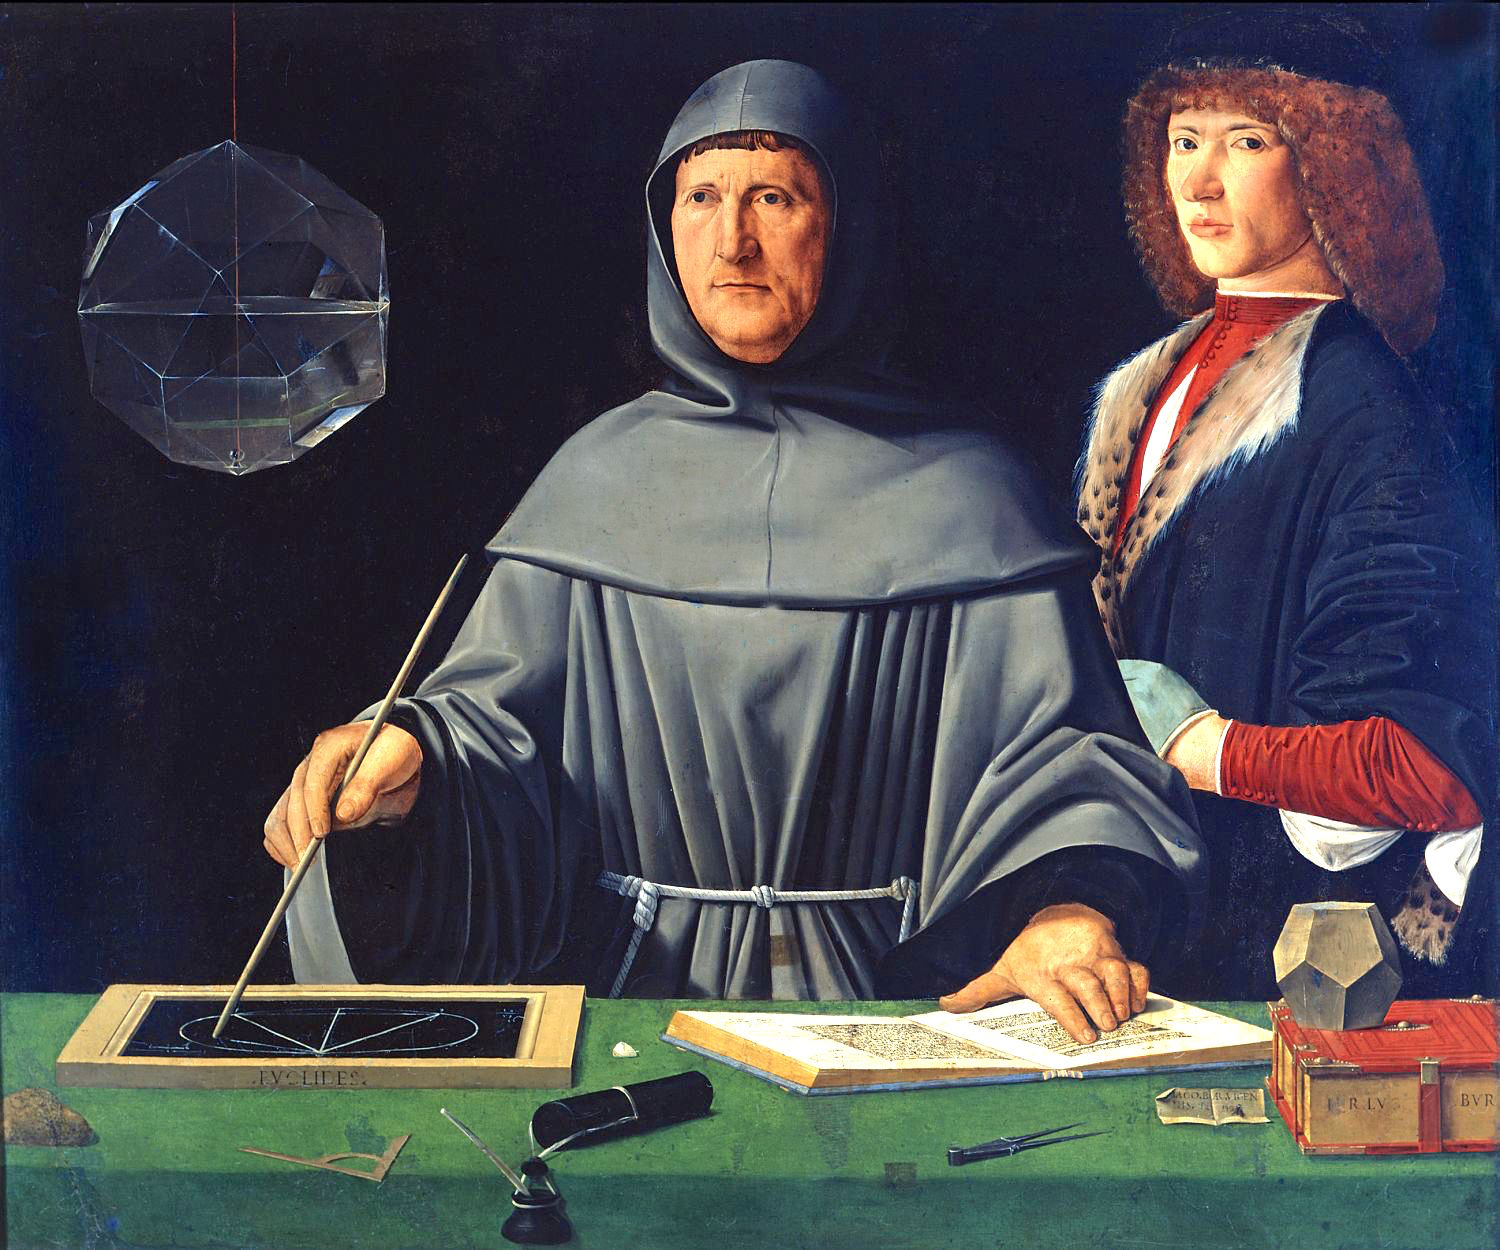
Portrait of Luca Pacioli attributed to Jacopo de' Barbari, circa 1500 which may have been (at least partially) painted by Pacioli's collaborator Leonardo da Vinci.
Summa de arithmetica, geometria, proportioni et proportionalita (Summary of arithmetic, geometry, proportions and proportionality) is a math book written by Luca Pacioli. It is a compendium of the mathematics that was known in Renaissance Italy. This included practical arithmetic, basic algebra, geometry and accounting. Written as a textbook and reference work, it was first published in 1494, two years after Columbus landed in the new world.
As Venice was an early adopter of the newly invented printing press, it was originally published there with a second edition printed in 1523 in Toscolano. About a thousand copies were printed, of which roughly 120 still exist. This was an extraordinary large run for the time and, in contrast to pre-press era when maybe 10 copies would be hand-made, it was a bestseller.
Why was a math book so popular?
First, because it was in Italian rather than Latin. Second, within the chapter on business, a section entitled Particularis de computis et scripturis (Details of calculation and recording) describes the accounting methods then in use among northern-Italian merchants, including double-entry bookkeeping, trial balances, balance sheets and various other tools employed by professional accountants to this day. The business chapter also introduces the rule of 72 for predicting an investment's future value.
Regarding this rule, the quote is:
In wanting to know of any capital, at a given yearly percentage, in how many years it will double adding the interest to the capital, keep as a rule [the number] 72 in mind, which you will always divide by the interest, and what results, in that many years it will be doubled. Example: When the interest is 6 percent per year, I say that one divides 72 by 6; 12 results, and in 12 years the capital will be doubled.
What it says is that if you want to know how long you need to wait for an investment to double, divide 72 by the interest rate. If the (compounded) interest rate is 6% then wait 72/6 or 12 years and you double your money.
This is a great rule of thumb and was devised before logarithms were invented which are more precise but harder to calculate. Even today this is a great rule and should be used instead of relying on spreadsheets or AI to get a quick answer. The accuracy is highest at interest rates above 5% which is well within investor rates of return.
Once you develop an intuition about time to double the interest (or rate of return) becomes a measure of time which is much more relatable. The investment thesis then becomes one of duration which rewards patience rather than gratification.
The problem is however that this rate of return must be maintained and compounded throughout the period. When it comes to returns on share prices, the rate of return can vary greatly and does so instantly and continuously during trading.
Balanced portfolios, index funds, etc. attempt to smooth out the variability and provide a predictable rate of return. For instance, the S&P 500 index, since its adoption of 500 stocks in 1957, has had compounded annual growth rate of 10.56% (excluding inflation). The 10% rule of thumb has been used to encourage investors to hold fast through long periods. At this rate the rule of 72 means you double your money every 7.2 years.
This is also used to discourage "stock picking" because individual stocks are both more volatile and more susceptible to disruption, exiting the index at an alarming rate. Indeed, disruption theory suggests that companies are surprisingly fragile insofar as they succumb to mismanagement with uncanny regularity.
Think of it another way: if it were not for disruption, a public company is a remarkable money printing machine. If it gets to a point of success, it should deliver constant growth consistently. Even 15% growth would mean investors would double their money every five years. That would allow $2000 to become $1 million in 50 years. A single stock purchase at age 15 would provide the individual a fully funded retirement.
The answer is that innovation theory is a theory of competitive behavior and that external factors force time horizons to be not long enough to preserve sustainable compound annual growth rates beyond a few years. Technologies change, people change, tastes change and management is distracted or unable to adjust to these changes.
Let's look at Apple as an example of consistency of return.
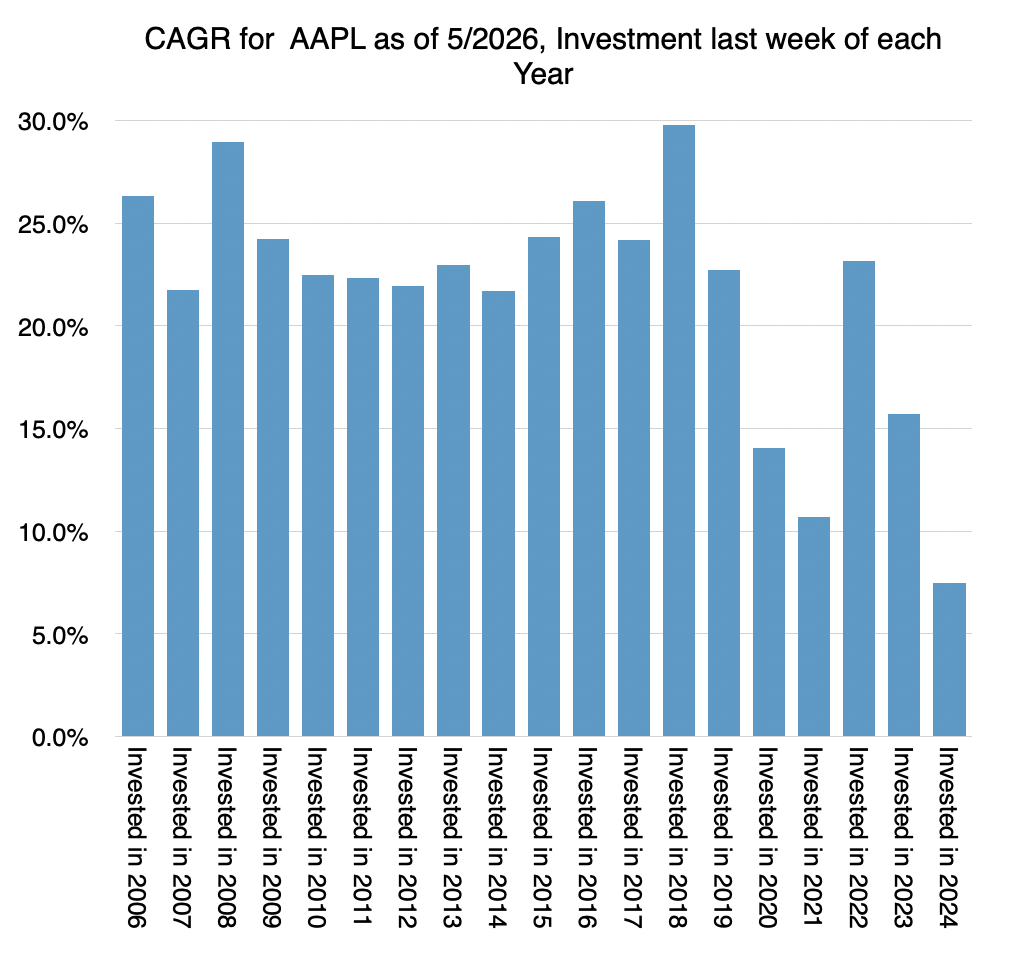
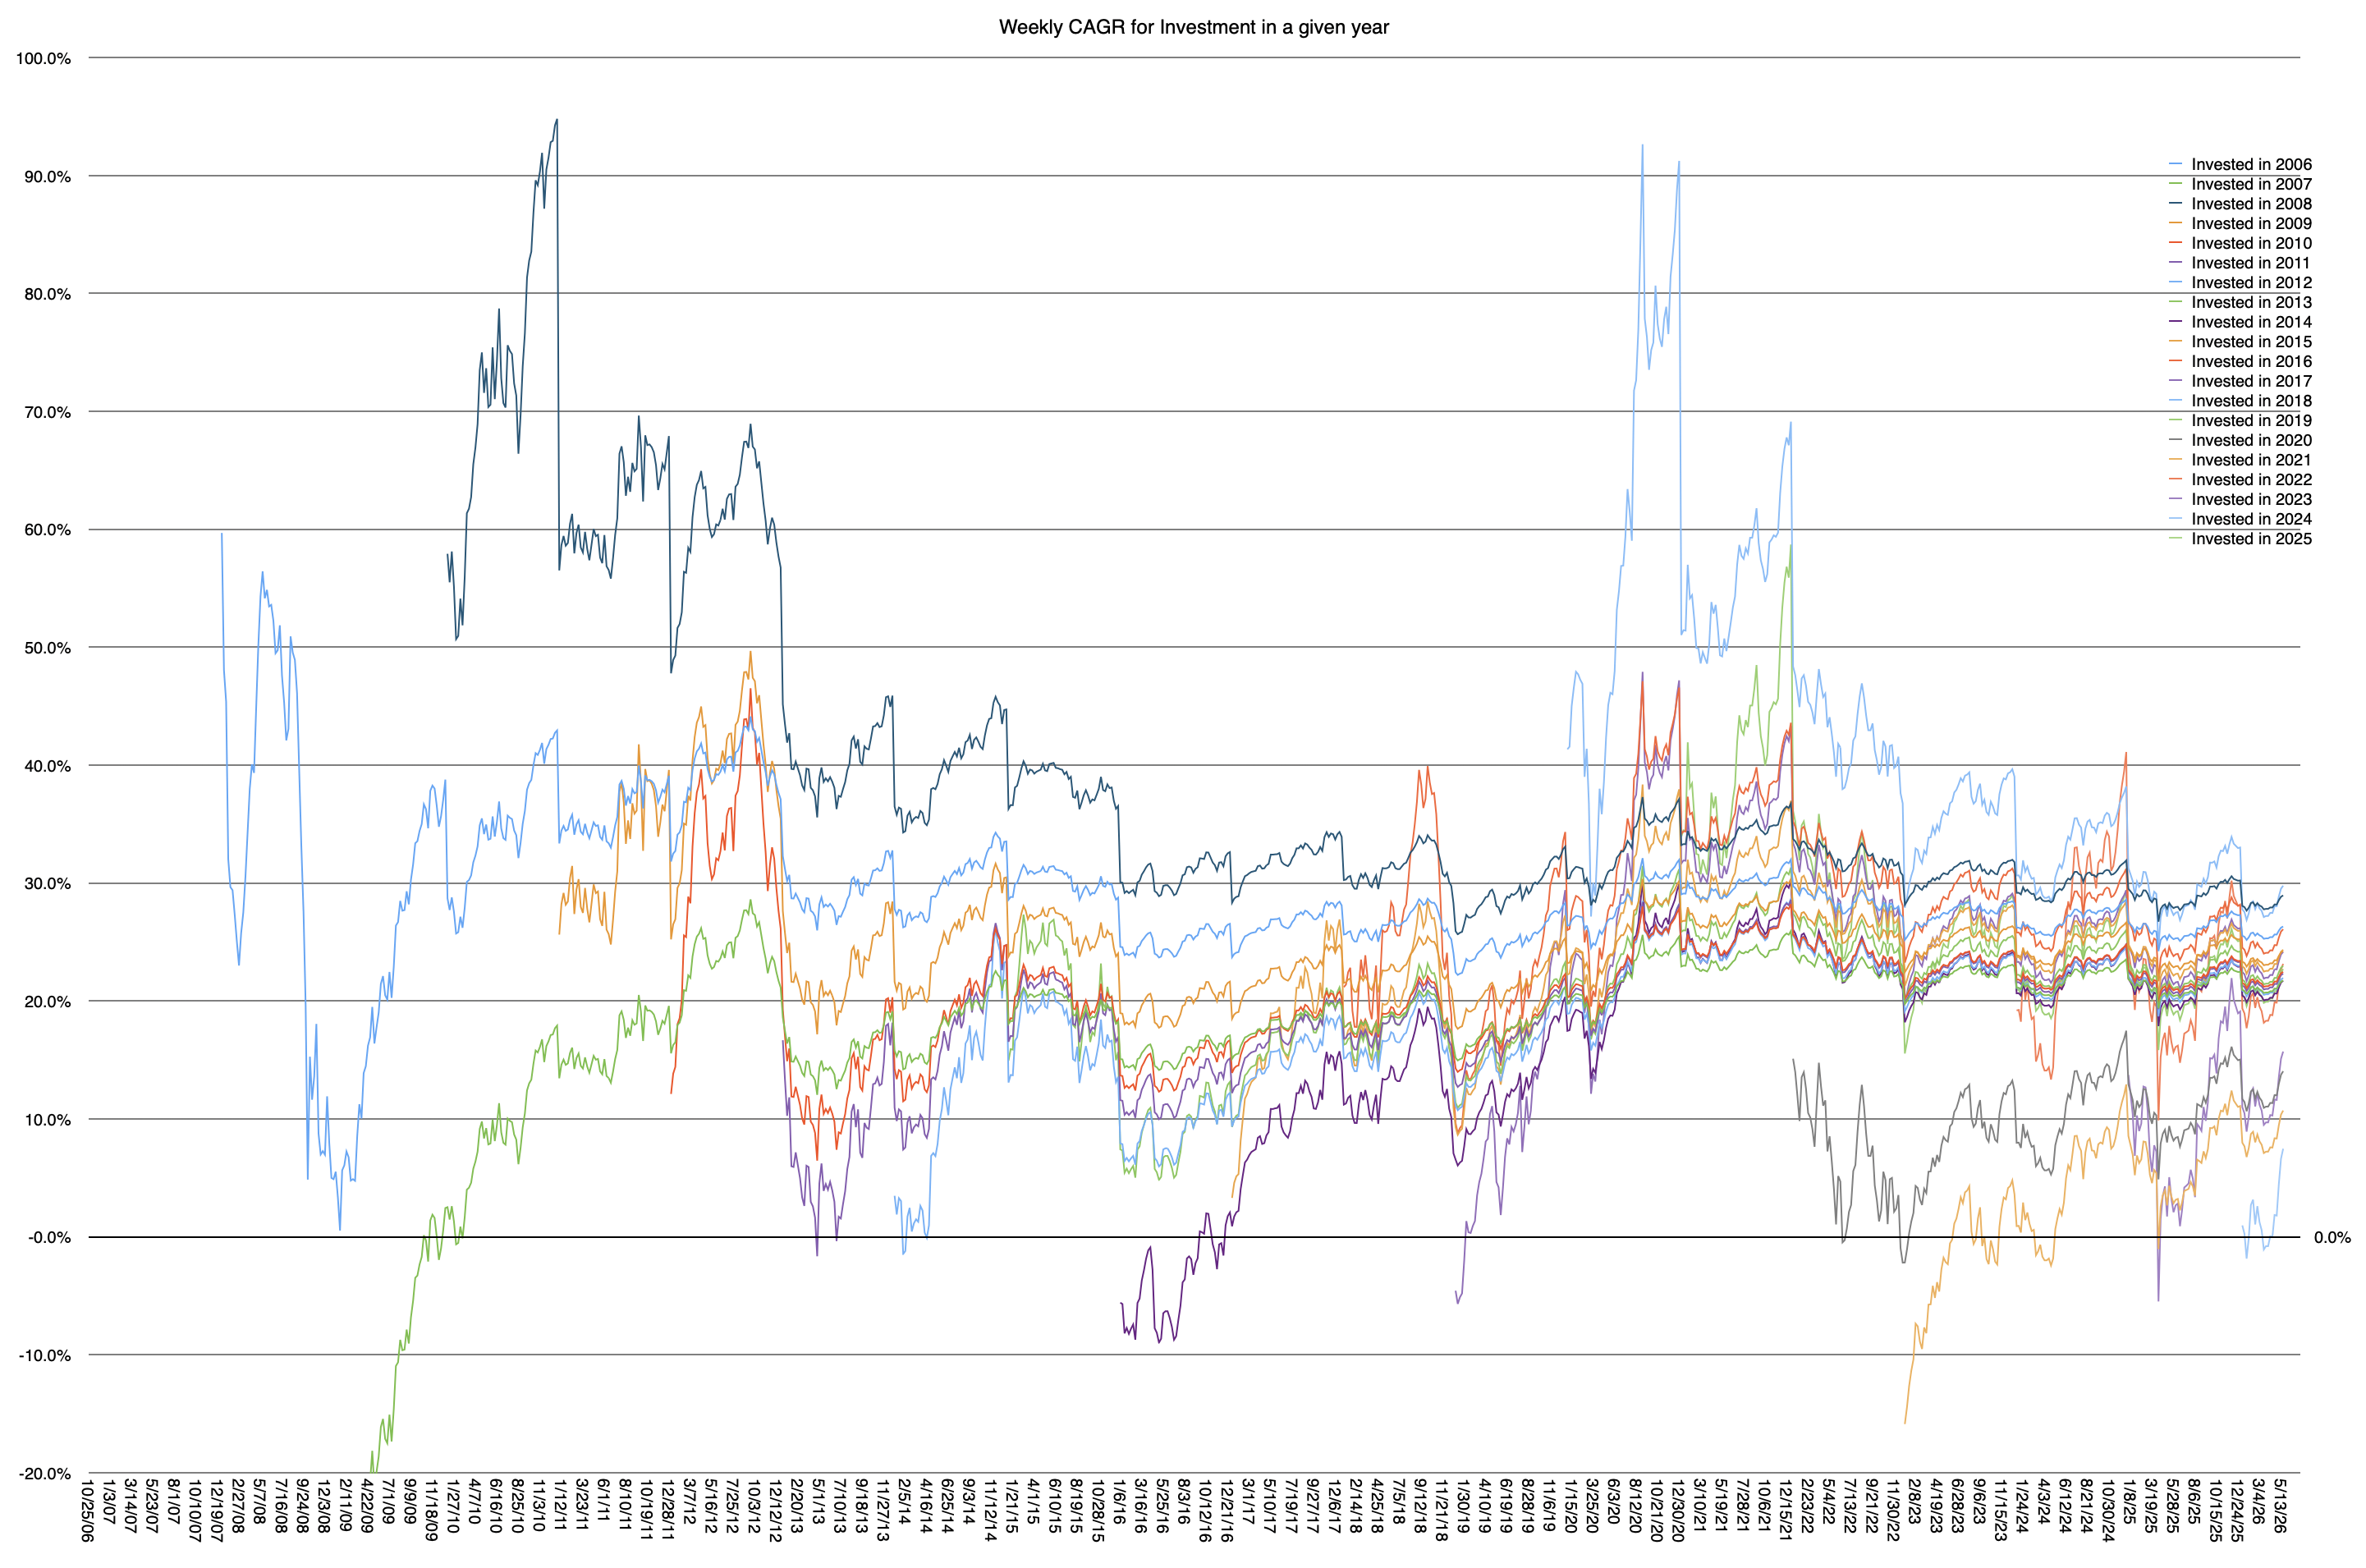
You should ask what is the rate of return on Apple shares in the same way that the S&P 500 index is measured (since 1957) to have a 10% compounded annual growth rate (CAGR). I went through this exercise for the last 20 years: Assuming investment during the last week of each year, what would the compound rate of have been today?
I graphed both the instant return for any point in history (the second graph) and return as of today (the end points of the second graph are shown in the first).
The answer is: For investments longer than 1 year, the average is 21.6%. For holding longer than 5 years the average is 23.6%. For holding even longer, it does not drop much below 24%. Note that as investments are made, short-term they can be far above or far below the median rate of return. they tend to converge on the median over time. And what a median that is!
If we use the rule of thumb that long-term investments in Apple have yielded about 24% then the rule of 72 means you double your money in three years, every three years.
This is extraordinary not just because of the 24% CAGR but that it has been going on for about 20 years.
The puzzle that Luca Pacioli and his students in Renaissance Italy must have considered has been the same as the one we have study today: How do you maintain that interest rate and hence that doubling period for long enough to benefit from it?
The question has always been about sustainability.
This is the question at the heart of Warren Buffett's investment thesis. He called it a moat. It's at the heart of management theory and it's called sustainable competitive advantage. And it's at the heart of Apple investment. Especially as the company was known as a hit-driven business. Hits are nice but they are not likely to be consistent. It's why it's had a low P/E ratio even though it was booming.
Apple has always been a tough thing to invest in.
But there is hope…
…At the time Summa de arithmetica, geometria, proportioni et proportionalita was published, the world had a CAGR of 0.1%. For most of human history, any spikes in productivity or technological innovation (such as the printing press used to print the book) resulted in population growth rather than sustained improvements in living standards. Output per capita had remained practically flat over centuries.
By the Industrial Revolution (1800 – 1913) CAGR increased 10-fold to 1.5% to 2.0%. The advent of mechanized manufacturing, steam power, and trade routes initiated an unprecedented era of sustained economic growth. For the first time, wealth generation outpaced population growth. It was the birth of plenty.
By the late 20th century (1945 to 1973) CAGR doubled again to 4.5% to 5.0%. Following the end of the Second World War, the global economy experienced the most rapid and sustained period of growth in human history. Driven by technological and market innovation, global output soared. Much of the way the world is now governed and planned comes from the lessons learned during this period.
From the 1970s to Present the world's CAGR has reduced to 2.8% to 3.5%. Much of this is due to globalization and the diffusion of innovations that were centered in early industrialized nations. The growth is also bifurcating into riskier technology investment (early adoption) and diffusion of technologies to later adopters.
The opportunity to re-accelerate to 5% global growth might exist if diffusion rates increase. That is, bringing value rapidly to large populations.
That should be the thesis. Apple's 23% growth could be extended and anticipated if it's seen as the distribution of the greatest ideas, which already exist, to a larger audience who, with the gained productivity leverage, return to invest again and again. It requires some degree of global and social stability but if you are willing to be an optimist in that regard, doubling every three to five years seems sustainable.
Apple sustained 20%+ for 20 years and if it holds this rate for another 20 it will be a longer period of prosperity than the post-war era which only lasted 28 years. No pressure, JT.
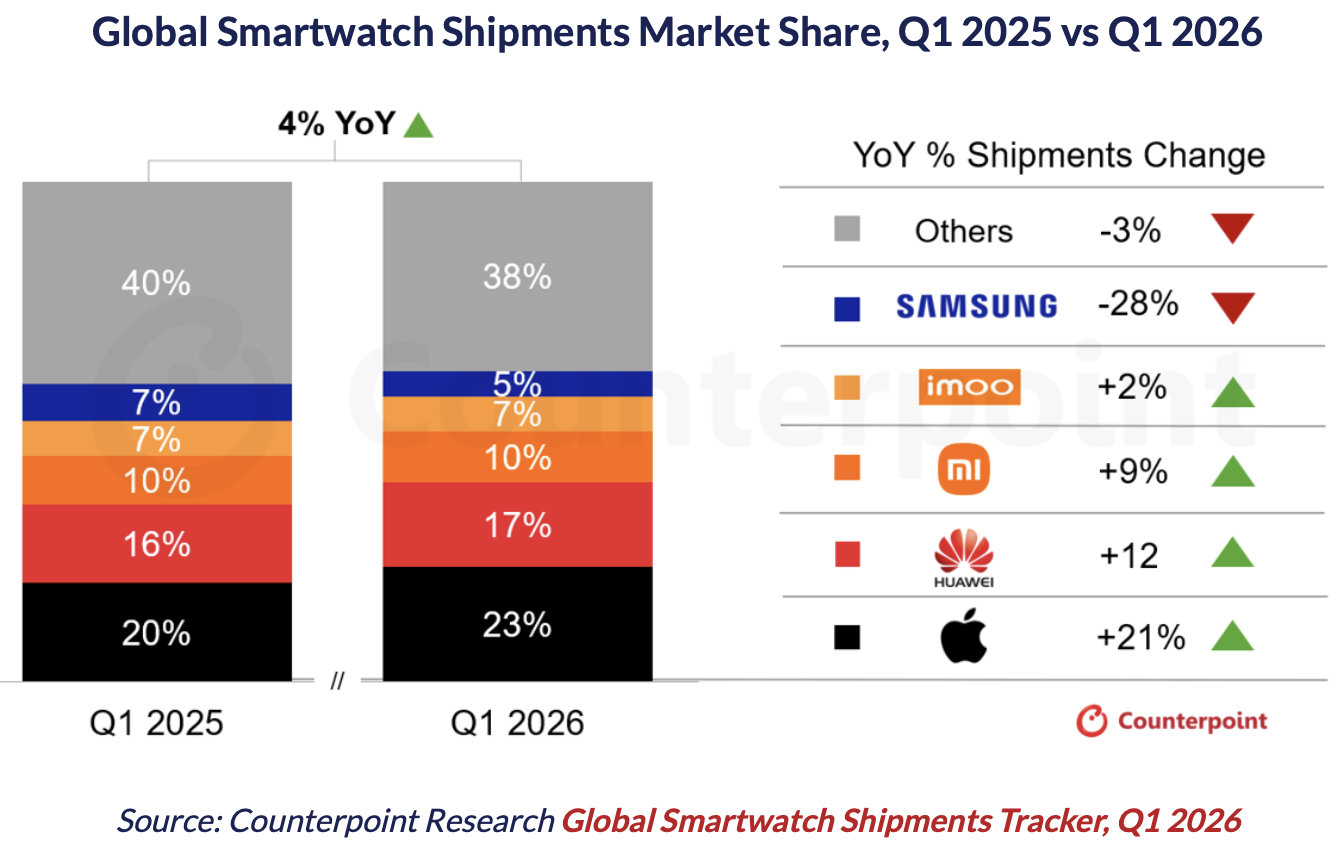
Apple grew at 21%. Global market grew 4% with forecast is 3% growth through 2030
Global smartwatch shipments grew 4% YoY in Q1 2026, driven by continued Apple adoption and the China market’s recovery.
Apple shipments rose 21% YoY, the fastest growth among the Top 10 brands.
Following the extension of the Chinese Government’s electronics subsidy and the rise of local demand, Huawei and other Chinese brands regained momentum.
Rising memory prices are expected to have a more limited impact on smartwatches given their lower BoM costs.
Commenting on Apple’s performance, Counterpoint Research’s Principal Analyst Anshika Jain said, “Apple has captured the highest shipment share of 23% and emerged as the strongest performer in Q1 2026, driven by the continued success of its refreshed lineup. While North America contributed over half of the total shipments of Apple, China and Europe recorded the fastest growth for the brand. The addition of meaningful health upgrades and the affordable SE 3 attracted new buyers.”
Emphasizing the rising ASP, Jain added, “Smartwatches’ ASP rose by 6% YoY in Q1 2026. The major drivers were the integration of improved sensors and advanced technologies to support health monitoring and AI capabilities. In addition, consumers’ transition from basic smartwatches to advanced smartwatches in emerging markets like India is also driving the overall ASP growth.”
The smartwatch market regained momentum in 2025 after a slowdown in 2024. This recovery was driven by brands introducing a variety of new features, such as satellite connectivity, 5G RedCap, AI capabilities, and more advanced health tracking for conditions like sleep apnea and hypertension. This has helped build strong growth momentum in the market. However, recent memory shortages and macro-economic factors are expected to slightly impact the overall growth rate for 2026. Even so, the effect is likely to be less severe than in other consumer electronics segments, supported by comparatively higher margins in premium smartwatches. As a result, the smartwatch market is projected to grow at a CAGR of 3% through 2030.
NB: 3% growth through 2030 is no growth at all. Non-consumption is catastrophically high and yet Counterpoint projects zero growth over four year. Apple's share at 23% roughly matches smartphone share and that may be plausible however the market for watches is still modest relative to the phone market. Something does not add up. Here are the numbers…
…There are an estimated 650 million smartwatch users worldwide. That is super low relative to phones and even estimates that the user base is projected to surpass 740 million by 2029 seem weak. There are approximately 5.78 to 5.83 billion smartphone users making watch penetration by 2030 barely 12%.
Only one in eight smartphone users uses a smart watch. How can 3% growth be acceptable?
There is enormous headroom for Apple Watch and I believe penetration is proceeding at a measured pace (20% growth is above iPhone over longer periods). The opportunity, like that for the Mac, is to address non-users with a compelling new value proposition. Is AI such a proposition? Perhaps, though it will take years.
A more likely catalyst is still a "killer app" for health and wellness. It's cheaper than GLP-1 drugs and has more of a chance to change habits.
Asymco Bulletin is a digest of all the work we have published for the week ending June 21, 2026.
Asymetric
Asymetric Podcast: Episode 138 — Watershed → Horace on WWDC 2026, John Ternus's timing, what we can learn from the candy bar, and Judd's indifference to origami. Also, World Cup predictions.
Now in beta for Asymco One subscribers; listen to Asymetricin your favorite podcast app. →
Tim Cook told the Wall Street Journal that price increases are unavoidable as Apple's range of options on memory costs has run out. WSJ estimates a $270 increase in the next iPhone Pro to maintain margins; another estimate puts it at $140 per average iPhone, which Apple could pass through with lower margins but unchanged cash flow. Either way, smaller vendors face an existential problem at $300 ASPs. This memory crunch is a hundred-year flood driven by AI demand, and the eventual drought will not arrive until at least 2028. →
Nota Bene
TD Cowen and Morgan Stanley increase Price Targets → TD Cowen raised Apple's target to $350 and Morgan Stanley took base to $360 with a $440 bull case, calling WWDC a chance to reframe Apple as an AI winner. The new average target is $305 with 34 published targets and 41 analysts following. In 2018 half of analysts also rated Apple hold or sell at the trillion-dollar milestone, and nothing changed. →
Office Hours
What's a billion between friends? → Bob V asked about the Apple-Google deal for the frontier model. People assumed far more than is actually happening: this is a narrow technology license, Google gets no data, and the contribution is swappable. What's a billion between friends? →
Where is the monetization? Follow the compute → Roger asked where AI monetization comes from beyond hardware. Follow the compute: if it is on-device, Apple bundles it; if it is in the cloud through an app or Siri, the user pays a subscription and Apple takes its usual distribution commission. The Services business does not need new economics, and the App Store may show another kink the way it did when subscriptions became dominant. →
Why is Apple selling hygiene? → Greg asked why Apple spent so much time on child safety at WWDC. Safety is hygiene, like plumbing, only noticed when it fails, and almost never marketable. Apple spending fifteen laborious minutes on it was not aimed at consumers, it was a message to policymakers that the custodian is doing its job. →
Asymetric 138, hosted by Horace Dediu and Judd Rubin.
Judd: The World Cup has only just begun, but somehow Horace has amassed 11 yellow cards. This is asymmetric. Horace, why are you being so rough on the refs and your fellow competitors?
Horace: I don't know what to say because I'm not even watching the World Cup. Never mind playing in it. But so, what can I say? First of all, the World Cup is, for me, something kind of very beloved. I used to watch it quite religiously when I was younger, and my family and my father in particular was always a big fan of what Americans call soccer, but the world calls football. And because I grew up in Europe, and I live in Europe now, it was always a big deal. We would kind of predict those first round games, like what the outcome would be, and have a competition with that. And I even went to see, in 94 when it played, I think it was 94, yeah, when the games were in the US again. And I actually went to see a couple of games. Miami and New England or Boston. But the last few years I just haven't been as excited about it. It feels like it's lost a lot of its charm. It's become very expensive. And I don't know if the right word is corporate. I don't think it is corporate, but it has felt more commercial in a way. Which isn't always bad, but I'm just thinking that football is a people's sport, or it's the beautiful game, the game that everyone plays even if they don't have any money. You just need a ball. And many people just don't, barely even use a real ball.
Judd: It's like they make their own. And feet.
Horace: Yeah, you need feet. But when I was hearing that ticket prices were like thousands of dollars and it was so exclusive, it just didn't feel like it used to. And also, the game has become much more defensive because it turns out you can game the game, so to speak. And the games are kind of a little bit less vibrant. But anyway, I'm not an expert. I just kind of don't have the passion anymore for it.
Judd: Okay. Good to know. When we were talking earlier you had said that it's been a watershed couple of weeks for Apple. Tell me more. Why do you think that is? What has been the major life, world, company changing events or series of events that makes you feel that way?
Horace: Well, we finally had, in WWDC, we finally had the kind of, I don't know if catharsis was the right word, but it's some revelation of what people had been hoping for for a long time. Which is, firstly, well, maybe, I hate to say it, but I think it's kind of like two years ago we had anticipated sort of Apple intelligence being something that was going to change everything, or at least bring AI into the world of Apple, and it didn't seem to do so. And now it seems like it actually has delivered on that promise of two years ago. Now, what it did is actually delivered beyond that, but people haven't yet absorbed just what changes will be coming, I think. Because I think, unlike a two-year-old promise, what we're seeing now is an integration that's far deeper, where the operating system is going to change dramatically the way it works for the user in terms of interpretation of their intentions. So I call it intention computing. And it's going to allow developers to participate with AI inside of their apps, and it'll make apps modular for an intent driven experience for the user. So they're reorchestrating the entire operating system and the entire app ecosystem to accommodate intent computing. That's my read of it. And that intent computing has very much been the promise of AI as a new way of doing computing versus touch computing, which has been the consistent interface for almost 20 years now. And touch was going to propagate into voice computing or spatial computing, and now it's intent computing. Now, actually, voice didn't really go very far. Spatial, the jury's still out, and I do think Apple's pushing hard on spatial, continuing to develop that, but it's far more, let's say spatial is far more, I would say, along the lines of what Mac is, whereas intent is much more along the lines of where phone is. What the dream of those who wanted to replace touch was, those who, for example, if you go back to Alexa, if you go back to, what's the Google version of that? You know, just smart speakers. If you go to Siri, even the original Siri, if you go to Humane, which had the notion of a microphone-only interface, maybe with like a mini projector. And even if you go to what OpenAI suggests that they are building, an AI-first device. The assumption behind all of these is that, first, you don't have touch; second, you don't have apps; and that your entire compute is a conversation with some intelligent agent, or the equivalent of a chatbot. And you ask it what you want to have done and it'll do it. By this I mean intent, because it's kind of like you just ask. It seems a bit utopian, because I think that it's not driven by analyzing what people actually do, but rather hoping to replace what they do now with this new way of doing things. Let's not forget that touch also didn't replace the way we were computing before touch. We had applications on our computers, but they weren't apps as we call them today, and they weren't, you know, involving swiping and gesturing. They involved mostly, you know, clicking and typing. So the idea of intent is just, tell me what you want and I'll get it done. And I think, as I said, it's a little bit utopian. It's, you know, remember Star Trek, you know, asking the computer. And yet when you look at what people actually do, they're not in an inquiry mode. They're not inquiring. They're not requesting. They're chilling. Entertainment, communications, they're doing things with their phones which are far more passive, you know, and far more like television than they are interrogatory or trying to be productive with a machine. That's, I think the reason behind intent's utopian vision is that it's created by computer people who think that computers are utility first, and, well, first, second and third. So I find it a little bit, the visions until now have been more or less, you know, not consumer friendly and not consumer accepted. But what Apple's building, in terms of intent, is a layer within the operating system. You can do those things, but at the same time you maintain all the other things that you're already doing. So you'll have the app economy, you'll have the app ecosystem, but apps will also be stitched together into workflows and experiences that would allow you to get things done. So, for example, instead of turning to three different apps to deal with your travel. You'll have an app for booking your flight, an app for booking your hotel, an app for booking your ride to the airport, maybe something more to do with setting your vacation settings in your calendar, maybe dealing with some shopping that you need to do before you leave. Instead, you might get all those things done with a few voice commands, which then will put together, it has to be iterative, so it'll give you back options and you'll go through them, and it'll connect to these apps that you're normally using. And my thesis is that Apple decided not to completely obsolete the app economy because it is somehow easier to replace all that. It isn't. They decided to keep trust and connections with developers and connections with data sets and connections with the trusted entities that are like banking, shopping, all those places you go. Those relationships will be preserved rather than you giving rights to all those things to a new entity that is this new agent. And so for that reason, I think the future that Apple is envisioning is where AI is layered on top of what we already have. That they call the system orchestrator, which routes your queries to multiple AI models but also to the apps that can work with those models and put the solution together.
Judd: That does sound very nice. It also sounds like a lot of, you know, maybe the methodology is slightly different than what's been talked about before, but as you were saying earlier, this is sort of where they seem to be where they were hoping slash promising to be a couple of years ago. But when I think watershed, I think something new. This feels like they're doing some really interesting things, but they're just sort of catching up to where they thought they would have been a couple years ago.
Horace: Well, Siri's gotten better and Siri has caught up to where it was promising to be. I mean, it's not even the way it should have been two years ago. It's where models are maybe as of six months ago. So things have gotten better from that point of view. So Siri has caught up and then surpassed where it was supposed to be. But my observation about intent is that it isn't only, it isn't just we have a new Siri, or we have new image playground, or we have new text creation tools and all of those things that work better that were introduced two years ago. Rather, we have, at the operating system, the orchestrator. And the ability for developers to work with these new Apple foundation models. By the way, there's five Apple Foundation models. Two are on device, three are in the cloud. One of them is hosted with Google. There is training that was supplied, or rather, you know, there was training data that was supplied by Google, and so Google's data was used to, you know, create these models to some degree. Possibly those will continue, that relationship will continue, and there'll be improvements over time also because of Apple and Google kind of partnering there. But one thing to note is that this isn't Gemini, this isn't any of the Google apps, any of the Google interfaces, and the data never leaves Apple's own servers, or what's called private compute. And so none of that was promised two years ago. The idea of the foundation models being updated. The on device foundation models, which by the way require quite a higher level of device performance that two years ago wasn't available. So they've done a lot to enrich this whole thing. And like I said, connections to developer, connections to Google, connections within the operating system, all of this is new. So let's just summarize it as, it's smarter, but it's also far more integrated.
Judd: That sounds great. You also were not shocked at how the market responded.
Horace: Yes. So the market, the stock fell immediately when, let me just put it as precisely as I can. During the keynote event, there were several segments. There was one on child safety, or, you know, safety in general. There was a previous segment to that that was on changes to the core operating systems, broadly speaking, not very detailed and not operating system by operating system the way we used to do it. And then finally Siri came in about two-thirds in, or Siri AI. And to introduce it came Mike Rockwell, who is the new head of Siri AI. He used to be the head of spatial computing, or vision pro actually, and he delivered vision pro and then moved to this role. As soon as he began speaking, and I mean within seconds, you know, they introduced him, he said hi, I'm here to introduce Siri AI, probably between the second and third syllable of Siri AI, the market fell. I was watching it. I was watching it and it had been up, up, up throughout the anticipation. It had been up for a long time before even the event occurred. But during the event, you can see it keep rising. And then, as soon, I think $317 right before Mike began speaking. And I of course blame Mike Rockwell for this. I mean, his outfit was terrible. His outfit as soon as he comes, not cool. I don't know, it was his haircut at the time, but clearly as soon as he began speaking, it felt like straight down and then it kept going and going and going to the end. Over the next couple of days it fell over twenty-five dollars. I mean, it's, but if the drop started as soon as he said Siri AI, is it just that—
Judd: people are freaked out at the name. If it was a different name, do you think it would have happened? What was the signal? Or did it just hit a number where it was far beyond what you've always described as a point. Many people said, you know, the market's got nothing to do with the event, the market's nothing to do with Siri.
Horace: I saw these feedback, as I had posted this on the social media, and I said no, I was watching, it was very precise. But notice that it wasn't based on what he said because he hadn't even begun explaining. He hadn't even done a demo. It just started falling as soon as, okay, now the presentation begins. It's time to sell, which is indicative of the phenomenon that's known as buy the rumor and sell the news. And the thing is that usually you don't know, but some people, you don't know the timing, so they'll say, well, as soon as the keynote begins, or as soon as the day begins of WWDC, people start to sell. Why not? But here they start to sell only when this Siri announcement was finally made. And it was spectacular. I've never seen a better representation of just sell the rumor, sorry, sell the news, because, you know, Siri, it doesn't matter what it is, they're announcing AI, they're doing all the things that everybody anticipated. It's time to sell, and it just kept going and going and going. And then days later people are trying to explain the quote unquote market's reaction, or Wall Street reaction, or investor reaction, or analyst reaction to WWDC, because it had kept, you know, it had fallen so much.
Judd: Will he be allowed to present again?
Horace: Yeah, exactly. I don't know. But of course, when Steve was on stage back in the day, we had calamitous, catastrophic falls similar to this. One of the worst was when he announced the MacBook Air. I have no idea, but I think the stock fell 20% in the next few days. The very first air, the launch of that brand. It's not explainable because it is entirely driven by some kind of momentum and market, you know, markets are not pricing at that point. What they're doing is, there's an anticipation that other people will sell, so you sell. So it's an avalanche of anticipations. And the same thing before, this is an anticipation of buying, so you buy. So it's all based on what other people might be doing, and what other people might be doing based on what other people might be doing. So it's kind of recursive, and it's a news cycle that leads to this kind of, you know, amplification, on the upside and on the downside.
Judd: So, but again, I thought this was... other than that, how was the play, Mrs. Lincoln?
Horace: that the kind of, these play, these types of games are over for Apple. It used to be much more prevalent, used to be much more common, but it became, let's say, less of a game. But it's interesting how the market itself is so hyperactive right now. We've had these international issues, we've had inflation issues, we've had consolidation or concentration inside of the tech sector. And so it just seems jittery. So my point though is, I kind of felt, because it was back to this game, I found it strangely comforting, because, hey, look, Apple is selling on good news. And the more the news piled on, by the way, throughout the week, you know, WWDC was still running. There were more and more events, more stuff coming out, there was more interviews with the executives and the picture of Siri AI, with, you know, the whole picture of the integration I've been speaking of, the relationship with Google, all those got fleshed out and it sounded better and better and better. Most analysts or whoever got their hands on the software said, wow, it really is pretty good, even being, you know, great, some people would say. And there was a lot of applause from the people watching the performance here of the product. That we're gonna need a lot more powerful hardware from Apple to take advantage of all these things. Obviously that is a positive for the business. So maybe that is not what was expected, but now we have a precision about exactly how many current devices can take advantage of the full scale of this improvement, and it's not many, so a lot more hardware will be needed. So my reading is, as an observer, as an analyst, there was kind of, I would say there wasn't a huge excitement during the event, because it was not their greatest event, especially taking so much time on the safety side of things, which isn't, it's, safety is a hygiene thing. You don't advertise that your system is more hygienic than ever. Just like people can't sell cars because they're safer, that is a not a purchase decision driver. So from the defense, yeah, well it works for one, but not many car makers. So it's flat, it's kind of, for me the whole keynote was a little bit flat. Also, by the way, the Siri demos were slow because they weren't faking it, and therefore that is exactly how their action happens. So from a snappiness and entertainment point of view, it was a bit like, it felt like there were a couple of beats off, you know, in the quality of the video. For me as an observer, again, it was like, okay, this is decent, this isn't great. But then as time after the event passed I was getting more and more and more impressed. Okay. The market went the other way. They hyped it up way in advance. They sold it deeply afterwards, ignoring all the interesting stuff coming out of WWDC. Historically though, that's how WWDC has always been sold off because people would always anticipate more than what was happening. In this case, they delivered actually more than they expected. Most people expected, and yet it's still sold off. And now it's bottomed out and it's probably gonna start recovering. But you know, there's a lot of cynicism around, as usual. And that's, again, encouraging to me in a way, because it means Apple works as an underdog, you know, it works better when it's underestimated. And it's great to see the market throwing away good, you know, the baby with the bathwater.
Judd: What else jumped out at you? I mean, not only just the keynote, but there were other events throughout the week and all sorts of other announcements. Was there anything else in particular you wanna touch on, for Tim Cook's last WWDC as CEO?
Horace: Well, a couple of things have been in the background. The news coming out of the analysts following this, the market for phones and computers and PCs has been, and this isn't getting a lot of highlights, but the market, because of the memory crisis, the market for computers is going to be down this year and the market for phones is going to be probably the worst year anyone can remember. I mean, we're going to see 20% drop for a lot of the vendors out there. And some may actually be almost in a state of, you know, economic or financial distress. Like, who, it's that bad. These are the smaller so-called budget phones, the lower price points of Android, okay. They're just not able to get, you know, any memory, and they're not gonna be able to ship their market shares.
Judd: Would now be a good time for us to introduce an Asymco phone.
Horace: Yeah, sure. It'll just be an iPhone with an Asymco logo on the back and we'll just charge double. But the idea of the market being in serious trouble is contrasted with the fact that Apple is, the same analysts are projecting Apple to be growing. Apple grew in the first quarter, projected equal growth in the second quarter, which is ending June. That growth would roughly be in line with the first quarter, which was like in the twenty percent plus. Now this is at a time when most of the vendors are seeing declines, and then the analysts are suggesting that declines will accelerate into the end of the year. So this sounds to me like a catastrophe. So while the market for smartphones is collapsing, Apple is somehow still increasing its volume. Now we don't know if it's going to actually continue their rapid growth into the second half of the year. But because it has had such a great success with iPhone 17, and because there's new product coming out, probably of the, you know, high-end, maybe a new version of air, a new version of fold, a new version of the pro products. And then the anticipation that 18, base 18 is not coming out until early next year means that 17, base 17 is gonna run through the end of this year. All of this is probably going to increase Apple's revenues in the iPhone segment. The NEO is doing amazingly well.
Judd: But time out, timeout. So did you just say you don't think that the iPhone 18 is gonna come out in the fall?
Horace: Well, that's what the rumors are saying, and they've been saying this for a while. The iPhone lineup into two. Now they already have an iPhone, the S, sort of the low-end version of the iPhone, was a spring product, springtime. So that started with the iPhone, I think it was C back in the day, and then became the S. And now the idea, I think, is that they're actually going to take the standard base model, okay, which is now maybe the mainstream model, and move that to a spring launch and keep the, by the way, there's a reason why in the December quarter the mix of the high-end product is far overwhelming. There's a lot more of the premium stuff sold, and not many people are rushing out to get the latest of the mid or low range of the iPhone. And they know this, and they've known this for a while. So it also makes sense to move around China a little bit. China holiday is in first quarter. And so moving the 18, and possibly also for India, I don't know when the Indian holidays are. But if we can move something off into the spring, it might be an interesting split. Now I don't think it's gonna affect sales that much because, like I said, there's not only a bias towards the high end, but we're going to have more high end than ever before. If a fold is coming, then the high-end lineup will be the pro, the pro max, the air, and then probably ultra will be the branding for the, so we're looking at four high-end iPhones we'll be launching in the fall, with hints of what might be the 18 base model coming in later. And thus also maybe concentrating a lot of the buyers to saying, okay, since this is what the latest is, we're gonna go with one of those four options, driving the ASP higher, and so on and so on. So yes, it's a radical departure, but it's been rumored for at least, I'd say, a year, maybe two years.
Judd: Well, I guess a couple things. I mean, in American football, not soccer, but in American football, there's a saying that when it comes to your quarterback position, if you have two starting quarterbacks, you really have no starting quarterbacks. So if you have four premium phones, don't you have zero? I mean, like, they can't all be premium. They can't all be. They're just expensive.
Horace: Well, you have a good point. And historically, you know, Apple's been about a simple and clean and clear product portfolio. You know, famously when Steve came back he eliminated half a dozen, whatever, there were so many different versions of back. He eliminated a lot of them and then introduced the iMac and it became, as you say, the quarterback, the leading quarterback. But with the iPhone over the years it's kind of gotten a little bit broader. And you see this in what, the so-called, my stairway to heaven is my, the breadth of the products available. Of course that includes different memory configurations, so that there are far more now than there used to be. Used to be one iPhone or maybe two, and now we have like about 15 with all the memory configurations, and not to mention the color configurations. But as far as the so-called premium, now there's this puzzle around fold, and I must say I'm a little bit confused by this product. I think we talked about this before, but I think when it opens, it kind of starts to look and feel a lot like an iPad. Like an iPad mini actually. And I'm not sure that people want to carry an iPad in their pocket. Of course, when closed it's a phone and it feels fine, but it is, the iPad is not necessarily, maybe it'll become, because if it is with you all the time, it'll become far more attractive for you to interact with the iPad type of interface. But I will say that one of the rumors about why they're doing this is that there's a lot of interest in China. And it isn't for software reasons, but rather because it is such a, it's such an event, it's such a theater, it's so theatrical, right? When you have a machine, a moving object, it's a different thing than something static, and so there might be a preference for something that shows action, that shows clever mechanicals. And that could be one of the reasons that market is appreciating it. I'm reminded, by the way, of the debate back when I was at Nokia, that there were flip phones that were very popular in the US. And Nokia resisted going to a flip phone. They had something called a monoblock, or the candy bar. The candy bar phone was the way Americans called it, but inside Nokia we called it the monoblock, and it was better by every possible thing you could measure. It had more durability, it had longer battery life, it was more durable, it was easier to use. You didn't have to do something to get something done. And it just was cheaper too. Obviously you could make it fancy and expensive, but it was cheaper to make and cheaper to manufacture and so on. So everyone, all the engineers were scratching their heads. Why Americans preferred flip phones. And Motorola launched the Razr, which was a super thin flip phone, and that went on to become the number one world bestseller in the phone space. So much so that, you know, they make dozens of versions, and eventually they relied so much on it that when it began to decline the whole Motorola failed. I mean, the whole company essentially collapsed. Strange story, but you know, you have a hit product and a couple of years later you're out of business. That was the story of Motorola. But it wasn't just because it was a fold, it was because they, I don't know, they made a lot of mistakes as well. But flips were very popular. And so when we try to find out why people wanted a flip phone, it was that this mechanical action felt like, I don't know if people felt like, well, that's one idea, but people felt like it's much more satisfying. It's satisfying to open it and answer and close it, to hang up, and especially if you don't like whatever the conversation was, it's satisfying to just hang up on something with violence. So it was, you know, as some people even in Japan, it was common to have tiny little flip phones with little antennas. So you had to flip for the phone and then extend the little antenna to make it work. And that's outrageous, you know. You have simplicity on one side, you have complexity on the other, and people are voting for complexity. Now, I don't suggest, and this is one of the reasons I think people reject, and Nokia, or sorry, Apple rejected a lot of these moving origami, you know, have your laptop flip inside out, have it be an iPad or a tablet with a pen. Do all these things as if it's kind of a convertible. But here we are. So maybe after, you'll know the answer to this question.
Judd: I won't. How popular are the current folding phones from, you know, Samsung or the other manufacturers? I mean, are they that popular?
Horace: Not that popular at all. They've been doing it for years.
Judd: Yeah.
Horace: Partly the reason they're not popular is that they are flimsy, and there's a visible crease, and they're gimmicky and cheap. The, but cheap feeling, but very expensive to buy, and this is the problem. And it isn't a killer function, what do you do when it's open? Well, you have a bigger phone screen, so maybe you watch videos or something. So it hasn't come with a killer app, if you will, for the bigger screen. So this is what's interesting about Apple, is whether they will, first of all the form factor is slightly different. It's shorter in height, and then when it opens it's much more like, like I said, like a mini iPad. And I think once it's in iPad mode it's going to be probably usable for entertainment and other things in a much more intuitive way. Maybe the keyboard and other things will be easier to use. I don't know what they're going to introduce in terms of software, besides just making it an iPad. So from Apple's point of view, they are also getting rid of the crease. It probably mechanically will be nearly magical. Probably they'll solve a lot of the durability issues as well. So there's a lot that they can fix about those products. And then there's something that needs to be done on the software side to make it more attractive and usable. So yes, there's room to improve, but it's not clear that people are craving this, except again, maybe culturally for various reasons. I do believe that $2,000 will make it very, very niche. You know, it'll cost more than a MacBook Pro.
Judd: This just feels like, I don't get it. I don't get it. This feels like it's like the cube. You know, like, sure, you can have a beautiful acrylic cube. But, okay.
Horace: But this is why I don't like to speak about rumored products, although there's a lot of evidence for this one. But no, I brought it up because I think the portfolios, the split between the two. I mean, we're talking about watershed, okay, and we're talking about how the market is contracting for phones. Into this, Apple is expanding its portfolio. It's going to launch a lot of new product in the fall. There's a lot of expectation that they might, if not volume wise, but at least in dollar wise, going to expand, they're gonna grow their business. And their market share probably will increase substantially. This is where it comes down to. Historically, Apple's had 18 to 20 percent of the phone market. A lot more in terms of the install base because the phones last longer. But with this crisis in memory, and with this market expansion in product, the lineup and the new spread of launch dates, it's possible that Apple is going to reach 22 to 25% market share in devices, or, I should say, in iPhone. Okay. In the phone market. And at the same time, in the PC market, we're looking at 10 million NEOs this year. I think the market share in the phone, it's much harder to make an impact in the PC market because Apple's share is relatively limited. You know, closer to ten to fifteen percent. And so, but they probably, we're going to see a couple of points increase there, and we're going to see a couple of points increase in the phone, and this is going to be going down in history, the twenty twenty-six, twenty twenty-seven time period we'll probably see a substantial increase in market share for Apple. We'll look back upon this year and ask what happened for that change to occur. And that's why I think now, this last few weeks we've had this WWDC with AI. And we've had the memory crisis, which also is caused by AI, you know, restructuring the phone market. Some analysts are suggesting we're not going to see a recovery to 2025 levels of phone sales for three to four years. That's three to four years for Apple to continually beat down their competitors. And Ternus is going to take over just at this moment when there's probably this market shift happening. I think we might, and I've been sort of pulling punches on this, but we might be looking at Apple doubling down on a market share strategy that will see them shoot up significantly. Something that we've been thinking for 20 years they might do, but they haven't done yet. They've always been kind of happy with their limited market share, but obviously extremely high revenue share and extremely high profit share, to the point, by the way, where their profit share might end up being nearly a hundred percent, if not actually one hundred percent, going into the end of this year. So this is why I think the watershed is maybe AI, but we don't yet see the impact of AI on the bottom line. But we're seeing evidence that the market share game is changing. Because they made this decision probably two years ago to split into a fall lineup and then a spring lineup. Yeah. I think the only thing is that it's compounded by the memory crisis. That's affecting, by the way, it's, let me clarify, it's less of an effect on Apple because they manage their supply chain very well. They're also not squandering a lot of this memory on cheap product with no margin. But it's also not affecting Samsung as much because Samsung also has more of a mix of premium product. They sell lots of cheap, but they can always retreat back into the premium, and they then drop a lot of low-end product and they can still be in the business of selling phones. But Samsung is doing very well selling memory. They're far more profitable selling components than they are selling phones. So for Samsung to actually exit the phone business would probably be a blessing, because they'll be like, well, thank God we don't have to deal with that low margin, typically negative actually on many of their phones. That's interesting. But it's all the other guys, the Vivo, the Oppo, which are, by the way, numbers three and four in volumes. Nobody's heard of them because they're China mainly, and they sell in Africa and they sell in Middle East and they sell in parts of Asia. But globally those are the four, the two big brands. There's some other one, oh, in India I forgot to mention, and there's a lot going into these markets that is at two hundred dollars price points. And those $200 price points are no longer sustainable with the cost of memory that's out there. So what we'll see is contraction, Apple's share goes up. Premium, what they call premiumization, premiumization, I don't even know how to pronounce this, but the idea of portfolios going to the high end even if you're not an iPhone, that's been happening for a while. So maybe we'll look back upon this year again as something of a, I would, you know, market discontinuity, cracks, it's something cataclysmic, it's something substantial.
Judd: Well, it could be. It could be. I mean, it's interesting to me in that, I think what I can't get away from, and I'm curious if they care about this at all, but just because something is expensive doesn't mean it's special. And I don't know what, what do you think they think is special about the iPhone at this point? I mean, obviously it's the best phone.
Horace: But this is a syndrome that occurs every year. But people are always remarking about the very, very high end of the market. So the premium iPhone, when it reached one terabyte and it reached a thousand dollars, people freaked out and said, oh my god, the iPhone is so expensive, why is the iPhone, they're just gouging, da-da-da. Well, again, that's the top of that staircase. It is the highest of many products, but if you look down into the middle of that distribution, of that range, that's where the most popular phones still sell. They're selling at, you know, six to eight hundred dollar price points. This is the bread and butter iPhone, whatever is the right analogy. That is a mainstream product that's not going away. There's also, by the way, low-end versions, and there's last year's versions that are still for sale. Those end up being the cheapest. And so all of those things are gonna carry on. What they're separating is that the launch window that used to be fall for Christmas purchase, which, by the way, Christmas is gifting. So when you gift people, you want to always show maybe a little bit more of your generosity. So the gifting process typically also attracts the premium. And then the students and everybody else who needs to buy medium grade phones, they're still, but the 17 is going to be still for sale. It's done very well this year. It's gonna continue next year as the low-end product. The 18's coming out a couple of months later. No big deal. It's just that from a marketing point of view, from a ramp, the production point of view, they probably were seeing this already, that the mainstream phone and the low end phones were doing better later in the year, and that is later in the next year versus the end of the year. So I don't think this is a giant change in how Apple thinks about premium. I think it's just a cadence question that some people said, which I find incorrect. They said, well, the seventeen is doing so well they're gonna keep it going a couple of months more. No, no, no. This was decided years ago, but they're going to start to launch in a kind of a two-phase process. And, by the way, I think it keeps the excitement of the iPhone moving into spring. Because the problem they've had is that people would see new iPhones in the fall and then there'd be nothing new and the competitors would take advantage. Point of fact, Samsung always launched six months out of phase with Apple. So if Apple had a big event in the fall, Samsung would launch six months later, literally, so that they would come in when Apple was, you know, being long in the tooth. So now Apple suddenly has fresh product coming also at the same, you know, not quite six months, but into that Samsung cycle, and it's going to drive excitement. And as I said, China, their holidays are different than ours. So I think there's some value to this staggered approach. You know, if I were to design it, in fact, from the very beginning I would have probably said, yeah, why don't you launch around the whole year so that people are always looking forward to something. Again, Steve was the one who said, no, we do once, simple, yada yada. But it was because of clarity, it was because of the simplicity, and it wasn't optimal in the case of the five, yeah.
Judd: Well, but it's also an event. It's also an event.
Horace: It's also an event.
Judd: And what they had been doing over the years is releasing new colors in the spring, but maybe that just wasn't enough. Anything else before we sign off?
Horace: Well, again, the AI thing is one of those things that we've been waiting for two years. But we're gonna probably have another ten years before it propagates to most of the people who are using Apple phones. So let me, you know, a lot of commentators that I think are smart about this have been saying, hey, it looks like AI will be first experienced by the majority of people through an iPhone. And that's very profound. It's not just that, yeah, using a chatbot is not in and of itself an experience. People, I mean, some people are addicted to it, some people are using it productively, some people are becoming mentally ill, whatever. Yes, but the majority of people, your mother, my grandmother, or, well, I don't have one, but, you know, these types of laggard users or mainstream users are probably going to experience AI through their iPhone.
Judd: Yeah.
Horace: And that's, you now, we're now seeing just what that experience might end up being. It's gonna be a Siri and it's gonna be apps. And as a final line, the economic model, everyone's been thinking that you pay for AI, you pay ChatGPT monthly, you pay Anthropic, or you pay whomever. What Apple's probably going to do is not charge, unless, maybe you have a new tier of iCloud accounts, that, you know, if you're a frequent user you might hit a limit and then you'll be invited to pay more. But also the developers are going to be probably charging extra for these types of AI functions, and so what that goes into is services, almost without any drama, without any change in business model. Suddenly Apple will be seeing an acceleration in services, which has been the growth story for forever now. And I'm pretty excited that, it's almost, it's almost, what's the word? It's almost anticlimactic. The financial model of AI is anticlimactic. It's there, there'll be lots of revenue, but it's not even mentioned by Apple. They never talked about it in WWDC. Fascinating.
Judd: Horace, this has been great. Thank you for taking the time today. Thanks to everybody listening. We will be back with you very soon on Asymmetric.