Asymco

Asymmetric Intelligence

Latest from Asymco

  1. The Android (in)adequacy: How to tell if a platform is good enough

    Research · 97 comments

    About 10 years ago I met an advertising executive in New York who explained the difficulty of advertising a new brand of deodorant to consumers. “Most people never change their deodorant,” I remember him saying. “They pick one brand when they are young, and stick with it for a long, long time. If it works, why switch?”

    The same theory can be applied to customers who are making the switch to smartphones today. Once they have picked a type of phone, whether it’s Apple iOS, Google Android or something else, it’s difficult, and often expensive, to switch. Consumers become comfortable with the interface and design of the phone and the apps they have purchased on that platform. If it works, why switch?

    Many Smartphone Customers Are Still Up for Grabs - NYTimes.com

    This quote says a lot. The notion that customers remain captive to a platform is well understood. After all, it seems impossible to get people to switch out of Windows (or Mac or iPod). Platform vendors are aware of this as the land grab for users seems to be running at full pitch.

    However, there is a critical condition described in the quote above: "If it works, why switch?"  The condition which keeps users loyal is that the product they chose is good enough--i.e. "it works." That's a symptom of over-service and commoditization. If a product, like deodorant, is good enough you won't be tempted to move to another brand even if it's marginally better since the new brand has switching costs in the form of uncertainties ("Will it be as good? What if I don't like the smell? etc.) People are inherently conservative and you can't compete with comfort and familiarity by launching a marginally better product.

    So with that in mind, why is it that millions are switching mobile platforms?In this blog I've cataloged the massive shifts occurring away from mobile platforms that have been around for years with deeply entrenched user bases. Microsoft's Windows Mobile, Nokia's Symbian, Palm's PalmOS and RIM's Blackberry have collectively lost tens of millions of users. A net of half a million Blackberries are being abandoned in the US every month.

    So we would need to say that the condition of "it works" or being good enough was not met with those platforms. The attraction of something better is clearly greater than the switching cost.

    So this highlights a good test for how to tell if smartphones are good enough: If users are fiercely loyal with a given platform then it's probably good enough but if they are willing to switch (i.e. disloyal) then it's probably not good enough. It seems like a trivial observation but it's a very important clue to the bigger question of whether we can "call the end" of the market. Just like it would have been premature to call the end in 2006 when Symbian and RIM seemed unbeatable, it will seem premature to call the end now in the event that a significant innovation is yet to appear.

    The correct calling of the end has profound investment implications. Do you (like Microsoft) invest billions in a new platform if you know that there is no more room for entrants? Should Samsung bother with Bada or HP with WebOS if the game is already over? Even more, should Apple even bother to improve iOS if they have no shot at switching a billion likely Android adopters. Why not just nurture the current installed base and work on building walls and moats around them?

    So with this hypothesis in mind, it makes sense to analyze whether Android or iOS, the current presumed champions, are "good enough" on the basis of how often users switch out of them. My bet is that neither is good enough and that there will be increasing churn between platforms. I imagine that Android is less sticky (and hence less than good enough) based on app consumption but there is little evidence of churn because most phones in use have been bought less than one device generation ago. More importantly, there have been few opportunities yet for switching as many Android buyers don't even have the choice of other platforms either due to where they live or how much income they have available.

    To really tell where we stand, we would need to collect stats on switchers to know just how satisfactory the platforms may be. Remember that a choice of a new deodorant on the same shelf at nearly the same price is the test for loyalty. For an adequacy test we need to see better distribution and more choices for consumers. It's still very early even in the US for any conclusions to be drawn about the adequacy of Android.
  2. Subscribe to Asymco One for full access to our research.

  3. How much is an iOS user worth to Apple? About $150. Every year.

    Research · 48 comments

    During the last WWDC Apple revealed that there were 54 million active Mac users. If we look at the history of the product we can see that it took about 5.5 years to sell 54 million Macs. If we assume therefore that the average lifetime of a Mac is 5.5 years and knowing that Mac sales generated revenues of about $73.8 billion then we can estimate the average revenues/year/mac user: $250.

    Repeating the exercise with 180 million current iOS users who purchased about 200 million iOS devices and assuming a life span of 3.5 years gives the average revenue/year/iOS user of about $150.

    These are recurring figures. If we assume these users are loyal then they will likely spend this amount indefinitely and each additional user will be worth a similar amount.

    So, for example, if we assume that the number of Mac users reaches 100 million then we can also assume that they will generate about $25 billion/yr in recurring revenues.

    Likewise, if we extrapolate growth of iOS to 500 million users then we can assume they will generate $74 billion/yr in recurring revenues.

    Adding these together gives a potential recurring income level of $95 billion/yr for installed base alone (excluding iPods, Peripherals, iTunes apps/songs, and Software sales.) Today that figure is about $40 billion/yr. [1]

    Interesting valuation exercises can follow. [2] It would also be interesting to perform a similar analysis for other vendors/platforms.

    ---

    Notes:

    1. Note that actual sales are considerably higher than this figure as new customers are added. These figures should be considered "baseline" sales.
    2. Thanks to a kind reader for suggesting this line of analysis.
  4. Subscribe to Asymco One for full access to our research.

  5. Nokia a trop écouté les réseaux télécoms

    Research · 70 comments

    My thanks to Robert van Apeldoorn, journalist for Trends Tendances Magazine, for asking good questions. My responses are reproduced below. The article (in French) is titled "Nokia a trop écouté les réseaux télécoms" and can be found in the June 23rd edition of the magazine along with more details in the article "Comment Nokia peut-il renaître?".

    -About your post “Does the phone market forgive failure”, that puts forward the idea that all mobile device vendors experiencing losses never really recover… It seems that this possible “rule” is more severe than in the computer industry. If Digital Equipement, Compaq, WordPerfect did fail, IBM and, yes, Apple, did survive failure and rebound strongly. Do you think that there is a difference between the industries? What makes the failures more lethal in the mobile device market ?

    The observation is unique to the mobile phone market and even there it's only an observation not a rule. It could be that Nokia will be the first mobile phone company that will recover from severe crisis, but history shows it to be very unlikely. I try to shed some light on the reasons why it's unlikely and what makes the mobile phone market so unforgiving. I think much of the problem rests with the fact that mobile phones are sold indirectly, through intermediaries who are amplifying both success and failure. A company like Apple was able to recover in the computer industry because it launched new products like iPod which could be sold directly to consumers. It had to convince the consumer and only the consumer. Having to convince a distributor, retailer, value added reseller, operator and consumer would be much more difficult. These intermediaries are "institutional" buyers who are risk averse and have low tolerance for untested ideas. Institutional buyers need to think about dealing with other people's money not just their own so they are doing the right thing from their point of view.

    Nokia needs to persuade first operators, then distributors and then consumers that its new products are great (even though maybe the old ones were not so great.) That's tough. Apple works in the other direction. It creates consumer demand then "sells" that demand to the intermediaries as needed.

    These intermediaries (which Steve Jobs famously called "orifices" to the market) amplify the success and failure of a company. For a long time after a product may lose favor with consumers, it will still be sold out of momentum of the channel. But it works the other way as well. If you're out of the channel, getting in is much harder even if the product may have favor with consumers. This is Microsoft's problem with Windows Phone. Surveys show that it's well liked by users, but because Microsoft relies on a long chain of intermediaries, it's still very hard to get started. Microsoft (and Nokia) rely on momentum to carry them once they get some traction and they plan to spend a lot of money ($ billions) to ensure they get some traction.

    -You are absolutely not optimistic at all about the Microsoft partnership (see “in memoriam” post). What could be the best solution? To enhance Symbian platform? Go for Android?  To create a new market with a new kind of device (cf book “How new ideas can win fast”)? Or to go back in the tire business ;-) ?

    I only observe and record data and then try to have a theory of why it happens that way. The empirical data shows that Microsoft has been very unsuccessful with mobile. Their partners seem to all have failed and the list is long. So the question is why. Is it just bad luck? Is there something wrong with management? Is it that perhaps there is a failure in strategy or business architecture?  All these are possible hypotheses but I believe the problem is that Microsoft has chosen not to integrate products and to rely on intermediaries at a time when that strategy leads to uncompetitive products. One can understand why they went with this strategy: They believe the scale of the market is so large that they cannot address it like they did with Xbox (building their own complete solution). However, that also means that they are likely to be uncompetitive during the time when integrated products/ecosystems are still not good enough and can iterate more quickly to capture the market. This was true for the iPod where Microsoft tried to license technology to device makers. It was true during the time of Windows Mobile when Microsoft's OS could not compete with either Blackberry or Symbian and it may still be true today with iPad which redefined what a computer could be.

    -What and when, precisely, Nokia did fail to understand how to be remain the market leader and innovator?

    I think the answer goes beyond the failures in execution or software development. Being late or sloppy with Symbian evolution is a symptom not a cause of the failure. What Nokia failed to understand is that software and data-oriented products would be built and sold and valued differently than voice-oriented products. Nokia listened very carefully to its best customers, the operators. Operators saw data as a sustaining improvement to their core business and steered Nokia into building "voice-plus" products. Every technology that came out of the laboratories was used to enhance the phone *as a terminal* in a network. Nokia never framed the product as a computer using the network as an accessory the way modern smartphones are valued (or if they did as with Maemo, it was a half-hearted effort). Users today are glued to apps and local media storage and see network access as a necessary inconvenience. The network is only valued in terms of being available.

    The re-framing of the device from being a terminal to being the center of user's focus is the "disruption" which is sweeping aside all the incumbents in the phone space. They all did what was expected of the best managers: they listened very closely to their best customers. That also leads to blindness when the industry itself is being ripped apart by disruptive forces.

    -In many aspects, Nokia developed many innovations (email on the phone, music store, smartphone with applications, tv on the phone,..). I remember visiting a Nokia exhibition four or five years ago, in Nice, with a broad and incredible new services range that I almost never see on the Belgian market. Many of the innovations were related (dependant) to a deal with telcos, as network device vendor. Blackberry (RIM) or Apple were more successful. Is it because they had nothing to sell as network device vendors ?

    This is answered by the previous answer as well. All of Nokia's services were designed to help operators improve their business. Operators were the best customers and they ensured Nokia would sell large volumes. But consumers did not see it that way. When a competitor came with an alternative, consumers defected en masse. By then it was too late to change the strategy. It takes years. Nokia still perseveres with this operator-first strategy. Elop continues to say they will do what operators need first. The first thing he did when on the job was visit every major operator. The decision on Windows Phone was based on whether operators saw it as a viable third alternative to the iOS/Android duopoly. Strategy is a matter of priorities not capabilities.

    -How is the Nokia strategic problem perceived in Finland ?

    The problem is very deeply felt in Finnish society. Nokia was a source of pride for the country and also a large employer both directly and indirectly. I think the impact is felt more psychologically than financially. There was a sense of betrayal when Symbian was publicly "terminated". Many people criticize present and past management, but I think that anger is misplaced. The failure of a company rarely comes from the failure of character or intelligence. It's usually a failure of being too rational, too reliant on best practices. What Finns need is a dose of independence in thought and a re-assertion of their willingness to take risks.

    The Finnish character is one of independence and perseverance in face of adversity. If Nokia loses its independence then it will need to deal with a lot more adversity. I believe however that innovation will continue. Case in point: Rovio, the maker of Angry Birds is a Finnish company.

  6. Subscribe to Asymco One for full access to our research.

  7. The iPhone at four; growing up or just growing?

    Research · 74 comments

    Ever since the iPhone launched four years ago (to the day), the question on everyone's mind has been: When will Apple expand the portfolio to reach into all market segments? I remember thinking in 2007 whether it would be in six months or a year that they would create a "mini", "nano" and "classic" line-up which served them so well with the iPod.

    Apple however took a different approach. To their credit, they focused on the platform and built a consistent experience around a fixed screen size to nurture an ecosystem. They also improved the power of the device so that experience would improve to be better and more robust. In other words, they treated every iPhone as not being good enough, needful of every megahertz of power, every pixel of screen and every minute of battery life. They polished the OS constantly and added APIs by the thousands.

    In other words, they acted like a computer software company, not like a "device vendor" or like a handset manufacturer which was everyone's (including mine) frame of reference.

    Having expanded from iPhone to iOS and built the platform into non-cellular centric computers like iPad and iPod touch, they clearly showed a nonchalance about the operator channel and the amplification power it offers (an amplification which comes with a hefty price of dependency and strategic illusion.)

    But the mind always wonders back to the question of portfolio. Now that the product is maturing, the hardware is getting nearly "good enough". Perhaps even Apple might now consider letting go of the "frontier" of what's technologically possible and consider expanding its reach to the broader audiences it has willfully kept out of reach.

    And broad they are.

    Based on data published by Deutsche Bank and the ITU, we can calculate roughly how many customers Apple's current iPhone positioning has left unserved. I chose to use pre-paid/post-paid split as a proxy for unaddressed/addressed. This is an imperfect proxy but a pretty good one as most pre-paid subs see a full price for the iPhone (retail around $700 to $1000) vs. post-paid customers seeing a price of $200 or below. The $200 happens to be an important psychological price inflection point where volumes increase dramatically.

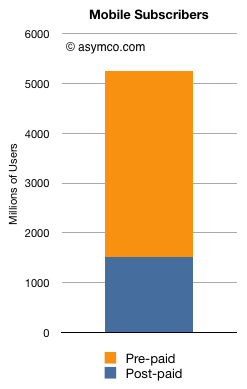
    The first chart shows the global split between pre-/post-paid subscribers as of 2010. Roughly 1.5 billion are post-paid and 3.7 billion are pre-paid. That means that nearly 70% of the world is not being addressed by the iPhone as it currently stands. Put another way, a shift in positioning might result in a 250% increase in addressable market.

    Tim Cook alluded to this in the last conference call when he said pre-paid markets, especially in China, are huge with share figures "starting with a nine". He also said separately that they would not be ceding any market--a hint if there ever was one, given the broadening of Android into previously feature-phone price bands.[1]

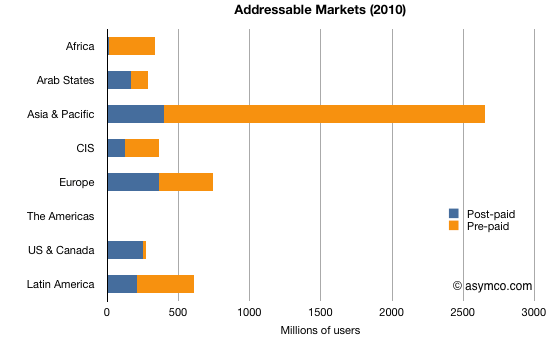
    We can even see the situation more clearly on a regional scale. The following chart shows the same pre-/post-paid split by region.

    You can visualize the iPhone having spent the last four years penetrating into the blue areas of the chart through the expansion of carrier agreements. With half the US & Canada area being finally filled in this year, most of the blue is now more-or-less within reach.

    Given the constraints on production, and given the improvements in the product and the improvements in the hardware (learning curves and price points) it may mean that Apple could finally be turning its attention to those orange areas.

    The time may be soon at hand that maturity coupled with limits of organic growth are leading the four-year-old iPhone to finally be re-defined as more than a post-paid skimming entrant. It may be time for the iPhone to more than just grow. It may be time for it to grow up and take on the whole market. Five billion people are waiting.

    ---

    Notes:

    1. Contrary to a commonly held belief, Apple does not shy away from market share. In the case of the iPod and even the original Apple 2, the company sought and obtained the top share ranking. In fact, the decision to pursue share vs profit is "context sensitive". Steve Jobs, at least, thinks so.
  8. Subscribe to Asymco One for full access to our research.

  9. Capital.bg | Nobody wants to buy RIM

    Research · 24 comments

    Технологии и наука | Хорацио Дедиу: Никой не иска да купи Research In Motion RIM - Капитал.

    My thanks again to Andrian Georgiev for interview questions [Bulgarian] related to RIM. My answers to his questions (in English) are below:

    Q: What should RIM do to reinvent itself? Should it stray from its business-oriented image?

    RIM had begun to move away from a business image already in 2005 or so when it started its "Pearl" brand and a consumer-oriented strategy. The company probably foresaw that business customers would not be enough to maintain the growth they had become accustomed to. The strategy has led to a growing popularity in Latin America and other regions like the Middle East where the product is used as a low-cost alternative to SMS for avid texters. Even in the US, many teenagers use Blackberries instead of iPhones because they can use it for the BBM service (at a lower cost). I believe that it is not coincidence that iMessage was launched.

    The company's salvation is not in branching into new markets but in establishing a credible platform. When Nokia announced that they would be the "third option" after the iPhone and Android ecosystems, they did not even mention the Blackberry. The fact that Blackberry is not seen as an ecosystem is the root of the problem.

    Q: How should RIM accelerate the introduction of QNX?

    QNX is a solid operating system and I believe RIM should have begun developing with it much earlier. By waiting long after the iPhone launched (and even after Android) to upgrade its OS, RIM missed a great opportunity. The foothold market the company had was wasted by not leveraging it into building a mobile computing ecosystem.

    There is little that can be done to move any more rapidly now. Product development cannot be done any faster. What the company could do is to very carefully define why QNX based products are better than the competition and not rely on specifications. In other words, what jobs does their platform solve for users that current solutions don't address? I note that this is the problem with the Playbook. It's not differentiated on what it does to improve the life of the user.

    Q: Should RIM move on with just one CEO?

    The problem is not the number of managers but their view of the world. What would benefit the company is a better marketing manager where marketing is defined as understanding of user needs. Engineering expertise is not enough.

    Q: What would you advice RIM to do in terms of R&D?

    RIM is an engineering led company. Many successful companies rightly develop their engineering skills first because that is what allows them to create new products more quickly. This is true of Nokia and also of Apple and Microsoft in their early years. What is difficult is to allow marketing people to define products after that early phase. This is partly due to the fact that there is less respect for "Marketing" among engineers. Many see it as a "soft" discipline where there is little rigor. But this is not an accurate or fair picture. Great marketing determines what products should be built not just how they should be sold. Engineering can discover new products based on new technology becoming available, but Marketing can discover new products based on unmet user needs. Both need each other.

    My advice would be to allow a way for R&D to absorb input from marketing.

    Q: Do you think that RIM could be bought by a bigger company in the short-term?

    Mature companies are usually bought for their assets and not so much for their vision or priorities. The opposite is true for young companies who are selling themselves to the public via IPOs. For young companies the vision or priorities of business models is seen as more important. When companies are only valued for their assets, they are usually very under-valued. When companies are only valued for their vision, they are usually over-valued.

    RIM's challenge is that nobody believes they have any vision and their assets are weak (no good ecosystem as I pointed out above.) So the price anybody would pay for RIM today would probably be far lower than what management thinks it's worth. And since they are still profitable they won't sell the company at a deep discount.

    So my guess is that we won't see any acquisition soon.

  10. Subscribe to Asymco One for full access to our research.

  11. Subscribe to Asymco One for full access to our research.

  12. Thinking over Apple's value

    Research · 71 comments

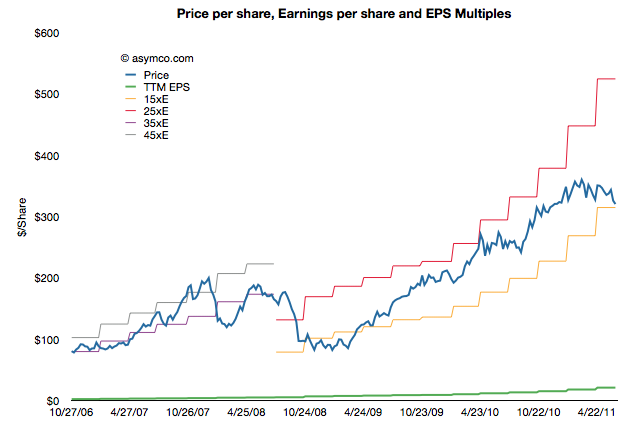
    In intra-day trading Apple's stock price traded at a P/E ratio below 15. That threshold is now at a price of about $315/share. Excluding cash the P/E is under 12. On a forward basis, there is widespread agreement that Apple has the reward (yield) profile of a bond without the risk of inflation.

    The history of the P/E ratio and the share price is shown in the following chart:

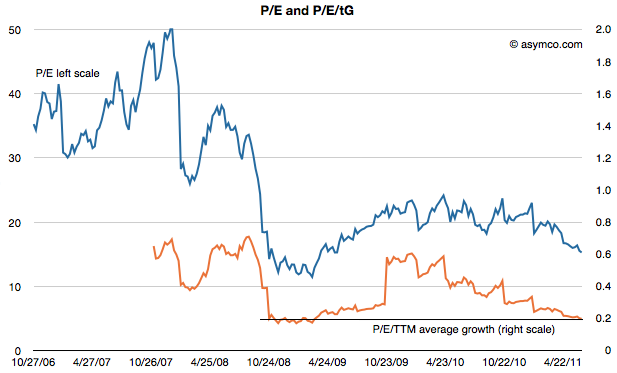
    As the chart shows, Apple traded in a range of P/E between 35 and 45 until late 2008 and has been trading between a range of 15 and 25 since about spring 2009. It might seem that the price is rewarding growth, but it's not.

    When adjusting for the growth the company has maintained, the company is at a similar P/E/tG (Price/Earnings/trailing Growth) to the depths of the recession.

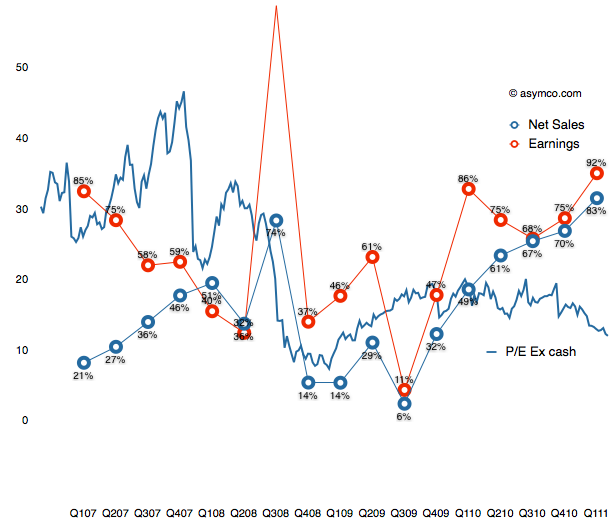
    At the trough shown above, the company was growing earnings at high 30% rates and sales in the teens. Today the company is growing earnings at 92% and sales at 83%. the following chart shows P/E ratio vs. growth.

    From a historic perspective, Apple is as cheap as it was at the bottom of the recession. At the time there were many reasons given for why the company would suffer 'headwinds'. Most commonly cited was that the company was a maker of "luxury" products and luxury does not sell in a recession.

    Today reasons being given for why the company will not prosper are far more nuanced. I won't re-iterate them but they deal with competition, platform issues, production issues, sympathy with companies that are failing, and saturation of markets.

    The trouble is that these arguments are easier to refute than the luxury vs. economy argument.  Exactly because the arguments are more precise, there is data that can be used to counter pessimism.

    And yet, with or without data, markets sometimes decide that profits are not reliable indicators of value created or potential for value creation.

  13. Subscribe to Asymco One for full access to our research.

  14. Subscribe to Asymco One for full access to our podcasts.

  15. Apple could buy the mobile phone industry

    Research · 75 comments

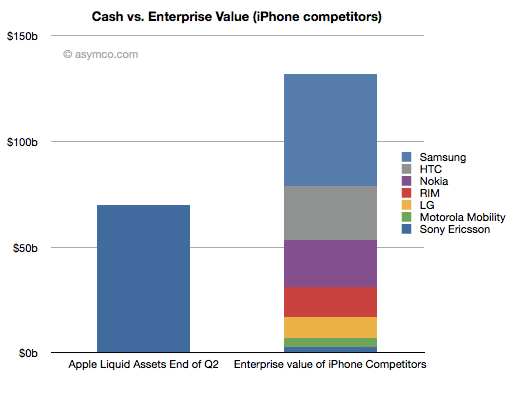
    The second quarter ends in less than two weeks. When it does, I expect Apple will have over $70 billion in Cash, Cash Equivalents, Short-term marketable securities and long-term Marketable Securities. That figure has been growing predictably.

    Also predictable has been the decline in value of Apple's mobile phone competitors. Most spectacularly Nokia and RIM. The enterprise values of the public companies selling 75% of all phones sold world-wide are as follows:

    • Nokia $22.6b
    • RIM $13.8b
    • HTC $25.4b
    • Motorola Mobility $4.2b

    The values of the profitable phone-making subsidiaries are a bit more difficult to estimate but we can use multiples of trailing operating profits. I generously use the multiple applied to HTC (14).

    • Sony Ericsson $0.21b x 14 = $3.0b
    • Samsung $3.76b x 14 = $53b

    That leaves valuing LG's phone business which has not been profitable in the last four quarters. I assume a nominal value of $10b. These data points are shown in the following chart:

    Given the current valuations, it would not be difficult for Apple to acquire every phone vendor except for Samsung with cash alone.

    The more remarkable thing is that as market values of phone vendors continue to decline, Apple's cash will continue to grow dramatically. Indeed, a time may soon come when Apple's cash will be worth more than the entire phone industry.

  16. Subscribe to Asymco One for full access to our research.

  17. The app industry vs. the music industry

    Research · 25 comments

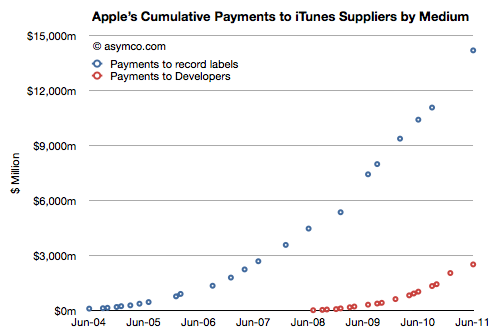
    By my estimate, Apple has paid out $16.6 billion to content owners. $2.5 billion to app developers and about $14 billion to music companies. The developer payments are published by Apple, the music payments are estimated based on total downloads and guesses about the split and pricing of that content (90% for the content and $1 to $1.2 average pricing over time.) There might be reason to move the music figure up or down but the difference will still be nearly a factor of 5.

    The cumulative payments are shown in the following chart:

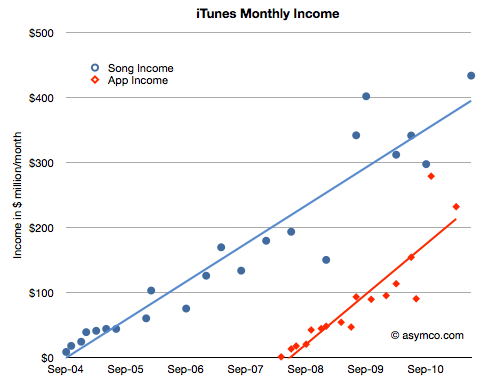
    From this perspective, the music business is still a far bigger ecosystem than apps. However that's cumulative data and digital music has been around far longer. The story can be told a different way: What's the rate of sale in the present period? From what we know about the business, we can see what Apple takes in for apps and music (I've already estimated what Apple "keeps" after paying content owners)

    The combined "sales rate" is a remarkable $665 million per month, but the split now is that music generates only twice the income of apps (i.e. cumulative is a factor of 5 but on a monthly basis the factor is 2). But what should be more impressive is how quickly the app business is ramping. By the slope of the trend lines, it would appear that app income will exceed music income within three years. Therefore, it's only a matter of time before apps generate as much income (exclusive of advertising) as music.

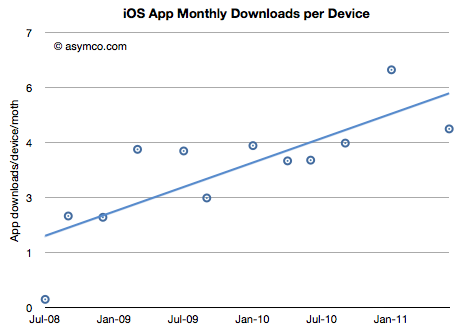
    Another perspective is the number of downloads per device per month. This shows that the rate of consumption of apps is increasing and is now about 6 apps per device per month.

    (You have to think of apps not as traditional computer applications or console games where each device has a certain number of expected apps attached, but rather that apps are more like a subscription where there is recurring monthly income).

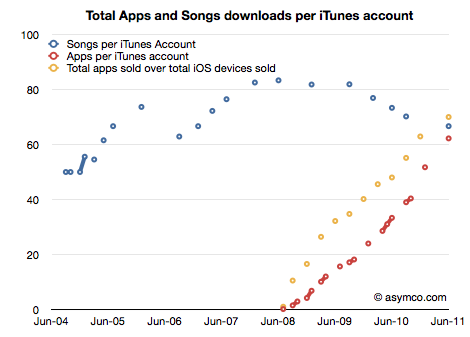
    I don't have a comparable figure for music because the number of iPods and Macs as target devices is hard to estimate, but I doubt consumption for music on a per device basis is increasing. As a consolation, I can estimate the number of apps or songs per iTunes account. Here the story is consistent.

    Each iTunes account has "consumed" about 67 songs but also 62 apps. Remarkable parity in such a short time. And the trend speaks for itself.

    All this data points again to the ascendancy of apps as a new medium. In a mere three years these digital objects have redefined themselves. They went from being tools to enhance the use of your phone to a new medium of expression and art. They have the ability to create a powerful economy of their own and will likely lead a profound shift in where value resides in mobile computing.

  18. Subscribe to Asymco One for full access to our research.

  19. iPhone liquidity: Why an unlocked Phone in the US matters

    Research · 93 comments

    The iPhone is now available in the US unlocked. Judging by the lack of reaction to the news, one would assume that this is not a significant event. I would argue however that it's a very significant event.

    What is unappreciated is that the iPhone is a very restricted product. Unlike any of Apple's other products (iPod, Mac and iPad), the iPhone is designed to be hard to get. Apple did not make it easy in the one dimension of ease that matters most: its purchase.

    Consider that many people in the world cannot buy an iPhone because it's not available locally. In case it is, in most cases you need to sign a contract and commit to a long-term relationship with a company other than Apple. In those cases where you don't sign a contract, you cannot use it with a service provider other than the one (arbitrarily) chosen for you.

    A few have been able to buy iPhones unlocked if they lived in a few countries (UK, France, Australia, Belgium, Hong Kong[1]) but those phones could only be purchased online if sent to a local address or in an Apple retail store--of which there are not many.

    Consider that in Europe alone, the following countries do not have iPhone distribution: Albania, Armenia, Azerbaijan, Belarus, Bosnia, Georgia, Iceland, Kazakhstan, Serbia and Ukraine. The populations total over 100 million people. In Asia the number of countries without iPhone distribution outnumber those with distribution. Add in Africa, Latin America and the Middle East and the unaddressed market begins to look very large.

    If you contrast this with every other phone platform out there, Blackberry, Android or Symbian, the iPhone is extremely restricted and the number of people that are permitted to buy it much more limited. The number of operators supporting Blackberry outnumber the iPhone at least by a ratio of two to one.

    Then there is the matter of distributors. This is a channel that iPhone does not leverage. Distributors account for more than half of Nokia's volumes. They buy in bulk and resell (sometimes illegally or in violation of contracts) vast quantities of phones.

    By offering unlocked iPhones in the US, the restriction on distribution is lifted to a large degree. What's different is that these phones can be purchased in 200+ retail locations. Many of these locations are in tourist hubs where there are large diaspora communities rotating continuously back to home countries. iPhones can now be purchased with cash and become as good as cash.

    And this is not a new phenomenon. When the original iPhone was available, Apple had to restrict buyers to 5 per person and stopped accepting cash because of the huge grey market demand. The same thing happened with the original iPad and with iPad 2 lines are still forming for it because distribution is so restricted. Consider also that sales in Verizon stores pale in comparison with those for GSM products.

    The way to think about it is that the iPhone has just become more "liquid" and it can now flow to parts of the world where it has been difficult to acquire. The iPhone was already liquid to some degree with unlocking and sales through Hong Kong/UK, but the US market's retail footprint and the lower costs that result will boost liquidity dramatically and probably increase volumes substantially.

    ---

    Note:

    1. According to Apple, the following 27 countries offer phones which are not "locked to carrier" : Belgium, Czech Republic, Finland, Germany, Greece, Italy, Luxembourg, Russia, Slovakia, Turkey, Hong Kong, India, Indonesia, South Korea, Macau, Malaysia, New Zealand, Singapore, Taiwan, Thailand, Vietnam, Bahrain, Kuwait, Qatar, Saudi Arabia, United Arab Emirates, South Africa