Asymco

Asymmetric Intelligence

Latest from Asymco

  1. Microsoft has received five times more income from Android than from Windows Phone

    Research · 197 comments

    Microsoft gets $5 for every HTC phone running Android, according to Citi analyst Walter Pritchard, who released a big report on Microsoft this morning.

    Microsoft is getting that money thanks to a patent settlement with HTC over intellectual property infringement.

    Microsoft is suing other Android phone makers, and it's looking for $7.50 to $12.50 per device, says Pritchard.

    HTC Pays Microsoft $5 Per Android Phone, Says Citi.

    A rough estimate of the number of HTC Android devices shipped is 30 million. If HTC paid $5 per unit to Microsoft, that adds up to $150 million Android revenues for Microsoft.

    Microsoft has admitted selling 2 million Windows Phone licenses (though not devices.) Estimating that the license fee is $15/WP phone, that makes Windows Phone revenues to date $30 million.

    So Microsoft has received five times more income from Android than from Windows Phone.

    Looking forward and assuming that Microsoft can receive this type of settlement from about half of the Android license takers, then the prospects of a windfall from Android dwarf the expected income from Windows Phone.

    Google's Android seems the best thing that could have happened to Microsoft's mobile efforts, ever.

    I could also calculate how the Android license income could be further funneled to Nokia (via their current agreement with Microsoft) for promotion of its phones. Thus, an Android licensee could reduce his margins in order to promote a competitor's products.

  2. Subscribe to Asymco One for full access to our research.

  3. A new mobile phone market index

    Research · 90 comments

    Measurements of "share" are abundant. There is journalistic value in summarizing performance in a single figure of "share" but it usually is a very limiting view. For example in the global mobile phone market there are at least the following measurements available:

    1. Share of all handset units sold
    2. Share of installed based of handsets (penetration)
    3. Share of smartphones
    4. Share of mobile computers
    5. Share of value (revenues) captured
    6. Share of profits
    7. Share of platforms
    8. Share within a given platform
    9. Share by regions/countries/geographies/demographics

    One could go on. So performance in a market can only be measured if you know to what end is that measure applied. Are you trying to determine current performance or are you assuming that the future will be different and trying to figure out what that future will look like?

    There is no good answer. It depends. But at least we can combine more than one share value into a summary. Mark Hernandez suggested that I put forward a "composite index" to measure vendor performance. I am willing to give it a try. The first iteration can be an unweighted average of four "shares":

    1. Share of all handset units sold (global)
    2. Share of smartphones
    3. Share of value (revenues)
    4. Share of profits

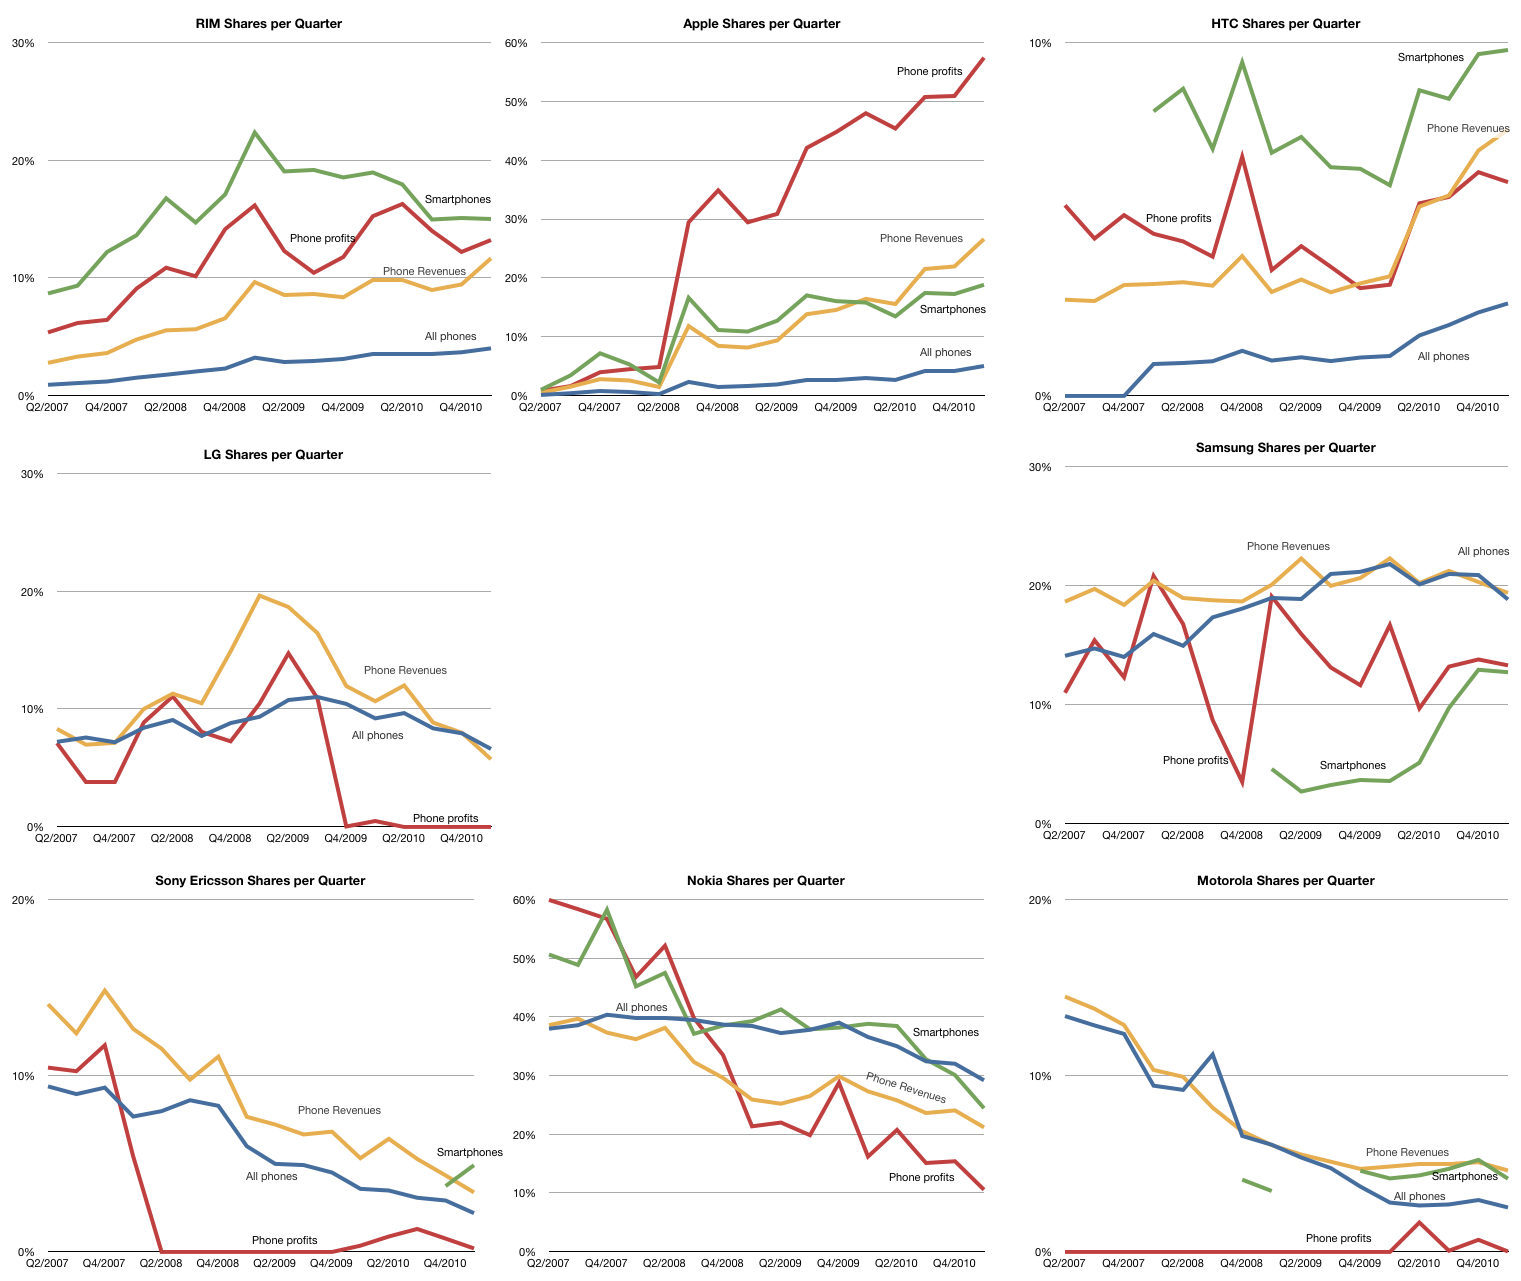
    The raw data for each share is shown in the following charts (note change of vertical scale: each gridline represents 10%).

    Note that the vendors are arranged in a particular way: top row are entrants, bottom row are incumbents with late incumbents from Korea arranged in the middle.

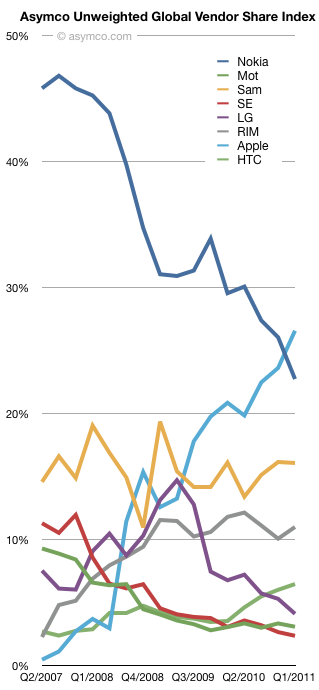
    Taking the average of each of the lines above, the unweighted share index (Units, Smartphones, Value and Profit) is shown below:

    Over the time period since Apple's entry in the market, the index shows interesting patterns:

    • Apple and Nokia trading places
    • Relative stability for Samsung
    • A leveling off for RIM
    • The Peaking for LG
    • Very tightly coupled declines for Motorola and Sony Ericsson
    • Gradual improvement in HTC

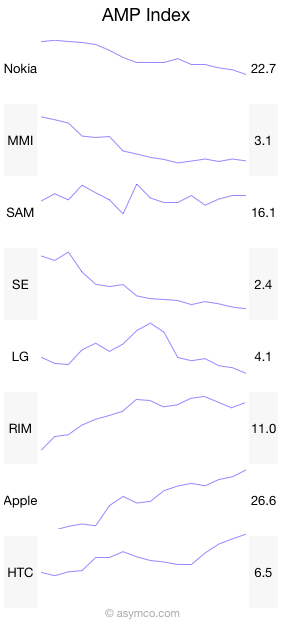
    And here it is in sparklines:

    Like many indices, this is a generalization that measures a section of reality. The value is in its use as a benchmark. If nothing else, it has journalistic value. I'm open to suggestions on how to improve it. Perhaps some form of weighting would be useful. Also, if anyone can suggest good name for it, it might be easier to communicate.

  4. Subscribe to Asymco One for full access to our research.

  5. A disruption is not sufficiently described by the success of some. Others must fail.

    Research · 46 comments

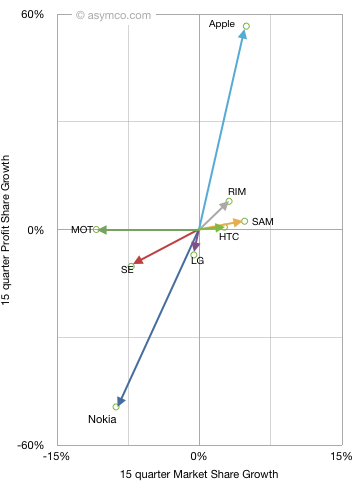
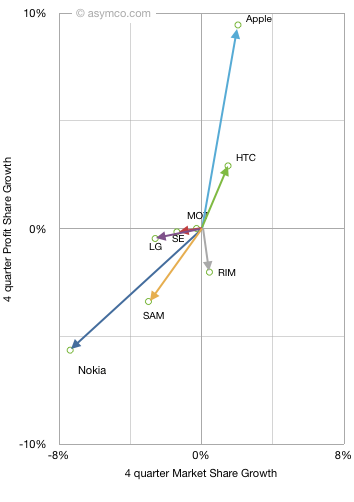
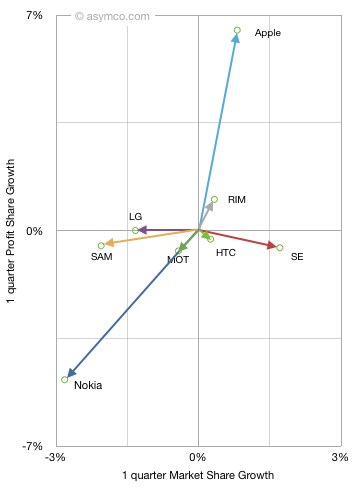
    Last fall I introduced the "vector space" model of visualizing vendor performance. It shows performance along two dimensions: market share growth vs. profit share growth for a set of competitors.

    When introduced, I chose a long time frame (15 quarters) to see the long-term pattern. This quarter I add two more time frames: year-on-year and sequential. This allows a view of how market change is itself changing. The three diagrams are shown below (note difference in scales)

    One way to interpret this is movement toward the upper right is positive while movement down or to the left is negative. A deeper meaning can be obtained from noting that the vector sum or "net" of vertical and horizontal data points should be zero (i.e. the gains in share should be at the expense of losses in share). In terms of phone market share the "net" is not zero as "others" are excluded, but the difference is visually not perceivable.

    Since we're dealing with share, one way to interpret the data is that "improvement" in one's position is offset by the "decline" in another's. We cannot ascribe the benefit of a vendor directly to the loss of another but overall net gainers are offset by net losers.

    By tracking this position change over time we can see if there is a set of consistent winners and a set of consistent losers. The pattern does show that:

    • Smartphone vendors grow consistently
    • Apple in particular has consistent growth with profit growth faster than share growth
    • Nokia in particular has consistent decline with profit decline faster than share decline
    • RIM shows profitability concern in the near term. In particular vs. HTC
    • Samsung shows some near term share loss, probably due to unbranded vendors
    • It's very rare to have a company lose market share while gaining profit share or to gain market share and lose profit share. This implies that in this market one does not trade off volume for profit.

    The correlation between profit and volume growth is very telling. As is the consistent clustering of winners and losers. This analysis demonstrates the shift in the industry is not a short term phenomenon but a disruptive changing of the guard. If history is any guide, this change is not going to be undone.


  6. Subscribe to Asymco One for full access to our research.

  7. Why the phone market is resilient to low-end disruption

    Research · 10 comments

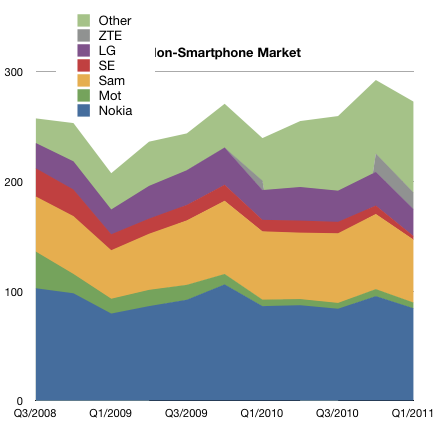
    The phone market excluding smartphones is not growing. Over a three year period it grew at 2% compounded.

    The following chart show the make-up of the market by vendor.

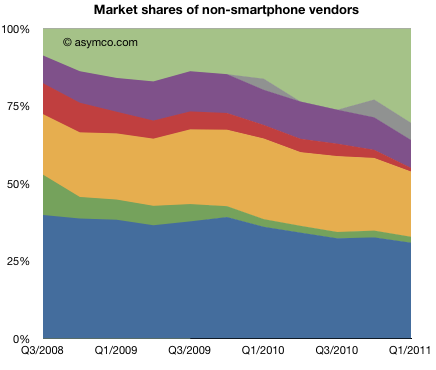
    Since it is not expanding rapidly, share over time has a lot more meaning.

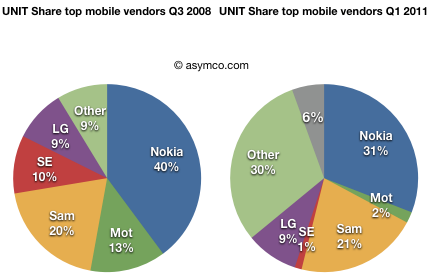
    The change in share over the last few years (since Q3 2008) is shown in the following two pie charts:

    Although many will argue that the non-smart market is one of great opportunity, the historic data shows that the market is not vibrant:

    • It's growing slowly if at all
    • Prices are falling as buyers find nothing of value in new products
    • There are fewer branded competitors (from 5 to 3)
    • There is increasing "white label" or unbranded volume growth (from less than 10% to over 30% share in three years)

    Although low end entries (in this case the unbranded new vendors) can signal disruptive potential, that potential is unlikely to manifest itself in voice-oriented products. Low-end disruptions take hold when markets are overshooting the expectations of the majority of buyers and incumbents are motivated to exit.

    However, if we consider all phones as a single market, then there is vast under-performance in the high end--something another set of entrants have taken advantage of and something neither the incumbents nor the low-end entrants are motivated or capable of pursuing.

    The phone market is not being disrupted because of the low end entrants. Nokia and Samsung are motivated to compete for those customers. It's being disrupted because the new market of mobile computing is completely asymmetric.

  8. Subscribe to Asymco One for full access to our research.

  9. "Other" vendors sell 10% of Smartphones but 30% of voice-oriented phones

    Research · 12 comments

    In the last post, I highlighted the difference between smartphones and non-smart device sales last quarter. The trajectory of share growth for smart devices would appear to have accelerated due to Android.

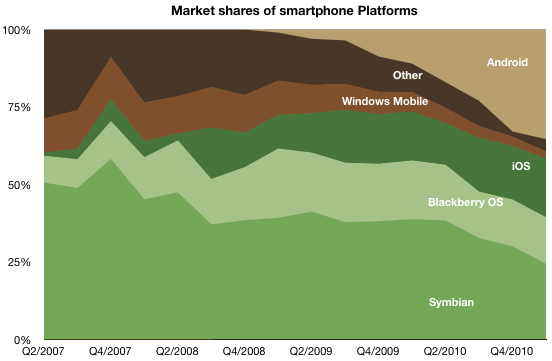
    The following charts show the evolution of smartphone vendors and platforms over the last few years.

    Like in the past, I used color clustering to show the separation between "integrated" (in green) and "modular" (in brown) platforms and their users.

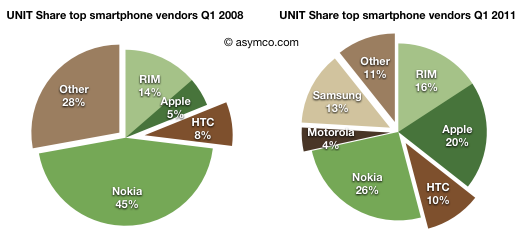
    Unlike the non-smart market where "other" make up 30% of the market, smartphones are still a big brand business. "Other" make up only 11% of units. and that number has been trending down. It would seem that the age of unbranded Android phones is still not upon us.

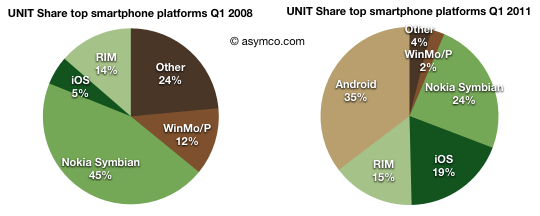
    Comparing three years "before and after" here is Q1 2008 vs. Q1 2011 by vendors share:


    Apple added 15% of share, Samsung 13%, Motorola 4%, RIM and HTC 2%. Nokia lost nearly 20% of share.

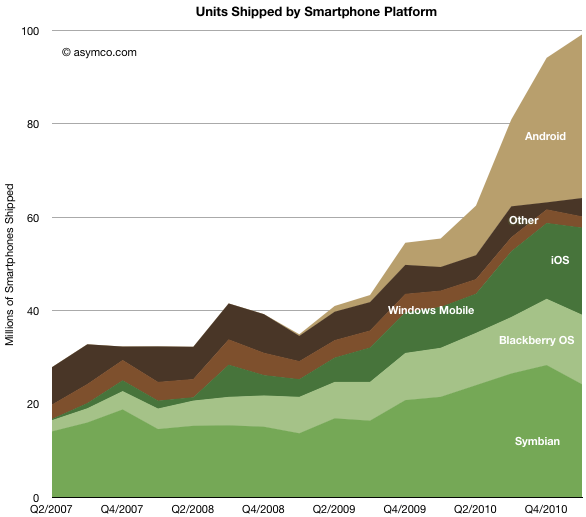
    From a platform point of view, the unit chart looks like this:

    Note that Android's growth came at a time when Symbian had a terrible quarter. The evidence is visible in the share chart:

    Android's gain seems to be at the expense of Other, Windows Mobile and Symbian. In the pie chart snapshot over a three year period the transfer seems clear.

    Android took 35% of share, iOS 14% and RIM 1%. Windows Mobile/Phone has collapsed to 2%.

    But again I would caution about drawing "sustainability" conclusions from looking at this market with a share perspective. As it's growing at a huge rate (73% year/year) it's bound to be become so large that single digit share numbers still amount to vast ecosystems while huge shares of fragmented products don't amount to much of value. To emphasize the point, I would remind that in 2008 Symbian was not just Nokia but a lot of "Other" was made up of Symbian in Japan. The combined fragmented footprint of Symbian was well over 60% of the market. It did not do much good for the platform.

  10. Subscribe to Asymco One for full access to our research.

  11. Smartphones: the end of the beginning or the beginning of the end?

    Research · 43 comments

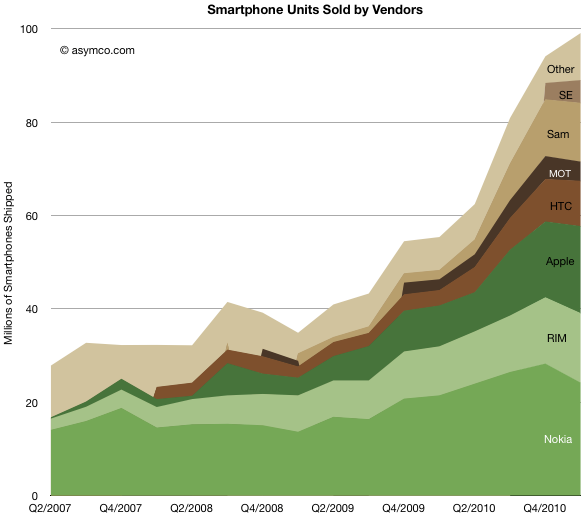
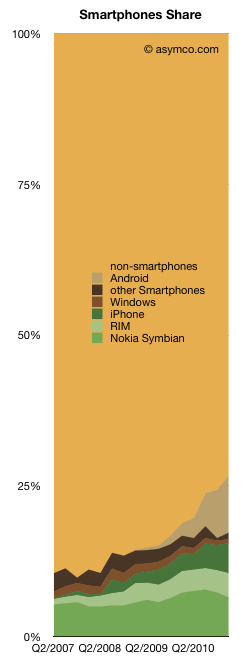
    The smartphone market grew to about 100 million phones last quarter. The volumes grew sequentially and as a result reached a new record share of 27% of total phones shipped. The chart on the left shows how this market evolved over the last few years.

    I've added each platform's contribution.

    While much of the focus will be on who had what share, the better question might be who has the better chance to beat smartphone non-consumption? Non-smart devices are still the dominant competitors. Though it's getting easier to win against them, they still have some compelling competitive advantages.

    What the chart shows is that Android (and phone versions of iOS) have taken share from direct competitors but have taken more from non-consumption. Rather than focusing on rivalry between platforms, minds should be focused on the shape of the smartphone adoption curve.

    The market is largely un-penetrated and yet some argue that "it's too late" to enter or that "the game is over" and winners have already been decided. This is an argument that we are at the beginning of the end. Once the market is predictable it's discountable. Once it's discountable it becomes economically uninteresting.

    I've argued that this is far from certain. In a short span of a few years, a decades old business has been re-defined. But that was just the device side of a larger business. Smartphones have been, so far, sustaining to the telcos who capture the vast majority of revenues and are thus the true incumbents.

    If and how they will be affected by further evolution of smart devices and new business models around them remains to be determined.

  12. Subscribe to Asymco One for full access to our research.

  13. The Rawr Chart

    Research · 30 comments

    The challenge with any performance metrics is that there is no single measure of business performance which is conclusive. The last few posts have covered mobile phone vendor performance measured by various methods. Growth (sequential, yearly and compounded multi-year),  margins, shares (units, profit and sales), rankings and time series. I've distinguished between smartphone pure plays and the diversified. Each is trying to shed light on what is a multi-dimensional puzzle.

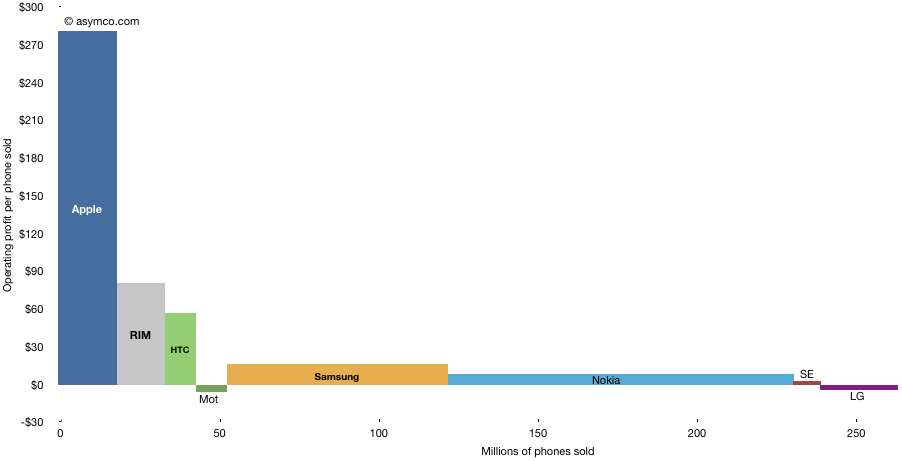
    I've used various charting tools and visualizations and they each render some clues, but the following chart is one of my favorites. It shows the way operating profit was distributed among the top vendors.

    The areas each represent the profit from mobile phone sales in Q1. The horizontal axis shows the volume of units and the vertical the profit per unit. It thus shows how "efficiently" profits were captured a unit basis. It also shows at a glance the different strategies employed and how they reflect performance. It shows who made money and who didn't. It shows the magnitude of differences.

    The shape of this chart has not changed in the last few quarters but it prompts speculation on how it might change in the following few years.

    I struggled to find a catchy name for this type of chart but @JustinD put it well here. Rawr indeed.

  14. Subscribe to Asymco One for full access to our research.

  15. Apple, RIM and HTC captured 75% of mobile phone operating profits in Q1

    Research · 32 comments

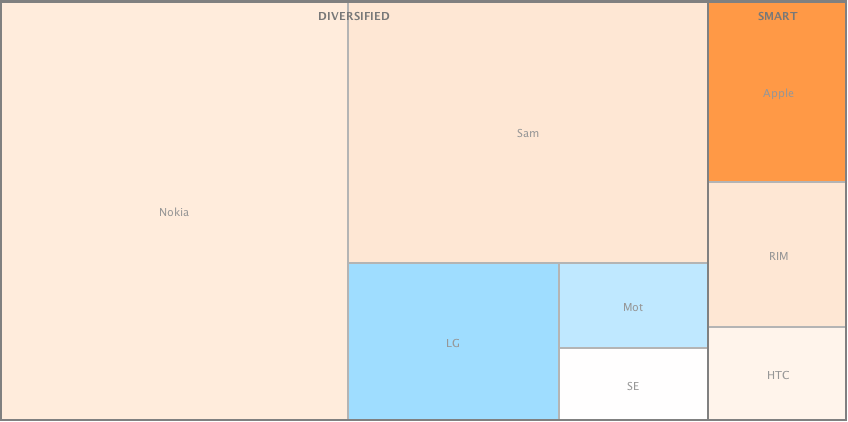
    I produced two alternate views of the primary mobile phone brands in terms of volumes sold and operating profit in Q1.

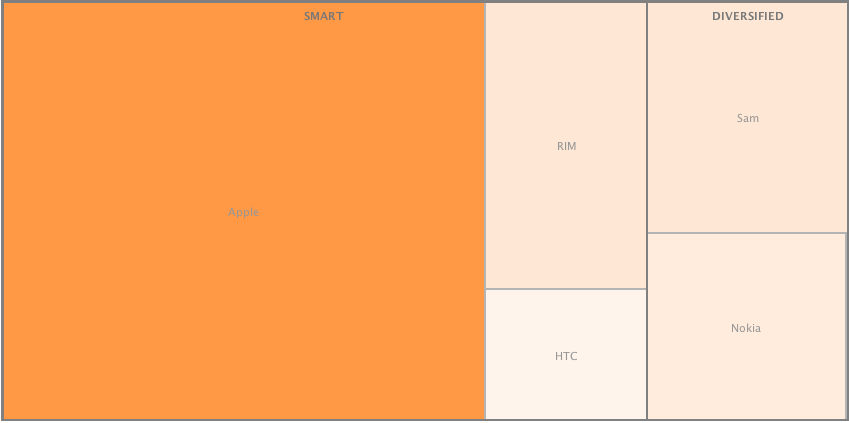
    These views[1] allow a comparison by categorized competitors. I grouped dedicated smartphone vendors (SMART) vs. diversified and used color coding for profitability (blue colors indicate loss-making vendors).

    The same view is drawn for profitability. Loss-making competitors are excluded.

    This view shows how 16% of the volumes for the smartphone vendors generated 75% of total profits. As smartphone penetration grows, those vendors who maintain a diversified portfolio will continue to see their average price and profitability slide.

    I've suggested before that I don't see non-smart devices being interesting to vendors in the near term. Each additional dumb phone added to a portfolio will decrease a company's operating margin. The market dynamics are such that I think non-smart phones will disappear entirely from branded portfolios in 3 to 5 years.

    ---

    Notes:

    1. These are called "tree views". I used Many Eyes experiment from IBM Research to create these charts.
  16. Subscribe to Asymco One for full access to our research.

  17. iPhone share of phone market in Q1: 5% volumes, 20% revenues, 55% profit

    Research · 40 comments

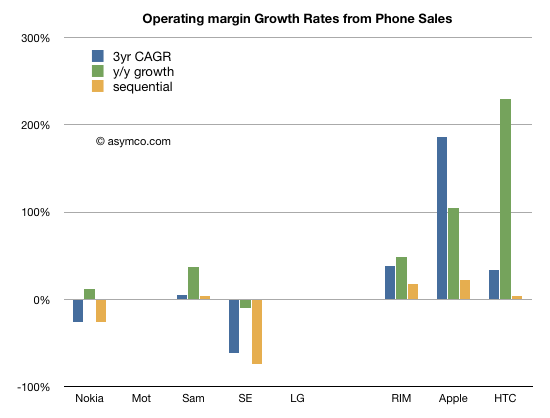
    Operating profits for the eight vendors I track increased at a compounded 25% over three years. As with revenues, the growth is concentrated. The following chart shows operating profit growth across three time frames: three year compounded, year/year and sequential. Loss-making vendors are excluded from this chart.

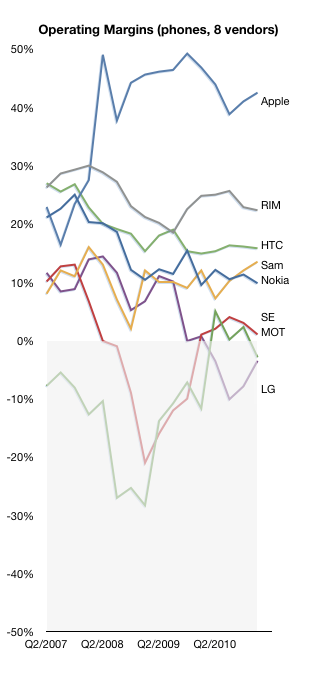
    Looking at individual performance, the following chart shows how each vendor performed over time:

    The mobile industry has historically been unforgiving. Companies that fall into unprofitability tend to stay there or exit/merge. This has claimed many: Ericsson, Siemens, Alcatel, BenQ, Palm, Sony, Toshiba, Handspring, NEC, Hitachi, Casio.

    LG, MMI and Sony Ericsson are all in the same precarious situation. We'll have to watch carefully whether a recovery is possible for any of them and whether Nokia will reach the same rocky position.

    Looking at operating profit shares, the picture is plain to see. While RIM, Samsung and HTC have maintained profit share, between 2007 and now, profit share has mostly shifted from Nokia to Apple.

    But this does not tell the whole story. Here are the absolute amounts of operating profit from mobile phones. Exactly three years ago Nokia was earning 47% profit share or $2.35 billion. This past quarter Apple's 57% was equivalent to $5.23 billion, more than twice as much.

    Finally, the league table shows how Nokia has now dropped from second to fourth in the last quarter. Not only Samsung, but RIM has overtaken Nokia as well.

    It's become routine to see Apple at the top of the list of profit earners from mobile phones.

  18. Subscribe to Asymco One for full access to our research.

  19. Did Microsoft pay for the wrong Skype?

    Research · 51 comments

    When a company is acquired, the price paid is usually higher than what the company is worth. This is because there is a "control premium" that needs to be paid so that the acquiring company can control the destiny of the acquired company (while the seller loses that right). So the question has to be what does the premium (or excess cost) buy? What is the value of that control? What will be the new destiny? Whose destiny is changed?

    Clayton Christensen succinctly defined the value in any company as the sum of three constituent parts: resources, processes and business models. Market value can be nothing more and nothing less than these three things.

    An acquisition has to be positioned on one of these targets just like a product is positioned on a specific market. The problem with being deliberate about where the value lies is that once positioned a certain way, the integration team will begin to execute on that plan. This means that the thing you decided was worth most (e.g. resources) gets all the attention and the other potential sources of value (processes or profit models) are discarded.

    This argument reduces to there being three separate companies being available. The buyer pays for all but gets to keep only one.

    When you look at it this way you realize that the reason most acquisitions fail is that the buyer throws away most of the real value in the company.

    For example, when looking at Skype through Microsoft's eyes, they could be valuing it for its resources (employees, management team, customers, or intellectual property.) Or they could be valuing its processes (how it makes software and how it recruits customers) or it could be its business model (viral distribution, very low prices with wide distribution, plan to disrupt telecommunications). Each of these is a separate, mutually exclusive deal with separate integration plan and separate strategic justification. Each is targeting a separate Skype.

    If Microsoft were to pay a premium for Skype's resources then they will probably not make use of the processes or business models. There is some value in this Skype. Microsoft could use the customer base to sustain their existing businesses and to up-sell services.

    But what if the real value is not in resources but in the business model? A model which would allow for Microsoft to disrupt its core business. Perhaps Microsoft could use the Skype approach to creating new customers, eliminating its partner network and expensive direct sales force. This would be a different Skype. It would have the potential to transform Microsoft. Microsoft could become what Skype is now: a communications network or carrier that disrupts the way people use network operators.

    This type of value exists in Skype but its asymmetry with Microsoft's core would make it a very tough sell internally. A recent article pointed out that when Skype was up for sale last time, Google's acquisition was sabotaged internally by people who realized that peer-to-peer would be "incompatible" with the centralized architecture of Google's services. If not for the effort of certain individuals, Google might have ended up with Skype and destroyed it with internal antibodies.

    Chances are that Microsoft paid for Skype's customers and engineers but will not apply the innovations of viral peer-to-peer distribution or disruptive voice pricing. If that happens then perhaps Microsoft will pay $8.5 billion for the wrong Skype and telecom disruption will find another home.

    Notes:

    Adapted from an answer published in Capital.bg. My thanks to Adrian Georgiev for asking the right questions.

  20. Subscribe to Asymco One for full access to our research.