Latest from Asymco
-
-
Gartner adds their Mac Q1 estimate to the pile
-
Mac mini and Mac Studio orders booming
-
AI as Infrastructure
Build it and they will come?
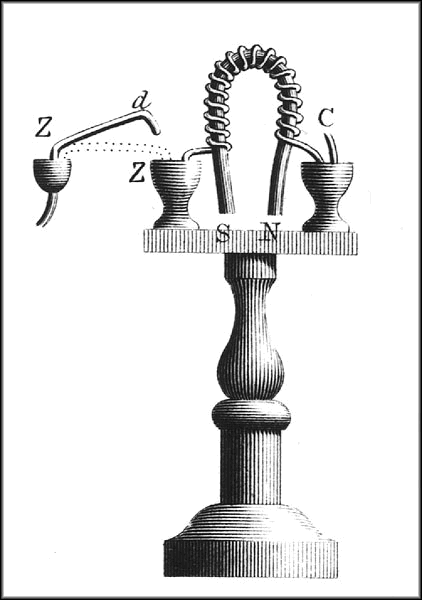
The first artificial electromagnet, invented by Sturgeon in 1824. Paper submitted to the British Royal Society of Arts, Manufactures, and Commerce. The magnet was made of 18 turns of copper wire.
ON September 3, 1821, 37 years after James Watt invented the concept of horsepower and started charging £5/horsepower/year for the use of his steam engine, the first demonstration of the production of a mechanical force by the interaction of an electric current and a magnetic field was given by Michael Faraday in the basement of the Royal Institution in London.
1820 is, in many chronicles1, noted as beginning of the industrial revolution. It marked the end of 50 years of war2, whose conclusion unleashed pent-up demand. That demand was served by relatively free trade, guaranteed by British naval power, coupled with property rights and financial instruments which allowed inventions of the previous century to finally be harnessed for commercial gain. The steam engine is the canonical invention of the era and its implementation as a source of power for factories, shipping, rail and machinery is legend.
Not usually noted as coincidental to this period is the electric motor. Yet not long after Faraday's 1821 demonstration in London, the first DC electric motor capable of turning machinery was invented by William Sturgeon. In 1832 he built on Faraday's electromagnet by incorporating a commutator which oscillated the direction of current to ensure continuous rotation.
However, for 30 years after its invention, no practical uses could be found for the electric motor. It wasn't because there was no demand. The steam engine was in use and, as Watt's £5/horsepower/year business model demonstrated, very lucratively so. The electric motor was not in use because there was no electricity distribution system. There were no power plants, there was no grid. The motor could not stand alone.
In contrast, the equivalent distribution system for steam was the coal industry. Coal as fuel pre-existed the steam engine. Used not just for heating, it was the fuel of foundries that made iron and other metals. More energy dense than wood, coal had been mined for thousands of years. From mining concessions to barges for transport on newly dug canals to bunkering for storage, sourcing coal was a well-developed, stable and profitable industry.
Finding coal to power a steam engine in the 19th century was not a problem. Finding electricity to power your electric motor was. You could not store it, you could not ship it, you could not meter or price it. It required a completely new value network and infrastructure.
For this reason, even though the electric motor was available through most of the 19th century, the period was still known as the age of steam. The electric grid—an infrastructure—was only possible by the late 1800s as generators, capacitors and AC power were perfected. It wasn't until the early 20th century that the age of electric power began.
This illustrates perhaps better than any other example that the device precedes the infrastructure. That is, that the instrument of utility precedes the network that enables it. the boat precedes the port, the locomotive precedes the railroad, the automobile precedes the motorway, the telegraph precedes the telegraph network, the radio precedes the radio network, the phone precedes the phone network, the cell phone precedes the wireless network and the smartphone precedes the social media. The device induces the supply of its own power.
The implications are profound. It puts to the test the idea that we need to build infrastructures before we know how they will be used. The inventors of electric motors or lights relied on batteries. Investors had to imagine a grid to power more than one. The inventors of the radio had to demonstrate a single transmitter/receiver pair. Investors had to imagine broadcasting. The inventors of the car had to find fuel in pharmacies. Investors had to imagine a gas station. Steve Jobs demonstrated the iPhone without an App store. Investors had to imagine a Services business.
As AI has emerged as a technology, we are in a strange position where the interface, born as a chatbot, suggested an infrastructure that is massive in scale. The magic sauce of GenAI isn't so much the algorithm, which is quite a simple idea. It's the scale of the data and computation that permits the illusion of intelligence.
In developing the commercial idea, investors are imagining the device while investing in the infrastructure. In other words, the investors are poised to put trillions of dollars to work on what amounts to "the grid" without knowing exactly what the motor will be.
The cash flows associated with infrastructures are very different from those of devices. Devices are iterated rapidly and evolve to changing tastes and discoveries of behavior. Infrastructures are built once, maintained and perhaps re-built but only after decades. Therefore financing for infrastructures is more likely through bonds (debt) rather than shares (equity). Returns are also much more subdued as the risk for infrastructures is lower. Regulation and relations with labor are also dramatically different.
Moreover, few businesses implement both the device and the infrastructure. Indeed, the capital structures, financing, longevity and valuations of the two types of businesses are dramatically different. In cases where they are merged, regulators typically intervene to separate them.
Watching from afar, it would seem that if AI is indeed infrastructure then it will not provide a brilliant business model. Like all network business models, you either iterate constantly at great expense to deliver the next generation or you harvest the built environment to pay back the investment, hoping that a parallel network does not steal users. But the cruelty of the model is that if you have a monopoly of any kind, your margins are beaten to zero by regulation and cost of parasitic maintenance.3
We can see this with all current "grids". From electric to hydrocarbon distribution, to communications and even food distribution. The struggles to avoid commoditization, corruption and corrosion of trust and a lack of innovation are endemic.
The device however, is another story.
- I recommend "The Birth of Plenty: How the Prosperity of the Modern World Was Created" by William J. Bernstein. Bernstein argues that in order to prosper, a country must possess four main attributes: property rights, the scientific rationalism, capital markets and an effective means of transportation and communications.
- Reverse chronology: French Revolution, 1803-1815, (including the War of 1812 in US & Canada), which followed a decade of the French Revolution 1789-1799 which followed the American Revolution 1765-1783. This global war, involving most world powers, lasted 50 years.
- In a research note published April 7, Goldman Sachs strategists led by Chief Global Equity Strategist Peter Oppenheimer acknowledged the historical basis for those concerns. "The history of technology breakthroughs, from the steam engine to railways, PCs and the internet, is littered with examples of new technologies that attracted large sums of capital to build out underlying infrastructure which have led, ultimately, to low returns," he said. "The gains are then enjoyed by other companies, many of which piggyback off the original investment," he added.
-
iPad at 16
-
Morgan Stanley has a stark message for investors in Apple
-
What are the odds of Apple surviving?
A tale of two Apples
What are the odds of it surviving another year, ten years, 50 years?
Companies don't last long. A recent study that analyzed thousands of European firms yielded a corporate life expectancy figure of 12.5 years. The Boston Consulting Group analyzed the entry, growth, and exit dates of 35,000 publicly listed companies and determined that one in ten of all public companies fail each year, a fourfold increase since 1965.
As I illustrated many years ago in a talk titled "The Unfortunate 500" most companies die not long after adolescence. Of the Fortune 500 1955-1960 cohort, the 81 companies which joined the index in those years, only 7 remain there today. One third of the corporations on the 1970 Fortune 500 list were no longer in existence thirteen years later. Broadly speaking, as a population, large companies that make it to the Fortune 500 listing have life expectancy within that group of 17 years.
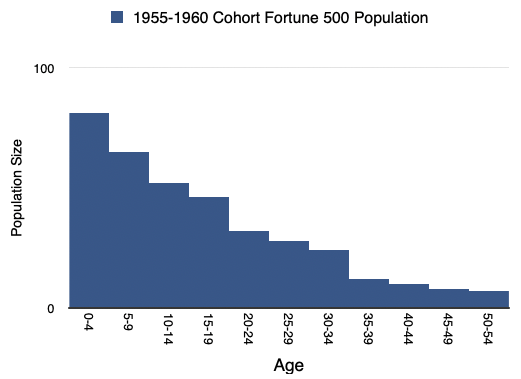
To illustrate further, here is the list of the companies that joined the Fortune 500 In 1976, the year of Apple's birth:
Entry Company Exit 1976 SuCrest 1976 1976 International Systems & Controls 1977 1976 Kewanee Industries 1977 1976 Hunt International Resources 1979 1976 Peabody Holding 1979 1976 Consolidated Aluminum 1981 1976 HP Hood 1981 1976 Envirotech 1982 1976 Peabody International 1984 1976 Hughes Tool 1987 1976 Cameron Iron Works 1990 1976 Foxboro 1990 1976 Tektronix 1994 1976 Mapco 1998 1976 Molson Coors Brewing 2009 1976 Baker Hughes 2014 1976 Masco 2014 1976 Ball 2014 1976 Ecolab 2014 1976 CF Industries 2014 Not one of those in the 1976 cohort are on the list today. The longest to survive managed to stay on for 38 years.
Apple joined the Fortune 500 in 1983. Here is a list of all the other companies that joined the index in 1983.
Entry Company Exit 1983 North American Coal 1983 1983 Datapoint 1986 1983 MEI 1986 1983 Mobay 1986 1983 Coleco Industries 1988 1983 Liquid Air 1988 1983 AH Robins 1989 1983 Sipco 1989 1983 Wilson Foods 1989 1983 Oxford Industries 1991 1983 DR Holdings Inc of Delaware 1992 1983 Media General 1992 1983 Wisconsin Dairies Cooperative 1992 1983 Ametek 1994 1983 Hanson Industries NA 1994 1983 Meredith 1994 1983 Snap On 1994 1983 Sun Diamond Growers 1994 1983 Universal Foods 1994 1983 Worthington Industries 1994 1983 AMDAHL 1994 1983 Dr Pepper Seven Up 1994 1983 Diebold 1994 1983 Echlin 1998 1983 Stone Container 1998 1983 Tyco International 1998 1983 Flowers Industries 2001 1983 Cooper Tire & Rubber 2005 1983 Tribune 2008 1983 Holly 2011 1983 Apple -- Apple is the only survivor from that cohort.
Out of about 2500 companies that existed in the Fortune 500 index since 1955, 50 are still in it. That's a survival rate of only 2%. Approximately 87% of all people born globally between 1955 and 2026 are still alive today. This is why I titled my talk The Unfortunate 500. If this was a human population it would be considered chronically unhealthy.
However, unlike people, large companies that make it past age 50 tend to stay alive (or independent, as most who exit the index do so because they are merged or acquired--another distinction from biological entities).
But the way they manage to be resilient is by adapting to a changing world in some fundamental ways. The environment a business lives in (technological, market, economical) changes more rapidly than the biological environment (genetic, radiological, reproduction).
Companies have to essentially re-define themselves and become something that has little to do with their initial conception.
In the case of Apple there are clearly two separate entities. The original and the one that was reborn in 1998 when Steve Jobs returned. When you look at the company closely, it's pretty clear that the second Apple was fundamentally different even though the original founder returned.
In some ways one could argue that Apple 1.0 eventually strayed from its original culture and the reset in 1998 returned it to a core that was resilient but it's more complicated than that.
To measure "distance" in terms of corporate culture you need to think of culture as a three dimensional vector. it's a composition of resources, processes and priorities (RPP). The combination of these forms what we call the "DNA" or the "culture" or the unwritten constitution of the firm.
The vector of RPP for Apple changed dramatically in Apple 2.0 in terms of resources (capital, software, silicon), processes (engineering, operations and marketing), and priorities (focus, integration, product/service cohesion)
I would summarize it as there being a tangible "theory of the firm" for version 2. The first version was very much a theory of the team: a group of great people without a binding operating model.
Stay tuned as we explore the Theory of Apple.
-
iPhone sales continue to surge into February - Bernstein
-
Asymco Office Hours Live Q&A with Horace Dediu: April 8, 2026
We are elated to have Gene Munster join our Live Q&A.
Asymco Office Hours will take place on:
Wed April 8 at 12pm ET / 9am PT.
Asymco One subscribers can sign up to attend the live Q&A and ask questions.
We are now opening the registration to non-subscribers to watch live. Asymco One subscribers will be able to ask questions.
Recording & transcripts will be available to Asymco One subscribers, shortly after.
Asymco One Subscribers:
Register for April 8 Office Hours where you can ask questions live.Non-Subscribers:
Join Asymco One as a Subscriber to participate OR
Just Register to Watch live.Contact us at events@asysmco.com if you have any questions.
For most up-to-date information, see
-
KeyBanc maintains a lack of clarity of thought
-
Apple's services continue to see increased engagement, spending