We plan to hold our annual event on or around the first week in June 2026. Stay tuned for details. If you have any requests or comments, feel free to reach out. Use comments below or email contact (at) asymco.com
"When Steve Jobs and I would walk around the Apple campus back in 2008/9, we talked about the Apple Car and he thought we need to do it."
Fadell says that Jobs's vision for the project was a people's car, inspired by the original Volkswagen. "What's the next generation people's car? What's going to be used in the cities?"
Where he believes Apple effectively tried to make a self-driving SUV, the company should have looked instead at changing how people thought about cars.
"Apple is a company that redefines certain aspects of life," he said. "It redefined what it was to do desktop publishing, or publishing in general. It redefined music. So they should redefine mobility."
Counterpoint Research published its latest market estimates for best selling phones in 2025. The list is:
iPhone 16
iPhone 16 Pro Max
iPhone 16 Pro
iPhone 17 Pro Max
Galaxy A16 5G
Galaxy A06 4G
iPhone 17
iPhone 15
Galaxy S25 Ultra
iPhone 16e
What’s notable, however, is that the base model iPhone 17 took 7th place. This contrasts with the iPhone 16 managing only 10th place in 2024, and very much reinforces the widespread view that the base 17 is the model to buy unless you specifically need one of the pro features. It’s the reason we crowned it as “the best overall iPhone in years.”
NB: Not as exciting as the 20% market share for the full year, the saturation of the list by Apple products is indicative of a dominance in revenues not just volumes of sale. The Apple products have a significantly higher average selling price.
The App Store alone saw over 850 million average weekly users globally. Developers earned over $550 billion on Apple platform since 2008.
Apple Pay eliminated well over $1 billion in fraud, while generating more than $100 billion in incremental merchant sales globally. Purchases made through Apple Pay significantly outpaced the overall growth in consumer spending levels during the peak holiday shopping period in November and December. Apple Pay is now available in 89 markets. with more than 11,000 banks and network partners — including more than 20 local payment networks. Tap to Pay on iPhone expanded to 34 additional markets — now covering most of Europe — and is live in a total of 50 markets, with more than 15 million merchants of all sizes across the world accepting contactless payments using just an iPhone
Apple TV eclipsed all prior viewership records in December 2025, with 36% increase in monthly engagement (total hours viewed). To date, Apple TV has amassed 672 award wins and 3,085 nominations (excluding 2026).
Apple Music reached all-time highs in both listenership and new subscribers.
Apple Fitness+ expanding to 28 additional countries and regions offering more than 8,000 workouts and meditations in 4K Ultra HD.
In 2025, Shazam generated over 1 billion recognitions per month.
Expanded Share Item Location feature in Find My to 27 additional airlines, bringing the total to 36. (This feature allows private and secure sharing of an AirTag’s or Find My network accessory’s location with an airline’s customer service, reducing “truly lost” or unrecoverable luggage by 90 percent)
Apple Podcasts expanded transcripts to over 125 million episodes in 13 languages.
Apple News solidified its position as the No. 1 news app in the U.S., Canada, and Australia, and No. 2 in the UK. News features over 3,000 publications and more than 600 titles with Apple News+. News+ expanded its offerings with the debut of Apple News+ Food, which includes 100,000 recipes from 60 publications in the U.S., the UK, Australia, and English-speaking Canada. Apple News now includes over 150 local newspapers and news feeds across 50 U.S. states, seven Canadian markets, and London.
Apple One Individual and Family plans are available in more than 100 markets world-wide, with Apple One Premier, which also includes Apple Fitness+, available in more than 20 markets.
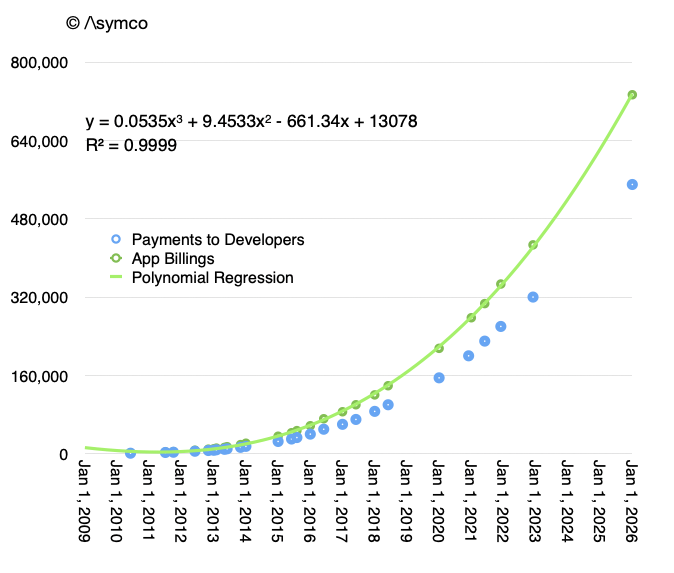
Historic data is not available on most of these singular data points however they are available at least for the payments to developers. In fact, there are 26 such data points. They are shown in the graph below as the blue dots.
The green dots and curve fitting them is my estimation of the total billings for App Store. That is, the total spent by customers on the App Store. To date, that amount is over three quarters of a trillion dollars. ($733 billion to be precise.)
Note that the data can be represented by a third order polynomial. Furthermore, since the r-squared is 0.9999, the function is very predictive. As an exercise, using this analysis it can be determined that $1 trillion will be achieved by the first quarter of 2028.
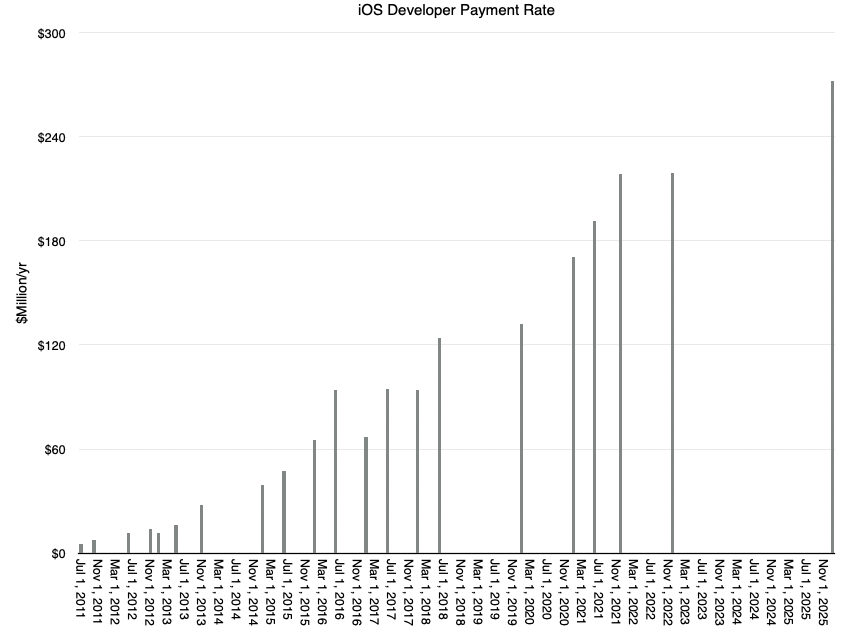
The beauty of a polynomial growth rate is that the rate of payment, that is the amount paid on a monthly basis, is itself accelerating. The following graph shows the payment rate in $million/day for developers.
This growth suggests that quite soon we will be nearing a rate of $300 million/day or $100 billion per year developer payment rate.
This is, of course, only the tip of the iceberg. As Eddie Cue points out in the press release,
In 2024, the App Store ecosystem facilitated $1.3 trillion in developer billings and sales, with more than 90 percent of that commerce going directly to developers, with zero commission paid to Apple.
To understand the totality of transactions on Apple platforms we need to explore the entirety of the App economy. There is for another post. Stay tuned.
Apple is set to report its strongest iPhone sales growth in four years on Thursday - and likely the company's best quarterly revenue to date…
Strong iPhone sales expected to power record Christmas quarter for Apple appeared first on MacDailyNews.
In China and developing markets, Apple drew customers with the refreshed camera design and higher storage capacity of the latest Pro devices.
The company led the global smartphone market last year with a 20% share, according to research firm Counterpoint, up from 18% in 2024.
Overall, Apple is expected to report that iPhone sales rose 13.8% in its October-December fiscal first quarter, according to analysts polled by LSEG. That would mark the strongest growth in more than four years.
Total revenue likely increased 11.4% to a record $138.43 billion, aided by a 14.1% jump in Apple’s the services business.
In Greater China, sales likely jumped about 15%, according to Visible Alpha data.
Some investors believe Apple can make money from AI without the massive infrastructure investments pledged by its Big Tech rivals.
“Apple can probably generate a positive return on very little AI investment, thanks to its distribution,” said Gerrit Smit, manager of the Stonehage Fleming Global Best Ideas Equity fund, which holds Apple stock.
Apple stock price today: AAPL climbs at the open as $315 target meets earnings week TechStock
JPMorgan analyst Samik Chatterjee bumped his Apple price target to $315 from $305, according to MarketScreener. Keep in mind, a price target reflects where an analyst expects a stock to land within a year—it’s not a guarantee.
Jefferies analyst Edison Lee remained cautious, maintaining a Neutral rating while cutting his price target to $276.47 from $283.36. These mixed calls highlight just how close the debate is ahead of earnings.
A tech columnist finds the Apple Health ChatGPT integration raises major red flags after feeding the AI bot a decade of Apple Watch data.
ChatGPT launched its ability to integrate Apple Health data on January 7, 2026. So Fowler connected ChatGPT Health to 29 million steps and 6 million heartbeat measurements stored in his Apple Health app, then asked the bot to evaluate his cardiac health. The results alarmed Fowler: ChatGPT gave him an F grade. Panicked, he went for a run and sent the report to his actual doctor.
His doctor’s response? “No,” Fowler wasn’t failing. In fact, his heart attack risk was so low that insurance likely wouldn’t cover additional testing to prove the AI wrong.
“The more I used ChatGPT Health, the worse things got,” Fowler wrote.
LLMs don't make good doctors. In fact they are quite dangerous. An opportunity for Apple to expound on its descriptive vs. prescriptive approach to health data.
Consensus estimates Apple to post about $138.4 billion in revenue and both GAAP and non-GAAP earnings per share (EPS) of around $2.67 for the December quarter. The numbers highlight at least an 11% year-over-year growth in EPS and revenue, but analysts are now tightening their margin forecasts despite favourable iPhone sales and AI roadmap.
In a note, Morgan Stanley analyst Erik Woodring reiterated an Overweight rating and an unchanged price target of $315, but cautioned investors that Apple stock could “trade sideways to modestly lower after earnings.”
The firm expects Apple to beat expectations, driven by stronger, more persistent iPhone demand. Woodring expects December-quarter revenue of about $80 billion, around 4% above consensus, and March-quarter revenue of $55.4 billion, about 8% above consensus, citing supply-chain checks and shipment data.
He said iPhone 17’s “strength remains underappreciated by the Street.”
Morgan Stanley sees cost assumptions as overly optimistic. The firm forecasts March-quarter operating expenses about 7% above consensus and a gross margin forecast 30 basis points below consensus, driven by rising memory costs.
As a result, Woodring sees limited scope for positive EPS revisions for Apple, even with a revenue beat.
Morgan Stanley also flagged potential downside risk to June quarter earnings, estimating EPS of $1.62 versus the consensus of $1.71, citing intensifying memory-related cost pressures. The firm also notes that Apple has historically underperformed the S&P 500 more in Q1 than in any other period.
Looking ahead to 2026
All things considered, Morgan Stanley believes Apple is positioned to outperform in 2026 as a wave of new products and AI-driven catalysts is set to shape the company’s growth trajectory. The firm particularly highlighted the relaunch of Siri in February and Apple Intelligence in June at Apple’s Worldwide Developers’ Conference (WWDC). Some notable introductions expected include its most “innovative iPhone in 10+ years (Foldable)“, plus the first smartphone powered by 2-nanometer chips, part of the iPhone 18 family.
The firm sees greater benefits from share gains and higher average selling prices, with Morgan Stanley underscoring an EPS of $9.77 for FY2027, roughly 7% above Wall Street consensus.
Earnings will be above consensus. All eyes will be on how margin guidance due to pressure from memory pricing. Every year it's another thing that is cause for drama. It never matters.
JPMorgan has raised its price target on Apple stock to $315 from $305, maintaining its overweight rating, as the bank expresses optimism…
JPMorgan boosts Apple price target to $315 ahead of earnings, citing strong iPhone 17 demand appeared first on MacDailyNews.
NB:
The iPhone 17 demand was evident during the last quarterly update from Apple. Management provided guidance one month into the quarter (and we are now one month into the next quarter) such that y/y growth of at least 13% in iPhone revenues was the only way to match that guidance.
As we approach the earnings release for the first fiscal/fourth calendar quarter for Apple, it's time to look back three months at what the company delivered and guided in the previous quarter.
The summary for results for fourth (fiscal) quarter of FY2025:
Revenue up 8% year-over-year, a new September quarter record.
EPS was up 13% year-over-year.
Product revenue was up 5% year-over-year driven by growth across iPhone and Mac.
iPhone revenue was up 6% year-over-year, and set a September quarter record despite supply constraints faced on several iPhone 16 and iPhone 17 models.
The iPhone active installed base grew to a new all-time high and had a quarterly record for upgraders. Also, Apple reached a new all-time high for installed base of active devices.
Mac revenue was up 13% year-over-year, driven by MacBook Air. Apple grew in every geographic segment, with strong double-digit growth in emerging markets. Mac installed base reached another all-time high, with nearly half of customers who purchased a Mac being new-to the product.
iPad was down 3% revenue and but over half of the customers who purchased iPad this quarter were new-to the product. iPad also had a September quarter record for upgraders.
Wearables, Home & Accessories Revenue for the category was flat y/y. Apple saw a September quarter record for upgraders to Apple Watch, and over half of Apple Watch buyers were new-to the product.Both the Apple Watch and AirPods installed bases reached new all-time highs.
Services again set a new all-time revenue record up 15% year-over-year. Apple saw double-digit growth in both developed and emerging markets. Apple saw a sequential acceleration across the majority of the categories and set new all-time records across Advertising, App Store, Cloud Services, Music, Payment Services, and Video. Apple saw a double digit growth in Apple Pay.
Guidance was provided as follows:
We expect iPhone revenue to grow double digits year-over-year, which would be our best iPhone quarter ever. On Mac, keep in mind, we expect to face a very difficult compare against the M4 MacBook Pro, Mac Mini and iMac launches in the year ago quarter. We expect Services revenue to grow at a year-over-year rate similar to what we reported in the fiscal year 2025.
We expect gross margin to be between 47% and 48%, which includes an estimated impact of $1.4 billion of tariff-related costs. And so for the December quarter, we expect operating expenses to be between $18.1 billion and $18.5 billion. We expect OI&E to be around $150 million, excluding any potential impact from the mark to market of minority investments and our tax rate to be around 17%.
Based on these forecasts my estimates for the top, bottom and middle lines are as follows:
Revenues: $140 Billion (+12%)
EPS: $2.70 (+12.5%)
iPhone: $78.9 Billion (+12%)
Mac: $9.4 Billion (+4%)
iPad: $8.5 Billion (+5%)
Wearables: $12.9 Billion (+10%)
Services: $30 Billion (+14%)
If there is an error in the above I would guess it's in iPhone being too low and the iPad/Mac and Wearables being too high. Nevertheless, I think this will be Apple's biggest quarter ever with significant growth acceleration on the top and bottom lines. [Notable will also be a rapid acceleration in R&D spending (+25%) as suggested by guidance.]
As we head into this blockbuster quarter, Apple shares are trading at a P/E ratio of 32 to 33, a significant drop from above 35 during previous few quarters. During the last three months, the share price has declined about 15% as Mr. Market looked at the money mountain above and decided he wanted none of it.