Asymco

Asymmetric Intelligence

Latest from Asymco

  1. That Competition Thing

    Research · 62 comments

    Bill, I think the smartphone market has always been competitive. [Only] the names have been changed.

    Tim Cook responding to Bill Shope's question on the competitive landscape, April, 2013.

    Indeed, over the years, the companies considered Apple's primary competitor have been many.

    In years gone by in the phone market there were RIM and Nokia and Palm and HTC. In the iPod era there was Creative and Sony and innumerable others long forgotten (not to mention the tyranny of DRM).

    Even today we struggle to decide whether Apple competes with Google first or Samsung. Or perhaps with the iPad it's with Amazon or  Microsoft. Or maybe iTunes is threatened by Netflix or Spotify. The Mac surely competes with HP and Dell and Toshiba. What about iCloud? Clearly it's Dropbox or Google Drive. iWork? Both Office and Google Docs.

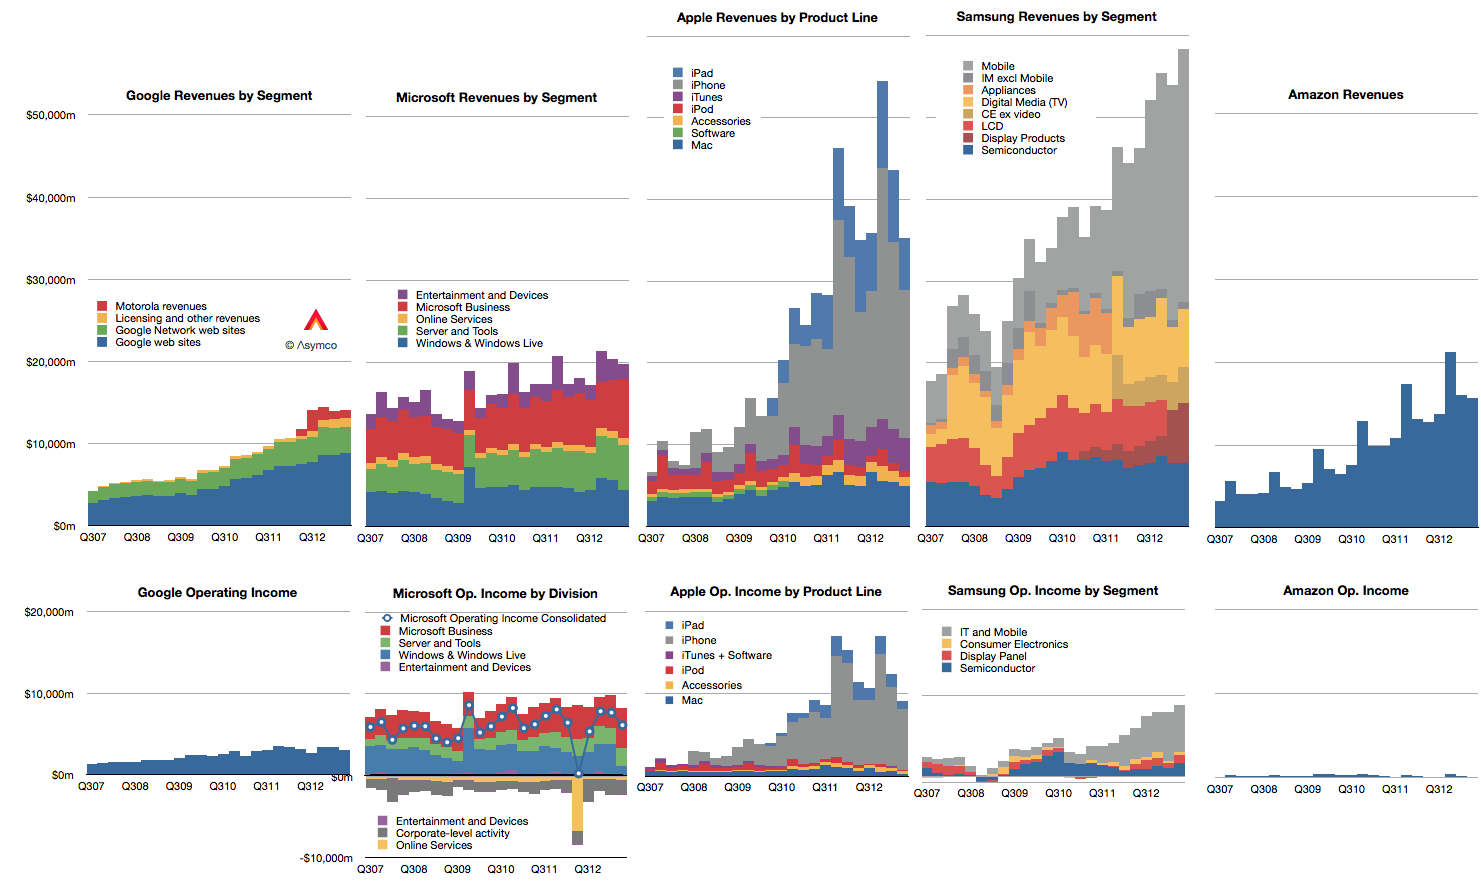
    Doing a competitive analysis for Apple is then mostly a struggle of whom to compare it to. So forgive me that I only track the few challengers shown below.
    Screen Shot 2013-08-13 at 8-13-2.14.59 PM

    Note also that these companies all may compete with Apple to some degree but they may not compete with each other. Competition, it seems, is not transitive.

    There isn't much that I can observe in the data that hasn't already been observed. Google shows steady but not spectacular growth in revenues with decreasing margins. Microsoft shows even more modest growth in revenues with flat earnings. Apple growth is moderating from near vertical while earnings pause. Samsung has great growth but there is a similar set of doubts about its sustainability and finally, Amazon continues to grow the top line by 20% and  has nothing to show for it.

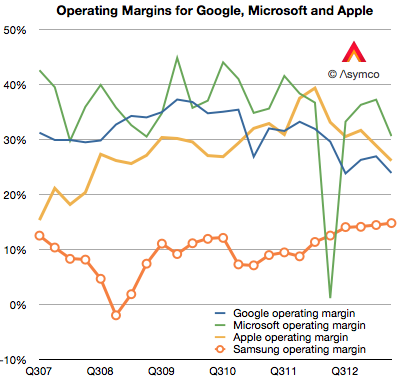
    Operating margins have mostly fallen with the exception of Samsung whose increasing reliance on smartphones has led to a modest increase, though not nearly to the level of the others. (Amazon, lacking in profits, cannot be compared.)
    Screen Shot 2013-07-30 at 7-30-10.54.44 PM


    In summary there is little change to report.

    Except that it's been reported that in the last quarter Samsung managed to "dethrone" Apple from the phone operating profit crown. This is a matter of estimates and for that we need to understand clearly the assumptions.

    I estimate that this is not the case. That indeed Apple remains most profitable phone maker by a wide margin.

    To estimate operating margins you need to estimate gross margin and the allocation of operating expenses (SG&A and R&D) to a particular "division" or product line. The problem is that Apple does not operate as a divisional organization so its marketing and R&D budgets (i.e. people) are not assigned permanently. You have to move them around based on whatever is being worked on at any given time.

    What's more, we need to account for the huge SG&A costs associated with iTunes and Retail. They both consume vast resources which cannot be allocated directly to any product. There are 41,000 people working in retail.  Also, some of the expenses for iTunes are overhead and cannot be considered cost of sales. That's also SG&A. Then there's corp research and design (Mansfield and Ive), which are not allocated to any particular product. When you slice out these costs, there is very little to apply to iPhone, etc.

    So if (and it's a big, sanctimonious if) you want to cast iPhone out as a separate business unit, it would be wildly profitable. There is a huge gross margin of 46% (this assumes a cost per unit of $316) and only another 5% of sales spent on engineering and marketing leaves a 41% operating margin or $7.4 billion. (Why only 5%? Because there's only 10.8% to allocate and after taking out iTunes, Retail you're really only left with 4.49% for SG&A and 3.3% for R&D or 7.79% so 5% is about two thirds of the operating budget).

    If you take all of Samsung's IM division which is PCs, Tablets and phones their operating profit was only $5.6 billion.

    You can see the difference in the grey areas of operating profit in the first graph above.

    Bear in mind that this is still an artificial comparison. The split of profit between product groups is not only an estimate by the analyst, it would be an estimate for Apple itself since it has only one P/L.
  2. The iPhone Stores

    Research · 29 comments

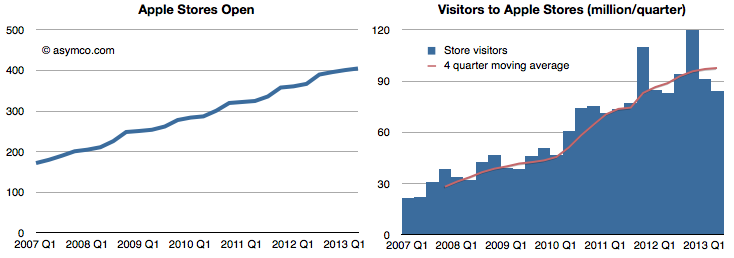
    Here are the latest performance figures for the Apple stores:

    Stores Open and Visitors

    Screen Shot 2013-07-30 at 7-30-2.17.25 PM

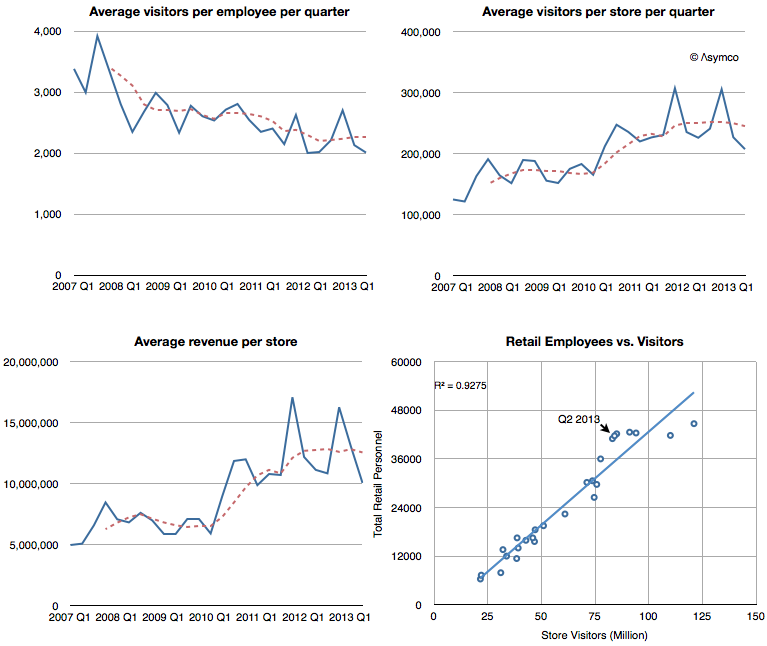
    Visitors per employee,Visitors per store, Revenues per store and Employees correlated with Visitors.

    Screen Shot 2013-07-30 at 7-30-2.15.23 PM

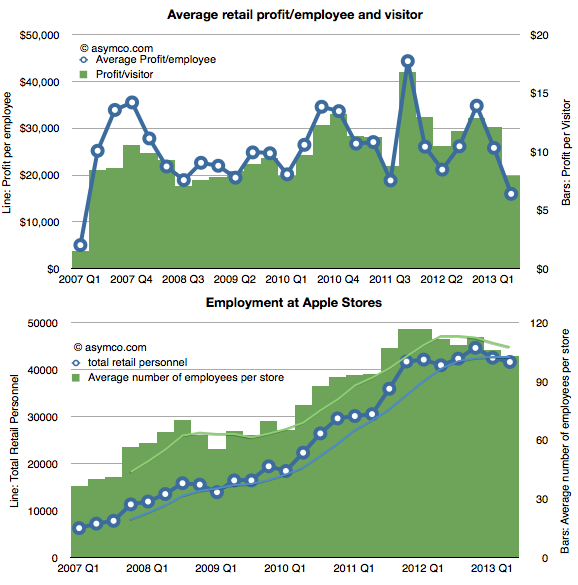
    Employment and Profitability (per Employee and per Visitor)

    Screen Shot 2013-07-30 at 7-30-2.17.48 PM

    The pattern that seems to appear is one of a plateau or peaking of sales, especially when values are seen on a per-store basis. Revenues, employment and visitors per store are all flat or slightly down when seen on a seasonally adjusted basis (trailing four period average).

    Profitability has been more steady over a long period, though more volatile in a short-term window.

    Seen in isolation, Apple Stores would appear to be coming to a point of quiescence.  But they should not be seen in isolation. Apple Stores mainly sell Apple products, so if Apple products slow then retail sales should also slow.

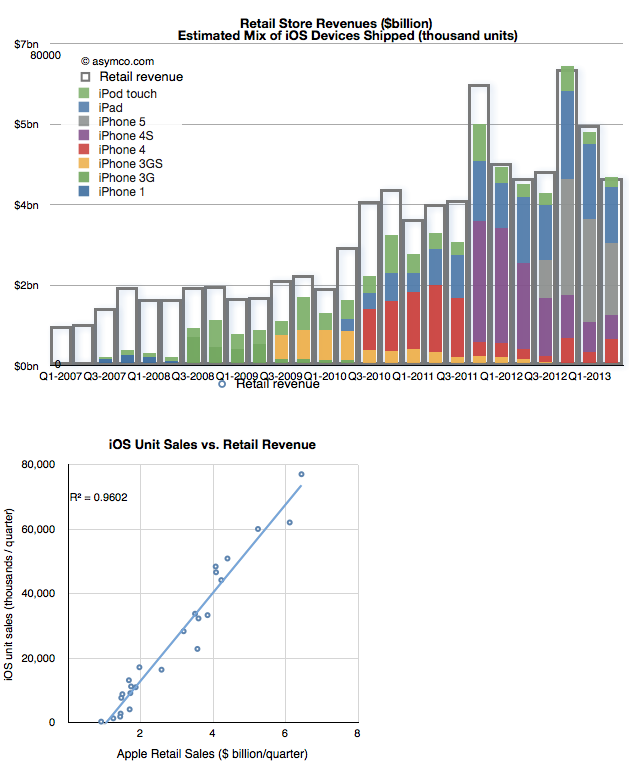
    Indeed, in 2007 Steve Jobs told Fortune that the Apple stores had been built to sell the iPhone and in 2010 Ron Johnson said the Apple stores had been built to sell the iPad. These statements were meant metaphorically but they are literally true when looking at what is actually sold. The following graph shows the relationship between iOS device sales and Retail revenues.

    Screen Shot 2013-07-30 at 7-30-2.17.56 PM

    The first chart shows the relationship plainly enough and the r-squared coefficient of 0.96 puts a finer point on it.

    So at the end of the day, the performance of the Apple stores depends on the performance of Apple's portfolio of products. It stands to reason that as iOS units slow, Apple stores should as well.

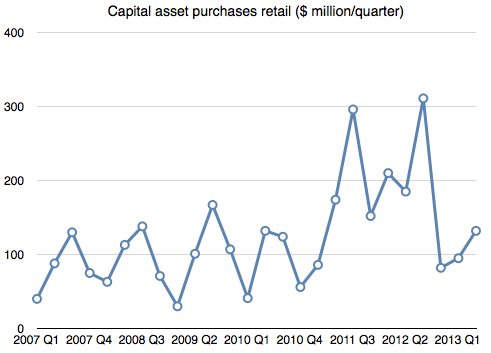
    This is something Apple management should be well aware of. Therefore, if Apple were confident in the future of iOS it would be investing in retail (as it would in other capital projects like manufacturing.)

    And that answer would be here:

    Screen Shot 2013-07-30 at 7-30-2.47.21 PM
  3. Apple's biggest acquisition

    Research · 76 comments

    At the end of the first quarter 2013 there were 946,035,000 fully diluted shares of Apple stock outstanding. At the end of the second quarter there were 924,265,000. The 21,770,000 shares that disappeared were purchased by Apple and retired. Apple shares traded between $390 and $463 during the quarter so it's hard to know exactly how much Apple paid for them, but at an average of $426.5 per share Apple would have spent $9.3 billion

    Management explains:

    In late April we executed a very successful debt offering issuing 17 billion of debt across 3, 5, 10 and 30 year maturities. We paid $2.8 billion in dividends in the quarter and we also utilized a total of $16 billion in cash on share repurchase activity through a combination of a new accelerated share repurchase program and open market purchases. $12 billion of the $16 billion was utilized under a new ASR program initiated with two financial institutions in April.

    An initial delivery of 23.5 million shares was made under this program with the final number of shares delivered in average price per share to be determined at the conclusion of the program, based on the volume weighted average purchase price of Apple’s stock over the program period, which will conclude in fiscal ‘14. In addition to the new ASR, we executed $4 billion of open market share repurchases, resulting in the retirement of 9 million additional shares.

    Later, during Q&A:

    Tavis McCourt - Raymond James: Thanks for taking my question. Peter, first a clarification on the share buyback and can you tell us what the ending basic share count was in the third quarter?

    Peter Oppenheimer: All of that is on the income statement, so you got the ending basic and diluted, but let me give you a couple of points that I think could be helpful for you. During the June quarter, we concluded the first $2 billion ASR program that we started in December and then so we got the final shares in on those, and we did our second ASR program of $12 billion, that started at the end of April and we received 23.5 million shares initially on that. And I went through in my prepared remarks, at some point during fiscal ‘14 that program will close and we will get the final number of shares. We also bought back $4 billion of stock in the open market during the June quarter and received about 9 million shares. So, the impact of those in the June quarter lowered our diluted share count in the quarter by about 22.9 million shares. And as you look forward into the September quarter before any further buybacks or any issuance to employees we would expect to see an additional approximate 11 million share benefit from the things that occurred during the June quarter.

    This is a bit convoluted, but it seems that Apple has committed to buy $16 billion worth of its shares but has not completed the retirements. They see an additional 11 million shares being retired from activities conducted in the June quarter. (Nota bene: when calculating future EPS, take these shares out of consideration.)

    If we add the 11 million yet-to-be-retired to the 21.7 million already retired and assume $16 billion was paid for them then the average price paid was $488.25.

    Not a bad price. Share re-purchases are valuable only if the price paid is low (a determination that is usually beyond the scope of management to make.)

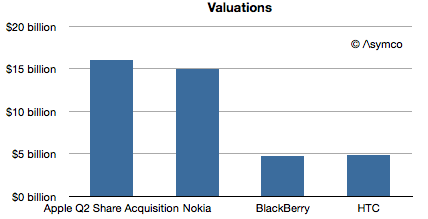
    But what is even more interesting is that if we consider the $16 billion expenditure as an acquisition, then Apple has made what amounts to its biggest. It's more than some familiar companies are worth:

    Screen Shot 2013-07-25 at 7-25-11.38.09 AM
  4. Apple’s 3Q FY13 Review (Padcast)

    Research · 16 comments

    Preview 3Q-13 screenshot

    Using interactive graphics and narration, this latest Apple Earnings Review discusses Apple's performance in relation of its historic performance as well as to expectations (published in the Preview) on the following topics:

    1. Guidance vs Actual performance: Now that Apple changed the way it provides guidance, are we seeing a new degree of precision in their signaling. We look at the history of earnings guidance and how effective (or not) the current method is in helping predict performance.
    2. Gross and Operating Margins analysis: What is the pattern of margins and how important are margins to the perception of competitiveness?
    3. Margins by product. How are margins allocated by product?
    4. Average selling prices for each product. Any surprises in Pricing? What was the magnitude, cause and significance of iPhone ASP drop.
    5. iOS product shipments. Comparison with expectations, trends and explanations. Overall iOS growth story.
    6. Cash balance and the effect on cash of share re-purchase.
    7. Sales growth and Earnings growth, a long term retrospective.

    Duration is about 1hr.

    As a reminder, the Padcast can be reviewed interactively users can access to the underlying data.

    It's available for download on the iPad for $19.99. Those who already bought the Preview will be receiving an updated version soon that includes the Review at no extra charge.

  5. Introducing Asymcar

    Podcast · 12 comments

    If Apple can have a hobby then so can Asymco.

    Jim Zellmer and I were having fun talking about cars and thought why not record our conversations and put them up for others to listen. That's how Asymcar got started.

    Besides having fun, what we plan to do is use the auto industry as a lens to understand how disruption works. Whereas Asymco is a narrative on an industry that is dynamic because of disruption, we hope to make Asymcar a narrative on an industry that isn't dynamic because of a lack of disruption. A sort of foil to Asymco (or maybe an Asymco Bizarro.)

    The approach is to use stories that everyone can understand whether you care about cars or not. The inspiration was the TV program Top Gear which satirizes the adolescence of the male mind, and thus appeals to all. With Asymcar we hope to bring a rich set of new metaphors to describe similarly curious phenomena.

    Check out the first Podcast: Tubular exoskeleton-type thing

  6. Switcher

    Research · 91 comments

    Nokia's Windows (Smart)Phone performance was drowned out last week by Microsoft's big announcement of the Surface inventory write-off. They are pieces of the same puzzle however.

    First, a look at Nokia.

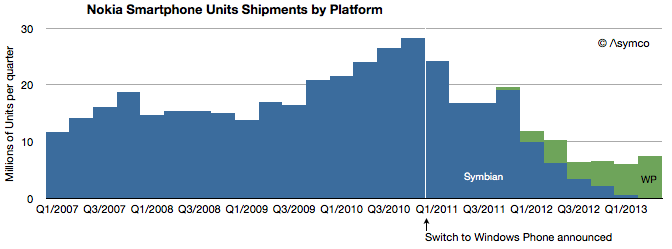
    There were 7.4 million Lumia phones sold in Q2 with 0.5 million sold in the US. Although Windows Phones grew sequentially from 5.6 million the previous quarter, and up from 4.0 million in the same quarter last year, total smartphones are down y/y and nearly flat over the last four quarters. This is of course because Symbian phones have finally disappeared from volume shipments. The following graph shows the history of Nokia's smartphone shipments.

    Although it's tempting to compare Lumia to iPhone (given the premium positioning in the US) the average price of €157 or $206 shows that Lumia is more adequately compared to Android. This is about a third of what Apple gets for its iPhones.

    That's not necessarily a bad thing. Nokia's always had a knack for mass-market phones and certainly that was one reason Microsoft was attracted to them. Presumably, the promise of the relationship was to insert Windows Phone into the Nokia development and distribution pipeline, squeezing out costs and filling up channels.

    Screen Shot 2013-07-22 at 7-22-3.24.21 PM

    The problem for the brand has been that although priced at Android levels, volumes are nowhere near and the gap is widening. At current activation rates, Android is selling 16.5x faster than Windows Phone (assuming 90% of Windows Phones are Lumia).

    So Nokia's problems become Microsoft's problems. As bad as Nokia seems to be doing with Lumia, it's doing a lot better than Microsoft with hardware. Here the story of the great Surface write-off should give pause. Microsoft announced that it would write off $900 million of Surface.  In terms of write-offs this is pretty significant. Compare it with the debacle of the PlayBook write-off when BlackBerry (then known as RIM) wrote off $485 million for tablets it could not sell. Or with Microsoft's own write-off for the Kin which took $240 million out of its shareholder's pockets. The only charge for hardware that I found higher was Microsoft's own Xbox 360 which cost it $1 billion for the "red ring of death".

    But this is not an unusual situation at Microsoft. Besides Xbox, Kin and Surface, Microsoft also declared victory in (read: shut down) SPOT watches, the Smart Display, Tablet PCs and the Zune. This is why when I heard about the Surface I asked who would be Microsoft's Tim Cook.

    By the way, $900 million write-off could amount to over 3 million devices, more if Microsoft is assuming some residual value in the inventory. Misjudging demand to such a degree that more units are disposed of than sold implies a basic failure of understanding of hardware businesses.

    Which brings up the question of what Microsoft will do. They are likely to double down on hardware (also signaled by their re-org) simply because in a device world (read: post-PC) the economics of licensing Windows and Office are evaporating. The price points of EULAs simply don't hold and there are good enough alternatives in use by the hundreds of millions of iOS and Android devices out there already. By withholding Office from iOS and Android, Microsoft has shown a billion people that they can live without it and they already knew they could live without Windows.

    So rather than fight, Microsoft chose to switch. Switching from software to hardware, however, is proving very hard. I'm sure quite a bit harder than management  thought.

  7. High Density #2: Tim Bajarin

    Podcast · 6 comments

    High Density is an interview show where we try to articulate what it means to be great. My guests offer observations and insights into the transformation of business and society through technology.

    Episode 2: Tim Bajarin

    Tim recalls the beginning, middle and end of the PC industry and we discuss the causes of each.

    via 5by5 | High Density #2: Tim Bajarin.

  8. What's an Android user worth?

    Research · 130 comments

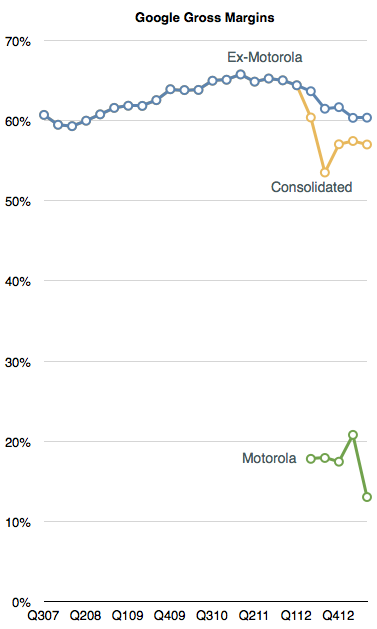
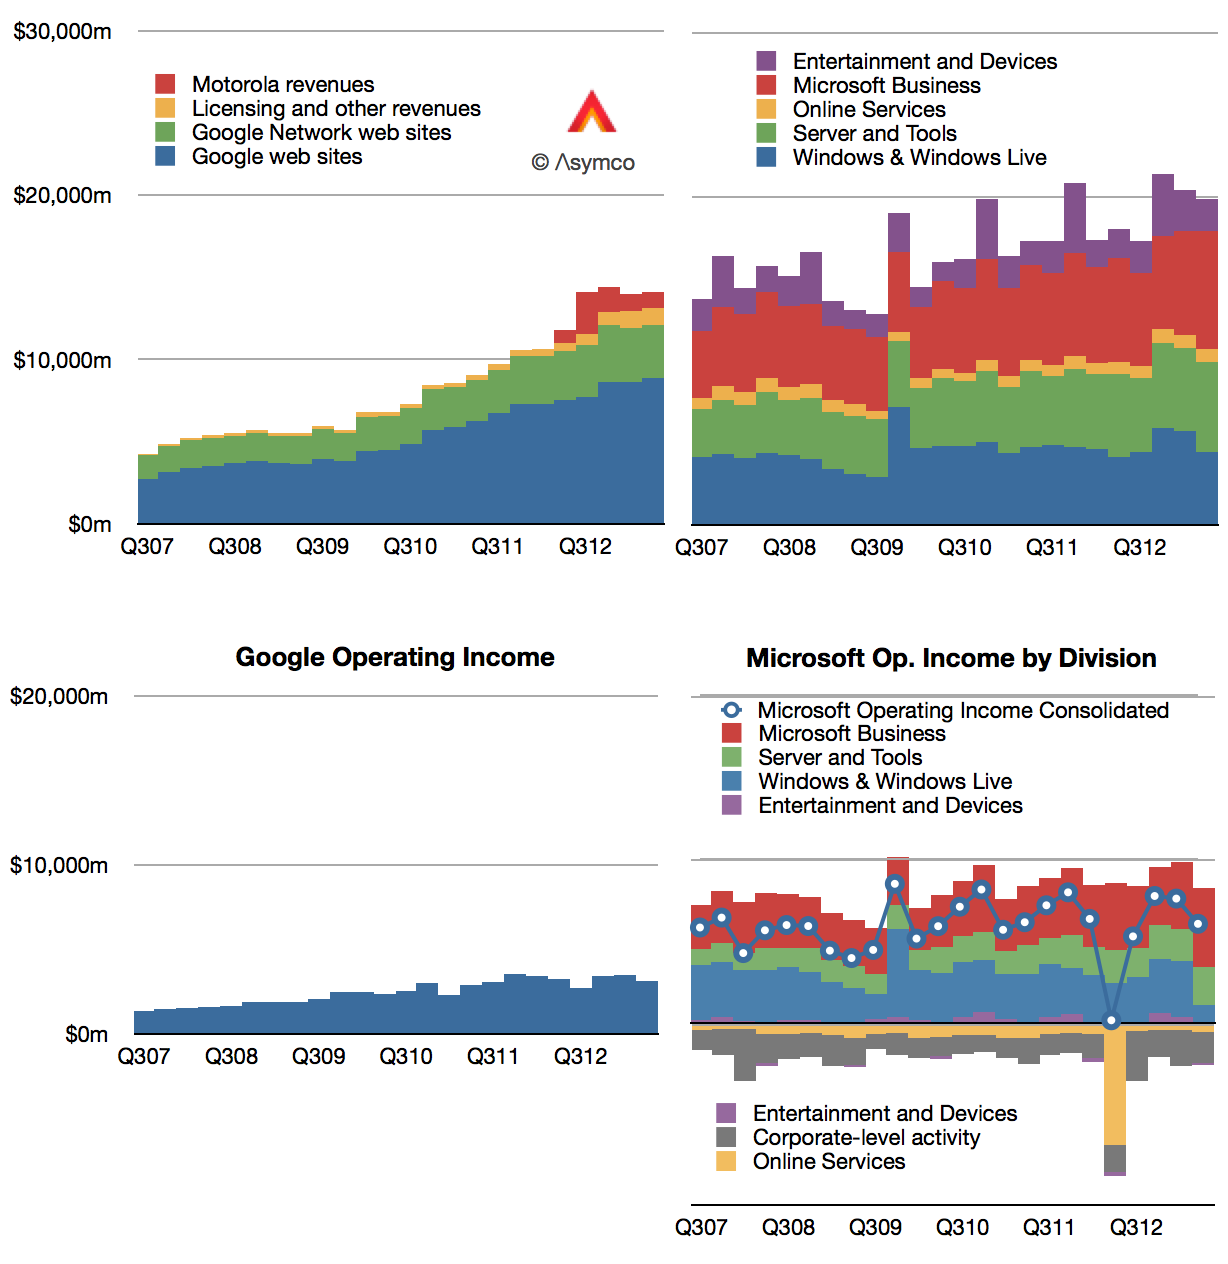
    Excluding Motorola, Google's gross margins have dropped for six out of the last nine quarters. They peaked at 65.8% in early 2011 but have now dropped to 60.4%. Including the drag from Motorola they are down to 57%.

    Screen Shot 2013-07-20 at 7-20-9.52.38 AM

    Gross margins include the effect of price, volume and direct costs of sales. Although sales have grown (see graph below), the pricing Google has been able to obtain (CPC) has fallen. The cause is unknown but there is a strong correlation between the growth in their mobile channel. For their part, management cites mobile as having an effect in reducing CPC though they caution that it's one of many factors.

    Screen Shot 2013-07-19 at 7-19-8.52.10 AM


    The elephant in the room is indeed the effect of 900 million activated Android devices (with 1.5 million added each day.) These nominal billion devices are a new channel that could be said to have doubled Google's addressable market in only the last three years. The effect of this doubling is perhaps partly underlying the top line growth shown above.

    How can we test this?

    I placed Google's performance alongside Microsoft's for a reason. Since Microsoft has had precisely zero benefit from any new mobile channels, and since its software is broadly tied to business spending (as is Google's), we can consider Microsoft as a control in what baseline non-mobile growth could be. From Q2 2010 to the present (the Android epoch), Microsoft's consolidated revenues grew by 24% (31% if we exclude Windows).  In contrast, Google's advertising revenues (excluding Motorola and licensing) have increased by a more robust 83%.

    So it's possible that mobile contributed to top line growth. The effect could be 50% over three years. The downside is of course that this comes from a doubling of the channel. The new channel is therefore half as engaging. In terms for bottom line, the effect would be seen as more subdued growth. Overall, income increased 32% for a nominal doubling of usage.

    Not that there's anything wrong with that.

    Expansion of user base usually comes with lower engagement and margins. I demonstrated the same effect with the vast expansion of iTunes customers.

    The only difference seems to be that markets reward Google's margin dilution but punish Apple's.

    Put another way, hypothetically, as she spends slightly less, the market value for an Apple user is disappearing while as he spends a lot less, the value placed on a Google user is increasing.

  9. The PC Calamity

    Research · 70 comments

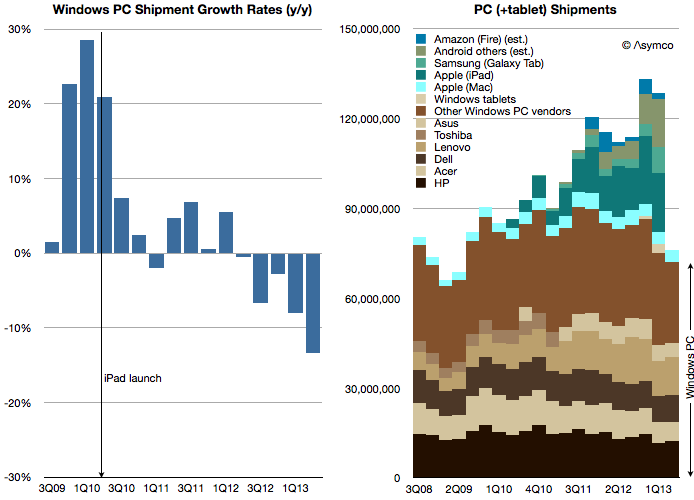
    As Intel has improved its products, their demand has decreased. Enormous efforts put into improvements are neither valued nor absorbed. The problem is not with the processors themselves but with the systems within which they are built:

    Screen Shot 2013-07-18 at 7-18-11.16.38 AM

    PC sales fell again last quarter and the contraction is likely to continue. We received affirmation of this as Intel cut sales and earnings forecasts and the crucial capital spending that creates supply in the longer term.[1]

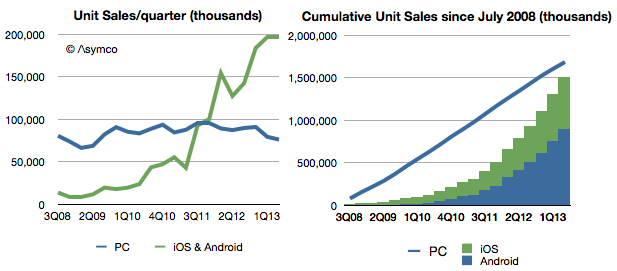
    At the same time, computing device sales have soared.

    Screen Shot 2013-07-18 at 7-18-5.07.35 PM

    Even excluding Android devices which don't register with Google's Play Store (and excluding Windows Phone devices), mobile ARM devices are selling at 2.6 times the rate of Intel-powered devices. Put another way, since the birth of Android nearly as many iOS and Android devices have been sold as PCs.

    In terms of install base, a computing category that did not exist six years ago has come to overtake one that has been around for 38 years.

    The calamity for Intel has been that they have had no part to play in the new category. Perhaps that is because they had every part to play in the old category.

    --

    Notes:

    1. Intel said it was cutting 2013 capital spending to $11 billion. The cut follows a reduction from $13 billion to $12 billion in April. Apple's budgeted capital spending for fiscal 2013 (ending September) was set at $10 billion.
  10. "Everybody has got a smartphone"

    Research · 63 comments

    … says UBS analyst John Hodulik, as quoted by the Wall Street Journal.

    No they haven't.

    According to the latest comScore survey data, 98 million Americans above the age of 13 don't use a smartphone as their primary phone. That's 41% of US mobile phone users.

    What's more, 2.5 million more people first started using smartphones in the three month period ending May vs. the three month period ending in April.

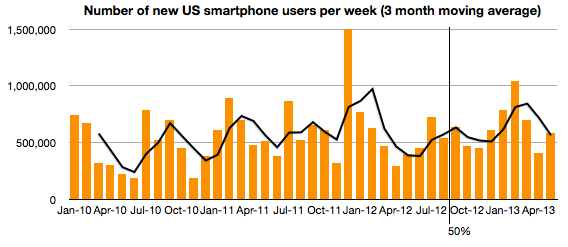
    The switching rate to smartphones is shown below:

    Screen Shot 2013-07-17 at 7-17-10.32.09 AM

    It shows the number of new-to-smartphone users who switched every week. It can be considered the "speed of adoption". The latest figure is 583k/week, above the 572k/week average maintained over the last 41 months.

    [I also added a three period moving average which shows a seasonal change in adoption. I also added a vertical line showing the point when 50% penetration was reached (August 2012).]

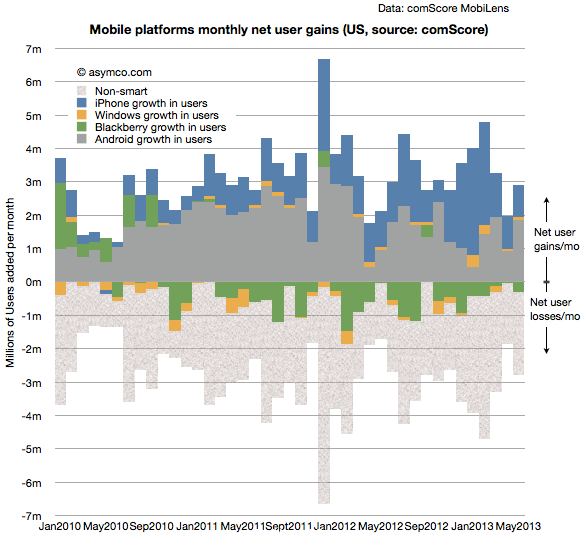
    The switching rate by platform is shown in the following graph:

    Screen Shot 2013-07-17 at 7-17-10.38.54 AM

    The data shows that churn between platforms (except for BlackBerry) is still negligible and that the majority of user losses can be attributed to non-smart devices.

    To summarize, with penetration now at about 60% in the US, the rate of adoption of smartphones is not slowing in any perceptible way.

    So not only is there no saturation, but there is no slowing of adoption of smartphones in the US, the most penetrated large market.

    Globally, the penetration of smartphones is less than half of that in the US. About 4 billion people are about to switch.

    Of course, they may not be willing to switch to what is currently offered to them in the market, but then again, the billion or so who adopted iOS and Android phones did not switch when the alternatives were BlackBerries, Palm, Symbian and Windows Mobile devices.