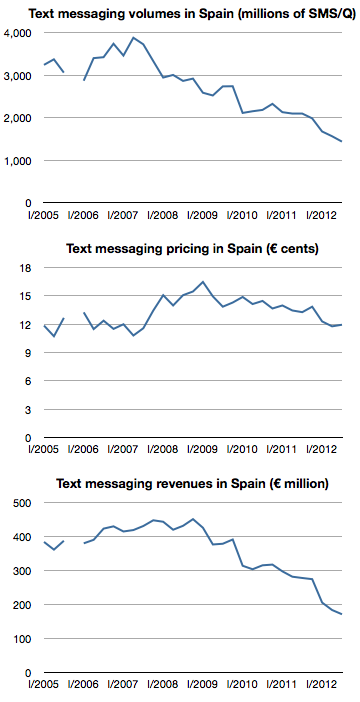
The following graphs show text messaging volumes, pricing and revenues for SMS in Spain.
After peaking at the end of 2008 at about €450/quarter, revenues have fallen by 60% to about €171 million in the third quarter of 2012. These figures represent almost 100% operating profit for operators so the impact is felt directly in the bottom line.
The culprit is IP-based messaging. Services like Whatsapp, iMessage and even Facebook offer "free" messaging to users who have a smartphone and a data plan. I've been told that 97% of Spanish smartphone users have Whatsapp installed. In some markets this "free" messaging is offered via BlackBerry Messaging.
The decline in SMS is coupled with a vast increase in IP-based mobile messaging. Whatsapp reported that it set a record of 18 billion messages processed over New Year's Eve. In October Apple announced that iMessage had delivered 300 billion messages during the preceding 12 months.
Globally SMS traffic is still rising. It's expected to reach 9.6 trillion in 2012, but at least one analyst forecasts that SMS’s share of global mobile messaging traffic will fall from 64% in 2011, to 42% in 2016.
The data from Spain suggests that the drop may happen more quickly than anticipated.
On assessing demand from "supplier checks"; measuring headroom and the race to a billion users; the disruption of computing becoming accepted by PC industry.
[Kaoru] Kato, president of NTT DoCoMo Inc., said that the firm would want to add the iPhone to its lineup of serviced smartphones if it could form a mutually beneficial contract with Apple, Inc.
Apple requires that carriers servicing its devices sell a fixed amount per year. Katō said that his company could handle such quotas if iPhones accounted for approximately 20%-30% of its overall smartphone sales.
When thinking about an iPhone launch, especially with a new operator, the crucial question is what is the minimum order quantity (MOQ). Some of the iPhone production is sold direct (as in the case of orders coming from Apple's online store) but the majority of units are sold via operator who order in batches.
This issue came to light when Sprint's order was leaked in late 2011. I discussed the order size at the time and put it in context. I concluded that Sprint MOQ was on average 7 million/yr., ramping with 4, 6, 9 and 12 million over a four year period. I concluded that this was not a particularly aggressive gamble.
Data published since then shows that Sprint actually sold 6.3 million during the first year, well ahead of my expected minimum order of 4 million and above even the expectations for the second year of sales. So far then Sprint and Apple gauged minimum demand quite accurately.
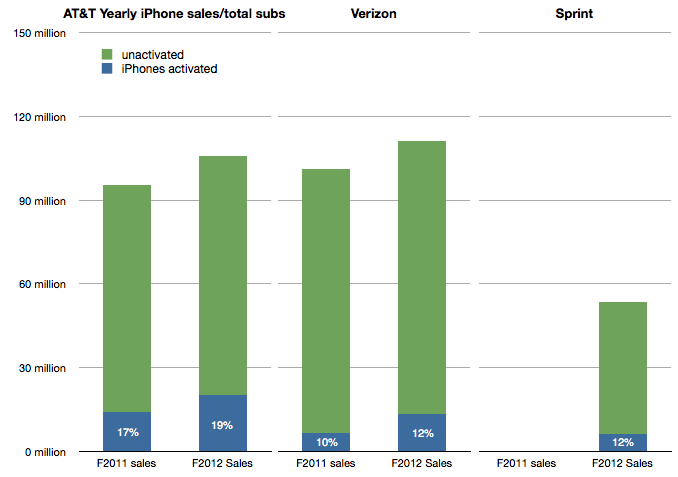
I also showed that the Sprint MOQ was probably indexed off their sub base. I suggested that, based on subs data at the time, Sprint was committing to roughly 13% of its subs buying an iPhone every year. This was indexed off the data showing that 17% of AT&T subs were buying iPhones every year and 10% for Verizon. (I also assumed that this run level would be ramped over time).
The updated totals for the 12 months ended October 2012 are 19% of AT&T subs purchased an iPhone, 12% for Verizon and 12% of Sprint. The performance is shown in the following graph:
Which leads us to think about how the MOQ for the iPhone is calculated. If we assume Sprint and Verizon performance is typical it would imply that an operator like DoCoMo would be required to purchase iPhones at the rate of about 10% to 12% of its sub base each year, modulated to some degree by a ramp.
NTT DoCoMo had 60.7 million subs in September 2012. 10% is about 6 million. Is Mr. Kato's quote above of 20%-30% of smartphone sales consistent with this?
In an earlier interview (in July) Mr. Katō also stated that the target for smartphone sales in the year to March 2013 was 13 million. 30% of that would be 4 million units.
This suggests that the iPhone MOQ for DoCoMo is only about 6% of subs. (4 million) Perhaps this is the basis of negotiation for an iPhone deal. Apple may have held out for 10% subs/yr. with Sprint on the basis of performance of the iPhone in the US but might be willing to settle for 6% subs/yr with DoCoMo, at least for the first year.
The MOQ figure as percent of subs for China Mobile would also be an interesting point of debate.
I last looked at the race to a billion in March 2011. Since then, I've been updating and adding data to the set giving a broader selection of platforms to compare.
Before we dive in, an explanation: the initial review excluded Windows (PC) and Facebook mainly because (a) the ramp scale I'm using is about a decade in duration and (b) I was reluctant to compare platforms that require payment to join to those that don't. The (DOS/Windows) PC ramped over several decades (starting in 1981) and Facebook is a service that costs nothing to join. There was much gnashing of teeth and shaking of fists as a result.
Therefore, in the interest of inclusion, I added both to the data set and let the chips fall where they may.
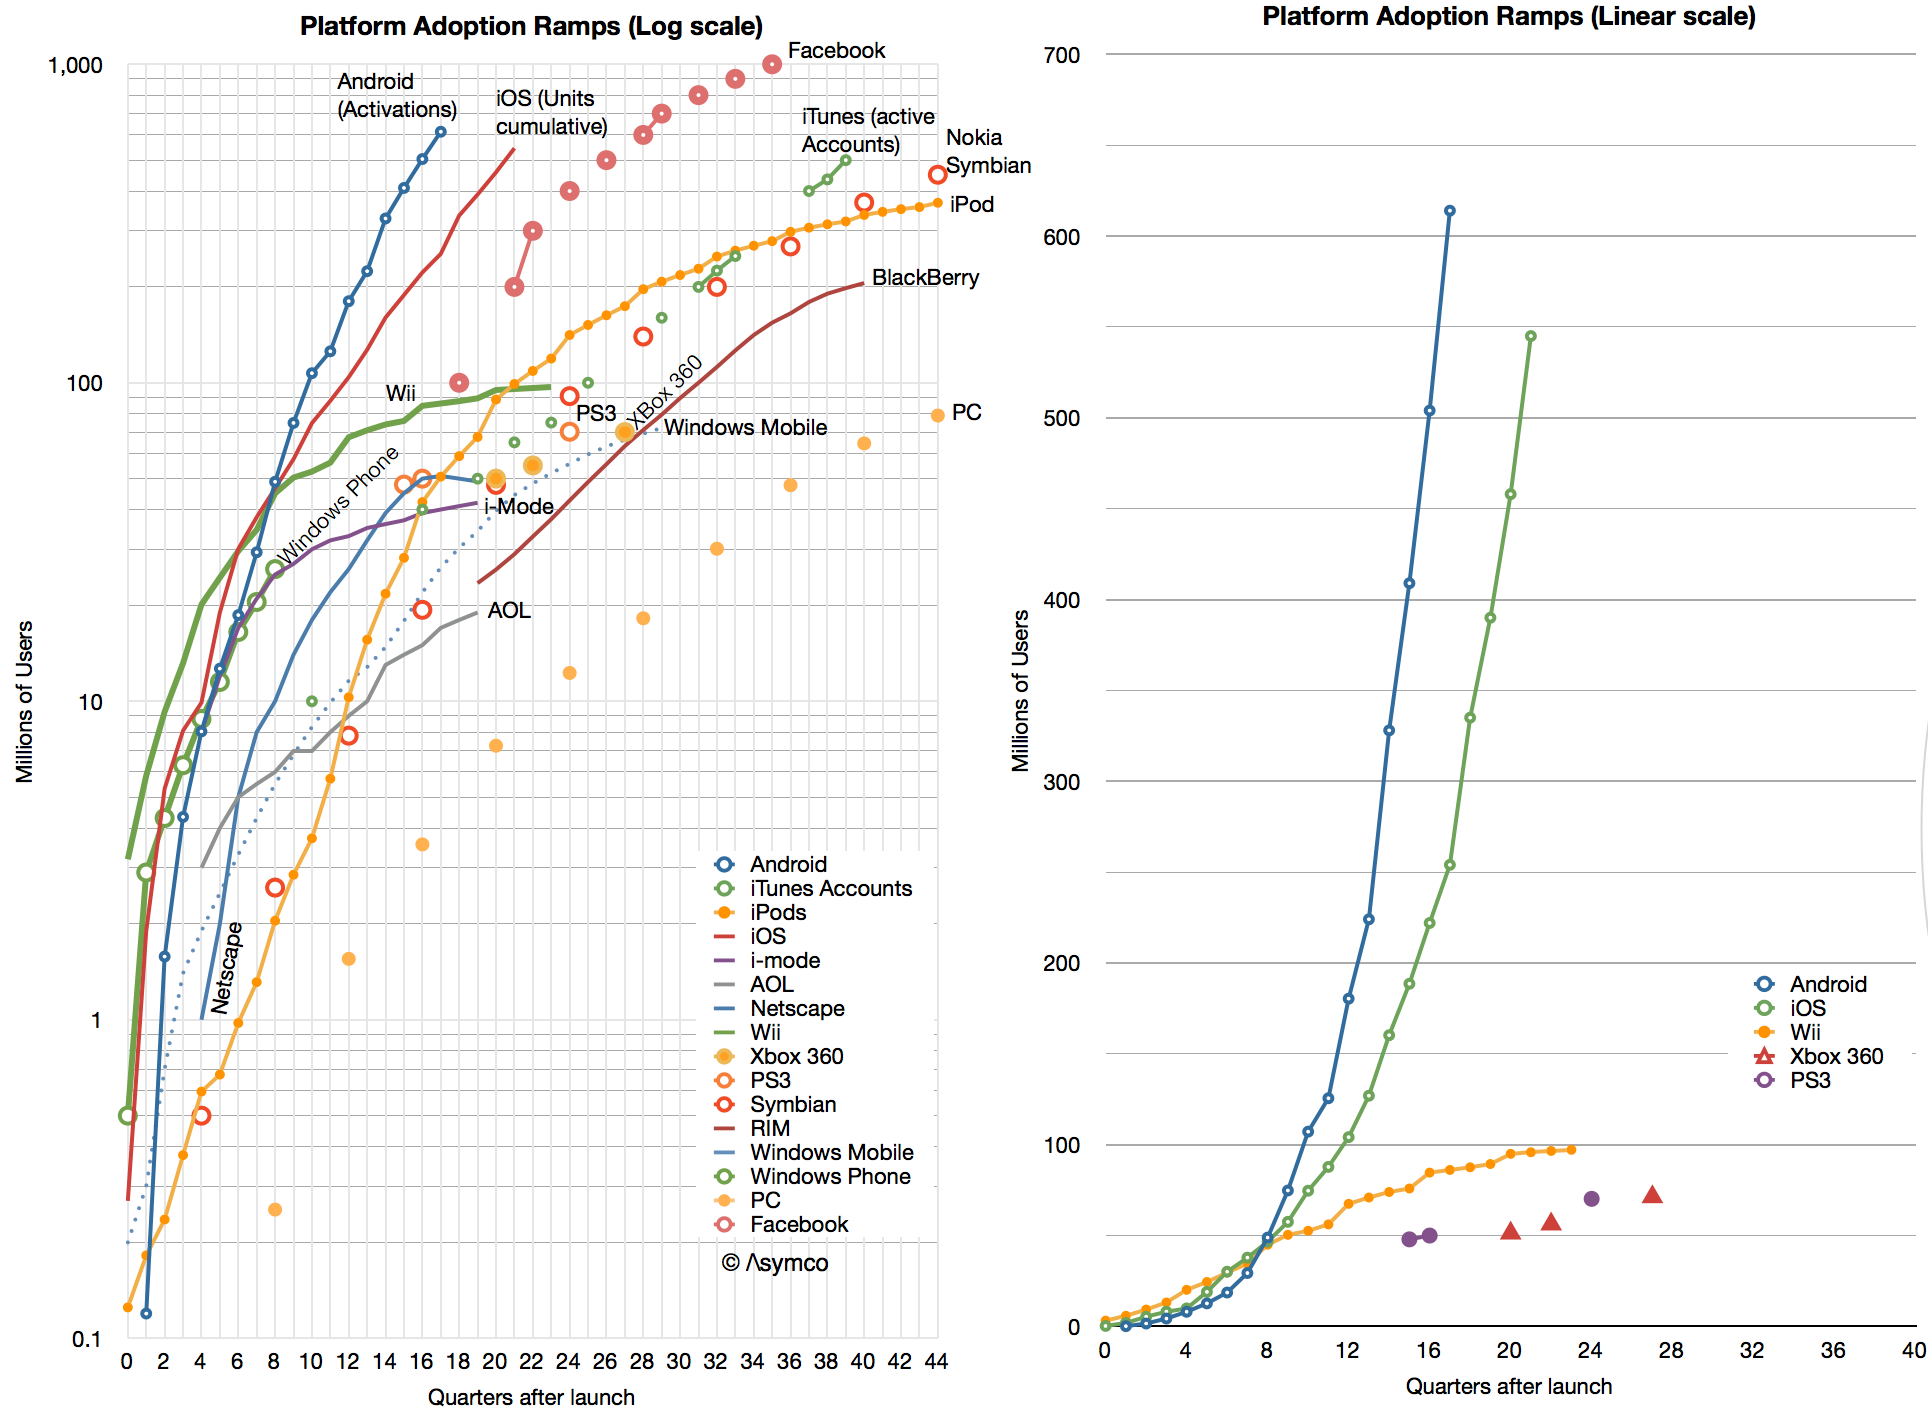
The data is shown below.
I kept the scale to about a decade so that individual lines can be resolved. As a result, you'll note that although Windows reached one billion first it did so slowly enough to be off the scale shown. Indeed, the "race to a billion" should be titled "The race to one billion users in less than a decade".
In such a competition, the winner would be Facebook which, in October 2012, 35 quarters after launch, reached the finish line. The second looks to be Android (probably this year) and the third iOS (sometime next year.)
That may sound like the end of it, but what the graph also shows are the more subtle trends:
Game consoles seem to saturate at below 100 million total. One can see the difference in ramps between recent mobile platforms and consoles in the second chart. There might be implications for which platforms will end up dominating the entertainment industry. There should also be some explanations of why consoles are so limited.
iTunes accelerated with iOS and left the iPod behind. This is unsurprising but it shows that a content platform can be more flexible than one attached to any particular device or architecture. An important lesson perhaps for those in the content businesses.
Early mobile platforms like Nokia's Symbian, RIM BlackBerry and Windows Mobile have faded indicating that there was no early-mover advantage in platforms. The same can be said for early PC platforms.
Windows Phone began by tracking the Android/iOS ramps but seems not to be accelerating into its second year in a way that implies potential parity.
Although Facebook did reach 1 billion rather quickly the slopes of Android and iOS indicate that they may overtake it in overall ecosystem size.
One billion is significant in several ways: First, because it is the "high-water mark" set by Windows and signifies what a global platform needs to become to be essentially "universal". Second, because it implies sustainability. A threshold perhaps from which network effects are sufficient to sustain (assuming some switching costs and an ability and willingness to adapt e.g. software, content or time investments from users.) Third, because it implies sufficient value to the ecosystem (assuming a monetization mechanism exists e.g. Windows software developers and IT managers.)
Looking beyond this milestone however, there is no reason why it should be thought of as a barrier. Mobile connections number over 5 billion and computing is likely to reach most of them. Therefore one billion may turn out to be only 20% penetration. In fact, I expect this series of posts will need to be updated in 2013 as "The race to two billion."
In 2011 Apple increased the availability of the iPhone by adding operators. In 2012 Apple increased availability by bringing the phone to operators more quickly. The question is: how much did iPhone 5 availability increase, exactly?
There is a way to find out. As an approximation, Apple periodically reports the availability of new iPhones by country. For example, Apple stated that they reached 100 countries for the iPhone 5 before 2012 ended. They also gave similar launch data for the iPhone 4S. Graham Spencer did a good job showing how country roll-outs changed over time.
However, country-level availability is not ideal because countries vary greatly in their ability to absorb iPhones. Announcing availability in Mauritius is not nearly as important as announcing Madagascar. A better measure would be to track the countries' populations being added, or, better still, the populations which subscribe to operators who have a distribution contract with Apple.
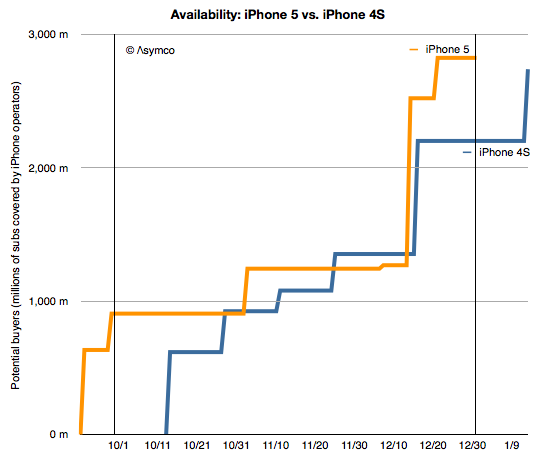
Which is what is shown in the following graph:
I plotted the "potential buyers" as the number of subs addressed by iPhone-carrying operators in the launch countries according to the time when the launches happened. I did so for the iPhone 4S in 2011 and the iPhone 5 in 2012[1].
Now we can address availability as the area under each of these lines.[2] The figure for the iPhone 4S adds up to be 100 billion "subscriber-days"[3] and for the iPhone 5 it's 130 billion subscriber-days during Q4 2011 and Q4 2012, respectively.
That's a handy measure: the iPhone 5 was 30% more available than the iPhone 4S. The big contribution was having China and Indonesia available during the fourth quarter rather than in January 2011.
There are a few observations which follow:
First, note that the increase in availability (area between the orange and blue lines) occurred both early and late in the quarter. The early period was mostly due to early launch in the US and the later period was due to earlier launch into China. China buying patterns are different than those in the US due to differing festive seasons so the bulk of Chinese buying may not happen during the fourth quarter.
However, delivery of product to China started earlier and there was a burst of buying (two million units in three days.)
Production should follow the availability schedule so it would be sensible to reduce production once the pipeline is full. Note that supplier cuts rumors surfaced right around the increased availability date of mid-December. Last year the rumors surfaced in November.
Increased availability does not always lead to increased sales but the iPhone 5 was constrained for longer than the iPhone 4S so it's possible that demand was therefore higher.
Increased distribution does not always mean increased production. However, Apple's investment in production tooling doubled year/year so there is a possibility that production did increase.
--
Notes:
Subscriber data is approximate. See addressable market discussion here.
The measurements are for the calendar quarter only, as bounded by the vertical lines.
A subscriber-day is a measure of availability where one subscriber has access to buy the product for one day.
In 2011 Microsoft's CEO bemoaned that revenue in China was about 5% of what it obtained in the US. Yesterday Apple's CEO suggested that revenue from China will overtake the US in the near future.
The contrast is even more stark when one considers the time and effort each company has made in China. Microsoft has been investing and promoting itself in China for decades while Apple barely had any presence 3 years ago.
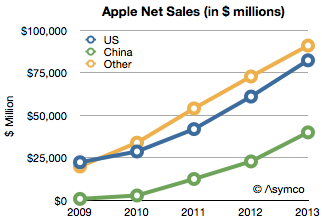
To put a finer point on this I show below Apple's sales by region:
Apple's China net sales in fiscal 2009 were only 769 million. In 2012 they were $22.8 billion. That is a figure greater than US sales three years earlier. Put another way, China sales grew in three years as much as they did in the US in 33.
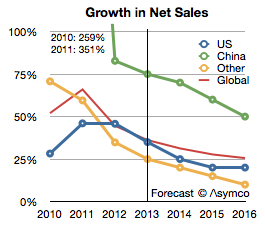
The growth rates were astronomical: over 250% in 2010 and 350% in 2011. In 2012 the growth slowed to 83% but that is still almost twice the US or the global average. The growth rates are shown in the following chart:
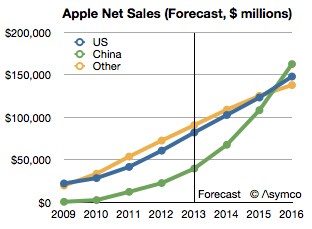
I added an estimate for growth into the future moderating to 50% for China and 20% for the US. If that happens then China will become the largest market for Apple by 2016 as shown below.
The reason for this growth is, of course, the iOS product lines. Growth started when the iPhone was introduced and surged with the iPad and every time updates were released.
The contrast with Microsoft now comes back into focus. China and the US have a roughly equal number of PCs but the mobile users in China exceed the US by a factor of three to one. The pool of users is so great that Apple obtained its growth even with reaching only 30% mobile network distribution coverage.
Without a mobile portfolio Microsoft is severely hampered. Of course, Microsoft is trying and has made several attempts to place its Windows Phone in the hands of Chinese users. It's a tough sale however because Microsoft must work through partners. They need to get vendors to license the OS and the operators to range the devices and retailers to push it. Given the flood of "free" Android variants they are having trouble even starting down that long road.
But more fundamentally, Microsoft's software licensing business model is severely limited in China because what it offers is not what is valued. Both on the PC or on the mobile device, what China values is the tangible. Software can be made valuable only if it can affect the purchase decision of hardware and it can do so only if it's sold as part of an integrated product. With Surface, Microsoft shows that it understands this. What does this imply for a Microsoft phone?
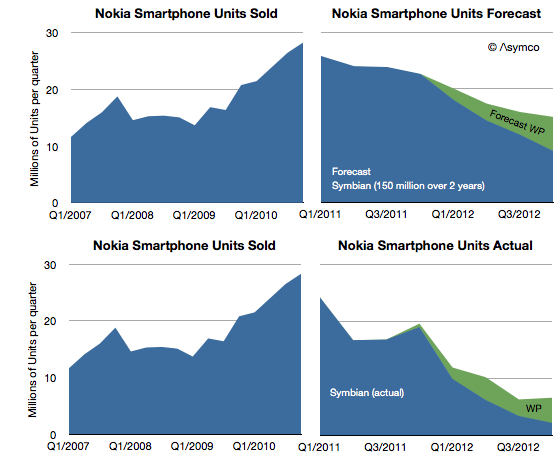
Nokia announced 4.4 million Lumia smartphones were shipped in Q4. That's about 14 million since the Lumia line was launched a year earlier. It isn't however nearly enough to replace the lost sales from Symbian. One year earlier Nokia shipped 19 million Symbian phones in the fourth quarter and the year before 28.3 million. The history of smartphone sales from Nokia is shown below:
I repeated the forecast I drew up in February 2011 when the platform switch was announced. That forecast was based on the company stating that 150 million Symbian phones would still be shipped. Symbian fell far more rapidly than I (and Nokia) expected and to date only 98 million have shipped. The last quarter's 2.2 million seems to be so low that it will be hard to imagine the platform lasting more than a few quarters.
My forecast for Windows Phone was 15 million (through Q4/2012) and the 14 million actually shipped is not far off. However, note that the sequential growth into the fourth quarter was lower than the same period last year. For the holiday quarter Nokia received almost no boost. If there is reason to be optimistic it's that there wasn't a decline in overall smartphones into Q4.
The overall result is that Nokia remains in an operating loss status and it's going to be very hard to recover. No phone vendor has successfully recovered to date. The company managed to book a €50 million one-time payment for IP rights (presumably from RIM) and is sustained by royalties and platform support payments from Microsoft. But even so it's barely breaking even.
The prospects for Windows Phone may be improving however. Operators in the US continue to talk about it. We don't have a split for AT&T's push this past quarter and estimates suggest that 80% of smartphone from AT&T were still iPhones but Verizon will also push the platform and there are suggestions it's doing well in Germany. HTC has also launched some WP flagship phones and may have had a good December as a result.
That translates into steady progress. But the growth of Android and iOS continue as well. Windows Phone needs to continue to persevere in adverse conditions for years to come. The Finns know a thing or two about that.
As it did yesterday, on occasion Apple reports the cumulative total downloads and payments to developers. Since this is done in variable time intervals, it makes analysis of the value of the app store difficult.
But not impossible.
The provision of developer revenues means we can determine the pricing of apps. The pricing of apps and the download totals allows us to determine the revenue of the store. Using the time stamps of the reports allows us to determine these quantities over time.
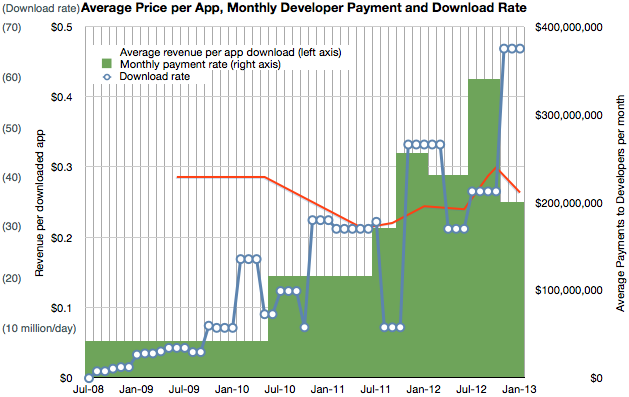
I've combined the data we have so far into the following graph.
It shows three quantities (on three separate scales) at a monthly resolution:
Download rate (in millions/day, interpolated from download totals)
Payment rate to developers (reported change in payment to developers/reported time interval)
Resulting revenue per download (in red, trailing average over a 10 month period)
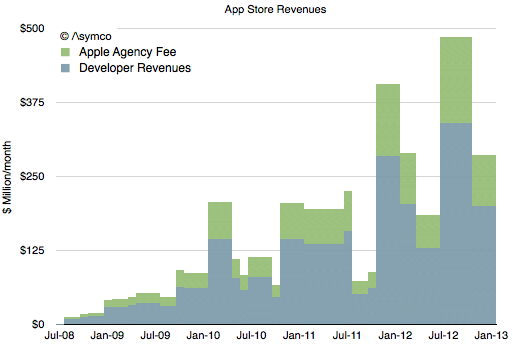
Having a price and quantity of app downloads allows for a complete picture of App Store revenues over time, shown below:
Note that I've separated the developer revenues from Apple's own revenues. The blue area should total cumulative developer payments (to a degree of error.)
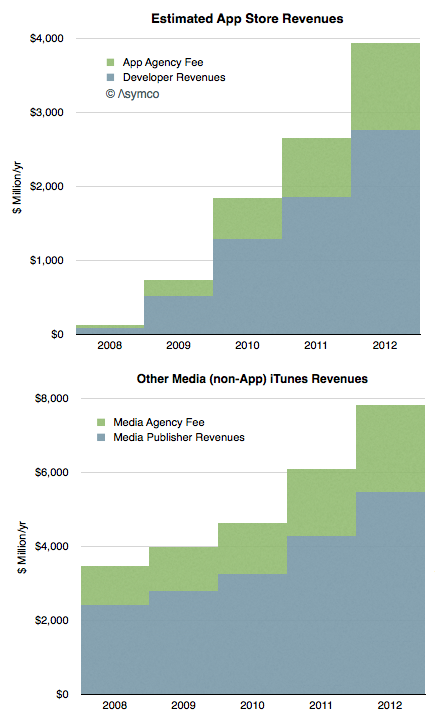
The green area above is what Apple includes in its financial reports as part of "Music" revenues. If we annualize these App Store revenues we can strip them out and show them separately from "other media" revenues.
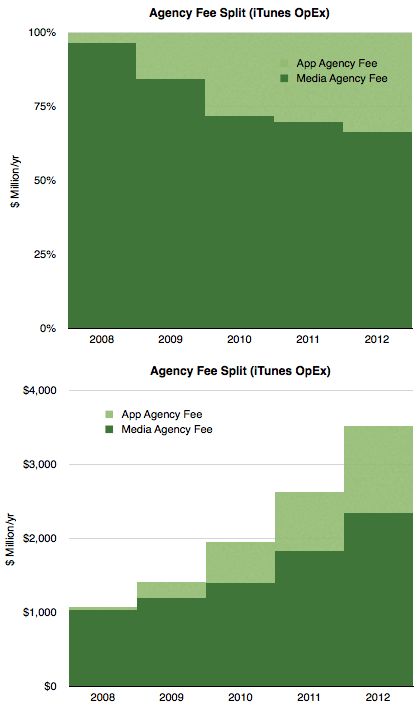
Concentrating on the green areas which represent what Apple "keeps" we see the following split:
Considering that Apple reports the iTunes store to being "slightly above break-even" then we can summarize the chart above as the operating expenses for the store.
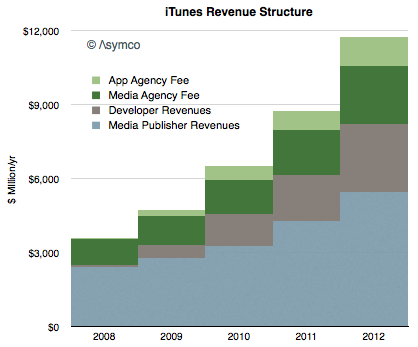
Finally, taking into account all the information above we can draw a complete picture of how revenues flow through the App Store:
Here are some conclusions:
The iTunes economy defined as gross revenues transacted through it is now about $12 billion/yr.
Over the last five years content owners (media and app) received a total of $24 billion while Apple spent about $10 billion to create those sales
Seen as a retail business, iTunes costs about $3.5 billion/yr to operate. This includes merchandising, payment processing and "shipping & handling".
Total revenues have risen steadily in a range of 32 to 38% compounded over the last 4 years.
Apps are now a third of all iTunes revenues, (about $4 billion/yr) having taken that share in only 4.5 years.
Non-app media still make up 2/3 of iTunes in terms of sales value but their growth is now 28% vs. about 50% for apps.
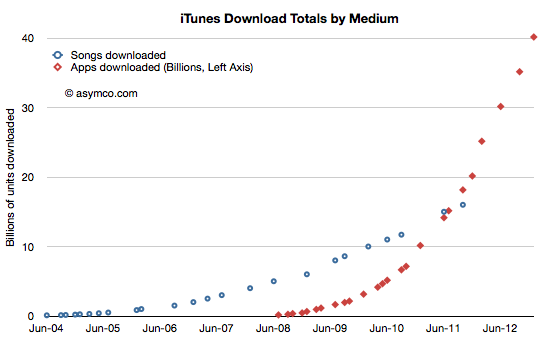
Apple reported over 2 billion unique app downloads (excluding re-downloads and updates) in December. The total downloads reached 40 billion, payments to developers reached $7 billion and the total iTunes accounts reached one half billion.
The total downloads is shown relative to total songs is shown in the following graph:
Although we have not received an update on song downloads for some time, it's probably safe to assume that twice as many apps have been downloaded as songs.
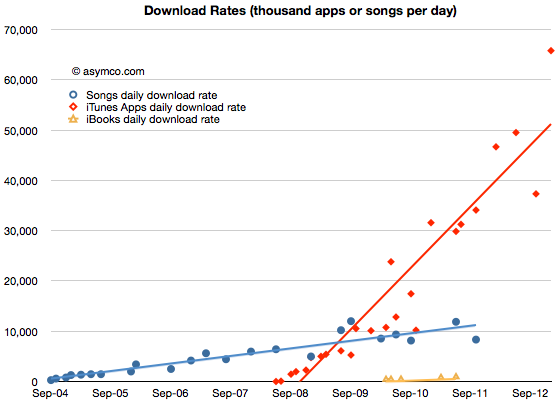
This data can be reduced to a download rate:
The apps daily download rate was about 65 million/day during the holiday period but may be averaging about 50 million/day on a yearly basis. Note however that the rate is increasing at approximately 1 million/day/month. That implies that the average rate will reach 100 million/day in 4 years and may spike to that level by 2015.
The revenues associated with that rate will be $14 million/day. More about that in the next post.
I've postponed my estimates for the fourth calendar for a long time. The reason is that there have been conflicting data to deal with and I've been hoping for some clues to give clarity. Unfortunately, even though I waited, I have not received many clues. Here are the challenges we have to deal with in this quarter:
Management gave very low guidance for the quarter's earnings and sales. Normally this should not be a concern since the long-term pattern has been for them to "sandbag" significantly. For example last year's fourth quarter was guided at $9.3 EPS while the company delivered $13.87, a 49% "beat" to their guidance. However Q2 and Q3 beats were only 7% and 13% respectively and if we assume a similar number (10%) for Q4 we get about $13/share which would be a year-on-year decline in earnings (down from $13.9). This has not happened for many, many years. Management explained this through a lengthy set of reasons including a shorter quarter (13 weeks vs. 14 weeks), new product launches, currency fluctuations, deferrals and unfavorable component pricing. Then again, similar explanations were used in the past with no reflection in what actually happened.
Management also launched a large number of new products. This normally leads to a surge in sales. In fact, 80% of revenues would come from a new portfolio of products. Having such a broad launch quarter into a holiday, would normally imply huge growth. Not only is this a critical launch quarter for many products but they also rolled out the iPhone to more markets more quickly than ever: 100 countries in three months. The broad roll-out implies a steeper ramp in production and thus more volumes. This would also contradict the lowered expectations from the CFO. However...
Production was constrained. It was quite a long time before waiting times decreased for the iPhone--longer than what we saw last year. In the earnings call Tim Cook said "It's difficult to predict when supply and demand will balance, but I'm feeling very confident on our ability to supply quite a few iPhones". This again implies significant acceleration but did they achieve the targets? He did also announce that they met their target of 100 countries during the quarter but it's not clear if this was as quickly met as they would have liked.
Margins are complicated. Launch quarters have lower margins typically and this is well understood. However, we have new products in the form of a new iPad at a new price point as well as the new iPhone which may have had some difficult manufacturing issues (i.e. yield). So how much faith do we put in the perennial pessimism in guidance?
There was a vast increase in CapEx in the prior quarter. Normally CapEx spending "leads" production and is in proportion to it. However, the surge in Q2 and Q3 seemed to be unmatched by vast new production, at least that's what we are led to believe by both consensus and by management guidance. Did this CapEx differ in character from previous CapEx? Was it more "strategic" and less "tactical"? Will the disconnect continue?
There are also the deeper questions:
Why there are no new operators being signed? The addressable market has not increased in the last 6 months. Why?
Is there a faster product cycle in the works? Is there a shifting of gears to a new product development process?
What's the nature of the relationship with Samsung as a supplier? Is their replacement characterizing the new type of CapEx spending?
All these currents make this quarter doubly difficult to forecast. And it does not help that it comes on the back of two weak quarters which were argued away as exhibiting transition effects.
So I'm very uncomfortable with my forecast and find it hard to defend this quarter. I considered not publishing one at all because it gives too much confidence when none is warranted. However, I received so many requests to publish that I relent and offer the following:
iPhone units: 55.5 million (50%/62%)
Macs: 5.0 million (-4%/+3%)
iPads: 24.4 million (58%/70%)
iPods: 11.2 million (-27%/-22%)
Music (incl. app) rev. growth: 25%/38%
Peripherals rev. growth: 10%/19%
Software rev. growth: 5.5%/14%
Total revenues: $60.0 billion (30%)
GM: 39.8%
EPS: $15.74 (13%)
I included two growth figures (in parentheses). The first is a straight y/y value and the second is adjusted by assuming there were 13 weeks last year (and that sales were evenly distributed over those weeks).
[We'll get a chance to go over this forecast and what is actually reported at Asymconf. Don't forget to sign up.]