Asymco

Asymmetric Intelligence

ASP

  1. Apple Remarks to Investors in FQ1 2018 Earnings Conference Call, Categorized and Annotated

    Conference · 149 comments

    The following is a transcript of the comments from Tim Cook (CEO) and Luca Maestri (CFO) at Apple's Q1 2018 Earnings Conference Call February 1, 2018. I color coded my interpretation of the comments into four categories:

    • Grey: Background and promotional commentary
    • Red: Strategy and signals of what management considers important and may include data beyond the regularly reported numbers.
    • Green: Financial data
    • Black: Commentary.
    • Blue: My commentary, in brackets.

    For a quick read of Apple's strategy, read the Red text. These comments are not repeated in financial reports. Highly recommended.

    For a quick read of Apple's financial performance, read the green text (which are replicated in financial reports). Read this if you don't want to wade through the financial reports.

    For marketing or product material, read the grey text.This is sometimes unique but also repeats product launch information.

    ----
    Tim Cook:  Thanks, Nancy and thanks everyone on the call, and welcome to everyone today. Before we dive into the quarter, I'd like to take a moment to talk about a significant milestone we recently crossed.

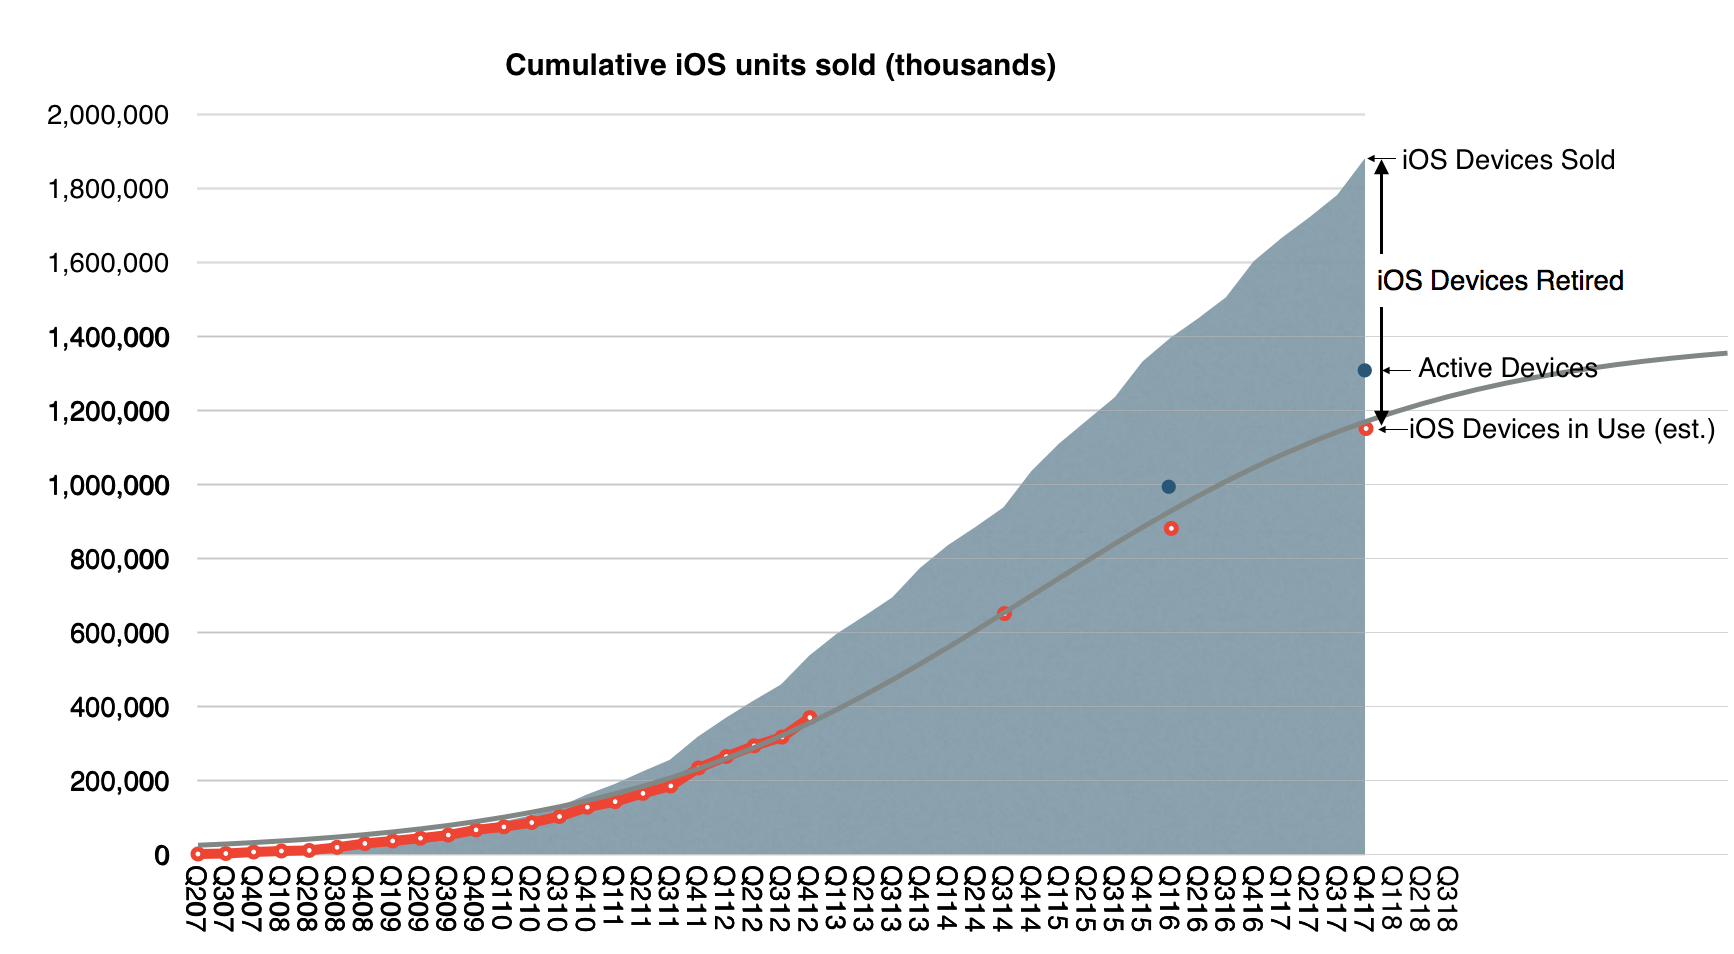
    Apple's active installed base reached 1.3 billion devices in January and is at an all-time high for all of our major products. 1.3 billion devices represents an astonishing 30% growth in just two years. It speaks to the strength and reliability of our products and our ecosystem, as well as the loyalty, satisfaction and engagement of our customers. It's also fueling tremendous growth in our services business, which I’ll talk about a little later in the call. [This is probably Apple's most important number. For at least the next 20 years this is the key performance metric and it can be used to derive company's valuation. A summary of the history of active devices vs. units sold is shown in the graph below:]
    Turning to the December quarter. We're thrilled to report Apple's biggest quarter ever, which set new all-time records in both revenue and earnings. We generated revenue of $88.3 billion, which is above the high-end of our guidance range, and it is up almost $10 billion or 13% over the previous all-time record we set a year ago.

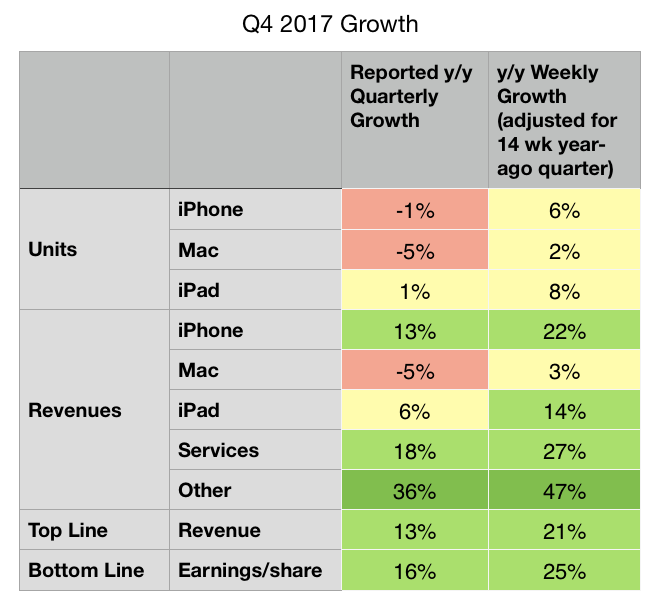
    It's also our fifth consecutive quarter of accelerating revenue growth with double digit growth in each of our geographic segments around the world. What makes us even more remarkable is that the quarter we're reporting today was 13-weeks long, while the year ago quarter was 14-weeks. When we look at the average revenue per week in the December quarter this year compared to last year, our growth was a stunning 21%. [The 13-week vs. 14-week year-on-year comparison is repeated several times. The summary differences are shown in the table below:] 
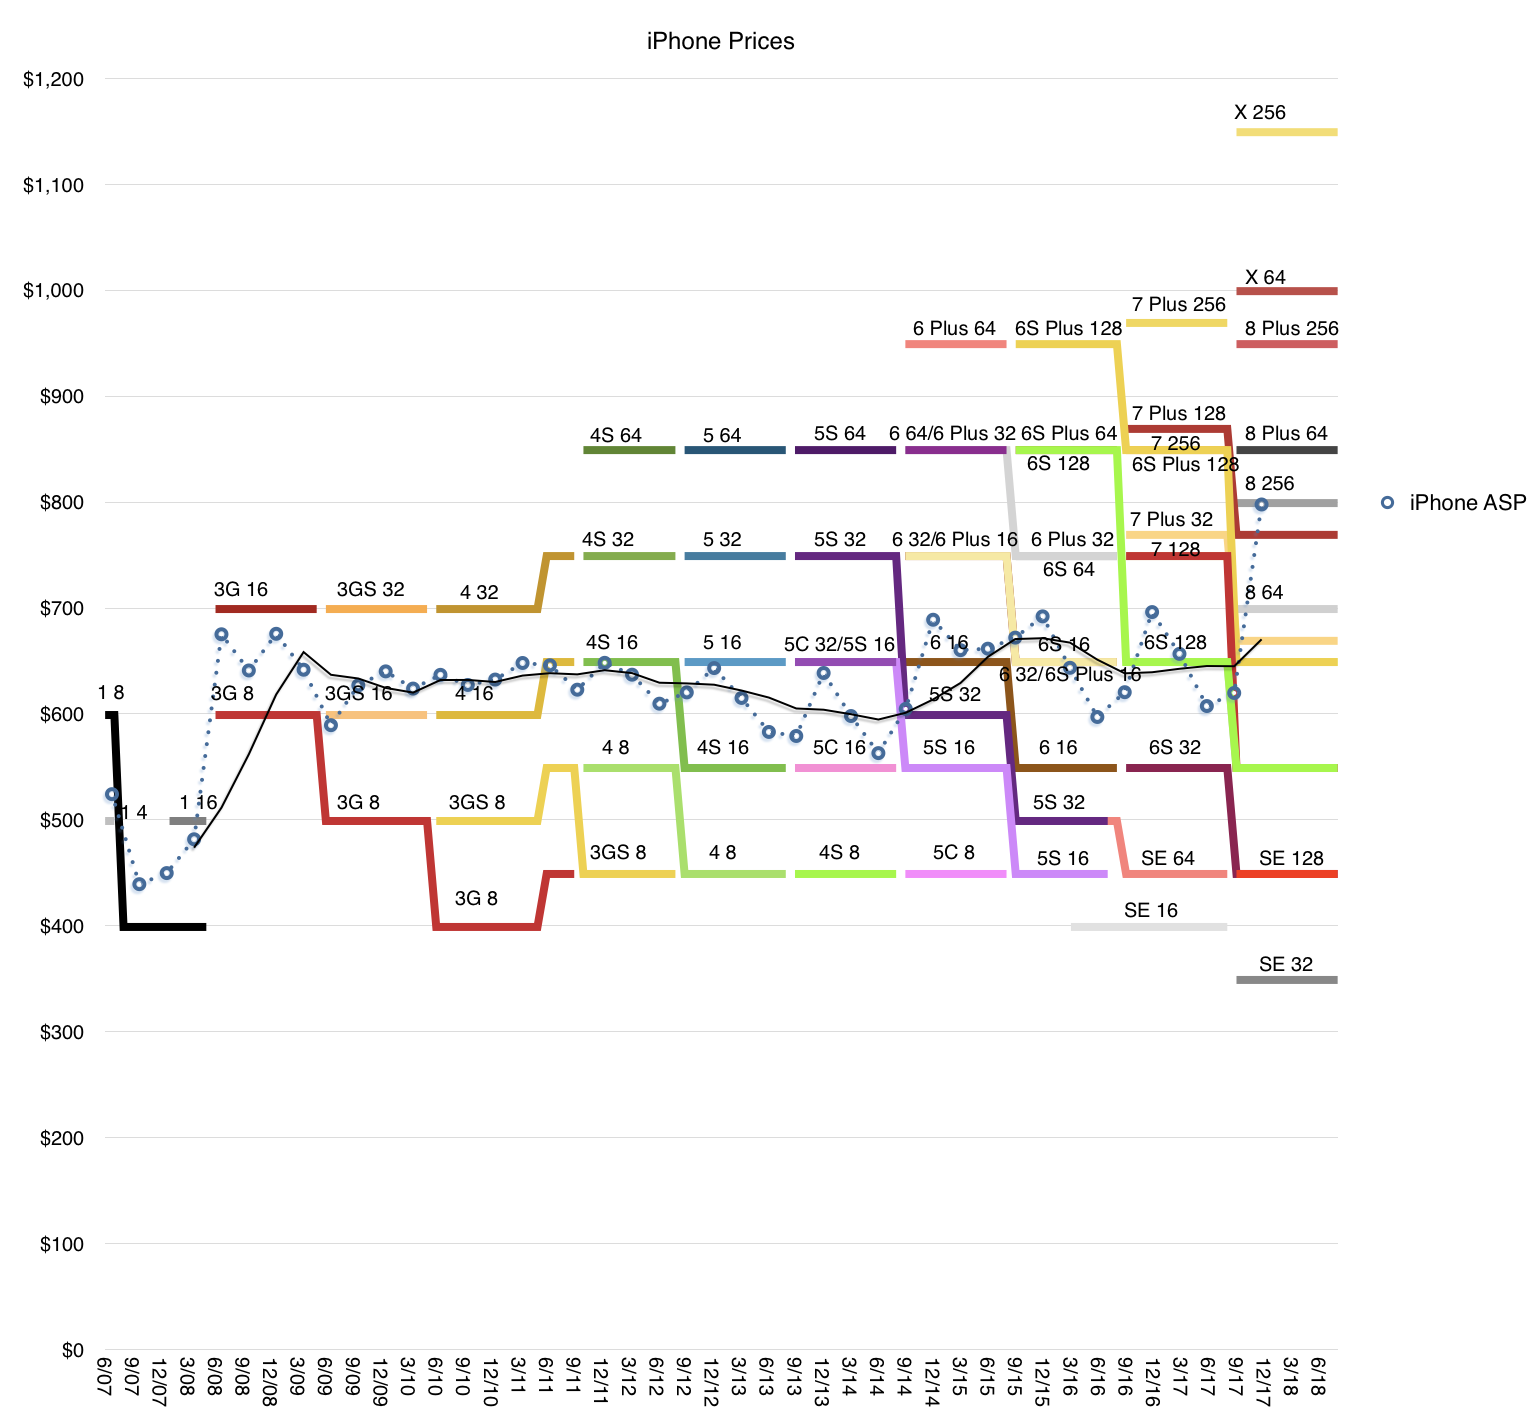
    Our growth was broad-based and a key driver was iPhone, which generated its highest revenue ever. iPhone X was the best-selling smartphone in the world in the December quarter according to Canalys, and it has been our top selling phone every week since it launched. iPhone 8 and iPhone 8 Plus rounded out the top three iPhones in the quarter. In fact, revenue for our newly launched iPhones was the highest of any lineup in our history, driving total Apple revenue above our guidance range. [The iPhone X is a huge hit. It drove the average selling price $100 higher y/y. This is not only unprecedented for Apple but for the entire Industry. The average smartphone sells for less than $300 while iPhones sold for $800. The gap is widening. The following graph shows the product mix and the average resulting price.] 
    I want to take a moment to recognize the tremendous amount of work that went into creating iPhone 10. Our teams carried out an extremely complex launch from both an engineering and operations perspective, executing an outstanding product ramp that required years of research and development; one that introduced innovative features like an edge-to-edge Super Retina Display and the TrueDepth Camera, which enables face ID. Our customers love these new features and the new gestures like simply swiping up from the bottom, which make using iPhone even more intuitive and enjoyable.

    Our team has put the technology of tomorrow in our customers’ hands today, set a standard for the next decade of smartphones and we are very proud of their achievements.

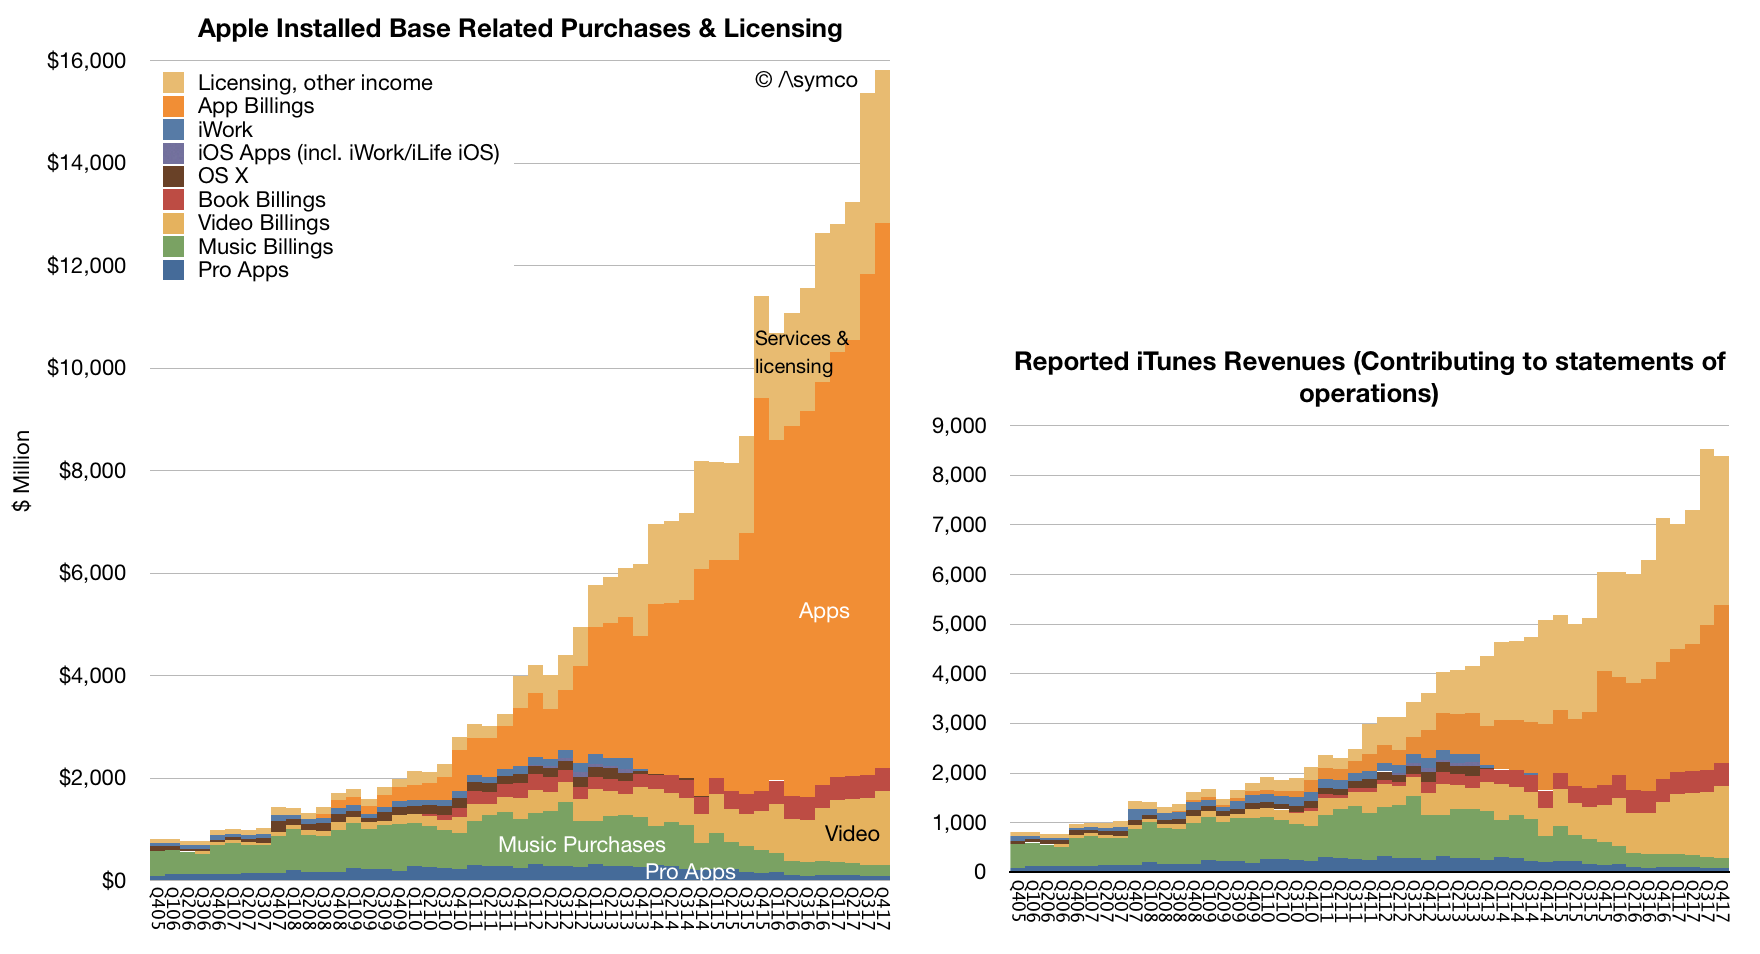
    It was another very strong quarter for services with revenue of $8.5 billion, up 18% over last year, and we’re on pace to achieve our goal of doubling our 2016 services revenue by 2020. The number of paid subscriptions across our services offerings passed 240 million by the end of the December quarter, that’s an increase of 30 million in the last 90 days alone, which is the largest quarterly growth ever. [Services has been growing relentlessly for over a decade. This steadiness of growth makes is a juggernaut. Apple is increasingly speaking about subscriptions as the key metric and 240 million is reaching record territory. The rise of Services is shown below (both revenues and consumer spending.)]
    We had an all-time record quarter for the App Store with our best holiday season ever. We’re seeing great excitement around augmented reality with customers now enjoying over 2,000 ARKit enabled app, spanning every category in the App Store. In December, when Pokémon GO released its new augmented reality features built with ARKit, it jumped the top of the App Store charts. Last week, on a stop in Toronto, I met developers who are hard at work on creative applications using ARKit from art appreciation to ecommerce, and I was very impressed with what I saw.

    Just for months after ARKit launched to the public, we’ve already released ARKit 1.5 in beta to developers around the world, and the response has been tremendous. Augmented reality is going to revolutionize many of the experiences we have with mobile devices. And with ARKit, we’re giving developers the most advanced tools on the market to create apps for the most advanced operating system running on the most advanced hardware. This is something only Apple can do.

    In addition to the App Store, several other services had their biggest quarter ever, including Apple Music, iCloud and Apple Pay, all of which saw growth in both active users and revenue.

    Apple Pay has reached an important milestone in the U.S. As a result of 50% year-over-year growth in merchant adoption, it’s now accepted at more than half of all American retail locations, which includes more than two-thirds of the country’s top 100 retailers. Now available in 20 markets, global Apple Pay purchase volume more than tripled year-over-year and we’re delighted to be expanding to Brazil in the coming months. [There are no absolute data points on Apple Pay but we do have some scattered growth data. The US data is cited here but in my experience it's more popular in select countries like UK where users are using it habitually]

    Today, you can use Apple Pay to take the subway in Guangzhou, China, see a concert at London’s Wembley Stadium or buy a souvenir in Yosemite National Park. In the U.S., we launched Apple Pay Cash in December, and it’s off to a terrific start. Millions of people are already using it to send and receive money with friends and family quickly, easily and securely; to split a bill, pay someone back, or send last minute gift right from the messages app.

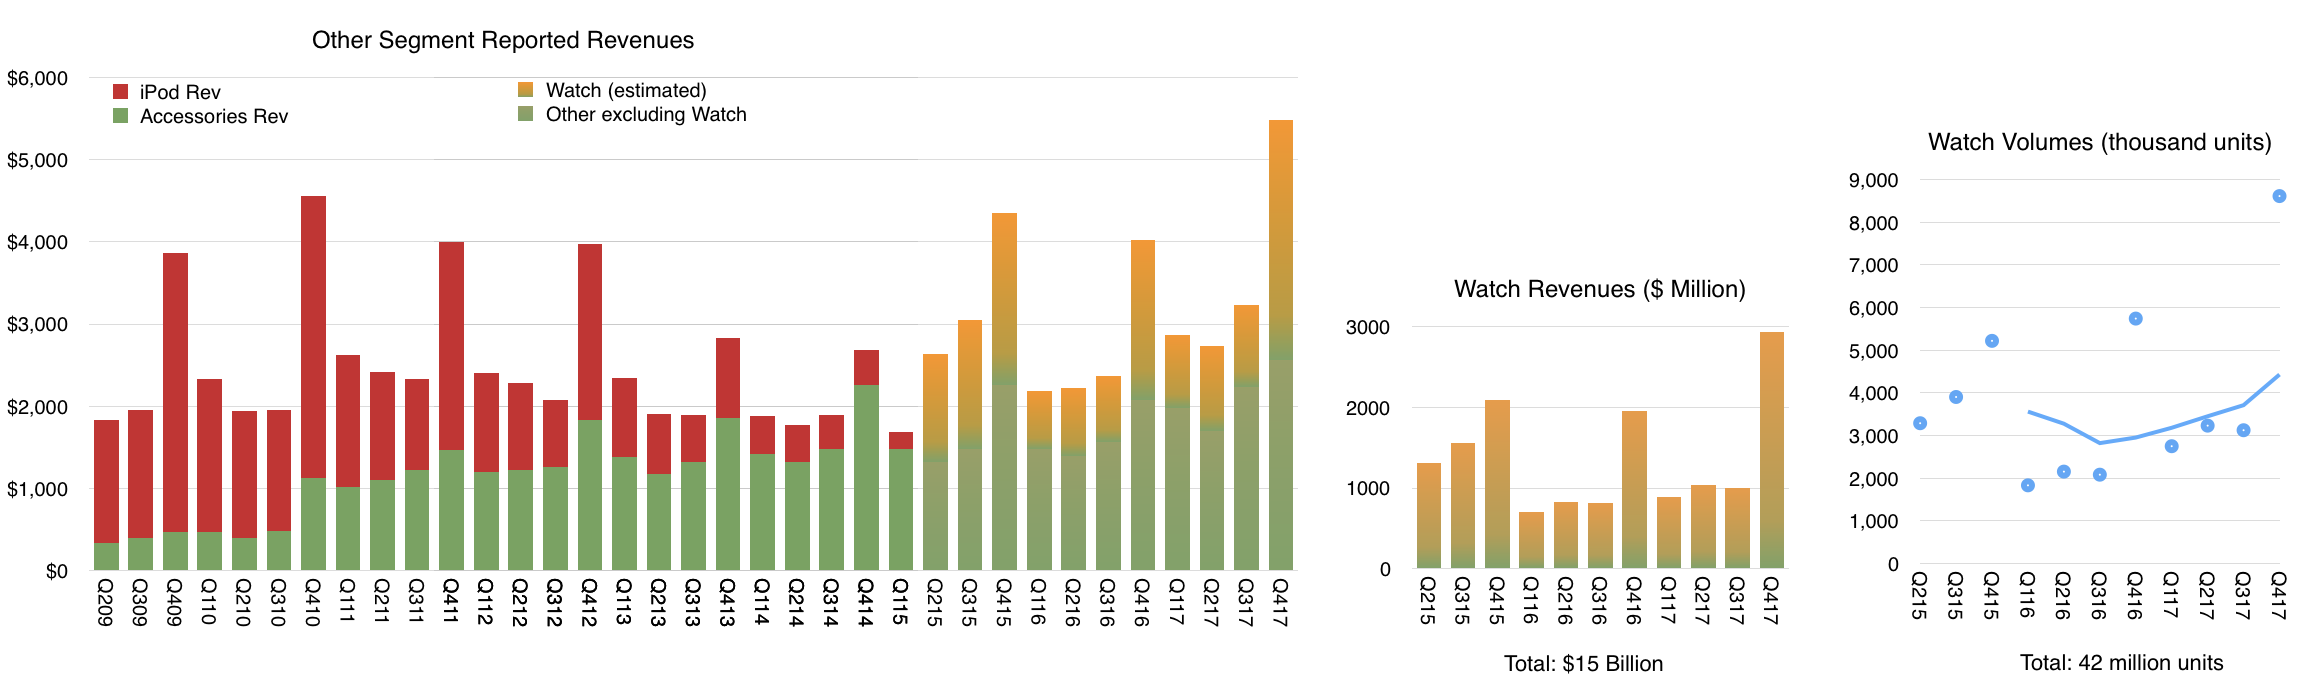
    It was our best quarter ever for the Apple Watch with over 50% growth in revenue and units for the fourth quarter in a row and strong double-digit growth in every geographic segment. Sales of Apple Watch Series 3 models were also more than twice the volume of Series 2 a year ago. Apple Watch is the most popular, smart watch in the world and gained market share during the quarter based on the latest estimates from IDC. [Apple Watch is growing consistently. The following graph shows my estimates of volume (total 42 million to date) and revenues (total $15 billion) based on all available data and commentary from management.]
    It was the third consecutive quarter of growth for iPad revenue, thanks to the strength of both iPad and iPad Pro. Based on the latest data from IDC, we gained share in nearly every market we track with strong outperformance in emerging markets.

    Worldwide, almost half of our iPad sales were the first-time tablet buyers are those switching to Apple, and that’s true in some of our most developed markets, including Japan and France. In China, new and switching users made up over 70% of all iPad sales.

    For Mac, we launched the all new, iMac Pro in mid-December. It’s an entirely new product line designed for our Pro users who love the all-in-one design of iMac and require workstation class performance. It's the fastest, most powerful Mac ever, delivering incredible computational power, for simulation and real time 3D rendering, immersive VR and complex photography audio and video projects. Worldwide, 60% of our Mac sales were the first time buyers and switchers and in China, that number was almost 90%.

    We're looking forward to getting HomePod in customers’ hands beginning next week. HomePod is an innovative wireless speaker, which delivers stunning audio quality wherever its placed in the home, thanks to the advanced Apple engineered hardware and software.

    Together with Apple Music, HomePod gives you instant access to one of the world's largest music catalogs. And with the intelligence of Siri, it’s a powerful assistant you control through natural voice interaction. We're very happy with the initial response from reviewers who've experienced HomePod ahead of its launch, and we think our customers are going to love this new product.

    We believe one of the key issues of the 21st century is education. And because of that, we've strengthened our commitment and investment into initiatives like everyone can code. To find the innovators of the future, we need to nurture the students of today. Our App Development with Swift curriculum, which is available free on iBooks, has been downloaded more than 1.2 million times worldwide with almost half of those coming from here in the United States. It’s also being taught in dozens of community colleges across the country, putting practical skills in the hands of today’s jobs seekers.

    I was in London two weeks ago as we announced that the program was expanding to more than 70 colleges and universities in Europe. Millions of students around the world will have the opportunity to add Swift to their coding vocabulary and gain skills that are essential for today’s economy.

    This is an exciting time at Apple and with the best lineup of products and services we've ever had and a set of initiatives that show how business can be a force for good in the world. We could not be more excited about our future.

    Now, for more details on the December quarter results, I'd like to turn over the call to Luca.

    Luca Maestri: Thank you, Tim. Good afternoon, everyone. Our business and financial performance in the December quarter were exceptional, as we set new all-time records for revenue, operating income, net income and earnings per share.

    Starting with revenue, we’re reporting an all-time record, $88.3 billion, up nearly $10 billion or 13% over the prior record set last year. It is our fifth consecutive quarter of accelerating revenue growth. As you know, the December quarter a year ago spanned 14-weeks compared to 13-weeks this year, which is important to consider as we have set the underlying performance of our business this year. When we look at average revenue per week, our growth rate was even higher at 21% with growth across all product categories for the third consecutive quarter.

    Our results were terrific all around the world with double digit revenue growth in all our geographic segments, an all-time quarterly record in the vast majority of markets we track, including the U.S., Western Europe, Japan, Canada, Australia and Korea, as well as Mainland China, Latin America, The Middle East, Central and Eastern Europe, and India.

    In Greater China, we were very happy to generate double digit revenue growth for the second quarter in a row and in emerging markets outside of Greater China, we saw 25% year-over-year growth.

    Gross margin was 38.4% at the high end of our guidance range. Operating margin was 29.8% of revenue. Our net income was $20.1 billion an all-time record, and up $2.2 billion over the last year. Diluted earnings per share were $3.89 also an all-time record and cash flow from operations was very strong at $28.3 billion.

    During the quarter, we sold 77.3 million iPhones, the highest number ever for a 13-week quarter. Average weekly iPhone sales were up 6% compared to December quarter last year with growth in every region of the world despite the staggered launch of iPhone 10. We established all-time iPhone revenue record in nearly every market we track with double-digit growth in all of our geographic segments. iPhone ASP increased to $796 from $695 a year ago, driven primarily by the launch of iPhone 10 and the success of iPhone 8 and 8 Plus.

    We exited the December quarter towards the lower end of our target range of five to seven weeks of iPhone channel inventory with less than 1 million more iPhones in the channel compared to the December quarter a year ago, in line with our growth in average weekly unit sales. Customer interest and satisfaction with iPhone are very, very strong for both consumers and business users.

    The latest data from 451 Research indicates U.S. customer satisfaction ratings of 96% or higher across iPhone models. In fact, combining iPhone 8, iPhone 8 Plus and iPhone 10, consumers reported an amazing 99% satisfaction rating. And among business customers planning to purchase smartphones in the next quarter, 77% planned to purchase iPhone. Our customers are also incredibly loyal with Kantar's latest U.S. research, reflecting a 96% iPhone loyalty rate, the highest ever measured. [Customer satisfaction is the second most important figure after active user base. Combining these two figures yields the recurring revenue value of the company. Remember what Deming said: the most important measurements for a company's value are the multipliers of a satisfied customer and a dissatisfied customer--these numbers never appear on any financial report but they are applied to all the numbers on every report].

    Turning to services. We had a terrific quarter with revenue of $8.5 billion, up 18% year-over-year and up 27% in terms of average revenue per week; that is an acceleration to the 24% services growth run rate that we experienced in the September quarter.

    The App Store set a new all-time revenue record. The Store’s all-new design is off to a fantastic start with quarterly store visitors, transacting accounts and paying accounts, reaching new all-time highs. During the week beginning December 24th, a record number of customers made purchases or downloaded Apps from the App Store, spending over $890 million in that seven-day period, followed by $300 million in purchases on New Year’s day alone.

    And according to App Annie’s latest report, the App Store continues to be the preferred destination for customer purchases by a very wide margin, generating nearly twice the revenue of Google Play. Across all our services offerings, paid subscriptions reached $240 million with growth of 58% over last year and they were a major contributor to the overall strong growth in services revenue. [Apple has half the user base of Google Android. This is based on Google's May 2017 report of 2 billion active devices vs. the 1.3 billion that we just got from Apple. And yet these users collectively spend twice as much on apps. This ratio of "half the users, twice the spending" has been cropping up in individual developer anecdotes and can also be seen in other metrics of engagement and consumption. This should not be surprising as it conforms to the Pareto distribution of economic value.]

    As Tim mentioned, it was our best quarter ever for Apple Watch. And when we add to this us from Beats and AirPods, our total revenue from wearables was up almost 70% year-over-year. In fact, wearables were the second largest contributor to revenue growth after iPhone, which is impressive for a business that started only three years ago. In total, our other products category set a new all-time record with quarterly revenue exceeding $5 billion for the first time. [Wearables now includes more than watches but watches are likely still the dominant product.]

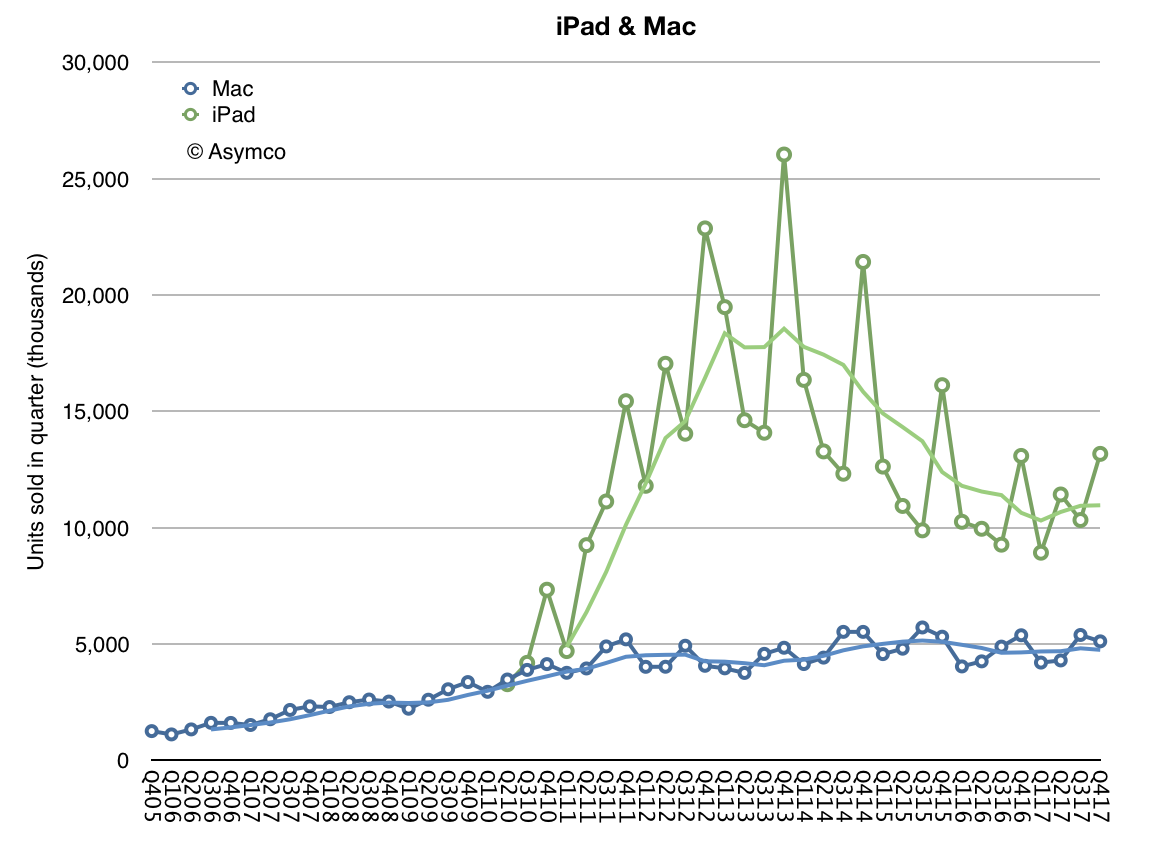
    Next, I’d like to talk about the Mac. We sold 5.1 million Macs during the December quarter, which translates to a 2% year-over-year increase in average sales per week. Mac performance was particularly strong in emerging markets with unit sales up 13% year-over-year and with all-time records in Latin America, in India, Turkey and Central and Eastern Europe. On a worldwide basis, the active install base of Macs was up double-digits year-over-year to a new record.

    It was also another growth quarter for iPad. We sold 13.2 million units with average iPad sales per week up 8% over last year’s December quarter. iPad sales grew strong double-digits in many emerging markets, including Latin America, the Middle East, Central and Eastern Europe and India, as well as developed markets, including Japan, Australia and Korea. The active install base of iPad has grown every quarter since its launch in 2010, and it reached a new all-time high in December, thanks to extremely high customer loyalty and large numbers of first-time iPad users. [iPad is clearly recovering from a long decline. ASPs are rising as it's being positioned as a PC alternative. Its low end functions are being absorbed by large screen iPhones.]
    NPD indicates that iPad had 46% share of the U.S. tablet market in the December quarter, up from 36% share a year ago. And the most recent surveys from 451 Research found that among customers planning to purchase tablets within 90 days, 72% of consumers and 68% of business users planned to purchase iPads. Customer satisfaction is also very high with businesses reporting a 99% satisfaction rating for iPad.

    We are seeing great traction in enterprise as businesses across industries and around the world standardize on iOS. For example, Intesa Sanpaolo, one of Europe’s leading banks, has chosen iOS as the mobile standard for its entire 70,000 employee base in Italy; choosing iOS for its security, user interface, accessibility and reliability, Intesa Sanpaolo will deploy native apps to improve employee productivity in customer support, human resources, and marketing across the company.

    And LensCrafters, one of the largest optical retail brands in North America, will be using over 7,000 iPad Pros to enable digital eye exams and digital optical measurements in a personalized and interactive experience. We’re also rolling out a new initiative, called Apple AtWork to help businesses implement employee choice programs more easily and offer Apple products company-wide.

    Resources from both Apple and our channel partners will enable enterprise IT and procurement teams to buy or lease Apple products more efficiently, streamline the setup of iPhone, iPad, and Mac, and deliver a seamless onboarding experience for employees. We launched the program with CDW in the U.S. last week, and we would be expanding to more channels and regions later this year.

    The December quarter was extremely busy for our retail and online stores, which welcomed 538 million visitors. Traffic was particularly strong during the four-weeks following the launch of iPhone 10, up 46% over last year. And across the quarter, our stores conducted over 200,000 today at Apple sessions, covering topics including photography, music, gaming, and app development, and art and design. Just last weekend, we opened our first store in Seoul, Korea and we’re looking forward to opening our first store in Austria in a few weeks. These newest openings will mark the expansion of our retail store presence to 21 countries.

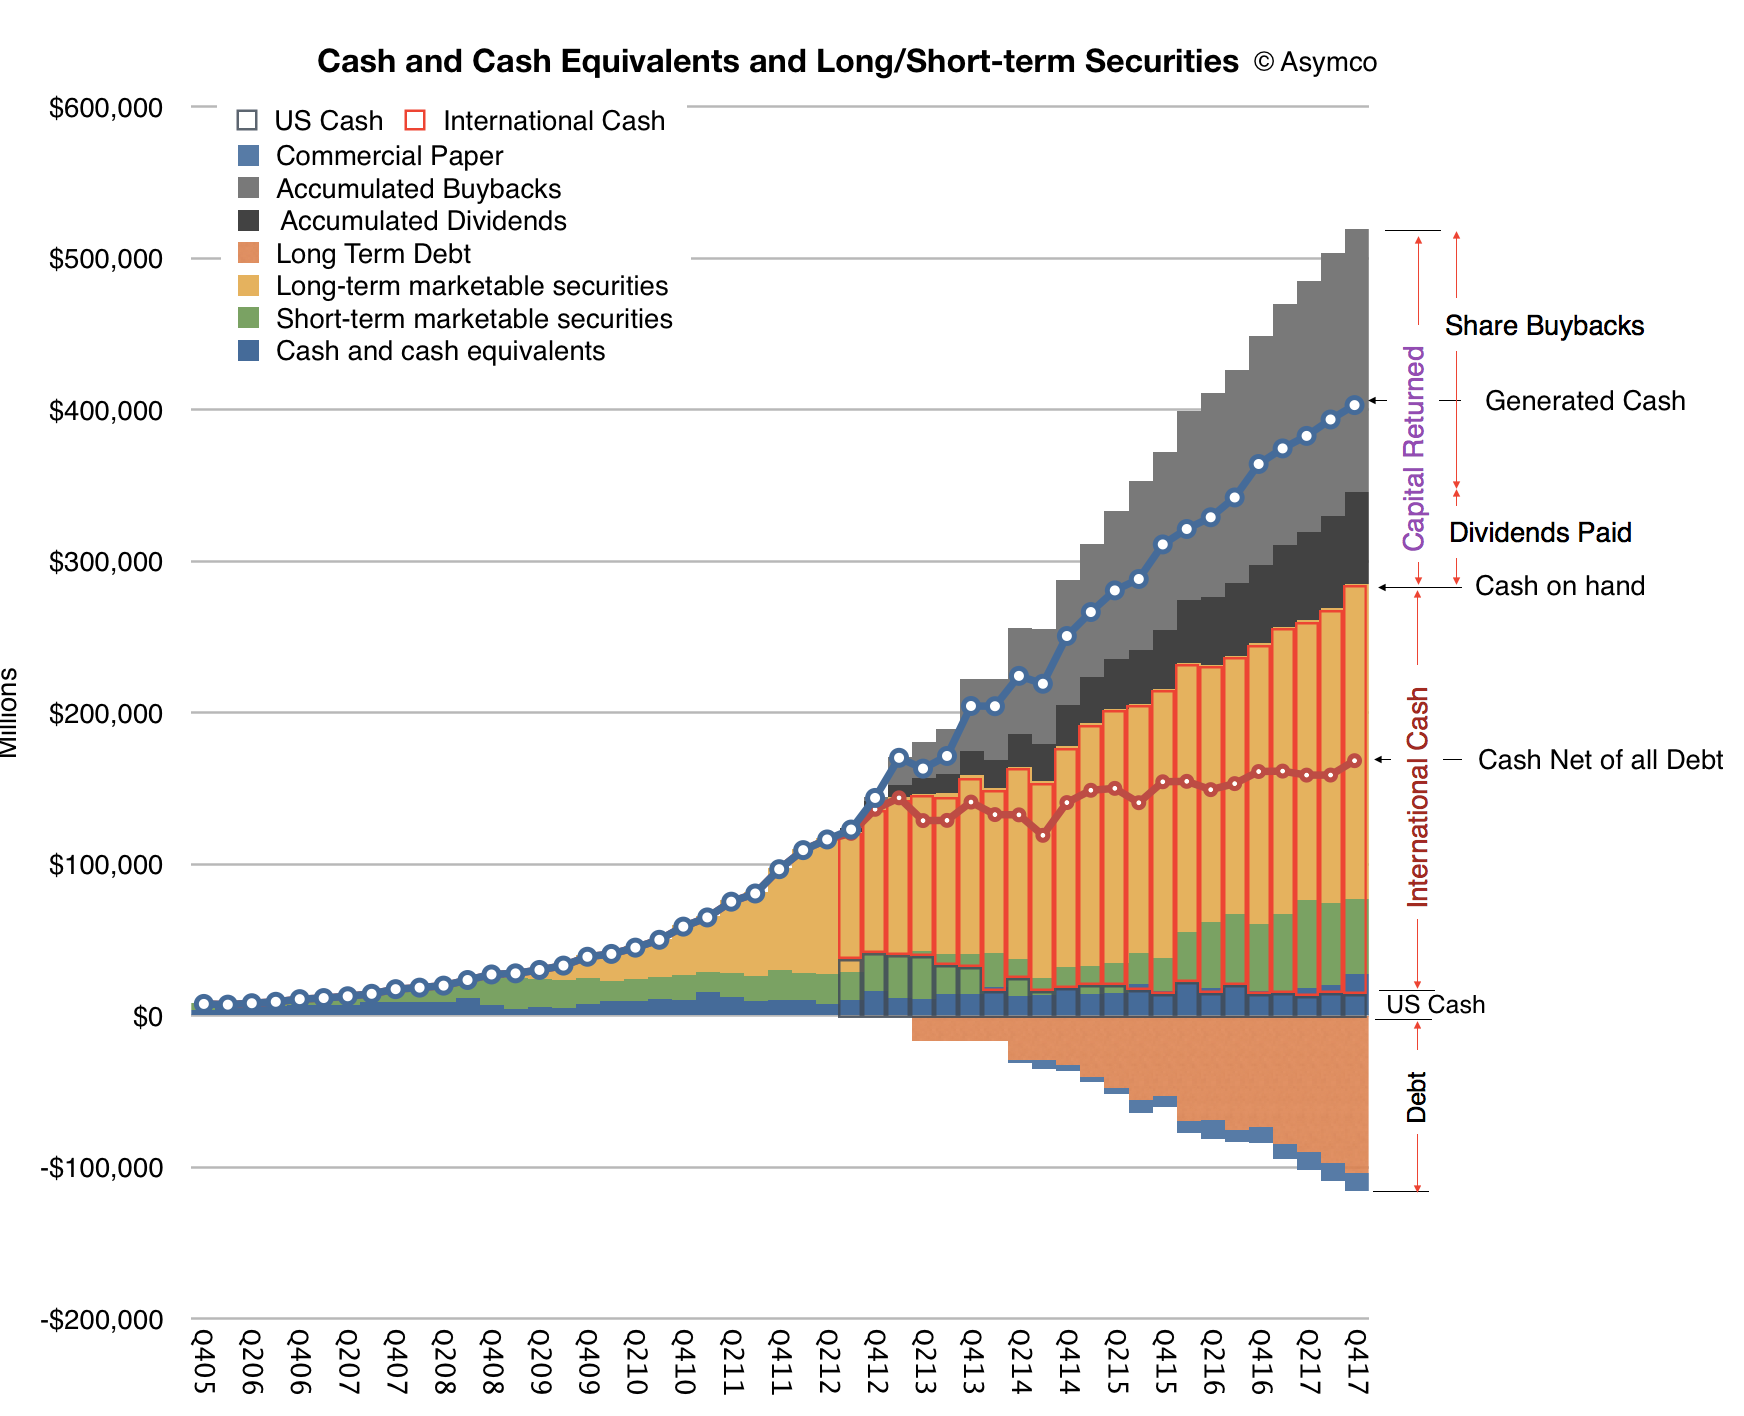
    Let me now turn to our cash position. We ended the quarter with $285.1 billion in cash plus marketable securities, a sequential increase of $16.2 billion. $269 billion of this cash, or 94% of the total, was outside the United States. We issued $7 billion in debt during the quarter, bringing us to $110 billion in term-debt and $12 billion in commercial paper outstanding, for a total net cash position of $163 billion at the end of the quarter. We also returned $14.5 billion to investors during the quarter. We paid $3.3 billion in dividends and equivalents, and spent $5.1 billion on repurchases of 30.2 million Apple shares through open market transactions.

    We launched a new $5 billion ASR program, resulting in initial delivery and retirement of 23.6 million shares and we retired 3.8 million shares upon the completion of our 12th ASR during the quarter. We’ve now completed over $248 billion of our $300 billion capital return program, including $176 billion in share repurchases against our announced $210 billion buyback program with $34 billion remaining under our current authorization. [An updated look at Apple's cash is shown below]
    Turning to taxes. Due to the recently enacted legislation in the U.S., we estimate making a corporate income tax payment of approximately $38 billion to the U.S. government on our cumulative past foreign earnings. This amount is very similar to what we had been accruing on those earnings in our financial results through fiscal year 2017, including the $38 billion payment. We will have paid over $110 billion of corporate income tax on our total domestic and foreign earnings during the last 10 years for a cash tax rate of about 26%. [Apple has paid more tax than any company in history, and is about the make the largest single payment to the US Treasury.]

    Our tax rate of 25.8% for the December quarter was close to our guidance of 25.5% as the lower U.S. statutory rate from the new legislation was effective offset by the remeasurement of deferred tax balances.

    As we move ahead into the March quarter, I'd like to review our outlook, which includes the types of forward looking information that Nancy referred to at the beginning of the call; we expect revenue to be between $60 billion and $62 billion; we expect gross margin to be between 38% and 38.5%; we expect OpEx to be between $7.6 billion and $7.7 billion; we expect OI&E to be about $300 million; and we expect the tax rate to be about 15%.

    Tax reform will allow us to pursue a more optimal capital structure for our company. Our current net cash position is $163 billion. And given the increased financial and operational flexibility from the access to our foreign cash, we are targeting to become approximately net cash neutral overtime. We will provide an update to our specific capital allocation plans when we report results for our second fiscal quarter, consistent with the timing of updates that we have provided in the past.

    Finally, today our Board of Directors has declared a cash dividend of $0.63 per share of common stock, payable on February 15, 2018, to shareholders of record as of February 12, 2018.
  2. Does the iPhone 8 have what it takes to be a success?

    Research · 96 comments

    Source: ¿El iPhone 8 tiene lo que se necesita para ser un éxito?

    The above interview was conducted October 17 with Carlos Morales
    Editor en Jefe, Forbes Digital (Mexico).

    The source questions and my answers in English are below:

    How can we read the fact that the new iPhone lineup raised so little noise? There was no massive lines outside the Apple Stores and people demonstrated almost zero interest in the new models compared with the hype motivated by the iPhone 7.

    I don’t know about you but I don’t like waiting in lines. I don’t think Apple considers waiting in lines to be a good user experience for its customers. Over the years Apple has been able to improve availability and online orders so that lines can be eliminated. I suggest a better way to gauge interest in new models and that would be to look at sales. Sales seem to be going up even as lines have been going down.

    The iPhone 8. What do you think of the fact that the iPhone 7 is outselling the iPhone 8?

    Is it a fact? I think this notion is coming from a survey of operator stores in the US over a short time period. The mix of phones has never been known and is a matter of speculation. The only data we do have is the average selling price derived by dividing the revenues by the number of units sold (and ignoring deferrals). This price set a new record during the last 12 months. Expectations are that it will increase to another record again next year. I might add that this has never been observed in the phone business as far as I know. The opposite has been the trend.

    Whats the outlook for the the iPhone 8 vs the iPhone 7 and the iPhone X?

    The iPhone 8 is likely to be the best selling model over the next 12 months. The iPhone X will be the best seller in the first quarter but I expect it will come second during the following quarters. The iPhone 7 will end up 3rd.

    What do you think about the smartphone prices, aren't they too high? How far can they be stretched ?

    Smartphone prices are very low. World-wide, average smartphones sell for less than $300. You can see a break-down by region here.

    iPhone prices are, on average, more than double the average of all smartphones. Note that apple’s latest line-up also includes the cheapest iPhone ever with the SE now starting at $350.

    I don’t think the average selling price will increase in 2018 globally. It will probably decrease as it has for a long time. Average iPhone prices will increase but probably only by $10 or so.

    The iPhone price tiers are well understood. I published an analysis here:

    More important however is that the iPhone remains priced at about $1/day, no matter the model, and as such the value users perceive is very high. The most expensive iPhone costs about 8 cents per hour of use, 1.4 cents each time you unlock it and 1 cent for ever 25 interactions you have with it (touches or taps). On a per use basis the iPhone is extraordinarily cheap. I know of no consumer product that is cheaper. This is determined partly by the intensity of use and by the high resale value (I assume 30% residual value after 2 years).

    Do we really need a borderless OLED display in a smartphone? What about the face recognition technology?

    Having no borders means you can get a screen that is bigger than the iPhone Plus in a phone the size of an iPhone. I think users will value getting more screen in a smaller phone. I certainly would. Having OLED means it can be curved a bit and also have nicer, truer black.

    Face recognition saves time and is more secure. I don’t know another way of making the experience better for something that you do 30,000 times a year.

    What do you think about the Apple Watch, which seems to be—finally—on the right track?

    The Apple Watch has been on the same track for 2.5 years. I don’t see any change in that trajectory.


  3. Good, Better, Best

    Research · 3 comments

    Before the iPhones 8 and X launched I made a prediction on what the iPhone would cost. I concluded that the iPhone price would not change. This is because it has never changed ((Apart from seasonality. Quarterly Minimum = $437, Quarterly maximum = $695, Quarterly Median = $631, Standard Deviation=$58)). Apple collected $767,758,000,000 for the 1,203,732,000 iPhones sold to the end of June or $ 637.8147 per phone.

    Of course this is the average price and that average is on a trailing 12 months basis and measures some of the deferrals in income that exist for obscure accounting reasons.

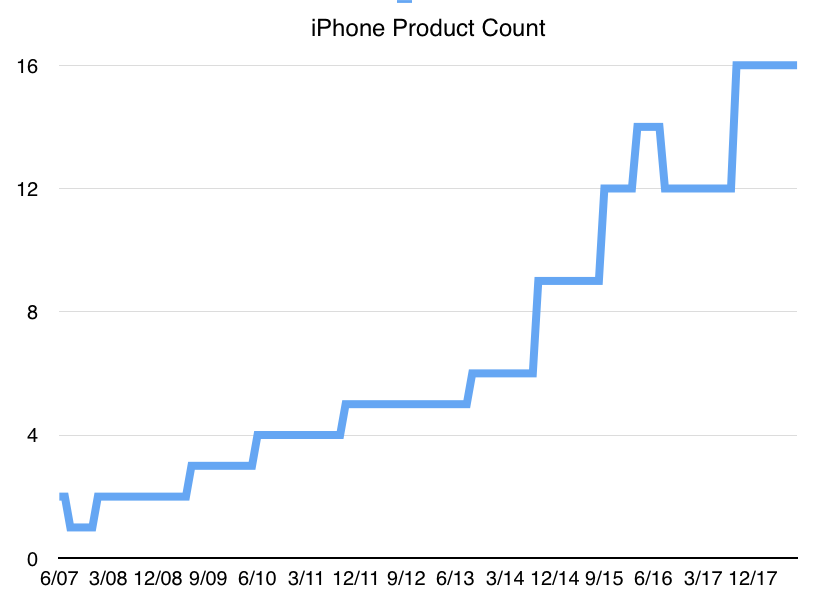
    Now that the new iPhones have launched, how probable is my prediction? The first mild surprise is that the total number of phone models has increased to 16. I had no prediction on product count but did not expect the 6S and 6S Plus to remain available. The following graph shows the total number of products in the mix (excluding color variations).

    The second surprise was that the iPhone SE has been upgraded in memory from 16Gb/64Gb to 32/128Gb and that the new 32Gb version is $50 cheaper than the old 16Gb. The 128Gb remains priced the same as its 64Gb predecessor.

    This means that the SE 32 now occupies a new lowest price band for iPhone: $350. It's a remarkably capable phone at the lowest price for an iPhone ever. It's $100 cheaper than the 5C 8 Gb which I bought 3 years ago.

    At this point my prediction looks precarious. The lowering of the lowest iPhone price could drag the mix down. Remember that historically the iPhone average selling price remained constant while the top of the range price increased. The most popular phone sold was likely to be toward the lower end and, with new buyers coming from new markets, the more affordable phones were proving very popular.

    Will the improved-but-lower-priced SE bring ASP down?

    Well, of course, we have to consider the action at the top of the range. The new iPhone X 64 was introduced with a $30 increase over the 7 Plus 256. However the 8 Plus 256 is priced $20 lower than its predecessor. This is something of a wash in terms of impact on average price.

    In addition, the iPhone X 256 is a considerable $159 jump from the 64GB. Gaps used to be $100 between memory bands. This new increased gap is because the memory bands are now 64/256 vs. 32/128/256 in the previous generation. The memory tiers are now two and they are quite far apart (4x).

    This places the top of the range at a new high, as expected, but it's a higher high. We see an $180 increase from the previous high. I had expected a more modest $80 jump which was closer to the ~$100 jumps seen three times before.

    Regardless of this surge in the top, the percent of units sold at that highest point is not likely to be very significant. X at 256Gb is a great product for enthusiasts but I suspect most people who want to experience the X will comfortably settle for the iPhone X 64. ((The trick here is that Apple offers this "stretch" goal of top iPhone at a $150 premium. The number of people who will stretch is always an interesting exercise. I estimate it at less than 5%.))

    The interesting action is in the middle of the pack. The meat of the increase in product mix is right in the $650 to $850 range where Apple went from 4 products to 6. And they are all highly competitive 7 and 8 iPhones. These products are made available at the $30 to $40/mo. plan rates, the sweet spot of consumer phone financing. What I call the "dollar-a-day" for an iPhone plan. Perfect for those who are holding onto 6/6Plus or earlier models and are ready for an update.

    Here, I believe, is where the sales action will be concentrated. I still predict that, apart from a transient launch period burst, the ASP will stick to its 10-year trajectory of mild increases (keeping with inflation.) In other words, the iPhone will cost about $650 for another year.

    This season the iPhones X will be door busters but over the whole year  customers will walk out with 7 and 8 iPhones. The big year of the X will be next year, after the X+1 ships.

    In summary, if you see the choice of Good, Better, Best, never underestimate the popularity of Better.


  4. How much will the new iPhone cost?

    Research · 83 comments

    The answer, regardless of when you ask, is: The same as the current iPhone.

    Of course, this is the answer to the question of what will the average new iPhone cost. The average selling price (which combines the revenues and the volumes of all units sold and is reported every quarter) has not varied very much since early 2008. To the degree that there is variance (between $600 and $700) it is due mostly to seasonality and reflects a mix of more expensive units during the launch quarters and a cheaper units during later periods when the product is older and due for an update.

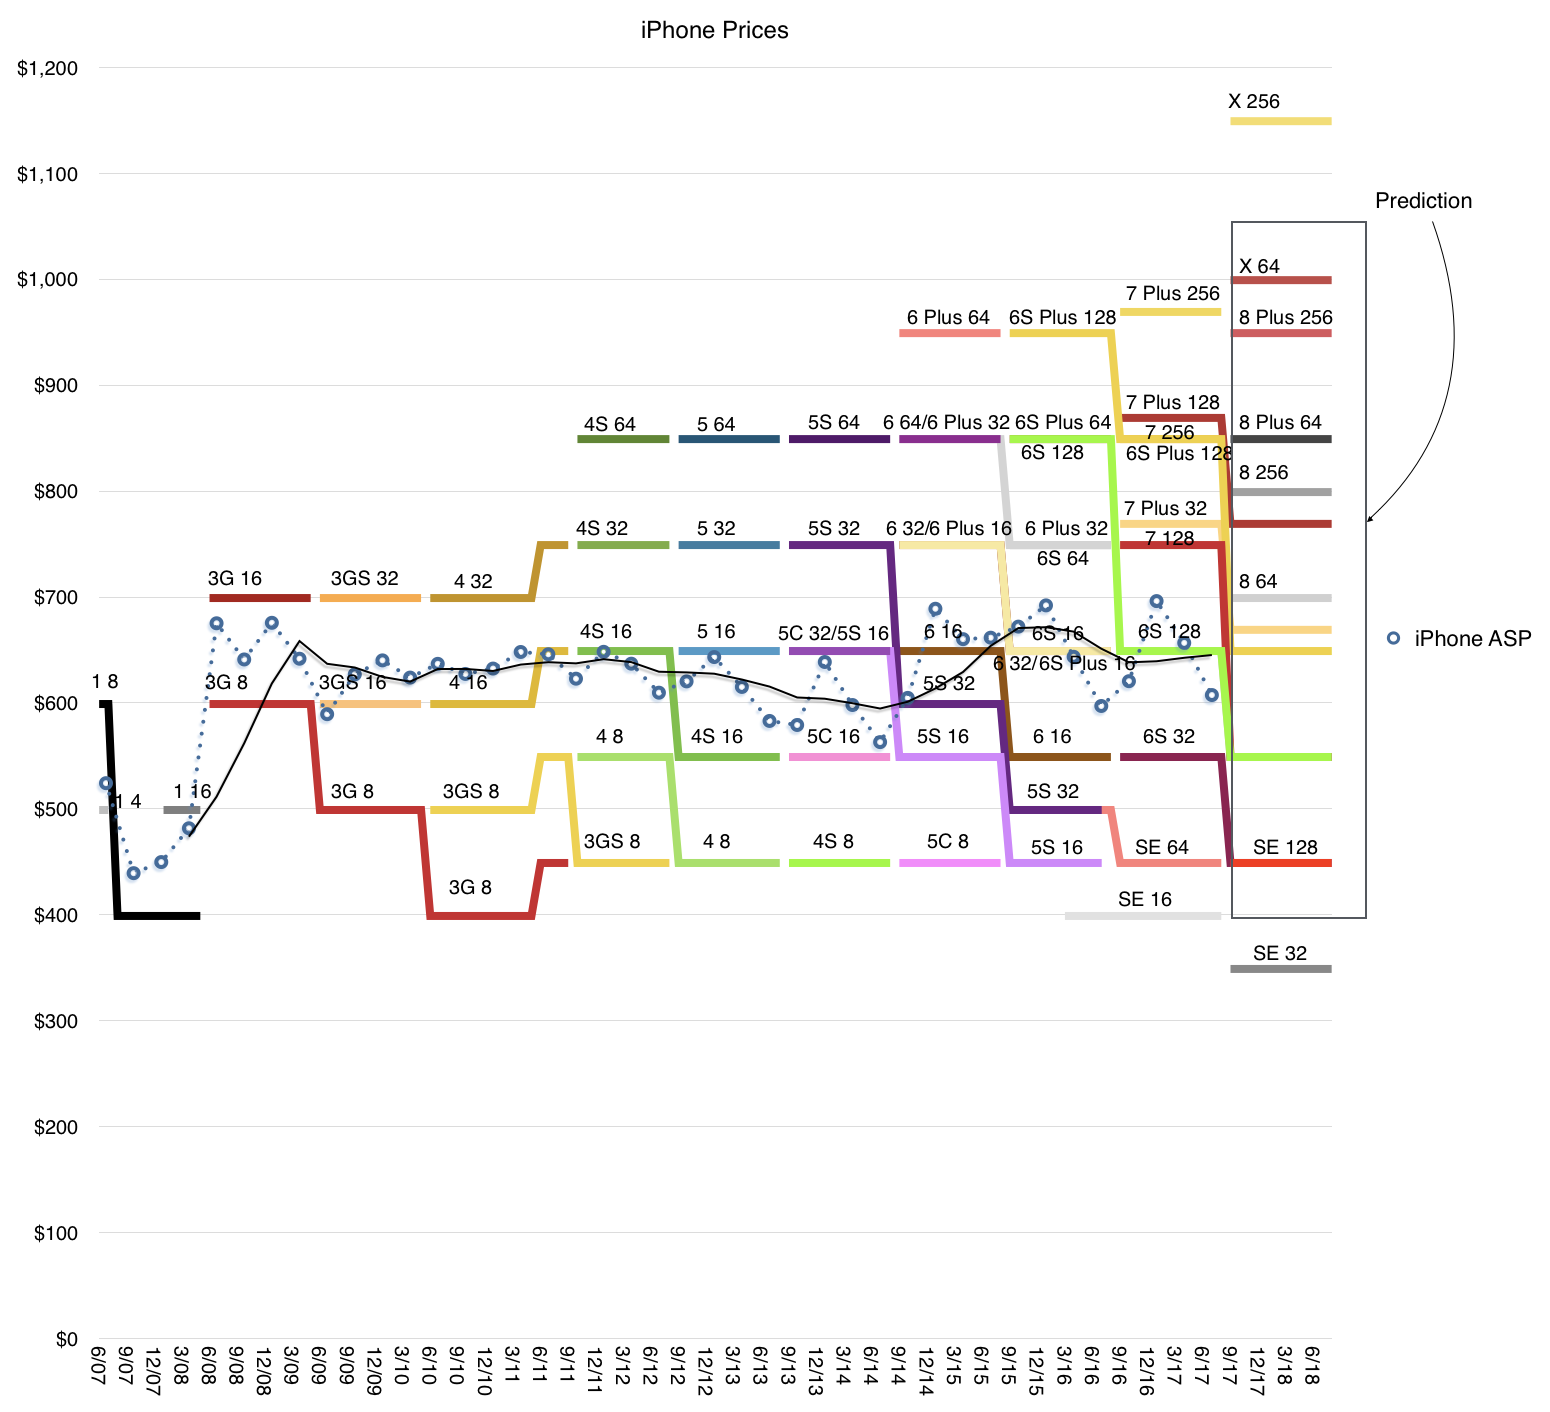
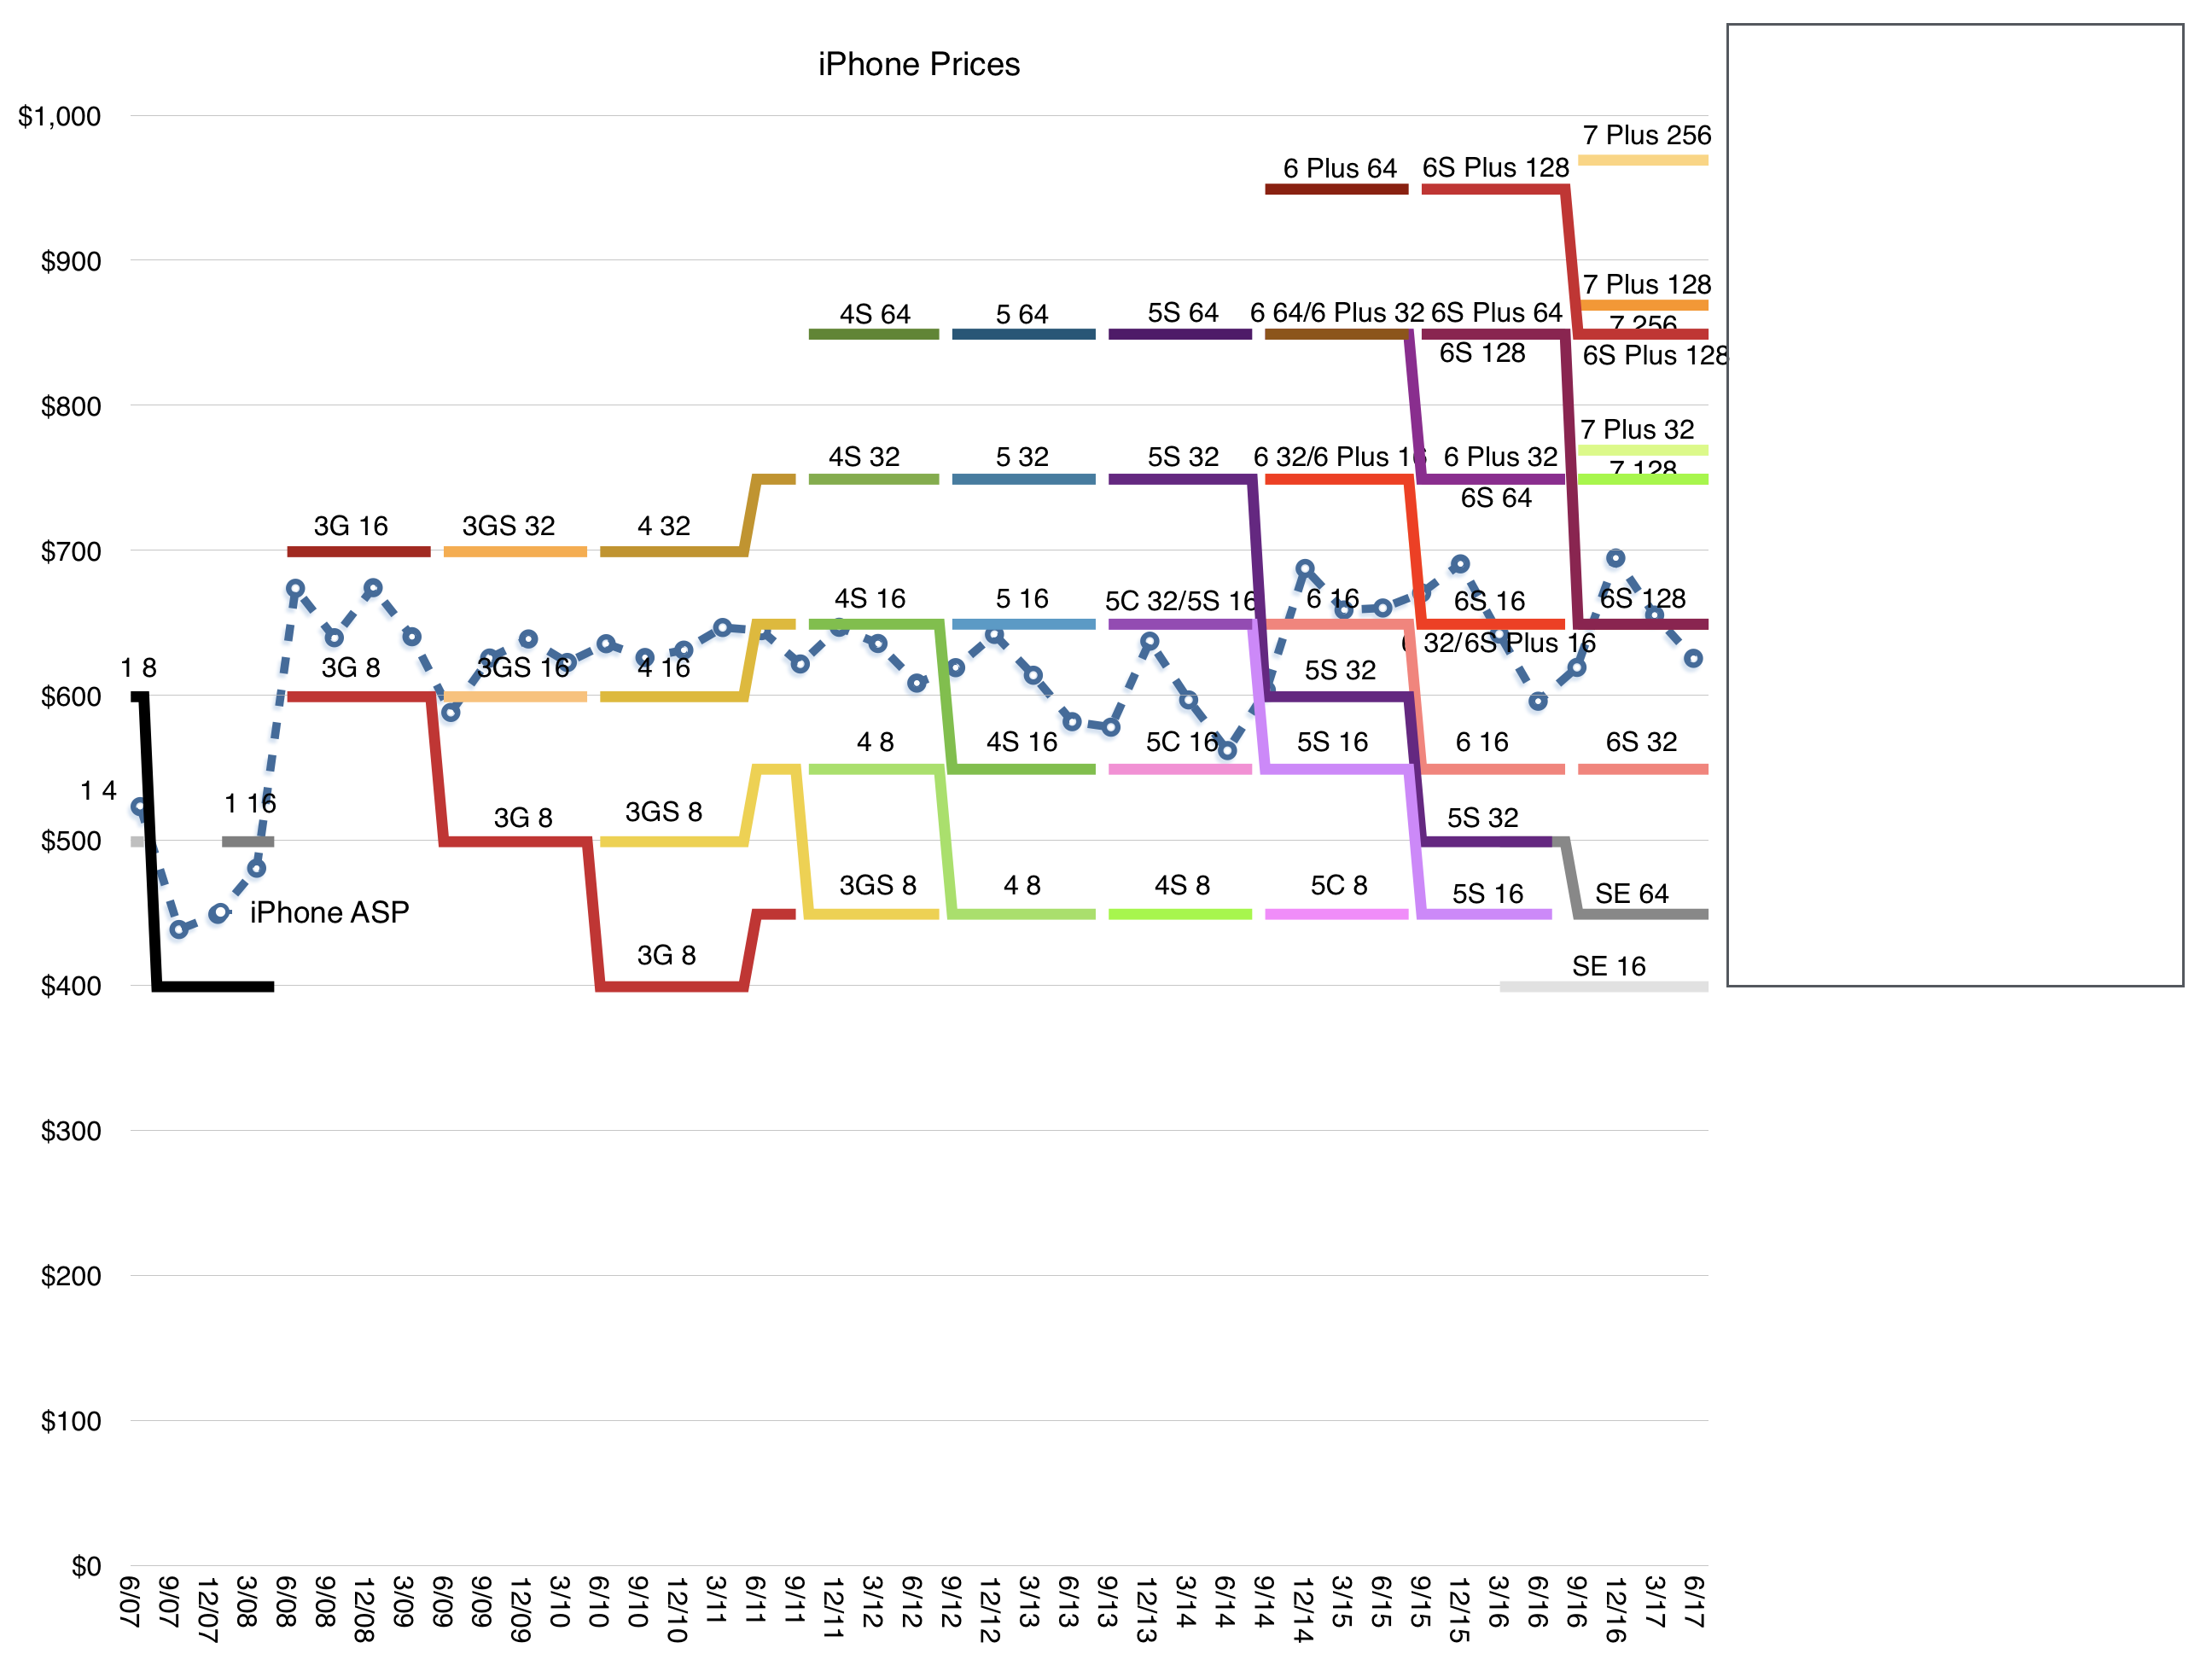
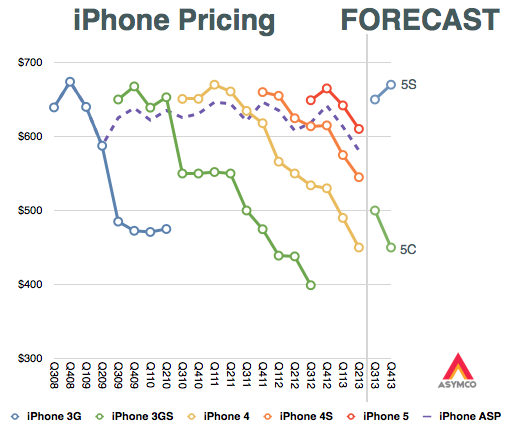
    The graph below shows the average selling price as a dashed line and the corresponding prices of individual product variants available for sale in the US during the same time frame. ((Prices outside the US vary depending on duties, taxes and currency hedging but generally are based on the US price))

    The graph shows a high degree of consistency of pattern: Every year a new iPhone is launched which replaces the one launched the year before. The older product is still offered at a reduced price. Price brackets are very firm and set at fixed intervals about $100 apart.

    A few minor changes in pattern over the years can be observed:

    • The original iPhone price changed due to a shift in subsidy model shortly after launch.
    • An increase of $50 mid-2011 when the iPhone became available unlocked.
    • Every three years a new, higher, price bracket is introduced, with a  doubling of maximum memory capacity.
    • The iPhone SE was introduced at a slightly lower price.
    • The last year saw a slight increase in the highest price.

    The overall pattern looks like a staircase with a widening price range where the lowest price remains constant and the upper price rises every three years by $100.

    The "floor" of the range is a consistent $400 while the "ceiling" has expanded from $700 to about $950.

    This year's ceiling is due for the fourth leg up and if the pattern persists, we should expect it to reach $1100.

    This iPhone staircase has been built over 10 years and I don't see it changing over the next three. I therefore drew the blank box over what I thought would be the price range from now until late 2020.

    This is what I call the staircase model of Apple pricing. The staircase model must be understood in combination with the flat iPhone average price as the product matures.

    As the product matures the user base grows (to nearly 1 billion today). Later buyers will opt for the lower price points, but the availability of higher, more aspirational models (sustained by the brand) means that a minority will gravitate upward, mainly because they can. This ensures that although the median and mode of the price trend downward, the average price stays the same.

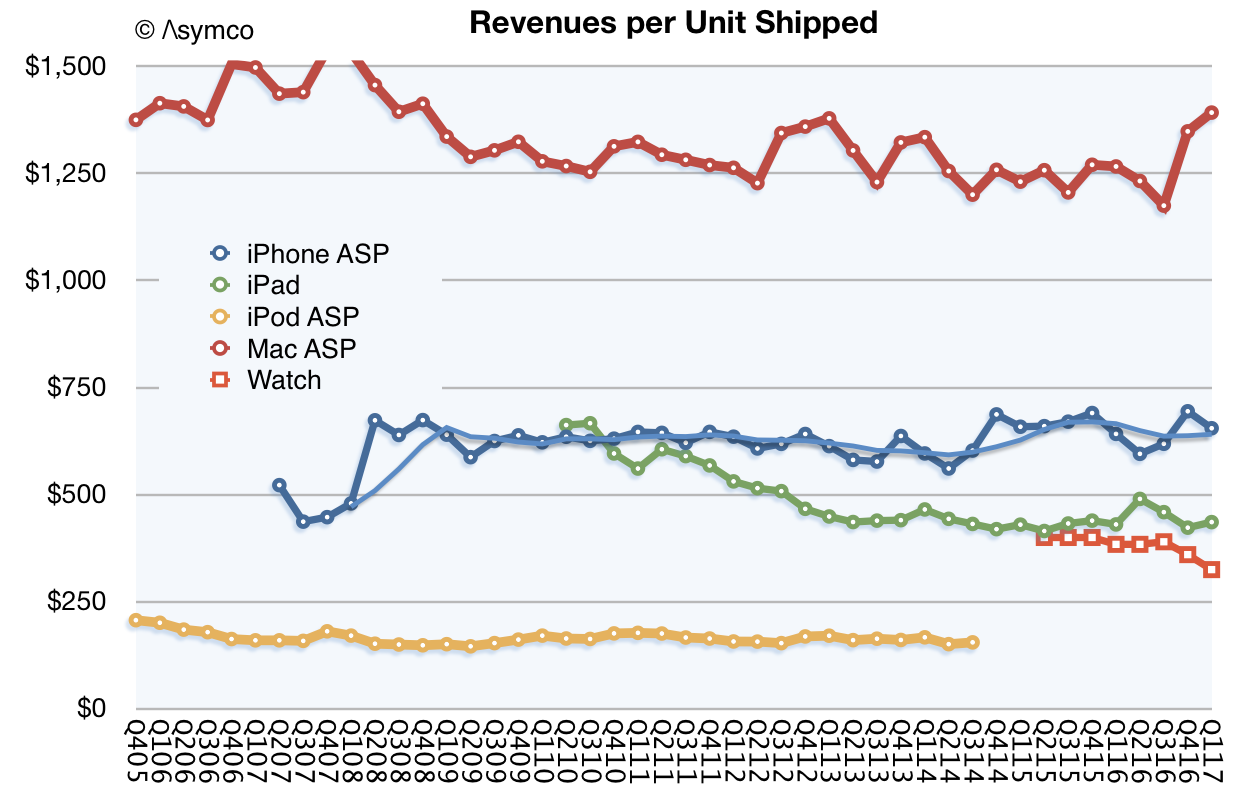
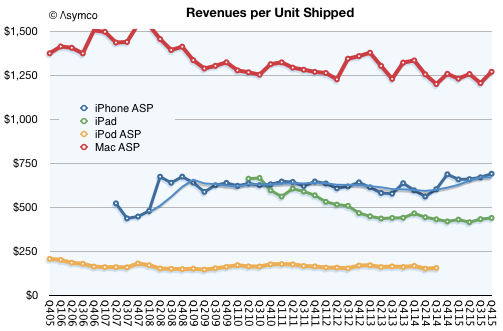
    The flatness of iPhone pricing is also to be understood in combination with the flatness of Mac, iPod and iPad average pricing (shown below)

    The technique of preservation of average price seems to be in effect across Apple. In other words, the evidence suggests that Apple prefers to keep average pricing for all products constant. Individual variants are priced so that, as the category matures, the changing mix leads to consistency in price ownership.

    Thus the iPhone can be seen as controlling the $650 point, the Mac $1200, the iPod $200 and the iPad $450. This pricing signals the product's value and the value of the brand.

    The signaling is not just to buyers but also to competitors. Ownership of price forces competitors to occupy adjacent brackets. This process begins at launch: the new Apple product is introduced in what is perceived as a premium stratum ((See for example the pricing of the new HomePod)) thus the reaction from competitors is to "undercut" it. But, as Apple climbs the price staircase, preserving the floor, it keeps competitors bunched up at the bottom. Competing in the same brackets with Apple is futile as other brands can't sustain the perceived premium position.

    The result is a remarkable consistency of average pricing which, coupled with a remarkable consistency of competitive positioning, coupled with a remarkable consistency of customer satisfaction and loyalty, leads to a remarkable predictability of cash flows and ability to invest in new product creation..

    Apple is thus quite easily understood as a remarkably consistent consumer products business. The only surprise that remains is how long it takes for that understanding to propagate.


  5. Priorities in a time of plenty

    Research · 42 comments

    How Apple is managed is one of its enduring mysteries. The idea that a company with $235 billion in sales is managed with a single P/L ((Profit and Loss statement is an income statement usually applied for a subset of a larger company which allows subdivisions to be managed individually.))  is fascinating in many ways. Not least of which is how it allocates resources. The fundamental question of which great idea gets to be funded and which great idea gets to be ignored is the core of every manager's dilemma. The Apple problem is at scale  when each decision's consequences are so momentous. In the case of Apple there are so few projects that reach the market and their impact is so great that one wonders how they can be sure they are doing the right thing.

    Conventionally, product development is filtered through a sieve of  metrics, market sizing and impact on top/bottom income lines. These "financial" measures of success are considered prudent and optimized for return on equity (also known as the maximization of shareholder returns).

    But this can be a toxic formula. The financial optimization algorithm always prioritizes the known over the unknown since the known can be measured and is assigned a quantum of value while the unknown is "discounted" with a steep hurdle rate, and assigned a near zero net present value. Thus the financial algorithm leads to promoting efficiency at the expense of creation. Efficiency may be the right priority when times are difficult and resources are scarce but creativity is the right priority in a time of plenty. And abundance is what being big is all about.

    To allow for some creation large firms create divisions. Some divisions are tasked with "core products" which are measured by a set of firm metrics and some are tasked with "emerging products" which are given a set of loose metrics. This leads to obvious resentment and war between divisions when resources need allocating.

    Ominously, the core divisions tend to always win. At the root of divisional power struggles are measurements--the roots of financial metrics. Managers fight with data. "You can't manage what you can't measure" they're taught. But if you have something that can be easily measured and something that is difficult to measure, won't the easily-measured be managed and the hard-to-measure be ignored?

    There is a general principle at work here: Managing by measurement is fraught with the pitfall of measuring the wrong thing. Making sure that you're measuring the right thing becomes the value-adding role of the manager. A role that is increasingly being neglected.

    The mass phenomenon of measuring the wrong thing because it's the easiest to measure is called "financialization". Financialization is the process by which finance and finances (rather than creation) determine company, individual and society's priorities. It comes about from an abundance of data that leads to fixation on what is observable to the detriment of awareness of hazards or obstacles or alternatives. This phenomenon is more likely when the speed of change increases and decision cycles shorten.

    Financialization is creeping into all aspects of society and the extent to which it infects companies is the extent to which they suffer from early mortality.

    So is Apple avoiding financialization? How can anyone avoid the tyranny of mis-optimization?

    The unified P/L might be a clue. It obviates the need for divisional rivalry and power-based or financial politics. Without divisional P/L, management can be organized functionally with the obvious benefit of de-politicization. The singular P/L does create another problem however: the absence of an alternative resource allocation algorithm centralizes the decision. By centralizing decisions at the highest level, few decisions can be taken and that means each decision has to be right more often. We swap a distributed but financialized process for a central but capricious one.

    So how is the central decision process made fair? What guides the allocation process?

    I believe that Apple does not avoid quantified decision making. I believe the logic of their decisions is based on a nuanced quantification of the company's customer base. Opting to think about how many customers they have rather than how many things they can sell could offer the Apple manager a better decision tool, avoiding financialization and mis-optimization.

    The guiding principle is putting the customer rather than the firm at the center of the decision process. The idea of this change of orientation extends to a re-definition of the purpose of the firm. Apple calls it its "North Star" and it places "making the best product" at that location.

    The challenge is how to measure "goodness" of product. It's easy to overshoot "best" and become too good. What regulates greatness is another measurement: absorption of what you create. The true orientation (which Apple won't confess to) is absorbable greatness.

    Absorbable greatness is measured through other proxies: customer creation, customer satisfaction, and customer retention. By adding and preserving great customers you can be sure that what you create is indeed the "best". Setting the goal, and indeed the purpose of the firm, as the creation and preservation of customers seems to be the unwritten constitution of Apple.

    The idea that the purpose of the firm is to create and maintain customers is not new ((Customer creation is in contrast to the notion that the purpose of the firm is to maximize shareholder returns. The notion of customer creation as primary purpose was popularized by Peter Drucker. The notion of optimization through shareholder value creation was popularized by Jack Welch.)) but it is relatively rarely practiced. The reason is that the data is harder to obtain. The data that comes from sales is crisp and concrete. The data about customers is muddy and soft. In a world where spreadsheets are used as weapons, the crisper the data, the better the ammunition.

    Clarity wins arguments but it may not be where salvation or truth can be found. Good judgement in a cloudy reality is a better compass than a clear road map to a fantasy world.

    Optimizing around customer acquisition rather than equity returns leads to a new set of metrics. What would these metrics look like for Apple?

    The company publicly offers three separate sets of quantity of customers and quality of customers.

    In terms of quantity we have:

    1. Number of iTunes accounts
    2. Number of iCloud accounts
    3. Number of active devices

    In terms of quality of customers we have:

    1. Average selling prices for devices (as a proxy for willingness to pay)
    2. Customer satisfaction (as a proxy for loyalty )
    3. Services and accessory revenues (post-sales and recurring value)

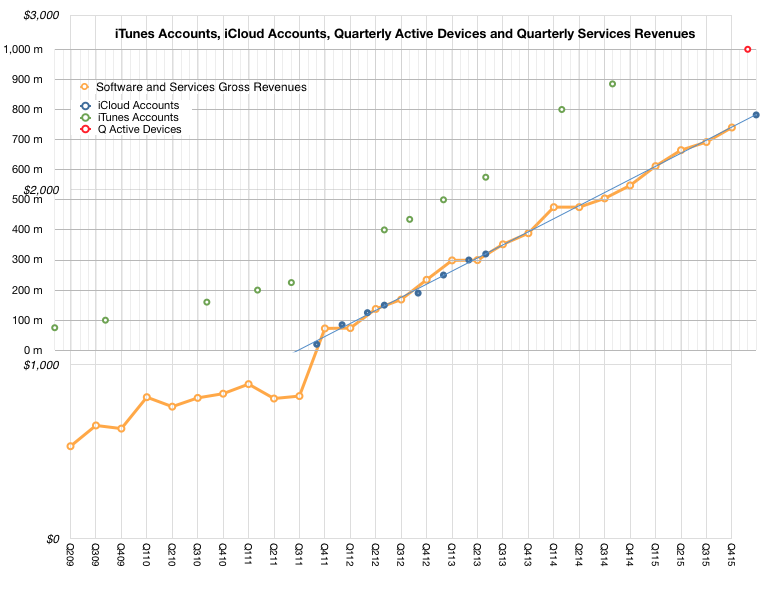
    The following graph shows the historic data for service accounts and corresponding services revenues.

    Screen Shot 2016-02-16 at 2-16-11.04.50 AM

    The following graph shows the average price per hardware product indicative of loyalty through stability in the face of growing competition.

    Screen Shot 2016-02-16 at 2-16-1.08.35 PM

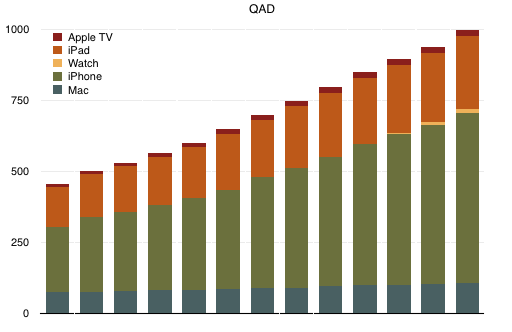
    The following graph shows an estimate of growth in active devices as a proxy of customer base.

    Screen Shot 2016-02-16 at 2-16-1.02.58 PM

    Unlike product shipments and revenue data which follow rises and falls in individual products due to the cyclicality of technology and adoption, these graphs show a smoothness and predictability of customer base behavior.

    Looking at Apple this way gives the impression that the company has a large number (nearly a billion) of repeat (subscribed to service) customers. These customers can be seen to spend a predictable recurring amount (average selling price) on Apple's brand. The repetition of these metrics in public commentary suggests that customer acquisition and retention are among Apple's goals.

    The key question is whether this is Apple's primary goal.

    Seen this way each centralized resource allocation question can be assumed to be prefaced with "In order to create/preserve customers should we...?"

    This leads to answers quite different from questions that start with "In order to sell/profit more should we...?"

    For instance, offering education products, retail store experiences, healthcare products, green energy initiatives, accessories, content and services make sense even if they may have poor financial "returns". These initiatives score highly on customer retention and satisfaction. They may lead to engagement and repeat sales. Managers working on these initiatives would gain the respect of their peers, leading to more esteem and higher quality output. Finally, and most importantly, these efforts would be preserved regardless of cyclical downturns.

    The assessment of analysts should therefore be couched in similar terms: "What is the impact of a new initiative in customer creation and preservation?" rather than "What is the impact of a new initiative in driving revenues and profitability".

    We can see immediately why the second question is popular while the first isn't: it's easier to assess an answer to the second because we have the data that allows for its calculation.

    This is why asking the wrong questions is popular.

    It's not cynicism. It's access to data.

  6. Apple Assurance

    Research · 42 comments

    Apple is categorized as a vendor of consumer electronics. More specifically, a member of the "Electronic Equipment" industry in the "Consumer Goods" sector. If indeed this is what it's thought to be selling, there is a problem because it isn't  what its customers are buying.

    Apple's customers buy a mix of hardware, software and services under a brand that assures a certain quality of experience. This bundling and integration of otherwise disparate things is why the brand is such a success.

    This anomaly between what Apple is thought to sell and what buyers actually buy can leave the casual observer confused. As a result the company's categorization as vendor of hardware deeply discounts its shares. It is, in other words a less valuable business. This is because a seller of consumer electronics does not benefit from "system valuation" since there is minimal loyalty to the product after the sale.

    The consumer electronics vendor has no network to leverage, no ecosystem adding value after the sale, no platform and works through multiple levels of distribution to reach the customer. In contrast, a system vendor can expect benefits from network effects, ecosystems, and a coveted relationship with the end user.

    The result is that the valuation of a consumer electronics vendor is based on the momentum of individual products. Apple has always been valued this way. Each hit product is considered to be a stroke of luck/genius and the chances of recurring are discounted to about zero. Regardless of the fact that it has a track record of "home runs", Apple's hit rate is not considered sustainable. ((The P/E ratio is the primary indicator in this analysis)). Certainly Apple is not valued as being able to generate reliably recurring revenues.

    But what if we were to value Apple on the basis of what people are buying rather than what it's thought to be selling?

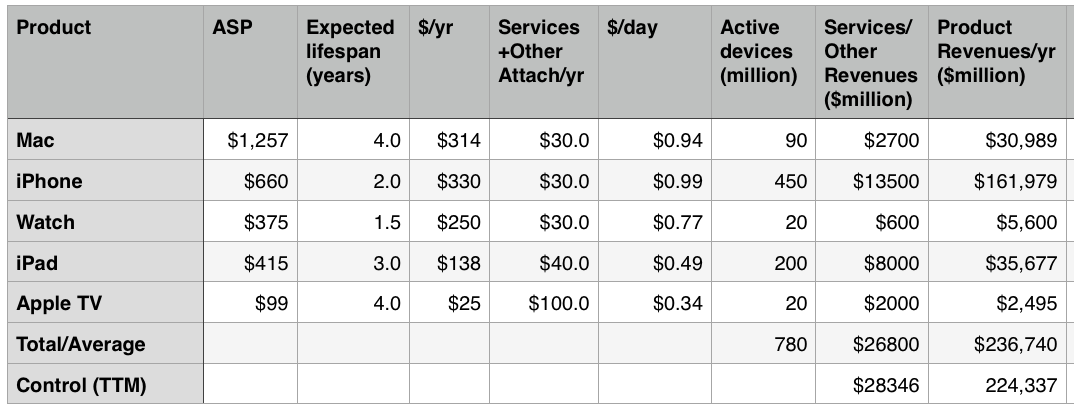
    The model is simple enough: determine the number of users, estimate the lifespan of the products, and figure out the services attached to the products; then, given the price, obtain a price per product per day. You then can get a recurring revenue figure.

    I did just that and the results are in the following table:

    Screen Shot 2015-09-15 at 5.13.27 AM

    The first column is the product, the second is the Average Selling Price (ASP), the third is the expected lifespan of the product, and the fourth column is a calculation of the end user’s “spending per year” on the product.

    The fifth column is an estimate of the revenues from Apple's Services and "Other" groups from post-sale revenues attached to the product. This Services revenue includes AppleCare, iCloud, Music, App Store, other stores, Beats, accessories, iAd, and Made for i (MFI) licensing. It also includes Google traffic acquisition revenues and other licensing.

    The sixth column is an estimate of the consumer "spend per day" on Apple's product lines taking into consideration Services.

    The seventh column is an estimate of the number of active devices in the hands of users. Note that these are expected to change over time.

    The eighth column is a calculation of Services/Other income on a per-product allocation. This is a test of the Services+Other estimate and is meant to sum to nearly what Apple currently reports as Services+Other revenues.

    The ninth column is a test of overall revenues on a per-product allocation. This should add up to total revenues (estimated for next year.) ((Naturally, the active devices estimate is the most sensitive but it should be tweaked to create a reasonable forecast for next year.))

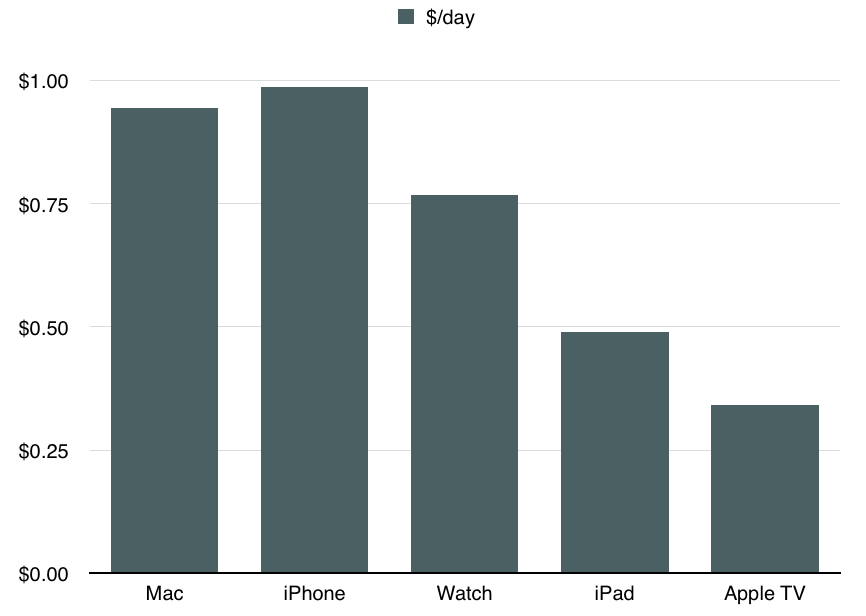
    The bottom line is the following graph which shows the revenue per device per day inclusive of Services and Other income (The sixth column).

    Screen Shot 2015-09-15 at 5.22.23 AM

    This is, in my opinion, a reasonable way to approach valuation of Apple as a business. It's also a way to inspect its strategy.

    As a valuation we can easily obtain the net present value. The model gives us sales and by estimating a net margin (which is remarkably steady around 22%) we can get the free cash flow.Iterate into perpetuity with a discount rate, and you can get the net present value of the company. With a modest growth rate leading to a billion active devices in use and a normalized revenue per device of $0.92 you can easily see cash flows equivalent to $1 trillion in present value.

    But much more interesting than this value is the notion that Apple is in business to deliver a product/service mix to loyal customers and to preserve their loyalty through constant improvement and innovation. You can see strategic intent in increasing the attach rate of services per device. You can see a strategic intent in building loyalty and the right customer base which is likely to be loyal. You can see strategic intent in the iteration of the product in a way that extends loyalty and expands the solid base but also increases the $/day rate. This analysis correctly informs almost all decisions the company makes.

    What we just saw in the launch of a new Apple TV and a new iPad is consistent with this strategy. Apple TV will have a higher service attach rate with apps while keeping pricing well below consoles thus expanding the user base. The iPad is increasing in price and getting more accessories. The developers are encouraged to build richer and more valuable apps that are uniquely enabled by the new device.

    The fact that Apple has just launched a subscription service for the iPhone  makes what was clearly their strategy all along plain to see however it has been a strategy in effect for decades.

    It isn't a difficult idea to embrace. It always surprises me that it's not more commonly held. The reason may be that Apple is mis-categorized.

    Or perhaps the entire categorization of industries and sectors is obsolete in what is a new post-industrial age. Some have figured this out already. Others will take longer.


  7. Interview With Horace Dediu: What To Expect When Apple's Expecting

    Research · 24 comments

    My thanks to Eric Jackson for his thought-out questions on Apple. As published in Forbes, here is his Interview With Horace Dediu: What To Expect When Apples Expecting.

    A few excerpts:

    Q: Do you expect to see a sapphire cover on the new iPhone(s)? Is that material significant?

    I expect Sapphire will become a signature feature across many products. I don’t know if they will have capacity to deploy on iPhone this year but on a watch it’s essential. Here’s a clue: if the screen has any curvature, especially around edges, it needs to be sapphire as glass can’t take strain in that shape. The scope of the plant they are building with GT implies that they will have massive volume potential with at least one major iPhone model using the material. It’s a significant material because it allows design freedom in new directions, especially curved (concave) touch surfaces that retain a jewel-like feel. This has Jony Ive all over it.

    Q: Is it fair to conclude now based on the 5C and 5S that Apple will never launch a “cheap iPhone”?

    Oscar Wilde said a cynic is someone who knows the price of everything and the value of nothing. When I see the word “cheap” I never know if it refers to price or value. And even when we talk about price, an iPhone is cheaper than buying all the things it replaces so it’s always been a low end disruptor in my mind. (I saw a tweet with an image of a Radio Shack ad from the 1980s and every single item available on that page is now a part of the iPhone. It would have cost thousands to buy all those things back then–and dollars were worth a lot more.) Furthermore, I think Apple holds a black belt in pricing. They seem to define their position in the market by anchoring certain prices and “owning” them. Given all that I would say that Apple is not going to move their price points much. They will expand the portfolio and offer some iPhones at $300 but they will be older models. The average selling price (ASP) I expect to remain constant on a year-long average.

    Q: In the past, Apple critics were quick to dismiss the new iPad and 5C iPhone as failures upon their introduction.  You never judge. You just report the facts and data.  That said, is there anything about past new Apple products launches that we should look at as a predictor of how a new iWatch might be received by customers?

    When the iPad was imminent the great debate was over whether it would run iOS or OS X. Many imagined a touch-based Mac rather than the “big screen iPod touch”. It was a tough call and one which Microsoft could not and still does not make. Therefore, the interesting question for me with respect to iWatch is: What OS it will run? I will be shocked to the core if it does not run iOS. It is my opinion that making iOS work on it is the entire reason Apple is sweating this segment. They are in it because they are trying to make a platform product with a novel user experience and all the power of an ecosystem run on a wrist. It’s as big a problem as getting a phone-sized device to run a touch UI was in 2007. That is the crucial contribution that Apple is making to this next generation of computing. Now you might ask what users are asking for in this segment. The answer is nothing. Nobody is asking for this. As nobody asked for the iPhone (or the Mac or the iPad). It’s a new computer form factor and how it will be used will be determined by the apps written for it. But it will work and be magical out of the box in version 1. This is in contrast to the single purpose or accessory model of wearables we see to date.

    Q: As a student of disruption, where is Apple most vulnerable to being disrupted?

    Apple is a new market disruptor but much of what is put forward as a threat to it is low-end disruption. I think Apple knows enough about how that happens that it can manage its way around it. The strategy they employ is one of attrition. If you wait long enough a low-end threat tends to wear itself out as it starves of profit and is constantly gnawed-at by alternatives. (You see, if the disruptor cannot manage a profit then they cannot climb up the trajectory to get on top of the incumbent. Being profitable is a key requirement for successful disruption in the long term.) The attrition strategy works as long as you have the fortitude to hold out and the deep pockets to keep improving your product as alternatives flame out. It is my belief that Jobs made sure that thinking is inculcated in the company. So if not low-end is the company vulnerable to new-market disruptors? This is more subtle and the threat here is what Google/FaceBook/Amazon and the other ecosystems are all about. It’s creating new usage models and shifting where consumers place brand value. I think this is more what keeps Apple’s management awake at night. They are not standing still however. iTunes and Software and Services (now with Beats on board) is the way they are staying on top of that threat.

    Lots more here.

  8. The billion dollar hobby

    Research · 67 comments

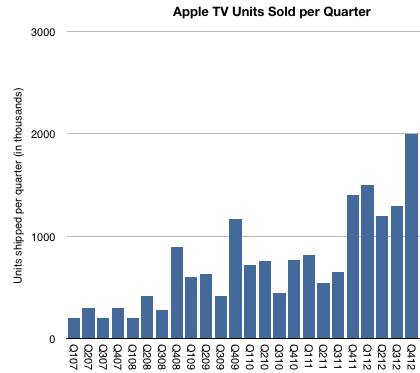
    During the latest shareholder meeting Tim Cook revealed that Apple TV sales were above $1 billion in the last fiscal year (ending September 2013). The company later clarified that this figure includes device and content sales.

    This poses a problem. In previous statements the company cited device (unit) shipments rather than value. The statements made to date suggested that cumulative volume of 3rd (current) generation Apple TV totaled 6 million units as of January 1, 2013.

    The following graph includes an estimate of quarterly Apple TV sales based on comments made to date.

    Screen Shot 2014-03-02 at 3-2-8.07.43 PM

    As there were no additional comments during 2013, the "Billion Dollar" quote is all we have to go with for the year.  The problem with trying to separate content from hardware is complicated by several factors:

    • How are we to attach content revenues to Apple TV? For example, what if I purchase a series of shows on iTunes or an iPhone and decide to watch them on my Apple TV. Do these purchases count as being "attached" to Apple TV? Do we attach the full transaction value or do we attach the portion that Apple keeps (as in agency accounting)?
    • How does Apple account for channel placement on Apple TV? Do the channels prominently displayed on its user interface pay for this access (even though the user needs a cable subscription?) Is this the primary source of content revenue that is attributed to Apple TV?
    • What about Netflix, YouTube, etc? What is the content licensing deal with these channels? Does the Netflix channel actually cause an Apple TV purchase or does the Apple TV purchase cause a Netflix subscription?
    • Without content, one might think that the $1 billion revenue would yield total device shipments approximately 10 million units in fiscal 2013 (assuming $99 unit pricing). This is not quite right however as Apple's revenue per unit is unlikely to be $99 unless all units are sold through its own retail stores (including online). Sales through other retailers probably allow for some retailer margin so Apple's average selling price will be below $99.
    • Another question is the fiscal year accounting. We have visibility into the fourth quarter of 2012 (about 2 million units est.) so we only need to fill in the first three calendar quarters of 2013 to understand the Billion Dollar volume.
    • Finally, I already estimate separately the overall video market (in my iTunes Business Report) which, based on historic data and other inferences suggests a total video content gross (contributing to iTunes revenues) of $1.8 billion for the fiscal quarter. If a significant portion (50%) of this were allocated to Apple TV it would imply that the hardware business contracted sharply in 2013. Put another way, if I add what we know about C2012 units (6 million and an ASP of $89) to what I estimate video content revenues to have been in 2012 ($1.6 billion) I get a $2.1 billion business. This would be a "two billion dollar" business in 2012.

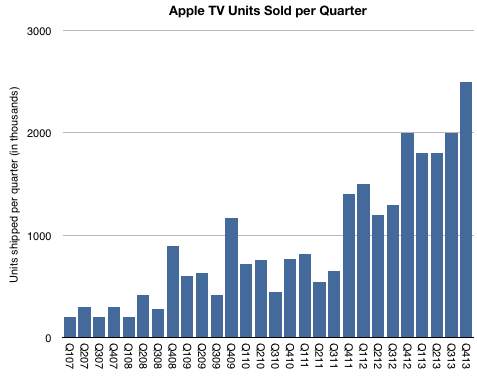
    All this makes the Billion Dollar Hobby a puzzle. The way I can make it square with existing assumptions is by saying that "Apple TV content revenues" are mostly, if not entirely, distribution revenues from channel placement rather than iTunes purchases. ((This revenue will end up in licensing/other revenues in iTunes/Software/Services segment and separate from Apple TV (which is a part of Accessories).))  As a result, my best guess now is that there were about 7.6 million Apple TVs sold in fiscal 2013, with a bit over 8 million for calendar 2013.

    If I'm right, the complete history of the shipments would be similar to this graph:

    Screen Shot 2014-03-02 at 3-2-9.08.24 PM

    By Apple standards this is indeed a modest story. The total units sold would add up to more than 25 million units with healthy growth. But it would not be in the same magnitude as other iOS devices which have so far sold 800 million units.

    More important than this picture however, or the Billion Dollar Business threshold, would be a better understanding of how Apple sees Apple TV as a business. We already knew that it was a low value hardware business. I even suggested that it's "Apple's equivalent of the Kindle": Hardware sold at low margins as a gateway for a high volume content business (iTunes). The problem with that model is that selling other people's content is never a good margin business. If it were to be sustained, Kindle may ultimately have to become an Amazon Prime salesman.

    So that leaves the Apple TV as a product without a satisfactory business model. Unsatisfactory, at least, to Apple's standards; hence the hobby label. But what if the model is turning out to be a platform for discovery of content and therefore the equivalent of (dare I say it?) a portal! ((Exclamation point.)) The TV UI certainly limits search or traditional browsing interaction but it enables eye candy for a few choice placed offers. It is a low interaction model. Think of how the prevailing UI for TV for decades has been that of pressing one button repeatedly, also known as channel surfing.

    If so , the business of Apple TV may be the auctioning of the real estate on the landing page. In some ways this is how iTunes is already behaving by "featuring" exclusive music content.

    There are all sorts of implications, which I will leave as an exercise to the reader.

  9. The price is right

    Research · 162 comments

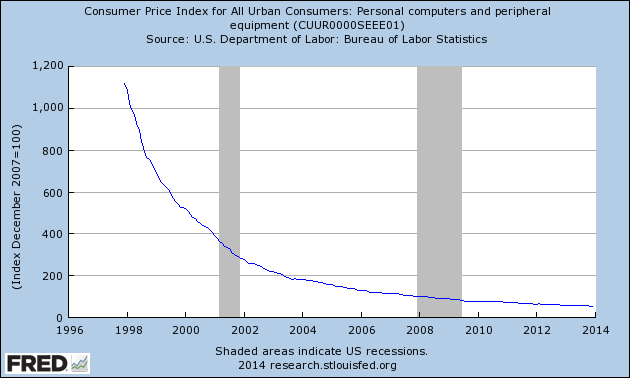
    One of the axioms of hardware business is that prices fall over time. The consumer price index for personal computers and peripheral equipment from 1998 to 2014 is shown below:

    CUUR0000SEEE01_Max_630_378

    The price index suggests that prices for computers should be 54% of 2007 levels. Charles Arthur illustrated this on a global basis using a separate set of data.

    The data shows that the weighted average selling price (ASP) of a PC has fallen from $614.60 in the first quarter of 2010 to just $544.30 in the third quarter of 2013, the most recent date for which data is available.

    The result is a chronically low margin for computer manufacturers. As Charles points out, the average profit for a PC is less than the price of a coffee at Starbucks. LG and Sony's exits from the market are symptomatic of the crisis. This is not a new phenomenon. There has been a long series of mergers, acquisitions and exits by incumbents.

    Except of course for one incumbent.

    The Mac, aged 30, seems to soldier on. Phil Schiller noted that of its original competitors, Apple is the only PC maker to still be in the market. One could imagine that this existence is marginal, or that the Mac managed to survive by giving up on unit volumes or pricing.

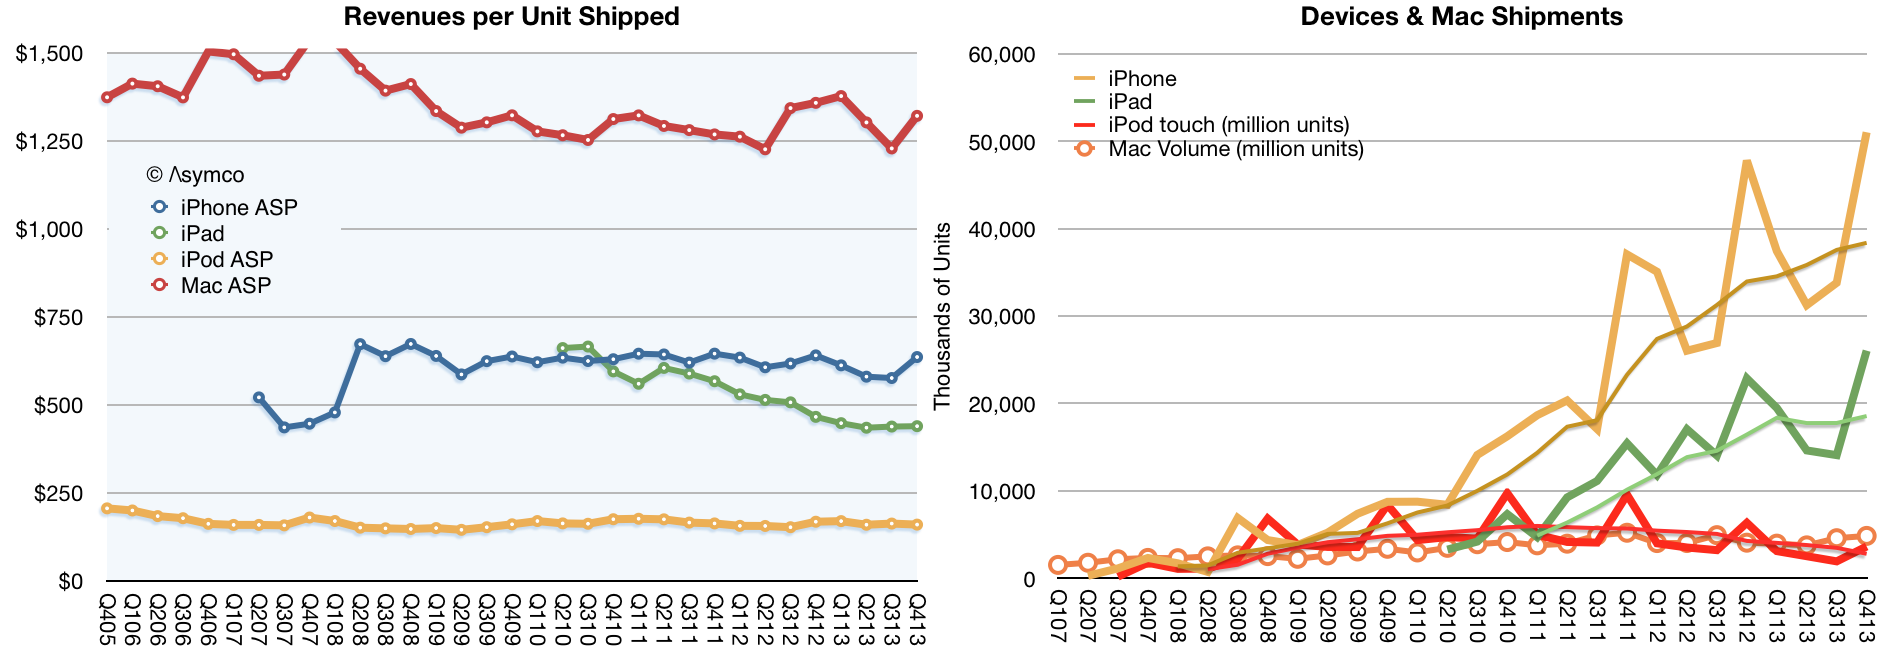
    The following graph shows the revenue per unit for the Mac and its volumes.

    Screen Shot 2014-02-20 at 2.59.43 PM

    The Mac not only continues to preserve pricing but it also seems to grow volumes at a time of overall market decline. Going back to the consumer price index, the Mac in December 2007 was priced, on average, at $1539. In December 2014, the price was $1322, with $40 deferred.

    So rather than being 54% of December 2007 prices, the Mac is almost at 90%.

    You'll note that along with the Mac I also illustrate the pricing of Apple's other devices. Even with the iPod, the pricing has remained stubbornly consistent for over 7 years. Whether the volumes are falling, rising rapidly or remaining flat, Apple's product pricing remains predictably consistent.

    The point being that the violation of the axiomatic price erosion rule in PCs is not anomalous. It suggests something about the violation of the same rule in devices. It suggests that perhaps the company does not respond to the same market forces.

    But we already know that. Jony Ive told us as much:

    “We’re keenly aware that when we develop and make something and bring it to market that it really does speak to a set of values. And what preoccupies us is that sense of care, and what our products will not speak to is a schedule, what our products will not speak to is trying to respond to some corporate or competitive agenda. We’re very genuinely designing the best products that we can for people.”

    The result is plain to see: Caring about the product means that it can be priced at a point which consumers care to pay.

    Trouble is, judging by how Apple is valued, nobody believes that this is sustainable. Regardless of the evidence within Apple's own history, it's the exception, not the rule and the bet continues to be that they cannot continue to remain an exception.

    Is Apple going to continue to repeal the laws that govern its industry, as it has for decades, or will it, as the market expects, abide by them?

  10. C is for Cognitive Illusion

    Research · 194 comments

    My assumption going into this, sixth iteration, of the iPhone was that we would see the expansion of the iPhone into two distinctly positioned products: a low-end C and a high-end S. The assumption was based on what what we saw with the iPad: the regular iPad and the mini iPad.

    By using the iPad as a template, my exercise in August was to forecast what the pricing ((Revenue/unit to be more precise)) might turn out to be for such a split-personality product.

    I expected the 5C would replace the "low end" n-2 variant ((Older by two generations as the iPad mini replaced the iPad 3)) and the 5S would continue as the core product. This is reflected in the original graph as devised in mid-August:

    Screen Shot 2013-08-12 at 8-12-11.44.05 AM

    The surprise was that the 5C was not "low end" in any way other than having a plastic case. It has a minor spec increase over the 5 but is otherwise a 5 feature set in a plastic skin. It also is priced as if it was the continuation of the 5, with a modest reduction in ASP.

    In addition, the continuation of the 4S and 4 (in China at least) means that the old strategy continues more-or-less unchanged.

    Knowing the line-up and pricing all that remains to understand is the positioning, or how the products are defined relative to each other.

    This is where there might be a shift happening. Under the old model the n-1 variant was meant to be a modest volume contributor to the portfolio, being essentially a cognitive illusion which encouraged buyers to stick with iPhone n at the expense of competitors. However, the new n-1 product (the 5C) has a distinct positioning that makes it seem fresh and not a lesser, stale version of the flagship. It is designed to appeal as a legitimate upgrade for iPhone 4/4S users.  It is, in other words, not meant as an illusion, and not focusing attention on the flagship ((It might still be an illusion for many but I'm suggesting that it won't be for most.)). Rather, it is meant to be a genuine, core product.

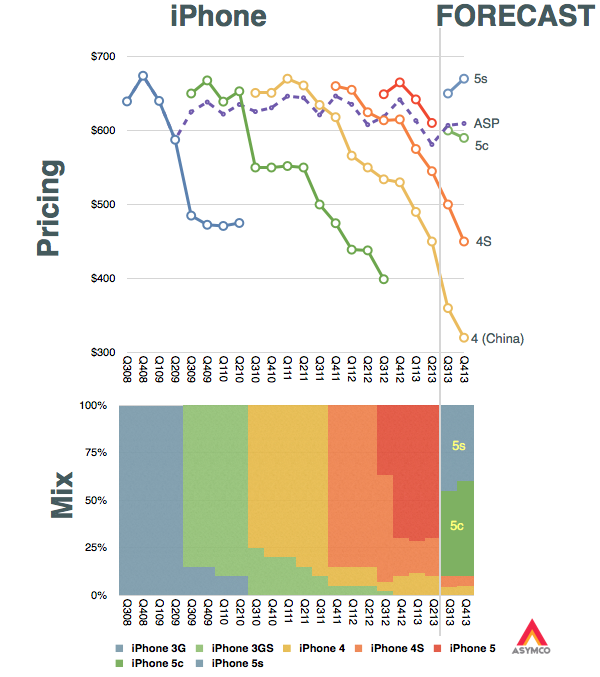
    As a result, I expect the mix of iPhones to be more evenly split between the C and S variants. I expect the C to even become the most popular version in the mid-term. My expectations are shown in the following graphs.

    Screen Shot 2013-09-11 at 9-11-11.57.11 AM

    There are several implications for this shift in positioning:

    1. Apple is recognizing that the market is actually "segmentable". This is the notion that one size does not fit all--a radical idea for the brand. Its mechanism to address it is a "good+better" portfolio. Note that this is not at all like the iPad where the Mini is actually suited to different tasks. The iPad can be thought of as a "small+big" portfolio. The iPhone shows a clear delineation within the same product.
    2. It is signaling that the premium may be more than what the mainstream needs. This is a corollary to the segmentation implication above but stands on its own because it also implies that the iPhone C is "good enough" and the S is more than good enough (or, to spin it another way, it is for "more demanding" customers.) It also implies that the premium "S" version will be a lower volume contributor.
    3. The third implication is that the basis of competition is shifting. ((It has always been expected to shift, but the timing is where all the value is captured)) The shift is toward competing for late adopters in advanced markets and with early adopters in trailing markets. The new C model is still not suitable for trailing markets as it still over-serves and is over-priced ((This post deals with the iPhone portfolio structure or the placement of iPhone models relative to one another. It does not deal with a separate question of why the overall pricing is so high. That question needs to be dealt with as a discussion about the jobs iPhone is hired to do and by whom. I'll re-visit this job-based segmentation of the market in a future post.)), but it is at least signaling the "end of the beginning" phase in the smartphone market.

    In summary I'd say that the C signals the beginning of the "good enough" phase which was also evidenced by the increasing mix of the older models during the last year. Financially it shows up as lower ASP, which, as the graph above implies, I expect to drop to $600 and lower during the next year.  Margins may not be affected much as the C is still very highly priced relative to its cost of production.

    Finally, if the good enough alternative is being "pinned" by Apple as the mid-range it also begs the question of why there isn't a specific "low end" version. It took six years for Apple to fork the product into two variants. Maybe it will take another year for it to stretch to a third. ((For more on the subject see S is for Service.))


  11. My interview with Chloe Cho on CNBC Asia's Cash Flow show

    Research · 3 comments

    My thanks to Kirk Burgess for providing this transcript:

    Horace Dediu interview on CNBC Asia Cash Flow show - 10th September 2013

    Chloe Cho (CNBC): Take us through what Apple is exactly trying to do?

    Horace Dediu: Well, this is the first time in the six years of this competition in the smartphone market that Apple has broadened its portfolio. We have seen only a single product launch every year--this is very unorthodox in the industry. Normally each competitor [ranges] dozens of devices. Apple's entry has been asymmetric from the start, and now in its sixth year we are expecting to see, finally, a broadening perhaps into two separate products. The question will be whether [there will be] a significantly lower price point for the so-called 5C and whether that will change the average selling price overall for the portfolio. The average selling price has been remarkably steady, and remarkably high, typically around $600 for the duration of this products life. Something, again, unprecedented. My expectation is the new price point will be quite a bit lower than $600, starting with about $450, it might drop a bit further, [which] would cause the overall price range to come down as we have seen with the iPad; [where we] also had a price erosion happen as the smaller version came out.

    Q: Horace, do you think they have got the timing right? Should they have done this a little bit earlier when the market wasn't so saturated and filled with cutthroat competition?

    A: Indeed, I think. As I said, as a product with six years in the market it's a bit late; I expected this to happen last year. I think a lot of the momentum that has been lost in the past year in terms of sales growth has been because of the lack of low end. To note also will be whether they indeed expand their carrier footprint. We are expecting something new in Japan and possibly China Mobile. There is a second announcement happening with a few hours delay in China. This is again the first time that has ever happened.

    Q: Horace, do you think they didn’t move down the value chain fast enough largely because they didn’t have a deal with China Mobile?

    A: Well that's always a good question whether they are driven more by carrier channels or are they driven more by consumer market expectations. I think it's a bit of both. We do have this hybrid approach where they continue selling this older product for one or two years after the new product is launched--so the 4 and 4S are still available while the 5 is being ranged. This strategy is hybrid I say because this isn't truly a low end product, it is a stale product that is being put out there. This [strategy] may be driven more by consumer demand, not so much what operators are asking for. With the 5C we might be looking at a solution for operators in particular.

    Q: Horace, how much do some these incumbents like Apple and Samsung need to be worried about Microsoft approaching their space?

    A: I believe Microsoft will not be competitive in the near term. I don't think [during] the next year we are going to see a very impactful entry from Microsoft. What Microsoft is likely do is lower prices significantly on Nokia's portfolio and their pipeline as it is. That might cause more pressure on the pricing, but the problem has been that consumers have not really been taking up the Windows Phone platform very aggressively. It has been somewhat successful in Europe but not taking off elsewhere. I think Microsoft will be in an integration mode with the Nokia assets into 2014, but I would expect in a year from now we might see some new entry product that would be exciting. I think 2-3 years down the road we might see something from Microsoft that would excite consumers as well.

    Q: There has been a lot of focus on which companies have a more integrated house, Apple or Samsung. In light of the fact that they are having to move into lower price points, in your view which is doing the better Job, Apple or Samsung?

    A: Well Samsung is a great industrial enterprise and they are doing very well by broadening as much as possible their portfolio, even before the smartphone race started for them, which was in 2010, they were known for being one of the most prolific product creators out there. They actually had over 100 different mobile phones, not smartphones, just regular mobile phones that they would range, and Nokia were extremely concerned by this pressure they were getting from Samsung.

    What they have seen since 2010 is the same thing, except with smartphones, and so they’ve been really prolific and covering the spectrum of price and screen and every other possible variant that could be made. I think however that Samsung hasn’t got a software platform under its belt. They could become a software player by taking over some of the control of Android as we have seen Amazon do, and thus really establish themselves as a platform player. They are doing so to some degree with the "Gear" product, and they might be doing something like this by launching their development conference this year.

    But they aren't yet a platform player whereas Apple is, but then again we just don’t know what the politics of Android are with respect to forking it by an OEM as large as Samsung.