Apple's revenue for the first quarter was $24.7 billion, which at 83% was the largest quarterly revenue growth they ever experienced. Operating margin was an all-time high of almost $7.9 billion, representing 31.9% of revenue and yielding 95% EPS growth.
After earnings were announced the share price reached $350.7. This includes $70 in cash. Trailing twelve months' earnings were $20.97. That makes the Price/Earnings ratio 16.7. Excluding cash, P/E is 13.4. The average growth over the past four quarters was 77%.
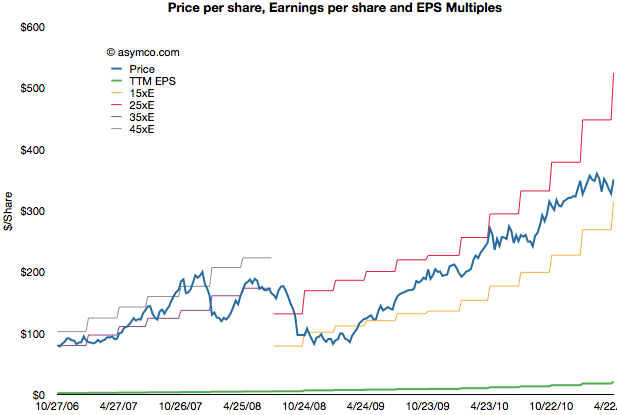
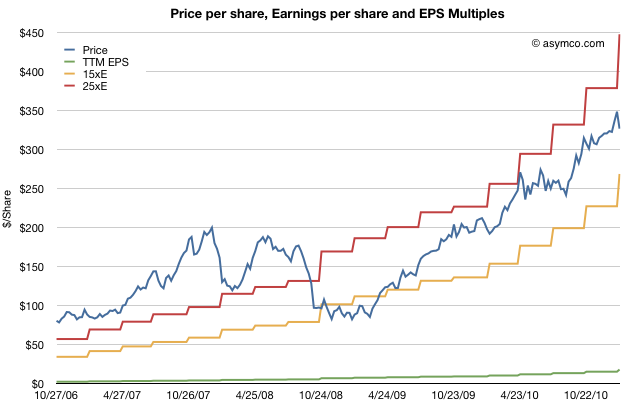
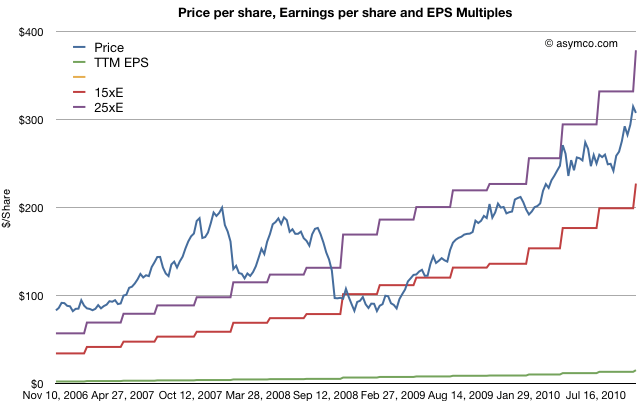
The following chart shows the share price vs. earnings. The green line is price and the blue line is share price. I also added multiples of the earnings to show how the stock traded in certain multiple bands.
During the period of 2006 to 2008 the company shares traded roughly in a range of 35 to 45 P/E. Since late 2008 the company shares have traded in a range of 15 to 25 P/E.
Share prices normally reflect potential earnings growth and past growth is often a good indicator of near term continuing growth. This is why the P/E is usually a proxy for growth. The faster the growth, the higher the P/E. Or so one would think.
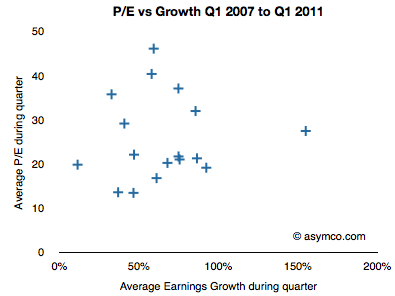
If we look at the P/E vs. earnings growth for Apple, the picture is not encouraging.
P/E and Growth don't seem at all correlated. In fact, if we drop two outliers it almost seems that P/E is insensitive to growth.
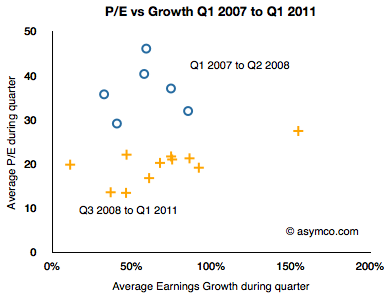
I took the data a step further and separated it into two clusters: pre-recession and post-recession.
The blue circles are Q1 '07 to Q2 '08 and the orange plus signs are Q3 '08 to Q1 '11. As the share price chart implies, there is a clustering of averages where during the 2007 and early 2008 period P/Es were in the 35 range while growth was in the 50s and P/Es below 20s with similar or higher growth ranges.
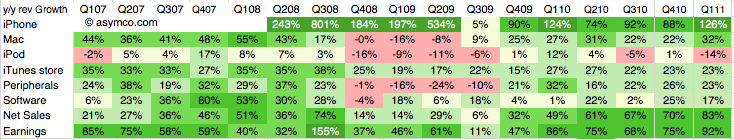
As the following scorecard shows, the company's growth is exceptional. That does not seem to be something that is being valued by investors.
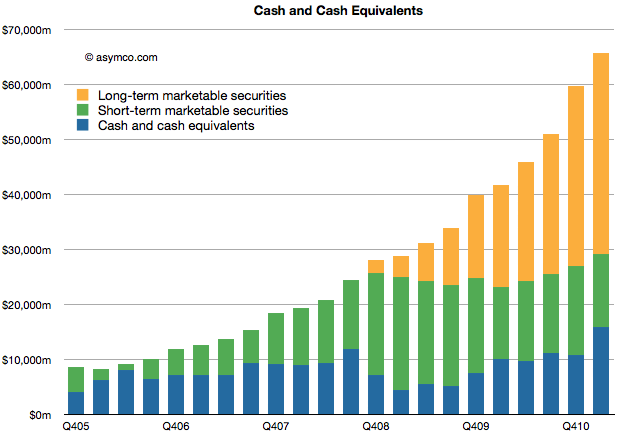
Apple's cash for short-term and long-term marketable securities totaled $65.8 billion at the end of the March quarter. Cash increased by $6.1 billion.
The increase in cash is net of approximately $900 million for prepayments and capital expenditures related to the strategic supply agreements that Apple announced last quarter.
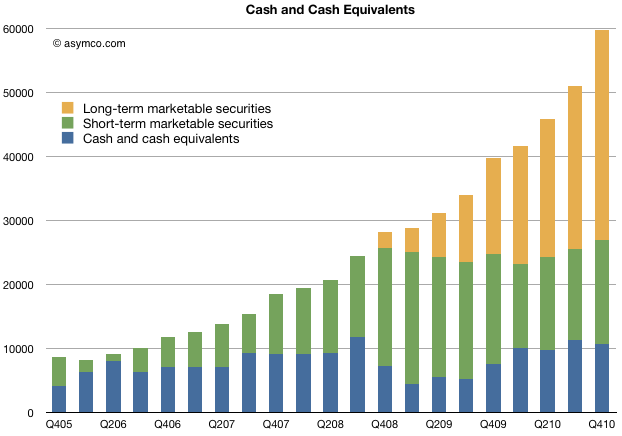
The following chart shows the historic cash, short-term and long-term liquid assets Apple holds.
As in previous quarters, the securities Apple holds are:
Cash
Money market funds
U.S. Treasury securities
U.S. agency securities
Non-U.S. government securities
Certificates of deposit and time deposits
Commercial paper
Corporate securitiesMunicipal securities
Although the asset classes are all liquid, those with longer maturity dates are classified as "long-term" securities (orange area in chart above) and are often not counted as "cash" in many financial databases.
The enormity of the overall size of this cash can be put into several perspectives:
The funds are big enough to place Apple's CFO office in the top 100 largest fund managers in the world and larger than any hedge fund manager.
Cash growth in one quarter was higher than the market cap of many companies. For example, if pre-payments were added back, the cash increased by about the market cap of Motorola Mobility.
Current cash is worth more than Nokia, RIM and Motorola Mobility's market caps, put together.
Apple's cash is worth half of Google's enterprise value.
About two years ago, in January 2009 the stock traded at a price of $78 with at least one analyst placing a target of $70 on the stock. Today Apple's cash is worth $67 70/share.
If you owned $100,000 of Apple stock, $19,000 of that would be cash and only about $80,000 would be "at risk" capital.
If Apple had no revenues, the current cash would sustain operations (SG&A and R&D) for over 7 years or until the middle of 2018.
When analysts cite limits to the rate of Apple's growth on the basis of the "law of large numbers" I wonder if there is an implied limit to how big this cash pile can grow. By looking at the chart its size seems to be growing faster all the time.
[Updated] The cash per share figure was wrong. It is $70/share.
At last night's closing price Apple was trading at a P/E of 16.3. Excluding cash that ratio was at 13. On a conservative forward basis (my estimates) the stock is priced at less than 10 times next twelve months' earnings.
These figures show a remarkable pessimism that has persisted around Apple for years. It was slightly, but not much, worse during the great recession. It persisted whether the company was growing at 30% of, as now, 95%.
There are many hypotheses about why Apple's earnings and growth are considered worthless. They come and go with the whims of the age: recession, elitist, luxury branding, health issues, macro "headwinds", earthquakes, phantom competition.
Lately it's become fashionable to blame Android. That's a curious thing to me, because Android has been discussed at length here and it has been shown to be, for the time being, benign. Apple has not "lost sales" to Android as it has been selling all it can produce. In some ways it's been a boon as a co-belligerent against non-consumption.
The argument that the discount is in effect because of the future of Android has one first strike against it: the fact that the market does not often discount the distant future. Capital markets are notoriously incompetent in spotting disruptions and often reward those who are failing right up until the bitter end.
But let's take the "Android hypothesis" (i.e. that Android is causal to Apple's share price) seriously and analyze it. How could the impact be measured?
Since Apple is trading at a fraction of (a) historic multiple (b) multiple based on growth (c) comparable companies' multiples then we can assume that a "normal" valuation would be twice the current (i.e. a multiple of about 32). That would still be a discount to growth and history but it would begin to match some of the comparables. A doubling of the P/E would be a good start.
But a multiple of 32 would imply a doubling of market cap, which means that the Android hypothesis is causing the evaporation of about $300 billion in future profits. So it stands to reason that it's responsible for a $300 billion destruction of Apple shareholder value.
That's an interesting number since Google itself is only worth about $169 billion.
The measurement then presents a remedy: If Apple bought Google (it already has a third of its value in cash) and it shut down Android, it could create $300 billion in value. If could even throw away all of Google and still walk out with a profit.
Since reporting on the 18th, I've mostly finished going over the the fourth quarter Apple data. Here is a quick summary of the articles that covered the financial and product performance:
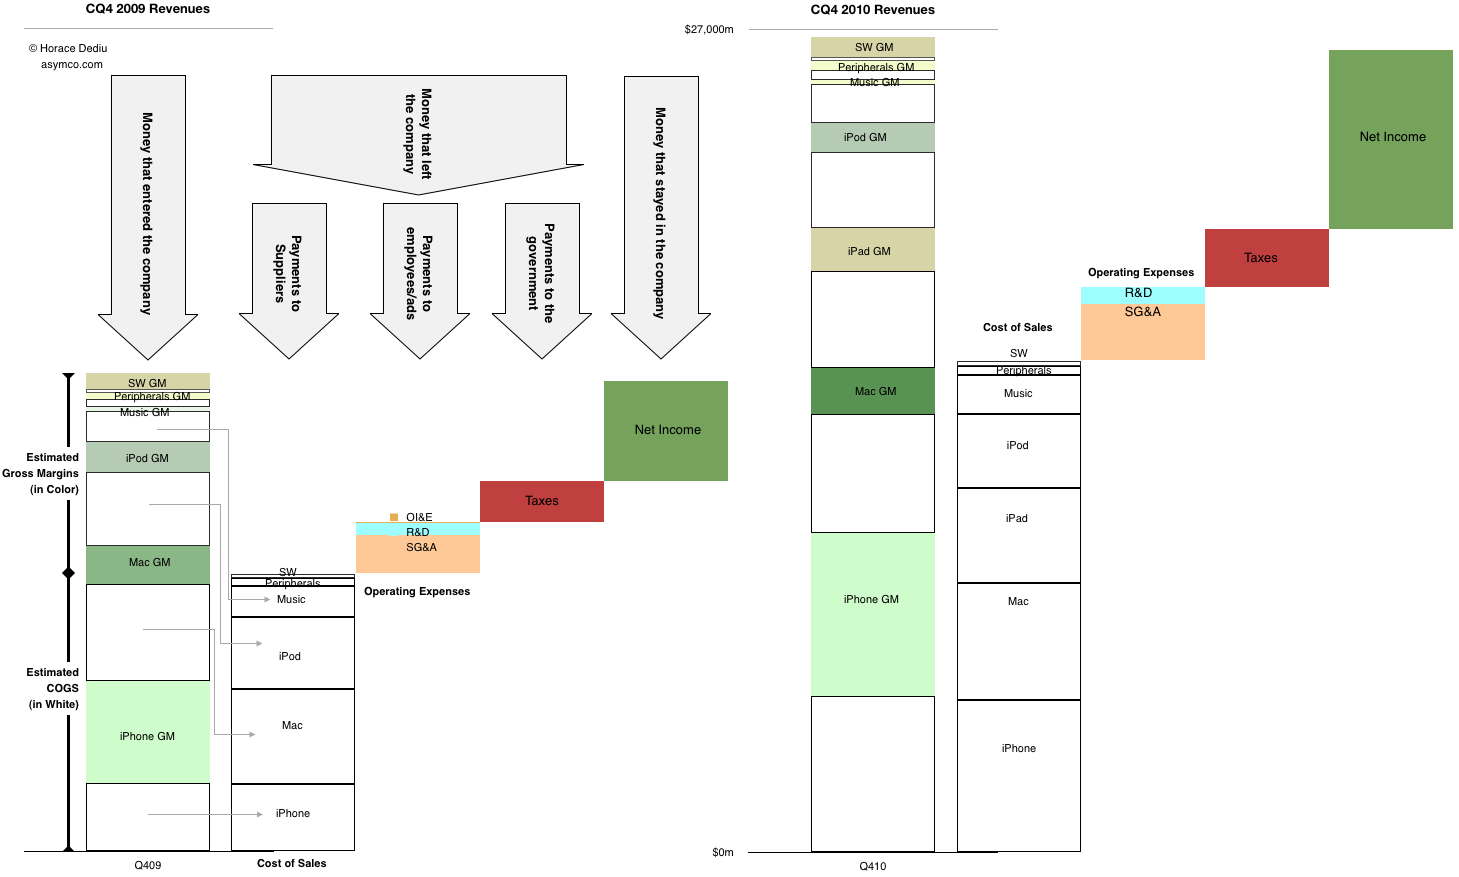
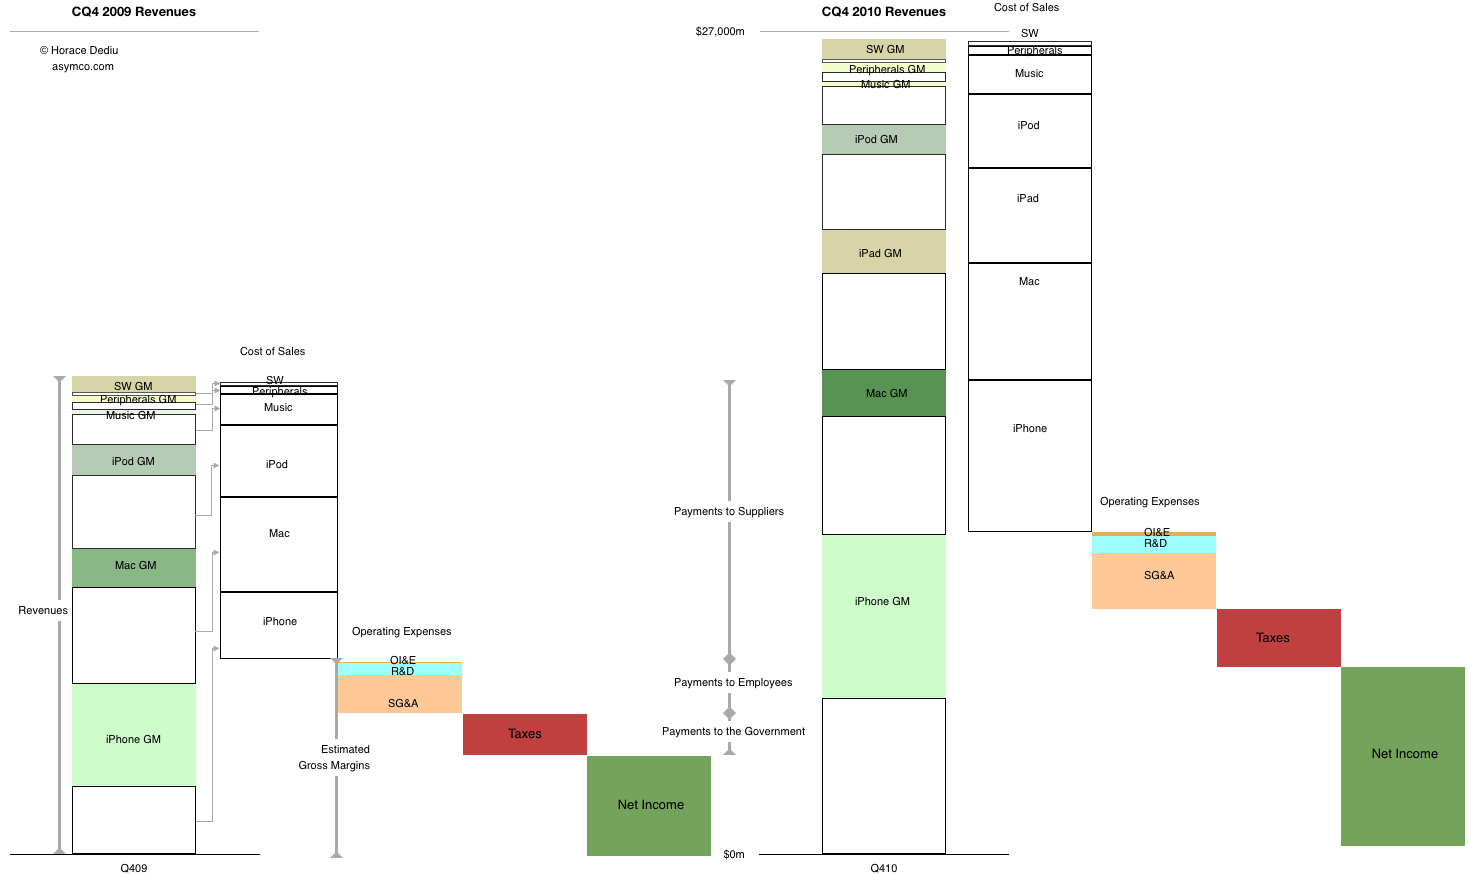
After introducing it last quarter, this is a chart that I'm trying to improve and use as a single snapshot of growth, product mix, profitability, cost structure and overall sales. The purist in me likes to see the chart clean but it can be a puzzle to some. So for the sake of explanation, this time I've added some annotations to the year-ago quarter.
The left half shows flows in the same quarter a year ago and the right side shows the flows in the fourth quarter just ended December 2010. You can see where sales came from, how much of each product's sales went to suppliers and how much was available to pay employees (and who got what). You can also see how much was paid in taxes and what was retained.
Please click on the figure (requires no scrolling when viewed on screens wider than 1464 pixels).
As shown in the Apple growth scorecard, the company's earnings growth is continuing at 75% with the top line increasing at the annual rate of 70%.
The $59 billion of cash on the balance sheet has reached the equivalent of $64 per share yielding an enterprise value of $263 per share based on closing price of January 21st.
The stock price has been rising but not outside a narrow P/E band. The following chart shows the stock price and the 15 P/E and 25 P/E bands that have bounded it for nearly three years.
As previously observed, this overall share appreciation is not accounting for the growth in earnings.
The trailing twelve months' earnings were $17.91 per share. Therefore the P/E ratio is now 18.2. Excluding cash, the P/E is at 14.7. However, that's based on 2010 levels of earnings. Those earnings are increasing very quickly.
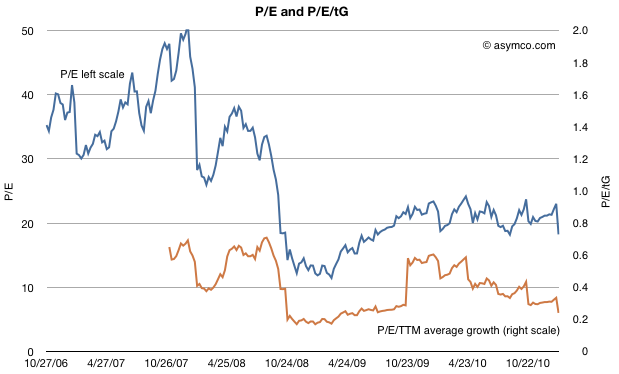
To account for earnings and their growth, I developed the following chart which shows the P/E and P/E/trailing-Growth for the stock.
The P/E is fluctuating on either side of 20 but when considering trailing growth, comparable companies, the macroeconomic conditions and guidance the value of the company is reaching new lows.
P/E/tG nearing recession lows
Earnings were 75% higher in 2010 than the year before. So based on the growth, the rule-of-thumb ratio P/E/trailing Growth (P/E/tG) is 0.24. This ratio (where 1.0 is seen as "fair value") is the lowest since July 2009, during the first months of recession recovery. The trend for this ratio is down (see the burnt orange line in the chart above). It's not far from hitting the lowest point during the recession at 0.17.
Now I'd like to reminisce a bit about that point in time. The stock had bottomed at $78/share[1]. It was trading at barely 3x cash and a P/E of 11 but growing 3x that level (32% in the slowest recession quarter but averaging much higher).
So today we are at a similar point in valuation. The cash is at $64/share, shares are priced 5x that amount and the growth is 4x P/E[2]. Although analyst targets are less comical, there is still the sense of extreme despondency when looking at the valuation ratios.
Guidance, Comparables and Macroeconomics
Unlike two years ago there aren't the same dark clouds on the macro horizon. The company is also not as cautious on its guidance (guiding 63% EPS growth must be a new record for a post-holiday quarter) and there is talk of bubble in valuation for comparable companies. Netflix, Amazon, and ARM have eye-watering valuations relative to growth.
A discount to the S&P 500
And to round out the tragic tale, Apple's P/E is, once again, at a discount to the S&P 500 P/E (14.7 vs. 16.57 respectively).
Given the new low in valuation contrasted with optimism on behalf of many (including management), on some forums there is discussion about Apple becoming the target for a take-over.
There is some perverse merit to this logic. With $64 in cash, $25/yr in earnings and 75% growth it's so cheap that if credit were available, it would make a tempting candidate. Private equity could take it private and use the gigantic cash flow to pay off debt (in about four years). In bygone days, this would have been an easy pitch.
Alas, the capital markets may not have liquidity for the size of the market cap Apple holds and I don't see any competitors able to get the leverage for an acquisition either. Or can they?
---
Notes:
In early summer 2009 some analysts put 12 month targets for the stock at $70, so their predictions were within $6/share to today's book value.
A buyer of shares two years ago would only have to wait two years to have 80% of their investment sitting in retained earnings. An investor who read the data from Apple and knew that the iPhone existed could not fail but be amazed.
When I wrote suggesting that the "best use of cash" was not acquisition but integration of manufacturing under the Apple control umbrella, the rumor that set off that discussion was that Apple was financing new facilities for its suppliers.
Those rumors were quashed, but we now know there is something to them.
During the September and December quarters, we executed long-term supply agreements with three vendors through which we expect to spend a total of approximately $3.9 billion in inventory component prepayments and capital expenditures over a two-year period. We made approximately $650 million in payments under these agreements in the December quarter, and anticipate making $1.05 billion in payments in the March quarter.
So Peter Oppenheimer confirmed that Apple is using its cash as a loan facility for its manufacturing partners. It's not for the first time either. Apple used the same leverage to ensure the supply of flash memory for the iPod line in 2005.
Philip Elmer-DeWitt reminds us Tim Cook confirmed:
The deal, he said, is similar to the one Apple cut five years ago:
"As you probably remember," he began, "we signed a deal with several flash [memory chip] suppliers back at the end of 2005 that totaled over $1 billion because we anticipated that flash would become increasingly important across our entire product line and increasingly important to the industry. And so we wanted to secure supply for the company.
Partly as a result was a dominant position in the music player market that is still paying off today.
The use of capital to pre-pay for production is not therefore new. What we saw last quarter however is that it's using capital to ensure there is additional capacity.
In other words, Apple Inc. pre-buys additional capacity by using Bank of Apple capital as a loan facility to bring more capacity online. How to judge this use of capital depends on your perspective:
From a fiscal perspective, Apple is acting like a trade lender (with moderate to low returns on capital.)
From the operational perspective Apple is acting as a limited manufacturing partner, just short of an equity holder.
From a strategic perspective, the Bank of Apple lends only to suppliers that commit to producing for Apple Inc. Thus locking out competitors.
This strategy is not without risk. Those loans are forward contracts on production. The risk is that production is unneeded and hence the loans won't be "paid back". But Apple knows demand and supply in this market better than anyone else, so it has an unfair advantage over the market. So the rewards are probably out of proportion to the risk.
By buying an option on production, not production itself Apple has a clever way to "own factories" without actually owning them: gain control over marginal increase in production without the impact from CapEX or depreciation.
The return on that option will never be seen on the OI&E line in the income statement and the cash once recycled back into the balance sheet will seem to be sitting unrewarded. But the return on that capital will show up in the bottom line by way of margin and top line expansion for years to come.
The committed capital is still tiny, but a proper analysis of Apple's cash management would be to look at the return on cash as more than the return on treasury bills.
But in this forum I've been critical of their strategy. Though I'll be the first to admit that such criticism is not founded on data but on intuition, strategy is always made in a vacuum of data. It is just an unfortunate fact of life that we don't have data about the future.
But what data we do have is about the past and it shows the contrast between Apple and Google.
As a sample, let's look at the performance in the last quarter:
[nohang]
Growth
Google
Apple
Revenue
26%
70%
Earnings
29%
75%
P/E
24.13
18.57
[/nohang] Apple grew about 2.5x faster. The companies are in very different businesses, but the money they make is the same color. The investors have been paying attention:
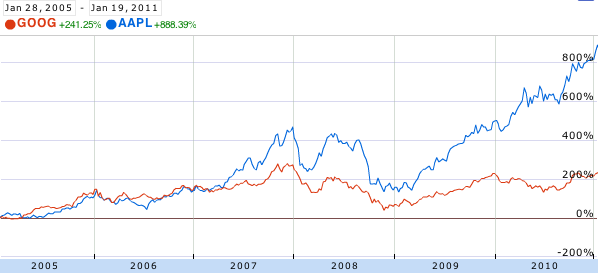
In 2005 and 2006, Apple and Google were neck-and-neck in terms of returns to shareholders. However, with the iPhone's arrival in 2007 the stocks diverged. Google gained 38% since January 2007 while Apple gained 300%.
However, going forward, the market is kinder to Google than to Apple, punishing Apple's 75% growth with a P/E of 18 (ex-cash 15) and rewarding Google's 29% growth with a P/E of 24 (22.5 ex-cash) . Although Google's P/E is proportionate relative to its growth, Apple's P/E implies deep pessimism.
But does Google's performance suggest management failure? Certainly not. It's been a great performance. Google is arguably at the top of its game. Market share of search has never been better.
Cracks in strategy are hard to spot. One hint is that most of Google's R&D efforts are defensive. Building browsers and mobile operating systems are methods to ensure they have distribution of search to as many screens as possible. These are expensive means to ensure channels are available for distribution. Expensive not only in terms of engineering costs but also in terms of relationships and opportunity costs.
But even a defensive posture is not sufficient for management change. What I think is the most serious failure is that for the past five years Google has not addressed the possibility of search itself becoming commoditized. Social media and app economies are asymmetric to search. They make money in different ways and appear to be less efficient or effective means to reach users, but they are growing. Facebook has overtaken Google in terms of page views and apps are a new interaction model for cloud-based content that does away with the indexing model Google champions.
The real condemnation of the leadership at Google is that there has been a failure to create entirely new disruptions. As the stock chart above confirms, Android and Chrome are, if successful, sustaining technologies for Google. That's not going to be enough.
The following chart shows the value of Apple's cash and cash equivalents for end of 2010:
This represents $64/share (current price per share is about $340, making the enterprise value about $276).
The company was trading at $64 per share in July 2006.
Here is a list of iconic companies whose market cap is less than Apple's cash.
Visa Inc. $59.63b
American Express Company $55.8b
The Boeing Company $53.16b
Morgan Stanley $43.5b
The Dow Chemical Company $41.8b
NIKE, Inc. 40.22b
Eli Lilly & Co. $40.12b
Texas Instruments Inc. $40.92b
Nokia $39.92b
News Corporation 37.72b
I would also make note of the trajectory of the cash. Growth is accelerating. The last quarter Apple added $8.7 billion in cash. A year earlier it added 5.8 billion and the year before that $3.6 billion.
The amount of cash added is more than the amount of cash the company had five years ago.
In 2010 the company added $20 billion to its cash reserves. In 2009 the company added about half that amount.
If the trend continues, Apple could see $100 billion in cash by this time next year. That's about what HP is worth now.
In a recent but recurring lament I asked why Apple shareholders are not being rewarded for the company's growth. I pointed out that there is no fundamental reason why the company should receive such a low P/E multiple (about 18 ex-cash trailing and 10x forward while maintaining 70% earnings growth for over a year).
There were many objections in the comments. Most of them dealt with recent reasons why doubts might have arisen among investors: Android hegemony or some perceived lack of competitiveness leading to margin compression or some macro hangover from the recession.
In this article I argue that none of these objections hold water. My argument hinges on the fact that there is a precise date when Apple ceased being seen as an exceptionally valuable company and that date precedes any of the causes being suggested.
The day of disillusionment was almost exactly three years ago: January 14th, 2008.
How to pin down the date of disillusionment
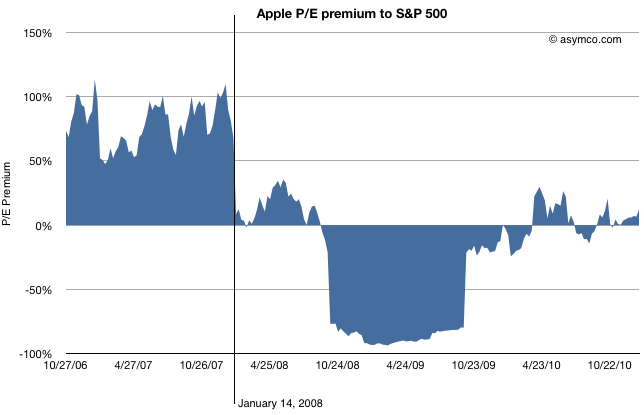
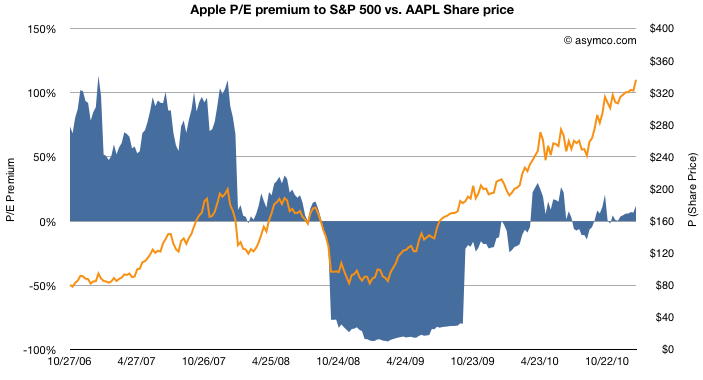
Consider the following chart.
The blue area represents either a premium (above 0) or a deficit (below 0) of Apple's P/E (ex-cash) relative to the S&P 500 P/E. This is a re-imaging of a chart, first introduced in June 2010 when I first pointed out that Apple was being discounted relative to the S&P 500.
By measuring P/E I am focusing not on the stock price, which has grown nicely, but the ratio of the price relative to earnings, which hasn't (see the next chart below). P/E is a fundamental measure of potential (its reciprocal is the stock's earnings yield.) It is usually highly correlated to the company's growth. If that P/E is uncorrelated to past growth, there is some significant discounting of future growth. It's the most significant (and simplest) measure of "faith" in a company.
By measuring the company's P/E relative to an index of other large companies (S&P 500 P/E) we can assess whether the company's potential is being valued as extraordinary or whether it's being valued as ordinary. In other words we are measuring whether a company is "special".
The chart shows that until January 14th, 2008 the company was valued at a significant earnings premium--a P/E consistently 50% higher than the norm.[1]
Following the collapse (about 40% drop in share price but 100% drop in P/E premium), there was a small recovery followed by a huge trough in valuation. During the recession quarters Q308 to Q309 S&P earnings fell to zero or below. As a result of S&P earnings collapse the S&P P/E shot up astronomically (as E approaches zero, P/E approaches infinity). Apple's earnings dropped as well but remained positive throughout that period bottoming at 37% growth(!) in Q408. As a consequence Apple's P/E fell as low as 11 while the market's went well above 100 (122.41 peak). The P/E deficit for Apple went 80%: Apple was valued as basically worthless (3x cash).
After the earnings recession, the S&P P/E recovered close to historic levels but Apple's P/E did not. It's in-line with the S&P but does not obtain the 50% premium preceding the recession.
So we can establish that the day that Apple's potential was discounted was nearly six months before the onset of recession.
What other discounting factors can we discard?
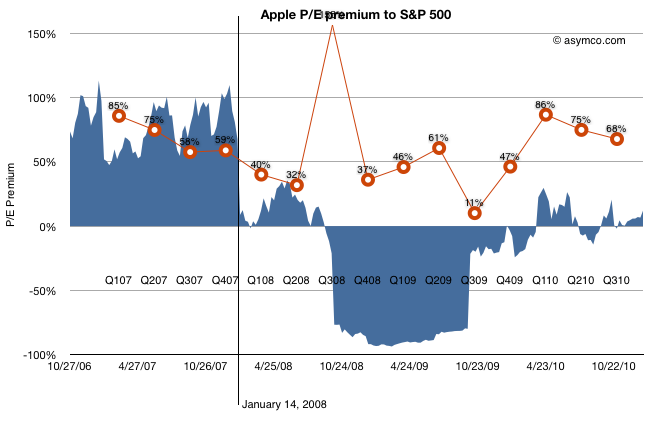
How about earnings growth itself? Did the collapse foretell an earnings collapse?
The chart above shows the P/E premium vs. earnings growth (in red). Although earnings growth began to slow soon after the 14th (earnings for CQ407 were not yet announced at that point), growth recovered six months later after the launch of the iPhone 3G[2]. Growth continued throughout 2009 and 2010 reaching new heights last year of 86%.
Still, the company received no premium to the S&P 500 P/E. Companies in the index averaged, at best, a quarter of Apple's growth in earnings.
What about Android? The first Android device did not ship until October 2008 (HTC Dream or T-Mobile G1). There were no appreciable Android volumes until 2009, one year after the drop in relative value and no talk of a threat until 18 months later.
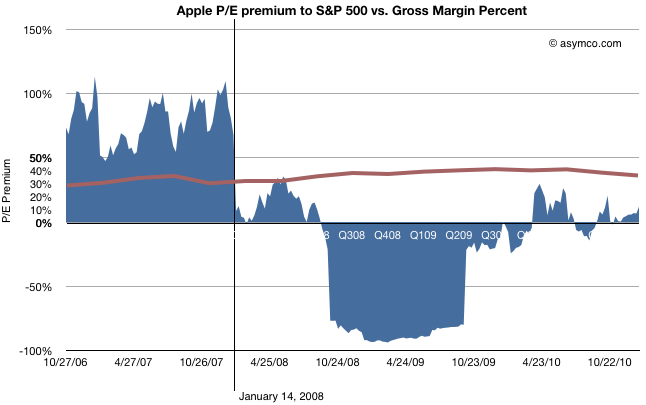
The last objection to be put aside is that of margin compression.
This last chart shows how margins (in brown) behaved during the same time period. They went up. The only slight decline took place during the last few quarters, after the launch of the iPad, long after the collapse.
Regardless of the adjustments with product launches, Apple's GM is the envy of the world and is not at all correlated with the loss of faith in the company.
So What happened on January 14, 2008?
Having led you this far in the story, I'm afraid I'm going to let you down at the end: The cause for the loss of faith is a mystery to me.
There is only one noteworthy event that took place on that date: Macworld 2008 (January 14-18). During the keynote, Steve Jobs introduced the Macbook Air (and Time Capsule and Leopard and pre-announced the iPhone SDK which, six months later led to the app supernova). I remember that day and I remember that the stock began selling off exactly at the point when the Air was mentioned. It has never been the same since.
Obviously, correlation is not causation. The Macbook Air need not be the cause for the loss of faith in Apple as an investment. Or can it? I'm hoping someone can explain this because to me it makes no sense. The product was not a home run but it did not do badly either and its current incarnation seems to be a hit. Whatever sins the original Air may have had have surely been expurgated by now.
Regardless the cause, the bottom line is that, in the eyes of investors, Apple stopped being "special" that day. Its valuation dropped to in-line the S&P and, given its growth, well below what a large growth company should be worth. The company's shares went into the bargain bin and are still there today.
---
[1] I should point out that the P/E ratio is based on post 2009 re-stated earnings. The restatement changed the P/E as the "E" changed. This was based on the abolition of subscription accounting for the iPhone. Although it may seem unfair to hold the market to this standard, restatement did not actually change cash flows which were transparent and visible to all, even to amateurs such as myself and the other unaffiliated analysts that published throughout this period. Earnings may be an opinion but cash flow is a fact. Valuation on the basis of cash flow should have yielded the same results as shown above.
[2] That quarter showed a y/y growth of 150% while the stock was in freefall. In fact, it was during that earnings day that Steve Jobs came on the conference call and pointed out the astronomic iPhone cash flow to an audience of analysts more concerned about their own jobs.
Yesterday I attended the first meeting of the Forum for Growth and Innovation. It's an initiative where practitioners of Clayton's Christensen's theory of innovation can review new academic research before it's published.
The Forum has another goal: to disseminate and propagate key learnings and ideas. As a keen student of the theory and a blogger, I am eager to provide a gateway for you, my audience, to this management theory.
My modus operandi has been to discuss an industry or a set of competitors in great detail while occasionally stepping back and suggesting a cause for the patterns of behavior we are witnessing. More often than not, the causes are described very well by the theories in Christensen's writings.
There are cases where the theory does not seem to match. That's actually the most exciting part of this process. Exception (or anomaly) handling is what allows the theory to evolve and improve.
Yesterday's event focused on M&A. It's a cliché to say that M&A is a recipe for failure but there are recipes to follow that minimize the chance of failure. The forum debated these recipes and we were treated to the wisdom from those who learned the hard way what works and what doesn't. (For example, the ex-CEOs of Best Buy, Arrow Electronics and a senior executive who worked under Jack Welch at GE.)
What I came away with was a new respect for the counter-intuitive and contradictory nature of acquisition integration. What often makes sense on paper like synergies or new growth can quickly turn to a loss of the core business. Recipes for deciding what to integrate and what to keep autonomous are an active area of research.
For this and many other reasons, it's easy to understand why Apple is reluctant to make large acquisitions. The market discounts Apple's cash because it is expected to evaporate in a mis-guided acquisition (since that's what management has shown a propensity to do in most other large US companies.)
I've written about why I think Apple's cash is worth more than other companies' cash (e.g. Microsoft.) Apple's reluctance to make large acquisitions and no record of such should provide some hope.
However, I don't think that reluctance is simply a coincidence or a lack of suitable candidates for acquisition. I think it's more a result of the company's processes and priorities. As long as the team in charge is focused on the details of execution and integration, and as long as acquisitions are complex and fraught with unknowable risk and lack of control, I see no acquisition in Apple's future.
In the previous article discussing the growth scorecard, I left open the question of how Apple's growth is reflected in its share price.
The approach to answering this question is to show how the share price correlates to that growth. The challenge for analysts has been that the company switched from subscription to current accounting for the iPhone (the largest component in its income statement). As they re-stated income and thus earnings, any historic review of P/E or other multiples of Earnings have to also be re-computed.
So this is what I've done:
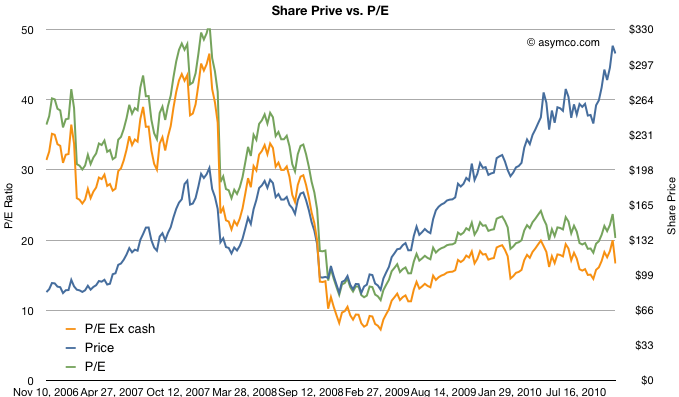
The first chart shows Apple's price per share (blue) vs. its trailing twelve months earnings (green) and multiples of those earnings (15x and 25x).
The chart shows how Apple was priced well above 25 P/E before October 2008 and has remained within the 15 to 25 multiple bands since the winter of 2008/2009. This seems fairly reasonable and the stock's rise is a cause of celebration for many, but a cause for concern for some. Is this rise in price matching a rise in value?
To answer, we need a way to look at the valuation of Apple. One way is to plot the P/E ratio over time. That would show how the market perceives the value of the company (i.e. how many years' worth of earnings is built into the price) The chart below does that.
I took the additional steps of plotting the P/E excluding cash from the price to show "P/E Ex cash" in the orange colored line and I also copied the Share price line from the first chart on this one for contrast.
What the P/E analysis shows is that as the stock rose, it's P/E ratio fell. This means that the "valuation" of the company is quite a bit lower now than it was in 2006 and 2007. In fact, as a multiple of profitability, Apple's stock is nearly half as valuable now as before the recession.
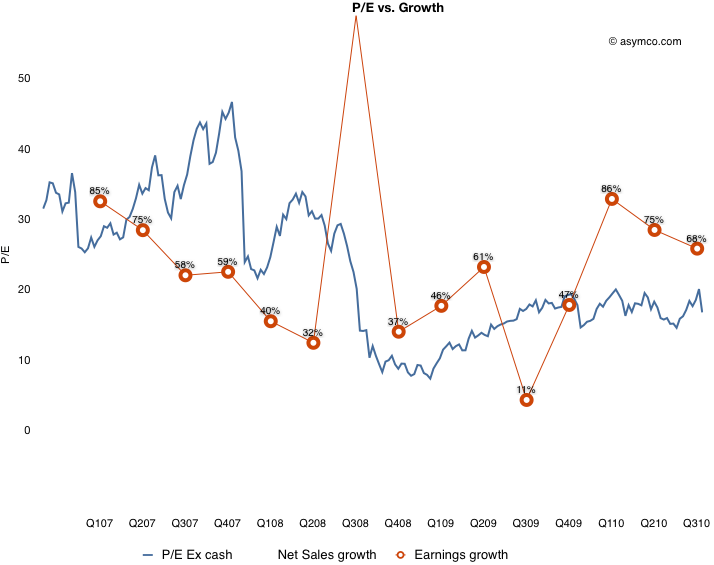
Since valuation is usually correlated with growth, (P/E is often compared in a ratio with Growth) we need to see whether the P/E in the chart above matches the actual growth of earnings. Fortunately we have just measured growth with the scorecard. Here are the two charts together:
What this shows is that while earnings growth did slow down in the lead-up to recession (with the hugely anomalous 3G launch spiking growth to 155% in Q308 causing the year-later plunge to 11%), growth picked up again in the depths of recession and has moved back to pre-recession levels. The only difference is that the multiple assigned to the stock has remained near recession lows. This is visualized by the blue line being mostly above the red line pre-crash and usually under it post-crash.
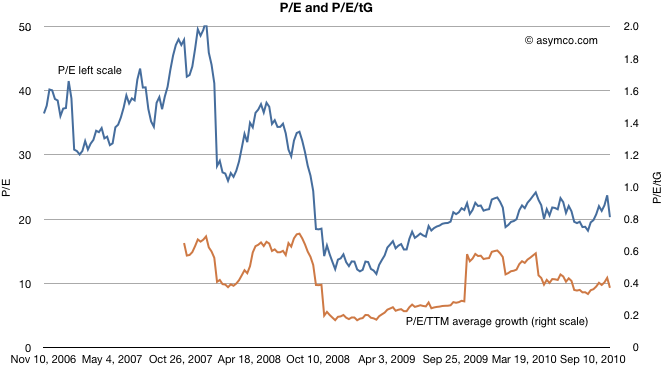
To put a finer point on this, I plot the ratio of P/E and trailing growth (P/E/tG) in the brown line below:
It shows that as a measure of valuation with respect to growth, Apple is trending down. A P/E/tG ratio of 0.4 and closer to 0.2 if we exclude cash shows very weak confidence.
The only conclusion I can draw is that the market does not believe that Apple has significant growth opportunities. A P/E of 20 with consistent 70% growth is, to be blunt, damnation. For comparison, Amazon just reported 16% growth in earnings and was rewarded with a P/E of 68.
Amazon notwithstanding, is Apple an anomaly? Is the disconnect between earnings growth and the stock price unique to Apple or does it apply to most other equities? Is pessimism about Apple a symptom of pessimism in general? I will suggest a way to answer this in a future article.