Asymco

Asymmetric Intelligence

earnings

  1. Apple's Growth Scorecard

    Research · 14 comments

    Every quarter I try to score growth by top, bottom and product lines. As unforeseen growth is the only driver creating shareholder value, it's of paramount importance to measuring a company's performance.
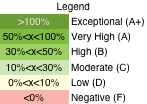
    For Apple, the analysis is fairly straight-forward. There are relatively few product lines (seven including the iPad). I measure y/y sales growth and try to form a picture that is easy on the eyes and mind.

    The method I'm using now is color coding growth for each line according to the legend to the left.

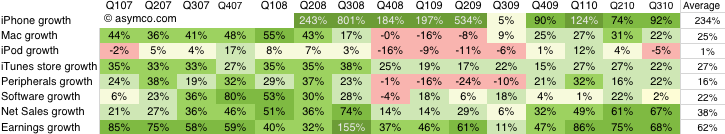
    The table that follows shows each product plus the Net Sales and Earnings lines according to this color coding. I also added an average column for reference.
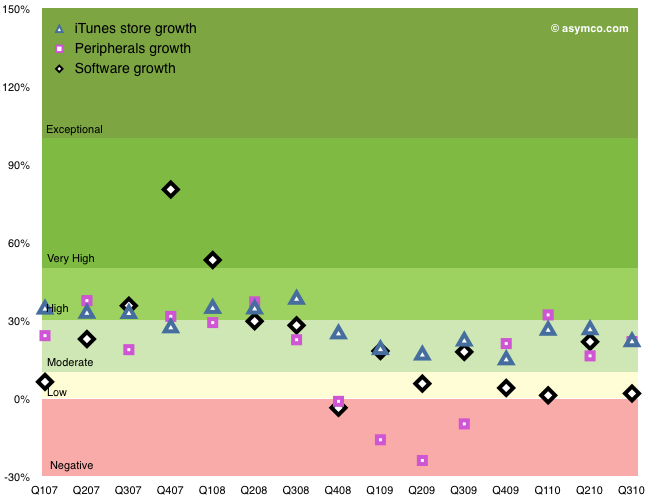
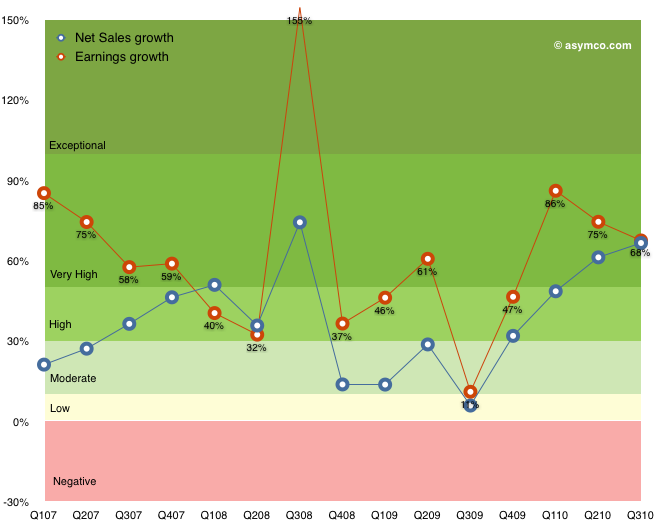
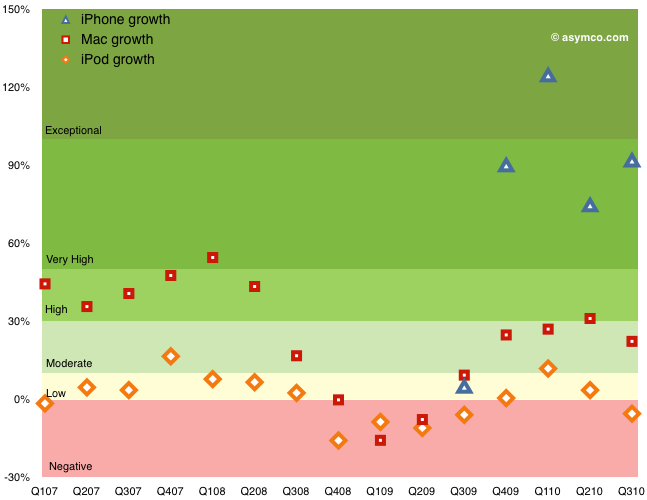
    The following graphs show the same data with color coding for the rates as they change over time. I broke the data into three charts: Top/Bottom lines, Hardware Products, Other Products.
    Discussion

    Hopefully this representation describes the company's growth without requiring too much explanation. Earnings growth, which determines ultimate value created is near all-time highs, well into the "Very High" (A) growth band. Apple have recovered from the Moderate-to-High (B/C) bands during the recession and are near the levels of 2007 when the company was trading at a P/E of 50 (today's P/E for Apple is 20). Sales growth broadly followed earnings growth.

    Within the products, the iPhone again shows exceptional performance. The growth during the first five quarters was (literally) off the scale (above 150%--see table for actuals). The average quarterly y/y growth has been 234%! Last quarter's 92% growth is very near the 100% threshold for exponential growth. This after three years in the market.

    The Mac growth is Moderate (B) and that may be because it was not a launch quarter for portables. The Mac underwent Very High (grade of A) growth for a period of 2008. The iPod shows weakness. The product has been in a Low-to-Negative  (D to F) band of growth since the iPhone launched. Clearly a mature product line but one which has been largely subsumed into the iPhone and iPad. The iPod touch is increasingly a large proportion of the iPod line.

    The non-hardware product lines are Low-to-Moderate growth products. The Peripherals business tracks very closely to the Mac business and dipped negative during the recession.

    Overall, the growth scorecard is in the "Very High" category, or a grade of "A", mostly driven by the iPhone and iPad. Whether this growth will be reflected in the share price is a question reserved for a future discussion.
  2. AT&T does not pay a higher price for iPhone exclusivity

    Research · 6 comments

    In last year's third calendar quarter earnings call (October 20, 2009) Tim Cook was asked:

    “So when you go from exclusive to multiple, you don’t change the charge to the carrier?”

    Cook answered: “Correct.”

    In this year's third calendar quarter earnings call (October 18, 2010) Tim Cook was asked again whether the future iPhone non-exclusive subsidy will affect the iPhone revenues and again Tim Cook repeated that it won't.

    Chris Whitmore - Deutsche Bank

    And what is your experience then when you've gone non-exclusive from a subsidy and margin standpoint on the phone, have you had to give anything up in the past?

    Tim Cook

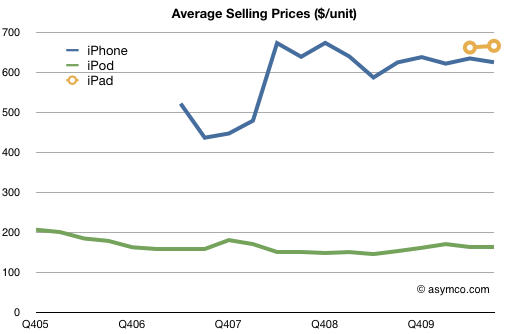
    We don't give specific information out on the margins. But I think you can look at our ASPs and see that they've generally stayed above $600, and that's despite opening up several markets from an exclusive market to a non-exclusive market.

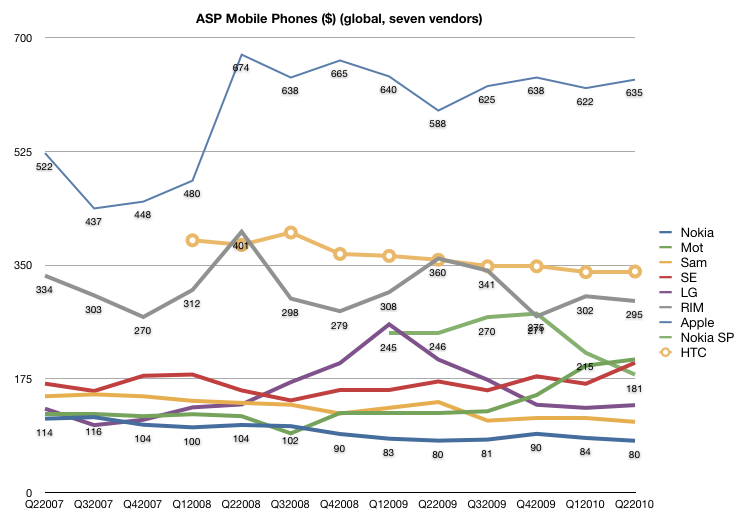
    The recurring assumption that the loss of AT&T exclusivity will cause iPhone price erosion is wrong and has been evident in the sales data for over a year now. Not only did Cook state clearly that there is one price for iPhone to the channel regardless of exclusivity but the price data shows that as Apple moved to non-exclusives in many regions of the world, the ASP remained fairly constant:

    Over the period when the blue line has been flat, Apple moved a number of markets from exclusive to non-exclusive.  There are three main countries where iPhones have a contractual exclusive relationship. That is the United States, Germany and Spain. (China and Japan are exclusive due to network technologies). All these markets will go to non-exclusive next year. I don't expect any change in the ASP as a result.

    The final data point comes from AT&T themselves when they revealed the price they paid for the iPhone was roughly the same as the ASP shown above.

  3. Apple's P/E drops below 20 (again), ex-cash P/E at 16.44

    Research · 7 comments

    Following earnings growth of 68%, after hours trading of AAPL at $300/share shows a P/E of 19.8. The company added over $5 billion in cash for a total of $51 billion or $52.9/share.

    Excluding cash from the price of $300 leads to an enterprise value of $249 and a trailing twelve months earnings of $15.15. The ex-cash P/E is therefore 16.44.

    P/E/trailing Growth is 0.29.

    My guess is that this is keeping AAPL cheaper than the S&P 500 on both P/E and P/E/G.

  4. RIM Quarterly update: just the numbers

    Research · 11 comments

    Noteworthy data (with my notes in parentheses.)

    • 12.1 million phones shipped, 11 million sold through (estimated iPhones for this Q range from 11 to 13 million)
    • Net subscriber account additions were 4.5 million which was lower than anticipated (41% of units sold through were to new subscribers which implies nearly 60% were to existing users)
    • Revenue grew 31% over the same quarter last year and GAAP earnings grew 76%.
    • The BlackBerry subscriber account base grew 56% year-over-year to over 50 million
    • RIM has shipped approximately 115 million handhelds to date. (note: 120 million iOS to date)
    • BlackBerries are available through over 565 carrier and distribution partners in approximately 175 countries and international markets (vs. 150 carriers and 88 countries for the iPhone)
    • Approximately 52% of revenue in the quarter was generated outside the United States and over 45% of BlackBerry subscriber account base is outside of North America. (70% of iPhones were sold outside the US through the first half of this year)
    • Torch was launched with one carrier but will expand to 75 next quarter
    • To date over 35 million BlackBerry Smartphones have downloaded App World at an average of over 1.5 million Apps are being downloaded every day which is up 40% sequentially (iOS apps are running at 17 million downloads per day)
    • Average selling price for RIM devices was $304 (vs. $600 for the iPhone)
    • Gross margin was 44.5% (upward of 50% for the iPhone)

    Research In Motion CEO Discusses F2Q2011 Results - Earnings Call Transcript -- Seeking Alpha

  5. Quarterly Earnings Multiples: The new normal?

    Research · 5 comments

    Based on the new iOS units numbers released I revised at the numbers for next quarter and it's very probable that EPS will be over $5.25.

    As recently as 2007 Apple was priced 50x one year's earnings.

    Now it's priced 47x one quarter's earnings.

    Should we consider applying old yearly earnings multiples to quarterly earnings as the new valuation normal?

  6. HTC: How They Compare

    Research · 17 comments

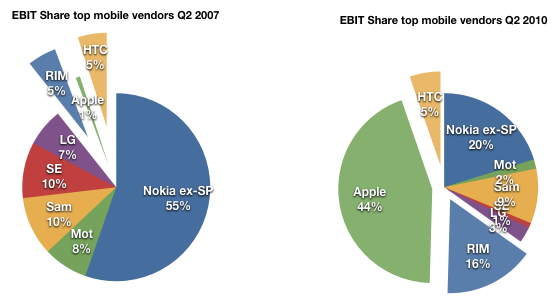
    In the last mobile market update series I wrote of  the evolution of market share, the shift in where dollars are spent, the tale of ASP erosion, profitability ratios over time and EBIT share over time.

    I did not include all vendors for various good reasons. The first survey (market share) did include an "others" category that made the volume data complete, but in the financial data sets, I chose to include the top 7 vendors that make up 80% of device volumes.

    One noteworthy vendor that was not included was HTC. HTC is an important vendor for several reasons:

    • it's a pioneer in smartphones having made the first Windows Mobile devices and the first Android devices
    • at one point it sold 80% of all Windows Mobile devices
    • even if it did not brand its devices, it was the name behind many re-branded or white-label operator branded phones
    • it has a brand of its own today and is expanding its reach

    HTC has been around building devices since 2001 and so it would be a pity to exclude them from any analysis of the effect of iPhone on the market or any discussion on the effect of smartphone disruption on feature phones.

    The challenge with HTC was that historically their branded devices and white label devices were not reported by the company separately. This matters because white label devices are valued differently. Typically these devices are not marketed by the original manufacturer so SG&A is not applied to their cost base. Operating margins, ASPs and hence profitability is not directly comparable with other OEMs.

    But HTC has recently changed its reporting. Thanks to a reader I discovered that, since 2008, HTC has been listing its ASP and Operating Margin making direct comparisons possible. I still don't have all the data, but enough to add HTC to the analysis.

    So, here are the 5 industry performance criteria, now with eight vendors listed.

    Volumes

    Note that HTC volumes start in 2008.

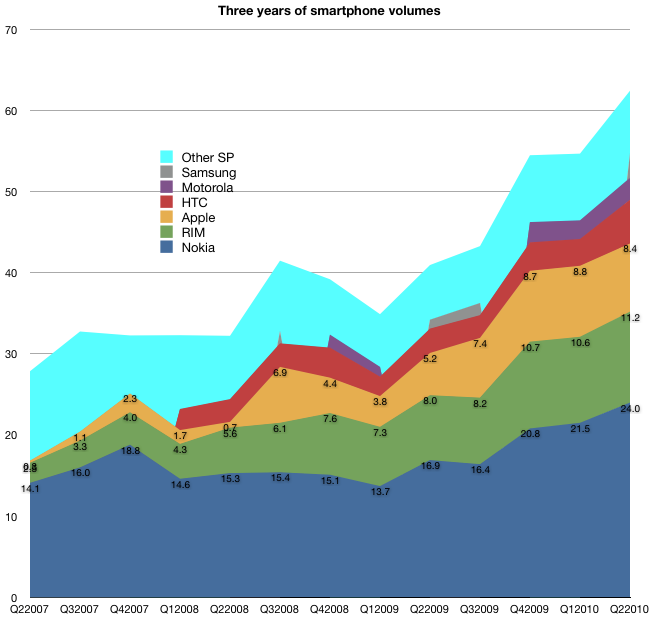
    The volume of units HTC sold has been increasing at about the rate of market growth.

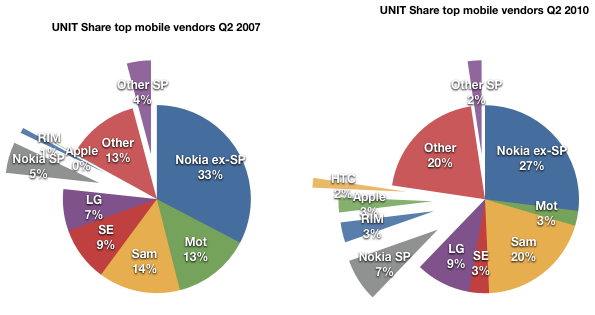
    As a result, HTC's share has not increased as dramatically as those of the other smartphone entrants.

    Sales

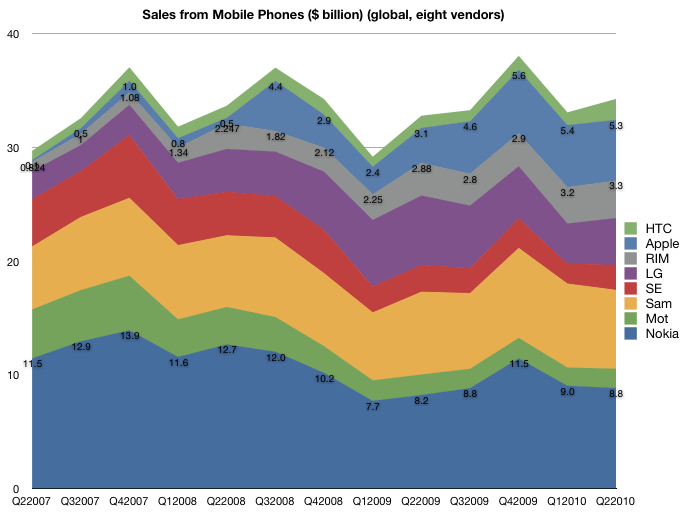
    A similar story in the sales picture. Although a consistent performer, the growth has not matched that of RIM and Apple.

    ASP

    The pricing story is also a mixed one. Although HTC lies between RIM and Apple in price, the erosion is more consistent with RIM and the rest of the industry.

    Margin

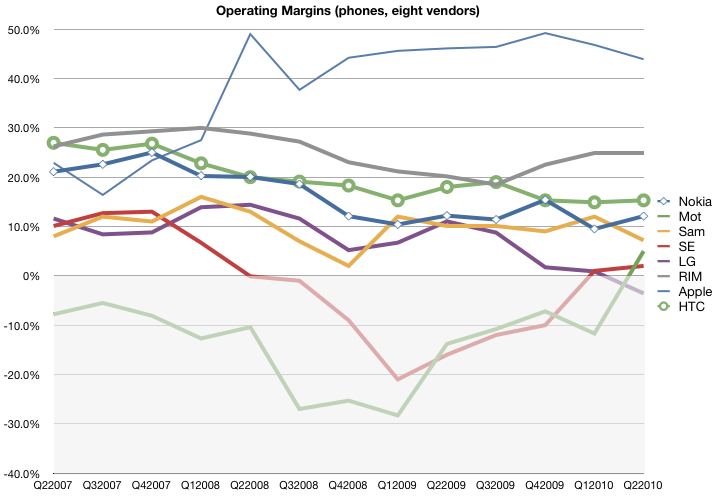
    The margin story is also not as positive as one might expect. The margins for HTC started out above Apple and RIM but have dropped to closer to industry average. This is not what one might expect from an exclusive smartphone vendor.

    Earnings

    The share of earnings has remained unchanged at 5% over the period of iPhone presence. It's perhaps a credit to HTC that they did maintain their position in the market with the massive change that has come to pass.

    However, here we also have to ask if HTC is riding a disruptive wave.

    When I wrote the last series, my definition of “loser” was a company that had faced a long series of operating losses and has no viable software assets of its own, making it vulnerable to Android (and Windows Mobile). Motorola first, Sony Ericsson second and LG now coming into the picture. Nokia is not a loser in this sense since it has remained profitable and does maintain an investment in software. Same with RIM and Samsung (now with Bada). When/if they do have the near death experience, they might opt for the Android lifeline (flimsy as it is).

    However HTC does not fit the mold of either "winner" or "loser". It's the Goldilocks company, not too hot, not too cold.

    But I would add that HTC is not an example of a winner because of its adoption of Android. HTC’s dependence on Windows Mobile made their move to Android the most desperate of all. Unlike the larger OEMs, who had their low end devices to fall back on, they are completely dependent on a smartphone OS vendor. When WinMo was showing the first signs of crisis in 2007, they were the first to flee to Android (think of why they would risk the wrath of Microsoft for something so fragile as Android in 07). They are also trying hard to escape the dependence by building up their own UI (SenseUI) and I would not be surprised if they move to their own OS in the future. Being associated with Android does not confirm them as "winners" but in fact, shows their vulnerability.

    What does this all say about Android?

    Again here my thesis is that Google chose to sustain the industry rather than try to upend it. I don't judge their motives, but the fact is that with Android, Google is not in a position to disrupt telecom. There were high hopes dashed with the Nexus One and hearts broken with net neutrality and now there are patent wars to be fought. Android, with its licensees, is still at the mercy of operators.

  7. Android's Pursuit of the Biggest Losers

    Research · 170 comments

    The mobile phone market is intertwined with the telecommunications industry which is vast and there are numerous competitors which are much more dynamic and better capitalized than the moribund PC or music player vendors. It’s also a regulated and fragmented global market with 1.2 billion units and 5 billion consumers—far greater than any of the markets Apple played in for its first 30 years.

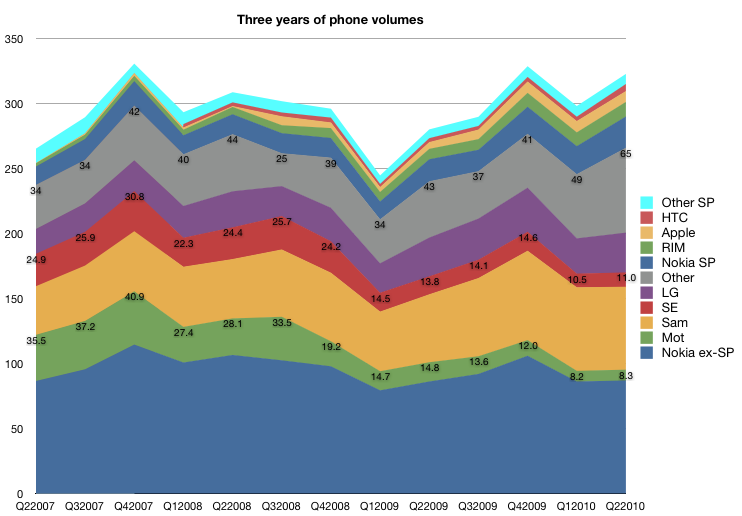
    Nevertheless, the iPhone has had a huge impact on the industry. To show just how much of an impact, I dove in and pulled over 500 data points on three years’ financial performance of seven competitors responsible for 80 percent of units being shipped today. The time frame covers the iPhone’s participation in the market so it allows for “before-and-after” comparisons.

    I divided the findings into five articles:

    1. Unit Volumes. The evolution of market share.
    2. Revenues. The shift in where dollars are spent.
    3. Selling prices. The tale of ASP erosion.
    4. Operating margin. Profitability ratios over time.

    Now I turn my attention to draw a bottom line from all the data above, namely the operating earnings (EBIT or Earnings before Interest and Taxation).

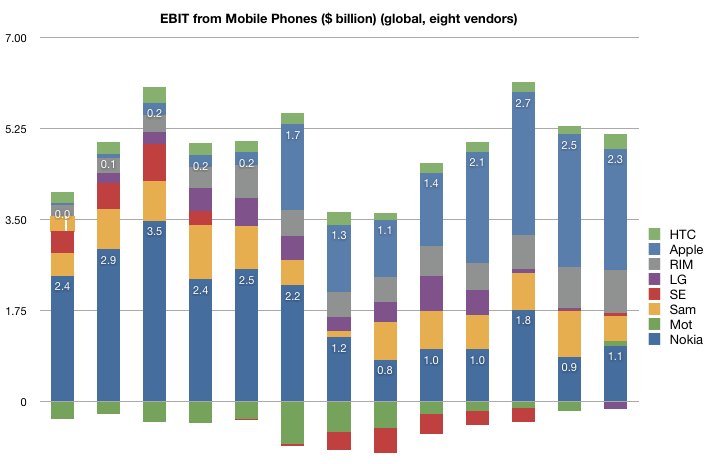
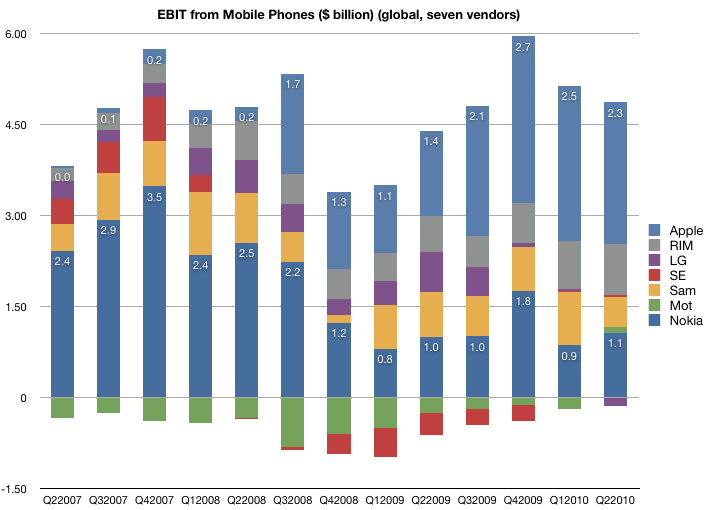
    The first chart shows the EBIT from the top seven vendors of mobile phones since the quarter when the iPhone launched. I annotated Nokia and Apple's bars to give perspective.

    The total available profits in the industry dipped to a bit under $4 billion at the trough of the recession, and have recovered to nearly $6 billion in the holiday quarter last year. However, not all vendors are profitable. As you might expect from looking at the operating margins, Motorola and Sony Ericsson have been generating losses for most of this time period. They have both reached profitability in the last quarter, though at very low levels and after having lost a large part of their sales. LG has turned negative this past quarter after being a modest earner for some time. Samsung has maintained a fairly even consistency in its profit capture, though with its expanding market share, it seems to have come at the cost of pricing.

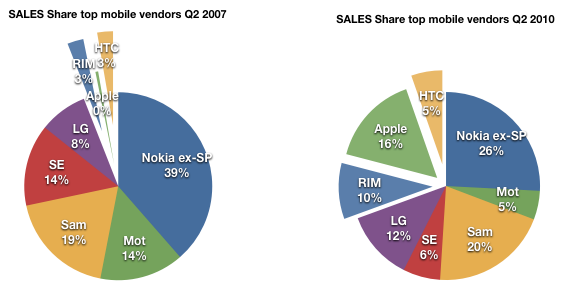
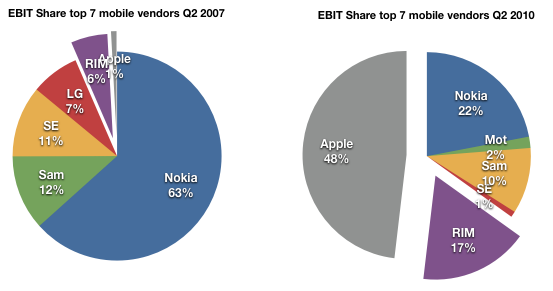
    Finally, looking at the pure smartphone vendors RIM and Apple, the picture is nothing short of astonishing. This before-and-after share-of-available-profit chart shows that the two entrants went from about 7% profit share to 65% in three years.

    Apple in particular is capturing about half of the available profits with three percent of the units. It dwarfs all the other vendors, more than double the nearest (Nokia). All that in three years and with the added burdens of only three models, a recession and limited distribution.

    What does it all mean?

    Here are my conclusions, enumerated:

    1. The lack of a real response. The recurring theme in this series of articles has been that giant multinational incumbents in a vast and rapidly growing industry, enjoying all the advantages that size and incumbency, have had their profits taken from them. And they don't seem to have put up much of a fight.
    2. It's all wealth transfer. Note the total amount of profit available has not increased markedly; this is not about incumbents growing the pie. Two thirds of what should have rightly been theirs moved from the incumbent shareholders to the entrant shareholders.
    3. Speed. This shift of profit occurred over an unprecedentedly short period of time.  Three years is no more than two product cycles in the industry and it's an order of magnitude faster than what happened historically to other industries.
    4. Disruption is the diagnosis here. The incumbents were caught in the headlights. Disruptive innovation leads to asymmetric competition and this is what we just witnessed. History has shown that the shift of profits is usually the last stage of disruption and is usually irreversible because the change in business models cannot happen at the rate of change of profit transfer.

    Which leads me to one final point.

    When analyzing the potential for challengers to the new winners, the most cited is Android. Can Android affect this redistribution of profit once again? And to whom?

    If Android is to become the dominant platform, does it depend on the success of its licensees? Who are these licensees and what are the chances that they will be able to align their businesses to what Android offers (a new revenue model based on services and advertising).

    One problem I see is that Google is making a bet on those same vendors who are now squeezed in the middle of that last pie chart: Samsung, LG, Motorola and Sony Ericsson. Nokia, Apple and RIM will certainly not take the OS over what they already have as it dilutes their differentiation and margins. That means Android is aligned with the biggest losers in the industry.

    So how likely are these disrupted ex-giants to recover and take Android forward? My bet: slim to none. Android does not offer more than a lifeline. It is not a foundation for long-term profitability as it presumes the profits accrue to the network and possibly to Google. Profit evaporation out of devices to Google may be a possibility at some time in the future, but only if the devices don't need too much attention to remain competitive. But because they're still not good enough (and they won't be for years to come), it's certain that attention to detail is what will be most important to stay abreast of Apple.[1]

    So here we have the real challenge to Android:  partnership with defeated incumbents whose ability to build profitable and differentiated products is hamstrung by the licensing model and whose incentives to move up the steep trajectory of necessary improvements are limited.

    In other words, Android's licensees won't have the profits or the motivation to spend on R&D so as to make exceptionally competitive products at a time when being competitive is what matters most.

    [1]: I would argue the same lack of symmetry with licensed software vendor Microsoft is what led the the failure of the same incumbents to make a dent in the industry with Windows Mobile [2003 to 2010].

  8. Apple's Valuation Struggle Continues

    Research · 11 comments

    asymco | Apple's Valuation Struggle.

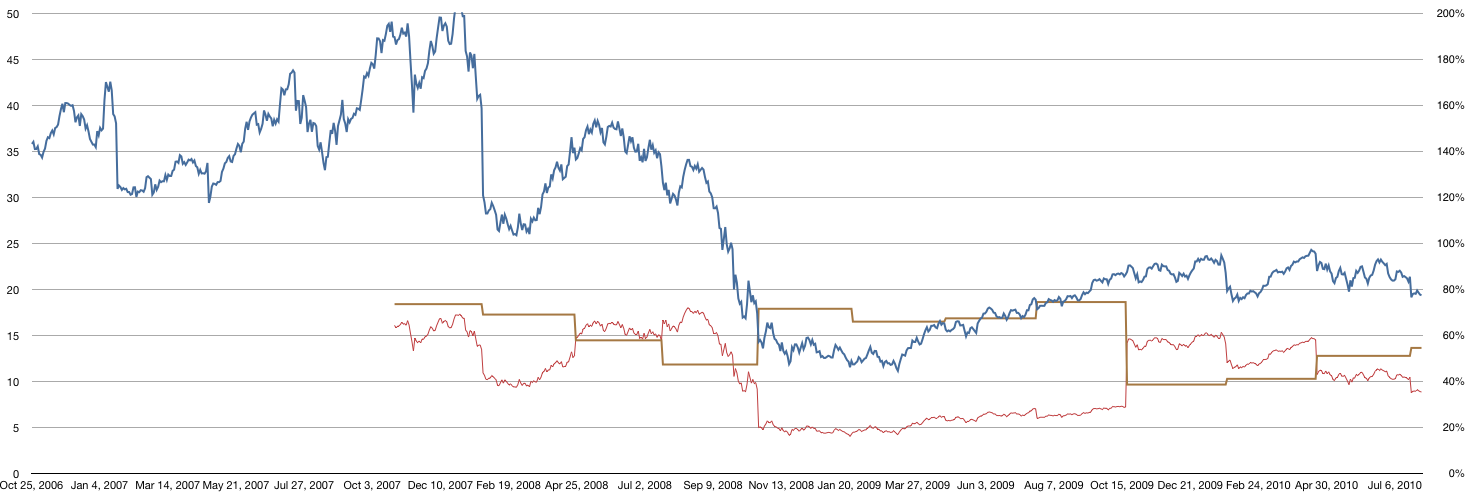
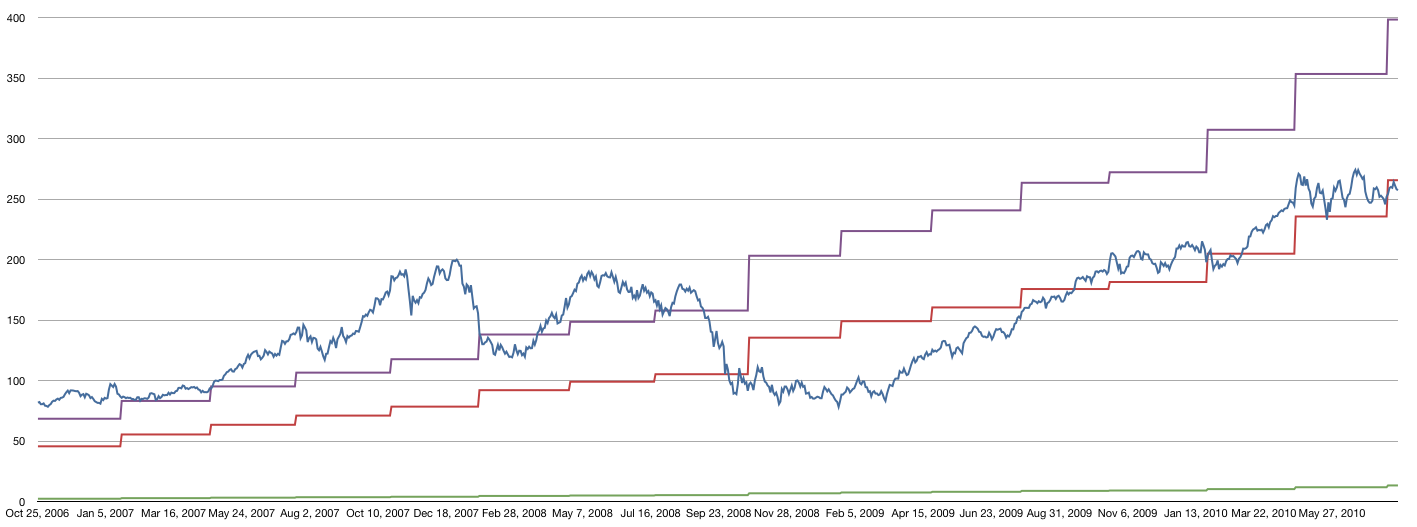
    As despondency over Apple's 75% earnings growth rate continues, it's time to revisit the historic P/E in contrast to growth for the company's earnings.

    The latest chart (below) shows the company's P/E ratio (in blue, left scale) vs. the trailing twelve months rolling growth rate (in brown, right scale) and the ratio between these two (in red, right scale).

    The red line can be considered a form of PEG (Price over Earnings over Growth) with the caveat the the Growth is trailing not forward and hence is based on actual data not fictional analyst "consensus".  I call this PETG (Price over earnings over trailing growth).

    The actuals show that Apple's price to trailing growth ratio is dropping to lows unseen since last year when the recession was still in effect.  At PETG below 20 the predominant sentiment displayed is extreme pessimism. 100 could be considered an even balance between pessimism and optimism. It now stands at 35.

  9. Estimating Fourth Quarter Earnings for Apple

    Research · 4 comments

    We expect revenue to be about $18 billion compared to $12.2 billion in the September quarter last year. We expect gross margins to be about 35%...

    We are targeting EPS of about $3.44.

    via Apple Inc. AAPL Q3 2010 Earnings Call Transcript.

    That $18 billion figure is extraordinary.  Consider that last year during the same quarter, the company received $12.2 billion, then the sales growth forecast is about 50%.  Granted that even though Apple just achieved 61% sales growth last quarter, Apple management is unusually aggressive in underestimating.

    Given this, I am looking at the following forecast:

    • iPhone units: 12.2 million (65% growth)
    • Macs: 4 million (30% growth)
    • iPads: 3.3 million (flat sequentially, production constrained)
    • iPods: 9.4 million (-8% growth)
    • Music growth: 26.7%
    • Peripherals growth: 21%
    • Software growth: 8%
    • Total sales: $19.0 billion (56% y/y growth)
    • GM: 42.3%
    • EPS: $4.78 (73% y/y growth)

    If this estimate proves correct, then at the end of the quarter (Oct 1) the trailing twelve months' earnings per share will be $15.29.  That is equivalent to P/E of 16.82 on the back of four quarters of earnings growth (47%, 86%, 75% and 73% respectively).  The price/earnings excluding cash would be 13.4.

  10. Apple considered less valuable than the average S&P 500 company [Updated]

    Research · 4 comments

    Apple just reached a new all-time closing high.  It's remarkable that so soon after a recession the stock is enjoying new highs.  The Dow would have to gain 40% to make the same claim.

    So some may ask whether Apple's stock is getting ahead of itself.  Perhaps it's showing signs of "irrational exuberance".

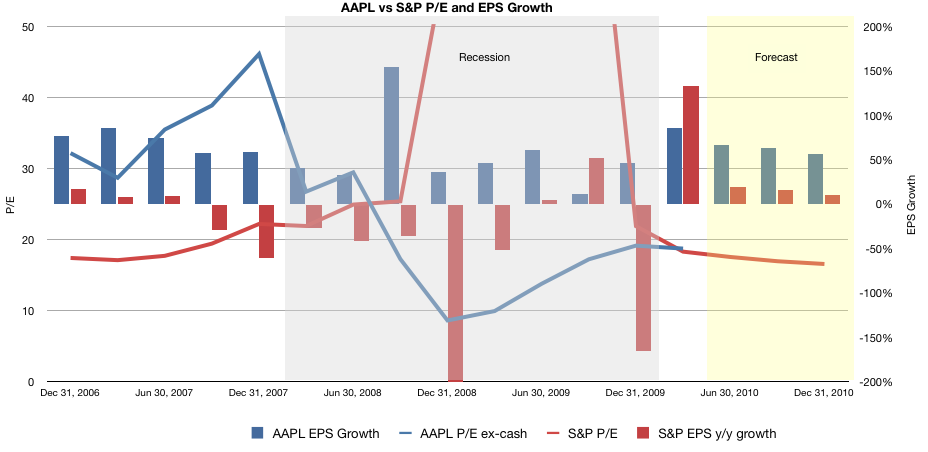
    This is not the case.  In fact, the stock is showing signs of irrational despondency.  This is demonstrated with the following graph.

    It shows AAPL Price (ex-cash) over Earnings vs. S&P P/E  (blue and red lines respectively on the left scale) overlaid with AAPL and S&P EPS growth (blue and red bars respectively on the right scale). I added grey shading to represent the recession period and yellow shading for the forecast period.

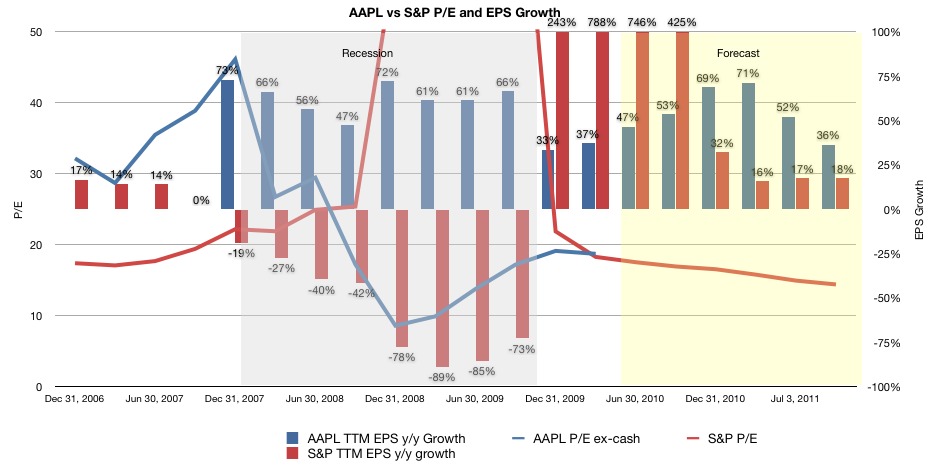
    [Updated] The same data is shown in the following graph where I used a 12 month rolling window (trailing twelve months) for the year-on-year growth to smooth out quarterly anomalies as per suggestion from Deagol in comments.

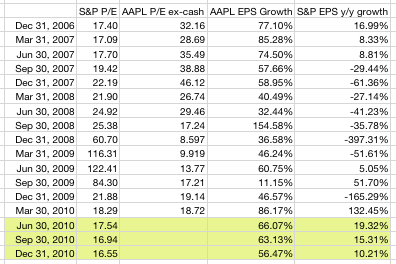
    Note how S&P earnings were indeed in a state of severe decline during the recession, and how the P/E gyrated wildly as a result. (I've had to clip the actual values in the graph for clarity but I include all the data in the table at the bottom of this article).  Post-recession S&P P/E began to return to normal at the beginning of this year and is forecast (by S&P) to align once again with the pre-recession growth in earnings.

    Now compare with what happened to Apple's stock.  Pre-recession the stock enjoyed a significant premium for growth.  The blue bars are significantly higher than the red bars in the 2006/2007 period and the blue line is naturally higher than the red line in the same period.

    During the recession, Apple continues to grow but the P/E drops to remarkably low levels (10).  Although Apple's earnings growth does diminish, it never goes away.  The anomalous growth in the third quarter of 09 is 11% due to the huge spike the year earlier with the launch of iPhone 3G.  Overall, the company continues growing at a good clip.

    Not so for its P/E however.  Even after the recession ended and AAPL accelerated growth to above 50% again, the P/E remained around 20.  I left out the forecast from the AAPL line so that readers can imagine their own.

    The bottom line is that at the new all-time high, Apple's shares are trading at a discount to their growth.  Not only lower than than Apple has enjoyed historically, but lower than the average of 500 of the largest companies in the US.  Those companies having earnings growth in the teens have recovered their valuation.  Apple with growth returning to above 50% hasn't.