JPMorgan has raised its price target on Apple stock to $315 from $305, maintaining its overweight rating, as the bank expresses optimism…
JPMorgan boosts Apple price target to $315 ahead of earnings, citing strong iPhone 17 demand appeared first on MacDailyNews.
NB:
The iPhone 17 demand was evident during the last quarterly update from Apple. Management provided guidance one month into the quarter (and we are now one month into the next quarter) such that y/y growth of at least 13% in iPhone revenues was the only way to match that guidance.
As we approach the earnings release for the first fiscal/fourth calendar quarter for Apple, it's time to look back three months at what the company delivered and guided in the previous quarter.
The summary for results for fourth (fiscal) quarter of FY2025:
Revenue up 8% year-over-year, a new September quarter record.
EPS was up 13% year-over-year.
Product revenue was up 5% year-over-year driven by growth across iPhone and Mac.
iPhone revenue was up 6% year-over-year, and set a September quarter record despite supply constraints faced on several iPhone 16 and iPhone 17 models.
The iPhone active installed base grew to a new all-time high and had a quarterly record for upgraders. Also, Apple reached a new all-time high for installed base of active devices.
Mac revenue was up 13% year-over-year, driven by MacBook Air. Apple grew in every geographic segment, with strong double-digit growth in emerging markets. Mac installed base reached another all-time high, with nearly half of customers who purchased a Mac being new-to the product.
iPad was down 3% revenue and but over half of the customers who purchased iPad this quarter were new-to the product. iPad also had a September quarter record for upgraders.
Wearables, Home & Accessories Revenue for the category was flat y/y. Apple saw a September quarter record for upgraders to Apple Watch, and over half of Apple Watch buyers were new-to the product.Both the Apple Watch and AirPods installed bases reached new all-time highs.
Services again set a new all-time revenue record up 15% year-over-year. Apple saw double-digit growth in both developed and emerging markets. Apple saw a sequential acceleration across the majority of the categories and set new all-time records across Advertising, App Store, Cloud Services, Music, Payment Services, and Video. Apple saw a double digit growth in Apple Pay.
Guidance was provided as follows:
We expect iPhone revenue to grow double digits year-over-year, which would be our best iPhone quarter ever. On Mac, keep in mind, we expect to face a very difficult compare against the M4 MacBook Pro, Mac Mini and iMac launches in the year ago quarter. We expect Services revenue to grow at a year-over-year rate similar to what we reported in the fiscal year 2025.
We expect gross margin to be between 47% and 48%, which includes an estimated impact of $1.4 billion of tariff-related costs. And so for the December quarter, we expect operating expenses to be between $18.1 billion and $18.5 billion. We expect OI&E to be around $150 million, excluding any potential impact from the mark to market of minority investments and our tax rate to be around 17%.
Based on these forecasts my estimates for the top, bottom and middle lines are as follows:
Revenues: $140 Billion (+12%)
EPS: $2.70 (+12.5%)
iPhone: $78.9 Billion (+12%)
Mac: $9.4 Billion (+4%)
iPad: $8.5 Billion (+5%)
Wearables: $12.9 Billion (+10%)
Services: $30 Billion (+14%)
If there is an error in the above I would guess it's in iPhone being too low and the iPad/Mac and Wearables being too high. Nevertheless, I think this will be Apple's biggest quarter ever with significant growth acceleration on the top and bottom lines. [Notable will also be a rapid acceleration in R&D spending (+25%) as suggested by guidance.]
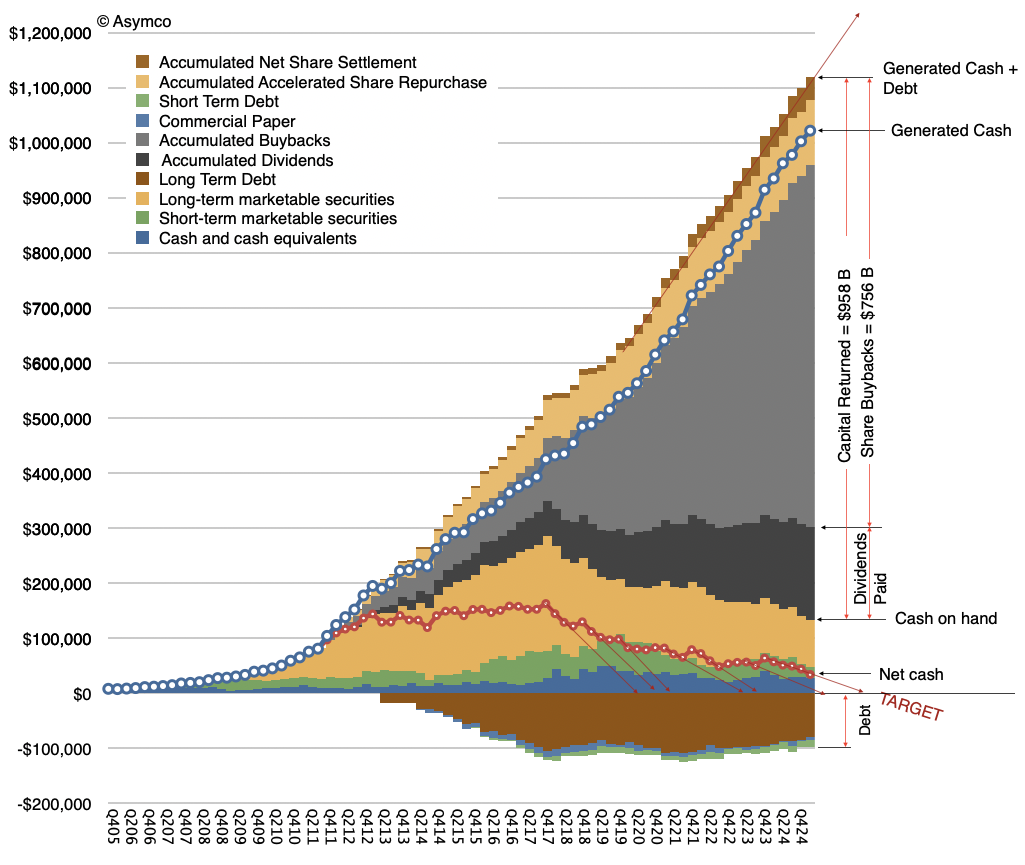
As we head into this blockbuster quarter, Apple shares are trading at a P/E ratio of 32 to 33, a significant drop from above 35 during previous few quarters. During the last three months, the share price has declined about 15% as Mr. Market looked at the money mountain above and decided he wanted none of it.
As we move ahead into the September quarter, I'd like to review our outlook, which includes the types of forward-looking information that Saori referred to at the beginning of the call. We expect our September quarter year-over-year revenue performance to be similar to the June quarter, assuming that the macroeconomic outlook doesn't worsen from what we are projecting today for the current quarter. Foreign exchange will continue to be a headwind, and we expect a negative year-over-year revenue impact of over 2 percentage points.
We expect iPhone and Services year-over-year performance to accelerate from the June quarter. Also, we expect the revenue for both Mac and iPad to decline by double digits year-over-year due to difficult compares, particularly on the Mac. For both products, we experienced supply disruptions from factory shutdowns in the June quarter a year ago and were able to fulfill significant pent-up demand in the year ago September quarter.
We expect gross margin to be between 44% and 45%. We expect OpEx to be between $13.5 billion and $13.7 billion. We expect OI&E to be around negative $250 million, excluding any potential impact from the mark-to-market of minority investments, and our tax rate to be around 16%.
Luca Maestri, CFO Apple Inc., Aug. 03, 2023
In August Apple reported Net sales growth of -1% and EPS growth of 5.4%. My expectation is a 1% sales growth with EPS growth of 11.4%. This might be slightly optimistic but it's based on the following assumptions:
iPhone unit growth of -1.4% (y/y) but revenue growth of 2% (as per guidance, up from -2% previous quarter's growth).
Mac unit and revenue growth of -12% (this might be optimistic, low confidence)
iPad unit growth of -2% but revenue growth of -12%.
Services revenue growth of 12% (acceleration from 8% q/q)
Wearables 2% revenue growth (consistent q/q, down from 10% y/y)
I estimate the gross margin to remain at 44.5%, open to be $13.5 billion (low-end of guidance), OI&E at -$250 million (per guidance) and tax rate at 16%.
The number of shares I estimated at 15.666 billion (down 109 million, below 126 million average drop for last 8 quarters.)
To summarize, for the fiscal fourth quarter 2023:
Total revenue: $91.1 billion
EPS: $1.43
Revenue by segment:
iPhone: $43.5 billion
iPad: $6.2 billion
Mac: $10.0 billion
Services: $21.5 billion
Wearables/Home/Accessories: $9.8 billion
Gross margin on total revenue: 44.5%
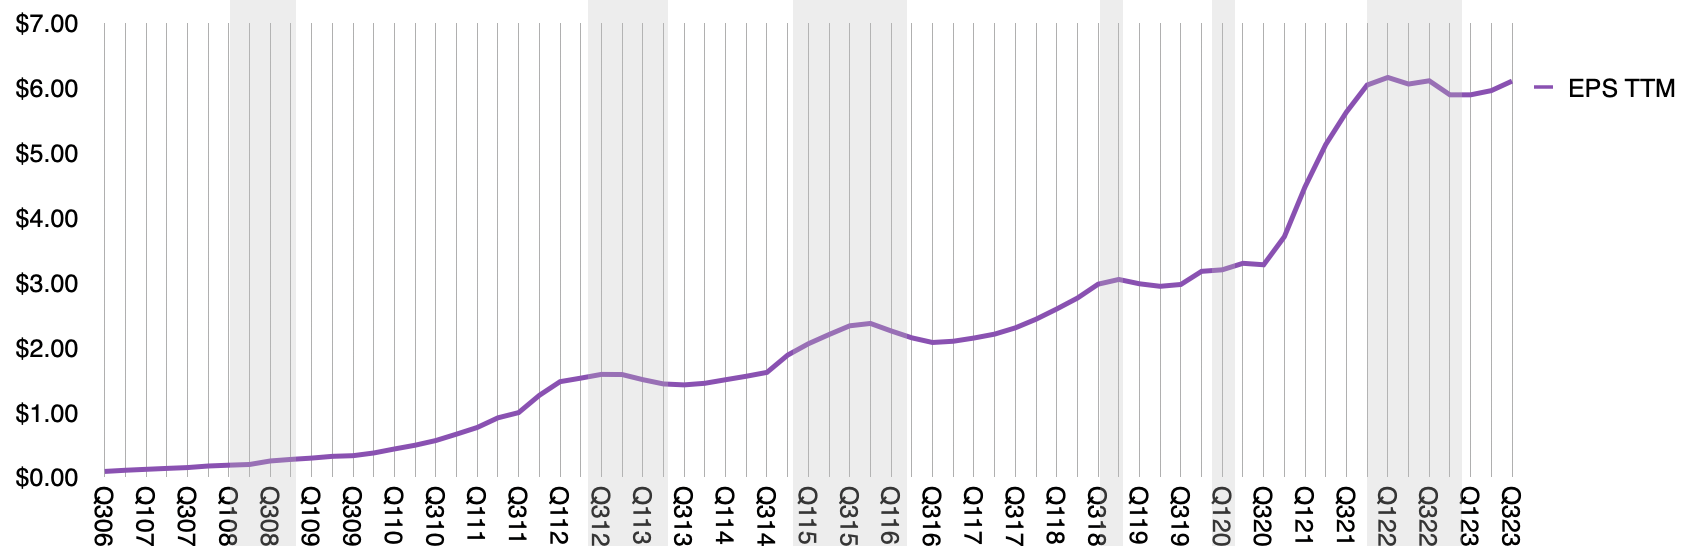
As can be seen in the following graph, my expectation is that the company will return to a pre-Covid growth trajectory (on a TTM EPS basis) after a transient surge and recovery due to the phenomenon of work-from-home and reduced travel. The uncertainty related to Covid is subsiding but macro and geopolitical uncertainties remain and the company continues to provide limited guidance.
As a rule, I don't like to make a forecast for Apple's performance during quarters where there is no guidance. There is a good reason why there is no guidance. The management does not feel confident that there is enough information to make a reasonable prediction. Keep in mind that the management has very detailed, very frequent updates on their business metrics.
Anyone who has run a business knows that signals of performance are abundant and one can only imagine how many signals arrive at Apple HQ from the 1.5 billion active devices, tens of thousands of points of sale, and a vast network of resellers. There are also billions of interactions in services. Then there are search queries, store visitor counts (online and physical), developer payments, app downloads, content downloads, subscriptions. All this information is collected and analyzed on (probably) a daily basis.
Also when guidance is given, it's usually a month into the next quarter. The company will have already seen about a third of the quarter already pass before they predict the next two thirds.
This last quarter in particular was even more difficult given the delays in launching the new iPhones and the dynamics related to the broader portfolio.
And yet, the company feels that they can issue some "insights on our expectations". Here is what was said about three months ago:
These directional comments assume that COVID-related impacts to our business in November and December are similar to what we've seen in October. […] [W]e expect iPhone revenue to grow during the December quarter despite shipping iPhone 12 and 12 Pro 4 weeks into the quarter and iPhone 12 mini and 12 Pro Max 7 weeks into the quarter.
We expect all other products in aggregate to grow double digits, and we also expect services to continue to grow double digits. For gross margin, we expect it to be similar to our most recent quarters despite the costs associated with the launch of several new products. For opex, we expect to be between $10.7 billion and $10.8 billion. We expect OI&E to be around $50 million and the tax rate to be around 16%.
Luca Maestri, Chief Financial Officer
So, given this information and some hints from IDC, Gartner and CIRP and China I'm willing to offer some estimates:
iPhone Revenue: $63.9 billion
Mac Revenue: $9.3 billion
iPad: $7.4 billion
Services: $15.1 billion
Wearables & Home: $12 billion
Net sales: $107.8 billion
Gross margin percent: 37.7%
EPS: $1.48 (Growth: 19%)
Of course, this is very speculative and I don't have a lot of confidence in it. If anything it may be on the high side.
I don't expect there to be guidance for the next quarter with a resumption of guidance only after the pandemic has largely subsided (probably Q3 of this year.)
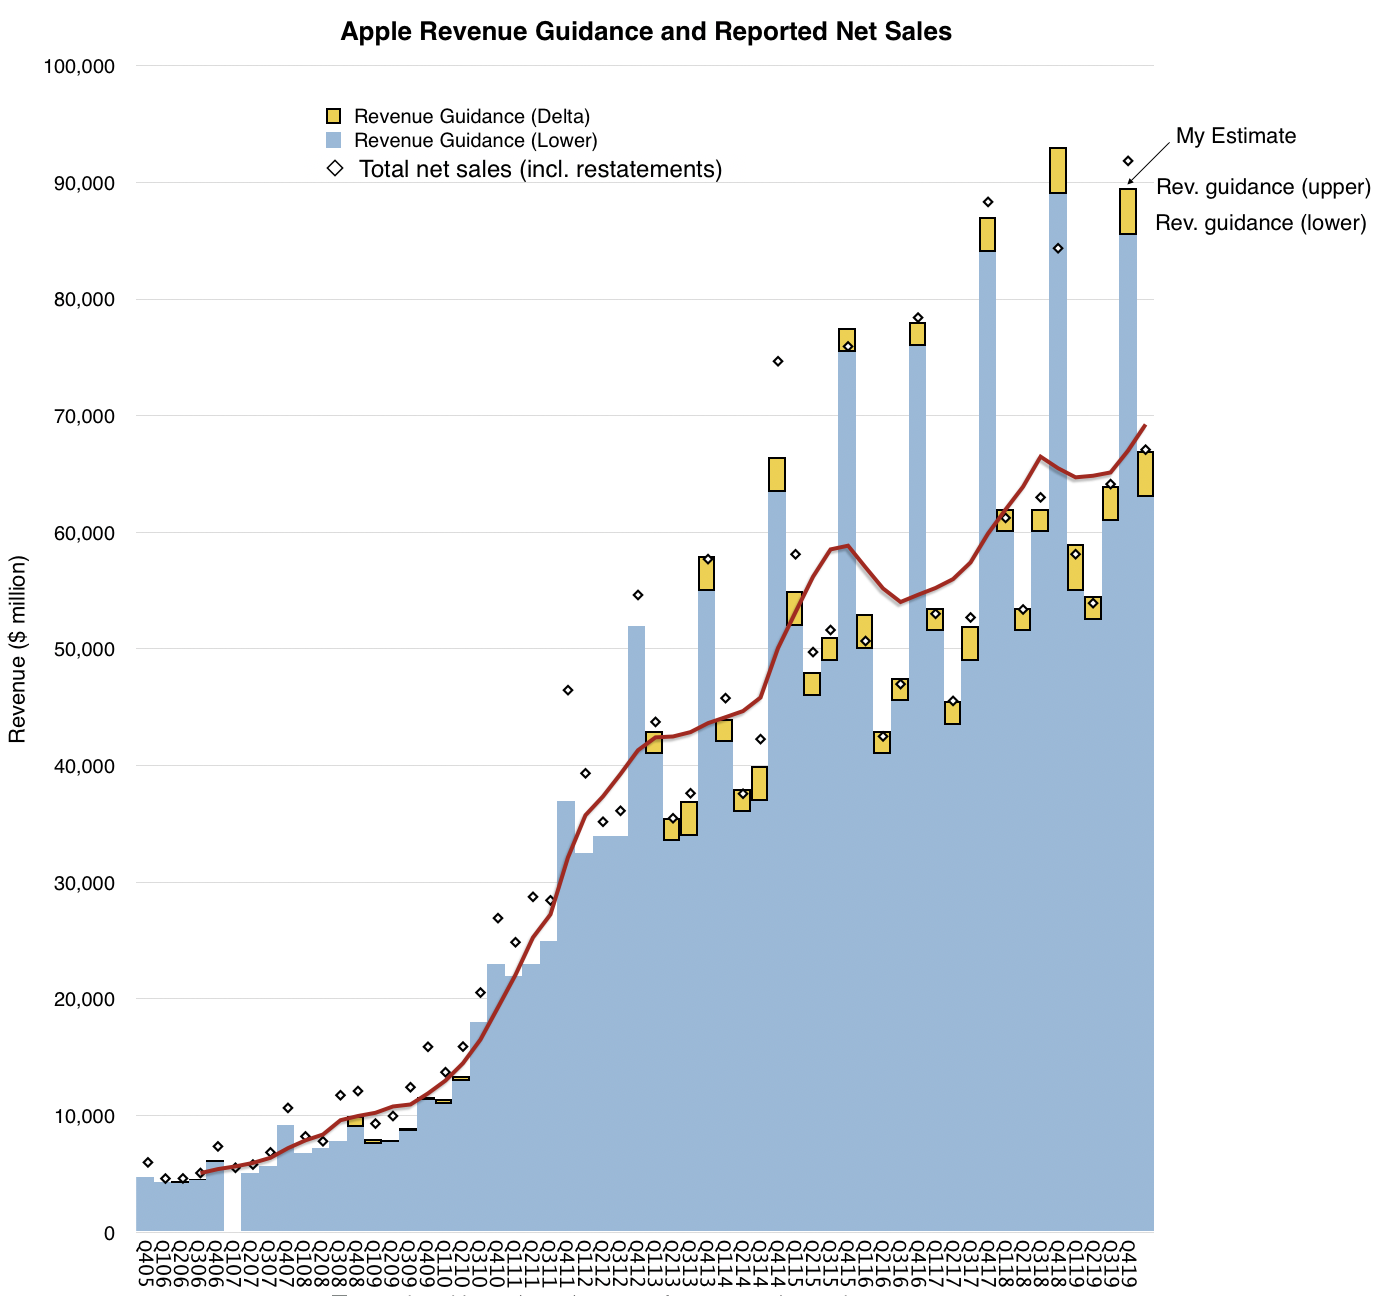
Exactly one month ago Apple reported their highest quarterly revenue ever. They also guided to growth of between 8.6% and 15.5% into the current (1st calendar) quarter. This guidance is illustrated as the right-most bar in the following graph:
Note that the growth is relative to the year-ago quarter. The quarter was almost a third over by the time the issuance of guidance but less than three weeks later the company withdrew their guidance. The company did not issue new guidance.
The reasons given were both a restricted supply and a disruption in demand due to the COVID-19 viral outbreak. That outbreak paralyzed China and in the 10 days since has come to threaten the world.
Apple was the first company to warn about the impact of the virus on its business but not the last. The market reaction was muted. Mysteriously, the market seems to be reacting to the outbreak at this later time even though the dynamics of the epidemic were foreseeable.
The question of impact on the business is still open but I'd like to reflect a bit on the impact of any number of possible disasters or "acts of God" on any business.
The greatest catastrophes in history were wars and pandemics. In the 20th century in particular there were two world wars and one large pandemic in 1918. Add to that a depression and you would think that century was cursed.
And yet, these crises merely delayed technologies. They did not eliminate them or the companies which introduced them. For example, the introduction of Television was delayed by WWII and the adoption of the automobile was paused. At the same time new innovations were introduced including plastics, radar and microwaves and jumps in manufacturing productivity. The 1918 flu was followed by the roaring 20's and WWII by the post-war boom years. The 20th century came to be celebrated as the most innovative time in history, a time when standards of living and prosperity exploded.
It's not prudent to ignore a pandemic but it's not prudent to contemplate an apocalypse will follow. Demand deferred is not demand destroyed. Civilization is fundamentally able to absorb these shocks and it's useful to look to history to see exactly how we managed to do so.
Three months ago Apple provided the following guidance:
As we move ahead into the June quarter,[…] We expect revenue to be between $51.5 billion and $53.5 billion. We expect gross margin to be between 38% and 38.5%. We expect OpEx to be between $7.7 billion and $7.8 billion. We expect OI&E to be about $400 million. And we expect our tax rate to be about 14.5%.
If we aim for a revenue figure close to the upper end of the range ($53.2 billion) and insert all the other figures (split the difference for OpEx) then then the company's fiscal third quarter looks as follows:
Revenues: $53.2b iPhone (units): 43.2 million iPad (units): 11.6 million Mac (units): 4.3 million Services ($): 9.5 billion Other products ($): 3.5 billion Gross margin (%): 38.6%
EPS ($): $2.26
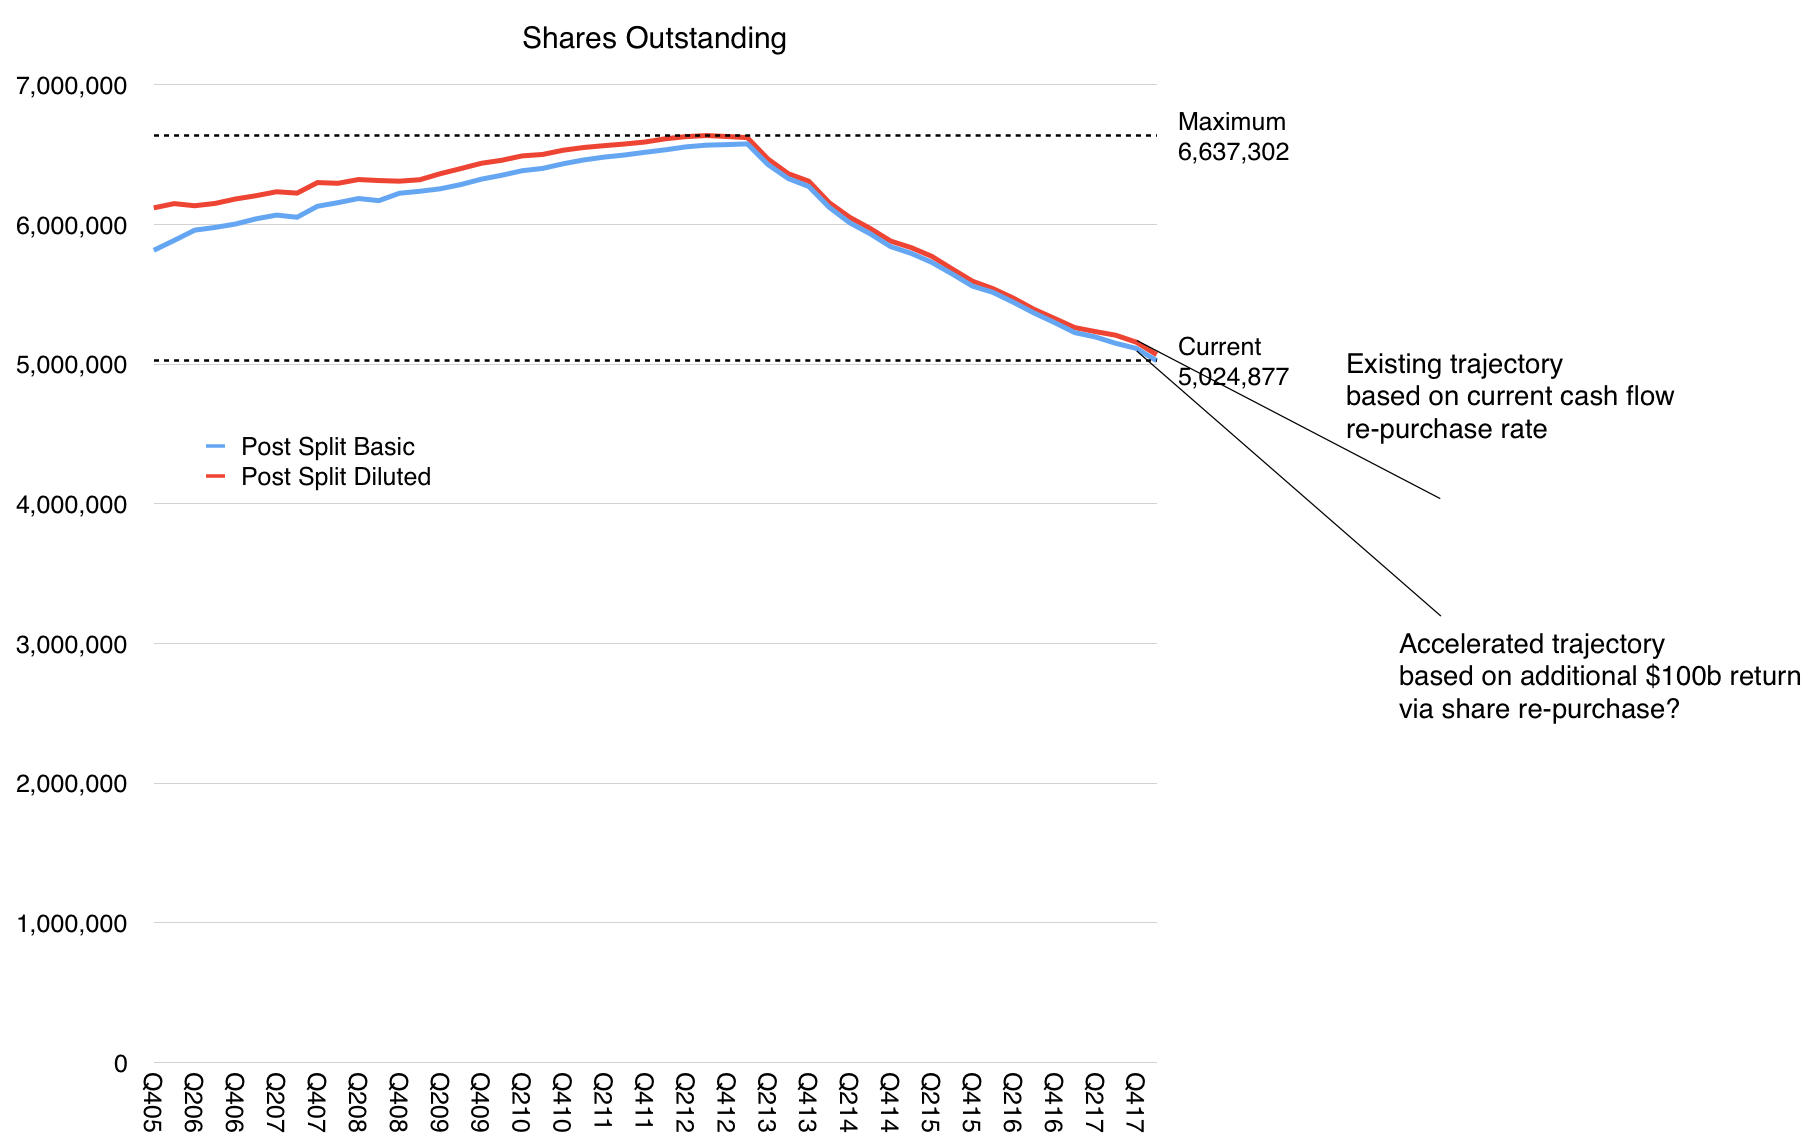
This last figure, the earnings per share, is the most speculative because it depends on another guidance that Apple gave: a new $100 billion share repurchase authorization and the fact that it has no time frame. For context, as of end of March the company had completed over $275 billion of its previous $300 billion capital return program and $10 billion remained for share re-purchases in the June quarter. It's unclear how much of the new authorization will be spent in the quarter.
That spending could indicate the share count but there are issues with this calculation as well. The $2.26 EPS I forecast is based on the assumption that the the same number of shares will be retired as in the previous quarter (about 89 million shares.) However the company spent $23.5 billion on repurchases of 137 million Apple shares through open market transactions (for an average price or $171.53, in-line with the quarter's trading average).
So why is the number of shares purchased (137 million) so different from the change in shares used to compute earnings per share (89 million)? I actually don't know.
The question of how many shares are available to calculating EPS is perhaps the last mystery in what is otherwise a very predictable business. The revenue growth and implied iPhone growth are pretty transparent. Incidentally, the EPS I'm forecasting is equivalent to growth of 35.8% y/y. The share price is trading at multiples about half of this growth rate so it's no wonder the company is spending most of the cash on re-purchases.
How quickly the $100 billion re-purchasing authorization will be used is another question. The effect in concentration of value per share could be profound as shown in the graph above which will have further implications on the "cash zero" direction for the company.
The following is a transcript of the comments from Tim Cook (CEO) and Luca Maestri (CFO) at Apple's Q1 2018 Earnings Conference Call February 1, 2018. I color coded my interpretation of the comments into four categories:
Grey: Background and promotional commentary
Red: Strategy and signals of what management considers important and may include data beyond the regularly reported numbers.
Green: Financial data
Black: Commentary.
Blue: My commentary, in brackets.
For a quick read of Apple's strategy, read the Red text. These comments are not repeated in financial reports. Highly recommended.
For a quick read of Apple's financial performance, read the green text (which are replicated in financial reports). Read this if you don't want to wade through the financial reports.
For marketing or product material, read the grey text.This is sometimes unique but also repeats product launch information.
---- Tim Cook: Thanks, Nancy and thanks everyone on the call, and welcome to everyone today. Before we dive into the quarter, I'd like to take a moment to talk about a significant milestone we recently crossed.
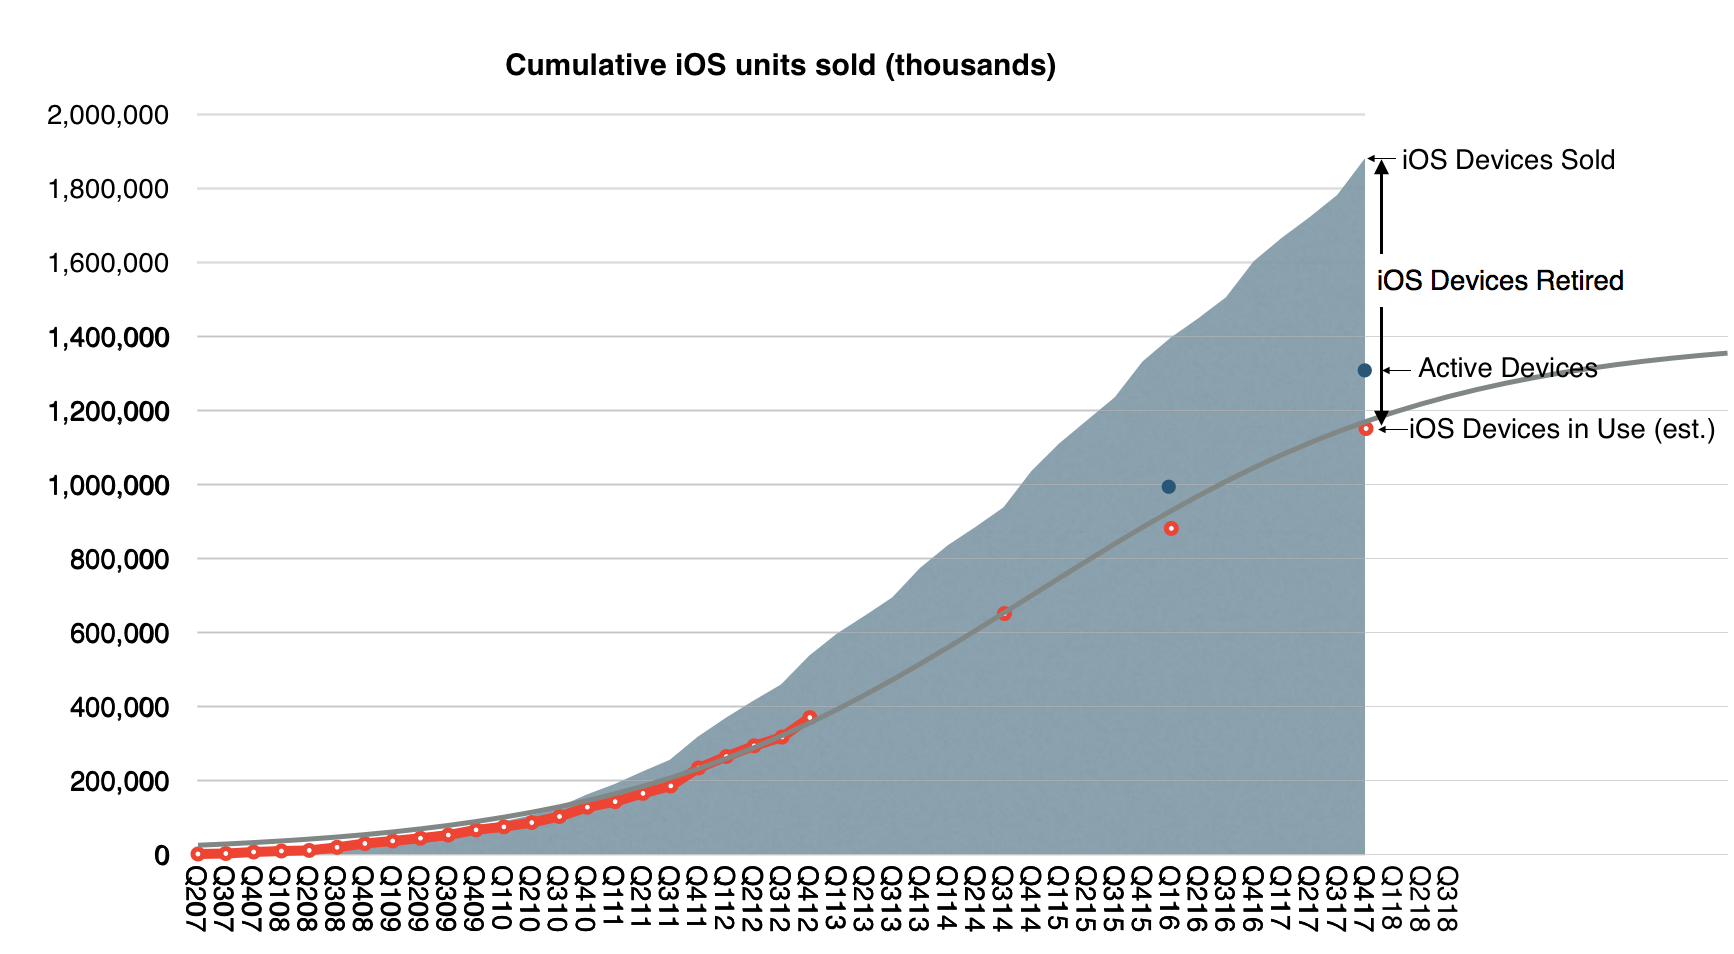
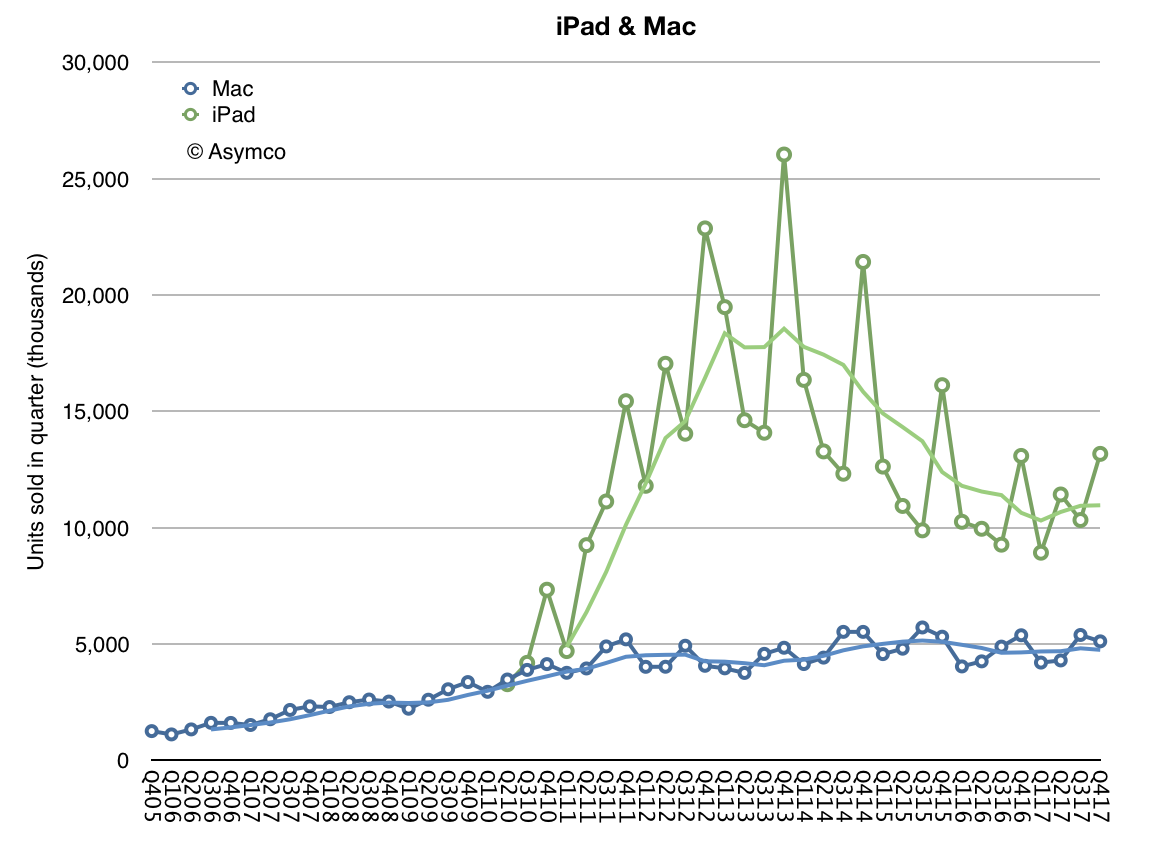
Apple's active installed base reached 1.3 billion devices in January and is at an all-time high for all of our major products. 1.3 billion devices represents an astonishing 30% growth in just two years. It speaks to the strength and reliability of our products and our ecosystem, as well as the loyalty, satisfaction and engagement of our customers. It's also fueling tremendous growth in our services business, which I’ll talk about a little later in the call. [This is probably Apple's most important number. For at least the next 20 years this is the key performance metric and it can be used to derive company's valuation. A summary of the history of active devices vs. units sold is shown in the graph below:]
Turning to the December quarter. We're thrilled to report Apple's biggest quarter ever, which set new all-time records in both revenue and earnings. We generated revenue of $88.3 billion, which is above the high-end of our guidance range, and it is up almost $10 billion or 13% over the previous all-time record we set a year ago.
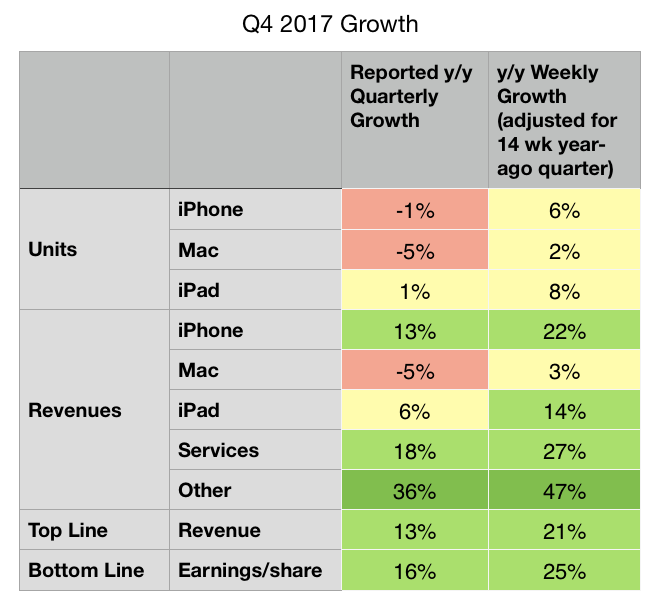
It's also our fifth consecutive quarter of accelerating revenue growth with double digit growth in each of our geographic segments around the world. What makes us even more remarkable is that the quarter we're reporting today was 13-weeks long, while the year ago quarter was 14-weeks. When we look at the average revenue per week in the December quarter this year compared to last year, our growth was a stunning 21%. [The 13-week vs. 14-week year-on-year comparison is repeated several times. The summary differences are shown in the table below:]
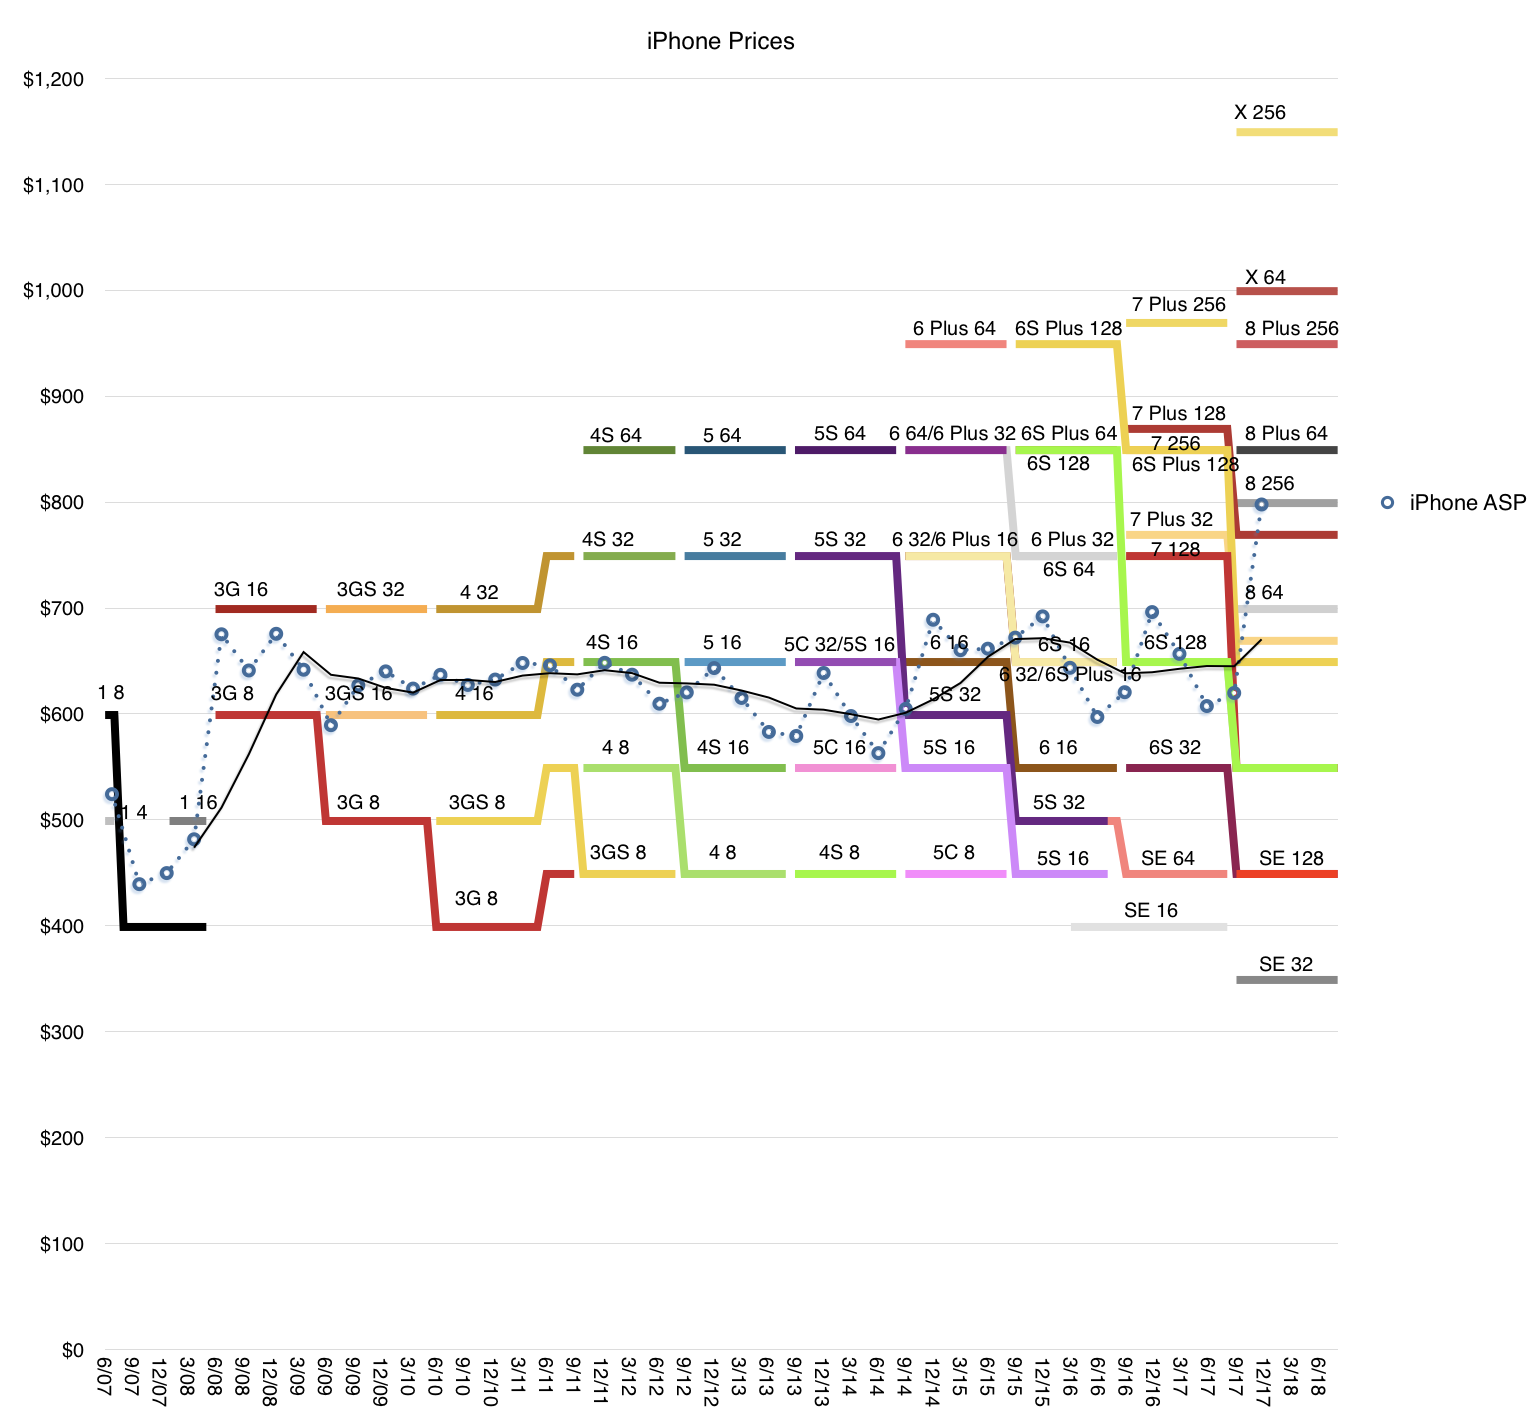
Our growth was broad-based and a key driver was iPhone, which generated its highest revenue ever. iPhone X was the best-selling smartphone in the world in the December quarter according to Canalys, and it has been our top selling phone every week since it launched. iPhone 8 and iPhone 8 Plus rounded out the top three iPhones in the quarter. In fact, revenue for our newly launched iPhones was the highest of any lineup in our history, driving total Apple revenue above our guidance range. [The iPhone X is a huge hit. It drove the average selling price $100 higher y/y. This is not only unprecedented for Apple but for the entire Industry. The average smartphone sells for less than $300 while iPhones sold for $800. The gap is widening. The following graph shows the product mix and the average resulting price.]
I want to take a moment to recognize the tremendous amount of work that went into creating iPhone 10. Our teams carried out an extremely complex launch from both an engineering and operations perspective, executing an outstanding product ramp that required years of research and development; one that introduced innovative features like an edge-to-edge Super Retina Display and the TrueDepth Camera, which enables face ID. Our customers love these new features and the new gestures like simply swiping up from the bottom, which make using iPhone even more intuitive and enjoyable.
Our team has put the technology of tomorrow in our customers’ hands today, set a standard for the next decade of smartphones and we are very proud of their achievements.
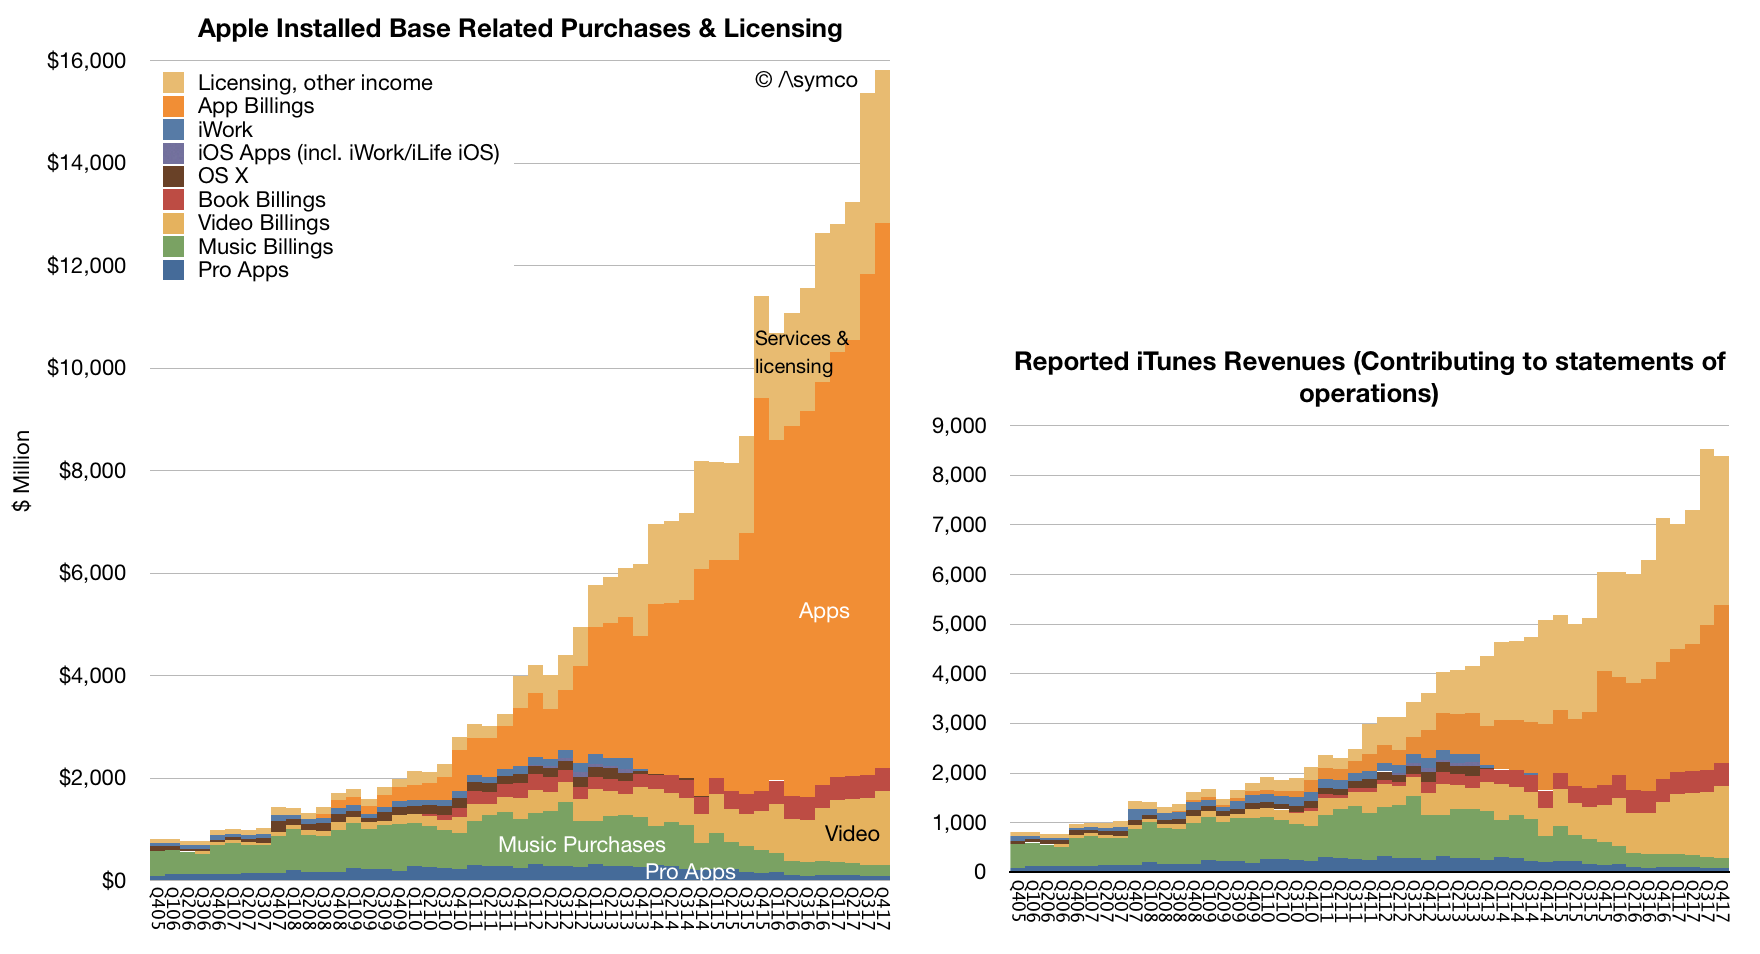
It was another very strong quarter for services with revenue of $8.5 billion, up 18% over last year, and we’re on pace to achieve our goal of doubling our 2016 services revenue by 2020. The number of paid subscriptions across our services offerings passed 240 million by the end of the December quarter, that’s an increase of 30 million in the last 90 days alone, which is the largest quarterly growth ever. [Services has been growing relentlessly for over a decade. This steadiness of growth makes is a juggernaut. Apple is increasingly speaking about subscriptions as the key metric and 240 million is reaching record territory. The rise of Services is shown below (both revenues and consumer spending.)]
We had an all-time record quarter for the App Store with our best holiday season ever. We’re seeing great excitement around augmented reality with customers now enjoying over 2,000 ARKit enabled app, spanning every category in the App Store. In December, when Pokémon GO released its new augmented reality features built with ARKit, it jumped the top of the App Store charts. Last week, on a stop in Toronto, I met developers who are hard at work on creative applications using ARKit from art appreciation to ecommerce, and I was very impressed with what I saw.
Just for months after ARKit launched to the public, we’ve already released ARKit 1.5 in beta to developers around the world, and the response has been tremendous. Augmented reality is going to revolutionize many of the experiences we have with mobile devices. And with ARKit, we’re giving developers the most advanced tools on the market to create apps for the most advanced operating system running on the most advanced hardware. This is something only Apple can do.
In addition to the App Store, several other services had their biggest quarter ever, including Apple Music, iCloud and Apple Pay, all of which saw growth in both active users and revenue.
Apple Pay has reached an important milestone in the U.S. As a result of 50% year-over-year growth in merchant adoption, it’s now accepted at more than half of all American retail locations, which includes more than two-thirds of the country’s top 100 retailers. Now available in 20 markets, global Apple Pay purchase volume more than tripled year-over-year and we’re delighted to be expanding to Brazil in the coming months. [There are no absolute data points on Apple Pay but we do have some scattered growth data. The US data is cited here but in my experience it's more popular in select countries like UK where users are using it habitually]
Today, you can use Apple Pay to take the subway in Guangzhou, China, see a concert at London’s Wembley Stadium or buy a souvenir in Yosemite National Park. In the U.S., we launched Apple Pay Cash in December, and it’s off to a terrific start. Millions of people are already using it to send and receive money with friends and family quickly, easily and securely; to split a bill, pay someone back, or send last minute gift right from the messages app.
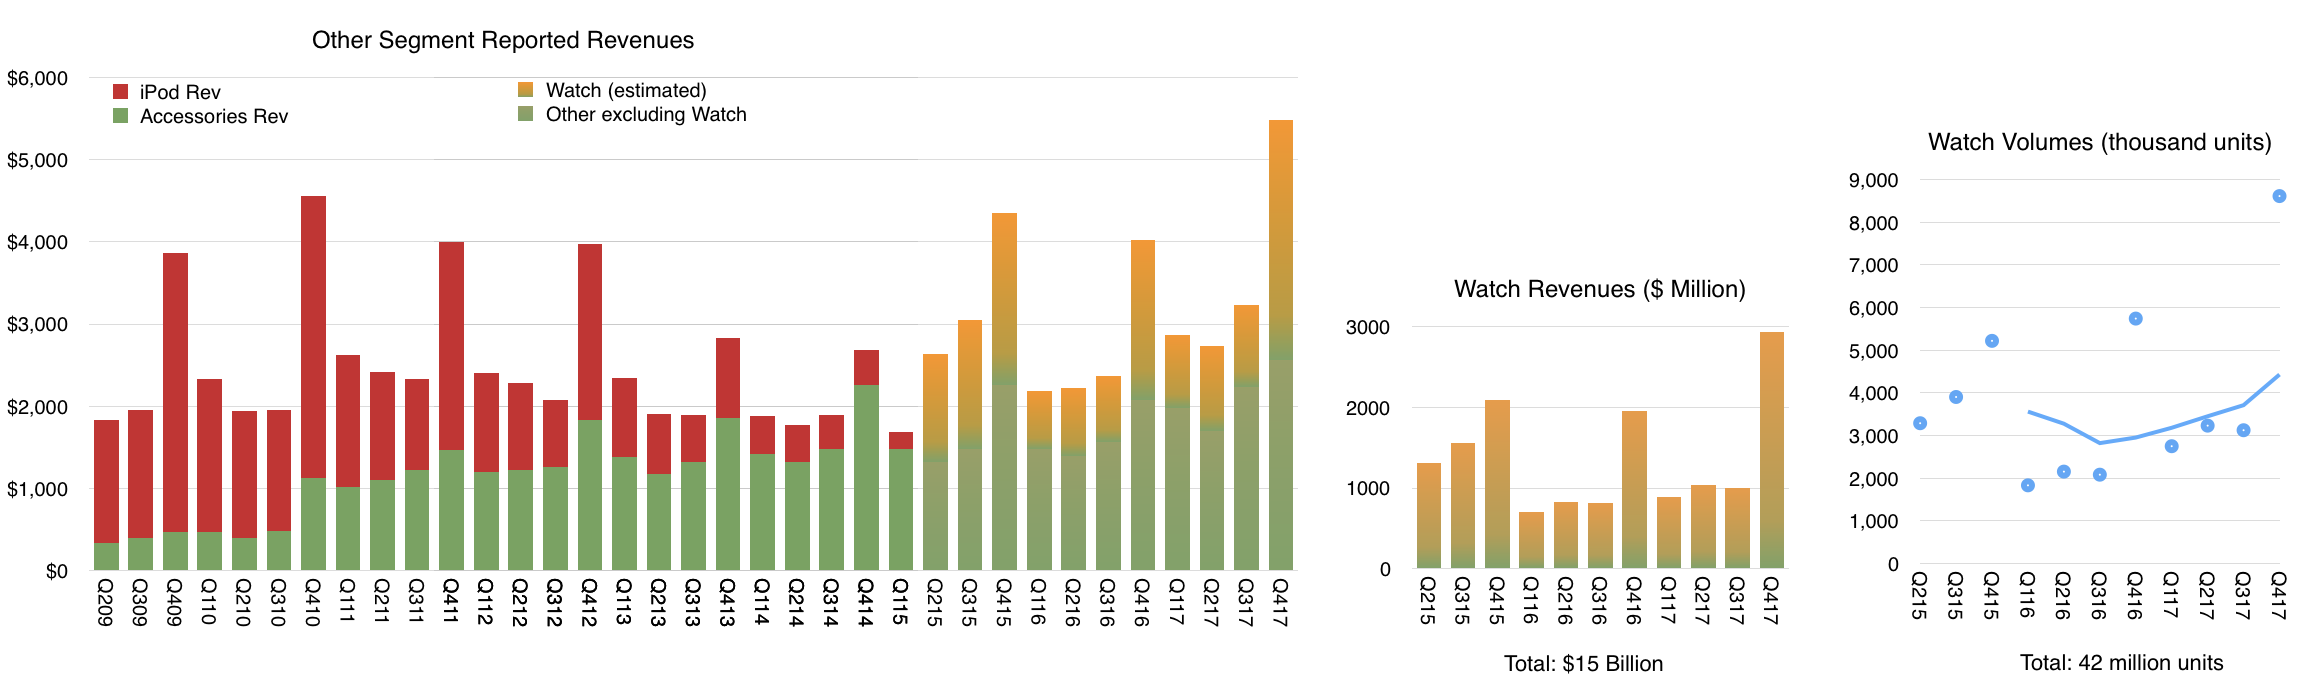
It was our best quarter ever for the Apple Watch with over 50% growth in revenue and units for the fourth quarter in a row and strong double-digit growth in every geographic segment. Sales of Apple Watch Series 3 models were also more than twice the volume of Series 2 a year ago. Apple Watch is the most popular, smart watch in the world and gained market share during the quarter based on the latest estimates from IDC. [Apple Watch is growing consistently. The following graph shows my estimates of volume (total 42 million to date) and revenues (total $15 billion) based on all available data and commentary from management.]
It was the third consecutive quarter of growth for iPad revenue, thanks to the strength of both iPad and iPad Pro. Based on the latest data from IDC, we gained share in nearly every market we track with strong outperformance in emerging markets.
Worldwide, almost half of our iPad sales were the first-time tablet buyers are those switching to Apple, and that’s true in some of our most developed markets, including Japan and France. In China, new and switching users made up over 70% of all iPad sales.
For Mac, we launched the all new, iMac Pro in mid-December. It’s an entirely new product line designed for our Pro users who love the all-in-one design of iMac and require workstation class performance. It's the fastest, most powerful Mac ever, delivering incredible computational power, for simulation and real time 3D rendering, immersive VR and complex photography audio and video projects. Worldwide, 60% of our Mac sales were the first time buyers and switchers and in China, that number was almost 90%.
We're looking forward to getting HomePod in customers’ hands beginning next week. HomePod is an innovative wireless speaker, which delivers stunning audio quality wherever its placed in the home, thanks to the advanced Apple engineered hardware and software.
Together with Apple Music, HomePod gives you instant access to one of the world's largest music catalogs. And with the intelligence of Siri, it’s a powerful assistant you control through natural voice interaction. We're very happy with the initial response from reviewers who've experienced HomePod ahead of its launch, and we think our customers are going to love this new product.
We believe one of the key issues of the 21st century is education. And because of that, we've strengthened our commitment and investment into initiatives like everyone can code. To find the innovators of the future, we need to nurture the students of today. Our App Development with Swift curriculum, which is available free on iBooks, has been downloaded more than 1.2 million times worldwide with almost half of those coming from here in the United States. It’s also being taught in dozens of community colleges across the country, putting practical skills in the hands of today’s jobs seekers.
I was in London two weeks ago as we announced that the program was expanding to more than 70 colleges and universities in Europe. Millions of students around the world will have the opportunity to add Swift to their coding vocabulary and gain skills that are essential for today’s economy.
This is an exciting time at Apple and with the best lineup of products and services we've ever had and a set of initiatives that show how business can be a force for good in the world. We could not be more excited about our future.
Now, for more details on the December quarter results, I'd like to turn over the call to Luca.
Luca Maestri: Thank you, Tim. Good afternoon, everyone. Our business and financial performance in the December quarter were exceptional, as we set new all-time records for revenue, operating income, net income and earnings per share.
Starting with revenue, we’re reporting an all-time record, $88.3 billion, up nearly $10 billion or 13% over the prior record set last year. It is our fifth consecutive quarter of accelerating revenue growth. As you know, the December quarter a year ago spanned 14-weeks compared to 13-weeks this year, which is important to consider as we have set the underlying performance of our business this year. When we look at average revenue per week, our growth rate was even higher at 21% with growth across all product categories for the third consecutive quarter.
Our results were terrific all around the world with double digit revenue growth in all our geographic segments, an all-time quarterly record in the vast majority of markets we track, including the U.S., Western Europe, Japan, Canada, Australia and Korea, as well as Mainland China, Latin America, The Middle East, Central and Eastern Europe, and India.
In Greater China, we were very happy to generate double digit revenue growth for the second quarter in a row and in emerging markets outside of Greater China, we saw 25% year-over-year growth.
Gross margin was 38.4% at the high end of our guidance range. Operating margin was 29.8% of revenue. Our net income was $20.1 billion an all-time record, and up $2.2 billion over the last year. Diluted earnings per share were $3.89 also an all-time record and cash flow from operations was very strong at $28.3 billion.
During the quarter, we sold 77.3 million iPhones, the highest number ever for a 13-week quarter. Average weekly iPhone sales were up 6% compared to December quarter last year with growth in every region of the world despite the staggered launch of iPhone 10. We established all-time iPhone revenue record in nearly every market we track with double-digit growth in all of our geographic segments. iPhone ASP increased to $796 from $695 a year ago, driven primarily by the launch of iPhone 10 and the success of iPhone 8 and 8 Plus.
We exited the December quarter towards the lower end of our target range of five to seven weeks of iPhone channel inventory with less than 1 million more iPhones in the channel compared to the December quarter a year ago, in line with our growth in average weekly unit sales. Customer interest and satisfaction with iPhone are very, very strong for both consumers and business users.
The latest data from 451 Research indicates U.S. customer satisfaction ratings of 96% or higher across iPhone models. In fact, combining iPhone 8, iPhone 8 Plus and iPhone 10, consumers reported an amazing 99% satisfaction rating. And among business customers planning to purchase smartphones in the next quarter, 77% planned to purchase iPhone. Our customers are also incredibly loyal with Kantar's latest U.S. research, reflecting a 96% iPhone loyalty rate, the highest ever measured. [Customer satisfaction is the second most important figure after active user base. Combining these two figures yields the recurring revenue value of the company. Remember what Deming said: the most important measurements for a company's value are the multipliers of a satisfied customer and a dissatisfied customer--these numbers never appear on any financial report but they are applied to all the numbers on every report].
Turning to services. We had a terrific quarter with revenue of $8.5 billion, up 18% year-over-year and up 27% in terms of average revenue per week; that is an acceleration to the 24% services growth run rate that we experienced in the September quarter.
The App Store set a new all-time revenue record. The Store’s all-new design is off to a fantastic start with quarterly store visitors, transacting accounts and paying accounts, reaching new all-time highs. During the week beginning December 24th, a record number of customers made purchases or downloaded Apps from the App Store, spending over $890 million in that seven-day period, followed by $300 million in purchases on New Year’s day alone.
And according to App Annie’s latest report, the App Store continues to be the preferred destination for customer purchases by a very wide margin, generating nearly twice the revenue of Google Play. Across all our services offerings, paid subscriptions reached $240 million with growth of 58% over last year and they were a major contributor to the overall strong growth in services revenue. [Apple has half the user base of Google Android. This is based on Google's May 2017 report of 2 billion active devices vs. the 1.3 billion that we just got from Apple. And yet these users collectively spend twice as much on apps. This ratio of "half the users, twice the spending" has been cropping up in individual developer anecdotes and can also be seen in other metrics of engagement and consumption. This should not be surprising as it conforms to the Pareto distribution of economic value.]
As Tim mentioned, it was our best quarter ever for Apple Watch. And when we add to this us from Beats and AirPods, our total revenue from wearables was up almost 70% year-over-year. In fact, wearables were the second largest contributor to revenue growth after iPhone, which is impressive for a business that started only three years ago. In total, our other products category set a new all-time record with quarterly revenue exceeding $5 billion for the first time. [Wearables now includes more than watches but watches are likely still the dominant product.]
Next, I’d like to talk about the Mac. We sold 5.1 million Macs during the December quarter, which translates to a 2% year-over-year increase in average sales per week. Mac performance was particularly strong in emerging markets with unit sales up 13% year-over-year and with all-time records in Latin America, in India, Turkey and Central and Eastern Europe. On a worldwide basis, the active install base of Macs was up double-digits year-over-year to a new record.
It was also another growth quarter for iPad. We sold 13.2 million units with average iPad sales per week up 8% over last year’s December quarter. iPad sales grew strong double-digits in many emerging markets, including Latin America, the Middle East, Central and Eastern Europe and India, as well as developed markets, including Japan, Australia and Korea. The active install base of iPad has grown every quarter since its launch in 2010, and it reached a new all-time high in December, thanks to extremely high customer loyalty and large numbers of first-time iPad users. [iPad is clearly recovering from a long decline. ASPs are rising as it's being positioned as a PC alternative. Its low end functions are being absorbed by large screen iPhones.]
NPD indicates that iPad had 46% share of the U.S. tablet market in the December quarter, up from 36% share a year ago. And the most recent surveys from 451 Research found that among customers planning to purchase tablets within 90 days, 72% of consumers and 68% of business users planned to purchase iPads. Customer satisfaction is also very high with businesses reporting a 99% satisfaction rating for iPad.
We are seeing great traction in enterprise as businesses across industries and around the world standardize on iOS. For example, Intesa Sanpaolo, one of Europe’s leading banks, has chosen iOS as the mobile standard for its entire 70,000 employee base in Italy; choosing iOS for its security, user interface, accessibility and reliability, Intesa Sanpaolo will deploy native apps to improve employee productivity in customer support, human resources, and marketing across the company.
And LensCrafters, one of the largest optical retail brands in North America, will be using over 7,000 iPad Pros to enable digital eye exams and digital optical measurements in a personalized and interactive experience. We’re also rolling out a new initiative, called Apple AtWork to help businesses implement employee choice programs more easily and offer Apple products company-wide.
Resources from both Apple and our channel partners will enable enterprise IT and procurement teams to buy or lease Apple products more efficiently, streamline the setup of iPhone, iPad, and Mac, and deliver a seamless onboarding experience for employees. We launched the program with CDW in the U.S. last week, and we would be expanding to more channels and regions later this year.
The December quarter was extremely busy for our retail and online stores, which welcomed 538 million visitors. Traffic was particularly strong during the four-weeks following the launch of iPhone 10, up 46% over last year. And across the quarter, our stores conducted over 200,000 today at Apple sessions, covering topics including photography, music, gaming, and app development, and art and design. Just last weekend, we opened our first store in Seoul, Korea and we’re looking forward to opening our first store in Austria in a few weeks. These newest openings will mark the expansion of our retail store presence to 21 countries.
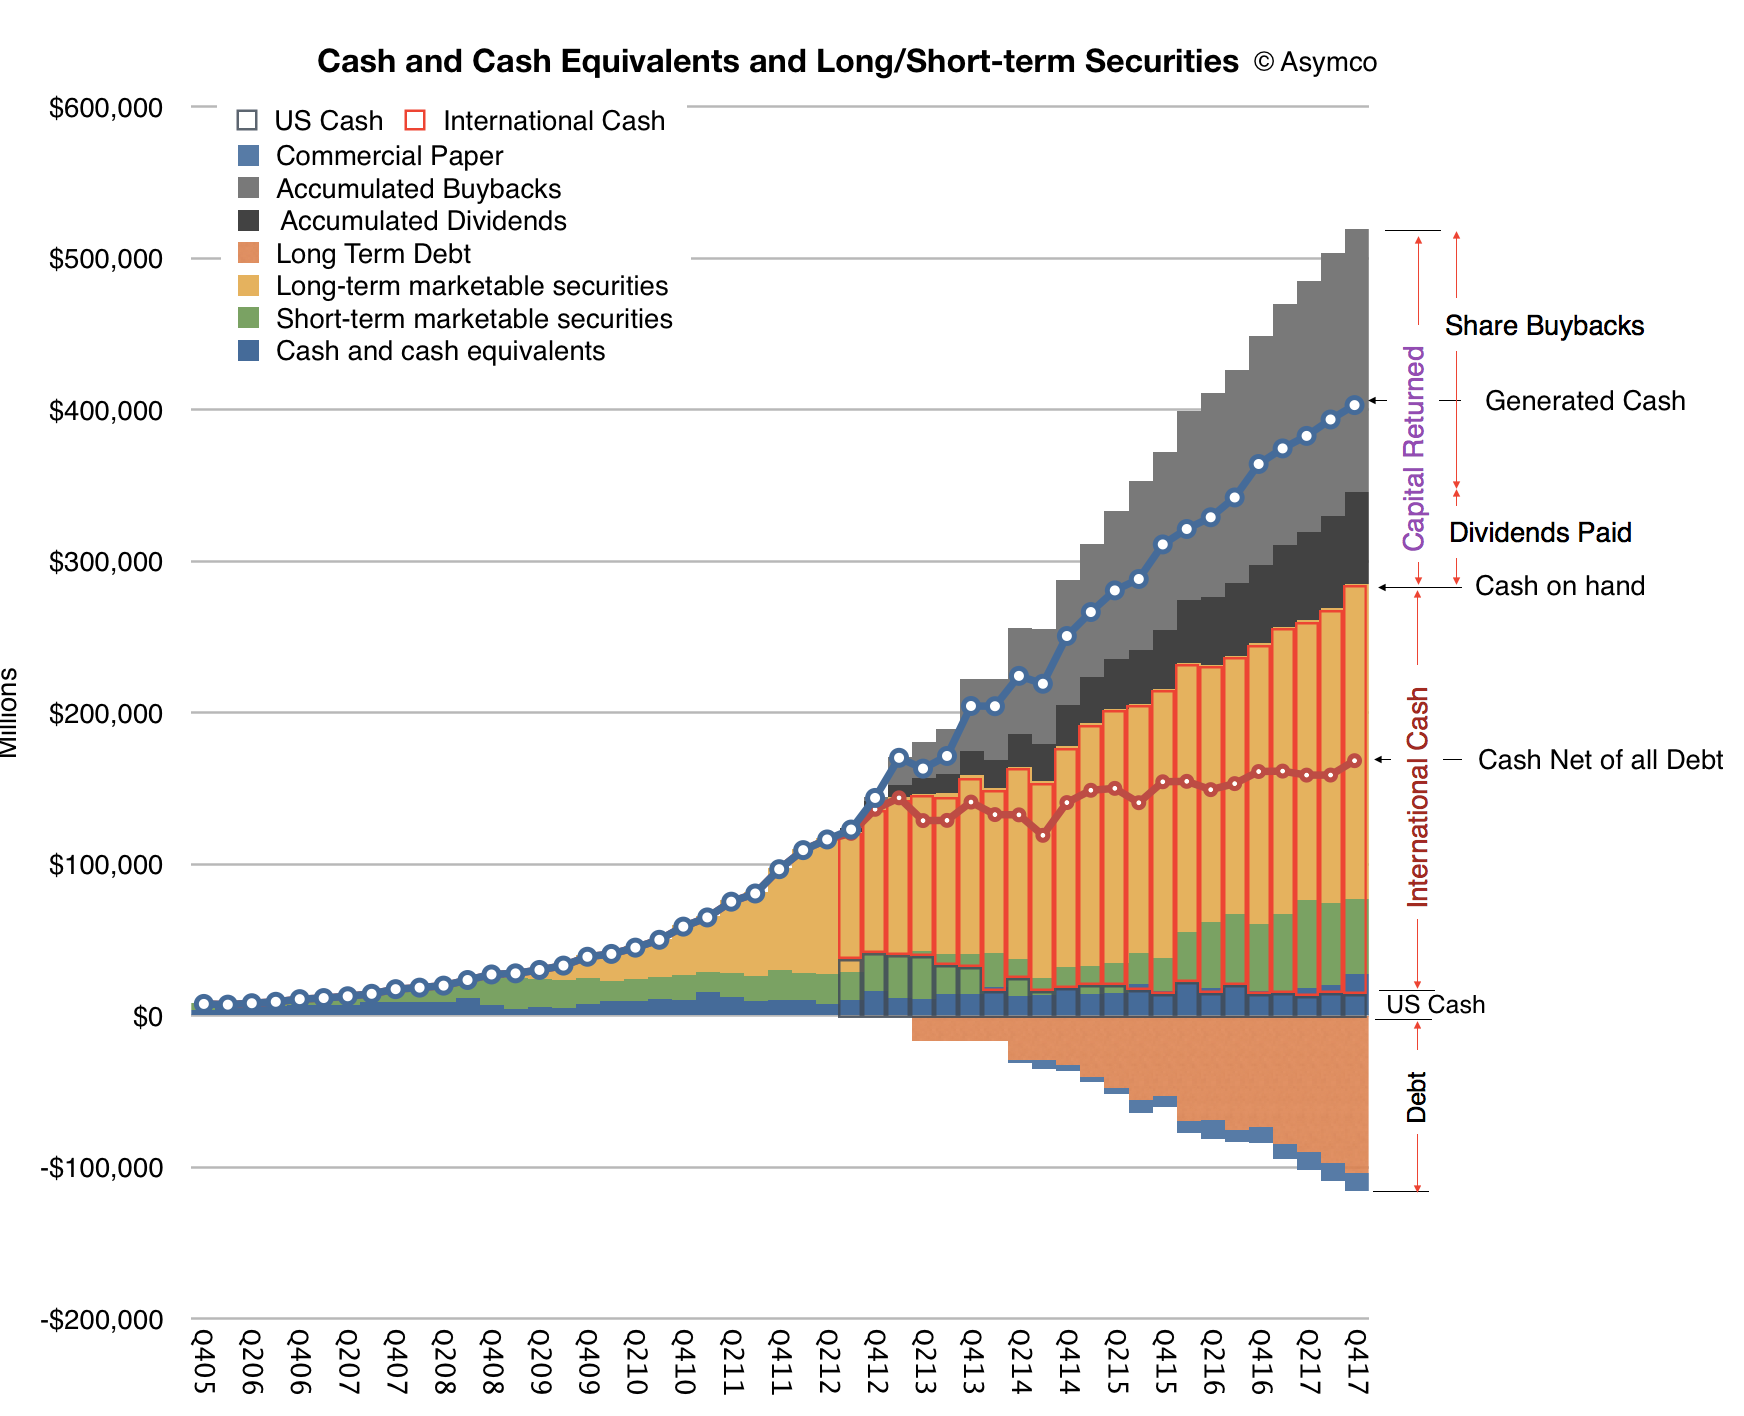
Let me now turn to our cash position. We ended the quarter with $285.1 billion in cash plus marketable securities, a sequential increase of $16.2 billion. $269 billion of this cash, or 94% of the total, was outside the United States. We issued $7 billion in debt during the quarter, bringing us to $110 billion in term-debt and $12 billion in commercial paper outstanding, for a total net cash position of $163 billion at the end of the quarter. We also returned $14.5 billion to investors during the quarter. We paid $3.3 billion in dividends and equivalents, and spent $5.1 billion on repurchases of 30.2 million Apple shares through open market transactions.
We launched a new $5 billion ASR program, resulting in initial delivery and retirement of 23.6 million shares and we retired 3.8 million shares upon the completion of our 12th ASR during the quarter. We’ve now completed over $248 billion of our $300 billion capital return program, including $176 billion in share repurchases against our announced $210 billion buyback program with $34 billion remaining under our current authorization. [An updated look at Apple's cash is shown below]
Turning to taxes. Due to the recently enacted legislation in the U.S., we estimate making a corporate income tax payment of approximately $38 billion to the U.S. government on our cumulative past foreign earnings. This amount is very similar to what we had been accruing on those earnings in our financial results through fiscal year 2017, including the $38 billion payment. We will have paid over $110 billion of corporate income tax on our total domestic and foreign earnings during the last 10 years for a cash tax rate of about 26%. [Apple has paid more tax than any company in history, and is about the make the largest single payment to the US Treasury.]
Our tax rate of 25.8% for the December quarter was close to our guidance of 25.5% as the lower U.S. statutory rate from the new legislation was effective offset by the remeasurement of deferred tax balances.
As we move ahead into the March quarter, I'd like to review our outlook, which includes the types of forward looking information that Nancy referred to at the beginning of the call; we expect revenue to be between $60 billion and $62 billion; we expect gross margin to be between 38% and 38.5%; we expect OpEx to be between $7.6 billion and $7.7 billion; we expect OI&E to be about $300 million; and we expect the tax rate to be about 15%.
Tax reform will allow us to pursue a more optimal capital structure for our company. Our current net cash position is $163 billion. And given the increased financial and operational flexibility from the access to our foreign cash, we are targeting to become approximately net cash neutral overtime. We will provide an update to our specific capital allocation plans when we report results for our second fiscal quarter, consistent with the timing of updates that we have provided in the past.
Finally, today our Board of Directors has declared a cash dividend of $0.63 per share of common stock, payable on February 15, 2018, to shareholders of record as of February 12, 2018.
"Our Model 3 program is on track to start limited vehicle production in July and to steadily ramp production to exceed 5,000 vehicles per week at some point in the fourth quarter and 10,000 vehicles per week at some point in 2018.”
Overall 2018 production guidance has been 500,000 units and 1,000,000 units in 2020.
The company shipped 220 Model 3s in the July, August and September months. This is well below the expectation of 75,000 that the 2016 guidance would suggest ((100,000 to 200,000 for the second half of 2017 suggests an average of 150,000 for the six months or 75,000 per quarter)) or the 1,630 that might be suggested by the "production grows exponentially" July proclamation.
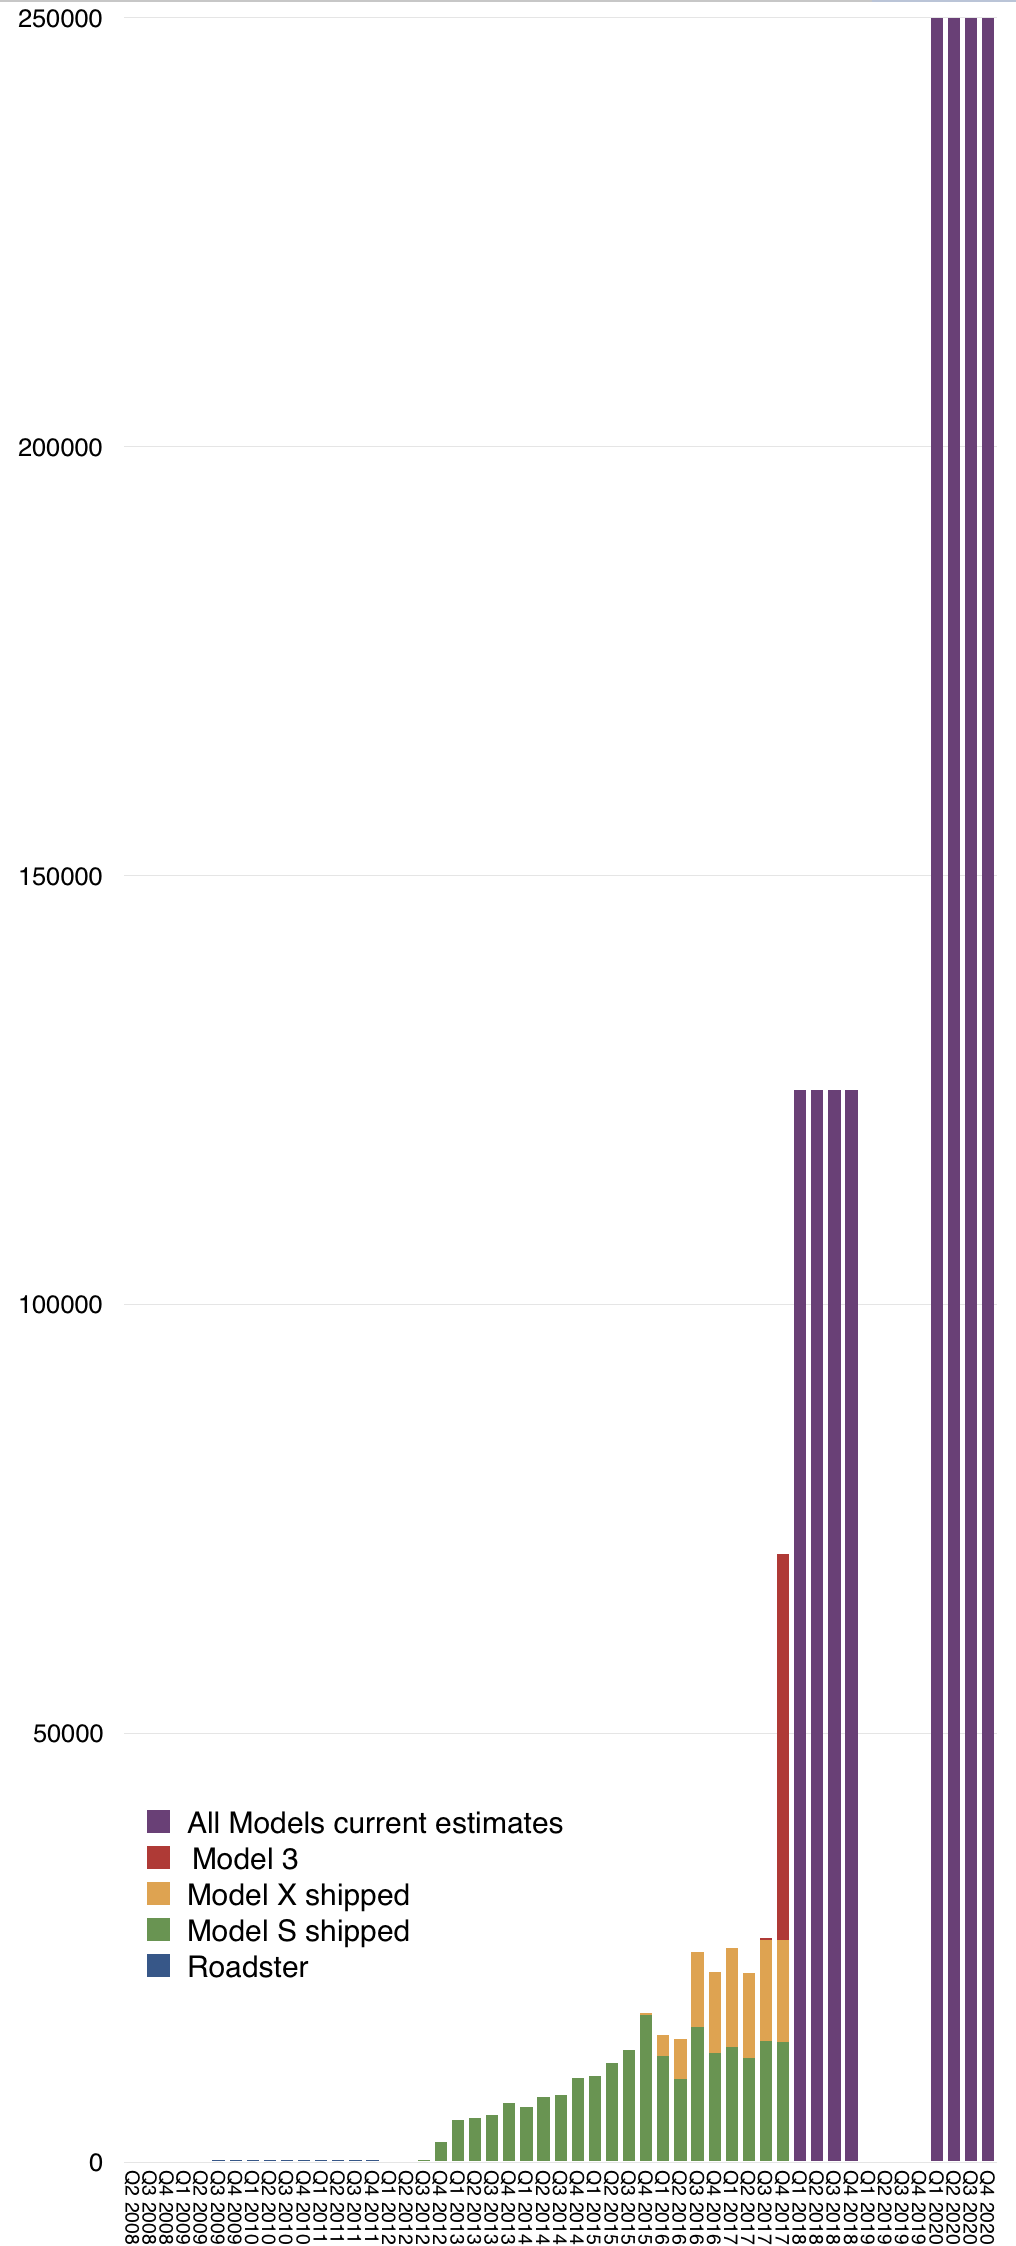
I entered the Q3 production data and kept the previous run rate predictions for Q4 and 2018 and 2020 in the following graph.
Note that the graph includes all previous shipments of Tesla cars throughout its history.
The red bar represents an estimate consisting of the sum of 10,000 Model 3 in October, 15,000 in November and 20,000 in December. This is consistent with reaching the target production of 20,000 in December.
The purple bars are distributing the planned production evenly throughout the 2018 and 2020 calendar years.
Before asking whether these predictions can be relied upon, I'd like to focus on the history of Model S and X production/shipments. Specifically the last five quarters.
Q3 2016: 24,500
Q4 2016: 22,200
Q1 2017: 25,000
Q2 2017: 22,900
Q3 2017: 25,930
Q4 2017: 25,845 ((This is an estimate based on another point of guidance: 100,000 models X and S for the 2017 year.))
Growth in this total figure has been remarkably low. Only about 4% y/y in the last quarter and sequentially the total has bounced in a narrow range.
This level (about 24,000 units/quarter on average) is a distinct plateau but it's also well above the average of the previous 4 quarters of about 15,000 units/quarter. It suggests that there was a “quantum leap” in production at the end of 2016, to a new plateau.
So the question is why, with so much pressure to produce cars to meet presumed unlimited demand, is output so limited?
To see just how limited, consider the rate of output. For the past 15 months and near future, the output is equivalent to 264 cars per day. If the Fremont factory is running three shifts, 11 cars are produced every hour. This is equivalent to a cycle time or takt time of 5.5 minutes.
This would be an tragic cycle time. Most car lines aim for run times between 1 and 2 minutes per station. For example BMW's Spartanburg plant produces 1400 units per day which yields a cycle time of 1 min. ((This assumes one line. The chassis/engine marriage step is clocked at 3 minutes so the worst case is that there are three lines running at 3 min. cycle time each.))
This measure of performance is so important that it drives the depreciation and capitalization schedule for tooling and the very lifeblood of the company: capital expenditures. An underutilized factory is a giant hole in a financial statement and destroys value as much as inventory does. Every manufacturer strives for maximum utilization and is sunk if it does not achieve a minimum threshold.
So why, after a few years of Model S production, is Tesla running at one fifth the speed of a BMW or Toyota plant? One obvious answer is that the company is not running 3 shifts but perhaps 2 or even 1. But why would they shut down the line when demand is infinite? If it is finite, is it really only 25k at most per quarter? That’s a paltry number considering the size of the market they operate in. BMW alone ships 2 million vehicles a year. Tesla X/S topping out at 100k a year suggests a serious limit to their opportunity.
Another possible explanation is that there aren't sufficient battery deliveries for continuous production. We hear about issues with battery throughput as transients that slow production. But the production data we have spans an 18 month period during which the speed has hardly budged. During this time additional battery capacity in the form of a Gigafactory has been announced.
If this giant new factory can’t reliably deliver batteries for 25k cars/quarter then how are we to believe that it can deliver for 125k units in a few months? If it's not batteries, then what? I don't know of other subsystems that are chronically constrained that we can point a finger at. Almost all other parts in a Tesla are sourced from existing supply chains.
The most likely suspect is that Tesla's S/X line is not fully operational. When you study production lines, generally they either work at a decent clip or they don't work at all. They are not designed to be dialed down to be as slow as 5 min for every 10 feet of car. It's much more likely that the line is idle for long periods of time. Perhaps even 2/3 of the time.
This is what is so mystifying about Tesla's exuberant predictions for the Model 3. The X/S line is bogged down and inefficient five years after production start but we are to believe that the Model 3 line will come to operate at >5x speed within weeks, on a new product? Maybe the X/S line is a failed experiment. Maybe the company is moving to "Version 2" and leaving the cruft in Version 1 without fixing it.
Maybe.
Tesla's asymmetric approach to automobile product development and distribution and ownership experience are key advantages but their asymmetry to functioning best practice production systems is a key disadvantage. The big competitive question is will incumbents get good at intelligent EV experiences faster than Tesla gets good at production.
Outsiders might ask "How hard can car building be?" and vote for Tesla winning this race.
There is no data on how fast an incumbent learns the EV experience delivery process, as it's never been tried before, but there is data on how fast a manufacturing company learns lean production. Those times were measured in decades.
[UPDATE]
In the week that followed this post new claims have been made on Tesla's production system by other publications.
Wards Auto published a story on problems with automating the Model 3 production line.
Wall Street Journal published a story on claims that Model 3 production was constrained by hand-building on parts of the line.
Edward Niedermeyer wrote in the Daily Kanban about regulatory documents that show limitations in production of the Model 3.
The most relevant quote to this post is the Wards claim that:
Its current production line in Fremont, CA, can’t build vehicles at [5,000 weekly] rate unless it runs two 10-hour shifts seven days a week, which is not likely for an all-new vehicle, even if everything goes smoothly. The plant presently runs two 8-hour shifts five days a week.
If this is true then the current Model S/X line is limited to about 50% of capacity or about 25 cars/working hour. This is equivalent to a takt time of 2.4 min/station. This is certainly much better than the estimated 5.5 and within a range of reasonableness, but one has to ask why is the line not operating more than half the time?
When I wrote about there being "infinite demand" for the X/S, the logic was that the X/S was still a niche product at 100k/yr and the category into which is sells is assumed to have a lot more headroom for their entry.
The observation that production is topping at 50% capacity for 18 months in a market that is quickly being targeted by competitors remains interesting to me.
Apple reports second calendar quarter results in about a week. I propose the following estimates:
Fiscal Q3 2017: Rev ($B) 45.321 EPS ($) 1.62 iPhone (units) 41 million iPad (units) 9.8 million Mac (units) 4.35 million Watch (units) 2.5 million Services ($) 7.2 billion Other products ($) 2.6 billion Gross margin (%) 38.4
The revenue estimate is visualized in relation to guidance (revenue between $43.5 billion and $45.5 billion) and shown in the context of previous actual revenues below:p
The estimates are also consistent with additional guidance provided:
Gross margin between 37.5% and 38.5%
Operating expenses between $6.6 billion and $6.7 billion
Other income/(expense) of $450 million
Tax rate of 25.5%
The estimates (and guidance) suggest modest growth of 7% in revenues and 13.7% EPS. The predictability of the quarter suggests that attention will mostly be focused on guidance for the next quarter.
Expectations can vary quite a bit because of the effects of a new launch. The product mix, pricing and timing are all unknown at this time.
What is known however is that the customer base for Apple is increasing and loyalty is higher than ever. What I sense, coming from very few data points, is that there are more iPhones in use than ever before. A few years ago when the market was less saturated it was easy to assume that commodity Android phones and tablets would surge and swamp iPhone/iOS usage.
This has not happened, indeed the data suggests that iOS usage is stronger than ever and that there are many more "switchers" moving from Android to iOS than vice-versa.
This may surprise some but if we look at the PC market, a similar phenomenon has been taking place for years. Mac usage grows and Macs are more visible and valuable than PCs.
It's important to note that in the latter, post saturation stages, the markets for both phones and computers are increasingly driven by brand value. This resistance to commoditization is due to buyers' perceptions of quality moving beyond utility and of the prioritization by buyers of new measures of performance. These new measures defy measurement.
Much of what is therefore required of market analysts is intuition.
The last quarter of 2016 was Apple's biggest ever. $78.4 billion in revenues. 78.3 million iPhones. Both records. Earnings of $3.36 ((On shares priced at the time around $105 or 3.2% yield quarterly earnings)) and cash reached new highs. The growth was modest but Services is now not just the second largest revenue but also the fastest growing, on track to doubling in four years.
The reason for this is the vastness of Apple's user base coupled with the loyalty the brand engenders. The company reached one billion active devices more than a year ago and is quite likely to have nearly a billion users. Not just any billion either--the best billion most probably.
The realization that Apple benefits from extreme quantity and quality of customers has led some observers to defer the imminence of Apple's demise. Share prices have risen lately to new highs and the ratios between these prices and earnings have started to come closer to the average of other large companies.
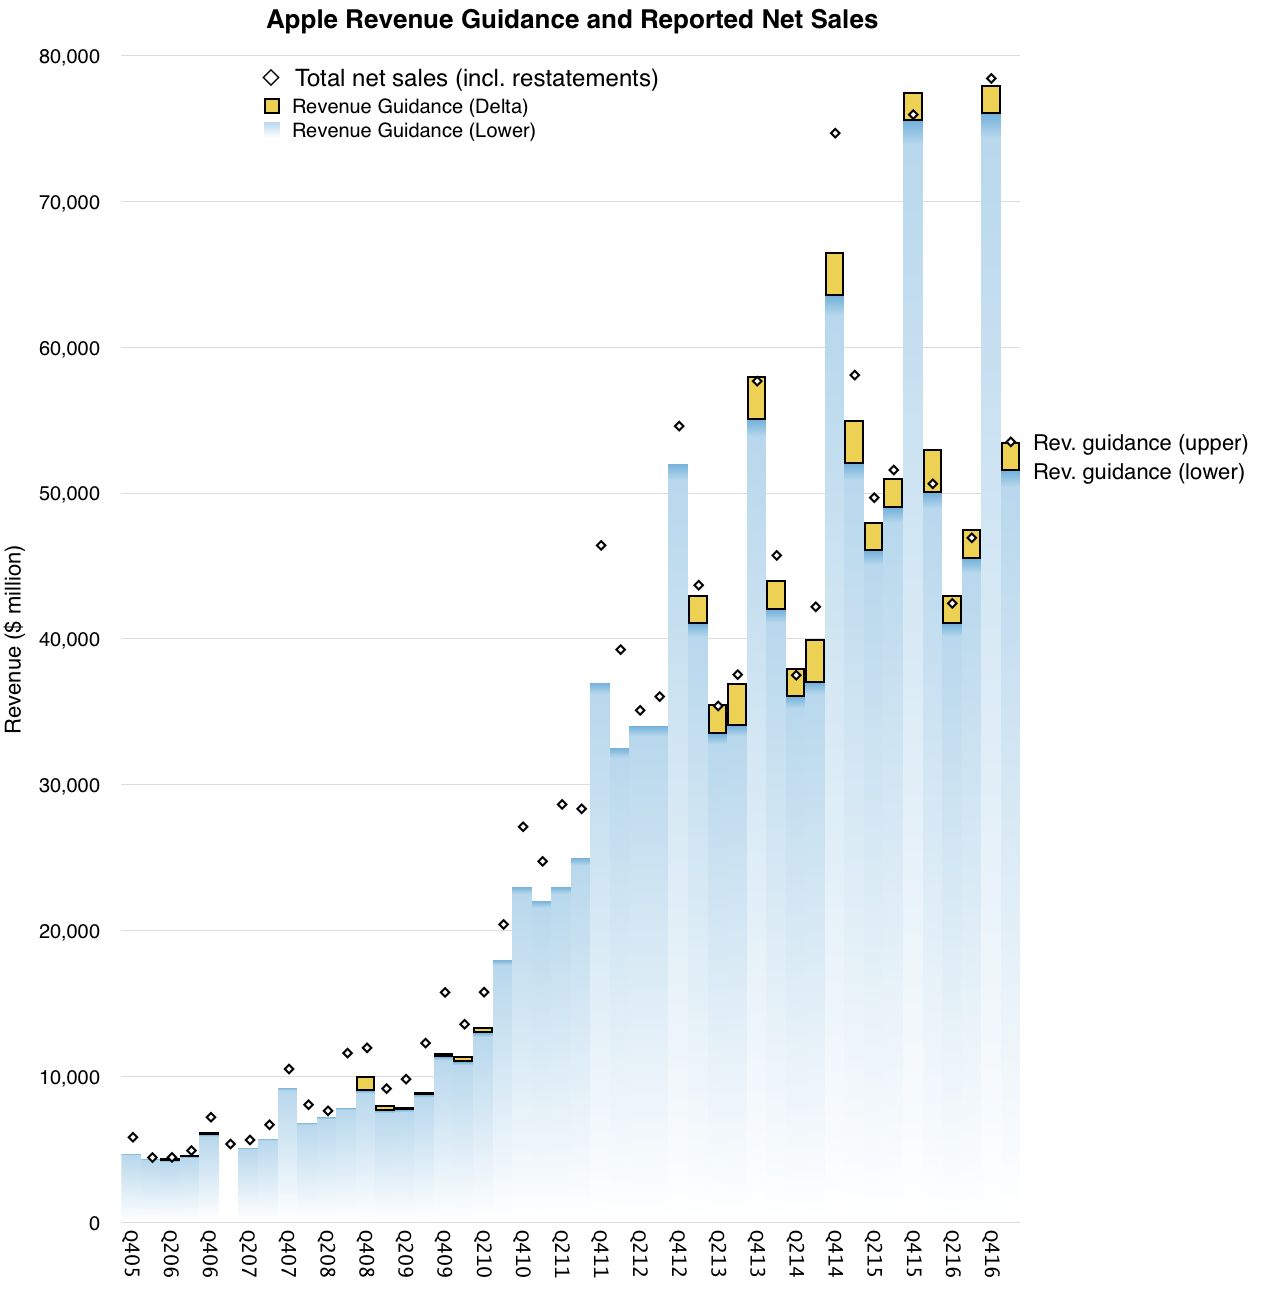
But enough with the reductio ad absurdum. Let's look at the next quarter. The company has been very precise with its own offered predictions (guidance) so it's a simple task to make an accurate forecast. The history of guidance vs. outcomes for revenues is shown below:
Placing the pipper on the upper edge of the guidance range was a safe targeting method for 11 of the last 17 quarters. We have never seen a drop below the bottom of the range but had a few overshoots, some huge. Doing this for the latest quarter and working backwards to the individual product contributions to revenue and using historical margin and cost patterns we can get the following core financial performance metrics:
I sent these estimates to Philip-Elmer DeWitt and I recommend looking at his survey of the other analyst estimates on his excellent Apple 3.0 blog.
Overall, the quarter is shaping up to offer slight growth y/y and indicating a plateau formed after the surge from the iPhone 6 surge in '15. All eyes are on the "super cycle" for the next iPhone.
The reason it's "super" is that the iPhone has a 2+ year cadence for form factor changes and the user base updates on a similar cycle. The demand is vast due to the user base and accumulated age of devices in use. Expectations are that supply will be offered to meet this demand.
If history is a guide then the next iPhone will be the best iPhone ever.
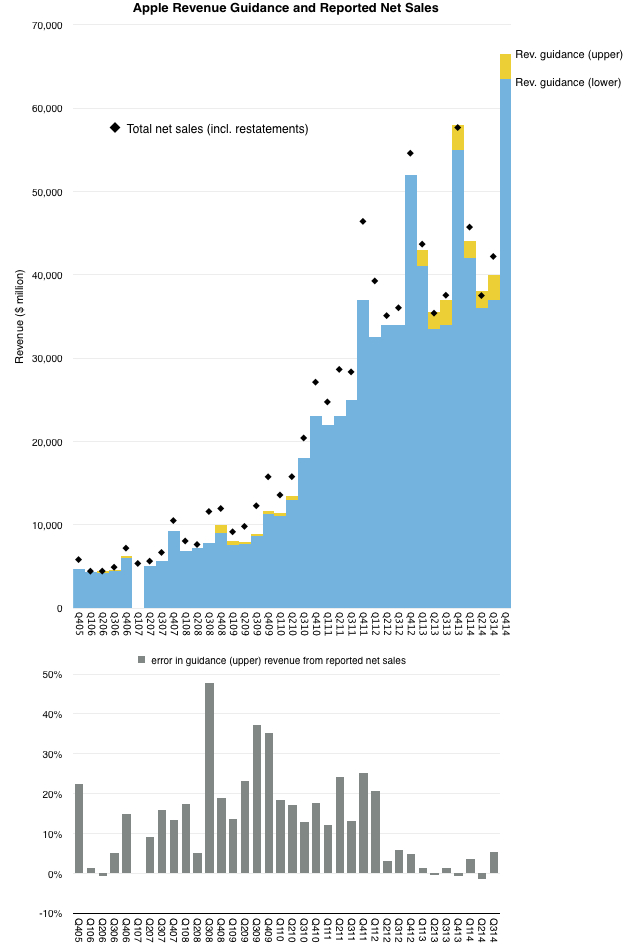
In Q3 2014 Apple's revenues were 5.3% higher than the upper end of their guidance. This is the highest error in guidance since the new range-bound reporting regime started two years ago.
The following graph shows the guidances given since 2005 and the actual revenues. The error (as a percent of upper guidance) is given in the second graph.
Note how since the newer, presumably more accurate method was introduced in 2012, the errors have decreased on average. As a result, for these two years, forecasting performance for Apple was no longer challenging. The only questions for the analyst were how to allocate the revenues among products and to guess how many shares would be retired.
Is this about to change? Could forecasting make a comeback as sport and leisure?
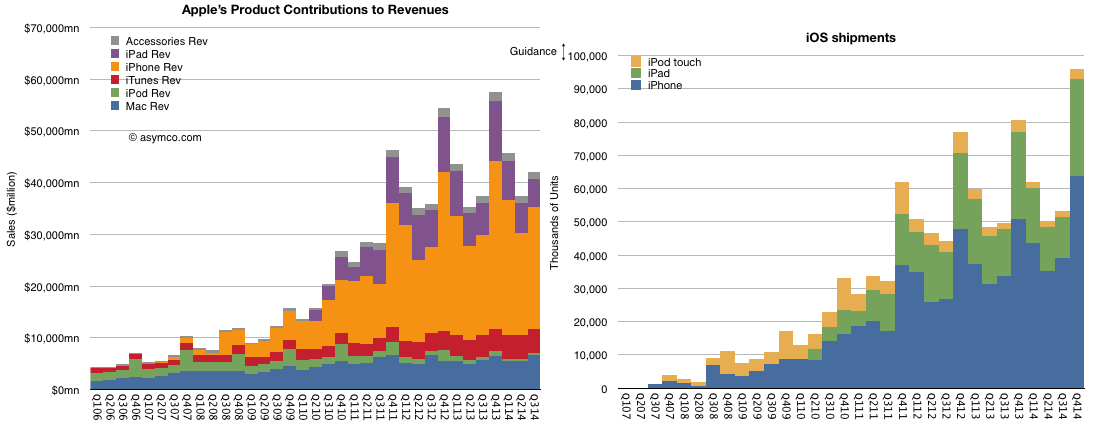
Assuming no error in Q4 yields the following shipment forecast:
That's about 95.5 million iOS devices in the quarter. That also means that the one billionth iOS device will have been sold sometime in the next few weeks. ((McDonalds took 23 years to serve its first billion hamburgers)) ((Over 650 million iPhones, 115 million iPods touch, 265 million iPads))