Asymco

Asymmetric Intelligence

PC

  1. The trouble with halos

    Research · 45 comments

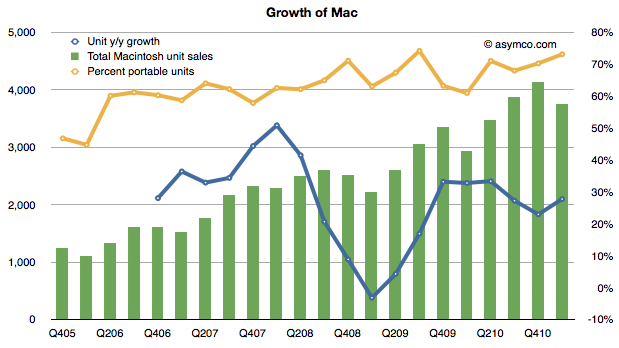
    The Mac grew at 28% while the overall PC market contracted at 3%. The Mac has outperformed the PC market overall for 20 consecutive quarters.

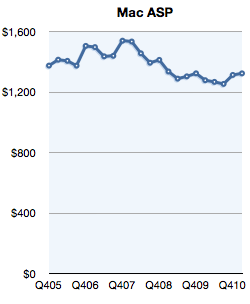
    Prices increased sequentially and year-to-year.

    I've mentioned the increasing shift of Mac mix to portables as a possible reason for the growth of the business. The Mac was one of the first to move to a portable form factor and has been pushing portability over performance for many years.

    The following chart shows the relationship between growth and portable mix:

    The trouble is that mix is not enough to explain the increasing gap with the rest of the PC industry. Windows PCs have also embraced portability and have even run down the path of over-serving portability with the netbook.

    Clearly something else must also be at work. This was even noted by Apple's COO Tim Cook in the last conference call in response to question on the effect of iPhone growth on the Mac:

    [iPhone] clearly seems to be creating a halo effect for the Mac. And I think that's one reason we see the growth that we are seeing on the Mac. It's amazing when you see the 28% year-over-year versus the worldwide market in PCs contracting by 3 points. It's an astonishing delta.

    The delta has been there for a while but it's widening and it's persistent.

    I've never been comfortable with the halo effect. Not because it's not happening but because we don't have a way to measure it. I've never seen reliable data that establishes a causal link. Lots of anecdote but little proof.

    The other problem with halo is that it implies illusion and hence impermanence. The halo effect is a cognitive bias which can mislead. An example would be judging a good-looking person as more intelligent.

    This effect is often exploited in marketing. It's quite common in the automotive industry where halo vehicles (e.g. Ford GT 40 or Dodge Viper) are created which promote sales for the entire brand even though they may lose money. These efforts often fail or have temporary benefits at best.

    When it's deliberate and an attempt to prop up something unworthy it seems deceptive, dangerous and temporary (buyers may be disappointed when they buy a Ford or Dodge and realize that they are not supercars and a reverse halo effect can emerge.)

    A halo effect should be used to boost a product that is under-rated not badly rated. This is when the effect creates benefit over a long period of time like the five years over which the Mac has over-performed.

  2. Windows generates less than a third the profit of iOS + OS X

    Research · 35 comments

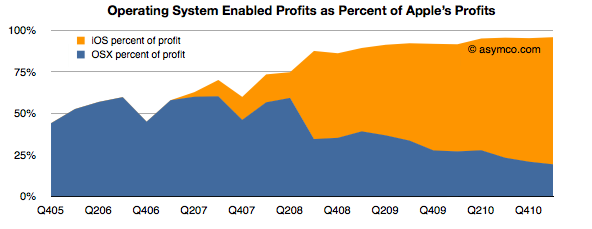
    While a lot of the credit for Apple's success is rightfully assigned to the iOS franchises, the OS X business has more than quadrupled in five years. This has happened without drastic price fluctuations. Neither holds for the overall PC industry which has seen both volume and sales decline while prices have eroded along with profitability. On top of that, growth has nearly evaporated.

    Even with this success, as a percent of total value created, the Mac accounts for a mere 13% of Apple's profit. Including software as part of the OS X franchise implies that OS X is enabling about 20% of Apple's profits.

    iOS, on the other hand, is accounting for more than 75%. These two platforms combined amount to 96% of Apple's profits (up from 50% four years ago).

    That's $9.8 billion from integrated platform-based devices. One can be very confident that this profit would be negligible without the software differentiation only Apple can offer.

    So $10 billion is a lot of profit to obtain from a business enabled by operating system platform software. How can we get a handle on this size? How big is this? We could compare this with another operating system business: Microsoft Windows.

    Microsoft's Windows and Windows Live Division obtained sales of $4.445 billion in the last quarter with an operating income of $2.764 billion.

    So although Windows earned about twice what the Mac earned[1], iOS and OS X together enable 3.5 times the profits of Windows.

    The end of an era is the end of growth in one dominant business model. The PC era was epitomized by the concentration of profits in a dominant operating system vendor. That growth has slowed if not ended. The post-PC era is being kicked off by a new business model where profits are being concentrated in a hardware+software+service integrator.

    --

    1. Or you could read this as: The Mac generates half the profits of Windows while iOS devices generate 2.3x Windows profits.
  3. A new era is only a new state of mind

    Research · 51 comments

    The following interview was conducted by Bruno Ferrari a writer about technology for EPOCA, the weekly magazine of Organizações GLOBO, the largest Brazilian media company on March 30 2011. The article (published in Portuguese here) is an edited subset of the following exchange.

    Q: In your analyses, you mention tablets as part of a new era, the “Post PC era”. Why do you think the PCs will be replaced by tablets?

    This is not quite correct. Post PC does not mean the end of the microcomputer. The way to think about it is this: The stone age did not end because we stopped using stones. Same with the iron age and the industrial era. The era of jet travel did not end automobile or even ship travel (though that changed to recreation rather than transportation for passengers.) Each phase of technology does not fully replace its predecessor. It offers a new set of solutions and perhaps a slightly different way of solving old problems. We'll still have PCs but we will use a new type of computer, an even more personal computer. The world still uses the microcomputer's technological ancestors.

    In terms of what new jobs will we hire the tablets to solve, they will vary greatly from what we used PCs for. Just like we used microcomputers for different things than we used time-shared minicomputers and mainframe computers. I expect social interaction, media consumption and entertainment will move from a PC to a tablet. New uses will emerge from the vast experiment that is the app phenomenon.

    Q: What are the new ways to interact with machines? With gestures? How will this change the market?

    Each major disruption of computing came from a new generation of input and/or output methods. Terminals (vs. punch cards) enabled minicomputers. The GUI enabled the rise of the microcomputer and touch is enabling the rise of the tablet. Perhaps this era will last decades perhaps only years, but there will be new input and output methods available. The world's research laboratories are filled with ideas from projection screens (from high brightness LEDs) to motion sensing (as implemented partly by Kinect) and even novel voice control methods. I believe that each major innovation will create a new wave of growth and, if coupled with a new business model, a new set of companies and platforms.

    Q: What are the main differences between PC and Post PC era?

    The main difference will be in the context in which the product will be used. Tablets and smartphones allow "computing" to be done in previously non-consuming contexts: while standing, while in the active company of others, while commuting or while lying back and relaxing. It will also allow more individual use. Like the transistor radio allowed teenagers to listen to rock-and-roll out of hearing range of their parents who had control over the family stereo, a truly personal computer will allow people to "escape" into a world of more intimate consumption and communication.

    Q: Do you think physical keyboards and mouse will be extinct?

    Even physical keyboards have been evolving dramatically. If you look back to the earliest IBM PC keyboards, they were mechanically complex and had a rich feel. Modern laptop keyboards are flimsy things with barely any feedback. Early PC keyboards were patterned after the needs of professional typists (aka secretaries). Current keyboards are designed around space constraints. Same with mice. They went from two to three to one to no buttons. With laptops we ended up with track balls,  little knobs in the middle of the keyboard or with trackpads. Users adjusted over time.

    What changed with tablets is the removal of an on-screen pointer. The pointer was there because the mouse/touchpad was one layer of abstraction for controlling what was on screen. Without a pointer you have direct manipulation. I'm sure many people who never used a mouse would find the direct method more intuitive and in a generation people will wonder how we put up with mice. Conversely, those who are used to a mouse will find it uncomfortable at first. Remember that in the 80s many keyboard experts found mice something that slowed them down.

    So I believe that people will adjust to a world without mouse pointers. I suspect children born today will grow up without ever using a mouse (or a phone with a wire permanently attached to the bottom).

    Q:  Apple has more than 90% of tablet market worldwide. Do you think Apple will be the leader of technology market in the next few years?

    The challenge for Apple is that they cannot serve the whole world. They can only grow so fast. On one hand we have their inability to meet demand and on the other we have alternative products which can. Market leadership may not be sustainable just because the market is so big and no single company can supply it. I do believe that Apple is not sitting on its hands however. Their culture promotes pushing forward.

    Q: At smartphone market, do you believe on a risk of a new duopoly, Apple-Google? Some analysis says that they’ll control the channel sales of software, content and hardware. The conclusion is companies like RIM, Nokia and HP (Palm) will not be able to keep up.

    Analysts differ in their opinions. IDC just released a forecast that shows Microsoft growing beyond iOS in four years. I don't try to make this type of prediction. At least not to a high degree of precision. I do believe that there will be more than two platforms. This is because the market is so large and so diverse and there are so many ways to reach customers (through operators, through retail stores, through online).

    Q: Can we compare the beginning of the tablets with PCs? Apple developed the interface and made ​​the first computers nice and easy to use. But Windows has allowed hardware manufacturers to invade the market, popularizing it. This will be repeated with Android? Or with other systems?

    Innovations are always copied. Even when protected by all sorts of laws or patents. What makes a company successful with innovation long term is to always keep innovating. Often coming up with the next big thing means damaging the old thing. That's hard to do for many companies so they don't do it and somebody else does. This is why great companies end up as formerly-great companies. As I pointed out above in the discussion about input methods, innovations are always bubbling up. As long as Apple takes these ideas and polishes them and brings them to market, they'll do all right.

    Q; How about Microsoft? Do you think the company will lose the podium in Post PC era?

    Microsoft already has lost its position as leader in personal technology. The end actually came in about 2000. Once Windows became "good enough" and did not crash so much, they have had a hard time finding something to improve. If you go back and watch every CES keynote that Microsoft presented since then it's been a litany of dead end ideas.

    Every major innovation since 2000 has been in consumer technology and that's never been an attractive business for Microsoft (with the exception of XBox which was really aimed at Sony and Nintendo without the intention of creating a new market.) Microsoft struggles not because they lack talent (engineering or management) but rather because their business model is relatively rigid. They make money through software licensing. You can see how that's a hard thing to sell to consumers ("I'm buying what?") Consumers tend to pay Microsoft through the purchase of another product. If the market demands hardware/software integration (like in a phone or tablet) or making money by giving software away (like Google), they struggle. This business model rigidity is present in almost all companies, so Microsoft is not uniquely troubled.

    Q: Most of the tablets will use mobile networks to connect to the internet. Do you think the world is ready with an infrastructure that supports this growth in access via mobile networks?

    This is a good question because the growth of mobile broadband is a major enabler (or constraint) on growth. Fortunately, the roll-out of mobile broadband is fairly predictable and it looks good. There are some challenges for operators long term in paying for the infrastructure, but they don't lack for financing today and the business case for more infrastructure seems to be very attractive. It will take time and it won't be even globally, but the incentives are clearly there. A lot of value is being created with mobile computing and much of that value will end up paying for the bandwidth.

    Q: How about the App Market. You posted recently a chart showing how fast developers are buying thickets for both Google and Apple developer events. You said that it is one signal of the Post PC Era. What will be the importance of apps on the next years. Do you think Apps market will be more important than hardware, content and OS market?

    Developers are one more sign that something big is happening. It's not the only sign and may not be the cause of the change, but it's yet another signal. But apps are a phenomenon that will result in something bigger than we can imagine. The way to think about apps is as a new medium, similar to the emergence of radio, television, cinema and even books. The app is a new art form as well as something that provides functional value. We don't know whether the app phenomenon will be tied to one platform or will evolve to something like HTML5, a common standard. But the value of having an app for everything is plainly evident. The economics, creative energy and dynamism of apps cannot be overestimated. I will write more about this subject as I think it's one of the most important consequences of the post-PC era.

    Q: What’s the destiny of the PC? Are they on their last years?

    Again, it's not so much that PCs will disappear any more than mainframes or servers have disappeared. What is more likely is that they will be used for isolated, focused jobs. The "end of an era" is the end of growth, not the end of existence. The PC has arguably reached end of growth in most developed markets. There is still strong growth in emerging economies but even there, much of that growth will probably be replaced with smart devices growth.

    Q: We had the Mainframe Era, the Terminal Era, the MiniPC Era, The PC Era and now we starting the PostPC Era. Do you imagine what Era we'll se after the tablets? When do you think is it going to happen?

    I don't try to be a futurist who can see with clarity technological change. I try to see the patterns of markets through the motivation of companies. With that in mind, my answer will be that large companies will acquire promising new technologies from start-up companies and implement products with global distribution. To see the future you therefore need to look at what small companies are doing today. I note that there is a lot of innovation in new communication methods (social media) and new input methods around gestures and display technology. I am skeptical about the power of voice controls.

    I'm most confident that there will be a re-definition of television, a "socialization" of almost all media. So I'll abstain from answering directly what happens after the Tablet Era. Perhaps something more personal and more of a companion than a tool.

  4. First quarter PC forecast: Windows down 2%, Mac+iPad up 250%

    Research · 100 comments

    Charles Arthur of The Guardian writes that PC sales "may have passed their peak".  That's a powerful, concise statement. It's backed up by a quote from Gartner's Mikako Kitagawa:

    "This was the third consecutive quarter of mobile PC shipment declines in the US"

    IDC even lays part of the blame to something called "media tablets"[1]:

    "While it's tempting to blame [PC] decline completely on the growth of media tablets we believe other factors [...] played equally significant roles."

    But there are several problems with both IDC and Gartner's analysis of the market. It's hard to make out causality from their data. There is separation by vendor but not by operating system and there is exclusion of devices hired to do the same jobs as PCs.

    For this reason, I need to do my own analysis. I retrieved Gartner's public statements on the overall market and layered actual Mac and iPad units sold. I also added my estimates for the Q1 2011 quarter just ended to complete the picture.

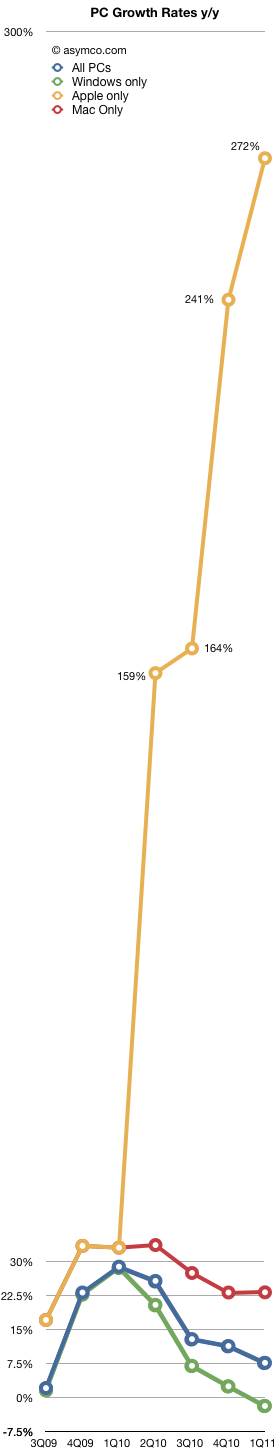
    We can now get an understanding of how the industry behaves with and without various platforms. The chart at the left gives the various growth rates of the market with platforms isolated from each other. I apologize for the shape of the chart but the scale does not permit a concise visual.

    Including the iPad, the total PC growth is shown by the blue line. It shows that the market peaked during the recovery but is now slowing considerably.

    The green line shows the PC industry excluding both the Mac and the iPad. Although it might include Linux or computers sold without an OS, the label "Windows PC" is a fairly close approximation. It shows that the market excluding Apple entered contraction this quarter and is out of sync with overall economic recovery and growth.

    The red line shows the behavior of the Mac franchise. It's well ahead of the overall market with 2x to 3x the growth. This has been a pattern for over 18 quarters.  I had some thoughts on this in a November 2010 hypothesis.

    But the most telling line is the orange line which includes both the Mac and the iPad. In an industry where growth is usually measured in single digits, the iPad business brings growth in three digits.

    This near tripling of unit sales is symptomatic of fundamental change that cannot be ignored. Although some analysts contend that the iPad is not causal to the decline in other PC sales, teasing out platforms data seems to show a divergent view.

    The bottom line is that Windows-only computer units are down 2.0% while OSX-based computer units are up 272% (this excludes both the iPhone and iPod touch).

    Correlation is not causation but tests or surveys where substitution can be proven do exist. For example, a recent survey shows that 77% of users reported that their PC usage decreased after getting a tablet. It also showed that 28% considered their iPad as their primary computer.

    So coupling the sales data with the usage data does point an accusatory finger for the decline on the iPad.

    In addition, some vendors are being hit harder than others which also hints at where substitution is happening. For example, IDC reports that Acer US unit shipments fell 42% in the first quarter and 16% globally (Gartner's numbers are less dramatic but in the same direction). Since Acer is known for its netbook computers it's another telling sign of possible substitution (Acer's own management has indicated as much.)

    So the weight of evidence is beginning to be conclusive: the iPad is the new PC. It should be clear by now that the iPad moves computing into new contexts so it does not yet substitute the PC market but extends it and increases consumption. Substitution is happening in low-end grazing type of usage, a place where the PC was ill-fitting anyway. Incumbent vendors might actually be relieved that the lower margin netbook is finally being supplanted and they can concentrate on the higher end.

    --

    Notes:

    1. Analysts like to call the iPad a "media tablet" but the same AdMob survey shows media consumption to be one of its least popular uses.
  5. Disruptive failure: How Acer Took Aim at Dell and HP and missed

    Research · 72 comments

    Two years ago:

    With new netbooks, laptops, desktops, and, yes, a smartphone, Acer CEO Gianfranco Lanci explains why he expects to soon overtake No. 2 PC maker Dell

    via Acer Boss Lanci Takes Aim at Dell and HP - BusinessWeek.

    Today Acer CEO and President Gianfranco Lanci resigned with immediate effect. Acer is in trouble. You can read more on Acer's current problems in the wake of the downward revision of its sales targets for two quarters here: Acer Should Overhaul Its Operation: Stan Shih | CENS.com - The Taiwan Economic News

    In a nutshell, whereas Acer under Lanci took aim at Dell and HP, it seems that Apple took aim at Acer. And whereas Lanci missed, Apple's aim was true.

    What is interesting here is that Acer had a very disruptive approach. They used the low end "netbook" concept to take share from incumbents motivated to move up-market.

    But what went wrong? Part of the answer is that "low end" does not just mean "cheap". Low end disruption is about also offering simplicity and performance along a new dimension or trajectory of improvement.

    Mobile computing could not be implemented as a low-end strategy because the modules available to portable computing could not be used to make it expand into new contexts of consumption. Windows and keyboards and all the input methods associated with portables could not be adapted to mobility. You could not use a netbook in places or at times when you did not use any other laptop.

    In addition the business model was not a good match. Low margins could not support development or new integration that could improve that which was not good enough. Acer did not have the means to tackle the problems of not-good-enough mobile computing. They did not build software and low margins meant that they could not even try to build software.

    Competitors also were motivated to respond. HP and Dell built their own netbooks which, arguably, were just as good (or, perhaps more accurately, just as bad) as Acer's. But more problematic was the fact that regular notebook prices dropped to netbook levels and the category came to mean "cheap" not "convenient".

    Finally, Acer's strategy did not have the time horizon necessary for true disruption. It takes many years to polish a product and nurture it up the trajectory. Acer was too impatient for growth and not patient at all for profit.

    Contrast this with Apple's tablet strategy:

    • It dealt with complexity of computing by removing it. This was not easy as simplification required a new platform altogether--something that portable computers could not benefit from.
    • It priced low but held on to margins because removal of complexity also reduced cost
    • The margins allow it to rapidly iterate on integrated development and improve the product
    • Competitors initially were not motivated to respond. They did not have the tools at hand to respond: no integrated operating system for PC vendors, no distribution for phone vendors.
    • Apple is also patient enough to wait for several product cycles. Even though demand is astronomical, the iPad still has a long way to go to become a new computing standard. Time is on Apple's side.

    Apple is effectively disrupting the PC with asymmetry. It contrasts with Acer's reliance on a sustaining, symmetric approach. The market was showing clear signs of over-service, declining margins, in-absorbable features and performance and complexity.

    Calling the winner in 2009 may have been tough given no iPad was visible, but knowing Apple's resources, processes and motivations should have guided observers to the right answer.

  6. The Post PC era as explained by developer events

    Research · 38 comments

    The World-Wide Developer Conference is an event for developers. It is not a trade show and it is not a consumer show or an enterprise show for salespeople. Except for the keynote, all events are subject to Non-disclosure Agreements so it's not even an event whose proceedings can be discussed openly.

    It's also expensive. Registration is at least $1,500. Attendants are there to learn and ask detailed questions about development. It's not for deal making. People not familiar with development would not be well served by the event. Registrations are therefore somewhat limited to about 5000.

    After the iPhone SDK was launched, the WWDC took on a new dimension. It became a mobile development event. As a result, 2008 was the first year when WWDC sold out. Attendance tripled over the Mac-only event the previous year.

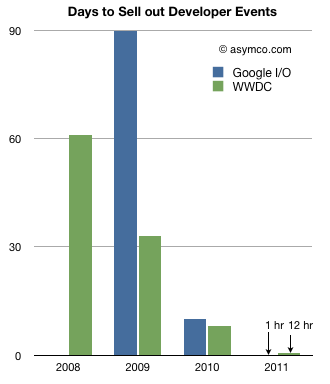
    Every year since, not only has WWDC sold out but it has sold out quicker every time. The following chart shows the days it took to sell out WWDC. I also added Google I/O data for comparison.

    In the era of the iPhone, the limited resource of attendant seats has always been exhausted at accelerated rates: from 60 days in 2008 to 0.5 days in 2011. A similar pattern emerged for the Android event.

    What should be noted is that these events are focused on post-PC development[1][2]. Clearly the increased interest among developers is for the mobile side of the business.

    Developers certainly seem to sense the way the wind is blowing. They are, as humans, prone to over-confidence but they are also often accused of being hard to please. The most common lament among new platform builders is "How do we attract developers?"  The platforms showcased here had no trouble attracting developers in the tens of thousands three years after being launched.

    The Post-PC era is evident in all kinds of data. This set (developer attendance to mobile development) is particularly stark. It's a proxy for investment and IT interest. There is a non-linear nature to this growth and history shows that non-linearity leads to unpredictable or unforeseeable change.

    ---

    Notes:

    1. WWDC still has Mac OS X tracks but that track was there pre-2008 and did not sell out the event.
    2. Microsoft hosts several developer events (PDC, MIX, and Tech·Ed) some of which also sell out, but they have a far wider focus.
  7. Analysts: Apple's growth next year to drop to half of what it could obtain during the recession

    Research · 72 comments

    Apple is having difficulty meeting demand for the iPhone and the iPad. It is growing both businesses at more than 100% and they make up about 65% of revenues, and 71% of profits. The Mac business is also growing at 2x to 3x the PC industry.

    Being supply constrained makes it therefore a great challenge to forecast future growth for the company. Supply issues and ramp rates are needful of an operational expertise few possess outside of the industry. But many take up this challenge, myself included. We put up our numbers every quarter and get scrutinized and challenged for our failures.

    So it's always exciting to see how others are looking at the big picture. Sadly, with the growth data being what it is, there seems to be a great deal of pessimism around the company's prospects. The P/E ratio has remained at despondent levels for over two years, barely tracking with the P/E of the S&P 500 and not reflecting the company's historic or current growth.

    The logical explanation is that pricing reflects a consensus that growth will fall off a cliff. Indeed this can be confirmed. Bloomberg surveyed analysts and they say:

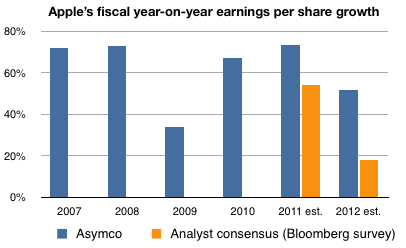
    Apple’s sales may climb 54 percent to $100.3 billion this fiscal year, which ends in September, the average prediction of analysts surveyed by Bloomberg. Growth may slow to 18 percent the following year.

    Fifty percent growth this year and 18 percent next year is indeed catastrophic. Consider the company's recent history as shown in the following chart:

    The company has been growing earnings around 70% a year since 2007 at least. The exception being 2009 when in the middle of the worst recession for a century the growth dropped to 34%.

    I took the liberty of adding the estimates cited above to the chart (in orange) while putting forward my estimates for the same time frame.

    I am, I believe, conservative in my estimates (for example, my estimates do not take into account any new product categories Apple may launch). But the prospect of 18% growth for the fiscal year beginning this October is quite hard to justify knowing what I know about the markets Apple competes in. As I've amply described in this blog, the mobile computing (aka post-PC) shift is underway and Apple is leading the charge. The prospect of billions of unserved customers beckons and Apple is crushed with demand.

    But let's not quibble about billions of desperately underserved consumers. The thing that sticks out from the chart is that analysts are forecasting growth about half of what Apple was able to achieve in 2009--a time when consumer spending practically stopped world-wide and there was talk of another depression.

    Either they're in agreement that we're in for something resembling a global plague starting in six months or they believe Apple is singularly positioned to drop the ball.

    I would love to hear some these scenarios defended because I see no evidence for either.

  8. On Feeds and Speeds

    Research · 54 comments

    And a lot of folks in this tablet market are rushing in and they're looking at this as the next PC. The hardware and the software are done by different companies. And they're talking about speeds and feeds just like they did with PCs

    Steve Jobs, iPad 2 launch event March 2011.

    I'm not above doing a feeds and speeds comparison.

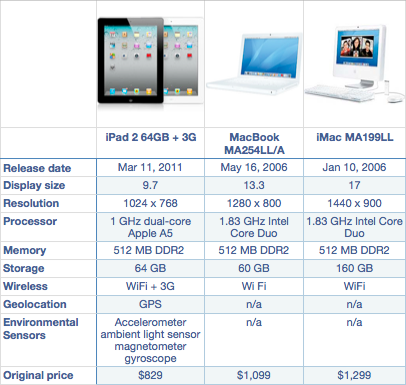
    All the products above have dual core processors, 512 MB of memory. The iPad processor is a bit slower. The iPad also has a slightly smaller resolution screen than a MacBook from mid 2006. However, unlike the others, the iPad has cellular broadband connectivity, loads more sensors, and a battery that will last at least 5 times longer.

    It's also a lot cheaper and a lot smaller.

    Although five years old, nobody would question that the MacBook or iMacs shown above are still computers. They still run the latest versions of OS X and are probably still in widespread use.

    The new iPad is still not considered a computer by the majority of market analysts. One wonders how long this will go on. The specs of the iPad are just going to keep getting better...

  9. What's a Post-PC device?

    Research · 86 comments

    Microsoft's Steve Ballmer argues that the tablet computers (aka slates, media tablets or iPads) are PCs. Steve Jobs argues that they are post-PC devices. There are analogies to trucks, cars and various metaphors for what these new devices symbolize. Some argue that because the iPad needs a PC, it's not a post-PC device.

    But how to define a new generation of computing? Since the PC is not the beginning of computing, it may make sense to look to the eras of computing that preceded it.

    The first post-mainframe computers worked alongside mainframes and were typically used by engineering departments (vs. the finance and accounting departmental role occupied by mainframes.) They did not require a dedicated (often external) mainframe service team and could be administered by in-department system administrators. Input was not through dedicated data entry personnel and output was not a ream of folded paper. Users could use a CRT terminal to interact with the computer directly. Digital Equipment Corporation, Control Data, HP, Honeywell, Prime, et. al. grew up in the shadow of IBM but thrived. Their products were cheaper and simpler to operate. Initially, the products were not more powerful.

    The first post-minicomputer microcomputers (also known as PCs) were used alongside mainframes and mini-computers. They were typically used for 2-dimensional spreadsheets analysis by individuals in many departments and were easier to justify cost-wise than the time-sharing cost structure of the incumbent computers. Many microcomputers were able to access mini-computers and mainframes through terminal emulation software (and sometimes special hardware boards) so they were still able to work with existing business processes. They did not require dedicated personnel for administration but had a shared support department. Input and data storage were on the "desktop" as was printing. Compaq, Dell, HP, Apple and IBM embraced this new form factor. Their products were cheaper and simpler to operate than the previous generation of computers. Initially, the products were not more powerful.

    The first post-microcomputer tablets are used alongside microcomputers for tasks such as presentations and entertainment. They have software available that allows access to desktop computers and services dependent on PC-architectured servers. They depend on PCs for data backup and software updates. They do not require IT support. They do not require a keyboard or a desk. Apple and many mobile phone vendors are embracing the new technology. They are cheaper and simpler to operate. The new products are not more powerful.

    To define a new generation of computing by its isolation and exclusion of the previous generation is not sustained by the history of computing.

    I would suggest that the definition of a new generation of computing is that the new products rely on new input / output methods and allow a new population of non-expert users to use the product more cheaply and simply.

    I might add that the consequences of each generational shift are:

    1. Consumption increases
    2. Skill required decreases
    3. Support required decreases
    4. There are new applications and use cases
    5. The economics are not favorable for incumbents
    6. The economics are favorable for new entrants
    7. The older generation slowly fades through diminished growth but never disappears
  10. Flummoxed, again

    Research · 184 comments

    The last time I took a snapshot of the iPad death watch it was March 9th, 2010. Almost a year ago. The now-classic quotes are reproduced here.  Last May I wrote:

    Apple keeps a tight lid on new products so that competitors don’t get a head-start on copying, but in the case of the iPad, advance knowledge would not have had any impact. Competitors look at the iPad and see nothing.  They’ll only react once the market explodes and they start to feel belated pain.

    I thought that would be that. As the success of the product would become self-evident, predictions of imminent demise would trail off. The pain of share loss would prompt a wave of challenger copycats. Imitation would be the the best form of flattery.

    But no.

    Critics were not silenced. One year, 15 million units, and $9.2 billion later I went back to the source of the quotes and found the following (published quotes dated after March 9th 2010). (Cited from aaplinvestors.net with some editing for brevity and relevance):

    “Problematically, the Android competition is just as expensive as the iPad lineup, so Apple obviously feels free to continue gouging consumers on iPad pricing.” Paul Thurrott, Windows IT Pro, 3 March 2011

    “Apple’s iPad 2 might be ‘magical’ but it still should’ve been better ... It needs more G’s. It’s still just a toy” Zach Epstein, Boy Genius 2 March 2011

    “11 reasons NOT to buy an iPad 2 ... Reason 5: Competition David Gewirtz, ZDNet, 23 February 2011

    “Given what I’ve seen of Honeycomb and Motorola’s excellent tablet, Cupertino will have some serious catching up to do with their iPad 2.” J.P. Mangalindan, Fortune, 4 February 2011

    “We very carefully chose our tablet processor, the Nvidia Tegra 2, and to really compete it will take [Apple] some time. You know, [Nvidia] is well known for graphics.” Jonney Shih, Asustek Computer, 3 February 2011

    “If you were to ask me in two years time, will Apple have less than 50 percent of the global tablet market, I think that’s a certainty. Neil Mawston, Strategy Analytics, 31 January 2011

    “We have an extreme focus on the innovation of LePad and LePhone because these products will dominate the future market. Though Apple is winning a significant share in the Chinese market, it has not gained a clearly leading position yet. Our advantage is we know this market better.” Liu Chuanzhi, Lenovo, 27 January 2011

    “The iPad may still be the lone leader, but with 100+ competitors on the way, it won’t likely keep its majority market share unless the pending next generation iPad really addresses all the complaints about the current version, like a missing camera and a lack of a USB port, and the company has to add those features without a major price increase - a tall order, to be sure.” James Brumley, Investopedia, 13 January 2011

    “Hands-on PlayBook demonstrations at CES showed its differentiation in multitasking and performance, which may be difficult for Apple/Android to rival.” Mike Abramsky, Royal Bank of Canada Analyst, 11 January 2011

    “Apple Inc.’s popular iPad is getting its strongest competition thus far as consumer-electronics manufacturers unveil tablet computers with bigger screens, front-facing cameras for video chatting and more.” Rachel Metz, AP Technology Writer, 3 January 2011

    Apple may be simply trying to get in ahead of Research in Motion’s aggressively priced PlayBook or combat the early success of Samsung’s Galaxy Tab.” Rick Aristotle Munarriz, The Street, 29 December 2010

    4. Competitors are coming. Brett Arends, Wall Street Journal, 22 December 2010

    Reason 6: WiFi is still unreliable David Gewirtz, ZDNet, 16 December 2010

    “I can’t imagine anyone under the age of 30 wanting an iPad. A PS3, Wii, GameBoy, or even a useful laptop maybe, but an iPad? Furthermore, I do not recall ever seeing anyone under 30 actually using an iPad.” John C. Dvorak, PC Mag, 13 December 2010

    “We hope our tablet PCs can reach a global market share of 10-20% initially, and become the market leader in two to three years.” Gianfranco Lanci, CEO and President, Acer, 26 November 2010

    “It’s a nice-to-have product, for those of us who don’t have a budget, but is it a must-have product? I don’t think so.” Ashok Kumar, Analyst, Rodman & Renshaw LLC, 12 November 2010

    “Steve Jobs never says anything without thinking through it carefully. But I think in this case he may be a little afraid of this category. And he’s finding whatever he can to attack because he sees [seven-inch tablets] as a challenge to the dominance of the iPad.” Adam Hanin, VP Marketing, Viewsonic, 1 November 2010

    “There could literally be millions of first-generation iPads gathering dust in people’s home offices already. This product is the tech industry’s biggest MacGuffin yet.” Paul Thurrott, Windows IT Pro, 23 October 2010

    “I cannot see a need for the thing.”John Dvorak, MarketWatch, 22 October 2010

    ”For those of us who live outside of Apple’s distortion field, we know that 7″ tablets will actually be a big portion of the market and we know that Adobe Flash support actually matters to customers who want a real web experience.” Jim Balsillie, Research In Motion, 20 October 2010

    “iPhone and iPad have been amazing products that have opened new markets. But I do not think they will own either market in a few years. Android will.” Fred Wilson, AVC.com, 18 October 2010

    “The constant search for an ‘iPad killer’ and the sheer multitude of tablet computers launching in the next 18 months should make Apple aware that its competition is fierce and will only become tougher.” Barbara E. Hernandez, PCWorld, 5 October 2010

    “HP’s New Tablet Could Be an iPad Spoiler HP’s decision to bundle a tablet computer with its new $399 printer could make trouble for competitors.” Cliff Edwards and Aaron Ricadela, Bloomberg Businessweek, 23 September 2010

    “Our tablet will be better than the iPad.” Chang Ma, VP Marketing, LG, 20 August 2010

    “Not only is Apple typically lost in the enterprise, but it focuses very little of its time there. And with a new, potentially more compelling tablet coming — the Cisco Cius — the iPad’s success in the corporate world could be short-lived. Here’s why:... 10 The power of Windows” Don Reisinger, Channel Insider, 5 August 2010

    “I don’t think there is one size that fits all…I’ve been to too many meetings with journalists who spent the first 10 minutes of the meeting setting up iPad to look like a laptop.” Steve Ballmer, Microsoft, 29 July 2010

    “ [...] It still isn’t the device that I’d take to a meeting because it has no input.” Bill Gates, Microsoft, 2 June 2010

    “Which means I end up on the iPad — and tablets more generally — where I started. Tablets will not create a new category, but will supplant (or merge with) one or more of the current substitutes: smartphones or netbooks.Here I am less optimistic about the iPhone and webOS than I am about Android. ” Joel West, professor of Innovation & Entrepreneurship, College of Business at San José State University, 30 May 2010

    “The iPad is useless. Beautiful, but useless. The iPad is too heavy. It’s awkward to hold and view in public. It’s fragile. It requires expensive accessories to protect it and extract more functionality. ”Josh Belzman, MSNBC.com, 20 May 2010

    “Mum, the iPad is not ‘amazing.’ It’s just marketed very well, both by Apple and its culpable partners in mainstream media. ” Paul Thurrott (in response to comment by Mum), Paul Thurrott’s Super Site for Windows, 26 April 2010

    “In short, I don’t get the ‘magical and revolutionary’ vibe that Apple chief executive Steve Jobs touted at the iPad’s January unveiling.” Rob Pegoraro, Washington Post, 9 April 2010

    “The first troubling sign is the fact that you can still get an iPad today. They didn’t sell out. The pure slate form factor has failed all these years because, other than for vertical applications, people want and/or need a keyboard for regular use. The fact of the matter is that a touch screen or bluetooth keyboard just doesn’t compensate.” Jonathan Yarmis, Ovum, part of Datamonitor Group, 6 April 2010

    “I don’t get it. It costs $500 for the basic model, when you could get a laptop with a lot more functionality for about the same price. The iPad hype machine has been in full effect this week, and I still think it’s just that—hype. ” Alex Cook, Frontier Outlook, 3 April 2010

    “As far as what this means to Apple, one thing to keep in mind: Even if the iPad sells more than the iPhone did in its first year, it’s still only around 5% of the company’s revenue. So it’s a very small slice. From there, it probably doesn’t grow as large as the smartphone market. So, if you’re buying under rumors, keep perspective in mind. The iPad’s a great product, but it’s probably not a game-changer.” Eric Bleeker, Analyst, Fool.com, 31 March 2010

    “The iPad will remain an expensive, niche device compared to all-purpose netbooks.I think that one of the iPad’s most important uses will be for reading ebooks and publications. Even so, though, when it comes to the marketplace, netbooks will sales still far outstrip those of the iPad.” Preston Gralla, PC World, 30 March 2010

    “Don’t Believe the iPad Hype. Apple has sold out pre-orders of the forthcoming device, but it could all be a marketing tactic. By not manufacturing enough iPads for the initial launch date, is this a case of Apple shooting itself in the foot?” Mike Schuster, Minyanville.com, 29 March 2010

    “‘iPad Killer’ May be Palm’s Last Hope”Tom Bradley, PC World, 20 March 2010

    “Even if your company has relented and now supports the iPhone, as growing numbers of businesses do (70% of the Fortune 100 are at least testing it, says Apple) you’ll want to say “No” to the iPad and other tablets. Here’s why: 8. Speaking of money, there is no money in the company budget to pay for iPads. 9. Not supporting iPad will be the enterprise norm. Robert McGarvey, CIO Update, 16 March 2010

    “This morning, the fool’s parade gets started. Apple is taking online “pre-orders” for its iPad tablet, which is supposed to begin shipping on April 3. Buying a new kind of product sight unseen is foolish. Especially given how mysterious Apple has been on what the iPad can do and what restrictions on capabilities and media access it will place on users and content providers.” Galen Gruman, InfoWorld, 12 March 2010

    “The recent launch of Apple, the iPad tablet, has won the award for the second edition of Fiasco Awards delivered this Thursday in Barcelona. From the more than 7,000 people who voted via the website www.fiascoawards.com, 4,325 have considered it the fiasco of the year. Fiasco Awards, 2010, 11 March 2010

    “I think I’ve mentioned this once or twice before, but it bears repeating until it sinks in: the Apple iPad is not unique, nor necessarily the best of breed in the media tablet sector it is spearheading. And it ain’t gonna help Apple shareholders any.’” Anders Bylund (TMF Zahrim), 11 March 2010

    From this critical review, it looks like 2011 will indeed be the year of the iPad 2.

  11. In memoriam: Microsoft's previous strategic mobile partners

    Research · 223 comments

    Microsoft's new "strategic partnership" with Nokia is not its first. For a decade the software company has courted and consummated relationships with a variety of companies in mobile and telecom. Here are the ones I can remember:

    • LG. In February 2009 Microsoft Corp. signed a multiyear agreement for Windows Mobile to be included on devices from LG Electronics Inc. LG would use Windows Mobile as its "primary platform" for smartphones and produce about 50 models running the software.

    What happened? LG made a few Windows Mobile devices but with WinMo uncompetitive, they abandoned the platform and moved to Android losing years of market presence and all their profits.

    • Motorola. In September 2003, Motorola  and Microsoft announced an alliance. "Starting with the introduction of the new Motorola MPx200 mobile phone with Microsoft Windows Mobile software, the companies will collaborate on a series of Smartphone and Pocket PC wireless devices designed to create a virtual "remote control" for the Web-centric, work-centric, always-on-the-go mobile professional." In addition, the alliance includes cooperation on joint marketing and wireless developer programs.

    What happened? Motorola launched a series of Windows Mobile phones culminating in the Motorola Q "Blackberry killer". As Motorola hit the rocks in profitability new management reached for the Android liferaft. The company now relies exclusively on the Droid franchise.

    • Palm. In September 2005 Palm and Microsoft announced a strategic alliance to "accelerate the Smartphone market segment with a new device for mobile professionals and businesses. Palm has licensed the Microsoft Windows Mobile operating system for an expanded line of Treo Smartphones, the first of which will be available on Verizon Wireless’ national wireless broadband network."

    What happened? Palm shipped a few Windows Mobile, famously dismissing Apple's potential entry as something "PC guys" could never achieve. A new CEO, a private placement and an acquisition later the company is a division of HP making its own operating system.

    • Nortel. When Steve Ballmer was famously laughing at the iPhone and saying that he likes the Windows Mobile strategy "a lot" he was sitting next to the then-CEO of Nortel (Mike Zafirovski formerly of Motorola) with whom the company had just closed a strategic deal.  "an alliance between Microsoft and Nortel announced in July 2006 ...  includes three new joint solutions to dramatically improve business communications by breaking down the barriers between voice, e-mail, instant messaging, multimedia conferencing and other forms of communication".

    What happened? Nortel declared bankruptcy two years later.

    • Verizon. In January 2009 "Verizon Wireless has selected Microsoft Corp. to provide portal, local and Internet search as well as mobile advertising services to customers on its devices. The five-year agreement will go into effect in the first half of 2009 when Microsoft Live Search is targeted to be available on new Verizon Wireless feature phones and smartphones." The deal would ensure Bing distribution to all of Verizon's smartphone customers.

    What happened? Bing did ship on some devices but in October 2009 Droid came to Verizon.

    • Ericsson. In September 2000, "Ericsson and Microsoft Corp. today launched Ericsson Microsoft Mobile Venture AB. This previously announced joint company will drive the mobile Internet by developing and marketing mobile e-mail solutions for operators. The first solutions are expected to be on the market by the end of the year. The company is part of a broader strategic alliance between Ericsson and Microsoft"

    What happened? Ericsson divested itself of the mobile division forming a joint venture which would go on and make more strategic alliances with Microsoft over Windows Mobile culminating in a loss of profits and eventual flight to Android.

    • Sendo. In February 2001, Microsoft announced a partnership, in which Microsoft bought $12m of Sendo shares and a seat on the board. Sendo was to be Microsoft's "go to market partner" for the Stinger smartphone platform that would become Smartphone 2002.

    What happened? Sendo after litigating IP issues with Microsoft went bankrupt in 2005.

    And finally,

    • Nokia. No, not this OS deal, but in August 2009 "The worldwide leader in software and the world’s largest smartphone manufacturer have entered into an alliance that is set to deliver a groundbreaking, enterprise-grade solution for mobile productivity. Today, Microsoft Business Division President Stephen Elop and Nokia’s Executive Vice President for Devices Kai Öistämö announced the agreement, outlining a shared vision for the future of mobile productivity. This is the first time that either company has embarked on an alliance of this scope and nature."

    The plan was to bring "Microsoft Office Mobile and Microsoft business communications, collaboration and device management software to Nokia’s Symbian devices."

    What happened? One and a half years later the same Stephen Elop announced that Symbian will be deprecated.