The world's largest PC company just launched a "media tablet[1]". Conflating the iPod Touch and iPad brands into "TouchPad" HP joins RIM in announcing an integrated OS/device product to compete as a platform vs. iOS and Android (and to some degree even against Windows).
There are others waiting in the wings. Presumably, Microsoft is hard at work to release a tablet-compatible Windows sometime near the middle of this decade. MeeGo is also going through its gestation period targeting Atom-based tablets. John Gruber notes the excitement around tablet platforms in his article about this post-PC renaissance in computing alternatives. I also noted that the end of the PC era was marked by the end of WinTel at CES.
In that context, yesterday's WebOS event was perhaps anticlimactic. But it's still remarkable. Consider how far we've come. Step back now and remember the dark days only one year ago when, right after the iPad announcement, a nearly unanimously chorus was pouring derision on the concept.
AAPLinvestors is still maintaining the iPad death watch which I took a snapshot of back in March 2010. To reminisce: It was exactly one year ago, on Feb. 10th 2010, that Bill Gates was quoted as saying "It’s a nice reader, but there’s nothing on the iPad I look at and say, ‘Oh, I wish Microsoft had done it.’" On the same day, Shannon Zimmerman of The Motley Fool wrote: "[Apple's] hamster-wheel of innovation ... may have hit a snag with the iPad." Those are just two of dozens other memorable quotes.
I noted last May that the secrecy surrounding the iPad prior to launch was unnecessary. Nobody understood the product for months after it launched (and many still don't a year later).
Apple keeps a tight lid on new products so that competitors don’t get a head-start on copying, but in the case of the iPad, advance knowledge would not have had any impact. Competitors look at the iPad and see nothing. They’ll only react once the market explodes and they start to feel belated pain.
Indeed, responses only came after sales figures started to cause consternation among competitors.
How did these presumably keen observers of the market fail to notice the sea change under way? This is not just a rhetorical question. It really is hard. Students of disruption know that spotting such change is a difficult skill to obtain. But it is a skill, not a gift.
So here we are, 12 months later and the derision has turned to flattery by imitation. The only scorn I hear about the TouchPad is that it can't come to market fast enough.
----
I find this term repugnant and highlight it here only to ridicule those who coined it.
People are lining up to call the market for mobile phones. Analysts and amateurs alike are connecting points on charts and predicting with confidence the future of mobile platforms. Consensus is forming that there is no future but a quiescent state. By the acclamation of pundits, the survivors are declared to be iOS and Android. They are also predictably arranged in a way similar to OS X and Windows. End of story.
Except for one thing.
3.5 years ago neither of these platforms existed. In fact, it was only two and a half years ago, in mid 2008, that one of the finalists even became a platform with the launch of an app store. The other "winner" only launched in a handset later that year and had no significant volumes until a year ago. In other words, these suddenly predictable platforms have been in existence for less than the life span of one device that runs them.
To point out how extraordinary this claim is, if we look back to the history of computing, could we have declared the PC industry future cut and dried in 1978, two years after the founding of Apple? What about 1983, two years after the emergence of the IBM PC? What about 1986, two years after the Mac? Or maybe 1990, after Windows was born? Maybe the writing was on the wall in 1997, two years after Windows 95 caught up with the Mac's UX. That would be 21 years after Apple's founding. Some would argue that even today the story of desktop or portable computing is far from over.
Sure, times have changed. Things move much faster now. But markets are also much bigger and take a long time to penetrate. Mobile channels are bounded by provincialism and parochialism.
What's more, it's not like there haven't been platforms before these two upstarts came along. I've seen 9 mobile platforms in 9 years (PalmOS, Windows Mobile, Symbian, Java, WebOS, Windows Phone, iOS, Android, RIM Blackberry). New platforms are still emerging and evolving (e.g. MeeGo, Bada, LiMo, QNX and Tapas).
So the existential question is this: If you were to draw a time line, would a mark in early 2011 signify the end of mobile platform history? The point in time when unforeseeable change will cease to happen?
Let me offer a hint as to why not: every major platform battle has been sparked by an innovation built around a new input method. The keyboard integrated into a personal computer in the 1970s, the mouse in the 1980s, the stylus in the 1990s and the fingertip in the 2000s. Each of these input methods created new platforms (DOS/Apple ][, MacOS/Windows, PalmOS/Windows CE, iOS/Android), new ecosystems, new industries, new competitors and new platform battles designed to enrich forecasting pundits. I won't even try to go back to the changed in the half century of computing prior to the PC.
So here's my challenge to the prognosticators: If you are willing to draw a line in the calendar now and say that no input methods will ever emerge in mobile computing after this point in time I'll buy the thesis that it's over and we can count our chips.
If you think that out of the hundreds of user experience patents being filed, and hundreds of prototypes being slaved over in labs throughout the world, not a single new product will emerge with a new way of interacting with a computing device, then it's time to move on to something other than what can be declared a commodity market.
But if you believe that, as happened four years ago, a new input method, previously only in the realm of mockups and movie magic, suddenly was shown, in a working product, on stage, then this business still has a chance of staying interesting.
‘Any argument that a pad is not a PC is simply out of sync,’ said Chiam. ‘With screen sizes of seven inches or above, ample processing power, and a growing number of applications, pads offer a computing experience comparable to netbooks. They compete for the same customers and will happily coexist. As with smart phones, some users will require a physical keyboard, while others will do without.’
‘Each new product category typically causes a significant shift in market shares,’ said Chiam. ‘Apple is benefiting from pads, just as Acer, Samsung and Asus previously did with netbooks. The PC industry has always evolved this way, starting when Toshiba and Compaq rode high on the original notebook wave.’
Five years ago, back when Gartner and IDC were confused about what a smartphone was Canalys was on top of the market and was the first to correctly describe the smartphone.
Kudos for being first again to recognize a re-defined market.
Apple set a new record for Mac sales in the fourth quarter. This was not a surprise. The growth was perhaps a bit lower than some expected (including me) but it was still a healthy 23% and 8x the PC growth rate. The Mac has outgrown the PC (and hence has gained share) for 19 quarters straight, nearly five years.
What's more interesting is where the growth came from. Every region outgrew the market. Asia-Pacific led with a 67% year-over-year increase, almost 10x the market. Japan grew at 56%, which is about 6x the market, and Europe and the United States both grew in double-digits despite both markets contracting overall.
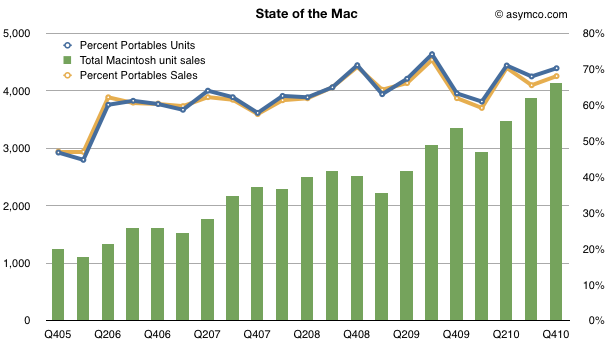
Looking over a longer time frame, the Mac has nearly quadrupled in volume in five years. In the last quarter of 2005, Apple sold 1.2 million units. In the latest quarter it sold 4.1 million. So the performance has been relatively good.
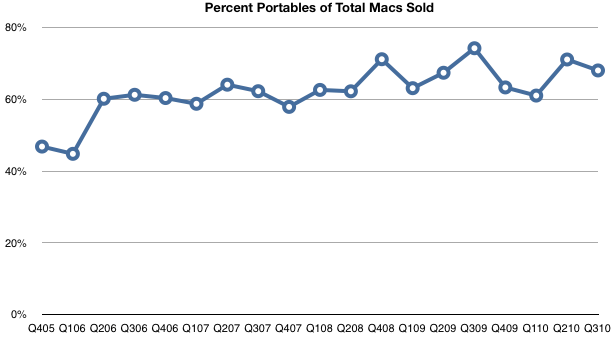
One significant reason for the growth has been the shift from desktop to portables. The lines show how the percent of portables went from about 50% to 70% of units and sales in four years.
[hang1column]
[/hang1column]
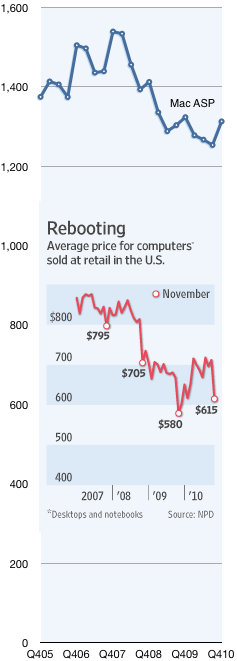
But what was surprising was that the average selling price increased to $1,313, up from $1,253 and nearly even with last year's $1,324.
Prices in the PC industry tend to fall. Actually, to be more precise, they tend to collapse. Compare the Mac's price trend with the rest of the industry as seen in the chart to the left[1]. It shows the Mac Average Selling Price which is what Apple books from selling into the channel vs. the retail price of PCs in the US.
The chart tells a partial story. The PC figures are retail while the Mac figures are wholesale. Furthermore, the PC figures include Mac, so stripping out the Mac would show the PC prices to be even lower. Lastly the Mac figures are global whereas the PC figures are US only.
But what I want to focus on is not the absolute difference, rather the relative value difference, which is diverging: The average PC went from $795 retail at the end of 2007 to $615 in November 2010. That's a drop of 22%. In the same time frame the Mac went from $1,539 to $1,313 wholesale, a drop of 15%.
In other words, the Mac price premium at the end of 2007 was at least 93% and it now is at least 114%.
So here's the real surprise: How does the Mac gain share while increasing its price premium over the PC?
The only answer I can offer is what I already wrote on the Mac in November:
...something changed with PCs when the laptop became “good enough”. With portable computing, the job the PC was hired to do evolved. It was more important that the product be well designed (for aesthetic value, usability and reliability) than just fast and spacious. The microprocessors were plenty fast but what mattered more was low power consumption, a low profile and tighter integration with software.
In other words, computers became re-integrated. You only need to touch the MacBook Air to understand why.
----
Notes:
The inset chart comes from The Wall Street Journal using data from NPD. The Mac data comes from Apple financial reports.
Since I spend most of my time thinking about what will happen, at the end of each year, rather than looking forward I like to look back to see how wrong I've been. The great thing about being wrong is that you learn something. Especially if you use a foundational theory to tie concepts together. Theory building is all about finding anomalies that adjust and improve it.
Fortunately, exactly one year ago, on December 30 2009 I wrote an article asking if Android was disruptive. It turned out to be the right question to ask for 2010.
What have I learned since?
My main argument in late 2009 was aimed at the reaction of the recently launched Nexus One. A product hailed as disruptive to mobile operators. I did not see it that way. In that respect I was right. The distribution juggernaut any phone platform faces stopped the Nexus One dead in its tracks.
I wrote:
Here’s the problem: since mobile broadband is by all accounts not good enough, it cannot be disrupted. Operators are very critical in building out this new mobile computing future and they are investing and will reap rewards. Bitpipe models will only emerge after 4G when there will be ubiquitous high speed networks and competition will shift away from coverage and more to price and convenience of plans.
What is happening instead of operator disruption is that mobile voice which is more than good enough is being disrupted. Businesses built around mobile voice (e.g. handset vendors who have not developed a viable business model around data) will simply evaporate and their profits will condense around entrants who have mobile computing platforms.
So the operators are as strong as ever. But the Android platform lived to fight on, regardless of the Nexus one. And it grew in ways I did not anticipate. I had expected integrated players to maintain a large share because they would be able to improve the product more rapidly than modular vendors (and assuming that the product needed improving).
Google is moving on this opportunity but they are not executing in a way that ensures they control the future platform due to the their being on the wrong side of the modular/integrated dichotomy.
So Android grew but it's not yet creating profits. It is perhaps laying the foundation for future profits and defending existing profits for Google but it is not yet a big profit center[1]. That is a cause for worry. Disruptors need to be hungry for profits and patient for growth.
I concluded:
Android will disrupt but I expect it will take 10 to 15 years. The life cycle of a new global network generation rollout is about 10 years. We’re in the middle stage of the 3G cycle that traces its beginnings to early this decade. 4G will take another 10 years.
Given what's happened this year does this forecast still hold?
Mainly yes. I stand by the notion that operators will be in the driver's seat for a few years to come. However Android has grown in an unexpected way: adoption by unbranded or relatively unknown vendors selling in emerging markets.
The Grey (market) Elephant in the room
Until 2010, it was very difficult to sell a phone without a recognizable brand. This is because brands helped overcome purchase anxiety for those buying a device for the first time. Brands mean trust and the lack of brand meant risk. Those who cannot afford to make purchase mistakes are more likely to lean on brands than the affluent.
But 2010 has seen a shift away from device brand value and more toward platform and function value. This shift was largely unforeseen and is very disruptive.
All those vendors are likely to adopt Android and in doing so will explode the low end of the market. They may even crush the branded voice-oriented market.
This growth can be slowed by operators but market forces will be very strong. These devices sell in grey markets and are often unlicensed, unbranded, untaxed and unregulated (and may even be illegal due to the absence of IMEI numbers).
So this is the real wild card for 2011: unbranded devices running Android could be the PC clones of the post-PC era. Will this phenomenon last or will the brands fight back? If they fight, the only weapon they could wield is innovation.
---
[1] Mobile efforts at Google are generating over $1 billion in revenues per quarter however these efforts include various other assets including AdMob which was acquired for $750 million. Furthermore, the headcount for Android and these other efforts is not small. I've heard as many as 3000 people are devoted to Google's mobile efforts.
When reading the comments disputing the possible end of the voice-phone era I'm reminded of similar comments disputing the end of the PDA era.
Although the Apple Newton pioneered the market in 1992 and John Sculley came up with the acronym, the Newton did not sell in significant volumes. It wasn't until 1997 with the Palm Pilot that the PDA market took off. Microsoft quickly followed with a licensed OS based on Windows CE. In 2001 Microsoft launched the Pocket PC brand to cement its attack on the PDA market. The first phones using a Microsoft OS were using something called Pocket PC Phone Edition. The first Nokia smartphones (Communicators) were built like mobile PDAs.
The logic was quite compelling. The original PDA was built to mobilize contacts, calendars and notes. They replaced bulky paper organizers and seamlessly synced to PC productivity software like Outlook. It was a compelling product in the US where small business customers needed to keep track of hundreds of contacts. Users could even 'beam' contacts to each other via infrared. The idea of adding a phone function to the device made sense insofar as contacts could be immediately dialed from the contact app rather than typed into another device's phone keypad.
By the early 2000's PDAs were forecast to sell by the hundreds of millions. There were millions of dedicated users who downloaded apps and thousands of developers being courted by platform builders. Palm even invented the word "ecosystem" as it refers to mobile platforms.
However, I remember reading sites dedicated to this community and there were many people who rejected the concept of a PDA with an integrated mobile phone. They liked the fact that the PDA was not bundled with a phone plan. They upgraded PDAs in a different cycle from phones and besides, phones are for talking and PDAs were for something else. It was even more difficult to justify the conflation of the two products when considering the corporate purchasing of PDAs. PDAs were procured by IT departments and phones came with contracts that were managed by a different department.
What's a device vendor to do? The most avid customers of PDAs did not like the idea of burdening the product with a phone. RIM was doing its thing with moving pagers to include voice, but that was a different job to be done. The story is picked up here by this comment:
I was hired by RIM in 1999 just before they began work on their first phone .... Coming from a two-way pager background, RIM decided that phones should have two-way push synchronization of pretty much everything that Exchange provided along with a limited WML browser. The general thought was that phones would never have sufficient power density or radios sufficient bandwidth to allow anything more. That was incredibly predictably wrong, but it's how things went down.
Along with RIM was Ericsson, Palm, Motorola, and Qualcomm. Motorola came from a similar background as RIM and went on to build very similar devices. Both Nokia and Ericsson had come from phones and had decided feature phones should have far more sophisticated PDA functions. Palm started with PDAs then moved to the phones, but adamantly dismissed ideas like wireless synchronization for years making their first attempts at smart phone far more like early Nokia Communicators than early Blackberrys...
So the point is that all these companies were fighting over what amounts to overgrown PDAs with phones and wireless stacks strapped on. Everyone assumed power density was no where even close to what was needed for general computing, that a full featured browser and heavy duty Internet services were impossible due to bandwidth and latency. Take a look at how our Java expert groups named standards, how people at the time talked about what features smart phones should have, and its clear that no one thought an iPhone was possible. Even Danger, which eventually went on to work on to create Windows Phone 7 and Android, was just working on a better Blackberry.
But what does this have to do with the future of voice-phones?
The problem is that the vendors that lost this game failed because they listened to their customers. Like with PDAs or with the original mobile phones or first generation of PCs, early adopters are not the audience that should be consulted on how to improve the product.
Early Windows Mobile users were ecstatic about the platform and rejected new UI metaphors because they wanted a "mobile Windows". Palm fans stuck with the PalmOS even though it was well past its shelf date in the Treo because they treasured the original PDA metaphors.
Every company paying attention to the market in 2005 would have been eagerly pursuing corporate buyers of PDAs and aiming complex products at enthusiastic PDA users.
And yet, non-consumers should also not be trusted with their opinions. Most early surveys would show that the vast majority of consumers found that mobile phones were not good value for the money. Later the same audience would declare that smartphones were not worth buying.
There are many voice-only users in the world who are happy with their products and not interested in any new options.
So what's a marketer to do?
If you can't ask early adopters and you can't ask non-consumers for hints then where can clues be found?
What history shows is that consumers have been happy to trade up to technology that offers more option value.
Television went from cheap/free over-the-air broadcast with limited channel options to expensive cable with large option value in channels. Even if most of those options went unused, they are still valued.
Telephony went from low cost reliable landlines to high cost, less reliable but with much more option valuable mobility. Having the option to call a person vs. calling a place (where a person might be) changed the calculation of whether you make the call. Calling became much more popular.
Data as well went from metered dialup to unmetered high option valued broadband. From a luxury, to the least likely service an unemployed user might give up.
Emerging market users hungered for mobile phones even though they cost more than several months' wages because they gave access to information and increased the option value of their labor.
Each of these huge technology transitions came associated with increased costs for the consumer, but that cost went toward the purchase of a far larger option value.
The problem is that users cannot calculate option value in their minds when faced with a market research questionnaire. How can they envision all the ways they would use a new product they've never used before? How can they "get it" without observing it in use or spending time thinking of "how they would use it" or asking someone who tried it? In a nutshell, users are willing to pay for option value but can't envision or quantify this value without observing a finished, polished product in use.
This is the problem faced today by branded phone vendors. Asking or observing current users of smartphones does not provide any incentive to sell low end versions. Asking or observing non-consumers seems to indicate no interest in newfangled complex or costly products.
But the calculus that must be made is one of option value. Does the new product offer significant option value? Will this option value be easily realized? This is not easy to determine, but it's a method that is far more promising than asking users their opinion.
The PDA was not a product that was introduced by the incumbent computer vendors because their customers did not ask for it. Once established, the PDA was not replaced by a product that PDA users asked for either.
Smartphones are following this well trodden path. The high end devices are evolving into computer replacements nobody asked for (but everybody will use). The low end products are adding data option value to voice-oriented users who never asked for anything more.
One of the most popular themes running through the mobile phone industry this year has been the unprecedented growth in Android adoption. I've argued that the adoption was initiated on the supply side by vendors and operators, but demand has certainly manifested itself.
Android is almost viral in the way it spreads. With no constraints on intellectual property, pricing, contracts, modification or terms of distribution, the incentives to push product out are phenomenal. It even works, mostly.
One hypothesis of the consequences of this viral adoption is that there will be a "commoditization" of smartphones with rapid price erosion to follow. This in turn might even lead to lower margins for Apple and RIM and most major vendors, including those selling Android itself.
In order to test this hypothesis, we need to look at what has been happening to prices. If prices have started tipping down at more than their usual rate then maybe commoditization is happening.
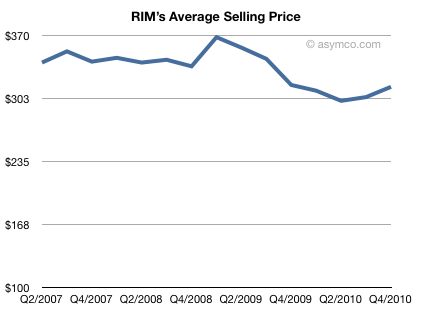
We can begin this test with the industry's canary in the coal mine: RIM. RIM has been struggling for growth in the very market where Android has been growing the fastest. Is RIM's pricing under pressure?
Interestingly, no. Their ASP (average selling price) decline, from an average of $350 to $310 in late 2009, came before the Android avalanche. During this year, the ASP has held steady, even rising in the last two quarters to $315 while Android activations reached 300k/day.
So I don't see a big problem with RIM, yet.
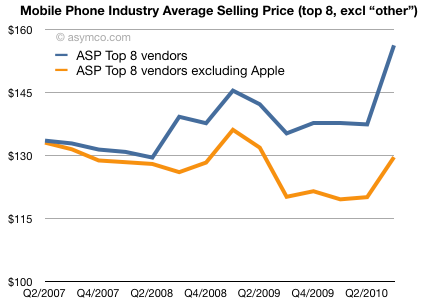
What about the industry as a whole? Can we see patterns that suggest imminent commoditization? Using the top 8 vendors (Nokia, Motorola, Samsung, Sony Ericsson, LG, RIM, Apple and HTC) and using volume-weighted ASP (total device sales divided by total units sold) we have the following chart:
Since the second half of 2007 the "industry ASP" (blue line) has actually increased. This is even though there was a huge recession in the middle of the time period.
This should be only slightly surprising. If you suspected that the iPhone may have a lot to do with that, you would be right. If you remove Apple from the mix, the second line (in orange) shows that the top vendors (ex-Apple) had some, but quite quite mild erosion (from an ASP of $133 to $129)[1].
This is far milder than what's been happening in the PC sector where prices are dropping catastrophically (According to NPD the average selling price of all Windows portable PCs has fallen from $659 in Oct. 2008 to $519 in Oct. 2009).
So Apple was a big contributor to the industry increasing its pricing power.[2] but even without Apple the industry has been holding on.
But is this just a lull?
Is Android going to stop the growth?
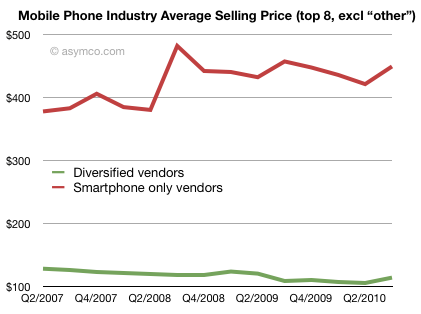
We can look at the pricing data one more way: If we separate the eight companies into two cohorts, the "diversified" vendors who sell both smartphones and regular phones vs. the "pure play" smartphone-only vendors, we get the following price history.
What is happening is that the diversified (Nokia, Samsung, LG, Sony Ericsson, Motorola) saw modest price declines (from $128 to $114) while the pure-players saw price appreciation (from $378 to $449). This is with the early impact of Android priced in. Unfortunately I don't have a chart showing non-smartphone prices in isolation, but I would be willing to bet it would be a significant negative slope.
In these two lines Android is not an independent variable. Android was adapted by some of the diversified vendors (all but Nokia), but in different ways. The thing is that Motorola and Sony Ericsson had great increases in ASP with Android. Among the pure-play vendors only HTC adopted Android and its performance is undistinguished vs. RIM which didn't.
So what, if anything, has Android done to pricing?
I argue that there is no evidence in the pricing data of a coming commoditization of smartphones. Android vendors were able to use the platform to move to higher pricing and the more they switched their portfolio to Android the more they got a better average price. At the same time those vendors who built smartphones without Android also saw strong price supports.
The only correlation with pricing power is whether you build smartphones or dumb phones. The more smartphones you build, the more price you can charge. This is regardless of platform.
The reason for this is that the smartphone market is growing so rapidly (90% y/y). There is limited direct competition between smartphones and a lot of competition between non-smartphones and smartphones--a battle smartphones are winning handily, irrespective of price. Smartphones seem to be what everyone wants.
So the real question that should be asked is:
Why do vendors bother making any dumb phones at all?
If you look at the third chart above you can see how attractive it must be for the diversified vendors to abandon the non-smart market to ZTE, Huawei et. al. Perhaps Nokia can still make a small profit there but to do so you need to run faster and faster toward extraordinarily low costs and prices. A point where phones cost less than everyday consumables. What keeps Samsung and LG in that game? Motorola and Sony Ericsson left once they hit profit warnings. Is that what it takes to drop what seems to be a loser business? I think not.
My bet is that by the end of 2012, it will be hard to find any branded phones which won't run a smartphone OS. Demand and supply of smartphones will race each other to overwhelm portfolio logic at the largest companies. The zero (visible) cost of Android will snowball this effect. What's even more provocative is that I believe the "others" will follow and abandon voice-oriented phones for smartphones almost immediately after the larger group.
I've long argued that the phone market should be studied as a whole because the competition is not between platforms but between smart and non-smart. Pricing is a leading indicator of what drives decision making inside vendors and it leads margin, and thence portfolio discussion. Android is expanding the market without crushing pricing. The margin expansion is what attracts more vendors and creates more demand. It's a virtuous cycle.
In a way, this is all good news--even for Apple. A world full of smartphone users is a better addressable market for iPhones than one filled with voice products. iPhone's traction was always in markets which had been seeded by some smartphones: the US with RIM and Europe with Symbian. Such a smartphone-soaked world will have better mobile broadband infrastructure, users with more demanding tastes and awareness of the value that a smart device can bring.
---
[1] The effect of "other" vendors not among the 8 listed is a big unknown. It's been estimated that they now make up as much as 30% of total volumes and that they are beginning to ship significant volumes with Android. Without visibility into that part of the market, we should be cautious. However, the eight vendors sampled here are still a significant cohort and the conclusions still appear reliable.
[2] This industry had, until 2007 suffered from chronic price erosion. Each sustaining innovation drove a mild burst of pricing power but it never seemed to last. From color screens to bluetooth, to 2.5G to 3G to MMS, to cameras to music playback, each hardware advance was not enough to keep the erosion away. The tipping point seems to be the iPhone and the shift to software as the component that drives price power.
In the latest version of Android, Google shifted from bitmaps to vector rendering for maps. The shift is probably more a function of available processing power on the device than a strategic shift to position value on the device rather than in the cloud. Vector maps, which are much more efficient in terms of bandwidth and local storage, have been the choice for in-car navigators but Google has always been using bitmap tiles which are fetched from a server and delivered only if the device is using a data connection. The downside for vectors is that they require a bit more local processing power.
I doubt that Google's move to vectors is part of a shift to more app-centered/edge-of-network strategy.
How is this relevant?
Google has been riding a wave of re-centralization of value toward the center of the network as broadband made the cloud feasible. Keep in mind that Microsoft rode a wave of de-centralization as value moved to the PC and away from the mainframe. As intelligence was pushed to the edge, Microsoft accrued value from enabling the edge as a locus of productivity. This is no small thing.
Then came apps.
The supernova that is the App Store illuminated the possibility that apps are perhaps a "pushback" on the center. Like all good disruptions this was unforeseen: Apple built the store and the apps sold; by the billions. Apple joined the world in a scramble to react. Something profound was happening, but the very brightness of this explosive growth blinds us to what is actually going on.
My hypothesis is that there is a tug-of-war going on between the mobile cloud and the device-at-the-edge. Both will become better and neither is good enough. Technology roadmaps point to both higher availability of local storage/processing power as well as faster, cheaper and more ubiquitous mobile broadband. So technology insight by itself is not enough to give us a clue to the outcome.
What I would focus on is what is more natural for the user. Note that Twitter and Facebook both have better interfaces with their apps than they do with their browser interfaces. That and innovations in game interaction points out that apps are as much a disruption of UI metaphors as they are of the locus of power in the network. It would not surprise me if people end up spending a larger part of their lives tethered to device-enabled social media, "firing" the PC from the job of social interaction.
If we believe the app will grow as the preferred interface for the web (and I'm leaning in that direction) then the implications are potentially harmful to Google. Google does not "do" interfaces. Their strategic assumption has been that interfaces are commodities. The browser is the universal interface. Perhaps HTML5 will offer sustenance to the concept, but it's not a panacea. Web apps have a long way to go to become competitive with hand-crafted app UIs. (While web apps have been possible for iPhone since its inception, developers vote en-masse for apps and almost zero popular web apps exist. Ditto for Flash-to-app interface ports.)
This brings us to focus on the asymmetry of business models.
the App Internet
What we end up with is the "app internet": a potential disruption of the browser-as-interface and the re-integration of the user experience around the device. Because the iTunes store allows money to be attached to new interface innovations, developers follow and compete on better interfaces rather than on access to the back end. The asymmetry ensues from the fact that by attaching profit to the point where the user touches the screen, Apple took the basis of competition for developers away from the cloud.
In other words, the point where the electrical charge of the human skin is detected is suddenly the exact location of value capture from mobile computing.
Of course, Google is responding, but since they did not focus on seamless and curated experiences, developers are not seeing returns for investment in interfaces at the touch point. As a consequence, Google apps developers seek ad revenues. In turn, this is a road that leads to less innovation in interfaces and more innovation in network-dependent services.
I sense a distinct asymmetry in app trajectories between the platforms due to core business model choices. Asymmetric competition causes the great fortunes to be made and great fortunes to be lost.
The release of the iPhone is rightly acclaimed as a watershed event in the history of telecom. It was a sensation. But it was also a product that was widely underestimated and dismissed. Even today expert opinion is divided. The critics of the product transitioned directly from labeling it a superfluous bauble to an obvious and copyable sustaining innovation. Advocates of the product describe it as revolutionary and dazzling with the potential for capturing significant profit share due to premium pricing and positioning.
So which is it?
I'll argue that it's none of the above. The iPhone is not superfluous, not easily copied, not revolutionary and not a premium product. What it is is disruptive.
First, we have to quickly define disruptive potential.
A product is disruptive if it competes with an existing, incumbent set of products on a new basis. It competes along a new measure of performance. That means it's either "low end" and hence cheaper, simpler, more modular and conformable, or it creates a "new market" where completely new measures of performance or quality are relevant.
In both "low end" and "new market" disruptions the product is usually wrapped in a business model that insulates it from incumbent response due to inherent asymmetries. Incumbents will find the economics of the entrant product unattractive and will be motivated to ignore it or actively avoid copying it.
The consequences of disruptive product entires are often catastrophic for the incumbents because, over time, the disruptor product vacuums up all the profits in the industry, robbing the incumbents of the fuel to respond by the time they become motivated to do so. In essence, the transfer of value to the new basis of competition happens so slowly that the threat is imperceptible until it's too late.
If we look at this definition, it's startling that the iPhone does not seem to fit.
As a phone, it's not cheaper, nor modular and hence not "low end". It did not create a new market. As a phone, although it did recruit more regular phone users into becoming smartphone users, it was not the first or last phone to do so. Its phone business model was not a radical departure. It was not ignored by the mobile phone incumbents who reacted with various degrees of urgency and vigor. It was actively copied in every way from the UI to the ecosystem to the pricing model and distribution.
The only thing that seems to have happened according to the disruptive formula was the transfer of profits from incumbents to Apple, at least temporarily.
So the iPhone seems to be correctly classified as a sustaining innovation. Something that moves the phone market forward and which, except for a temporary misallocation of profits, will entrench the incumbents after they manage to copy it effectively.
However, here is where we have to dig a little deeper.
Market analysis easily becomes myopic when looking only at a market defined by a product. I've argued in the past that strategic insight comes from looking at products that cross over their market boundaries. Especially products that are hired to do different jobs than the same products in their categories. The iPod may seem like an MP3 player but it caused catastrophic profit collapse in multiple industries. It knocked out the CD business, it crippled the component audio system "Hi-Fi" industry, it razed the music retail business and affected the entire music value chain. It's still pounding at the gates of video and TV production. And, almost as a side-show, it crushed the Walkman.
Even though it was a music player, the MP3 device market was the smallest target for the iPod. It turned out to be far more dangerous to ancillary industries. The reason is subtle: it competed as an integrated ecosystem. You hired the iPod to serve you music everywhere, not just in your living room. And it did the job in an integrated way from source to earbuds taking what was a hodgepodge of modular components built around analog music and smoothly integrated them to deliver music in new, non-consuming contexts.
The lesson is therefore that when looking at the iPhone one has to look at ancillary industries not just at phones.
Phones have always been a component in a wider inter-related telecom value network. Even today they are often called "terminals" in the industry meaning that they are the end points of a network. Similar to the PC, the iPhone enables a migration of intelligence away from the center toward the edge of the network resulting in a de-valuation of the network itself.
I argue that the real disruption of mobile computing (i.e. iPhone) is made possible not by the smartphone technologies but by mobile broadband. Once broadband became mobile with 3G the smartphone could shift its focus (jobs it's hired to do) from voice to data. That shift is disruptive to incumbents because they built their businesses around operator distribution and operator service economics. With apps, mobile computing brings with it services which allow all communications to be independent of operators. Selling ringtones, maps, email and video-on-demand are all dead business plans today. But operators clung on to these hopes for many years and forced vendors to comply to this strategy.
The incumbents relied so much on the telecom value chain, where the value flows from the monthly service charge, that they would not deploy technologies or business models that were asymmetric to operator business models. This is the root cause for Nokia and Samsung and Motorola and LG "missing the boat" on smartphones. All the vendors had the pieces of technology on their shelves. But when they took these technologies to their customers, the customers rejected the package.
This is why entrants like RIM and Apple could easily gain a foothold and grow. They had modest volumes, sold new concepts like business email and new UIs with iconic designs, but did not go after the core business model. This is similar to how iPod/iTunes got a toehold with the record labels. By the time the disruption took hold, operators were addicted to the new high-ARPU being generated even though they were all pure bitpipe plans. A bird in the hand is worth two in the bush, so the new device brands stuck.
Do the incumbents still have time to respond effectively? It's less and less likely. They cannot build the new computing ecosystem without the distribution power of operators. Note that iPhone 'clones' in Android are still sold via operators and that nobody is interested in making either iPod touch clones or iPad clones sold independent of the operator channel/subsidy model. This is not because of technical or economic reasons but because of a lack of distribution (and lack of integrated content).
When you step back and look at the phone in the context of the network business model as well as the shifts in consumer jobs to be done you realize the potential is far greater than taking share from incumbents. The iPhone is not divided into a portfolio of different phones, but it's a part of a portfolio of new mobile computing products. It just happens to be the only one which still depends on the cellular operator distribution network.
Seen as part of a new mobile computing paradigm and following the trajectory of the mainframe, mini-computer, PC and laptop, the iPhone is an essential, non-superfluous device for a vast population of new users.
Seen as an integrated app ecosystem with strong network effects, it's not easily copied. Responses that only account for it as a glass and metal object of desire will fall way short of being competitive. As the hardware was always available to competitors, it's not a revolution in hardware or even in user experience.
Most importantly, seen as a computing alternative merged with a communication appliance, it and its siblings are not premium products. The pricing and service structure around it make it seem a low cost alternative for solving the jobs it's hired to do.
When the iPhone vs. Android rhetorical war heats up, both sides bring up the history of Macs vs. Windows PCs. The commonly held thesis is that Windows triumphed as the PC was commoditized (and modularized). This triumph was at the expense of the over-serving and over-priced Mac.
This is a largely accurate view of what happened during the 90s. But the problem with this thesis is that (1) the PC's job has been slowly changing in the last decade (2) the Mac keeps growing faster than the PC and (3) Apple keeps capturing a vast portion of the profits in the PC industry.
These anomalies or contradictions to the thesis imply that something changed. What changed and can these changes turn the tables on the market and create an opportunity for a new computing disruption?
The PC of the 90s was hired first by companies as a productivity boosting tool and second by consumers as a way to duplicate their work productivity and communications in their personal lives.
However something changed with PCs when the laptop became "good enough". With portable computing, the job the PC was hired to do evolved. It was more important that the product be well designed (for aesthetic value, usability and reliability) than just fast and spacious. The microprocessors were plenty fast but what mattered more was low power consumption, a low profile and tighter integration with software.
The product was also purchased in a different way. A desktop could be purchased on specs alone, sight unseen, from a catalog. But a laptop had to be touched, hefted and the screen had to be observed and the whole design contemplated before a purchase decision was made. The product had an integrated keyboard, display, touchpad and storage. It was not easily serviced by end users. It was, in a word, re-integrated.
You can see how portability changed the job and therefore everything else as well. Consumer tastes became important, retail distribution became necessary and R&D resources had to be applied to solve what was no longer good enough: the whole package.
Vendors which did not prioritize design, retail and R&D were left flat-footed.
At the same time, systems software became more commoditized and productivity software became portable. The old measures of performance were being over-shot while the new measures of performance were under-served.
While this shift was underway on the hardware side, Microsoft continued to improve their product to serve more demanding business productivity jobs. Their software was not getting optimized for this new portable consumer job. They left the new market open to disruption.
In stepped the MacBook with good enough (and improving) office productivity. With excellent appeal along the dimensions of performance consumers demand most of all. It was priced higher than other laptops but the price points were affordable and, inflation-adjusted, lower than they'd ever been. It should not be a surprise that Apple was one of the first vendors to see its portables line become bigger than its desktop lines. The market evolved to the point where what Apple had was what the buyers needed.
The shift to portability is a compelling story for Apple as disruptor in the PC market. It may not result in a complete reversal of the PC hegemony but it allows Apple to grow a product line at triple the growth rate of the market. A market that was considered completely dominated by entrenched incumbents with an unbreakable profit formula.
But with the iPad Apple is clearly also aiming at disrupting the Mac (and, transitively, the PC as a whole.) The iPad can be seen as an evolution toward seamless portability; the mobile computing paradigm shift.
The iPad outsold the Mac after two quarters in the market. It's important to understand the effect the iPad is having on PCs. Data is trickling in that potential notebook buyers are "postponing" purchases due to the iPad. The netbook market has witnessed a significant slowing which has trickled down to the performance of everybody in the value chain, from Microsoft, to PC vendors, Intel, AMD and retailers.
So naturally we need to ask how it has affected the Mac.
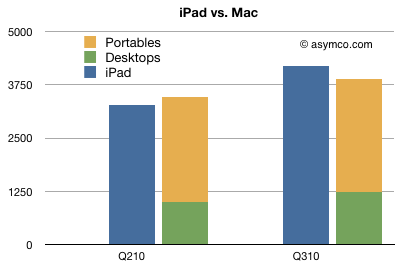
The following chart shows how the iPad has outsold the Mac the past quarter. The iPad was on the market for six months while the Mac has been for sale for 322 months--a shocking achievement.
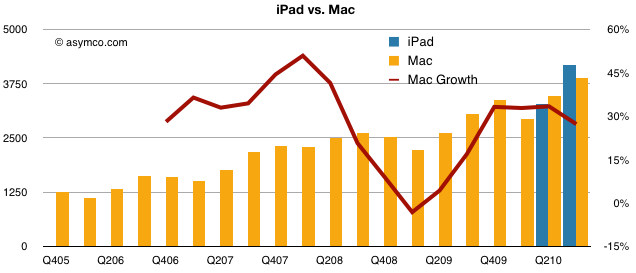
But the Mac has not slowed down. It grew faster than the overall PC market (units grew at 27.3% and revenues grew at 22%) as it has grown for most of the past 18 quarters.
The performance is also highlighted in the following chart showing the history of the Mac units by quarter over nearly five years. The Mac had a slowdown during the recession but the dip in growth in the last quarter does not seem significant.