Asymco

Asymmetric Intelligence

platform

  1. A new era is only a new state of mind

    Research · 51 comments

    The following interview was conducted by Bruno Ferrari a writer about technology for EPOCA, the weekly magazine of Organizações GLOBO, the largest Brazilian media company on March 30 2011. The article (published in Portuguese here) is an edited subset of the following exchange.

    Q: In your analyses, you mention tablets as part of a new era, the “Post PC era”. Why do you think the PCs will be replaced by tablets?

    This is not quite correct. Post PC does not mean the end of the microcomputer. The way to think about it is this: The stone age did not end because we stopped using stones. Same with the iron age and the industrial era. The era of jet travel did not end automobile or even ship travel (though that changed to recreation rather than transportation for passengers.) Each phase of technology does not fully replace its predecessor. It offers a new set of solutions and perhaps a slightly different way of solving old problems. We'll still have PCs but we will use a new type of computer, an even more personal computer. The world still uses the microcomputer's technological ancestors.

    In terms of what new jobs will we hire the tablets to solve, they will vary greatly from what we used PCs for. Just like we used microcomputers for different things than we used time-shared minicomputers and mainframe computers. I expect social interaction, media consumption and entertainment will move from a PC to a tablet. New uses will emerge from the vast experiment that is the app phenomenon.

    Q: What are the new ways to interact with machines? With gestures? How will this change the market?

    Each major disruption of computing came from a new generation of input and/or output methods. Terminals (vs. punch cards) enabled minicomputers. The GUI enabled the rise of the microcomputer and touch is enabling the rise of the tablet. Perhaps this era will last decades perhaps only years, but there will be new input and output methods available. The world's research laboratories are filled with ideas from projection screens (from high brightness LEDs) to motion sensing (as implemented partly by Kinect) and even novel voice control methods. I believe that each major innovation will create a new wave of growth and, if coupled with a new business model, a new set of companies and platforms.

    Q: What are the main differences between PC and Post PC era?

    The main difference will be in the context in which the product will be used. Tablets and smartphones allow "computing" to be done in previously non-consuming contexts: while standing, while in the active company of others, while commuting or while lying back and relaxing. It will also allow more individual use. Like the transistor radio allowed teenagers to listen to rock-and-roll out of hearing range of their parents who had control over the family stereo, a truly personal computer will allow people to "escape" into a world of more intimate consumption and communication.

    Q: Do you think physical keyboards and mouse will be extinct?

    Even physical keyboards have been evolving dramatically. If you look back to the earliest IBM PC keyboards, they were mechanically complex and had a rich feel. Modern laptop keyboards are flimsy things with barely any feedback. Early PC keyboards were patterned after the needs of professional typists (aka secretaries). Current keyboards are designed around space constraints. Same with mice. They went from two to three to one to no buttons. With laptops we ended up with track balls,  little knobs in the middle of the keyboard or with trackpads. Users adjusted over time.

    What changed with tablets is the removal of an on-screen pointer. The pointer was there because the mouse/touchpad was one layer of abstraction for controlling what was on screen. Without a pointer you have direct manipulation. I'm sure many people who never used a mouse would find the direct method more intuitive and in a generation people will wonder how we put up with mice. Conversely, those who are used to a mouse will find it uncomfortable at first. Remember that in the 80s many keyboard experts found mice something that slowed them down.

    So I believe that people will adjust to a world without mouse pointers. I suspect children born today will grow up without ever using a mouse (or a phone with a wire permanently attached to the bottom).

    Q:  Apple has more than 90% of tablet market worldwide. Do you think Apple will be the leader of technology market in the next few years?

    The challenge for Apple is that they cannot serve the whole world. They can only grow so fast. On one hand we have their inability to meet demand and on the other we have alternative products which can. Market leadership may not be sustainable just because the market is so big and no single company can supply it. I do believe that Apple is not sitting on its hands however. Their culture promotes pushing forward.

    Q: At smartphone market, do you believe on a risk of a new duopoly, Apple-Google? Some analysis says that they’ll control the channel sales of software, content and hardware. The conclusion is companies like RIM, Nokia and HP (Palm) will not be able to keep up.

    Analysts differ in their opinions. IDC just released a forecast that shows Microsoft growing beyond iOS in four years. I don't try to make this type of prediction. At least not to a high degree of precision. I do believe that there will be more than two platforms. This is because the market is so large and so diverse and there are so many ways to reach customers (through operators, through retail stores, through online).

    Q: Can we compare the beginning of the tablets with PCs? Apple developed the interface and made ​​the first computers nice and easy to use. But Windows has allowed hardware manufacturers to invade the market, popularizing it. This will be repeated with Android? Or with other systems?

    Innovations are always copied. Even when protected by all sorts of laws or patents. What makes a company successful with innovation long term is to always keep innovating. Often coming up with the next big thing means damaging the old thing. That's hard to do for many companies so they don't do it and somebody else does. This is why great companies end up as formerly-great companies. As I pointed out above in the discussion about input methods, innovations are always bubbling up. As long as Apple takes these ideas and polishes them and brings them to market, they'll do all right.

    Q; How about Microsoft? Do you think the company will lose the podium in Post PC era?

    Microsoft already has lost its position as leader in personal technology. The end actually came in about 2000. Once Windows became "good enough" and did not crash so much, they have had a hard time finding something to improve. If you go back and watch every CES keynote that Microsoft presented since then it's been a litany of dead end ideas.

    Every major innovation since 2000 has been in consumer technology and that's never been an attractive business for Microsoft (with the exception of XBox which was really aimed at Sony and Nintendo without the intention of creating a new market.) Microsoft struggles not because they lack talent (engineering or management) but rather because their business model is relatively rigid. They make money through software licensing. You can see how that's a hard thing to sell to consumers ("I'm buying what?") Consumers tend to pay Microsoft through the purchase of another product. If the market demands hardware/software integration (like in a phone or tablet) or making money by giving software away (like Google), they struggle. This business model rigidity is present in almost all companies, so Microsoft is not uniquely troubled.

    Q: Most of the tablets will use mobile networks to connect to the internet. Do you think the world is ready with an infrastructure that supports this growth in access via mobile networks?

    This is a good question because the growth of mobile broadband is a major enabler (or constraint) on growth. Fortunately, the roll-out of mobile broadband is fairly predictable and it looks good. There are some challenges for operators long term in paying for the infrastructure, but they don't lack for financing today and the business case for more infrastructure seems to be very attractive. It will take time and it won't be even globally, but the incentives are clearly there. A lot of value is being created with mobile computing and much of that value will end up paying for the bandwidth.

    Q: How about the App Market. You posted recently a chart showing how fast developers are buying thickets for both Google and Apple developer events. You said that it is one signal of the Post PC Era. What will be the importance of apps on the next years. Do you think Apps market will be more important than hardware, content and OS market?

    Developers are one more sign that something big is happening. It's not the only sign and may not be the cause of the change, but it's yet another signal. But apps are a phenomenon that will result in something bigger than we can imagine. The way to think about apps is as a new medium, similar to the emergence of radio, television, cinema and even books. The app is a new art form as well as something that provides functional value. We don't know whether the app phenomenon will be tied to one platform or will evolve to something like HTML5, a common standard. But the value of having an app for everything is plainly evident. The economics, creative energy and dynamism of apps cannot be overestimated. I will write more about this subject as I think it's one of the most important consequences of the post-PC era.

    Q: What’s the destiny of the PC? Are they on their last years?

    Again, it's not so much that PCs will disappear any more than mainframes or servers have disappeared. What is more likely is that they will be used for isolated, focused jobs. The "end of an era" is the end of growth, not the end of existence. The PC has arguably reached end of growth in most developed markets. There is still strong growth in emerging economies but even there, much of that growth will probably be replaced with smart devices growth.

    Q: We had the Mainframe Era, the Terminal Era, the MiniPC Era, The PC Era and now we starting the PostPC Era. Do you imagine what Era we'll se after the tablets? When do you think is it going to happen?

    I don't try to be a futurist who can see with clarity technological change. I try to see the patterns of markets through the motivation of companies. With that in mind, my answer will be that large companies will acquire promising new technologies from start-up companies and implement products with global distribution. To see the future you therefore need to look at what small companies are doing today. I note that there is a lot of innovation in new communication methods (social media) and new input methods around gestures and display technology. I am skeptical about the power of voice controls.

    I'm most confident that there will be a re-definition of television, a "socialization" of almost all media. So I'll abstain from answering directly what happens after the Tablet Era. Perhaps something more personal and more of a companion than a tool.
  2. iOS vs. Android: the tale as told by Wall Street

    Research · 90 comments

    Yesterday I wrote about the growth in Android vs. iOS. The two platforms' can be said to be enjoying healthy growth, though in markedly different patterns.

    The consequences of this growth are being felt across the telecom and computing industries. There are almost 300 million platform devices in use today that were not even dreamed of three years ago. Operators are transporting petabytes more data and dozens of phone vendors are scrambling to meet demand. There are tens of billions of app downloads and hundreds of thousands of apps being sold by tens of thousands of new app publishers. There is a lot of hay being made while the sun shines.

    But what about the poor saps that are funding the development? What about the shareholders of the companies behind these platforms. Are they being rewarded or punished?

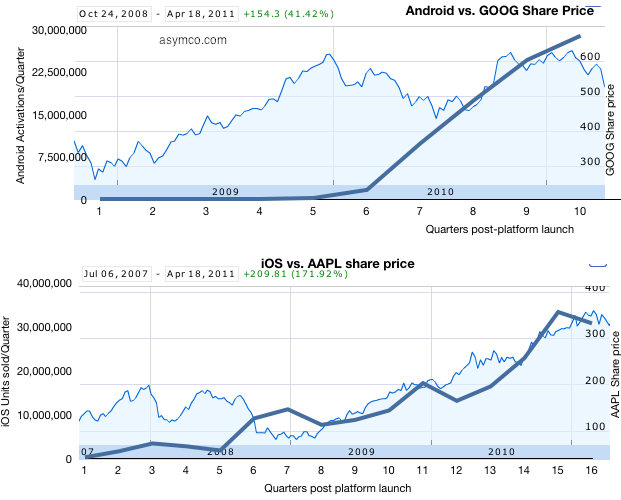
    The following charts tell the story:

    I took the platform growth data published yesterday and overlaid it on the share price data (source: Google finance). Each plot begins at the point in time when the respective platform was available in the market and ends today. There are two vertical axes: the left side axis shows "activations" or units sold and corresponds to the thick blue line; the right side axis shows share price and corresponds to the area chart. Overall date range and growth in share price is shown in the upper left corner.

    What can we interpret from this superimposition?

    1. Both Apple and Google shareholders saw share price appreciation during the two platforms' histories. Apple shareholders benefited more (+172% vs. +41%)
    2. Apple's share price appreciation seems highly correlated to iOS growth but Google's doesn't. Google share price had dramatic growth during 2009 while Android was moribund and was flat to down during 2010 when Android growth was explosive.
    3. We can also interpret the difference as Google's fortunes being far less dependent on mobile platforms than Apple's. Google has been subject to selling pressure this year due to corroding cost structures irrespective to platforms growth. Conversely, Google may not benefit from mobile computing as handsomely as Apple.

    Correlation is not causation and clearly there are many factors at work in share price changes but I think it's fair to say that Apple is obtaining fuel for growth with iOS while Google is in a more precarious situation with mobility--partly benefiting but partly threatened. The market behaves in bizarre ways in the short term but in the long term one can see logic and reason.

  3. The Android step function

    Research · 40 comments

    There is precious little data on Android units sold. There are estimates but no actual summary. Google themselves don't seem to know as they don't report sales, preferring to report "activations."

    Assuming that activations means "unique activations of new devices" then we can draw some equivalency between Google's reports and the reported units of iOS sold. There is some uncertainty with respect to iPod touch units, but that is not very big (estimates are drawn from Apple's reporting of overall iOS units at several points in time.)

    To estimate Android, I took the download rates currently available and placed them in the month when they were published. I then interpolated the data monthly and quarterly.

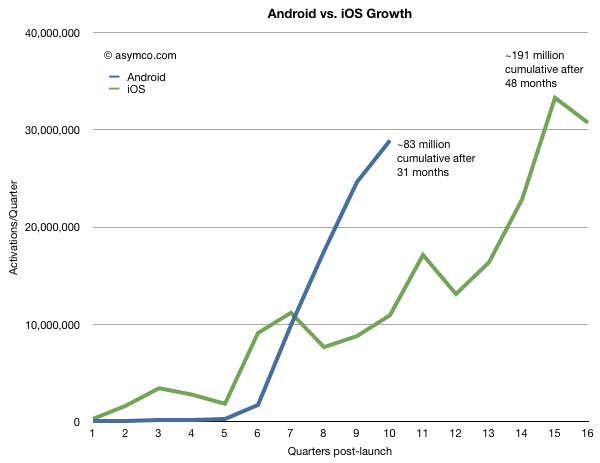
    To make the comparison more valuable, I chose to index the starting point at the launch of each respective platform and plot quarterly units (or activations). This way we can observe how the platforms ramped in growth and where they were at similar points in their lifetimes.

    The following graph results.

    There is likely to be more seasonality in Android data than is shown, but the impressive thing is that Android is running at three times the equivalent adoption rate for iOS at similar points in time. In fact Android is being "sold" as rapidly as iOS today even though iOS has been in the market about 15 months longer.

    Overall, cumulative units sold for iOS are still about twice as many but if Android will continue to grow as rapidly as it does now, it will likely overtake iOS in installed base in less than a year.

    One should be careful about drawing conclusions that this implies effective competition. Both platforms are growing very quickly. iOS is growing at at least 100%/yr and Android's second year was 65x bigger than its first. iOS growth is limited by the ramp rates of a limited portfolio of products. Android growth is limited by how quickly vendors can bring out products. Neither platform is demand constrained and hence they are competing for share of growth not for share of a fixed pie.

    Extrapolation is a dangerous game, but the chart above shows some predictability in Apple's curve whereas Android has a "step function" or discontinuous feel to it and that's a curious thing.

    Not so much for its lack of predictability but because it's so asymmetric to iOS.

    A dictum of classical physics states that in nature everything is continuous. However, in quantum physics everything is discontinuous. Both models of the physical universe have their uses.

    It should be noted that both business models represented above can also co-exist, at least for the foreseeable future.

  4. First quarter PC forecast: Windows down 2%, Mac+iPad up 250%

    Research · 100 comments

    Charles Arthur of The Guardian writes that PC sales "may have passed their peak".  That's a powerful, concise statement. It's backed up by a quote from Gartner's Mikako Kitagawa:

    "This was the third consecutive quarter of mobile PC shipment declines in the US"

    IDC even lays part of the blame to something called "media tablets"[1]:

    "While it's tempting to blame [PC] decline completely on the growth of media tablets we believe other factors [...] played equally significant roles."

    But there are several problems with both IDC and Gartner's analysis of the market. It's hard to make out causality from their data. There is separation by vendor but not by operating system and there is exclusion of devices hired to do the same jobs as PCs.

    For this reason, I need to do my own analysis. I retrieved Gartner's public statements on the overall market and layered actual Mac and iPad units sold. I also added my estimates for the Q1 2011 quarter just ended to complete the picture.

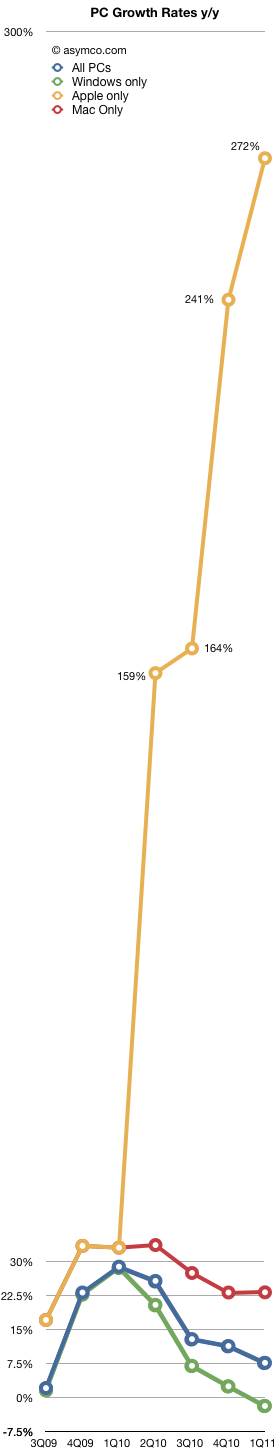
    We can now get an understanding of how the industry behaves with and without various platforms. The chart at the left gives the various growth rates of the market with platforms isolated from each other. I apologize for the shape of the chart but the scale does not permit a concise visual.

    Including the iPad, the total PC growth is shown by the blue line. It shows that the market peaked during the recovery but is now slowing considerably.

    The green line shows the PC industry excluding both the Mac and the iPad. Although it might include Linux or computers sold without an OS, the label "Windows PC" is a fairly close approximation. It shows that the market excluding Apple entered contraction this quarter and is out of sync with overall economic recovery and growth.

    The red line shows the behavior of the Mac franchise. It's well ahead of the overall market with 2x to 3x the growth. This has been a pattern for over 18 quarters.  I had some thoughts on this in a November 2010 hypothesis.

    But the most telling line is the orange line which includes both the Mac and the iPad. In an industry where growth is usually measured in single digits, the iPad business brings growth in three digits.

    This near tripling of unit sales is symptomatic of fundamental change that cannot be ignored. Although some analysts contend that the iPad is not causal to the decline in other PC sales, teasing out platforms data seems to show a divergent view.

    The bottom line is that Windows-only computer units are down 2.0% while OSX-based computer units are up 272% (this excludes both the iPhone and iPod touch).

    Correlation is not causation but tests or surveys where substitution can be proven do exist. For example, a recent survey shows that 77% of users reported that their PC usage decreased after getting a tablet. It also showed that 28% considered their iPad as their primary computer.

    So coupling the sales data with the usage data does point an accusatory finger for the decline on the iPad.

    In addition, some vendors are being hit harder than others which also hints at where substitution is happening. For example, IDC reports that Acer US unit shipments fell 42% in the first quarter and 16% globally (Gartner's numbers are less dramatic but in the same direction). Since Acer is known for its netbook computers it's another telling sign of possible substitution (Acer's own management has indicated as much.)

    So the weight of evidence is beginning to be conclusive: the iPad is the new PC. It should be clear by now that the iPad moves computing into new contexts so it does not yet substitute the PC market but extends it and increases consumption. Substitution is happening in low-end grazing type of usage, a place where the PC was ill-fitting anyway. Incumbent vendors might actually be relieved that the lower margin netbook is finally being supplanted and they can concentrate on the higher end.

    --

    Notes:

    1. Analysts like to call the iPad a "media tablet" but the same AdMob survey shows media consumption to be one of its least popular uses.
  5. Mobile device OS upgrades: How hard can it be?

    Research · 45 comments

    Until the iPhone's arrival in 2007, upgrading the software on a mobile phone was a rare experience for users. So rare that effectively it was not done. Few people were bothered though since they did not see the product they used as a software product.

    This was even true for Windows Mobile and Symbian which were licensed platforms. Microsoft tried several times to offer upgrade paths, but more often than not the device vendors did not push out updates or the process required to perform an upgrade made it the reserve of either those who were paid to do it or those who enjoyed the challenge.

    In the era of the modern smartphone, upgrades are more common. Certainly with the iPhone the process is easy enough that opting out of an upgrade is more challenging than opting in. But it's still not as common with other platforms. Even with all the resources and experience behind them, Microsoft is still stumbling with Windows Phone upgrading.

    UPDATE 1-Microsoft explains phone software update delay | Reuters

    But is it really a matter of blundering or is there evidence of nominal partners working at cross-purposes?

    Upgrading a mobile device is technically challenging. There are many things that can go wrong. Integration helps, but it is also possible for a modular solution to be implemented. There are harder things to coordinate.

    However, things go wrong and as the linked article above shows, fingers get pointed. Device vendors who have no stake in a platform can easily interpretan upgraded OS as one fewer hardware upgrade. Platform vendor's lament that device guys want to proliferate unique versions and act with passive aggression. Device vendors see the software upgrade cycle as increased support and engineering costs with no upside. Consumers don't know whom to blame and often turn to the operators since that's who they pay every month.

    The problem of upgrade failure is a symptom of a deeper dysfunction inherent in immature modular business architectures. It's not just that the brightest at Microsoft or Nokia or Google can't make an upgrade stick. It's that the upgrade is not universally beneficial to the value chain. To remedy this, licensors have to resort to contractual obligations to ensure upgrades, but enforcement is non-trivial and can lead to aggravated relationships.

    Unless all licensees of a platform find compelling value in shouldering the burden of upgrades, they will continue to be really hard. This leads to increasing fragmentation and a corrosion of platform value for licensed platforms vis-à-vis their integrated alternatives.

  6. Pattern recognition for smartphone investors

    Research · 42 comments

    I spent the last few days in Hong Kong at a conference discussing the smartphone industry. The participants were mainly investors or investment managers. One of the most frequently asked questions was how to spot investable trends in this notoriously unpredictable sector.

    The data I presented did not offer much of an answer. If anything, it showed just how much the industry has changed and how unlikely it is to remain a facsimile of what it is today.

    But theory allows us to still make some bold claims. Grounding your investment thesis in pattern recognition rather than extrapolation should be the better strategy. So here are the telltale signs I recommend watching for investable ideas.

    1. In hardware look for what's not good enough. The smartphone is great. But it's not good enough for many jobs that we can recognize with little effort. For example, smart devices never seem to have enough battery life. Storage, screen quality and speed are pretty good, but battery life is worse than what voice phones offered years ago. Companies dedicated to improving battery technology or charging technology should be worthy of a bet. Breakthroughs in power saving will be much more valuable than breakthroughs in storage or processing speed or screens.
    2. Pricing needs innovation. Phone pricing is opaque, user unfriendly and often leaves buyers confused and angry. I use the word innovation instead of reduction because it's not about making prices necessarily lower, but removing complexity and defining value clearly through price. The challenge is not just for devices but for service providers as well. Companies innovating by abstracting pricing complexity will do very well. Interestingly, pricing innovation is not as easily copied as it may seem. It is often coupled with business model innovation and cost restructuring.
    3. Applications currently conform to platform needs but there will come a time when platforms will need to conform to application needs. By applications I mean not just apps but the app/service bundle that will drive consumer purchasing behavior. If we consider social media, entertainment and shopping as applications, it will make sense for those applications to eventually take some control or equity in the platforms. Android is the first sign of this: search and services associated with search and advertising sought control over platforms. Perhaps Facebook, Amazon and Baidu will feel a similar need.
    4. As a new medium, apps will eventually be more valuable than the tools used to render them. The global app brands are probably not yet born, but some day they will be as important as Disney, News Corp and Universal Pictures in their heyday. The App Store is the incubator for these embryonic megabrands.

    I realize that these are not specific enough investable ideas but casting your eye on patterns should yield better returns than selecting winners from a set of "current players".  After all the great returns from smartphones to date have come from bets on entrants (HTC, Apple, RIM) and not from incumbents (Nokia, Microsoft or Motorola).


  7. The pitfall in platform predictions

    Research · 52 comments

    It's a great misfortune that we don't have data about the future. It makes it hard to tell what's going to happen.

    It's even harder because although sometimes we have data about the past, the past and the future don't always look the same.

    Clearly that's what makes predictions about mobile computing platforms tricky. Nothing that has happened recently had been predicted by those who had tried to do so in the past.

    The difficulty is compounded if trying to forecast in the long term like 4 or 5 years ahead. The tendency is to extrapolate what has been happening to date.

    It's tempting to project whatever trends one sees into the future. The problem is that some trends are more visible than others.

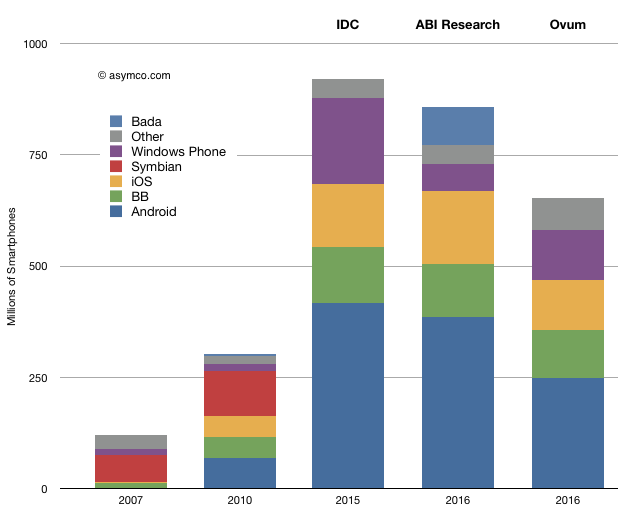
    For example, let's look at the following three forecasts (IDC, ABI Research and Ovum) projecting platforms for 2015 and 2016. Although there are some differences in magnitude of the entire market, there is a strong similarity between the forecasts and with the current trends[1].

    However, when comparing what was happening in 2007 with the market three years later[2] it's clear that most of the change was from the entry of iOS and Android (and a large expansion in RIM as well.)

    So how are we to be sure that there won't be another entrant between now and 2016? I presume the argument is that the market is "too big" for a newcomer to make an impact. This argument is equivalent to saying that some organizations are "too big to fail". That might has a right of its own.

    However, the evidence has shown that no Goliath has ever stood for long against a suitably equipped David, especially in technology.

    Given this knowledge, the pattern or trend that I see more than any other is that the future will be dramatically different than the past. This invalidates any forecast which assumes otherwise, including all those above.

    ---

    Notes:

    1. The primary difference seems to be with how to treat Symbian. Some forecasters are replacing it with Windows Phone while others are mixing in a bit of "other" and Bada into what used to be Nokia's share.
    2. It's quite pointless to try to compare 2005 with 2010 as on this chart's scale (bounded by 1 billion units/yr), the size of the market and the size of each participant's share are indiscernible. As pointed out earlier, predictions from that era focused on PDA market shares and there was no agreed-upon definition of mobile computing competitors.
  8. Google vs. Android Part V

    Research · 145 comments

    When I began the series of posts on Google vs. Android I put forward some questions about the business logic of Google becoming an operating system supplier, especially as that role can be seen as being counter-productive to Google's strategy.

    I noted three strategy costs associated with a zero priced systems software bundle.

    1. A opportunity cost with other platform vendors, namely Apple who might retaliate against Google's core business.
    2. Versions of the software being usurped and modified to provide distribution to Google's competitors.
    3. Damage to Google's brand and positioning and negotiating power in relation with other members of their value chain.

    More fundamentally, Google-as-systems-software is asymmetric to Google-as-cloud-software and contradicts the value proposition that Google enables value in the web not in accessing the web. Android appears to be a nod in the direction that systems software still matters.

    In my numerous posts on the need for integrated development in the era of mobile computing, I also criticized any device vendor that chose to rely on a software stack from an external supplier as foolish. I claimed that they would end up creating uncompetitive products. I thus labeled Google's pursuit of them as ultimately futile.

    More than a year has passed since I began this critique of Android. It seemed quixotic as Android volumes exploded and a mad rush to the platform spun it into becoming the biggest mobile platform by units.

    However those costs did not go away. As the platform grew, they compounded. At first I wondered whether Google management was seriously considering the cost or whether it was giddy with the semblance of success.

    Well, finally, it seems that Google management has begun to acknowledge that these costs exist. In a recent Bloomberg story there are many claims that Google is reversing many of the operating principles of Android. Namely:

    • Restrictions on who gets what version of software when
    • Restrictions on what changes can be made to the software
    • Requirements for approval for source code changes

    These changes, if feasible, will affect the ecosystem dramatically. It will also reduce the second type of cost associated with the platform (the cost of enabling competitors.)

    Good news for Google then.

    There are still the other problems (disconnect from business model, loss of goodwill, damage to negotiating power). But there is actually a more sinister new problem brought about with the new crackdown: Android will no longer be disruptive.

    I also wrote a few posts (e.g. What has Android done for Apple?) where I claimed that Android has the power to accelerate smartphone adoption, especially in the "Wild East." The power of Android was with the little vendors--the ZTE and Huaweis of the world. They could finally make smartphones cheaply--almost as cheaply as voice phones--and not have to negotiate licenses and pay for software IP.

    It would be these smaller "unbranded" vendors that would really disrupt and, with them, Android would become ubiquitous for the billions of mobile broadband non-consumers.

    However, with the new policies, it's much harder for this to happen. Smaller vendors will look at the new hoops they have to jump through and probably say "no thanks." In a beauty contest, they don't look so good next to the big brands.

    They may turn to homebrewed versions of Linux or new forked Androids. This redefinition of openness will essentially remove Google from the disruptive trajectory of mobile computing.

    So we're back to the old question: Google vs. Android, who wins? If Android still has hidden costs to Google and, with its sheep's clothing cast aside, no longer offers significant distribution to the low end then how will Google benefit? The answer that there will be additional ad revenue does not cut it. That revenue would have come from placement deals with other incumbent platforms (just like Google manages to compete on PCs without having to provide its own OS).

    As Google figures this out, its licensees are at the mercy of the ensuing decision. Good luck with that.


  9. The controversy of playing it safe: What's IDC's Smartphone Market Message?

    Research · 53 comments

    IDC released a new forecast for the worldwide smartphone market which included a long range forecast--all the way to 2015.

    Most people fixated on the share data in 2015. Not hard to do since whoever wrote the press release highlighted this flashy headline. Putting aside the three significant digits of accuracy on every data point and the hard to swallow declaration that a painfully underperforming (in more ways than one) Windows Phone will overtake iOS and BlackBerry to become the second largest platform by units/year in 2015, there is much more to the report.

    Using only the public data from the press release we can put together a pretty good picture of the transition being forecast and determine some of the (unstated) assumptions being made. It's these assumptions about the underlying market dynamics which illuminate far more than the falsely precise share data.

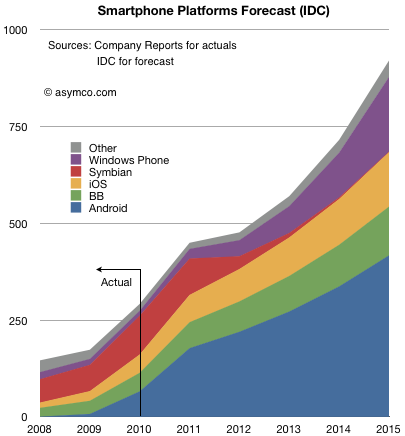
    The following chart shows both historic platform performance (which is detailed in the Asymco Interactive data sets on a quarterly basis) and the forecast based on the given compound growth rate published.[1]

    I see three main assumptions being made:

    1. Nokia (or more precisely Symbian) share will be swapped for Windows Phone. The transition period 2011 to 2015 shows approximately 150 million Symbian devices will be sold which is the stated goal for Nokia. IDC is making an assumption that the hardware vendors will roughly maintain their respective shares irrespective of platform dynamics and that Nokia will switch its share of users from one platform to another in a predictable way.
    2. iOS and BlackBerry will maintain share. Presumably this is also driven by hardware channel dynamics and relationships with carriers.
    3. Android will grow share slightly but the vast bulk of growth will come from market growth.
    4. Market growth is strong but undramatic.

    Overall this is not a controversial set of assumptions.

    Except perhaps that it assumes that the basis of competition in the market is unchanging. Of course it's well understood that the basis has shifted during the tumultuous 2007 to 2010 and forecasts made before the iPhone was launched sound absurd today.

    But IDC says that the unpleasantness won't happen again. From listening to the conversations going on today on this blog and elsewhere, their assumption that things will not change (again) is fairly deeply ingrained, indeed conventional wisdom. In that sense IDC is not taking any liberties with the future. The projections of current realities onto the future leads to this type of forecast and status quo defenders should be satisfied, if not rejoice.[2]

    However, there are a few more consequences of even this uncontroversial forecast which should make keen observers sit up and notice.

    If we look at more than the before and after snapshots and comfortable pie-splitting sound-bites there are some profound seismic things being implied.

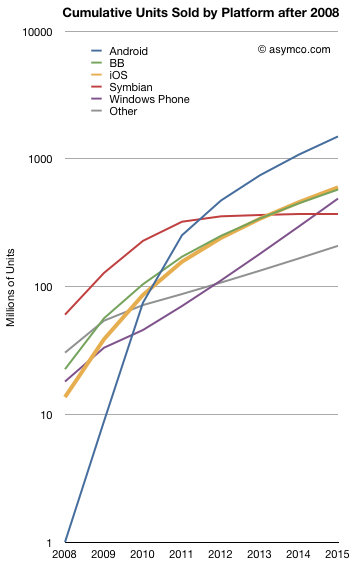
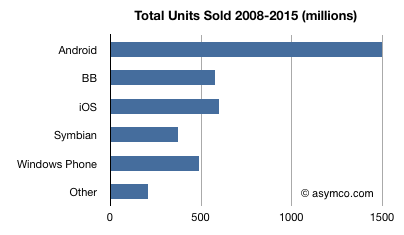
    For example the entire market will be nearly 1 billion smartphones a year (in four years!). Even more startling, considering the "race to a billion" discussion we've been having, some of the platforms seem to be reaching that threshold rather quickly. The following chart shows the cumulative unit sales for the candidate platforms on a log scale:


    Android is considered likely to break one billion units in five years post-launch. Windows Phone will sell nearly half a billion units and Blackberry will be well over that number.

    I tallied the cumulative platform unit totals below:

    No less than four platforms will have sold half-billion units by 2015. The suggestion that Android will "win" by having the most units sold seems as hollow as the suggestion that Symbian "won" by having the most users in 2008. Not so much because it will go on to lose them, but because there were plenty of viable alternatives for users to buy and developers to build for. Half a billion users cannot be easily ignored.

    So even "safe" assumptions can lead to astonishing results in this market. Namely, IDC is saying that the smartphone market will not have any platform losers.

    There is one more thing the report implies. If you look at the ranking of leading platforms (by units/year) in 2008,  2015 and, with a little extrapolation, 2016/2017 you get:

    Rank in 2008Rank in 2015Rank in 2016/2017
    SymbianAndroidAndroid
    OtheriOSWindows Mobile
    RIMRIMiOS
    Windows MobileWindows MobileRIM
    iOSSymbianOther
    AndroidOtherSymbian


    In other words, there is a complete reversal being projected. An almost perfect flip: those on top end up at the bottom and those on the bottom end up on top. That's about as controversial as it gets. Pretty impressive for a set of safe assumptions.

    --

    Notes:

    1. You should ignore the shape of the curve between 2011 and 2015 as it assumes the CAGR is applied to every year. Although the press release shows a CAGR, the actual report may include various fluctuation in yearly growth. The starting point of 2011 and the end result in 2015 however should be the same.
    2. If, on the other hand, you believe that exponential growth, rapid gains in communications speed, new breakthroughs in interaction with devices, and entrants winning with new business models are causes for a disruption, then perhaps extrapolation may not be the way to forecast this market.
  10. The Post PC era as explained by developer events

    Research · 38 comments

    The World-Wide Developer Conference is an event for developers. It is not a trade show and it is not a consumer show or an enterprise show for salespeople. Except for the keynote, all events are subject to Non-disclosure Agreements so it's not even an event whose proceedings can be discussed openly.

    It's also expensive. Registration is at least $1,500. Attendants are there to learn and ask detailed questions about development. It's not for deal making. People not familiar with development would not be well served by the event. Registrations are therefore somewhat limited to about 5000.

    After the iPhone SDK was launched, the WWDC took on a new dimension. It became a mobile development event. As a result, 2008 was the first year when WWDC sold out. Attendance tripled over the Mac-only event the previous year.

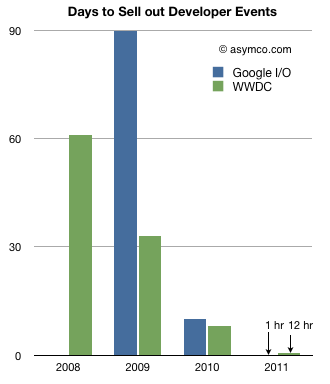
    Every year since, not only has WWDC sold out but it has sold out quicker every time. The following chart shows the days it took to sell out WWDC. I also added Google I/O data for comparison.

    In the era of the iPhone, the limited resource of attendant seats has always been exhausted at accelerated rates: from 60 days in 2008 to 0.5 days in 2011. A similar pattern emerged for the Android event.

    What should be noted is that these events are focused on post-PC development[1][2]. Clearly the increased interest among developers is for the mobile side of the business.

    Developers certainly seem to sense the way the wind is blowing. They are, as humans, prone to over-confidence but they are also often accused of being hard to please. The most common lament among new platform builders is "How do we attract developers?"  The platforms showcased here had no trouble attracting developers in the tens of thousands three years after being launched.

    The Post-PC era is evident in all kinds of data. This set (developer attendance to mobile development) is particularly stark. It's a proxy for investment and IT interest. There is a non-linear nature to this growth and history shows that non-linearity leads to unpredictable or unforeseeable change.

    ---

    Notes:

    1. WWDC still has Mac OS X tracks but that track was there pre-2008 and did not sell out the event.
    2. Microsoft hosts several developer events (PDC, MIX, and Tech·Ed) some of which also sell out, but they have a far wider focus.
  11. Understanding RIM's tablet platform app strategy

    Research · 135 comments

    Yesterday RIM reported their quarterly earnings. The results were mixed to slightly negative and the shares were down 10% in after-hours trading.

    I'll work through the smartphone market data at a later time but for now what I want to focus on is RIM's strategy which really means understanding RIM's intentions or their approach to the market. For that we have to go straight to the source: what management actually says. Trouble is, management often speaks in a jargon that is unfamiliar to people (sometimes unfamiliar to anyone outside the company).

    Strategy analysis involves translation. So here follows the interpretation of Jim Balsillie's remarks during the conference call (transcript sourced from Businessinsider.com).

    What Balsillie SaidMy interpretation
    First of all, what we announced is Gingerbread. This is not Honeycomb. I don't know what the number of Honeycomb apps is, but it's not very many. Whereas Gingerbread they've got lots of them.RIM will support Android apps in the PlayBook tablet. As there is not one Android, I need to clarify that RIM will not support Android tablet (Honeycomb) apps but Android phone (Gingerbread) apps. So RIM's tablet will support Android phone apps even though our tablet does not actually have a phone in it, but requires tethering to a BlackBerry for cellular data.
    You've got the volume of the handset apps, so if you're looking for the tonnage of apps, or some kind of long tail stuff, you've got it.This support means there will be many apps including apps that are not very popular. We don't like supporting unpopular apps. We like a few good quality apps but this approach allows us to offer all kinds of apps.
    At the end of the day, people are going to want performance.However, many apps will not run smoothly.
    You're just not going to get things like gaming and multimedia, you're not going to get the speed going through a VM interface. If you want content, or Flash type stuff, or you're looking at AIR-type, evolving web-type assets, that's what you're going to do.Games and graphics will not run well through emulation. For processor intensive experiences we will have native execution options or browser apps.
    There's no compromise here. You've got the tonnage of apps. And you've got the performance. Do I think the tonnage is overplayed? Yes.By supporting emulation of Android apps we can offer a large catalog of so-so apps while having a small portfolio of high quality native apps.
    But if you think it's about having a couple hundred thousand apps, there you goFor people who value large selections, they can go to one store.
    Do we believe it's about super high performance? YesBut for those people who value quality, they can come to our store.
    I'll just offer that observation that today broadly in the world without any specific comment on us or our competitors, there are multiple ecosystem patterns that need to be consideredBeside emulation and native we also think there are many other ways to deliver applications.
    Do we believe it's about full web fidelity? Yes.For example, Flash.
    These are concepts that were really relegated as not technically possible, which we're doing here. This is a no compromise environment.Because of Moore's law, Flash is becoming viable on a mobile device.
    If you want to work on Android, great. Do we think people will want to migrate web assets? YesThen there are browser apps.
    Do we think they're going to want super high performance native assets with the SDK? AbsolutelyWe will have our own native SDK.
    You think they're going to want to use their Flash based stuff for an offline Flash/AIR type environment? YesAnd support Flash.
    I'm just not interested in these sort of religious application tonnage issues.  I really think we put that issue to bed.We have a new platform but catalog sizes can no longer be used against us.
    And if you think the whole world's going to want to develop for Gingerbread, fine. Do I think that's going to happen? Then why is there a different environment for a tablet? And you know about the performance issues and you know about the app volume issues, cause it's tough. And that's why QNX mattersGoogle's ecosystem is fragmented, Android apps are not able to rely on competitive hardware and there is too much competition. That's why developers should target QNX (which is unfragmented, built on fast hardware and there are few apps on it).
    Is this stuff going to go more in the browser and HTML 5 and more native? These are going to be strong trends. But if you want these app players for different VMs -- and don't forget we have 25,000 BlackBerry 6 appsBrowser apps will increase in value and we also have legacy BlackBerry apps.
    So, at the end of the day, we believe this is going to be about performance. It's going to be about enterprise greatness.But we believe in a future with native applications running on QNX.
    Things like multi-threaded capability, symmetric multiprocessing. We believe it's about an uncompromised web. We believe it's about enterprise security. True multitasking, not with suspension -- and that matters because you're going to want to run these things in the background.Because QNX is a robust operating system with PC-like performance. It also supports a good browser.
    But I'm out of the religious war on tonnage, which I'm delighted.However, before QNX takes off, we will provide access to catalogs of apps which are built for other platforms.