In the mobile phone industry, and indeed, in most technology sectors, price decline is a fact of life. Component prices tend to drop while their performance increases. This rapid obsolescence drives prices down constantly. Competition also plays a part as undifferentiated products are rapidly imitated.
This phenomenon has its own term: price erosion. It's built into most business plans and forecasts.
But how real is it? What are the implications in terms of market share if one accelerates price erosion or reverses it?
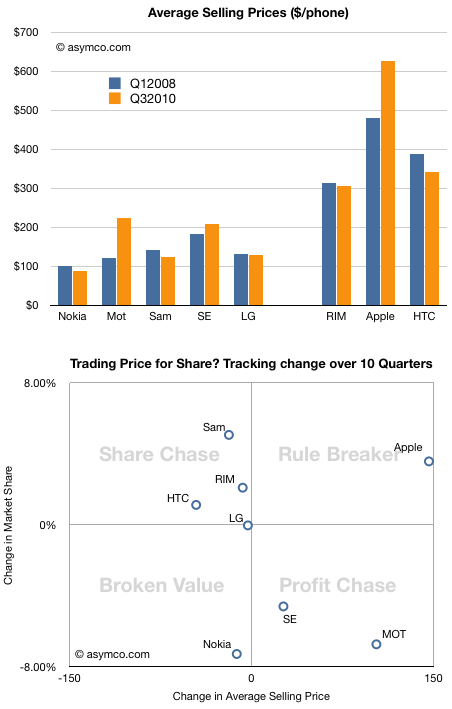
This chart shows the average selling price for all the vendors whose data I maintain over a period of time.
Normally, a drop in price is followed by an increase in share, and an increase in price by a drop in share. To test this hypothesis, I tacked on another chart that shows how share and price have been traded off in the market over the last ten quarters.
Note how prices have dropped for all but three vendors. Two of those vendors (Motorola and Sony Ericsson) have lost share. One, Apple, has gained share. The rest, whose prices did drop, had increases in share, very roughly in proportion to the price drops. Again, we have one exception, Nokia, which suffered both price and share loss.
Except for these two anomalies, the vendors are placed on the -45 degree diagonal that would show expected price elasticity in the market.
I took the liberty of breaking the chart into four quadrants, and gave them names suggesting the strategies of the companies.
Lying along the traditional trade-off axis are either Profit chasing or Share chasing strategies. Anomalies off the axis are either Rule Breakers or Broken Value propositions.
This view of the companies allows us to abstract and think about market evolution.
It would be interesting to think how these players will evolve over time.
It's quite possible that LG will move into the profit chasing model (as they already indicated they would by building more smartphones). These strategies are typical of companies squeezed from the bottom and the top. I once called this group "the biggest losers" and suggested that they are the best target for Android.
It's also possible that Nokia will move into the same quadrant, though their profit algorithm favors share above all else.
The biggest question is whether Apple's rule breaking is sustainable. It's not clear whether they are interested in share as that does not have all that much to do with their definition of "greatness". But a platform strategy begs for volumes.
This remains the biggest puzzle facing observers of this market.
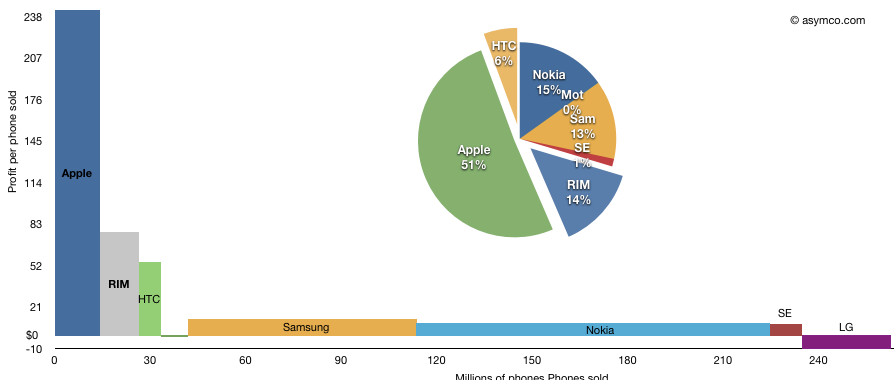
The following chart shows the third quarter's profitability of eight top phone vendors as a measure of phones sold multiplied by profit per phone.
I've added the pie-chart showing the rectangular areas as a percent of available profit in the peer group. Note that LG losses are excluded from the pie chart but included in the area chart.
The total area represents total profit. This representation shows how the largest vendors make relatively little profit per phone but the large unit profit for Apple and RIM gives them a significant share of total industry profits.
LG saw its profit fall apart today as its summer results were hurt by its weakness in phones. Its profit plunged 99 percent, down from $805.6 million a year ago to $6.7 million. The Korean company was dragged down by its mobile group, which had a record loss of $270 million. The company's total phone shipments also dropped, going down 10 percent from year to year at 28.4 million.
Sales from its handset business climbed 20 percent to $2 billion last quarter, helping to narrow its loss to $43 million from $216 million a year earlier. The division had an operating profit, excluding some charges, of $3 million. Motorola said it shipped 3.8 million smartphones last quarter.
Motorola shipped a total of 9.1 million phones. This is down 33% from the year-ago quarter's 13.6 million units but up 10% sequentially from 8.3 million last quarter.
I'll summarize the top tier vendors' unit volumes, sales value, price and profitability in a few days.
After the last earnings report, many noted that Apple's gross margins dipped. Turley Muller noted in a letter to PED that the cause was probably the aggressive ramp in iPhone 4 production which broke new records at 14.1 million units.
That may be. My estimate of iPhone margin shows it dropping to about 49% from the more usual 55% (sometimes even higher). We'll never know exactly how much, but sometimes margins drop. RIM and Nokia are punished for drops in the GM percent so why shouldn't Apple?
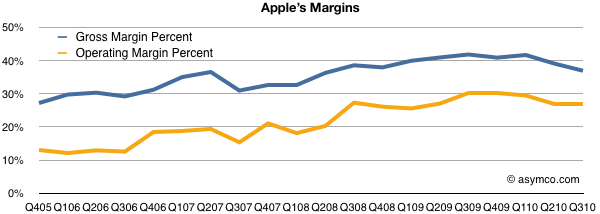
However, there are some other factors to consider: the overall margin is currently historically very high. As the high-margin iPhone makes up more of the total product mix, the overall margin should be growing. And it is. The chart below shows the trend since 2005. GM was in the high 20's five years ago.
Note however the other margin: operating margin. After taking the fixed costs into consideration (which we saw to be shrinking as a percent of sales), Apple's bottom line profitability has been rising slightly more rapidly than the GM. It has plateaued recently but not dipped significantly.
Also note that there have been dips in the past from which GM expansion resumed. One such dip was at the launch of the first iPhone in 2007, though we can't be sure that was attributed to the iPhone itself or to other factors like that most cited by management: components costs.
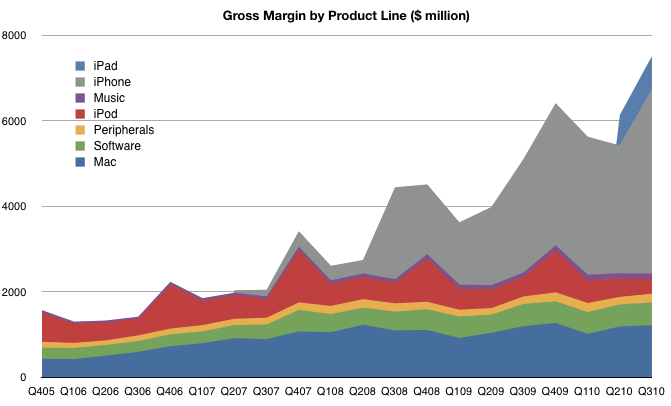
However, the bottom line profitability is only part of the picture. It would be instructive to look at which product contribute how much. You won't see this analysis often because the gross margin by product is not published by Apple and it takes quite a bit of guesswork to get there.
I maintain product-level gross margins and compute the overall GM bottom-up. The product-by-product line profitability is based on several assumptions which I won't detail here, but those assumptions lead to the following contribution chart:
There are several takeaways here:
The iPhone is huge (57% of gross profits). It is far more important than most people assume. Without it, the company would not have materially grown EPS since 2007.
The "Music" which includes iTunes revenues is tiny. Many people assume that iTunes is a large contributor to Apple's operating profitability but operating margins on the store are 10 percent. Peripherals add more to the bottom line than the iTMS/App Store. The benefit of the iTunes/App Stores is in the hardware sold.
Software contributes more now than the iPod. This is completely under everyone's radar but Apple's software business has been growing and with 80% gross margins (assumed) it's a big part of the profit picture.
The iPad margins are lower than the iPhone. As it grows in volume, the profit share will grow, but it's a long way from being the profit share leader.
This picture should also be a warning to Apple's competitors. If they seek to grow shareholder value and shift profits away from Apple they need to see just how much of that profit is captured in hardware. At the same time, they need to realize that it's the non-hardware businesses which make the hardware so desirable. Like it's products, Apple's income statement is very inter-dependent.
One of the most hotly debated subjects in the mobile phone business is the importance of market share. It's also a topic of lore in the PC industry. Briefly the two arguments are:
Market share matters more because it drives network effects which ultimately drive competition out of the market, creating the opportunity for monopoly rents.
Profit share matters more because profit is the only fuel that can drive innovation. Any macro downturn or shift in strategy can cause a company to cease investing in unprofitable projects.
The old disruptor's adage: "Be hungry for profits and patient for growth" is challenged by the equally disruptive: "Grow share with lower prices in exchange for new revenue sources."
There are many rich anecdotes to support each strategy, but how about some data? Fortunately we have some: the market and profit shares for vendors covering 80% of the world's largest technology market over a three year period. The vendors are a good proxy for the market, the time frame is long enough to cover seasonality and anomalies and the market is very big (over 1.2 billion devices) and very broad (world-wide).
The only question is how to measure success. One measure is how various strategies benefit the asset owners, i.e. the share holders. Benefit to society, employees and consumers are very difficult to measure. But share holder benefit is easily obtained by measuring change in share prices.
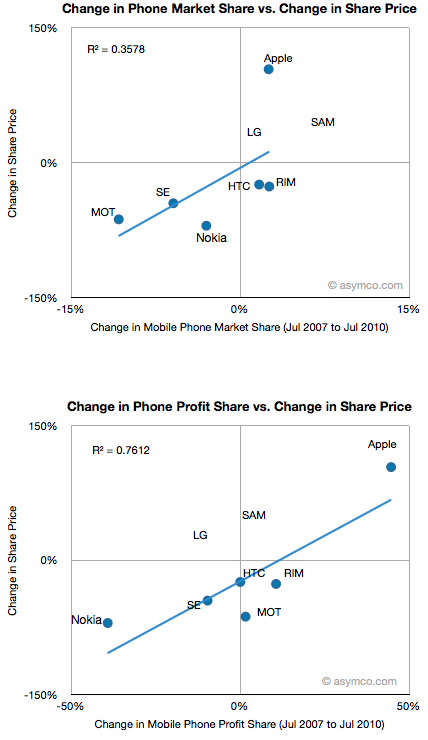
So, here are two charts:
The percent change in market share vs. percent change in share price for the top mobile phone vendors.
The percent change in profit share vs. percent change in share price for the same vendors. (see note 1 for time frame discussion).
I showed the R-squared value of the correlations. (See note 2 regarding LG and Samsung). At r-squared of 0.36 share price is not well correlated to market share while at 0.76 it is rather well correlated to profit share. To a financial analyst this would seem obvious. After all, share price reflects the present value of future cash flows which are clearly coupled to profit and hence to profit share growth. However, as many technology observers would point out, market share determined the success of Microsoft and Google, and to some degree Nokia.
High market share can cause competitors to be starved of components or ecosystem developers. At the same time, high profit share can cause competitors to be starved of capital.
What does this analysis add to the argument? Note that this data covers a hardware business. Is hardware relevant? It does not scale as rapidly and has a short shelf life. It's also notoriously difficult to distribute. However, outside of the service revenues for cellular voice and data, device hardware is the only pool of money that has any material dimension in the industry. It's also the pool of money with the highest margin in the industry. For the time being and the foreseeable future, hardware is the only business model worth anything in mobile computing.
The data shows that in this particular but substantial market profit share is closely correlated to shareholder value creation. It also shows that profit loss is closely correlated with shareholder destruction. The dominant data comes from Apple and Nokia, which appear to be polar opposites in performance on both measures.
In other articles I've shown how profits have shifted from incumbents to entrants in the smartphone disruption. This shift has resulted in direct benefit and loss to the owners of the two asset classes. To suggest that market share alone is a determinant of "success" in the device market must exclude the effect on shareholders and, ultimately, the management and employees of the companies concerned. The virtuous/vicious cycles will be fed by the profit variable more than any other.
I don't think the market share argument holds water in this market and this data supports my belief. It may be that as value shifts over time away from hardware the benefit will shift as well, but business models alternatives to hardware have not emerged after ten years of experimentation. If anything, the idea of selling hardware as a way of capturing service revenue was pioneered by RIM and perfected by Apple. Nothing I've seen so far is challenging this model. Whoever attempts to siphon the device pool of money (which has remained fairly constant over the smartphone disruption) needs to solve system-wide problems like the dependence on the network and the life-cycle of portable electronics.
----
Notes:
The dates when performance was sampled are are July 1 2007 to July 1 2010. The latest quarter (3Q10) has not been included in this data as it has not been fully reported. The data will be updated with the latest quarter as soon as it's possible.
For many competitors the share price is dependent on more than performance in the mobile phone market. In particular, LG, Samsung, Motorola and Apple have diversified product lines which affect their share prices. Two of those companies (LG and Samsung) are conglomerates and their share performance is dominated by businesses other than mobile so I did not include their data in the correlation measure (though their place on the chart is shown). Motorola and Apple's stock prices were, to a very large extent, driven by their mobile phone performance over the same period so their data is included in the correlation analysis. The other vendors have been primarily focused on mobile phones.
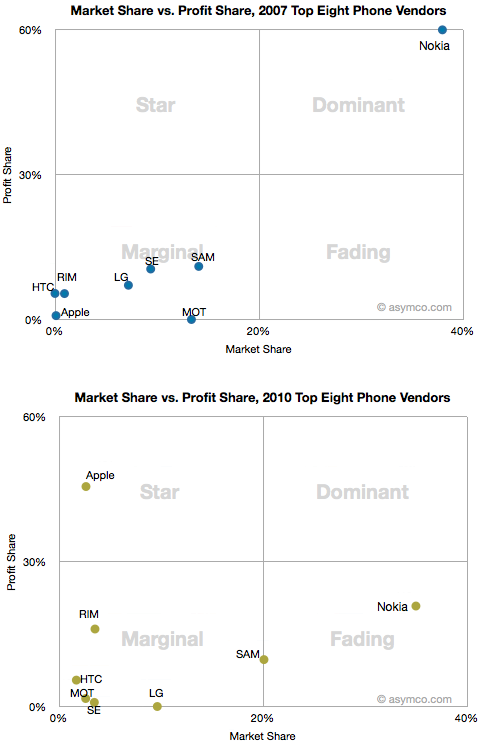
I plotted the vendors on share of market and share of profit axes in two different points in time: Q2 2007 and Q2 2010. I further broke the chart into four quadrants as shown:
I chose to label the quadrants to indicate the possible categorization of the companies.
Dominant: large market share and large profit share
Star: low market share with large profit share
Fading: high market share with low profit
Marginal: low market share and low profit
It's interesting to note the shift over the time period of the eight vendors. Whereas Nokia moved from Dominant to Fading, only Apple rose from Marginal to Star. The Marginal players dispersed their placement with Samsung moving laterally toward Nokia while RIM followed in the Apple trajectory and increased profit share while maintaining relatively low share.
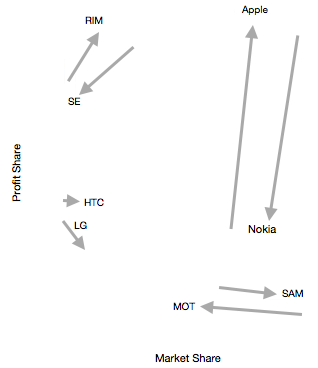
Thinking about motion around these two dimensions could be reduced to a vector model. If each vendor is represented by an arrow showing direction and distance moved, we can compare each vendor vs. a symmetric competitor which might account for the loss or gain of share.
The vectors can be paired as follows:
Although the data does not contain all market participants, the shifts in share are quite closely conserved with the vector magnitude (arrow length) and angle (direction) paired. Note how Nokia and Apple swapped Profit without too much impact in Units volume. Similarly, RIM and Sony Ericsson traded profits and volumes quite symmetrically. Samsung also took volume while Motorola lost it. HTC and LG did not change positions dramatically.
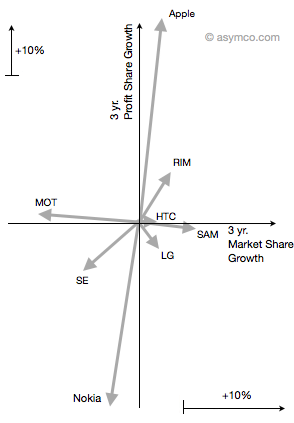
Finally, moving all vectors to the same origin leads to this view of share gain/loss over three years in two dimensions:
It becomes quite easy to see who the winners and losers are and by how much.
This model is only an observation of the shifts in market power and is not conclusive about where share was gained or lost, however there is compelling symmetry which also matches the intuition of observers.
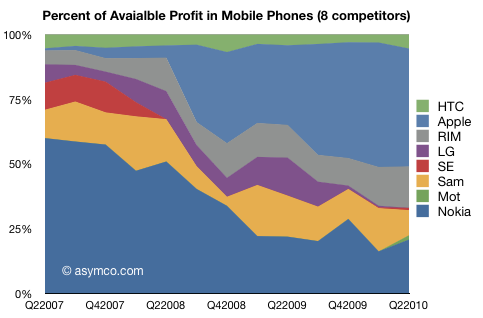
A quick update on the analysis of mobile phone profits. If the available profit[1] (i.e. excluding losses) were summed and each vendor's profit were measured as a percent of this total, this chart would tell the story of the last three years:
Note that profit share has mostly shifted from Nokia to Apple, though Sony Ericsson and LG were also casualties and Motorola has not had anything to lose.
Some assume that the future belongs to the Koreans but we see that the relatively small amount of profit that Samsung has (less than RIM actually) has not changed much. HTC is also shown to be a steady performer but not having displaced much from competitors.
Will Android change this picture? As I've argued before, Android is most attractive to the unprofitable and the strategically constrained. Can having undifferentiated new products change this? As Nokia is unlikely to license Android, and RIM seems very unlikely and Apple is out of the picture, the only possible contenders are Samsung, LG, HTC, Motorola and Sony Ericsson.
Motorola and Sony Ericsson have both returned to profitability but with a very small volume Android strategy. However the incumbents fielding Android are really facing a far more sinister threat: the smaller local brands in China (e.g. ZTE) and emerging markets.
On profitability, the smaller challengers are unlikely to make a large impact, but they will constrain the profits of other licensees. The distribution of phones on a global scale is challenging without a brand, and brands are very expensive to build. It's still possible over a longer timer frame that a small brand like HTC can emerge on a global stage. But in terms of profit capture, challengers will mostly "steal" from the already constrained big brands running with Android.
--
[1] Profit is not the only measure of success and can sometimes be a deceptive indicator. For this reason I look at a longer time frame so that anomalies, seasonality and business cycles are smoothed over. As flawed as it is as a measure, the most important reason to pay attention to profit is that it's the only fuel for growth in the long term. Companies that are consistently unprofitable (e.g. Motorola) face diminishing degrees of strategic freedom further lubricating a downward slope toward financial distress.
As previously described in an earlier piece on the transistor, there is a theory that underlies much of what this web diary is about. Telecommunications is undergoing wrenching change. And not for the first time. The history of the industry is filled with disruption and thus with drama that leads to fine storytelling.
One such great story is that of Western Union and the telegraph.
Western Union was formed as a company in 1851 and ten years later had completed the first transcontinental telegraph line. Following on that breakthrough, it introduced the first digital real-time data service, the stock ticker, in 1866. Business boomed and by 1870 it was the world's most powerful telecommunications company.
By any standards it was innovative: it offered remarkable and revolutionary telecom data services, a century before the Internet. But in the century that followed why didn't Western Union become the leader in voice communications, ceding that position to the Bell companies?
Alexader Graham Bell did not invent the voice telephone with the intention of toppling Western Union. In the language of today's technology entrepreneurship he hoped Western Union would be his "exit". He pitched the phone to them as an improvement to their core telegraphy business. Bell offered the patents for the telephone to Western Union for a mere $100,000, roughly $2 million in today's dollars. In other words, today the deal would be: two million dollars to own all voice IP.
Western Union passed
Now why would they do that? Imagine you are an analyst at Western Union advising management on technology acquisition and M&A. What process would you use to evaluate it? First, most obviously, you would try to get feedback from marketing and sales. They should go out and survey their customer base to find out who would be interested and how much they would be willing to pay.
The sales force would naturally seek out their best customers and ask them first. Those customers were the stock ticker users. They were extremely voracious users of the ticker tape system. It should be no surprise why we have "ticker tape parades"--there was enough of the stuff lying around offices in New York to shower down and flood Broadway end-to-end". Ticker tape was a boon to merchants and traders. Chicago would know what's happening in the New York stock exchange instantaneously. Price data was traveling at the speed of light. The sender and receiver were in lock-step sync. To suggest to these customers a voice product would sound like a step backward. Why would they want to talk to the other party? The data was coming on tape and it was also recorded for posterity. Speaking with the other person meant confusion and delay and a mess of record keeping.
The word from the customers would be a resounding negative.
Second would be the business model. How would you charge for voice? Data was subscription based, and the fees were huge. Voice would be metered and the price low. If targeting consumers, telegrams were priced by the word, but you couldn't price voice by the word. Marketing would stare back at you as if you had committed a judgement error.
Thirdly you would look at the cost side. Operations would give you more bad news. Voice technology was different enough that it needed new infrastructure. Switchboards, operators, handsets and new power and insulator requirements were all expensive and had no clear return. Voice was a loser all around.
So the decision was perfectly reasonable, smart even.
This is not to suggest that Western Union did not accept any new technology or invest in it. For decades after the phone, Western Union continued to invest in innovation: It introduced an electronic payment system (called money transfer) in 1871. In 1914 it offered the first charge card and in 1923 it introduced teletypewriters. Singing telegrams followed in 1933 and fax service in 1935. Intercity wireless microwave communications were introduced in 1943. Telex came in 1958 and the product of marketing genius, the 'Candygram' in the 1960s. By 1964 its network was all wireless using a transcontinental microwave system. Western Union became the first American telecommunications corporation to maintain its own fleet of geosynchronous communication satellites, starting in 1974. The fleet of satellites, called Westar, carried communications within the Western Union company for telegram and mailgram message data to Western Union bureaus nationwide.
And it wasn't lacking in talent either. Western Union had the best telecom managers in the business and was raking in profits to fund expansion. It attracted the best and brightest engineers for generations. Western Union probably passed on hundreds of other inventions and ideas, and rightly so.
So what happened to WU?
It's still around. However, due to declining profits and mounting debts, Western Union slowly began to divest itself of telecommunications-based assets starting in the early 1980s. Due to deregulation in the US, Western Union began sending money outside the country, re-inventing itself as "The fastest way to send money worldwide". In 1987, an individual investor acquired control of Western Union through an outside of chapter 11 process that was a complex leveraged recapitalization. After several other changes in ownerships and moves through bankruptcy, WU is now a public company with an enterprise value of about $12 billion based entirely on international money transfer business.
3G as a disruptive technology
Today we've come around full circle. Whereas voice was disruptive to a data network provider in the 20th century, data is disruptive to a voice network provider in the 21st. The mis-application of 3G network technology to sustain voice-oriented business models gives one a strong sense of déjà vu.
The telecom world moved swiftly to 1G and 2G cellular voice. Each new generation of mobile telecom was sustaining the core business model of subscriptions feeding centrally managed networks and symbiotic device vendors benefiting from handset and switching system upgrades. Standardization, international expansion, lower price points and network effects made this industry the most ubiquitous technology distributor the world had ever seen.
3G however was different. It was effectively mobile broadband data. It enabled data services to be de-coupled from the network operators. IP protocols did not require the servers to be located on operator premises or even to be managed or monitored by them. Devices could be general purpose computers not specific purpose communicators. Incumbents did not adapt to this well. They continued to build business plans according to a central-switch blueprint.
So although incumbents did not reject the smartphone as a technology, they tried to make it sustaining when plainly it isn't. They essentially tried to cram it into their business models.
The struggle to keep the service structure of telecom centered around the network operator will continue, but short of pulling the plug on 3G and LTE, there is little that the incumbents can do to stop it.
So what's the lesson?
Some technologies are embraced and some are rejected. You can't fault every rejection and you can't praise every acceptance. The most likely reason for embracing something is that it helps grow your existing business. The most likely reason for rejection is that it may harm your business. Even acceptance sometimes leads to mis-application in sustaining the core rather than planning for its demise.
The decision on how to handle something new and potentially disruptive requires a different sense of what's right and wrong about it.
--
Photo: Former headquarters of WU, located at 60 Hudson, New York.
LG Doesn't See Return To Operating Profit Until Early Next Year
By Roger Cheng and Jung-Ah Lee Of DOW JONES NEWSWIRES
SEOUL (Dow Jones)--LG Electronics (066570.SE), which readily concedes it is late to the smartphone game, said it plans to launch 10 more smartphones and sell 5 million devices by the end of the year as it scrambles to catch up with the rest of the industry.
But the aggressive move, which includes increasing the research and development budget by a third and ramping up its spending on marketing, means the company's once-flagship mobile devices unit won't likely return to an operating profit until early next year, said Chang Ma, vice president of marketing for the division.
"We have to just bear it," Ma told Dow Jones Newswires on Wednesday, adding that he hopes to see a turnaround after the fourth quarter.
The mobile phone market is intertwined with the telecommunications industry which is vast and there are numerous competitors which are much more dynamic and better capitalized than the moribund PC or music player vendors. It’s also a regulated and fragmented global market with 1.2 billion units and 5 billion consumers—far greater than any of the markets Apple played in for its first 30 years.
Nevertheless, the iPhone has had a huge impact on the industry. To show just how much of an impact, I dove in and pulled over 500 data points on three years’ financial performance of seven competitors responsible for 80 percent of units being shipped today. The time frame covers the iPhone’s participation in the market so it allows for “before-and-after” comparisons.
Now I turn my attention to draw a bottom line from all the data above, namely the operating earnings (EBIT or Earnings before Interest and Taxation).
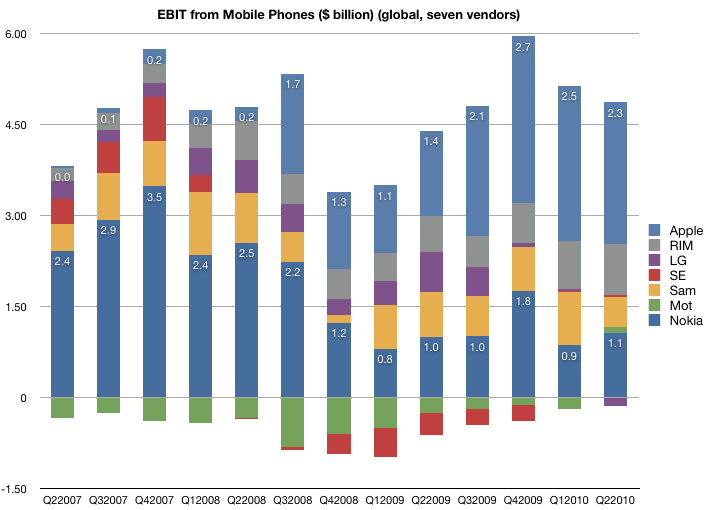
The first chart shows the EBIT from the top seven vendors of mobile phones since the quarter when the iPhone launched. I annotated Nokia and Apple's bars to give perspective.
The total available profits in the industry dipped to a bit under $4 billion at the trough of the recession, and have recovered to nearly $6 billion in the holiday quarter last year. However, not all vendors are profitable. As you might expect from looking at the operating margins, Motorola and Sony Ericsson have been generating losses for most of this time period. They have both reached profitability in the last quarter, though at very low levels and after having lost a large part of their sales. LG has turned negative this past quarter after being a modest earner for some time. Samsung has maintained a fairly even consistency in its profit capture, though with its expanding market share, it seems to have come at the cost of pricing.
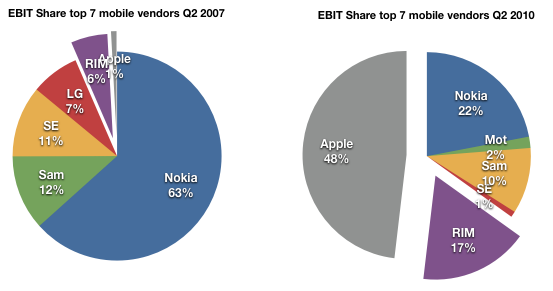
Finally, looking at the pure smartphone vendors RIM and Apple, the picture is nothing short of astonishing. This before-and-after share-of-available-profit chart shows that the two entrants went from about 7% profit share to 65% in three years.
Apple in particular is capturing about half of the available profits with three percent of the units. It dwarfs all the other vendors, more than double the nearest (Nokia). All that in three years and with the added burdens of only three models, a recession and limited distribution.
What does it all mean?
Here are my conclusions, enumerated:
The lack of a real response. The recurring theme in this series of articles has been that giant multinational incumbents in a vast and rapidly growing industry, enjoying all the advantages that size and incumbency, have had their profits taken from them. And they don't seem to have put up much of a fight.
It's all wealth transfer. Note the total amount of profit available has not increased markedly; this is not about incumbents growing the pie. Two thirds of what should have rightly been theirs moved from the incumbent shareholders to the entrant shareholders.
Speed. This shift of profit occurred over an unprecedentedly short period of time. Three years is no more than two product cycles in the industry and it's an order of magnitude faster than what happened historically to other industries.
Disruption is the diagnosis here. The incumbents were caught in the headlights. Disruptive innovation leads to asymmetric competition and this is what we just witnessed. History has shown that the shift of profits is usually the last stage of disruption and is usually irreversible because the change in business models cannot happen at the rate of change of profit transfer.
Which leads me to one final point.
When analyzing the potential for challengers to the new winners, the most cited is Android. Can Android affect this redistribution of profit once again? And to whom?
If Android is to become the dominant platform, does it depend on the success of its licensees? Who are these licensees and what are the chances that they will be able to align their businesses to what Android offers (a new revenue model based on services and advertising).
One problem I see is that Google is making a bet on those same vendors who are now squeezed in the middle of that last pie chart: Samsung, LG, Motorola and Sony Ericsson. Nokia, Apple and RIM will certainly not take the OS over what they already have as it dilutes their differentiation and margins. That means Android is aligned with the biggest losers in the industry.
So how likely are these disrupted ex-giants to recover and take Android forward? My bet: slim to none. Android does not offer more than a lifeline. It is not a foundation for long-term profitability as it presumes the profits accrue to the network and possibly to Google. Profit evaporation out of devices to Google may be a possibility at some time in the future, but only if the devices don't need too much attention to remain competitive. But because they're still not good enough (and they won't be for years to come), it's certain that attention to detail is what will be most important to stay abreast of Apple.[1]
So here we have the real challenge to Android: partnership with defeated incumbents whose ability to build profitable and differentiated products is hamstrung by the licensing model and whose incentives to move up the steep trajectory of necessary improvements are limited.
In other words, Android's licensees won't have the profits or the motivation to spend on R&D so as to make exceptionally competitive products at a time when being competitive is what matters most.
[1]: I would argue the same lack of symmetry with licensed software vendor Microsoft is what led the the failure of the same incumbents to make a dent in the industry with Windows Mobile [2003 to 2010].