
Asymco

Asymmetric Intelligence

smartphone

  1. FaceTime and the elevation of emotion over function

    Research · 8 comments

    With 50 million clients installed likely this year, FaceTime is a service which may have potential.  By potential I mean, of course, its potential to make a dent in the universe, the universal goal Jobs has set for Apple so many years ago.

    It's entirely possible that FaceTime will be an inconsequential nice-to-have enhancement to the iPhone platform that sustains and improves the iOS (and OSX) franchise. But it's also entirely possible that FaceTime could become a disruptive challenger to the functional voice-oriented telecom network.

    What you choose to measure determines what you know

    The thing that jumps out at me is the service's under-performance along metrics that the industry defines as critical but over-performance on dimensions that the industry considers non-critical.

    It suffers from poor coverage (WiFi only), a limited network of possible users, high bandwidth requirements which are still hard to match and a steep price point for initial entry.

    But I would say data-oriented devices were similarly met with poor performance 4 to 5 years ago. No 3G, poor coverage, few services and high prices. Even today there are many telecom skeptics who think smartphones are toys for the well-to-do or IT types and not something for the mass market.  As can be easily seen however, all the shortcomings of the mobile-data-oriented-device (aka smartphone) turned out to get ironed out with time. You just need to plot a historic graph of network performance and device price points to see where they're going to go.

    On the other side of the equation FaceTime offers huge performance on the dimension of emotional attachment to a device and to a conversation. The FaceTime experience is qualitatively distinct from either desktop video chat or device-based VoIP. It's intimate, emotional and stirring, (just look at the commercial) not to mention accessible by just about anyone. These new measures of performance cannot yet be quantified with spreadsheets and measuring the effect will not be a priority for anyone in the industry for a long time to come. Therefore, the asymmetry is there implicitly.

    So here we have classic Apple: shifting of the basis of competition so subtly that it's almost imperceptible while under way yet glaringly obvious after the fact.

    So what does FaceTime have to do with FaceBook?

    When FaceBook launched, I don't recall observers predicting that a site allowing college students to keep track of their friends after graduation would grow into the stickiest site by time spent online ever seen. Nor that it would become a site that swallowed all online communications including IM and email. Nor a site that would possibly challenge search consumption. The performance attributes that FaceBook relied on were not in algorithms but in the emotional hooks that relationships have with people. FaceBook was personal, emotive and private, the exact opposite of what the Web offered a decade ago.

    So, like the names imply, both these services are about Faces, the first objects we as humans recognized after birth. That's a powerful image to have a handle on.

    The pattern that emerges is that Web 2.0, Telecom 2.0 and Personal Computing 2.0 will pivot on the elevation of emotion over function. That may be a banality but empires have been built on less.
  2. When will the smartphone become a commodity?

    Research · 21 comments

    I am taking a comment thread and promoting it to an article so as to expose it to a larger audience. There are two points of view:

    Ariel writes:

    I believe that next year and perhaps the year after that will see intense competition on the OS platform front, but eventually one will dominate the other(s) by a significant margin (and this also depends on the cloud and how it will be adopted across platforms). This happens as a result of a unified platform in which many can compete on lower margins instead of the development of the entire package and platform, which all goes hand in hand with commoditization.

    However, to predict that smartphones will not be commoditized within the next three years is bold to say the least. The desktop was settled very quickly, and in this industry of exponential growth, it can be assumed it will not take longer for a similar scenario to settle.

    I reply:

    I’ve been observing (professionally) the smartphone market from its inception and was holding my breath for the commoditization of handsets that Microsoft promised all the way from 2004 through 2009. Several generations of Windows Mobile were predicated on the imminent stabilization of hardware and user experiences years before the iPhone came along. Not only Microsoft but Palm via PalmSource, Symbian as a consortium of all incumbents, Sun & IBM via Java, DoCoMo with iMode and not least of all, Qualcomm with BREW all made the same bets and ran with horizontal strategies toward a smartphone future built on the lessons of the PC industry. The only holdout for the integrated approach was the one company that everybody marked for dead: RIM. It’s also the only one who raked in all the profits.

    All this happened before 2007.

    To suggest that this time, in 2010, it’s different: that the definition of the smartphone as it exists today is the product at its zenith; that user experiences and expectations and hardware specifications and platform dynamics will be henceforth frozen with minor sustaining tweaks to look forward to is, in my opinion, a far riskier bet.

    I don’t try to be a futurist or predictor of how the product will evolve, but I can see a dozen ways of how the very definition of a smartphone will change and how in 4 years we’ll have products that won’t be recognizable as such today.

    So much depends on when the smartphone (or more broadly mobile computing) reaches this point of good enough. It's at the root of all hypotheses of how the market will evolve.

  3. Gartner: Symbian will lose smartphone battle, Microsoft's standardised handsets will win the day

    Research · 8 comments

    I had to do some digging to find this to contrast to the recent Gartner prediction that Symbian will be the market share leader in 2014.

    The following article appeared in 2003:

    Symbian will lose smartphone battle

    By Rob Jones at Gartner Symposium ITxpo, Cannes [07-11-2003]

    Microsoft's standardised handsets will win the day, says Gartner

    Analyst Gartner has warned that, without a concerted effort by Symbian and its backers, Microsoft will sweep them aside in the smartphone business.

    Redmond's ability to offer standardised handsets which are easier for businesses to support and use will help the software giant win corporate approval, the market watcher predicted.

    Nick Jones, vice president and research fellow at Gartner, said that, while Microsoft did not have a good corporate smartphone today, he believed it would do by the end of 2004.

    The analyst predicted that Microsoft will ship a phone boasting strong integration of a range of packages, such as Exchange and Outlook.

    Symbian, he added, needed to resolve a number of issues to be a credible, corporate alternative. Its platform and menus differ slightly on various handsets, which means that they often do not have the same user interface.

    "Symbian is not very committed to fixing this problem. So Microsoft is getting stronger and Symbian is not addressing the corporate market," explained Jones.

    "This is unattractive for chief information officers. They need standard systems and that's what Microsoft will provide.

    "If by the end of next year Symbian hasn't solved its problems, Microsoft will be a very strong competitor for a standard corporate smartphone.

    "Symbian could lose the battle and at the moment I'd have to say it will probably happen."

  4. Gartner Predicts Mobile OS Market Share

    Research · 15 comments

    Lots of people apparently think it’s a big deal that Gartner is predicting Android will surpass iOS for second place. But why is that necessarily a good thing, given that they’re predicting Symbian will remain in first place? Who thinks Symbian is actually doing well? Nokia’s board sure doesn’t.

    via Daring Fireball Linked List: Gartner Predicts Mobile OS Market Share.

    I also noted with amusement that by 2014 "other" is slated to sell 85 million units or nearly 10% share, up from 6.1% in 2009. These "others" will be selling more than twice what Apple is expected to sell this year. Is "other" WebOS, Bada, MeeGo, LiMO? If so they're in for a healthy future.

    But dwelling on details like these is missing the point. To see how improbable this prediction is, let's go back to 2006 and ask what Gartner was forecasting would happen now.

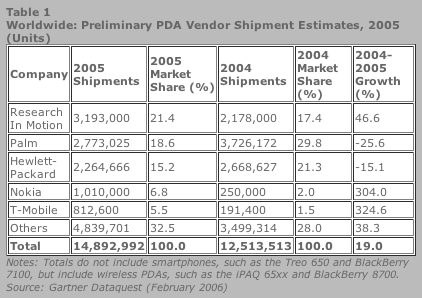
    First thing to note is that in 2006 Gartner was busy tracking PDA sales. You might wonder why this is relevant. The reason is because a significant proportion of RIM's Blackberries counted as wireless PDAs and were therefore considered to compete with Palm's Treos, HP's iPaq and Dell's famous Axim. Nokia was in the running with its Communicators. Here is how Gartner characterized the equivalent market in early 2006:

    So I'll just come out and say it: In 2006 Gartner did not have a clue what a smartphone was. By their admission:

    Gartner defines a PDA as a data-centric handheld computer weighing less than one pound that is primarily designed for use with both hands. These devices use an open market operating system supported by third-party applications that can be added into the device by end users. They offer instant on/off capability and synchronization of files with a PC. A PDA may offer WAN support for voice, but these are data-first, voice-second devices.

    In other words, in 2006 Gartner was splitting phones with operating systems into two separate markets: data-oriented wireless PDAs and voice-oriented smartphones. The split was mostly based on the judgement of the analyst on whether a device was "voice" or "data" oriented. I suppose they used the primary input method as a proxy: numeric keypads meant the device was one-handed and therefore voice-oriented. If the device had a full keyboard and/or a stylus-actuated touch screen then it was a two-handed data-oriented device. But even this proxy was not quite enough, sometimes devices were classified whimsically.

    To make it more complicated, they bundled non-cellular but Wi-Fi enabled PDAs with wireless PDAs. This made some sense from a corporate IT point of view (their primary customer base) as these data-oriented devices would be used either on a LAN or a WAN (Wide Area Networks: what Gartner anachronistically called cellular networks.)

    The presence or absence of a cellular radio did not enter into their view of these devices. So if you asked Gartner in 2006 to forecast smartphones (as we know them now) in 2010, I suppose you'd get what they forecast for "data-centric" devices.

    So assuming that today's smartphones are mostly "data-centric" we would have to look back on their view of that market and not the voice market which was seen as an entirely different thing. Their answer should have had something to do with the market leaders and participants in 2006. As the table above shows Gartner showed that RIM, Palm and HP led in 2005 with Nokia and T-Mobile[1] pulling up the rear.

    However, from a platform point of view, at the beginning of 2006

    Microsoft Windows CE was the No. 1 PDA operating system (OS) in 2005 as 7.05 million PDAs were loaded with the OS, up 33 percent from 2004 shipments of 5.28 million units. Palm OS PDA shipments declined 34 percent to 2.96 million units in 2005.

    In late 2006, Gartner made further predictions for the year:

    In 2006, Gartner expects the PDA market to increase by 6.3 percent to 16 million units. The market will continue to be driven by broader availability of cellular-enabled PDAs from wireless carriers. Gartner estimates that 53 percent of all PDAs shipped in the first half of 2006 featured integrated cellular capability, up from 46 percent during the same period in 2005. “The share of PDAs purchased by enterprises will continue to increase; it accounted for 49 percent of all PDA shipments in the second quarter of 2006 and Gartner expects that the enterprise market will account for 52 percent of all PDA shipments in 2006,” said Todd Kort.

    At this time I have not yet dug up a Gartner "Wireless PDA OS" four year forecast from the year 2006 but I suspect it would not show devices running Google's Android operating system or any running something called iOS.

    I also seem to remember that they were suggesting that Windows would be the leading mobile platform. Although it was trailing in 2006, Gartner was quite bullish on the disruptive challenger from Redmond.

    [1] T-mobile is in the list because it was common practice in 2006 for operators to market Pocket PC Phone Edition devices made by HTC under their own name. Orange, Vodafone and Verizon also had own-brand HTC Windows touch-based devices. Now what does that strategy remind me of?

  5. Why OPK was fired

    Research · 27 comments

    Under Kallasvuo Nokia embarked on the most dramatic shift in its business since entering the mobile phone business in the early 90s.

    The shift was not into mobile software which began in 2001 under his predecessor. It was not into enterprise solutions which also preceded his tenure. OPK's main contribution was the move into mobile services.

    The concept of mobile services may be an unfamiliar one for casual observers because it has not become a visible business for operators and certainly not for handset vendors. It's also a complicated business model that requires some deeper understanding of the way the telecom industry is structured.

    What Nokia had in mind was to offer various value-added, billable services to operators which would be enabled by Nokia handsets. The types of services included music subscriptions (Comes With Music), email (several acquisitions), photo sharing, and navigation.

    The idea was that since many operators would not be capable of rolling out own brand services and could not do the heavy back-end lifting or the integration with handsets, someone could step in and roll out white labeled solutions world-wide. Third parties would also find it impossible to integrate and would lack the relationships Nokia had with operators world-wide.

    For example, Nokia could enable a South American operator to offer email services to all their customers (with or without smartphones) and that service could be offered at a certain incremental price over the basic voice plan. The client implementation could be device independent but Nokia devices would probably work better. This would lead to higher ARPU which could be shared with Nokia.

    Anyone can see that this is a complicated business plan and is therefore unlikely to be successful. But what makes it a complete failure is the realization that most buyers will resist the idea of paying for individual services separately. $1/mo for email, $2/mo for music, $3/mo for maps, etc. is repulsive. Users stampeded instead to unlimited data plans and smartphones which offered all these services and hundreds more for free or at prices negotiated with third party providers, rather than the untrusted network operators.

    And therein lies the entire cause of Nokia's strategic failure: an operator centric point of view. It led to poisoned devices and irrational business plans.

    Which leads to the question in the headline. Is this mistake recognized and is it big enough to cause such a disruptive CEO dismissal?

    I argue yes. Strategic errors are forgivable, but the they become a capital offense when they turn into a derailment of the core business. Instead of being enhanced with value-added services, the core business collapsed under the disruptive attack of unlimited data.

    But it gets worse. Like the capital offense that Robbie Bach was guilty of at Microsoft, there has to be some direct accountability. To add insult to injury, OPK single-handedly pushed through the biggest and stupidest acquisition in Nokia's history. To support this flawed vision of mobile services OPK bought Navteq for $8.1 billion in October 2007.

    Intended as a service that could be rolled out on all phones and monetized through operator billing, Nokia maps is a free service that will never return anything to shareholders.

    Missing where the puck was going is one thing but burning precious capital is another. This, in my humble opinion, is why OPK was fired.

    Speaking of pucks, here's hoping fresh Canadian eyes will see where it's going.

  6. Smartphone market growing faster than expected

    Research · 9 comments

    IDC raised its 2010 smartphone sales growth forecast to 55 percent from 44 percent earlier. Citing booming smartphone demand it also lifted its forecast for overall cellphone market growth to 14.1 percent from 12.6 percent.

    via Cellphone market growing faster than expected -IDC | Reuters.

    Keep in mind the 55% growth figure when reviewing analyst forecasts for iPhone growth. If their forecast is less than that then it implies market share loss. When I suggested 50% compounded annual growth rate (CAGR) for iPhone going forward 3 years, there was a lot of skepticism but this market is growing faster than most people expected.

    I still believe that Apple can grow the iPhone at least as fast as the market.

    Here are the quarterly y/y growth rates for iPhone units since sales began:

    159% 516% 88% 90% 644% 7% 100% 131% 61%

    On a yearly basis:

    2007: 3.7 million

    2008: 13.7

    2009: 25.1

    2010 first half: 17.15

    2010 (my estimate): 44.4

  7. Nokia's fifth last chance

    Research · 26 comments

    The cellphone maker will unveil its new flagship model E7, which comes with a large touchscreen and full keyboard, at the show in London, two sources with direct knowledge of Nokia's plans told Reuters.

    via PREVIEW-Nokia bets on new smartphones for recovery | Reuters.

    Analysts have been saying that Nokia has one last chance to fix (software, UI, strategy, etc.) for some time now.

    Nokia sold 24 million smartphone units sold in Q2 which represented significant growth. Sales and Profits however were both down but to say that Nokia is facing imminent demise is misguided.

    How is Nokia able to sell so many units when its portfolio elicits so much pathos?

    The reason Nokia can still coast with poor products is that they have a vast distribution network. I don't know the exact distribution but let's assume that half their phones go through carriers and half through distributors who resell unlocked phones world-wide. Carriers will continue to carry the phones because they slot into well-established portfolio slots and distributors will continue to distribute because the product is competitive in markets where there are no other unlocked smartphones at the same price.

    So predicting imminent failure without taking into account distribution inertia is showing a lack of understanding of the market. The same insensitivity to distribution is why so many predictions of Microsoft's "death" or RIM's "death" fail.

    The less sensational but more accurate description of Nokia's predicament is that their strength in distribution prevents them from reforming their business model in order to benefit from the disruption that mobile broadband is bringing to mobile telecommunications.

    That's a mouthful.

  8. 54 apps have been downloaded for every iOS device sold

    Research · 19 comments

    At the September 1st music event, Apple announced that 6.5 billion apps were downloaded and that there had been 120 million iOS devices sold.

    This works out to 54 apps per iOS device.

    On June 7 Apple reported 5 billion apps over 100 million iOS devices or an average of 50 apps for iOS device.

    On April 8th, I computed that the app attach rate was 47.

    Is this rate noteworthy?

    Let's rewind to two years ago.  August 27th, 2008, soon after the App store launched.

    Nokia had just declared that its users had downloaded over 90 million applications over the past 2 years. An analyst estimated that over 100 million users globally use Nokia smartphones/converged devices, implying an attach rate of less than 1 app/smartphone.

    My, how expectations have changed.

  9. LG says WP7 will outperform Android

    Research · 1 comment

    LG has reportedly told Korean sources that “it expects WP7 to outperform the two rival smartphone operating systems” – one of these platforms is definitely Android (I’m not sure about the other platform LG is referring to; Symbian? iOS? BlackBerry?).

    via LG to bank heavily on Windows Phone 7, says WP7 will outperform Android » Unwired View.

    While Samsung believes WP7 is doomed, LG believes it will RULE!

    This might go some way to explain why LG is in such dire straits when it comes to smartphone share.

  10. Apple devices take 41% of mobile traffic in Finland

    Research · 4 comments

    In first half of 2010, iPhone and iPod touch traffic increased from 33.9% to 41% in Finland. Apple's devices account for a very small percent of the total phones in use in Nokia's home country.[1] The analysis was performed by QAim on a sample of 64 million "mobile downloads".

    Google Translate.

    Original article in Finnish.

    "A wave of iPhone and iPod owners behave differently than others."

    Weird bunch, those iPhone owners...

    [1] Installed base of iPhone is small but share of smartphones in recent quarters is above 20%.  See: YLE: Nokia’s smartphone share crumbles in Finland

  11. Life's (Not So) Good

    Research · 10 comments

    Follow-up to LG dreams of smartphones.

    LG Doesn't See Return To Operating Profit Until Early Next Year

    By Roger Cheng and Jung-Ah Lee  Of DOW JONES NEWSWIRES

    SEOUL (Dow Jones)--LG Electronics (066570.SE), which readily concedes it is late to the smartphone game, said it plans to launch 10 more smartphones and sell 5 million devices by the end of the year as it scrambles to catch up with the rest of the industry.

    But the aggressive move, which includes increasing the research and development budget by a third and ramping up its spending on marketing, means the company's once-flagship mobile devices unit won't likely return to an operating profit until early next year, said Chang Ma, vice president of marketing for the division.

    "We have to just bear it," Ma told Dow Jones Newswires on Wednesday, adding that he hopes to see a turnaround after the fourth quarter.

    It takes R&D to make an Android phone?

    (Thanks to MfH for link.)