This question sounds like a tautology. It's like asking "Will Apple rule the iPod market?" But redundancy has not stopped WSJ journalist Benjamin Pimentel from asking. His answer to the question is below:
But while Apple apparently has the edge in the emerging tablet war, it is unclear if the company will end up dominating the market the way it has come to rule the digital music player market with the iPod.
Gartner's Fiering said the iPad has "raised the bar and suppliers are now scrambling to make sure they get it right."
IDC now projects 6 million tablet devices to ship this year, including 4 million iPads, Shim said. But while Apple has taken the lead, he added, the company faces the "burden of lifting or defining this entire new market," because there are no other competitive devices available.
"In the iPhone market, they learned from everybody else," he added in a video interview. "In this new space, there's nobody else to kind of bounce ideas of so to speak."
But Apple may not have to feel so alone for long.
Fiering specifically pointed to H-P's as the best positioned challenger, given its scale, reach and its upcoming merger with Palm.
"There are not too many suppliers that can pull all those pieces together," she said. "H-P could if they integrate the Palm acquisition properly."
Another IDC analyst, Crawford Del Prete, agreed saying, while the "buzz" from H-P had generally been defensive in relation to the iPad, "the longer term story is far more interesting."
"Given H-P's massive scale, I think they have the ability to drive new price points for this kind of product," he said. "With a lower price point, the category becomes far more interesting."
via PC Makers Look To Challenge Apple's IPad - WSJ.com.
Before diving into the statements above it's worth noting where the journalist went to get opinions to fill his column. He called Gartner and IDC. Quoting industry analysts is a standard operating procedure to fill column-inches with material that does not offend. But how good are they?
In my years of watching those who watch markets I formed a ranking of analyst types and their likely accuracy with respect to prognosticating a market shift. In order from most accurate to least accurate:
- The most accurate are rank amateurs (deagol, Muller, et. al). Independent bloggers who do some fact checking tend to make the boldest but most accurate forecasts.
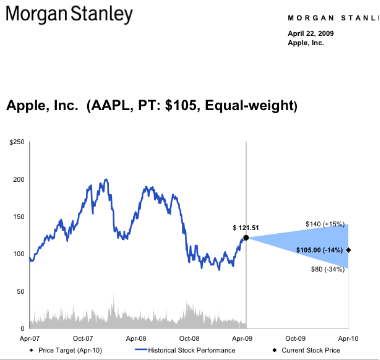
- The next most accurate are sell-side analysts (purveyors of analyst reports from established brokerages). They follow financials for individual companies. You might think their record is quite poor, but in fact they are much better than..
- Industry analysts (like Gartner, IDC). Their forecasts and sensitivity to disruption are often off by an order of magnitude. This is partly because they forecast a bit further out than Wall St. but also because they are closer to their industry clients-- the source of their ideas. They spend a lot of time talking to the least accurate forecasters...
- The corporate analysts. They are typically hired to advise management in the incumbent companies. These are people who have the most information about the way the industry is performing on a daily basis.
You might notice a pattern here: the closer you are to the market, the less likely you are to observe how that market is crumbling around you. You cannot see the forest for the trees.
How could this be? How can having more access give you a poorer picture? The answer lies in the asymmetry of a disruptive attack. The more you know about how things are the less you know about how things could be.
In practice, the analyst information value chain works like this:
Corporate analysts feed information to management that management is comfortable digesting. Those managers then hire industry analysts to validate their opinions. Industry analysts are keen to maintain a relationship with those firms and so they listen carefully to the prejudices of their clients. They then hold up a mirror to those myths and consolidate those opinions for wider distribution and quotation by journalists at respectable publications.
Stock analysts listen with one ear to the chatter but with the other to the way the wind blows with the stock market. Sometimes they actually sample the data in the value chain directly by calling acquaintances in the market and hire interns to watch what's happening in the shops. They then build an opinion that has some level of surprise but that they hope will not stray too far into controversy so that they can keep their jobs in case they are wrong. The safe bet is always to say that things will stay mostly the way they are, but to say it in clever ways.
So that just leaves only one group of analysts with independence from a paycheck who can make an opinion on the basis of facts alone.
This post has become longer than I planned, so I'll dive into the exact answer to the article claims in part II.