After 1 2 3 million units sold in 28 60 80 days, it’s time to review the analysts’ predictions:
First year iPad unit forecasts (sourced from TMO Finance Board)
Brian Marshall, Broadpoint AmTech 7.0
David Bailey, Goldman Sachs 6.2
Kathryn Huberty, Morgan Stanley 6.0
Shaw Wu, Kauffman Bros. 5.0
Mike Abramsky, RBC Capital Markets 5.0
Gene Munster, Piper Jaffray 3.5
Ben Reitzes, Barclays Capital 2.9
Keith Bachman, BMO Capital 2.5
Jeff Fidacaro, Susquehanna 2.1
Chris Whitmore, Deutsche Bank 2.0
Scott Craig, Merrill Lynch 1.2
Peter Misek, Canaccord Adams 1.2
Doug Reid, Thomas Weisel 1.1
Yair Reiner, Oppenheimer 1.1
Looks like at least half two thirds three quarters of these guys have already blown it.
For the record, in January I forecast 6 million units for calendar 2010 (and 10 million in first year). It looks like I'll be facing the iPad dunce corner as well.
Apple just reached a new all-time closing high. It's remarkable that so soon after a recession the stock is enjoying new highs. The Dow would have to gain 40% to make the same claim.
So some may ask whether Apple's stock is getting ahead of itself. Perhaps it's showing signs of "irrational exuberance".
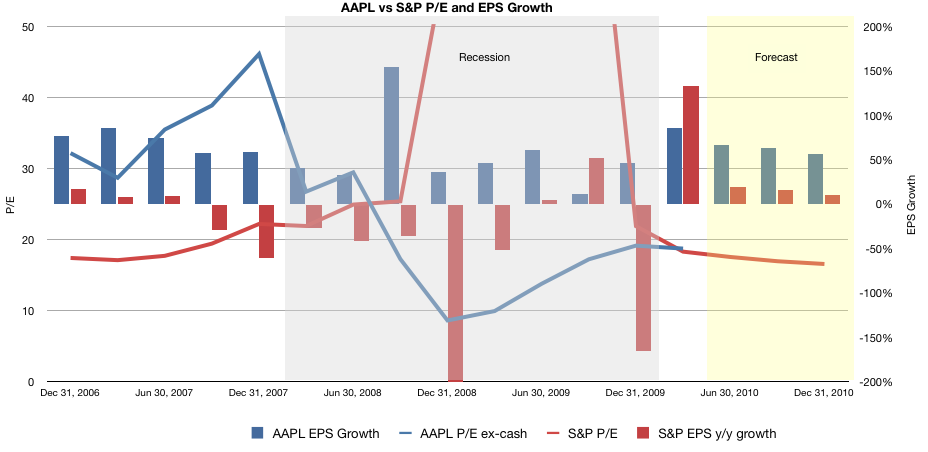
This is not the case. In fact, the stock is showing signs of irrational despondency. This is demonstrated with the following graph.
It shows AAPL Price (ex-cash) over Earnings vs. S&P P/E (blue and red lines respectively on the left scale) overlaid with AAPL and S&P EPS growth (blue and red bars respectively on the right scale). I added grey shading to represent the recession period and yellow shading for the forecast period.
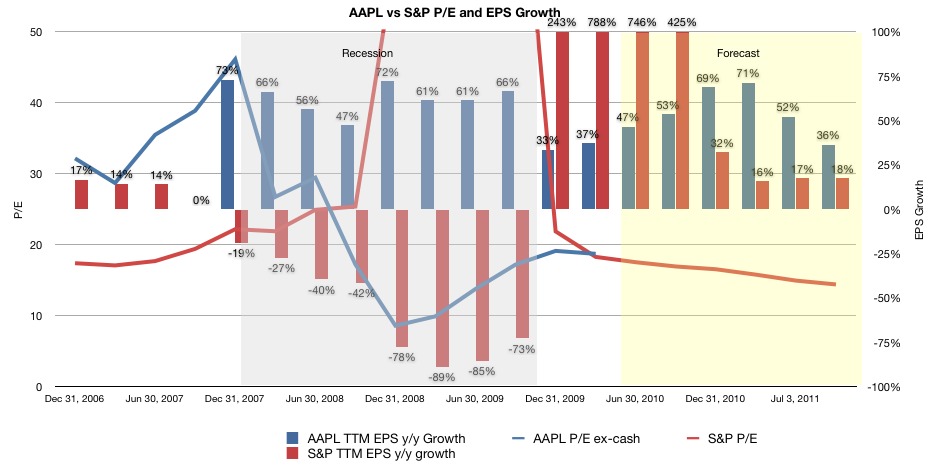
[Updated] The same data is shown in the following graph where I used a 12 month rolling window (trailing twelve months) for the year-on-year growth to smooth out quarterly anomalies as per suggestion from Deagol in comments.
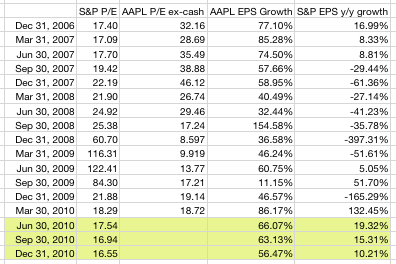
Note how S&P earnings were indeed in a state of severe decline during the recession, and how the P/E gyrated wildly as a result. (I've had to clip the actual values in the graph for clarity but I include all the data in the table at the bottom of this article). Post-recession S&P P/E began to return to normal at the beginning of this year and is forecast (by S&P) to align once again with the pre-recession growth in earnings.
Now compare with what happened to Apple's stock. Pre-recession the stock enjoyed a significant premium for growth. The blue bars are significantly higher than the red bars in the 2006/2007 period and the blue line is naturally higher than the red line in the same period.
During the recession, Apple continues to grow but the P/E drops to remarkably low levels (10). Although Apple's earnings growth does diminish, it never goes away. The anomalous growth in the third quarter of 09 is 11% due to the huge spike the year earlier with the launch of iPhone 3G. Overall, the company continues growing at a good clip.
Not so for its P/E however. Even after the recession ended and AAPL accelerated growth to above 50% again, the P/E remained around 20. I left out the forecast from the AAPL line so that readers can imagine their own.
The bottom line is that at the new all-time high, Apple's shares are trading at a discount to their growth. Not only lower than than Apple has enjoyed historically, but lower than the average of 500 of the largest companies in the US. Those companies having earnings growth in the teens have recovered their valuation. Apple with growth returning to above 50% hasn't.
These were rhetorical questions designed to demonstrate that a growth rate of 50% (compounded) over three years was clearly possible through reduction to absurdity of alternative scenarios.
The question of iPhone as iPod vs. iPhone as Mac businesses is at the crux of any investment in Apple today and the key strategic question facing Apple and all its competitors. Anyone holding or considering buying AAPL shares should answer this question for themselves.
To the top-down market share scenarios above I add the following, more direct, signals Apple has made regarding their iPhone-for-all strategy:
The fact that they entered the market at all. When they were building iPods, Apple came to understand that to be a device company means to be a phone company. The device business is much more sensitive to volume (i.e. economies of scale) than the PC business. Nokia proves this point every day. You can’t be in the device business with low volumes and stay profitable for long. This is because you can't get component pricing low enough to sustain margins that can afford you R&D sufficient to differentiate your product. Therefore you cannot stay in the phone business with low volumes (see Palm).
Apple repeatedly signaled that they will not permit a pricing umbrella for their products. Although the product seems priced highly now it’s only because that’s what the market can bear and because of the possibility of taking a cut from service revenues. The iPhone is not as expensive as it might seem relative to other smartphones, it just has a huge gross margin (50% at least). Apple can keep their costs low through volume but they can also tweak pricing down if they need to.
The platform approach. Apple is putting in an enormous effort to orchestrating a mobile platform. This is the most obvious signal. Platforms are expensive to build. If the cost to build a mobile phone is x, the cost to build a mobile platform is 10x. Platforms are expensive to maintain but generate enormous rents if volumes are built and users are retained. The platform’s value grows as the n*log(n) of the number of users (Metcalfe’s law).
Susquehanna Financial's Jeff Fidacaro: To $335 from $325.
Kaufman Bros.' Shaw Wu: To $340 from $320.
Piper Jaffray's Gene Munster: To $348 from $340.
Caris and Co.'s Robert Cihra: To $325 from $310.
Morgan Stanley's Katy Huberty: To $332 from $310.
International Strategy & Investment Group's Abhey Lamba: initiate with $320.
Cowen's Matthew Hoffman: initiate with $326.
At yesterday's closing price Apple was trading at a 12-month trailing P/E multiple of 23 despite revenue growth that may exceed 50% and EPS growth that may exceed 70%.
Using the highest target of $348 price target as an example, it prices the shares at a P/E of less than 30 times the most recent 12-month earnings which does not take into account the contributions from the iPad.
Apple is on track to report three consecutive quarters of record revenue and earnings (beginning with the June quarter) and current analyst price targets do not reflect the current and anticipated rates of revenue and earnings growth.
In Japan’s second cell-phone merger this month, Fujitsu and Toshiba said Thursday they will merge their handset operations ... NEC, Casio Computer and Hitachi merged their phone units earlier this month.
Mergers usually happen in a mature industry when there is excess capacity and decreasing growth. In the mobile phone market we've seen several companies disappear or merge over the past decade:
Ericsson
Sony
Alcatel
Siemens
Casio
NEC
Hitachi
Fujitsu
Toshiba
Palm
Handspring
Motorola tried but failed to get itself acquired.
But we've just seen forecasts where the smartphone market is growing and is expected to continue growing at 40%. Why is there consolidation in a growing market?
The obvious answer is that none of the companies listed above had any significant smartphone businesses. But that begs another question: why? Is the smartphone market so different than the mobile phone market?
If the answer is yes, then there is an implied asymmetry. Asymmetry is symptomatic of disruption. Disruption then leads one to ask how the other incumbents will cope?
“We have long maintained that the company’s ponderous corporate culture would eventually find its footing, but with competitors attacking fiercely at both the low and high end, deterioration in its core European market, and a lengthening timeline for Symbian^3, which may not live up to expectations anyhow, shares will plunge well below recession lows,” he warns.
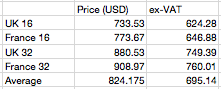
As a footnote to the unlocked iPhone 4 story, it's worth noting that the average Apple store pricing for UK and France is around $824 (assuming equal blending between the two countries and between the two models). Excluding corresponding VAT leads to an approximate ASP of $695.
Operators probably get a slightly better price so my estimate for the iPhone 4 ASP of $600 seems reasonable with potential upside based on product and regional mix.
The most impressive number for us is the change in units shipped. For example, leader Nokia held 66.6% of the marketshare in Q1 of '09, and 45.2% in Q2 for a 7% change in units shipped. Meanwhile, Apple held 10.2% in Q1 '09 and 40.3% in Q1, '10 for a 532.1% change in units shipped.
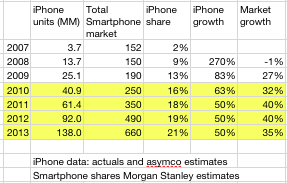
In a previous article I asked what it would take for the iPhone to reach 20% of the world's smartphone market? (answer: 50% growth).
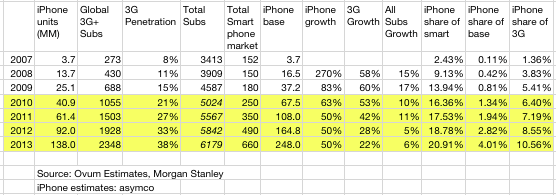
Now I take a look at the whole market measuring three underlying quantities:
the number of total wireless subscribers world-wide
the number of 3G subscribers
the number of smartphones sold every year 2007 to 2013
The forecast for 2013 is:
total subs: 6.2 billion
total 3G subs: 2.4 billion (38% of all WW users)
660 million smartphones sold in 2013
I also computed the installed base of iPhones based on units sold per year according to the following schedule: 100% of iPhones in use during first year, 75% in use after second year, 50% in use in the third year, 25% in the fourth and 0% in the fifth and after.
If the iPhone can sustain 50% growth then the following are possible in 2013:
4% of world’s users using an iPhone (248 million iphone users)
On a yearly basis, iPhone has been growing at 270% in 2008,83% in 2009 and 130% so far this year. The growth has been faster than the growth of the smartphone market during the same time. As a result, the market share of the iPhone has increased from 2% in 2007 to 13% in 2009.
The question now is: What is the required growth rate for iPhone to maintain growth in share as the overall market grows?
Taking market estimates from Morgan Stanley, I tried to fit an iPhone growth rate which would result in a 20% share for Apple by 2013. This rate turns out to be a conservative 50%/yr. Any growth beyond 50% would result in well over 20% share for the iPhone.