Asymco

Asymmetric Intelligence

Research

  1. Calling the end of innovation in mobile computers

    Research · 72 comments

    People are lining up to call the market for mobile phones. Analysts and amateurs alike are connecting points on charts and predicting with confidence the future of mobile platforms. Consensus is forming that there is no future but a quiescent state. By the acclamation of pundits, the survivors are declared to be iOS and Android. They are also predictably arranged in a way similar to OS X and Windows. End of story.

    Except for one thing.

    3.5 years ago neither of these platforms existed.  In fact, it was only two and a half years ago, in mid 2008, that one of the finalists even became a platform with the launch of an app store. The other "winner" only launched in a handset later that year and had no significant volumes until a year ago. In other words, these suddenly predictable platforms have been in existence for less than the life span of one device that runs them.

    To point out how extraordinary this claim is, if we look back to the history of computing, could we have declared the PC industry future cut and dried in 1978, two years after the founding of Apple? What about 1983, two years after the emergence of the IBM PC? What about 1986, two years after the Mac? Or maybe 1990, after Windows was born? Maybe the writing was on the wall in 1997, two years after Windows 95 caught up with the Mac's UX. That would be 21 years after Apple's founding. Some would argue that even today the story of desktop or portable computing is far from over.

    Sure, times have changed. Things move much faster now. But markets are also much bigger and take a long time to penetrate. Mobile channels are bounded by provincialism and parochialism.

    What's more, it's not like there haven't been platforms before these two upstarts came along. I've seen 9 mobile platforms in 9 years (PalmOS, Windows Mobile, Symbian, Java, WebOS, Windows Phone, iOS, Android, RIM Blackberry). New platforms are still emerging and evolving (e.g. MeeGo, Bada, LiMo, QNX and Tapas).

    So the existential question is this: If you were to draw a time line, would a mark in early 2011 signify the end of mobile platform history? The point in time when unforeseeable change will cease to happen?

    Let me offer a hint as to why not: every major platform battle has been sparked by an innovation built around a new input method. The keyboard integrated into a personal computer in the 1970s, the mouse in the 1980s, the stylus in the 1990s and the fingertip in the 2000s. Each of these input methods created new platforms (DOS/Apple ][, MacOS/Windows, PalmOS/Windows CE, iOS/Android), new ecosystems, new industries, new competitors and new platform battles designed to enrich forecasting pundits. I won't even try to go back to the changed in the half century of computing prior to the PC.

    So here's my challenge to the prognosticators: If you are willing to draw a line in the calendar now and say that no input methods will ever emerge in mobile computing after this point in time I'll buy the thesis that it's over and we can count our chips.

    If you think that out of the hundreds of user experience patents being filed, and hundreds of prototypes being slaved over in labs throughout the world, not a single new product will emerge with a new way of interacting with a computing device, then it's time to move on to something other than what can be declared a commodity market.

    But if you believe that, as happened four years ago, a new input method, previously only in the realm of mockups and movie magic, suddenly was shown, in a working product, on stage, then this business still has a chance of staying interesting.
  2. The remarkable stability of pricing

    Research · 27 comments

    Prices provide accurate, independent signals about where, when, and how to create and deploy value-creating innovations. The mechanism of free markets signals what should be rewarded and what shouldn't. When comparing competitors, prices are the best indicators of differentiable positioning.

    However, prices are sometimes anomalous and subject to transient market conditions. It's therefore important to observe pricing over a long time frame.

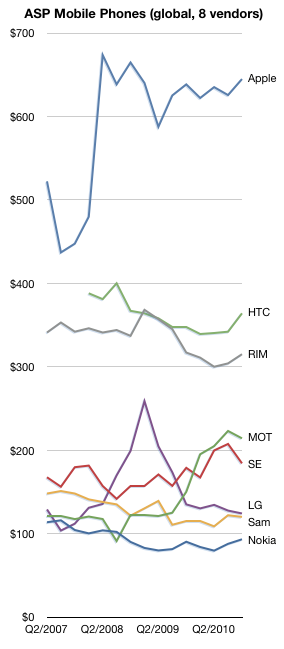
    This chart shows the average selling prices for all phones sold by the eight publicly traded phone vendors (covering approximately 70% of the market) since mid-2007.

    There is remarkable stability in the pricing of the competitors. One could argue that only Motorola and LG saw significant swings in price. (Apple's instability in 2007 was due to the revenue sharing deal for the 2G iPhone on AT&T).

    Motorola pared down its portfolio (and its market share) and as a result has seen a doubling in ASP. LG had a rapid rise and rapid fall as its feature phone business boomed and busted.

    But otherwise, pricing trends are subtle: down from Nokia and Samsung. Slight decrease for RIM and HTC and stable for Apple. In a future post I'll dive into the relationship between pricing power and share.

  3. The Asymco way

    Research · 49 comments

    When I started Asymco.com I did not have a plan. I did not have a policy or vision statement. I wrote what I found interesting. I knew nothing of blogging or of web publishing as a business. Over the following nine months I learned a few things. I also learned a bit about how web publishing (and publishing in general) works.

    My observations were brought into clear focus by this brief overview of the core values of web publishing summed up by this leaked document form AOL: "The AOL Way".

    AOL tells its editors to decide what topics to cover based on four considerations: traffic potential, revenue potential, edit quality and turn-around time.

    AOL asks its editors to decide whether to produce content based on "the profitability consideration."

    The documents reveal that AOL is, when the story calls for it, willing to boost traffic by 5 to 10% with search ads and other "paid media."

    AOL site leaders are expected to have eight ideas for packages that could generate at least $1 million in revenue on hand at all times.

    In-house AOL staffers are expected to write five to 10 stories per day.

    AOL knows its sites are too dependent on traffic from AOL.com, and it wants its editors to fix the problem by posting more frequently, with more emphasis on getting pageviews.

    This codification of values has inspired me to put in writing my own priorities for Asymco:

    • Learn by writing. Teach by listening.
    • Improve. Move the intellectual ball forward.
    • Illuminate topics which are bereft of analysis.
    • Be notable. "The proliferation consideration." How likely is the idea to being widely re-published?
    • Review. Encourage participation by reading all comments and reply to as many as possible. Police comments with zero tolerance.
    • Repair. Declare and correct errors.
    • Select. Publish only when the contribution is unique. Avoid redundancy, clutter and noise. Don't waste reader time.

    Many have asked: What about the business model? I'm afraid there isn't one. I'm still naive enough to think that if I build a great product then everything else will take care of itself.

  4. Making it up in volume: How profit and volumes traded-off in the fourth quarter

    Research · 24 comments

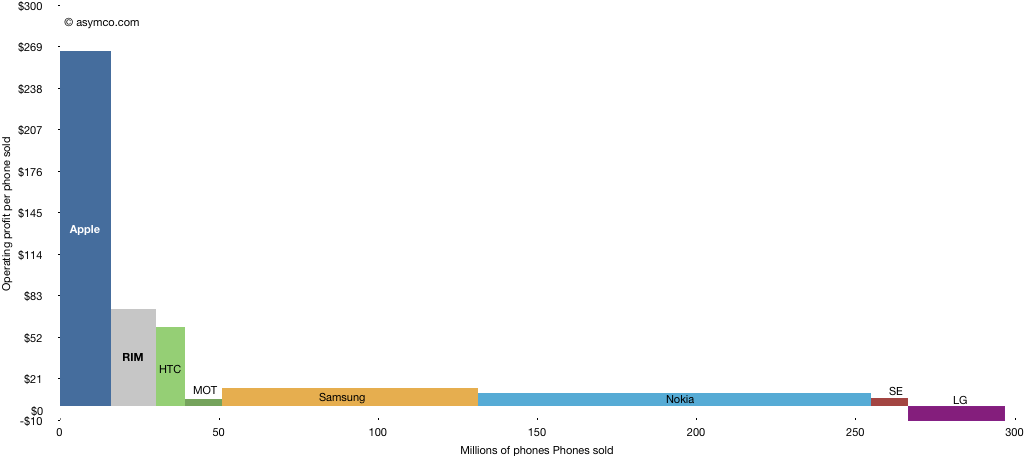
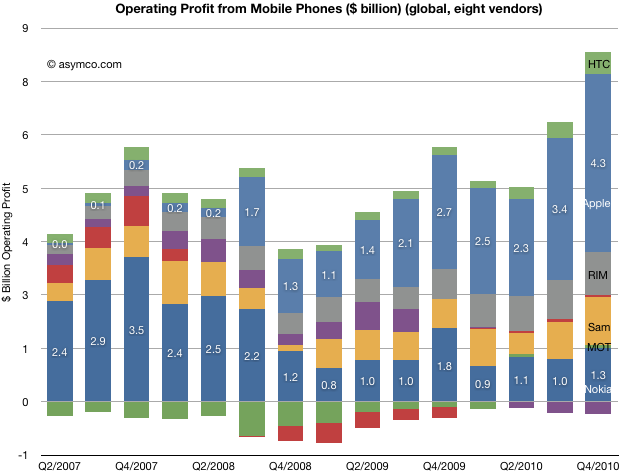
    Today's charts show the amount of profit captured by the top eight public mobile phone companies in two different ways.

    The first, as a bar chart:

    The second shows the way they captured it by taking into consideration the number of devices sold.

    Please click on the image for a full size view (1024 pixels wide).

    Generally speaking, vendors which are focused on smartphones have higher pricing and higher profitability (pricing discussion will follow at a later time). However, some, like Motorola and Sony Ericsson are still trying to recover from the collapse of their non-smartphone business and have higher prices but not very high margins overall. LG does not seem far behind.

    Samsung and Nokia profit per device is quite small but they "make it up in volume".

    The areas above represent operating profits and are comparable. One wonders how the ratios between horizontal and vertical dimensions for these boxes will change over time.

    Since the overall market will expand, the sum of all horizontal dimensions will increase. As the first chart shows, there is no law for the conservation of profits in the industry, so it's possible that the sum of all these areas will increase, but it's still hard to imagine it increasing by an order of magnitude.

    Will the industry remain clustered into a tall-and-narrow group and a short-but-wide group? That's a question with many strategic implications..

  5. Google as Android "Vendor"

    Research · 113 comments

    In a recent tally of mobile OS market share estimates from Canalys, the market was organized by OS vendors. The number of devices sold by operating system vendor includes as many OS's as each vendor may supply.

    For example, Microsoft licensed two different OS's during the period: Windows Mobile 6.5 and Windows Phone 7. Nokia also offered multiple versions of Symbian, which have varying degrees of inter-operability.

    Google's offerings include (as per footnote) OMS and Tapas platforms in addition to Android.

    Fragmentation is not a new subject as OS licensing models have been ripe with it for as long as they existed.

    What I want to draw attention to is the concept of Google as "vendor."

    A vendor in the traditional supply chain model is a supplier that sells to an up-stream value-adding stage of the value chain. The word itself has as its root the word "vend" which means to sell.

    But we know Google does not sell Android. And it's not just that Google builds a product and ships it for free.

    There are no contracts associated with the transaction of downloading the Android source. No contract means no obligations, no warranties, no terms and no conditions. The product is not indemnified against litigation. There are no licenses, no support, no copyrights and no patent license granted.

    The contract-less nature of Android makes it easy to distribute. It's one of the key reasons why distribution can grow at 600% a year--there is no distribution in the classic sense. The real disruptive advantage for Android lies in the removal of distribution costs (not just development costs). Google themselves admit that they have no idea who implements the software and how it's used.

    Which makes the classification of Google as a "vendor" a misnomer. The notion of 'vending' something implies a contract. What Google does is write code and place it on an FTP server.

    It's a wonderful way to save on SG&A (there is no sales, general or administrative expense.) But as everyone knows, there is no such thing as a free lunch.

    By avoiding any contractual engagement with the authors of the source code, implementors are subject to independent litigation for IP violations. This is why HTC and Motorola are targets for Apple and not Google.  Google is no more liable for writing Android than the author of a book on bomb making is liable for the bombs put into use [1].

    Patent violation rests with implementation, not the writing of the idea itself.

    Furthermore, Google cannot ensure Android users have any specific experience. They can't encourage upgrades, service models or any form of common UI. The experience, like the protection of property is the responsibility of the implementor.

    Can Google change this approach with Android? Not as long as Android is open source. Can Google change Android from being open source? No, they don't own the source to Android. Nobody does.

    ---

    Notes:

    1. If the bomb making book was a copy of another, then the author is liable, which is the case being made by Oracle.
  6. The iPhone share: 17.25% of smartphones, 4.2% all phones

    Research · 13 comments

    The mobile phone market is growing rapidly. It grew 18% in the last quarter. The smartphone market grew even faster, about 75%.

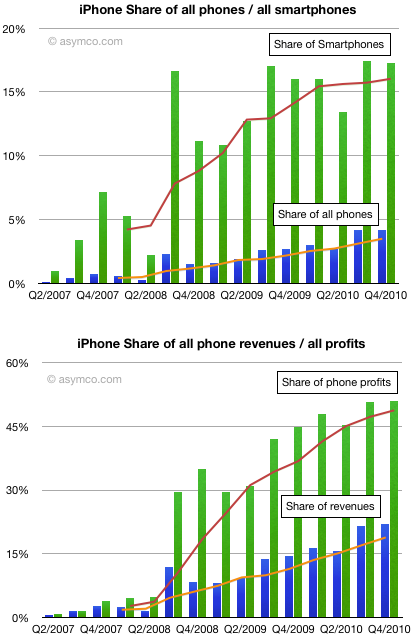
    To grow share in this market means growing even faster than the market. What we can see from the following charts is how the iPhone as a product grew in share since it was launched 3.5 years ago:

    Unit share growth slowed in the last quarter but the fourth quarter is not usually the most expansive for Apple. That is usually the third quarter which is the first full-availability launch quarter.

    The iPhone ended the quarter with 17.25% smartphone share and 4.2% phone share. Share of revenues was about 22% and share of earnings was about 51%.

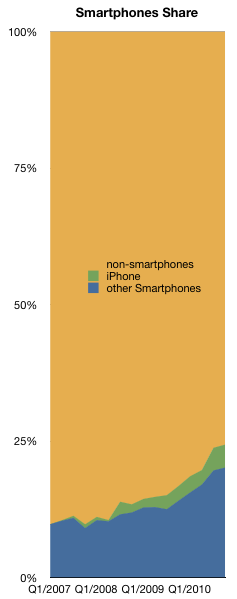
    I still hold that 20% smartphone share is possible for the iPhone. As the smartphone market slowly becomes the entire phone market (see chart to the left) that share will be worth something.

  7. Fourth quarter mobile phone industry overview

    Research · 58 comments

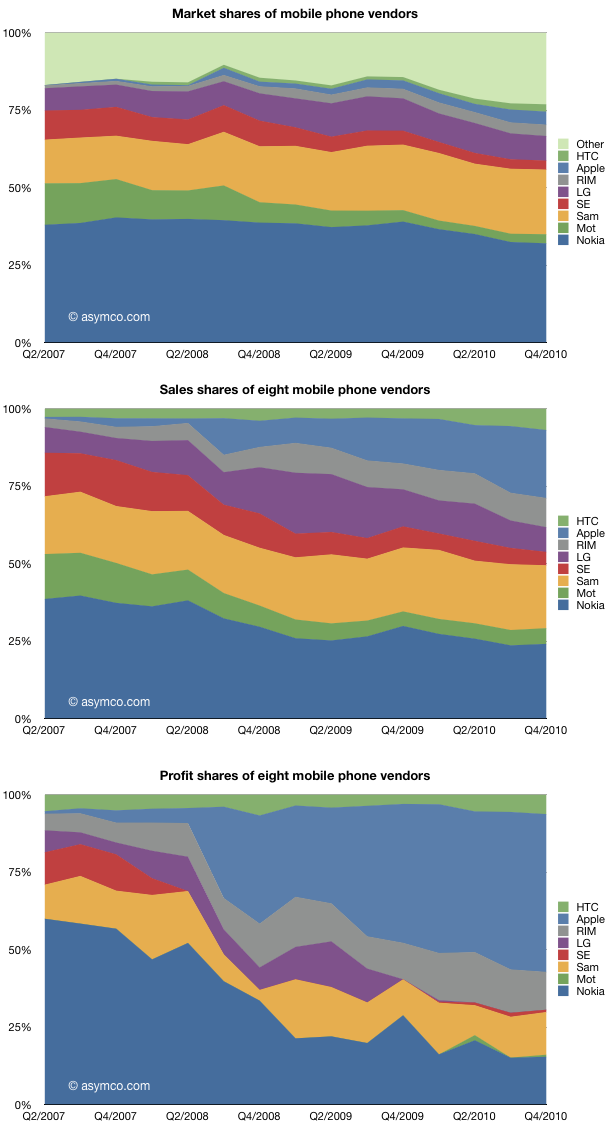
    The following chart shows the units, sales and profit shares for the top eight phone vendors.

    The fourth quarter did not see change in the ranking of the top eight vendors except for Sony Ericsson dropping in sales rank (to eighth). Samsung beat RIM to third spot in profit ranking, a position it held for most of 2009.

  8. Of Platforms, Operating Systems and Ecosystems

    Research · 21 comments

    In the earnings Q&A Stephen Elop used the word 'Platform' once, 'Operating System' three times and 'Ecosystem' 15 times.

    Though they seem interchangeable, the three phrases have significant differences in meaning. Briefly put, a Platform is a business model concept,  an OS is a technology concept and an Ecosystem is a marketing concept.

    Platform

    A platform, as the New York Times recently pointed out, can take many forms. The Barbie doll is a platform as is the US Interstate Highway system. These are products or infrastructure that allow other products to be 'built on top' and can thus charge rents from them. When building platforms, a company needs to think of how to make their work foundational so it can support other structures. Other examples of platforms are browsers, the Apple 30 pin dock connector, Game Consoles and Facebook.

    In terms of innovation theory, a platform is a signal to industry that the company is willing to allow its innovations to be extended and thus share in the creativity of adopters. There is however a down side: platform adopters may also create so much value that users will shift loyalties to the layers above the platform thus restricting the freedom of the platform owner to modify or modernize the underlying platform.

    This loss of control over the roadmap often forces platform owners to institute draconian limits to the extensibility of the platform (e.g. the iPhone developer restrictions.) In other cases, platform owners have acquired and integrated various core apps or services so that the platform and core apps can be upgraded in sync. This was the impetus to the development of Microsoft Office. Office was motivated by a need to prevent Lotus from slowing the upgrade path for Windows not, as it's assumed, to create a new revenue source. However, again, the effect is the destruction of the ability to innovate on that particular area (no new Word Processor or Spreadsheet programs for 20 years).

    It takes a great deal of work to platformize a product. I would guess 10x more than a similar product which does not allow collaborative innovation. Platforms are difficult to build, require delicate balancing acts to maintain but can be enormously valuable due to network effects.

    Operating System

    In contrast an Operating System has a very clear technical definition. It has been extended to include many applications and services, but it's basically the control system of a computer. An OS may or may not be a platform. For example embedded operating systems typically do not have APIs to support applications. Some basic mobile operating systems support applications through a sandbox like JaveME (in this case the platform is Java) and are therefore also not platforms.

    A company licensing an OS may not accept the platform with the license or may not consider it valuable. It's even possible to license an OS and consider the platform value to be a liability to your own strategy (arguably HP fits in this scenario as regards to Windows. HP had its own operating systems and tried to build alternative platforms in spite of Windows).

    An example of an OS with minimal platform value may be WebOS which has a very limited API for native applications.

    Ecosystem

    The word ecosystem as it applies to technology was coined by Palm to describe the app vendors that built apps and the accessories for its Palm Pilot. This is not a common word as it's largely equivalent to Platform. The subtle difference is that it's used in a marketing context to signal platform value. Having a large ecosystem implies the acceptance of a platform by a large base of developers.

    For example a platform may not have a viable ecosystem if there are few developers and/or little economic value 'on top' of the platform. Symbian is often cited as being a decent OS, but a poor platform with a mediocre ecosystem.

    So these three phrases are overlapping but have a different tone. Although perhaps unintentional, Elop's emphasis on Ecosystem vs. Platform or OS, might signal that what's missing from Nokia's strategy is the motivation or encouragement of developers to participate. My prediction of WP7 licensing may not fit well with this deficiency but perhaps Microsoft's ecosystem building potential is still greater than Nokia's.

    I should also point out that Nokia's platform strategy has also included an intermediate layer called Qt that enables cross-platform ecosystems, thus making the OS irrelevant. Technically this may have merit, but it's a long haul to getting an ecosystem for it.

  9. Steve Jobs on Apple's priorities

    Research · 30 comments

    To me, Apple exists in the spirit of the people that work there, and the sort of philosophies and purpose by which they go about their business. So if Apple just becomes a place where computers are a commodity item and where the romance is gone, and where people forget that computers are the most incredible invention that man has ever invented, then I'll feel I have lost Apple. But if I'm a million miles away and all those people still feel those things and they're still working to make the next great personal computer, then I will feel that my genes are still in there.

    Jobs Talks About His Rise and Fall - Print - Newsweek

    In the language of innovation theory that Clayton Christensen created, companies are characterized by three attributes

    1. Resources
    2. Processes
    3. Values (or Priorities)

    Resources come and go, typically arriving every morning and leaving every evening.

    Processes take a lot of hard work to change but they can be changed.

    Values and priorities are almost immutable. They are what Jobs refers to as the "genes".

    The fact that Steve Jobs said these words about Apple in 1985 after his first departure gives one hope that in 2011 (after his return and departure and return and departure again) the genes are still in there.

  10. Stephen Elop's ecosystem messages

    Research · 66 comments

    Yesterday I made my predictions on Nokia's new platform strategy. They should  be treated as pure guesswork, but they are informed guesses. I based them on public information.

    That information comes in the form of statements from Nokia's CEO at the earnings call. I made a table of all the statements that dealt with platform decisions and my interpretations of those statements.

    You may do your own interpretation, but to me there is significant evidence here to support my predictions.

    What Elop SaidMy interpretation
    In certain markets where there’s a greater preponderance of competing platform devices, we have some competitiveness problemsWe have problems in the US
    Broadly the conversation about operating system and positioning of relative operating systems in different places is something that we'll reserve for the February 11th meeting,Different markets require different operating systems
    The general comment I’d like to make though is that in today’s world it is the case that given the different price performance characteristics of different chipsets, we get into situations, where the best experiences are not necessarily delivered by systems that are capable of delivering the highest end experiences. We have to be very mindful at what level of the price curve we deliver what type of device with what operating system.Different price points require different operating systems
    When I think about geographies, the area, I've mentioned this indirectly during my comments, but I'll be more precise in answering your question and that is clearly, there is a pattern of disappointments in the United States. A pattern there where efforts have been made, competitiveness, challenges exist and we very much need to address thoseWe have problems in the US. We're going to address these.
    That's why I characterize very clearly in the framework for the decision making ahead, that whatever the strategy is that we outline on February 11th, we very clearly will be ensuring that it gives us the opportunity to reopen doors in markets such as the US and some others where we have not recently been presentWe are going to enter the US with this platform
    With respect to the question of ecosystems and so forth, it's important to note, in my opening comments, I referenced the fact that there are today different ecosystems and different patterns at playDifferent OS for different markets
    If you like the high-end ecosystems where there is particular rate of momentum and share gain taking place. At the same time, the dynamics at the very low end of market which itself is an ecosystem of sorts, is very different with very different demands and expectationsHigh end and low end require different OS
    I'll just offer that observation that today broadly in the world without any specific comment on us or our competitors, there are multiple ecosystem patterns that need to be consideredMore on the need for multiple OS
    I'd also point out that very critical in whatever combination of ecosystem or ecosystems or whatever our strategy outlines, the need to maintain sustainable differentiation between ecosystems and within the ecosystem relative to our competitors in that ecosystem is a top priority. In everything we consider, that’s something that will be very much on our mind.What we chose gives us some degree of differentiation--It's possible concessions were negotiated
    With respect to comparisons to other ecosystem shifts and things like that, the real thing that one must focus on is the quality of products in the market, the momentum that one already hasSymbian is not going to disappear
    As we’ve described the Symbian momentum that we have today; a consideration of shift of ecosystem, certainly you have to consider that potential of market share changesSymbian will lose share
    With respect to the ecosystem comment, without getting into specifics of different options and things like that in detail, what I will say is that the word catalyze is to imply that there is a wide variety of participants in our world, and that includes competitors, it includes operators, other technology firms and so forth who in many respects have a common interest relative to the potential strength of other ecosystems and how they may develop over timePartner is a tech firm that has common interest -- i.e. market entry
    The catalyst of an ecosystem could be considered as making sure the right conditions are formed in the right companies, work in such a way that alternatives emerge in a marketplace that may not exist todayLooking at growing the market for the partner-- Microsoft
    We made a decision to not proceed as people have thought we would proceedThis is not going to be business as usual
    You'll see that pattern of decision making from us in terms of being very crisp about what constitutes great experiences and ensuring that that is what we are delivering to our customers.This is a marketing-led effort. We're going to stay on message and not waffle on about technology