Asymco

Asymmetric Intelligence

analyst

  1. Expectations for the Quarter

    Research

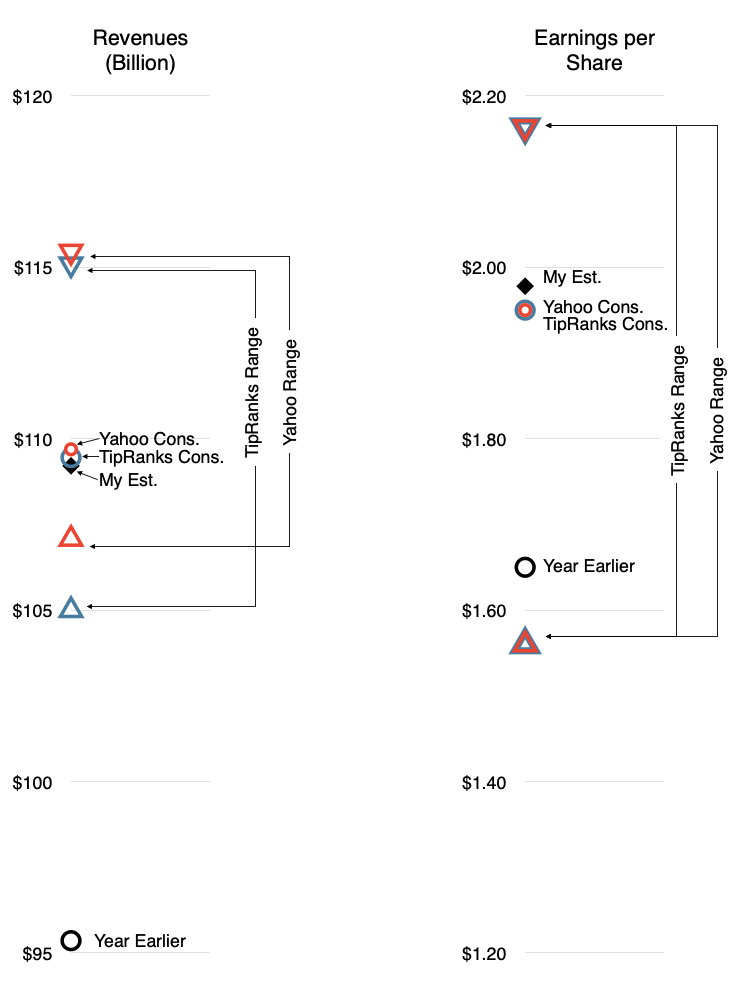
    Revenue and EPS consensus, year-ago results and my expectations

    Yahoo Finance

    Yahoo Finance's revenue estimate for Apple in Q2 stems from 31 analysts. As of April 25, the average estimate is $109.69 billion, with a low of $107.08 billion and a high of $115.37 billion. 

    For the earnings per share estimate, 32 analysts put it at an average of $1.95. The low is $1.56 and the high is $2.16. 

    TipRanks

    TipRanks also does its own analyst polling on Apple's quarter. In its forecast as of April 19, its consensus is for a revenue of $109.45 billion, with a high of $115 billion and a low of $105 billion. 

    On the earnings per share, the consensus is $1.95, with a high of $2.16 and a low of $1.56.

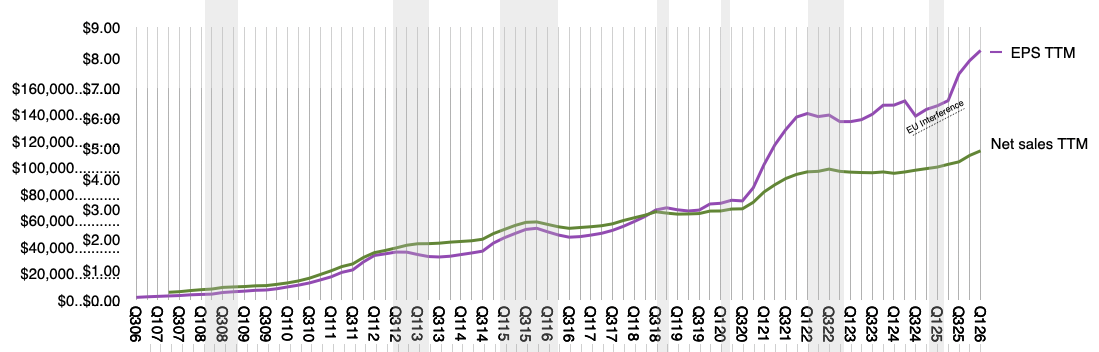
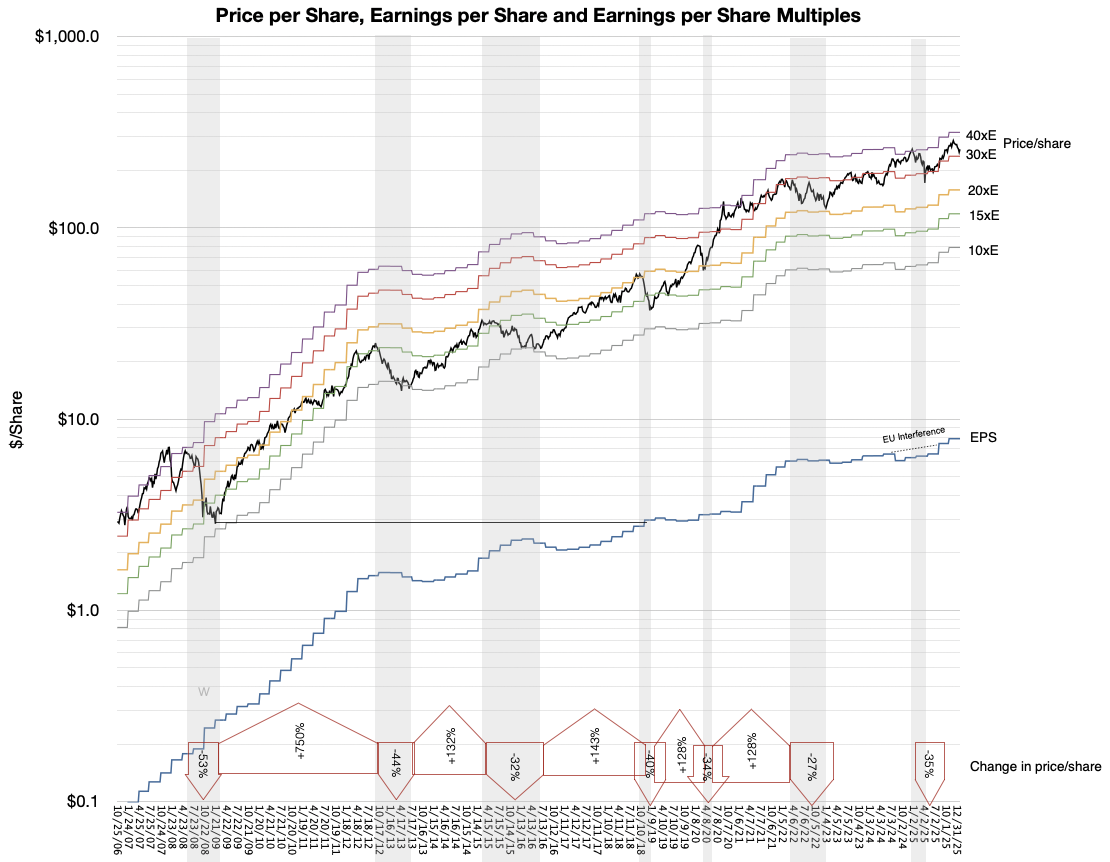
    A summary of the expectations include year earlier results and my own estimates is shown the following graph:

    UBS Raises Price Target from $280 to $287 but Maintains Neutral Rating
  2. Asymco Bulletin 010 - Apr 26, 2026

    Bulletin

    Asymco Bulletin is a digest of all the work we have published for the week ending Apr 26, 2026.


    Office Hours

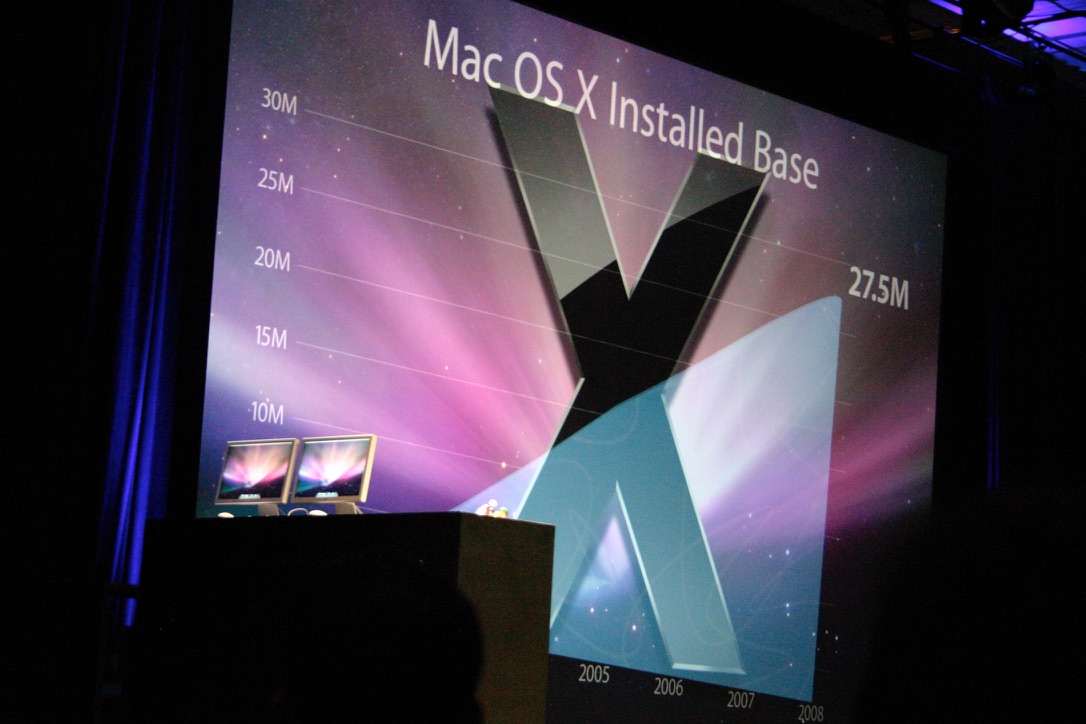
    WWDC June 9th, 2008, Photo by Author

    Office Hours Live Q&A with Horace Dediu: Friday May 1, 2026 → Join Asymco One for an exclusive Office Hours Live Q&A to delve into Apple's landmark quarter and ask your questions—register now and bring a guest!

    Listen to: Apple Earnings Call →
    Thu, April 30, 2026 5PM ET / 2 PM PT

    Join our Live Discussion →
    Fri, May 1, 2026, 12PM ET / 09AM PT


    Research

    Succession, study of the firm vs. study of the person

    A part of Horace's interview with Asahi Shimbun on the 50th Anniversary of Apple's founding. The portion here discusses management succession and occurred on April 1. Apple announced the succession of Tim Cook as CEO to John Ternus last week. This analysis of Apple leadership decisions focuses on culture and attributes of the firm rather than attributes of the persons leading it. It may prove a more reliable predictor in future leadership changes.

    …, the speculation is John Ternus is the next in line. I think that's a very plausible hypothesis. And one reason, by the way, is I always maintain if you study the company from a cultural point of view, you'll realize that there are people who cannot be CEO. You may not know who it's going to be, but I can tell you who won't be. Many people over the years suggested candidates, and I would say no, never. And here are examples. Johnny Ive would never be CEO. An external hire would never be CEO. Even a head of marketing would never be CEO. Many people think that Apple is a brilliant marketing company. No, it's an engineering company. It's a huge secret out there. →

    John Ternus has left big shoes to fill

    Writing the story of John Ternus' tenure as Apple CEO from April 21, 2040. What changed and what didn't.

    It’s been 15 years but John Ternus has finally stepped down as Apple CEO. Analysts described the transition as expected rather than disruptive, noting that investors had long anticipated Ternus’ eventual departure. Nevertheless, he leaves with many questions still unanswered about Apple’s long term strategy. Apple incoming CEO faces a defining challenge: Fixing the company’s Services dependence. It’s been a tumultuous tenure for Ternus but he is leaving with significant accomplishments: John grew Apple devices to 4.5 billion from 2.5 billion when he took over in 2026. Many have pointed out that he has been building on… →

    The Composition of Active Devices

    The Composition of Active Devices

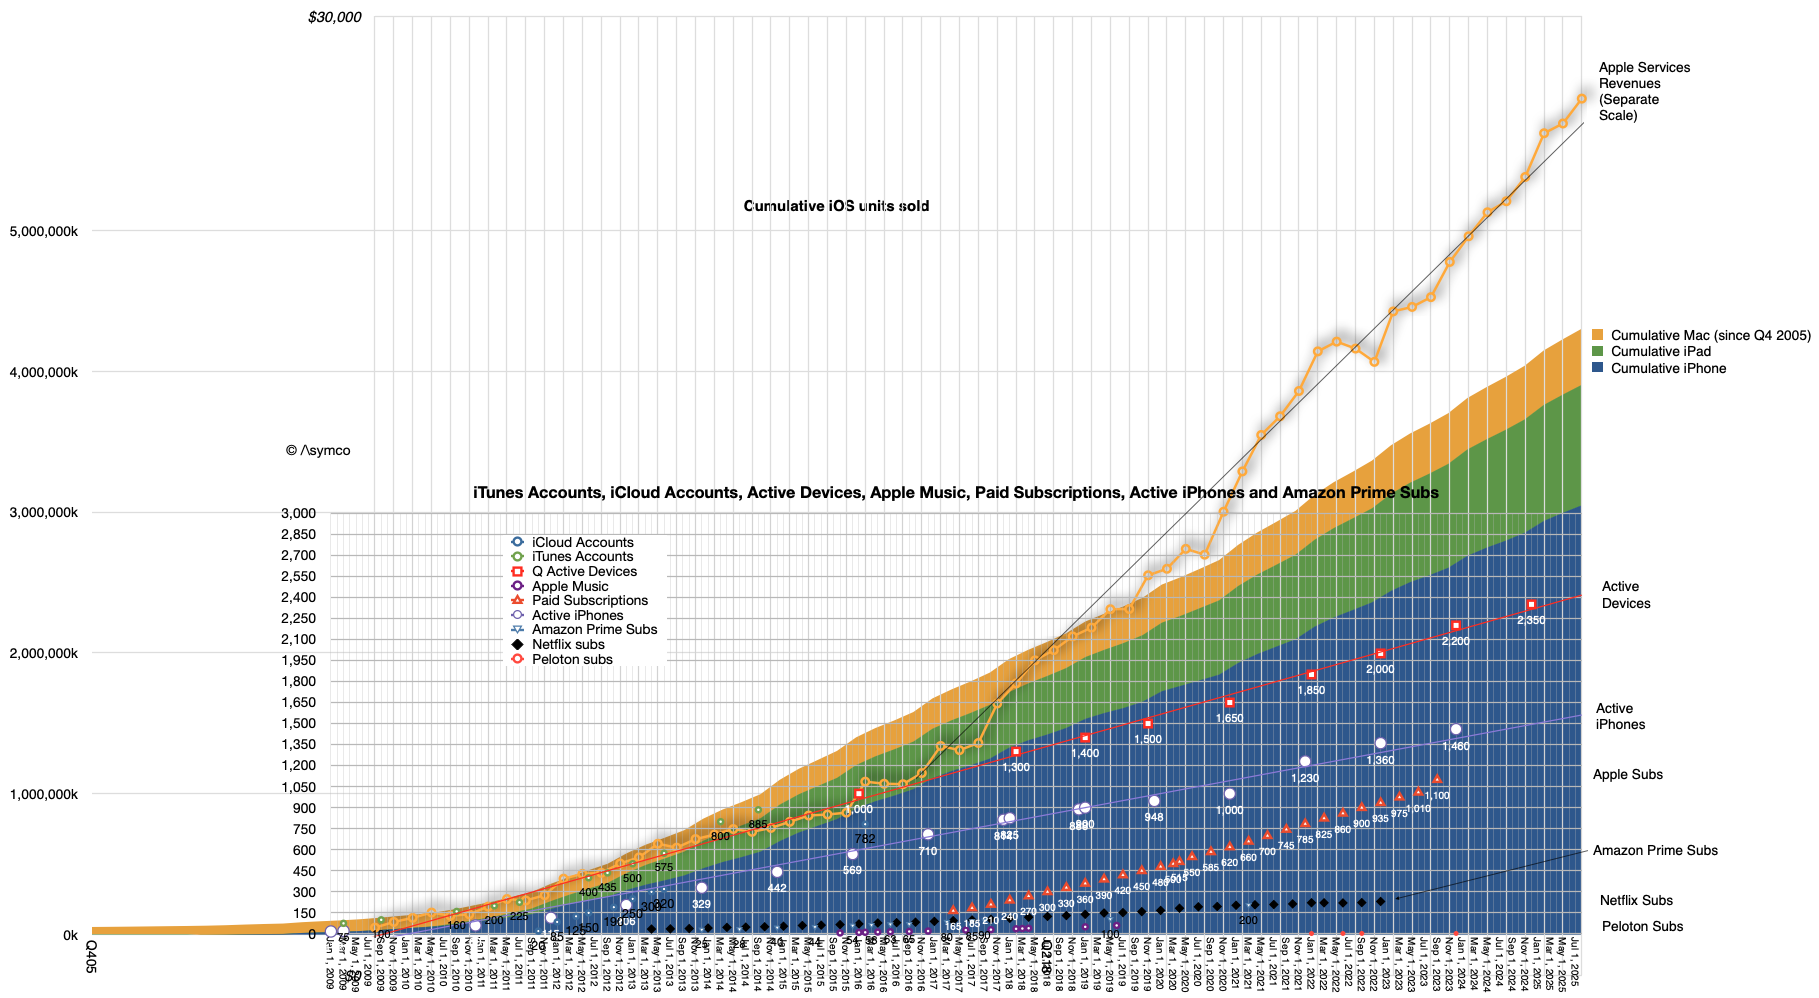
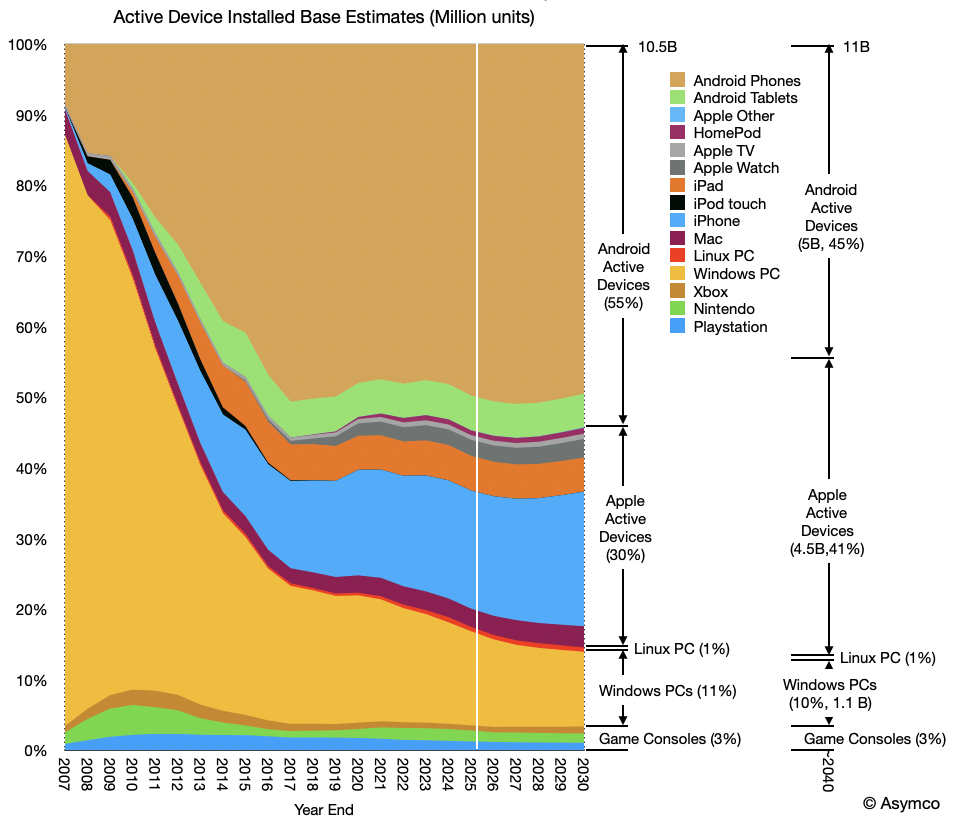
    In January this year Apple reported that there were 2.5 billion active Apple devices in use. This figure has been getting updated for years and I’ve been reporting its trajectory and other measures that are correlated to it. For instance the number of Apple subscriptions, Apple Services revenues and other historical indicators such as iCloud accounts and Apple Music.

    Simplifying, I published the “ACTIVE” model which makes some basic projections of this total device count and it’s shown below” One element of the analysis that has eluded me was the more precise composition of this total “devices”. →


    Nota Bene

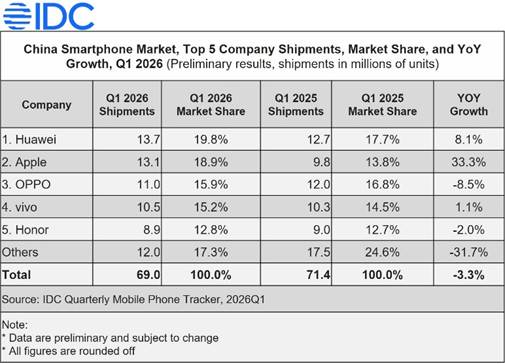
    IDC: Apple Grows 33.3% in China as Market Declines 3.3% in Q1 2026

    IDC: Apple Grows 33.3% in China as Market Declines 3.3% in Q1 2026

    IDC: Apple Grows 33.3% in China as Market Declines 3.3% in Q1 2026 → CounterPoint reports a 4% YoY decline in China's Q1 2026 smartphone shipments, with Huawei and Apple holding nearly equal shares around 20% each, as memory shortages impact the market.

    Both researchers say Apple share in China is about 19%, nearly tied with Huawei at 20%…

    Some analysts are increasing their targets finally realizing that the memory supply crisis might be beneficial to Apple. This should have been noted already three months ago when Apple provided extraordinary guidance for the March quarter. →


    MacBook Neo Sold Out Through April

    MacBook Neo Sold Out Through April

    MacBook Neo Sold Out Through April → Despite high demand and stockouts, Apple's strong brand and competitive pricing could turn challenges into opportunities for market expansion.

    Microsoft’s cheapest laptop is three times more ex…

    As I will argue in a further post perhaps this is one of those pivotal moments. →


    Goldman forecasts fiscal second-quarter EPS of $2.00

    Goldman forecasts fiscal second-quarter EPS of $2.00

    Goldman forecasts fiscal second-quarter EPS of $2.00 → Goldman Sachs remains bullish on Apple, forecasting $2.00 EPS driven by strong iPhone and Services growth, dismissing overly pessimistic sentiment as the company consistently gains 100 million new customers annually.

    My target of $1.98 seems amiss.…

    What is always happening, the reaction that is always ongoing, is the creation of 100 million new customers every year. Accelerating this process is not a matter of just new products or change in sentiment with AI. Much of this rate is due to overall global economic and demographic change. →


    What’s the consensus on $AAPL?

    What’s the consensus on $AAPL?

    What’s the consensus on $AAPL? → Apple's strong analyst backing with a 15:1 Buy:Sell ratio and $315 target contrasts its 39% year-to-date rise, overlooking potential future growth.

    The consensus is positive though share price target does not consider significant share gains and service growth acceleration into 2027.

    NB: The consensus is positive though share price target does not consider significant share gains and service growth acceleration into 2027. →


    Apple 3.0: JP Morgan expects that Apple will beat its own guidance next week

    Apple 3.0: JP Morgan expects that Apple will beat its own guidance next week

    Apple 3.0: JP Morgan expects that Apple will beat its own guidance next week → Analyst Samik Chatterjee projects Apple's EPS to rise to $2.05 from $1.96, driven by strong iPhone and Mac demand, with a revenue boost to $112.7 billion, while I estimate a slightly lower 20.2% EPS growth, anticipating guidance will be met.

    Read the original for a more detailed commentary from Chatterjee. He implies Apple will grow EPS 24%…

    …My own estimate is about 20.2%. I look forward to a lively quarterly update. The primary source of growth must be the iPhone and I have that growing at 19% revenue growth. Last quarter the growth was 23%. Perhaps Chatterjee is assuming a similar growth rate into March quarter. That is not impossible but I am assuming guidance will be met rather than exceeded. →


    Asymco One gives you full access to our research, analysis, and commentary. Subscribe with code BULLETIN for a discount.

    Feedback: Have questions or comments? Reach out to us at contact@asymco.com. We’d love to hear from you.

  3. What's the consensus on $AAPL?

    Nota Bene

    Buy:Sell is 15:1

    The analyst consensus price target sits at $297.46, with 31 Buy ratings against just 2 Sell ratings across 48 analysts. Both Citi and Morgan Stanley sit above consensus at $315, signaling above-average conviction. Apple stock is up 39% over the past year, so the transition arrives with the stock already reflecting significant strength.

    Citi and Morgan Stanley both maintained Buy/Overweight ratings with $315 price targets on AAPL stock.

    Source: 24/7 Wall St. via Analyst: Atif Malik

    NB: The consensus is positive though share price target does not consider significant share gains and service growth acceleration into 2027.

  4. John Ternus has left big shoes to fill

    Research · 4 comments

    April 21, 2040

    It's been 15 years but John Ternus has finally stepped down as Apple CEO. Analysts described the transition as expected rather than disruptive, noting that investors had long anticipated Ternus' eventual departure. Nevertheless, he leaves with many questions still unanswered about Apple's long term strategy. Apple incoming CEO faces a defining challenge: Fixing the company’s Services dependence.

    It's been a tumultuous tenure for Ternus but he is leaving with significant accomplishments:

    • John grew Apple devices to 4.5 billion from 2.5 billion when he took over in 2026. Many have pointed out that he has been building on Tim Cook's success and that John has only added 2 billion devices in 15 years, averaging 110 million per year. The reality is that most of those have been switchers from Android rather than first-time users. Because of this, Android's 5 billion active devices means Android users still outnumber Apple users. Apple's users do have attach rates of over 2.5 devices per user including passive AI wearables but the competition is not standing still. The new CEO will face the challenge of trying to wrest majority market share in a saturated 12 billion active device market.
    • With over 2 billion customers, Apple is capturing over 40% of all AI revenues. Critics point out that the company has not grown beyond its core: high net worth and high income households. Much of that foundation was laid by his predecessor and arguably all that John has done is maintain a base that grew organically as global income has risen. Over a billion middle/high income individuals have joined the world economy as Apple users but that is hardly attributable to Ternus. His engineering acumen did not give him the insight into marketing to low income countries where most of the users are shunning Apple products.
    • John has had to navigate a challenging geopolitical situation with the rise of India as the world power and the decline of China. Critics pointed out that Apple's dependence on India is an Achilles' heel and that his transition of production and market growth from China to India has been rough and challenges remain with regulation and labor unrest. The Indian middle class has been the growth engine for a decade but, as all eyes are on Africa and South America, Apple has been on its back foot.
    • Apple grew the AI business but now depends too much on in. Growth since 2038 has slowed from mid teens to low teens and analysts are pointing out that Apple is too dependent on Services as its biggest source of revenue. Apple's P/E ratio is now below the average of the Fab Five reflecting investor skepticism that it can capitalize on submersible data centers in international waters. Its insistence on local sovereignty for data storage goes against the bathospheric consensus.
    • Competition has been kept at bay, so far. Apple has seen off challenges by Anthropic, Netflix and SpaceX but there are hundreds of startups looking to build the next Services killer. Billions of satisfied customers are not the moat they used to be.

    Apple has made it this far, recently celebrating its 65 anniversary but there is no guarantee that it can continue its run as the world's most valuable company. The next CEO has to steer the ship Ternus just managed to helm through stormy seas.

  5. Succession, study of the firm vs. study of the person

    Research · 2 comments

    The Asahi Shimbun Interview Part 5

    Coronation of Celestine V; ~1215 – 1296. The only Pope to be crowned twice.[1]

    Horace Dediu / Takeshi Narabe & Dylan Weir / Asahi Shimbun Interview, April 1, 2026

    Dylan Weir • 31:51
    There's been some reports that Tim Cook is on the way out and some speculation about who might replace him. Is that your sense, that he will be leaving soon?

    Horace Dediu • 32:06
    One thing that hints in that [direction] is that the board members are actually limited to age 65 and he is on the board although they can extend that by vote. So one should imagine that there is an age limit. The hypothesis however is that he's too valuable. Not so much as the manager but as the negotiator and as the diplomat. Because we live in such difficult times from a geopolitical point of view he somehow has managed, i don't know how, nobody knows how, even Warren Buffett recently pointed out that he thinks that's one of his greatest skills: that everybody likes Tim Cook.

    That includes China that includes Trump that includes Europe. Somehow he gets along with everyone. So his ability to be the diplomat, will it be perhaps valued further? One possibility would be that he actually becomes executive chairman as opposed to CEO. That he continues in that role without having to do day-to-day operations.

    There are people who are very good at that. And who've been on the bench for a long time and who've been cultivated for a long time to step in his place. So in that sense, on these fundamental questions of biological life...

    You know, I think one hypothesis that makes sense is that he might stay as long as there's a Trump administration, because again, he's able to navigate that world. But yes, I think ultimately, though, he will be gone. And there's no question. And when he joined, he knew he'd be gone some day. There's no naiveté about his need to hand things to the next generation. And I think that was part of the thinking under Steve as well: How do we hand this off? And they've been thinking about it ever since.

    But anyway, the speculation is John Ternus is the next in line. I think that's a very plausible hypothesis. And one reason, by the way, is I always maintain if you study the company from a cultural point of view, you'll realize that there are people who cannot be CEO. You may not know who it's going to be, but I can tell you who won't be. Many people over the years suggested candidates, and I would say no, never. And here are examples. Johnny Ive would never be CEO. An external hire would never be CEO. Even a head of marketing would never be CEO. Many people think that Apple is a brilliant marketing company. No, it's an engineering company. It's a huge secret out there.

    If you look at the headcount, if you divide the employees by their job functions, you'll see that engineering is by far, three to four times, bigger than the next category, which would be perhaps marketing or operations. So what does that mean from a cultural point of view? It means that the people who are engineers want to have a boss who can listen and understand them. And they don't think, if you know engineering culture, […] that someone who's from marketing is going to be able to understand them because they don't have the cultural and the educational background or the mentality around engineering.

    And so the people who need to run Apple have to be competent with engineering. In the case of operations, it's one of those acceptables because they are at least covering engineering as one of their constituencies. So they have to bridge between manufacturing, distribution, and all these things. So engineers respect operations. Engineers respect manufacturing. So in that sense, when you look at the candidates, I do think John is one of those who fits the bill. Of course, there could be many others as well.

    Dylan Weir • 36:36
    That's fascinating. Thank you.

    Horace Dediu • 36:41
    I think if I may just summarize, I think it's very rare that any analysis--and I come from an engineering background and I did my work always in a lot of data, using a lot of data. But the more I study Apple, the more I think it needs to be analyzed culturally. And it's a very difficult thing to do because we have no data. We have only some anecdotes. But you have to, as an analyst, you have to be humble and see that the data, perhaps that [which is] most important, is not available.

    When it's dark outside and you're searching around the lamp, well, that's the only area that you have light. but the truth could be in the darkness. And that area under the light, that's your data set. And the solution is somewhere else perhaps. And that's why you have to have this idea: what tools can we use other than looking at the light? Use all your senses. Use other perceptions.

    And so that's why I think Apple is a peculiar thing. And by the way, the analysts out there who do try to stay out of the data [delve] more into psychology, they tend to really study the man or woman. They'll study the personality as an alternative [to the data]. So they'll say, well, the company's success depends on Zuckerberg. We have to know who he is. Or Tim Cook or Steve Jobs or Larry Ellison, whomever it is.

    There are people who specialize in understanding that person but i don't think Apple is that. I think [personality is] important but you have to study the whole. The whole way they do things internally. They give us plenty of hints; they say all the time that it's a team effort. They'll always say "no it's not me, it's it's a group effort".

    And and they always say "we" [not I].

    You know, we have a lot of debates [but I believe] we have to take them at their word that it isn't just the individual.

    Takeshi Narabe •

    Thank you so much it's very you know insightful analysis thank you very much.

    Horace Dediu • 38:57
    i love your questions. You have great questions and that's always my my biggest thrill. And not that i'm not being asked what color is the next iPhone.

    Previous in series: Part 4: How not to over serve; The machinery of vanity

    Interview as published: 聞 Asahi Shimbun on Apple & Innovation

    1. Sic transit gloria mundi means "thus passes the glory of the world". The phrase was used in papal coronation ceremonies between 1409 and 1963. As the newly chosen Pope proceeded from the sacristy of St. Peter's Basilica, the procession stopped three times. On each occasion, a papal master of ceremonies would fall to his knees before the Pope, holding a silver or brass reed, bearing a tow of smoldering flax. For three times in succession, as the cloth burned away, he would say in a loud and mournful voice, "Pater Sancte, sic transit gloria mundi!". These cautionary words served as a reminder of the transitory nature of life and earthly honors.
  6. Asymco One: Mobile Computing

    Research · 2 comments

    As you know, as we crossed into 2001, the great crash occurred.

    Ben Thompson • 25:05
    Yep. And suddenly a job offer from a big phone company sounds pretty great.

    Horace Dediu • 25:09
    Yeah, but the crash occurred and it impacted my startup because I couldn't raise money anymore. And that's why I'm throwing in the towel. I'll take this idea to Nokia and build it inside of this company. So for the first year, I worked out of the U.S. and then they invited me to come to Finland. And I fell in love with it, not to mention finding someone to fall in love with. Yeah, I'm still here.

    So we created an internal venture called media distribution. And it struggled for a couple of years. We partnered with a publishing company here in Finland that is the biggest newspaper and magazine company. And we worked with them. 9-11 happened. We worked with them throughout that period to test this idea of distributing content on phones. That's how I met my wife. She was working for the publishing firm. Remember when Apple News launched? I forget how many years ago it was already. It was five, six years ago. [My wife] texted me during the keynote. She goes, "you realize that's what we were working on together in 2001?"

    It was called Project Melissa. Project Melissa was this idea of Apple News today. And that was [our project] 20 years earlier. That just goes to show you the story of my life. I was doing search 10 years before Google existed. I was doing e-books 10 years before Amazon launched the Kindle. I was doing smartphones and media distribution on smartphones 20 years before Apple showed how it's done.

    So my problem has been that I see things happening or see where things are going, but way too early. And that's why one of the theses I have over time is the idea that the difference between a futurist and a billionaire is knowing when one thing happens. So it's not about knowing what's going to happen. A lot of people are very good at that.

    Ben Thompson • 27:31
    Including Nokia, to your point.

    Horace Dediu • 27:33
    Nokia, science fiction writers, Elon Musk, a lot of people predict this. But getting the timing right is where the money is made. And so that was one of those lessons I learned.

    Ben Thompson • 27:45
    Well, when you talk about the publishing and Nokia and the reading and all those sorts of things, what it makes me think of is when the iPhone comes along in 2007, And I'm very curious to get your perspective on what that was like inside Nokia when the iPhone launches.

    Horace Dediu • 27:59
    I'll tell you exactly.

    Ben Thompson • 28:00
    But before I get there, but to this publishing point specifically, the key bit was the Internet was permissionless in terms of producing content. Like, it's great that you met your wife, but the fact that you needed to be in a situation where you could meet your wife was actually the reason why it wasn't going to happen. Because if you have to make a deal to do everything, it's just never going to get there. Whereas if you can just surf the Internet, the real Internet, and no one needs to do anything to adapt to it, suddenly you get it all for free. And then you get the virtual cycle going where they're making stuff for you. And that was sort of the, that's the timing bit is like the, the external structure around what you're doing.

    Horace Dediu • 28:41
    Yeah, it's, it's, it's complex and it's multi-causal and you're right. It's multiple, the reasons why things happen the way they are. And it's just not foreseeable. The internet was, and by the way, the thing that really caused the project to fail and be abandoned--this media distribution side note-- it was the fixation on DRM.

    DRM actually killed a lot of great businesses with content ideas back in the day, whether it was music or video or textual. It was people just obsessed about protecting it before they obsessed about distributing it and making it great. And this is why when iTunes came along, even though there were some circumstances there with being on a Mac and not on the PC, that the publishers finally said, why don't we go ahead with this?

    So long story there. But as far as what Nokia was doing, after four years of doing this startup inside of Nokia that did not work out, I got into the job of strategy analysis and competitive analysis. So they asked me to do Microsoft.

    Microsoft was the biggest worry for everyone because they had intentions of being in the phone business. They made no secret about it. They had prototypes. They were working with competitors to Nokia. [Intending to] give them the operating system so that [for instance] Samsung running Microsoft [Mobile]. That was the effort.

    They were pushing on all fronts. Nokia was holding out and saying "we've got our own operating system" and so on. So they gave me this job because every other competitor was hardware. All the analysts were covering hardware. I was the only guy who was covering a software company.

    And in doing that, I was also sort of nibbling at Apple a little bit because the iPod had come out. The iPod was doing amazing, but it wasn't a phone product. And I was kind of looking at it a little bit.

    Now Christensen comes back in the picture, because his book had taken off. He had already written the second book, which is The Innovator Solution. And I was like, hang on a second, a lot of stuff that I read in the book, and I remember back from my days at school, applies to Apple here because they're doing a lot of interesting things with being disruptive as the case may be.

    Nokia itself had been disruptive in its early years. But I'm focused on Microsoft. And my point was that we can fight this battle and win, but we got to be very careful. And there's a lot of twists and turns there, but I took it upon myself also to understand what's going to happen with this media product from Apple.

    And then I began to write a few internal notes because nobody was covering Apple. This is interesting and important. Imagine you have a team of a dozen analysts, you could put them on multiple jobs, assign people to multiple problems. No one thought that Apple was a problem to be looked at, even part time. No, there was nothing interesting about it.

    And part of that had to do with the fact that [Nokia perceived that Apple had been] one foot in the grave already in the 90s. And now they were this little toy media company. They didn't really have scale. Phones were on the orders of billions of users already. And this iPod was in the tens of millions, maybe a hundred million. So it was orders of magnitude. There was no real worry there.

    But I was really annoyed at this thing. And I started building a model. I remember distinctly opening a spreadsheet, looking at research reports and thinking to myself, let's look at the history of the iPod, how it's growing. And I started to match that to the Razr, which was the most viral product at the time, the Motorola Razr.

    Even Nokia was jealous about this thing. At that time, [Motorola] had cumulative sales of 50 million, which was considered way too scary. (And BlackBerry was another one, by the way.) So I'm doing this and I'm like, hang on a second, what if they do a phone and it's a combination of the Razr and the iPod, could that resonate? And I just put it out there. I said, it's possible. And there was a rumor of the iPhone coming out.

    Ben Thompson • 33:31
    So Apple did do a Motorola Razr with iTunes functionality. Did that actually end up, because that was a flop. And did that actually make people not as like more relaxed?

    Horace Dediu • 33:46
    Because we knew that it didn't run an operating system. It didn't have a developer API, there was nothing, no hooks in it. It was just an appliance. And as such, it was like a feature phone. And that was not interesting. We had been talking and pounding the table on smartphones already since 2001. Remember, when I joined, we had a communicator. We had Symbian, Series 60. We had the interfaces. We had all picture phones, music, etc.

    Ben Thompson • 34:20
    I was a user as well.

    Horace Dediu • 34:22
    And I had done the numbers, and by 2005, people were burned out on smartphones. Because the projection was like this, but it was more like this. It wasn't growing as much as you thought it would. And so a lot of people said, especially the top management was like, "you guys are very enthusiastic about the software stuff, but it's just not working out. We're going to double down on hardware."

    So there was a lot of burnout. So, but I kept looking at the phone at Apple and I suggested, hey, what if this thing scaled anyway? Like I said "what if they could sell as many as 50 million?" That was my provocation. And people were like, dude... I was essentially taken aside and told, tone it down. First of all, you're not doing yourself any favors by being so provocative. You're just going to lose credibility. My boss, who's a great guy he just took me aside and said, just don't do that. You know, it's bad for you.

    Ben Thompson • 35:22
    And this is like 2005, 2006, around then?

    Horace Dediu • 35:25
    Well, already 2006, because the iPhone was rumored. It wasn't out, but it was like, if you're going to have iPod success and you're going to do this crap phone with Motorola, you're probably thinking, maybe they're going to do something interesting beyond that, because we knew they could, in theory, do something.

    We didn't see the touch interface, but we saw maybe like a scroll wheel or something. You know, Tony Fadell was running the thing. So, bottom line is, when it finally came out, it was January 2007. It came out and was not for sale, but it was on stage. And I was so excited. And I said, this is unbelievable.

    I remember running into the office the next day. Usually you socialize at lunch hour, sitting in the cafeteria, talking to your friends and asking them what do they think about this? And most people just said, oh, it doesn't look that interesting. aspects of it were copied. There were copies from here and there. There are other people that do touch. You know, a stylus has been around for a long time with BlackBerry also doing amazing things with keyboard and so on and so on.

    So there was a lot of cynicism and sort of not really interesting. I said, man, it's running OS X, it was running a full operating system. And I said, this is going to get developers working on it. But again, the other thing, the other head fake from Apple was that Steve Jobs said they're not going to put any apps on this thing unless Apple write them. I was anticipating far more than even was being talked about. And for that reason, it was just super frustrating. Anyway, I left in 2009. But by then, Nokia were still not following Apple.

    Ben Thompson • 37:13
    How is that possible? Like even two years on, this device is out there.

    Horace Dediu • 37:19
    Because it still didn't have distribution. And this is the thing that consumed everyone following the iPhone in the beginning. It's like they had one launch partner. It was initially Cingular, became AT&T. Don't forget that the old AT&T had nothing to do with this AT&T. It was just a rebrand of Cingular, which was a crappy, small, not very small, it was maybe second tier [operator.]

    Ben Thompson • 37:47
    Verizon didn't want to do it. Apple did this again and again. Verizon was number one.

    Horace Dediu • 37:50
    Verizon was number one. Absolutely. But Verizon was in CDMA. But the thing is that it was a crappy network and they didn't have a lot of points to sale. They didn't have distribution. and everybody said this, you need 500 network operators to saturate the global market, right?

    And how fast are you going to be able to obtain distribution was the question. And so they're so cantankerous. You know, Apple is known as being "my way or the highway."

    Verizon said no for years. Nokia was like, this is not going to fly. These guys are, if anything, they're naive. Don't forget, by the way, there's a separate story on how BlackBerry dealt with the iPhone. There's a movie about it, by the way. Everybody should watch it. But basically, everyone had the similar responses: that this is not kosher.

    This is not the way things are done in this business. It's all about relationships with operators. It's about getting shelf space. It's about getting salesmen in the store who are bribed effectively with a commission to tell you what to buy, effectively yank the phone out of your hands and give you another one. So this was a very dirty business at the street level.

    Ben Thompson • 39:19
    So do you know what was the first what was the first article of mine that I think you ever linked to? It was about precisely. No, no, you don't need to know. I know because it was very formative to me. That's what I'm going to tell you. It was basically about talking about this was how distribution worked.

    And what Apple changed about the whole thing was that customers actually switched networks for the iPhone. And it was doing just sort of a traditional sort of business school analysis of and pointing out the power shifted to instead of distribution to the buyers. Basically, what I ended up writing about for 13 years now is demand mattering more than sort of the supply bit. But it was the exact same thing. That's why you linked to it. You are you are already on board with it.

    Horace Dediu • 40:04
    But it was also the thing that resonated for me personally. Not that I knew something about the phone. Mostly I knew how big it could get. I knew that there were billions of people, many more billions than used PCs, which was by far the most dominant influence in technology.

    Most people oriented themselves, like even Gruber and others who were Mac first and then all these accessories. But I knew the phone would be a couple of zeros more. That was number one.

    Number two, there was this problem of the incumbency, which were all the phone makers, who were so far from understanding what the software dynamics of platforms were. By the way, platform theory was developed by Microsoft. They pretty much invented the whole idea.

  7. Monday Notes: Neo still sinking in

    Nota Bene · 5 comments

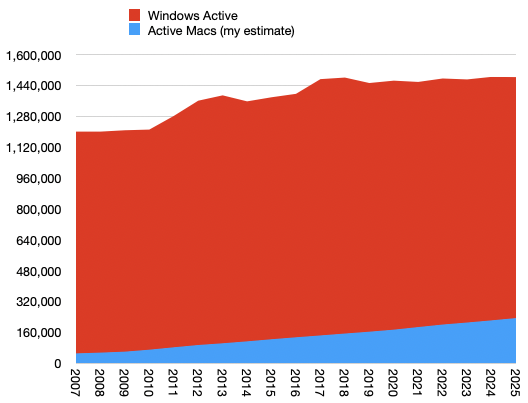
    260 million Mac users? Huge room for growth.

    It’s a massive untapped opportunity for Apple, whose Mac installed base of 260 million units lags far behind the iPhone installed base of 1.5 billion units. Mohan believes the total addressable market for the Neo could be $32 billion for 2026. If Apple can capture just 10% of that market for budget laptops, and do so with a 19% operating margin, the company can boost earnings per share by an incremental 3 cents, according to Mohan.

    “We see Neo driving meaningful adoption for first-time Mac owners with a distinct customer base relative to the Air and Pro models,” Mohan wrote.

    The Neo will dramatically disrupt competitors in the market for budget personal computers, Seaport analyst Jay Goldberg wrote in a Monday note, as the $500 to $700 price tier is one of the most profitable segments for PC makers. Both Mohan and Goldberg have a buy rating and $320 price target on Apple’s stock, implying over 20% of upside from current levels.
    Read: Apple turns 50. Here’s how it can shake its midlife crisis.

    As Apple expands into the budget computer market, the company is also looking to seize share from its smartphone competitors during a period of memory crunch. Artificial-intelligence infrastructure is gobbling up so much memory that many suppliers have sold out their capacity through at least next year. That has an impact on makers of consumer hardware that also count memory as a key component.

    Apple has been paying a premium to buy up memory chips in what Goldberg believes is a “is part of a deliberate strategy for the company to tighten conditions for its competitors.”
    This strategy forces competitors to either raise prices for customers or reduce the memory content in their products, according to Goldberg. Meanwhile, he believes Apple intends to maintain both the memory content and pricing of its phones, allowing the iPhone maker to gain share even as the overall phone market shrinks by roughly 10%.

    This strategy “will not come cheap for Apple,” Goldberg warned, noting that Apple’s product gross margin could sink to the low-30% range from the high-30% range seen a year ago.
    “That said, we think the company can make up for some of this lost ground through its share gains,” he wrote, as new Apple users are likely to subscribe to Apple’s higher-margin subscription services to offset the hardware costs.

    Mohan expressed similar sentiments, arguing that the Neo could lead to a stickier overall installed base for Apple and “increased services use over time.”

    Source: MarketWatch

    NB: Two analysts, two stories. The Neo will move the needle and the supply crunch will hamper competition…

    As I wrote before, the key metric is the number of Mac users. 260 million is a reasonable assumption. Over 350 million Macs have been sold in the last 20 years. If we assume half are new to the platform then 175 million have been added. The base in 2006 was probably in the 50 to 60 million range putting the total today at 250 million.

    It's a long way to go to 1 billion Mac users and I don't know if it will ever happen given that most will have to switch from Windows and the lock-in is strong regardless of a better and cheaper alternative being available.

    Nevertheless, a doubling of the Mac user base is certainly a worthy and achievable goal over the next decade.

  8. Asymco One Office Hours Live Q&A with Horace Dediu & Gene Munster: April 8, 2026

    Office Hours

    A lively discsussion of Apple topics such as:

    • Geopolitics: China concentration; Taiwan tail risk
    • Financials: Solid near-term growth
    • AI: Critical narrative shift; to be proven
    • Growth Strategy: User expansion
    • Business Model: Evolution: hardware → services → Personal AI platform
    • Moat: Privacy + integration; trust

    Non-Subscribers:

    Join Asymco One as a Subscriber to participate OR

    Just Register to Watch live.

    Contact us at events@asysmco.com if you have any questions.

    For most up-to-date information, see

  9. iPhone sales continue to surge into February - Bernstein

    Nota Bene · 1 comment

    Apple's iPhone continued strong sales in February

    Apple’s iPhone continued strong sales last month, thanks to the popularity of the iPhone 17 line, Bernstein analysts wrote in an investor note on Monday.

    According to the report, global iPhone sell-through increased 26% year over year in February. Overall, the analysts say iPhone 17 unit sales are up 20% versus last year’s iPhone 16 through September and January.

    The base model iPhone 17 accounted for 39% of that growth, while the iPhone 17 Pro Max made up 21% of the increase.

    Average selling price, or ASP, also climbed in February, growing 6.9% year over year. So far, ASP has improved each month since the iPhone 17 launched in September, with the exception of October, Bernstein said.

    The analysts said China provided the biggest boost to ASP, with growth of 20.2% year over year.

    Source: Yahoo Finance

    NB: Guidance provided by management was at the end of January and thus February was well within sight.

  10. Apple at 50 - Ben Thompson interviews Horace Dediu

    Podcast · 4 comments

    Ben Thompson of the Stratechery interviews Horace on the Stratechery Plus Podcast to discuss Horace's journey to become an influential tech analyst: early career in research, business school under Clayton Christensen, and his time at Nokia during the rise of the iPhone. 

    The conversation further explores Disruption Theory in the context of both smartphones and AI, why Christensen misjudged Apple, and whether AI could challenge today’s tech giants. It also marks the launch of Dediu’s new paid service Asymco One and reflects his continued conviction in Apple Inc. at its 50-year milestone.

  11. Survey shows iPhone improved retention, purchase intent, growth in services, service pricing, product mix, foldable upside

    Nota Bene · 1 comment

    Attach rates for iCloud reached about 42%, while Apple Music stood near 30%

    The iPhone ecosystem is showing signs of increased customer loyalty and steady demand, while its high-margin services business remains a key support to profitability, according to UBS analysts.

    The bank, which maintains a 'Neutral' rating on Apple with a 12-month price target of $280, cited findings from its Evidence Lab survey of roughly 4,000 iPhone users globally. The data suggests that iPhone “stickiness” continues to improve, even as replacement cycles remain relatively stable.

    UBS said the average age of iPhones in use globally was largely unchanged year-over-year at about 33 months. Outside China, device age edged slightly higher to around 38 months, a trend the analysts said could push some upgrade demand into 2027.

    At the same time, customer retention strengthened, with the global iPhone retention rate rising about 200 basis points to roughly 74%. Gains were particularly notable in the United States and China, where retention increased by 200 and 700 basis points, respectively. UBS belives that this indicates Apple is maintaining share despite a competitive smartphone market.

    Purchase intent also improved across regions, with more surveyed users indicating their next smartphone would be an iPhone. The UK recorded the largest increase, while China also saw a meaningful rise despite what UBS described as a challenging competitive backdrop.

    The report highlighted continued growth in Apple’s services ecosystem, particularly iCloud and Apple Music. Attach rates for iCloud reached about 42%, while Apple Music stood near 30%, trends UBS said should help sustain services gross margins above 75% through fiscal 2026 and 2027.

    Higher-tier iCloud usage is also increasing, even as Apple raises base storage on newer devices. Among iPhone 17 users, 77% reported subscribing to mid- to high-tier iCloud storage plans, compared with roughly 60% across the broader installed base. UBS noted that additional services uptake carries incremental gross margins of at least 90%, helping offset potential pressure from rising memory costs.

    On the hardware side, consumers are also opting for higher storage configurations. UBS wrote that 56% of iPhone 17 users purchased models with more than the base storage, up about 800 basis points year-over-year. This shift could support product margins, with incremental storage estimated to generate gross margins of around 75% on roughly one-fifth of sales.

    Looking at the installed base, UBS estimates about 68% of iPhones in use are from the 14 through 17 series, while around 40% are Pro or Pro Max models. The analysts said this premium segment could be a target market for a potential foldable iPhone, though they expect the opportunity to be relatively limited given the anticipated price range of $2,000 to $2,500.

    UBS estimates a foldable launch could result in as many as 8 million units in fiscal 2026, contributing roughly 6 million incremental iPhone shipments, or about a 2% uplift to its forecast of 251 million units.

    Source: Yahoo Finance

    NB: Neutral rating. Let's summarize the findings.