Asymco

Asymmetric Intelligence

Android

  1. And then there was one. Sony Ericsson to stop making Symbian phones

    Research · 17 comments

    Sony Ericsson is to stop making smartphones featuring Nokia’s Symbian operating system.

    The move means that the troubled Finnish mobile maker is likely to be the only significant user of Symbian.

    Analysts said Sony Ericsson’s decision confirmed the “failure” of Symbian as an open source platform, given that it was supposed to be used by several large mobile makers.

    via FT.com / Technology - Sony Ericsson to stop using Symbian system.

    While Android and Windows Phone continue with a licensing model, the list of abandoned licensed mobile operating systems grows:

    • First there was the original PalmOS/Garnet OS (from Access), licensed in its day by several vendors including Samsung.
    • Then came SavaJe that was dead on arrival.
    • Then there was Windows Mobile with over a thousand devices and hundreds of licensees. Now a fading memory.
    • There's LiMo, licensed by operators but not not seen in the wild.
    • And now the mighty Symbian is standing with no takers (except its own parent).

    Note that MeeGo, WebOS, BlackBerry OS and Bada are not licensed.

    In 2010, as Windows Phone is not yet shipping, it's clear that for any vendor without their own operating system, Android has been the only choice.

    The question I have is: how long before every top tier vendor has their own OS?

  2. Escape from license-land: Measuring phone vendor commitment to licensed mobile platforms

    Research · 29 comments

    Windows Phone had its day in the sun yesterday. After discarding its previous seven-year effort with Windows Mobile, Microsoft started with a clean sheet of paper. However, whereas the software has been re-built, the business model has not. WP is still a licensed operating system whose primary customers are mobile phone vendors. With Symbian mostly out of the picture, WP becomes only the second viable commercially licensed mobile OS, after Android.

    So with two licensed platforms in the running, how do we measure success in the licensing business? Units sold to end users is one metric. But that data will have to include the performance of vendors and operators and other distributors. And it will take a year to do valid comparisons. The only indicative metric we have available today is how many devices have been committed by vendors.

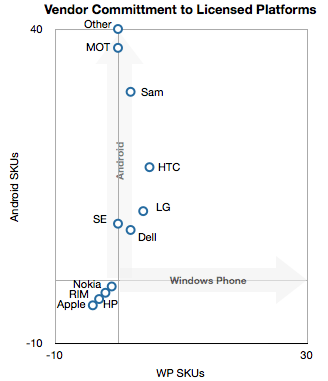
    As WP is out of the gate with device announcements, we can actually measure this. We can plot each vendor's commitment to various platforms as an early indicator of strategic success. To that end, here's the methodology: I took all smartphone vendors and tallied how many SKUs they have announced or leaked for either the WP or Android platforms (source: pdadb.net). I then plotted each vendor on two "commitment axes" (see notes below).

    The more to the right a vendor lies, the more committed they are to Microsoft's platform. The more to the top a vendor lies in the chart, the more committed they are to Google's platform. The vendors which don't have any licensed products lie below the origin.

    What we can observe is that Microsoft has pulled several, though not all vendors partially to its side. The level of commitment is not yet very high and it has not likely reduced their commitment to Android. In other words, points are moving to the right but not (yet) down.

    Framing the platforms this way helps us discuss how the market might evolve with these questions:

    1. Is Microsoft's re-entry going to peel vendors away from Android. In other words, will points move down as well as to the right.
    2. Is there motivation for some vendors to move to their own platforms like the non-committed? We've shown that profits accrue disproportionately to the vendors below the origin. As a result, is the pool of available top tier vendors going to shrink?
    3. Will vendors commit to single platforms or maintain this split OS loyalty strategy? Will we see LG migrate to WP exclusive and will Others remain exclusive in Android?

    I'll throw out my predictions to start:

    Microsoft's strategy is aimed at top tier vendors more than to the "others". This is due to a lesson they learned with Windows Mobile: having a ton of SKUs does not guarantee a healthy ecosystem (a lesson that Android has not acknowledged as true). There are positive and negative consequences. The positive is that Microsoft control the experience better, create a better brand and can participate in an effective dialogue with operators. The negative is that they are going to deal with a diminished licensee pool.

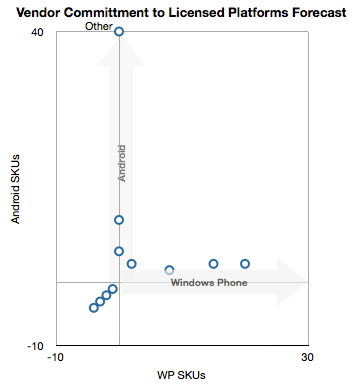
    On the second question my prediction is that vendors are going to move "down and to the left" away from the licensing model. If they can't go direct to that quadrant, vendors will consolidate portfolios around one licensed platform. The distribution of commitment I forecast will look like this:

    Maintaining multiple platform development teams is expensive. Branding is also confused. The upside is that you get to play the operator's divide-and-conquer game of platform dilution (aimed at the non-licensing players in the lower left corner).

    In particular, Samsung, with Bada, is likely to find ways out of license-land. Sony Ericsson may stick with Android and LG may move to Windows exclusively. That really leaves only HTC and Dell as licensees with multiple licenses.

    This axial alignment is not a healthy thing if you are a platform vendor. Having one or two dedicated customers means the power of the buyer is much higher and their wishes become your command.

    Which leaves only one true prize in the game: the "others". Android is clearly the darling of "Others" who are being shunned by Microsoft. Can "Others" become the lever for Google to pry open the market? History and the tangled web that is operator distribution does not point in that direction.

    ------

    Notes:

    1. I considered products announced only since Jan 1, 2010
    2. I did not consider any Windows Mobile legacy commitments
    3. "Other" vendors are off the scale with over 100 SKUs but represented as having 40 SKUs so as to be kept on chart
  3. What did Andy Rubin mean by saying WP7 was created for political reasons?

    Research · 24 comments

    In an interview with PCMag, Rubin said,

    "Look, the world doesn't need another platform. Android is free and open; I think the only reason you create another platform is for political reasons. Why doesn't the whole world run with [Android]? They don't like the people who developed, or "not invented here [NIH]"

    I note some irony in the suggestion that Windows Phone is superfluous when the acquisition of Android was an attempt to limit the growth of Windows Mobile. But that historical footnote is not entirely relevant here. The point Rubin raises is that WP is politically motivated. And by political he suggests two things: that there is mistrust of Google or NIH among potential licensees.

    The NIH argument falls flat because anyone considering WP7 would also have NIH issues with Microsoft. So that really leaves only the question of trust.

    Why would anyone mistrust Google when they offer operating systems software? How about these reasons:

    It's clear that Microsoft is buying its way back into Mobile (it went so far as to pay incentives and guarantees to established developers to convince them to port existing apps or write new ones for WP7), but that is not a political ploy. It's just good old fashioned brute force.

    The mistrust that Google earned for itself with operators, device vendors and potential content partners is rooted in its business model with Android. Hiding the costs of "openness" behind a veneer of freedom. In addition, putting forward competing products like Nexus One threaten the entire value chain.

    I'd say the politics of Microsoft licensing are a lot more transparent. Redmond is the devil they know.

  4. Daring Fireball Linked List: Andy Rubin Talks Android

    Research · 29 comments

    What value have the carriers brought? Seriously. What software on Android phones have the carriers added that’s any good at all?

    Things you don’t hear iPhone users say: “Man, this iPhone would be even better if my carrier could ‘add value’ to it.”

    via Daring Fireball Linked List: Andy Rubin Talks Android.

    Good questions.  I would seriously like to hear any answers to these questions as I have never used any of these operator software phones.

  5. Is Android share of Web lagging iOS share of Web?

    Research · 12 comments

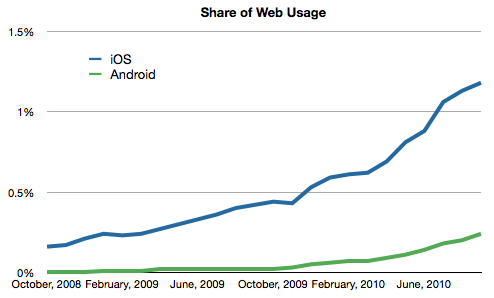
    Of all the public statistics about platform share, Share of web use must be the most important measure for Google. The more browsing people do, the more searching they do and if Google search is most likely for a platform then the more income Google derives from that platform.

    NetMarketshare.com has offered an insight into the split between Android and iOS as search platforms and it shows how iOS is still five times more likely to yield search revenue than Android. That multiple is likely to shrink as the gap narrows, but it still demonstrates the power of iOS to drive Google's bottom line. It's no wonder then why Google has renewed their default placement of Google search in mobile Safari (a guarantee they don't seem to share with all Android licensees.)

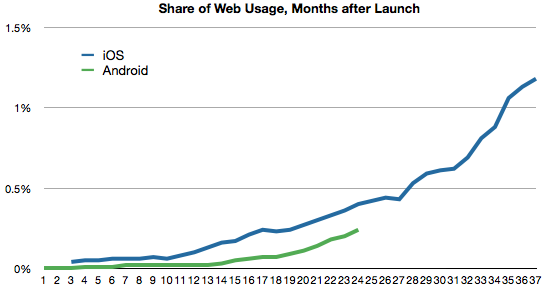
    But Android launched later than iPhone, so everyone should be asking how rapidly the share of Web has grown since the start of each platform. When iPhone launched in 2007 it was almost competing with mobile web non-consumption. The alternative mobile browsing experiences were so bad that it's hard to remember anyone putting up with them. A year later, the bar was set higher and Android filled a vast chasm of demand for mobile browsing for people who could not buy an iPhone.

    At the same point in the life of each platform, Android seems to be exploding in units sold. With this proliferation of Android licenses, it should be interesting to see if their unit share numbers are reflected in web share numbers. So far the story is not convincing. The growth in Web share is not pacing faster than iOS achieved at a similar point in time.

    So far, 24 months into the life of each platform, iOS leads by almost 50% higher share.

    iOS/mobile Safari has the advantage of iPod and iPad for distribution but that does not explain the relative lag of Android with respect to Web share as Android has a large number of SKUs.

    It may be too early to draw conclusions, but anyone trying to analyze Google's strategy with Android should be paying close attention to this.

  6. Android licensees: If you're not paying, you're being sold

    Research · 34 comments

    The latest litigation lollapalooza over Android reminds one of the old web adage that if you're not paying for content, you're the asset being sold.

    That's certainly one of the consequences of the Android licensing model. The mobile phone vendors with no software intellectual property are pawns in a game between IP holders. It's clear that Microsoft and Apple and Oracle (and perhaps Nokia) have IP issues with Google. But it's the licensee device vendors which are most often the accused. Whether Google indemnifies or not is an open question, but the evidence is that the vendors are exposed.

    The proof is in the fact that HTC is paying Microsoft for the use of Android. It's conceivable that Microsoft also asked Motorola for Android royalty payments but were rebuffed. It's also possible that since HTC is still a large scale Windows Mobile licensee, they were given a way out of the Android IP trap by Microsoft. We don't know if there were confidential deals between LG and Samsung on this issue (as they are both committed to the Windows Phone platform but shipping Android). In either case, Motorola may be forced to do the same and pay (Microsoft) for Android.

    It's understood that Google gains some value from Android but also has hidden costs from it as well. Now the licensees have to recognize their hidden costs of the platform as well. There is the IP tax but also the question of control over one's destiny. Google is selling the vendors as an asset class to advertisers. Is that a positive consequence for their brands?

  7. Microsoft suits target Android phones

    Research · 18 comments

    Microsoft Corp. said Friday it has filed patent-infringement lawsuits with the International Trade Commission and in the U.S. District Court for the Western District of Washington against Motorola Inc., targeting Motorola mobile phones based on Google Inc.’s Android software

    via Microsoft suits target Android phones - MarketWatch.

    This follows infringement suits by Apple against HTC targeting Android and by Nokia against Apple targeting GSM patents (with obligatory counter-suits, of course.)

    There was a time when Motorola was a key design win for Microsoft and their Windows Mobile in 2003 with the MPx series. In fact, Motorola still ships Windows Mobile devices like the ES400 and FR68. These are for industrial applications but there were many mainstream Motorola Windows Mobile volume products. The most famous perhaps was the MOTO Q in 2006.

    I'm sure part of the value pitch for Windows Phone is indemnification from IP infringement. Windows Phone will be the only licensed OS that offers this coverage and it's a non-trivial selling point.

  8. Is Google's income from the iPhone offsetting its losses from Android: Cataloging Google's non-Google Phones

    Research · 27 comments

    Google has created a partial list of phones that run Google services.

    Google Phone Gallery.

    I notice with interest that it's called a Google Phone Gallery not an Android Phone Gallery.

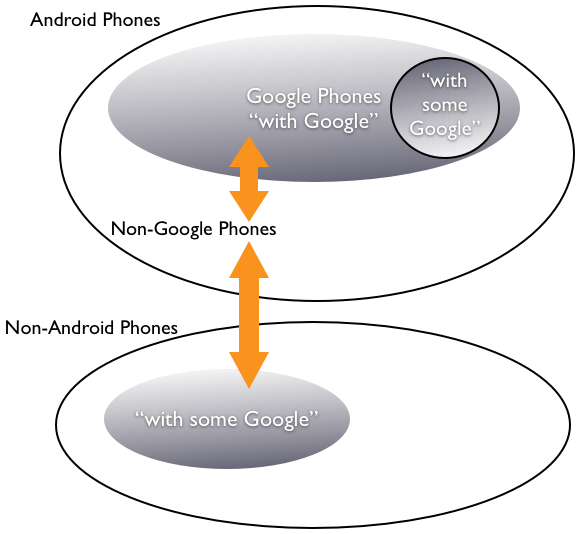
    What's more, there is a distinction of All Phones and Phones "with Google". Of course that implies that we can get a list of Google Phones "without Google" (or maybe more accurately, "with partial Google").

    To clarify, according to Google there are three categories of Android Phones:

    • Google Phones "with Google" have been optimized for use of Google Mobile Services, providing easy access to Search, Voice Search, Google Talk, Google Maps, Gmail, Sync, YouTube and Android Market (where available).
    • Google Phones "without Google" list includes Android phones that have the Android market, Search, Maps and Gmail. You can get this list by subtracting the Google Phones "with Google" from all the Google Phones.
    • Non-Google phones. Android phones that have no Android market or any Google services. You can get this list by taking a list of all Android phones (e.g. from pdadb.net) and subtracting all Google Phones.

    I would also add a fourth category of Google phones:

    • Non-Android phones that serve up Google services just fine.

    Since the list is not complete, I won't tally it here, but it suggests a large number of Non-Google phones is possible.

    [I drew the following Venn diagram to help explain the situation. The shaded areas are those which generate revenue for Google. The interesting struggle (marked with arrows) is between the non-Android Phones with some Google and the Android Phones without any Google.]

    Now the question that needs to be asked is: How many of the Non-Google Android phones are built to compete with Google (e.g. on Search, Voice, Maps, Media and App sales)? And a second question: How are the Non-Android phones "with some Google" competing with the Non-Google Android phones.

    In other words, from Google's point of view: how successful are companies other than Google at delivering Google services in spite of competition from companies with Android phones delivering services that compete with Google?

    The classic example being: how effective are iPhones with Google services at competing with Verizon Droid Android phones that deliver Microsoft services? In this scenario Apple is delivering value to Google shareholders while Verizon (using Android) is taking it away.

    Is this trade-off a net positive?

    In other words, is Google's income from the iPhone offsetting its losses from Android?

  9. Unix's Revenge

    Research · 98 comments

    With QNX now firmly roadmapped at RIM and Android spreading among vendors like a virus, I wanted to point out that these operating systems share one ancestor: Unix.

    A technical triumph

    Technically Linux, which underlies Android, among others, is walled off from Unix from an IP point of view, but the philosophical and architectural lineage goes back to 1969's Unix. It was an amazingly well thought-out operating system which has stood the test of time mostly due to its modular architecture. It was not always clear that Unix would make it this far, and in many ways it was written off.

    There is some poetic justice in its comeback. Unix could have become a default for desktop computers. When Windows emerged from the shadow of DOS, Microsoft had the option to base NT on a flavor of Unix. But Bill Gates, no doubt motivated by license fee considerations, hired a group of developers from Digital Equipment Corporation and many elements of the NT design reflect earlier DEC experience with VMS and RSX-11. Microsoft went with that new architecture rather than Unix and that code lives on even in the current Windows 7.

    So Unix missed a chance to become the core of the desktop experience throughout the 1990's. It was relegated to the perilous high end: Sun workstations, servers and supercomputers. It seemed to be at a dead end. Fortunately, in stepped open source. Linux picked up the pieces and forged ahead to become a serious server operating system but never got beyond a toehold in the desktop.

    The death of Unix(tm) was also forestalled because of the efforts of others. Sun, IBM and even a startup called NeXT kept development alive. When NeXT was acquired by Apple, OS X was born and in 2000 Unix was once again on the desktop.

    Meanwhile, the Linux kernel also became device friendly and it was embedded into an increasing number of vertical applications while powering most of the new web servers that fed the dot com era.

    Now we've entered a new decade of devices where Unix(-like) operating systems will, on a CPU basis, probably out-install Windows. Not only is iOS based on Unix, but Android and MeeGo and even Bada are based on Linux as are QNX and WebOS. Google, Apple, HP, RIM, Samsung and Nokia are all now betting heavily on Unix or Unix-like implementations. The success is so overwhelming that there are really only two hold-outs: Microsoft and the rapidly depreciating Symbian.

    Value Chain Evolution

    There is more to this than a sentimental technology riches to rags to riches story. The history of kernel adoption is evidence of the evolution of value chains and the tension between modular and integrated business architectures. It also supports a hypothesis of why Microsoft could not respond to a tectonic shift of power.

    As a kernel, Unix was modular which allowed it to scale both down to devices and up to mainframes. It could conform to the applications above it (like being a server or being an embedded controller) and did so far more readily than Windows. In fact, Windows could not conform to applications outside its core PC and server domain.

    For Unix, the point of modularity was reached early in the 1990's and, through the Linux implementation, it allowed the lowest layers of the software to become commoditized (and free). This commodity status was actually what Microsoft tried to avoid by integrating Windows with the layers above it. This was a conscious and deliberate decision which also led to trouble with anti-trust regulators. The decision seemed to have paid off. Microsoft won.

    However, the very strategy which Microsoft used to maintain a monopoly caused its rigidity of response to a new, post-PC market. Unix fit right in with the new shift in the basis of competition: toward more personal, portable and conformable computing. Windows did not. Microsoft had to build a completely new OS to deal with devices (Windows CE has little if any shared code with Windows NT et. al.). The dual OS strategy continues to hobble Microsoft as each is stretched into new dimensions: the desktop Windows being dragged into the high end and into tablets while the device Windows is re-written to accommodate new input methods.

    The modular Unix just keeps conforming to new applications. It helps that it's open source but the open sourcing is a result of the modularity not the cause for it. So far, it looks like there is no stopping the revenge of Unix. It's been a long journey for Unix and I, for one, am cheering the comeback.

  10. WebOS: HP, and HP Only. QNX: RIM and RIM Only

    Research · 14 comments

    WebOS: HP, and HP Only.

    With the launch of RIM's tablet computer based on QNX and HP's confirmation that WebOS will not be licensed, we have

    • Apple the largest tablet and music player company,
    • HP the largest PC company,
    • RIM the largest smartphone company in the US, and
    • Nokia largest smartphone company in the world

    avoiding Android.

    These are the companies which today are profitable and enjoy large market shares. Why did they choose integrated (aka "closed") software with their hardware vs. the modular (aka "open") approach offered by Google and Microsoft?

    See also: asymco | Android’s Pursuit of the Biggest Losers