Asymco

Asymmetric Intelligence

hardware

  1. Where is the monetization? Follow the compute

    Office Hours Research · 3 comments

    An Office Hours question asked by Roger S., June 9, 2026.

    Q: Beyond selling more capable hardware — phones, Macs, iPads — is there real monetization in all of this AI?

    Absolutely. They gave us an architecture: it’s about intent, about orchestration, about routing a request through multiple models and input types, and then deciding whether it goes through an app or back to Siri. Where’s the money? My answer is: follow the compute.

    If this works on-device, the user is happy buying the device, with the memory it needs, and Apple bundles all of that into the purchase price. Developers still sell their apps, but they’re not selling extra compute. But if a result requires heavy computation in the cloud, through an app, then trace it: who sends you the bill? That invoice comes from somewhere. If it’s a developer or a model supplier, it isn’t free — they’ll ask you to subscribe to get the answer, priced as a fixed fee or variable. Apple gets its usual commission, thirty percent or fifteen, somewhere in between.ssss

    If Siri depends on services that don’t go through an app, then Siri charges back through iCloud for the compute. So all they’ve really done is take the exact same business model — Services with subscriptions — and either fold compute into existing subscriptions or add new ones. Apple gets the same distribution commission it always has. Nothing changes. In fact, the absence of any commentary from Apple about new economics is, to me, a tacit acknowledgment that nothing different is needed.

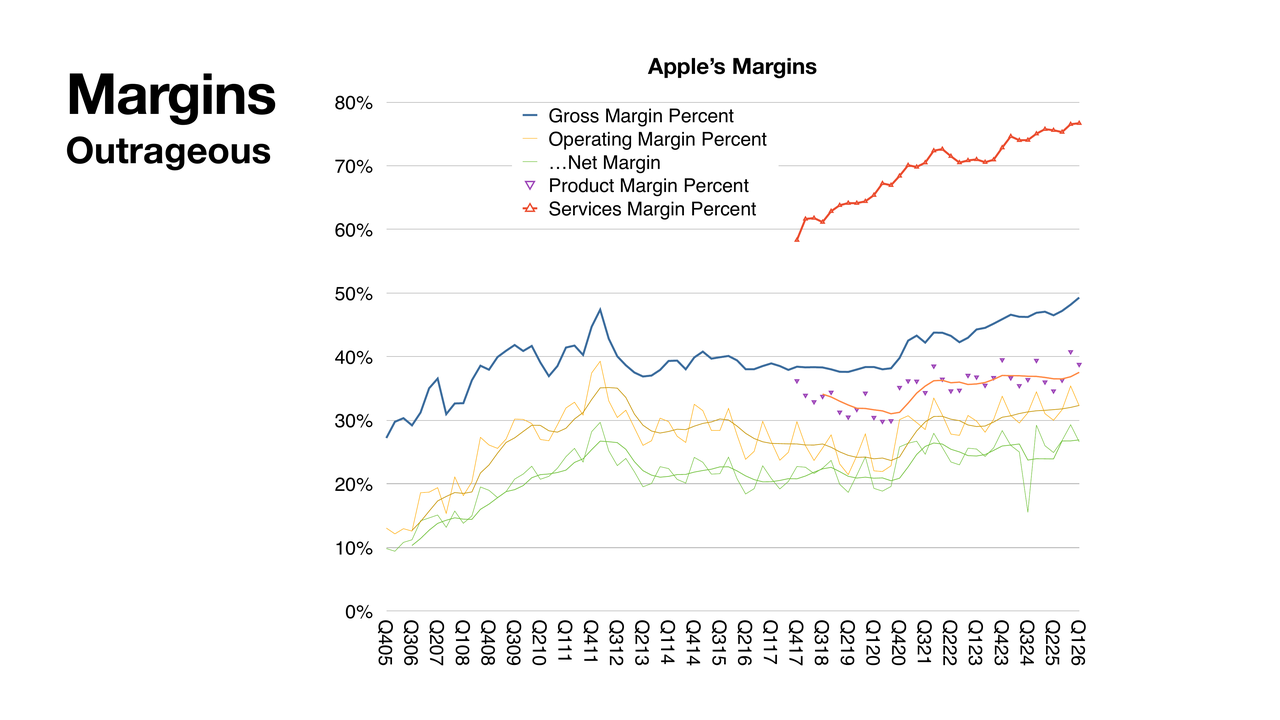
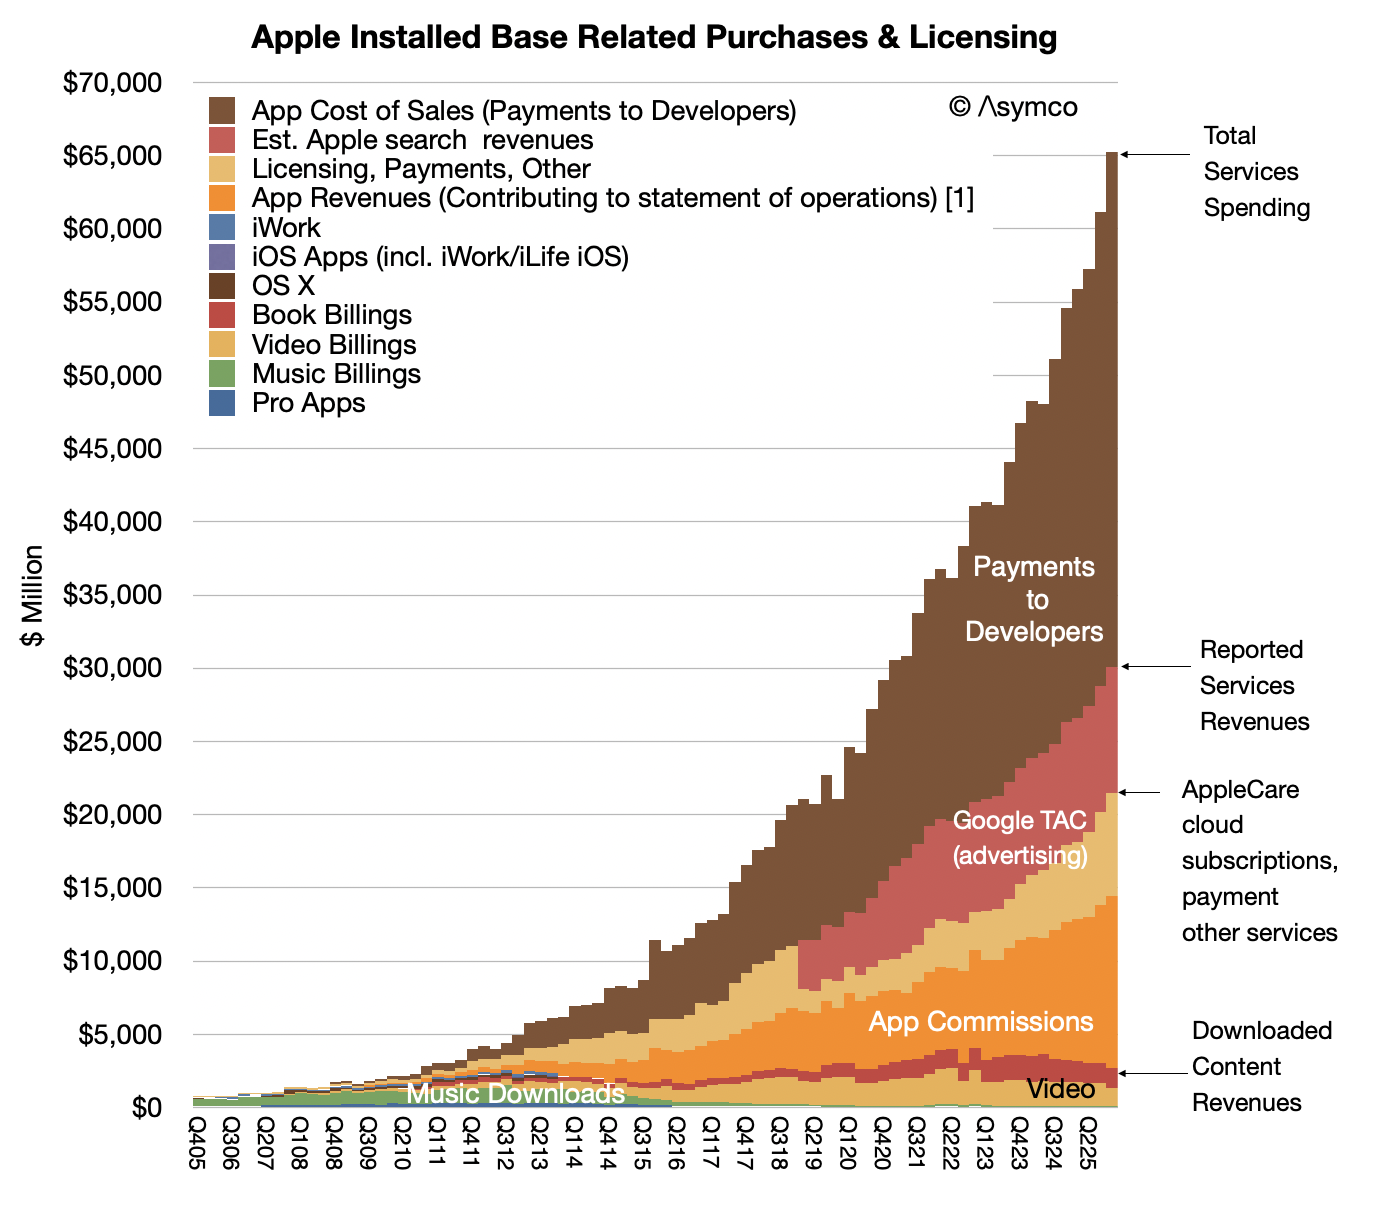
    That means the App Store, and if anything economically interesting happens, you’ll see another kink in its trajectory — the way we saw a kink when subscriptions became dominant. To users, it’s invisible. Maybe the monthly services bill rises ten percent; maybe they add a couple of subscriptions and drop one. It all reflects in Services, at a 72%+ gross margin, with a hardware uptick alongside. I reckon it’s a ten-year cycle before half of the Apple base are AI active daily, paying something for it. Developers will just see more of the same, only bigger.


    Editor’s Note: This was one of the questions asked by participants in Asymco’s June 2026 Office Hours live Q&A session, open to Asymco One subscribers.


    Subscribe to Asymco One for more in-depth analysis and commentary like this.

  2. WWDC Special: Asymco Office Hours - June 2026 - Live Q&A with Horace Dediu: Recording & Transcript

    Office Hours

    Recording and transcript of the June 9, 2026 Asymco One Office Hours, recorded the day after Apple's WWDC 2026 keynote. Horace Dediu shares his impressions of the event and takes questions from Asymco One subscribers.

    Recording

    Subscribe to Asymco One to listen to the recording and read the transcript.

    Transcript

    Sign up and latest updates at asymco.com/live.

  3. Apple Intelligence: Show me the money!

    Research · 3 comments

    AI sales are booming. AI FCF not so much. So what new cash flows does Apple Intelligence unlock?

    Portrait of Charles Babbage (c. 1820)

    Apple's release of a new framework for AI at WWDC26, centered mainly on new layers in the device/OS which process intent to either on-device or world models and couple it to experiences which are system-wide, including apps.

    This is how the data and the inferences flow but what about the cash?

    I am writing without a full picture in mind, and perhaps one does not yet exist, but my assumption for at least three years has been that the value of AI will split between the creation of (frontier) models and their distribution. Apple chose to focus on local models, license or partner for frontiers and stitch together the means for distributing both.

    That is until on-device will be good enough to perhaps bring all models in-house.

    But distribution is always where it's at. So how do the new announcements affect this?

    Let's follow the money. The costs of inference will be partly borne by Apple for what they keep in private cloud but mainly by apps and hence subscriptions which will include marginally increasing compute costs. This will lead to increasing or new subscription pricing and the usual commissions for App Store distribution.

    The fact that this is all implied rather than explicitly stated should be seen as a tacit acknowledgment that the Services business will not change much, if at all. It will perhaps benefit from an uplift if the new AI-powered apps are very popular.[1] This new AI might create more demand or expand existing demand. That will all depend on the innovations developers come up with.

    But the elephant in the monetization conference room is hardware. AI demands a huge step-function increase in computing resources--both compute and storage and integrated memory. The minimum requirements are already leaving two to three year old hardware behind.[2]

    Again, if AI is compelling enough, users will need to upgrade. Not just their phones but the Macs, iPads, Vision Pros, Watches, probably AirPods too. Then there is Home which is seeing foreshadows of a significant AI enabled upgrade. This means HomePods but also probably new devices altogether. Rumors of spectacles coming are par for the course. Health will also be revolutionized.

    This idea that AI is monetized through hardware should hardly be a surprise…

    1. Services has a lot of headroom for growth as non-consumption is still pretty competitive
    2. But don't worry, adoption curves being what they are, and regional/political obstructionism will imply a decade or more before perhaps half the install base is using Apple Intelligence with some frequency.
  4. Q4 PC shipments are expected to fall 20% year-over-year, 11.3% for the full year

    Nota Bene · 7 comments

    If it wasn't for the MacBook Neo the fall would have been much worse.

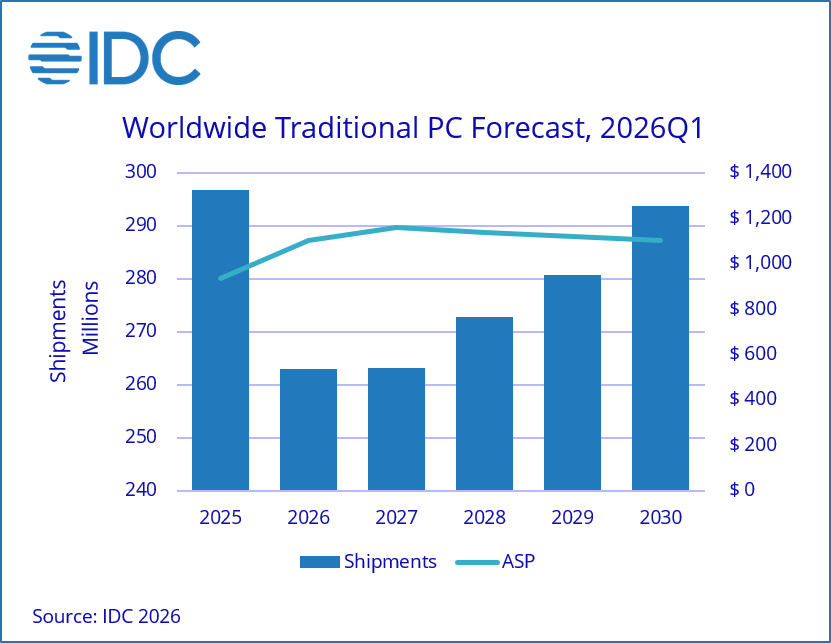
    IDC now forecasts global PC shipments will decline 11.3% for the full year, with conditions worsening progressively through Q4, when shipments are expected to fall 20% year-over-year.

    Pull-forward demand masked the problem, temporarily

    The first quarter of 2026 offered a deceptively encouraging signal, with shipments growing 3% versus the same period last year. But that strength was largely borrowed from the future. Buyers, both consumer and commercial, accelerated purchases ahead of anticipated price hikes and product availability constraints.

    Pull-forward demand masked the problem, temporarily

    “The anticipation of rising prices and of limited availability of some system configurations due to memory and other component shortages has led some end-users to make purchases earlier than anticipated,” said Jean Philippe Bouchard, Vice President of Devices and Consumers at IDC. “We’re not seeing any relief to the memory shortage situation before the end of 2027, which means prices will continue to rise and PC manufacturers will struggle to maintain full product portfolios for the foreseeable future.”

    One notable wildcard is Apple’s MacBook Neo, which has driven stronger-than-expected notebook demand and prompted IDC to revise its notebook forecast upward.

    Source: IDC

    NB: The problem is a memory shortage: PC manufacturers are struggling to maintain product portfolios.

    “The introduction of the MacBook Neo is putting real pressure on the entire PC ecosystem,” said Jitesh Ubrani, research manager for IDC’s Consumer Devices Trackers. “We expect vendors to respond with a combination of new silicon, a more efficient OS from Microsoft, and aggressive promotional pricing.”

    “The competitive pressure from the Neo is providing a partial offset to broader price increases, keeping some low-cost notebook options alive. But the overall trajectory for average selling prices (ASPs) is firmly upward. IDC forecasts ASP growth of 17% in 2026, and even as memory capacity expands over the next two years, pricing is unlikely to return to 2025 levels,” Ubrani added.

    As the graph shows, IDC forecasts no recovery in volumes until after 2030. This is a multi-year opportunity for Apple and may reset market share dynamics permanently.

  5. iPhone Share of US Big 3 Carriers reaches 75%, 77% with Verizon

    Nota Bene · 2 comments

    Android down 14.4%. Small players getting crushed.

    Apple’s quarter one (Q1) 2026 iPhone sales volume in the US was up 1.3% year-over-year (YoY), outperforming the country’s overall smartphone market.

    That market declined 5.7% YoY, according to Counterpoint’s US Monthly Smartphone Channel Share Tracker. Apple’s share of volume grew by 4% YoY, as Android device sales declined 14.4% YoY.

    On the impact of the delayed launch,Graham said, “The premium smartphone space in the US is highly consolidated compared to some other markets, with Apple, Google, Samsung and, to some extent, Motorola comprising the vast majority of sales here. When one brand delays a flagship launch, it opens a window of opportunity to fill that vacuum. Apple did just that.”

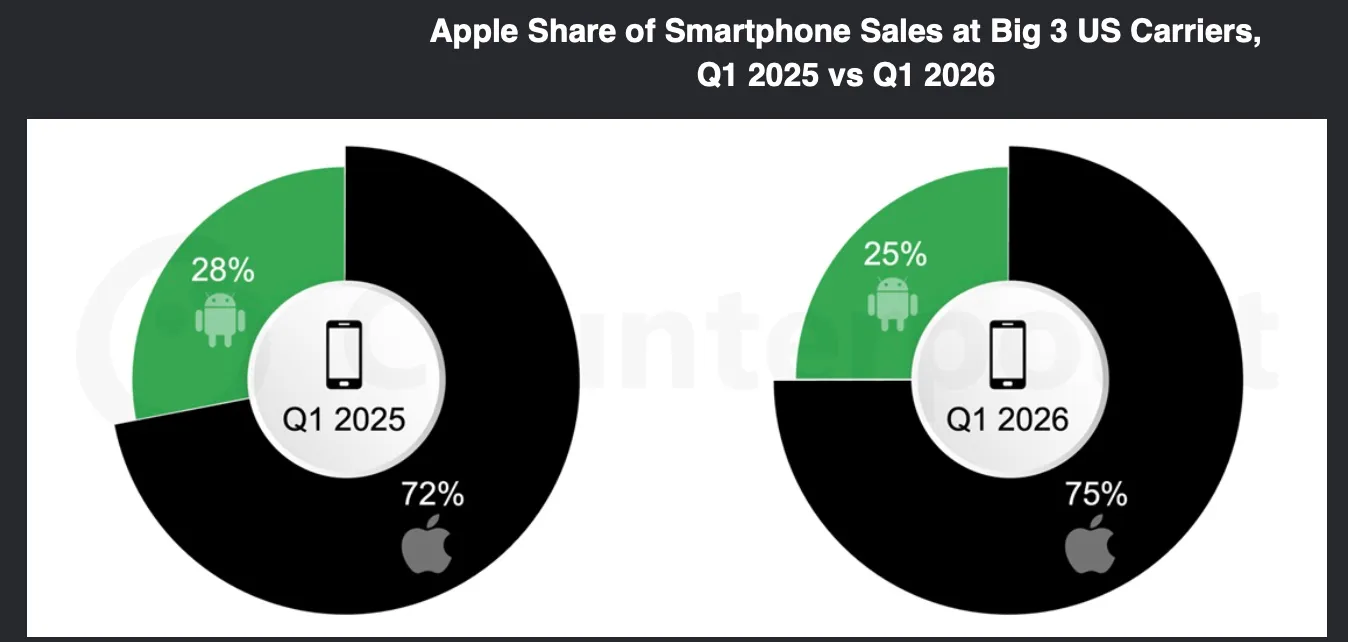
    Apple grew its market share in each of the Big 3 US carriers. Its share grew the most at Verizon to 77% in Q1 2026.

    “If Apple can avoid significant price increases and continue to outpace its peers in promotional dollars, it will be tough for Android manufacturers to keep up in the year ahead, said Klaehne.

    Source: Counterpoint Research

    NB: What are the dynamics of the US market? The split between Apple and the rest of the market seems to be starker than ever. It's ask if there is a K shaped market emerging…

  6. Is Apple an Enterprise Gatekeeper?

    Research · 1 comment

    Asked by David Emery

    Q: What's the potential legal regulatory risk to the Apple enterprise combining both products and services? You can make a case that services growth over top of the monopoly in hardware is an illegal monopoly. That seems to be the way regulators are going. And forcing a split between services and products could definitely damage Apple as a whole.

    Sure. So let me take a European — not just point of view, but sort of a language. The language is that of being a gatekeeper, and a gatekeeper has a responsibility not to exclude competitors, because if you're big enough as a gatekeeper, you effectively are a platform for millions and millions. And so it matters how many. It's not just a gatekeeper per se, but a gatekeeper with a sufficient audience. And the logic there is that you can't bundle your own services and therefore exclude — especially by putting yours as a default, then the others have a hard time competing.

    And that is an antitrust logic. May or may not agree with it. I certainly don't, but I'd say it's a clear argument when seen through this gatekeeping phrase.

    Now, the difference — what you're asking is in business. Well, that doesn't fall under the same restriction. Usually, because antitrust is about consumer protections. There's a lot of businesses which get into complex deals that are tolerated because it doesn't affect the mass population. Now, of course, collusion and other things are still illegal. But I think you get a little bit more of a pass if you're solving the problem for businesses. There's one reason why Microsoft got away with what they were doing for so many decades. It's only when, in the late 90s, consumer personal computing became so prominent that there arose an antitrust argument about bundling everything into the operating system that got them into trouble.

    So I think Apple's bundling hardware and services for business users is probably going to be okay for a while. I would just say it's a question of quantity rather than the logic at this moment, so I wouldn't worry about it yet.

    But there are ways around it. Even if you do want to worry about it, there are ways around it which basically deal with providing provisions for alternatives, and that's what Apple's done to comply over and over again. Bending over backwards, providing alternatives, providing options. But then nobody uses those options, because they're far more complicated.

    The law is futile on this, because it doesn't take into consideration user satisfaction. It doesn't take into consideration the ease of things as opposed to the existence of things. It's nice to have options, but if it's complicated and annoying and expensive, you don't use the options. And so they have a very crude mechanism to try to enforce some utopian view of economic benefit. It just tends to create unnecessary penalties for consumers and producers, and as a result, they're just tripping over themselves. It just leads to all kinds of dysfunction.

    Quality is what Apple's always said — quality, experience, ease of use. And bureaucracies are not oriented around either quality, efficiency, or delighting anything. It's incompatible with all of the work people do at Apple. And so it ends up being a net negative, overall, in my opinion.

    This was one of the questions asked by the participants in Asymco's May 2026 Office Hours live Q&A sessions, open to Asymco One subscribers.

    See also: May 2026 Office Hours

  7. Apple's R&D investments top 10% of sales as AI race creates 'sense of urgency'

    Nota Bene · 3 comments

    Don't confuse R&D with CapEx

    Apple’s R&D spending hit 10.3% of revenue in the March quarter, as the the tech giant ramps up investments in artificial intelligence.

    The increase puts Apple closer to the rest of megacap tech on R&D, though the iPhone maker is still taking a very different approach when it comes to capital expenditures, according to CNBC. R&D spending was up from 7.6% in the prior period and 9% in the same quarter a year earlier. While sales jumped 17%, the fastest rate of growth for any quarter since 2021, R&D climbed twice as quickly, increasing almost 34% from a year prior, according to CNBC.

    “That’s a sign that Apple is seeing a sense of urgency around new AI products,” said Gene Munster, managing partner at Deepwater Asset Management.”

    Horace Dediu, founder of Asymco, agreed that a major question is where all that spending is going. Much of the increase, he said, is likely tied to talent, teams and experiments in training and modeling, rather than the kind of large-scale data center deployment underway at the hyperscalers. But he also said Apple is pushing across hardware, investing in silicon, optics, batteries, materials, sensors and smaller form factors.”

    "AI is an obvious candidate, but R&D is not capex," Dediu said.

    Excerpt From Apple's R&D investments top 10% of sales as AI race creates 'sense of urgency' by MacKenzie Sigalos, Jennifer Elias, CNBC

    Source: CNBC

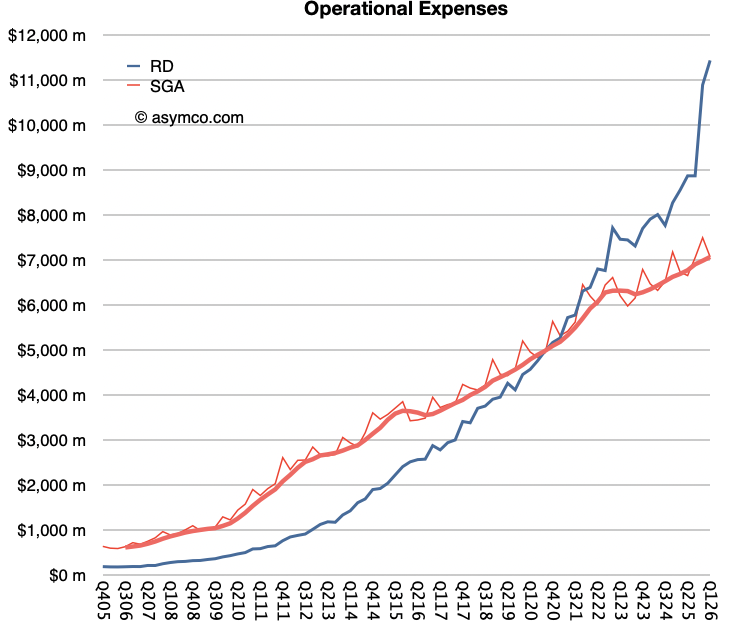
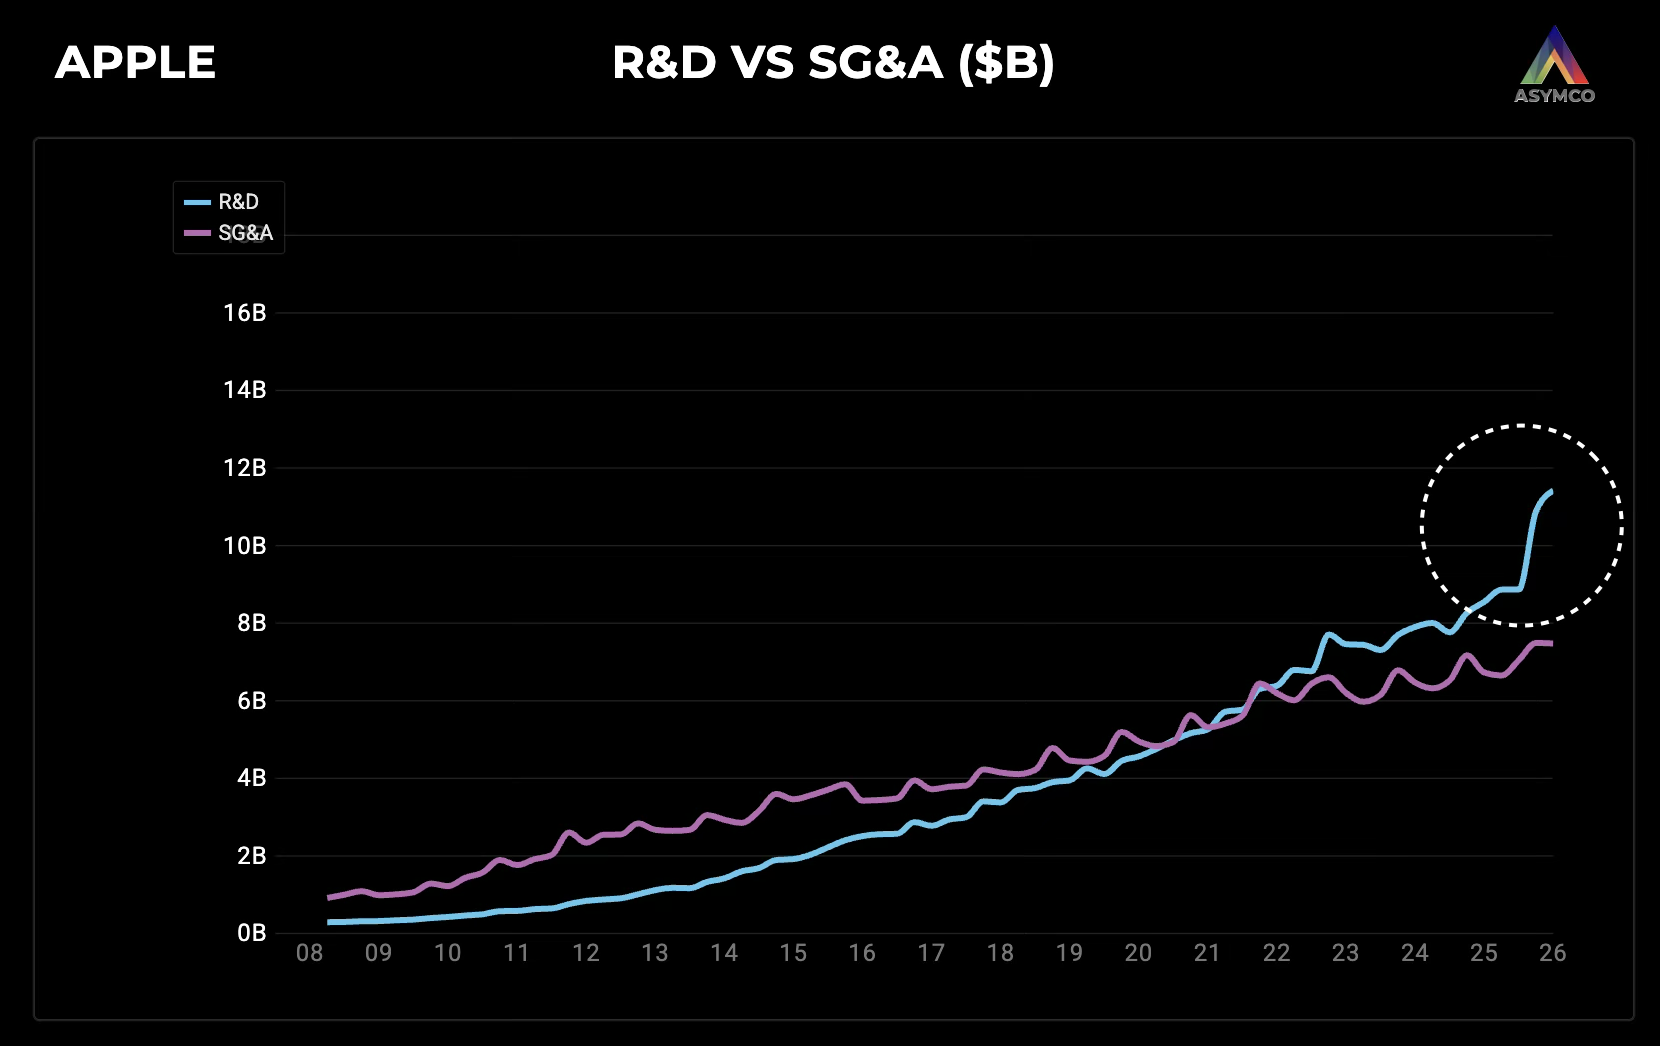
    NB: Apple has been increasing its R&D spending from around 2% to 9% of sales on a 4-trailing quarter basis. It has overtaken SG&A which has remained around 7% since 2011.

  8. Why is Apple's R&D run rate suddenly $40 billion/yr.?

    Research · 1 comment

    Office Hours question asked by Frederich H. on May 1, 2026.

    Q: Any thoughts on the breakdown of R&D, with that big jump?

    It's hard to tell. I do think they're buying — that does include some hardware. A lot of hardware. I think they're building quite a bit of capacity in order to implement their versions of AI. They're not for deployment, but they're for testing and experimenting. They're hiring people as well, obviously that's included. But I do think it used to be they bought equipment for testing — I don't know, radio frequencies, and testing the iPhones, and semiconductors, and testing a lot of things like that. But I do think probably there's a lot more spending now on the stuff that feeds AI. It's not on the level that a hyperscaler's doing, because they're building it for scale, and Apple's maybe building it for testing.

    We're talking about here, look, $11 billion in R&D, that's in one quarter. So that goes out to about $40 billion a year.

    Mostly, I think this is people, but there is some equipment involved. It's just maybe different ways of capitalizing it, because capital equipment is a complex story.

    It seems like a big jump, but it's only $2 billion more compared to the prior period. It's recurring though. And the reason that this stays steady and keeps growing is because people are on the payroll. And so if there's more and more people, that's paid every period — the reason, by the way, you see SG&A being seasonal is because there's temporary people in the stores. That involves people who are hired for the holidays in the Apple stores. So that's where you see some less than steady. But engineering people are more steady. But if there's a spike, there might be something going on where there was some equipment involved.

    See also R&D Acceleration section of Apple 2026 FQ2 Presentation.

    —
    Editor's Note: This is a lightly-edited revision of a question asked by participants in Asymco's May 2026 Office Hours live Q&A sessions, open to Asymco One subscribers.

  9. Asymco One: Mobile Computing

    Research · 2 comments

    As you know, as we crossed into 2001, the great crash occurred.

    Ben Thompson • 25:05
    Yep. And suddenly a job offer from a big phone company sounds pretty great.

    Horace Dediu • 25:09
    Yeah, but the crash occurred and it impacted my startup because I couldn't raise money anymore. And that's why I'm throwing in the towel. I'll take this idea to Nokia and build it inside of this company. So for the first year, I worked out of the U.S. and then they invited me to come to Finland. And I fell in love with it, not to mention finding someone to fall in love with. Yeah, I'm still here.

    So we created an internal venture called media distribution. And it struggled for a couple of years. We partnered with a publishing company here in Finland that is the biggest newspaper and magazine company. And we worked with them. 9-11 happened. We worked with them throughout that period to test this idea of distributing content on phones. That's how I met my wife. She was working for the publishing firm. Remember when Apple News launched? I forget how many years ago it was already. It was five, six years ago. [My wife] texted me during the keynote. She goes, "you realize that's what we were working on together in 2001?"

    It was called Project Melissa. Project Melissa was this idea of Apple News today. And that was [our project] 20 years earlier. That just goes to show you the story of my life. I was doing search 10 years before Google existed. I was doing e-books 10 years before Amazon launched the Kindle. I was doing smartphones and media distribution on smartphones 20 years before Apple showed how it's done.

    So my problem has been that I see things happening or see where things are going, but way too early. And that's why one of the theses I have over time is the idea that the difference between a futurist and a billionaire is knowing when one thing happens. So it's not about knowing what's going to happen. A lot of people are very good at that.

    Ben Thompson • 27:31
    Including Nokia, to your point.

    Horace Dediu • 27:33
    Nokia, science fiction writers, Elon Musk, a lot of people predict this. But getting the timing right is where the money is made. And so that was one of those lessons I learned.

    Ben Thompson • 27:45
    Well, when you talk about the publishing and Nokia and the reading and all those sorts of things, what it makes me think of is when the iPhone comes along in 2007, And I'm very curious to get your perspective on what that was like inside Nokia when the iPhone launches.

    Horace Dediu • 27:59
    I'll tell you exactly.

    Ben Thompson • 28:00
    But before I get there, but to this publishing point specifically, the key bit was the Internet was permissionless in terms of producing content. Like, it's great that you met your wife, but the fact that you needed to be in a situation where you could meet your wife was actually the reason why it wasn't going to happen. Because if you have to make a deal to do everything, it's just never going to get there. Whereas if you can just surf the Internet, the real Internet, and no one needs to do anything to adapt to it, suddenly you get it all for free. And then you get the virtual cycle going where they're making stuff for you. And that was sort of the, that's the timing bit is like the, the external structure around what you're doing.

    Horace Dediu • 28:41
    Yeah, it's, it's, it's complex and it's multi-causal and you're right. It's multiple, the reasons why things happen the way they are. And it's just not foreseeable. The internet was, and by the way, the thing that really caused the project to fail and be abandoned--this media distribution side note-- it was the fixation on DRM.

    DRM actually killed a lot of great businesses with content ideas back in the day, whether it was music or video or textual. It was people just obsessed about protecting it before they obsessed about distributing it and making it great. And this is why when iTunes came along, even though there were some circumstances there with being on a Mac and not on the PC, that the publishers finally said, why don't we go ahead with this?

    So long story there. But as far as what Nokia was doing, after four years of doing this startup inside of Nokia that did not work out, I got into the job of strategy analysis and competitive analysis. So they asked me to do Microsoft.

    Microsoft was the biggest worry for everyone because they had intentions of being in the phone business. They made no secret about it. They had prototypes. They were working with competitors to Nokia. [Intending to] give them the operating system so that [for instance] Samsung running Microsoft [Mobile]. That was the effort.

    They were pushing on all fronts. Nokia was holding out and saying "we've got our own operating system" and so on. So they gave me this job because every other competitor was hardware. All the analysts were covering hardware. I was the only guy who was covering a software company.

    And in doing that, I was also sort of nibbling at Apple a little bit because the iPod had come out. The iPod was doing amazing, but it wasn't a phone product. And I was kind of looking at it a little bit.

    Now Christensen comes back in the picture, because his book had taken off. He had already written the second book, which is The Innovator Solution. And I was like, hang on a second, a lot of stuff that I read in the book, and I remember back from my days at school, applies to Apple here because they're doing a lot of interesting things with being disruptive as the case may be.

    Nokia itself had been disruptive in its early years. But I'm focused on Microsoft. And my point was that we can fight this battle and win, but we got to be very careful. And there's a lot of twists and turns there, but I took it upon myself also to understand what's going to happen with this media product from Apple.

    And then I began to write a few internal notes because nobody was covering Apple. This is interesting and important. Imagine you have a team of a dozen analysts, you could put them on multiple jobs, assign people to multiple problems. No one thought that Apple was a problem to be looked at, even part time. No, there was nothing interesting about it.

    And part of that had to do with the fact that [Nokia perceived that Apple had been] one foot in the grave already in the 90s. And now they were this little toy media company. They didn't really have scale. Phones were on the orders of billions of users already. And this iPod was in the tens of millions, maybe a hundred million. So it was orders of magnitude. There was no real worry there.

    But I was really annoyed at this thing. And I started building a model. I remember distinctly opening a spreadsheet, looking at research reports and thinking to myself, let's look at the history of the iPod, how it's growing. And I started to match that to the Razr, which was the most viral product at the time, the Motorola Razr.

    Even Nokia was jealous about this thing. At that time, [Motorola] had cumulative sales of 50 million, which was considered way too scary. (And BlackBerry was another one, by the way.) So I'm doing this and I'm like, hang on a second, what if they do a phone and it's a combination of the Razr and the iPod, could that resonate? And I just put it out there. I said, it's possible. And there was a rumor of the iPhone coming out.

    Ben Thompson • 33:31
    So Apple did do a Motorola Razr with iTunes functionality. Did that actually end up, because that was a flop. And did that actually make people not as like more relaxed?

    Horace Dediu • 33:46
    Because we knew that it didn't run an operating system. It didn't have a developer API, there was nothing, no hooks in it. It was just an appliance. And as such, it was like a feature phone. And that was not interesting. We had been talking and pounding the table on smartphones already since 2001. Remember, when I joined, we had a communicator. We had Symbian, Series 60. We had the interfaces. We had all picture phones, music, etc.

    Ben Thompson • 34:20
    I was a user as well.

    Horace Dediu • 34:22
    And I had done the numbers, and by 2005, people were burned out on smartphones. Because the projection was like this, but it was more like this. It wasn't growing as much as you thought it would. And so a lot of people said, especially the top management was like, "you guys are very enthusiastic about the software stuff, but it's just not working out. We're going to double down on hardware."

    So there was a lot of burnout. So, but I kept looking at the phone at Apple and I suggested, hey, what if this thing scaled anyway? Like I said "what if they could sell as many as 50 million?" That was my provocation. And people were like, dude... I was essentially taken aside and told, tone it down. First of all, you're not doing yourself any favors by being so provocative. You're just going to lose credibility. My boss, who's a great guy he just took me aside and said, just don't do that. You know, it's bad for you.

    Ben Thompson • 35:22
    And this is like 2005, 2006, around then?

    Horace Dediu • 35:25
    Well, already 2006, because the iPhone was rumored. It wasn't out, but it was like, if you're going to have iPod success and you're going to do this crap phone with Motorola, you're probably thinking, maybe they're going to do something interesting beyond that, because we knew they could, in theory, do something.

    We didn't see the touch interface, but we saw maybe like a scroll wheel or something. You know, Tony Fadell was running the thing. So, bottom line is, when it finally came out, it was January 2007. It came out and was not for sale, but it was on stage. And I was so excited. And I said, this is unbelievable.

    I remember running into the office the next day. Usually you socialize at lunch hour, sitting in the cafeteria, talking to your friends and asking them what do they think about this? And most people just said, oh, it doesn't look that interesting. aspects of it were copied. There were copies from here and there. There are other people that do touch. You know, a stylus has been around for a long time with BlackBerry also doing amazing things with keyboard and so on and so on.

    So there was a lot of cynicism and sort of not really interesting. I said, man, it's running OS X, it was running a full operating system. And I said, this is going to get developers working on it. But again, the other thing, the other head fake from Apple was that Steve Jobs said they're not going to put any apps on this thing unless Apple write them. I was anticipating far more than even was being talked about. And for that reason, it was just super frustrating. Anyway, I left in 2009. But by then, Nokia were still not following Apple.

    Ben Thompson • 37:13
    How is that possible? Like even two years on, this device is out there.

    Horace Dediu • 37:19
    Because it still didn't have distribution. And this is the thing that consumed everyone following the iPhone in the beginning. It's like they had one launch partner. It was initially Cingular, became AT&T. Don't forget that the old AT&T had nothing to do with this AT&T. It was just a rebrand of Cingular, which was a crappy, small, not very small, it was maybe second tier [operator.]

    Ben Thompson • 37:47
    Verizon didn't want to do it. Apple did this again and again. Verizon was number one.

    Horace Dediu • 37:50
    Verizon was number one. Absolutely. But Verizon was in CDMA. But the thing is that it was a crappy network and they didn't have a lot of points to sale. They didn't have distribution. and everybody said this, you need 500 network operators to saturate the global market, right?

    And how fast are you going to be able to obtain distribution was the question. And so they're so cantankerous. You know, Apple is known as being "my way or the highway."

    Verizon said no for years. Nokia was like, this is not going to fly. These guys are, if anything, they're naive. Don't forget, by the way, there's a separate story on how BlackBerry dealt with the iPhone. There's a movie about it, by the way. Everybody should watch it. But basically, everyone had the similar responses: that this is not kosher.

    This is not the way things are done in this business. It's all about relationships with operators. It's about getting shelf space. It's about getting salesmen in the store who are bribed effectively with a commission to tell you what to buy, effectively yank the phone out of your hands and give you another one. So this was a very dirty business at the street level.

    Ben Thompson • 39:19
    So do you know what was the first what was the first article of mine that I think you ever linked to? It was about precisely. No, no, you don't need to know. I know because it was very formative to me. That's what I'm going to tell you. It was basically about talking about this was how distribution worked.

    And what Apple changed about the whole thing was that customers actually switched networks for the iPhone. And it was doing just sort of a traditional sort of business school analysis of and pointing out the power shifted to instead of distribution to the buyers. Basically, what I ended up writing about for 13 years now is demand mattering more than sort of the supply bit. But it was the exact same thing. That's why you linked to it. You are you are already on board with it.

    Horace Dediu • 40:04
    But it was also the thing that resonated for me personally. Not that I knew something about the phone. Mostly I knew how big it could get. I knew that there were billions of people, many more billions than used PCs, which was by far the most dominant influence in technology.

    Most people oriented themselves, like even Gruber and others who were Mac first and then all these accessories. But I knew the phone would be a couple of zeros more. That was number one.

    Number two, there was this problem of the incumbency, which were all the phone makers, who were so far from understanding what the software dynamics of platforms were. By the way, platform theory was developed by Microsoft. They pretty much invented the whole idea.
  10. Monday Notes: Neo still sinking in

    Nota Bene · 5 comments

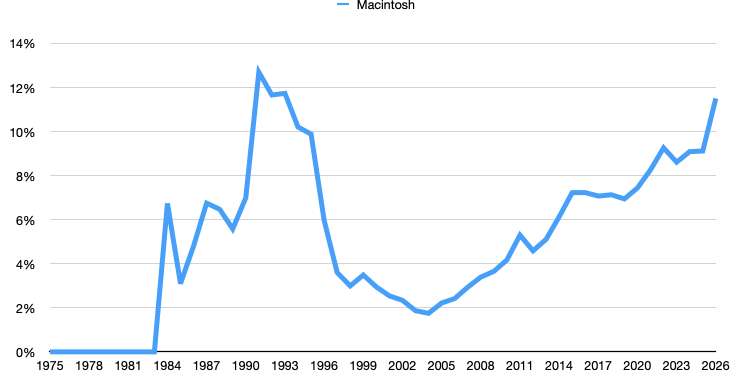
    260 million Mac users? Huge room for growth.

    It’s a massive untapped opportunity for Apple, whose Mac installed base of 260 million units lags far behind the iPhone installed base of 1.5 billion units. Mohan believes the total addressable market for the Neo could be $32 billion for 2026. If Apple can capture just 10% of that market for budget laptops, and do so with a 19% operating margin, the company can boost earnings per share by an incremental 3 cents, according to Mohan.

    “We see Neo driving meaningful adoption for first-time Mac owners with a distinct customer base relative to the Air and Pro models,” Mohan wrote.

    The Neo will dramatically disrupt competitors in the market for budget personal computers, Seaport analyst Jay Goldberg wrote in a Monday note, as the $500 to $700 price tier is one of the most profitable segments for PC makers. Both Mohan and Goldberg have a buy rating and $320 price target on Apple’s stock, implying over 20% of upside from current levels.
    Read: Apple turns 50. Here’s how it can shake its midlife crisis.

    As Apple expands into the budget computer market, the company is also looking to seize share from its smartphone competitors during a period of memory crunch. Artificial-intelligence infrastructure is gobbling up so much memory that many suppliers have sold out their capacity through at least next year. That has an impact on makers of consumer hardware that also count memory as a key component.

    Apple has been paying a premium to buy up memory chips in what Goldberg believes is a “is part of a deliberate strategy for the company to tighten conditions for its competitors.”
    This strategy forces competitors to either raise prices for customers or reduce the memory content in their products, according to Goldberg. Meanwhile, he believes Apple intends to maintain both the memory content and pricing of its phones, allowing the iPhone maker to gain share even as the overall phone market shrinks by roughly 10%.

    This strategy “will not come cheap for Apple,” Goldberg warned, noting that Apple’s product gross margin could sink to the low-30% range from the high-30% range seen a year ago.
    “That said, we think the company can make up for some of this lost ground through its share gains,” he wrote, as new Apple users are likely to subscribe to Apple’s higher-margin subscription services to offset the hardware costs.

    Mohan expressed similar sentiments, arguing that the Neo could lead to a stickier overall installed base for Apple and “increased services use over time.”

    Source: MarketWatch

    NB: Two analysts, two stories. The Neo will move the needle and the supply crunch will hamper competition…

    As I wrote before, the key metric is the number of Mac users. 260 million is a reasonable assumption. Over 350 million Macs have been sold in the last 20 years. If we assume half are new to the platform then 175 million have been added. The base in 2006 was probably in the 50 to 60 million range putting the total today at 250 million.

    It's a long way to go to 1 billion Mac users and I don't know if it will ever happen given that most will have to switch from Windows and the lock-in is strong regardless of a better and cheaper alternative being available.

    Nevertheless, a doubling of the Mac user base is certainly a worthy and achievable goal over the next decade.

  11. Asymco Bulletin 008 - Apr 12, 2026

    Bulletin

    Asymco Bulletin is a digest of all the work we have published for the week ending Apr 12, 2026.

    Research

    Can a company outlive its founder? Microsoft at 51, Apple at 50 and The Auteur Theory of Business

    Much more was said of Jobs’ departure signaling the end of Apple than of Gates’ departure signaling the end of Microsoft. And much more was celebrated of Apple 50 than Microsoft 50. Why is that?

    If you were to structure an experiment to determine the influence of processes and personalities on the outcomes of a company, you would be hard pressed to find a better pair to study. Apple and Microsoft were founded almost at the same time, due to the same enabling technologies (microprocessors) and led by two iconoclastic founders of the same age acting out of similar impulses.

    The divergences were that one concentrated on software while the other on hardware. But rather than pairing up in a match made in heaven, both tried to outmaneuver the other in order to avoid dependency. →

    Valuation in a time of AI

    Valuation in a time of AI

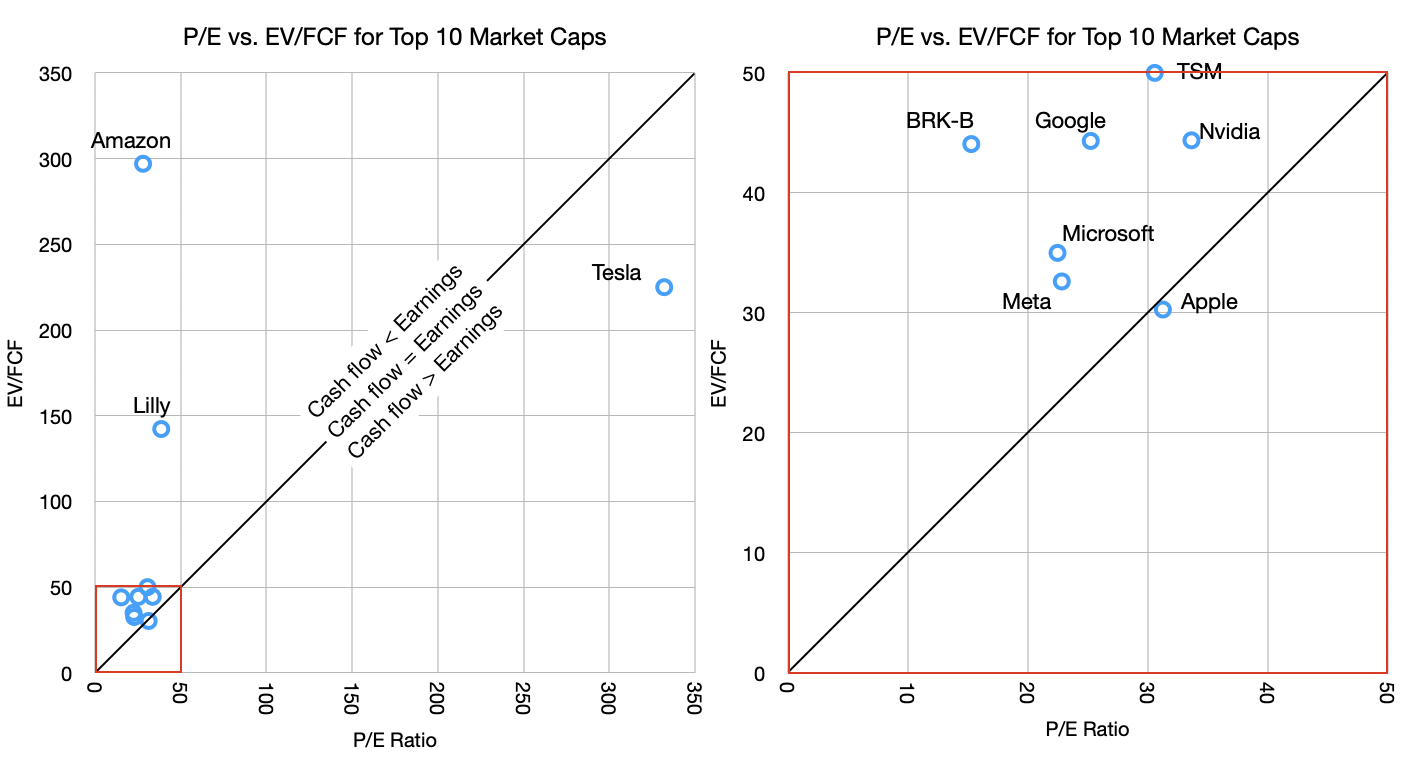
    Cash flow is a fact, earnings are an opinion and share price is a dream.

    A company’s total worth is the number of outstanding shares multiplied by their value. This product is called the market capitalization or Market Cap.

    That’s a simplification. If you want to be more accurate, you should take the Market Cap and net out cash and debt–these are not part of the future flows of cash that can benefit shareholders.

    More precisely, there is another measure called the Enterprise Value (EV) which is the total price tag of a company, representing what it would cost to buy the entire business and pay off its debts. EV = Market Cap + Total Debt + Preferred Stock + Minority Interest – Cash and Cash Equivalents.

    This is the precise and complete measure of the firm’s value but we use the shortcut of Market Cap since In most cases the Preferred stock and minority interest are negligible and if cash equals debt then the result is EV =~ Market Cap. it’s easier to calculate anyways as the shares outstanding and share price are easily available. Not so for EV. →

    What are the odds of Apple surviving?

    What are the odds of Apple surviving?

    A tale of two Apples

    What are the odds of it surviving another year, ten years, 50 years?

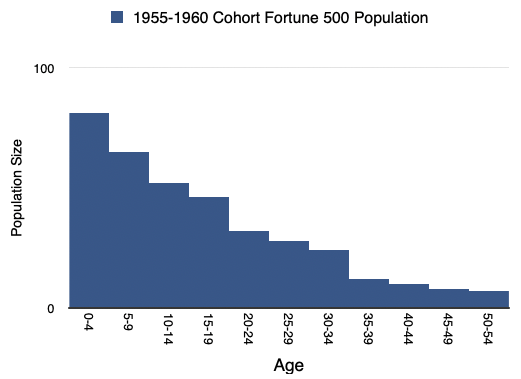
    Companies don’t last long. A recent study that analyzed thousands of European firms yielded a corporate life expectancy figure of 12.5 years. The Boston Consulting Group analyzed the entry, growth, and exit dates of 35,000 publicly listed companies and determined that one in ten of all public companies fail each year, a fourfold increase since 1965.

    As I illustrated many years ago in a talk titled “The Unfortunate 500” most companies die not long after adolescence. Of the Fortune 500 1955-1960 cohort, the 81 companies which joined the index in those years, only 7 remain there today. One third of the corporations on the 1970 Fortune 500 list were no longer in existence thirteen years later. Broadly speaking, as a population, large companies that make it to the Fortune 500 listing have life expectancy within that group of 17 years. →

    iPad at 16

    Redundant or Post-PC?

    Today marks the 16th anniversary of when Apple released the first-generation iPad.

    To many, including Alan Kay, the tablet form factor makes much more sense than the PC form factor. It’s more approachable, more intuitive and certainly smaller and more portable. As the graph shows, quickly after launch, the iPad overtook sales of the Mac.

    The problem arose that whereas the iPad was smaller, the iPhone what smaller still–so much so that users would take phones with them everywhere. At the same time, the “PC” shrank as well so that many notebook (laptop) computers became thin, light and had day-long battery life. The Mac at least became no bigger a burden to carry than an iPad.

    So the iPad was stuck in the middle between an iPhone, that did more and more, and a Mac that was very portable. At this point many said that the iPad was a dead end form factor. →

    AI as Infrastructure

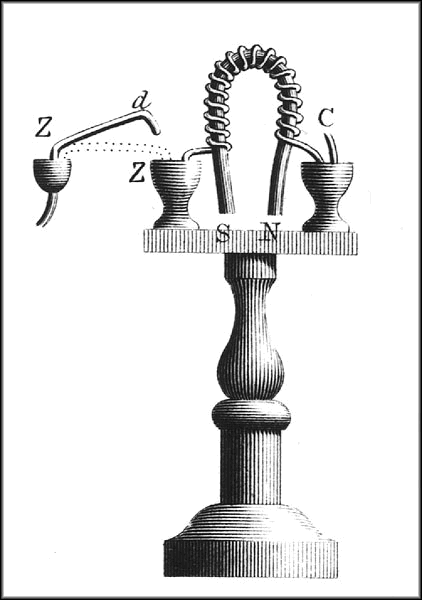
    ON September 3, 1821, 37 years after James Watt invented the concept of horsepower and started charging £5/horsepower/year for the use of his steam engine, the first demonstration of the production of a mechanical force by the interaction of an electric current and a magnetic field was given by Michael Faraday in the basement of the Royal Institution in London.

    1820 is, in many chronicles, noted as beginning of the industrial revolution. It marked the end of 50 years of war, whose conclusion unleashed pent-up demand. That demand was served by relatively free trade, guaranteed by British naval power, coupled with property rights and financial instruments which allowed inventions of the previous century to finally be harnessed for commercial gain. The steam engine is the canonical invention of the era and its implementation as a source of power for factories, shipping, rail and machinery is legend.

    Not usually noted as coincidental to this period is the electric motor. Yet not long after Faraday’s 1821 demonstration in London, the first DC electric motor capable of turning machinery was invented by William Sturgeon. In 1832 he built on Faraday’s electromagnet by incorporating a commutator which oscillated the direction of current to ensure continuous rotation.


    Nota Bene.

    The Motley Fool asks: Where Will Apple Stock Be in 5 Years? → Not reading this article is probably a wise decision. Shares could perform in line with the S&P 500’s long-term average Investors can follow a straightforward exercise to try and figure out where Apple’s stock price will be in late March 2031. It’s important to consider both the valuation and profit gains. We just released a […] →

    Apple’s services continue to see increased engagement, spending

    Apple’s services continue to see increased engagement, spending → The survey of 3,500 smartphone users reveals a significant rise in average monthly spend on Apple services to $13, driven by increased adoption of premium offerings like AppleCare/One, Apple TV+, and Apple Music, with notable shifts towards AI features despite muted upgrade intent, though potential US bias may affect overall accuracy. →

    KeyBanc maintains a lack of clarity of thought → The analyst's note on Apple is overly cryptic and lacks clarity, making it difficult to assess its validity or relevance. →

    iPhone sales continue to surge into February – Bernstein → February saw robust iPhone sales driven by the iPhone 17 line, with global unit sales up 26% and ASP climbing 6.9%, yet January-February revenue estimates oddly lag behind projections, sparking confusion. →

    Morgan Stanley has a stark message for investors in Apple → Morgan Stanley's survey indicates strong potential for Apple stock, highlighting record iPhone upgrade intentions, especially in China, improved switching rates, and significant interest in a future foldable iPhone. These factors support robust FY26 shipment forecasts and suggest a possible revenue boost from new products. Despite some concerns about declining willingness to pay for AI features, Morgan Stanley maintains an optimistic outlook with a $315 price target. The article criticizes TheStreet's editorial approach for misrepresenting the positive survey findings as negative news about Apple. →

    Mac mini and Mac Studio orders booming → Apple's Mac sales are surging due to the M5 chips' enhanced AI capabilities, outpacing other platforms and driving demand despite current shipping delays. →

    Gartner adds their Mac Q1 estimate to the pile

    Gartner adds their Mac Q1 estimate to the pile → In Q1 2026, Apple's Mac sales surged impressively by 10.7% to 12.7% year-over-year, driven by the MacBook Neo's appeal, securing a 10.6% global market share and maintaining fourth place among PC vendors, amidst a 4% rise in overall PC shipments. →


    Office Hours

    Asymco Office Hours Live Q&A with Horace Dediu: April 8, 2026

    Asymco Office Hours Live Q&A with Horace Dediu & Gene Munster took place on April 8, 2026 → Topic dicsussed: Apple Topics discussed: 

    • Geopolitics: China concentration; Taiwan tail risk
    • Financials: Solid near-term growth
    • AI: Critical narrative shift; not yet proven
    • Growth Strategy: User expansion
    • Business Model Evolution
      hardware → services → Personal AI
    • Moat: Privacy + integration; trust;

    Consider subscribing to Asymco One gives you full access to our research, analysis, and commentary. Subscribe with code BULLETIN for a discount.

    Feedback: Have questions or comments? Reach out to us at contact@asymco.com. We’d love to hear from you.