The problem will be in using some comparable as a measure of reference. This is a problem because first, there is no equivalent product in history, second, there are few similar products that are pre-ordered and sold without user samples being available, and third it's being sold through a very limited channel (on-line Apple Store). Lastly, the number includes only delivered units vs. reservation for pick-up.
Nevertheless, the figure is intriguing. One class of comparable products might be new smartphone products from companies that were launching on new platforms.
One example is the Android G1--the first Android device. It sold 663k units in the launch quarter. Another is the Nokia 5800, Nokia's first touch capable device. It sold 536k units in the first quarter (up to 1 million in the first 3 months). Sony Ericsson's first Windows Mobile device was the X1. It sold 237k units in the first quarter of sales. The first Sense UI HTC device (the Diamond) sold about 1 million units. The RIM Storm, RIM's first touch device sold 1.6 million units. Finally the iPhone which sold 1.1 million units in the first full quarter of sales (about 1.4 million if we include the weekend sales that fell outside the first quarter).
The iPad does seem to be doing rather well relative to these products. Again, their figures were for a full 90 days of sales and were sold through physical retail channels in a variety of geographic markets.
I will be surprised if the number of units sold in Apple's CQ2 don't exceed 1 million. (Apple will book all these sales only on delivery which means they won't appear in CQ1 sales figures). This will probably mean better performance with a new platform than Nokia, Google, Sony Ericsson or HTC and perhaps better than the iPhone.
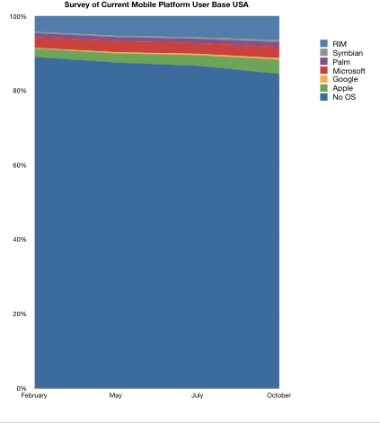
iPhone now tops WinMo and is second only to RIM. The only line that is going down is the dumbphone category which lost 10 million users.
Those users were mostly switched to RIM and Apple. RIM gained about 4.3 million users and Apple gained about 3.5 million.
Android user base still lowest of all platforms and increased by about 0.6 million. They are likely to beat Palm however next few quarters. At this rate however it's very hard to see an installed base that is going to challenge Apple for a long time.
"...in our October study of 600 European decision makers in medium and large enterprises, more than 20% said they expect the iPhone to be the dominant smart phone platform for running business applications in their organisation within the next 3 to 5 years. In France, the iPhone was ahead of Windows Mobile and RIM in this regard – a remarkable result.”
This short quote brought back to mind the recently formed partnership between Nokia and Microsoft to deal with RIM. One fruit of this relationship is a recent job posting atcareers.microsoft.com which seeks Symbian developers to work for Microsoft:
Job Category: Software Engineering: Development Location: India, Hyderabad Job ID: 702365 Division: Microsoft Business Division
The Office team is looking for a self-motivated and highly passionate Developers to contribute in building a new team and drive discipline excellence in the delivery of Office Mobile and Communication experiences for Nokia’s Symbian smartphones.
Microsoft and Nokia have formed a global alliance to design, develop and market mobile productivity, communications and collaboration solutions.
Under the terms of the agreement, the two companies will begin collaborating immediately on the design, development and marketing of productivity solutions for the mobile professional, bringing Microsoft Office Mobile and Microsoft business communications, collaboration and device management software to Nokia’s Symbian devices. These solutions will be available for a broad range of Nokia smartphones starting with the company’s business optimized range, Nokia Eseries. The two companies will also market these solutions to businesses, carriers and individuals.
This project builds on the existing relationship with Nokia who is optimizing access to email and other personal information with Exchange Activesync. Next year, Nokia intends to start shipping Microsoft Office Communicator Mobile on their smartphones, followed by other Office applications and related software and services in the future.
While the iPhone wins hearts and minds in IT through sheer brilliance Nokia tries to become a supplier to IT departments through a strategy deeply rooted in the 1980s: the manipulation and exertion of control over file formats. As IT has diminished in importance (to the point of ceasing to matter to some) it's hard to understand this misplaced alliance with Microsoft over something so inconsequential.
So Dell is making Android mobile phones while Nokia is making Windows PCs. A curious confluence of poor management decisions.
Why is all this dilution of core competence happening? Average punditry would suggest it's all about "convergence" and the overlapping of mobile and until-recently-fixed computing.
Er, not quite.
The economics of plastic bits shipped in cardboard boxes has not changed. It's as lousy a business as it has always been, whether the plastic bits are small or large. Some would argue that the gross margins of mobile devices are higher than those of computers, but that's not true on average. The gross margin on average mobile phones is just as low (<10%) as it is on PCs. There are about the same number of competitors and rivalry and global marketplace.
If indeed, margins were the only story, why would Nokia choose to chase the low margin PC business while holding (albeit very tentatively) 50% global share in "smartphones"? Similarly, why would RIMM choose to chase the low end consumer business (link: Blackberry Pearl et. al.) while having the fat margins of thinly penetrated business devices to wallow in? Finally, why would there be hundreds (literally link: www.pdadb.net) Windows Mobile smartphone licensees, the vast majority of which don't manage to sell more than the 50k minimum volume licenses they are obliged to order?
The fact of the matter is that the money being chased by device vendors is not being paid for devices, but for the service plans those devices enable. More precisely, these businesses are concerned with capturing a share of ARPU uplift from mobile data services. As such, they are mostly offering hardware as enticements for the *change* in ARPU that mobile broadband creates. Success depends on the power of that hardware to compel users to switch to higher data service fees.
The first proponent in his "hardware as ARPU booster" was actually Microsoft back in 2003 when they entered the mobile OS market. One of their value propositions was that Windows Mobile would boost data ARPU. The reality was not so compelling however as WinMo turned out to be too awkward to use for most users and the power of the platform lay fallow. In reality, the first successful hardware ARPU booster was RIM. In the middle of this decade, RIM showed that a Blackberry user could be worth between $5000 and $8000 in NPV ARPU to an operator. For that juicy pie, RIM was handsomely rewarded with a small "cut" that boosted their margins to above 50% making them the most profitable device vendor on the planet.
The realization only began to set in about 2007 as every other vendor began applying resources to deliver ARPU boosters. Apple took note early and executed beautifully with the iPhone, mastering the "get paid for ARPU" game, and in the process capturing 50%+ gross margins and (depending on the quarter) up to 30% of all profits in the device industry.
To forecast how this game will be played and how sustainable this boosterism is, we need to segment or categorize the market according to ARPU. The way to visualize this is what I call the "wedding cake" model. Each cake layer represents the population of users in that ARPU segment and the thickness of that layer represents the delta of ARPU to the layer below.
The base layer is huge (billions of customers) and represents the prepaid voice market. The average "thickness" of this layer is about $10/mo.
The next layer is smaller and represents the postpaid voice market. The thickness is about $30, representing the "boost" over prepaid.
The next layer is smaller still and represents the postpaid voice+data market where the data is a-la-carte. This is typical of plans where the buyer pays separately for certain data services (e.g. email, navigation, etc.) and pays on a per-megabyte basis for browsing. The ARPU differential is about $20.
Finally the top layer is the unlimited data plan packaged with bucket voice and SMS. Here the ARPU differential is another $30.
At its highest, the cake is about $100/mo., though the width of the top layer and hence the population of paying customers at that price point is quite small relative to the other layers.
Now each layer is covered with a "frosting" which is the device hardware revenue. Obviously the frosting gets a bit thicker the higher the layer, but it's a relatively thin layer compared to the "cake" thickness. In the higher layers the trend is in fact to make the frosting as thin as possible (<$99 NPV or <$4/mo. for a 24 mo. contract.) The devices which enable the top layers are clearly more complex and expensive to make, but the end-user pricing is trending down. The trick is therefore to convince the operators to pay a piece of the "cake" to the device vendor in exchange for migrating users to these higher layers.