Takeshi Narabe • 22:44 Japanese companies always follow and concentrate on seeking additional functions so that is very in contrast to Apple so there is a growing concern that Apple might be falling into the same spec trap that runs parallel. Japanese firms you know focusing on incremental hardware improvements like you know iPhone's more thinner and thinner...
Horace Dediu • 23:34 It's true. But I will say to the defense of Apple, of course, they need to maintain some improvement. Otherwise, people may not consider buying it. They do think hard, though, about what needs to be improved. And many times they don't improve things that many people ask for. They'll say, "Oh, you need a refresh rate of hundreds of hertz." They don't bother with that. Or they [won't offer] more resolution, more than even the eye can see. They don't do that. But they'll do a lot with the camera.
And they'll probably do more. They do amazing things with audio. They do really, really interesting things as far as... Like face ID was something that was nobody asked for. But now it's a very, very useful thing. People recognize the value. So I do think there's a roadmap there that's kind of interesting.
But here's the bottom line, you know, Christensen said, that the trajectory of what performance people expect is not as steep as the trajectory that companies can deliver. And that's why you overshoot. What Apple has been able to do, at least through the lifespan of the iPhone so far, is to cause people's interest in more improvements to rise a little bit.
And so the theory basically says that there is a flat trajectory to the user demand of performance. But my [observation] is that eventually you do drag people up, just like with non-consumption. People don't ask for a better camera, but once you give it to them, they're like, oh, yeah, I really want an even better camera.
[The performance demand] it created... I mentioned the short video TikTok format, It was the phone's camera that allowed [average] people to suddenly become filmmakers. And it allowed people to become "vanity machinery"[1]. It became all about vanity, all about selfies. And [as a result] you have to have a front camera and a back camera and you have to have editing software and you have to have a more powerful processor and you need a huge amount of storage when you're dealing with video.
So suddenly, the phone needs more and more and more. But the demand for video editing on a phone was created essentially from nothing. It was created by the supply of camera. And so, yes, that is a theory that you have a problem if you overshoot. But I think in the old days, a consumer electronics company would add buttons.
I was at Nokia for a long time, and we had buttons and buttons and buttons. We had one phone with over 100 buttons on it.[2] That wasn't very useful. So the idea of Apple is that they remove buttons. They make it even cleaner in that design, and they make it easier. So face ID is an example, and privacy is important.
By the way, that's another thing that they sold to people. If you think about it, nobody asked for privacy because everybody was okay with sharing. But the fact is, it's like the automotive industry has safety, and nobody asked for safety either. But you should deliver safety, you should protect the passenger. [Today] it's considered hygiene. [If] you don't have it, it's bad, but if you have it, nobody cares. But in the case of Apple, they're pushing on privacy.
So yes, it is a concern that you overshoot. However, one more defense of Apple is that they introduce these wearables. So if you take the AirPods, for example, again, not a product anybody asked for. And when they were first introduced, they were made fun of because it was [so funny looking.]
The AirPods are a very clever new product, [they are] an extension of the iPhone. They're not the iPhone per se, but we have a wonderful must-have accessory. I feel like I'm naked without taking my AirPods with me. The same with the watch. Another product extension. Again, it's an option. You don't have to have it, but once you have it, it becomes addictive.
There are many things on the watch, which again, from health reasons, from managing information that I only need to look at for a few seconds, all of those things. (I'll give you a simple example. I never check the weather on my phone. I only check the weather on my watch because it's there with the temperature always on the home screen. And if I want to learn more, I tap on it. I don't even know how to do it on the phone anymore. You know, I have to find the weather app and then scroll and things like that. Never do that anymore.)
So there are things you do now with accessories that the phone has essentially been disrupted by. But it's still at the heart of the network of Apple. It used to be the Mac was at the center. Now it's the iPhone. So again, this is cleverness.
I was a student of Christensen, and Christensen always thought that Apple was not disruptive, and that Apple would be disrupted by the low end. [I was not so sure.] I was a bit sensing that there was a disturbance in the theory because in many ways Apple's behavior is so atypical to a normal company. And most companies would do the wrong thing, but somehow Apple managed to not step on those mines, not to fall into those traps.
Why? I'm not quite sure. And we continue to have the discussion. I really think it's culture. I really think that they've solved the Innovators Dilemma. Not by reading a book, not by taking a university class, but by always being extremely nervous, extremely careful and extremely passionate and extremely paranoid. All of these things.
Which points out the vulnerability of Apple. If that culture breaks, if the management, the next generation doesn't know how to do it, then suddenly it might fail. Because it's held together by such a force that it's hard to write it down. It's public information actually, that they have Apple University, which is meant to teach internally how things are done to the next generation of managers.
So this is something they are trying to codify and to preserve. And that's an experiment, I would say, because it's not easy. But again, that's a self-critique, an introspection, looking at yourself and asking, why am I good? How do I make sure we continue? Few companies do this. Founder-led companies might, because the founder is the company, in a sense. The founder is the culture. The founder's personality is more or less how everything is done. So those companies, to speak of, let's say, Meta with Zuckerberg, even Google, and those companies, or Amazon a little bit with Bezos, although he's mostly gone.
[But], that's not an answer, because the founder doesn't last 50 years in that job. And as we talked about one century, no way is it possible. It's beyond the human lifespan.
The word I was looking for was "influencer" but "vanity machinery" came out. Perhaps that's a better term.
I had the Nokia Communicator in mind, which was a clamshell with a full (but tiny) keyboard plus a full numerical keypad on the outer shell. The idea of mechanical keyboards was not only popular with Nokia but with the RIM Blackberry as well.
A transcript of the May 1, 2026 Asymco One Office Hours, recorded one day after Apple's Fiscal Q2 2026 earnings call. Horace Dediu presents his analysis of the quarter and takes questions from Asymco One subscribers. Hosted by Horace Dediu and Farshad Nayeri.
Horace Dediu: So I'll do a short presentation, and then we're going to open it up for questions. We are speaking approximately one day after Fiscal Second Quarter 2026 earnings call. Let's dig into it and see if we can understand it even better.
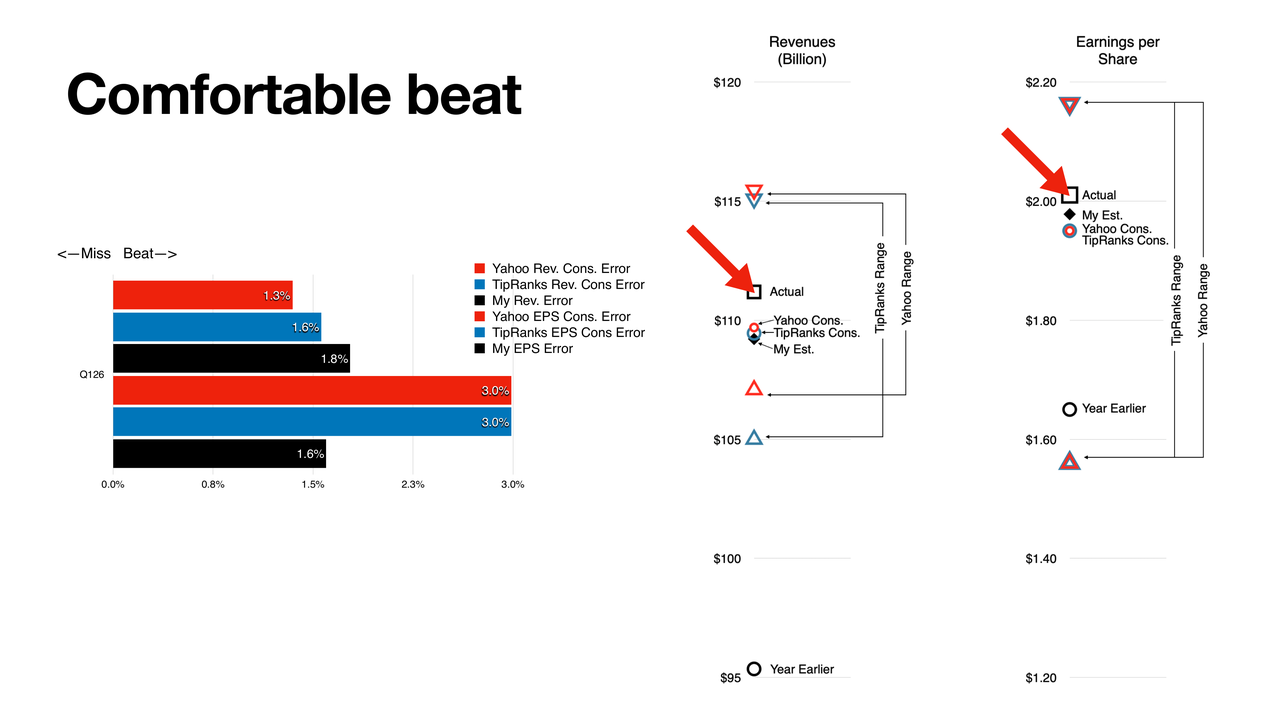
First, I think that there was a comfortable beat from already a highly elevated expectation.
So we had a range of estimates— I collected those from Yahoo and TipRanks, each one had about 30 [analysts], probably a lot of overlap between them. So we had a range of about 105 to 115 in terms of revenues in billion, and then we had EPS in a range of about 1.6 to about 2.15.
And not only did it beat the consensus, but also you can see what happened a year earlier, which is the circle at the bottom of the graph. So the beat was from already a pretty high growth rate expected from the year before.
So we have a measure of how each of us, myself included, performed relative to the actual results.
I was about 1.8% under revenues delivered, and 1.6% on EPS. And then you can see red is Yahoo and blue is TipRanks.
So speaking for myself, I was perhaps a little bit too conservative on my revenues, and I was a little bit more accurate, relatively speaking, on EPS. Roughly speaking, again, I think these are not big errors, 1% to 2%. Worst case, 3% on the consensus basis.
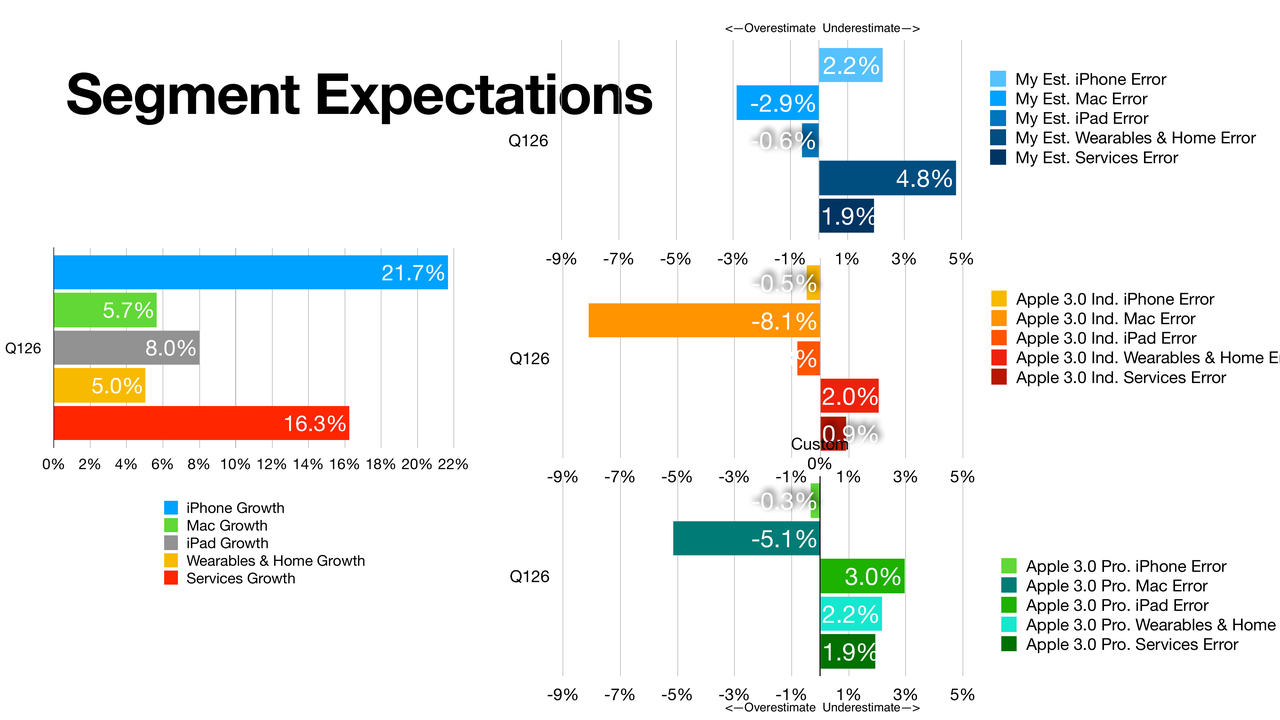
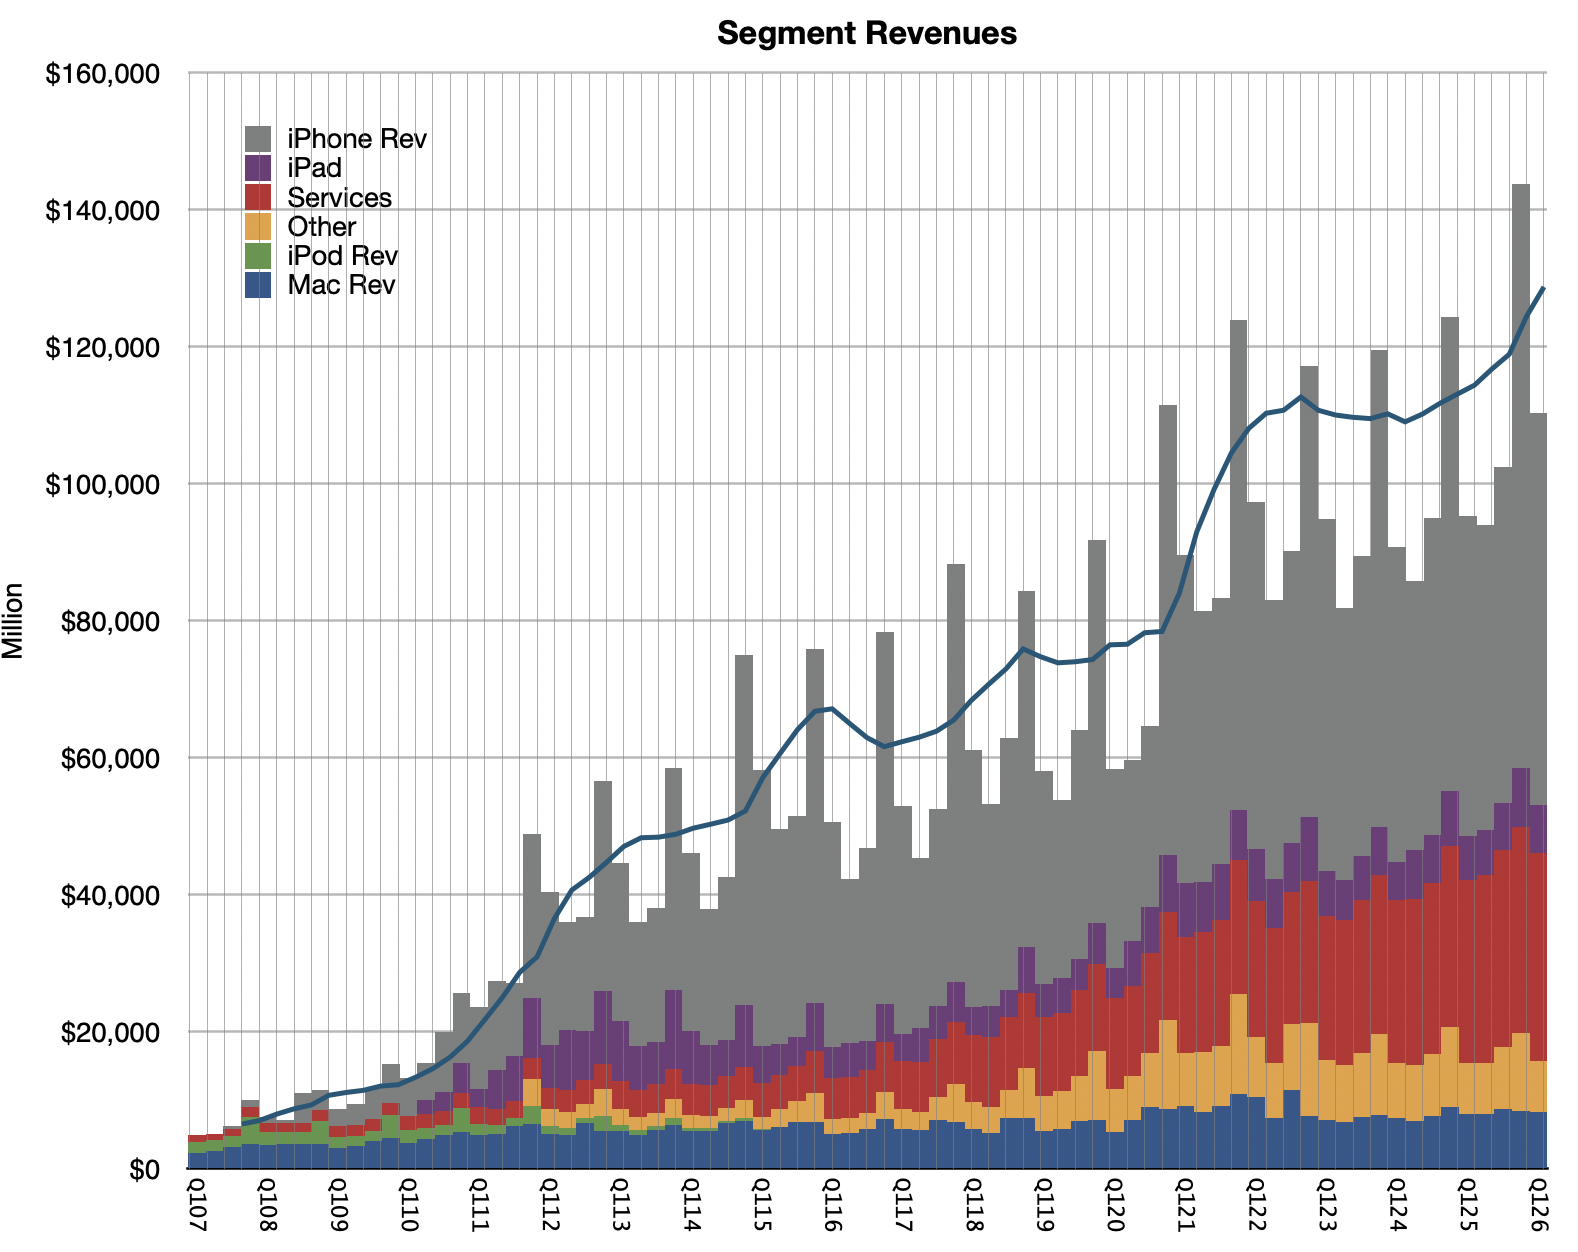
Now, on the segments, these are the actual growth that we ended up with, iPhone almost 22%, 16% on services, 8% on the iPad, which is impressive. 5.7 on the Mac, we'll talk about that a little bit, and 5% on wearables and growth.
Segment level, again, the worst case, you're looking at an 8% overestimation on the Mac. The Mac— I think a lot of people, once they saw the Neo come out, once they heard about the Mac mini stockouts, when they heard about the Claude bots, you know, everybody buying up all these Macs, there was an expectation of a big boom in the Mac, but those all happened fairly late in the quarter. My expectation was a little bit over, but not as much. I was off about 3% on that estimate. So although we saw 5.7% growth, some people expected double digits. Also, the pros had the same fault there.
Overall, though, I think these are pretty impressive. I didn't break out the geographic segments. China grew extremely well. Rest of the world, that grew very well. Management also pointed out that they're doing very well in developing markets. So overall, regionally, there were some extraordinary performances. But as we see here, just the iPhone was incredible, 22%. Very similar to performance in the previous holiday quarter, where, again, unprecedented growth, or at least in the near history of the product.
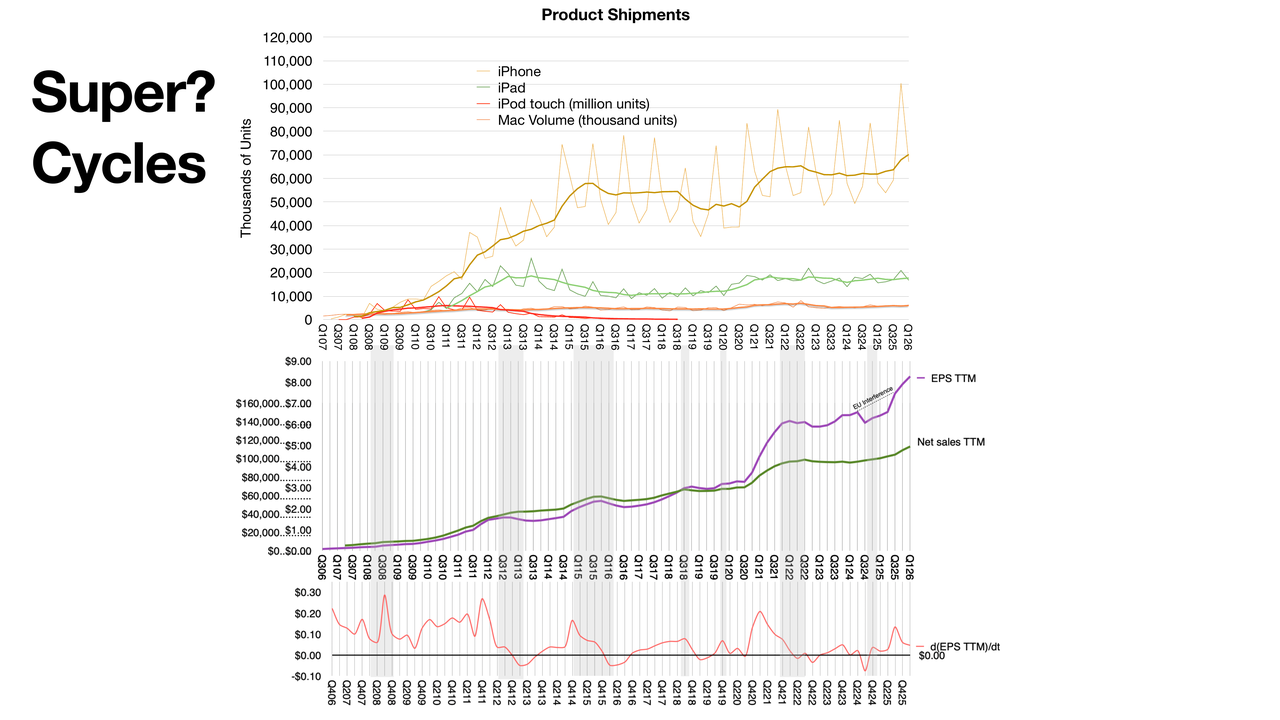
And we'll get into some reasoning why that is. People talk about super cycles, people talk about the assumption that we have these giant surges once in a while. Well, here's how to look at it.
There are two graphs here. The bottom graph shows in green the net sales, but trailing 12 months, so it's smoothed out, so we don't see the spikes on the holidays. That's the green line. Above that, we have the EPS line. Now you'll see how they tracked very similarly for a while, and then they began to diverge. That occurred around COVID. It also occurred during the surge in services, especially subscriptions and services. But still, there's a similar pulse, if you will, a cyclicality to it.
I mean, part of that has to do with the introduction of a new form factor. This has been true all the way back since 2012. When a new iPhone comes, especially a new, distinctive-looking iPhone, people will go out, especially in China, buy it for showing off that they have the latest, which there's nothing wrong with that. But then the second year usually is not the same, the phone is not new, it's the same form factor. That has to do a lot with tooling. That's a long, old story, that the tooling is depreciated on a two-year schedule, so you're going to produce roughly the same look a couple of years in a row, and then by the next cycle, you'll see people upgrading or replacing their older phones. So you're going to have this— I guess what they used to call a super cycle.
And you see it also in the upper graph, where I try to separate out of sales just the phones. Now this is an estimate because we have no unit sales for the phones since 2018, so some of that is an estimate. But you'll see again, once you smooth out the cyclicality, you'll see these surges once in a while. Now, again, this is a valid observation, but I don't think it's the main driver. The oscillation isn't huge, it might be significant, but it's a blend of many things.
The bottom graph is particularly interesting. The gray areas are when the stock price fell. And the red line represents the derivative of EPS. And you'll see how, when that is about to dip, there's usually a stock price sale going on. I wouldn't say it's predictive, but it's an interesting pattern to go through.
So what's happening now? You'll see from the iPhone, there's a new surge happening. Now, when Tim has been asked this question, he says that, well, the iPhone 17's really nice, people really love it, and that's a good answer, but the fact is, it's a distinctive-looking product. Some say it's the orange color, but it's certainly attractive. So we're seeing this pattern, a nice surge.
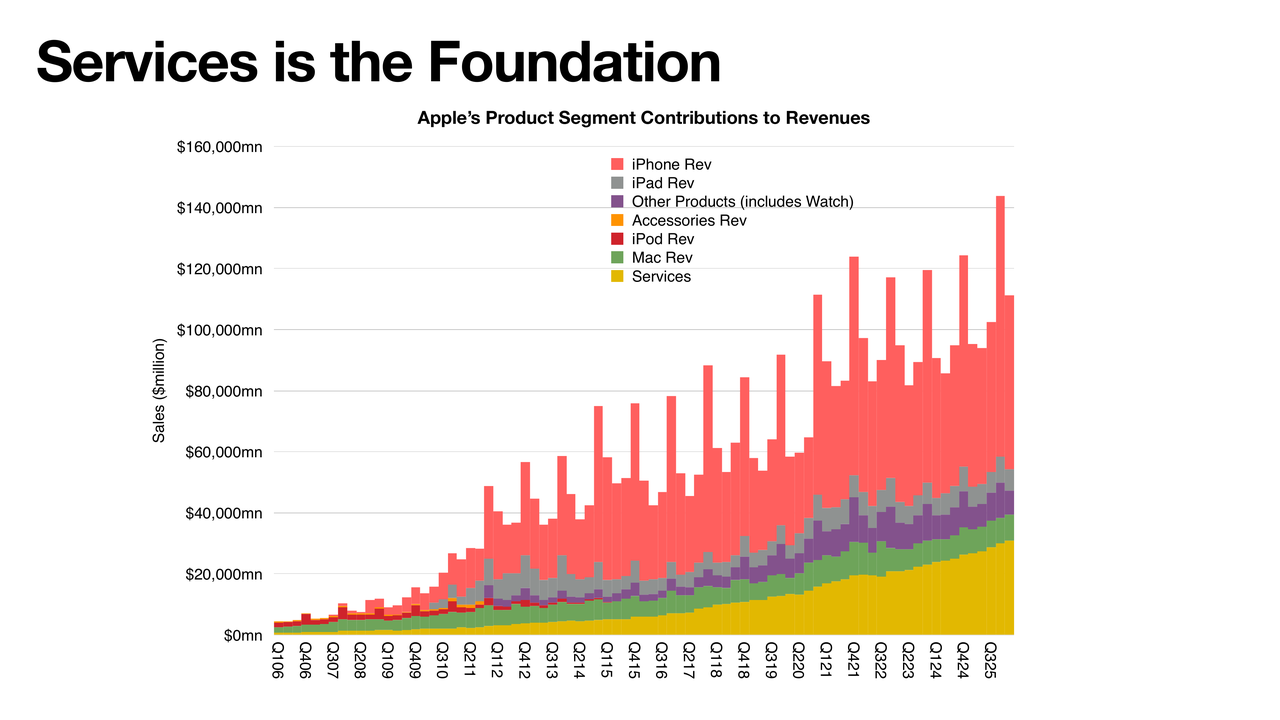
We'll get into the guidance in a minute, and that actually demonstrates that we're in some kind of an acceleration. But here's the thing, underneath all that, services is just absolutely steady growth, compound growth, and as a result, it just lifts the whole story.
Here, services is at the bottom. Normally, in a graph like this, you want to put the oldest products at the bottom and the newer ones at the top, but I wanted to highlight the fact that services is foundational, in the sense of showing how it holds up everything else.
Most people put it the other way, they say the iPhone holds everything up, but services is looking more and more to be the thing that keeps people in the ecosystem. There's a lot of value there. There's a lot of things people depend on there, and I think it's one of the reasons people don't switch. So it's another one of these stories that people aren't appreciating enough. It's been years and years of pounding the table on services, but here you see it, just how important it is. It's the tide that lifts all the boats, and the boats being all the products.
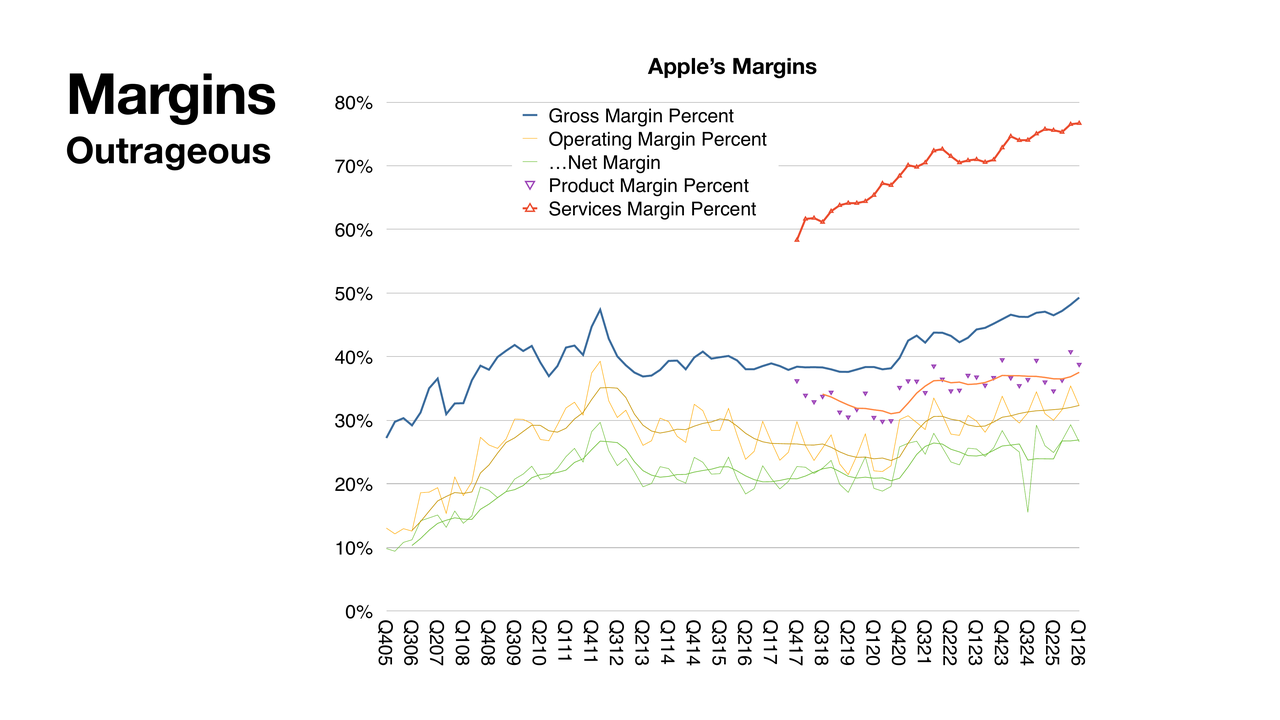
So let's now talk a little bit about margins. Unbelievable, unbelievable margins. We just hit almost 50% on gross margins. Gross margin here is the blue line. And that's composed of two subcategories. We have services in red at the top, and we have products with the purple triangles.
And although products margins are exceptional— they're right around 40%— those services, again, are pulling the whole average up, and you can see that bend in the curve in the blue line, where we were very steady around 40%, but as services took more and more; it just pulled the whole curve up.
And we also see here operating and net margins, which also are going up, naturally. There is a little bit more operating expense. We'll get into that, which maybe decreases the slope of the bottom line. But this gross margin is absolutely incredible. We just haven't seen anything like this since 2010-11. We saw that surge back then, and then it sort of leveled out, and everybody was happy with 40%, and now we're flirting with 50. I just cannot believe it.
Just one more thing. I remember being an analyst decades ago, when I was looking at different companies in hardware and software, in phones and computers and so on, and everybody was really impressed by Microsoft, because Microsoft, had an 80% gross margin, because there was very little cost of sales. That's exceptional. An 80% margin business is a money printing machine. And everybody was impressed and jealous of Microsoft that they could pull that off. Of course, Microsoft, a software company, is going to have extraordinary margins, right?
And so for a phonemaker like Nokia, there was something to be jealous of. And here we are with Apple services, a significant component on the business, approaching also almost 80% right now. And it's still rising. I just can't get over how impressive this is.
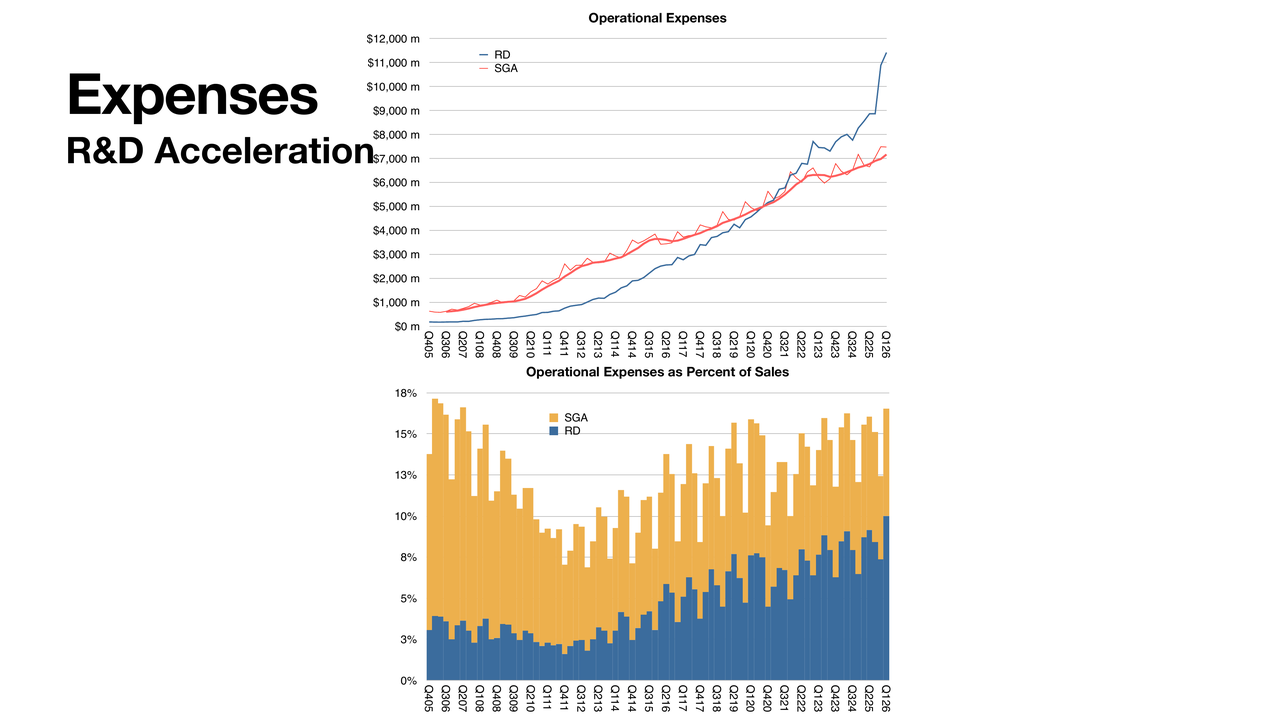
R&D Acceleration
A little bit about the difference between gross and net— you have to take out the operational expenses, and this is what we have here. It's interesting what's happened. Obviously, you see R&D overtaking on the absolute basis. So R&D overtook SG&A already in 2021. And now it's just [going] almost vertical.
By reading a little bit the guidance, I think it's going to taper a bit into the next quarter. But what we see is a significant R&D increase, also as a percent of sales, which you're seeing below in the graph below, but in a stacked fashion. In that sense, the two of them together are now approaching— haven't yet reached— a percentage of sales that was in evidence around 2007 and 8, when the iPhone was just emerging. But you'll see back then, R&D was tiny, SG&A was huge as a percent of sales. So much so that R&D—this is during Steve Jobs era, R&D was like 2% of sales. And now it's approaching 8%, which is extraordinary. Because that's an engineering company that's doing breakthrough work.
And that's something that Apple's not recognized for doing. There's a negative side of spending a lot on R&D. The positive, though, is that Apple is doing a lot of fundamental research now. This isn't fixing products, this isn't updating OS. This is engineering that is really driving what might be considered breakthrough. And that's something— and I've said this to the media when interviewed about Ternus and the succession— I said, the new CEO will need to be— this is before he was announced— I said [the CEO] would need to be someone who is acceptable to engineering, because Apple is an engineering company today. Fundamentally, culturally, operationally, it's an engineering company, and it is being now led by an engineer.
Steve Jobs was not an engineer. And none of the other CEOs were engineers. Tim Cook was an operations manager. He was excellent in a fundamental part of the business. And that is acceptable to engineers, culturally speaking. But the thing is that John is an engineer's engineer. He understands the culture of engineering and will understand how to motivate and retain talent, as well as to allocate capital effectively, not wasting it on pipe dreams. Engineers have a tendency to try to chase dreams, by the way, so you got to be harsh sometimes to shut things down. So, keep an eye on the R&D— it's a great story.
However overdoing it can be a problem. There are downsides to an engineering-led company where, again, it turns into kind of an engineering welfare state. Engineers tend to get projects and do a lot of navel-gazing, which needs to be managed carefully.
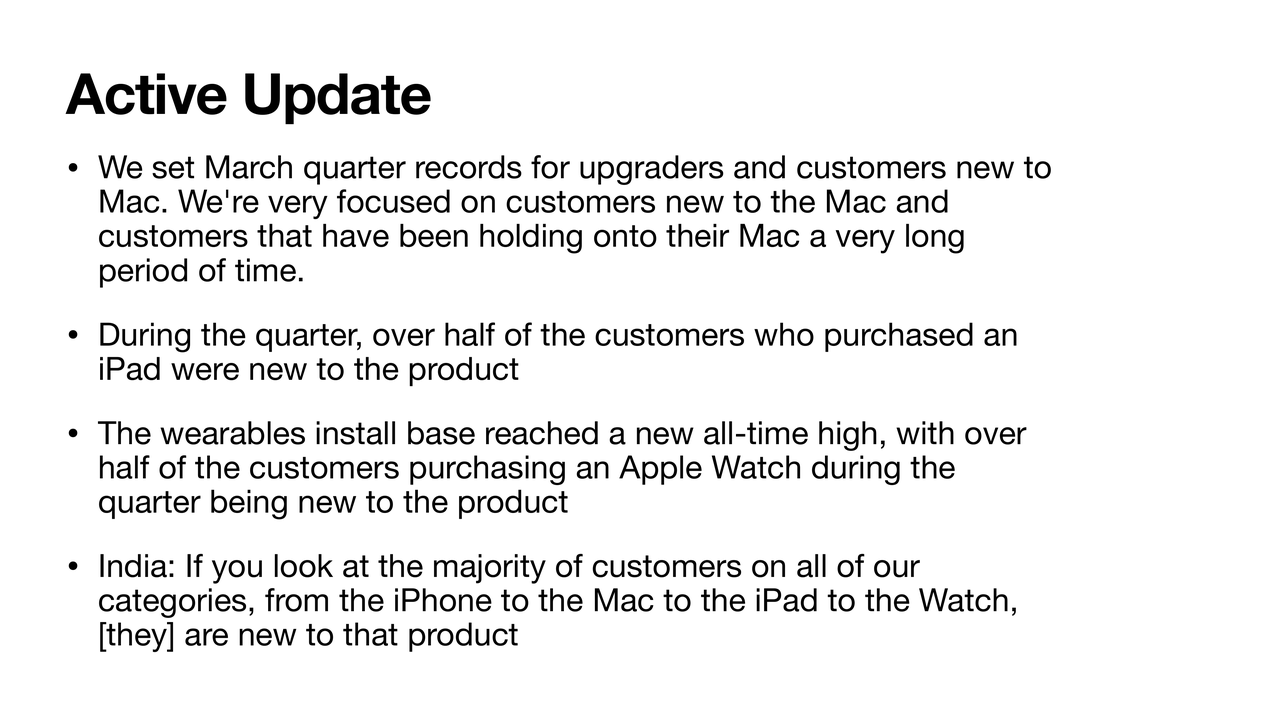
Now, let's just touch on ACTIVE. Active is the number of users, the fundamental measure of the value of the company. It's not counting iPhones. It's counting users, and these are the comments from management, just so we capture them. They come every quarter. Sometimes some products are mentioned, sometimes they're not.
So here's what we have exactly on the topic. Record upgraders and customers new to the Mac. They mentioned that Mac lifespans have been long, which is good and bad. They talk about the iPad, half the customers being— over half— new to the product. Same with the Apple Watch, this has been going on for a while.
So this is going to be important when we measure installed base, because if we see every quarter an estimate for the number of watches, or Macs, or iPads, you just take half of that and allocate it to the installed base, and the other half is growth of the installed base. So there's an interesting way to measure that, and I've been applying it. We're going to keep an eye on this.
And finally, there was a mention with respect to India during an answer to the question. The citation is that the iPhone, Mac, iPad, watch, all of these have a majority of customers that are new to the product in India. As you would expect, part of the developing market story. But this drum is still getting beaten. And that's a positive. Always want to look forward to that every quarter.
So let's jump in now to what I thought was the most unexpected comment during the call. I've pasted in here exact, verbatim the comments from the CFO. I need to point out a few things here, and I've highlighted these things in bold.
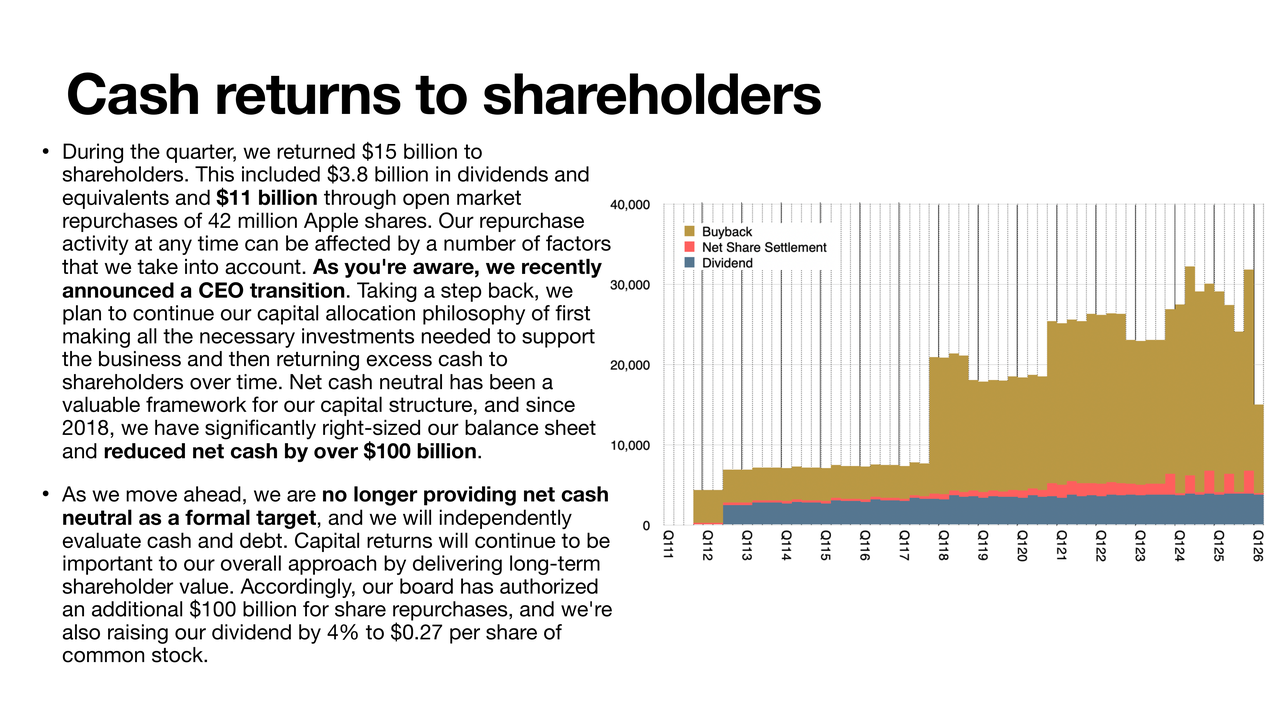
One is the dividend. The dividend number is 3.8. Last quarter was 3.9, so that's not a surprise. However, open market purchases were only $11 billion. Now, that is represented in the graph by the buyback, and that is this mustard color. And you'll notice it is extremely low. The previous quarter, we were over 25 on buyback, so we're less than half that. This is an anomaly. You'll see that it does not match the rest of the graph at all.
The blue area is dividends. The reddish area is net share repurchases, or settlements. And there's a pattern to both. Dividends has been growing in a predictable fashion, very steady. Buybacks have been somewhat steady, but up and down a little bit. During the last few periods, we've seen something unprecedented.
Now, you'll see that the 11 from last quarter was offset by a much higher number the previous quarter, but on balance, we're still down. And there's also these comments that say that they are abandoning the net cash neutral position. And I'm wondering if it's already started, because this $11 billion caught me by surprise.
I've highlighted that "our repurchase activity at any time can be affected by a number of factors that we take into account." So this was essentially explaining why sometimes there's a difference in the amount of purchases, right? And then in the middle of that commentary, he says, "as you're aware, we recently announced a CEO transition." Why does that comment fit in the middle of a paragraph, talking about the general theme?
I read this as it suggests that already the CEO choice is deciding how much to allocate to capital returns. And it appears— and again, I could be wrong— but it appears that John is probably against the idea of huge returns to shareholders in capital form. So keep an eye on this. This was, I found, very, very strange and out of character in a way. Very out of character of a Tim Cook presentation. I'm not judging it, I'm just pointing out that it isn't normal.
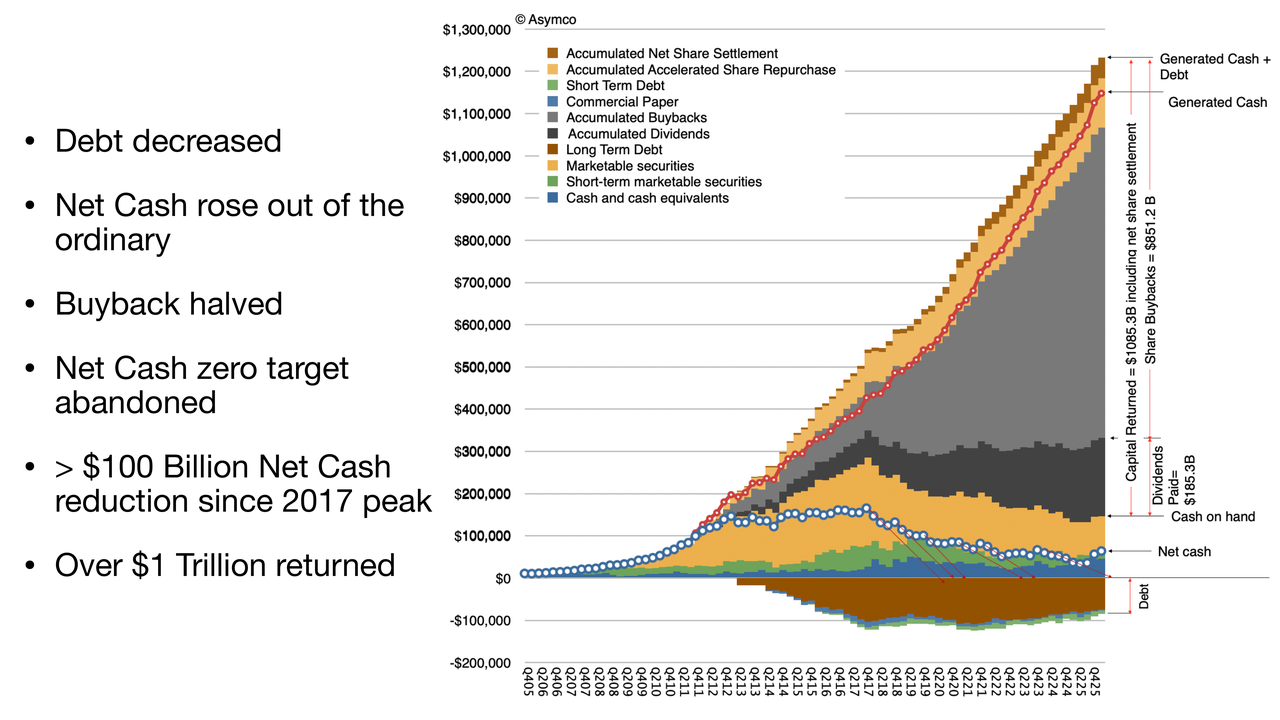
So here's the bottom line. This is the graph representing what's happening with the entire cash position and return of capital. The debt has decreased slightly, and it has been decreasing. And that's a good thing. As interest rates go up, you don't want to hold debt. A lot of that is fixed rate, but they're not taking on more. It seems like they're paying it down.
Net cash, which is the blue dotted line, has now been increasing two quarters in a row. Now, it's increased in the past, but never for long. It's had only one tick, during the holiday period. Here, where we're seeing two ticks— holiday and the quarter after.
Now, if you'll notice here, I'm going to try to zoom in. Those red lines represent what I would say were the trajectories to get to net cash zero. So that blue line, since they announced it, they kept missing the target. You would see that, another year goes by, and there's a notch up. Overall, the trend is down, but they haven't kept that path down all the way to zero. And that is now completely abandoned.
Again, we'll have to figure out why. The buyback, as I mentioned, halved— at least more than halved— to 11. Net cash zero abandoned, $100 billion net cash reduction. You'll see that this blue dot line has gone down by about half. It was down even further than that until it came back a bit. So that is going from about $160 billion net cash to the current $62 billion, which is why we get to 100 reduction. And $1 trillion overall return, which is, again, something they mentioned. In fact, they're at $1.085 trillion. And still $100 billion will be allocated further. Whether they actually spend it is another matter, but that's been approved.
So now— is this good news or bad news? I don't think it matters. I think at the end of the day, the value of the company doesn't change because of this. The value might be captured in the share price, or it might be captured as a percentage of the company that has been increasing.
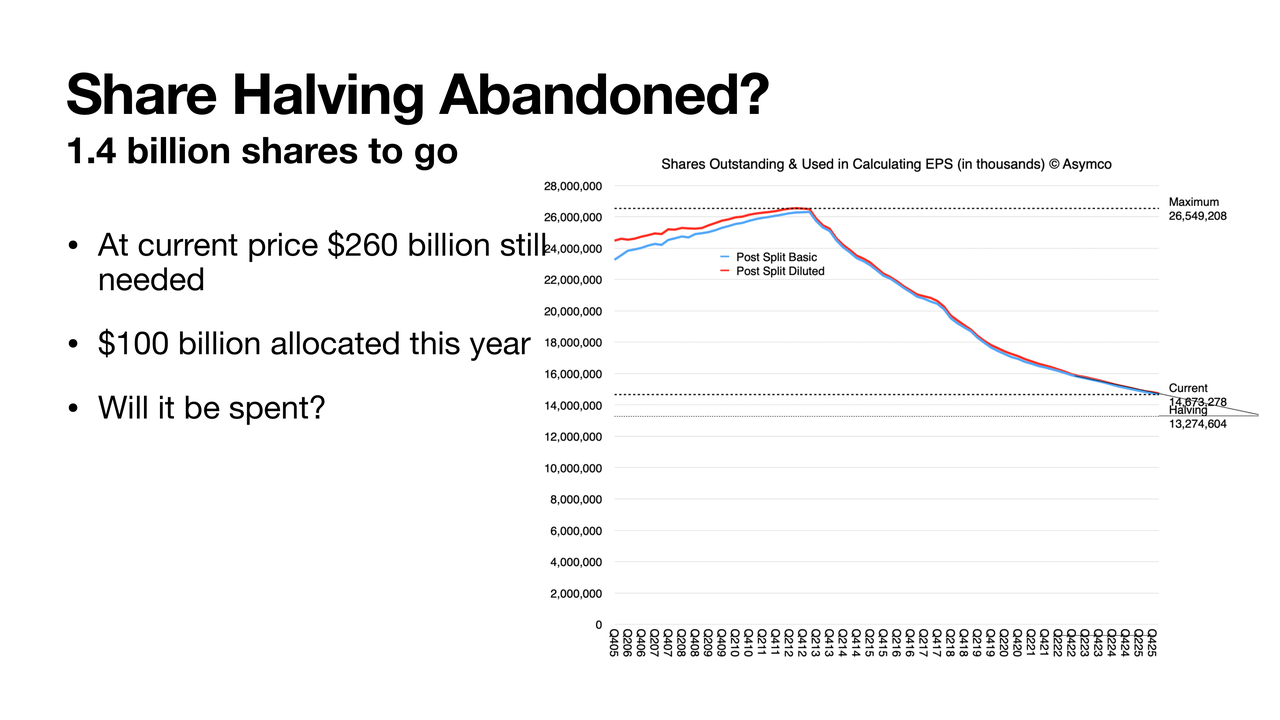
In fact, let me just pop into the next slide. What does this mean? Are we never going to reach what I call the halving? Well, we were at the maximum 26.5 billion shares. And now we've reduced that to about 14.6. Half would be 13.2. So we're still going down. But there's 1.4 billion shares to go before it's half of what the max was. Now, this is an arbitrary figure. I just thought it was an interesting target to have. And as you can see, it's getting asymptotic as the price goes up. It should be harder and harder to get there. But we have $100 billion allocated. $260 billion at the current share price would need to be spent to get to half. But probably we're not going to get there. I really don't— if I were a betting man, I would say we're probably going to see this taper.
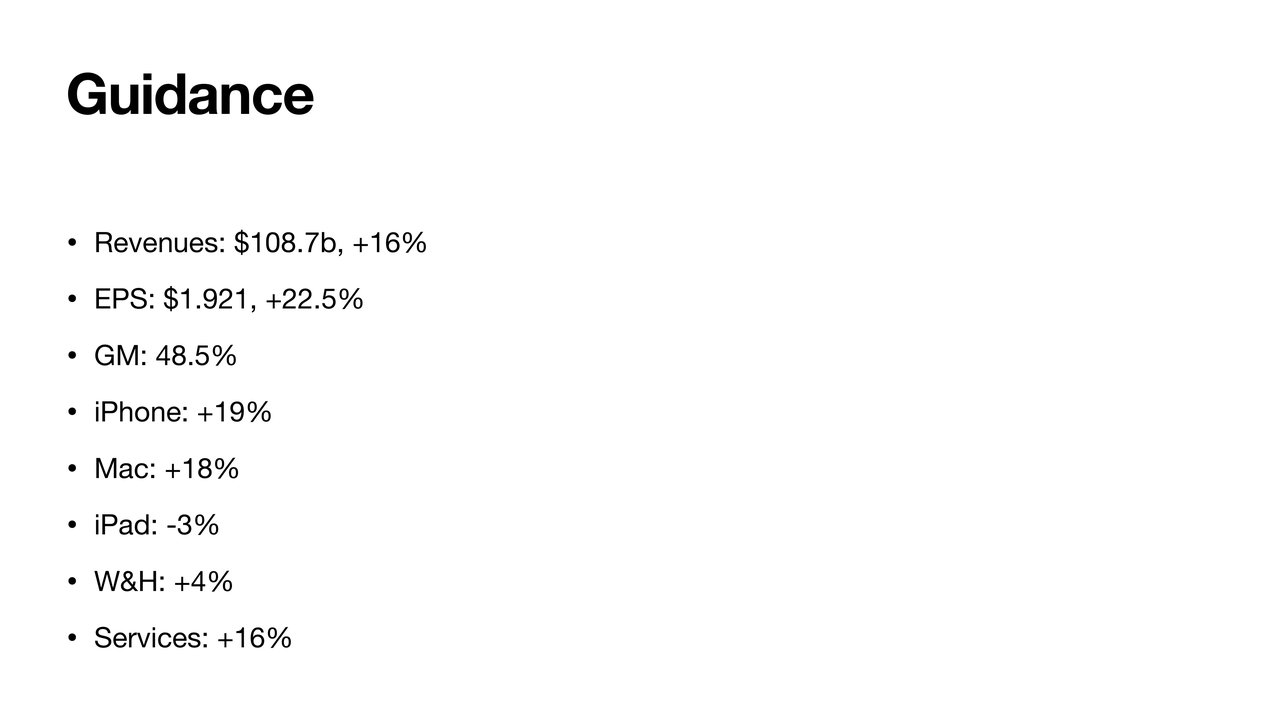
Let's look a little bit at guidance. This is based on what management already communicated. So if you put in the numbers they gave us, you will get revenue growth of 16%, coming at about— well, they guided 14 to 17, so I'm estimating 16 conservatively right now. That gets you to $108.7 billion. If you put in the other numbers— the margin, the OI&E and the tax— and do something about this share reduction. (We're still going to probably see a share reduction.) We're going to look at EPS 1.92. Which is another 22% growth. This is what we had last quarter as well.
I'm putting gross margin at the top of the guidance. [Last quarter] they went over. They guided high, and even so they went over, so I'm going to assume they're going to still hit towards the upper end of the range. I'm exactly at the upper end of that range.
If those things are true, the iPhone almost necessarily has to grow about 19%. Now, here, I'm dialing the Mac way up to 18% growth, because I do think they're going to get a lot more Mac Neos into customers' hands. Now, that's a lower price point, but it will drive sales. So yeah, I could be a little bit high on this. If I am, then iPhone needs to go a little bit higher because I still think they're going to get the revenue there.
They did warn that iPad is facing a tough comp, so I'm putting iPad down 3%. Wearables and home, 4%. It was 5% last time, so maybe consistency there. And Services, just the same as before, 16%, could come in a little bit less. But if it does, again, it's going to be put into something else like the iPhone.
So overall revenue growth, I think 16% is very much being telegraphed. And as I always say, they already have April on their books. They're communicating exactly at the end of April. They're not going to lie to us and withhold data from April. They know about a third [of the quarter] already, so that's why this guidance is so useful.
And, as you saw with my error analysis, nowadays, people's estimates are very close. There's a lot of consistency. We're not off more than a couple percentage from each other. That's just because they're so accurate on their guidance.
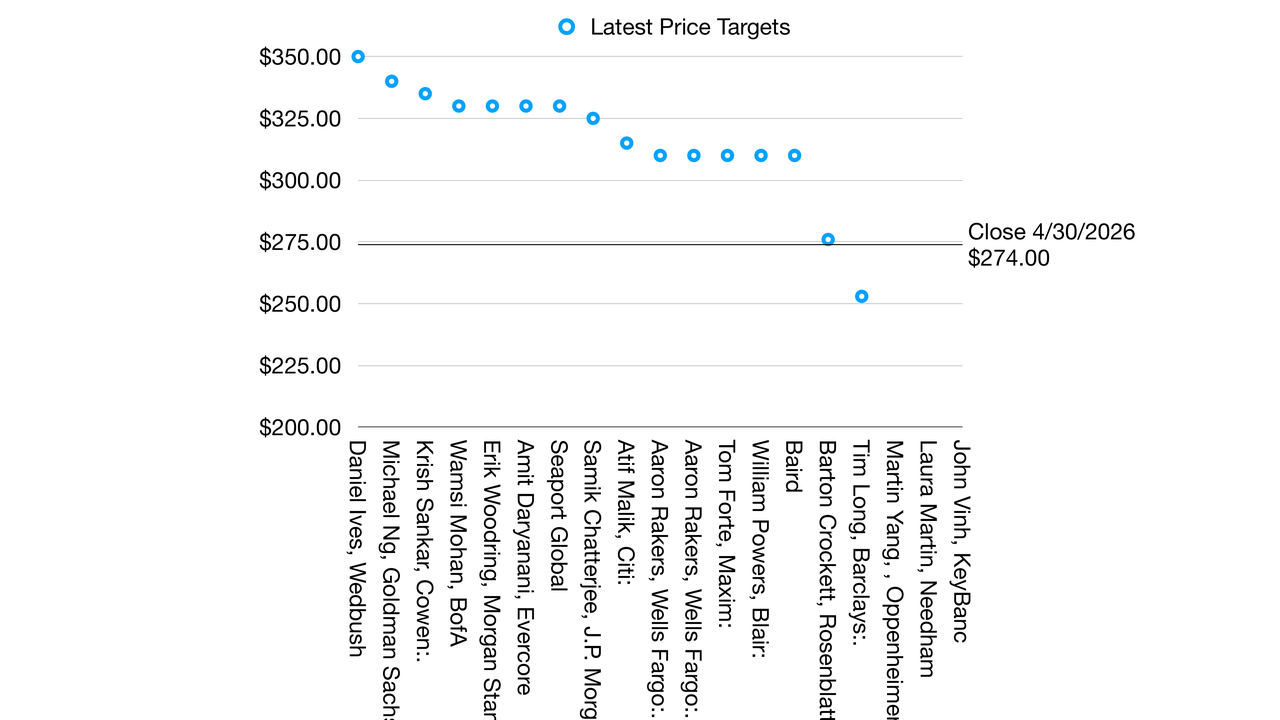
And speaking of analysts, one more graph. This is just some of the latest price targets. I'm just trying to bring everything together that came out today. This is all very brand new. A lot of targets moved up. Not that it's all that important, but people are getting more and more excited. Almost all the targets from anybody who has a positive— effectively a buy rating— is now above $310 as a target. There's two who are negative, that are at 270 and below. This is Barclays and Rosenblatt. And then there's a few which have no ratings. So they're typically neutral.
But overall, all these numbers are higher than they used to be. Now, again, I don't use that very much, but it's worth keeping an eye on things just to get a sense of how the sentiment is out there. And it looks like the stock is responding positively today. Not by much— 3% or so, last I checked. But that's the story today.
So given that, this is my first take on the quarter. Love to take questions.
-- End of Presentation --
Editor's Note: This presentation is made available to non-subscribers for a limited time. Subscribe to Asymco Oneforfull access to this and other content.
In January this year Apple reported that there were 2.5 billion active Apple devices in use. This figure has been getting updated for years and I've been reporting its trajectory and other measures that are correlated to it. For instance the number of Apple subscriptions, Apple Services revenues and other historical indicators such as iCloud accounts and Apple Music.
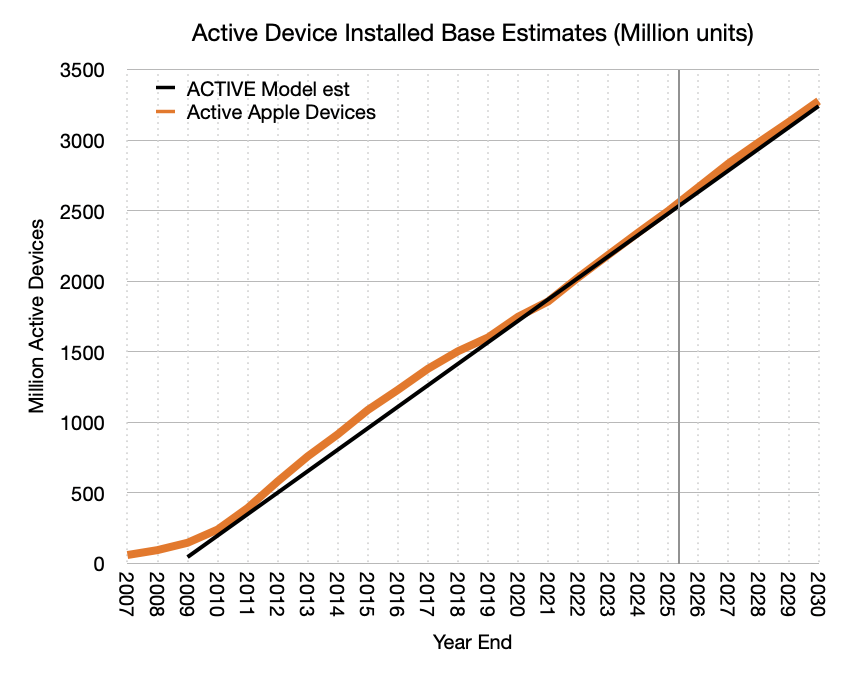
Simplifying, I published the "ACTIVE" model which makes some basic projections of this total device count and it's shown below"
One element of the analysis that has eluded me was the more precise composition of this total "devices". In other words, which devices and what is their mix. We have seen numbers for iPhones but not for other types of devices. I should note that this is not easily derived because we have neither the units sold (only revenues) and we don't know how long they stay in use. The measure of active population implies that the products are bought, used and eventually retired.
The only clue we have, beside quarterly revenues--and even there wearables and home are not separated by product--is that management occasionally mentions that "more than half" of buyers of a specific product are "new to the product". It's not much to go on.
But there are other data sets we can tap. StatCounter provides a share of platforms in use by aggregating browser identifying data for a moderately large set of web sites. That may help with share of base but not with how much the total base is. Various other analysts do try to summarize some of the installed base for particular dates.
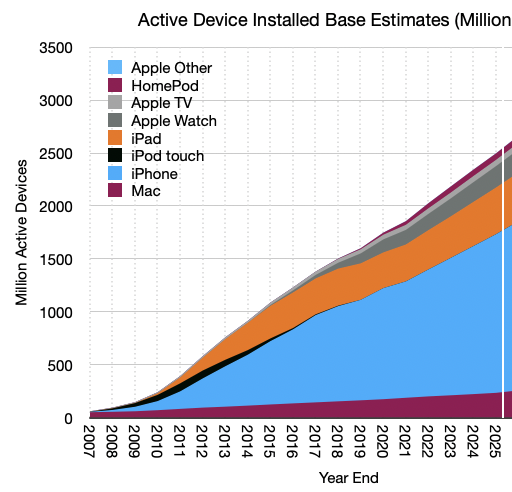
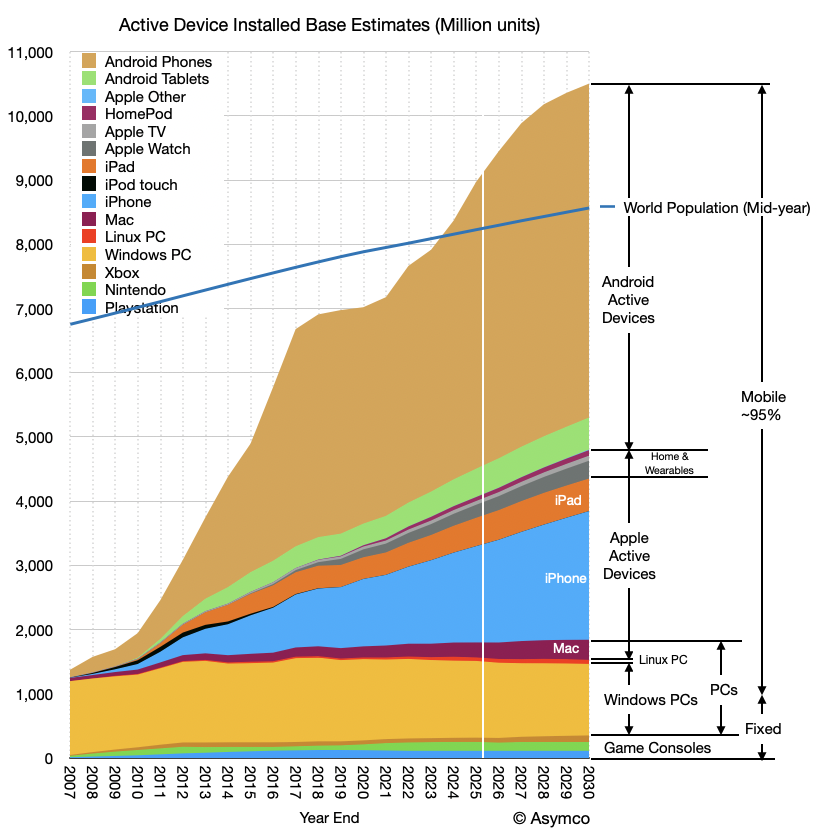
Combining all the available data and some interpolation, I set out to do is to provide a yearly count of the population of Apple devices for each year since 2007. Then to try to forecast this population to 2030. The result is shown below:
The following is a summary for the components for the end of 2025 in millions:
Year-end
Mac
iPhone
iPad
Watch
Apple TV
HomePod
Other
2025
233
1500
442
203
58.5
61.75
0.5
This history looks like this:
What about the future? Let's dig in.
This is a future five years away. Is this growth rate and consistency in mix a reasonable assumption?
To answer, we should zoom out and look at not just Apple's device base. The following graph shows also Android phones and tablets, Windows, Linux (PC) and Game Consoles.[1] It contrasts mobile and "non-mobile" computing and shows the total global population (blue line).
I have several observations:
The total device population now exceeds the total human population. The total number of phone lines was already higher for some time[2] but what are shown here are "computers" insofar as they have CPUs and operating systems that can run third-party apps.
Given the device count exceeds human count, how much higher can this total go? The forecast shows a slowing of growth within the next five years but this is not a certainty. The attach rate of devices/person could well exceed 1.2 to 1.3 and go to levels seen in wealthy countries (above 2.) If that is the case then the device total may exceed 16 billion at saturation. This has implications for how far current strategies and business models can run.
The composition of device types is fairly constant and form factor substitution is rare. New categories beyond phones and current wearables are hard to anticipate but even if they emerge, the evidence suggests they are additive. Evidently the phone did not so much displace the PC but build on top of it. The potential for wearables and home devices to explode is there but it's hard to image these stealing "share of pocket" any more than phones stole "share of desk or share of backpack". If they do explode, they will add to the total via higher attach rates. 3x human population (24 billion) is possible with new wearables and home[3].
AI holds many promises but how AI is accessed is not necessarily requiring of or benefiting from new device types. The smartphone is still the best AI device imaginable[4]. Ambient or passive computing can be provided by existing wearables but, as the graph shows, these are augmentative to phones. If AI introduces a completely new form factor, the impact will take decades to diffuse. As the graph shows, the mobile era is now approaching 20 years with the next five years foreseeable with some confidence. The next 15 years will be discussed in a future post.
Android typically captures non-consumers who eventually churn into Apple devices. This means that as long as non-consumption exists, Android grows and as long as Android exists Apple grows. If and when Android growth stops then the dynamics will change and Apple might change strategy to accelerate churn.[5]
Google and Apple will be the primary distributors for all software and services into the foreseeable future. Try as they might, challengers face over 9 billion in installed base. Note well how entrenched Windows has been on the desktop even as (free) Linux and (better) macOS alternatives have harvested usage. This rigidity has held over the 1.5 billion addressable market for 30 years now. For additional evidence consider the dynamics, or lack thereof, of the game console business.
It excludes servers and early phone platforms such as Symbian, Blackberry and Linux phones.
According to ITU Facts and Figures 2024, there were 112 mobile-cellular subscriptions per 100 inhabitants globally in 2024
Households are 1/3 human population and vehicles are only about 1/7 so Home and Automotive don't move the needle much.
AI is, if anything, putting the "smart" back in "smartphone".
This might be what is happening with the Mac Neo, decades after the PC market saturated. Perhaps pieces have finally fallen into place but apart from Chromebooks, it's been very difficult to challenge the Windows PC head-on. (Though the iPad was possibly designed to displace some of the PC usage, it hit mainly with non-consuming very young or very old and PC use was unaffected.)
Ben Thompson of the Stratechery interviews Horace on the Stratechery Plus Podcast to discuss Horace's journey to become an influential tech analyst: early career in research, business school under Clayton Christensen, and his time at Nokia during the rise of the iPhone.
The conversation further explores Disruption Theory in the context of both smartphones and AI, why Christensen misjudged Apple, and whether AI could challenge today’s tech giants. It also marks the launch of Dediu’s new paid service Asymco One and reflects his continued conviction in Apple Inc. at its 50-year milestone.
50 already? It seems only a blink of an eye since I wrote Apple at 40. Let's try copy & paste.
In Apple’s first 40 50 years it shipped 1,591,092,250 5,126,211,000 computers[1].
This shipment total is higher than any other computer company in its first 40 50 years. Actually there are no other PC makers that are 40 50 years old. One computer maker (IBM) is older but they only sold PCs for 24 years and what they still sell they don’t sell in high numbers.
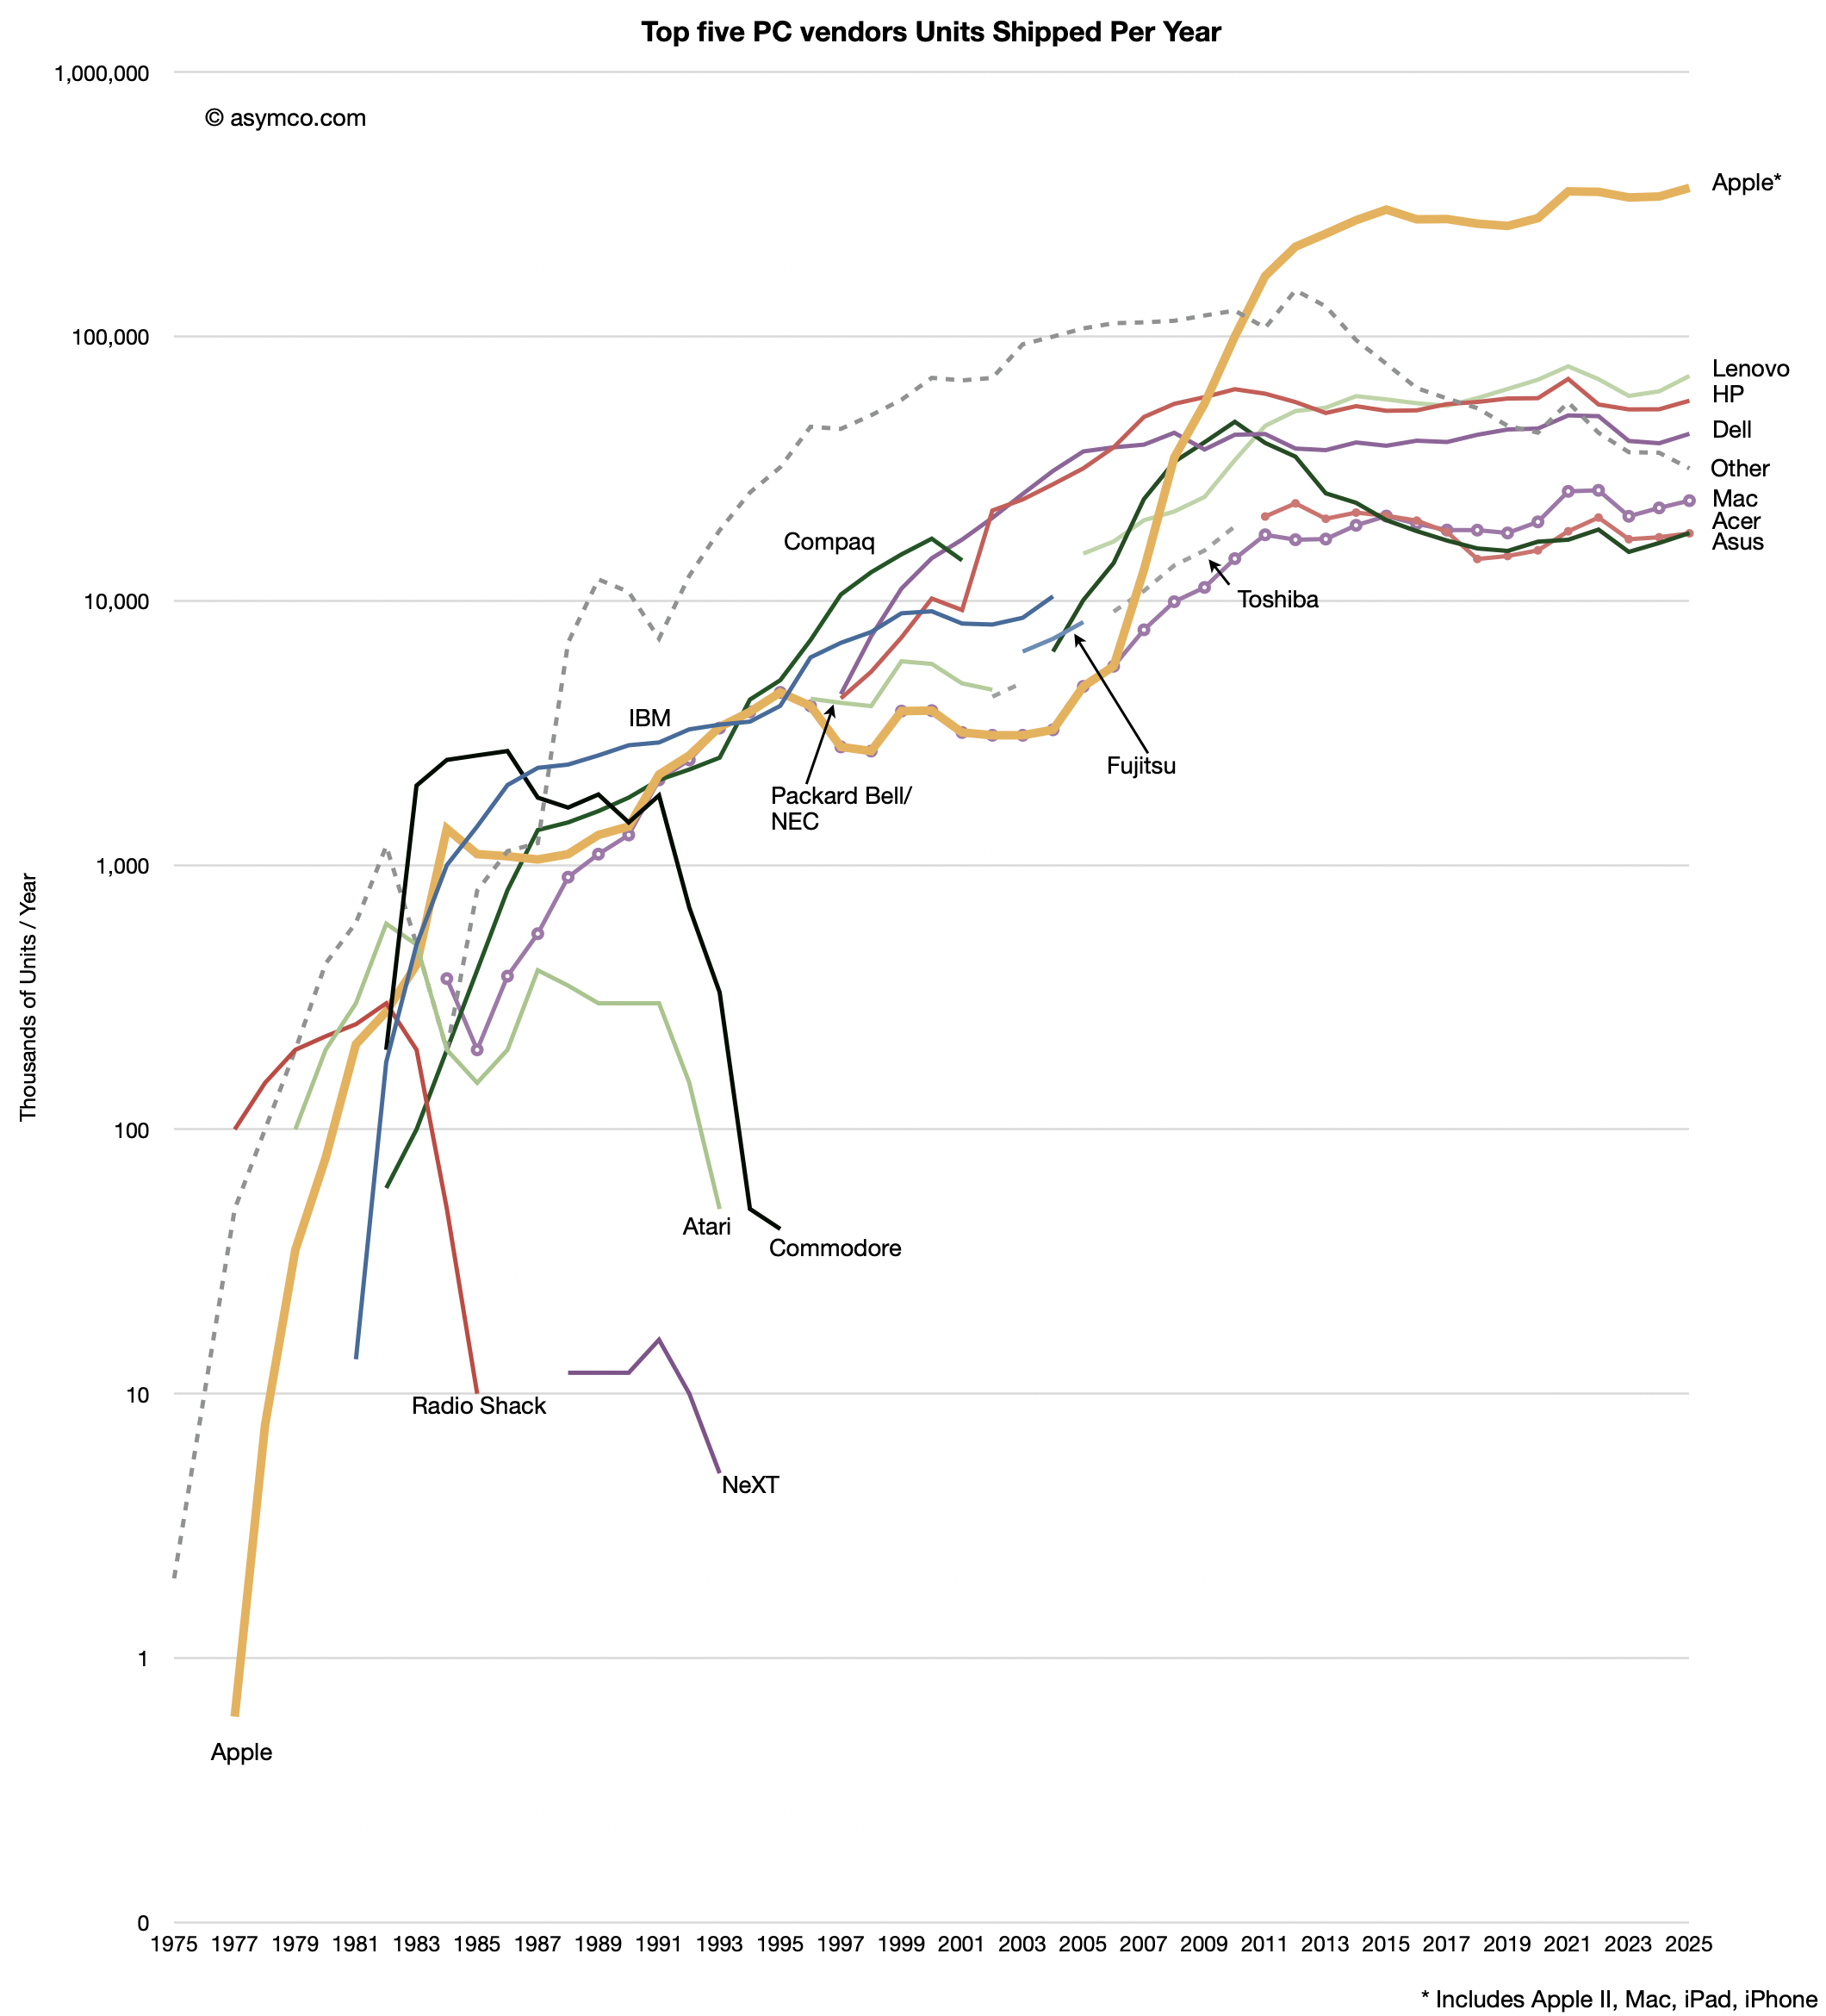
That does not make Apple the top seller in a given year. Looking at only the Mac, Apple’s traditional form factor personal computer, Apple is fifth fourth in market share. If including the iPad, it was the top computer vendor in 2011 and, including the iPhone, it was first in 2009.
The following graph shows the top computer makers by units sold since 1975, a year before Apple was founded. (Click on the graph to see a higher resolution.)
Note that the graph is log scale and in multiples of 1000. Following the yellow Apple line we can see how it started with fewer than 1000 units shipped in its first year to today when it is shipping more than 1 million computers every day[2]. It's also quite remarkable to count how many other companies have come and gone in this top five list and imagine how many came and went in the "other" category.
Who remembers Atari, Commodore, Packard Bell, Compaq? Few said that they were doomed while they were in the running. Going back to Apple at 40,
After having a 40 50 year run and after selling more computers than all American and Japanese computer companies put together, how should we think about the next 40 50 years?
First, clearly Apple shifted from being a “computer company”. It has already changed its name to exclude the word “Computer.” That [came to mean that] it sells devices (which happen to also include computers.) We don't use computers to compute anyway. We use them to make decisions, keep track of things, speed things up and to communicate and to entertain.
After convincing the world that it's a not just a computer company, the next challenge has been to convince the world that it's also not just a product company. It did so by launching Services as a group (formerly known as iTunes Software and Services) and then separating the financial reporting so that Services can be measured with its own gross margin. Year after year management emphasized Services growth in its commentary. Services has grown into the second largest segment, 26% of total revenues ($112.8 billion out of 435.6 billion in calendar 2025.)
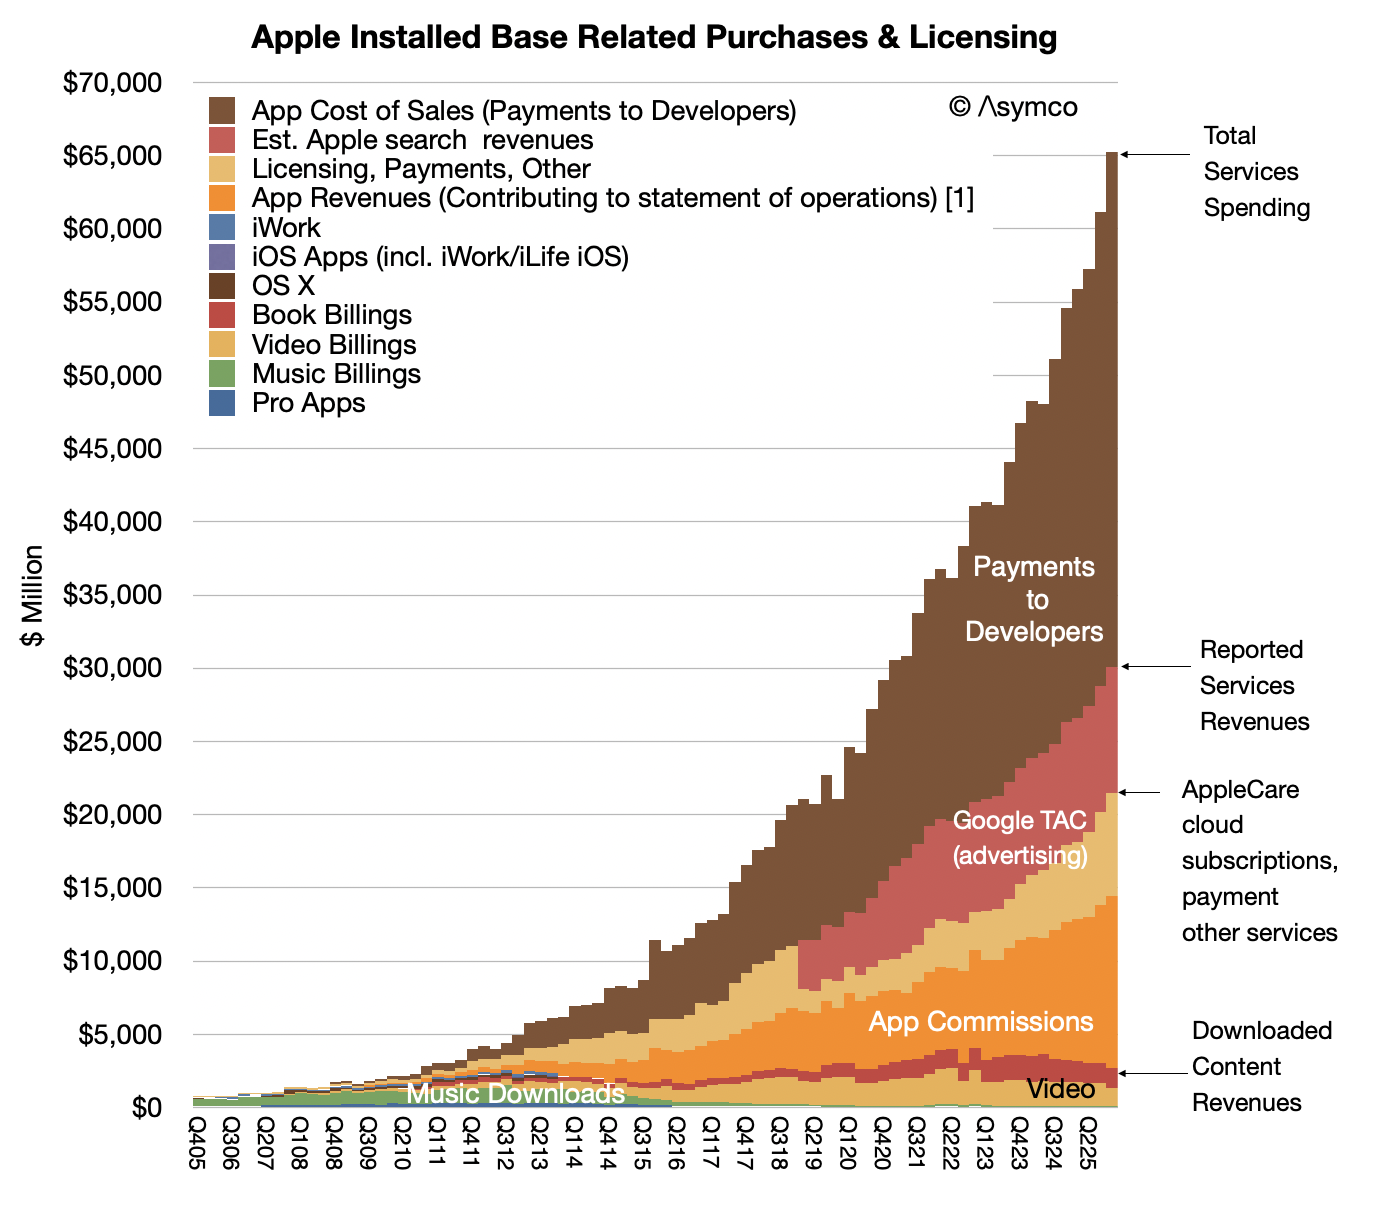
Services, if it stood alone, would be number 40 in the Fortune 500 list of largest companies by sales. It has been impossible to ignore it. Considering how much customers actually spend on Apps, Content and Services, the total is even bigger at $240 billion last year[3]. As a result, some, perhaps most, recognize Apple as a Products & Services company.
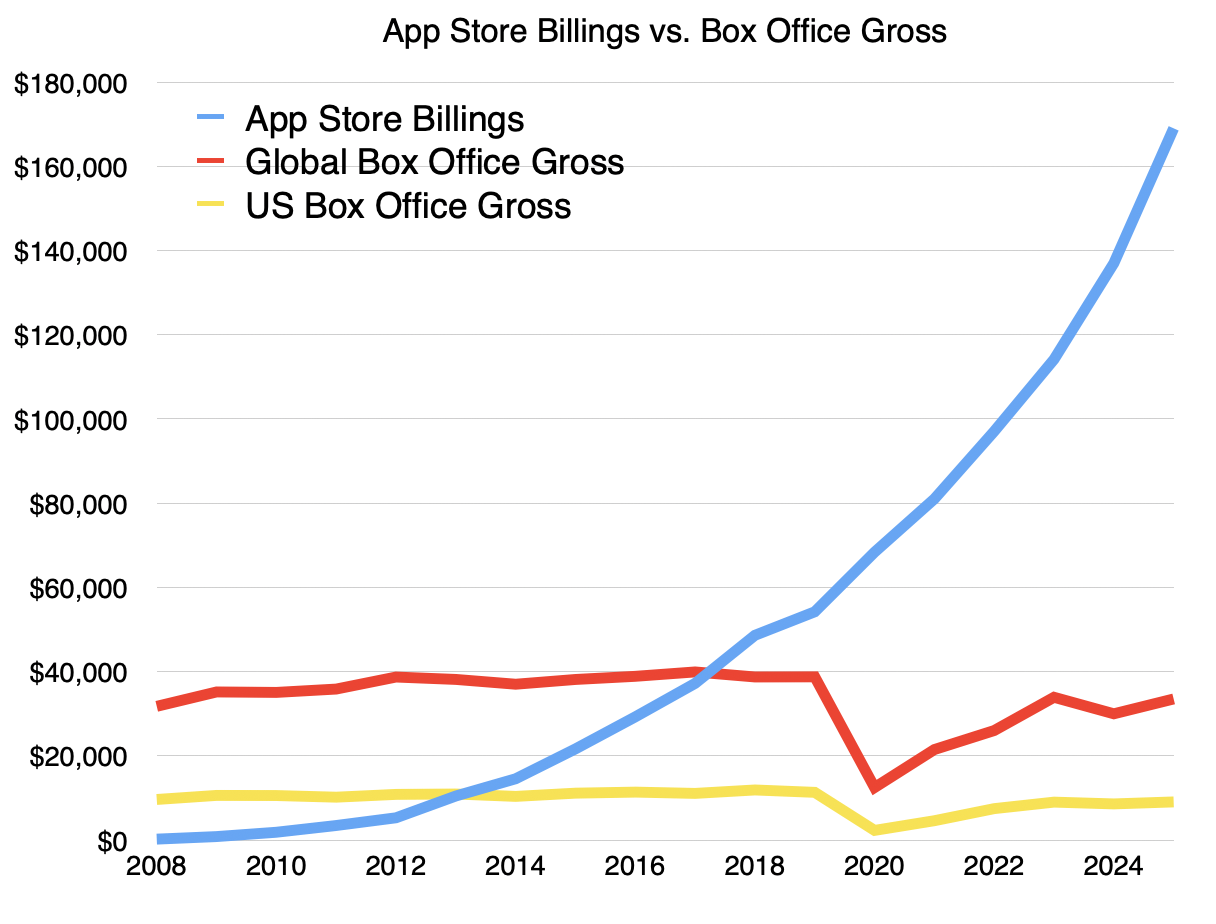
The App store alone attracts $169 billion in spending per year (2025) and that is now 5x what theatrical movie sales bring in world-wide.[4]
So if Apple is today at least a bundle of Products and Services then what will Apple be 50 years from now?
Again from Apple 40:
My simple proposal is to think of Apple as a customer creator. It creates and maintains customers. The more it creates, the more it prospers. The more customers it preserves the more it’s likely to persevere. This measure of performance for a company is not easy to obtain. It’s not a line item in any financial report.
The closest figure we have is that today Apple has one 2.5 billion active devices in use. It has around 1.1 billion users [5]. Using the devices as a proxy, we can say that this audience has more than doubled in the last decade.
So we know that at least Apple has created a large number of customers. Knowing total devices sold and number in use means that we can be sure that 63% of all the computers Apple sold are still in use. This means that most customers are recent customers. Are they going to come back?
If we then factor in the size and persistence of Apple’s audience (customer base) we might conclude that there are factors which will allow it to grow rather than shrink. My analysis based on public data shows that the customer base has been increasing steadily.
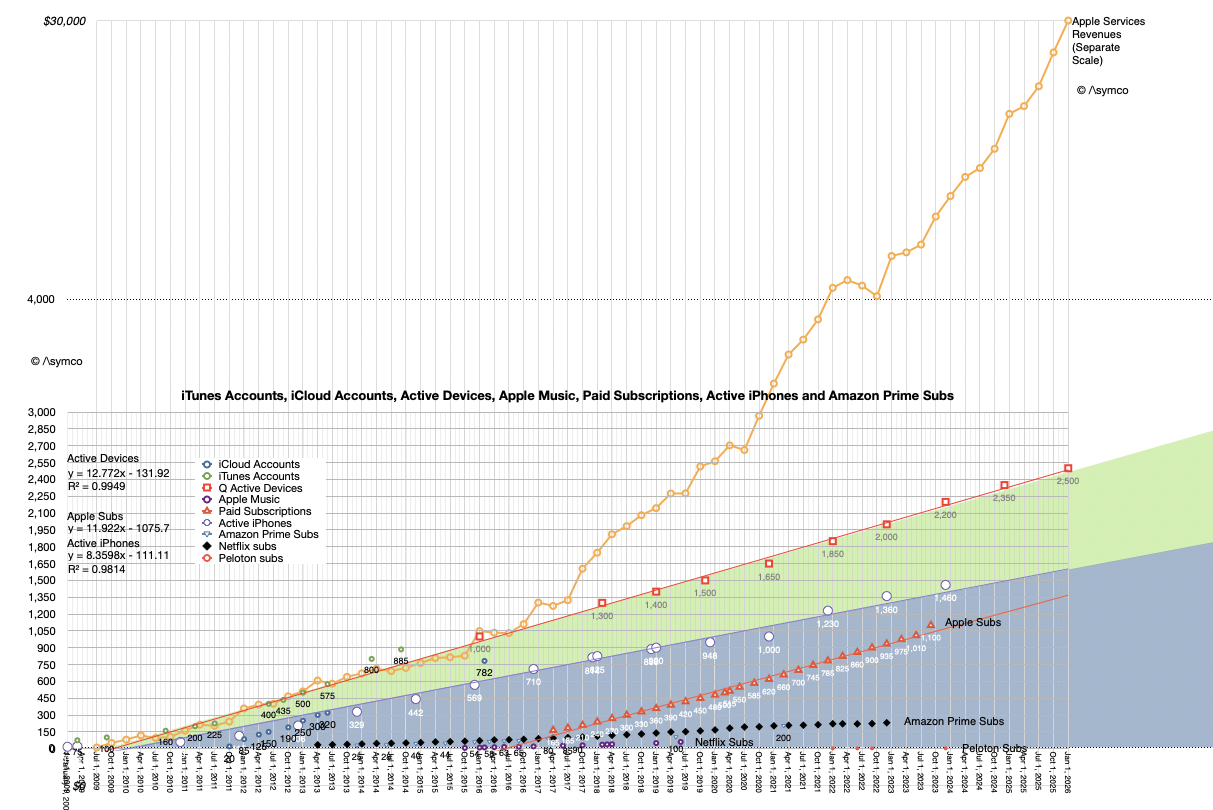
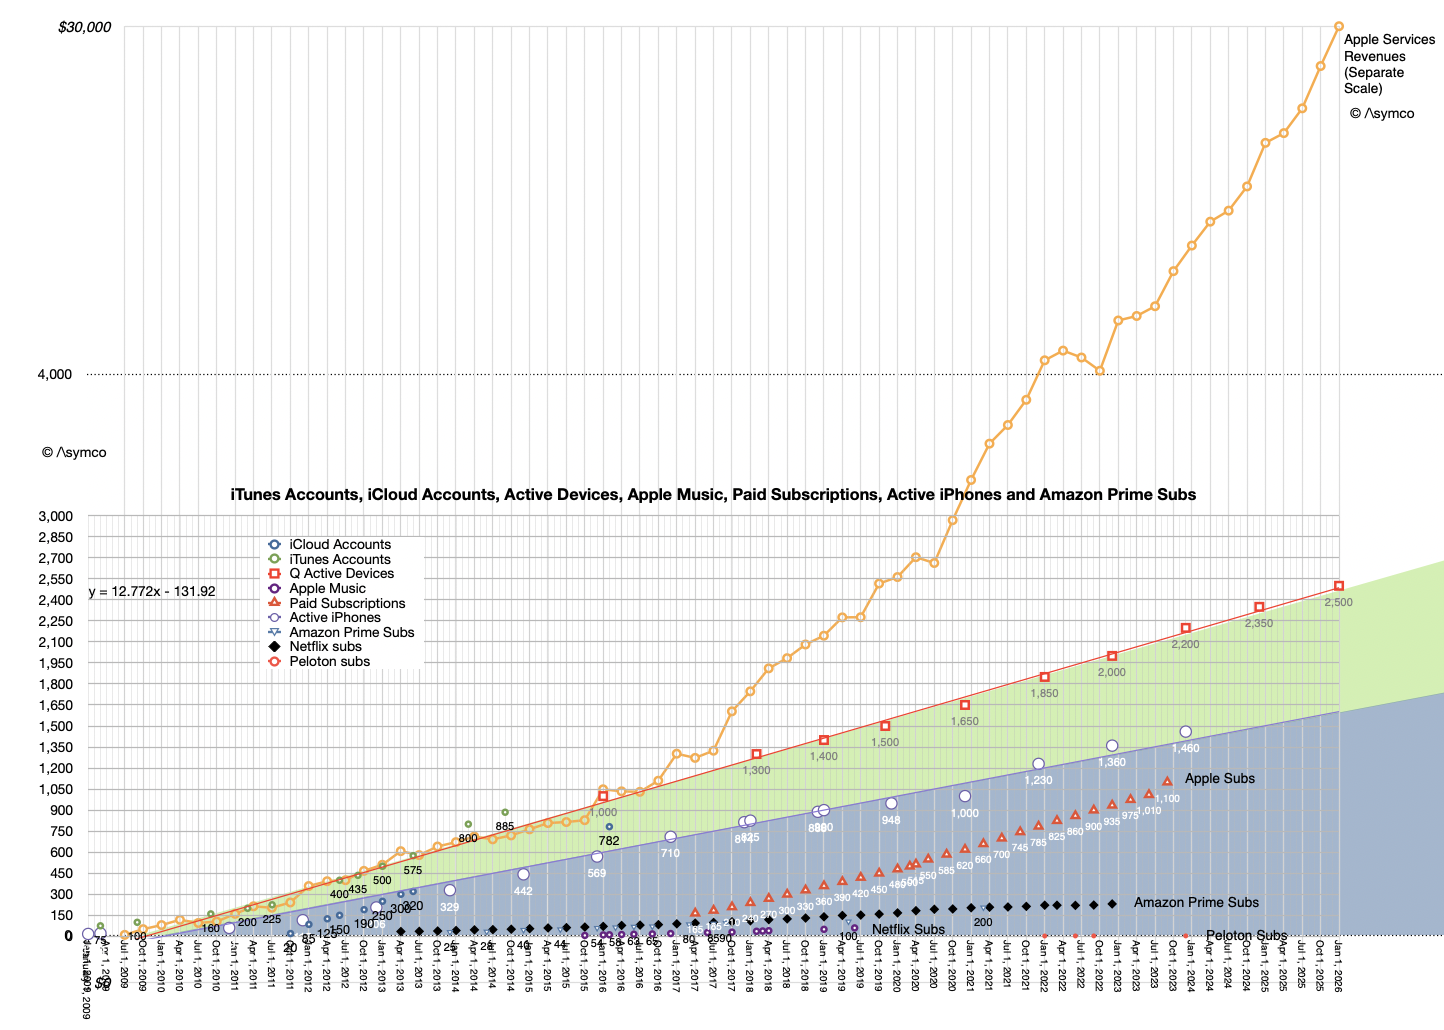
And here is a graph showing the size of device base and implications for subscriptions. services and comparisons with other consumer aggregators. Note the forward looking nature of a linear extrapolation of the historical data.
10 years ago, I continued:
Combining the history of customer creation and customer preservation with the value obtained from each customer implies that the next 40 years will be about creating another large tranche of customers whose willingness to spend on whatever Apple creates will be relatively unchanged.
We don’t know the limit. One billion was hard to imagine even one year ago. We might see two billion devices in short order. Perhaps not. Perhaps as we have a multitude of devices about us all day the number will become less meaningful. But if the number of middle class customers grows and as Apple keeps its products within their reach, there is no reason to think that there will be a reversal of the last 40 years in terms of customer acquisition.
This analysis contradicts the current perception of the company as reflected by its stock price. That price assumes the audience will wither ((With a P/E ratio of 11, without a change in revenue per user, the only justification would be the audience shrinking by more than 90% over the next 20 years.)) That is not insanity. It is what we could expect if Apple were unexceptional.
We did see 2 billion. We actually saw 2.5 billion. The assumption of a company in distress as reflected by the P/E ratio of 11 is gone. It's safe to say that Apple is exceptional.
But note that we are only 10 years into that 40 year forecast from a decade ago. Do we still feel confident that the company can last 30 more years given what we've seen so far? If one company could get through the next 30 I would say it is Apple. And if it is so then I think it will get through the next 50.
One more Thing
So, the plan is to make more of the same. It's more than enough.
Including Apple II, Mac, iPhone, iPad and iPod touch; excluding Apple Vision Pro, Apple TV and other iPods. Includes Q1 shipments estimated
2025 shipments were above 364.9 million excluding Apple Vision Pro, Apple TV, Apple Watch.
A Fortune 15 ranking. This would be the case if payments to developers were counted as sales but that is not the case for accounting reasons. As a result Services margins are an extraordinary 76%, on the order of a software only business like Microsoft Office.
As an aside, when I first started tracking this data it was early 2015. The App store had just overtaken US Box Office revenues and the outrage at my comparison and the skepticism that this sustainable was impressive. Much of the outrage was due to my choice of the headline "Bigger Than Hollywood". You can still read the 72 comments. App store billings are now nineteen times bigger than US Box office billings. I still stand by the idea that the App Store is Bigger than Hollywood. It is in fact bigger than many other forms of entertainment combined--more about this later
Stay tuned for a detailed exposition of this audience
Apple has taken full ownership of its hit workplace drama series Severance, acquiring all intellectual property and rights from production studio Fifth Season in a deal valued at just under $70 million, according to a new report. That makes additional seasons of the fan-favorite show — and spinoff series — more likely.
YouTube is the new TV. Now finally on Apple Vision Pro.
Starting today, an official YouTube app is available on the Apple Vision Pro, allowing you to watch videos on a theater-sized screen with immersive visionOS Environments.
Every video on YouTube is available in the new, standalone visionOS app, including standard videos, 180° videos, 360° videos, and YouTube Shorts. And on the newer Apple Vision Pro with the M5 chip, you can even watch YouTube videos in 8K.
We are proud to report that we have a new record for our installed base with more than 2.5 billion active devices. -Tim Cook
2.5 billion active devices follows the announcement of 2.35 billion active devices a year ago, a growth of 150 million devices in one year. Let's examine some of the implications.
By my estimate, Apple sold about 250 million iPhones, 23 million Macs, 40 million Watches, 70 million iPads. Other devices including Apple TVs, Apple Vision Pro, Apple HomePods may add another 10 million units. Therefore the total number of "connected" devices sold is around 400 million/yr.
Adding 150 million to the active base in one year implies that 250 million devices are replacements, many surely are reused but also at least a third (37.5%) of units sold are expanding the base. This is reflected by management's occasional mention that "nearly (or, alternatively, over) half of customers who purchased a <product> being new to the product".
In the last quarter and for quite some time, <product> has been the Mac, the iPad and Apple Watch. If we use my estimates of units sold during the full year that means 17 million Macs, 20 million Watches and 35 million iPads were sold to new users. These add up to 72 non-iPhone new devices in use. That suggests about 78 million new iPhone users.
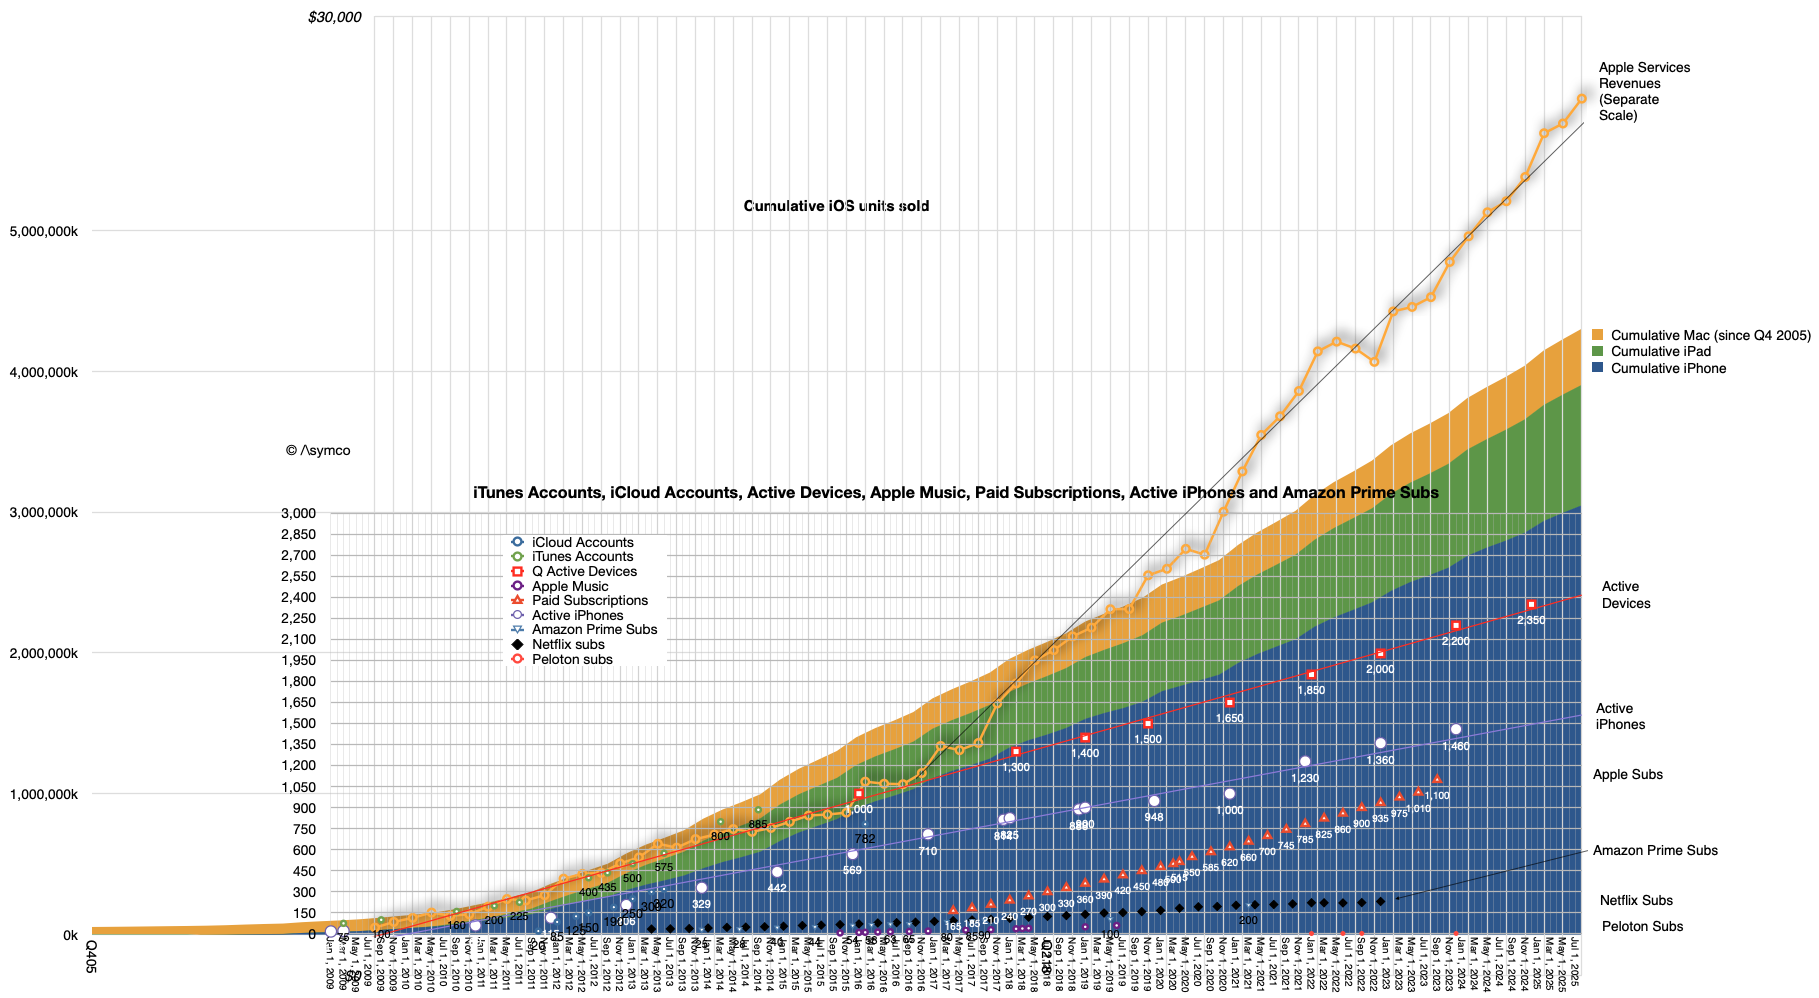
How does this compare to the following pattern:
The line to focus on is the red with square points. "Q Active Devices" is the history of what Apple calls "Quarterly Active" devices or those which ping an Apple server at least once a quarter. The data appears to be linear, or the growth is about 150 million per year at least since 2016. Historic data on the iPhone is also shown with a blue line. That is also consistent with about 100 million new iPhones in use every year. This is a bit higher than the 78 million bottom-up analysis of new users. I'd argue that Watch numbers may be a bit too high and perhaps iPad as well.
The mix is a matter of debate but overall this consistency allows for some confident forecasting.
The iPhone will reach 1.7 billion active users by this time next year.
There will be three billion active devices by early 2029.
Services, which is shown in the second graph is clearly correlated to active device growth.
The consistency in active device growth is far more important than device sales in a particular period and determines the value of the company.
Knowing this, here are some additional observations:
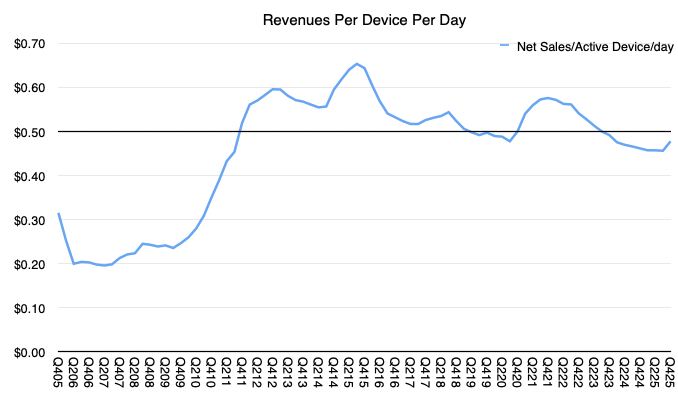
Yearly revenues per active device are $129, services revenues per active device are $45 for a total revenue per active device at $174/device/yr. That is equivalent to 48c/device/day. Data shows that daily revenues have been an average of 53c/device/day for 59 quarters. My rule of thumb is 50c/day per active device is a good estimate for Apple's revenues, and estimate that I have been holding for over 14 years.
There are additional implications. With a base of 1.65 billion iPhones, and knowledge of replacement vs. new-to-product/switcher growth what is their average lifespan and thus replacement rate and therefore what is the average selling price?
One of the biggest puzzles of my adult life was this question: Why do people pay to attend live events when broadcasts and/or recorded versions are free? Not only do people tend to pay for live events, the costs are extraordinarily high. Earlier this year, 32% of planned concertgoers expected to spend $500 or more attending events, a LendingTree survey found. The survey also revealed 38% of concertgoers were willing to pay more for better seats, up to $328 for their favorite artists. The average price for a Drake concert is $600 and for Taylor Swift it's $2,424(!) Adding travel, accommodations, opportunity costs and transactions costs, the live event costs can easily run in the thousands per event.
And it does not end there. Live events offer an inferior experience. The seat location can be far from the action, acoustics can be poor and there is usually a lack of multiple angles or replays (in the case of sports) to see the details of the action. Often, spectators have to watch large screens in order to actually see what is going on. In other words, they pay a great deal to watch the event on TV even if they are at the event.
This puzzle came back to me also when attending the Apple Vision Pro launch at this year's WWDC. Those of us watching it in person basically watched what everyone at home saw, but in a degraded outdoor screen experience complete with sun glare and wind noise. Of course, we also got to see the device up-close and some even got demos. But this was the exception. Most spectators at live events do not obtain access to the talent. They may get to chat with friends or meet new ones but that is entirely haphazard.
Now I know all the arguments about "presence" and the feeling of being a part of the event itself and the sense of occasion and shared experience that it generates. It's something movie theater operates are trying to also convey even while they are screening recorded content. Clearly there is some value to this. But $3000 of value?
Let's then assume that, since the market is always right, there is $3000 of value in a premium live event. Consider a season pass to top sports leagues. Consider concerts, night clubs and band gigs. Then there is the line of business that I happen to also offer: live talks and conferences. How does technology affect this particular form of content?
Well, I believe Apple has an idea. Apple, after all, invented the product-release-as-an-event. That is, Apple created event marketing–and everyone followed. Apple was first to know the value of the technology show business and in particular live show business.
But delivering such businesses is not reliably profitable. The more reliable business is ticketing–an annoying racket. Putting on the show is touch-and-go. It might be sustainable until costs rise due to the talent asking for a greater share, or other service providers following suit. It's also difficult to stay on top as crowds are fickle and tastes change.
This is why I think Apple's Vision Pro is at least partly aimed at "performance conveyance," rather than the more crude "recorded media playback" job to be done. If this is so, then the business model that makes sense is to license rights to performances and deliver them. The same way that licensing rights to recorded content and delivery was the business model of screen-based devices.
So what does Performance Conveyance mean? Well, we have to look at performer quality, brand and the experience itself. If they come together well then Apple can say they deliver on the job of "live". And if so, then they can charge accordingly. Hence, whereas Apple Music is $10/mo. or Apple TV is $10/mo. or a bundle of services is $30/mo., then why wouldn't Apple Live be $300/mo?
If not subscription then perhaps à la carte payment for events: sports, concerts, et. al. In combination it's not unreasonable that Apple with Spatial Computing and Vision will offer a new tier of service bundle pricing with an average revenue per user of $3000/yr.
That would certainly solve my puzzle.
[Edit: I forgot to mention the value of theme parks and (ersatz) tourism in general. Clearly this is such a powerful idea that industries have been created around it.]