Asymco

Asymmetric Intelligence

Research

  1. The cognitive illusion that is iPhone n-1

    Research · 28 comments

    How do you think about the iPhone 3GS after the iPhone 4 is out? I have a hypothesis that it's not what it seems.

    The standard logic is that the 3GS (which I will call the n-1 where n is the current phone version) is a lower-priced leftover that covers a lower price point and expands the market.

    I think it's designed to give the illusion that the iPhone 4 is actually more desirable steering more potential buyers to the new (nth) phone.

    To illustrate I'm going to call upon the wonderful example given by behavioral economist Dan Ariely at the TED talks.

    Imagine I give you a choice: Do you want

    • (a) "a weekend to Rome, all expenses paid" or
    • (b) "a weekend in Paris, all expenses paid"?

    They are different but compelling choices. Perhaps a survey would find these two choices equally popular.

    Now imagine I added a third option to these two that nobody wanted:

    • (c) having your car stolen.

    It seems a strange choice, because how could having your car stolen in this set influence anything? Obviously (a) or (b) would be the only compelling options. But what if the option for having your car stolen was not exactly like this. What if the third option was

    • (a-) "a trip to Rome, all expenses paid but no free coffee with breakfast."

    Given that you can have Rome with coffee, why would you want Rome without coffee? It's an inferior option just like having your car stolen.

    But, the moment you add Rome without coffee as an option, Rome *with* coffee becomes more popular and people choose it much more often. Having Rome without coffee makes Rome with coffee seem superior, not just to Rome without coffee but even to Paris.

    Adding (a-) to the set of choices (a) vs. (b) makes choosing (a) much more likely.

    He goes on to describe a subscription offer from The Economist which, by inclusion of an inferior option, steered people to choose a more expensive option.

    My point here is that I hypothesize that the iPhone n-1 (Rome without coffee) is an inferior option to the iPhone n (Rome with coffee) and that it steers more people to choose iPhone n not just over iPhone n-1 but over the competition (Paris). Of course the inferiority of iPhone n-1 is offset by its lower price, but I put it that the difference of $100 is not that great in the eye of most users when they see the difference with the new model. The price difference does not make the iPhone n-1 look all that great. It's still Rome without coffee.

    We don't have precise stats to prove that iPhone n-1 is ignored as an option, but the ASP numbers never seem to drop. They seem to indicate that the overwhelming number of iPhones sold are the top of the line. Therefore the presence of an inferior option does not dilute the average selling price, but, in fact, increases overall volumes of the top product.
  2. IBM Survey: The cell phone is no longer a gadget – it’s what IT is going to become

    Research · 3 comments

    “In all areas of software development, mobile computing is seen as the number-one hottest IT opportunity next year,” said Jim Corgel, an IBM general manager of independent software vendors and developer relations who was involved in the survey. “Not only will mobile spike to the forefront, but by 2015, respondents said it will dominate everything. The cell phone is no longer a gadget – it’s what IT is going to become.”

    via IBM Survey Says Mobile Apps Will Dominate Enterprise - Venture Capital Dispatch - WSJ.

    Developers are usually not very good at predicting specific business winners or losers (to prove this consider why developers don't spend their energy and earn their living picking tech stocks instead of writing code.)

    However, developers are very good at spotting long term technology trends. It was developers who championed the early internet and it was developers who saw potential in social networking. To see a survey of developers confirm that mobile devices will dominate IT, in contradiction to most incumbent strategies, is encouraging.

  3. How many iPads next year? Analyst Sees 45 Million IPads In 2011

    Research · 19 comments

    The contact, says [Ticonderoga's] White, shipped more than 6 million parts to Apple during the third quarter of the year and expects to ship 7 million more in the fourth quarter.

    Since Apple uses one unit of this particular component in each iPad, that adds up to shipments of 13 million iPads in the second half of 2010. For 2011, the contact believes Apple will sell as many as 45 million iPads

    via Analyst Sees 45 Million IPads In 2011, Next Gen IPad Launching Soon - Elizabeth Woyke - Mobilized - Forbes.

    These numbers are not unreasonable. I expect about 35 million next year, though that could go up considerably depending on what we hear about last quarter.  We only really have one data point so far meaning the data set is to double in a few days.

  4. The strategic tension inherent in the iPhone franchise

    Research · 25 comments

    I don't write product reviews and I don't pass judgement on individual products but I do own and test various products. For example I have the Android powered Samsung Galaxy 5 (GT-I5500) and the experience is, in my opinion, better than for recent Symbian phones but not as smooth as for Apple's products.

    But that's not what this article is about.

    It's about the price. The price for the Samsung is one third that of the iPhone 4 (both devices unlocked and sold in Europe with a 23% VAT). It was also purchased in a department store with as much hassle as buying a pair of gloves.

    When it comes to the product, it may be a fair trade-off: one third the price for one third the product. The specs are not only worse but the whole experience is rougher and cruder. But that "one third the product" may be just good enough for a large population of users who are now satisfied even with "one tenth the product". The price point should be evaluated as a valid threat.

    But Apple can respond. It's not like this is asymmetric competition. As the iPod shows, Apple can make money with low end products. Easily. Is this entry price point (€200 unlocked) something Apple should cover? My answer would be an unqualified yes.

    For operator distribution, the subsidized price combined with a high-end offering is by far the best marketing mix (price, promotion, positioning, etc.) However, for non-operator distribution, a lower spec unlocked device sold through tens of thousands of points of purchase (like the iPod, and soon, iPad) makes a lot of sense from a platform point of view.

    These two channels are often in conflict due to subsidy and exclusivity clauses. This conflict makes the decision to ignore the non-operator channel compelling. The economics for the operator channel are always going to trump the non-operator channel. But as the platform expands across geographies and income segments not covered by the operator-subsidized channel, these populations will need to be addressed.

    So this is the inherent strategic tension for the iPhone franchise: Whether to use the iPhone brand to enable ubiquitous mobile computing outside operator channels, or use iPod/iPad as a complementary but separate brand to engage in an orthogonal attack.

    I suspect the decision has been made. We will observe the consequences next year.

  5. The symmetry of share shifts in mobile phones

    Research · 49 comments

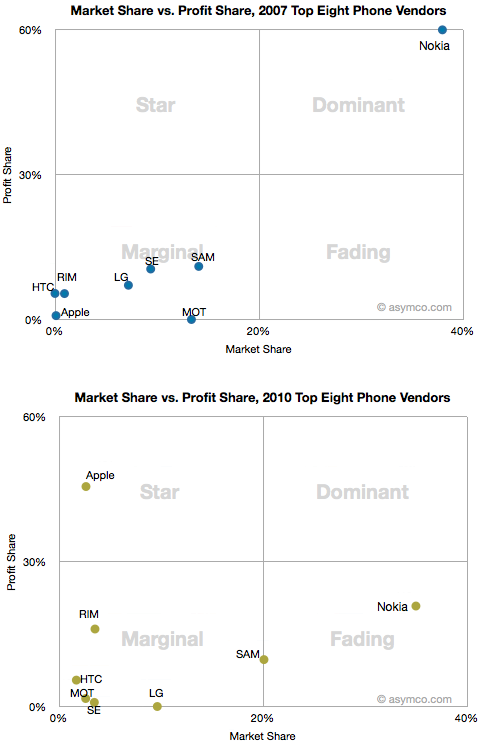
    Thanks to a reader's suggestion, I took another look at the profit and market share data from the mobile phone market overview posted last quarter. This time to compare the vendors on two dimensions at the same time.

    I plotted the vendors on share of market and share of profit axes in two different points in time: Q2 2007 and Q2 2010. I further broke the chart into four quadrants as shown:

    I chose to label the quadrants to indicate the possible categorization of the companies.

    • Dominant: large market share and large profit share
    • Star: low market share with large profit share
    • Fading: high market share with low profit
    • Marginal: low market share and low profit

    It's interesting to note the shift over the time period of the eight vendors. Whereas Nokia moved from Dominant to Fading, only Apple rose from Marginal to Star. The Marginal players dispersed their placement with Samsung moving laterally toward Nokia while RIM followed in the Apple trajectory and increased profit share while maintaining relatively low share.

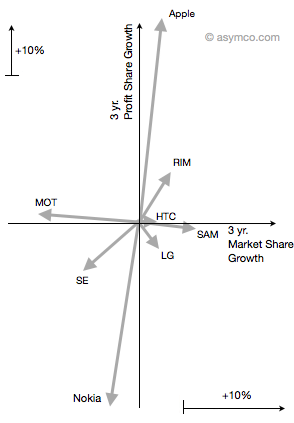
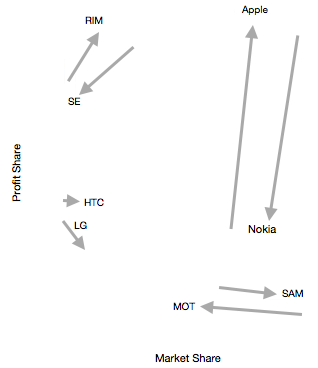
    Thinking about motion around these two dimensions could be reduced to a vector model. If each vendor is represented by an arrow showing direction and distance moved, we can compare each vendor vs. a symmetric competitor which might account for the loss or gain of share.

    The vectors can be paired as follows:

    Although the data does not contain all market participants, the shifts in share are quite closely conserved with the vector magnitude (arrow length) and angle (direction) paired. Note how Nokia and Apple swapped Profit without too much impact in Units volume. Similarly, RIM and Sony Ericsson traded profits and volumes quite symmetrically. Samsung also took volume while Motorola lost it. HTC and LG did not change positions dramatically.

    Finally, moving all vectors to the same origin leads to this view of share gain/loss over three years in two dimensions:

    It becomes quite easy to see who the winners and losers are and by how much.

    This model is only an observation of the shifts in market power and is not conclusive about where share was gained or lost, however there is compelling symmetry which also matches the intuition of  observers.

  6. New Comment system in use

    Research · 23 comments

    I activated IntenseDebate comments. This allows many features (see below) including the editing of comments.

    There might be some issues or bugs that will be discovered only once the system is in use so let me know what you observe.

    The key features claimed are:

    • Reply By Email
    • Users Reputations
    • RSS Feeds
    • Widgets
    • Threaded Comments
    • Tracking and Notifications
    • Profiles
    • Comment Voting
    • Social Traffic Drive

    Readers will be able to follow the conversation within the comments better with comment threading. Comment threading makes reading comments manageable and returns the value of insightful comments to your site. Not only will your readers be more likely to comment, but they'll be more likely to return to leave multiple comments as the debate gets going. Comment notification emails alert your readers when someone has responded to their comment and makes responding a piece of cake with our Reply By Email feature.

    In addition, your readers will be able to vote on the comments made, and gain reputation points giving their comments more authority. Readers can subscribe to comments through our support of various RSS readers. Readers can follow their friends as they comment their way across the Internet. Not to mention that Intense Debate is a great tool for promoting their own blogs.

  7. Ticonderoga sees over 15 million iPads in 9 months

    Research · 13 comments

    White contends iPad could be “one of the most coveted gifts” this holiday season; he sees the company selling 7.1 million units in the September 2010 fiscal year, with 19.9 million in 2011, and 25.8 million in 2012.

    The analyst said his target is based on 20x his interest expense/income adjusted calendar 2011 pro forma EPS estimate, plus net cash of $49.43 a share.

    via Apple: Ticonderoga Starts With Buy, Street-High $430 Target - Tech Trader Daily - Barrons.com.

    If Apple hits 5 million in the just ended September quarter and 7 million in the December quarter, we're looking at over 15 million iPads in nine months of sales. The iPhone took about 20 months to reach the same level.

    If the iPad is ramping up more than twice as fast as the iPhone, (aka the Jesus Phone) what does that make it?

    See also: iPad Death Watch : AAPLinvestors

  8. AT&T Set to Release Multiple WP7 Devices, T-Mobile anchors launch event

    Research · 6 comments

    As of two weeks ago, AT&T was to be the launch partner for Windows Phone. AT&T had been expected to unveil phones from HTC, Samsung and LG, according The Wall Street Journal.

    Windows Phone Thoughts: AT&T Set to Release Multiple WP7 Devices.
    Today we hear that the invitations for the October 11 launch event have gone out, without mention of AT&T:

    "T-Mobile reps will be present for device showing and their service offering discussion," according to the invite.

    Can't wait for the spin.

  9. iPad lead seen as 'overwhelming'

    Research · 37 comments

    Chris Whitmore predicted 2.0 million iPads would be sold in 2010 soon after the product launched. (asymco | Analysts predict iPad sales)

    More recently, Chris Whitmore writes for Deutsche Bank:

    "We believe Apple's lead in the tablet market will prove difficult to close by the onslaught of competing products coming over the next several quarters," he writes in a note to clients issued early Monday. "Ultimately, we expect the slew of upcoming competition to fall flat from a user experience standpoint while struggl[ing] to materially undercut the iPad on price."

    How far ahead is Apple (AAPL)? According to Whitmore:

    12-18 months in content (see chart)

    2 or more years in terms of other media acquisition and integration via iTunes

    Untold dollars in terms of component pricing

    via iPad lead seen as 'overwhelming' - Apple 2.0 - Fortune Tech.
    Compare this fresh (re-)assessment with the following points I made in May of this year:

    The iPad comes with an even bigger value chain [than the iPod] bolted on: the App Store. Apple is flogging not just an “app player” but also a new way to develop and distribute software. If you cut “music” and paste “apps” you see the immediate parallel between iPod and iPad. The app ecosystem will quickly grow to be larger than the music ecosystem with the mobile software business already eclipsing the music business.

    ...

    So the iPad challengers face five daunting obstacles:

    Recognition of a threat from a seemingly benign product

    Execution on hardware against the best integrator on the planet

    Execution on software against a new UI metaphor fortress surrounded by a patent moat

    Integration of hardware and software to a sublime whole

    Re-building a value chain for which they have no handle vs. a broad and deep existing universe of app/content creation distribution and consumption enjoying logarithmic network effect value.

    asymco | Will Apple rule the iPad market? (part II)

    Welcome to the club, Chris.

  10. Goldman downgrades Microsoft, blames iPad

    Research · 22 comments

    "We believe the intrinsic value of shares cannot be unlocked if the status quo remains, and we have increased caution near term on a more elongated PC refresh cycle, combined with the newer threat of notebook cannibalization from tablets, where Windows does not yet have a presence," write Goldman Sachs analyst Sarah Friar and associates in the introduction to the report.

    More advice about what to do about this in the linked article: Goldman downgrades Microsoft, makes case for major overhaul.

    I'd skip over the recommendation to break up the company but the observation that Microsoft might face earnings threat from iPad is provocative. Usually it takes a few years for the incumbent to feel pain and react. The pain might be sooner than expected though the reaction might still take some time as the Windows Phone response to iPhone is taking its sweet time.

  11. Updated estimates for Apple's fourth quarter earnings

    Research · 12 comments

    We expect revenue to be about $18 billion compared to $12.2 billion in the September quarter last year. We expect gross margins to be about 35%...

    We are targeting EPS of about $3.44.

    via Apple Inc. AAPL Q3 2010 Earnings Call Transcript.

    I've updated my estimates from the July forecast as follows:

    • iPhone units: 12.2 13 million (65% 77% growth)
    • Macs: 4 million (30% growth)
    • iPads: 3.3 5 million
    • iPods: 9.4 9.7 million (-5% growth)
    • Music growth: 26.7% 25%
    • Peripherals growth: 21% 15%
    • Software growth: 8%
    • Total sales: $19.0 $20.5 billion (56% 69%y/y growth)
    • GM: 42.3% 40.4%
    • EPS: $4.78 $5.00 (73% 81% y/y growth)

    The main news items that affected the changes in estimates were:

    1. iPhone continues to be supply constrained.
    2. iPad supply nearly matching demand though not yet rolled out in all markets
    3. new iPods look compelling though offset by back to school promos

    Follow other estimates at Deagol's site:
    Deagol's AAPL Model: Fiscal 4Q 2010 Final Estimates