Asymco

Asymmetric Intelligence

Research

  1. The parable of the the PDA: predicting the smartphone's future

    Research · 55 comments

    When reading the comments disputing the possible end of the voice-phone era I'm reminded of similar comments disputing the end of the PDA era.

    Although the Apple Newton pioneered the market in 1992 and John Sculley came up with the acronym, the Newton did not sell in significant volumes. It wasn't until 1997 with the Palm Pilot that the PDA market took off. Microsoft quickly followed with a licensed OS based on Windows CE. In 2001 Microsoft launched the Pocket PC brand to cement its attack on the PDA market. The first phones using a Microsoft OS were using something called Pocket PC Phone Edition. The first Nokia smartphones (Communicators) were built like mobile PDAs.

    The logic was quite compelling. The original PDA was built to mobilize contacts, calendars and notes. They replaced bulky paper organizers and seamlessly synced to PC productivity software like Outlook. It was a compelling product in the US where small business customers needed to keep track of hundreds of contacts. Users could even 'beam' contacts to each other via infrared. The idea of adding a phone function to the device made sense insofar as contacts could be immediately dialed from the contact app rather than typed into another device's phone keypad.

    By the early 2000's PDAs were forecast to sell by the hundreds of millions. There were millions of dedicated users who downloaded apps and thousands of developers being courted by platform builders. Palm even invented the word "ecosystem" as it refers to mobile platforms.

    However, I remember reading sites dedicated to this community and there were many people who rejected the concept of a PDA with an integrated mobile phone. They liked the fact that the PDA was not bundled with a phone plan. They upgraded PDAs in a different cycle from phones and besides, phones are for talking and PDAs were for something else.  It was even more difficult to justify the conflation of the two products when considering the corporate purchasing of PDAs. PDAs were procured by IT departments and phones came with contracts that were managed by a different department.

    What's a device vendor to do? The most avid customers of PDAs did not like the idea of burdening the product with a phone. RIM was doing its thing with moving pagers to include voice, but that was a different job to be done. The story is picked up here by this comment:

    I was hired by RIM in 1999 just before they began work on their first phone .... Coming from a two-way pager background, RIM decided that phones should have two-way push synchronization of pretty much everything that Exchange provided along with a limited WML browser. The general thought was that phones would never have sufficient power density or radios sufficient bandwidth to allow anything more. That was incredibly predictably wrong, but it's how things went down.

    Along with RIM was Ericsson, Palm, Motorola, and Qualcomm. Motorola came from a similar background as RIM and went on to build very similar devices. Both Nokia and Ericsson had come from phones and had decided feature phones should have far more sophisticated PDA functions. Palm started with PDAs then moved to the phones, but adamantly dismissed ideas like wireless synchronization for years making their first attempts at smart phone far more like early Nokia Communicators than early Blackberrys...

    So the point is that all these companies were fighting over what amounts to overgrown PDAs with phones and wireless stacks strapped on. Everyone assumed power density was no where even close to what was needed for general computing, that a full featured browser and heavy duty Internet services were impossible due to bandwidth and latency. Take a look at how our Java expert groups named standards, how people at the time talked about what features smart phones should have, and its clear that no one thought an iPhone was possible. Even Danger, which eventually went on to work on to create Windows Phone 7 and Android, was just working on a better Blackberry.

    via: shacknews

    But what does this have to do with the future of voice-phones?

    The problem is that the vendors that lost this game failed because they listened to their customers. Like with PDAs or with the original mobile phones or first generation of PCs, early adopters are not the audience that should be consulted on how to improve the product.

    Early Windows Mobile users were ecstatic about the platform and rejected new UI metaphors because they wanted a "mobile Windows". Palm fans stuck with the PalmOS even though it was well past its shelf date in the Treo because they treasured the original PDA metaphors.

    Every company paying attention to the market in 2005 would have been eagerly pursuing corporate buyers of PDAs and aiming complex products at enthusiastic PDA users.

    And yet, non-consumers should also not be trusted with their opinions. Most early surveys would show that the vast majority of consumers found that mobile phones were not good value for the money. Later the same audience would declare that smartphones were not worth buying.

    There are many voice-only users in the world who are happy with their products and not interested in any new options.

    So what's a marketer to do?

    If you can't ask early adopters and you can't ask non-consumers for hints then where can clues be found?

    What history shows is that consumers have been happy to trade up to technology that offers more option value.

    • Television went from cheap/free over-the-air broadcast with limited channel options to expensive cable with large option value in channels. Even if most of those options went unused, they are still valued.
    • Telephony went from low cost reliable landlines to high cost, less reliable but with much more option valuable mobility. Having the option to call a person vs. calling a place (where a person might be) changed the calculation of whether you make the call. Calling became much more popular.
    • Data as well went from metered dialup to unmetered high option valued broadband. From a luxury, to the least likely service an unemployed user might give up.
    • Emerging market users hungered for mobile phones even though they cost more than several months' wages because they gave access to information and increased the option value of their labor.

    Each of these huge technology transitions came associated with increased costs for the consumer, but that cost went toward the purchase of a far larger option value.

    The problem is that users cannot calculate option value in their minds when faced with a market research questionnaire. How can they envision all the ways they would use a new product they've never used before? How can they "get it" without observing it in use or spending time thinking of "how they would use it" or asking someone who tried it? In a nutshell, users are willing to pay for option value but can't envision or quantify this value without observing a finished, polished product in use.

    This is the problem faced today by branded phone vendors. Asking or observing current users of smartphones does not provide any incentive to sell low end versions. Asking or observing non-consumers seems to indicate no interest in newfangled complex or costly products.

    But the calculus that must be made is one of option value. Does the new product offer significant option value? Will this option value be easily realized? This is not easy to determine, but it's a method that is far more promising than asking users their opinion.

    The PDA was not a product that was introduced by the incumbent computer vendors because their customers did not ask for it. Once established, the PDA was not replaced by a product that PDA users asked for either.

    Smartphones are following this well trodden path. The high end devices are evolving into computer replacements nobody asked for (but everybody will use). The low end products are adding data option value to voice-oriented users who never asked for anything more.
  2. Apple has accepted nearly 400,000 apps in 2.5 years

    Research · 12 comments

    There are now well over 390,366 apps in the app store[1]

    via 10,000 Apps! - Presented by 148Apps.com :: 10,000 iPhone and iPod Touch applications in the iTunes App Store.

    Since launch, December has been the month with the most apps added. In December 2008 3,800 apps were added, in 2009 25,517 and in 2010 it looks like we might get nearly 30k new apps.

    That amounts to nearly 1000 new apps per day.

    It also seems that 500k apps will have arrived by mid-2011. As the production of apps continues to grow one wonders if this new medium will turn out to become more popular than recorded music in terms of creative output.

    [1] That includes about 65,000 inactive apps.

  3. The $85 Smartphone and the imminent extinction of non-smartphones

    Research · 136 comments

    In a recent article I made the claim:

    My bet is that by the end of 2012, it will be hard to find any branded phones which won’t run a smartphone

    I also showed how pricing has evolved over the last three years.

    Two days later an article in Fortune's Google24/7 blog highlighted the possible price points of low-end smartphones:

    I had a chance to speak with Jim Tran, VP/GM – Handset Line of Business for Broadcom, who was able to elaborate on the details of the new processor and what it meant for the industry.  Here are some of Broadcom's bullet points:

    The BCM2157 baseband, since it combines many functions on one chip, is able to run more efficiently, meaning less battery power will be needed than on current basic handsets

    Low-cost, low-power, 65 nm digital CMOS process means the silicon will be cheap

    The dual-core processors will run at 500-800mhz.

    Supports portable Wifi hotspot and Android 2.2 and up

    But the kicker is the price.  Tran says that phones made from the BCM2157 chipset will retail for under $100 and may dip as low as $75.  Those devices should debut in just 3-6 months (and we might hear about them next month at CES)....

    To be clear, That sub $100 price is not the cost of materials, it is the suggested retail price after the manufacturers (and carriers) have taken their profits.

    via 2011 will be the year Android explodes - Google 24/7 - Fortune Tech.

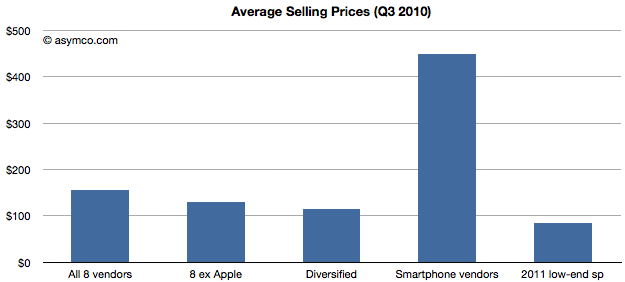
    My own data shows that the average selling price for the top eight phone vendors for Q3 of 2010 was $156. Smartphone-only vendors were charging $450 on average and diversified vendors selling both smart and non-smart phones were charging $144 on average.

    Nokia's ASP for its entire line-up was $88 (spread over about 84 million non-smart and 26.5 million smartphones).

    What strikes me about the claim from Broadcom is that a $100 retail price for a smartphone implies an ASP of about $85 or so (assuming $15 or a very modest 18% channel mark-up).

    That means that a smartphone could be built using this chip which would have nearly half the average price of all branded phones sold last quarter.

    It would also be priced cheaper than the average price Nokia charged for all its phones (75% of which were non-smart phones.)

    And this type of phone could be available not in three years in three months.

    The chart above shows how prices could collapse.

    Of course, low price is not the only condition for the widespread substitution of smart devices in vendor portfolios. But it does take away a significant objection. It no longer seems far-fetched to say that in another two years the price points for smartphones will be low enough to make them marketable in all markets. This may in fact be true next year.

    I suspect that non-branded vendors will lead the way and make these devices widely available in emerging markets. The question will then be entirely up to the branded vendors whether they will follow or will they try to market dumb phones vs. smart phones at similar price points. Will buyers opt for a branded device with no ecosystem or unbranded device with the Android ecosystem?

    It becomes harder to envision any reason why non-smart devices will earn positions in portfolios two years from now.

    Note that I'm not suggesting that the market for high-end smartphones is threatened yet--there is still a lot of innovation that still needs to happen to shape that market into one of mobile computing (vs. mobile phoning).

    Instead, what I am suggesting is that the bottom of the phone market is very vulnerable to becoming smart. This may sound like an odd sort of disruption, but it's a very sinister threat to companies who are in the business of selling brands and not platforms.

  4. Apple now trading at 10.5 times Deagol's fwd EPS estimate ex cash

    Research · 54 comments

    Apple now trading at 12.9 times Deagol's fwd EPS estimate (10.5x after excluding cash).

    Deagol's AAPL Model: Fiscal 1Q 2011 Final Estimates.

    The revenue growth rate is expected to continue at 66% (following 61% and 67% for previous two quarters). Earnings growth is also expected to be maintained at 70% as it has been over the full calendar year.

    Apple continues to be one of the cheapest stocks in the S&P 500 when measured by growth multiples.

    After years spent thinking about it, I can only conclude that the company's depressed valuation is due to the uncertainty surrounding the CEO succession plans.

  5. Microsoft's mobile effort: back to the future?

    Research · 41 comments

    Windows Phone 7 launched on 10 devices over 60 carriers in over 30 countries with 1.5 million of channel inventory in 6 weeks. Given the breadth of distribution, that number is not huge, amounting to less than 10k phones per operator.

    Curiously, Windows Mobile was still selling in significant volumes last quarter. Maybe even higher than WP7 is selling now. In Q3 2009 Canalys reported 3.6 million WinMo units sold. In Q3 2010  Gartner estimated 2.3 million were sold through to end users. Even nine months ago Windows Mobile was running at 3.7 million units or over 1.8 million every six weeks.

    Microsoft also announced they have 18,000 developers with 4,000 apps on the WP7 marketplace. That's one developer for every 83 devices in inventory.

    Microsoft's Achim Berg:

    our numbers are similar to the performance of other first generation mobile platforms...

    We're comfortable with where we are, and we are here for the long run; Windows Phone 7 is just the beginning.

    In terms of first generation platforms, I assume he is referring to Android and iPhone. That claim of similar volume growth is perhaps a bit too optimistic. However, he's very wrong about WP7 being the beginning for Microsoft's efforts in mobile. Not even close.

    Microsoft has had mobile software products in the market for over a decade. In 2003 Gartner declared that Microsoft would sweep Symbian aside. In 2006 they were the odds-on favorites to win the mobile platform game on the basis of developer support.

    Microsoft's Windows Mobile was selling more in 2003 than Microsoft's Windows Phone is selling in 2010. At the time, Microsoft also boasted of having a huge developer base (larger, in fact, than the number of users of the product; their .NET developer base being counted as mobile developers.)

    Furthermore, prior to the launch of iPhone's App Store, Microsoft spokespersons scoffed at the idea that Apple could field a catalog larger than Windows Mobile which led with over 13,000 apps in August of 2008.

    Dragging out these old figures isn't meant to deride Microsoft. They were not alone in failing to capitalize on early leads in mobile. Palm, Nokia, DoCoMo and Qualcomm all failed. RIM is arguably failing as we speak. Some have argued that Apple is also about to be undone by Android.

    The point is that dramatic, violent change was possible even five years after foothold markets were established.

    The question for today is: Is it still possible? Can a new platform still gain traction?

    Microsoft is clearly betting that it can. Their seemingly quixotic attack on the market can only be justified on the basis that it's still early days. They must reason that un-penetrated markets are huge and that the existing platforms are not sticky enough to prevent switching.

    At least one analyst agrees. IDC made the forecast that 32 million “Windows Mobile/Phone” devices will sell during all of 2011. I took issue with those forecasts at the time but if they deliver that volume they will get around 10% share, enough to stay on the map. If they don't then Microsoft will look more like Mobile Zune than Mobile Windows. The stakes are high.

    So even though they may have airbrushed Windows Mobile from history, Microsoft's current strategy is a direct consequence of them having failed with a seemingly strong platform.

  6. Is HTML5 a Flash in the pan?

    Research · 31 comments

    When Apple promoted HTML5 as an alternative to Flash, the value was said to be in being an open standard, and in having better efficiency for device-based execution.

    The problem is that there are no authoring tools for HTML5. Flash is popular because it's fairly easy to kick start the creative process. You buy the tools from Adobe for a few hundred dollars and begin to tinker. With HTML5 you need to be a programmer, read arcane documentation, search for sample code and manually integrate results into publishing systems. That's bush league.

    iAd Producer narrows the gap a bit.

    The bigger question that I struggled with is whether web apps are competitive enough. The absence of tools is a damning accusation that they aren't. Note that Apple is first introducing production tools for iAd, not for web apps in general nor web content in particular.

    So why isn't there an iWeb-like tool to allow consumers to design web sites (for MobileMe Galleries for example) which benefit from HTML5? At the other end of the spectrum, where are the Apple equivalents to Adobe's Flash Professional (with CS5 integration)?

    The tools for HTML5 are just not there. Tools are the first things needed to build an ecosystem. Is their absence due to a lack of demand or are there no skilled toolmakers outside of Adobe?

    When the market is failing to deliver a solution, I question the need for the solution in the first place. It's also worth while to follow the money: Adobe makes money only on the tools for Flash, not on distribution of content. For anyone to disturb Adobe's franchise, it's tools that need to be put forward as alternatives. Tools are not easy to build. Are the incentives simply not there?

    I hope iAd producer is the first in a series of tools from Apple to build an HTML5 ecosystem. Whatever the future of web apps is, it's coming very slowly. No wonder Flash is still a viable business for Adobe.

  7. Poll: How would you like to get Asymco data?

    Research · 7 comments

    I am preparing a productization of the data underlying the models I use. I am working with Timetric.com to build the product and we are considering several options for packaging and pricing/access.

    The first question I have is about how readers would like to see the data. I put up a poll to the right.

    More questions will follow.

  8. What has Android done for Apple?

    Research · 44 comments

    One of the most popular themes running through the mobile phone industry this year has been the unprecedented growth in Android adoption. I've argued that the adoption was initiated on the supply side by vendors and operators, but demand has certainly manifested itself.

    Android is almost viral in the way it spreads. With no constraints on intellectual property, pricing, contracts, modification or terms of distribution, the incentives to push product out are phenomenal. It even works, mostly.

    One hypothesis of the consequences of this viral adoption is that there will be a "commoditization" of smartphones with rapid price erosion to follow. This in turn might even lead to lower margins for Apple and RIM and most major vendors, including those selling Android itself.

    In order to test this hypothesis, we need to look at what has been happening to prices. If prices have started tipping down at more than their usual rate then maybe commoditization is happening.

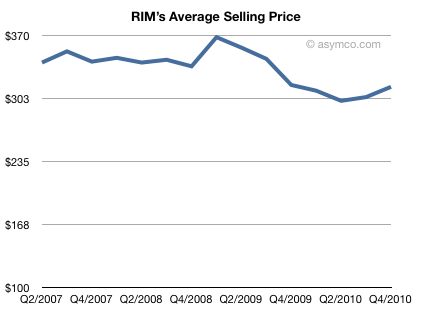
    We can begin this test with the industry's canary in the coal mine: RIM. RIM has been struggling for growth in the very market where Android has been growing the fastest. Is RIM's pricing under pressure?

    Interestingly, no. Their ASP (average selling price) decline, from an average of $350 to $310 in late 2009, came before the Android avalanche. During this year, the ASP has held steady, even rising in the last two quarters to $315 while Android activations reached 300k/day.

    So I don't see a big problem with RIM, yet.

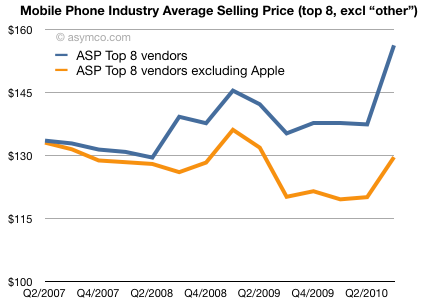
    What about the industry as a whole? Can we see patterns that suggest imminent commoditization? Using the top 8 vendors (Nokia, Motorola, Samsung, Sony Ericsson, LG, RIM, Apple and HTC) and using volume-weighted ASP (total device sales divided by total units sold) we have the following chart:

    Since the second half of 2007 the "industry ASP" (blue line) has actually increased. This is even though there was a huge recession in the middle of the time period.

    This should be only slightly surprising. If you suspected that the iPhone may have a lot to do with that, you would be right. If you remove Apple from the mix, the second line (in orange) shows that the top vendors (ex-Apple) had some, but quite quite mild erosion (from an ASP of $133 to $129)[1].

    This is far milder than what's been happening in the PC sector where prices are dropping catastrophically (According to NPD the average selling price of all Windows portable PCs has fallen from $659 in Oct. 2008 to $519 in Oct. 2009).

    So Apple was a big contributor to the industry increasing its pricing power.[2] but even without Apple the industry has been holding on.

    But is this just a lull?

    Is Android going to stop the growth?

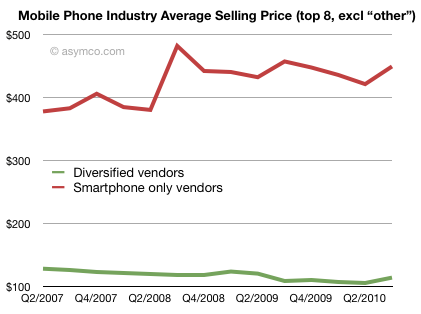
    We can look at the pricing data one more way: If we separate the eight companies into two cohorts, the "diversified" vendors who sell both smartphones and regular phones vs. the "pure play" smartphone-only vendors, we get the following price history.

    What is happening is that the diversified (Nokia, Samsung, LG, Sony Ericsson, Motorola) saw modest price declines (from $128 to $114) while the pure-players saw price appreciation (from $378 to $449). This is with the early impact of Android priced in. Unfortunately I don't have a chart showing non-smartphone prices in isolation, but I would be willing to bet it would be a significant negative slope.

    In these two lines Android is not an independent variable. Android was adapted by some of the diversified vendors (all but Nokia), but in different ways. The thing is that Motorola and Sony Ericsson had great increases in ASP with Android. Among the pure-play vendors only HTC adopted Android and its performance is undistinguished vs. RIM which didn't.

    So what, if anything, has Android done to pricing?

    I argue that there is no evidence in the pricing data of a coming commoditization of smartphones. Android vendors were able to use the platform to move to higher pricing and the more they switched their portfolio to Android the more they got a better average price. At the same time those vendors who built smartphones without Android also saw strong price supports.

    The only correlation with pricing power is whether you build smartphones or dumb phones. The more smartphones you build, the more price you can charge. This is regardless of platform.

    The reason for this is that the smartphone market is growing so rapidly (90% y/y). There is limited direct competition between smartphones and a lot of competition between non-smartphones and smartphones--a battle smartphones are winning handily, irrespective of price. Smartphones seem to be what everyone wants.

    So the real question that should be asked is:

    Why do vendors bother making any dumb phones at all?

    If you look at the third chart above you can see how attractive it must be for the diversified vendors to abandon the non-smart market to ZTE, Huawei et. al. Perhaps Nokia can still make a small profit there but to do so you need to run faster and faster toward extraordinarily low costs and prices. A point where phones cost less than everyday consumables. What keeps Samsung and LG in that game? Motorola and Sony Ericsson left once they hit profit warnings. Is that what it takes to drop what seems to be a loser business? I think not.

    My bet is that by the end of 2012, it will be hard to find any branded phones which won't run a smartphone OS. Demand and supply of smartphones will race each other to overwhelm portfolio logic at the largest companies. The zero (visible) cost of Android will snowball this effect. What's even more provocative is that I believe the "others" will follow and abandon voice-oriented phones for smartphones almost immediately after the larger group.

    So what have the Androids ever done for us?

    I've long argued that the phone market should be studied as a whole because the competition is not between platforms but between smart and non-smart. Pricing is a leading indicator of what drives decision making inside vendors and it leads margin, and thence portfolio discussion. Android is expanding the market without crushing pricing. The margin expansion is what attracts more vendors and creates more demand. It's a virtuous cycle.

    In a way, this is all good news--even for Apple. A world full of smartphone users is a better addressable market for iPhones than one filled with voice products. iPhone's traction was always in markets which had been seeded by some smartphones: the US with RIM and Europe with Symbian. Such a smartphone-soaked world will have better mobile broadband infrastructure, users with more demanding tastes and awareness of the value that a smart device can bring.

    ---

    [1] The effect of "other" vendors not among the 8 listed is a big unknown. It's been estimated that they now make up as much as 30% of total volumes and that they are beginning to ship significant volumes with Android. Without visibility into that part of the market, we should be cautious. However, the eight vendors sampled here are still a significant cohort and the conclusions still appear reliable.

    [2] This industry had, until 2007 suffered from chronic price erosion. Each sustaining innovation drove a mild burst of pricing power but it never seemed to last. From color screens to bluetooth, to 2.5G to 3G to MMS, to cameras to music playback, each hardware advance was not enough to keep the erosion away. The tipping point seems to be the iPhone and the shift to software as the component that drives price power.

  9. [Updated] RIM's sales down 15% in the US, up 112% outside the US

    Research · 41 comments

    First, a round-up of the quarter's numbers:

    • 14.2 million devices shipped, sell-through: 12.3 million
    • expect to ship 14.5 to 15 million units in the next quarter
    • ASP of approximately $315
    • US, UK and Canada are 56% of sales
    • US represented 34% of the total revenue
    • Last year US represented 57% of revenue
    • BlackBerry Torch launched in over 75 new markets, Torch launched with the $99 pricing from AT&T
    • BlackBerry Curve 3G launched with 118 carriers in 48 countries
    • China Mobile introduced BIS for small-to-medium sized businesses. The service starts at $14 per month
    • App World applications grew 60%
    • More than 16,000 applications available
    • 2 million downloads daily
    • 1,000 vendors registered for PlayBook apps
    • Revenue: $5.5 billion
    • Net subscriber additions: 5.1 million
    • Top three customers: 12%, 9%, and 9% of revenue
    • The same quarter a year ago: 25%, 13% and 10% of revenue
    • Service revenue in Q3: $835 million
    • Software revenue: $78 million
    • Gross margin in the quarter was 43.6%
    • Cash: $2.5 billion

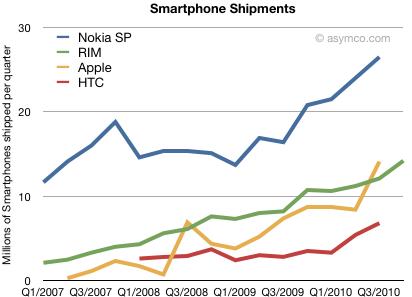
    For comparison, here are a select few vendors' smartphone reported shipments. RIM is the first to report and we'll be hearing the the rest by the end of January.

    The number most RIM "bears" focus on is the new subscriber additions. At 5.1 million out of 14.2 million units sold implying that the new subscribers added per unit sold is 0.34, a new low.

    The bulls will argue that the gross margin is healthy and slightly higher than anticipated.

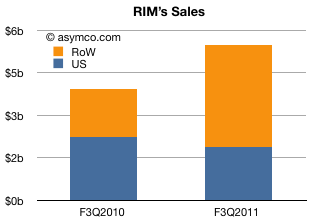
    My observation is that the company is finding growth outside its traditional markets. Given the figures above, the US went from $1.65b in revenue to $1.87b; a mere 13% growth while the company experienced 89% overall growth in revenues.

    The following chart illustrates the situation:

    Of the total increase in sales ($1.6 billion), the US contributed -15% while the rest of the world accounted for 112%.

    This can be seen as positive news since RIM has been weak internationally for many years and they really need to penetrate world markets. However, a -15% growth in the US is implies significant share loss in a rapidly growing and traditional stronghold.

  10. It's time for Apple to look at owning factories again

    Research · 95 comments

    Toshiba plant to make LCD panels for Apple: report | Reuters.

    Apple will invest in a portion of the investment for the factory, the Nikkei said.

    This is one of the more interesting news items I've seen for a while.

    [UPDATE] Toshiba denies rumor Apple will invest in mobile display subsidiary

    There was a time when Apple designed and owned factories. From an interview with John Sculley:

    That went all the way through to the systems when he built the Macintosh factory. It was supposed to be the first automated factory but what it really was a final assembly and test factory with a  pick-to-pack robotic automation. It is not as novel today as it was 25 years ago, but I can remember when the CEO of General Motors along with  Ross Perot came out just to look at the  Macintosh factory. All we were doing was final assembly and test but it was done so beautifully. It was as well thought through in design as a factory--a lights out factory requiring many people--as the products were.

    During the 90s the manufacturing function moved outside Apple's ownership umbrella. It was more economical, more flexible and more scaleable to outsource manufacturing to Asia. The time has come to rethink this.

    For the past few decades outsourced manufacturing has grown in scale and scope as prices fell and quality increased. However there are signs that this global web of suppliers and assemblers is reaching a point of disruptive change.

    Press attention has focused on labor practices, pay structures and the enormity of factory towns where literally millions of workers are employed and housed. As is often the case press attention only hints at some causality and as such misses the point. Journalists looking for a story about child labor or suicidal workers might serve us better by putting the spotlight on the fact that factory towns are not competitive.

    centralized Manufacturing is not good enough for the coming mobile computing disruption

    The real problem with Chinese factory towns is that they are not flexible enough. By concentrating facilities and workers, electronics manufacturers have improved on measures of scale and quality but are still only able to ramp up and down on individual products once or twice per year. This does not meet the need to increase responsiveness to markets and the pace of development and design. It also reaches some critical overweight mass. Capacity cannot double or triple again to meet the need of six billion consumers. There are signs that the business model must change.

    Typically a product is born in Product Marketing, progresses through Design, R&D and then to Manufacturing and finally to Sales. Each of these stages of development has to be re-started for each new product, often in a pipeline fashion. However, some of these stages are increasing their cycle times while others are at their limits. This limits the throughput of the whole chain. If, for example, R&D can put out two product designs in the space it takes for one Sales cycle then they need to be tasked with different product while they wait for "capacity" in Sales to catch up.

    My contention is that the bottleneck in device product development is now manufacturing. The evidence is that Apple (among many others) cannot meet demand. Sometimes it's a lack of components, but often there is a forecast error and capacity is simply not allocated. What I also see is that this bottleneck is not solvable with the current value chain architecture. When there are 5 billion consumers of platform devices, centralized factory town manufacturing does not match the cycle time of either design or of consumption.

    The answer to low capacity is more investment in more lines of production, more workers and more suppliers. However the problem is that this takes time. The window of opportunity for a product is less than six months.

    Consider the iPhone product cycle. A new variant goes into development 18 months to two years before it's launched. It's ready for manufacturing a few months before launch. The R&D team is off making the next version long before the product hits any shelves. The cycle time for R&D changes unpredictably. Sometimes it slips, sometimes it may be shorter because the changes are minor. Perhaps marketing sees the need to react to changing market conditions. However, manufacturing plods along at an inflexible rate.

    How can it be fixed?

    I'm not an expert in this area, but as a student of disruption I see signs of opportunity to re-engineer the manufacturing business model. The patterns from history are plain to see: Centralized systems get broken down and re-aligned with new bases of competition. Value chains disintegrate and re-integrate as profit algorithms change.

    The new algorithm says you need to ramp production quickly (up and down) and to increase "product turns" from one to two each year. Each ramp needs to be even bigger than they are now. Maybe by a factor of two. Products should be built closer to where they are consumed to drive costs and delays out of transportation and tariffs. Carbon footprints need to be reduced.

    Sounds daunting. But the rewards could be enormous. The business model may need re-definition. By owning the means of production, the value added can be shifted to another point (i.e. production can be run at a loss in exchange for higher margins elsewhere.)

    All this requires capital. Lots of it. Apple has it. I see no better use for it than to re-define production as a synchronized development module.

    It's time to look at owning factories again.