Recording and transcript of the June 9, 2026 Asymco One Office Hours, recorded the day after Apple's WWDC 2026 keynote. Horace Dediu shares his impressions of the event and takes questions from Asymco One subscribers.
The iPhone maker is trading at 2.5x its ecosystem value and 1.5x its economic impact
Apple today announced the global App Store ecosystem facilitated over $1.4 trillion in developer billings and sales in 2025, according to a new study by economists at Analysis Group. For more than 90 percent of the billings and sales facilitated by the App Store ecosystem, developers did not pay any commission to Apple. Since 2019, the size of the App Store ecosystem has nearly tripled, as the App Store remains the safest and best place for users to discover and download apps. .
Bill Gates once said you have a platform when other people make more money from it than you do.
In other words, success is if there is more value created on top of it than captured from it.
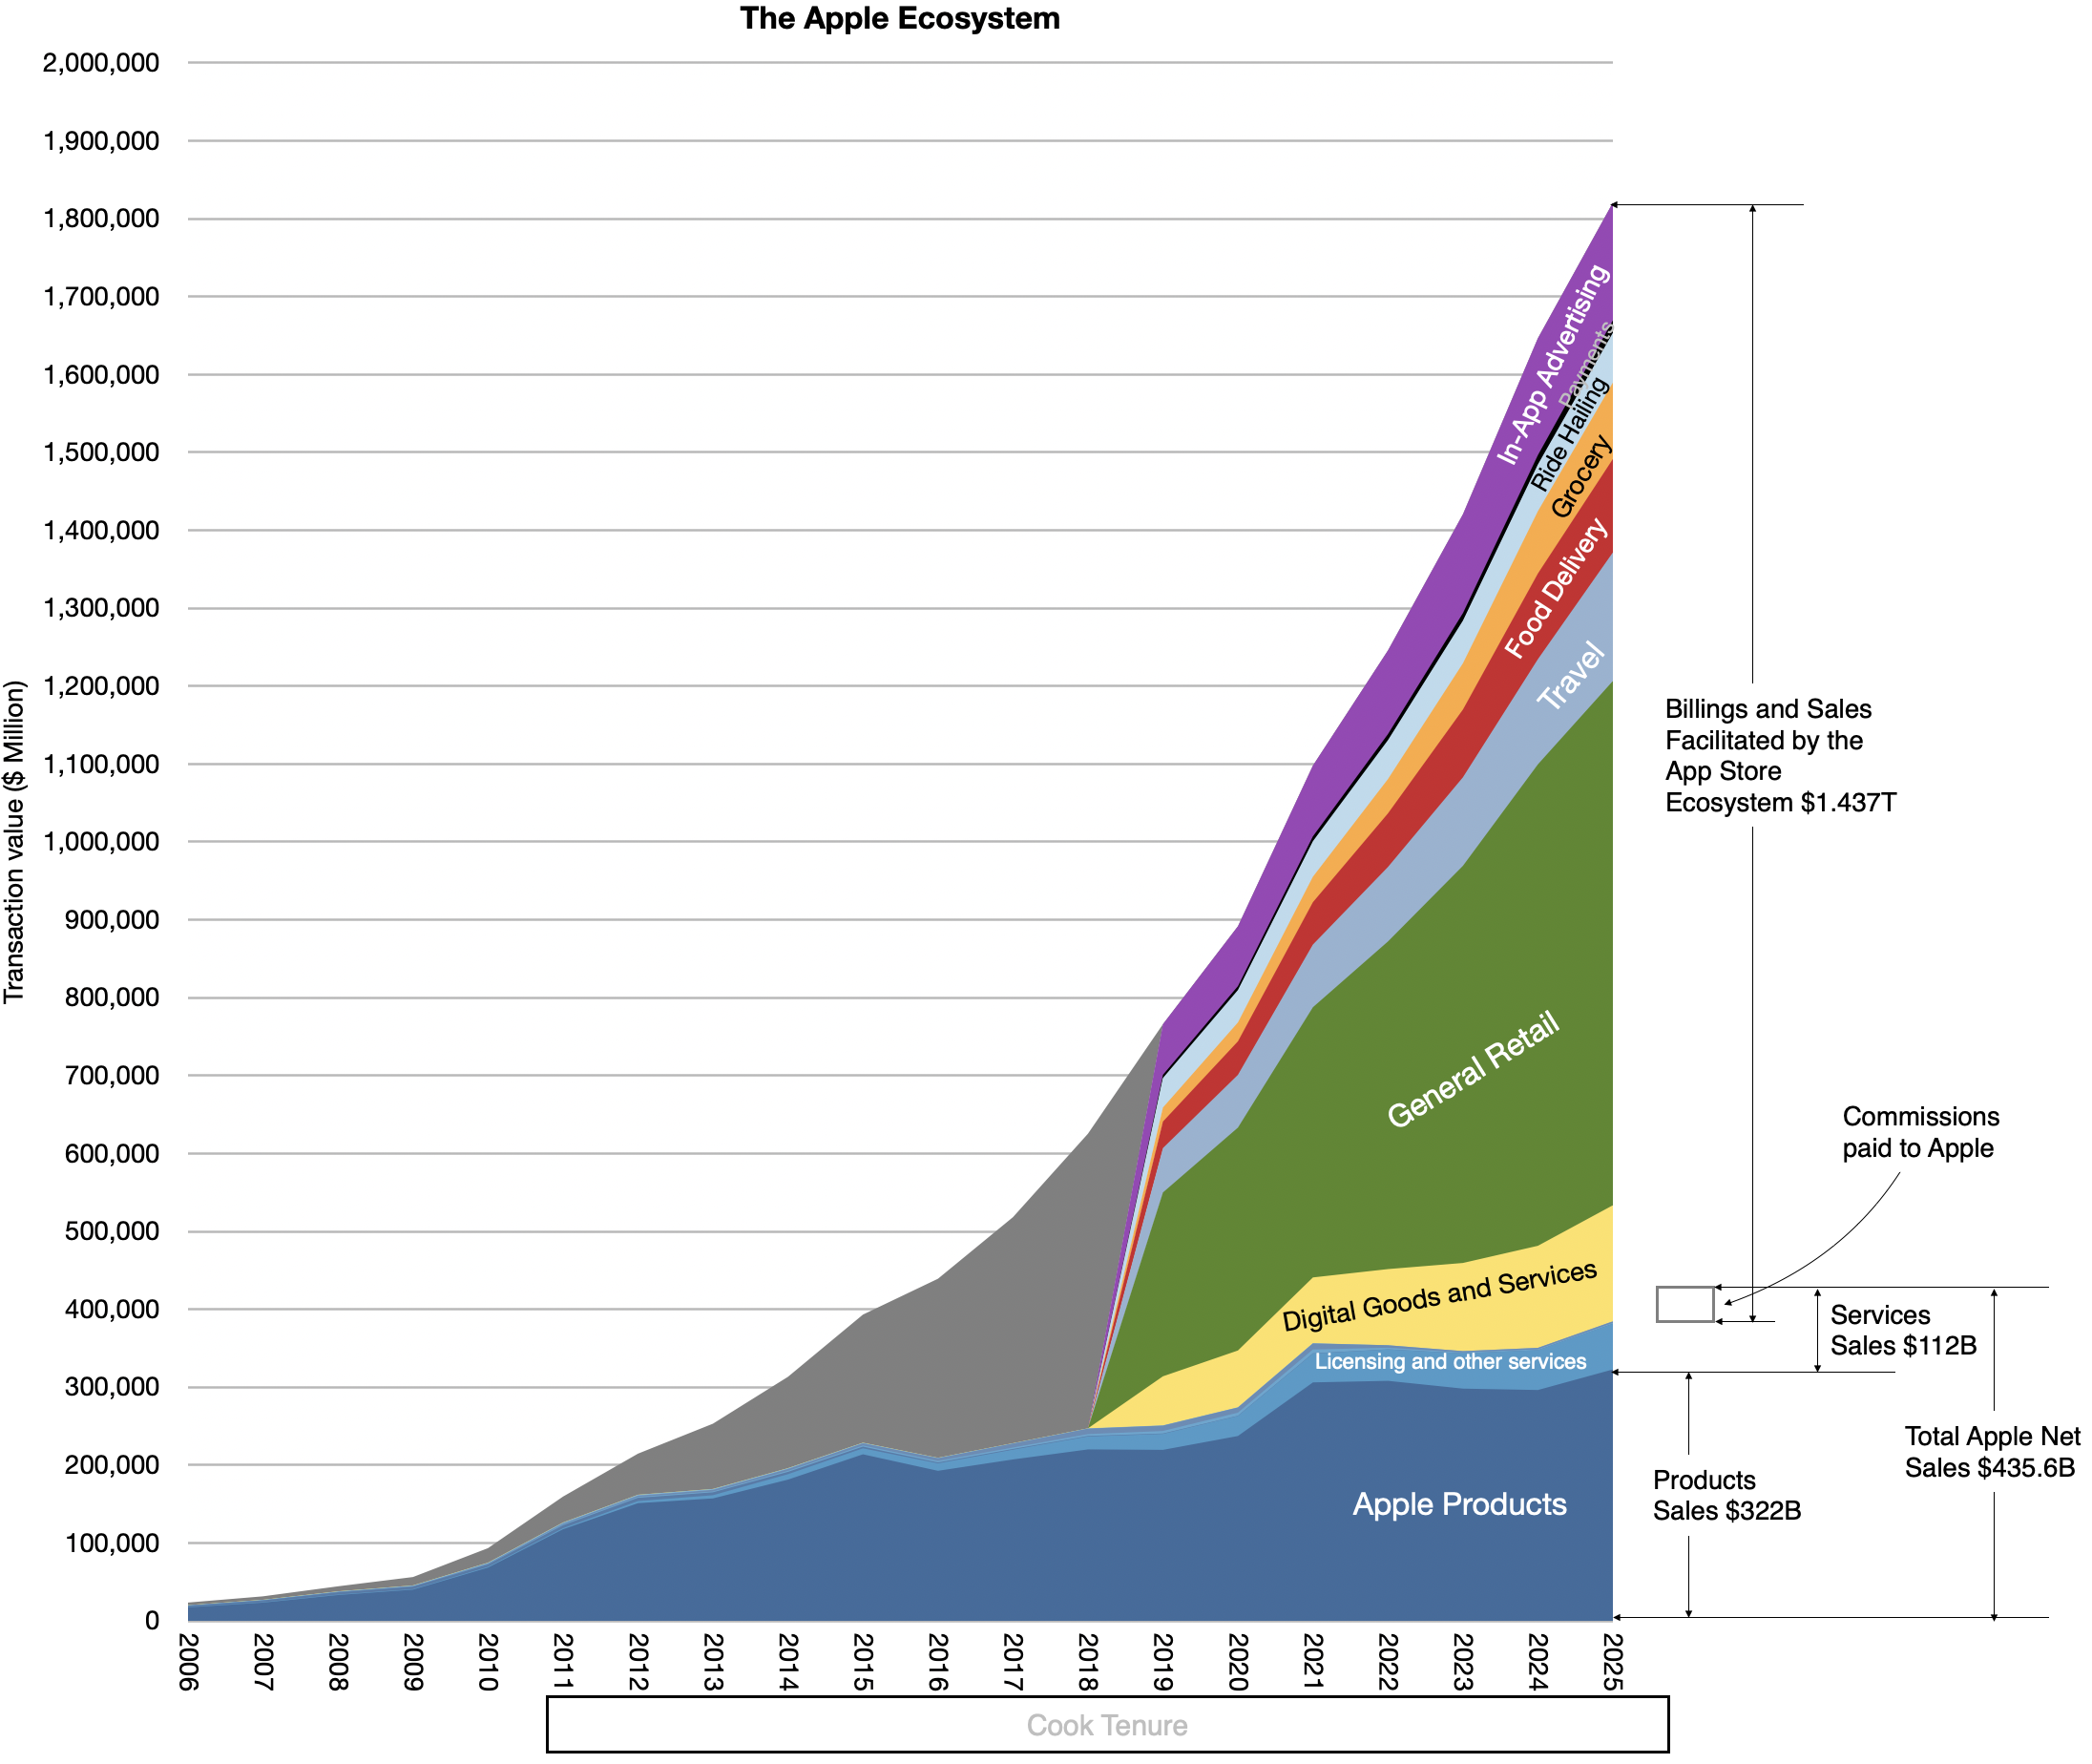
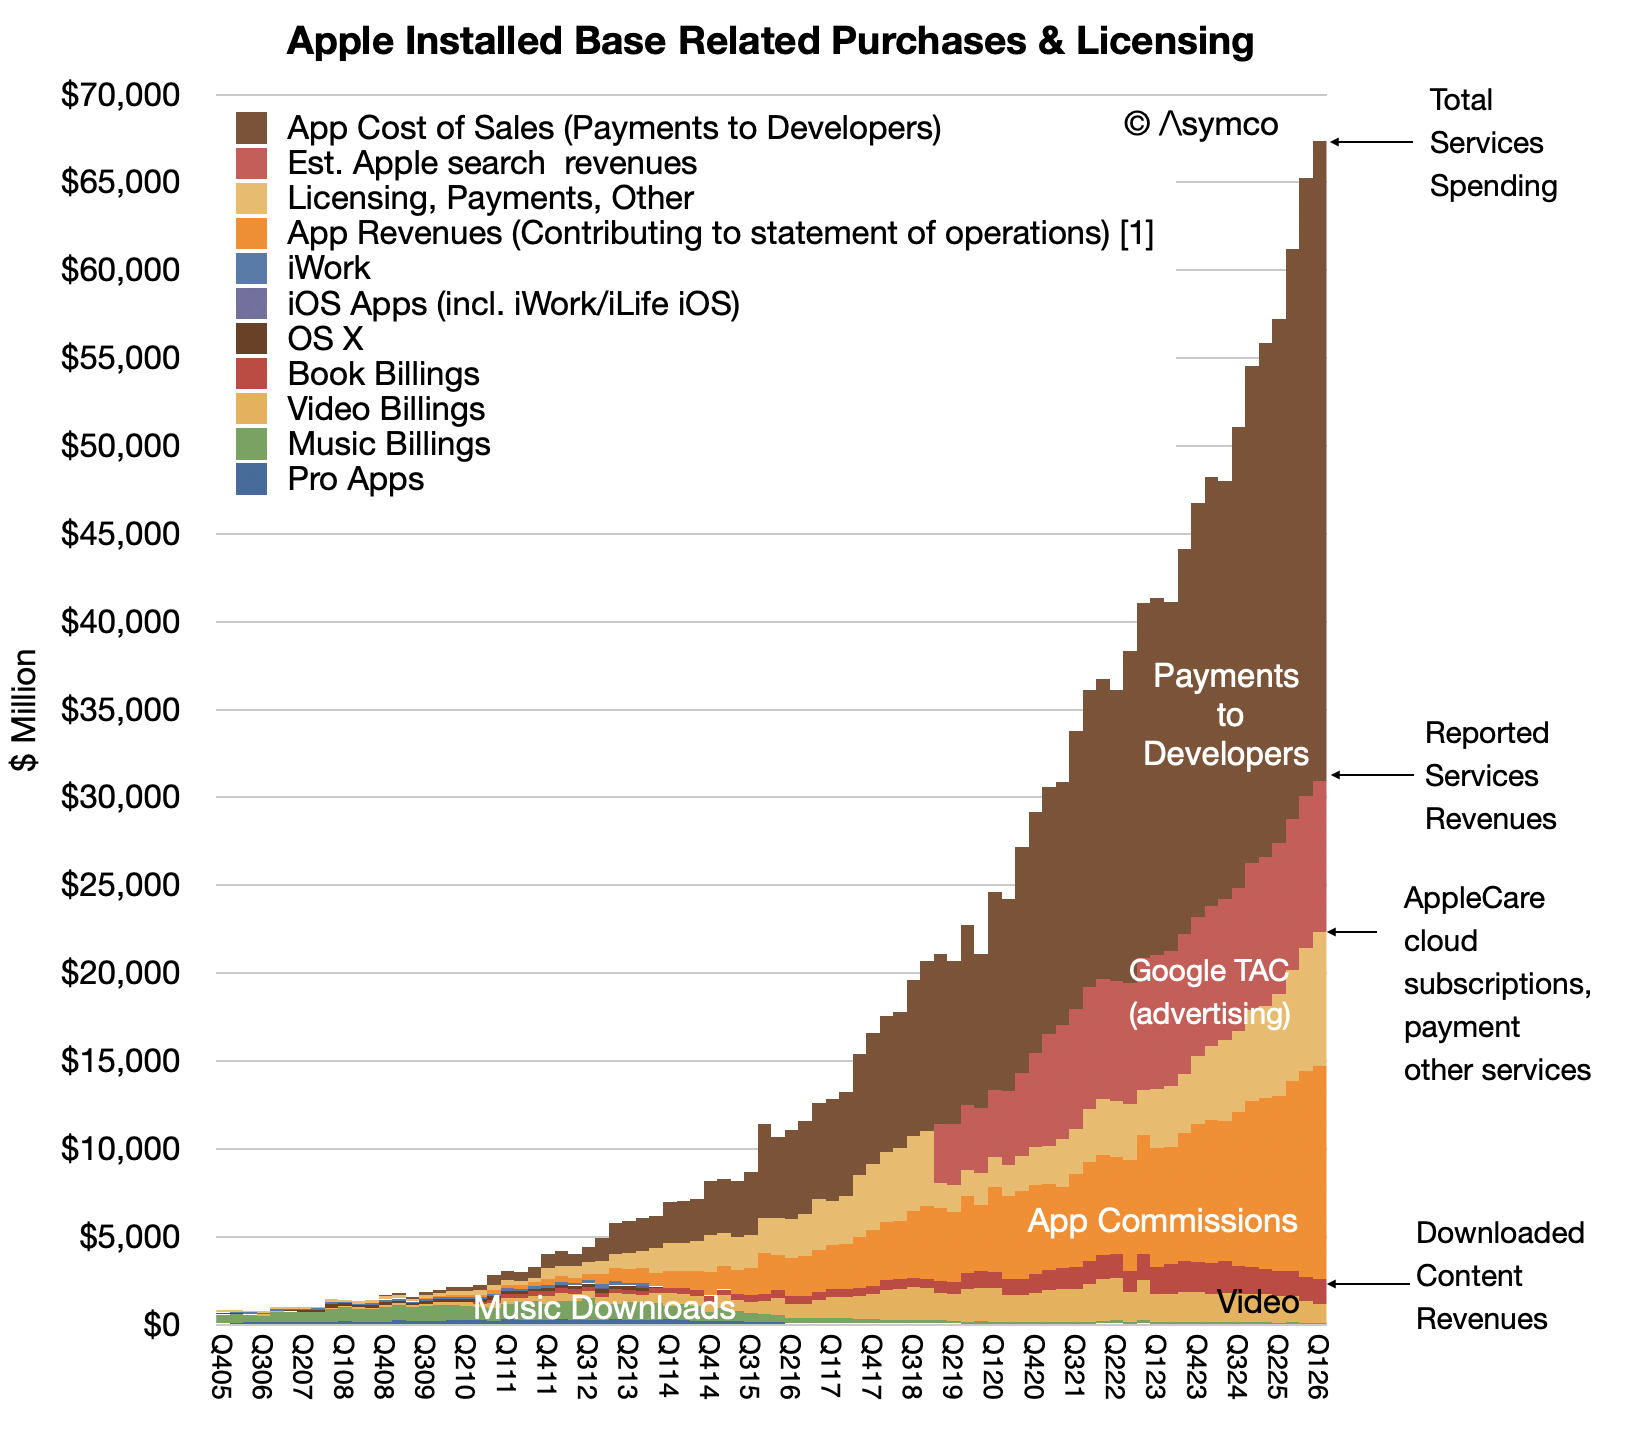
Few platforms qualify but Apple's certainly does. Apple's ecosystem is shown in the graph below.
Apple's direct payments to developers were about $126.7 billion but, as the Analysis Group report shows, Apple and the developers enabled transactions dwarfing app store transactions. In 2025 Apple captured a tiny fraction of the economic activity it induced on its platforms (about $57 billion out of $1.437 trillion or 4%).
Combining the billings and sales facilitated by the App Store and Apple's direct sales of products and services leads to a total of over $1.8 trillion. I call this the Apple Ecosystem (Apple + App Store.)
But that's not everything. There are lots of economic activities on the platform that do not involve the App Store. Activity on browsing and social media and messaging apps probably add another 50% on top of this, perhaps even 100%. I call this the Apple Economy (Apple + App Store + All other transactions.)
Ultimately, the 1.4 billion Apple users using 2.5 billion devices are likely inducing as much as $3 trillion of economic activity.
It seems to me that we need a way to measure a multiple of this activity as perhaps a fundamental metric of value creation.
At $4.57 trillion current market cap, the value is only 2.5x its ecosystem and 1.5x its economic footprint.
The company “may be on the brink of some real AI sizzle.”
Reitzes said people are becoming more comfortable using voice commands, and Apple could benefit from this shift as technology becomes more voice-driven.
Reitzes also said the upgraded Siri could become a standalone tool that many Apple users rely on, even instead of apps like OpenAI’s ChatGPT. He described it as an “agent-style interface” that could make the Apple ecosystem more unique and spark fresh excitement among developers.
Additionally, he highlighted that no other consumer tech company has both parts of that system under one trusted setup. He added that this advantage will become even clearer—and more valuable—as AI systems get more complex and start acting more independently.
Overall, he expects Apple to post about $613 billion in revenue by fiscal 2028.
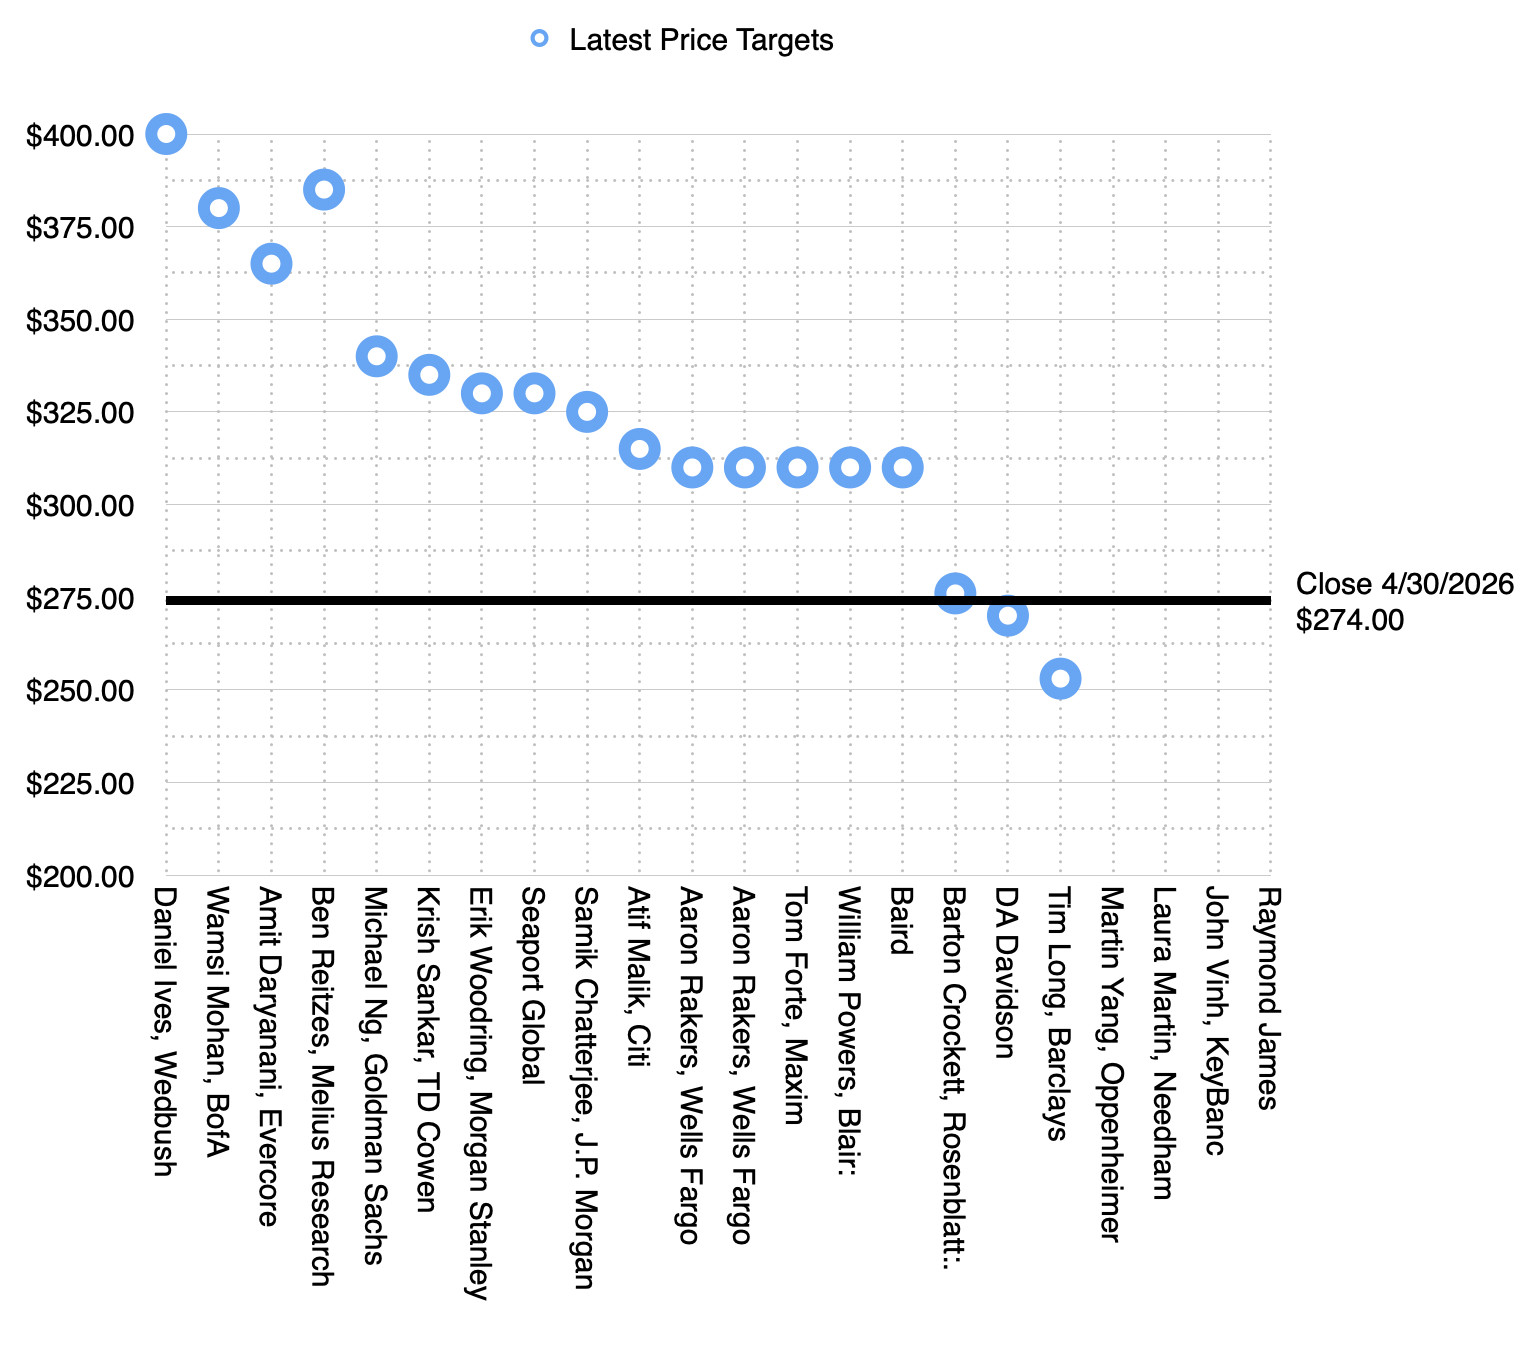
NB: Latest analyst targets are shown with Melius' stepping up. Analysts are coming round.
This upgrade follows Bank of America boosting its price target to $380 a share.
“In an agentic world, value accrues to the platform that controls user intent, personal context, app access, permissions, identity, authentication, payments, and trust,” said BofA’s senior equity research analyst Wamsi Mohan.
“Smartphone is the scaled consumer device where these factors already converge,” he added. “If AI assistants become the new front door…we think Apple should have meaningful leverage over model providers, app developers, merchants, advertisers, and payment networks.”
An agentic version of Siri could boost 2030 revenue by as much as $65 billion, Wamsi and his team estimated, adding up to $2 billion in incremental earnings over the next four years.
Reitzes sees the new Apple Siri as a stand-alone app that has the potential to replace ChatGPT for Apple's 2.5 billion installed devices, while proving to be “an agentic interface that can further differentiate the Apple ecosystem and ignite a level of excitement with developers not seen since the early days of the App store.”
But it’s also likely to establish Apple as the leader in consumer-use AI.
“If agentic AI shifts the market from answering questions to taking actions, the critical control point becomes centered around owning the endpoint,” Wamsi said. “Apple does not need to own the best frontier model if it owns the trusted interface that routes intent across local models, Apple-controlled cloud models, external models, and app actions.”
Reitzes at Melius sees that shift, which he describes as a “shot in the arm” for Apple’s app store, driving “a massive new product cycle that keeps iPhone growth going.”
He’s also observing that Apple’s architecture, with on-device models handling lighter workloads and its private cloud taking on the larger ones, makes it unique.
“No other consumer technology company has both legs of that architecture under a single trust model, and we think that gap becomes more visible, and more valuable, as agentic complexity scales,” he said.
“Agentic AI is a structural tailwind that will force consumers to get the latest and greatest Apple device because it will work better than other brands.”
NB: Do alternative app stores provide similar fraud prevention Analysis? Does the European Union review these analyses to determine how their citizens are protected. In the alternative, is the EU benefit analysis of users end at arbitrary market access metrics? I don't hear much about alternative App Stores and their popularity. Quelle surprise!
Goldman Sachs is pushing back on negative sentiment surrounding Apple ahead of its second-quarter earnings, arguing that the stock's recent underperformance reflects fears that do not match the company's underlying position.
But analyst Michael Ng said, "concerns for Apple are overly pessimistic given its much stronger relative position."
Goldman Sachs forecasts fiscal second-quarter EPS of $2.00, above the Street consensus of $1.93, with outperformance expected across iPhone revenue, Mac revenue and gross margins.
Favorable foreign exchange and strong Services revenue growth are also expected to flatter results.
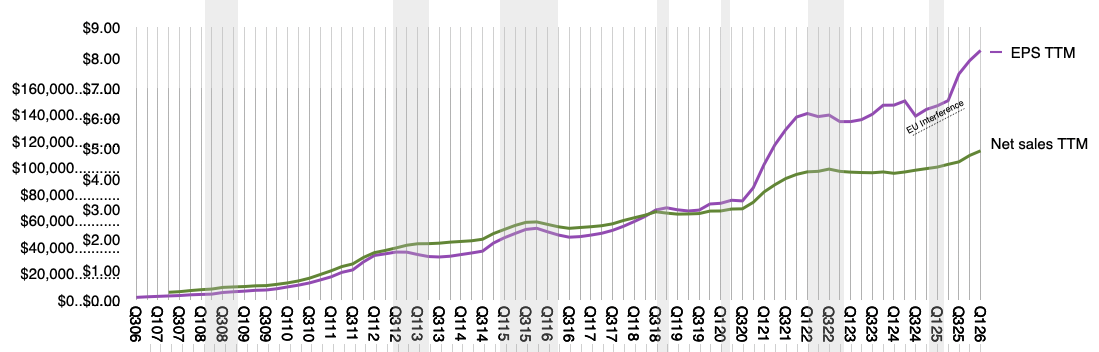
On Services, Goldman Sachs projects 14% year-on-year growth despite another slow App Store quarter, with iCloud+, AppleCare+, prior price increases on Apple TV+ and solid advertising performance cited as supporting drivers.
Looking ahead, the bank sees advertising inventory expansion in the App Store and Maps as further tailwinds.
Recent data points cited by Goldman Sachs include high-end smartphone outperformance flagged by TSMC on its latest earnings call, iPhone share gains in China, and reports that Apple is actively securing mobile DRAM supply while keeping pricing competitive.
The bank sees further catalysts ahead, including WWDC, where new AI Siri features are expected, and the fall iPhone lineup, which Goldman Sachs described as likely "the most innovative ever with the introduction of the iPhone Fold."
The latest effort, known internally as “Transformer,” is being developed within its devices and services unit, according to four people familiar with the matter. The phone is seen as a potential mobile personalization device that can sync with home voice assistant Alexa and serve as a conduit to Amazon customers throughout the day, the people said.
The initiative is the newest chapter in a years-long effort to bring to market Bezos’ long-held vision of a ubiquitous voice-driven computing assistant akin to the voice-controlled computer in science fiction series “Star Trek.”
Bezos had envisioned a smartphone that had shopping at its core and could take on Apple by offering shipping convenience and discounts through the Prime membership. Along the way, Amazon could gain a wealth of new data about users only available through mobile phones combined with purchase history and content preferences.
As envisioned, the new phone’s personalization features would make buying from Amazon.com, watching Prime Video, listening to Prime Music or ordering food from partners like Grubhub easier than ever, the people said. They asked for anonymity because they were not authorized to discuss internal matters.
A key focus of the Transformer project has been integrating artificial intelligence capabilities into the device, the people said. That could eliminate the need for traditional app stores, which require downloading and registering for applications before they can be used.
The project is being led by a year-old group within Amazon’s devices unit called ZeroOne, whose mandate is to create “breakthrough” gadgets, the people said. ZeroOne is led by J Allard, a former Microsoft executive involved in such devices as the Zune music player and Xbox gaming console.
The head of Amazon’s devices and services unit, Panos Panay, has been working to reverse years of unprofitability in the division. That includes a forthcoming tablet that will—for the first time—run Android instead of Fire OS and could sell for around $400, which Reuters was first to report.
One inspiration for the new phone has been the Light Phone, two of the people said, a $700 minimalist smartphone with a camera, map, calendar and not much else, such as an app store or web browser.
A dumbphone or feature phone could also help Amazon market it as a potential second handset to accompany iPhones and Samsung Galaxies already in customers’ pockets, the people said. Such handsets, like the Light Phone and flip phones, accounted for 15% of global handset sales in 2025, according to Counterpoint Research.
Apple is on pace to surpass $1 billion in artificial-intelligence revenue this year, a tidy sum that demonstrates the company’s AI advantage even as it struggles to deliver an AI strategy of its own.
That means they typically pay the App Store tax, roughly 30% of subscription fees in the first year and 15% a year thereafter, though rates vary by country. Generative AI apps paid Apple nearly $900 million in App Store fees in 2025, according to the analysis firm AppMagic.
Three-fourths of the revenue Apple rakes in from GenAI apps in its App Store comes from ChatGPT, according to AppMagic. Next, at about 5%, is xAI’s Grok. Apple’s revenue from GenAI apps rose from about $35 million in January 2025 to a high of $101 million in August. Sales have fallen from their peak, partly because ChatGPT downloads have declined, according to the data.
Asymco Bulletin is a digest of all the work we have published for the week ending March 1, 2026.
Office Hours
Our firstOffice Hours interactive seminar and Ask Me Anything questions/answer session will be on March 4th, after, presumably all the new announcements Apple will be making during the week. I will be broadcasting to you en vivo y en directo from Paris.
Apple March 4 Special Event – Q&A → Join us for an exclusive Asymco One live Q&A on March 4 at 3pm ET to dissect Apple's latest business moves. →
Greater China (GC) is a specific reporting segment for Apple, encompassing Mainland China, Taiwan, Hong Kong, and Macao, with a combined population nearing 1.5 billion. This region is not just a significant contributor to Apple's revenue—accounting for 18% of net sales in Q4 2025—but also a dynamic landscape of technological adoption and consumer behavior. The smartphone user base in GC has surged from 690 million in 2016 to nearly a billion in 2025, with projections reaching 1.08 billion by 2029.
The iOS ecosystem within GC exhibits varied dynamics across its constituent regions. While Macao maintains a steady iOS share of around 60%, Mainland China and Taiwan show different trajectories. Analyzing these trends through mobile OS share data reveals iOS's ascent, suggesting robust potential for further penetration and user engagement. As Apple navigates this complex market, understanding GC's historical growth patterns and future prospects is crucial for capitalizing on emerging opportunities and sustaining its competitive edge. →
Nota Bene
Apple #1 phone vendor in Europe → Apple leads Q4 2025 with a 7% YoY shipment rise driven by iPhone 17, while Samsung follows with 4% growth; Xiaomi faces a 6% decline amid shifting regional dynamics. →
iPhone becomes India’s top single export item → In 2025, Apple's iPhone exports from India, driven by Tata and Foxconn plants and a robust supply chain, reached $23 billion, making smartphones the top export category. →
Apple’s App Store growth is reaccelerating → Apple's Services, beyond just the App Store, are poised for robust growth, driven by global market expansion and strong hardware demand. →
Here’s why demand for Macs has spiked → Mac lead times have surged to multi-year highs due to increased demand, notably impacting models like Mac Studio, MacBook Pro M4, and Mac Mini. →
A resource for AVP news → "AVP VIP offers a weekly, ad-free digest of tech news and insights, accessible to Asymco One members." →
Eddy Cue says Brazil is Apple TV’s second-largest market, talks Netflix-Warner merger → In an interview, Apple's Eddy Cue highlighted Brazil as the second-largest and fastest-growing market for Apple TV subscribers, while noting potential impacts from proposed streaming regulations and a possible Netflix-Warner deal. Specific user and device numbers were not disclosed. →
Apple’s App Store revenue growth is strengthening in February, with Morgan Stanley saying the latest data points to a faster pace of expansion heading into the March quarter.
The firm’s analyst, Erik Woodring, said in a note Monday that App Store net revenue is growing 9 percent year-over-year month-to-date, which represents “a 230bps acceleration from January off a 700bps easier Y/Y compare.”
Woodring added that quarter-to-date revenue is now rising 7.5 percent, putting it “50bps behind our +8.0% Y/Y March quarter App Store forecast.”
The bank kept its March-quarter App Store growth and Services growth forecasts unchanged at 8 percent and 13.5 percent, respectively.
Morgan Stanley said the acceleration is broad-based across major markets. China’s App Store is growing 4 percent year-over-year after a decline in January, while the U.S. is rising 3 percent, a 40-basis-point improvement. Japan is down 1 percent, while the rest of the world is seeing 22 percent growth.
The analysts also cited rising Mac lead times, noting they have “quickly inflected to multi-year highs” due to demand for the on-device AI tool OpenClaw.
They said stronger Taiwan component supplier revenue in January is another positive indicator, pointing to “very robust strength in server demand coming from the largest global cloud service providers.”
Previously, on February 3, Goldman Sachs maintained its Buy rating and $330 price target on Apple Inc., highlighting favorable App Store spending trends. The firm noted the company’s App Store spending acceleration of approximately 7% YoY in January 2026, relative to the 6% growth in December last year. While Entertainment grew 7% (from 3% to 10%), the Games division declined 3% YoY.
Goldman Sachs believes that App Store spending will continue to be a meaningful growth catalyst for the company’s Services revenue in the future
Investment bank Goldman Sachs discussed Apple Inc. in January. It reiterated a Buy rating and a $330 share price target on the firm. The bank discussed the firm’s App Store performance in its coverage. It outlined that the App Store spending trends were improving as spending grew by 7% in January to accelerate by one percentage point over December’s 6% growth. Goldman added that the App Store growth should contribute meaningfully to Apple Inc. Services business.
Along with Goldman Sachs, Bernstein also praised the firm. It reiterated an Outperform rating and a $325 share price target. Bernstein cited Apple Inc.’s record iPhone revenue and optimistic growth guidance to point out that the firm was correctly navigating the turmoil in the memory industry.