Recording and transcript of the June 9, 2026 Asymco One Office Hours, recorded the day after Apple's WWDC 2026 keynote. Horace Dediu shares his impressions of the event and takes questions from Asymco One subscribers.
Market contraction expected for second half of year.
Omdia reports that Europe (ex. Russia) smartphone market grew 2% to 33 million units in 1Q26.
Key vendor highlights from 1Q26 include
Samsung was Europe’s largest vendor as it grew 3% to 12.6 million units. Effective discounting of the Galaxy A16 4G helped Samsung boost volume, offsetting declines related to the delayed launch of the Galaxy S26, A57 and A37.
Apple grew 9% to 8.8 million iPhones, driven by robust iPhone 17 series demand in addition to benefiting from a wider mid-range coverage from the iPhone 15 and iPhone 16e. Noticeably, Apple’s strong results came despite lower and fewer discounts than in previous years.
Xiaomi retained third place despite declining 15% to 4.5 million units, as it was more immediately impacted by supply-side difficulties. However, Xiaomi’s ASP grew 21% compared with 1Q25, boosted by a record-strong Xiaomi 17 and 15T series performance, which drove year-on-year value growth despite the shipment decline. Premium sales were particularly strong in France, Germany, and Spain.
Motorola grew 17% to 1.9 million units, driven by rapid expansion in Spain and Portugal, alongside continued progress in France and Italy.
OPPO grew 9% to 1.3 million units, largely driven by its comeback in France alongside growth in Romania and Poland. With both realme and OnePlus now under its umbrella, OPPO is restructuring to optimize its portfolio and strategy with ambitions to strengthen its European position.
HONOR, ranking sixth, was the fastest-growing vendor among the largest players, with shipments increasing more than 60% compared to 1Q25. HONOR’s growth is underpinned by its portfolio being expanded further down the price-tiers.
"The average-selling-price (ASP) of smartphones in Europe surged to a record-high level of €580 in 1Q26," added Bjorhovde. "This was largely caused by lower availability of devices costing less than €200, which made up an all-time low of just 25% of shipments. Additionally, the high-end remained resilient thanks to Apple’s growth. The focus from both vendors and channel partners has shifted from volume to value to deliver results and operational sustainability. Many vendors who normally focus on the mass market segments are increasingly concentrating on the mid-to-high-end, hoping to benefit from less price-sensitive and upgrade-willing buyers."
[My emphasis]
"The first quarter of 2026 delivered beyond expectations, but the outlook remains bearish as the rapidly escalating memory bottleneck worsens," commented Bjorhovde. "Omdia forecasts shipments into Europe to decline 12% in 2026, but the majority of this will come in the second half of the year.
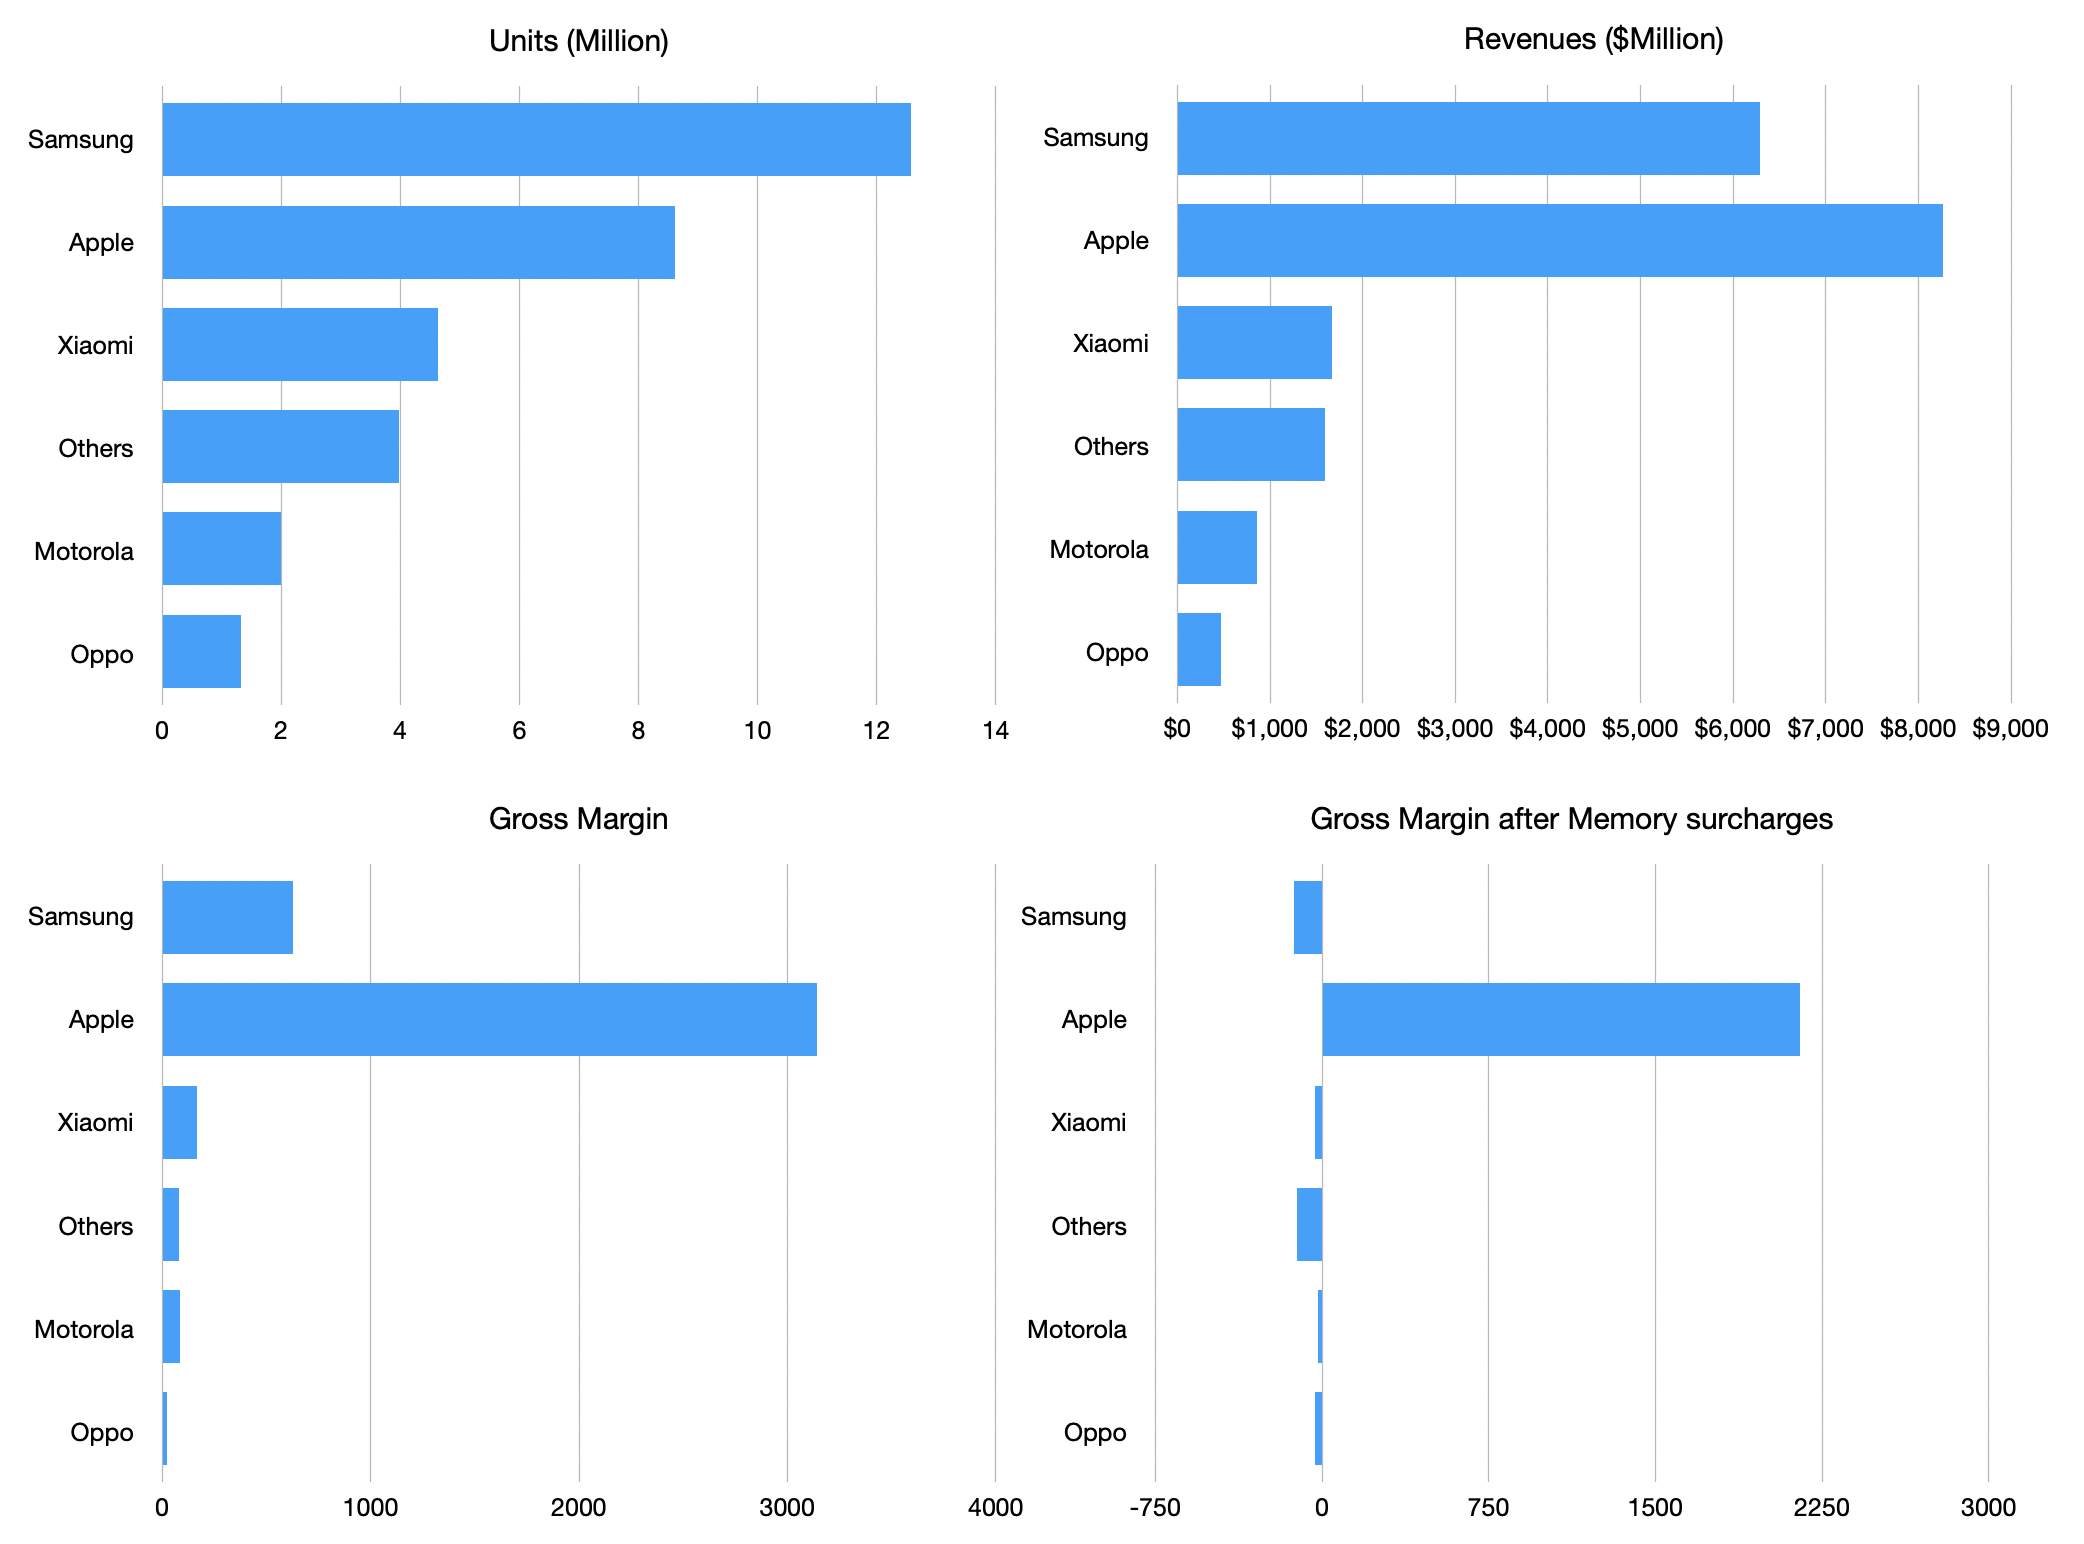
Applying average pricing per vendor and average gross margins gives the following picture of the market:
Apple currently captures 26% of unit volume, 43% of ...
The Latin American smartphone market grew 3% year over year in 1Q 2026 to 34.8 million units, supported by proactive inventory accumulation and the delayed pass-through of rising memory costs. Omdia analyzes the market’s uneven vendor performance, as Samsung and Xiaomi strengthened their leading positions, while HONOR and Apple saw sharp growth supported by entry-level and premium demand, respectively.
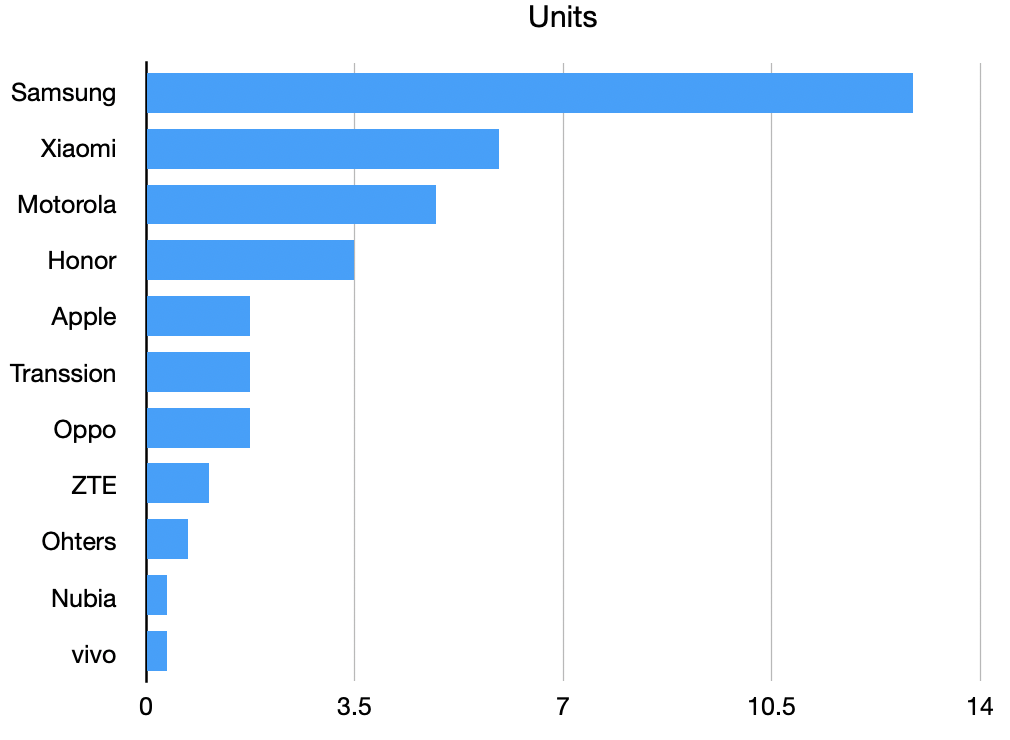
Samsung led the region, shipping 12.9 million units (+9% YoY) and lifting share to 37%, its highest quarterly level since 1Q 2023, supported by strong performance of A‑series models across low‑end and mid‑high segments. Xiaomi held second, marking a sixth consecutive quarter of growth with 6.0 million units and 17% share, driven by double‑digit gains in Central America and Peru and solid traction of the Redmi Note 15 series in the mid‑high range. Motorola ranked third, contracting 5% YoY to 4.9 million units and 14% share, largely reflecting a 37% drop in shipments of US$100–US$200 devices, where G06 and G17 are key models. HONOR consolidated in fourth with 30% YoY growth to 3.4 million units and a 10% share, propelled by its Play 10 in the entry segment (below US$100), which approached half a million units sold for the first time.
Apple completed the top five with a 31% YoY increase, supported by an exceptional performance in Mexico (+80% YoY) and robust reception of the iPhone 17 series.
A transcript of the May 1, 2026 Asymco One Office Hours, recorded one day after Apple's Fiscal Q2 2026 earnings call. Horace Dediu presents his analysis of the quarter and takes questions from Asymco One subscribers. Hosted by Horace Dediu and Farshad Nayeri.
Horace Dediu: So I'll do a short presentation, and then we're going to open it up for questions. We are speaking approximately one day after Fiscal Second Quarter 2026 earnings call. Let's dig into it and see if we can understand it even better.
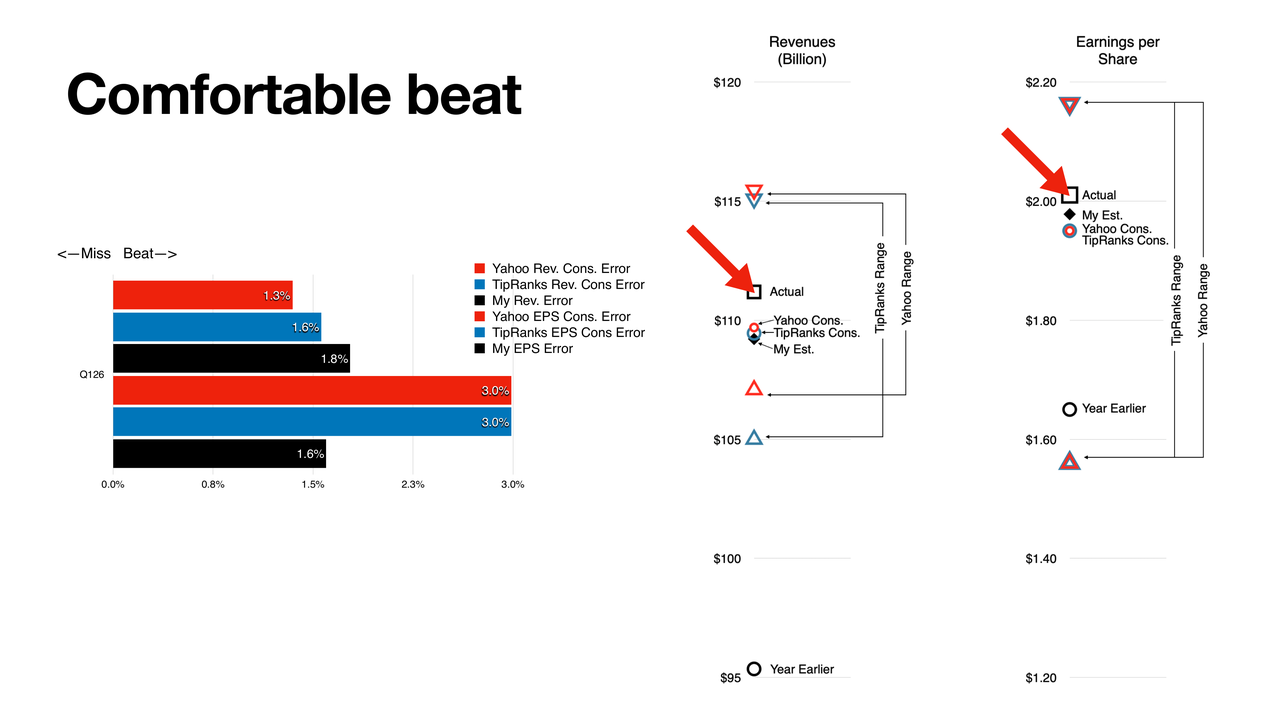
First, I think that there was a comfortable beat from already a highly elevated expectation.
So we had a range of estimates— I collected those from Yahoo and TipRanks, each one had about 30 [analysts], probably a lot of overlap between them. So we had a range of about 105 to 115 in terms of revenues in billion, and then we had EPS in a range of about 1.6 to about 2.15.
And not only did it beat the consensus, but also you can see what happened a year earlier, which is the circle at the bottom of the graph. So the beat was from already a pretty high growth rate expected from the year before.
So we have a measure of how each of us, myself included, performed relative to the actual results.
I was about 1.8% under revenues delivered, and 1.6% on EPS. And then you can see red is Yahoo and blue is TipRanks.
So speaking for myself, I was perhaps a little bit too conservative on my revenues, and I was a little bit more accurate, relatively speaking, on EPS. Roughly speaking, again, I think these are not big errors, 1% to 2%. Worst case, 3% on the consensus basis.
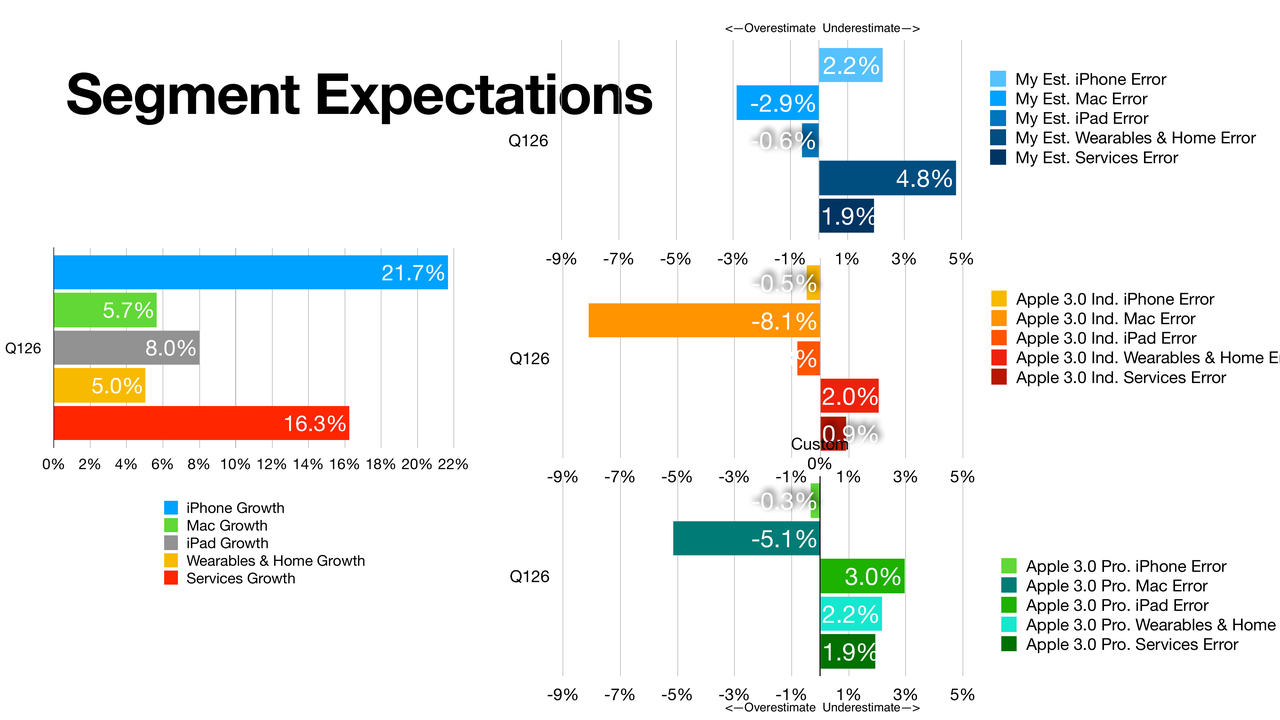
Now, on the segments, these are the actual growth that we ended up with, iPhone almost 22%, 16% on services, 8% on the iPad, which is impressive. 5.7 on the Mac, we'll talk about that a little bit, and 5% on wearables and growth.
Segment level, again, the worst case, you're looking at an 8% overestimation on the Mac. The Mac— I think a lot of people, once they saw the Neo come out, once they heard about the Mac mini stockouts, when they heard about the Claude bots, you know, everybody buying up all these Macs, there was an expectation of a big boom in the Mac, but those all happened fairly late in the quarter. My expectation was a little bit over, but not as much. I was off about 3% on that estimate. So although we saw 5.7% growth, some people expected double digits. Also, the pros had the same fault there.
Overall, though, I think these are pretty impressive. I didn't break out the geographic segments. China grew extremely well. Rest of the world, that grew very well. Management also pointed out that they're doing very well in developing markets. So overall, regionally, there were some extraordinary performances. But as we see here, just the iPhone was incredible, 22%. Very similar to performance in the previous holiday quarter, where, again, unprecedented growth, or at least in the near history of the product.
And we'll get into some reasoning why that is. People talk about super cycles, people talk about the assumption that we have these giant surges once in a while. Well, here's how to look at it.
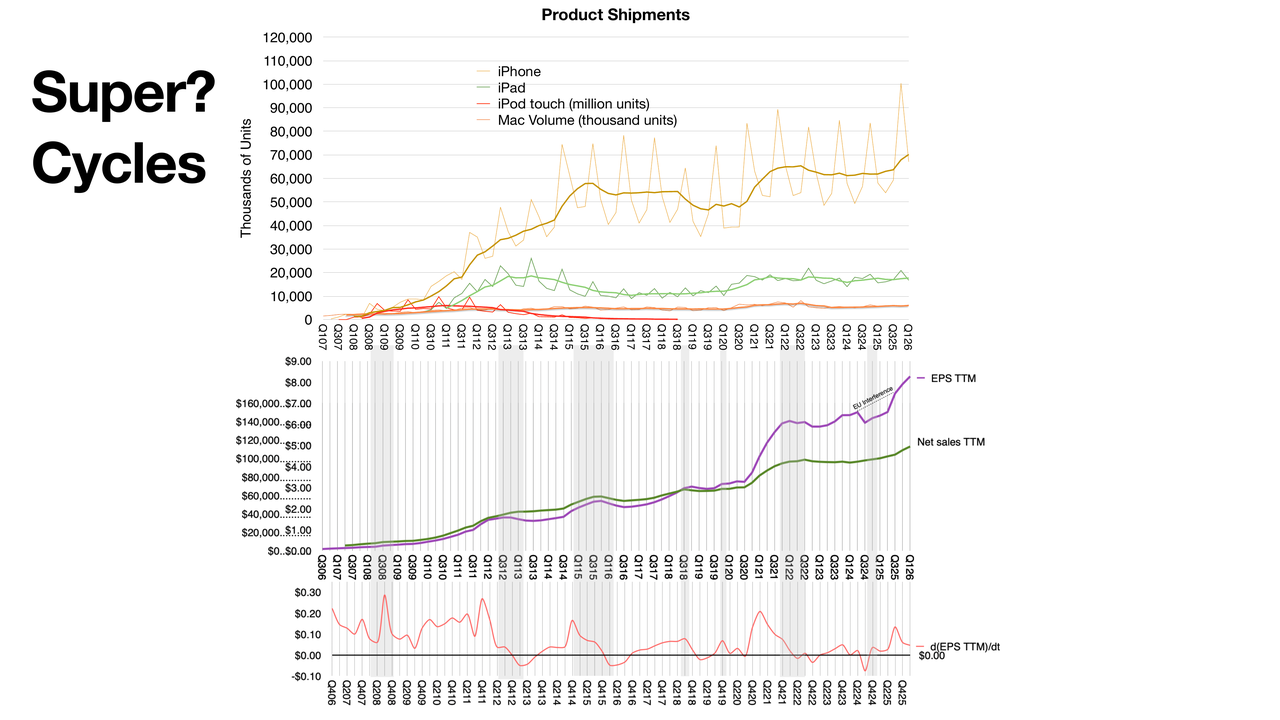
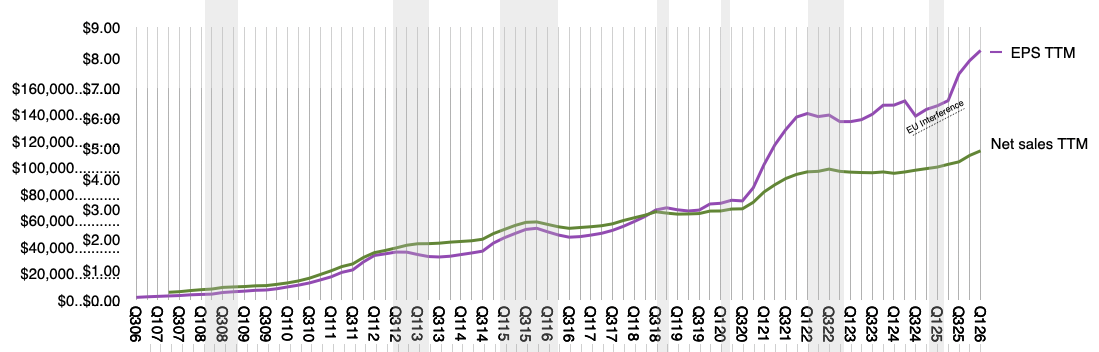
There are two graphs here. The bottom graph shows in green the net sales, but trailing 12 months, so it's smoothed out, so we don't see the spikes on the holidays. That's the green line. Above that, we have the EPS line. Now you'll see how they tracked very similarly for a while, and then they began to diverge. That occurred around COVID. It also occurred during the surge in services, especially subscriptions and services. But still, there's a similar pulse, if you will, a cyclicality to it.
I mean, part of that has to do with the introduction of a new form factor. This has been true all the way back since 2012. When a new iPhone comes, especially a new, distinctive-looking iPhone, people will go out, especially in China, buy it for showing off that they have the latest, which there's nothing wrong with that. But then the second year usually is not the same, the phone is not new, it's the same form factor. That has to do a lot with tooling. That's a long, old story, that the tooling is depreciated on a two-year schedule, so you're going to produce roughly the same look a couple of years in a row, and then by the next cycle, you'll see people upgrading or replacing their older phones. So you're going to have this— I guess what they used to call a super cycle.
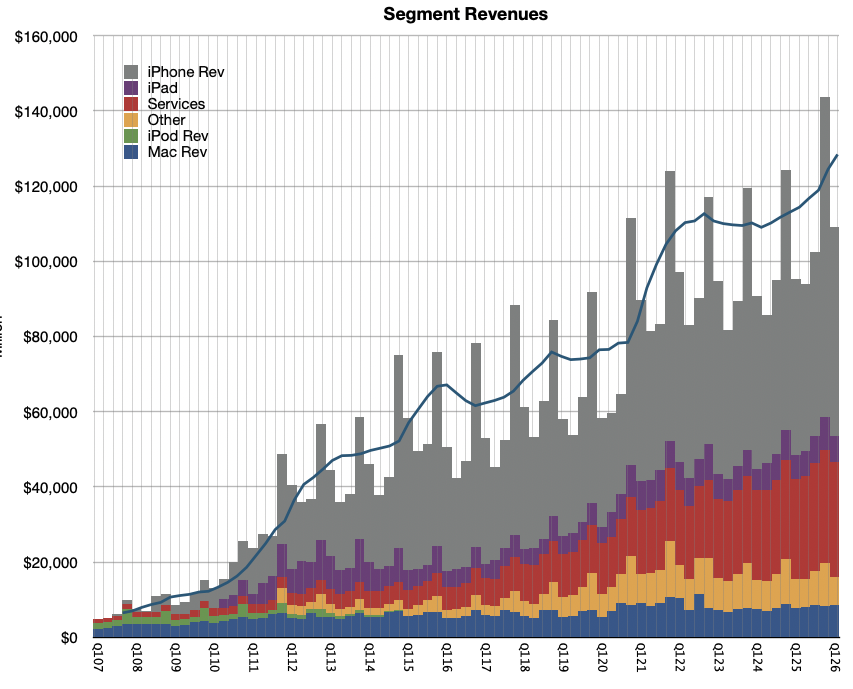
And you see it also in the upper graph, where I try to separate out of sales just the phones. Now this is an estimate because we have no unit sales for the phones since 2018, so some of that is an estimate. But you'll see again, once you smooth out the cyclicality, you'll see these surges once in a while. Now, again, this is a valid observation, but I don't think it's the main driver. The oscillation isn't huge, it might be significant, but it's a blend of many things.
The bottom graph is particularly interesting. The gray areas are when the stock price fell. And the red line represents the derivative of EPS. And you'll see how, when that is about to dip, there's usually a stock price sale going on. I wouldn't say it's predictive, but it's an interesting pattern to go through.
So what's happening now? You'll see from the iPhone, there's a new surge happening. Now, when Tim has been asked this question, he says that, well, the iPhone 17's really nice, people really love it, and that's a good answer, but the fact is, it's a distinctive-looking product. Some say it's the orange color, but it's certainly attractive. So we're seeing this pattern, a nice surge.
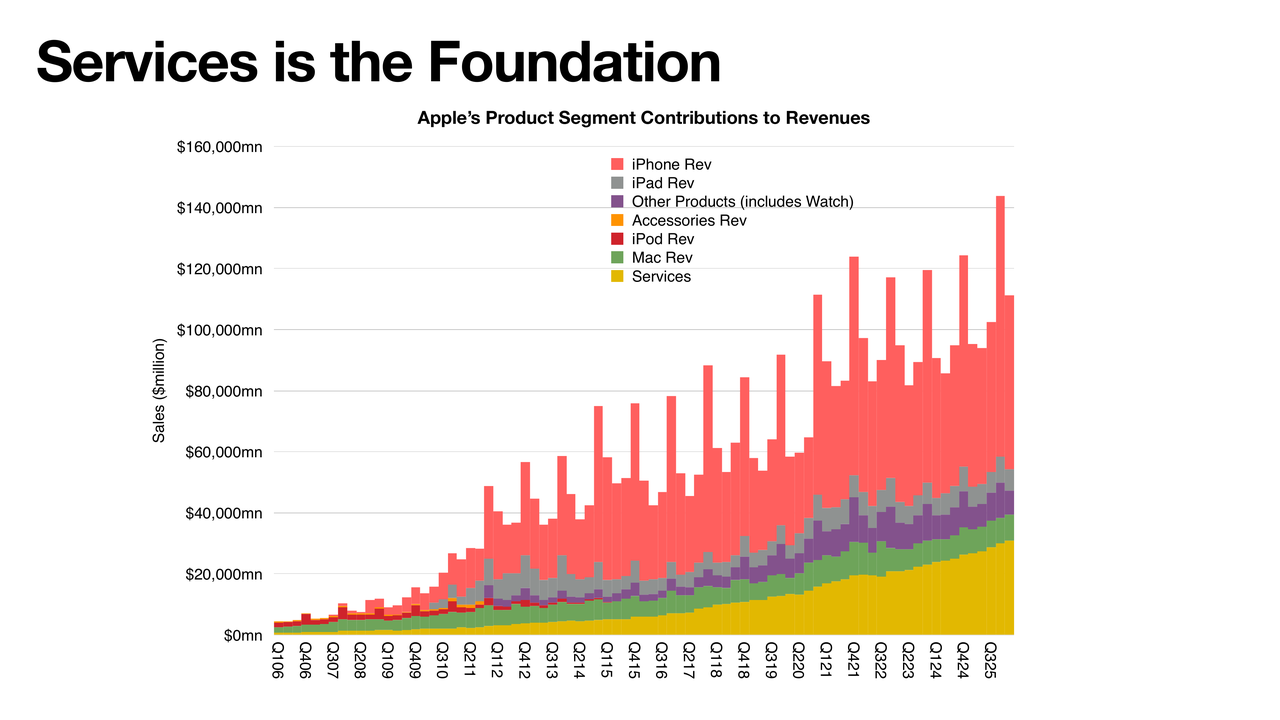
We'll get into the guidance in a minute, and that actually demonstrates that we're in some kind of an acceleration. But here's the thing, underneath all that, services is just absolutely steady growth, compound growth, and as a result, it just lifts the whole story.
Here, services is at the bottom. Normally, in a graph like this, you want to put the oldest products at the bottom and the newer ones at the top, but I wanted to highlight the fact that services is foundational, in the sense of showing how it holds up everything else.
Most people put it the other way, they say the iPhone holds everything up, but services is looking more and more to be the thing that keeps people in the ecosystem. There's a lot of value there. There's a lot of things people depend on there, and I think it's one of the reasons people don't switch. So it's another one of these stories that people aren't appreciating enough. It's been years and years of pounding the table on services, but here you see it, just how important it is. It's the tide that lifts all the boats, and the boats being all the products.
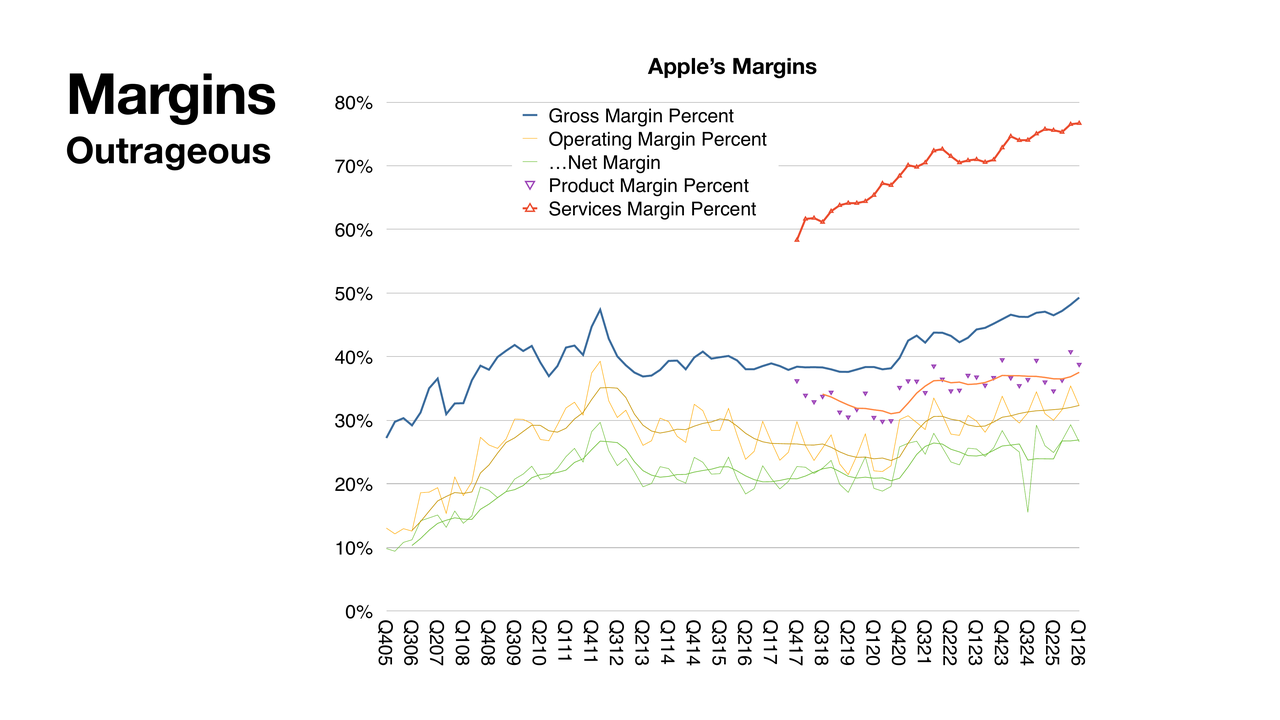
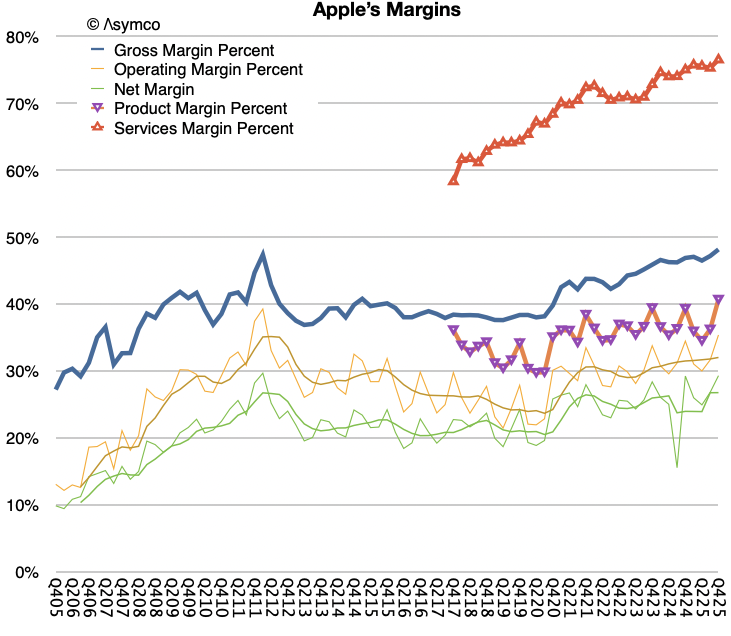
So let's now talk a little bit about margins. Unbelievable, unbelievable margins. We just hit almost 50% on gross margins. Gross margin here is the blue line. And that's composed of two subcategories. We have services in red at the top, and we have products with the purple triangles.
And although products margins are exceptional— they're right around 40%— those services, again, are pulling the whole average up, and you can see that bend in the curve in the blue line, where we were very steady around 40%, but as services took more and more; it just pulled the whole curve up.
And we also see here operating and net margins, which also are going up, naturally. There is a little bit more operating expense. We'll get into that, which maybe decreases the slope of the bottom line. But this gross margin is absolutely incredible. We just haven't seen anything like this since 2010-11. We saw that surge back then, and then it sort of leveled out, and everybody was happy with 40%, and now we're flirting with 50. I just cannot believe it.
Just one more thing. I remember being an analyst decades ago, when I was looking at different companies in hardware and software, in phones and computers and so on, and everybody was really impressed by Microsoft, because Microsoft, had an 80% gross margin, because there was very little cost of sales. That's exceptional. An 80% margin business is a money printing machine. And everybody was impressed and jealous of Microsoft that they could pull that off. Of course, Microsoft, a software company, is going to have extraordinary margins, right?
And so for a phonemaker like Nokia, there was something to be jealous of. And here we are with Apple services, a significant component on the business, approaching also almost 80% right now. And it's still rising. I just can't get over how impressive this is.
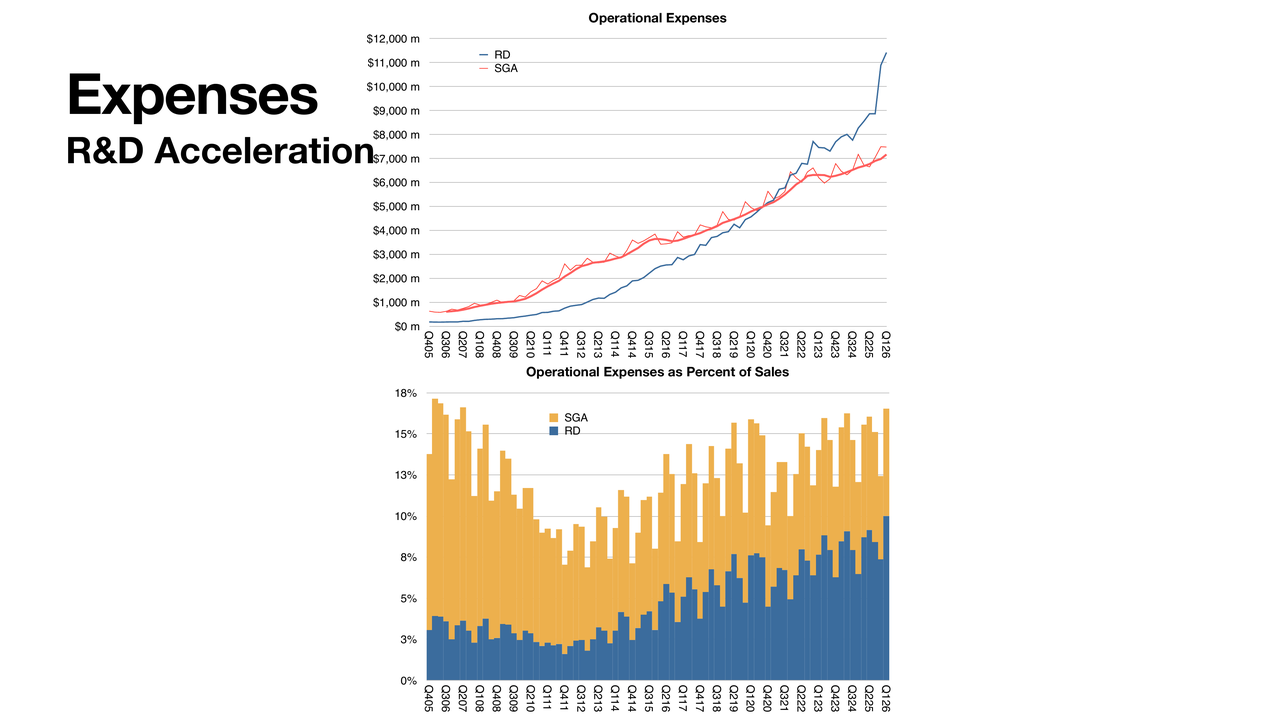
R&D Acceleration
A little bit about the difference between gross and net— you have to take out the operational expenses, and this is what we have here. It's interesting what's happened. Obviously, you see R&D overtaking on the absolute basis. So R&D overtook SG&A already in 2021. And now it's just [going] almost vertical.
By reading a little bit the guidance, I think it's going to taper a bit into the next quarter. But what we see is a significant R&D increase, also as a percent of sales, which you're seeing below in the graph below, but in a stacked fashion. In that sense, the two of them together are now approaching— haven't yet reached— a percentage of sales that was in evidence around 2007 and 8, when the iPhone was just emerging. But you'll see back then, R&D was tiny, SG&A was huge as a percent of sales. So much so that R&D—this is during Steve Jobs era, R&D was like 2% of sales. And now it's approaching 8%, which is extraordinary. Because that's an engineering company that's doing breakthrough work.
And that's something that Apple's not recognized for doing. There's a negative side of spending a lot on R&D. The positive, though, is that Apple is doing a lot of fundamental research now. This isn't fixing products, this isn't updating OS. This is engineering that is really driving what might be considered breakthrough. And that's something— and I've said this to the media when interviewed about Ternus and the succession— I said, the new CEO will need to be— this is before he was announced— I said [the CEO] would need to be someone who is acceptable to engineering, because Apple is an engineering company today. Fundamentally, culturally, operationally, it's an engineering company, and it is being now led by an engineer.
Steve Jobs was not an engineer. And none of the other CEOs were engineers. Tim Cook was an operations manager. He was excellent in a fundamental part of the business. And that is acceptable to engineers, culturally speaking. But the thing is that John is an engineer's engineer. He understands the culture of engineering and will understand how to motivate and retain talent, as well as to allocate capital effectively, not wasting it on pipe dreams. Engineers have a tendency to try to chase dreams, by the way, so you got to be harsh sometimes to shut things down. So, keep an eye on the R&D— it's a great story.
However overdoing it can be a problem. There are downsides to an engineering-led company where, again, it turns into kind of an engineering welfare state. Engineers tend to get projects and do a lot of navel-gazing, which needs to be managed carefully.
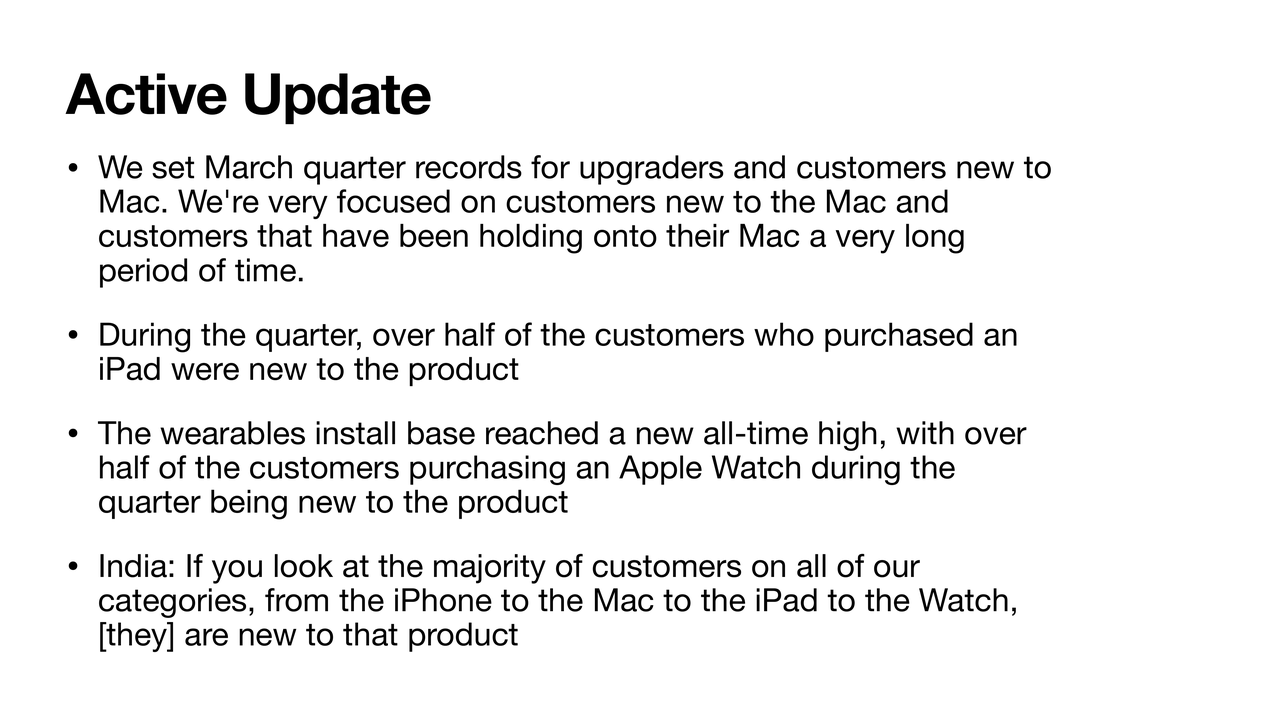
Now, let's just touch on ACTIVE. Active is the number of users, the fundamental measure of the value of the company. It's not counting iPhones. It's counting users, and these are the comments from management, just so we capture them. They come every quarter. Sometimes some products are mentioned, sometimes they're not.
So here's what we have exactly on the topic. Record upgraders and customers new to the Mac. They mentioned that Mac lifespans have been long, which is good and bad. They talk about the iPad, half the customers being— over half— new to the product. Same with the Apple Watch, this has been going on for a while.
So this is going to be important when we measure installed base, because if we see every quarter an estimate for the number of watches, or Macs, or iPads, you just take half of that and allocate it to the installed base, and the other half is growth of the installed base. So there's an interesting way to measure that, and I've been applying it. We're going to keep an eye on this.
And finally, there was a mention with respect to India during an answer to the question. The citation is that the iPhone, Mac, iPad, watch, all of these have a majority of customers that are new to the product in India. As you would expect, part of the developing market story. But this drum is still getting beaten. And that's a positive. Always want to look forward to that every quarter.
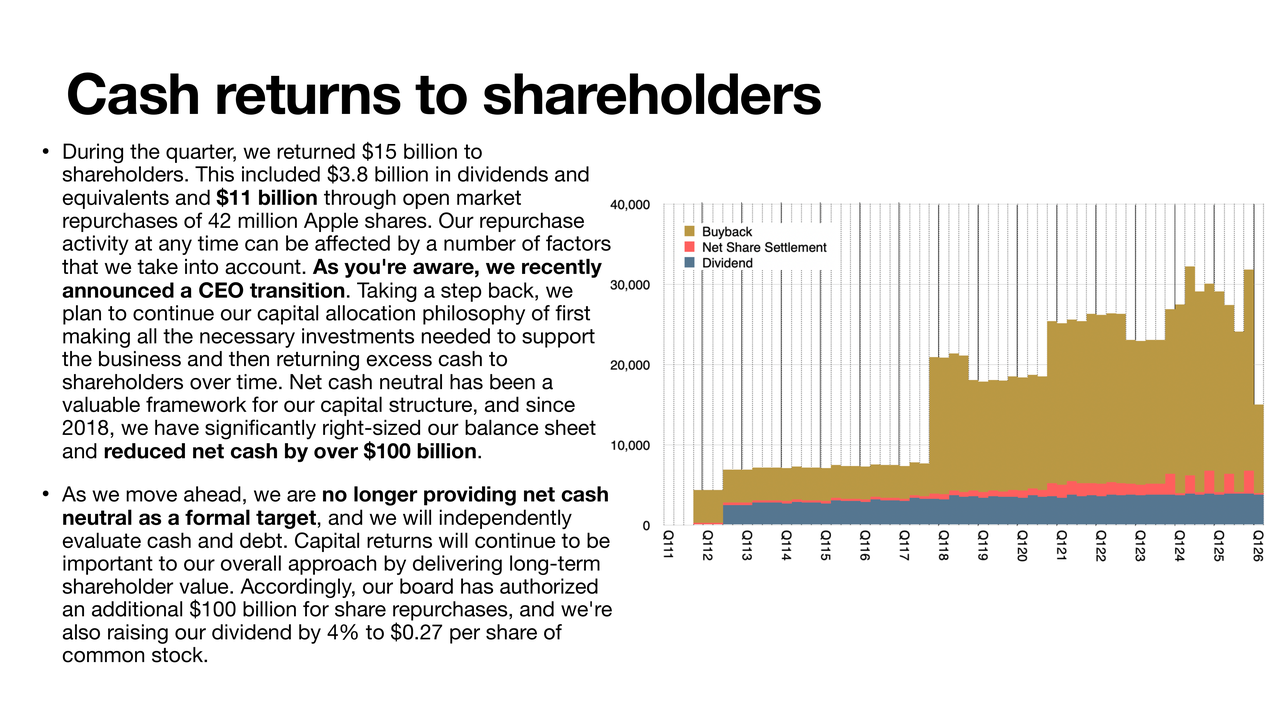
So let's jump in now to what I thought was the most unexpected comment during the call. I've pasted in here exact, verbatim the comments from the CFO. I need to point out a few things here, and I've highlighted these things in bold.
One is the dividend. The dividend number is 3.8. Last quarter was 3.9, so that's not a surprise. However, open market purchases were only $11 billion. Now, that is represented in the graph by the buyback, and that is this mustard color. And you'll notice it is extremely low. The previous quarter, we were over 25 on buyback, so we're less than half that. This is an anomaly. You'll see that it does not match the rest of the graph at all.
The blue area is dividends. The reddish area is net share repurchases, or settlements. And there's a pattern to both. Dividends has been growing in a predictable fashion, very steady. Buybacks have been somewhat steady, but up and down a little bit. During the last few periods, we've seen something unprecedented.
Now, you'll see that the 11 from last quarter was offset by a much higher number the previous quarter, but on balance, we're still down. And there's also these comments that say that they are abandoning the net cash neutral position. And I'm wondering if it's already started, because this $11 billion caught me by surprise.
I've highlighted that "our repurchase activity at any time can be affected by a number of factors that we take into account." So this was essentially explaining why sometimes there's a difference in the amount of purchases, right? And then in the middle of that commentary, he says, "as you're aware, we recently announced a CEO transition." Why does that comment fit in the middle of a paragraph, talking about the general theme?
I read this as it suggests that already the CEO choice is deciding how much to allocate to capital returns. And it appears— and again, I could be wrong— but it appears that John is probably against the idea of huge returns to shareholders in capital form. So keep an eye on this. This was, I found, very, very strange and out of character in a way. Very out of character of a Tim Cook presentation. I'm not judging it, I'm just pointing out that it isn't normal.
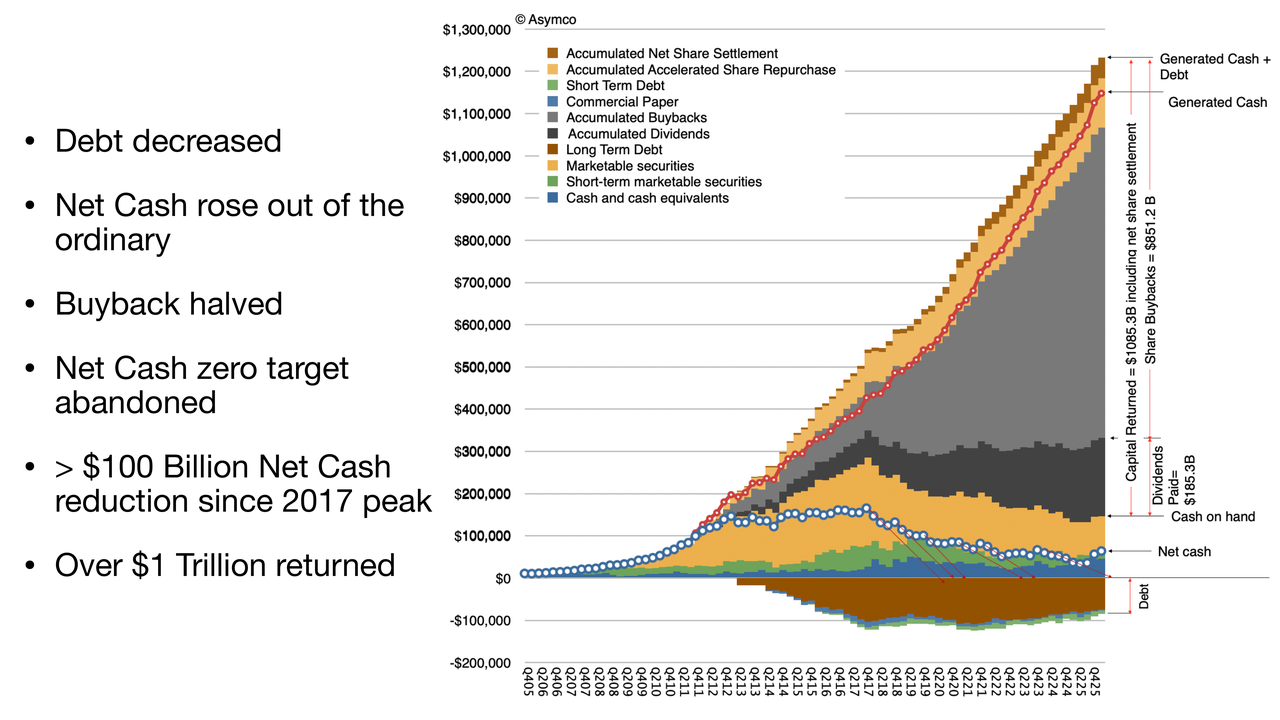
So here's the bottom line. This is the graph representing what's happening with the entire cash position and return of capital. The debt has decreased slightly, and it has been decreasing. And that's a good thing. As interest rates go up, you don't want to hold debt. A lot of that is fixed rate, but they're not taking on more. It seems like they're paying it down.
Net cash, which is the blue dotted line, has now been increasing two quarters in a row. Now, it's increased in the past, but never for long. It's had only one tick, during the holiday period. Here, where we're seeing two ticks— holiday and the quarter after.
Now, if you'll notice here, I'm going to try to zoom in. Those red lines represent what I would say were the trajectories to get to net cash zero. So that blue line, since they announced it, they kept missing the target. You would see that, another year goes by, and there's a notch up. Overall, the trend is down, but they haven't kept that path down all the way to zero. And that is now completely abandoned.
Again, we'll have to figure out why. The buyback, as I mentioned, halved— at least more than halved— to 11. Net cash zero abandoned, $100 billion net cash reduction. You'll see that this blue dot line has gone down by about half. It was down even further than that until it came back a bit. So that is going from about $160 billion net cash to the current $62 billion, which is why we get to 100 reduction. And $1 trillion overall return, which is, again, something they mentioned. In fact, they're at $1.085 trillion. And still $100 billion will be allocated further. Whether they actually spend it is another matter, but that's been approved.
So now— is this good news or bad news? I don't think it matters. I think at the end of the day, the value of the company doesn't change because of this. The value might be captured in the share price, or it might be captured as a percentage of the company that has been increasing.
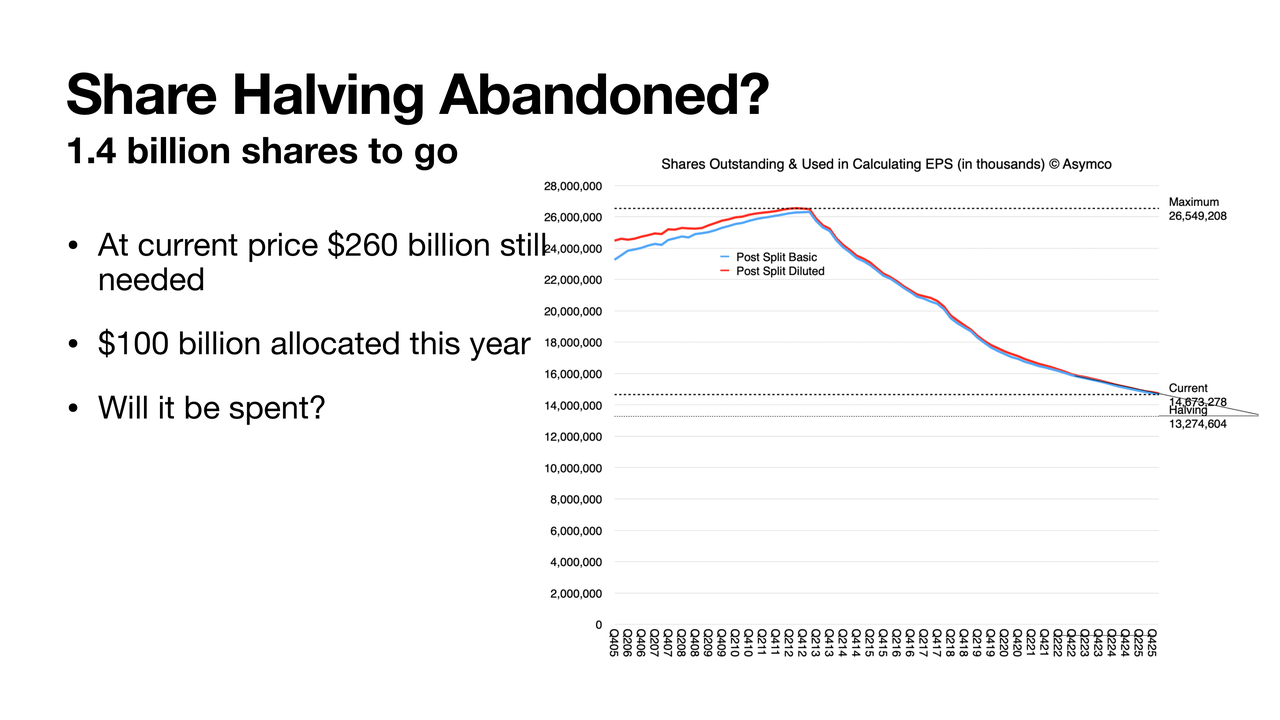
In fact, let me just pop into the next slide. What does this mean? Are we never going to reach what I call the halving? Well, we were at the maximum 26.5 billion shares. And now we've reduced that to about 14.6. Half would be 13.2. So we're still going down. But there's 1.4 billion shares to go before it's half of what the max was. Now, this is an arbitrary figure. I just thought it was an interesting target to have. And as you can see, it's getting asymptotic as the price goes up. It should be harder and harder to get there. But we have $100 billion allocated. $260 billion at the current share price would need to be spent to get to half. But probably we're not going to get there. I really don't— if I were a betting man, I would say we're probably going to see this taper.
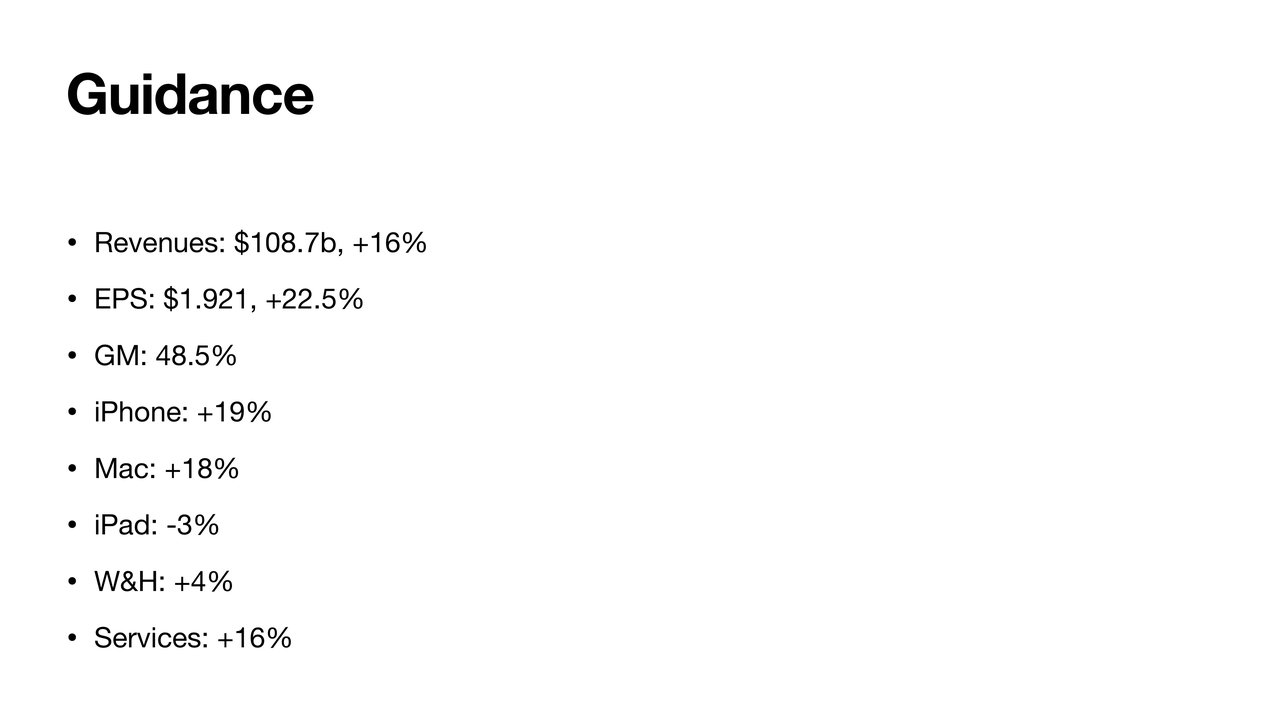
Let's look a little bit at guidance. This is based on what management already communicated. So if you put in the numbers they gave us, you will get revenue growth of 16%, coming at about— well, they guided 14 to 17, so I'm estimating 16 conservatively right now. That gets you to $108.7 billion. If you put in the other numbers— the margin, the OI&E and the tax— and do something about this share reduction. (We're still going to probably see a share reduction.) We're going to look at EPS 1.92. Which is another 22% growth. This is what we had last quarter as well.
I'm putting gross margin at the top of the guidance. [Last quarter] they went over. They guided high, and even so they went over, so I'm going to assume they're going to still hit towards the upper end of the range. I'm exactly at the upper end of that range.
If those things are true, the iPhone almost necessarily has to grow about 19%. Now, here, I'm dialing the Mac way up to 18% growth, because I do think they're going to get a lot more Mac Neos into customers' hands. Now, that's a lower price point, but it will drive sales. So yeah, I could be a little bit high on this. If I am, then iPhone needs to go a little bit higher because I still think they're going to get the revenue there.
They did warn that iPad is facing a tough comp, so I'm putting iPad down 3%. Wearables and home, 4%. It was 5% last time, so maybe consistency there. And Services, just the same as before, 16%, could come in a little bit less. But if it does, again, it's going to be put into something else like the iPhone.
So overall revenue growth, I think 16% is very much being telegraphed. And as I always say, they already have April on their books. They're communicating exactly at the end of April. They're not going to lie to us and withhold data from April. They know about a third [of the quarter] already, so that's why this guidance is so useful.
And, as you saw with my error analysis, nowadays, people's estimates are very close. There's a lot of consistency. We're not off more than a couple percentage from each other. That's just because they're so accurate on their guidance.
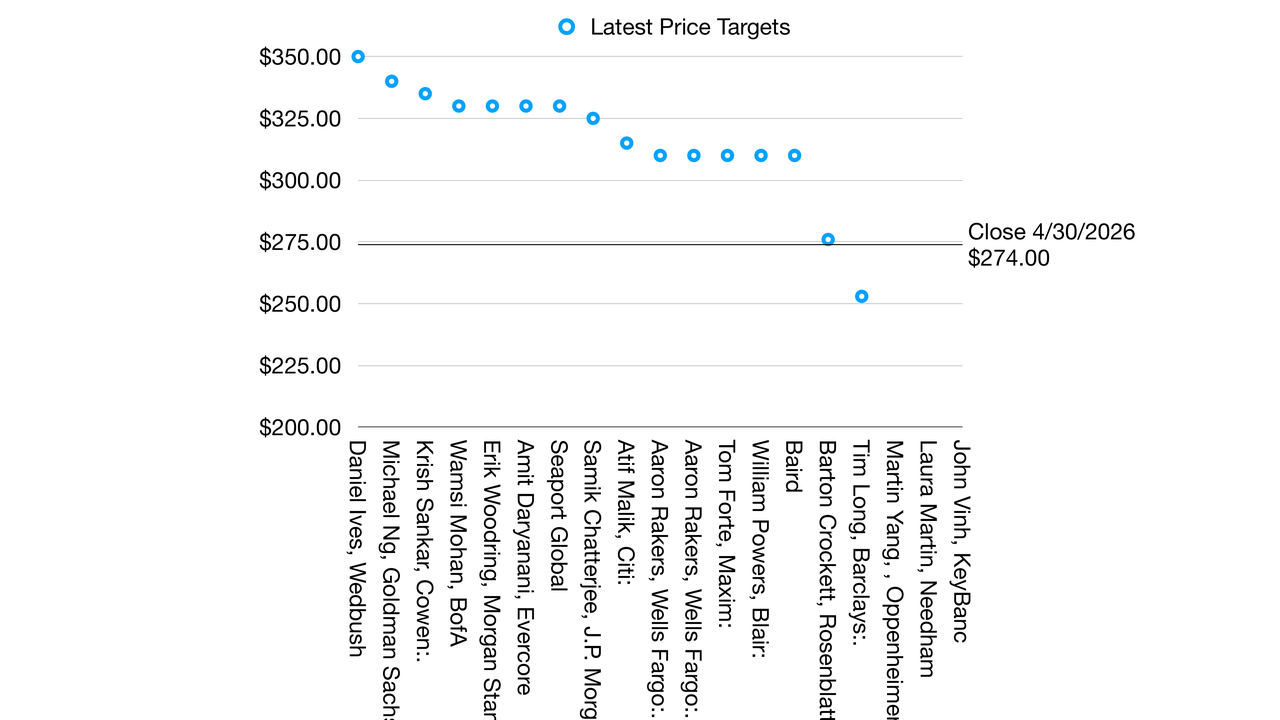
And speaking of analysts, one more graph. This is just some of the latest price targets. I'm just trying to bring everything together that came out today. This is all very brand new. A lot of targets moved up. Not that it's all that important, but people are getting more and more excited. Almost all the targets from anybody who has a positive— effectively a buy rating— is now above $310 as a target. There's two who are negative, that are at 270 and below. This is Barclays and Rosenblatt. And then there's a few which have no ratings. So they're typically neutral.
But overall, all these numbers are higher than they used to be. Now, again, I don't use that very much, but it's worth keeping an eye on things just to get a sense of how the sentiment is out there. And it looks like the stock is responding positively today. Not by much— 3% or so, last I checked. But that's the story today.
So given that, this is my first take on the quarter. Love to take questions.
-- End of Presentation --
Editor's Note: This presentation is made available to non-subscribers for a limited time. Subscribe to Asymco Oneforfull access to this and other content.
Expectations are low due to memory pricing, apparently.
Apple has multiple catalysts for strong revenue growth, so investors shouldn’t be spooked by any margin pressure from rising memory…
“Memory inflation will pressure margins, but this is well-known, and iPhone revenue upside sets up for a better than feared June quarter guide,” Woodring wrote.
He added that any announcements regarding an AI powered Siri at the company’s Worldwide Developers Conference in June, and the expected release of a foldable iPhone, would be positive tailwinds that can help push the stock higher after earnings.
Woodring, who rates the stock as Overweight with a $315 price target, also thinks Apple stands out against large tech peers as the company continues to report strong free cash flow while competitors continue to spend massive amounts of capex on building out AI infrastructure.
We expect gross margin downside to be more than offset by revenue upside in the June quarter guide, making for a better than feared earnings and a clearing event into WWDC this June, and the iPhone launch in September.
While our gross margin forecast remains below Consensus given rising memory cost pressure, continued strength in iPhone, Mac, and Services revenue should more than offset this pressure and result in a June quarter implied EPS guide in-line with Street estimates (~$1.74) – a better-than-feared outcome against relatively low expectations.
At 28x next year GAAP EPS – roughly the midpoint of Apple's historical 24-34x valuation range – valuation is neither cheap nor taxing, but with our ~$10 of FY27 EPS 5% above Consensus, we see a path to $300 for Apple shares by this September, driven by modest multiple expansion and more robust positive EPS revisions.
Revenues and growth rates for iPhone, Mac, iPad, Services, Wearables, plus Net Sales, Gross Margin, Operating Expense, Other Income and Expense, Tax Rate, Net Income, Share Count and EPS with a comparison to CFO guidance.
Kevan Parekh, Apple CFO: As we move ahead into March, I would like to review our outlook, […]. We expect our March total company revenue to grow by 13% to 16% year over year, which comprehends our best estimates of constrained iPhone supply during the quarter.
We expect services revenue to grow at a year-over-year rate similar to what we reported in December. We expect gross margin to be between 48-49%. We expect operating expenses to be between $18.4 billion and $18.7 billion, which is at a similar level to what we reported in December and driven by higher R&D on a year-over-year basis. We expect OI&E to be around $100 million, excluding any potential impact from the mark-to-market of minority investments, and our tax rate to be around 17.5%.
I've seen several market reports which estimate that iPhone shipments grew around 3% to 6% in the quarter. When I plug in, say, IDC's iPhones number into my model, and assume quite aggressive growth on the other categories (including Services) I get a y/y revenue growth of 11%. This is far below Kevan's January's guidance quoted above (13% to 16%).
Are IDC, Gartner, et. al. signaling a huge miss?
I need to point out that in the preceding December quarter the iPhone grew revenues at 23%! In order for Apple to hit its targets
I'd also point out that when Kevan Parekh made his forecast, in late January, a full month was already on the books for Apple. Visibility into the next month would have been relatively good as orders from the channel are partly foreseeable. For a change from implying nearly 20% growth in sales/14% in units one third of the way in, to IDC's 3% in units for the whole quarter would imply a collapse in demand into February and March. We're talking double digit decline in order volumes.
Moreover, IDC commentary on Apple is
Apple secured second place, driven by the strong performance of the iPhone 17 series, which saw significant growth in China of over 30%. This led to a 3.3% year-over-year increase in global sales for Q1. Although demand remains robust, supply disruptions and a reduction in channel support in some key markets have hindered growth..
30% growth in China! For this to be tied to 3.3% growth globally would imply significant declines elsewhere. I struggle to see how this adds up.
Here is my complete forecast for the quarter including growth rate for revenues for iPhone, Mac, iPad, Services, Wearables, Net Sales, Gross Margin, Operating Exp., OIE, Tax Rate, Net Income, Share Count and EPS with a comparison to CFO guidance.
Attach rates for iCloud reached about 42%, while Apple Music stood near 30%
The iPhone ecosystem is showing signs of increased customer loyalty and steady demand, while its high-margin services business remains a key support to profitability, according to UBS analysts.
The bank, which maintains a 'Neutral' rating on Apple with a 12-month price target of $280, cited findings from its Evidence Lab survey of roughly 4,000 iPhone users globally. The data suggests that iPhone “stickiness” continues to improve, even as replacement cycles remain relatively stable.
UBS said the average age of iPhones in use globally was largely unchanged year-over-year at about 33 months. Outside China, device age edged slightly higher to around 38 months, a trend the analysts said could push some upgrade demand into 2027.
At the same time, customer retention strengthened, with the global iPhone retention rate rising about 200 basis points to roughly 74%. Gains were particularly notable in the United States and China, where retention increased by 200 and 700 basis points, respectively. UBS belives that this indicates Apple is maintaining share despite a competitive smartphone market.
Purchase intent also improved across regions, with more surveyed users indicating their next smartphone would be an iPhone. The UK recorded the largest increase, while China also saw a meaningful rise despite what UBS described as a challenging competitive backdrop.
The report highlighted continued growth in Apple’s services ecosystem, particularly iCloud and Apple Music. Attach rates for iCloud reached about 42%, while Apple Music stood near 30%, trends UBS said should help sustain services gross margins above 75% through fiscal 2026 and 2027.
Higher-tier iCloud usage is also increasing, even as Apple raises base storage on newer devices. Among iPhone 17 users, 77% reported subscribing to mid- to high-tier iCloud storage plans, compared with roughly 60% across the broader installed base. UBS noted that additional services uptake carries incremental gross margins of at least 90%, helping offset potential pressure from rising memory costs.
On the hardware side, consumers are also opting for higher storage configurations. UBS wrote that 56% of iPhone 17 users purchased models with more than the base storage, up about 800 basis points year-over-year. This shift could support product margins, with incremental storage estimated to generate gross margins of around 75% on roughly one-fifth of sales.
Looking at the installed base, UBS estimates about 68% of iPhones in use are from the 14 through 17 series, while around 40% are Pro or Pro Max models. The analysts said this premium segment could be a target market for a potential foldable iPhone, though they expect the opportunity to be relatively limited given the anticipated price range of $2,000 to $2,500.
UBS estimates a foldable launch could result in as many as 8 million units in fiscal 2026, contributing roughly 6 million incremental iPhone shipments, or about a 2% uplift to its forecast of 251 million units.
On January 30, JPMorgan analyst Samik Chatterjee raised the price target on the stock to $325 while reiterating an “Overweight” rating. The firm is confident on the stock as it sees Apple results as reassuring for investors.
According to the firm, Apple’s latest financial results should help “calm investor nerves” about memory-related impacts on gross margins and concerns regarding a Services slowdown. This is despite the magnitude of iPhone revenue upsides, which is “noteworthy” itself.
JP Morgan also highlighted Apple delivering “record Product gross margins” in the December quarter, with the March quarter also anticipated to show record product gross margins.
This, the firm believes, should help investors be reassured regarding the materiality of the impact that investors have been concerned about related to rising memory costs.
“Record Product gross margins in the December quarter and an implied March quarter record Product gross margin should help reassure investors around the materiality of the impact that investors have been concerned about in relation to rising memory costs, even though management acknowledged slightly higher impact in March quarter than the December quarter.”
While the commentariat assumes the worst, Apple delivers the best.
Last quarter Apple delivered a gross margin of 48.2%. This was above the high end of their guidance range and up 100 basis points sequentially. Management commented that this was "driven by favorable mix and leverage."
Further, products gross margin was 40.7%, up 450 basis points sequentially, driven by favorable mix and leverage. Services gross margin was 76.5%, up 120 basis points sequentially, driven by mix.
This performance is even more astonishing considering the history shown below. Apple is quite simply, delivering at the highest gross and net margins in its history.
Note that the graph actually projects forward one quarter because we have the following guidance: "We expect gross margin to be between 48-49%." The graph reflects the high end of this guidance range.
So what's going on? Especially as a drumbeat of constant doom is being broadcast by pundits. The conference call itself seemed to be dedicated to margins. It became what I call the Margin Call.
Amit Daryanani, the first questioning analyst, specifically kicked off with the following:
"there is a lot of focus on the impact of memory to host the companies, and I would love to kind of get your perspective when you are first guiding gross margins up into March. Talk about, a, your comfort in securing the bit that you need for shipment and b, how do we think about memory inflation flowing through Apple's model over time?"
Tim Cook answered:
We are currently constrained, and at this point, it is difficult to predict when supply and demand will balance. The constraints that we have are driven by the availability of the advanced nodes that our SoCs are produced on. And at this time, we are seeing less flexibility in the supply chain than normal, partly because of our increased demand that I just spoke about. From a memory point of view, to answer your question, memory had a minimal impact on Q1. So the December gross margin. We do expect it to be a bit more of an impact on the Q2 gross margin, and that was comprehended in the outlook of 48 to 49% that Kevin gave earlier.
what Apple is saying is that they are constrained by production of silicon but not of memory. They do see some impact in the future but that is included in a guidance of margin expansion.
Analysts still could not believe this, the following exchange soon followed:
Ben Reitzes: So the next question is on gross margin. I am pretty shocked I gotta hand it to you, Tim. I am, you know, that you are able to do 48 to 49. What is really going on there? How are you doing that with this memory, the NAND prices? Is it due to mix that there is a good less hardware and more services? Services and services margins are going up. How are you doing it to keep it at 48 to 49?
Kevan Parekh: Yeah, Ben. This is Kevin. [] Let me start maybe by just reflecting on the Q1 gross margin. I think we talked about the fact that we landed at 48.2%, so just above the high end of the range we provided, [], on the last call. [] if you look at that performance, [], we were up 100 basis points sequentially. We talked about the fact that we had favorable mix. [], as you know, when we have a good product cycle, strong price cycle we are seeing for iPhone, that does lend itself to a bit more favorable opportunity on the [] leverage side.
So we are having a strong iPhone cycle as Tim outlined. And so that also translates itself. So we talked about products sequentially went up by 450 basis points. So I think, in general, I think we are just seeing, [], favorable mix dynamics as well. [], service continues to contribute as well. That business is growing, [], double digits, so that also is a contributor. And I think that, [], if you looked at our guidance, [], we are providing a similar range to where we reported in December. There are going to be a few puts and takes. [], we do expect to see favorable mix in the services.
As you know, when we move from Q1 to Q2, that tends to be the case, and that is partly offset by a seasonal loss leverage. So there will be puts and takes, but again, we feel pretty good about the guide of 48 to 49%, which is similar to the range we reported in December.
Still not enough. Two more questions followed on margin. I will quote one here.
Aaron Rakers: Yep. And then as a quick follow-up, you know, kind of tied to memory, maybe not so much, but part of this current generation iPhone cycle is you clearly deepened some of your own internal silicon capabilities on the device. I am curious if that if we should think about that as a lever and maybe a supportive factor to gross margin that might be underappreciated and any thoughts on where we go from here as far as continual opportunities of internalizing your own silicon? Thank you.
Timothy D. Cook: Yeah. I will let Kevin talk about the gross margin. But in terms of the product, which is at the heart of what we think about in the user, Apple silicon has just been an incredible game changer for us. Starting with iPhone and then on iPad and, of course, the Mac as of a few years ago. And so we believe it is a game changer and a major advantage.
Kevan Parekh: Yeah. And as far as impact on gross margin, yeah, we have been, as you know, investing in core technologies like our own silicon and our own modem. And certainly, while those do provide opportunities for cost savings and can be plugged in margins, they also importantly provide, [], the differentiation that is really important for our products as well and us more control of our roadmap. So I think there is a lot of strategic value to it, but also we are seeing, [], investments in our core technologies impacting, [], gross margin in a positive way.
After all this, the financial commentariat continues to assume that Apple will be hit with margin pressure from memory and that has presumably been affecting the share price since the call.
Well, we've seen all this before. Before the great memory crisis Apple was going to be constrained by tariffs, by China, by developer dissatisfaction, by AI, by regulators, etc.
The feeling one gets is that Apple is always navigating through a minefield of pitfalls and gotchas. The opposite is true. It's highly likely that Apple has sufficient leverage which increases its access to supply and that everyone is keen to work with the company. Leverage comes from scale, from lead time, from vertical integration and from engineering. Management is saying as much. Indeed, the evidence of leverage across the supply chain and over the entire ecosystem and economy is evident in its margin expansion story told in the graph above.
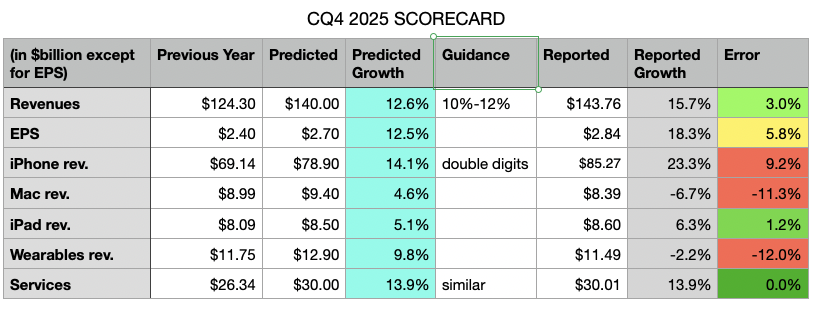
My predicted growth is in the light blue column, the reported growth is in the grey column and my errors are in the last column. Also included is the guidance from the previous quarter's conference call.
The table shows my errors were primarily in underestimating iPhone, while over-estimating Mac and Wearables. The errors mostly cancelled each other out on the top line (off by 3 percentage points) but, due to an underestimation of the gross margin led to a bottom line error of 5.8 percentage points.
The Mac overestimation was based on not paying enough attention to the comparable from the year earlier. I was warned: "On Mac, keep in mind, we expect to face a very difficult compare against the M4 MacBook Pro, Mac Mini and iMac launches in the year ago quarter". Wearables are similarly underperforming due to lack of new product launches.
But the iPhone underestimation is simply because the new products are a massive hit. Nobody predicted this level of performance. Indeed Apple was caught by surprise and has been unable to meet demand. They are still going to be below supply/demand balance going well into the first quarter of 2026.
Finally, an error on the margin came from Apple's continuing over-performance on supply chain management.
Apple is providing the following guidance [my emphasis]:
We expect our March total company revenue to grow by 13% to 16% year over year, which comprehends our best estimates of constrained iPhone supply during the quarter.
We expect services revenue to grow at a year-over-year rate similar to what we reported in December. We expect gross margin to be between 48-49%. We expect operating expenses to be between $18.4 billion and $18.7 billion, which is at a similar level to what we reported in December and driven by higher R&D on a year-over-year basis. We expect OI&E to be around $100 million, excluding any potential impact from the mark-to-market of minority investments, and our tax rate to be around 17.5%.
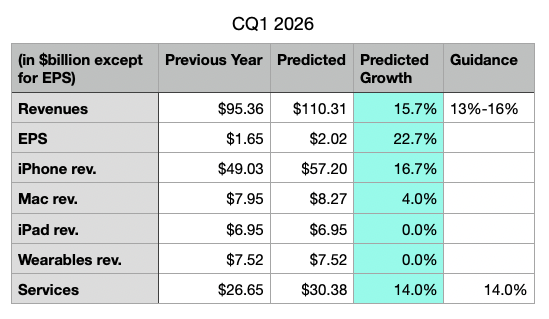
Based on provided guidance, I'm making the following predictions for the next quarter:
It's vey important to note that Apple is guiding gross margin to be between 48-49%, a record high and something that we will discuss in the next post. This results in a 22% to 23% EPS growth rate!
Note also that Apple guided revenue growth between 10% and 12% and delivered 12.6%. They guided grass margins between 47% and 48% and delivered 48.2%. It's highly probable that their top-of-the-range guidance will also be exceeded slightly and that my current estimates are therefore modest. [NB: the guidance is being put forward at the end of the first month of the quarter therefore the company already has booked one third of the quarter and has very clear visibility into the next third.]
According to JP Morgan analyst Samik Chatterjee, citing Sensor Tower, Apple's App Store revenue for May 2025, increased by 4.9% month-over-month (which compares to an average sequential increase of 2.3%) and an acceleration of year-over-year revenue to 13.0% in May versus up 11.8% in April. On a year-over-year basis, the App Store downloads increased by 3.1% in May (versus +5.8% in April) according to Chatterjee.
This analysis is based on app download sampling and may be indicative of the activities of consumers on the App Store. Services revenue in the first calendar quarter was $26.6 billion, up 12% year-over-year and at an all-time revenue record. Services gross margin was 75.7%, up 70 basis points sequentially, also an all-time record.
The world however seems to be having a problem with Apple Services. After years of skepticism of its relevance, now that it has achieved a run level above $100 billion/yr., it's being criticized for being harmful to competition.
The comments that it's unfair to developers or that it deters innovation are uninformed to say the least. What is missing from that analysis is that the App Store is only a small fraction of the entire ecosystem around Apple's platforms and that the economic activity the platforms enable is immense.
Let's learn.
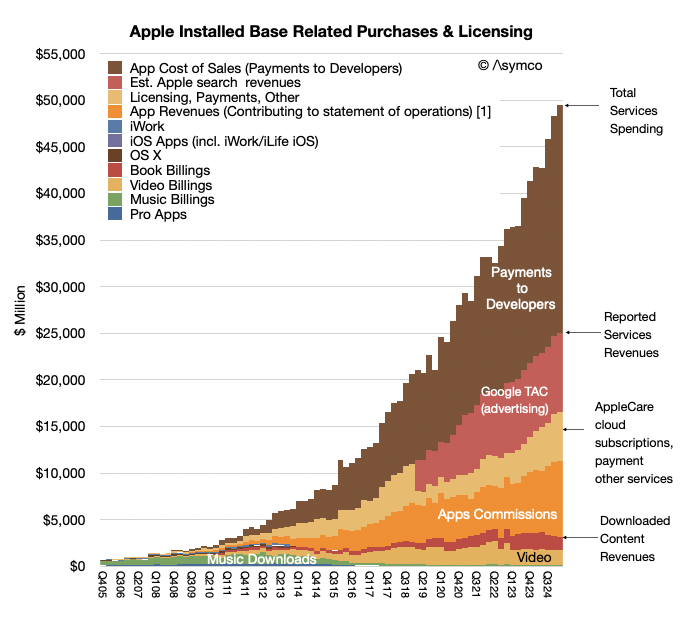
Over the last year Apple reported a bit more than $102 billion in revenues for Services at a very high margin. The reason it was such a high margin was partly due to the fact the Services does book all payments from customers through the App store as revenues. In other words it does not include payments to developers as either revenue or costs. Those payments pass through but they are certainly part of the economic activity on the store. It would be indeed unusual for a physical store not to report what it pays for what it sells as part of revenues. But this is the basis Apple chose (or was obligated to choose) as the way to report App Store revenues.
Thus considering the payments to developers, the economic activity directly related to the App Store amounts to $120 billion/yr which includes commissions of about $30 billion/yr (last 12 months) and payments to developers of about $90 billion/yr (implying about 25% blended average commission rate.)
So including payments to developers the Services business grosses $186 billion/yr. of which 102 billion is reported as revenue, with the 75% gross margin and $90 billion is paid to developers "off the books".
But that $102 billion in revenues is only about 30% App Store commissions. The rest includes many types of income: It includes:
Advertising which consists of Apple's own advertising services and third-party licensing arrangements notably the distribution fees for Google search (accounting for most of Googles "TAC" or traffic acquisition costs.
AppleCare, Apple's own extended warranty service.
Cloud Services which provide content synchronization.
Digital Content which not only includes the App Store but also stores for books, music, video, games and podcasts. Apple also offers digital content through subscription-based services, frequently bundled, including Apple Arcade, essentially a game subscription service; Apple Fitness, a personalized fitness service; Apple Music, which offers music streaming and on-demand radio stations; Apple News, a subscription news and magazine service; and Apple TV, which offers exclusive original content produced by Apple and live sports access licensed sometimes exclusively by Apple.
Payment Services which offers Apple Card, a co-branded credit card, and Apple Pay, a cashless payment service.
The quarterly view is summarized in the graph above. So a fixation on the commission is only a view into 16% of Services as an economic foundation (the orange area in the graph above).
But that's still only a sliver of the whole picture.
A report written by Jessica Burley, Analysis Group and Professor Andrey Fradkin, Boston University Questrom School of Business has estimated that the global App Store ecosystem facilitated $1.3 trillion in developer billings and sales in 2024. As the report writers say: "For more than 90% of the billings and sales facilitated by the App Store ecosystem, developers did not pay any commission to Apple."
How is this not visible? The reason is that this economic activity is distributed over the millions of purchases Apple users make through its iOS Apps every day. This includes traditional App Store "Billings" including paid downloads and in-app purchases, including subscriptions, that use Apple’s in-app purchase system and “Sales” which includes money spent by customers purchasing goods and services in general using any iOS and iPad OS apps. Apps developed by Apple such as Apple Music, Safari or browser apps such as Chrome are excluded from this analysis.
The economic activity unleashed by the App Store now reaches well over $1.3 trillion/yr. As the authors further explain,
While the present analysis captures the major app monetization strategies available to developers, the full economic impact of the App Store ecosystem extends beyond the estimates provided in this report, as the current methodology does not capture all of the ways in which the App Store ecosystem facilitates sales, or all of the benefits created by apps. For example, the App Store supports “companion apps” that raise the value of a company’s goods and services, including smart home apps and health apps. In addition, many apps now use different monetization strategies. As such, this analysis does not account for all the ways in which the App Store ecosystem creates value.
Furthermore the report breaks down the categories as Digital Goods and Services, Physical Goods and Services, M-Commerce (General Retail, Travel, Food Delivery and Pickup, Grocery, Ride Hailing), Digital Payment and In-App Advertising.
In addition the report estimates these categories from 2019 as well as 2024 providing a growth perspective: Over the past five years, the App Store ecosystem has more than doubled in size, increasing from $514 billion in 2019 to nearly $1.3 trillion in 2024.
It also identifies regional dynamics between the US, China, Europe (with select countries) and Rest of World (with select Asian countries).
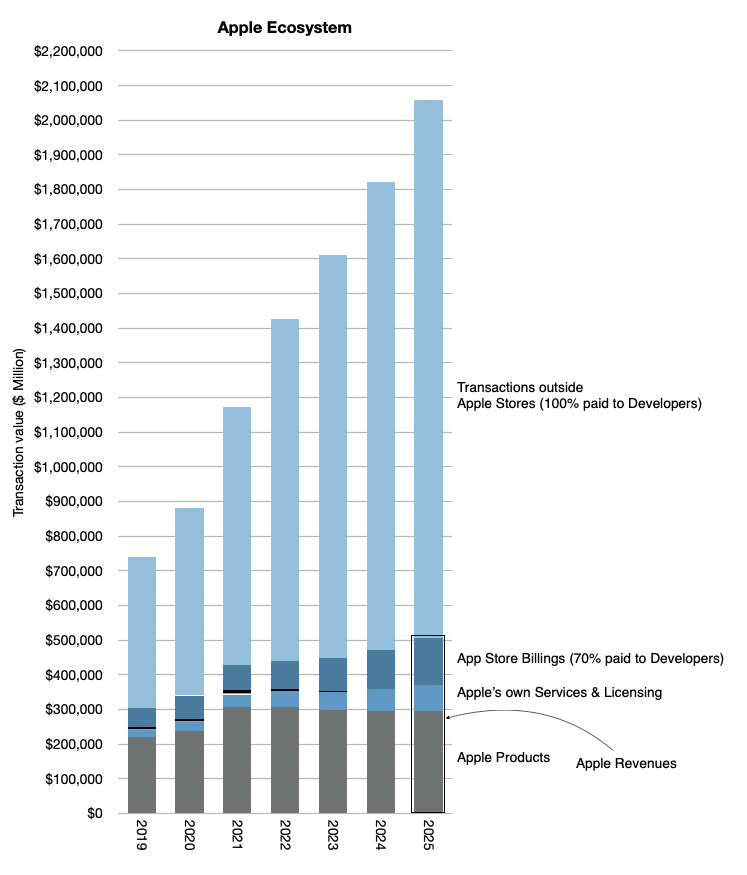
I've been keeping my own analysis of what I called the Apple Economy and it includes these transactions outside the App Store and Apple's own products and services. If I were to subtract Apple's own revenues from the total, for 2024 I was getting about 1.4 trillion (out of a total of over 1.8 trillion).
My point was always to estimate the economic impact of Apple beyond its own sales. This gave us perspective to assume that in 2025 the total would reach over $2 trillion. The graph below gives the perspective which also implies a doubling since 2020 to 2024.
The new report from Burley and Fradkin is a detailed, bottom-up analysis which quantifies what was perceived as the economic value of Apple being far more than what the financial data records.
Bill Gates once stated in reference to Zuckerberg's assertion that Meta was developing a "platform" that it's not a platform unless the economic value of everybody that uses it exceeds the value of the company that creates it.
Apple captures about $30 billion as sales but delivers over $1.3 trillion in sales, a multiple of 43! I would call that generous. In addition it doubles the market in 4 to 5 years. I'd call that market expanding not constraining. Finally, it's a market that Apple created out of nothing. I'd call that market creation not destruction.
If judged on the question of creation and satisfaction of the customer, i.e. the ultimate purpose of the firm, the App Store and Services in general has satisfied 1.4 billion people. That they are spending over $1.3 trillion and doubling in 4 years is nothing short of astonishing.
We'll discuss this topic and other topics related to Apple at ACTIVE: The Apple Investor Conference, which takes place on next Tuesday, June 10th, the day after the WWDC25 keynote.