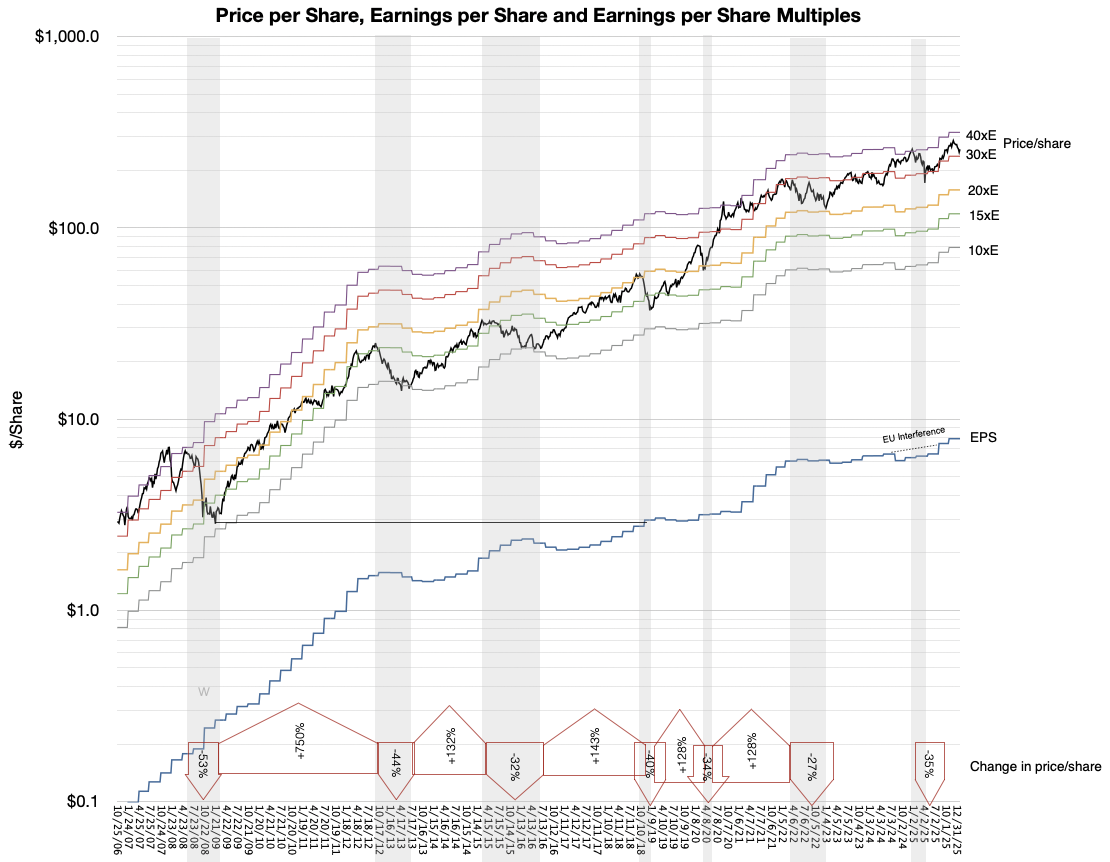
The analyst consensus price target sits at $297.46, with 31 Buy ratings against just 2 Sell ratings across 48 analysts. Both Citi and Morgan Stanley sit above consensus at $315, signaling above-average conviction. Apple stock is up 39% over the past year, so the transition arrives with the stock already reflecting significant strength.
Citi and Morgan Stanley both maintained Buy/Overweight ratings with $315 price targets on AAPL stock.
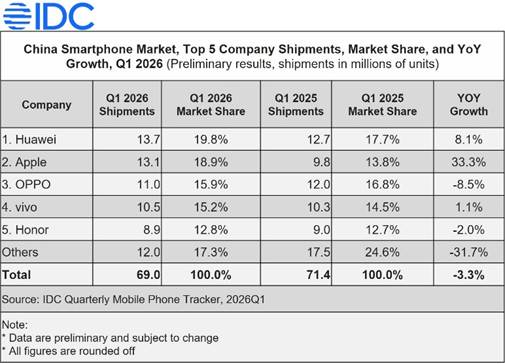
China smartphone shipments fell 3.3% in Q1 2026 to 69M units, with Huawei and Apple driving premium demand despite rising costs and supply constraints.
China’s smartphone shipments declined 4% YoY in Q1 2026, as memory shortages disrupted supply and drove up costs across OEMs.
Huawei led the market in Q1, supported by its domestic supply chain advantages and stable pricing. As a result, the brand recorded its highest-ever quarterly share in China since Q4 2020.
Apple delivered the strongest growth among the top six brands, and it is widely seen as best positioned to navigate the memory crunch.
NB: Both researchers say Apple share in China is about 19%, nearly tied with Huawei at 20%…
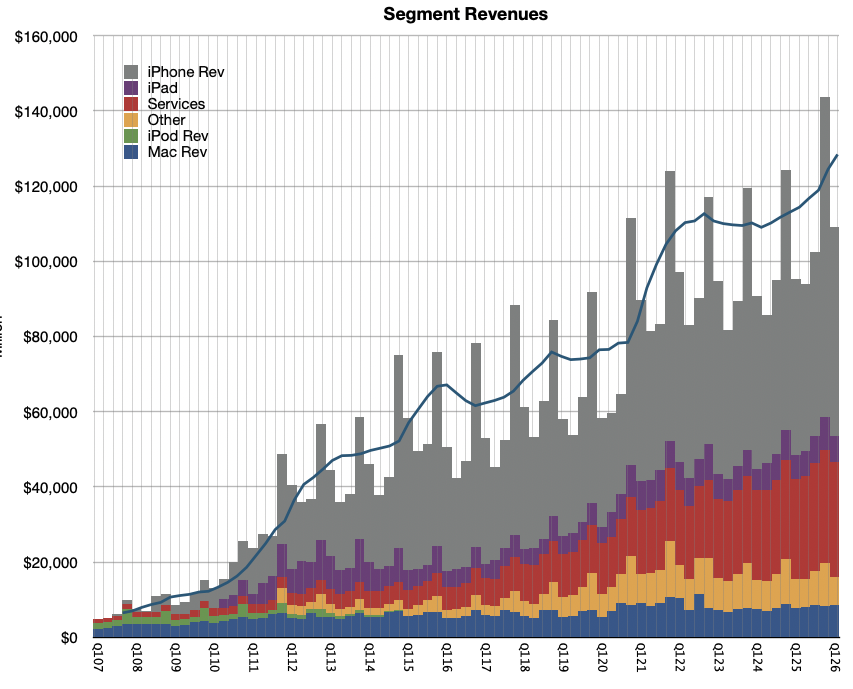
Revenues and growth rates for iPhone, Mac, iPad, Services, Wearables, plus Net Sales, Gross Margin, Operating Expense, Other Income and Expense, Tax Rate, Net Income, Share Count and EPS with a comparison to CFO guidance.
Ref. conference call's guidance, Kevan Parekh, Apple CFO: As we move ahead into March, I would like to review our outlook, […]. We expect our March total company revenue to grow by 13% to 16% year over year, which comprehends our best estimates of constrained iPhone supply during the quarter. We expect services revenue to grow at a year-over-year rate similar to what we reported in December. We expect →
In a recent interview Apple management was asked about AI, which is perceived as an area where Apple has been struggling. Greg Joswiak replied: We’ve been doing things with intelligence for many years, right? And gen AI allows us an opportunity to do that even more. So I’m excited about that, but boy, this is not a sprint. This is a marathon.
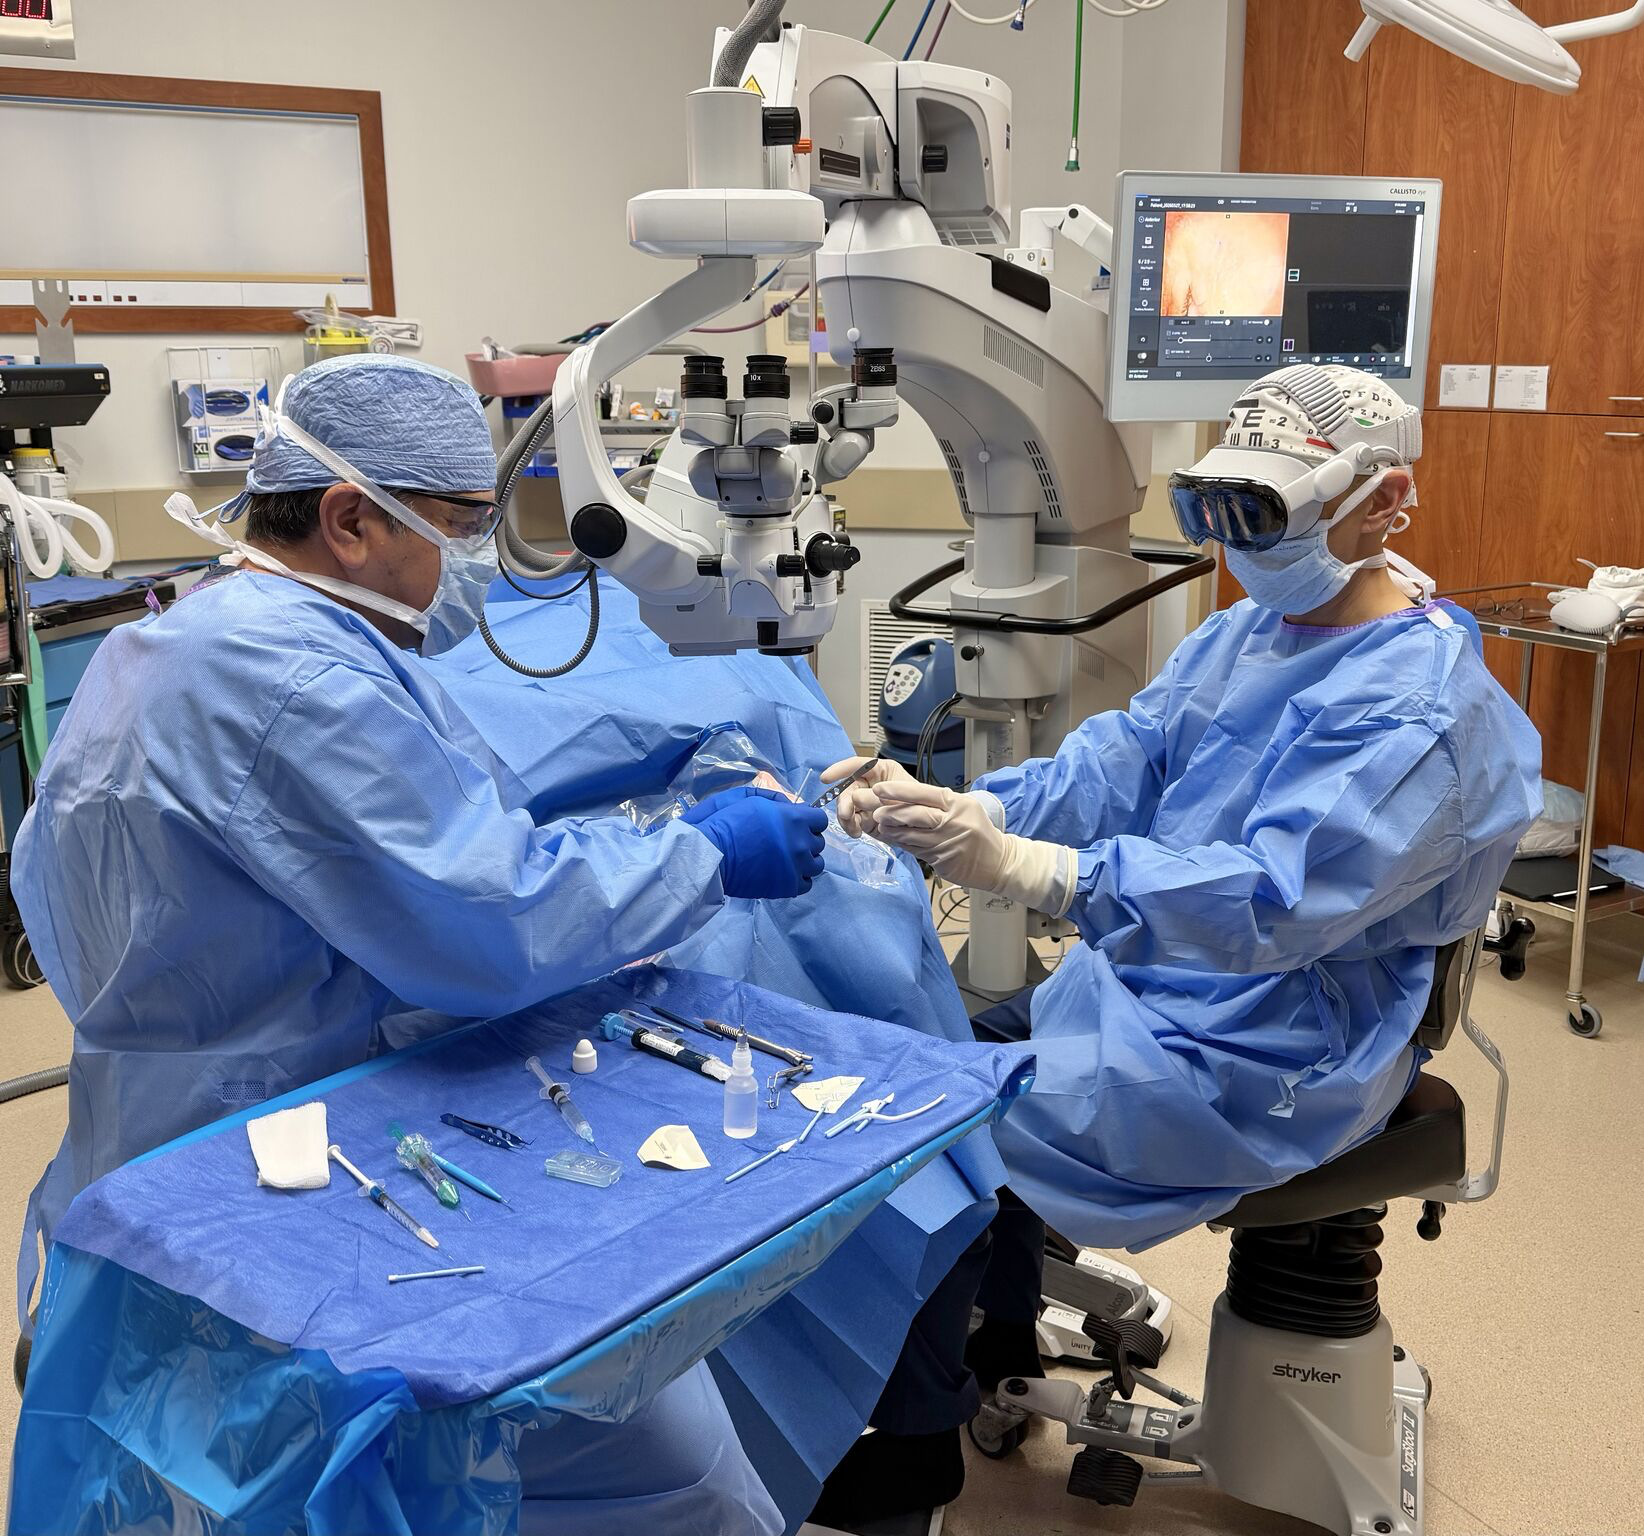
In contrast to AI, Spatial Computing is being largely ignored. It is however making significant leaps in utilization, especially in verticals. →
At just $3,000, the Studio Display XDR democratizes medical imaging, undercutting specialized monitors by up to 90% and revolutionizing healthcare accessibility.
The Studio Display XDR is priced at $2,899 with a VESA mount, and it is more affordable than many specialized medical imaging monitors.
It allows a new set of people to do what previously required only specialists to do and allows specialists to do more than they used to do. →
BofA slightly ups Apple's price target to $325, forecasting $113B revenue and $2.00 EPS for Q2, driven by strong iPhone sales and Services growth, slightly above my estimates of $110B and $2.00.
Q2 forecast update
My own estimates for Q2 revenues and EPS are $110B…
More to follow as we get closer to the earnings release date but this is a good preview. →
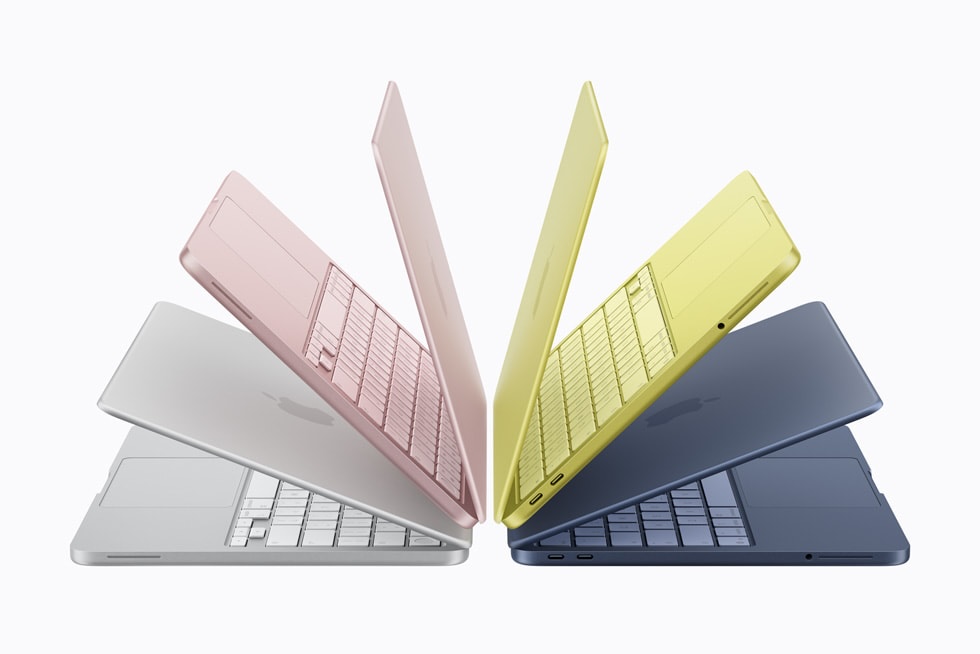
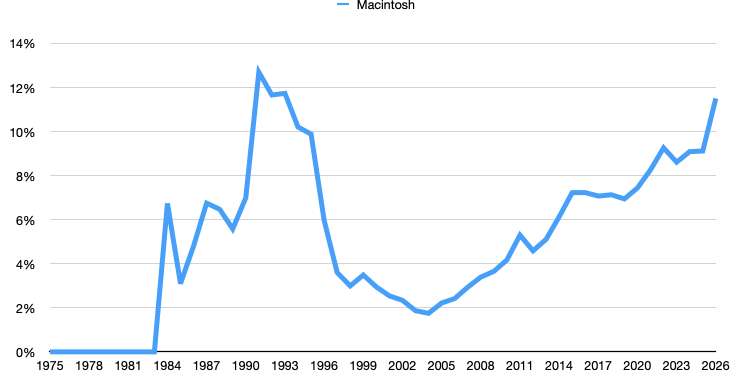
Apple's Mac shipments grew 5.4% to capture 11% market share in Q1 2026, driven by MacBook Air and Neo sales, with revenue estimates slightly differing from unit projections.
Apple growing at double market rate.
Omidia estimates that Apple reached a market shar…
…e of 11% with shipments growing 5.4% due to solid MacBook Air sales performance and the initial sell-in of the MacBook Neo.. This means 5.4% growth for Apple y/y. As I noted in my Office Hour yesterday, I adjusted my Mac growth from 0% to 6% based on the new products launched. This is an estimate of revenues not units but it might be pretty close. Omidia estimates 7,112 million units whereas I’m a little above 6 million. We seem to disagree on ASP. →
Amazon's acquisition of Globalstar boosts its satellite internet ambitions and strengthens ties with Apple, while highlighting the limited reach of space-based networks compared to terrestrial ones.
I assume Apple has wanted to steer clear of Starlink but it’s not clear that was a primary consideration in choosing Globalstar.
Starlink, considered the dominant player, serves about 11 million users. I would note that 11 million is 0.1% of the number of cellular subscriptions worldwide. →
iPhone users boast nearly quadruple the loyalty of Android counterparts, with actual annual switching rates favoring Apple slightly, despite inflated survey intentions.
I did a deep dive into the data and came up with graph above. The original report shows intention numbers which seem quite high. For instance, the net switching rate between iOS and Android is 10% in favor of Apple. This would imply that the entire user base would flip in 10 years. It would also imply…
I think actual net churn is 1.7% of the base each year. That’s still 100 million a year. For now it seems Apple is happy to maintain that rate. →
This episode of Asymco Office Hours covers a wide range of topics related to Apple, including geopolitical risks, financial performance, AI developments, and business strategy. The discussion is led by Horace Dediu and Gene Munster, with insights from industry experts.
BofA raised the firm’s price target on Apple to $325 from $320 and keeps a Buy rating on the shares ahead of fiscal Q2 earnings due after market close on Thursday, April 30. The firm, which sees upside to Street estimates given continued strong sales of iPhone and double-digit growth in Services revenue, forecasts Q2 revenue and EPS of $113B and $2.00, respectively.
Revenues and growth rates for iPhone, Mac, iPad, Services, Wearables, plus Net Sales, Gross Margin, Operating Expense, Other Income and Expense, Tax Rate, Net Income, Share Count and EPS with a comparison to CFO guidance.
Kevan Parekh, Apple CFO: As we move ahead into March, I would like to review our outlook, […]. We expect our March total company revenue to grow by 13% to 16% year over year, which comprehends our best estimates of constrained iPhone supply during the quarter.
We expect services revenue to grow at a year-over-year rate similar to what we reported in December. We expect gross margin to be between 48-49%. We expect operating expenses to be between $18.4 billion and $18.7 billion, which is at a similar level to what we reported in December and driven by higher R&D on a year-over-year basis. We expect OI&E to be around $100 million, excluding any potential impact from the mark-to-market of minority investments, and our tax rate to be around 17.5%.
I've seen several market reports which estimate that iPhone shipments grew around 3% to 6% in the quarter. When I plug in, say, IDC's iPhones number into my model, and assume quite aggressive growth on the other categories (including Services) I get a y/y revenue growth of 11%. This is far below Kevan's January's guidance quoted above (13% to 16%).
Are IDC, Gartner, et. al. signaling a huge miss?
I need to point out that in the preceding December quarter the iPhone grew revenues at 23%! In order for Apple to hit its targets
I'd also point out that when Kevan Parekh made his forecast, in late January, a full month was already on the books for Apple. Visibility into the next month would have been relatively good as orders from the channel are partly foreseeable. For a change from implying nearly 20% growth in sales/14% in units one third of the way in, to IDC's 3% in units for the whole quarter would imply a collapse in demand into February and March. We're talking double digit decline in order volumes.
Moreover, IDC commentary on Apple is
Apple secured second place, driven by the strong performance of the iPhone 17 series, which saw significant growth in China of over 30%. This led to a 3.3% year-over-year increase in global sales for Q1. Although demand remains robust, supply disruptions and a reduction in channel support in some key markets have hindered growth..
30% growth in China! For this to be tied to 3.3% growth globally would imply significant declines elsewhere. I struggle to see how this adds up.
Here is my complete forecast for the quarter including growth rate for revenues for iPhone, Mac, iPad, Services, Wearables, Net Sales, Gross Margin, Operating Exp., OIE, Tax Rate, Net Income, Share Count and EPS with a comparison to CFO guidance.
It’s a massive untapped opportunity for Apple, whose Mac installed base of 260 million units lags far behind the iPhone installed base of 1.5 billion units. Mohan believes the total addressable market for the Neo could be $32 billion for 2026. If Apple can capture just 10% of that market for budget laptops, and do so with a 19% operating margin, the company can boost earnings per share by an incremental 3 cents, according to Mohan.
“We see Neo driving meaningful adoption for first-time Mac owners with a distinct customer base relative to the Air and Pro models,” Mohan wrote.
The Neo will dramatically disrupt competitors in the market for budget personal computers, Seaport analyst Jay Goldberg wrote in a Monday note, as the $500 to $700 price tier is one of the most profitable segments for PC makers. Both Mohan and Goldberg have a buy rating and $320 price target on Apple’s stock, implying over 20% of upside from current levels. Read: Apple turns 50. Here’s how it can shake its midlife crisis.
As Apple expands into the budget computer market, the company is also looking to seize share from its smartphone competitors during a period of memory crunch. Artificial-intelligence infrastructure is gobbling up so much memory that many suppliers have sold out their capacity through at least next year. That has an impact on makers of consumer hardware that also count memory as a key component.
Apple has been paying a premium to buy up memory chips in what Goldberg believes is a “is part of a deliberate strategy for the company to tighten conditions for its competitors.” This strategy forces competitors to either raise prices for customers or reduce the memory content in their products, according to Goldberg. Meanwhile, he believes Apple intends to maintain both the memory content and pricing of its phones, allowing the iPhone maker to gain share even as the overall phone market shrinks by roughly 10%.
This strategy “will not come cheap for Apple,” Goldberg warned, noting that Apple’s product gross margin could sink to the low-30% range from the high-30% range seen a year ago. “That said, we think the company can make up for some of this lost ground through its share gains,” he wrote, as new Apple users are likely to subscribe to Apple’s higher-margin subscription services to offset the hardware costs.
Mohan expressed similar sentiments, arguing that the Neo could lead to a stickier overall installed base for Apple and “increased services use over time.”
NB: Two analysts, two stories. The Neo will move the needle and the supply crunch will hamper competition…
As I wrote before, the key metric is the number of Mac users. 260 million is a reasonable assumption. Over 350 million Macs have been sold in the last 20 years. If we assume half are new to the platform then 175 million have been added. The base in 2006 was probably in the 50 to 60 million range putting the total today at 250 million.
It's a long way to go to 1 billion Mac users and I don't know if it will ever happen given that most will have to switch from Windows and the lock-in is strong regardless of a better and cheaper alternative being available.
Nevertheless, a doubling of the Mac user base is certainly a worthy and achievable goal over the next decade.
Much more was said of Jobs’ departure signaling the end of Apple than of Gates’ departure signaling the end of Microsoft. And much more was celebrated of Apple 50 than Microsoft 50. Why is that?
If you were to structure an experiment to determine the influence of processes and personalities on the outcomes of a company, you would be hard pressed to find a better pair to study. Apple and Microsoft were founded almost at the same time, due to the same enabling technologies (microprocessors) and led by two iconoclastic founders of the same age acting out of similar impulses.
The divergences were that one concentrated on software while the other on hardware. But rather than pairing up in a match made in heaven, both tried to outmaneuver the other in order to avoid dependency. →
Cash flow is a fact, earnings are an opinion and share price is a dream.
A company’s total worth is the number of outstanding shares multiplied by their value. This product is called the market capitalization or Market Cap.
That’s a simplification. If you want to be more accurate, you should take the Market Cap and net out cash and debt–these are not part of the future flows of cash that can benefit shareholders.
More precisely, there is another measure called the Enterprise Value (EV) which is the total price tag of a company, representing what it would cost to buy the entire business and pay off its debts. EV = Market Cap + Total Debt + Preferred Stock + Minority Interest – Cash and Cash Equivalents.
This is the precise and complete measure of the firm’s value but we use the shortcut of Market Cap since In most cases the Preferred stock and minority interest are negligible and if cash equals debt then the result is EV =~ Market Cap. it’s easier to calculate anyways as the shares outstanding and share price are easily available. Not so for EV. →
What are the odds of it surviving another year, ten years, 50 years?
Companies don’t last long. A recent study that analyzed thousands of European firms yielded a corporate life expectancy figure of 12.5 years. The Boston Consulting Group analyzed the entry, growth, and exit dates of 35,000 publicly listed companies and determined that one in ten of all public companies fail each year, a fourfold increase since 1965.
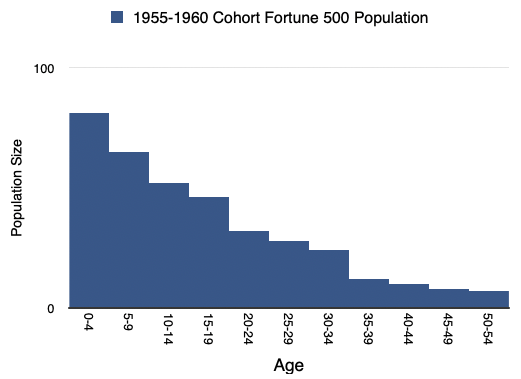
As I illustrated many years ago in a talk titled “The Unfortunate 500” most companies die not long after adolescence. Of the Fortune 500 1955-1960 cohort, the 81 companies which joined the index in those years, only 7 remain there today. One third of the corporations on the 1970 Fortune 500 list were no longer in existence thirteen years later. Broadly speaking, as a population, large companies that make it to the Fortune 500 listing have life expectancy within that group of 17 years. →
Today marks the 16th anniversary of when Apple released the first-generation iPad.
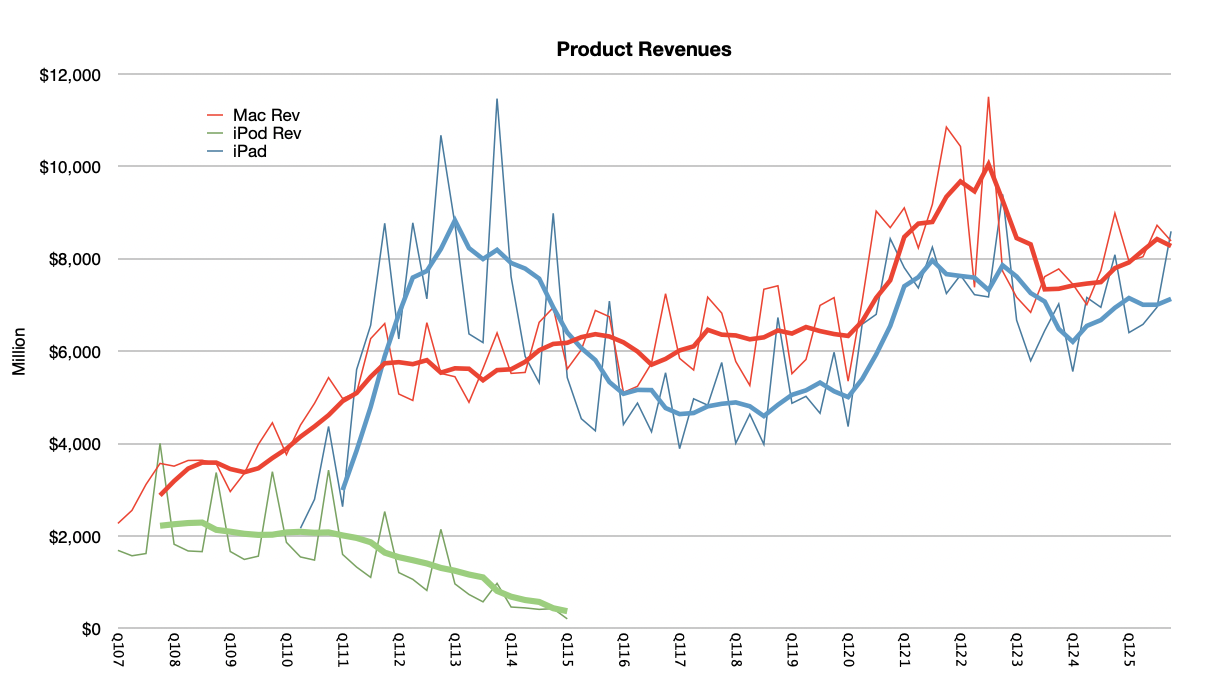
To many, including Alan Kay, the tablet form factor makes much more sense than the PC form factor. It’s more approachable, more intuitive and certainly smaller and more portable. As the graph shows, quickly after launch, the iPad overtook sales of the Mac.
The problem arose that whereas the iPad was smaller, the iPhone what smaller still–so much so that users would take phones with them everywhere. At the same time, the “PC” shrank as well so that many notebook (laptop) computers became thin, light and had day-long battery life. The Mac at least became no bigger a burden to carry than an iPad.
So the iPad was stuck in the middle between an iPhone, that did more and more, and a Mac that was very portable. At this point many said that the iPad was a dead end form factor. →
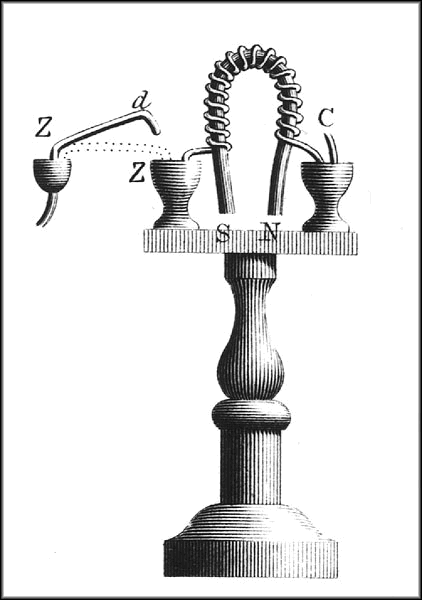
ON September 3, 1821, 37 years after James Watt invented the concept of horsepower and started charging £5/horsepower/year for the use of his steam engine, the first demonstration of the production of a mechanical force by the interaction of an electric current and a magnetic field was given by Michael Faraday in the basement of the Royal Institution in London.
1820 is, in many chronicles, noted as beginning of the industrial revolution. It marked the end of 50 years of war, whose conclusion unleashed pent-up demand. That demand was served by relatively free trade, guaranteed by British naval power, coupled with property rights and financial instruments which allowed inventions of the previous century to finally be harnessed for commercial gain. The steam engine is the canonical invention of the era and its implementation as a source of power for factories, shipping, rail and machinery is legend.
Not usually noted as coincidental to this period is the electric motor. Yet not long after Faraday’s 1821 demonstration in London, the first DC electric motor capable of turning machinery was invented by William Sturgeon. In 1832 he built on Faraday’s electromagnet by incorporating a commutator which oscillated the direction of current to ensure continuous rotation.
Nota Bene.
The Motley Fool asks: Where Will Apple Stock Be in 5 Years? → Not reading this article is probably a wise decision. Shares could perform in line with the S&P 500’s long-term average Investors can follow a straightforward exercise to try and figure out where Apple’s stock price will be in late March 2031. It’s important to consider both the valuation and profit gains. We just released a […] →
Apple’s services continue to see increased engagement, spending → The survey of 3,500 smartphone users reveals a significant rise in average monthly spend on Apple services to $13, driven by increased adoption of premium offerings like AppleCare/One, Apple TV+, and Apple Music, with notable shifts towards AI features despite muted upgrade intent, though potential US bias may affect overall accuracy. →
iPhone sales continue to surge into February – Bernstein → February saw robust iPhone sales driven by the iPhone 17 line, with global unit sales up 26% and ASP climbing 6.9%, yet January-February revenue estimates oddly lag behind projections, sparking confusion. →
Morgan Stanley has a stark message for investors in Apple → Morgan Stanley's survey indicates strong potential for Apple stock, highlighting record iPhone upgrade intentions, especially in China, improved switching rates, and significant interest in a future foldable iPhone. These factors support robust FY26 shipment forecasts and suggest a possible revenue boost from new products. Despite some concerns about declining willingness to pay for AI features, Morgan Stanley maintains an optimistic outlook with a $315 price target. The article criticizes TheStreet's editorial approach for misrepresenting the positive survey findings as negative news about Apple. →
Mac mini and Mac Studio orders booming → Apple's Mac sales are surging due to the M5 chips' enhanced AI capabilities, outpacing other platforms and driving demand despite current shipping delays. →
Gartner adds their Mac Q1 estimate to the pile → In Q1 2026, Apple's Mac sales surged impressively by 10.7% to 12.7% year-over-year, driven by the MacBook Neo's appeal, securing a 10.6% global market share and maintaining fourth place among PC vendors, amidst a 4% rise in overall PC shipments. →
The Omdia research group says Mac sales grew 10.7% year-over-year in the first quarter of 2026, while the IDC research system says the growth was 9.1%. Now Gartner says Mac sales grew 12.7% year-over-year.
This research group says Apple sold approximately 6.7 million Macs in the first quarter of 2026 for 10.6% global market share. That compares to sales of 5.9 million Macs and 9.8% market share in the first quarter of 2025.
Apple remains in fourth place among worldwide PC vendors. Ahead of it are Lenovo (26.5% market share), HP (19.3% market share), and Dell (10.6% market share). Note that none of the research groups count tablets, even the iPad Pro, as PCs.
“Apple grew 12.7% year-over-year, which was the largest jump among the major vendors and resulted in a 0.8% increase in market share,” said Rishi Padhi, research principal at Gartner. “This performance was primarily driven by robust demand for the MacBook Neo, particularly among new Mac users and buyers in the education sector. This strategic positioning enabled Apple to attract cost-conscious consumers seeking high-performance devices, further solidifying its competitive advantage in the segment.”
Worldwide PC shipments totaled 62.8 million units in the first quarter of 2026, a 4% increase from the first quarter of 2025, according to preliminary results by Gartner, Inc.
Today marks the 16th anniversary of when Apple released the first-generation iPad. After Steve Jobs announced the iPad on January 27, 2010, it launched a few months later on April 3, 2010.
The iPad was the first device that Apple released with a custom-designed chip, the Apple A4.
The concept of a tablet device like the iPad actually predated the iPhone, and Apple had a prototype project in the works in 2004. Then-Apple CEO Steve Jobs wanted to prioritize the iPhone, so the iPad was put on hold until after the iPhone was established.
Apple priced the iPad at $499, and Jobs called it a "magical and revolutionary device at an unbelievable price." Like the iPhone, the iPad dominated the tablet space, and it still continues to do so today. Apple sold a million iPads in the first month, and while competitors like Microsoft and Samsung quickly came out with competing tablets of their own, the iPad has no match.
Apple has led the global tablet market for over a decade and no competitor comes close to matching its tablet market share. As of the fourth quarter of 2025, Apple's market share was 44.9 percent, with Samsung the next closest at 14.7 percent.
Apple has expanded its iPad lineup over the years, and we now have multiple sizes at multiple price points.
The graph above shows the iPad revenues compared to the Mac and the iPod. I included the iPod since the iPad was originally dismissed as a "big screen iPod touch". On the other hand, it was also seen as a PC or Mac substitute. To many, including Alan Kay, the tablet form factor makes much more sense than the PC form factor. It's more approachable, more intuitive and certainly smaller and more portable. As the graph shows, quickly after launch, the iPad overtook sales of the Mac.
What iPad has done is carved a niche that is resilient. After 16 years, I reckon about 910 million have been sold with about 70 million more sold each year. The product has a particularly long lifespan in use and may continue to be used for as long as 10 years. Total lifetime revenuel has been over $403 billion with about $29 billion last year. The total user base is between 400 and 450 million users. In the U.S., the iPad is highly prevalent, with over 40% of Americans owning an iPad in 2024.
Neither killer nor killed, the iPad is just a great "in between" product with plenty of value. I have no doubt that it will still be popular 16 years from now.
Cash flow is a fact, earnings are an opinion and share price is a dream.
A company's total worth is the number of outstanding shares multiplied by their value. This product is called the market capitalization or Market Cap.
That's a simplification. If you want to be more accurate, you should take the Market Cap and net out cash and debt--these are not part of the future flows of cash that can benefit shareholders.
More precisely, there is another measure called the Enterprise Value (EV) which is the total price tag of a company, representing what it would cost to buy the entire business and pay off its debts. EV = Market Cap + Total Debt + Preferred Stock + Minority Interest - Cash and Cash Equivalents.
This is the precise and complete measure of the firm's value but we use the shortcut of Market Cap since In most cases the Preferred stock and minority interest are negligible and if cash equals debt then the result is EV =~ Market Cap. it's easier to calculate anyways as the shares outstanding and share price are easily available. Not so for EV.
To get a sense of how much you're paying for the company it makes sense to divide the Market Cap by the company's Earnings so you get an idea of how many years it will take to get back your investment. When dividing both Market Cap and Earnings by the number of shares it becomes the famous P/E ratio or Price per share / Earnings per share.
But if you want to be fully precise, instead of using Market Cap you should use Enterprise Value. In that case the denominator should be Free Cash Flow or FCF[1]. The ratio becomes EV/FCF. Free Cash Flow is a better measure than earnings because it takes into consideration depreciation, change in working capital and capital expenditures. It measures the actual cash a company generates after paying for its operating and capital expenditures.
EV/FCF takes into consideration unusual situations such as huge amounts of cash or debt or capital expenditures which removes shareholder access to what the company "earns" on paper. This why the adage of "earnings are an opinion but cash flow is a fact" exists.
I used EV/FCF years ago to value Apple because at a time when it held huge amounts of cash. This was before it began aggressively reducing its cash through its capital return program. The P/E ratio at the time was very low but excluding the cash, it was even lower. It was a huge red flag indicating that the company was being priced for liquidation, or as some analyst put it, priced like a steel mill going out of business. If at that time you did not believe that its demise was imminent you would have surely been richly rewarded.
Today the anomaly that throws the P/E off is not Cash but CapEx. And it's not for Apple but for the other mega caps or AI "hyper scalers". Without worrying who is or isn't in the "Magnificent 7" I compiled the largest 10 market capitalization companies and looked at their P/E and EV/FCF ratios. At time of writing:
Company
Market Cap
P/E Ratio
EV/FCF
NVDA
$4,014,456,963,072
33.6
44.4
AAPL
$3,624,949,514,240
31.3
30.3
GOOG
$3,304,174,911,488
25.2
44.3
MSFT
$2,667,926,257,664
22.5
35.0
AMZN
$2,157,182,320,640
28.0
297.0
TSM
$1,641,528,688,640
30.6
50.0
TSLA
$1,333,163,982,848
332.0
225.0
META
$1,356,802,949,120
22.8
32.6
BRK-B
$1,023,780,323,328
15.3
44.1
LLY
$793,550,454,784
38.6
142.3
As recently as six months ago, there was a lot of talk about an AI bubble. Back then I looked at the data then and by looking at the P/E ratios convinced myself that the valuations were not "bubble" level. They were in the mid-thirties. These were not historical high especially when considering the growth these companies were experiencing (over 30%). Since then prices have come down significantly.
This is as the CapEx elephant in the room has been making itself known and there is renewed alarm at the scale of capital spending. This is reflected in the EV/FCF number but not in the P/E number.
The table above shows how much more elevated the EV/FCF ratio is relative to P/E for many of the companies. This "truer" measure of what you are paying as a share buyer is now reflecting in reduced share price and hence reduced P/E.
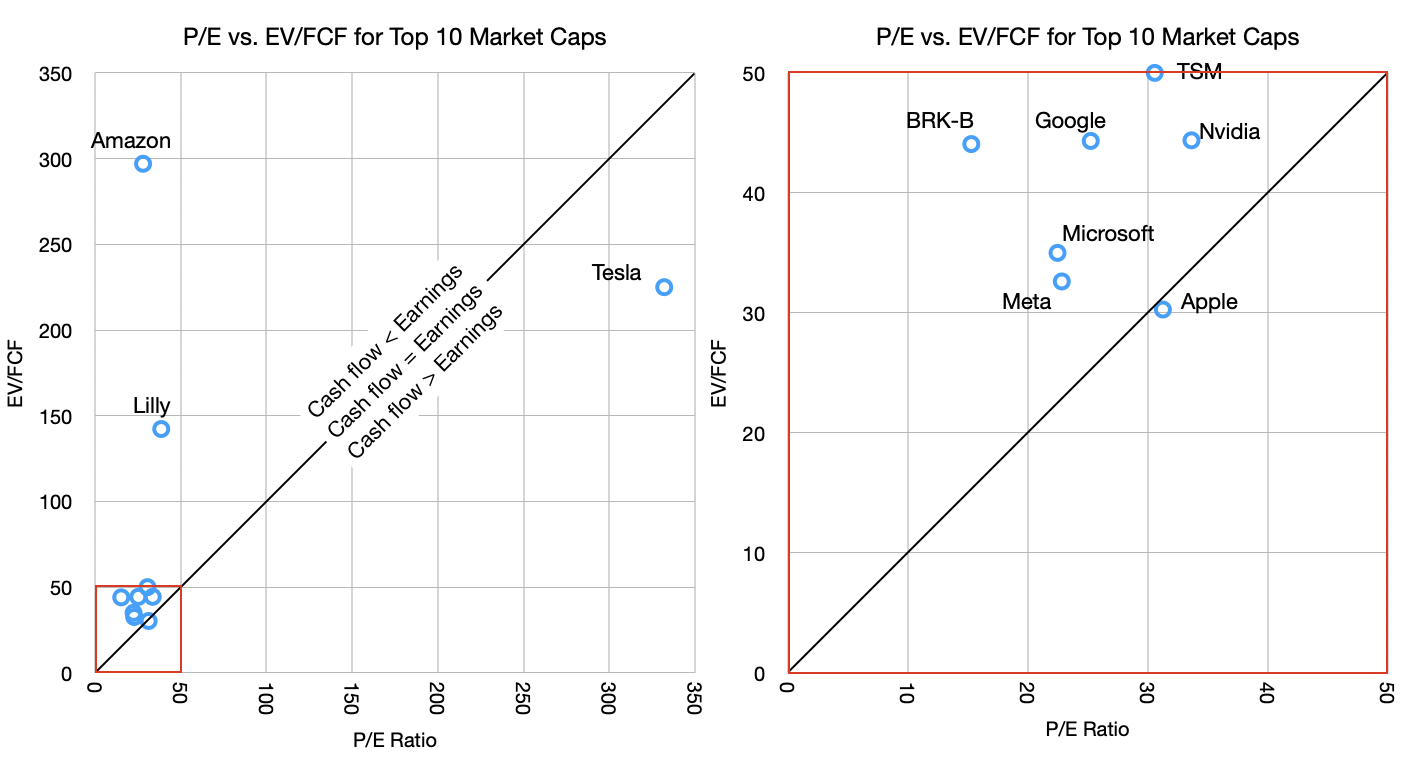
Of course, this is not true for Apple. Apple's P/E ratio and EV/FCF are nearly identical. To see this more clearly I put together these graphs.
The graph shows the P/E vs. EV/FCF for the companies in the table. The graphs are the same data but the one on the right is zoomed in on the lower left corner (note the red squares).
The reason for the zoom is that there are three outliers. Tesla, Amazon and Lilly. Tesla has absurd valuation on both P/E (300 to 400 range in last 6 months) and EV/FCF while Amazon has an outrageous EV/FCF value due to abnormal capital spending. Basically, Tesla has negligible earnings (and negative growth) while holding astronomical share price and Amazon is spending far above its median on CapEx. Amazon's 10-year EV/FCF is much lower, at approximately 55.
But let's ignore the outliers and concentrate on the other seven in the cluster. These are below 50 P/E and 50 EV/FCF thresholds.
Note that I drew a diagonal line representing the equation of P/E = EV/FCF. This should, under normal circumstances, hold for most stocks. Just like Market Cap should roughly equal Enterprise Value so Earnings should equal Free Cash Flow.
Most companies should not stray too far from this line. But what we are seeing, with the notable exception of Apple, is that most tech companies have cash flow far below earnings. This is again due to the CapEx elephant.
The argument goes that this is a temporary situation with that capital being wisely deployed for returns from AI. Presumably, these companies will swing to the other side of the line, where cash flows will exceed earnings, compensating for the capex that was denied to the shareholders.
This is where the old adage comes into play: Earnings are an opinion but cash flow is a fact. I added to that "and share price is a dream". Take the free cash flow and multiply it by a "dream" and you get the price the market sets. This dream is the multiple.
What makes the AI "bubble" interesting is how it's not fueled by debt[2] but by cash flow. Companies are turning over large portions (almost all and sometimes more) of their cash flows to investing in the dream of AI profits. All but one, of course.
There is something obviously contrarian in Apple's strategy. Perhaps it's not Apple that is odd but rather there is groupthink on behalf of the others. The question of who's right will rest on whether it turns out that AI is going to commoditize quickly or perhaps never, whether AI turns out to be modular or integrated, whether AI exhibits disruptive or sustaining competitive responses, whether it's an infrastructure subject to regulatory corrosion or whether it will migrate to the edge and iterate freely, whether it's a new experience or simply better existing experiences, whether it creates new markets or just makes existing ones more efficient.
These are not new questions. They have been applied to all software and hardware innovations of the last 40 years. We have a lot of history to inform us.