
Asymco

Asymmetric Intelligence

Windows

  1. A new era is only a new state of mind

    Research · 51 comments

    The following interview was conducted by Bruno Ferrari a writer about technology for EPOCA, the weekly magazine of Organizações GLOBO, the largest Brazilian media company on March 30 2011. The article (published in Portuguese here) is an edited subset of the following exchange.

    Q: In your analyses, you mention tablets as part of a new era, the “Post PC era”. Why do you think the PCs will be replaced by tablets?

    This is not quite correct. Post PC does not mean the end of the microcomputer. The way to think about it is this: The stone age did not end because we stopped using stones. Same with the iron age and the industrial era. The era of jet travel did not end automobile or even ship travel (though that changed to recreation rather than transportation for passengers.) Each phase of technology does not fully replace its predecessor. It offers a new set of solutions and perhaps a slightly different way of solving old problems. We'll still have PCs but we will use a new type of computer, an even more personal computer. The world still uses the microcomputer's technological ancestors.

    In terms of what new jobs will we hire the tablets to solve, they will vary greatly from what we used PCs for. Just like we used microcomputers for different things than we used time-shared minicomputers and mainframe computers. I expect social interaction, media consumption and entertainment will move from a PC to a tablet. New uses will emerge from the vast experiment that is the app phenomenon.

    Q: What are the new ways to interact with machines? With gestures? How will this change the market?

    Each major disruption of computing came from a new generation of input and/or output methods. Terminals (vs. punch cards) enabled minicomputers. The GUI enabled the rise of the microcomputer and touch is enabling the rise of the tablet. Perhaps this era will last decades perhaps only years, but there will be new input and output methods available. The world's research laboratories are filled with ideas from projection screens (from high brightness LEDs) to motion sensing (as implemented partly by Kinect) and even novel voice control methods. I believe that each major innovation will create a new wave of growth and, if coupled with a new business model, a new set of companies and platforms.

    Q: What are the main differences between PC and Post PC era?

    The main difference will be in the context in which the product will be used. Tablets and smartphones allow "computing" to be done in previously non-consuming contexts: while standing, while in the active company of others, while commuting or while lying back and relaxing. It will also allow more individual use. Like the transistor radio allowed teenagers to listen to rock-and-roll out of hearing range of their parents who had control over the family stereo, a truly personal computer will allow people to "escape" into a world of more intimate consumption and communication.

    Q: Do you think physical keyboards and mouse will be extinct?

    Even physical keyboards have been evolving dramatically. If you look back to the earliest IBM PC keyboards, they were mechanically complex and had a rich feel. Modern laptop keyboards are flimsy things with barely any feedback. Early PC keyboards were patterned after the needs of professional typists (aka secretaries). Current keyboards are designed around space constraints. Same with mice. They went from two to three to one to no buttons. With laptops we ended up with track balls,  little knobs in the middle of the keyboard or with trackpads. Users adjusted over time.

    What changed with tablets is the removal of an on-screen pointer. The pointer was there because the mouse/touchpad was one layer of abstraction for controlling what was on screen. Without a pointer you have direct manipulation. I'm sure many people who never used a mouse would find the direct method more intuitive and in a generation people will wonder how we put up with mice. Conversely, those who are used to a mouse will find it uncomfortable at first. Remember that in the 80s many keyboard experts found mice something that slowed them down.

    So I believe that people will adjust to a world without mouse pointers. I suspect children born today will grow up without ever using a mouse (or a phone with a wire permanently attached to the bottom).

    Q:  Apple has more than 90% of tablet market worldwide. Do you think Apple will be the leader of technology market in the next few years?

    The challenge for Apple is that they cannot serve the whole world. They can only grow so fast. On one hand we have their inability to meet demand and on the other we have alternative products which can. Market leadership may not be sustainable just because the market is so big and no single company can supply it. I do believe that Apple is not sitting on its hands however. Their culture promotes pushing forward.

    Q: At smartphone market, do you believe on a risk of a new duopoly, Apple-Google? Some analysis says that they’ll control the channel sales of software, content and hardware. The conclusion is companies like RIM, Nokia and HP (Palm) will not be able to keep up.

    Analysts differ in their opinions. IDC just released a forecast that shows Microsoft growing beyond iOS in four years. I don't try to make this type of prediction. At least not to a high degree of precision. I do believe that there will be more than two platforms. This is because the market is so large and so diverse and there are so many ways to reach customers (through operators, through retail stores, through online).

    Q: Can we compare the beginning of the tablets with PCs? Apple developed the interface and made ​​the first computers nice and easy to use. But Windows has allowed hardware manufacturers to invade the market, popularizing it. This will be repeated with Android? Or with other systems?

    Innovations are always copied. Even when protected by all sorts of laws or patents. What makes a company successful with innovation long term is to always keep innovating. Often coming up with the next big thing means damaging the old thing. That's hard to do for many companies so they don't do it and somebody else does. This is why great companies end up as formerly-great companies. As I pointed out above in the discussion about input methods, innovations are always bubbling up. As long as Apple takes these ideas and polishes them and brings them to market, they'll do all right.

    Q; How about Microsoft? Do you think the company will lose the podium in Post PC era?

    Microsoft already has lost its position as leader in personal technology. The end actually came in about 2000. Once Windows became "good enough" and did not crash so much, they have had a hard time finding something to improve. If you go back and watch every CES keynote that Microsoft presented since then it's been a litany of dead end ideas.

    Every major innovation since 2000 has been in consumer technology and that's never been an attractive business for Microsoft (with the exception of XBox which was really aimed at Sony and Nintendo without the intention of creating a new market.) Microsoft struggles not because they lack talent (engineering or management) but rather because their business model is relatively rigid. They make money through software licensing. You can see how that's a hard thing to sell to consumers ("I'm buying what?") Consumers tend to pay Microsoft through the purchase of another product. If the market demands hardware/software integration (like in a phone or tablet) or making money by giving software away (like Google), they struggle. This business model rigidity is present in almost all companies, so Microsoft is not uniquely troubled.

    Q: Most of the tablets will use mobile networks to connect to the internet. Do you think the world is ready with an infrastructure that supports this growth in access via mobile networks?

    This is a good question because the growth of mobile broadband is a major enabler (or constraint) on growth. Fortunately, the roll-out of mobile broadband is fairly predictable and it looks good. There are some challenges for operators long term in paying for the infrastructure, but they don't lack for financing today and the business case for more infrastructure seems to be very attractive. It will take time and it won't be even globally, but the incentives are clearly there. A lot of value is being created with mobile computing and much of that value will end up paying for the bandwidth.

    Q: How about the App Market. You posted recently a chart showing how fast developers are buying thickets for both Google and Apple developer events. You said that it is one signal of the Post PC Era. What will be the importance of apps on the next years. Do you think Apps market will be more important than hardware, content and OS market?

    Developers are one more sign that something big is happening. It's not the only sign and may not be the cause of the change, but it's yet another signal. But apps are a phenomenon that will result in something bigger than we can imagine. The way to think about apps is as a new medium, similar to the emergence of radio, television, cinema and even books. The app is a new art form as well as something that provides functional value. We don't know whether the app phenomenon will be tied to one platform or will evolve to something like HTML5, a common standard. But the value of having an app for everything is plainly evident. The economics, creative energy and dynamism of apps cannot be overestimated. I will write more about this subject as I think it's one of the most important consequences of the post-PC era.

    Q: What’s the destiny of the PC? Are they on their last years?

    Again, it's not so much that PCs will disappear any more than mainframes or servers have disappeared. What is more likely is that they will be used for isolated, focused jobs. The "end of an era" is the end of growth, not the end of existence. The PC has arguably reached end of growth in most developed markets. There is still strong growth in emerging economies but even there, much of that growth will probably be replaced with smart devices growth.

    Q: We had the Mainframe Era, the Terminal Era, the MiniPC Era, The PC Era and now we starting the PostPC Era. Do you imagine what Era we'll se after the tablets? When do you think is it going to happen?

    I don't try to be a futurist who can see with clarity technological change. I try to see the patterns of markets through the motivation of companies. With that in mind, my answer will be that large companies will acquire promising new technologies from start-up companies and implement products with global distribution. To see the future you therefore need to look at what small companies are doing today. I note that there is a lot of innovation in new communication methods (social media) and new input methods around gestures and display technology. I am skeptical about the power of voice controls.

    I'm most confident that there will be a re-definition of television, a "socialization" of almost all media. So I'll abstain from answering directly what happens after the Tablet Era. Perhaps something more personal and more of a companion than a tool.
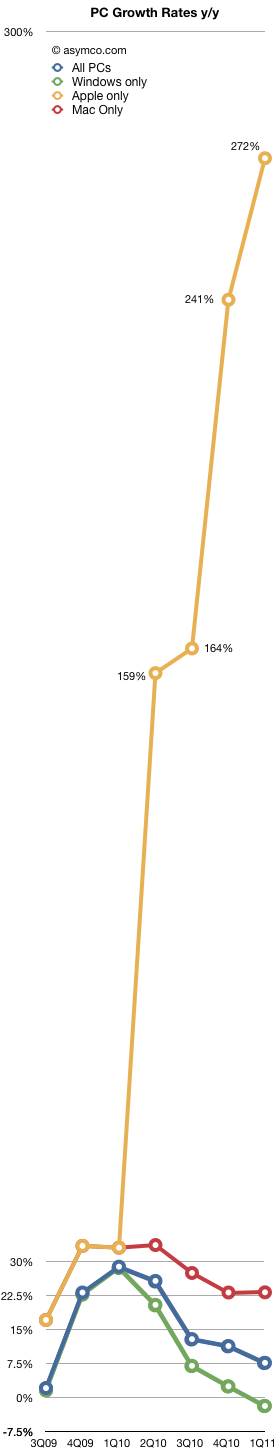
  2. First quarter PC forecast: Windows down 2%, Mac+iPad up 250%

    Research · 100 comments

    Charles Arthur of The Guardian writes that PC sales "may have passed their peak".  That's a powerful, concise statement. It's backed up by a quote from Gartner's Mikako Kitagawa:

    "This was the third consecutive quarter of mobile PC shipment declines in the US"

    IDC even lays part of the blame to something called "media tablets"[1]:

    "While it's tempting to blame [PC] decline completely on the growth of media tablets we believe other factors [...] played equally significant roles."

    But there are several problems with both IDC and Gartner's analysis of the market. It's hard to make out causality from their data. There is separation by vendor but not by operating system and there is exclusion of devices hired to do the same jobs as PCs.

    For this reason, I need to do my own analysis. I retrieved Gartner's public statements on the overall market and layered actual Mac and iPad units sold. I also added my estimates for the Q1 2011 quarter just ended to complete the picture.

    We can now get an understanding of how the industry behaves with and without various platforms. The chart at the left gives the various growth rates of the market with platforms isolated from each other. I apologize for the shape of the chart but the scale does not permit a concise visual.

    Including the iPad, the total PC growth is shown by the blue line. It shows that the market peaked during the recovery but is now slowing considerably.

    The green line shows the PC industry excluding both the Mac and the iPad. Although it might include Linux or computers sold without an OS, the label "Windows PC" is a fairly close approximation. It shows that the market excluding Apple entered contraction this quarter and is out of sync with overall economic recovery and growth.

    The red line shows the behavior of the Mac franchise. It's well ahead of the overall market with 2x to 3x the growth. This has been a pattern for over 18 quarters.  I had some thoughts on this in a November 2010 hypothesis.

    But the most telling line is the orange line which includes both the Mac and the iPad. In an industry where growth is usually measured in single digits, the iPad business brings growth in three digits.

    This near tripling of unit sales is symptomatic of fundamental change that cannot be ignored. Although some analysts contend that the iPad is not causal to the decline in other PC sales, teasing out platforms data seems to show a divergent view.

    The bottom line is that Windows-only computer units are down 2.0% while OSX-based computer units are up 272% (this excludes both the iPhone and iPod touch).

    Correlation is not causation but tests or surveys where substitution can be proven do exist. For example, a recent survey shows that 77% of users reported that their PC usage decreased after getting a tablet. It also showed that 28% considered their iPad as their primary computer.

    So coupling the sales data with the usage data does point an accusatory finger for the decline on the iPad.

    In addition, some vendors are being hit harder than others which also hints at where substitution is happening. For example, IDC reports that Acer US unit shipments fell 42% in the first quarter and 16% globally (Gartner's numbers are less dramatic but in the same direction). Since Acer is known for its netbook computers it's another telling sign of possible substitution (Acer's own management has indicated as much.)

    So the weight of evidence is beginning to be conclusive: the iPad is the new PC. It should be clear by now that the iPad moves computing into new contexts so it does not yet substitute the PC market but extends it and increases consumption. Substitution is happening in low-end grazing type of usage, a place where the PC was ill-fitting anyway. Incumbent vendors might actually be relieved that the lower margin netbook is finally being supplanted and they can concentrate on the higher end.

    --

    Notes:

    1. Analysts like to call the iPad a "media tablet" but the same AdMob survey shows media consumption to be one of its least popular uses.
  3. Flummoxed, again

    Research · 184 comments

    The last time I took a snapshot of the iPad death watch it was March 9th, 2010. Almost a year ago. The now-classic quotes are reproduced here.  Last May I wrote:

    Apple keeps a tight lid on new products so that competitors don’t get a head-start on copying, but in the case of the iPad, advance knowledge would not have had any impact. Competitors look at the iPad and see nothing.  They’ll only react once the market explodes and they start to feel belated pain.

    I thought that would be that. As the success of the product would become self-evident, predictions of imminent demise would trail off. The pain of share loss would prompt a wave of challenger copycats. Imitation would be the the best form of flattery.

    But no.

    Critics were not silenced. One year, 15 million units, and $9.2 billion later I went back to the source of the quotes and found the following (published quotes dated after March 9th 2010). (Cited from aaplinvestors.net with some editing for brevity and relevance):

    “Problematically, the Android competition is just as expensive as the iPad lineup, so Apple obviously feels free to continue gouging consumers on iPad pricing.” Paul Thurrott, Windows IT Pro, 3 March 2011

    “Apple’s iPad 2 might be ‘magical’ but it still should’ve been better ... It needs more G’s. It’s still just a toy” Zach Epstein, Boy Genius 2 March 2011

    “11 reasons NOT to buy an iPad 2 ... Reason 5: Competition David Gewirtz, ZDNet, 23 February 2011

    “Given what I’ve seen of Honeycomb and Motorola’s excellent tablet, Cupertino will have some serious catching up to do with their iPad 2.” J.P. Mangalindan, Fortune, 4 February 2011

    “We very carefully chose our tablet processor, the Nvidia Tegra 2, and to really compete it will take [Apple] some time. You know, [Nvidia] is well known for graphics.” Jonney Shih, Asustek Computer, 3 February 2011

    “If you were to ask me in two years time, will Apple have less than 50 percent of the global tablet market, I think that’s a certainty. Neil Mawston, Strategy Analytics, 31 January 2011

    “We have an extreme focus on the innovation of LePad and LePhone because these products will dominate the future market. Though Apple is winning a significant share in the Chinese market, it has not gained a clearly leading position yet. Our advantage is we know this market better.” Liu Chuanzhi, Lenovo, 27 January 2011

    “The iPad may still be the lone leader, but with 100+ competitors on the way, it won’t likely keep its majority market share unless the pending next generation iPad really addresses all the complaints about the current version, like a missing camera and a lack of a USB port, and the company has to add those features without a major price increase - a tall order, to be sure.” James Brumley, Investopedia, 13 January 2011

    “Hands-on PlayBook demonstrations at CES showed its differentiation in multitasking and performance, which may be difficult for Apple/Android to rival.” Mike Abramsky, Royal Bank of Canada Analyst, 11 January 2011

    “Apple Inc.’s popular iPad is getting its strongest competition thus far as consumer-electronics manufacturers unveil tablet computers with bigger screens, front-facing cameras for video chatting and more.” Rachel Metz, AP Technology Writer, 3 January 2011

    Apple may be simply trying to get in ahead of Research in Motion’s aggressively priced PlayBook or combat the early success of Samsung’s Galaxy Tab.” Rick Aristotle Munarriz, The Street, 29 December 2010

    4. Competitors are coming. Brett Arends, Wall Street Journal, 22 December 2010

    Reason 6: WiFi is still unreliable David Gewirtz, ZDNet, 16 December 2010

    “I can’t imagine anyone under the age of 30 wanting an iPad. A PS3, Wii, GameBoy, or even a useful laptop maybe, but an iPad? Furthermore, I do not recall ever seeing anyone under 30 actually using an iPad.” John C. Dvorak, PC Mag, 13 December 2010

    “We hope our tablet PCs can reach a global market share of 10-20% initially, and become the market leader in two to three years.” Gianfranco Lanci, CEO and President, Acer, 26 November 2010

    “It’s a nice-to-have product, for those of us who don’t have a budget, but is it a must-have product? I don’t think so.” Ashok Kumar, Analyst, Rodman & Renshaw LLC, 12 November 2010

    “Steve Jobs never says anything without thinking through it carefully. But I think in this case he may be a little afraid of this category. And he’s finding whatever he can to attack because he sees [seven-inch tablets] as a challenge to the dominance of the iPad.” Adam Hanin, VP Marketing, Viewsonic, 1 November 2010

    “There could literally be millions of first-generation iPads gathering dust in people’s home offices already. This product is the tech industry’s biggest MacGuffin yet.” Paul Thurrott, Windows IT Pro, 23 October 2010

    “I cannot see a need for the thing.”John Dvorak, MarketWatch, 22 October 2010

    ”For those of us who live outside of Apple’s distortion field, we know that 7″ tablets will actually be a big portion of the market and we know that Adobe Flash support actually matters to customers who want a real web experience.” Jim Balsillie, Research In Motion, 20 October 2010

    “iPhone and iPad have been amazing products that have opened new markets. But I do not think they will own either market in a few years. Android will.” Fred Wilson, AVC.com, 18 October 2010

    “The constant search for an ‘iPad killer’ and the sheer multitude of tablet computers launching in the next 18 months should make Apple aware that its competition is fierce and will only become tougher.” Barbara E. Hernandez, PCWorld, 5 October 2010

    “HP’s New Tablet Could Be an iPad Spoiler HP’s decision to bundle a tablet computer with its new $399 printer could make trouble for competitors.” Cliff Edwards and Aaron Ricadela, Bloomberg Businessweek, 23 September 2010

    “Our tablet will be better than the iPad.” Chang Ma, VP Marketing, LG, 20 August 2010

    “Not only is Apple typically lost in the enterprise, but it focuses very little of its time there. And with a new, potentially more compelling tablet coming — the Cisco Cius — the iPad’s success in the corporate world could be short-lived. Here’s why:... 10 The power of Windows” Don Reisinger, Channel Insider, 5 August 2010

    “I don’t think there is one size that fits all…I’ve been to too many meetings with journalists who spent the first 10 minutes of the meeting setting up iPad to look like a laptop.” Steve Ballmer, Microsoft, 29 July 2010

    “ [...] It still isn’t the device that I’d take to a meeting because it has no input.” Bill Gates, Microsoft, 2 June 2010

    “Which means I end up on the iPad — and tablets more generally — where I started. Tablets will not create a new category, but will supplant (or merge with) one or more of the current substitutes: smartphones or netbooks.Here I am less optimistic about the iPhone and webOS than I am about Android. ” Joel West, professor of Innovation & Entrepreneurship, College of Business at San José State University, 30 May 2010

    “The iPad is useless. Beautiful, but useless. The iPad is too heavy. It’s awkward to hold and view in public. It’s fragile. It requires expensive accessories to protect it and extract more functionality. ”Josh Belzman, MSNBC.com, 20 May 2010

    “Mum, the iPad is not ‘amazing.’ It’s just marketed very well, both by Apple and its culpable partners in mainstream media. ” Paul Thurrott (in response to comment by Mum), Paul Thurrott’s Super Site for Windows, 26 April 2010

    “In short, I don’t get the ‘magical and revolutionary’ vibe that Apple chief executive Steve Jobs touted at the iPad’s January unveiling.” Rob Pegoraro, Washington Post, 9 April 2010

    “The first troubling sign is the fact that you can still get an iPad today. They didn’t sell out. The pure slate form factor has failed all these years because, other than for vertical applications, people want and/or need a keyboard for regular use. The fact of the matter is that a touch screen or bluetooth keyboard just doesn’t compensate.” Jonathan Yarmis, Ovum, part of Datamonitor Group, 6 April 2010

    “I don’t get it. It costs $500 for the basic model, when you could get a laptop with a lot more functionality for about the same price. The iPad hype machine has been in full effect this week, and I still think it’s just that—hype. ” Alex Cook, Frontier Outlook, 3 April 2010

    “As far as what this means to Apple, one thing to keep in mind: Even if the iPad sells more than the iPhone did in its first year, it’s still only around 5% of the company’s revenue. So it’s a very small slice. From there, it probably doesn’t grow as large as the smartphone market. So, if you’re buying under rumors, keep perspective in mind. The iPad’s a great product, but it’s probably not a game-changer.” Eric Bleeker, Analyst, Fool.com, 31 March 2010

    “The iPad will remain an expensive, niche device compared to all-purpose netbooks.I think that one of the iPad’s most important uses will be for reading ebooks and publications. Even so, though, when it comes to the marketplace, netbooks will sales still far outstrip those of the iPad.” Preston Gralla, PC World, 30 March 2010

    “Don’t Believe the iPad Hype. Apple has sold out pre-orders of the forthcoming device, but it could all be a marketing tactic. By not manufacturing enough iPads for the initial launch date, is this a case of Apple shooting itself in the foot?” Mike Schuster, Minyanville.com, 29 March 2010

    “‘iPad Killer’ May be Palm’s Last Hope”Tom Bradley, PC World, 20 March 2010

    “Even if your company has relented and now supports the iPhone, as growing numbers of businesses do (70% of the Fortune 100 are at least testing it, says Apple) you’ll want to say “No” to the iPad and other tablets. Here’s why: 8. Speaking of money, there is no money in the company budget to pay for iPads. 9. Not supporting iPad will be the enterprise norm. Robert McGarvey, CIO Update, 16 March 2010

    “This morning, the fool’s parade gets started. Apple is taking online “pre-orders” for its iPad tablet, which is supposed to begin shipping on April 3. Buying a new kind of product sight unseen is foolish. Especially given how mysterious Apple has been on what the iPad can do and what restrictions on capabilities and media access it will place on users and content providers.” Galen Gruman, InfoWorld, 12 March 2010

    “The recent launch of Apple, the iPad tablet, has won the award for the second edition of Fiasco Awards delivered this Thursday in Barcelona. From the more than 7,000 people who voted via the website www.fiascoawards.com, 4,325 have considered it the fiasco of the year. Fiasco Awards, 2010, 11 March 2010

    “I think I’ve mentioned this once or twice before, but it bears repeating until it sinks in: the Apple iPad is not unique, nor necessarily the best of breed in the media tablet sector it is spearheading. And it ain’t gonna help Apple shareholders any.’” Anders Bylund (TMF Zahrim), 11 March 2010

    From this critical review, it looks like 2011 will indeed be the year of the iPad 2.

  4. Where is the Windows Phone Tablet?

    Research · 78 comments

    The Windows Phone platform currently has hardware specifications that imply a cellular phone device. What is interesting in light of the new WebOS TouchPad, the newly announced Android tablets, the RIM Playbook and the iPad is that this supposed "third horse" of Windows Phone has no hint of present or future presence in the tablet form factor.

    That might have something to do with the plans to move Windows to the tablet form factor. Perhaps Microsoft thinks that pocket size devices deserve a separate operating system, platform and ecosystem than portable mobile computers. Perhaps Microsoft plans to have two separate interfaces for these tablets (slates vs. tablets?) Then again, Ballmer held up a Windows Phone and said "This is Windows too."

    It gets confusing.

    The bottom line is that without a tablet implementation, Windows Phone developers and content providers will find that the WP ecosystem will have a limited addressable market and will not be suitable for all forms of media or apps. Tablets are currently expected to grow even more rapidly than smartphones did and so there will be significant numerical advantages to those platforms that support multiple screen sizes and form factors.

    Now that Nokia has anointed the Windows Phone platform as its exclusive conveyance to the device market, the question in the headline becomes: Where is the Nokia tablet?

  5. In memoriam: Microsoft's previous strategic mobile partners

    Research · 223 comments

    Microsoft's new "strategic partnership" with Nokia is not its first. For a decade the software company has courted and consummated relationships with a variety of companies in mobile and telecom. Here are the ones I can remember:

    • LG. In February 2009 Microsoft Corp. signed a multiyear agreement for Windows Mobile to be included on devices from LG Electronics Inc. LG would use Windows Mobile as its "primary platform" for smartphones and produce about 50 models running the software.

    What happened? LG made a few Windows Mobile devices but with WinMo uncompetitive, they abandoned the platform and moved to Android losing years of market presence and all their profits.

    • Motorola. In September 2003, Motorola  and Microsoft announced an alliance. "Starting with the introduction of the new Motorola MPx200 mobile phone with Microsoft Windows Mobile software, the companies will collaborate on a series of Smartphone and Pocket PC wireless devices designed to create a virtual "remote control" for the Web-centric, work-centric, always-on-the-go mobile professional." In addition, the alliance includes cooperation on joint marketing and wireless developer programs.

    What happened? Motorola launched a series of Windows Mobile phones culminating in the Motorola Q "Blackberry killer". As Motorola hit the rocks in profitability new management reached for the Android liferaft. The company now relies exclusively on the Droid franchise.

    • Palm. In September 2005 Palm and Microsoft announced a strategic alliance to "accelerate the Smartphone market segment with a new device for mobile professionals and businesses. Palm has licensed the Microsoft Windows Mobile operating system for an expanded line of Treo Smartphones, the first of which will be available on Verizon Wireless’ national wireless broadband network."

    What happened? Palm shipped a few Windows Mobile, famously dismissing Apple's potential entry as something "PC guys" could never achieve. A new CEO, a private placement and an acquisition later the company is a division of HP making its own operating system.

    • Nortel. When Steve Ballmer was famously laughing at the iPhone and saying that he likes the Windows Mobile strategy "a lot" he was sitting next to the then-CEO of Nortel (Mike Zafirovski formerly of Motorola) with whom the company had just closed a strategic deal.  "an alliance between Microsoft and Nortel announced in July 2006 ...  includes three new joint solutions to dramatically improve business communications by breaking down the barriers between voice, e-mail, instant messaging, multimedia conferencing and other forms of communication".

    What happened? Nortel declared bankruptcy two years later.

    • Verizon. In January 2009 "Verizon Wireless has selected Microsoft Corp. to provide portal, local and Internet search as well as mobile advertising services to customers on its devices. The five-year agreement will go into effect in the first half of 2009 when Microsoft Live Search is targeted to be available on new Verizon Wireless feature phones and smartphones." The deal would ensure Bing distribution to all of Verizon's smartphone customers.

    What happened? Bing did ship on some devices but in October 2009 Droid came to Verizon.

    • Ericsson. In September 2000, "Ericsson and Microsoft Corp. today launched Ericsson Microsoft Mobile Venture AB. This previously announced joint company will drive the mobile Internet by developing and marketing mobile e-mail solutions for operators. The first solutions are expected to be on the market by the end of the year. The company is part of a broader strategic alliance between Ericsson and Microsoft"

    What happened? Ericsson divested itself of the mobile division forming a joint venture which would go on and make more strategic alliances with Microsoft over Windows Mobile culminating in a loss of profits and eventual flight to Android.

    • Sendo. In February 2001, Microsoft announced a partnership, in which Microsoft bought $12m of Sendo shares and a seat on the board. Sendo was to be Microsoft's "go to market partner" for the Stinger smartphone platform that would become Smartphone 2002.

    What happened? Sendo after litigating IP issues with Microsoft went bankrupt in 2005.

    And finally,

    • Nokia. No, not this OS deal, but in August 2009 "The worldwide leader in software and the world’s largest smartphone manufacturer have entered into an alliance that is set to deliver a groundbreaking, enterprise-grade solution for mobile productivity. Today, Microsoft Business Division President Stephen Elop and Nokia’s Executive Vice President for Devices Kai Öistämö announced the agreement, outlining a shared vision for the future of mobile productivity. This is the first time that either company has embarked on an alliance of this scope and nature."

    The plan was to bring "Microsoft Office Mobile and Microsoft business communications, collaboration and device management software to Nokia’s Symbian devices."

    What happened? One and a half years later the same Stephen Elop announced that Symbian will be deprecated.

  6. The (iPod)Touch(i)Pad

    Research · 99 comments

    The world's largest PC company just launched a "media tablet[1]". Conflating the iPod Touch and iPad brands into "TouchPad" HP joins RIM in announcing an integrated OS/device product to compete as a platform vs. iOS and Android (and to some degree even against Windows).

    There are others waiting in the wings. Presumably, Microsoft is hard at work to release a tablet-compatible Windows sometime near the middle of this decade. MeeGo is also going through its gestation period targeting Atom-based tablets. John Gruber notes the excitement around tablet platforms in his article about this post-PC renaissance in computing alternatives. I also noted that the end of the PC era was marked by the end of WinTel at CES.

    In that context, yesterday's WebOS event was perhaps anticlimactic. But it's still remarkable. Consider how far we've come. Step back now and remember the dark days only one year ago when, right after the iPad announcement, a  nearly unanimously chorus was pouring derision on the concept.

    AAPLinvestors is still maintaining the iPad death watch which I took a snapshot of back in March 2010. To reminisce: It was exactly one year ago, on Feb. 10th 2010, that Bill Gates was quoted as saying "It’s a nice reader, but there’s nothing on the iPad I look at and say, ‘Oh, I wish Microsoft had done it.’" On the same day, Shannon Zimmerman of The Motley Fool wrote: "[Apple's] hamster-wheel of innovation ... may have hit a snag with the iPad." Those are just two of dozens other memorable quotes.

    I noted last May that the secrecy surrounding the iPad prior to launch was unnecessary. Nobody understood the product for months after it launched (and many still don't a year later).

    Apple keeps a tight lid on new products so that competitors don’t get a head-start on copying, but in the case of the iPad, advance knowledge would not have had any impact. Competitors look at the iPad and see nothing.  They’ll only react once the market explodes and they start to feel belated pain.

    Indeed, responses only came after sales figures started to cause consternation among competitors.

    How did these presumably keen observers of the market fail to notice the sea change under way? This is not just a rhetorical question. It really is hard. Students of disruption know that spotting such change is a difficult skill to obtain. But it is a skill, not a gift.

    So here we are, 12 months later and the derision has turned to flattery by imitation. The only scorn I hear about the TouchPad is that it can't come to market fast enough.

    ----

    1. I find this term repugnant and highlight it here only to ridicule those who coined it.
  7. Calling the end of innovation in mobile computers

    Research · 72 comments

    People are lining up to call the market for mobile phones. Analysts and amateurs alike are connecting points on charts and predicting with confidence the future of mobile platforms. Consensus is forming that there is no future but a quiescent state. By the acclamation of pundits, the survivors are declared to be iOS and Android. They are also predictably arranged in a way similar to OS X and Windows. End of story.

    Except for one thing.

    3.5 years ago neither of these platforms existed.  In fact, it was only two and a half years ago, in mid 2008, that one of the finalists even became a platform with the launch of an app store. The other "winner" only launched in a handset later that year and had no significant volumes until a year ago. In other words, these suddenly predictable platforms have been in existence for less than the life span of one device that runs them.

    To point out how extraordinary this claim is, if we look back to the history of computing, could we have declared the PC industry future cut and dried in 1978, two years after the founding of Apple? What about 1983, two years after the emergence of the IBM PC? What about 1986, two years after the Mac? Or maybe 1990, after Windows was born? Maybe the writing was on the wall in 1997, two years after Windows 95 caught up with the Mac's UX. That would be 21 years after Apple's founding. Some would argue that even today the story of desktop or portable computing is far from over.

    Sure, times have changed. Things move much faster now. But markets are also much bigger and take a long time to penetrate. Mobile channels are bounded by provincialism and parochialism.

    What's more, it's not like there haven't been platforms before these two upstarts came along. I've seen 9 mobile platforms in 9 years (PalmOS, Windows Mobile, Symbian, Java, WebOS, Windows Phone, iOS, Android, RIM Blackberry). New platforms are still emerging and evolving (e.g. MeeGo, Bada, LiMo, QNX and Tapas).

    So the existential question is this: If you were to draw a time line, would a mark in early 2011 signify the end of mobile platform history? The point in time when unforeseeable change will cease to happen?

    Let me offer a hint as to why not: every major platform battle has been sparked by an innovation built around a new input method. The keyboard integrated into a personal computer in the 1970s, the mouse in the 1980s, the stylus in the 1990s and the fingertip in the 2000s. Each of these input methods created new platforms (DOS/Apple ][, MacOS/Windows, PalmOS/Windows CE, iOS/Android), new ecosystems, new industries, new competitors and new platform battles designed to enrich forecasting pundits. I won't even try to go back to the changed in the half century of computing prior to the PC.

    So here's my challenge to the prognosticators: If you are willing to draw a line in the calendar now and say that no input methods will ever emerge in mobile computing after this point in time I'll buy the thesis that it's over and we can count our chips.

    If you think that out of the hundreds of user experience patents being filed, and hundreds of prototypes being slaved over in labs throughout the world, not a single new product will emerge with a new way of interacting with a computing device, then it's time to move on to something other than what can be declared a commodity market.

    But if you believe that, as happened four years ago, a new input method, previously only in the realm of mockups and movie magic, suddenly was shown, in a working product, on stage, then this business still has a chance of staying interesting.

  8. Of Platforms, Operating Systems and Ecosystems

    Research · 21 comments

    In the earnings Q&A Stephen Elop used the word 'Platform' once, 'Operating System' three times and 'Ecosystem' 15 times.

    Though they seem interchangeable, the three phrases have significant differences in meaning. Briefly put, a Platform is a business model concept,  an OS is a technology concept and an Ecosystem is a marketing concept.

    Platform

    A platform, as the New York Times recently pointed out, can take many forms. The Barbie doll is a platform as is the US Interstate Highway system. These are products or infrastructure that allow other products to be 'built on top' and can thus charge rents from them. When building platforms, a company needs to think of how to make their work foundational so it can support other structures. Other examples of platforms are browsers, the Apple 30 pin dock connector, Game Consoles and Facebook.

    In terms of innovation theory, a platform is a signal to industry that the company is willing to allow its innovations to be extended and thus share in the creativity of adopters. There is however a down side: platform adopters may also create so much value that users will shift loyalties to the layers above the platform thus restricting the freedom of the platform owner to modify or modernize the underlying platform.

    This loss of control over the roadmap often forces platform owners to institute draconian limits to the extensibility of the platform (e.g. the iPhone developer restrictions.) In other cases, platform owners have acquired and integrated various core apps or services so that the platform and core apps can be upgraded in sync. This was the impetus to the development of Microsoft Office. Office was motivated by a need to prevent Lotus from slowing the upgrade path for Windows not, as it's assumed, to create a new revenue source. However, again, the effect is the destruction of the ability to innovate on that particular area (no new Word Processor or Spreadsheet programs for 20 years).

    It takes a great deal of work to platformize a product. I would guess 10x more than a similar product which does not allow collaborative innovation. Platforms are difficult to build, require delicate balancing acts to maintain but can be enormously valuable due to network effects.

    Operating System

    In contrast an Operating System has a very clear technical definition. It has been extended to include many applications and services, but it's basically the control system of a computer. An OS may or may not be a platform. For example embedded operating systems typically do not have APIs to support applications. Some basic mobile operating systems support applications through a sandbox like JaveME (in this case the platform is Java) and are therefore also not platforms.

    A company licensing an OS may not accept the platform with the license or may not consider it valuable. It's even possible to license an OS and consider the platform value to be a liability to your own strategy (arguably HP fits in this scenario as regards to Windows. HP had its own operating systems and tried to build alternative platforms in spite of Windows).

    An example of an OS with minimal platform value may be WebOS which has a very limited API for native applications.

    Ecosystem

    The word ecosystem as it applies to technology was coined by Palm to describe the app vendors that built apps and the accessories for its Palm Pilot. This is not a common word as it's largely equivalent to Platform. The subtle difference is that it's used in a marketing context to signal platform value. Having a large ecosystem implies the acceptance of a platform by a large base of developers.

    For example a platform may not have a viable ecosystem if there are few developers and/or little economic value 'on top' of the platform. Symbian is often cited as being a decent OS, but a poor platform with a mediocre ecosystem.

    So these three phrases are overlapping but have a different tone. Although perhaps unintentional, Elop's emphasis on Ecosystem vs. Platform or OS, might signal that what's missing from Nokia's strategy is the motivation or encouragement of developers to participate. My prediction of WP7 licensing may not fit well with this deficiency but perhaps Microsoft's ecosystem building potential is still greater than Nokia's.

    I should also point out that Nokia's platform strategy has also included an intermediate layer called Qt that enables cross-platform ecosystems, thus making the OS irrelevant. Technically this may have merit, but it's a long haul to getting an ecosystem for it.

  9. This is the most exciting CES ever

    Research · 149 comments

    At this year's CES two unthinkable things happened:

    1. The abandonment of Windows exclusivity by practically all of Microsoft's OEM customers.
    2. The abandonment of Intel exclusivity by Microsoft for the next generation of Windows.

    Many of Microsoft's customers chose to use an OS product from Microsoft's arch enemy. Some chose to roll their own. Microsoft, in turn, chose to port its OS to an architecture from Intel's arch enemy.

    These actions confirm the end of the PC era. Although most people would characterize the era as exemplified by a particular form factor or market, for me the definition of that era is the way the value chain was structured and hence how profits were captured.

    That era was marked by the condensation of profits around two companies, Intel and Microsoft, with the simultaneous evaporation of profits from all other participants in the value chain.

    To achieve this, Microsoft maintained a monopoly on the distribution of operating systems and Intel maintained a monopoly as the single supplier of chip architectures for that operating system.

    These monopolies are both over. And they both ended at the same time. And it happened this week.

    Who says CES is boring this year?

  10. How sticky is Android?

    Research · 204 comments

    There is an assumption floating around the debates in this and other forums that the "battle" between mobile platforms is a land grab. The unspoken implication of this assumption is that once a user is captured she is permanently locked into the chosen platform never to move to another again as long as she lives.

    For example @dutchtender remarked:

    many people's first smart phone will be android. android can take them "cradle to grave." android will be there with a higher end solutions when they can afford it

    This is a strong but untested claim. It may be true but we owe it a bit of thought.

    A long time ago I tried to model platform growth is by using a version of Metcalfe's law. I suggested that the value of a network is proportional to n log (n) where n is number of nodes in that network[1]. This was somewhat based on common sense as it measures the possible links between n nodes with degradation due to the limits of social graphs.

    The value the network creates is what developers as well as all the other participants in the ecosystem are able to tap into. The platform vendor gets to capture a share as well of course. As the value grows it tends to create network effects or a self-reinforcing cycle.

    What I'm saying then is that we can treat a platform as a network, where each node is linked to another node by the commonality of experience.

    The proxy of the model was Windows. Twenty years ago, having Windows meant that you could exchange files with other Windows users simulating a sort of network protocol. You could also ask your peer group for help and get software tips and new consumption ideas. So the more people used Windows the more likely it was that you also had to use it. Avoiding Windows limited your ability to be part of productive society (this is no longer true by the way, which is one reason Microsoft is in trouble).

    If we fast forward to the mobile post-PC world, when it comes to platforms the shared experience is that of apps. People can communicate their app experiences and their usage better if they have the same platform. They can also learn from each other how to better use the products and how to solve problems. The more people that use a mobile platform, them more value it generates for platform participants.

    The other factor determining value is that a platform also creates sunk costs. Usually called "investments" by users these are costs that are incurred and have a potential for future value. This means that the apps purchased and time spent learning and adjusting to the platform are sunk costs which users are reluctant to abandon. (Notwithstanding the fact that as sunk, these costs should be ignored when comparing the value of another platform,--psychology is what keeps users loyal even if it's not in their best interest.) This "sunk" factor of value is not as powerful as the sharing of experiences value since it does not scale with the number of users. That cost is a constant multiplier on top of the n log (n).

    So the overall "value" of a platform is K n log(n). Where K is the stickiness of sunk costs.

    Can this be stated plainly without the math?

    When you compare two platforms you have to ask how contiguous users (n) grows and how stickiness (K) grows. The issue with fragmentation is that it actually cuts n. Many people won't be able to share experiences if their devices don't work the same way. Same with geographic density of a platform. If, as was the case with Symbian, there are few segments that became saturated with the platform then n is reduced.

    The issue with a lack of paid or compelling apps is that it cuts stickiness, so that you don't have any sunk costs. Similarly the presence of ported or common apps means that K is reduced for any single platform. Nokia's Symbian has a serious problem with both consistency and with commonality of experience. RIMM depends too much on the commonality of messaging which is quickly becoming a commodity due to portability of the experience.

    So in the end it's not just about how big the user base n is (which is the only thing that is measurable). It's how contiguous n is and how compelling the content.

    This is too sketchy a model to be practically applied but it offers a thought experiment: does any given platform have

    • A large, contiguous user base with strong concentrations of users in the same demographic or psychographic segments?
    • A significant set of unique content (apps) which require costs from the user (in terms of data, time or cash)

    It's not a clear cut case in my mind that Android benefits from these as much as iOS does. If that's the case, users are more likely to be moving on a one-way street between these two: from Android to iOS and not vice versa. The same thought experiment can be engaged in between any two platform contenders.

    ---

    [1] Metcalfe's law is actually an n*n growth curve but recent research indicates that social networks scale in value as n log (n).

  11. The parable of the the PDA: predicting the smartphone's future

    Research · 55 comments

    When reading the comments disputing the possible end of the voice-phone era I'm reminded of similar comments disputing the end of the PDA era.

    Although the Apple Newton pioneered the market in 1992 and John Sculley came up with the acronym, the Newton did not sell in significant volumes. It wasn't until 1997 with the Palm Pilot that the PDA market took off. Microsoft quickly followed with a licensed OS based on Windows CE. In 2001 Microsoft launched the Pocket PC brand to cement its attack on the PDA market. The first phones using a Microsoft OS were using something called Pocket PC Phone Edition. The first Nokia smartphones (Communicators) were built like mobile PDAs.

    The logic was quite compelling. The original PDA was built to mobilize contacts, calendars and notes. They replaced bulky paper organizers and seamlessly synced to PC productivity software like Outlook. It was a compelling product in the US where small business customers needed to keep track of hundreds of contacts. Users could even 'beam' contacts to each other via infrared. The idea of adding a phone function to the device made sense insofar as contacts could be immediately dialed from the contact app rather than typed into another device's phone keypad.

    By the early 2000's PDAs were forecast to sell by the hundreds of millions. There were millions of dedicated users who downloaded apps and thousands of developers being courted by platform builders. Palm even invented the word "ecosystem" as it refers to mobile platforms.

    However, I remember reading sites dedicated to this community and there were many people who rejected the concept of a PDA with an integrated mobile phone. They liked the fact that the PDA was not bundled with a phone plan. They upgraded PDAs in a different cycle from phones and besides, phones are for talking and PDAs were for something else.  It was even more difficult to justify the conflation of the two products when considering the corporate purchasing of PDAs. PDAs were procured by IT departments and phones came with contracts that were managed by a different department.

    What's a device vendor to do? The most avid customers of PDAs did not like the idea of burdening the product with a phone. RIM was doing its thing with moving pagers to include voice, but that was a different job to be done. The story is picked up here by this comment:

    I was hired by RIM in 1999 just before they began work on their first phone .... Coming from a two-way pager background, RIM decided that phones should have two-way push synchronization of pretty much everything that Exchange provided along with a limited WML browser. The general thought was that phones would never have sufficient power density or radios sufficient bandwidth to allow anything more. That was incredibly predictably wrong, but it's how things went down.

    Along with RIM was Ericsson, Palm, Motorola, and Qualcomm. Motorola came from a similar background as RIM and went on to build very similar devices. Both Nokia and Ericsson had come from phones and had decided feature phones should have far more sophisticated PDA functions. Palm started with PDAs then moved to the phones, but adamantly dismissed ideas like wireless synchronization for years making their first attempts at smart phone far more like early Nokia Communicators than early Blackberrys...

    So the point is that all these companies were fighting over what amounts to overgrown PDAs with phones and wireless stacks strapped on. Everyone assumed power density was no where even close to what was needed for general computing, that a full featured browser and heavy duty Internet services were impossible due to bandwidth and latency. Take a look at how our Java expert groups named standards, how people at the time talked about what features smart phones should have, and its clear that no one thought an iPhone was possible. Even Danger, which eventually went on to work on to create Windows Phone 7 and Android, was just working on a better Blackberry.

    via: shacknews

    But what does this have to do with the future of voice-phones?

    The problem is that the vendors that lost this game failed because they listened to their customers. Like with PDAs or with the original mobile phones or first generation of PCs, early adopters are not the audience that should be consulted on how to improve the product.

    Early Windows Mobile users were ecstatic about the platform and rejected new UI metaphors because they wanted a "mobile Windows". Palm fans stuck with the PalmOS even though it was well past its shelf date in the Treo because they treasured the original PDA metaphors.

    Every company paying attention to the market in 2005 would have been eagerly pursuing corporate buyers of PDAs and aiming complex products at enthusiastic PDA users.

    And yet, non-consumers should also not be trusted with their opinions. Most early surveys would show that the vast majority of consumers found that mobile phones were not good value for the money. Later the same audience would declare that smartphones were not worth buying.

    There are many voice-only users in the world who are happy with their products and not interested in any new options.

    So what's a marketer to do?

    If you can't ask early adopters and you can't ask non-consumers for hints then where can clues be found?

    What history shows is that consumers have been happy to trade up to technology that offers more option value.

    • Television went from cheap/free over-the-air broadcast with limited channel options to expensive cable with large option value in channels. Even if most of those options went unused, they are still valued.
    • Telephony went from low cost reliable landlines to high cost, less reliable but with much more option valuable mobility. Having the option to call a person vs. calling a place (where a person might be) changed the calculation of whether you make the call. Calling became much more popular.
    • Data as well went from metered dialup to unmetered high option valued broadband. From a luxury, to the least likely service an unemployed user might give up.
    • Emerging market users hungered for mobile phones even though they cost more than several months' wages because they gave access to information and increased the option value of their labor.

    Each of these huge technology transitions came associated with increased costs for the consumer, but that cost went toward the purchase of a far larger option value.

    The problem is that users cannot calculate option value in their minds when faced with a market research questionnaire. How can they envision all the ways they would use a new product they've never used before? How can they "get it" without observing it in use or spending time thinking of "how they would use it" or asking someone who tried it? In a nutshell, users are willing to pay for option value but can't envision or quantify this value without observing a finished, polished product in use.

    This is the problem faced today by branded phone vendors. Asking or observing current users of smartphones does not provide any incentive to sell low end versions. Asking or observing non-consumers seems to indicate no interest in newfangled complex or costly products.

    But the calculus that must be made is one of option value. Does the new product offer significant option value? Will this option value be easily realized? This is not easy to determine, but it's a method that is far more promising than asking users their opinion.

    The PDA was not a product that was introduced by the incumbent computer vendors because their customers did not ask for it. Once established, the PDA was not replaced by a product that PDA users asked for either.

    Smartphones are following this well trodden path. The high end devices are evolving into computer replacements nobody asked for (but everybody will use). The low end products are adding data option value to voice-oriented users who never asked for anything more.