Asymco

Asymmetric Intelligence

Horace Dediu

  1. John Ternus has left big shoes to fill

    Research · 4 comments

    April 21, 2040

    It's been 15 years but John Ternus has finally stepped down as Apple CEO. Analysts described the transition as expected rather than disruptive, noting that investors had long anticipated Ternus' eventual departure. Nevertheless, he leaves with many questions still unanswered about Apple's long term strategy. Apple incoming CEO faces a defining challenge: Fixing the company’s Services dependence.
    It's been a tumultuous tenure for Ternus but he is leaving with significant accomplishments:

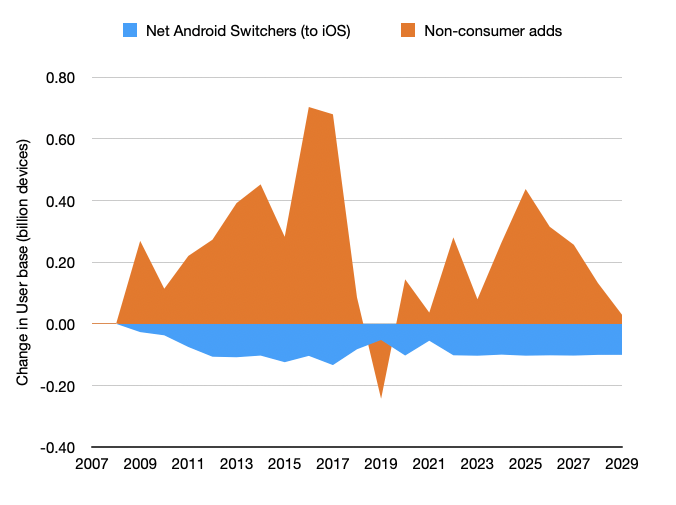
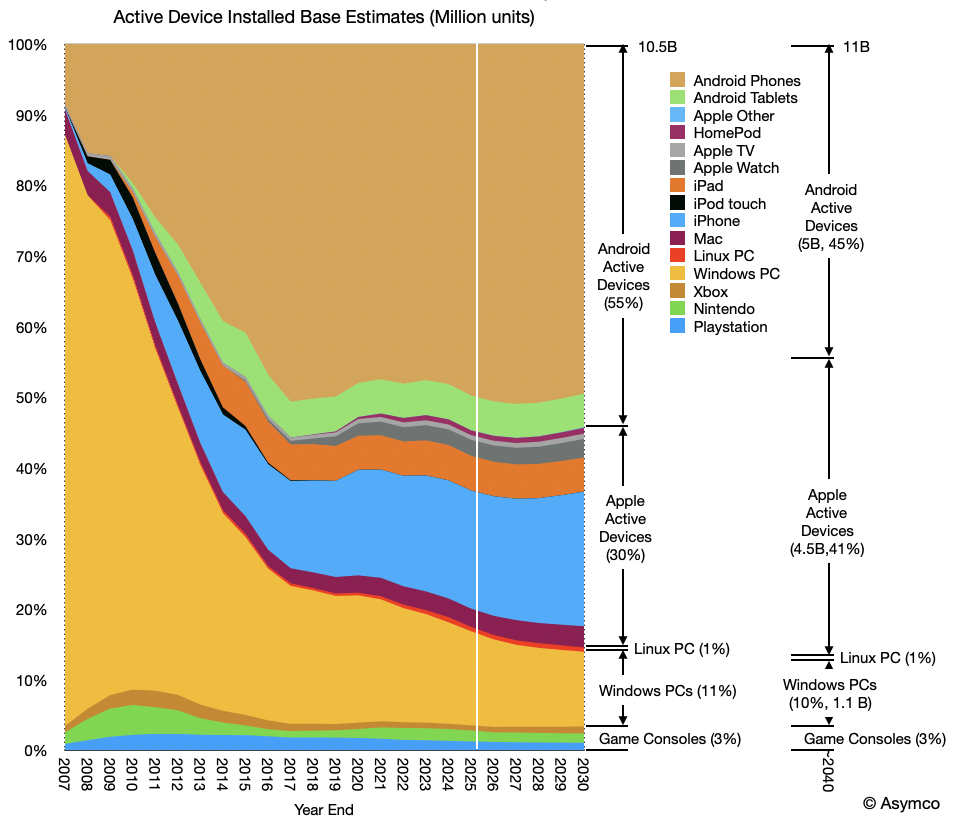
    • John grew Apple devices to 4.5 billion from 2.5 billion when he took over in 2026. Many have pointed out that he has been building on Tim Cook's success and that John has only added 2 billion devices in 15 years, averaging 110 million per year. The reality is that most of those have been switchers from Android rather than first-time users. Because of this, Android's 5 billion active devices means Android users still outnumber Apple users. Apple's users do have attach rates of over 2.5 devices per user including passive AI wearables but the competition is not standing still. The new CEO will face the challenge of trying to wrest majority market share in a saturated 12 billion active device market.
    • With over 2 billion customers, Apple is capturing over 40% of all AI revenues. Critics point out that the company has not grown beyond its core: high net worth and high income households. Much of that foundation was laid by his predecessor and arguably all that John has done is maintain a base that grew organically as global income has risen. Over a billion middle/high income individuals have joined the world economy as Apple users but that is hardly attributable to Ternus. His engineering acumen did not give him the insight into marketing to low income countries where most of the users are shunning Apple products.
    • John has had to navigate a challenging geopolitical situation with the rise of India as the world power and the decline of China. Critics pointed out that Apple's dependence on India is an Achilles' heel and that his transition of production and market growth from China to India has been rough and challenges remain with regulation and labor unrest. The Indian middle class has been the growth engine for a decade but, as all eyes are on Africa and South America, Apple has been on its back foot.
    • Apple grew the AI business but now depends too much on in. Growth since 2038 has slowed from mid teens to low teens and analysts are pointing out that Apple is too dependent on Services as its biggest source of revenue. Apple's P/E ratio is now below the average of the Fab Five reflecting investor skepticism that it can capitalize on submersible data centers in international waters. Its insistence on local sovereignty for data storage goes against the bathospheric consensus.
    • Competition has been kept at bay, so far. Apple has seen off challenges by Anthropic, Netflix and SpaceX but there are hundreds of startups looking to build the next Services killer. Billions of satisfied customers are not the moat they used to be.

    Apple has made it this far, recently celebrating its 65 anniversary but there is no guarantee that it can continue its run as the world's most valuable company. The next CEO has to steer the ship Ternus just managed to helm through stormy seas.
  2. Succession, study of the firm vs. study of the person

    Research · 2 comments

    The Asahi Shimbun Interview Part 5

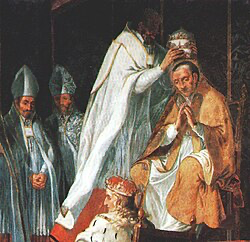
    Coronation of Celestine V; ~1215 – 1296. The only Pope to be crowned twice.1

    Horace Dediu / Takeshi Narabe & Dylan Weir / Asahi Shimbun Interview, April 1, 2026

    Dylan Weir • 31:51
    There's been some reports that Tim Cook is on the way out and some speculation about who might replace him. Is that your sense, that he will be leaving soon?

    Horace Dediu • 32:06
    One thing that hints in that [direction] is that the board members are actually limited to age 65 and he is on the board although they can extend that by vote. So one should imagine that there is an age limit. The hypothesis however is that he's too valuable. Not so much as the manager but as the negotiator and as the diplomat. Because we live in such difficult times from a geopolitical point of view he somehow has managed, i don't know how, nobody knows how, even Warren Buffett recently pointed out that he thinks that's one of his greatest skills: that everybody likes Tim Cook.

    That includes China that includes Trump that includes Europe. Somehow he gets along with everyone. So his ability to be the diplomat, will it be perhaps valued further? One possibility would be that he actually becomes executive chairman as opposed to CEO. That he continues in that role without having to do day-to-day operations.

    There are people who are very good at that. And who've been on the bench for a long time and who've been cultivated for a long time to step in his place. So in that sense, on these fundamental questions of biological life...

    You know, I think one hypothesis that makes sense is that he might stay as long as there's a Trump administration, because again, he's able to navigate that world. But yes, I think ultimately, though, he will be gone. And there's no question. And when he joined, he knew he'd be gone some day. There's no naiveté about his need to hand things to the next generation. And I think that was part of the thinking under Steve as well: How do we hand this off? And they've been thinking about it ever since.

    But anyway, the speculation is John Ternus is the next in line. I think that's a very plausible hypothesis. And one reason, by the way, is I always maintain if you study the company from a cultural point of view, you'll realize that there are people who cannot be CEO. You may not know who it's going to be, but I can tell you who won't be. Many people over the years suggested candidates, and I would say no, never. And here are examples. Johnny Ive would never be CEO. An external hire would never be CEO. Even a head of marketing would never be CEO. Many people think that Apple is a brilliant marketing company. No, it's an engineering company. It's a huge secret out there.

    If you look at the headcount, if you divide the employees by their job functions, you'll see that engineering is by far, three to four times, bigger than the next category, which would be perhaps marketing or operations. So what does that mean from a cultural point of view? It means that the people who are engineers want to have a boss who can listen and understand them. And they don't think, if you know engineering culture, […] that someone who's from marketing is going to be able to understand them because they don't have the cultural and the educational background or the mentality around engineering.

    And so the people who need to run Apple have to be competent with engineering. In the case of operations, it's one of those acceptables because they are at least covering engineering as one of their constituencies. So they have to bridge between manufacturing, distribution, and all these things. So engineers respect operations. Engineers respect manufacturing. So in that sense, when you look at the candidates, I do think John is one of those who fits the bill. Of course, there could be many others as well.

    Dylan Weir • 36:36
    That's fascinating. Thank you.

    Horace Dediu • 36:41
    I think if I may just summarize, I think it's very rare that any analysis--and I come from an engineering background and I did my work always in a lot of data, using a lot of data. But the more I study Apple, the more I think it needs to be analyzed culturally. And it's a very difficult thing to do because we have no data. We have only some anecdotes. But you have to, as an analyst, you have to be humble and see that the data, perhaps that [which is] most important, is not available.

    When it's dark outside and you're searching around the lamp, well, that's the only area that you have light. but the truth could be in the darkness. And that area under the light, that's your data set. And the solution is somewhere else perhaps. And that's why you have to have this idea: what tools can we use other than looking at the light? Use all your senses. Use other perceptions.

    And so that's why I think Apple is a peculiar thing. And by the way, the analysts out there who do try to stay out of the data [delve] more into psychology, they tend to really study the man or woman. They'll study the personality as an alternative [to the data]. So they'll say, well, the company's success depends on Zuckerberg. We have to know who he is. Or Tim Cook or Steve Jobs or Larry Ellison, whomever it is.

    There are people who specialize in understanding that person but i don't think Apple is that. I think [personality is] important but you have to study the whole. The whole way they do things internally. They give us plenty of hints; they say all the time that it's a team effort. They'll always say "no it's not me, it's it's a group effort".

    And and they always say "we" [not I].

    You know, we have a lot of debates [but I believe] we have to take them at their word that it isn't just the individual.

    Takeshi Narabe •

    Thank you so much it's very you know insightful analysis thank you very much.

    Horace Dediu • 38:57
    i love your questions. You have great questions and that's always my my biggest thrill. And not that i'm not being asked what color is the next iPhone.

    Previous in series: Part 4: How not to over serve; The machinery of vanity

    Interview as published: 聞 Asahi Shimbun on Apple & Innovation

    1. Sic transit gloria mundi means "thus passes the glory of the world". The phrase was used in papal coronation ceremonies between 1409 and 1963. As the newly chosen Pope proceeded from the sacristy of St. Peter's Basilica, the procession stopped three times. On each occasion, a papal master of ceremonies would fall to his knees before the Pope, holding a silver or brass reed, bearing a tow of smoldering flax. For three times in succession, as the cloth burned away, he would say in a loud and mournful voice, "Pater Sancte, sic transit gloria mundi!". These cautionary words served as a reminder of the transitory nature of life and earthly honors.
  3. MacBook Neo Sold Out Through April

    Nota Bene · 3 comments

    I keep holding out that this is not a problem

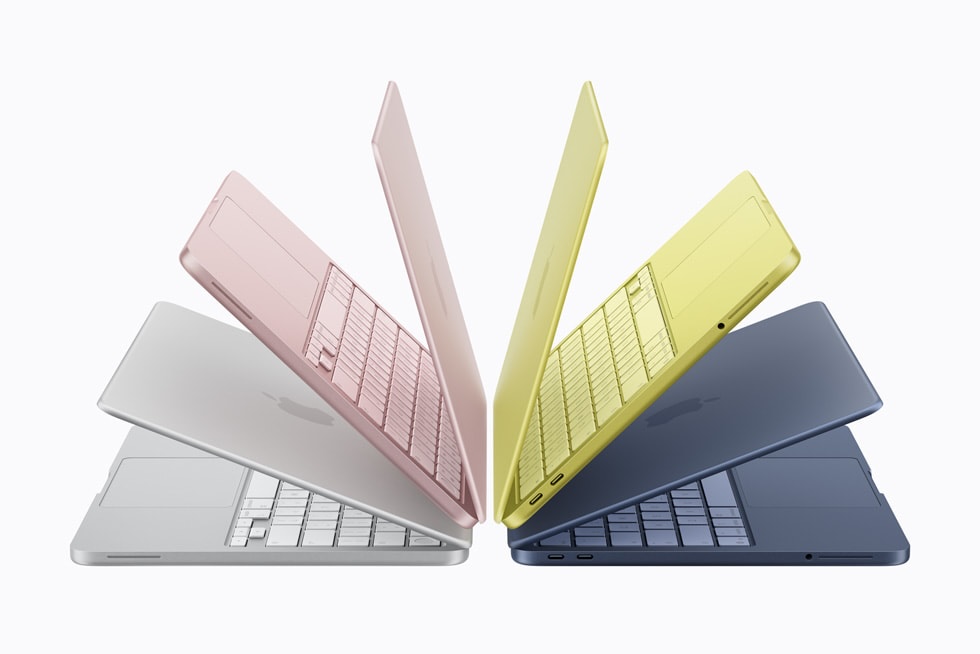
    Apple's MacBook Neo has been a huge hit, and it's still in high demand over a month after it launched. The ‌MacBook Neo‌ is just $599, and with PC makers raising prices because of global RAM shortages, the Neo's low price tag and Apple allure are even more appealing.

    Source: MacRumors

    NB: Microsoft's cheapest laptop is three times more ex…

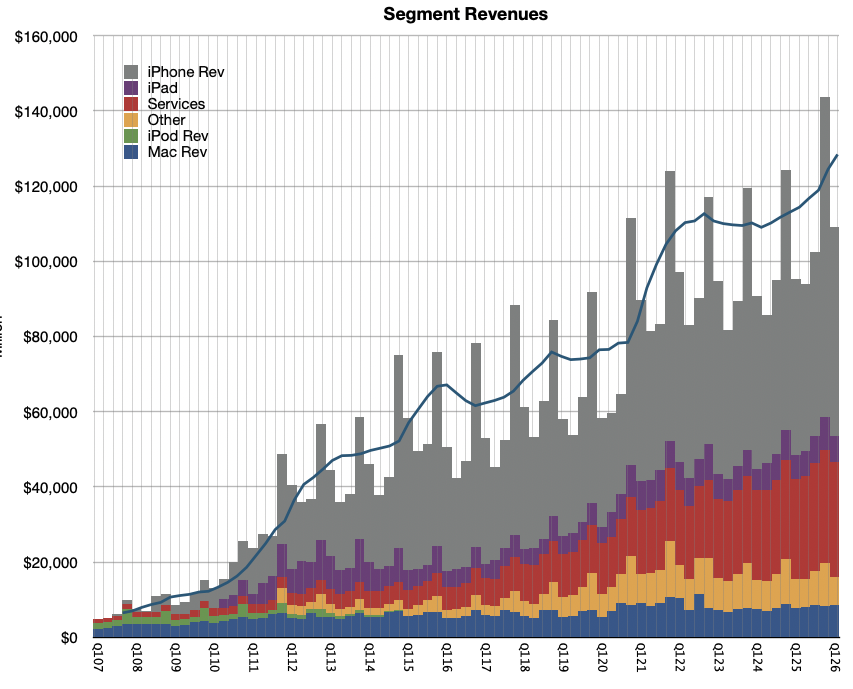
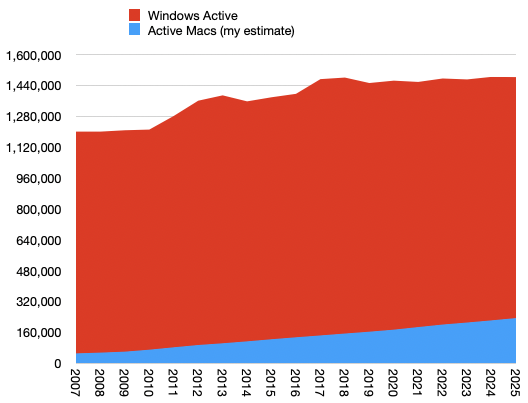
    …pensive. Selling out is a problem is customers will abandon the purchase and buy something else. I suspect some may but some may even buy another Mac. The Mac Mini and Studio are also in stockout status. It's a windfall for the Mac but the big picture is shown in the graph below. Can Apple bend the blue curve?

    As I will argue in a further post perhaps this is one of those pivotal moments.

    MacBook Neo Sold Out Through April


  4. IDC: Apple Grows 33.3% in China as Market Declines 3.3% in Q1 2026

    Nota Bene

    Counterpoint says 20% and -4%

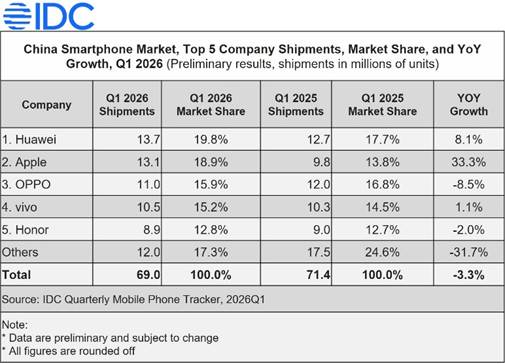
    China smartphone shipments fell 3.3% in Q1 2026 to 69M units, with Huawei and Apple driving premium demand despite rising costs and supply constraints.

    Source: IDC

    Separately, CounterPoint research reports;

    China’s smartphone shipments declined 4% YoY in Q1 2026, as memory shortages disrupted supply and drove up costs across OEMs.

    Huawei led the market in Q1, supported by its domestic supply chain advantages and stable pricing. As a result, the brand recorded its highest-ever quarterly share in China since Q4 2020.

    Apple delivered the strongest growth among the top six brands, and it is widely seen as best positioned to navigate the memory crunch.

    NB: Both researchers say Apple share in China is about 19%, nearly tied with Huawei at 20%…

    …. The big loser seems to be "Other" down 32%. Clearly Apple management saw this coming and guided accordingly.

    Some analysts are increasing their targets finally realizing that the memory supply crisis might be beneficial to Apple. This should have been noted already three months ago when Apple provided extraordinary guidance for the March quarter.


  5. Asymco Bulletin 009 - Apr 19, 2026

    Bulletin

    Asymco Bulletin is a digest of all the work we have published for the week ending Apr 19, 2026.

    Research

    Estimates for Apple’s March Quarter 2026

    Estimates for Apple’s March Quarter 2026

    Revenues and growth rates for iPhone, Mac, iPad, Services, Wearables, plus Net Sales, Gross Margin, Operating Expense, Other Income and Expense, Tax Rate, Net Income, Share Count and EPS with a comparison to CFO guidance.

    Ref. conference call's guidance, Kevan Parekh, Apple CFO: As we move ahead into March, I would like to review our outlook, […]. We expect our March total company revenue to grow by 13% to 16% year over year, which comprehends our best estimates of constrained iPhone supply during the quarter. We expect services revenue to grow at a year-over-year rate similar to what we reported in December. We expect →

    The Inevitability of Combining the Digital and Physical Worlds

    The Inevitability of Combining the Digital and Physical Worlds

    In a recent interview Apple management was asked about AI, which is perceived as an area where Apple has been struggling. Greg Joswiak replied: We’ve been doing things with intelligence for many years, right? And gen AI allows us an opportunity to do that even more. So I’m excited about that, but boy, this is not a sprint. This is a marathon.

    In contrast to AI, Spatial Computing is being largely ignored. It is however making significant leaps in utilization, especially in verticals. →


    Nota Bene

    Monday Notes: Neo still sinking in

    Monday Notes: Neo still sinking in →

    Apple's potential to double its Mac user base through strategic budget expansion and memory supply tactics presents a promising growth trajectory.

    260 million Mac users? Huge room for growth.

    Two analysts, two stories. The Neo will move the needle and the supply crunch will hamper competition…

    Nevertheless, a doubling of the Mac user base is certainly a worthy and achievable goal over the next decade. →

    Apple Studio Display XDR Now Cleared for Diagnostic Radiology

    Apple Studio Display XDR Now Cleared for Diagnostic Radiology →

    At just $3,000, the Studio Display XDR democratizes medical imaging, undercutting specialized monitors by up to 90% and revolutionizing healthcare accessibility.

    The ‌Studio Display‌ XDR is priced at $2,899 with a VESA mount, and it is more affordable than many specialized medical imaging monitors.

    It allows a new set of people to do what previously required only specialists to do and allows specialists to do more than they used to do. →

    Antelope standing beside a wooden desk with a vintage Macintosh computer

    All of a sudden, everyone is doomed except Apple →

    Despite optimistic predictions for Mac growth, persistent skepticism argues Apple faces inevitable doom due to supply issues and product flaws.

    As honored as I am to be the recipient of an antlers tip, I must respectfully disagree…

    The only thing you could be sure of is that Apple is doomed. →

    Computer History Museum interviews Bertrand Serlet

    Computer History Museum interviews Bertrand Serlet →

    Bertrand Serlet, a pivotal yet understated architect behind Apple's OS X, exemplifies the profound impact of tech's quiet innovators.

    Pay attention to the quiet ones

    This is one in a series on Apple’s quieter heroes.…

    That this interview only has 6000 views after three years shows how much untold history exists. →

    Bank of America raises Apple price target to $325 from $320 →

    BofA slightly ups Apple's price target to $325, forecasting $113B revenue and $2.00 EPS for Q2, driven by strong iPhone sales and Services growth, slightly above my estimates of $110B and $2.00.

    Q2 forecast update

    My own estimates for Q2 revenues and EPS are $110B…

    More to follow as we get closer to the earnings release date but this is a good preview. →

    Omdia releases first estimate for Q1 PC unit shipments →

    Apple's Mac shipments grew 5.4% to capture 11% market share in Q1 2026, driven by MacBook Air and Neo sales, with revenue estimates slightly differing from unit projections.

    Apple growing at double market rate.

    Omidia estimates that Apple reached a market shar…

    …e of 11% with shipments growing 5.4% due to solid MacBook Air sales performance and the initial sell-in of the MacBook Neo.. This means 5.4% growth for Apple y/y. As I noted in my Office Hour yesterday, I adjusted my Mac growth from 0% to 6% based on the new products launched. This is an estimate of revenues not units but it might be pretty close. Omidia estimates 7,112 million units whereas I’m a little above 6 million. We seem to disagree on ASP. →

    Apple and Amazon Partner on Satellite Deal

    Apple and Amazon Partner on Satellite Deal →

    Amazon's acquisition of Globalstar boosts its satellite internet ambitions and strengthens ties with Apple, while highlighting the limited reach of space-based networks compared to terrestrial ones.

    I assume Apple has wanted to steer clear of Starlink but it’s not clear that was a primary consideration in choosing Globalstar.

    Starlink, considered the dominant player, serves about 11 million users. I would note that 11 million is 0.1% of the number of cellular subscriptions worldwide. →

    iPhone vs Android Switching Rates →

    iPhone users boast nearly quadruple the loyalty of Android counterparts, with actual annual switching rates favoring Apple slightly, despite inflated survey intentions.

    I did a deep dive into the data and came up with graph above. The original report shows intention numbers which seem quite high. For instance, the net switching rate between iOS and Android is 10% in favor of Apple. This would imply that the entire user base would flip in 10 years. It would also imply…

    I think actual net churn is 1.7% of the base each year. That’s still 100 million a year. For now it seems Apple is happy to maintain that rate. →


    Office Hours

    Asymco One Office Hours Live Q&A with Horace Dediu & Gene Munster: April 8, 2026

    Asymco One Office Hours Live Q&A with Horace Dediu & Gene Munster: April 8, 2026 →

    Asymco Office Hours, April 8, 2026

    Hosts: Horace Dediu and Gene Munster

    This episode of Asymco Office Hours covers a wide range of topics related to Apple, including geopolitical risks, financial performance, AI developments, and business strategy. The discussion is led by Horace Dediu and Gene Munster, with insights from industry experts.


    Podcast

    Asymetric Podcast: Waterloo

    Asymetric Podcast: Waterloo →

    In this Asymmetric Podcast episode, Horace muses on buying flowers, highlights Apple's distinguishing product, and teases his new research. →


    Asymco One gives you full access to our research, analysis, and commentary. Subscribe with code BULLETIN for a discount.

    Feedback: Have questions or comments? Reach out to us at contact@asymco.com. We’d love to hear from you.

  6. iPhone vs Android Switching Rates

    Nota Bene · 3 comments

    Bitchin' ain't Switching

    SellCell’s Smartphone Loyalty Survey 2026 shows iPhone and Android loyalty at record highs, but Android users still switch more.

    Key findings

    iPhone loyalty stands at 96.4%, up from 91.9% in 2021

    iPhone switching stands at 3.6%

    Android loyalty stands at 86.4%, with switching at 13.6%

    Android users are nearly four times more likely to switch than iPhone users

    Samsung loyalty stands at 90.1%, up from 74% in 2021

    Samsung switching stands at 9.9%

    Google loyalty stands at 86.8%, up from 65.2% in 2021

    Google switching stands at 13.2%

    The loyalty gap between iPhone and Android now stands at 10 percentage points

    Price and value are the biggest drivers of switching

    Technology is the second biggest driver

    Overall, loyalty has increased across all major brands since 2021

    Source: SellCell.com Blog

    NB: I did a deep dive into the data and came up with graph above. The original report shows intention numbers which seem quite high. For instance, the net switching rate between iOS and Android is 10% in favor of Apple. This would imply that the entire user base would flip in 10 years. It would also imply...

    ... that Apple gains over 400 million new users every year as Android base is about 4 billion. But we know that Apple gains about 100 million a year based on the active device tally (now at 2.5 billion active devices and 1.5 billion active iPhones).

    Therefore, based on the known install bases and growth therein, we can determine that the actual switching rate from Android to iOS is about 2.6% for any given year and the switching rate from iOS to Android is about 0.9%. Android still gains overall users since new users are converted from non-consumption.

    About 300 million are still being added to Android while 100 million are lost to iOS.

    As time goes on and saturation is reached (near 5 billion active smartphones) then the churn will imply that Android will eventually become a net user loser.

    That probably won't happen before 2030. When saturation does happen however, I will be watching to see if Apple chooses a different strategy to accelerate switching similar to what it is doing with the MacBook Neo at a time of PC market saturation.

    The lesson here is that switching intention surveys showing a net 10% churn rate don't mean that the actual switching rate is net 10%. The intention to switch is a sentiment but actual switching is often more difficult than a wish to do so.

    I think actual net churn is 1.7% of the base each year. That's still 100 million a year. For now it seems Apple is happy to maintain that rate.

  7. Apple and Amazon Partner on Satellite Deal

    Nota Bene · 2 comments

    Counting satellites and subscribers

    Amazon said on Tuesday that it’s agreed to acquire satellite company Globalstar, a major step for the e-commerce business as it works to build out a space-based Wi-Fi service through its Leo initiative.

    Amazon also announced that it signed an agreement with Apple to provide satellite connectivity for current and future iPhone and Apple Watch features. The partnership was made possible via an existing deal Apple already had with Globalstar.

    Amazon said on Tuesday that it plans to work with Apple on future satellite services. “Amazon will continue to support iPhone and Apple Watch models currently using Globalstar’s existing and planned upcoming low Earth orbit satellite constellations, being manufactured by MDA Space, and collaborate with Apple on future satellite services using Amazon Leo’s expanded satellite network,” a news release read.

    Source: Barron's via Apple Stocks

    NB: I assume Apple has wanted to steer clear of Starlink but it's not clear that was a primary consideration in choosing Globalstar.

    The deal gives Amazon access to Globalstar’s network of two dozen satellites. Amazon has the aim of deploying about 3,200 satellites in Earth’s low orbit by 2029. Amazon currently operates a network of more than 200 satellites and is preparing to roll out its satellite internet services later this year.

    Globalstar powers Apple’s “emergency SOS” feature and had received an investment of $1.5 billion for 20% share. Under that development, the network would expand to 54 satellites. Amazon and Apple have signed an agreement to continue the services.

    Incidentally, given the acquisition price, Apple's $1.5 billion investment is now worth $2.13 billion.

    The acquisition of Globalstar by Amazon is a positive for Apple as it ensures there is additional investment in space-based networks and thus there isn't the possibility for a single supplier situation. Apple's investment in Globalstar was already a signal of their intention to sustain competition. However, it should be understood that space-based networks were never going to rival land-based except for remote locations and emergency or military use.

    Starlink, considered the dominant player, serves about 11 million users. I would note that 11 million is 0.1% of the number of cellular subscriptions worldwide.


  8. Omdia releases first estimate for Q1 PC unit shipments

    Nota Bene

    Apple growing at double market rate.

    According to the latest research from Omdia, total shipments of desktops, notebooks, and workstations in 1Q26 increased by 3.2% year-over-year to 64.8 million units. Notebooks (including mobile workstations) saw a modest year-over-year increase of 2.6% in Q1 to 50.8 million units. Meanwhile, desktops (including desktop workstations) performed slightly better, up 5.4% to 14.0 million units. Growth was supported by vendors and channel partners pulling orders forward ahead o

    Source: Yahoo Finance

    NB: Omidia estimates that "Apple reached a market shar…

    …e of 11% with shipments growing 5.4% due to solid MacBook Air sales performance and the initial sell-in of the MacBook Neo.". This means 5.4% growth for Apple y/y. As I noted in my Office Hour yesterday, I adjusted my Mac growth from 0% to 6% based on the new products launched. This is an estimate of revenues not units but it might be pretty close. Omidia estimates 7,112 million units whereas I'm a little above 6 million. We seem to disagree on ASP.


  9. Bank of America raises Apple price target to $325 from $320

    Nota Bene

    Q2 forecast update

    BofA raised the firm’s price target on Apple to $325 from $320 and keeps a Buy rating on the shares ahead of fiscal Q2 earnings due after market close on Thursday, April 30. The firm, which sees upside to Street estimates given continued strong sales of iPhone and double-digit growth in Services revenue, forecasts Q2 revenue and EPS of $113B and $2.00, respectively.

    Source: TipRanks Financial

    NB: My own estimates for Q2 revenues and EPS are $110B…

    …and $2.0, respectively. These are equivalent to top line growth of 15% and bottom line 22%. It would be the highest growth since the Covid era.

    A $2/share implies a current P/E (inclusive of the Q2 that just ended) of 30.

    More to follow as we get closer to the earnings release date but this is a good preview.  


  10. The Inevitability of Combining the Digital and Physical Worlds

    Research · 1 comment

    Seeing is believing

    AI is attracting all the attention but one should be careful because if there is one thing about technology is that timing is everything and when attention is concentrated it signals that time is distorted.

    In a recent interview Apple management was asked about AI, which is perceived as an area where Apple has been struggling. Greg Joswiak replied:

    We've been doing things with intelligence for many years, right? And gen AI allows us an opportunity to do that even more. So I'm excited about that, but boy, this is not a sprint. This is a marathon, right? We're going to be doing stuff with intelligence for decades, not months or years.

    He also declined to comment on smart glasses, but said we're in the "early innings of spatial computing," while Ternus said that combining the digital and physical world is an "inevitability." The two were tight-lipped about any upcoming Apple products, but Joswiak said Apple is "working on some pretty cool stuff."

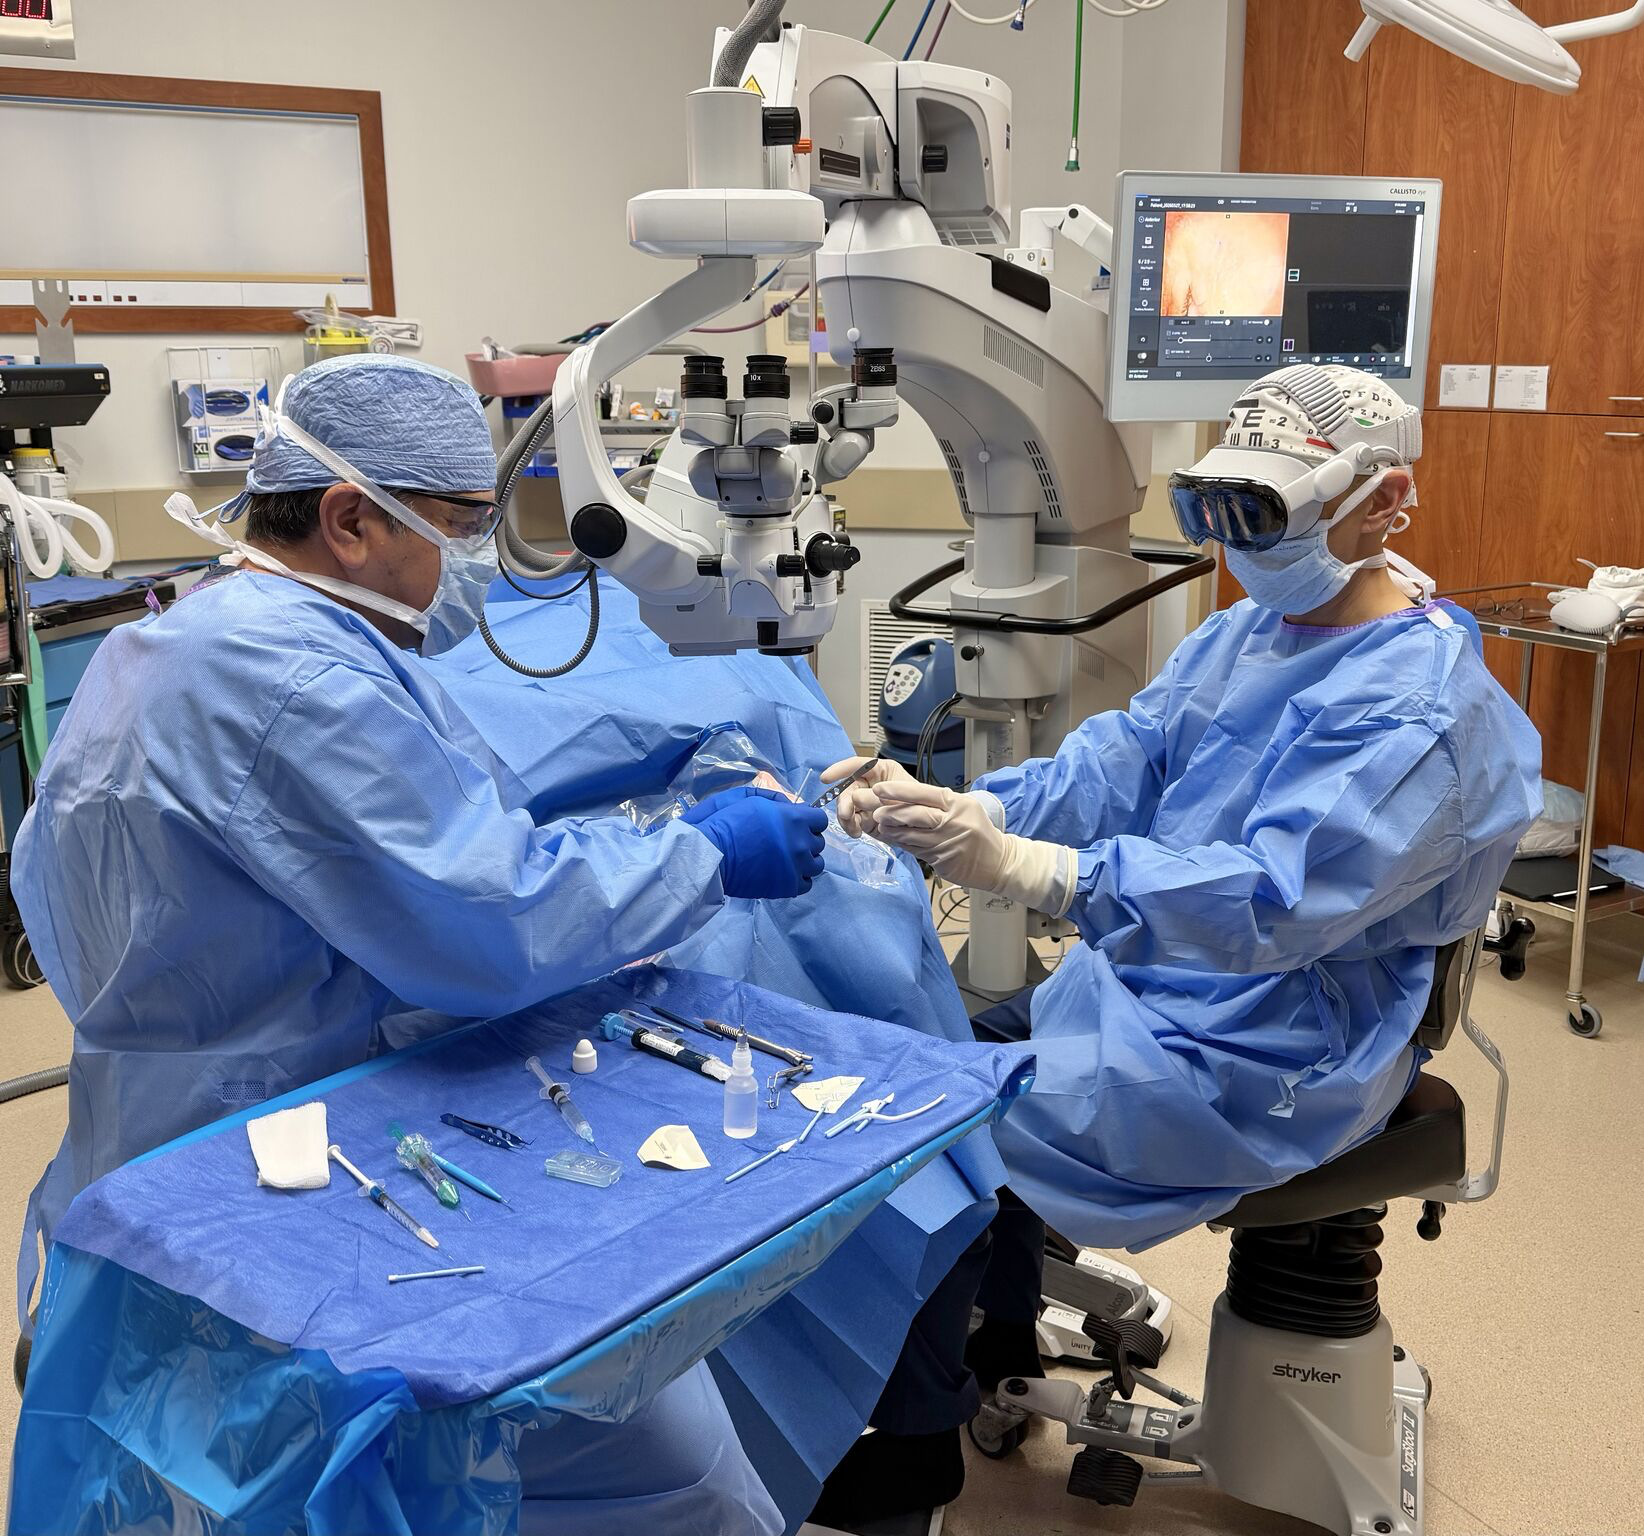
    In San Diego, Dr. Tommy Korn has been performing surgery with the Apple Vision Pro.

    We’re studying how spatial visualization may redefine microsurgery.
    • IRB-approved1
    • One of the first of its kind in microscopic eye surgery
    • Safety & feasibility study

    Technology used:
    • Apple Vision Pro - 2nd generation M5
    • ZEISS Medical Technology Artevo 850 3D Digital Microscope
    • ClearSphere spatial app from ClearSurgery

    Source: LinkedIn

    The idea of adding a layer of information or enhancing vision through a wearable computer being used to repair the vision of damaged eyes, I'd say that's pretty cool stuff.

    To oversimplify, the Apple Vision Pro is being used to substitute looking directly through microscope eyepieces, freeing the surgeon from neck and eye strain and allowing additional information to be shown without averting their gaze from the procedure. This improves outcomes and reduces fatigue allowing more procedures to be performed by the same surgeon or allowing more surgeries to be performed by more individuals with fewer obstacles to training.

    Spatial computing (SC) is also not a sprint. Joz said it's a product that has been brought from the future into the present and, as I use it, I feel that is indeed the case. And like AI, there are benefits being measured today. But what strikes me is the contrast in attention.

    Far more attention and capital is being applied to AI vs. SC but both are inevitable. The contrast might have something to do with psychology or attention markets but it shows that opportunities are not secrets. They are just unnoticed.

    1. An Institutional Review Board (IRB) in surgery is an independent ethics committee that reviews, approves, and monitors research involving human surgical patients to ensure their safety, rights, and welfare. It acts as a mandatory watchdog, evaluating surgical trials, new devices, and techniques to maintain high ethical standards.
  11. Computer History Museum interviews Bertrand Serlet

    Nota Bene

    Pay attention to the quiet ones

    Interviewed by Hansen Hsu on 2023-09-20 in Mountain View, CA

    Serlet joined Xerox PARC’s Computer Science Laboratory in 1984, working in the Cedar/Mesa programming language and development environment, still creating design tools for VLSI, developing the multiprocessor Dragon machine. In 1989, Serlet followed Hullot to Steve Jobs’ NeXT Computer. At NeXT, Serlet worked with Hullot on the AppKit team, releasing OpenStep, the update to the NeXTSTEP operating system. With Hullot and Lee Boynton, Serlet wrote a new version of the Workspace Manager, the equivalent to the Macintosh’s Finder desktop environment. After spending a year working remotely in France, Serlet moved back to California and became a manager at NeXT, leading the effort to create the Foundation framework, factoring out fundamental data structures from the user interface-focused AppKit framework for the next release of OpenStep. Serlet’s group would go on to work on Enterprise Objects Framework (EOF) and WebObjects until NeXT’s acquisition by Apple in 1997.

    At Apple, Serlet led the development of Rhapsody, which became Mac OS X. During the following years, Serlet would lead the development of OS X, ultimately becoming Executive Vice President of Software after Avie Tevanian, all the way through the beginnings of 10.7 Lion. Serlet also worked closely with Scott Forstall, who was instrumental in the development of the Carbon framework and the Aqua interface for OS X, and ultimately led the iPhone/iOS software development team, which was derived from OS X. Serlet would leave Apple in 2011 after recruiting Craig Federighi to replace him, and would go on to found startups involved with the cloud and silicon.

    Source: YouTube, CHM

    NB: This is one in a series on Apple's quieter heroes.…

    …I think Bertrand Serlet is one of the key builders of the operating system at the heart of the 2.5 billion devices that make Apple what it is. I have a few of these quiet hero interviews which I will link to.

    The interviews may be long but I found them fascination. It helps perhaps that I overlapped with the careers of these individuals and can relate to the technologies and challenges they faced.

    That this interview only has 6000 views after three years shows how much untold history exists.