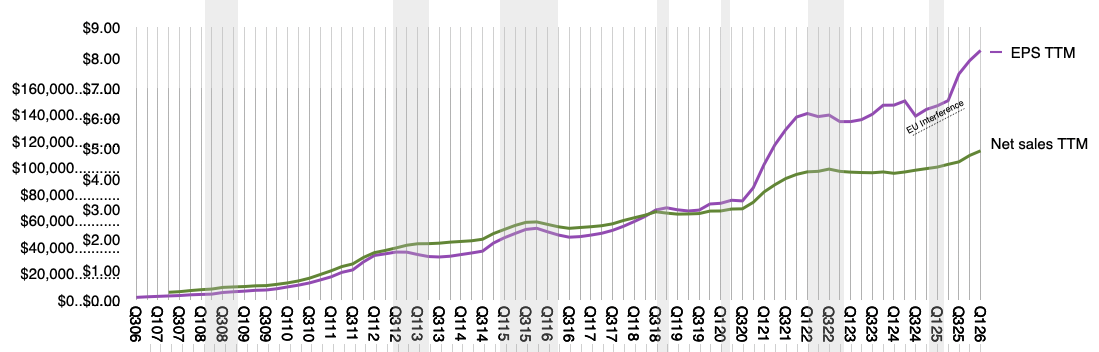
Expectations are low due to memory pricing, apparently.
Apple has multiple catalysts for strong revenue growth, so investors shouldn’t be spooked by any margin pressure from rising memory…
“Memory inflation will pressure margins, but this is well-known, and iPhone revenue upside sets up for a better than feared June quarter guide,” Woodring wrote.
He added that any announcements regarding an AI powered Siri at the company’s Worldwide Developers Conference in June, and the expected release of a foldable iPhone, would be positive tailwinds that can help push the stock higher after earnings.
Woodring, who rates the stock as Overweight with a $315 price target, also thinks Apple stands out against large tech peers as the company continues to report strong free cash flow while competitors continue to spend massive amounts of capex on building out AI infrastructure.
We expect gross margin downside to be more than offset by revenue upside in the June quarter guide, making for a better than feared earnings and a clearing event into WWDC this June, and the iPhone launch in September.
While our gross margin forecast remains below Consensus given rising memory cost pressure, continued strength in iPhone, Mac, and Services revenue should more than offset this pressure and result in a June quarter implied EPS guide in-line with Street estimates (~$1.74) – a better-than-feared outcome against relatively low expectations.
At 28x next year GAAP EPS – roughly the midpoint of Apple's historical 24-34x valuation range – valuation is neither cheap nor taxing, but with our ~$10 of FY27 EPS 5% above Consensus, we see a path to $300 for Apple shares by this September, driven by modest multiple expansion and more robust positive EPS revisions.
Apple is set to report fiscal second-quarter results on April 30, and investment firm UBS is expecting a “slight” upside to the consensus, based on Mac and iPhone-related strength.
“Supply chain checks and analysis of sell-through data suggest modest upside to our iPhone estimates while demand for the Neo and Mac mini suggests demand at least in-line with our Mac rev forecast,” UBS analyst David Vogt wrote in a note to clients. Vogt reiterated his Neutral rating on Apple but raised his price target to $287 from $280.
Turning to guidance, Vogt said he is expecting a “solid” offering for the June quarter and upped his earnings estimates as a result.
“Rising memory prices and Apple's ability to secure adequate supply is driving smartphone share gains for the iPhone product line at the expense of the broader Android ecosystem in our view,” Vogt explained. “In addition, solid demand for the Mac portfolio in part driven by initial success of the lower priced 'Neo' as well as demand for the 'mini' increasingly used to run AI agents like OpenClaw should drive incremental upside relative to our expectations.”
A consensus of analysts expects Apple to earn $1.94 per share on $109.73B in revenue for the fiscal second quarter.
NB: Missing the forest for the trees. Tune in to the post earnings discussion on Office Hours.
"At least in-line" is as weak as one can be in enthusiasm. “Supply chain strength and sustained demand/share gains for the iPhone 17 series should lift iPhone rev up ~20% YoY,” is more robust.
The neutral rating suggests that he does not see any strategic leverage gain as weak phone hands are shaken out.
TD Cowen analyst Krish Sankar reiterated a Buy rating and a $325 price target on AAPL stock. He expects Apple to report over 15% year-over-year revenue growth for the March quarter and to guide June-quarter revenue up about 10% year-over-year, driven by healthy iPhone 17 demand and the new MacBook Neo.
Key watch items: Apple’s ability to manage memory cost inflation and the launch of a compelling AI‑powered Siri. Sankar believes Apple will continue gaining share in both smartphones and PCs, with sentiment already positive heading into earnings.
Apple is set to report earnings on April 30. Currently, analysts expect AAPL to post revenue of $109.45 billion in fiscal Q2, up from $95.36 billion in the year-ago quarter. Further, the company is expected to report earnings of $1.95 per share, compared with earnings of $1.65 in the prior-year quarter.
NB: Consensus building that memory crunch will be neutral to positive.
Forward looking growth guidance is the key question now. 10% is a good guess. I am not putting forward a number but double digits seems plausible given the apparent success of both the iPhone and Mac in this product cycle.
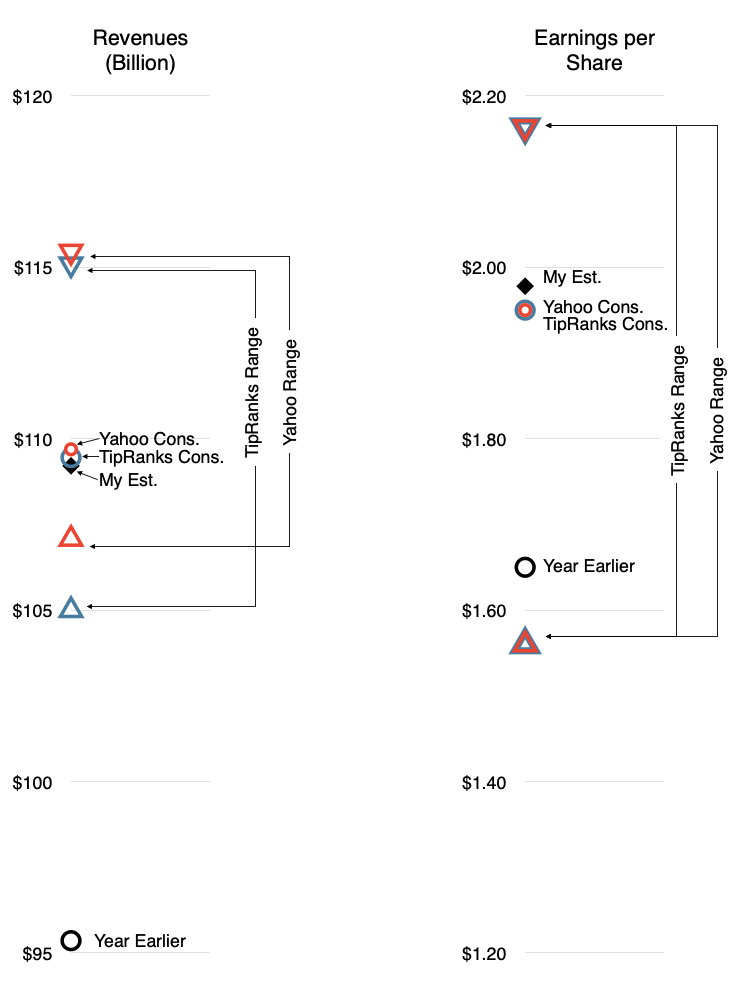
Revenue and EPS consensus, year-ago results and my expectations
Yahoo Finance
Yahoo Finance's revenue estimate for Apple in Q2 stems from 31 analysts. As of April 25, the average estimate is $109.69 billion, with a low of $107.08 billion and a high of $115.37 billion.
For the earnings per share estimate, 32 analysts put it at an average of $1.95. The low is $1.56 and the high is $2.16.
TipRanks
TipRanks also does its own analyst polling on Apple's quarter. In its forecast as of April 19, its consensus is for a revenue of $109.45 billion, with a high of $115 billion and a low of $105 billion.
On the earnings per share, the consensus is $1.95, with a high of $2.16 and a low of $1.56.
A summary of the expectations include year earlier results and my own estimates is shown the following graph:
"Apple’s new boss needs to restore its magic for the AI era"
If Mr Ternus does “nothing but keep the ship on course”, Apple could almost double its number of devices from 2.5bn globally to 4.5bn over the next 15 years, reckons Horace Dediu, a veteran Apple analyst. That would be a huge platform on which to run—and monetise—AI apps. As users subscribe to ChatGPT or other AI apps, “Apple will just take a cut,” Mr Dediu adds. By one estimate, Apple is close to generating $1bn in ai revenues so far this year via the App Store, despite having no flagship ai product.
Azeem Azhar, author of Exponential View, another newsletter, adds that to overcome bottlenecks in cloud-based AI, routine queries may be shifted to “edge” devices, creating a big opportunity for Apple. In Mr Azhar’s telling, the future will involve “a combination of the highly portable phone with the persistent desktop or server. Both play to Apple’s strengths.”
There is, however, a more radical path available to Mr Ternus, which is to develop a new “form factor” beyond the iPhone that is more suitable for the interactive nature of ai than doomscrolling on a touchscreen. Competitors are already trying to turn the smartphone into yesterday’s technology. Meta, the social-media giant run by Mark Zuckerberg, is selling millions of AI-powered smartglasses. Sir Jony Ive, the design guru who helped Jobs create the iPhone, has teamed up with OpenAI to develop a brand new gadget of unknown form. To keep up, Mr Ternus may have to reinvigorate Apple’s product line-up with a determination that eluded Mr Cook.
Apple’s Vision Pro virtual-reality headset, though an over-priced flop, may help the new boss develop Apple smartglasses. The company is also reportedly working on a wearable AI pin. Mr Dediu says that one of Mr Ternus’s main strengths may be his devoted following among Apple’s engineers, who have been pivotal to the firm’s success. “Ternus will come out as an engineer’s engineer,” he says. “He is hard-core. That might energise the teams.”
NB: As is often the case, a 45 minute discussion turns into two sentences. The article sadly does not provide hints at the future direction of the company. But we can…
…What we can foresee with certainty is what I said: the momentum is there for a doubling of the business without any new initiatives. The cultural fit for Ternus is 100%. That is based on the data we have but it is not the limit of what can be done. It is up to Apple to create the future.
This is not about AI or any new form factors but about harnessing the new technologies with Apple's existing operational capabilities and existing market access in a way that competitors cannot replicate. Thus unforeseen growth can be created and, by definition, it's not possible to tell what that may be.
But I can foresee that the organization is robust and well managed enough to create this unforeseen growth.
A part of Horace's interview with Asahi Shimbun on the 50th Anniversary of Apple's founding. The portion here discusses management succession and occurred on April 1. Apple announced the succession of Tim Cook as CEO to John Ternus last week. This analysis of Apple leadership decisions focuses on culture and attributes of the firm rather than attributes of the persons leading it. It may prove a more reliable predictor in future leadership changes.
…, the speculation is John Ternus is the next in line. I think that's a very plausible hypothesis. And one reason, by the way, is I always maintain if you study the company from a cultural point of view, you'll realize that there are people who cannot be CEO. You may not know who it's going to be, but I can tell you who won't be. Many people over the years suggested candidates, and I would say no, never. And here are examples. Johnny Ive would never be CEO. An external hire would never be CEO. Even a head of marketing would never be CEO. Many people think that Apple is a brilliant marketing company. No, it's an engineering company. It's a huge secret out there. →
Writing the story of John Ternus' tenure as Apple CEO from April 21, 2040. What changed and what didn't.
It’s been 15 years but John Ternus has finally stepped down as Apple CEO. Analysts described the transition as expected rather than disruptive, noting that investors had long anticipated Ternus’ eventual departure. Nevertheless, he leaves with many questions still unanswered about Apple’s long term strategy. Apple incoming CEO faces a defining challenge: Fixing the company’s Services dependence. It’s been a tumultuous tenure for Ternus but he is leaving with significant accomplishments: John grew Apple devices to 4.5 billion from 2.5 billion when he took over in 2026. Many have pointed out that he has been building on… →
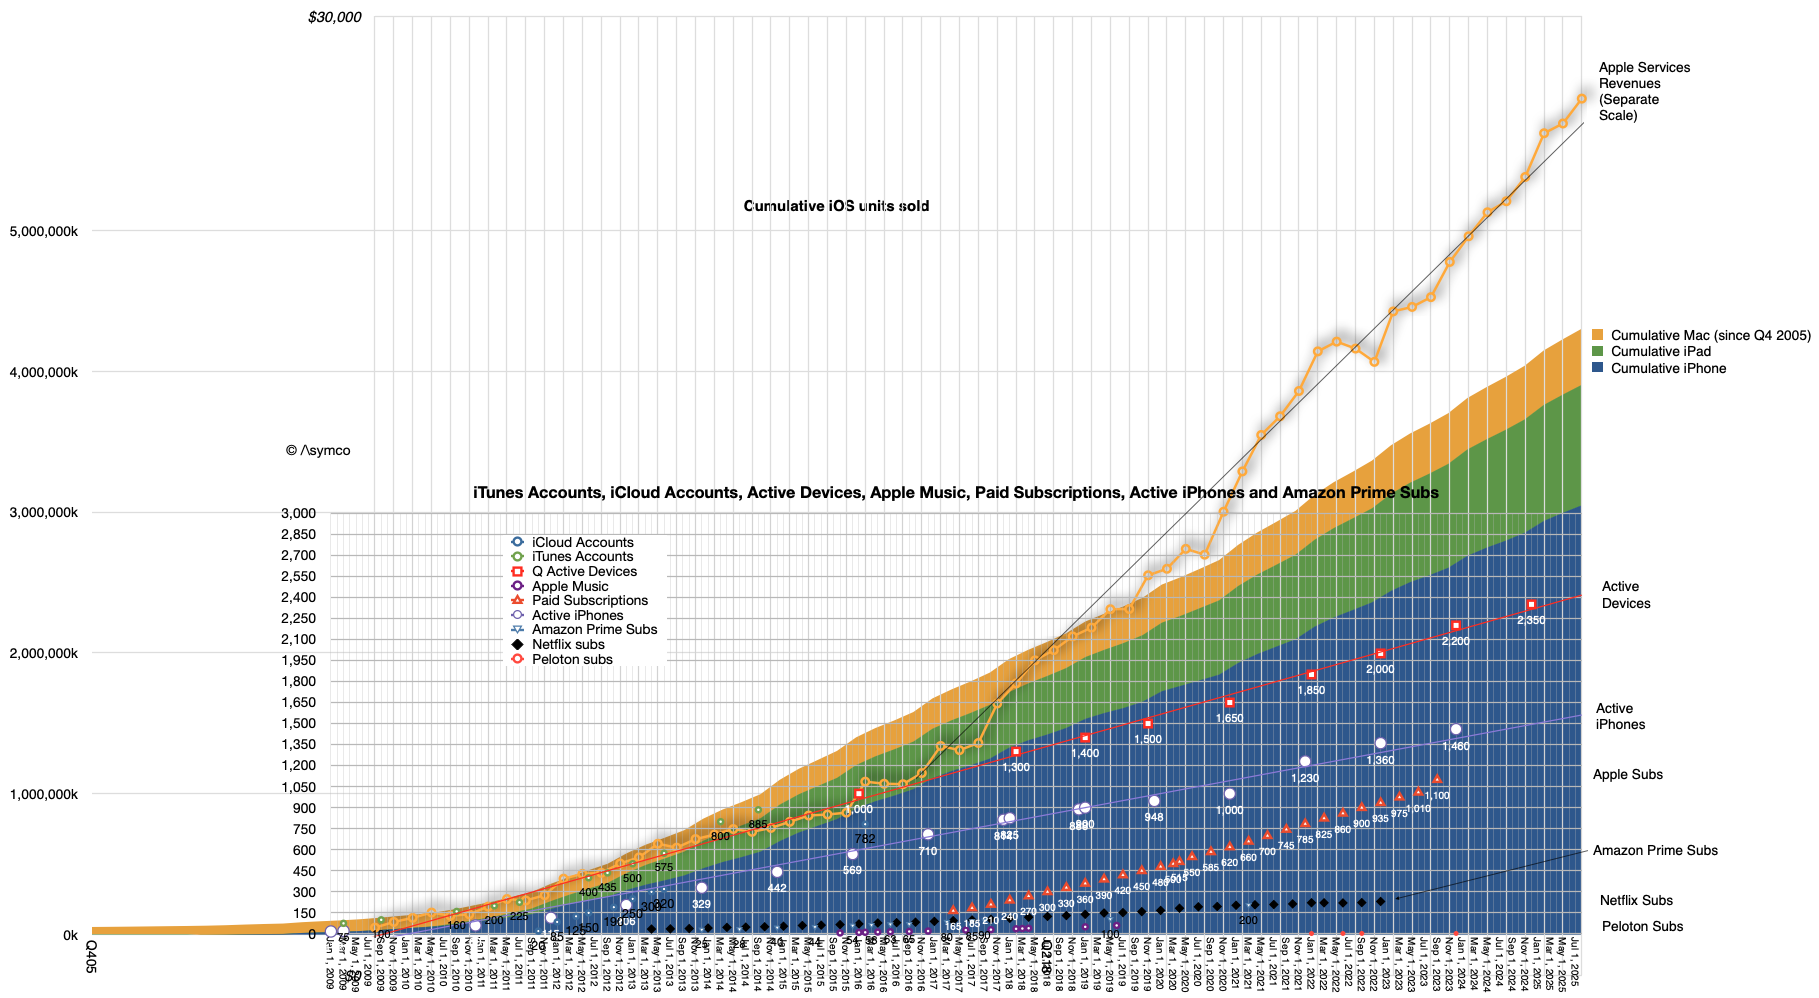
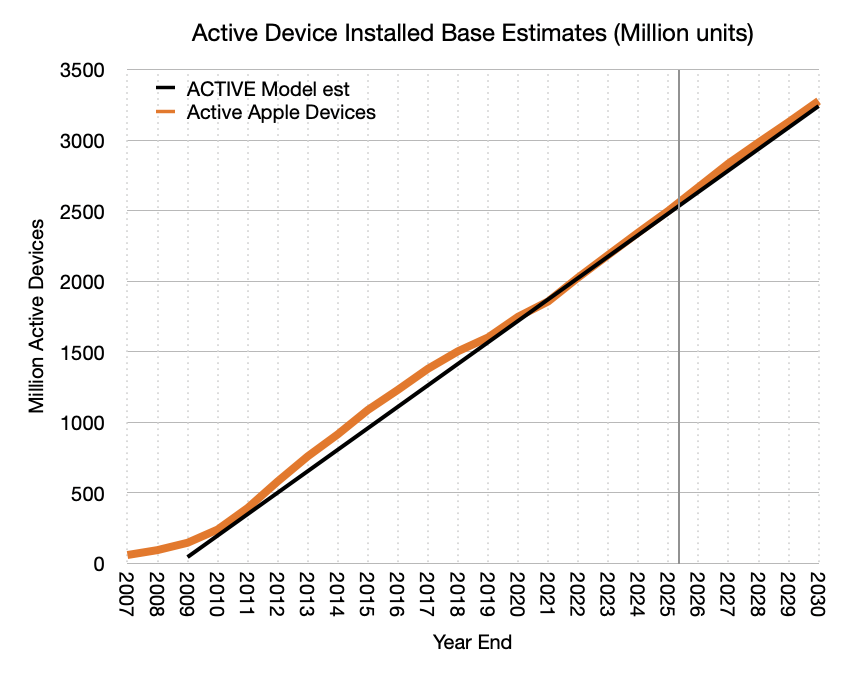
In January this year Apple reported that there were 2.5 billion active Apple devices in use. This figure has been getting updated for years and I’ve been reporting its trajectory and other measures that are correlated to it. For instance the number of Apple subscriptions, Apple Services revenues and other historical indicators such as iCloud accounts and Apple Music.
Simplifying, I published the “ACTIVE” model which makes some basic projections of this total device count and it’s shown below” One element of the analysis that has eluded me was the more precise composition of this total “devices”. →
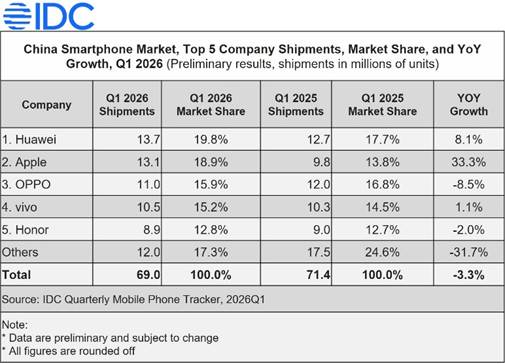
Both researchers say Apple share in China is about 19%, nearly tied with Huawei at 20%…
Some analysts are increasing their targets finally realizing that the memory supply crisis might be beneficial to Apple. This should have been noted already three months ago when Apple provided extraordinary guidance for the March quarter. →
MacBook Neo Sold Out Through April → Despite high demand and stockouts, Apple's strong brand and competitive pricing could turn challenges into opportunities for market expansion.
Microsoft’s cheapest laptop is three times more ex…
As I will argue in a further post perhaps this is one of those pivotal moments. →
Goldman forecasts fiscal second-quarter EPS of $2.00 → Goldman Sachs remains bullish on Apple, forecasting $2.00 EPS driven by strong iPhone and Services growth, dismissing overly pessimistic sentiment as the company consistently gains 100 million new customers annually.
My target of $1.98 seems amiss.…
What is always happening, the reaction that is always ongoing, is the creation of 100 million new customers every year. Accelerating this process is not a matter of just new products or change in sentiment with AI. Much of this rate is due to overall global economic and demographic change. →
What’s the consensus on $AAPL? → Apple's strong analyst backing with a 15:1 Buy:Sell ratio and $315 target contrasts its 39% year-to-date rise, overlooking potential future growth.
The consensus is positive though share price target does not consider significant share gains and service growth acceleration into 2027.
NB: The consensus is positive though share price target does not consider significant share gains and service growth acceleration into 2027. →
Apple 3.0: JP Morgan expects that Apple will beat its own guidance next week → Analyst Samik Chatterjee projects Apple's EPS to rise to $2.05 from $1.96, driven by strong iPhone and Mac demand, with a revenue boost to $112.7 billion, while I estimate a slightly lower 20.2% EPS growth, anticipating guidance will be met.
Read the original for a more detailed commentary from Chatterjee. He implies Apple will grow EPS 24%…
…My own estimate is about 20.2%. I look forward to a lively quarterly update. The primary source of growth must be the iPhone and I have that growing at 19% revenue growth. Last quarter the growth was 23%. Perhaps Chatterjee is assuming a similar growth rate into March quarter. That is not impossible but I am assuming guidance will be met rather than exceeded. →
AI makes the strong stronger. That is the opposite of disruption.
The iPhone appears stronger than ever despite Apple’s AI struggles, and that’s not a coincidence, says Perplexity CEO Aravind Srinivas.
Speaking on the latest episode of the This Week in AI podcast, Srinivas indicated that the iPhone only stands to benefit from continual AI improvement.
"Here’s my opinion. I haven’t said this before. The phone, the iPhone is actually not getting disrupted by AI at all. In fact, the more AI works better, the iPhone essentially becomes your digital passport."
Perplexity’s CEO touts Apple’s ecosystem and silicon advantages as some of the reasons why the iPhone is positioned for continued success. It’s also, in his view, why Apple can afford to move slow with its long-delayed Siri overhaul.
"My sense is that even though a lot of people have opinions on how bad Siri is or good Siri is, [Apple has] the ability to take time and do things they want to do, because they have advantages as a brand that people truly trust. The ecosystem lock-in is underrated. Auxiliary hardware devices, the chip advantage, all of this is really underrated right now. Srinivas also mentions how the iPhone is central to people’s lives for many reasons that have nothing to do with AI."
He says, “It has your wallet, it has all your cards, it has your passes, it has your health records, you connect with other human beings through it, you do FaceTimes, you do calls, you have photos of precious moments in your life.” All of these are extremely personal, and as a result, users won’t easily switch away from iPhone.
NB: Knowing the theory of disruption provides a three year lead in decision making. The observation...
...is that the iPhone is "entrenched" or protected by a moat or ecosystem or some other euphemism of "lock-in". But these are not the reasons why iPhone is sustained by a new technology. It's simply that Apple is incentivized to embrace it. The company has all the resources necessary to participate and can observe that the new technology is beneficial to its customers.
Therefore it will fold the new ideas into its business model. Disruption means it find the new thing either less profitable, not relevant or addressing customers that it does not have or want.
None of these conditions apply to AI. AI leads to more profit for Apple, is very relevant and aimed squarely at its best customers.The question becomes not why would Apple not embrace AI but why wouldn't it.
"Our expectations for March-Q (F2Q) earnings include beats on revenue relative to the telegraphed outlook, helped by both better demand for iPhones... as well as better demand for Macs." — Analyst Samik Chatterjee
Chatterjee has raised his top and bottom line estimates significantly in the last 3 months. Revenue: To $112.7 billion from $109.6 billion (up 2.8%) .
NB: Read the original for a more detailed commentary from Chatterjee. He implies Apple will grow EPS 24%…
…My own estimate is about 20.2%. I look forward to a lively quarterly update. The primary source of growth must be the iPhone and I have that growing at 19% revenue growth. Last quarter the growth was 23%. Perhaps Chatterjee is assuming a similar growth rate into March quarter. That is not impossible but I am assuming guidance will be met rather than exceeded.
In January this year Apple reported that there were 2.5 billion active Apple devices in use. This figure has been getting updated for years and I've been reporting its trajectory and other measures that are correlated to it. For instance the number of Apple subscriptions, Apple Services revenues and other historical indicators such as iCloud accounts and Apple Music.
Simplifying, I published the "ACTIVE" model which makes some basic projections of this total device count and it's shown below"
One element of the analysis that has eluded me was the more precise composition of this total "devices". In other words, which devices and what is their mix. We have seen numbers for iPhones but not for other types of devices. I should note that this is not easily derived because we have neither the units sold (only revenues) and we don't know how long they stay in use. The measure of active population implies that the products are bought, used and eventually retired.
The only clue we have, beside quarterly revenues--and even there wearables and home are not separated by product--is that management occasionally mentions that "more than half" of buyers of a specific product are "new to the product". It's not much to go on.
But there are other data sets we can tap. StatCounter provides a share of platforms in use by aggregating browser identifying data for a moderately large set of web sites. That may help with share of base but not with how much the total base is. Various other analysts do try to summarize some of the installed base for particular dates.
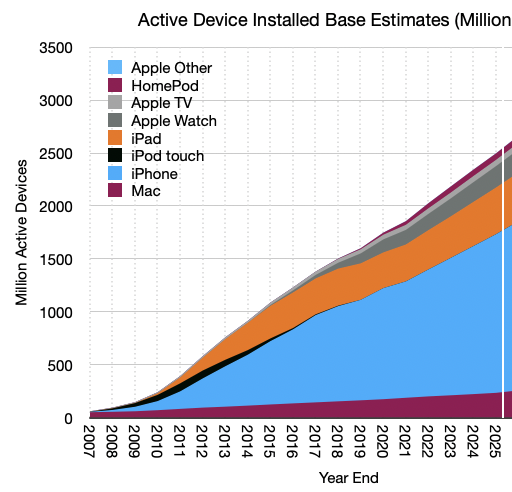
Combining all the available data and some interpolation, I set out to do is to provide a yearly count of the population of Apple devices for each year since 2007. Then to try to forecast this population to 2030. The result is shown below:
The following is a summary for the components for the end of 2025 in millions:
Year-end
Mac
iPhone
iPad
Watch
Apple TV
HomePod
Other
2025
233
1500
442
203
58.5
61.75
0.5
This history looks like this:
What about the future? Let's dig in.
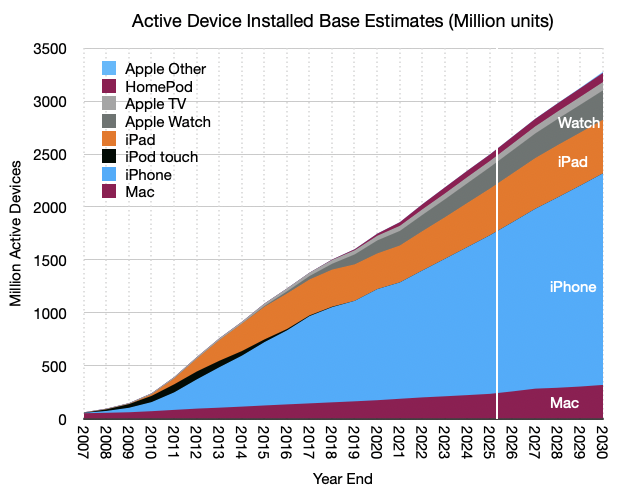
The forecast is shown in the graph and table below. The model predicts about 3.2 billion active devices by 2030.
Year
Mac
iPhone
iPod touch
iPad
Apple Watch
Apple TV
Home Pod
Apple Other
2007
50
4
5
2008
54
17
15
7
2009
59
42
35
9
2010
69
86
59
15
10
2011
82
166
76
55
13
2012
93
276
75
121
15
2013
102
382
61
195
17
2014
112
482
43
259
18
2015
123
599
26
308
8
22.49
2016
133
700
13
336
20
27.135
2017
143
825
7
339
33
31.36
2018
153
900
5
350
56
35.67
4.2
2019
162
950
345
95
38.85
10.1
2020
173
1050
338
123
43.865
19.9
2021
186
1100
349
138
47.84
34.7
2022
200
1200
372
154
52.305
48.3
2023
210
1300
393
170
54.91
57.8
2024
221
1400
418
187
57.75
60.6
0.2
2025
233
1500
442
203
58.5
61.75
0.5
2026
257
1600
462
218
62.5
66.75
0.7
2027
282
1700
480
233
66.5
71.75
1
2028
291
1800
495
248
70.5
76.75
2
2029
302
1900
502
263
74.5
81.75
4
2030
317
2000
507
278
78.5
86.75
10
By 2030 the iPhone will be about 60%, Mac 10%, iPad 15%, Wearables 10% and Home products about 5%. The difference from 2025 will not be great. The iPhone today is about 60%, Mac is 9%, iPad 18%, Wearables 9% and Home 4%.
The revenue impact in the growth of this ecosystem can be computed. Although we have a figure in terms average revenue per device, looking at individual products allows a more precise view. For instance, revenue per Mac per year vs. revenue per Watch per year can be now separated.
That will all be forthcoming.
This is a future five years away. Is this growth rate and consistency in mix a reasonable assumption?
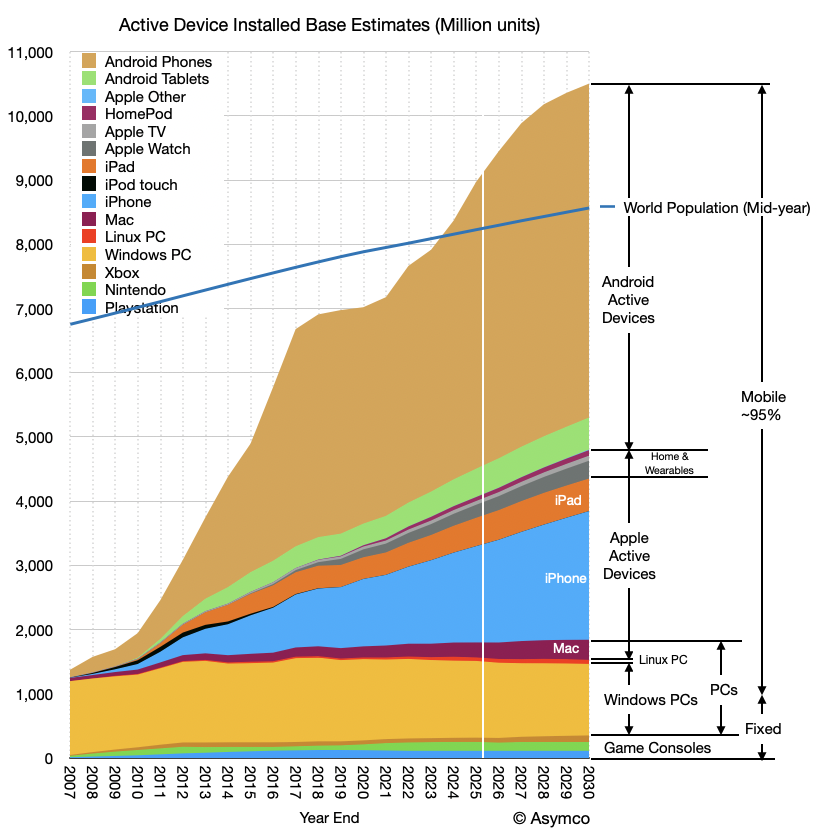
To answer, we should zoom out and look at not just Apple's device base. The following graph shows also Android phones and tablets, Windows, Linux (PC) and Game Consoles.1 It contrasts mobile and "non-mobile" computing and shows the total global population (blue line).
I have several observations:
The total device population now exceeds the total human population. The total number of phone lines was already higher for some time2 but what are shown here are "computers" insofar as they have CPUs and operating systems that can run third-party apps.
Given the device count exceeds human count, how much higher can this total go? The forecast shows a slowing of growth within the next five years but this is not a certainty. The attach rate of devices/person could well exceed 1.2 to 1.3 and go to levels seen in wealthy countries (above 2.) If that is the case then the device total may exceed 16 billion at saturation. This has implications for how far current strategies and business models can run.
The composition of device types is fairly constant and form factor substitution is rare. New categories beyond phones and current wearables are hard to anticipate but even if they emerge, the evidence suggests they are additive. Evidently the phone did not so much displace the PC but build on top of it. The potential for wearables and home devices to explode is there but it's hard to image these stealing "share of pocket" any more than phones stole "share of desk or share of backpack". If they do explode, they will add to the total via higher attach rates. 3x human population (24 billion) is possible with new wearables and home3.
AI holds many promises but how AI is accessed is not necessarily requiring of or benefiting from new device types. The smartphone is still the best AI device imaginable4. Ambient or passive computing can be provided by existing wearables but, as the graph shows, these are augmentative to phones. If AI introduces a completely new form factor, the impact will take decades to diffuse. As the graph shows, the mobile era is now approaching 20 years with the next five years foreseeable with some confidence. The next 15 years will be discussed in a future post.
Android typically captures non-consumers who eventually churn into Apple devices. This means that as long as non-consumption exists, Android grows and as long as Android exists Apple grows. If and when Android growth stops then the dynamics will change and Apple might change strategy to accelerate churn.5
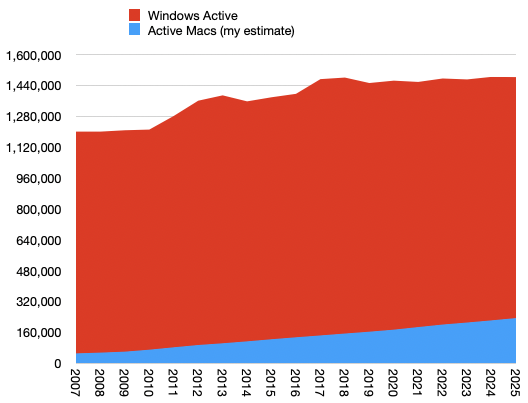
Google and Apple will be the primary distributors for all software and services into the foreseeable future. Try as they might, challengers face over 9 billion in installed base. Note well how entrenched Windows has been on the desktop even as (free) Linux and (better) macOS alternatives have harvested usage. This rigidity has held over the 1.5 billion addressable market for 30 years now. For additional evidence consider the dynamics, or lack thereof, of the game console business.
It excludes servers and early phone platforms such as Symbian, Blackberry and Linux phones.
According to ITU Facts and Figures 2024, there were 112 mobile-cellular subscriptions per 100 inhabitants globally in 2024
Households are 1/3 human population and vehicles are only about 1/7 so Home and Automotive don't move the needle much.
AI is, if anything, putting the "smart" back in "smartphone".
This might be what is happening with the Mac Neo, decades after the PC market saturated. Perhaps pieces have finally fallen into place but apart from Chromebooks, it's been very difficult to challenge the Windows PC head-on. (Though the iPad was possibly designed to displace some of the PC usage, it hit mainly with non-consuming very young or very old and PC use was unaffected.)
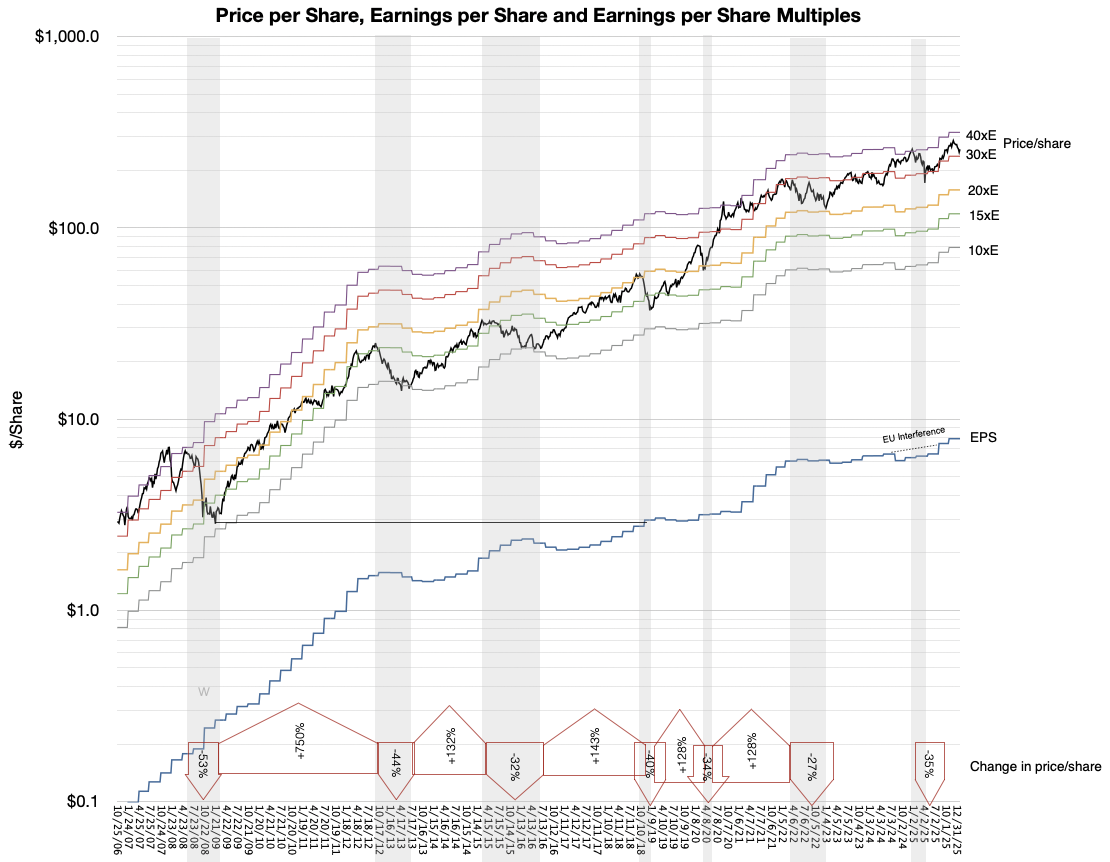
The analyst consensus price target sits at $297.46, with 31 Buy ratings against just 2 Sell ratings across 48 analysts. Both Citi and Morgan Stanley sit above consensus at $315, signaling above-average conviction. Apple stock is up 39% over the past year, so the transition arrives with the stock already reflecting significant strength.
Citi and Morgan Stanley both maintained Buy/Overweight ratings with $315 price targets on AAPL stock.
Goldman Sachs is pushing back on negative sentiment surrounding Apple ahead of its second-quarter earnings, arguing that the stock's recent underperformance reflects fears that do not match the company's underlying position.
But analyst Michael Ng said, "concerns for Apple are overly pessimistic given its much stronger relative position."
Goldman Sachs forecasts fiscal second-quarter EPS of $2.00, above the Street consensus of $1.93, with outperformance expected across iPhone revenue, Mac revenue and gross margins.
Favorable foreign exchange and strong Services revenue growth are also expected to flatter results.
On Services, Goldman Sachs projects 14% year-on-year growth despite another slow App Store quarter, with iCloud+, AppleCare+, prior price increases on Apple TV+ and solid advertising performance cited as supporting drivers.
Looking ahead, the bank sees advertising inventory expansion in the App Store and Maps as further tailwinds.
Recent data points cited by Goldman Sachs include high-end smartphone outperformance flagged by TSMC on its latest earnings call, iPhone share gains in China, and reports that Apple is actively securing mobile DRAM supply while keeping pricing competitive.
The bank sees further catalysts ahead, including WWDC, where new AI Siri features are expected, and the fall iPhone lineup, which Goldman Sachs described as likely "the most innovative ever with the introduction of the iPhone Fold."
There was little to argue in this. Management telegraphed more or less the same forecast and the note simply iterates more recent data points from supply chain. WWDC is the perennial "catalyst" though it never turns out that way. A catalyst is a compound or substance that accelerates a chemical reaction. The search for an accelerant is unnecessary as the reaction happens with or without it. Somehow we believe that without a catalyst nothing happens.
What is always happening, the reaction that is always ongoing, is the creation of 100 million new customers every year. Accelerating this process is not a matter of just new products or change in sentiment with AI. Much of this rate is due to overall global economic and demographic change.