Office Hours question asked by Frederich H. on May 1, 2026.
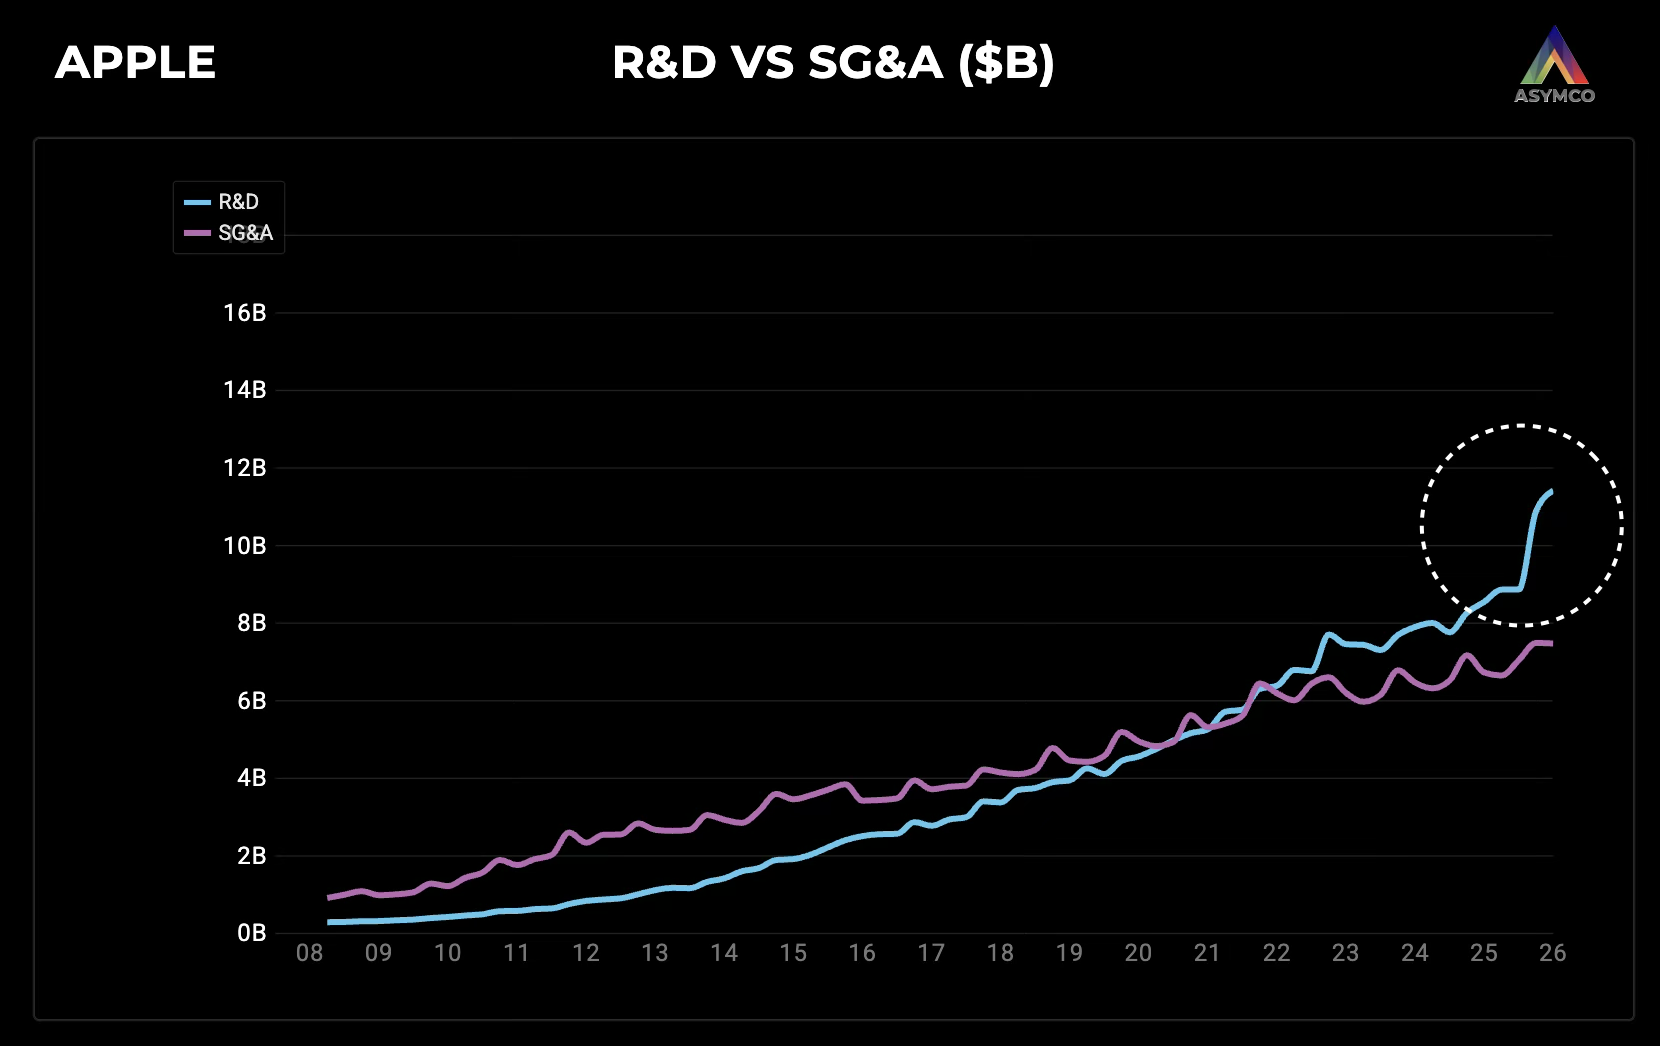
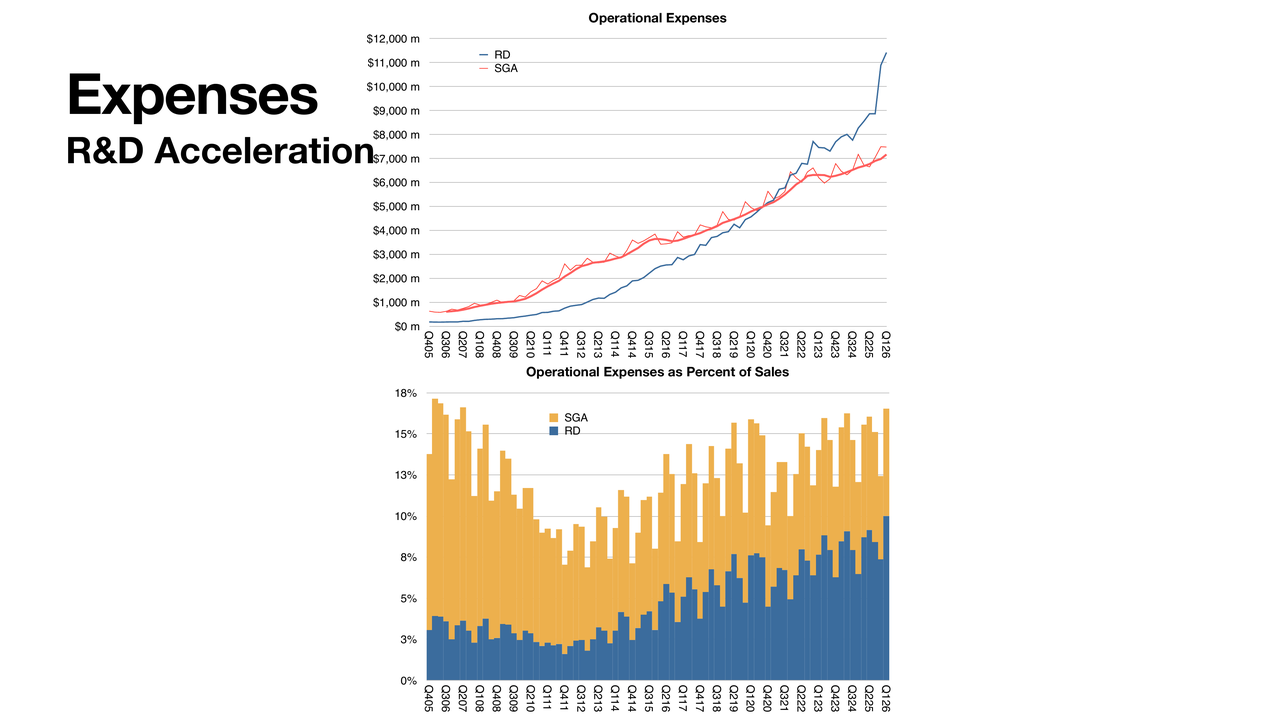
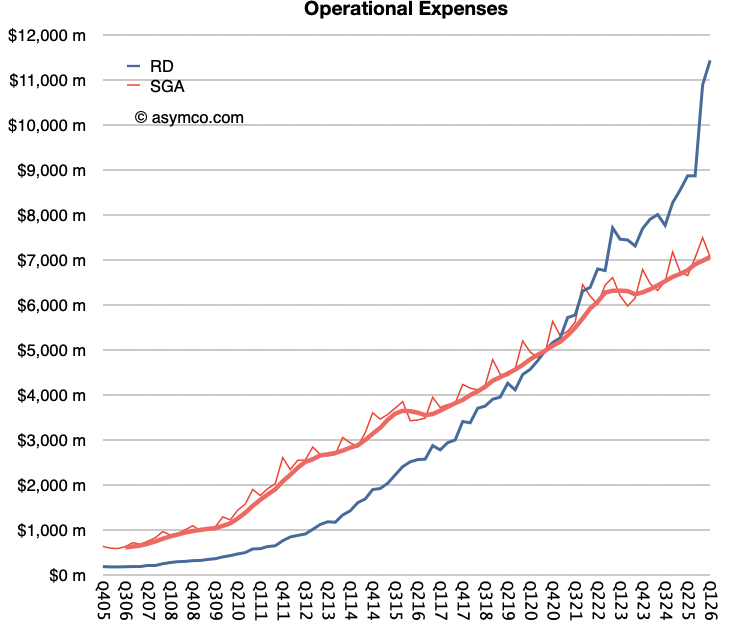
Q: Any thoughts on the breakdown of R&D, with that big jump?
It's hard to tell. I do think they're buying — that does include some hardware. A lot of hardware. I think they're building quite a bit of capacity in order to implement their versions of AI. They're not for deployment, but they're for testing and experimenting. They're hiring people as well, obviously that's included. But I do think it used to be they bought equipment for testing — I don't know, radio frequencies, and testing the iPhones, and semiconductors, and testing a lot of things like that. But I do think probably there's a lot more spending now on the stuff that feeds AI. It's not on the level that a hyperscaler's doing, because they're building it for scale, and Apple's maybe building it for testing.
We're talking about here, look, $11 billion in R&D, that's in one quarter. So that goes out to about $40 billion a year.
Mostly, I think this is people, but there is some equipment involved. It's just maybe different ways of capitalizing it, because capital equipment is a complex story.
It seems like a big jump, but it's only $2 billion more compared to the prior period. It's recurring though. And the reason that this stays steady and keeps growing is because people are on the payroll. And so if there's more and more people, that's paid every period — the reason, by the way, you see SG&A being seasonal is because there's temporary people in the stores. That involves people who are hired for the holidays in the Apple stores. So that's where you see some less than steady. But engineering people are more steady. But if there's a spike, there might be something going on where there was some equipment involved.
An Office Hours question asked by Fred S., May 1, 2026
Q: Ever since Johny Srouji started talking about Apple Silicon and the power consumption for the performance and the unified memory, and now we've seen the Mac mini surge, I just wonder about high-end computing. The whole area of where that Mac architecture may go beyond its success as an individual consumer computing product. From all the high-end workloads that might be coming their way.
The story of Apple is one of personal computing. It's not a story of servers, it's not a story of clouds, it's not a story of centralized computing. They've tried once or twice to make a server product, and they abandoned it. They've even abandoned the high-end Pro product, and created the almost-as-fast Studio product.
Now, that does not mean they're shying away from high-power computing. They're just saying, we're going to put that high-power computing in a desktop, or in the laptop, or even in the phone. Everyone who's grown up throughout the personal computer era can remember Moore's Law, and how exponential growth has driven computation to levels that seemed impossible just a few years earlier. We've hit some slowdowns, but fundamentally, the potential exists.
And by the way, it's not even a classic computational CPU problem. We're dealing with AI. We're mostly dealing with high bandwidth, large data, and we're dealing with simple calculations on it in parallel, which means the architecture is much more around large matrix computations. This is why Nvidia came from graphics. Graphics was the same problem — a graphics accelerator is a matrix problem. And so is machine learning. So different variations of these have come in as a sort of a parallel to the CPU, the general computation problem.
The idea Apple has is that they're going to catch up with whatever is done on the server, they're going to do it on the device. You can call it Edge, you can call it personal — the old term was personal computing.
I may be naive, but I think we'll get very powerful desktop computers that can do what is essentially AI, but for the individual. The other aspect here is that Apple is a consumer company, not a B2B company — it's a B2C. They want to bring that power to as many people as possible. And they're certainly delivering hundreds of millions of computers a year. Nvidia's making tens of millions of computers a year. Apple is capable of doing orders of magnitude more.
So I think they're going to affect the disruption in AI. It's not going to be that there's no profit in AI, it'll be that it'll be done with Edge more, especially as it doesn't have to be a world model — it can be a personal model. If you want to look up something globally, you can use the cloud, but if you want to deal with tasks in your world, you're going to work with Apple computers.
It may take years to get there. But in the meantime, I don't think a centralized service — these OpenAI, or Anthropic, or Microsoft, who are trying to make us a singular superintelligence — is necessary for everyone. It'll be a good reference, but it's not how you want to handle your personal information. So I think that's what the future is, and I think Apple's very much planning for it.
It sounds cliche, but when Apple started, it was IBM that dominated computing. And IBM was about centralized computing, and their thesis was everything we now call "the cloud" — but it was all in one big computer that served the entire organization, whether that organization is a government or a big company. And then we went to mini computers, then we went to desktop computers, then we went to portable computers.
Then, fast forward 25 years and we had Google. Well, now central computing is the internet. In the internet, everything needs to be indexed to be able to be found. So they created an index in the cloud. And then a lot of companies moved that computing they used to have locally into the cloud, as a shared resource from Amazon, AWS, and others, and that became cloud compute. Even now, those are the drivers for growth for Microsoft and Amazon and Google.
The AI part of that is tiny — there's revenue from AI, but there's a lot of revenue from cloud. That still is valuable. But that's not a job for consumers. You do some things in the cloud — you store things, you search, you communicate in messages and so on. But most of the data that matters to you will get also indexed locally, so you can pull up your photos, pull up these things, and it'll be a blend of the two.
So that's where Apple lives, and I don't see anything fundamentally changing about this, because computation tends to commoditize. Software tends to be replicated. Algorithms tend to be replicated. In fact, even the AIs we have today were all because people publish papers, and one company invents it, another implements it, as was the case with the transformer. As far as I understand, it was Google who actually wrote the paper on it.
An Office Hours question by J.P. answered on May 3, 2026.
Q: With the ascension of John Ternus becoming the new CEO -- will it lower the criticism from the perennial Apple haters and critics?
No, no, of course not. Of course not, come on. You should know better than this. If anything, it'll amplify.
I wrote a piece about this. Titled, "John Ternus will have left big shoes to fill." This is his epitaph. This would be when, in 2040, he'll retire, and this is the article that will get written then. And the criticisms he will have faced will be the same.
We mustn't forget that when Steve was around and was the CEO, the amount of abuse he got was worse, in my opinion, than what Tim got. The criticisms of his incompetence, of his lack of ethics, morals, and overall bad decision-making were legend. I think he was accused of criminal behavior, even.
So we tend to forgive and give peace to the deceased. But while they're alive they will be skewered. I think John will be as criticized as any [Apple] CEO. And you can use your imagination for the reasons and all the failures and all the bad, all the things he'll miss, all the things he'll do wrong, all the incompetence. That he doesn't know how to run anything. It's time for a change. Inevitable.
Asymco Bulletin is a digest of all the work we have published for the week ending May 3, 2026.
Editor's Note: Starting next week, we will be sending Asymco Bulletin to Asymco One subscribers only. You will still receive Updates when new posts are published per your notification settings.
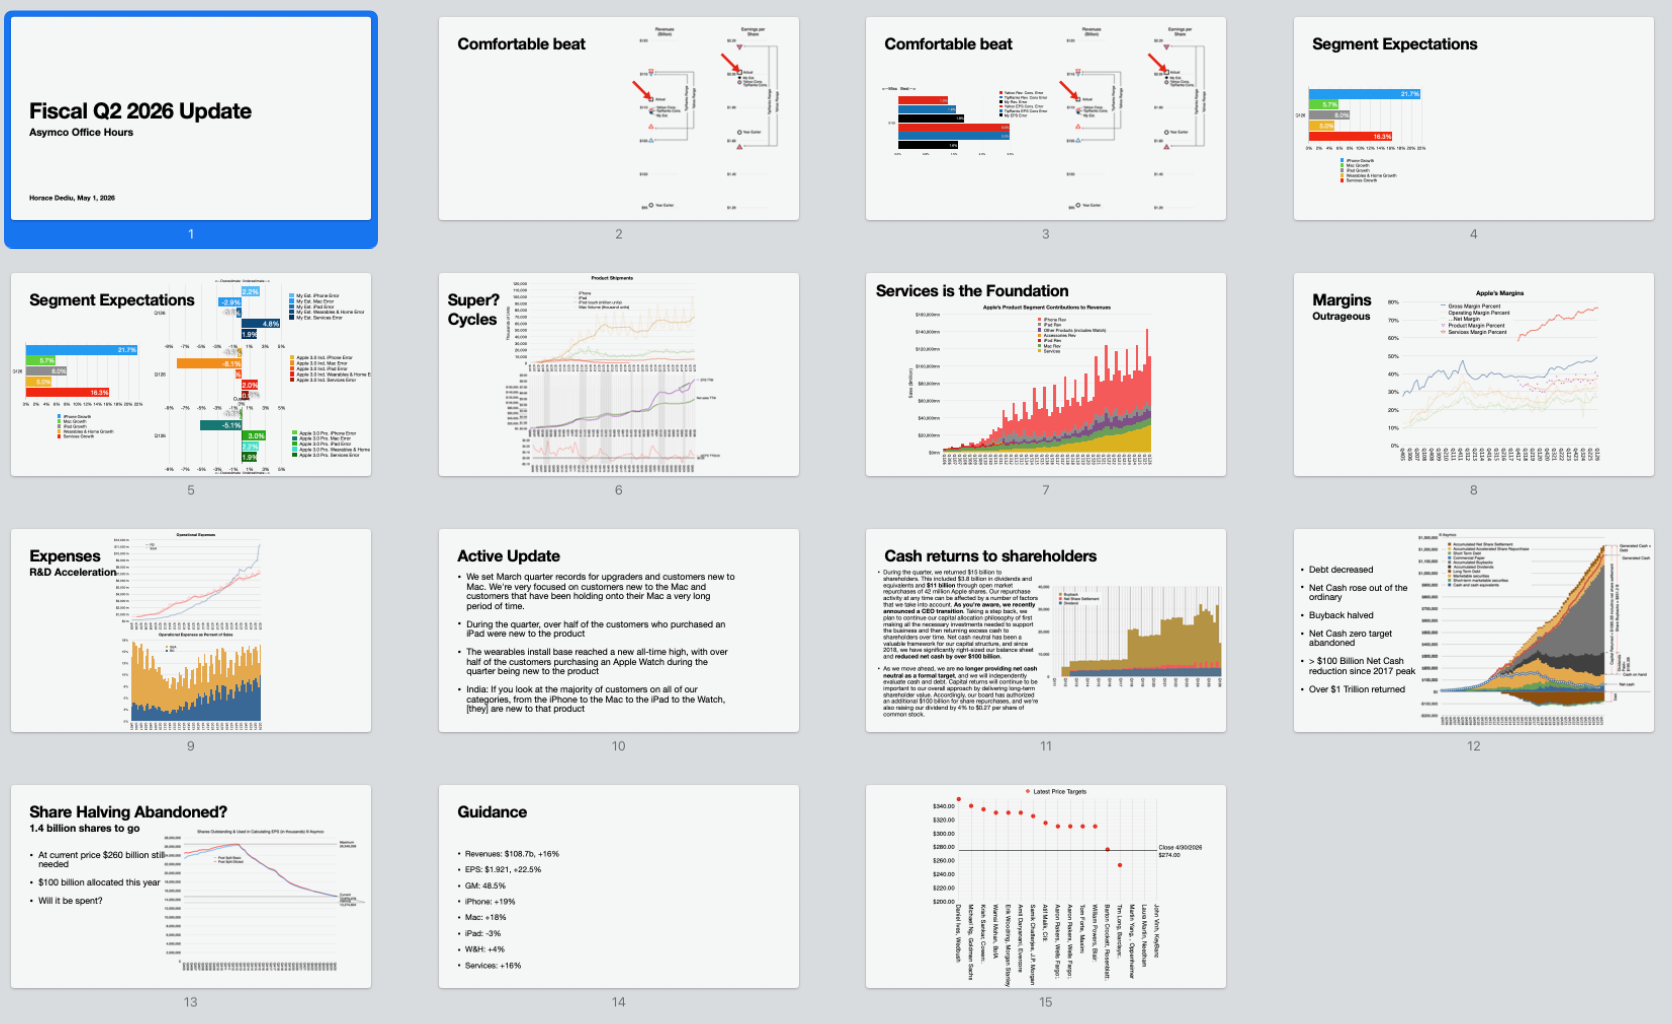
In Asymco One's May 1, 2026 Office Hours session, review of Apple's Q2 2026 earnings, segment growth: iPhone at 22%, Services at 16%, iPad at 8%, Mac at 5.7%, and wearables at 5%. Steady, foundational growth of Services, Gross margins reached nearly 50%, R&D spending surged, a shift in Apple's capital return strategy showing perhaps the hand of John Ternus. Guidance suggests 16% revenue growth, 22% EPS growth. Analyst sentiment turned positive post-earnings, with most price targets rising above $310. Apple's evolving identity as an engineering-centric company was the focus of many questions. →
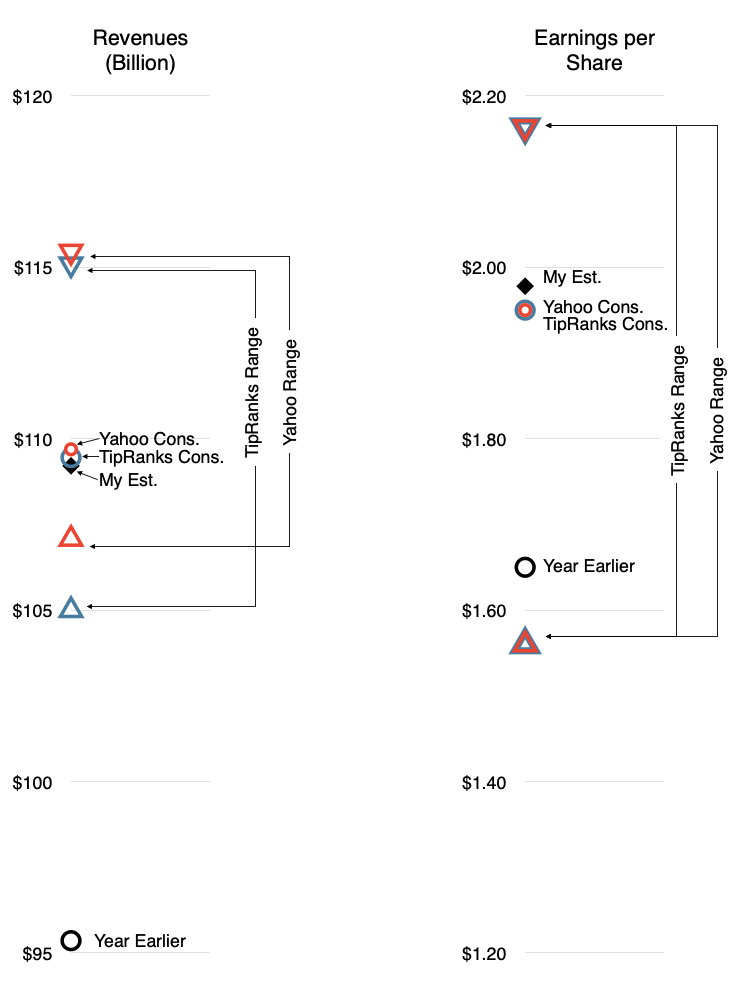
Revenue and EPS consensus, year-ago results and my expectations Yahoo Finance Yahoo Finance’s revenue estimate for Apple in Q2 stems from 31 analysts. As of April 25, the average estimate is $109.69 billion, with a low of $107.08 billion and a high of $115.37 billion. For the earnings per share estimate, 32 analysts put it at an average of $1.95. The low is $1.56 and the high is $2.16. TipRanks TipRanks also does its own analyst polling on Apple’s quarter. In its forecast as of April 19, its consensus is for a revenue of $109.45 billion, with a high of →
TD Cowen: 15% revenue growth, 10% growth guidance → Apple is projected to gain market share in both smartphones and PCs, driven by strong iPhone 17 demand and the new MacBook Neo, with anticipated revenue growth of over 15% in Q3 and positive sentiment ahead of earnings.
Morgan Stanley forecasts fiscal second-quarter EPS of $1.74→ Despite memory pricing pressures, Apple's strong iPhone sales, potential AI and foldable iPhone announcements, solid free cash flow, and favorable market conditions position it for better-than-expected earnings and a possible stock rise to $300 by September.
Is Apple borrowing Samsung’s Market Expansion Strategy?→ Bernstein SocGen maintains optimism on Apple's strategic pricing and ecosystem strength, forecasting EPS growth and potential market share gains, while Samsung faces smartphone profit challenges but thrives in memory.
Separately, it’s been reported that Samsung might see its first operation loss from its phone division, resulting in Apple capturing 100% (or more) of global smartphone profits. Simultaneously, Samsung is seeing huge profit gains from memory, even overtaking Nvidia’s profitability. This is remarkable…
Apple share of the smartphone SoC market grew from 15% to 19% in Q1 → In Q1 2026, global smartphone SoC shipments fell 8%, but Apple thrived in the premium market by leveraging its efficient supply chain and passing costs to consumers, boosting its market share from 15% to 19%.
Google to sell TPU chips as Gemini shows returns → Why pour cash into Nvidia when you can craft your own cutting-edge chips like Google, and then turn that innovation into a lucrative side hustle by selling them to tech giants like Meta and Anthropic?
The Vision Products Group Expanding → Gurman's 2025 dissolution claim clashes with 2026's active Vision Products Group hiring spree. The Vision Products Group posted 14 new senior roles last week.
Below are Horace's live commentary during the release of Apple FQ2 2026 Earnings, lightly edited. For an in-depth look, and a discussion of what turned out to be a record-breaking quarter, join uss at Asymco Office Hours: Apple Live Q&A.
Transcript: Friday 30 April 2026, 4:30pm-6pm EST | asymco@mastodon
Apple will release earnings at 4:30PM ET and conference call begins half hour later and lasts for one hour. I will try to make some comments as I process the news. This might be the 75th Apple conference call I listen to.
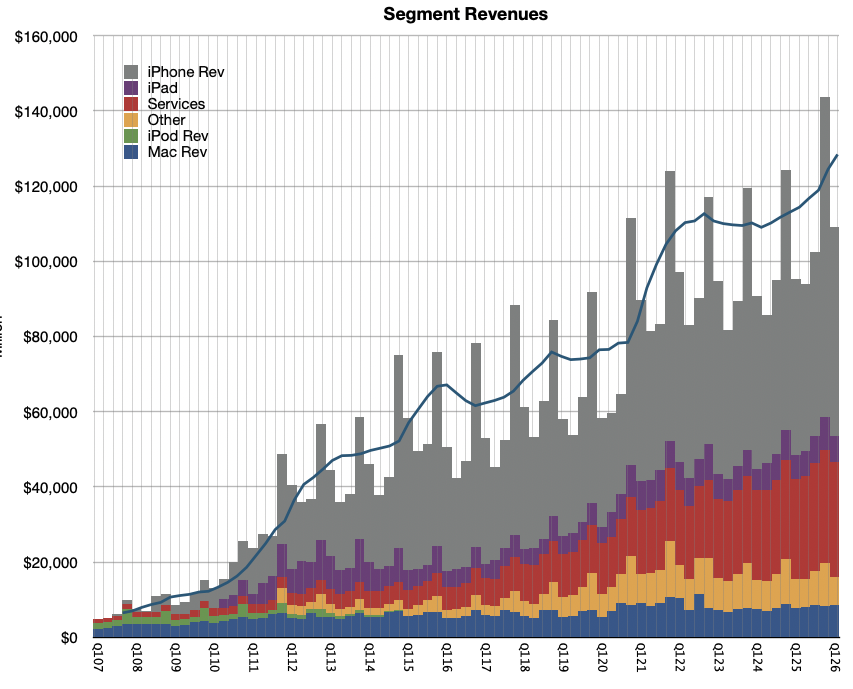
My estimates: EPS $1.98 Rev. $109.2b iPhone Rev 55.716684 Mac Rev 8.640 iPad Rev 6.9552 Wearables & Home Rev 7.522 Services Rev 30.3753
iPhone revenue came in at $56.99 billion. My estimate was $55.71b.
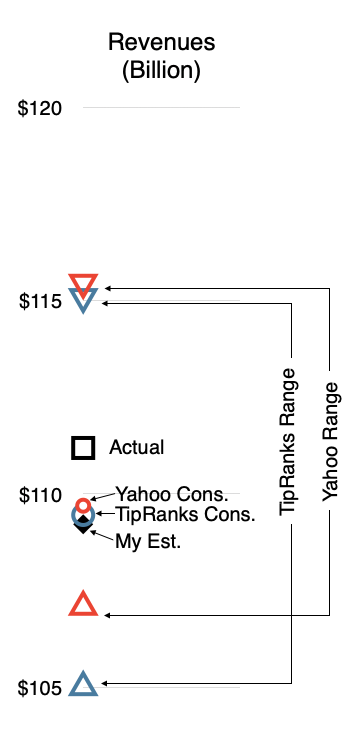
Here is a graph of the expectations vs. actual Revenue results.
iPhone revenues grew 22%. Extraordinary. The growth barely slowed from 23% the previous quarter.
Mac revenue growth was 6%. Slightly less than I expected.
Revenues were up 17%, earnings per share were up 22%. Best March quarter ever.
The board of directors has declared a cash dividend of $0.27 per share of the, an increase of 4 percent. Repurchase program authorized for up to $100 billion for the next 12 months. No surprises here.
Greater China growth was 28%.
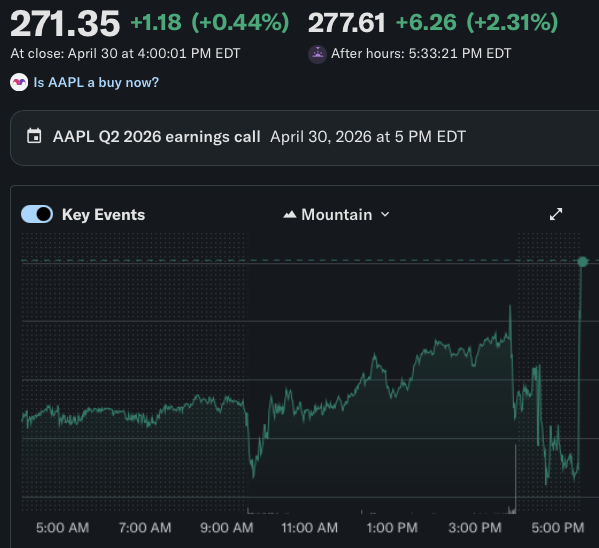
Apple shares are down 0.6% after-hours. Normal drop when company beats on the top and bottom. The big drop comes when the CFO talks guidance.
John Ternus will join the call for a few remarks.
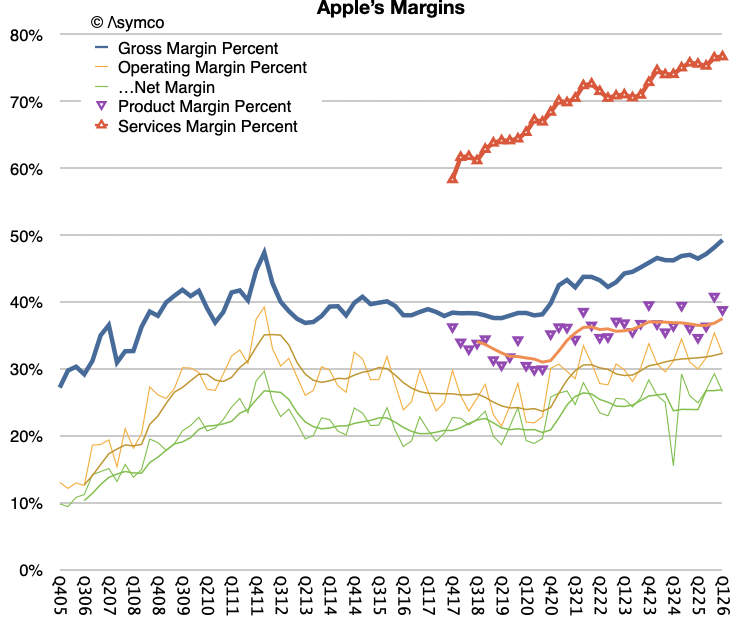
Gross margin came in at a record high of 49.3%. This is three months after the great memory panic of 2026 was declared.
Shares fall 0.81% after John Ternus remarks.
Apple reports double digit growth in every emerging market.
Mention of Mac Neo leads to more drops in the share price as the pain of share growth sinks in. Now down 1% after hours.
iPhones went to the moon, stock not mooning.
“Our strong business performance during the March quarter generated over $28 billion in operating cash flow and drove new March quarter records for both operating cash flow and EPS,” The fact that Apple did not turn over this cash flow t...
5% in Wearables and Home. Modest growth is shameful growth. Compounding shompounding.
Apple has 6 stores in India. So much more to do there.
Supply constraints mean that the growth could have been higher —CFO.
Active iPhone install base grew to all-time high. (No surprise). Customer satisfaction was 99% for iPhone 17 in the US.
Customer satisfaction for Mac was 97%. Half of customers buying an iPad are new to the product. Most of these new customers are in emerging markets. Customer sat for iPad at 98%.
Tap to pay (Apple Pay) now in 50 markets.
Net cash was $62 billion. No longer placing net cash neutral as a target!!!! OMG OMG.
June Q guidance: 14% to 17% growth. Shares recovered to +1.35%.
Margin guidance: 47.5% to 48.5%. Despite the great memory panic of 2026 being in full effect.
Shocked, shocked, shocked that CFO remarks did not crash the stock.
Tim says they did see higher memory costs. For the June quarter they expect significant higher memory costs and more beyond that. Still, margins are brilliant.
A part of Horace's interview with Asahi Shimbun on the 50th Anniversary of Apple's founding. The portion here discusses management succession and occurred on April 1. Apple announced the succession of Tim Cook as CEO to John Ternus last week. This analysis of Apple leadership decisions focuses on culture and attributes of the firm rather than attributes of the persons leading it. It may prove a more reliable predictor in future leadership changes.
…, the speculation is John Ternus is the next in line. I think that's a very plausible hypothesis. And one reason, by the way, is I always maintain if you study the company from a cultural point of view, you'll realize that there are people who cannot be CEO. You may not know who it's going to be, but I can tell you who won't be. Many people over the years suggested candidates, and I would say no, never. And here are examples. Johnny Ive would never be CEO. An external hire would never be CEO. Even a head of marketing would never be CEO. Many people think that Apple is a brilliant marketing company. No, it's an engineering company. It's a huge secret out there. →
Writing the story of John Ternus' tenure as Apple CEO from April 21, 2040. What changed and what didn't.
It’s been 15 years but John Ternus has finally stepped down as Apple CEO. Analysts described the transition as expected rather than disruptive, noting that investors had long anticipated Ternus’ eventual departure. Nevertheless, he leaves with many questions still unanswered about Apple’s long term strategy. Apple incoming CEO faces a defining challenge: Fixing the company’s Services dependence. It’s been a tumultuous tenure for Ternus but he is leaving with significant accomplishments: John grew Apple devices to 4.5 billion from 2.5 billion when he took over in 2026. Many have pointed out that he has been building on… →
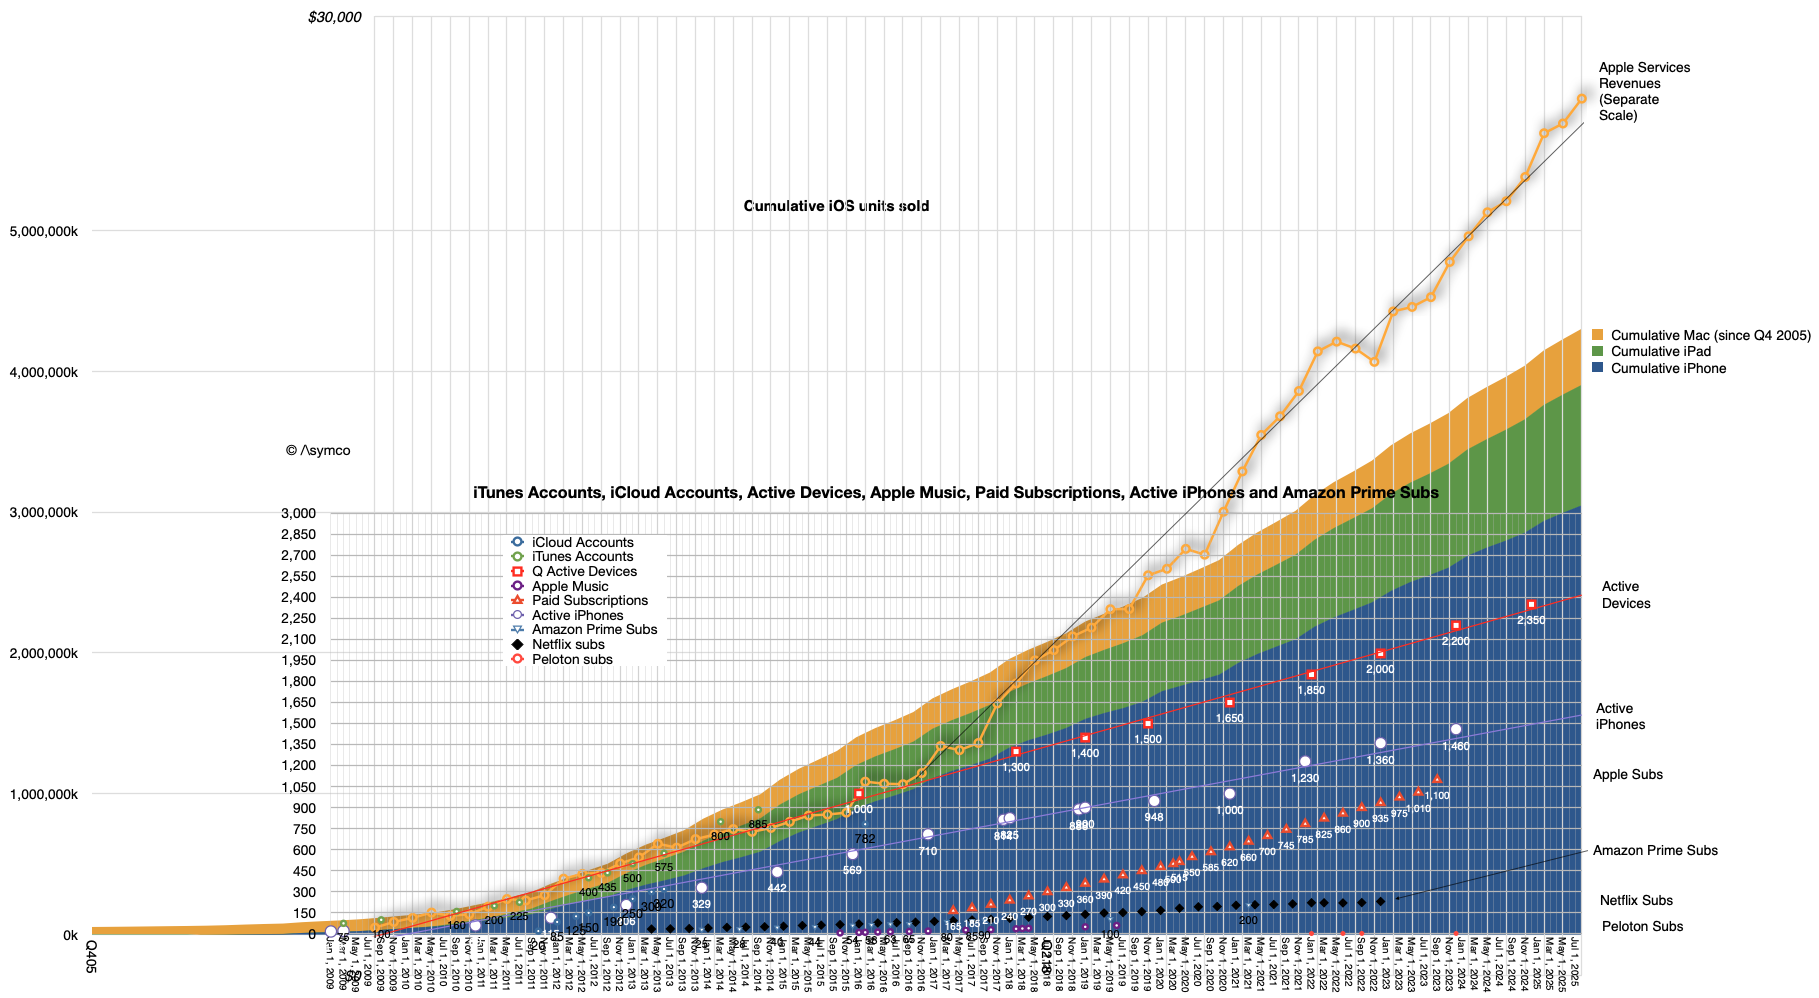
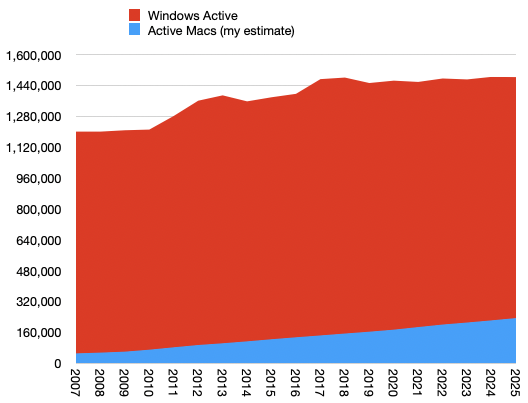
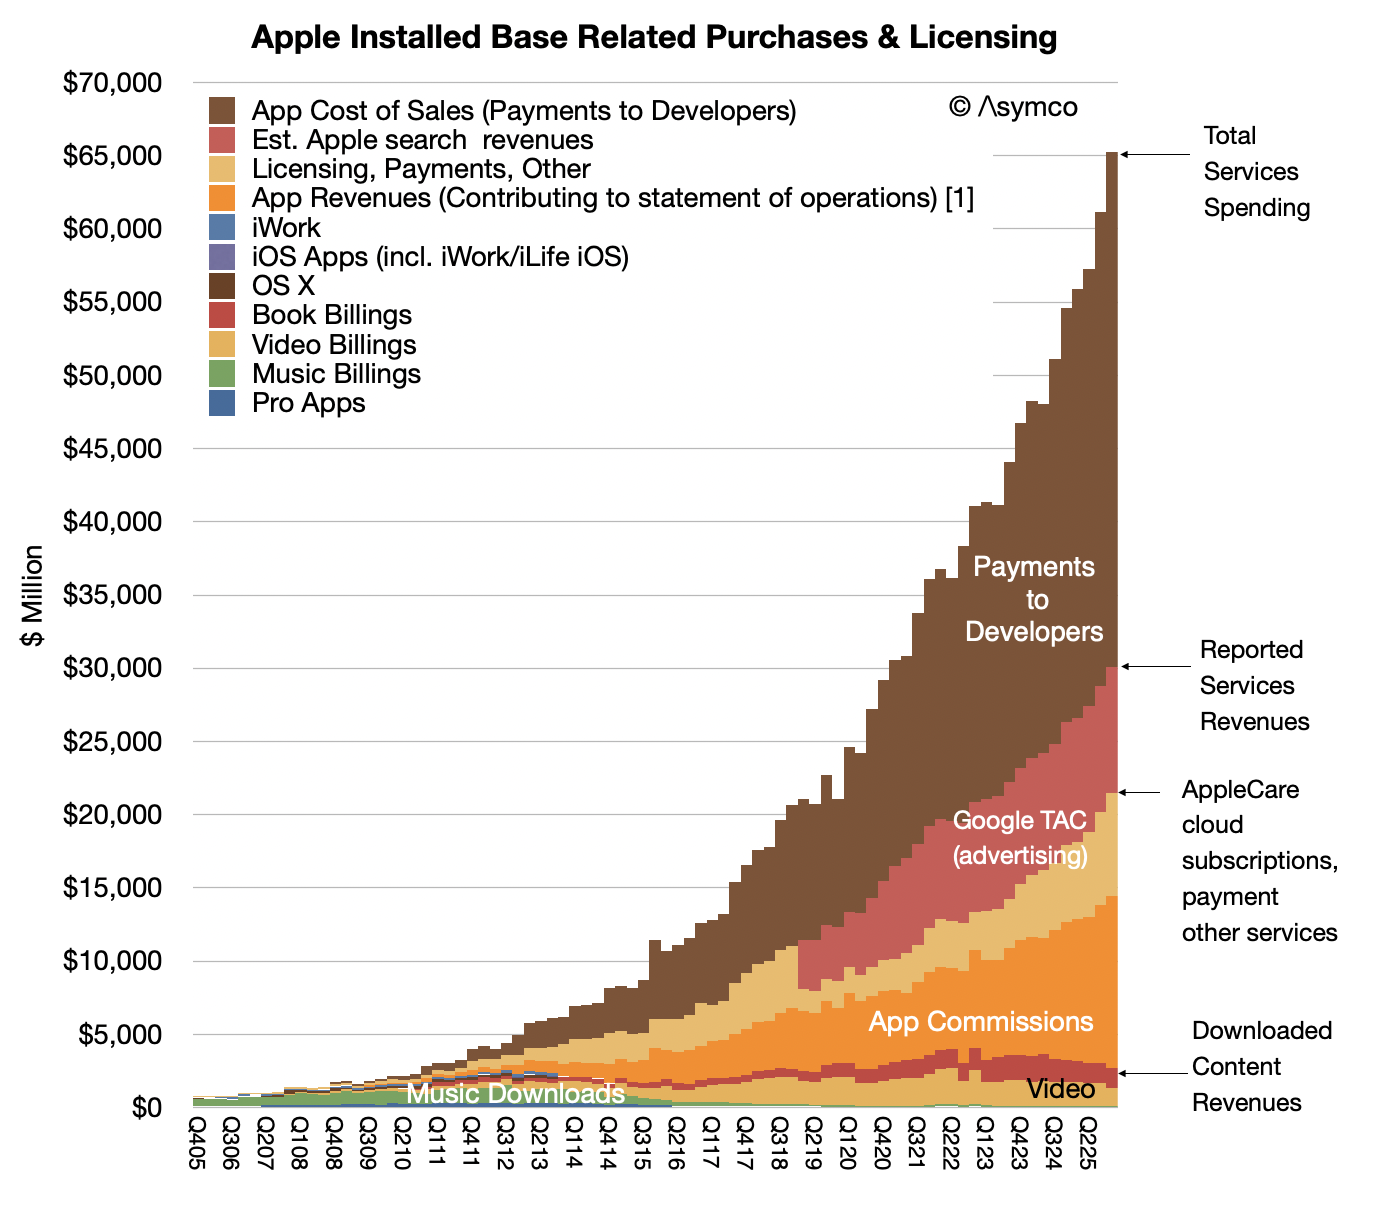
In January this year Apple reported that there were 2.5 billion active Apple devices in use. This figure has been getting updated for years and I’ve been reporting its trajectory and other measures that are correlated to it. For instance the number of Apple subscriptions, Apple Services revenues and other historical indicators such as iCloud accounts and Apple Music.
Simplifying, I published the “ACTIVE” model which makes some basic projections of this total device count and it’s shown below” One element of the analysis that has eluded me was the more precise composition of this total “devices”. →
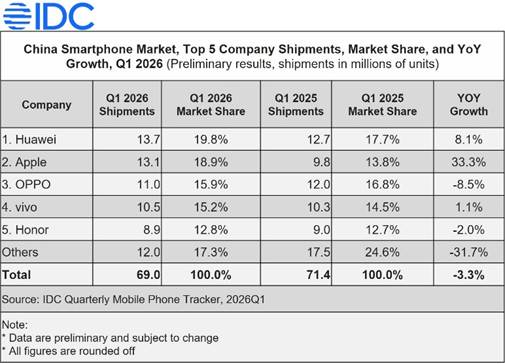
Both researchers say Apple share in China is about 19%, nearly tied with Huawei at 20%…
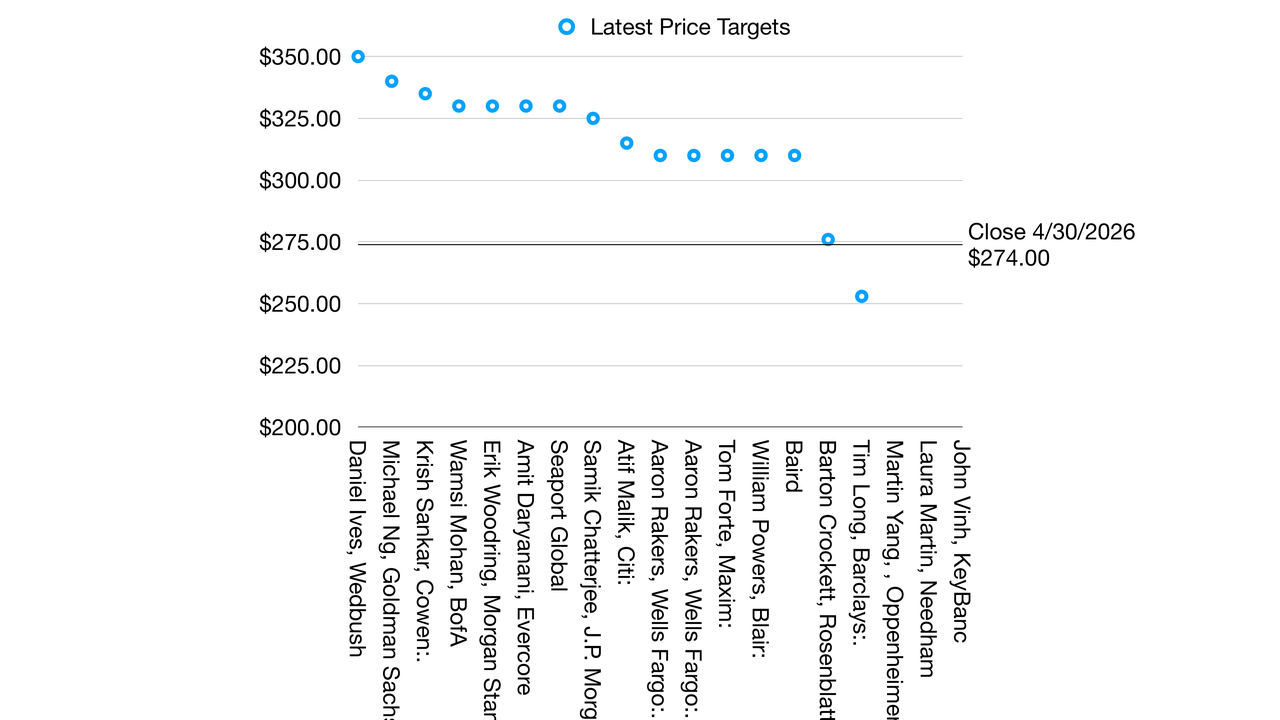
Some analysts are increasing their targets finally realizing that the memory supply crisis might be beneficial to Apple. This should have been noted already three months ago when Apple provided extraordinary guidance for the March quarter. →
MacBook Neo Sold Out Through April → Despite high demand and stockouts, Apple's strong brand and competitive pricing could turn challenges into opportunities for market expansion.
Microsoft’s cheapest laptop is three times more ex…
As I will argue in a further post perhaps this is one of those pivotal moments. →
Goldman forecasts fiscal second-quarter EPS of $2.00 → Goldman Sachs remains bullish on Apple, forecasting $2.00 EPS driven by strong iPhone and Services growth, dismissing overly pessimistic sentiment as the company consistently gains 100 million new customers annually.
My target of $1.98 seems amiss.…
What is always happening, the reaction that is always ongoing, is the creation of 100 million new customers every year. Accelerating this process is not a matter of just new products or change in sentiment with AI. Much of this rate is due to overall global economic and demographic change. →
What’s the consensus on $AAPL? → Apple's strong analyst backing with a 15:1 Buy:Sell ratio and $315 target contrasts its 39% year-to-date rise, overlooking potential future growth.
The consensus is positive though share price target does not consider significant share gains and service growth acceleration into 2027.
NB: The consensus is positive though share price target does not consider significant share gains and service growth acceleration into 2027. →
Apple 3.0: JP Morgan expects that Apple will beat its own guidance next week → Analyst Samik Chatterjee projects Apple's EPS to rise to $2.05 from $1.96, driven by strong iPhone and Mac demand, with a revenue boost to $112.7 billion, while I estimate a slightly lower 20.2% EPS growth, anticipating guidance will be met.
Read the original for a more detailed commentary from Chatterjee. He implies Apple will grow EPS 24%…
…My own estimate is about 20.2%. I look forward to a lively quarterly update. The primary source of growth must be the iPhone and I have that growing at 19% revenue growth. Last quarter the growth was 23%. Perhaps Chatterjee is assuming a similar growth rate into March quarter. That is not impossible but I am assuming guidance will be met rather than exceeded. →
Revenues and growth rates for iPhone, Mac, iPad, Services, Wearables, plus Net Sales, Gross Margin, Operating Expense, Other Income and Expense, Tax Rate, Net Income, Share Count and EPS with a comparison to CFO guidance.
Ref. conference call's guidance, Kevan Parekh, Apple CFO: As we move ahead into March, I would like to review our outlook, […]. We expect our March total company revenue to grow by 13% to 16% year over year, which comprehends our best estimates of constrained iPhone supply during the quarter. We expect services revenue to grow at a year-over-year rate similar to what we reported in December. We expect →
In a recent interview Apple management was asked about AI, which is perceived as an area where Apple has been struggling. Greg Joswiak replied: We’ve been doing things with intelligence for many years, right? And gen AI allows us an opportunity to do that even more. So I’m excited about that, but boy, this is not a sprint. This is a marathon.
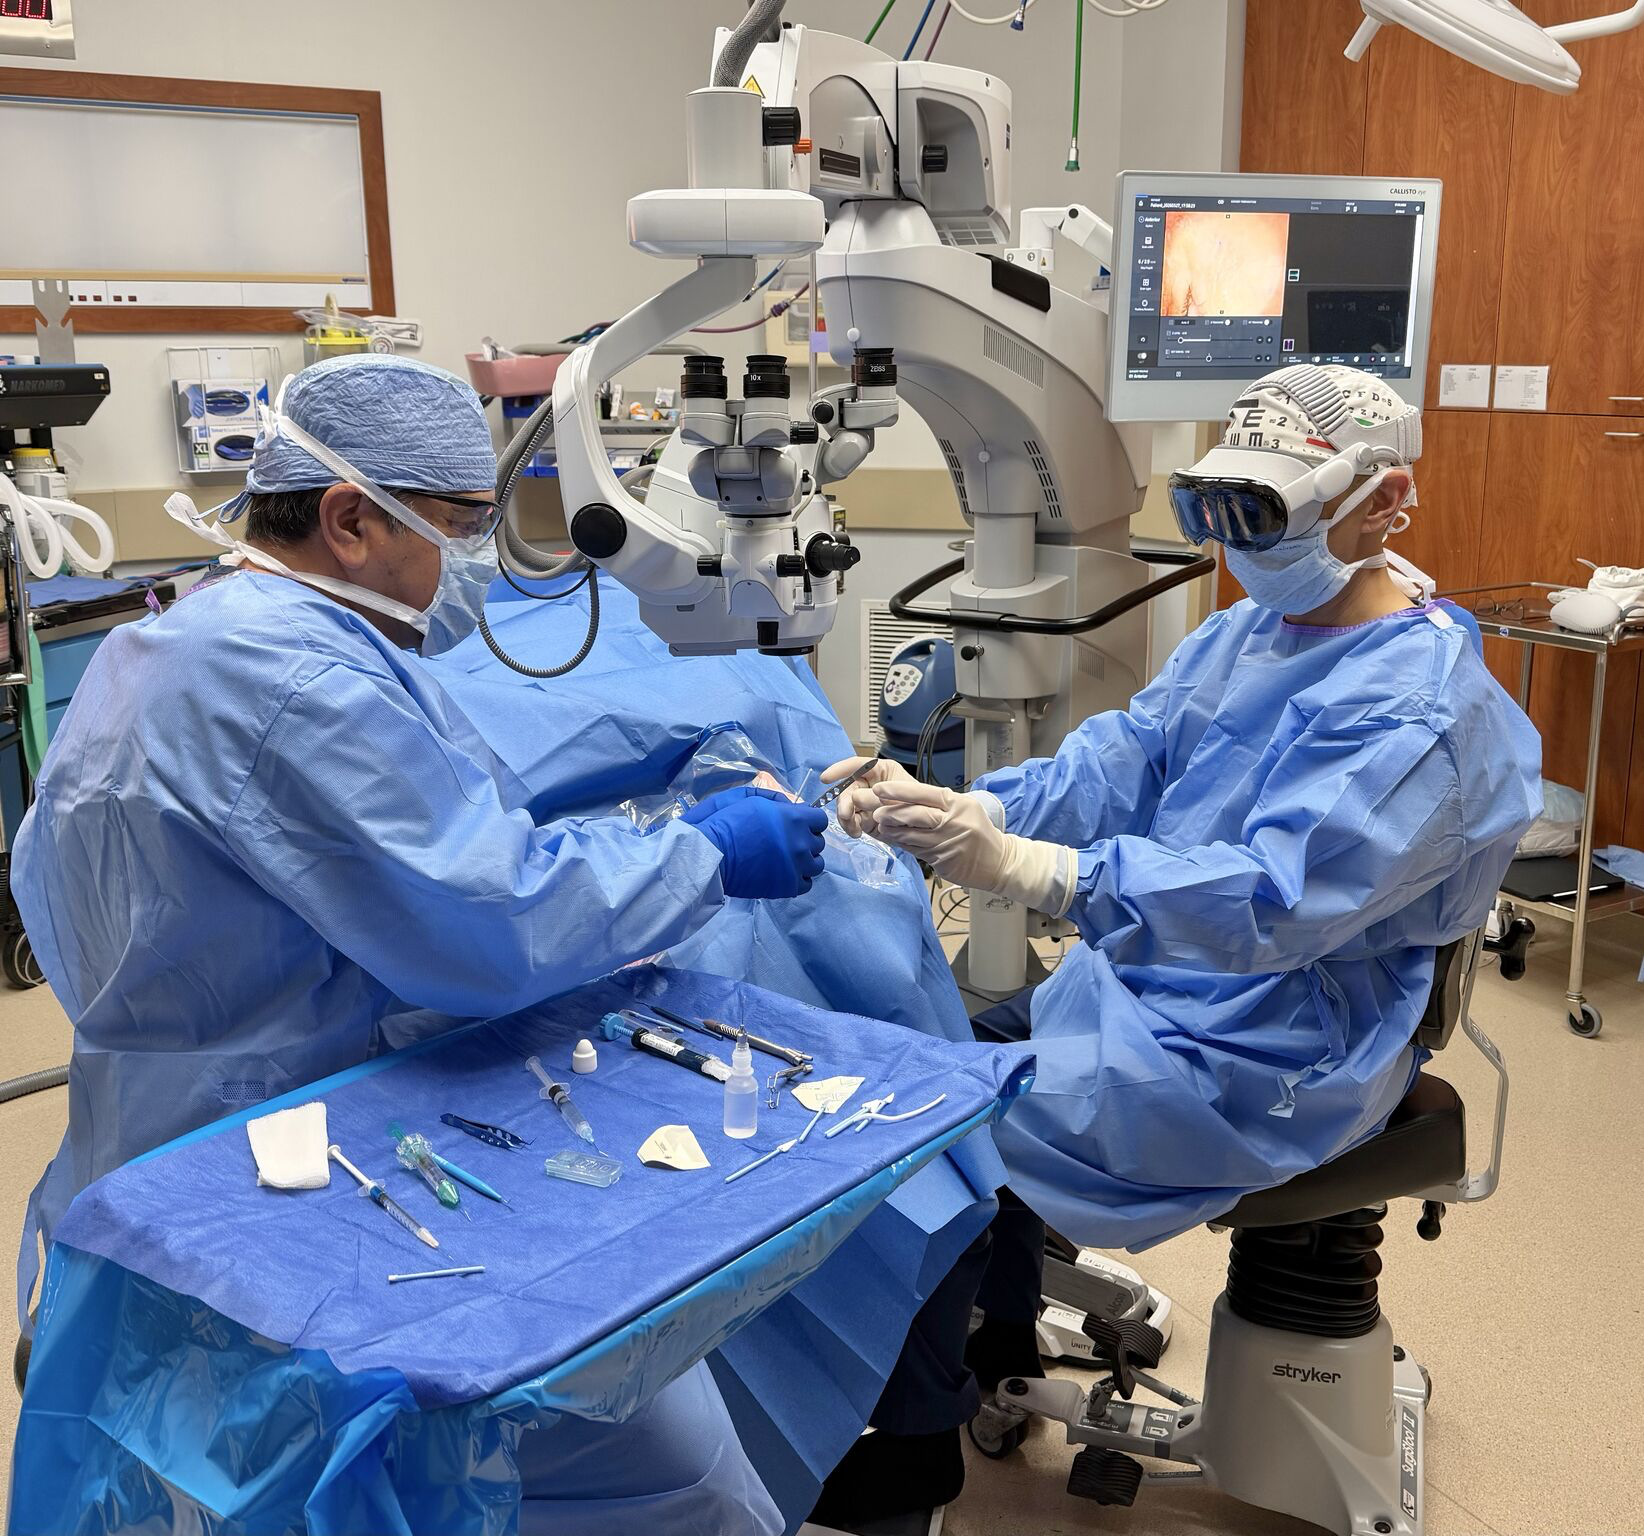
In contrast to AI, Spatial Computing is being largely ignored. It is however making significant leaps in utilization, especially in verticals. →
At just $3,000, the Studio Display XDR democratizes medical imaging, undercutting specialized monitors by up to 90% and revolutionizing healthcare accessibility.
The Studio Display XDR is priced at $2,899 with a VESA mount, and it is more affordable than many specialized medical imaging monitors.
It allows a new set of people to do what previously required only specialists to do and allows specialists to do more than they used to do. →
BofA slightly ups Apple's price target to $325, forecasting $113B revenue and $2.00 EPS for Q2, driven by strong iPhone sales and Services growth, slightly above my estimates of $110B and $2.00.
Q2 forecast update
My own estimates for Q2 revenues and EPS are $110B…
More to follow as we get closer to the earnings release date but this is a good preview. →
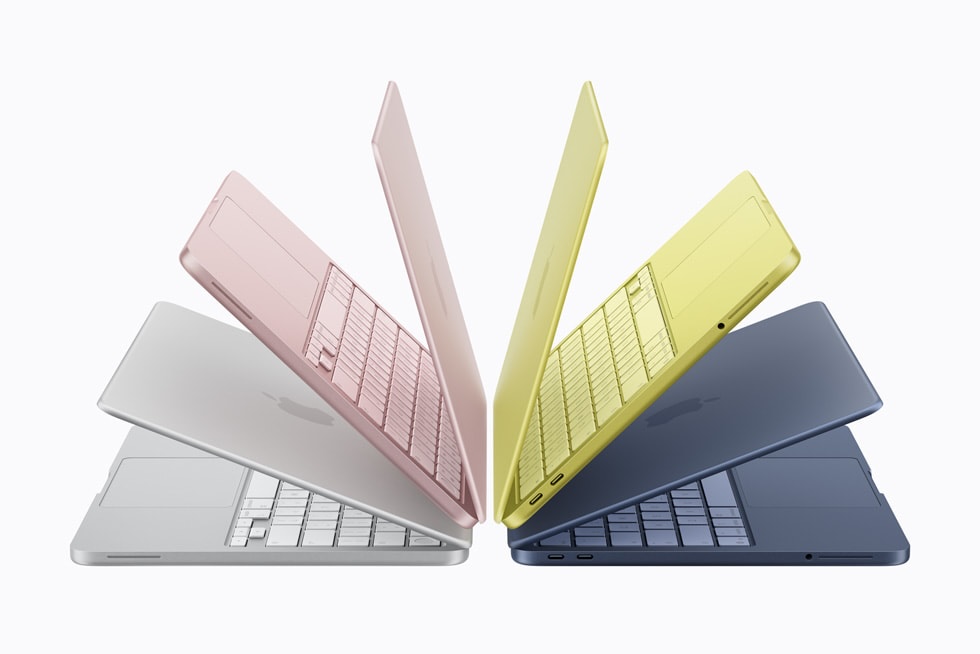
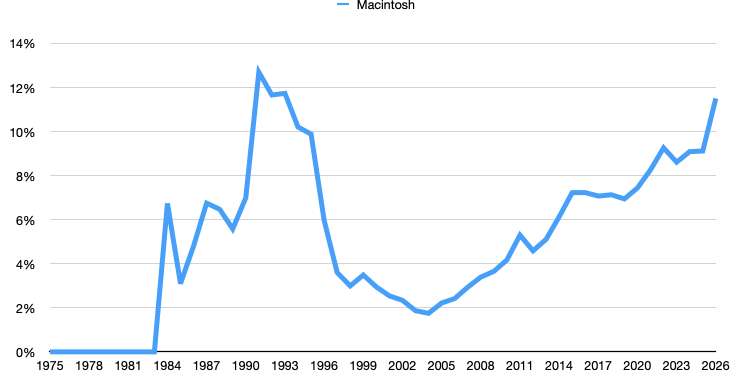
Apple's Mac shipments grew 5.4% to capture 11% market share in Q1 2026, driven by MacBook Air and Neo sales, with revenue estimates slightly differing from unit projections.
Apple growing at double market rate.
Omidia estimates that Apple reached a market shar…
…e of 11% with shipments growing 5.4% due to solid MacBook Air sales performance and the initial sell-in of the MacBook Neo.. This means 5.4% growth for Apple y/y. As I noted in my Office Hour yesterday, I adjusted my Mac growth from 0% to 6% based on the new products launched. This is an estimate of revenues not units but it might be pretty close. Omidia estimates 7,112 million units whereas I’m a little above 6 million. We seem to disagree on ASP. →
Amazon's acquisition of Globalstar boosts its satellite internet ambitions and strengthens ties with Apple, while highlighting the limited reach of space-based networks compared to terrestrial ones.
I assume Apple has wanted to steer clear of Starlink but it’s not clear that was a primary consideration in choosing Globalstar.
Starlink, considered the dominant player, serves about 11 million users. I would note that 11 million is 0.1% of the number of cellular subscriptions worldwide. →
iPhone users boast nearly quadruple the loyalty of Android counterparts, with actual annual switching rates favoring Apple slightly, despite inflated survey intentions.
I did a deep dive into the data and came up with graph above. The original report shows intention numbers which seem quite high. For instance, the net switching rate between iOS and Android is 10% in favor of Apple. This would imply that the entire user base would flip in 10 years. It would also imply…
I think actual net churn is 1.7% of the base each year. That’s still 100 million a year. For now it seems Apple is happy to maintain that rate. →
This episode of Asymco Office Hours covers a wide range of topics related to Apple, including geopolitical risks, financial performance, AI developments, and business strategy. The discussion is led by Horace Dediu and Gene Munster, with insights from industry experts.
Much more was said of Jobs’ departure signaling the end of Apple than of Gates’ departure signaling the end of Microsoft. And much more was celebrated of Apple 50 than Microsoft 50. Why is that?
If you were to structure an experiment to determine the influence of processes and personalities on the outcomes of a company, you would be hard pressed to find a better pair to study. Apple and Microsoft were founded almost at the same time, due to the same enabling technologies (microprocessors) and led by two iconoclastic founders of the same age acting out of similar impulses.
The divergences were that one concentrated on software while the other on hardware. But rather than pairing up in a match made in heaven, both tried to outmaneuver the other in order to avoid dependency. →
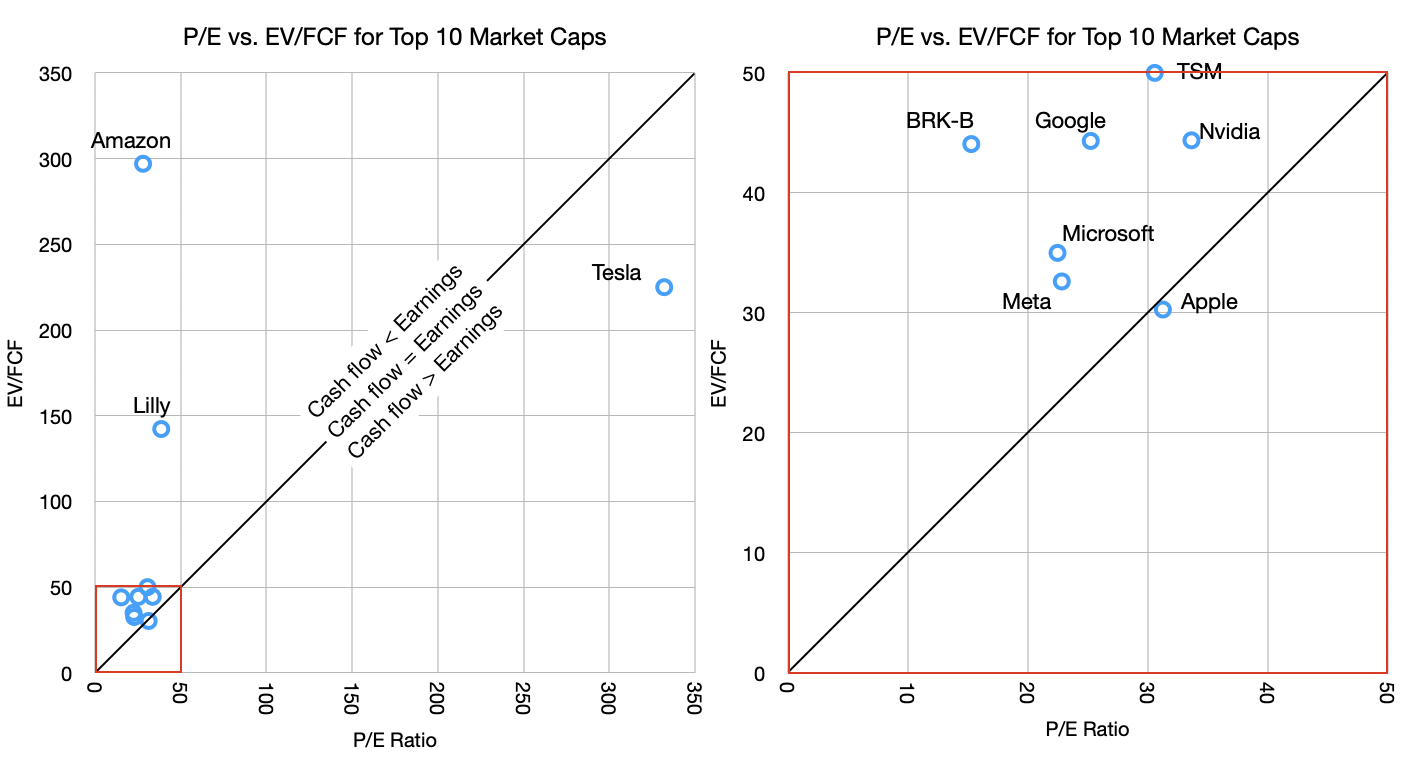
Cash flow is a fact, earnings are an opinion and share price is a dream.
A company’s total worth is the number of outstanding shares multiplied by their value. This product is called the market capitalization or Market Cap.
That’s a simplification. If you want to be more accurate, you should take the Market Cap and net out cash and debt–these are not part of the future flows of cash that can benefit shareholders.
More precisely, there is another measure called the Enterprise Value (EV) which is the total price tag of a company, representing what it would cost to buy the entire business and pay off its debts. EV = Market Cap + Total Debt + Preferred Stock + Minority Interest – Cash and Cash Equivalents.
This is the precise and complete measure of the firm’s value but we use the shortcut of Market Cap since In most cases the Preferred stock and minority interest are negligible and if cash equals debt then the result is EV =~ Market Cap. it’s easier to calculate anyways as the shares outstanding and share price are easily available. Not so for EV. →
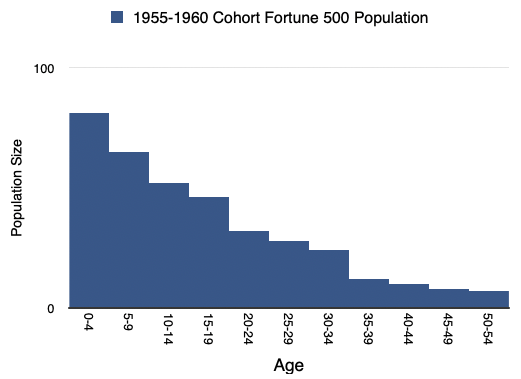
What are the odds of it surviving another year, ten years, 50 years?
Companies don’t last long. A recent study that analyzed thousands of European firms yielded a corporate life expectancy figure of 12.5 years. The Boston Consulting Group analyzed the entry, growth, and exit dates of 35,000 publicly listed companies and determined that one in ten of all public companies fail each year, a fourfold increase since 1965.
As I illustrated many years ago in a talk titled “The Unfortunate 500” most companies die not long after adolescence. Of the Fortune 500 1955-1960 cohort, the 81 companies which joined the index in those years, only 7 remain there today. One third of the corporations on the 1970 Fortune 500 list were no longer in existence thirteen years later. Broadly speaking, as a population, large companies that make it to the Fortune 500 listing have life expectancy within that group of 17 years. →
Today marks the 16th anniversary of when Apple released the first-generation iPad.
To many, including Alan Kay, the tablet form factor makes much more sense than the PC form factor. It’s more approachable, more intuitive and certainly smaller and more portable. As the graph shows, quickly after launch, the iPad overtook sales of the Mac.
The problem arose that whereas the iPad was smaller, the iPhone what smaller still–so much so that users would take phones with them everywhere. At the same time, the “PC” shrank as well so that many notebook (laptop) computers became thin, light and had day-long battery life. The Mac at least became no bigger a burden to carry than an iPad.
So the iPad was stuck in the middle between an iPhone, that did more and more, and a Mac that was very portable. At this point many said that the iPad was a dead end form factor. →
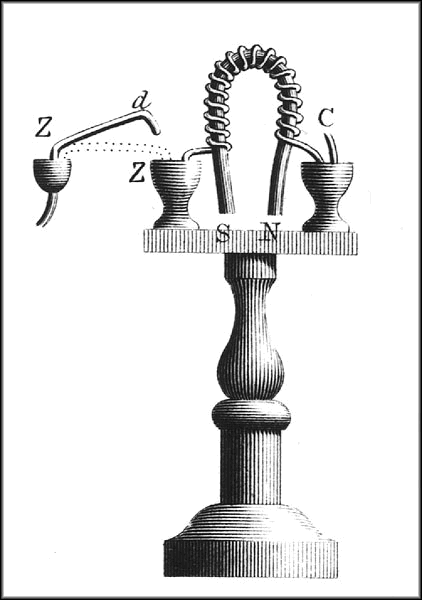
ON September 3, 1821, 37 years after James Watt invented the concept of horsepower and started charging £5/horsepower/year for the use of his steam engine, the first demonstration of the production of a mechanical force by the interaction of an electric current and a magnetic field was given by Michael Faraday in the basement of the Royal Institution in London.
1820 is, in many chronicles, noted as beginning of the industrial revolution. It marked the end of 50 years of war, whose conclusion unleashed pent-up demand. That demand was served by relatively free trade, guaranteed by British naval power, coupled with property rights and financial instruments which allowed inventions of the previous century to finally be harnessed for commercial gain. The steam engine is the canonical invention of the era and its implementation as a source of power for factories, shipping, rail and machinery is legend.
Not usually noted as coincidental to this period is the electric motor. Yet not long after Faraday’s 1821 demonstration in London, the first DC electric motor capable of turning machinery was invented by William Sturgeon. In 1832 he built on Faraday’s electromagnet by incorporating a commutator which oscillated the direction of current to ensure continuous rotation.
Nota Bene.
The Motley Fool asks: Where Will Apple Stock Be in 5 Years? → Not reading this article is probably a wise decision. Shares could perform in line with the S&P 500’s long-term average Investors can follow a straightforward exercise to try and figure out where Apple’s stock price will be in late March 2031. It’s important to consider both the valuation and profit gains. We just released a […] →
Apple’s services continue to see increased engagement, spending → The survey of 3,500 smartphone users reveals a significant rise in average monthly spend on Apple services to $13, driven by increased adoption of premium offerings like AppleCare/One, Apple TV+, and Apple Music, with notable shifts towards AI features despite muted upgrade intent, though potential US bias may affect overall accuracy. →
iPhone sales continue to surge into February – Bernstein → February saw robust iPhone sales driven by the iPhone 17 line, with global unit sales up 26% and ASP climbing 6.9%, yet January-February revenue estimates oddly lag behind projections, sparking confusion. →
Morgan Stanley has a stark message for investors in Apple → Morgan Stanley's survey indicates strong potential for Apple stock, highlighting record iPhone upgrade intentions, especially in China, improved switching rates, and significant interest in a future foldable iPhone. These factors support robust FY26 shipment forecasts and suggest a possible revenue boost from new products. Despite some concerns about declining willingness to pay for AI features, Morgan Stanley maintains an optimistic outlook with a $315 price target. The article criticizes TheStreet's editorial approach for misrepresenting the positive survey findings as negative news about Apple. →
Mac mini and Mac Studio orders booming → Apple's Mac sales are surging due to the M5 chips' enhanced AI capabilities, outpacing other platforms and driving demand despite current shipping delays. →
Gartner adds their Mac Q1 estimate to the pile → In Q1 2026, Apple's Mac sales surged impressively by 10.7% to 12.7% year-over-year, driven by the MacBook Neo's appeal, securing a 10.6% global market share and maintaining fourth place among PC vendors, amidst a 4% rise in overall PC shipments. →