“The N8 is certainly a step in the right direction, it’s much more multimedia,” Per Lindberg, an independent technology analyst at MF Global in London, told Marayam Nemazee on Bloomberg Television’s “Countdown.” “But whether it will move Nokia’s market share upwards is more debatable,” he said adding that Android phones are becoming an “formidable force.”
This is the same Per Lindberg who, in January of this year, reiterated his February 2009 Sell rating on Apple and the entire smartphone industry:
"There is no doubt, in my mind, that the whole sector is hugely overstretched," says the London-based physics PhD and MBA graduate who joined MF Global Ltd. in 2008 after 10 years at investment bank Dresdner Kleinwort.
"The whole sector is priced as if the average player would sustain 25 per cent margin in eternity," he adds.
"It's bordering on absurdity. This will end in tears."
He is willing to use the b-word: "Many stock bubbles are generated by sell-side analysts generating enthusiasm for the companies they cover."
To date however, it's Mr. Lindberg's call that's been the costly one for investors. He has maintained his sell rating on Apple since early February of last year, causing investors who followed his advice to miss out on a more than 110-per-cent surge in the share price.
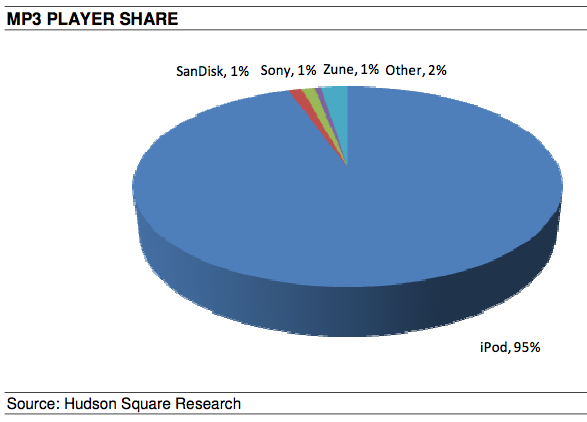
Survey data on US College students' music player share.
Can't wait for the Youtube video of the Zune team getting down with an iPod funeral. After all, the Zune has higher market share than the recently celebrated Windows Phone 7.
Lots of people apparently think it’s a big deal that Gartner is predicting Android will surpass iOS for second place. But why is that necessarily a good thing, given that they’re predicting Symbian will remain in first place? Who thinks Symbian is actually doing well? Nokia’s board sure doesn’t.
I also noted with amusement that by 2014 "other" is slated to sell 85 million units or nearly 10% share, up from 6.1% in 2009. These "others" will be selling more than twice what Apple is expected to sell this year. Is "other" WebOS, Bada, MeeGo, LiMO? If so they're in for a healthy future.
But dwelling on details like these is missing the point. To see how improbable this prediction is, let's go back to 2006 and ask what Gartner was forecasting would happen now.
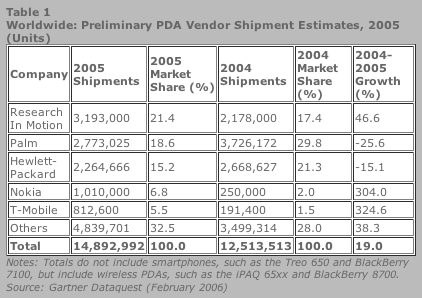
First thing to note is that in 2006 Gartner was busy tracking PDA sales. You might wonder why this is relevant. The reason is because a significant proportion of RIM's Blackberries counted as wireless PDAs and were therefore considered to compete with Palm's Treos, HP's iPaq and Dell's famous Axim. Nokia was in the running with its Communicators. Here is how Gartner characterized the equivalent market in early 2006:
So I'll just come out and say it: In 2006 Gartner did not have a clue what a smartphone was. By their admission:
Gartner defines a PDA as a data-centric handheld computer weighing less than one pound that is primarily designed for use with both hands. These devices use an open market operating system supported by third-party applications that can be added into the device by end users. They offer instant on/off capability and synchronization of files with a PC. A PDA may offer WAN support for voice, but these are data-first, voice-second devices.
In other words, in 2006 Gartner was splitting phones with operating systems into two separate markets: data-oriented wireless PDAs and voice-oriented smartphones. The split was mostly based on the judgement of the analyst on whether a device was "voice" or "data" oriented. I suppose they used the primary input method as a proxy: numeric keypads meant the device was one-handed and therefore voice-oriented. If the device had a full keyboard and/or a stylus-actuated touch screen then it was a two-handed data-oriented device. But even this proxy was not quite enough, sometimes devices were classified whimsically.
To make it more complicated, they bundled non-cellular but Wi-Fi enabled PDAs with wireless PDAs. This made some sense from a corporate IT point of view (their primary customer base) as these data-oriented devices would be used either on a LAN or a WAN (Wide Area Networks: what Gartner anachronistically called cellular networks.)
The presence or absence of a cellular radio did not enter into their view of these devices. So if you asked Gartner in 2006 to forecast smartphones (as we know them now) in 2010, I suppose you'd get what they forecast for "data-centric" devices.
So assuming that today's smartphones are mostly "data-centric" we would have to look back on their view of that market and not the voice market which was seen as an entirely different thing. Their answer should have had something to do with the market leaders and participants in 2006. As the table above shows Gartner showed that RIM, Palm and HP led in 2005 with Nokia and T-Mobile[1] pulling up the rear.
However, from a platform point of view, at the beginning of 2006
Microsoft Windows CE was the No. 1 PDA operating system (OS) in 2005 as 7.05 million PDAs were loaded with the OS, up 33 percent from 2004 shipments of 5.28 million units. Palm OS PDA shipments declined 34 percent to 2.96 million units in 2005.
In late 2006, Gartner made further predictions for the year:
In 2006, Gartner expects the PDA market to increase by 6.3 percent to 16 million units. The market will continue to be driven by broader availability of cellular-enabled PDAs from wireless carriers. Gartner estimates that 53 percent of all PDAs shipped in the first half of 2006 featured integrated cellular capability, up from 46 percent during the same period in 2005. “The share of PDAs purchased by enterprises will continue to increase; it accounted for 49 percent of all PDA shipments in the second quarter of 2006 and Gartner expects that the enterprise market will account for 52 percent of all PDA shipments in 2006,” said Todd Kort.
At this time I have not yet dug up a Gartner "Wireless PDA OS" four year forecast from the year 2006 but I suspect it would not show devices running Google's Android operating system or any running something called iOS.
[1] T-mobile is in the list because it was common practice in 2006 for operators to market Pocket PC Phone Edition devices made by HTC under their own name. Orange, Vodafone and Verizon also had own-brand HTC Windows touch-based devices. Now what does that strategy remind me of?
“In our view, investors are missing the way BlackBerries are eating into Nokia’s messaging phone share in Europe, Latin America and Southeast Asia now that the E-series demand is slowing,” he writes. “We believe the Torch is on pace for 500K units in August,
Torch selling 500k units a month may be good news to RIM but it's hardly a barnburner.
The news about Nokia losing share to RIM is another curious data point. First, because it identifies two competing smartphone classes (E-series and Blackberries) as "messaging phones". That's like saying that HP is losing share to Dell in the "email PC" business. Though the classification of general purpose devices by single uses is probably fair here since these devices are not much good for anything else.
In first half of 2010, iPhone and iPod touch traffic increased from 33.9% to 41% in Finland. Apple's devices account for a very small percent of the total phones in use in Nokia's home country.[1] The analysis was performed by QAim on a sample of 64 million "mobile downloads".
Flush with $45 billion in cash and investments ($50 per share) and no debt, Apple sports an enterprise value of about $190 per share. Compare that to $15 of earnings this year and enough catalysts to make next year’s estimate of $18 seem easily attainable, and you have a stock that actually trades at a discount to the S&P 500.
Frequent readers of this blog know they're in good company. There have been over 1000 comments in but a few months and, without any qualification, they have all been valuable.
I've been delighted that contributing readers are not only civil and polite, but that they almost always move the intellectual level of the blog higher. That's very gratifying because although one major consideration when publishing is creating a large audience, a high quality audience is much more important. Especially to a site dedicated to elevating analytical discourse.
So, being analytical, I wanted to find out how to characterize the audience and understand the attributes of the readers. Naturally, where appropriate I would like to share that information. I hope to share some stats, perhaps with some interesting highlight, every month.
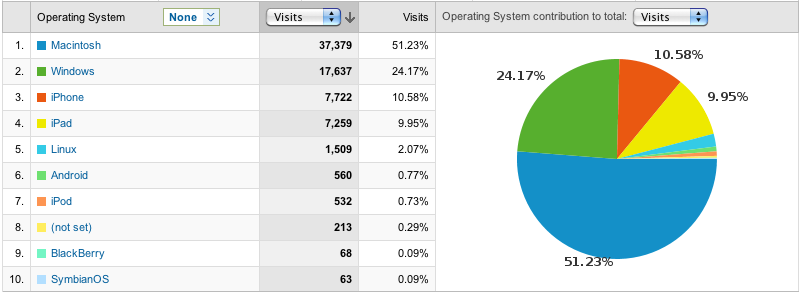
To kick off, here is a snapshot of one month's worth of visits to www.asymco.com ranked by operating system.
What is perhaps unexpected is that mobile platforms (iPhone, iPad, Android etc.) generated more views than Windows. When comparing browsers, I also observed that Internet Explorer makes up only about 5% of views. (If that's not a leading indicator of the intellect of the readers, I don't know what is.)
Time will tell whether these ratios persist, but so far, it seems that Asymco readers are at least eating their own dogfood.
I've been asked in comments on this blog who will win the "mobile war".
I use two analytical tools to answer this question: (1) history (2) value chain analysis.
History shows that operators are very important and hence very powerful in this market. That makes sense on many levels. They control what phones you get to buy, they decide the pricing and they decide frequently how you can use the phone. This is because the networks are expensive to build and maintain and there is an implicit bargain struck that the user and device should conform to the operator.
Value chain analysis tells me that as networks are not good enough, tight integration of the business models of the phone vendors and the operators is necessary to climb up the trajectory toward good enough as quickly as possible.
Therefore, given the distribution of value/bargaining power in the chain, it’s reasonable to assume that it’s operators who will decide which platforms win/lose and to what degree.
That simply means that no single platform can win a disproportionate share because it would threaten the balance of control the operators require. So talk of “dominance” of one platform or another is hyperbole. The most likely scenario is an even distribution of share between 4 or 5 competitors, so I expect iPhone and Android to get 20% share each.
This is not “fair” or economical or efficient, but it’s the way it’s going to be for a long time. If you're a fan, don't despair. In a few years, it still means hundreds of millions of units a year for each platform.
If you want to dream or hope for a more efficient outcome, you’ll have to look outside the cellular network model. I.e. think how iPod/iPad and Android tablets will evolve into communications products.
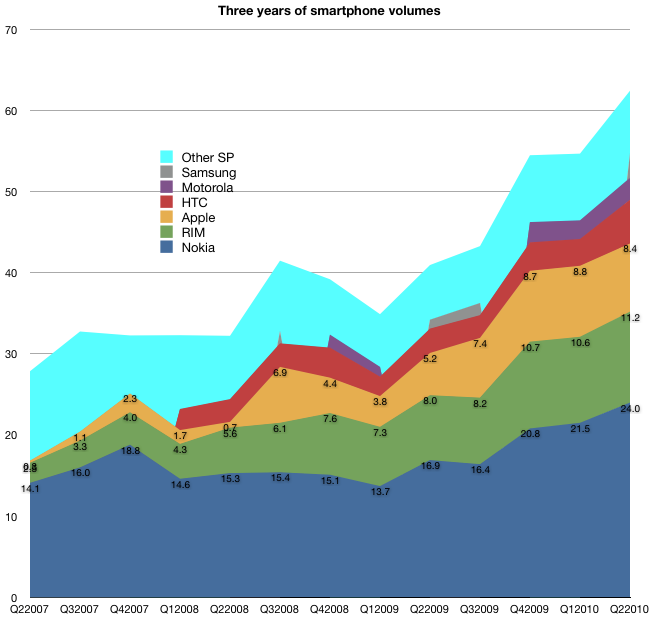
I did not include all vendors for various good reasons. The first survey (market share) did include an "others" category that made the volume data complete, but in the financial data sets, I chose to include the top 7 vendors that make up 80% of device volumes.
One noteworthy vendor that was not included was HTC. HTC is an important vendor for several reasons:
it's a pioneer in smartphones having made the first Windows Mobile devices and the first Android devices
at one point it sold 80% of all Windows Mobile devices
even if it did not brand its devices, it was the name behind many re-branded or white-label operator branded phones
it has a brand of its own today and is expanding its reach
HTC has been around building devices since 2001 and so it would be a pity to exclude them from any analysis of the effect of iPhone on the market or any discussion on the effect of smartphone disruption on feature phones.
The challenge with HTC was that historically their branded devices and white label devices were not reported by the company separately. This matters because white label devices are valued differently. Typically these devices are not marketed by the original manufacturer so SG&A is not applied to their cost base. Operating margins, ASPs and hence profitability is not directly comparable with other OEMs.
But HTC has recently changed its reporting. Thanks to a reader I discovered that, since 2008, HTC has been listing its ASP and Operating Margin making direct comparisons possible. I still don't have all the data, but enough to add HTC to the analysis.
So, here are the 5 industry performance criteria, now with eight vendors listed.
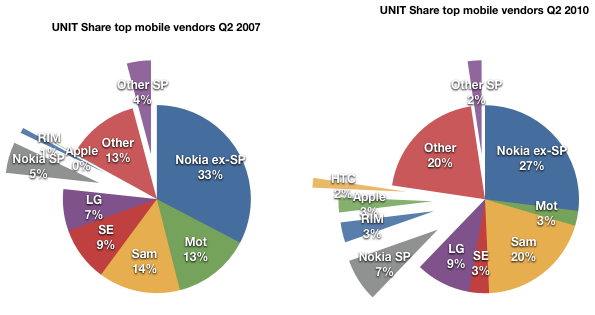
Volumes
Note that HTC volumes start in 2008.
The volume of units HTC sold has been increasing at about the rate of market growth.
As a result, HTC's share has not increased as dramatically as those of the other smartphone entrants.
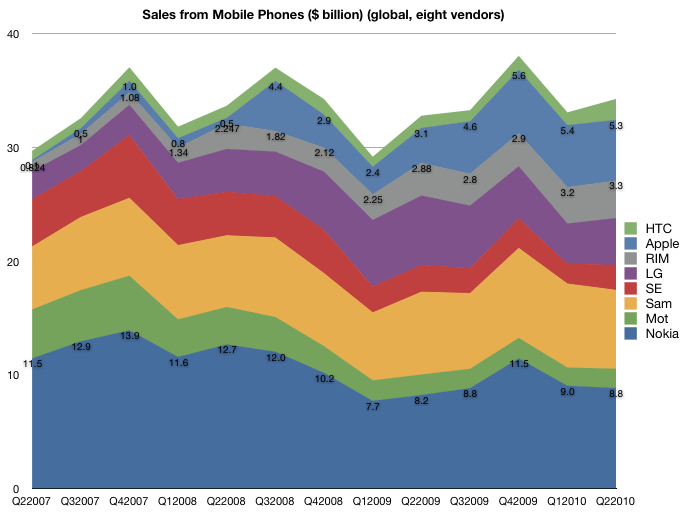
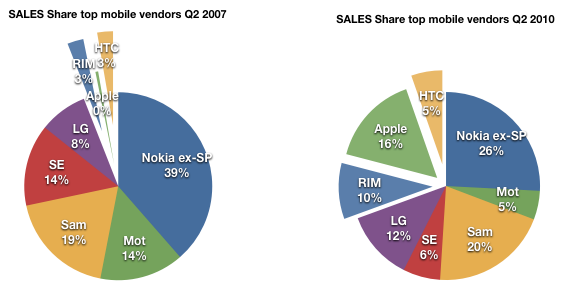
Sales
A similar story in the sales picture. Although a consistent performer, the growth has not matched that of RIM and Apple.
ASP
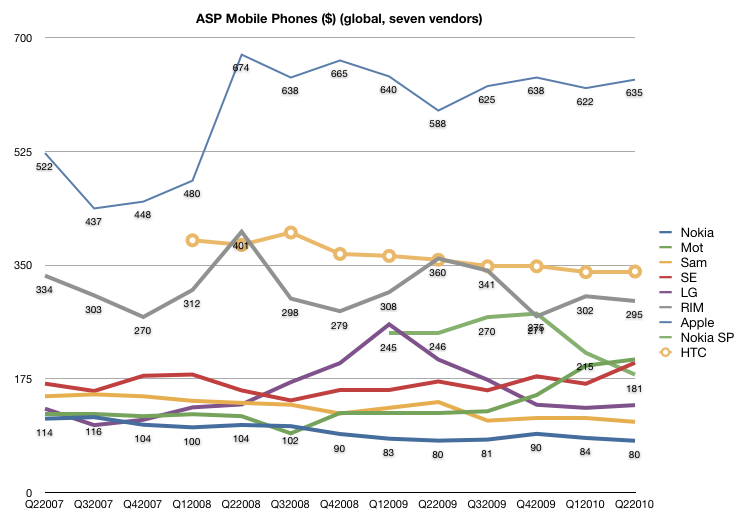
The pricing story is also a mixed one. Although HTC lies between RIM and Apple in price, the erosion is more consistent with RIM and the rest of the industry.
Margin
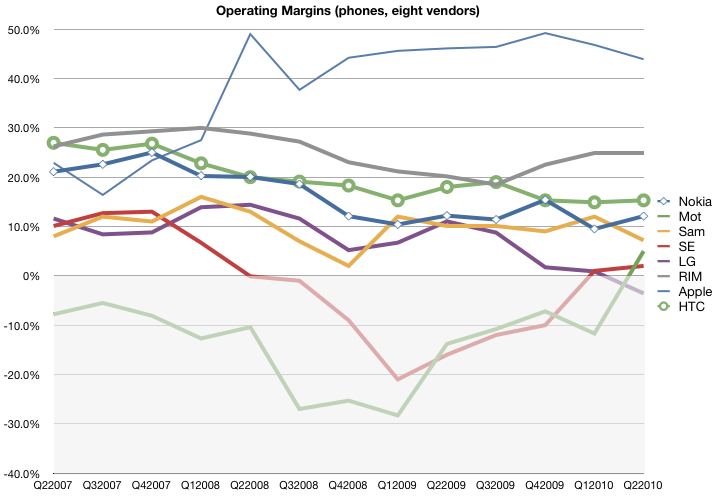
The margin story is also not as positive as one might expect. The margins for HTC started out above Apple and RIM but have dropped to closer to industry average. This is not what one might expect from an exclusive smartphone vendor.
Earnings
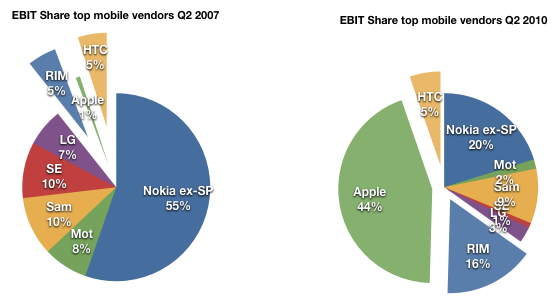
The share of earnings has remained unchanged at 5% over the period of iPhone presence. It's perhaps a credit to HTC that they did maintain their position in the market with the massive change that has come to pass.
However, here we also have to ask if HTC is riding a disruptive wave.
When I wrote the last series, my definition of “loser” was a company that had faced a long series of operating losses and has no viable software assets of its own, making it vulnerable to Android (and Windows Mobile). Motorola first, Sony Ericsson second and LG now coming into the picture. Nokia is not a loser in this sense since it has remained profitable and does maintain an investment in software. Same with RIM and Samsung (now with Bada). When/if they do have the near death experience, they might opt for the Android lifeline (flimsy as it is).
However HTC does not fit the mold of either "winner" or "loser". It's the Goldilocks company, not too hot, not too cold.
But I would add that HTC is not an example of a winner because of its adoption of Android. HTC’s dependence on Windows Mobile made their move to Android the most desperate of all. Unlike the larger OEMs, who had their low end devices to fall back on, they are completely dependent on a smartphone OS vendor. When WinMo was showing the first signs of crisis in 2007, they were the first to flee to Android (think of why they would risk the wrath of Microsoft for something so fragile as Android in 07). They are also trying hard to escape the dependence by building up their own UI (SenseUI) and I would not be surprised if they move to their own OS in the future. Being associated with Android does not confirm them as "winners" but in fact, shows their vulnerability.
What does this all say about Android?
Again here my thesis is that Google chose to sustain the industry rather than try to upend it. I don't judge their motives, but the fact is that with Android, Google is not in a position to disrupt telecom. There were high hopes dashed with the Nexus One and hearts broken with net neutrality and now there are patent wars to be fought. Android, with its licensees, is still at the mercy of operators.
The mobile phone market is intertwined with the telecommunications industry which is vast and there are numerous competitors which are much more dynamic and better capitalized than the moribund PC or music player vendors. It’s also a regulated and fragmented global market with 1.2 billion units and 5 billion consumers—far greater than any of the markets Apple played in for its first 30 years.
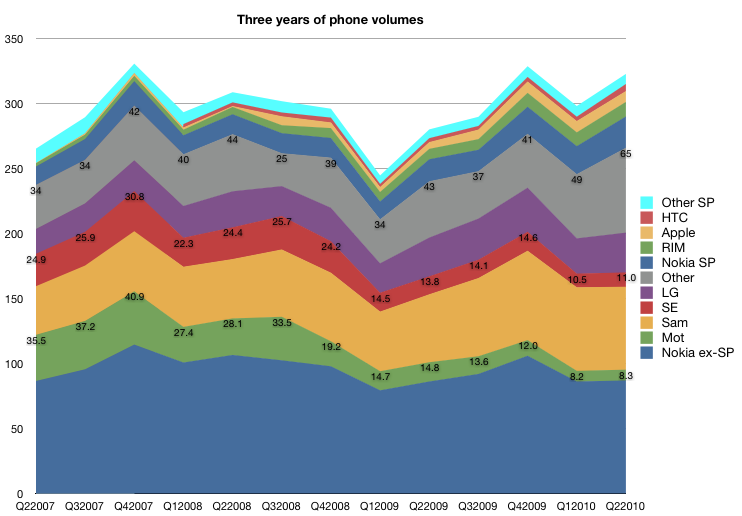
Nevertheless, the iPhone has had a huge impact on the industry. To show just how much of an impact, I dove in and pulled over 500 data points on three years’ financial performance of seven competitors responsible for 80 percent of units being shipped today. The time frame covers the iPhone’s participation in the market so it allows for “before-and-after” comparisons.
Now I turn my attention to draw a bottom line from all the data above, namely the operating earnings (EBIT or Earnings before Interest and Taxation).
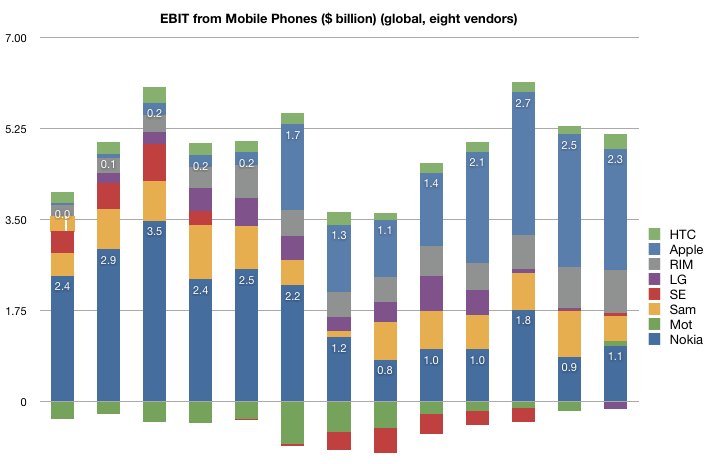
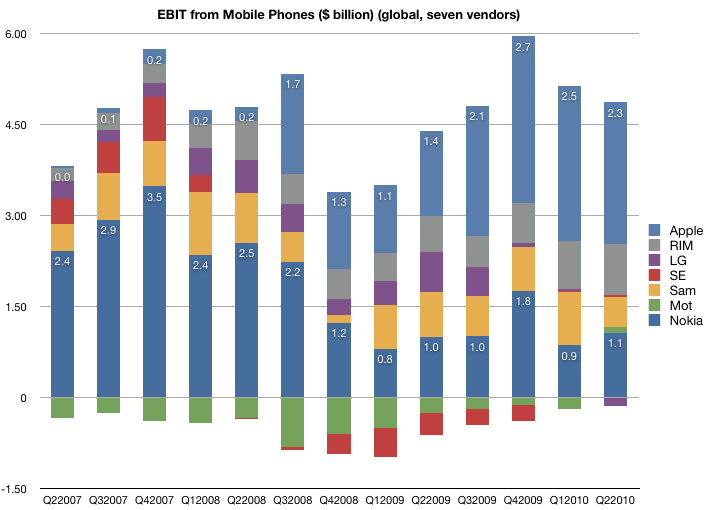
The first chart shows the EBIT from the top seven vendors of mobile phones since the quarter when the iPhone launched. I annotated Nokia and Apple's bars to give perspective.
The total available profits in the industry dipped to a bit under $4 billion at the trough of the recession, and have recovered to nearly $6 billion in the holiday quarter last year. However, not all vendors are profitable. As you might expect from looking at the operating margins, Motorola and Sony Ericsson have been generating losses for most of this time period. They have both reached profitability in the last quarter, though at very low levels and after having lost a large part of their sales. LG has turned negative this past quarter after being a modest earner for some time. Samsung has maintained a fairly even consistency in its profit capture, though with its expanding market share, it seems to have come at the cost of pricing.
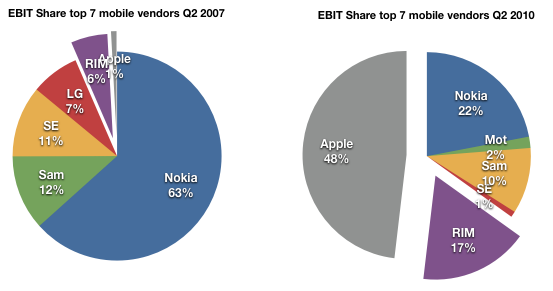
Finally, looking at the pure smartphone vendors RIM and Apple, the picture is nothing short of astonishing. This before-and-after share-of-available-profit chart shows that the two entrants went from about 7% profit share to 65% in three years.
Apple in particular is capturing about half of the available profits with three percent of the units. It dwarfs all the other vendors, more than double the nearest (Nokia). All that in three years and with the added burdens of only three models, a recession and limited distribution.
What does it all mean?
Here are my conclusions, enumerated:
The lack of a real response. The recurring theme in this series of articles has been that giant multinational incumbents in a vast and rapidly growing industry, enjoying all the advantages that size and incumbency, have had their profits taken from them. And they don't seem to have put up much of a fight.
It's all wealth transfer. Note the total amount of profit available has not increased markedly; this is not about incumbents growing the pie. Two thirds of what should have rightly been theirs moved from the incumbent shareholders to the entrant shareholders.
Speed. This shift of profit occurred over an unprecedentedly short period of time. Three years is no more than two product cycles in the industry and it's an order of magnitude faster than what happened historically to other industries.
Disruption is the diagnosis here. The incumbents were caught in the headlights. Disruptive innovation leads to asymmetric competition and this is what we just witnessed. History has shown that the shift of profits is usually the last stage of disruption and is usually irreversible because the change in business models cannot happen at the rate of change of profit transfer.
Which leads me to one final point.
When analyzing the potential for challengers to the new winners, the most cited is Android. Can Android affect this redistribution of profit once again? And to whom?
If Android is to become the dominant platform, does it depend on the success of its licensees? Who are these licensees and what are the chances that they will be able to align their businesses to what Android offers (a new revenue model based on services and advertising).
One problem I see is that Google is making a bet on those same vendors who are now squeezed in the middle of that last pie chart: Samsung, LG, Motorola and Sony Ericsson. Nokia, Apple and RIM will certainly not take the OS over what they already have as it dilutes their differentiation and margins. That means Android is aligned with the biggest losers in the industry.
So how likely are these disrupted ex-giants to recover and take Android forward? My bet: slim to none. Android does not offer more than a lifeline. It is not a foundation for long-term profitability as it presumes the profits accrue to the network and possibly to Google. Profit evaporation out of devices to Google may be a possibility at some time in the future, but only if the devices don't need too much attention to remain competitive. But because they're still not good enough (and they won't be for years to come), it's certain that attention to detail is what will be most important to stay abreast of Apple.[1]
So here we have the real challenge to Android: partnership with defeated incumbents whose ability to build profitable and differentiated products is hamstrung by the licensing model and whose incentives to move up the steep trajectory of necessary improvements are limited.
In other words, Android's licensees won't have the profits or the motivation to spend on R&D so as to make exceptionally competitive products at a time when being competitive is what matters most.
[1]: I would argue the same lack of symmetry with licensed software vendor Microsoft is what led the the failure of the same incumbents to make a dent in the industry with Windows Mobile [2003 to 2010].
The key bit: “At the critical juncture […], when they should have gone for market share, they went for profits.” I think this encapsulates Jobs’s philosophy since taking over Apple in 1997. Take the high end of the market first, establish a brand and presence, then steadily start to expand.
I've long argued that Apple is in the phone business to win significant share (i.e. greater than the share they have had in the PC business). Since the phone market is vast (1.2 billion phones sold in the last four quarters) iPhone volumes must be as well.
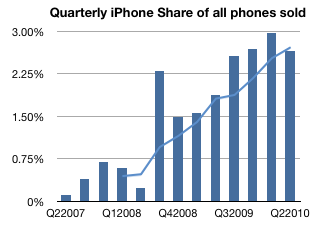
So how has share evolved, and what can we expect? This is a graph of quarterly share for iPhone including a four period moving average:
The trend is clear to see. With seasonal variation due to the launch cycle, the share is likely to increase over 3% and keep going. How far can it go? That's a strategic decision for Apple's management. If we are to take Steve Jobs' word that their plan is not to be a niche player in any market they target then I have to conclude that Apple is aiming above 10%.
The volume expansion in the US due to the end exclusivity is only the latest in a series of distribution deals that Apple has brought to bear: International expansion, dropping exclusivity in other countries and broadening the portfolio (including earlier models in current line-up) are all natural and obvious moves in a broader market push.
Pricing might be considered another lever that Apple could use, though that seems unnecessary today.
I conclude that growth in iPhone sales of 50% per year seems entirely possible for the next few years. Such growth would allow Apple to reach 10% of the world's 3G subscribers by 2013. That would still be only 4% of all phones and 20% of smartphones.