Asymco

Asymmetric Intelligence

Horace Dediu

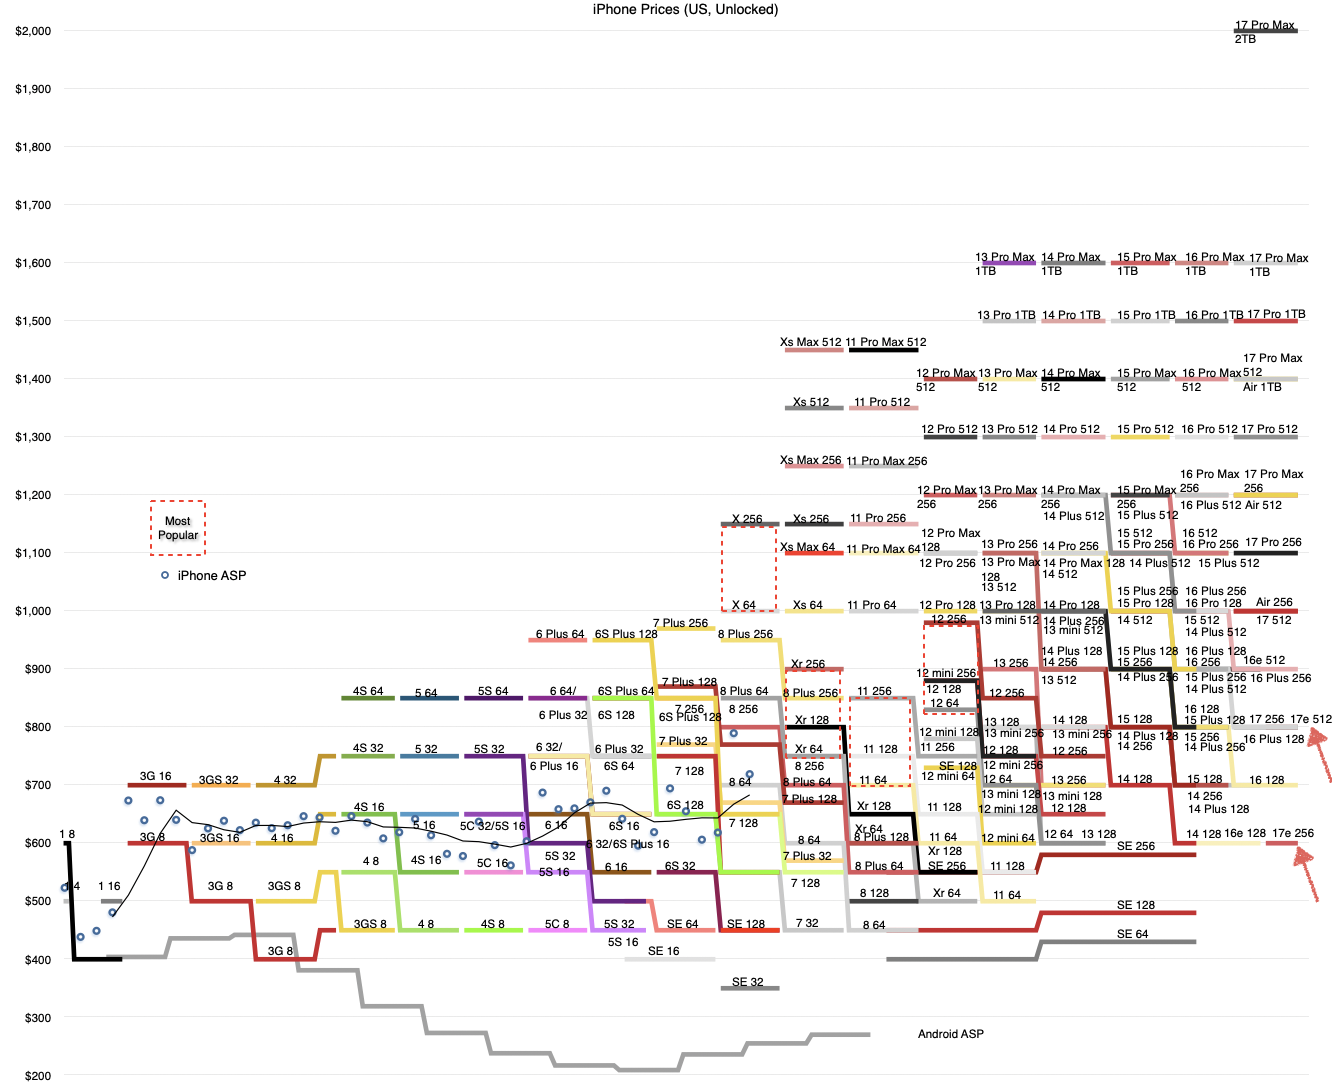
  1. Will Apple preserve iPhone 18 Pro pricing at 17 Pro levels?

    Nota Bene · 4 comments

    History says yes.

    The global smartphone market is facing structural pressure from rising memory prices. In particular, the spread of AI technology is sharply increasing demand for high-performance memory, tightening supply and pushing prices up quickly. As a result, some Android manufacturers have raised prices on new products, and low-margin budget models could shrink in the market. The industry also sees the trend as potentially leading to a contraction in the overall Android market size.

    Against this backdrop, Apple has chosen a strategy of keeping prices for its main models unchanged. Pu’s analysis said the iPhone 18 Pro is likely to start at $1,099 and the Pro Max at $1,199, maintaining the existing price range. That would be the same as the previous model. It is interpreted as a strategy to secure price competitiveness even if Apple accepts some margin decline to defend market share.

    Apple is also expected to pursue a two-track strategy that considers both price accessibility and profitability. It would keep base-model prices to lower the barrier to entry, while raising prices for higher-end models with larger storage capacity to offset profits. It has also been suggested that an ultra-premium iPhone 18 Ultra could be added, and the overall average selling price (ASP) is expected to rise.

    Ultimately, Apple’s strategy aims to exploit weaknesses in the Android camp, which is under pressure to raise prices. While rivals face demand contraction from higher prices, Apple could keep prices relatively stable and expand user inflows. A recent rise in demand from Android users switching to iPhones has also been detected, raising the likelihood that Apple will strengthen its influence in the premium market through this strategy.

    Source: 디지털투데이 via Analyst: Jeff Pu

    NB: There is always a huge surprise when Apple does the same thing it always does.

    Rule 1: Pricing choices Apple makes are based on a strategy.

    Rule 2: Apple does not respond to competition with changes in pricing

    Rule 3: Apple does not respond to supplier pricing with changes in pricing.

    Rule 4: The secondary market absorbs low end demand.


  2. Tata Electronics' workforce expands to 75,000 from 15,000

    Nota Bene · 1 comment

    Measuring how far India will go in production.

    According to The Economic Times, citing unnamed sources, "Tata Electronics has expanded its workforce to 75,000, surpassing Taiwanese rival Foxconn's headcount in the country, making it Apple's largest contract manufacturer by headcount currently." The report added that the expansion has been driven primarily by its large-scale Hosur facility in Tamil Nadu.

    Supply-chain sources said the company's workforce growth marks a sharp increase from about 15,000 in 2023, reflecting an aggressive scaling strategy supported by major capital investment, factory acquisitions, and rapid capacity buildout. The expansion includes its 500-acre Hosur campus, which has become the core hub of iPhone assembly in India.

    Tata Electronics has combined acquisitions of Taiwanese contract manufacturers' Indian assets with greenfield investment to accelerate entry into Apple's supply chain. It acquired former Wistron(3231.TW) and Pegatron(4938.TW) facilities, while simultaneously expanding its Hosur plant, which began iPhone assembly operations in 2025.

    In addition to assembly, the company is also moving upstream into semiconductor assembly and test (OSAT) and component localization, supported by large-scale funding injections in recent fiscal years. These investments aim to build a vertically integrated electronics manufacturing base spanning assembly, packaging, and supply chain services.

    The reported figure of 75,000 employees reflects both direct and acquired operations across Tata Electronics' manufacturing footprint in southern India. One source noted that the rapid scale-up has enabled the company to meet Apple's production requirements while overtaking Foxconn(2317.TW) in local headcount, although industry participants expect rankings to fluctuate as other facilities ramp up.

    Source: Source

    NB: If we add Tata and Foxconn, we are probably in the 200,000 range this year. The comparable China model is …

    …in the 2 million scale. I can imagine that India could scale to 1 million easily thus reaching about 50% of what China is producing. This may not mean a reduction in capacity in China but a net gain. This implies roughly three more doublings of expansion (200k -> 400k -> 800k -> 1000k+).

    From 2023 to the present the number of doublings is also about three (15k -> 30k -> 60k -> 75k) suggesting perhaps four to five years of aggressive growth still to come in India.

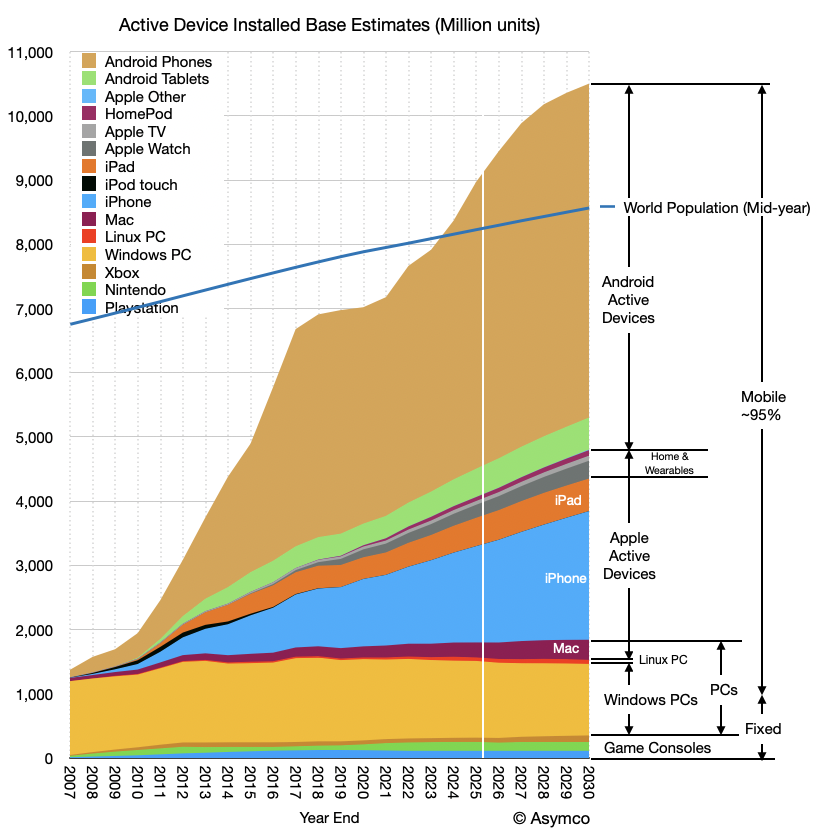
    This needs to be matched to the overall expansion of user base that is already in the Active device forecast.


  3. Will Apple avoid giving their cash flow to Nvidia?

    Research · 3 comments

    Asked by Jay Goldberg

    Q: Do you think Apple will start investing heavily in AI data centers?

    There's rumors and actually statements from Apple saying that they're working on a server chip. Google has a server chip. Amazon's got a server chip. These are effectively aimed at Nvidia. And if you can make something, you tend to do it. Now, of course, there's some protection — Nvidia's got other special sauce, but their margin is everybody's opportunity. They have a huge margin. And everybody's writing huge checks. As I say, hyperscalers are just handing over their entire cash flows to Nvidia. And that means their shareholders' entire wealth is being handed off to Nvidia shareholders. So there's a transfer of wealth happening right now. Presumably, because we're going to get some benefit later, but if that's happening and people are irritated by it, they're going to find a way to do what Nvidia does.

    And Apple, of course, can and will do that. Now, whether that'll get deployed at the edge or in Apple's own cloud — because they probably also don't want to write checks to Nvidia, and they'll say, well, we can do it, and we won't necessarily sell them, like Google wants to. They'll probably just use them themselves. And that's something certainly they're capable of.

    The question I was always asking is how many are we talking about? Because if it's in the tens of millions, or even single-digit millions — for Apple, single digits. Is it worth it to develop your own designs? There's a limit to how many you can deploy. And probably you're going to have to replace them every so often, so there's a question about how much it costs to keep on the treadmill.

    But it is an interesting question, and I think everybody's capable of doing what Nvidia's doing. But it's about execution, timing, delays. Look at what happened with the Qualcomm chip — how long it took Apple to finally deploy the communications chip relative to the amount of grief it had to deal with. First, of course, it moved out of Intel. It moved out of Qualcomm now, and now the question is, is it going to move out of the server supplier chain? And that's a complex decision. But again, Apple's not doing it because they want to be in that business. It's more that they want to avoid dependency.

    This was one of the questions asked by the participants in Asymco's May 2026 Office Hours live Q&A sessions, open to Asymco One subscribers.
    See also: May 2026 Office Hours

  4. Why is Apple's R&D run rate suddenly $40 billion/yr.?

    Research · 1 comment

    Office Hours question asked by Frederich H. on May 1, 2026.

    Q: Any thoughts on the breakdown of R&D, with that big jump?

    It's hard to tell. I do think they're buying — that does include some hardware. A lot of hardware. I think they're building quite a bit of capacity in order to implement their versions of AI. They're not for deployment, but they're for testing and experimenting. They're hiring people as well, obviously that's included. But I do think it used to be they bought equipment for testing — I don't know, radio frequencies, and testing the iPhones, and semiconductors, and testing a lot of things like that. But I do think probably there's a lot more spending now on the stuff that feeds AI. It's not on the level that a hyperscaler's doing, because they're building it for scale, and Apple's maybe building it for testing.

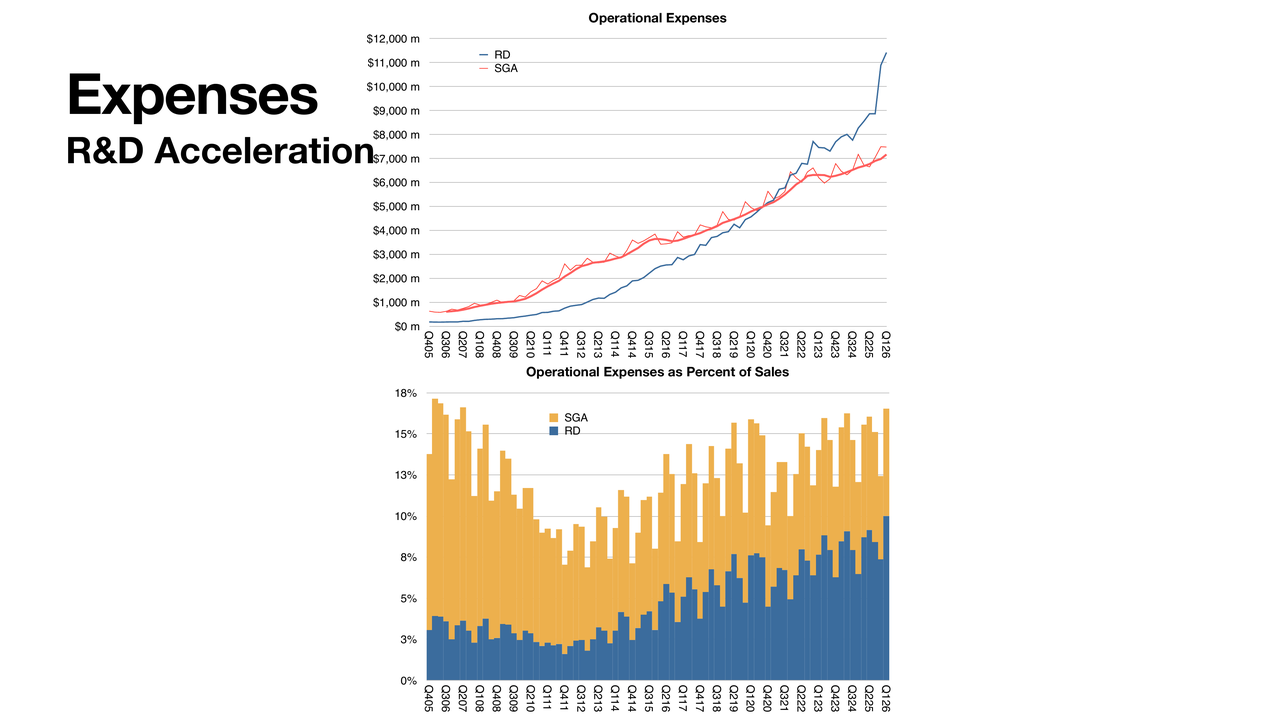
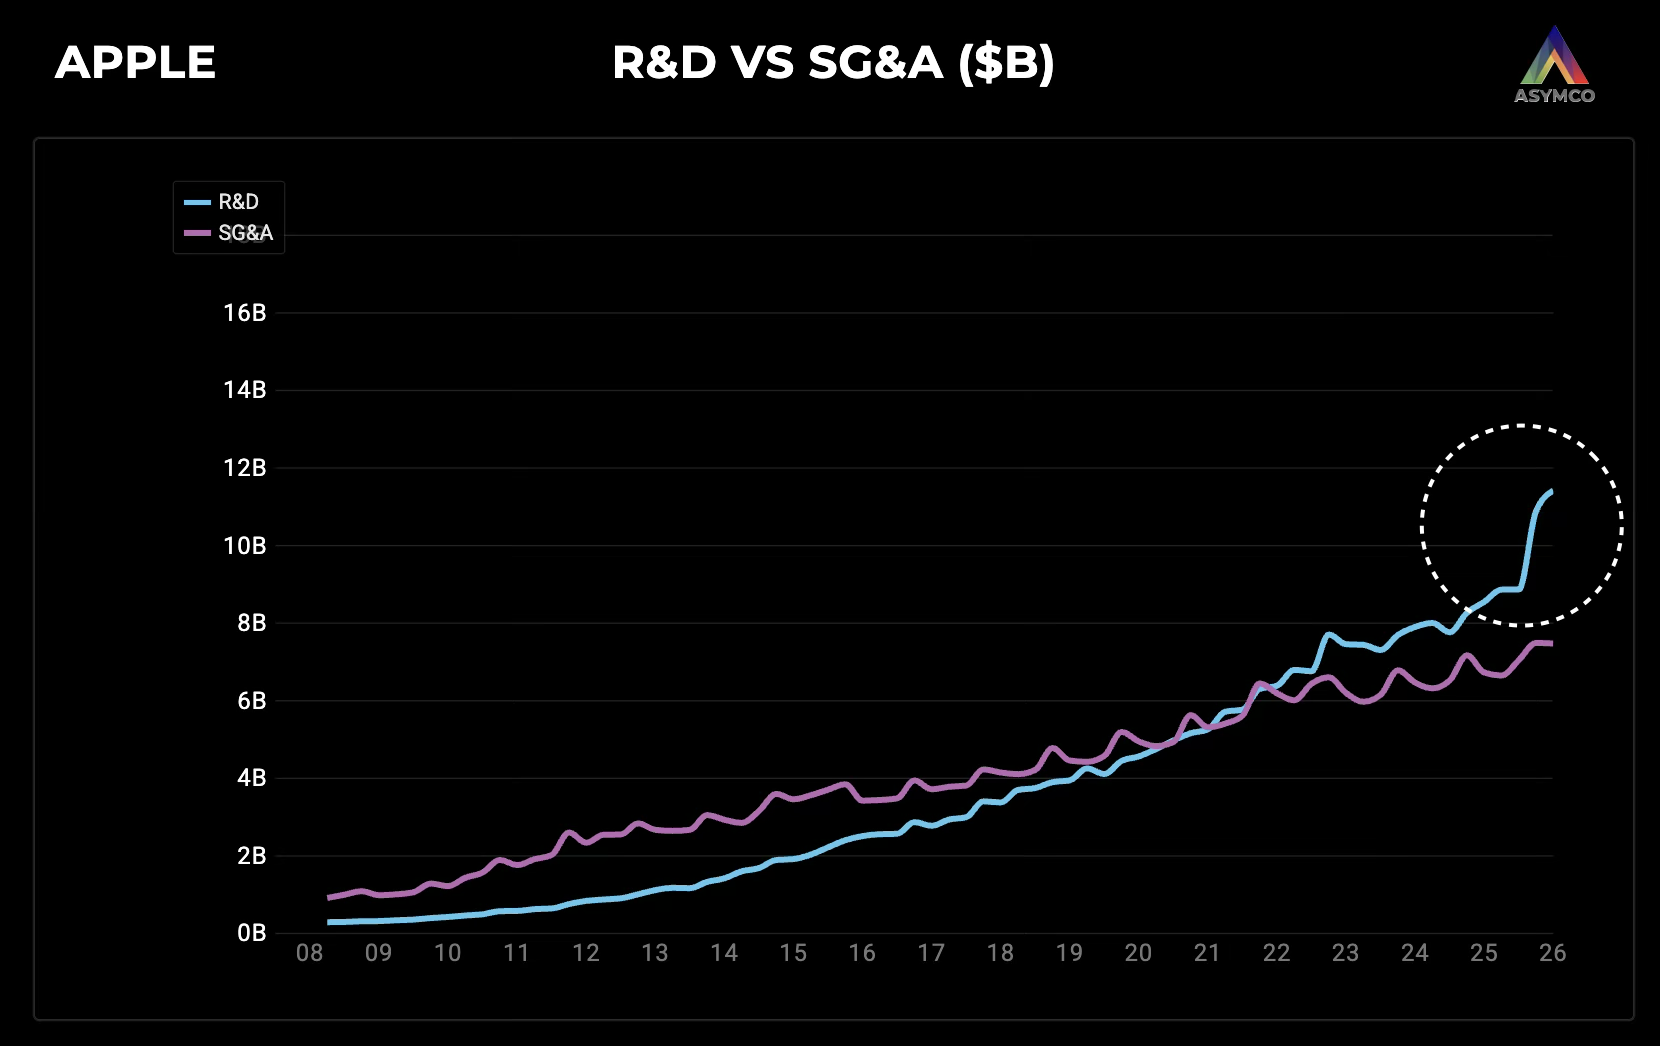
    We're talking about here, look, $11 billion in R&D, that's in one quarter. So that goes out to about $40 billion a year.

    Mostly, I think this is people, but there is some equipment involved. It's just maybe different ways of capitalizing it, because capital equipment is a complex story.

    It seems like a big jump, but it's only $2 billion more compared to the prior period. It's recurring though. And the reason that this stays steady and keeps growing is because people are on the payroll. And so if there's more and more people, that's paid every period — the reason, by the way, you see SG&A being seasonal is because there's temporary people in the stores. That involves people who are hired for the holidays in the Apple stores. So that's where you see some less than steady. But engineering people are more steady. But if there's a spike, there might be something going on where there was some equipment involved.

    See also R&D Acceleration section of Apple 2026 FQ2 Presentation.

    —
    Editor's Note: This is a lightly-edited revision of a question asked by participants in Asymco's May 2026 Office Hours live Q&A sessions, open to Asymco One subscribers.
  5. Why won't Apple become a cloud company?

    Research · 2 comments

    An Office Hours question asked by Fred S., May 1, 2026

    Q: Ever since Johny Srouji started talking about Apple Silicon and the power consumption for the performance and the unified memory, and now we've seen the Mac mini surge, I just wonder about high-end computing. The whole area of where that Mac architecture may go beyond its success as an individual consumer computing product. From all the high-end workloads that might be coming their way.

    The story of Apple is one of personal computing. It's not a story of servers, it's not a story of clouds, it's not a story of centralized computing. They've tried once or twice to make a server product, and they abandoned it. They've even abandoned the high-end Pro product, and created the almost-as-fast Studio product.

    Now, that does not mean they're shying away from high-power computing. They're just saying, we're going to put that high-power computing in a desktop, or in the laptop, or even in the phone. Everyone who's grown up throughout the personal computer era can remember Moore's Law, and how exponential growth has driven computation to levels that seemed impossible just a few years earlier. We've hit some slowdowns, but fundamentally, the potential exists.

    And by the way, it's not even a classic computational CPU problem. We're dealing with AI. We're mostly dealing with high bandwidth, large data, and we're dealing with simple calculations on it in parallel, which means the architecture is much more around large matrix computations. This is why Nvidia came from graphics. Graphics was the same problem — a graphics accelerator is a matrix problem. And so is machine learning. So different variations of these have come in as a sort of a parallel to the CPU, the general computation problem.

    The idea Apple has is that they're going to catch up with whatever is done on the server, they're going to do it on the device. You can call it Edge, you can call it personal — the old term was personal computing.

    I may be naive, but I think we'll get very powerful desktop computers that can do what is essentially AI, but for the individual. The other aspect here is that Apple is a consumer company, not a B2B company — it's a B2C. They want to bring that power to as many people as possible. And they're certainly delivering hundreds of millions of computers a year. Nvidia's making tens of millions of computers a year. Apple is capable of doing orders of magnitude more.

    So I think they're going to affect the disruption in AI. It's not going to be that there's no profit in AI, it'll be that it'll be done with Edge more, especially as it doesn't have to be a world model — it can be a personal model. If you want to look up something globally, you can use the cloud, but if you want to deal with tasks in your world, you're going to work with Apple computers.

    It may take years to get there. But in the meantime, I don't think a centralized service — these OpenAI, or Anthropic, or Microsoft, who are trying to make us a singular superintelligence — is necessary for everyone. It'll be a good reference, but it's not how you want to handle your personal information. So I think that's what the future is, and I think Apple's very much planning for it.

    It sounds cliche, but when Apple started, it was IBM that dominated computing. And IBM was about centralized computing, and their thesis was everything we now call "the cloud" — but it was all in one big computer that served the entire organization, whether that organization is a government or a big company. And then we went to mini computers, then we went to desktop computers, then we went to portable computers.

    Then, fast forward 25 years and we had Google. Well, now central computing is the internet. In the internet, everything needs to be indexed to be able to be found. So they created an index in the cloud. And then a lot of companies moved that computing they used to have locally into the cloud, as a shared resource from Amazon, AWS, and others, and that became cloud compute. Even now, those are the drivers for growth for Microsoft and Amazon and Google.

    The AI part of that is tiny — there's revenue from AI, but there's a lot of revenue from cloud. That still is valuable. But that's not a job for consumers. You do some things in the cloud — you store things, you search, you communicate in messages and so on. But most of the data that matters to you will get also indexed locally, so you can pull up your photos, pull up these things, and it'll be a blend of the two.

    So that's where Apple lives, and I don't see anything fundamentally changing about this, because computation tends to commoditize. Software tends to be replicated. Algorithms tend to be replicated. In fact, even the AIs we have today were all because people publish papers, and one company invents it, another implements it, as was the case with the transformer. As far as I understand, it was Google who actually wrote the paper on it.


    Editor's Note: This was one of the questions asked by the participants in Asymco's May 2026 Office Hours live Q&A sessions, open to Asymco One subscribers.
  6. Big shoes to fill: will the haters spare John Ternus?

    Research · 1 comment

    An Office Hours question by J.P. answered on May 3, 2026.

    Q: With the ascension of John Ternus becoming the new CEO -- will it lower the criticism from the perennial Apple haters and critics?

    No, no, of course not. Of course not, come on. You should know better than this. If anything, it'll amplify.

    I wrote a piece about this. Titled, "John Ternus will have left big shoes to fill." This is his epitaph. This would be when, in 2040, he'll retire, and this is the article that will get written then. And the criticisms he will have faced will be the same.

    We mustn't forget that when Steve was around and was the CEO, the amount of abuse he got was worse, in my opinion, than what Tim got. The criticisms of his incompetence, of his lack of ethics, morals, and overall bad decision-making were legend. I think he was accused of criminal behavior, even.

    So we tend to forgive and give peace to the deceased. But while they're alive they will be skewered. I think John will be as criticized as any [Apple] CEO. And you can use your imagination for the reasons and all the failures and all the bad, all the things he'll miss, all the things he'll do wrong, all the incompetence. That he doesn't know how to run anything. It's time for a change. Inevitable.

    —
    Editor's Note: This is a lightly-edited question by an Asymco One participant answered during our May 2026 Office Hours live Q&A sessions.

  7. Asymco Bulletin 011 - May 3, 2026

    Bulletin

    Asymco Bulletin is a digest of all the work we have published for the week ending May 3, 2026.

    Editor's Note: Starting next week, we will be sending Asymco Bulletin to Asymco One subscribers only. You will still receive Updates when new posts are published per your notification settings.

    Office Hours

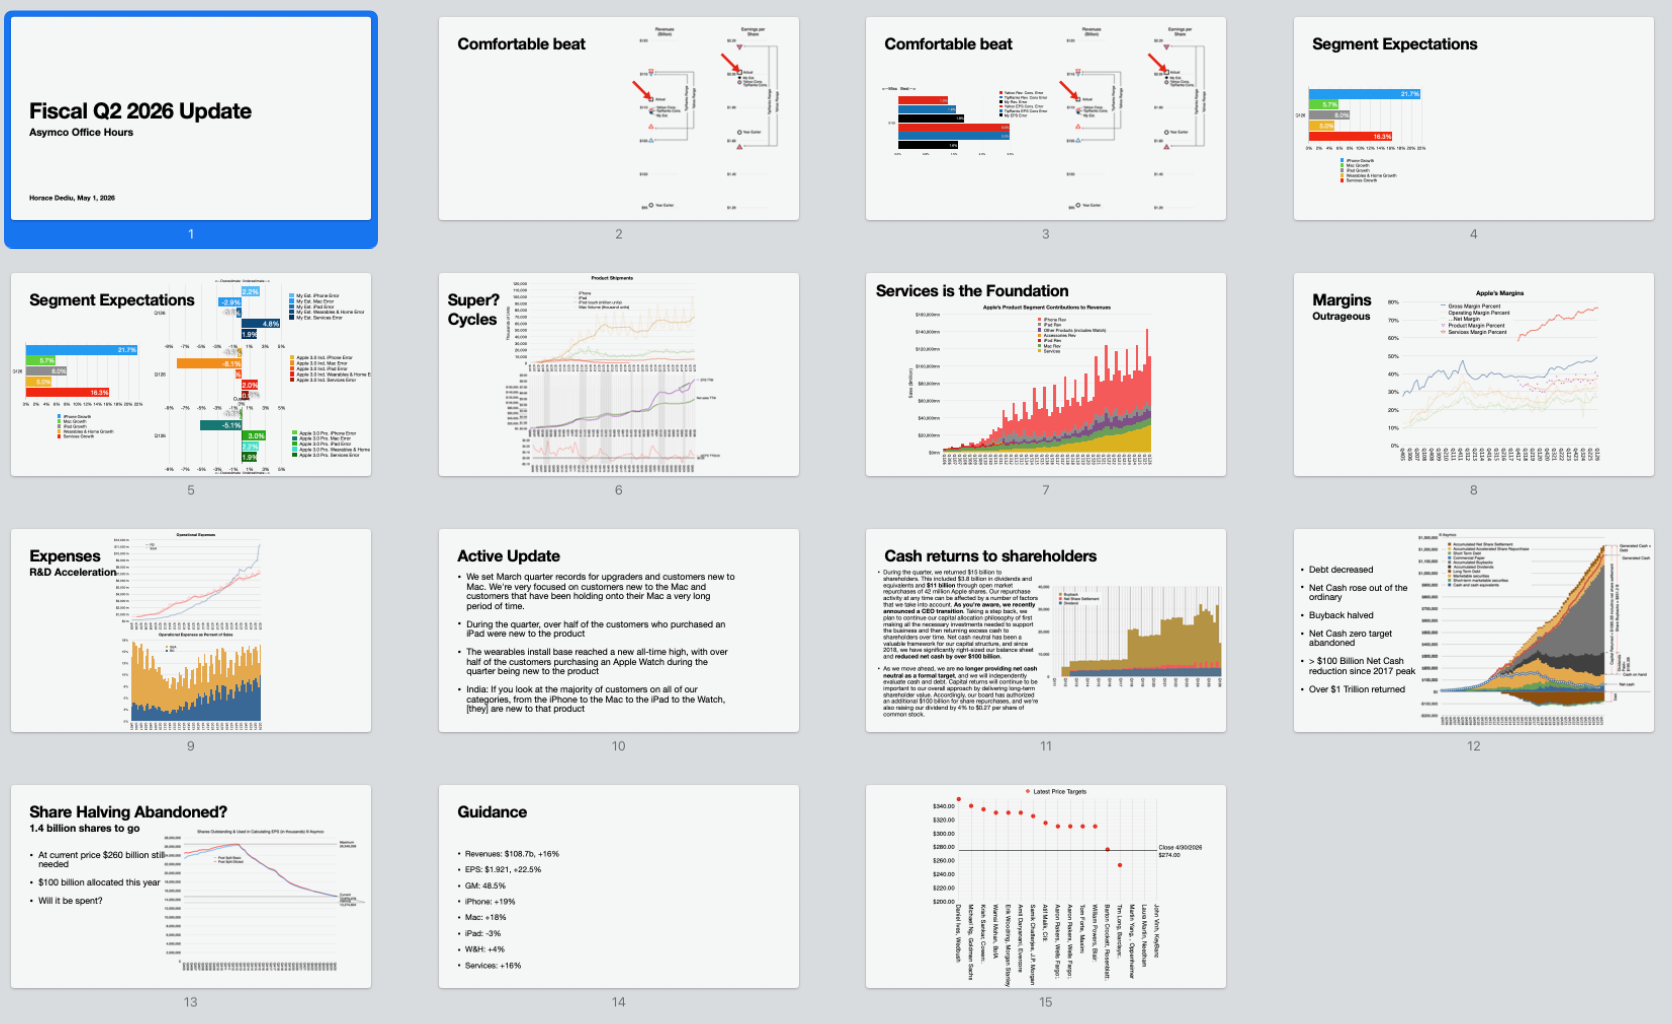
    Asymco Office Hours — Apple Fiscal Second Quarter 2026 Review: The Presentation

    Apple FQ2 2026 Earnings Review

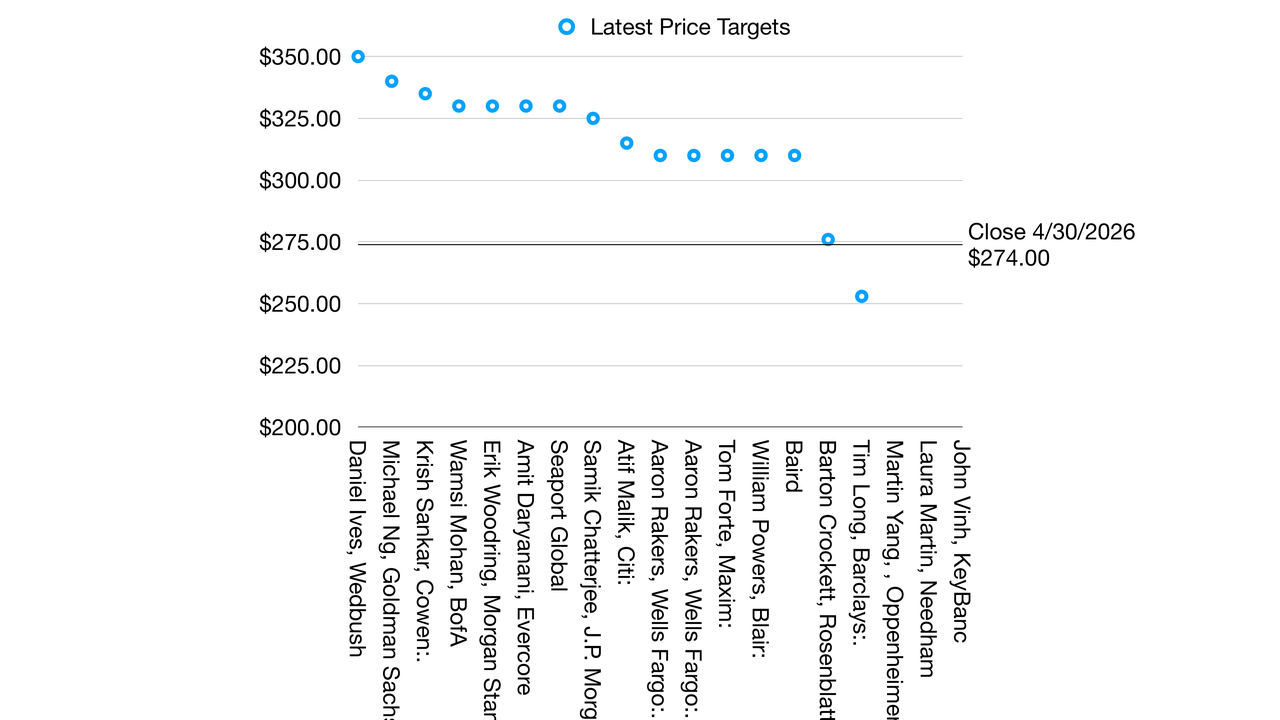
    In Asymco One's May 1, 2026 Office Hours session, review of Apple's Q2 2026 earnings, segment growth: iPhone at 22%, Services at 16%, iPad at 8%, Mac at 5.7%, and wearables at 5%. Steady, foundational growth of Services, Gross margins reached nearly 50%, R&D spending surged, a shift in Apple's capital return strategy showing perhaps the hand of John Ternus. Guidance suggests 16% revenue growth, 22% EPS growth. Analyst sentiment turned positive post-earnings, with most price targets rising above $310. Apple's evolving identity as an engineering-centric company was the focus of many questions. →

    Research

    Expectations for the Quarter

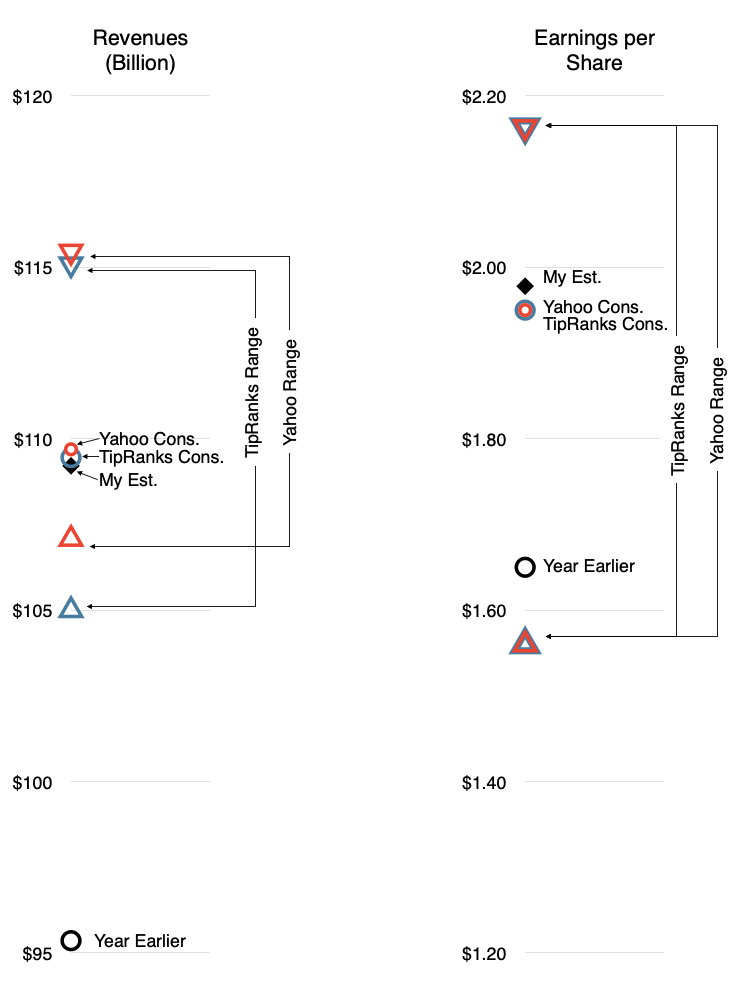
    Revenue and EPS consensus, year-ago results and my expectations Yahoo Finance Yahoo Finance’s revenue estimate for Apple in Q2 stems from 31 analysts. As of April 25, the average estimate is $109.69 billion, with a low of $107.08 billion and a high of $115.37 billion. For the earnings per share estimate, 32 analysts put it at an average of $1.95. The low is $1.56 and the high is $2.16. TipRanks TipRanks also does its own analyst polling on Apple’s quarter. In its forecast as of April 19, its consensus is for a revenue of $109.45 billion, with a high of →

    UBS Raises Price Target from $280 to $287 but Maintains Neutral Rating

    Nota Bene

    The Economist Interview: Hints at the future direction of the company → As is often the case, a 45 minute discussion turns into two sentences. The article sadly does not provide hints at the future direction of the company. But we can…

    TD Cowen: 15% revenue growth, 10% growth guidance → Apple is projected to gain market share in both smartphones and PCs, driven by strong iPhone 17 demand and the new MacBook Neo, with anticipated revenue growth of over 15% in Q3 and positive sentiment ahead of earnings.

    UBS Raises Price Target from $280 to $287 but Maintains Neutral Rating → Apple's fiscal Q2 shows promise with iPhone strength and solid Mac demand, especially for the budget-friendly Neo and AI-capable Mac mini, potentially boosting earnings beyond expectations.

    Morgan Stanley forecasts fiscal second-quarter EPS of $1.74 → Despite memory pricing pressures, Apple's strong iPhone sales, potential AI and foldable iPhone announcements, solid free cash flow, and favorable market conditions position it for better-than-expected earnings and a possible stock rise to $300 by September.

    Is Apple borrowing Samsung’s Market Expansion Strategy? → Bernstein SocGen maintains optimism on Apple's strategic pricing and ecosystem strength, forecasting EPS growth and potential market share gains, while Samsung faces smartphone profit challenges but thrives in memory.

    Separately, it’s been reported that Samsung might see its first operation loss from its phone division, resulting in Apple capturing 100% (or more) of global smartphone profits. Simultaneously, Samsung is seeing huge profit gains from memory, even overtaking Nvidia’s profitability. This is remarkable…

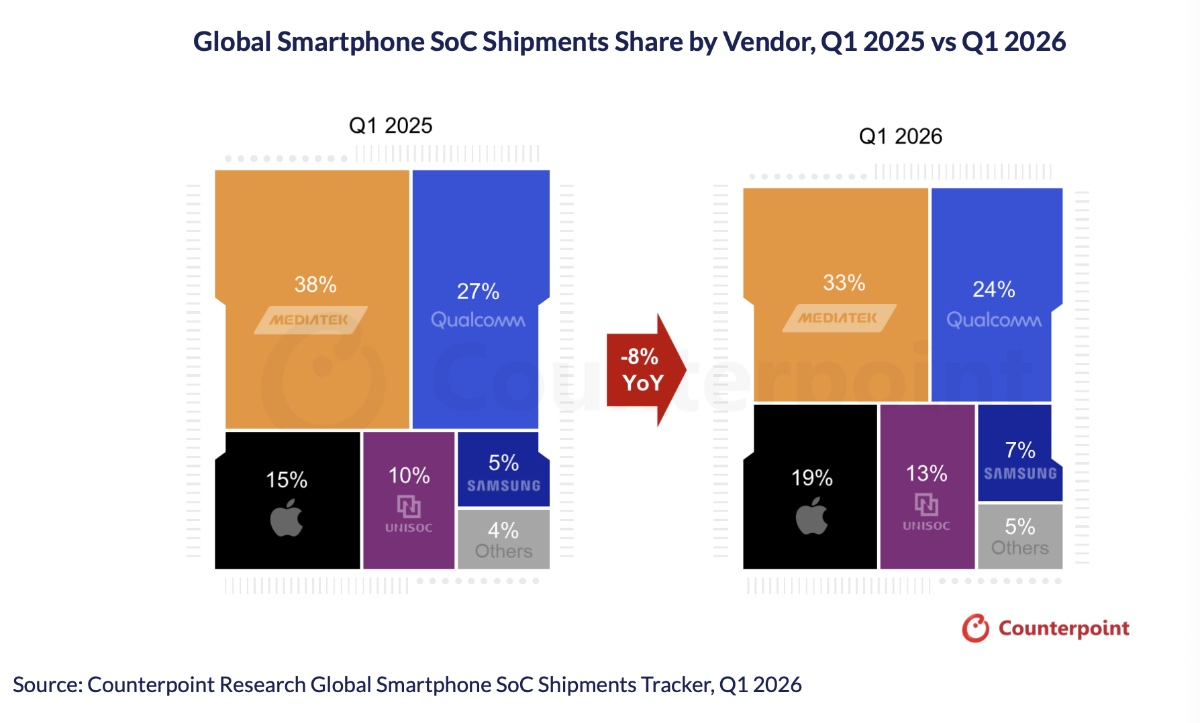
    Apple share of the smartphone SoC market grew from 15% to 19% in Q1 → In Q1 2026, global smartphone SoC shipments fell 8%, but Apple thrived in the premium market by leveraging its efficient supply chain and passing costs to consumers, boosting its market share from 15% to 19%.

    Google to sell TPU chips as Gemini shows returns → Why pour cash into Nvidia when you can craft your own cutting-edge chips like Google, and then turn that innovation into a lucrative side hustle by selling them to tech giants like Meta and Anthropic?

    The Vision Products Group Expanding → Gurman's 2025 dissolution claim clashes with 2026's active Vision Products Group hiring spree. The Vision Products Group posted 14 new senior roles last week.


    Asymco One gives you full access to our research, analysis, and commentary. Subscribe with code BULLETIN for a discount.

    Feedback: Have questions or comments? Reach out to us at contact@asymco.com. We’d love to hear from you.

  8. The Vision Products Group Expanding

    Nota Bene · 3 comments

    Mark Gurman claims Apple dissolved the Vision Products Group in 2025, but that contradicts the fact that this group is still active and hiring new employees as of April 27 2026. Mark Gurman is pretty much the main source of all reports regarding the vision pro apart from supply source analysi...

    Source: Reddit r/apple via Reddit r/VisionPro

    NB: The Vision Products Group posted 14 new senior roles last week.

    The Vision Products Group is hiring for multiple senior-level software engineering positions across cutting-edge areas — Al, augmented and virtual reality, and more! These roles offer the chance to work on innovative products that will impact billions of users.

    Maybe it's time to introduce the Anti-Gurman index: Buy each dip induced by a Gurman leak dump.


  9. Google to sell TPU chips as Gemini shows returns

    Nota Bene · 2 comments

    Why give all your cash to Nvidia? Why not make your own chips? Then why not sell them?

    Google said that it plans to sell its custom Tensor Processing Units (TPUs) to select customers who will install the chips in their own data centers.

    The move is a change from Google’s prior strategy, which saw it rent out TPU capacity to customers from its own data centers — and is yet another strike at AI chip king Nvidia.

    The announcement, during the company’s Q1 earnings call, comes a week after Alphabet announced two new TPUs: its TPU 8t for AI training and TPU 8i for inferencing.

    Alphabet didn’t disclose potential customers, but it signed a multiple-gigawatt agreement for next-generation TPUs with Anthropic earlier this month, with chips expected to begin coming online in 2027.

    And according to The Information, Alphabet has also entered into a multibillion-dollar chip deal with Meta (META).

    Source: Yahoo Finance

    NB: Alphabet Q1 sales grew 22% to $110 billion, with Cloud up 63% to $20 billion. Operating margins grew by 220 basis points, with services and cloud operating margins both increasing y/y.

    The search business continues to benefit from AI. AI overviews and AI mode are sustaining as search sales grew 19%.

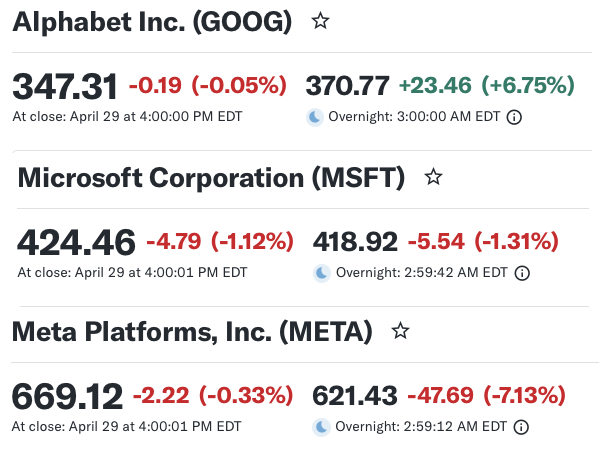
    A year ago, Google was trading as if it had lost the artificial intelligence race. Shares are up 6.8% after-hours to all-time high even after growing 114% from a year ago.

    Though Google is considered an Apple competitor, the reality is that the two companies are very much in a partnership with Google's payments to Apple being treated as "advertising" revenues (part of Services). The relationship is being expanded with the Gemini deal.

    In many ways Apple has effective equity in Google and Google is demonstrating how sustaining AI is to its core business. That sustenance is transitive to Apple.

    Moreover, as Google's TPU strategy puts them in direct competition with Nvidia, it exposes the age-old adage that "there is no shortage that is not followed by a glut".

    Amazon is also offering up its own chips to customers and Apple is developing its own AI chips.

    In his annual shareholder letter, Amazon CEO Andy Jassy said that the company’s chip business, which includes its Graviton, Trainium, and Nitro processors, has an annual revenue run rate of greater than $20 billion.

    When Apple ships the inevitable edge AI silicon in a billion devices, the democratization of AI compute will dawn. Remarkably, some can see the dawn already at sunset.


  10. Apple share of the smartphone SoC market grew from 15% to 19% in Q1

    Nota Bene

    Supply disruptions strengthen the strongest

    Global smartphone system-on-a-chip (SoC) shipments declined 8% year-over-year (YoY) in quarter one (Q1) of 2026, according to Counterpoint Research’s latest Global Smartphone SoC Shipments Preliminary View report. However, it’s good news for Apple.

    Counterpoint says the premium segment has remained relatively resilient, with higher costs largely passed on to end consumers. Meanwhile, the entry-level manufacturers are increasingly adopting lower-cost chipsets to keep smartphone prices competitive.

    Qualcomm and MediaTek recorded double-digit declines in shipments. In contrast, Apple, Samsung, Google and UNISOC posted positive growth.

    Apple saw its share of the global smartphone SoC market grow from 15% in the first quarter of 2025 to 19% in the first quarter of 2026. Some explanation: A smartphone SoC (System-on-a-Chip) is a single, integrated chip that combines all essential computing components—CPU, GPU, memory, and connectivity modems (5G/Wi-Fi)—into one unit.

    Apple silicon is a series of proprietary, ARM-based systems-on-a-chip (SoCs) designed by Apple for its ecosystem, providing high-performance computing through a unified memory architecture and specialized components. They power iPhones (A-series), Macs (M-series), iPads, and wearables (S-series), focusing on superior power efficiency and security.

    Source: Apple World Today

    NB: Counterpoint Senior Analyst Shivani Parashar says that their integrated supply chains helped …

    …Apple, Samsung and Google to better mitigate the impact of the ongoing memory crunch. Supply crunches affect the smaller more than the stronger. It always surprises me when the reactions to such events (such as Covid disruptions) suggest negative impact on Apple, the strongest of the market leaders.

  11. Is Apple borrowing Samsung's Market Expansion Strategy?

    Nota Bene · 1 comment

    On March 18, 2026, Bernstein SocGen Group reaffirmed its “Outperform” rating and $340 price target for Apple Inc.

    Comparing it to Samsung’s 2009–2013 strategy, which saw Samsung increase its global smartphone share from 4% to 32% in Q3 2013, Bernstein emphasized Apple Inc.’s recent product launches as a strategy to widen portfolio price bands, driving share gains at the low end while raising prices at the high end to maintain margins. Although Samsung eventually lost market share to Chinese manufacturers, the firm said the stickiness of Apple’s iOS ecosystem will help it sustain long-term market share.

    Bernstein projected a 12% increase in fiscal 2027 EPS from share gains, split equally between hardware and services, assuming Apple Inc. captures 10% of Chinese manufacturers’ smartphone market share amid their supply issues. Some noteworthy product developments include the introduction of the $549 AirPods Max 2, the App Store cost reduction in China from 30% to 25%, and plans for a foldable iPhone.

    Source: Yahoo Finance

    NB: Separately, it's been reported that Samsung might see its first operation loss from its phone division, resulting in Apple capturing 100% (or more) of global smartphone profits. Simultaneously, Samsung is seeing huge profit gains from memory, even overtaking Nvidia's profitability. This is remarkable…

    Samsung seeing windfall profits from a memory shortage but a contraction from its phones suggests a migration of value in the value chain. AI has effectively pushed profit "down" the stack from device/OS to components, and perhaps up also to services.

    Apple has over the years invested down the stack to Silicon and up the stack to Services. What a surprise! The commentariat has not quite grasped this but has already jumped to conclusions that Apple is getting squeezed from supply chain and AI.

    The future however is not so sweet for either components or AI-as-a-service. There has never been a shortage that was not followed by a glut. The semiconductor business is known for this boom/bust cycle and this time it's not different. Unless AI conquers distribution, privacy, experiences and understanding & mastery of jobs-to-be-done while preventing commoditization through replication and scale economies of compute, there will not be a break-out new business model. There is no clear reason why Apple won't figure out any of the unknowns while preserving an ecosystem advantage.

    Samsung has the same challenge they've always had: how to create its own ecosystem and control over its future via its own platforms.