When it thinks about customer convenience, Walmart waits 12 years.
When we think about convenience, we think about a lot of things, but making shopping feel simpler and more seamless from start to finish is a big part. And one of the moments where that matters most is at checkout.
Beginning Aug. 24, we will be adding Tap to Pay to our payment options at select Walmart stores and Sam’s Club locations, with plans to roll it out to all U.S. stores and clubs by the end of 2026 and to fuel stations by mid-2027.
My expectation six years ago was that Apple Pay would be a “$1 billion business” by 2020. This was based on a take rate of 15 basis points ($15/$10,000 in transactional value). Juniper Research, which regularly examines payment transaction markets, now expects that Apple will see global Apple Pay transactions of $686 billion by 2024.
At that 15 basis point rate it amounts to $1.03 billion. Thus this particular research suggests that I was off by 4 years, making the $1 billion pay day a 10 year target rather than six.
What's the state of Apple Pay today?
According to various sources, Apple Pay handled $7.6 trillion in transactions in 2025. From that, Apple Pay generated an estimated $5.6 billion in revenue in 2025. ($7.4/$10,000 or 7.4 bp, half of the take rate in 2014) This is a significant increase from $6 trillion in transactions estimated in 2022. My estimate of $1 billion in 2020 seems to have been conservative.
Apple Pay’s user base has surpassed 818 million in 2025. This represents a significant increase from 2022's 507 million users. 65.6 million were users in the US.
Projections are that the user count will climb to 87.5 million users in the US by the end of 2026. Surveys suggest that over 22% of the US population aged 14 and older uses Apple Pay daily.
The service now handles about 10% of all global card transactions, doubling its share from a few years ago. In the US, Apple Pay accounts for roughly 5.6% of all retail sales, including both in-store and digital channels. In the US alone, Apple Pay is expected to facilitate $2.9 trillion in payments, accounting for 32% of all contactless point-of-sale activity. Apple Pay has a 49% mobile payment market share in the US as of 2025. This is double the share of second placed Google Pay.
Notably, 62% of Apple Pay users live in households with an annual income above $100,000.
94% of US retail establishments accept Apple Pay in 2026. This number has reached near-ubiquity in the US, up from 85% in previous years. With WalMart's 12 year delayed acceptance the total will reach even higher. Globally, the service is now available in 95 countries.
Apple now processes more than 14.2% of all online consumer payments. This share is growing rapidly.
As of 2026, more than 11,000 banks worldwide supported Apple Pay. The number doubled from 5,480 in 2020.
Apple Pay accounts for 54% of all US in-store mobile wallet transactions. Apple is dominating this market, with Google Pay and PayPal at around 13% each. 71% of Gen Z mobile wallet users in the US choose Apple Pay first and consider digital wallet as primary payment option. Gen Z currently has an 8.8% usage rate among the total US population, compared to 4% for Millennials and 1.1% for Gen X.
Over $1 billion in fraud was eliminated globally through Apple Pay in 2025.
Why Walmart could not …
accept this reality for 12 years speaks to a peculiar myopia probably rooted in an outdated strategic vision of cost minimization.
Regardless of this, the irony of citing customer convenience as a factor in the decision does not address why it took 12 years of customer punishment to come to the conclusion that what they can't measure (satisfaction) trumps what they can measure (6.4 basis points of take rate.)
I'm sure it wasn't the calculus of customer satisfaction that changed their mind but rather the litany of statistics cited above that suggest they missed out on a behavioral trend and thus incurred loss in brand value.
In 2004, a frenzy spread across Harvard Yard in days. Four billion users later, we are only just catching up.
Harvard itself had planned to publish a college-wide digital version of a student registry along the lines of The Freshman Register, the physical book handed out to all first-year students, who traditionally used it to scour each other’s high school photos for the purposes of icebreaking and dating potential. (“The Face Book” was the informal name for that book on campus.)
[…]
on the first day, 650 users logged on; two weeks later, it was 4,300, including a few alumni and even fewer faculty members. A month later, Thefacebook had spread to other, carefully chosen, colleges—Columbia, Stanford, and Yale—and had signed up 10,000 people. Harvard’s users alone had viewed individual profiles 1.5 million times in less than a month, at a time when profile viewing was still the main activity.
Social Media has grown to be one of the primary activities consuming the most time on all devices, Apple's included. A majority of news, entertainment and communications has moved to these products and therefore their impact on how advertising and content are created has been permanently altered. Social Media takes up the largest share of total screen time. Instagram, TikTok, Facebook: 3+ hours. WhatsApp, Messages, Telegram: 2+ hours. YouTube, Netflix, Amazon Prime: 2 hours. Thus, if we include short video and messaging, social media could take more than 4 hours per day for the average user.
However, after a mere 22 years it seems that the thesis of Social Media has all but disappeared. It's no longer "Social" but rather "Algorithmic" Media. As conceived, the content seen by social media users was generated by other users--it was peer-to-peer. Driven by curiosity about social cohorts, initially classmates, later friends and family and, later still, semi-professional creators.
Today what one sees on social media rarely includes content from friends, family, classmates, or even the people you chose to follow. This transition been hard to notice mainly because the changed come gradually and subtly, but considering how people use the products, it began to change already more than seven years ago, with TikTok.
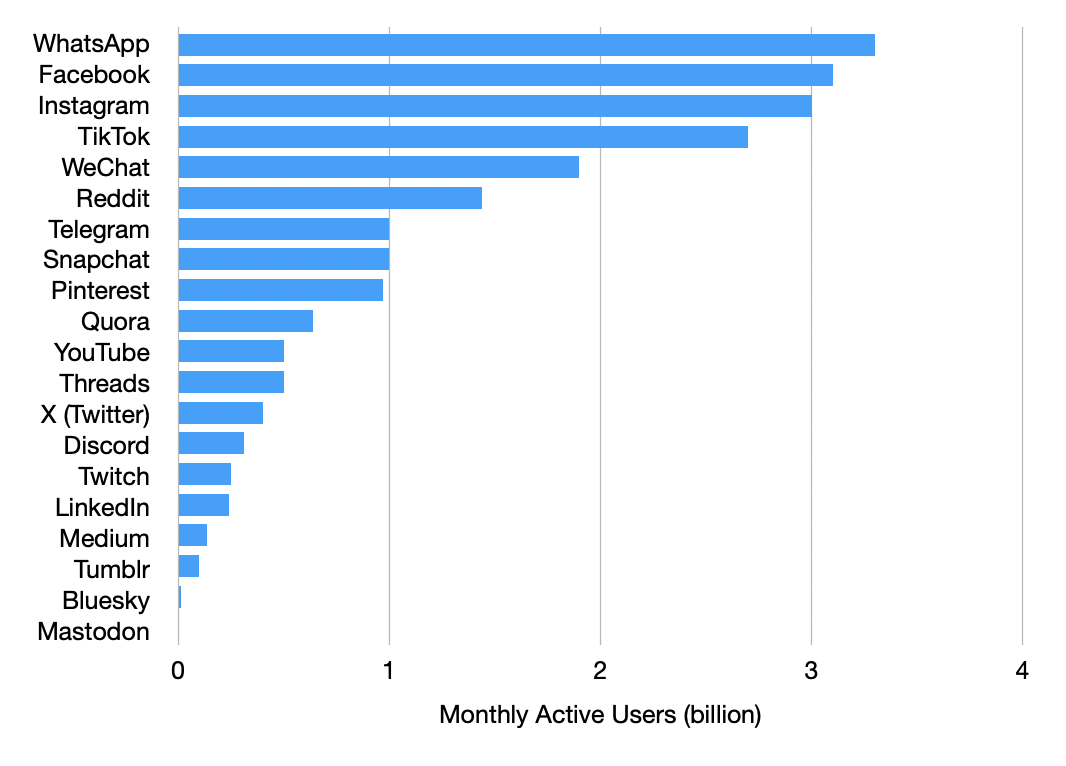
At first glance, social media seems stronger than ever. There are 22 billion active accounts across the top 20 "platforms"1. The ranking is shown below.
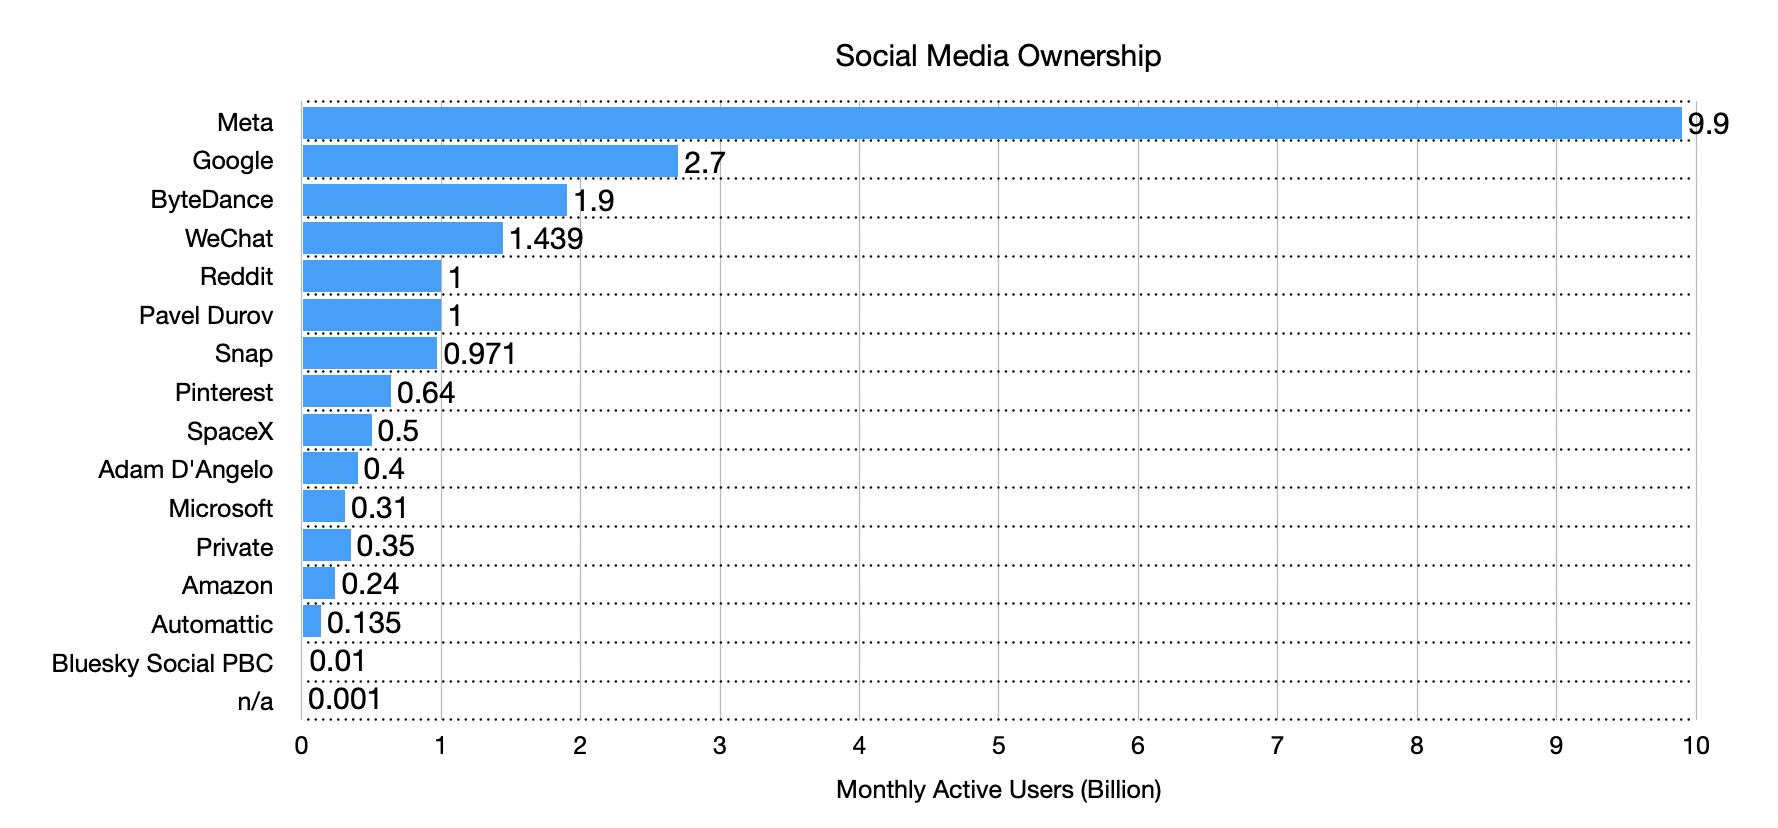
Ownership of these platforms is not self-evident so I also combined them into this chart.
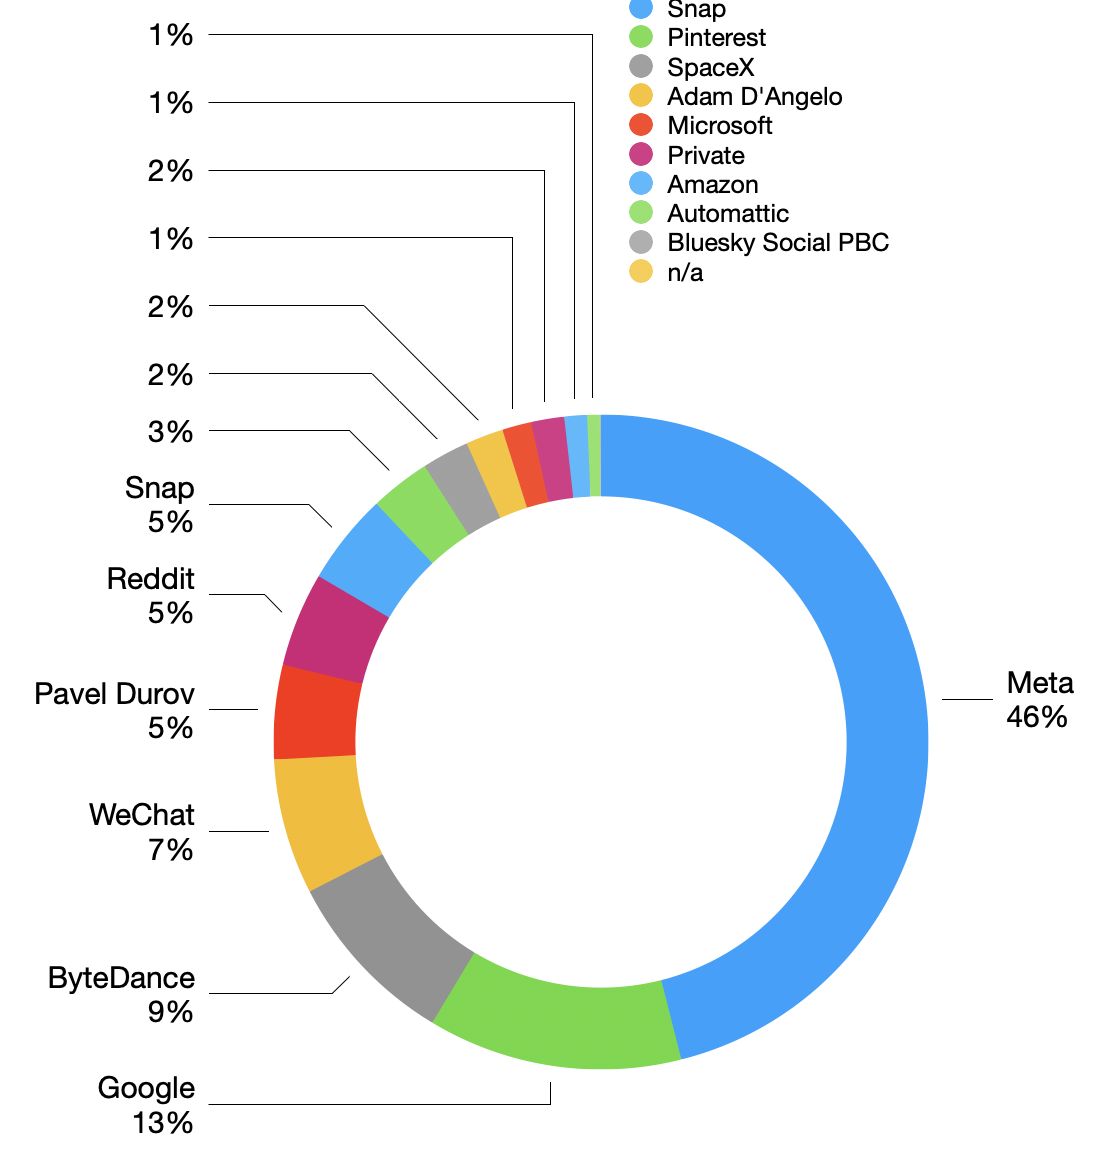
Meta holds about half of the monthly active user account (MAUs). The other interests are, roughly, Google, China (ByteDance and WeChat), modest-sized public companies, private companies and even individuals. Some non-profit or decentralized organizations also bring up the rear.
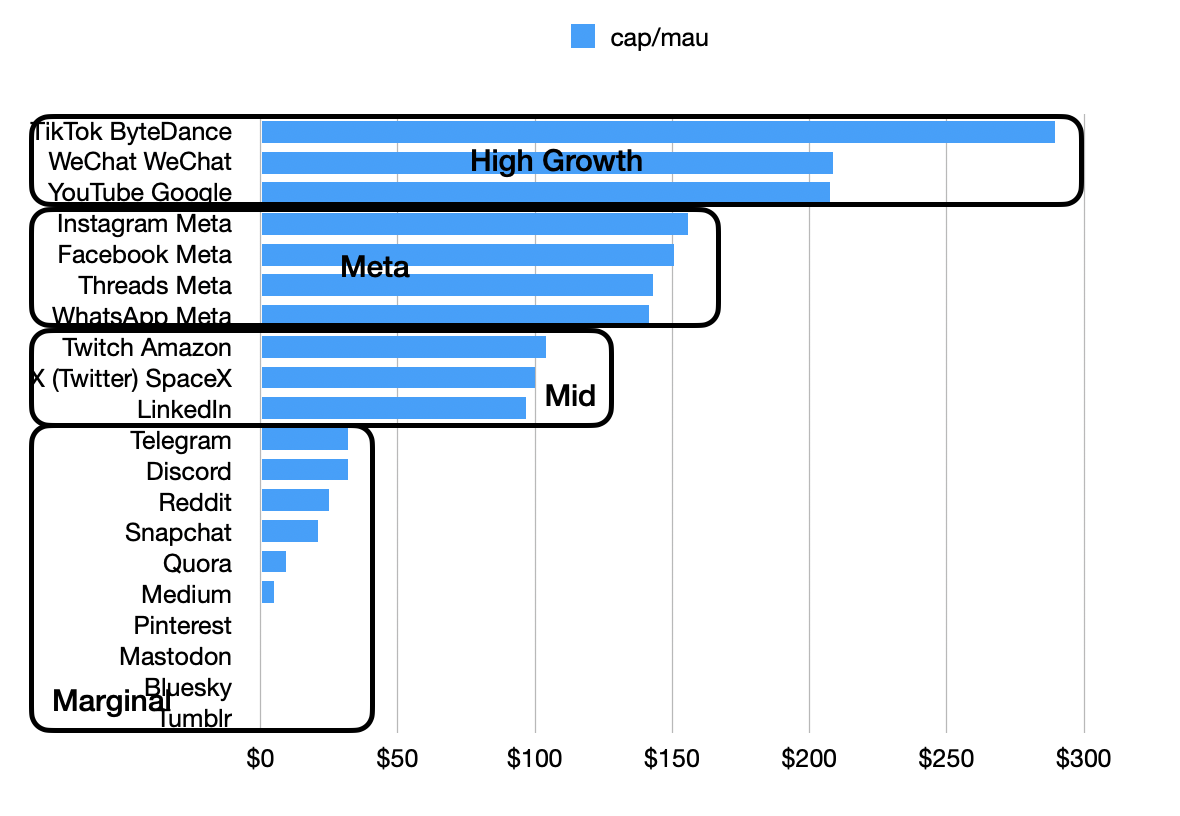
If taking a market value point of view (market capitalization per MAU) the clusters show up as follows:
A MAU is worth between $100 and $250 in net present value. Notable outliers are TikTok at $300/MAU on the upper end and the marginal players shown at below $50/MAU. The main difference in value seems to be the rate of growth.
Meta however is a good proxy for the entire space. Not just because it was the "OG" or first mainstream success with Facebook but also because it has morphed itself through acquisitions and replication to get onto the trends that resonate. Messaging (buying WhatsApp), photos (copying Snap with Instagram), short video (replicating TikTok), and Threads (replicating short text Twitter) are all invented elsewhere.
Thus observing Meta, one can't help but see how the "media" usage has shifted. It's anecdotal but one hears that Facebook demographics aged in North America and Europe, but still young in much of South Asia and Africa. FB is seen as "best for B2C with mature audiences, local businesses, and ad spend (Facebook Ads remain one of the most sophisticated targeting platforms anywhere). Organic reach for pages is low, but the platform's reach for paid distribution is unmatched."
Meanwhile, Instagram demographics center on millennials and Gen Z with Reels now the primary growth engine. E-commerce integration via Shopping makes it best for "B2C, lifestyle brands, and personal brands with a visual aesthetic."
Threads has grown faster than expected (equaling the usage of Twitter/X after only three years, by leveraging Instagram's social graph.) Its algorithm is still being tuned — chronological-leaning feeds with discovery boosts.
And this is the clue: "the algorithm" determines what people see. It's what creators live and die on. It's what determines virality. This algorithmic distribution has spread to YouTube and back to X, both of which offered, by default, followed content first and "suggestions" only as an option.
Today followers don't matter because users are no longer given what they follow by default. The odds of a follower seeing what a creator posts are insignificant.
This is all in pursuit of "engagement" or screen time. It works. Usage is up, addiction is up and dopamine is up.
However it's also corrosive. For all the new type of scrolling induced, the sense of satisfaction with the medium is dropping. It results in a sense of loss at the end and regret. It exhausts and irritates and preys on what we used to call vices.
More than a decade ago I posited that each social media is positioned on one of the seven deadly sins. In the standard list, the seven deadly sins according to the Catholic Church are pride, envy, wrath, gluttony, lust, sloth, and greed. Which media went with which sin is left as a fun exercise.
It was a tongue-in-cheek post but over time it became reality. The media seemed to be designed to "trigger" rather than inform or relax the user. Even if not intentional, an algorithm "learns" that negative emotions are more valuable than positive. This is a biological necessity: threats are more important than comforts and we evolved to pay more attention to them.
I believe that as the rush to maximally trigger users, the corrosion will ultimately undermine the businesses.
For this reason Meta is finding itself is a difficult business proposition. The ads are working but the audience is exhausted and the regulators and lawsuits keep pouncing. Meta today trades at a P/E of 20 and a 50% return over five years (compare with e.g. Google at 144% or Apple at 110%).
What comes next?
The algorithm is likely to move beyond heuristics. If we look at the methods uses so far, starting with TikTok, it seems that the rules were very basic: dwell time, categorization, engagement triggers such as like, comment and subscribe indicate what the user likes. Provide more and more of the signals that resonate. These were the result of trials and errors with a simple optimization in mind.
This is a slippery slope to a glut of stimulus.
The way this overshoots is with AI. More and more study of what people respond to leads to a perfect picture of the person's psyche. But there lies the problem. This is the formulation of narcotics and how they create undesirable dependencies.
It may be all right to addict billions of people but it does not last. Addiction with no lasting benefit will ultimately be regulated. This happened with alcohol and tobacco and other narcotics. Society realizes that these are to be managed if not banned. People recognize that they are being manipulated and turn to some form of authority to help them from themselves.
The future of the misnamed social media may be that it becomes treated as a controlled substance. The tobacco of the current century. It has so far evolved too rapidly to be controlled but attempts to do so will continue.
Turbocharging it with AI will not convince us that it is becoming more beneficial but rather the opposite.
The evidence of this aversion to the model is shown in the valuation of the companies involved. They are starting to reek of malfeasance and are not particularly desirable by capital.
I use the term loosely since, as Bill Gates once pointed out, a platform isn't valid unless the participants "on top" of it make more profits than the platform itself. A social media platform should benefit its content creators more than it benefits itself, perhaps in a 5:1 ratio. That certainly does not seem to be the case for the typical creator platforms. This is in contrast to software platforms such as Windows and iOS where there is more economic activity that is created and not even touched by the platform.
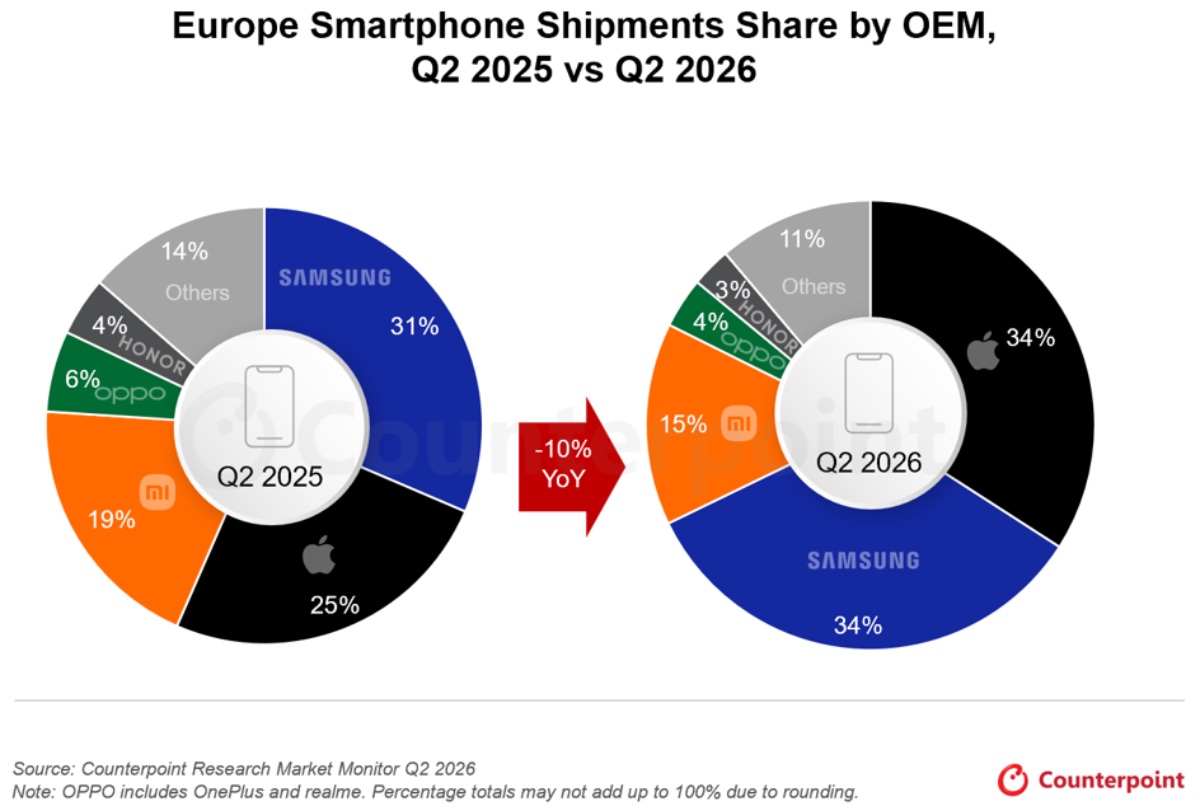
As the market shrinks, Apple now has 34% of Europe’s smartphone market
Europe’s smartphone market took a further tumble in quarter two (Q2) of 2026 with shipments falling 10% year-over-year (YoY) to 35 million units, the region’s weakest second-quarter tally in three years, according to Counterpoint Research’s Q2 2026 Smartphone Market Monitor.
However, it was good news for the iPhone. Apple increased its smartphone market share in Europe to 34% as of the second quarter of 2026. That compares to 31% in the second quarter of 2025.
Apple is tied with Samsung, which also has 34% of Europe’s smartphone market.
“It continues to be a very challenging time for the Europen smartphone market,” Counterpoint Associate Director Jan Stryjak. “An uncertain financial outlook across much of the region means consumers remain hesitant to make discretionary purchases, which is not being helped by the widespread lack of promotions as manufacturers looked to protect margins. In Q2 2026, things were relatively better in Western Europe where a very impressive quarter by Apple and marginal growth by Samsung softened the drop, although Eastern Europe suffered a significant decline as budget segments were squeezed and most Chinese manufacturers struggled.”
NB: This phenomenon is more than one quarter in duration. Counterpoint expect further declines over the next few quarters, especially for lower-end players. Indeed, they expect Apple to outperform the market "for the foreseeable future".
It's still hard to say if the market is permanently affected by this component shortage. Unlike previous perturbations, the effect today might be that it will make the phone industry unattractive to many current incumbents to the point of causing an exit. This would not be the first time.
It seems that Apple and Samsung are the only ones thriving in the market. Samsung benefiting more from the components business than from the complete phone product. As I mentioned in previous dispatches, the market is cracking. Whether is breaks altogether remains uncertain.
One possibility is that 2/3 of the incumbents call it quits and exit but at the same time a new set of entrants wade in. The entrants may see an opportunity with new form factors such as AI-based wearables, though they would be not-quite-a-phone.
Historically we might look back on 2026 as the year that the phone market cracked and the transition to wearable computing took off.
Of course, Apple is energized by this transition because it was never a phone company to begin with.
We are considering an in-real-life Office Hours this fall, either in Boston or the Bay Area, open to Asymco One subscribers. If you would be interested in attending, write to events@asymco.com.
What has servitization ever done for us? Necessity is the mother of invention but return on invested capital is the mother of innovation. Invention is big ideas with unclear benefits. Innovation is big benefits with unclear ideas. This is why inventions are easy to point out but hard to find useful while innovations are very useful but hard to explain. Innovation is a matter of many small changes with big returns. The bigger this ratio between return and change, the more profound the innovation. Moving from selling music on physical media to digital files and then to subscribing to an →
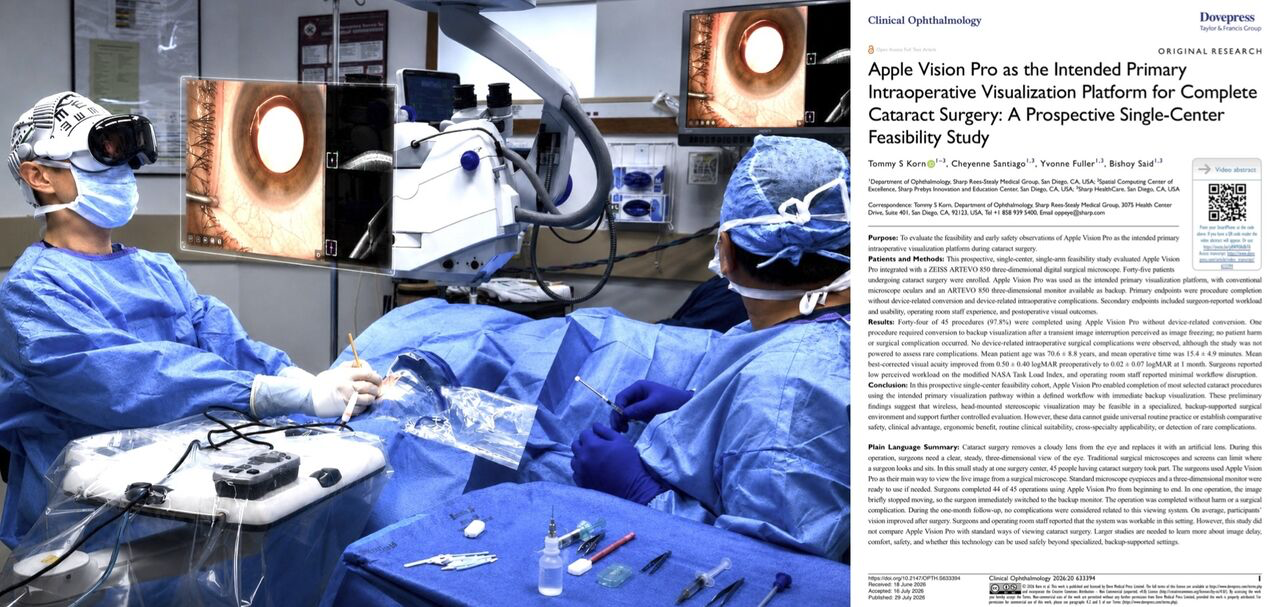
Apple Vision Pro as the Primary Visualization Platform for Cataract Surgery. Dr. Tommy Korn co-authored a new study of the Apple Vision Pro and spatial computing in cataract surgery. It has been peer reviewed and published in Clinical Ophthalmology. I had spent a day shadowing Dr. Korn as he performed a dozen surgeries. It is remarkable that those delicate operations–saving people’s vision–can be assisted so competently by the Apple Vision Pro. Dr. Korn and his team evaluated the 2nd generation Apple Vision Pro (M5) using the ClearSphere app as the primary 3D view for cataract surgery. This surgery replaces the →
A state of the union look at the market for mobiles. Looking at the IDC data on smartphone shipments (2014 to present), the pattern shows a peak in 2017. Covid caused a contraction and recovery but since then the unit market has not reached pre-Covid levels. Moreover, the current memory supply crisis is expected to cause a dip unlike any of the previous ones. IDC expects the market in 2026 to decline double digits and another 1.1% decline in 2027. This may be optimistic. Yearly volumes could drop below 1 billion. The sub-$100 entry-level device tier could become permanently constrained →
Nota Bene
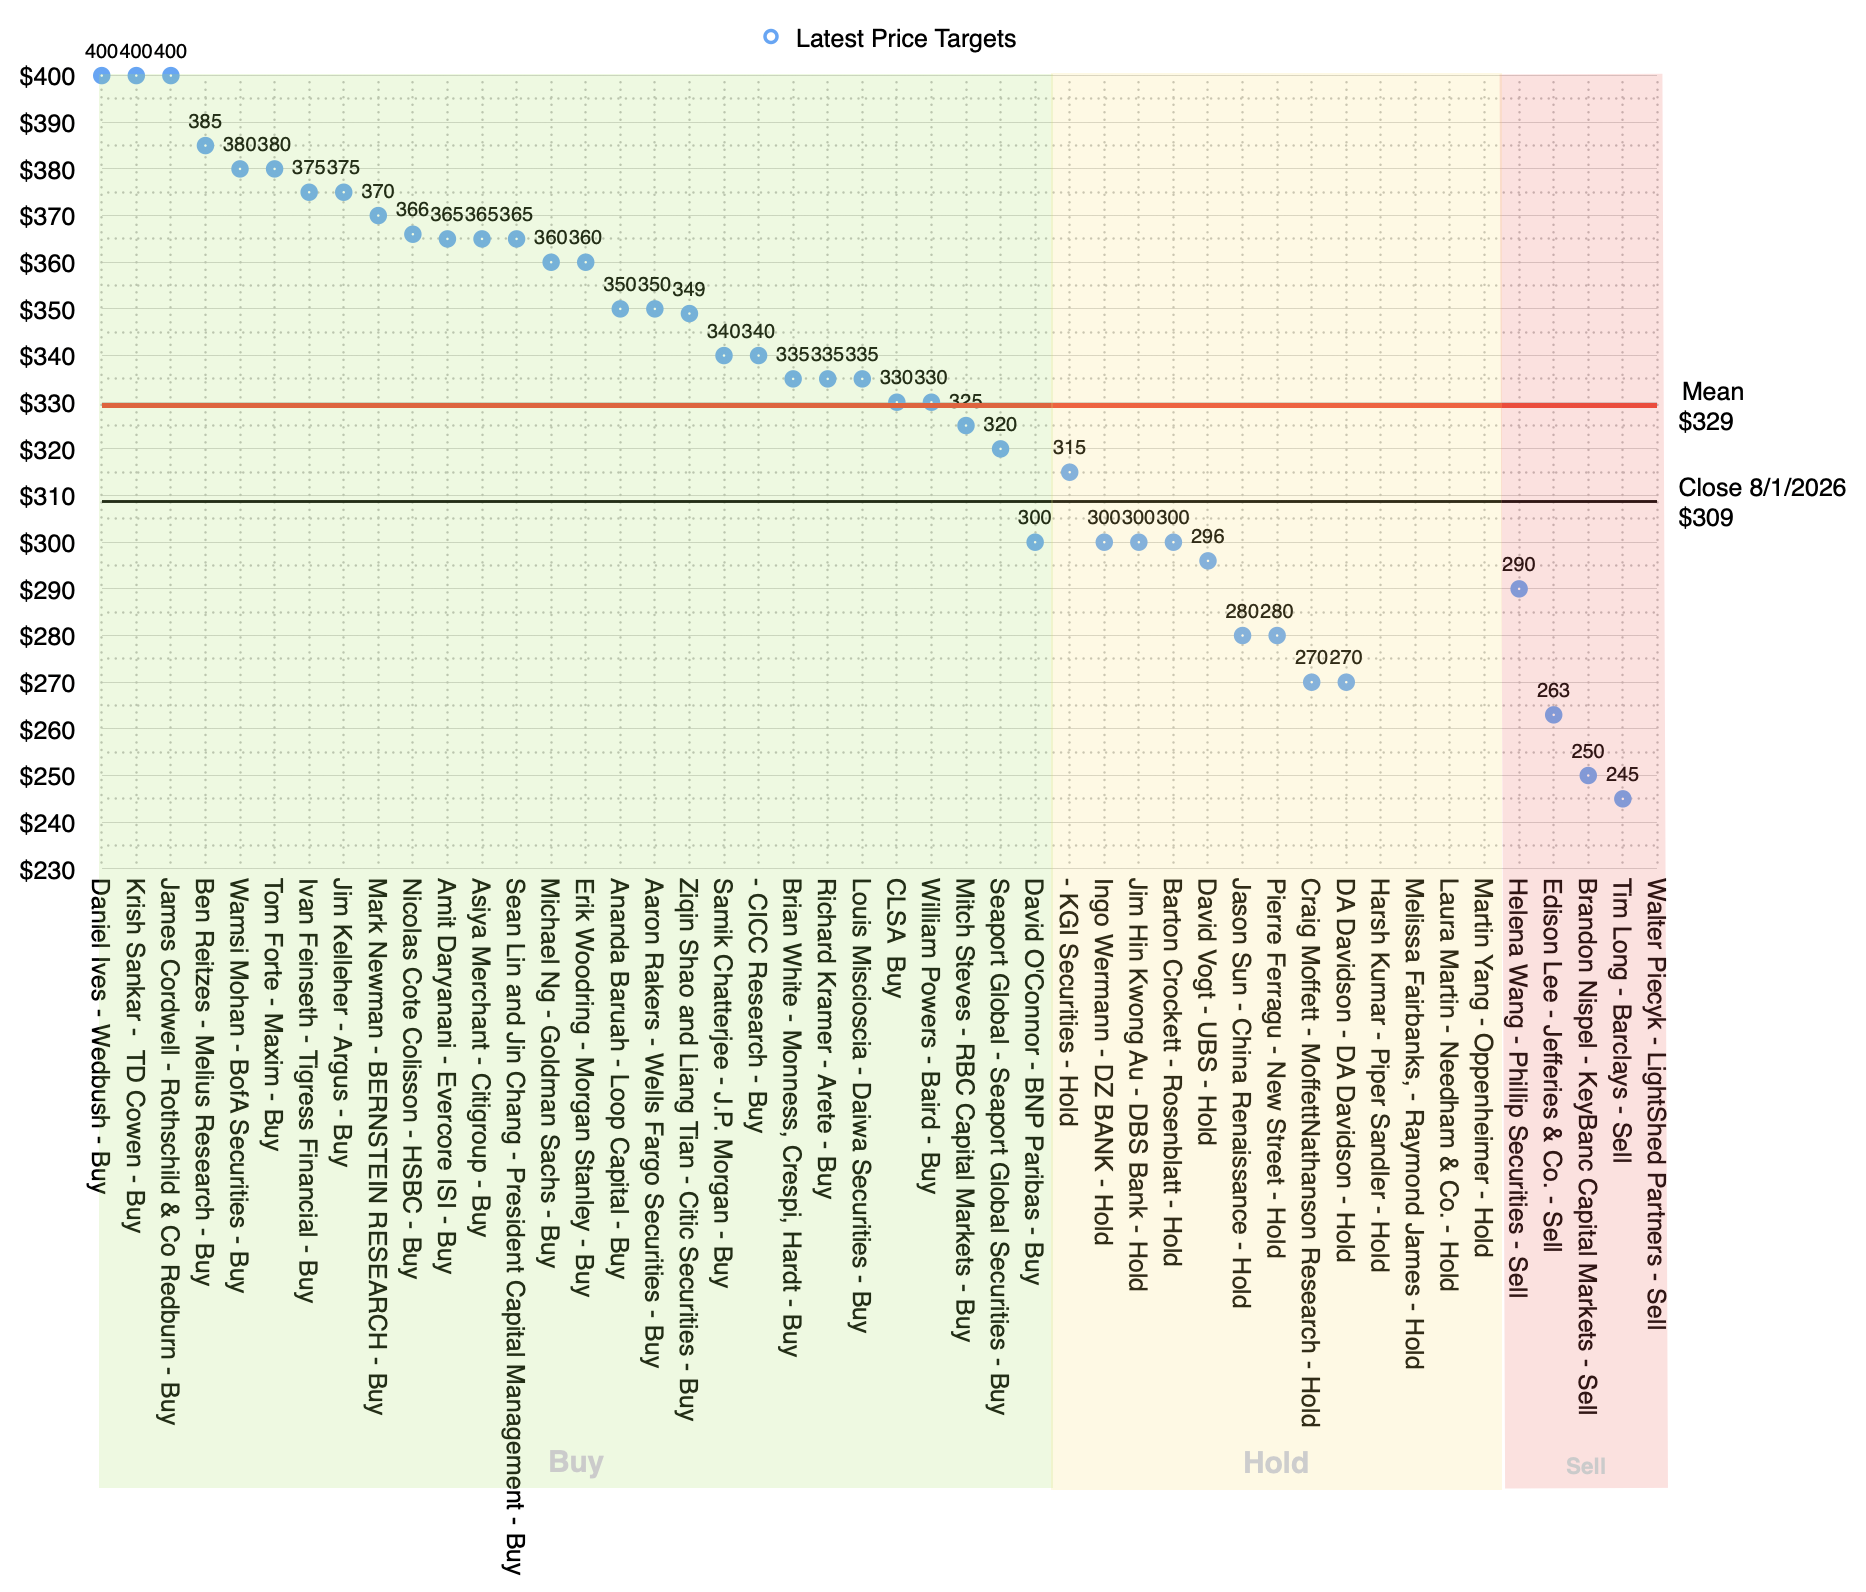
Rothschild & Co. Redburn upgrades Apple to ‘Buy’ from ‘Neutral’ → Redburn moved its target from $260 to $400 on the expectation of an iPhone Ultra at $2,199 lifting lineup ASP by 11% into June 2027. The jump looks dramatic until you notice the prior target was set almost a year ago, in September 2025. Eight other ratings and targets have moved in the two weeks since earnings, in both directions. A large revision mostly measures how long an analyst waited to revise. →
Office Hours
Apple TV: content is still king → Frederick H. asked why Apple is obsessed with making movies and shows. Libraries were being vacuumed up and locked into silos, so Apple chose to build its own from zero rather than buy anyone else's. Quality became the goal because awards are the only measurable proxy left once streaming destroyed ratings and box office. Sony learned this with Betamax and bought a studio for the same reason. If someone else owns the content, they dictate what you are allowed to build to display it. →
Apple and memory chips: a flat no, then a quiet maneuver? → Joseph B. asked whether Apple would buy a memory maker. Memory is a different business with different dynamics and it only works at a scale Apple could not absorb alone, so it does not resonate with them. I expected them to build or buy anyway, and instead they issued a flat public rejection, which surprised me. They will back into it another way, financing someone else, maneuvering, something involving Intel. It would be fitting if Intel became a memory company again, having left memory for CPUs at its origin. →
AI: a technology in search of a job → Bob V. asked how well Apple is pushing back on being late to AI. Reviews of the betas have been positive and the story has played out, but none of that is the point. For consumers, AI is still a technology searching for a job to be done, with real niches that are not consumer niches. ChatGPT is not the answer any more than TCP/IP or the 8088 was, and a chat prompt is a low bandwidth interface, a command line by another name. Emoji generators and image editing are features, not apps, and Siri is a feature too. →
Schulze-Melander expects Apple to launch the iPhone Ultra in September, giving it a new product category to tap while potentially lifting the average selling price of its broader iPhone lineup.
The analyst estimates the device could cost $2,199, or about an 83% premium to the iPhone 17 Pro Max, meaning even relatively modest volumes could have a meaningful impact on Apple's revenue mix.
The firm expects the foldable iPhone to increase Apple's average selling price for the iPhone lineup by 11% by June 2027.
Apple could [also] have [a] revamped artificial intelligence strategy.
NB: This upgrade was from $260 to $400 which seems significant. This might be because the last target that I could find was in September 2025, so almost a year ago. Not sure if anything of note occurred since. But this is not the only change in analyst targets. There have been 8 other changes in ratings and targets in the two weeks since earnings. Four price target cuts, four downgrades, four price target raises and one upgrade…
Aug. 11 Loop Capital Cuts Target to $340 From $350, Keeps Buy Rating
Aug. 11 Daiwa Securities Raises Price Target to $335 From $325, Keeps Outperform
Aug. 10 Jefferies Downgrades to Underperform From Hold, Cuts PT to $263.66 From $285.56
Aug. 6 Citic Securities Raises Raises PT to $349 From $300, Keeps Add Rating
Aug. 4 China Renaissance Downgrades Apple to Hold From Buy, Cuts Price Target to $280 From $329
Aug. 4 CICC Raises Price Target on Apple to $340 From $310, Keeps Outperform Rating
Aug. 3 DZ Bank Downgrades From a Buy to Neutral rating
Aug. 3 Phillip Securities Downgrades Apple to Reduce From Neutral, Cuts PT to $290
The average price target is $329. There are 28 Buy, 13 Hold and 5 Sell ratings. 15 Analysts have not updated ratings in over a year.
Much was made of the Jefferies downgrade which seems to have hinged on a rumor of the cancellation of the iPhone 20(!) The rumor was debunked by three sources within hours but it did not deter coverage of the downgrade and its reason for days after.
The trend apparent is that analysts who previously insisted on counting iPhones have turned to predicting iPhone pricing, thus swinging between "too high" or "too low" reasons for Apple's imminent market failure.
The AI (win/fail, take your pick) drumbeat still attracts attention but overall it seems less loud.
An Office Hours question asked by Bob V., July 31, 2026.
Q: I've seen mostly positive reviews from the press about the AI features in Apple's public betas. How well do you think Apple is doing in pushing back against the perception that they're “too late to AI”?
It seems like by now that story has played out. Most of the reviews have been positive since WWDC. But then it turned into a discussion saying: well, it's not going to move the needle, it's going to take too long, there's dependency on Google, and this and that. None of this matters. AI, from a consumer point of view, is still a technology searching for a job to be done. I'm not in any way a bear on AI. I'm not dismissive of it. But what they call product-market fit hasn't happened. It has niches, and they're not consumers. There are individual users and buyers of the technology, and they might be using it on a day-to-day basis, but that's very early days. It doesn't have that resonance yet. It needs to be packaged in certain ways.
Quality is first and foremost, and once we see how it works, people will slowly, slowly discover things to do with it. And those will resonate. We got there the same way with social media. We got there with short video. We got there with the idea of a great camera on the phone. Nobody asked for it, and when you gave it to them, they went: what do I need so much quality for? I have three lenses on my phone — why do I need three lenses? But it turns out that camera turned out to be a killer app.
So how do we get there? I don't think it's ChatGPT. That's like saying TCP/IP. That's like saying Intel 8088 — something technical. It's also an interface that's notoriously low bandwidth. You have to converse in language, in complex language, prompts, as if we're dealing with a keyboard, the old days of the command line. And I think Apple's initial attempt, which failed, was to make things like emojis, and image editing, and trivial things. Those aren't apps either; those are features. The app is not a technology, it's not a feature. It's something that packages all those things, and does it in a way that's easy to discover and to evolve.
That's the problem Apple faces: it isn't something you can test for, because the number of queries that could be made is indefinite. And I don't think it's very easy to modularize the problem. If you're looking for high quality at all times, which is how Apple operates, it's difficult to meet that criteria. Siri is a natural thing here. Siri was way ahead of its time as an idea, and implementing Siri with the latest technologies makes sense. Maybe Siri usage will go up and up — but that's not a business. Siri is a feature.
Editor's Note: This was one of the questions asked by participants in Asymco's July 2026 Office Hours live Q&A session, held the day after Apple's FQ3 2026 earnings and open to Asymco One subscribers.
Subscribe to Asymco One for full access to this and other content.
A state of the union look at the market for mobiles.
Looking at the IDC data on smartphone shipments (2014 to present), the pattern shows a peak in 2017.
Covid caused a contraction and recovery but since then the unit market has not reached pre-Covid levels. Moreover, the current memory supply crisis is expected to cause a dip unlike any of the previous ones.
IDC expects the market in 2026 to roughly 1.09 billion units and another 1.1% decline in 2027. This may be optimistic. Yearly volumes could drop below 1 billion.
The sub-$100 entry-level device tier remains permanently constrained or uneconomical, pushing average selling prices higher. Emerging markets will fall the most. The Middle East and Africa are forecast to drop roughly 23%, Central and Eastern Europe down 19%, and Asia-Pacific (excluding Japan and China) down 14%.
In the US, Counterpoint says that sub-$100 smartphone sales declined nearly 65% during Q2 2026 compared with the year-ago period. The rest of the market fell by 45% as smaller manufacturers struggled to navigate component cost increases.
US Q2 smartphone market update: Overall: -5% Top 4 OEMs Apple, Samsung, Motorola, Google: -4% All others: -45% Prepaid: -11% Sub $100: -64% Apple reported N. American sales +11%.
Yet the number of smartphone users is not decreasing. There are approximately 5.78 billion unique smartphone users worldwide, accounting for over 70% of the global population. Moreover, there are over 7.6 billion active smartphones in use globally. (1.3 phones per user.) According to data trackers like Counterpoint Research, the active installed base grows by low single digits annually.
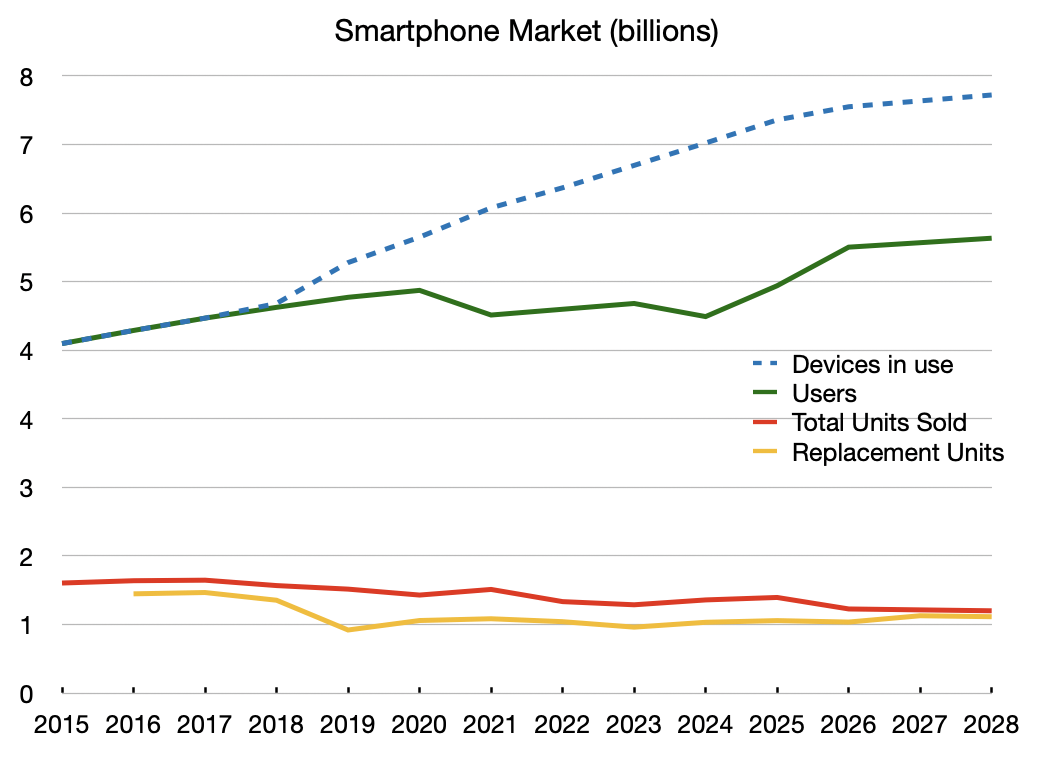
The history and near future of these measures are shown below:
Note the confluence of two trends: the increase of users and devices in use and the decline in unit sales. I also pointed out in the graph that of the units sold a certain number must be going to new users (as long as new users is growing). The remaining units (shown in yellow) are replacement units. That means they are used to maintain the base which is shown as the dashed blue line.
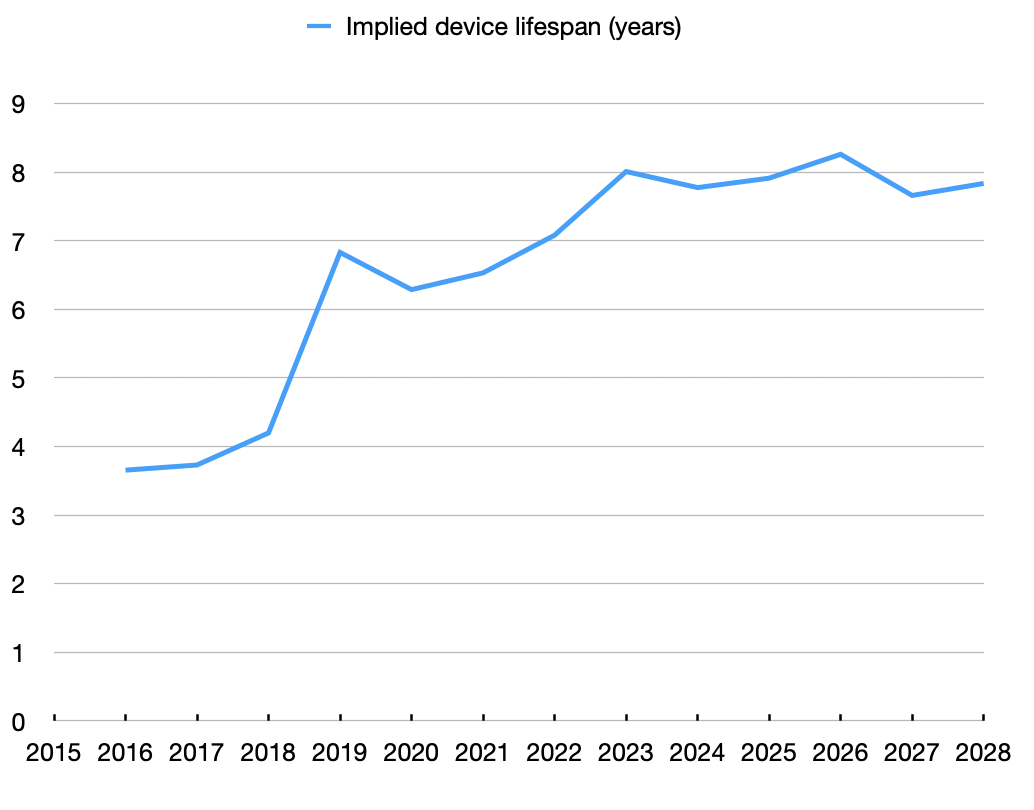
But if the dashed line is increasing (from 4 to nearly 8 billion) and the replacement number is constant (about 1 billion) then the phones in use must be lasting longer.
Dividing the base by the replacement rate gives the implied device lifespan, shown below:
If the sales and base data is correct then the lifespan must have grown from below 4 years in 2016 to about 8 years in 2023. It has held steady since and may stay there through 2028.
Eight years is a much longer time frame for an average phone's life than many may consider reasonable. No Android vendor supports their phones that long. However, Apple supports iPhones with major iOS software updates for about 5 to 7 years from their release date. They often provide critical security patches for an extra 1 to 2 years after a phone stops getting main iOS upgrades. This means Apple support lasts about 8 years.
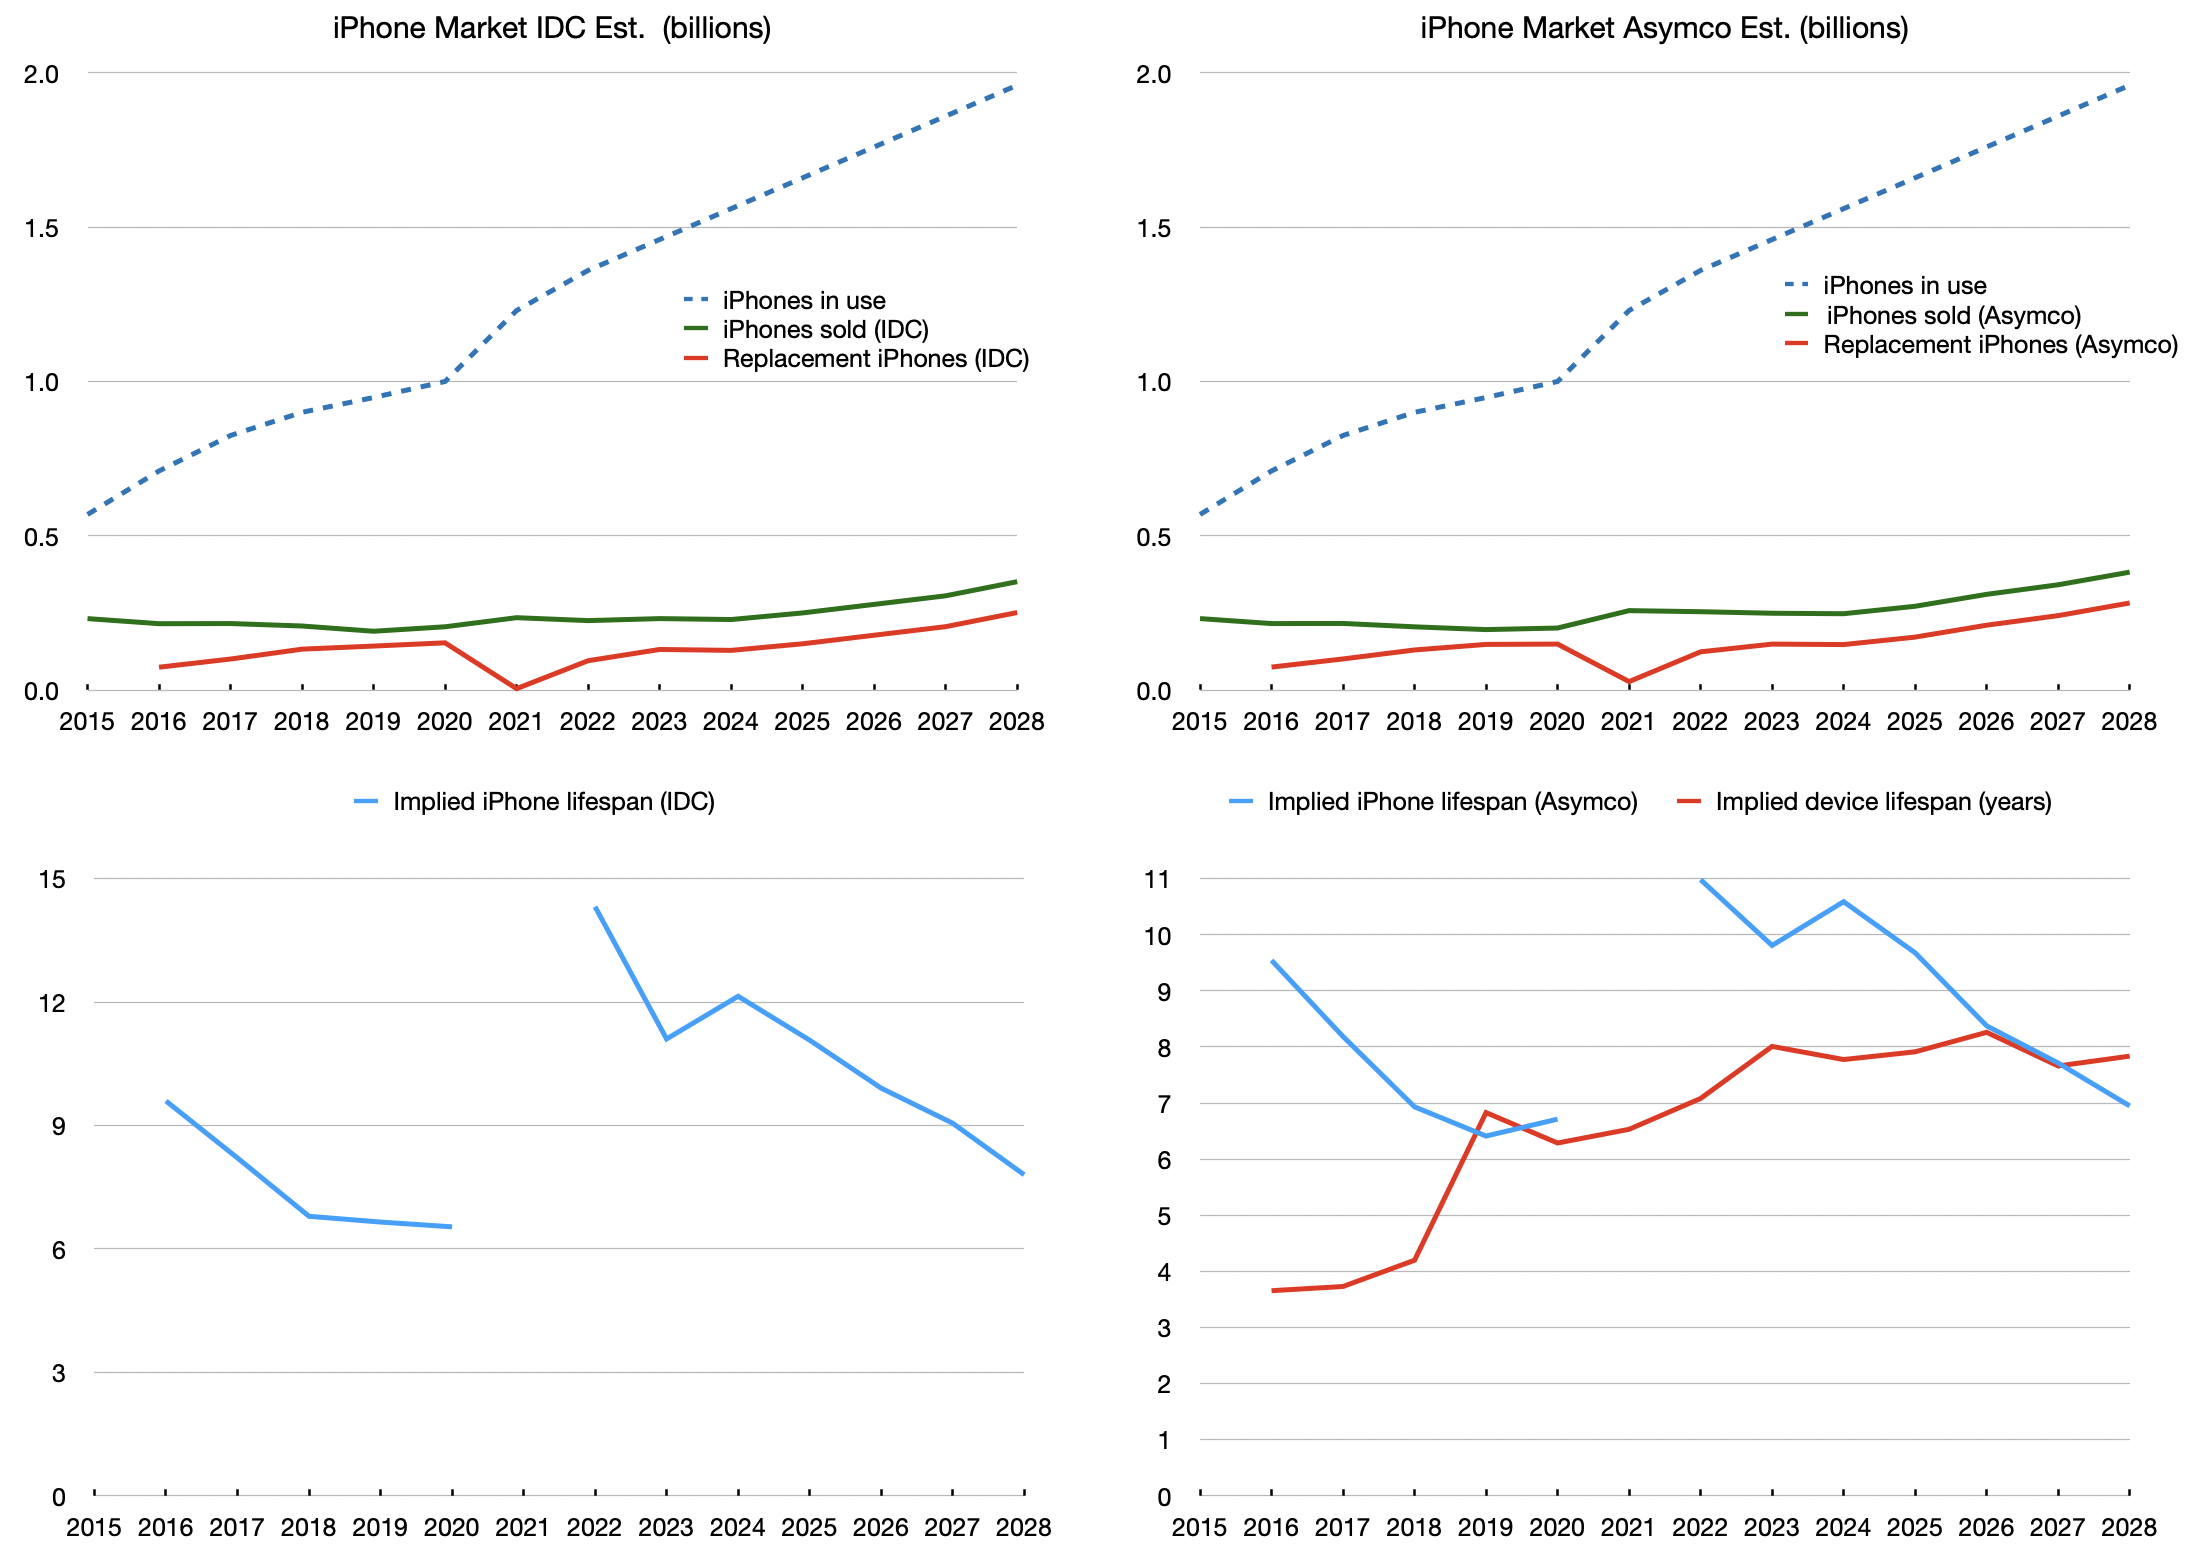
To confirm this we should analyze at the iPhone separately from the global market in the same way: installed base, units sold and implied longevity.
I used IDC data for iPhone unit sales in the graphs on the left and my own estimates in the graphs on the right. The installed base is based on Apple released data and extrapolations.
Apart from an anomaly in 2021 due to the recovery from Covid, the average lifespan for the iPhone (blue lines in the bottom graphs) holds at 8.5 in my data and 9.4 in the IDC data.
There are two reasons I believe my estimates to be more likely correct. First, because they also align with the overall market data (red line, right bottom graph) and second, they align with the support that Apple grants.
One more thing.
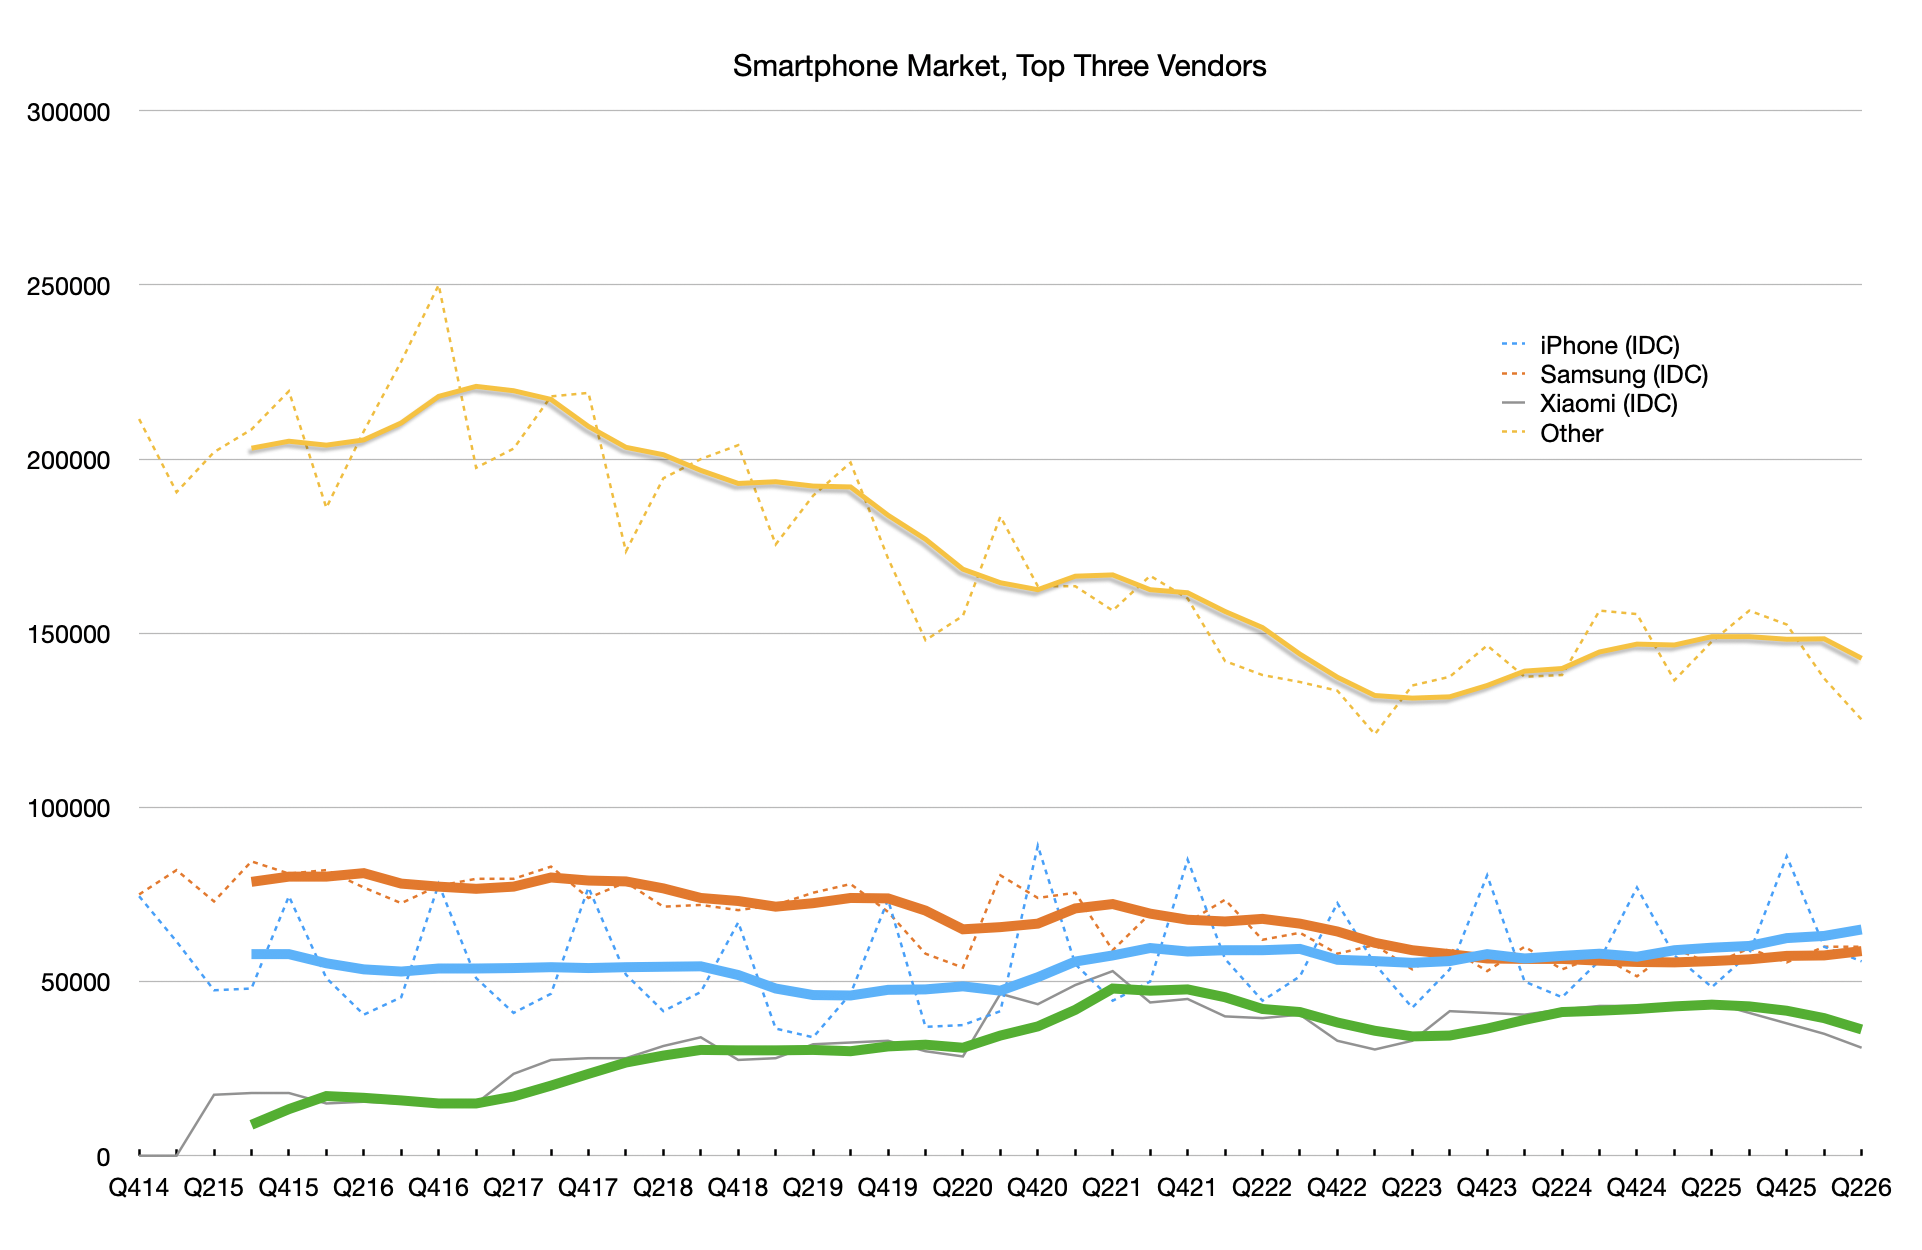
IDC also offers estimates of Samsung and Xiaomi unit sales. I show these estimates below.
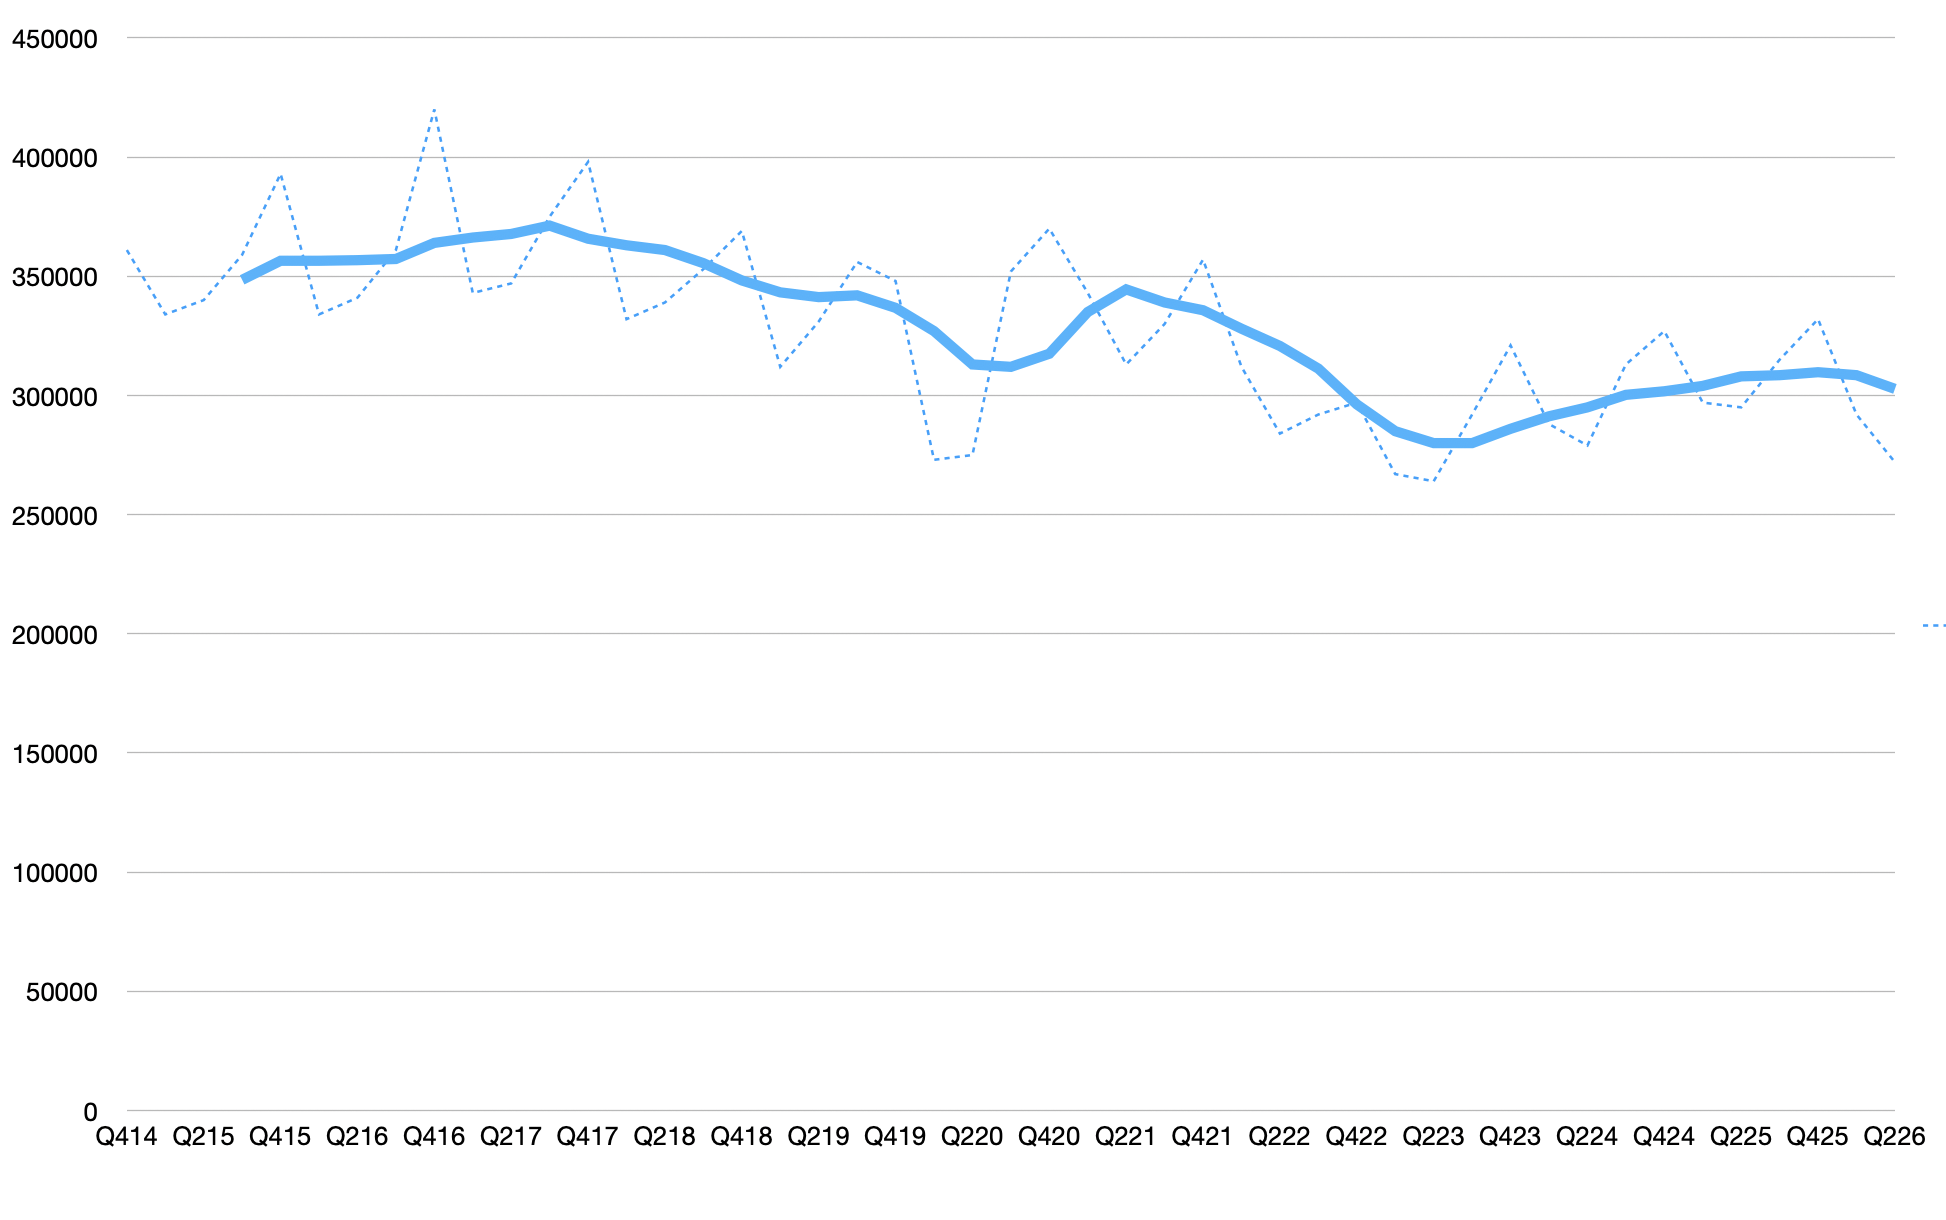
To remove the noise of seasonality, I provided twelve-month averages (solid lines). Note that their estimate for the iPhone (which is lower than mine) puts Apple ahead of Samsung since 2024.
Also note that the "Other" vendors combined are in a secular decline in volumes which will accelerate into the rest of 2026 and 2027. It's unknown whether this trend will continue in the longer term.
So what are the takeaways from this state of market review? Where are Smartphones going?
Apple the volume leader. It's been the profit leader since inception. It's been the sales value leader as well for a very long time. Being the volume leader may be a surprise to some. Moreover, we might be seeing a shift in strategy intended to drive even higher share gains and install base gains into new markets. There are profound implications when Apple is no longer only 20%. It already has the best quintile but can it harvest the second?
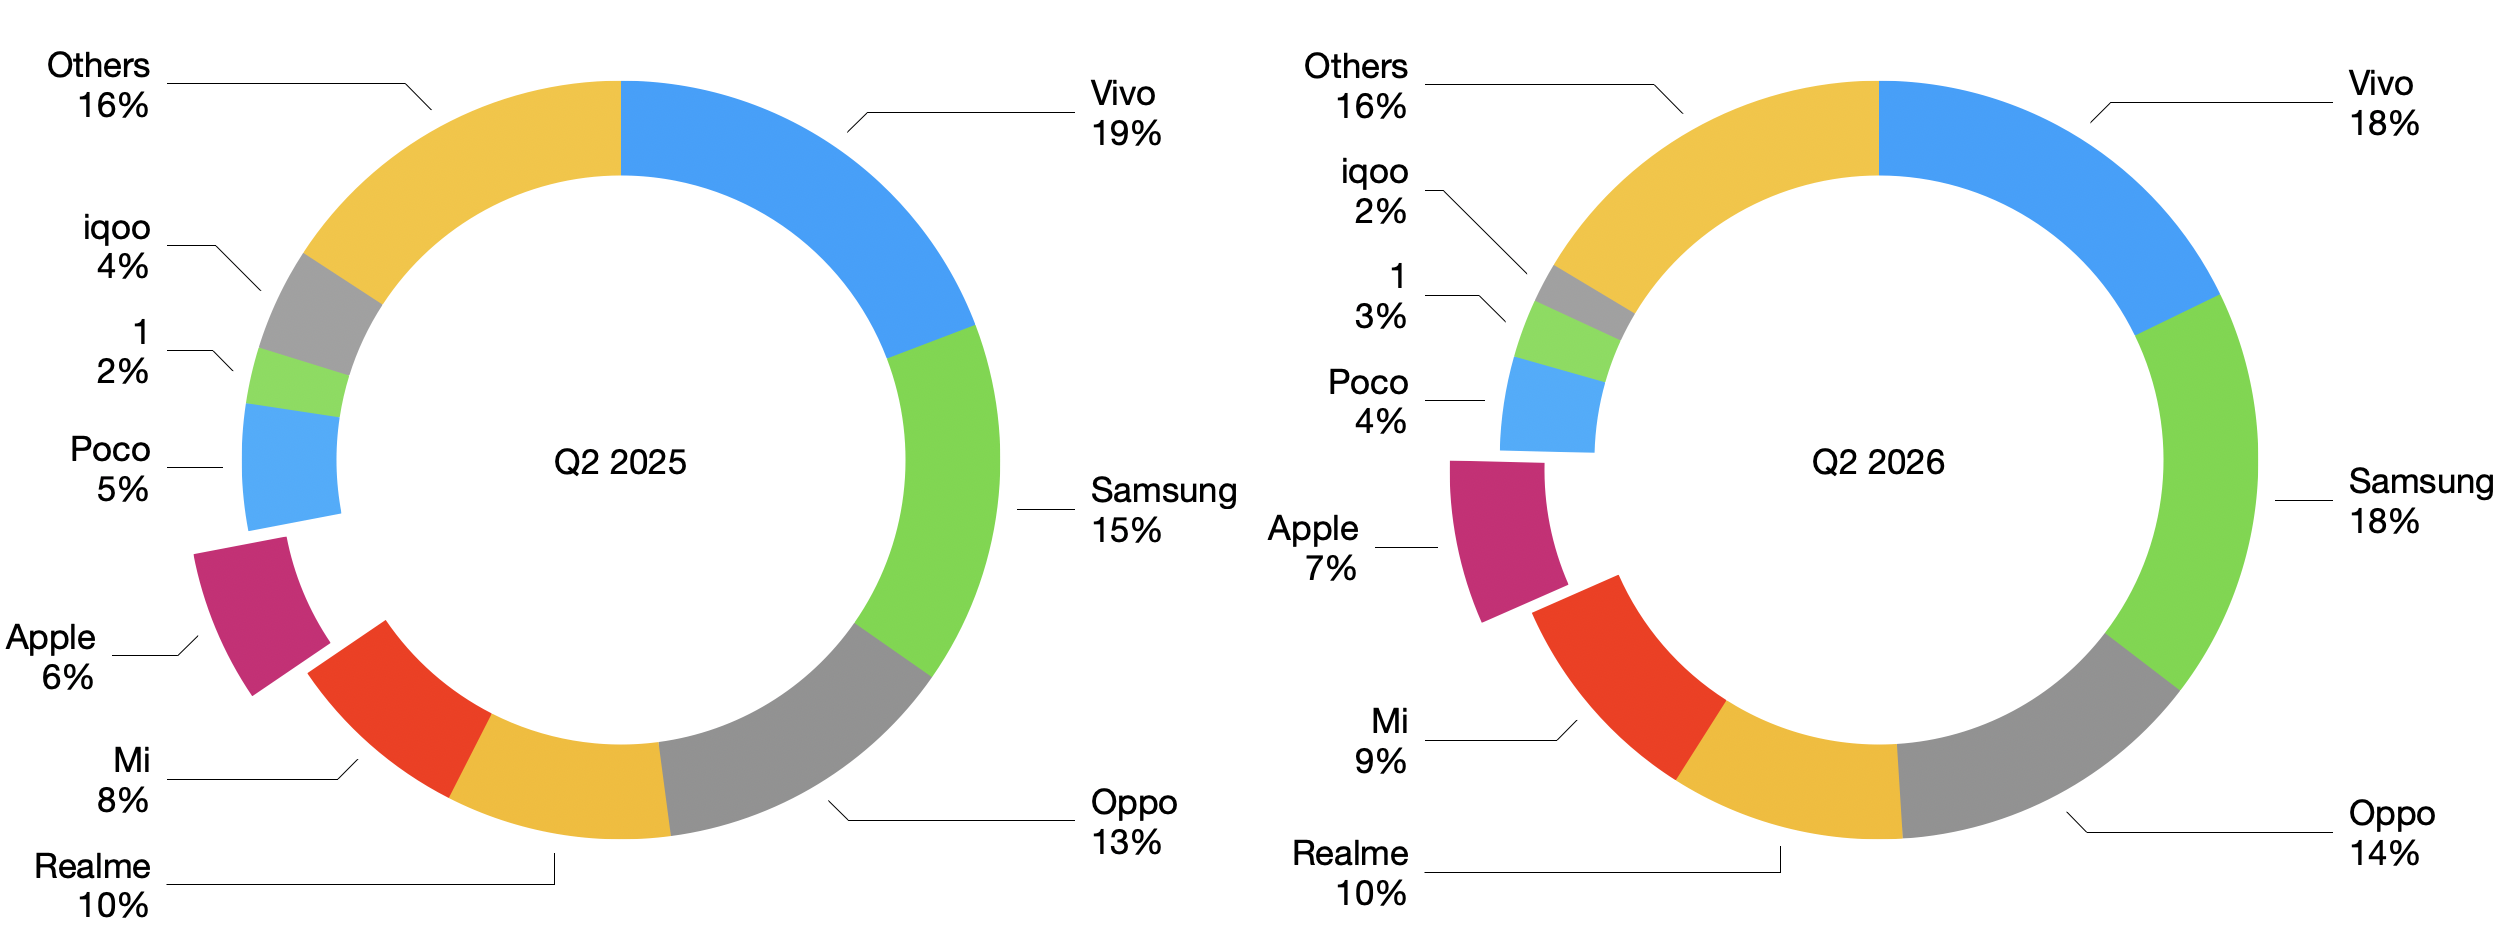
The low-end market may be in check-mate. The premiumization of the market has been underway for a while but apart from Apple, vendors are having a hard time profiting from phones. History has seen the exit of many phone makers. Nokia, Motorola, Sony-Ericsson, Panasonic, and many others are gone. They were all huge at their peak. Now we see brands such as Oppo, Vivo, Poco, RealMe, iqoo in the top 10. See the graph below for the Indian market. They are losing share and the lower the volume, the less likely the recovery.
Longevity matters. Support for 8 years should be standard but it isn't. Apple saw this early and made the infrastructure commitment to carry users to a future device lifespan. This includes the secondary market. This is reflected in the residual value of the phones and in their desirability in the used market. As phones last longer they are also more expensive; a natural tradeoff.
The user base is nearing a peak. 6 billion may not yet be it, but there are only 8 billion people on the planet. I would guess that 7 billion might be saturation. However, we're seeing 1.3 units/user attach rate. That may increase, as it has been.
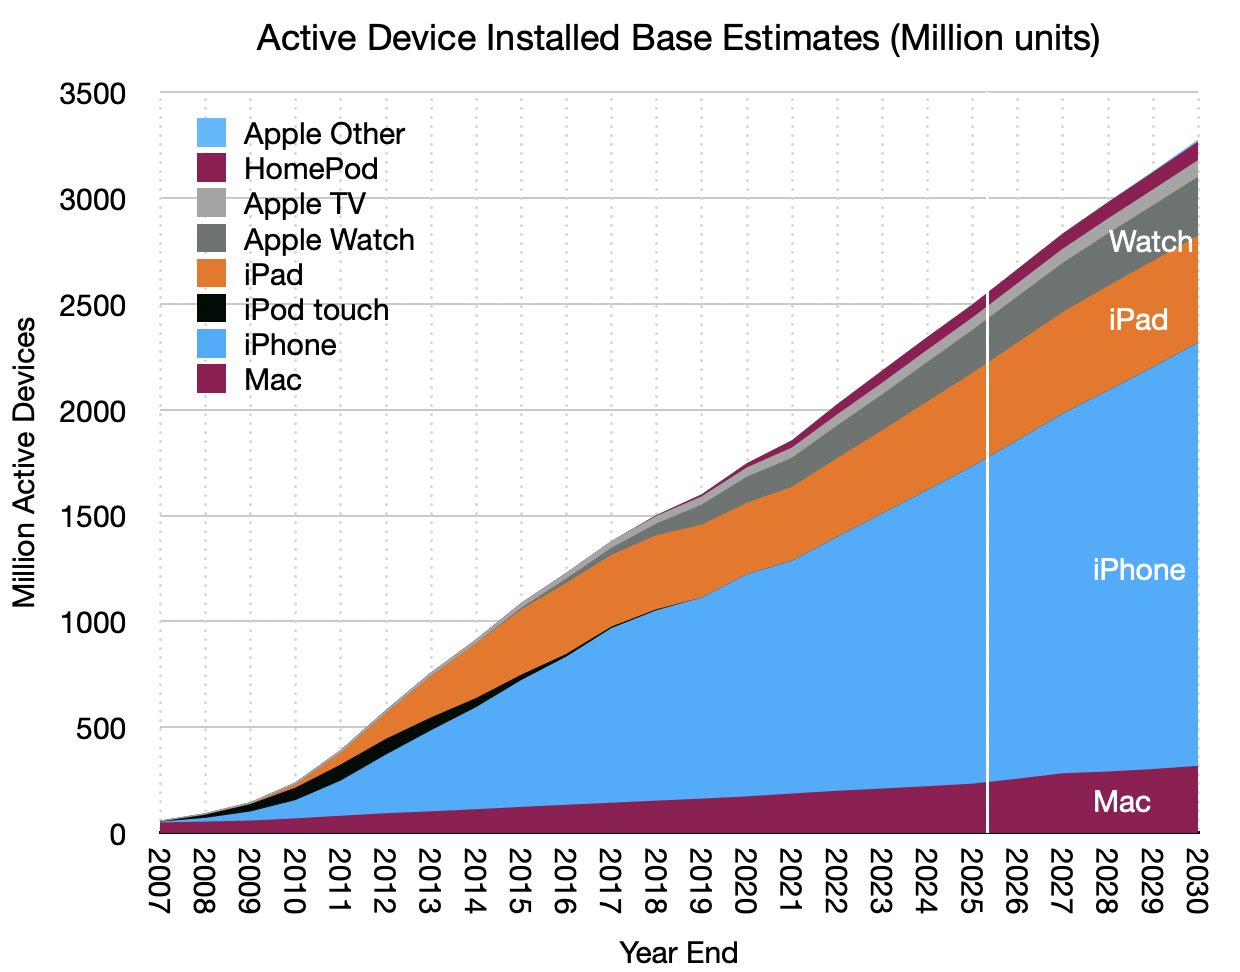
The total smartphone base thus may reach 10 billion (1.4 attached to 7 billion). The iPhone should be able to reach 2 billion in use with a total Apple active device base near 3.5 billion. This could easily happen by 2031.
An Office Hours question asked by Joseph B., July 31, 2026.
Q: Would Apple buy a memory maker — get into RAM itself?
They said they wouldn't get into this, and I'm surprised they said it — even if they thought they would, I don't know why they would insist on it publicly. I think they feel that it's not within their wheelhouse, as they say. It's not their core competence. It's not that they cannot create it. I'm not going to get into the weeds on this, but basically it's hard. It's unique. It has different dynamics. It's impossible unless you have huge scale, and alone, Apple is probably not big enough as a consumer of its own products, so they'd have to sell them. It just doesn't resonate with them at all.
I thought, maybe six months ago, that as a response to this, they would — despite everybody — buy or build their own. It's funny: they came out with a flat rejection of that. Now I think they'll maybe go behind the scenes, encouraging others to do it, possibly through financing, political maneuvering, something with Intel, something to do with all the cronyism that goes on in Washington these days. I don't know. But they'll back in, as they say. They'll maneuver and figure it out.
It would be ironic if Intel becomes a memory company, after having switched to CPUs from memory at its origin. This is where you are if you're in the semi business: you get whipsawed. It's such a tough business.
Editor's Note: This was one of the questions asked by participants in Asymco's July 2026 Office Hours live Q&A session, held the day after Apple's FQ3 2026 earnings and open to Asymco One subscribers.
Subscribe to Asymco One for full access to this and other content.
Apple Vision Pro as the Primary Visualization Platform for Cataract Surgery
Dr. Tommy Korn authored a new study of the Apple Vision Pro and spatial computing in cataract surgery. It has been peer reviewed and published in Clinical Ophthalmology.
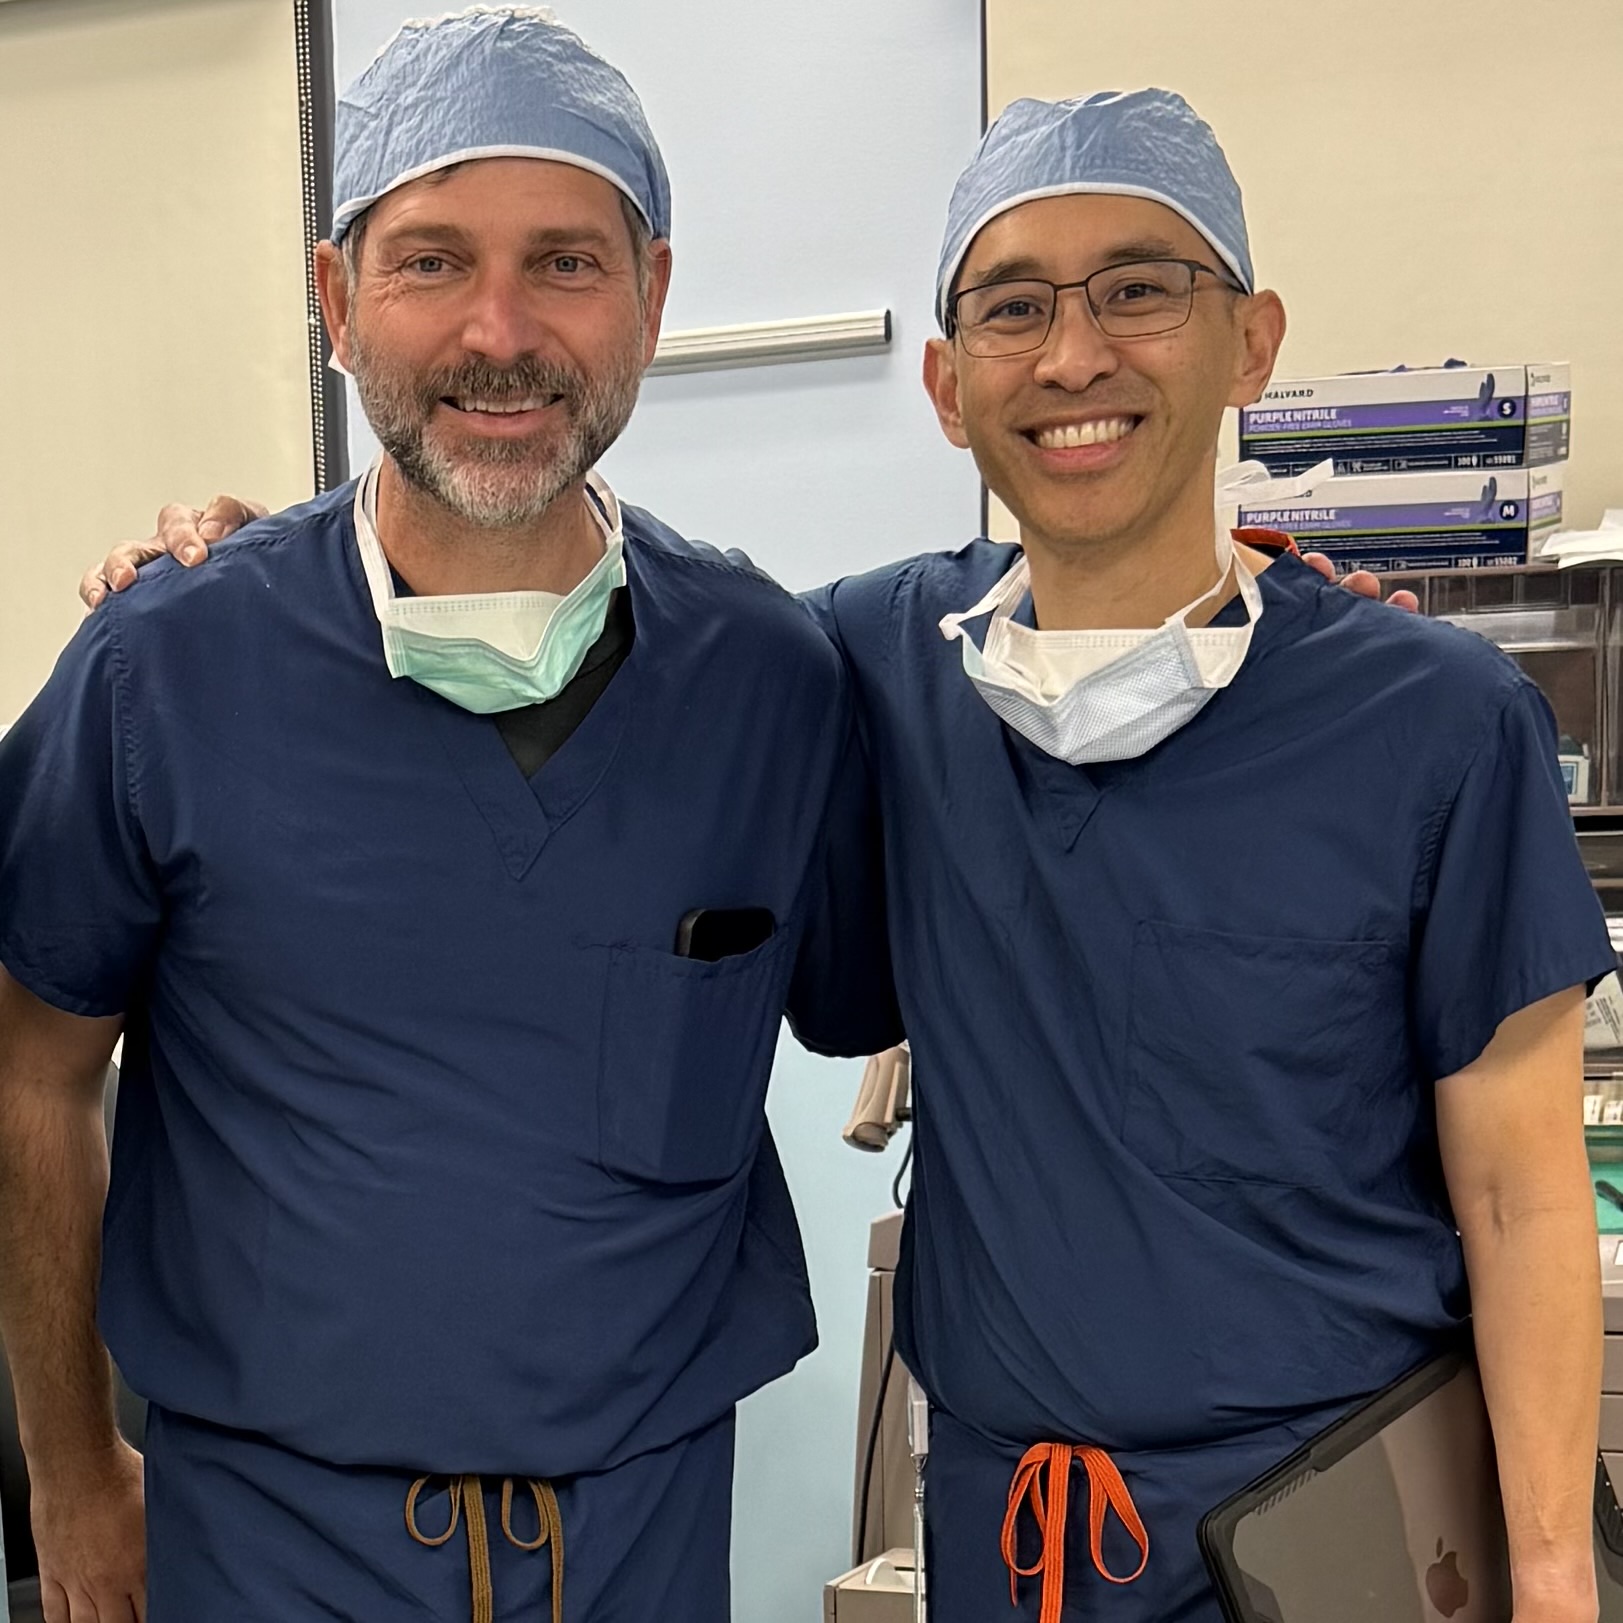
I had spent a day shadowing Dr. Korn as he performed a dozen surgeries. It is remarkable that those delicate operations--saving people's vision--can be assisted so competently by the Apple Vision Pro.
Dr. Korn and his team evaluated the 2nd generation Apple Vision Pro (M5) using the ClearSphere app as the primary 3D view for cataract surgery. This surgery replaces the cataract-clouded natural lens in the human eye with a fixed focal length artificial lens. It restores vision to many who would otherwise be blind.
First of its kind: 1st prospective study of Apple Vision Pro as the ophthalmologist’s primary 3D view for complete live microscopic cataract surgery from start to finish.
Wireless, high-definition 3D microscopic view
45 cataract operations studied
Easy on surgeons: physical demand just 1.07 out of 21
Excellent outcomes: about 20/20 average vision at one month
Strong surgical team acceptance: 100% confident assisting with future cases
Safety built in: Zero device-related surgical complications observed; 2 backup systems always ready
This study helps lay the scientific and clinical foundation for what comes next in spatial computing and surgery.
For generations, eye surgeons have worked through microscope eyepieces and fixed screens, often maintaining painful postures. Spatial computing creates the possibility of something very different: A surgical cockpit built around the surgeon.
At a recent conference on the topic it was clear to me that many surgeons are looking at this platform for multiple benefits:
Ergonomic benefits: comfortable position for surgeon
Navigation (finding/positioning of instruments or procedures on patient)
Visualization of complex data in real time. No need to turn or seek out data on various monitors.
Space saving over fixed monitors.
Situational awareness
Productivity, remote work, remote operation of surgical robots and cost savings over fixed external monitors.
Dr. Korn calls it "A personalized 3D workspace built around the surgeon."
It's still early days for spatial computing and yet the benefits are clearly measured and now peer reviewed.
Congratulations to Dr. Tommy Korn, pictured on the right with yours truly.
Necessity is the mother of invention but return on invested capital is the mother of innovation.
Invention is big ideas with unclear benefits. Innovation is big benefits with unclear ideas. This is why inventions are easy to point out but hard to find useful while innovations are very useful but hard to explain.
Innovation is a matter of many small changes with big returns. The bigger this ratio between return and change, the more profound the innovation. Moving from selling music on physical media to digital files and then to subscribing to an infinite catalog is an example. Moving from hardware warranties to AppleCare subscriptions is another. Overall, the entire Services business is the best example.
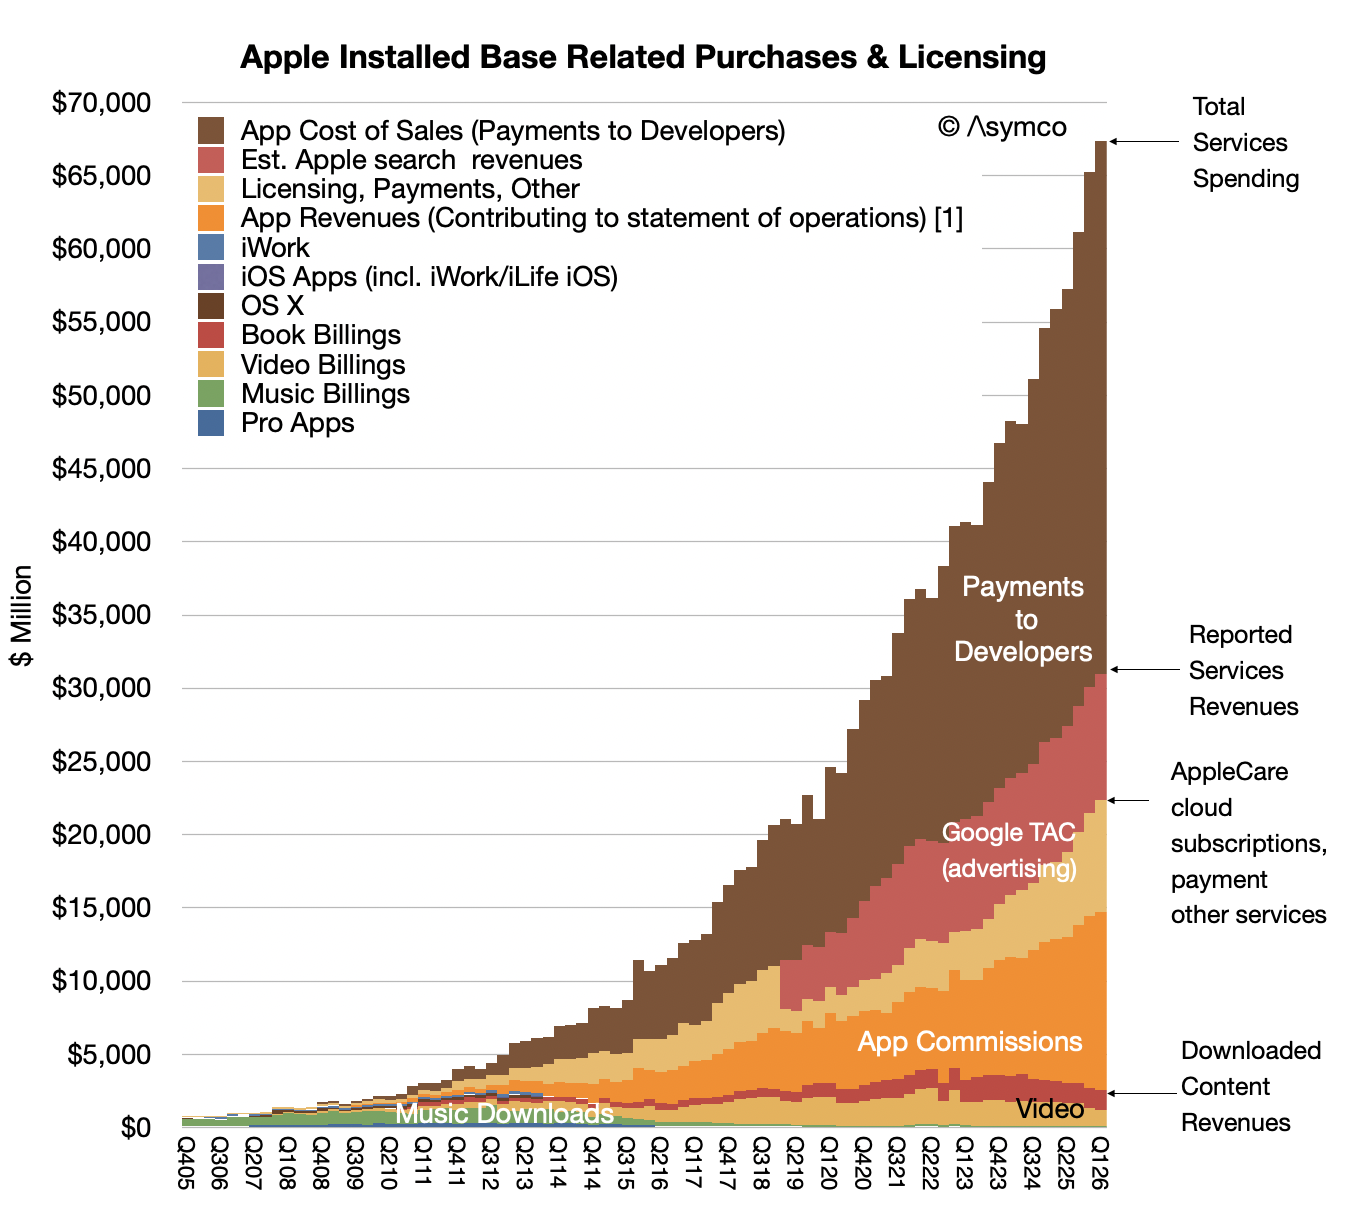
Services has delivered a compound growth rate of 20% for 20 years, growing from $3.3 billion in 2006 (as iTunes Software and Services) to $120 billion for the last twelve months. Along the way, the gross margin on Services has increased to 75%.
A 20% compounded growth rate for 20 years with 75% margins is a strong indicator of innovation. Yet, there is hardly any accounting its components. Hardly and single thing to point to as the "big idea". I tried for decades to provide a view into Services, such as it is:
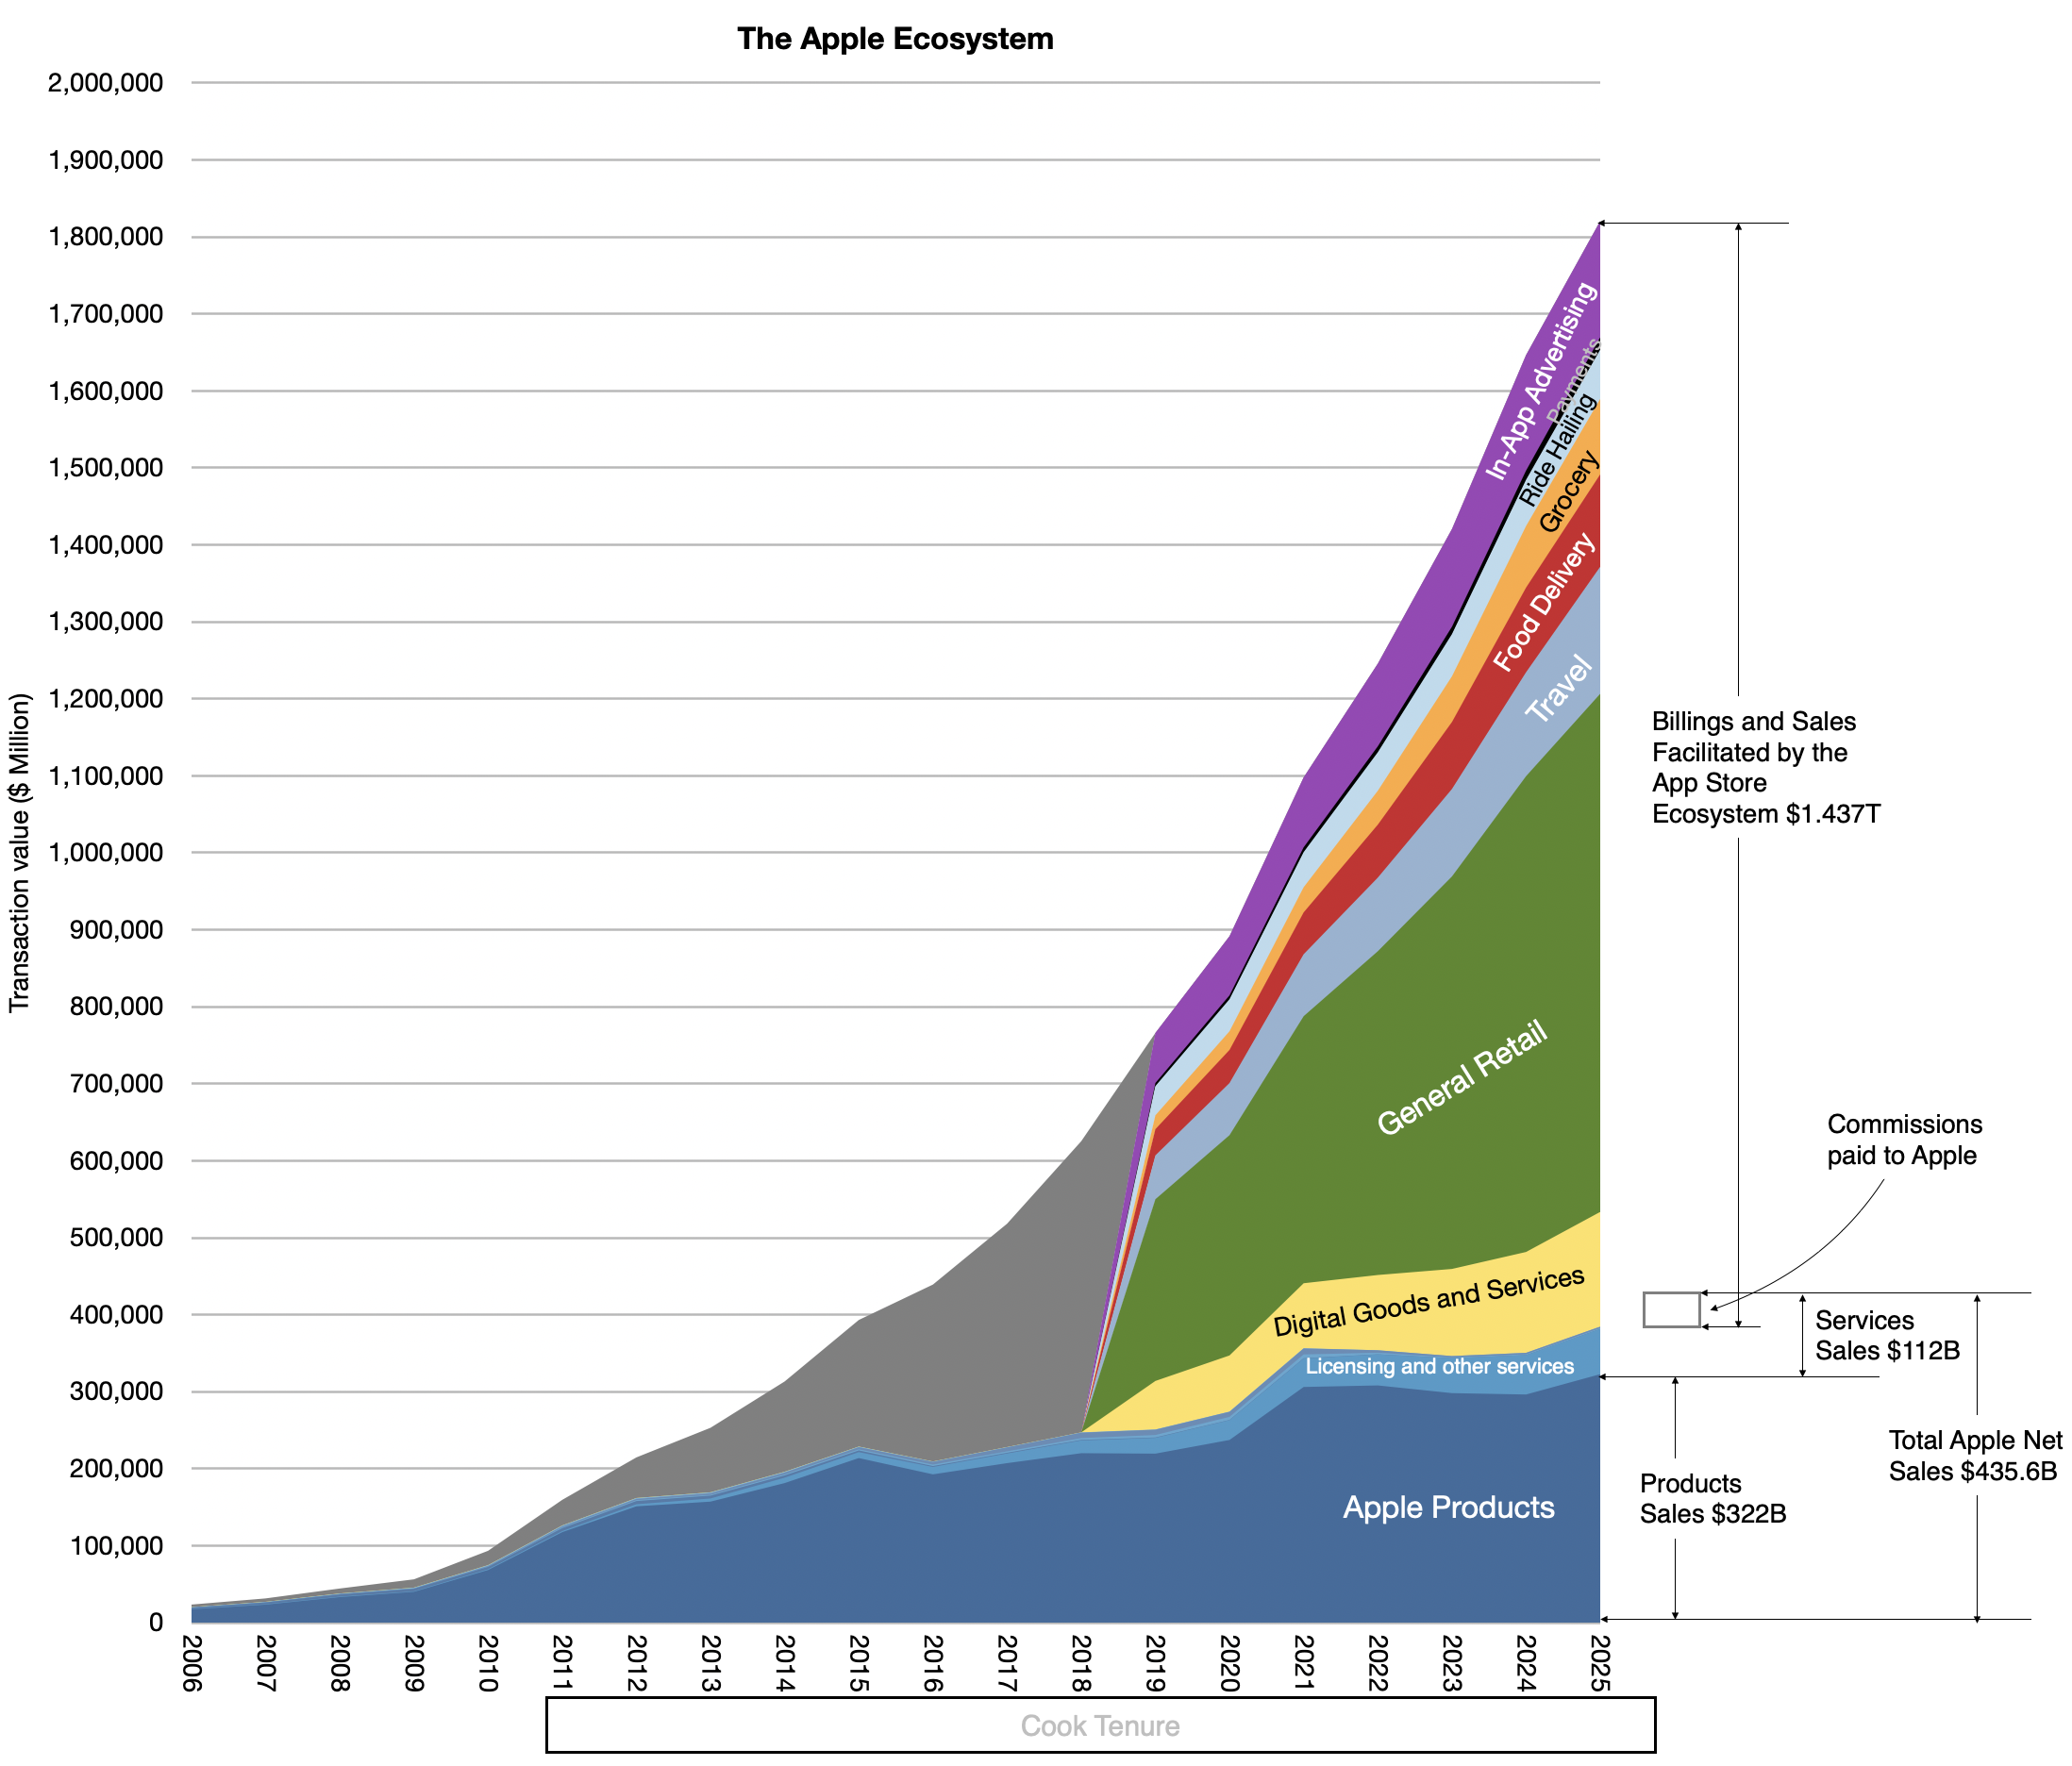
Moreover, Apple's own Services category of revenues is but a small part of the activities on top of the stack of products and services that enable third parties to provide additional value. I call this the Apple Ecosystem and it is approaching $2 trillion/yr.
The servitization of music, warranties, television, storage, food, travel, transportation and many other products is unrelenting and extremely valuable but we can't point out what one thing made it possible.
It's a lot of small things. But one of these things just arrived and most did not notice it.
The innovation is the servitization of Apple's core Products (shown in the bottom of the graph above). The brand is Apple Upgrade.
Apple Products, iPhone, Mac, iPad, Wearables & Home have still been mainly sold individually. A cumulative total of at least 5.2 billion devices of which 2.5 billion are still in use. Each requires a single initial purchase decision from one of 1.5 billion customers. The product then follows a life of use and perhaps a change in user with a secondary purchase decision. Finally it enters a disposal state where it might be recycled.
That's a difficult picture to see. Many participants are involved beside Apple and the initial buyer. Many distribution channels, many secondary markets, many resellers, etc. This is why the products business has not been "servitized" or turned into a service. Services are more predictable but they require management and management depends on data. Apple keeps a relationship with the user once they are registered through iCloud but the path of the product itself is often invisible.
That is what is about to change.
The mechanics, trade-ins, monthly financing, hardware upgrades, aren’t new. Apple has offered versions of all of them for years. What’s new is a subtle change in defaults and what it means for who captures the residual value of a returned device.
Economically, the iPhone Upgrade and iPhone Payments programs are the same as Apple Upgrade. The purchase is "fiancialized" where multiple payments are substituted for a single purchase. But with the older system, only the iPhone was included and the product was default "owned" by the user during the loan period. Apple Upgrade applies to many, almost all, products and the default is that Apple "owns" the product until the finance (lease) term ends.
This ownership comes with risks and rewards. The risk is that the product is damaged, defaulted on or impaired in some way before the term ends. The reward is that there is control over its use after it is returned. The assumption is that the vast majority are returned and not bought-out and that is because of the attraction of new versions and the simplicity of rolling over a new lease.
Therefore the residual value is available to Apple but also access to inventory for resale. The used and refurbished phone market size is estimated at $65.20 billion and 315 million units in 2025 and expected to grow to $70 billion in 2026 and is forecast to reach $100 billion by 2031. That estimate might be low if Apple Upgrade grows rapidly.
iPhones account for roughly 40% to 50% of the global secondary, used, and refurbished smartphone market. That estimate implies that one used iPhone is sold for every two new iPhones. If one were to add the secondary market to the primary, iPhone unit sales are 450 million/yr.
The demand is such that Apple could increase sale (together with resale) volumes by 30% rather than the 15% for new alone. Demand from non-consuming markets in particular could drive this secondary market.
Naturally, the margin on the secondary markets will be lower than the primary but it may be a very sustainable and additive margin. Moreover, the relationship with the customer would be created at purchase time and could lead to a future upgrade path. For instance sale of AppleCare, accessories and personalization. The customer creation process would be better managed and more predictable vs. the third party resale channel.
The knowledge gained would also inform decision making. Usage patterns, pricing, mix, all benefit from perfect visibility into the secondary market. Apple is the one handling the sale, the device setup, the AppleCare pitch, and the accessories conversation. It also knows exactly when that customer is coming back.
This benefit would not appear if the Upgrade program proves unpopular. But that is why the Apple Upgrade is such a good deal. Almost too good.
Effectively, Apple Upgrade is free financing. Instead of paying upfront, the buyer pays monthly but not more than what the product is priced at. Apple is effectively eating the cost of the capital.
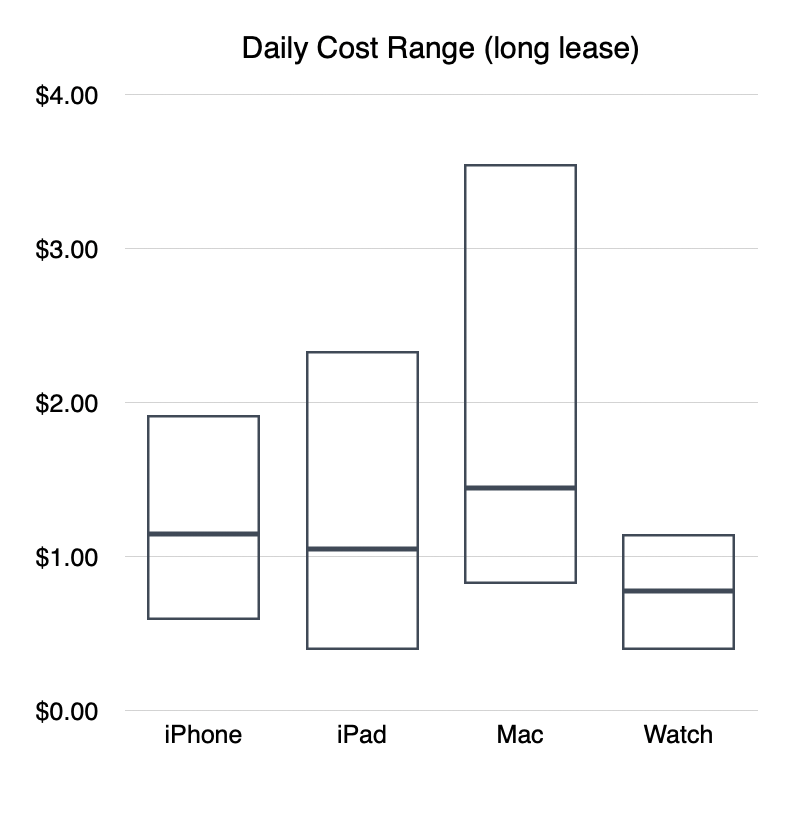
The optics of a price that is almost $1/day, easily calculated, will be very compelling. Apple Upgrade product daily pricing distribution is shown below:
iPhone pricing optics shift entirely. $17.99 a month or $1,099 upfront are the same phone. One of those prices is a lot more agreeable. The psychology of this decision process is well known but there is not baiting here. The lower price is genuinely a better deal.
It's also a lot easier to let go of the product in one or two years and stay with the latest version. And not just for the iPhone any more.
Along the way, with global expansion, the Apple Upgrade program is effectively the servitization of Apple Products. It is both a growth strategy, in terms of users and revenue, and an innovation that changes the relationship between Apple and its customers.
Next will be the bundling of Apple Upgrade into Apple One. The idea that one subscription will offer all the phones, computers, tablets, wearables, home appliances and services for a family under one monthly price.
Bundling and unbundling. The biggest innovations ever.
An Office Hours question asked by Frederick H., July 31, 2026.
Q: What is the reason for the obsession with making movies and TV shows? There must be a strategy behind this.
It's one of those things you get enlightened on after thinking about it for three years, and then it comes together: wait a minute, maybe it's much simpler than I thought. As a strategy thinker, you look at Apple TV and say: if they hadn't done this, then all the content would have been locked up in silos, and you'd have no access to those silos. This was happening already — old titles, movie libraries, TV libraries were being vacuumed up and aggregated into huge piles. People were buying all these rights and locking things up. I remember I used to be able to download, on Apple TV, shows like Big Bang Theory or Seinfeld, and then they just weren't available anymore. Somebody bought them up and locked them away and said: you need to sign up with Amazon to get your favorites, or to get old movies, new movies, whatever.
So Apple said: if that's the way it goes, we're not going to go around trying to buy all these old movies. That's not our way. We're not going to buy content libraries. Instead, we're going to make our own. You literally start with zero, and you build up your own library. The question then is how much you spend, how big it is, what kind of movies. The decision, I think, Tim Cook made was: quality first. And how do you measure quality? Awards — because that's the only metric that exists if you can't measure usage. You don't have box office, and you don't have distribution in theaters. You're never going to get the user numbers, because you'd have to build up a huge chicken-and-egg: buy a huge library, get a lot of users, and then you can say it's the best-selling, or it's the most popular. That doesn't work in streaming. Everything's siloed, everything's compartmentalized, so the ratings make no sense anymore. What you do instead is go for some artificial measure of quality determined by some group of experts, supposedly. Unfortunately, there's no other metric for quality right now. So: we're going to aim for all these awards, and then we can advertise that fact. We can claim that quality is above all.
Why? Because in the age of streaming, if they didn't, the Apple customer would think more and more that the place of content is not Apple. We get music there, we get podcasts there. Already it's not there in terms of YouTube, which is short-form video. But they said: for long-form video, we need to be there for brand reasons, and possibly for the idea that it's the device that consumes the greatest content. I do believe they were also thinking long-term for the Vision Pro and other things: we're going to need to get into sports, into live, into events. Because the screen doesn't stay the way it is now. Screens become more wearable, things become three-dimensional. And if we don't control the content, then we can't create the tools.
This brings me back to the old days when Sony was in this game. Sony was struggling to convince people to start with Betamax versus VHS. They lost that battle, and they said: VHS won because more studios supported it, more content was behind it. So Sony said, we'll have to buy a studio. They became filmmakers, and they became a music company, so that content would reside, ultimately, on Memory Sticks, DVD, and Blu-ray. If we don't own the content, then we cannot sell the product that plays it, and we cannot get royalties from the media it plays on. It's outdated now, but the point was they realized content was king. If you don't own it, then you are at the mercy, and the margins are destroyed, because you can't innovate — you have to go to commodity product. I think that influenced a lot of people back in the day, including Steve Jobs, who realized: if you deal with content — long story with Pixar there. So why make content? Same as always: because content is king. Because without it, if somebody else owns it, then they'll dictate terms to you on what you can use to display it.
I heard from Judd, my podcast partner, that things are rough in Hollywood these days — the industry is going through a terrible crisis, perhaps an existential one. And yet, so much new stuff is coming out; there's so much production going on. Yes, but it's all controlled by the streamers. It has changed dramatically from the creative side. The money flows and the deals that are done are completely different now, and this caused a huge disruption. This spending on production, even if it's billions, is pocket change for Apple and Amazon, maybe Disney. It's the tail wagging the dog: the distributors, who everybody thought were just a bunch of nerds, ended up dominating it.
Editor's Note: This was one of the questions asked by participants in Asymco's July 2026 Office Hours live Q&A session, held the day after Apple's FQ3 2026 earnings and open to Asymco One subscribers.
Subscribe to Asymco One for full access to this and other content.