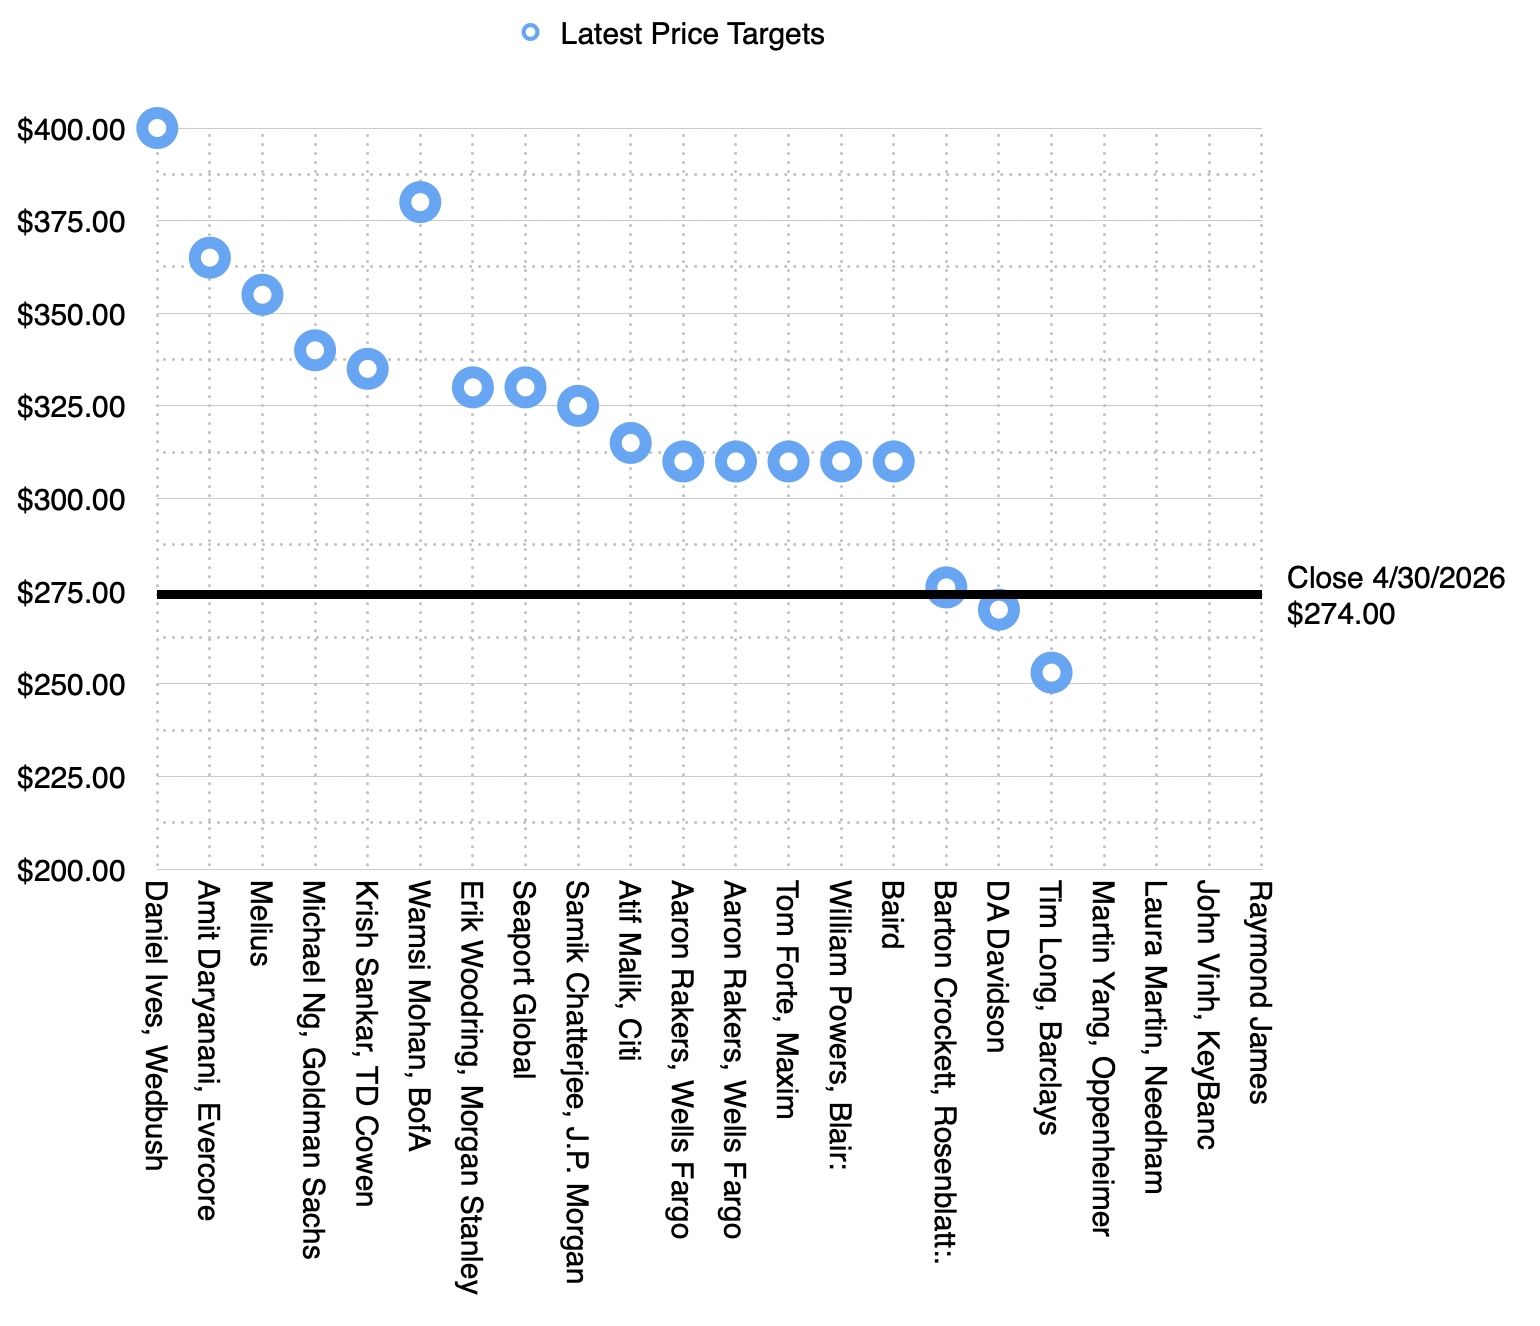
Morgan Stanley analyst Erik Woodring believes Apple’s upcoming Worldwide Developers Conference could begin to change that perception. The 5-star analyst reiterated his Overweight rating and $330 price target, arguing that a successful AI strategy could unlock a higher valuation for Apple stock, with a bull-case scenario reaching as high as $440 per share.
He noted that Apple’s recent strength has been driven by its products and services business rather than AI. However, companies viewed as “AI winners” have often earned higher valuations over the past two years, and Woodring believes Apple could soon be seen as one of them.
Why WWDC Could Be a Turning Point for Apple
Woodring believes Apple now has more of the tools needed to compete in AI. He pointed to Google’s Gemini models supporting Apple Foundation Models, Apple’s strong focus on privacy, and what appears to be a renewed push around Siri and Apple Intelligence. Unlike many of its rivals, Apple is not spending heavily on building AI infrastructure. Instead, the company can use its massive base of iPhone, iPad, and Mac users to bring new AI features to consumers. That approach could help Apple grow its AI offerings without the huge costs faced by some competitors.
The analyst also sees an opportunity for Apple to help ease some of the industry’s AI capacity constraints. A more capable Siri and improved Apple Intelligence platform could bring AI tools to millions of users through Apple’s existing ecosystem.
For investors, the bigger story may be valuation. Woodring believes that if WWDC shows a clear path for Apple’s AI plans, the stock could earn a higher multiple. In that scenario, he sees shares reaching $365 to $385, with a bull-case valuation of as much as $440.
Takeshi Narabe • 16:20 [Y]ou also mentioned about the Japanese companies, overshooting, performance oversupply was also one of the reason that Japanese electronics giants were outmaneuvered by Apple: the insistence on in-house component manufacturing and a critical absence of software and service-led business as you mentioned now.
Horace Dediu • 17:02 It's a tough one. I think I know what you're getting at, but I think the puzzle there is that you try to make things better and you think by making things better you're going to be more successful and that was another observation by Christensen that sometimes you if you listen to your customers they'll ask you to do things better because that's all [the customer] can imagine.
I think the canonical example for me would be the game consoles. [...]Every new generation was more powerful and the way [the platforms] would decide how to improve it would be by talking to their customers and who are the best customers?
They are those who spend the most on games and the most on consoles. and they would survey those [customers] and [the customers] would always say "we need more performance in terms of refresh rate or, I don't know, how many dimensions of performance there are in games--i'm not particularly a user.
So the problem is that it's not just Sony but Nintendo, Xbox, everyone in the gaming industry was listening to the gamers and the most prolific and demanding gamers were those who spent the most money.
But if you compare mobile gaming to console gaming, it was always worse on all those dimensions. But if you [instead] measure how much time people spend on on mobile games, initially it was quite small, but over time it grew and grew and the number of people using phones for gaming is in the billions. In contrast, the number of people using consoles saturated at most at 30 percent of households in the United States. I don't know what it is in every country and there are many still. That's an okay business but it's not measured in the billions of users and arguably those users are not the ones you want to listen to.
The only exception was Nintendo with the Wii, which actually tried to expand to non-consumers, tried to expand to elderly people (so that they can do some movement) with the product or to young children. And that was a brief moment of success in the incumbents. But I think fundamentally, even that too gets passed to the phone.
So this is a classic example. How Apple plays in this game is a very tricky one because...
The company “may be on the brink of some real AI sizzle.”
Reitzes said people are becoming more comfortable using voice commands, and Apple could benefit from this shift as technology becomes more voice-driven.
Reitzes also said the upgraded Siri could become a standalone tool that many Apple users rely on, even instead of apps like OpenAI’s ChatGPT. He described it as an “agent-style interface” that could make the Apple ecosystem more unique and spark fresh excitement among developers.
Additionally, he highlighted that no other consumer tech company has both parts of that system under one trusted setup. He added that this advantage will become even clearer—and more valuable—as AI systems get more complex and start acting more independently.
Overall, he expects Apple to post about $613 billion in revenue by fiscal 2028.
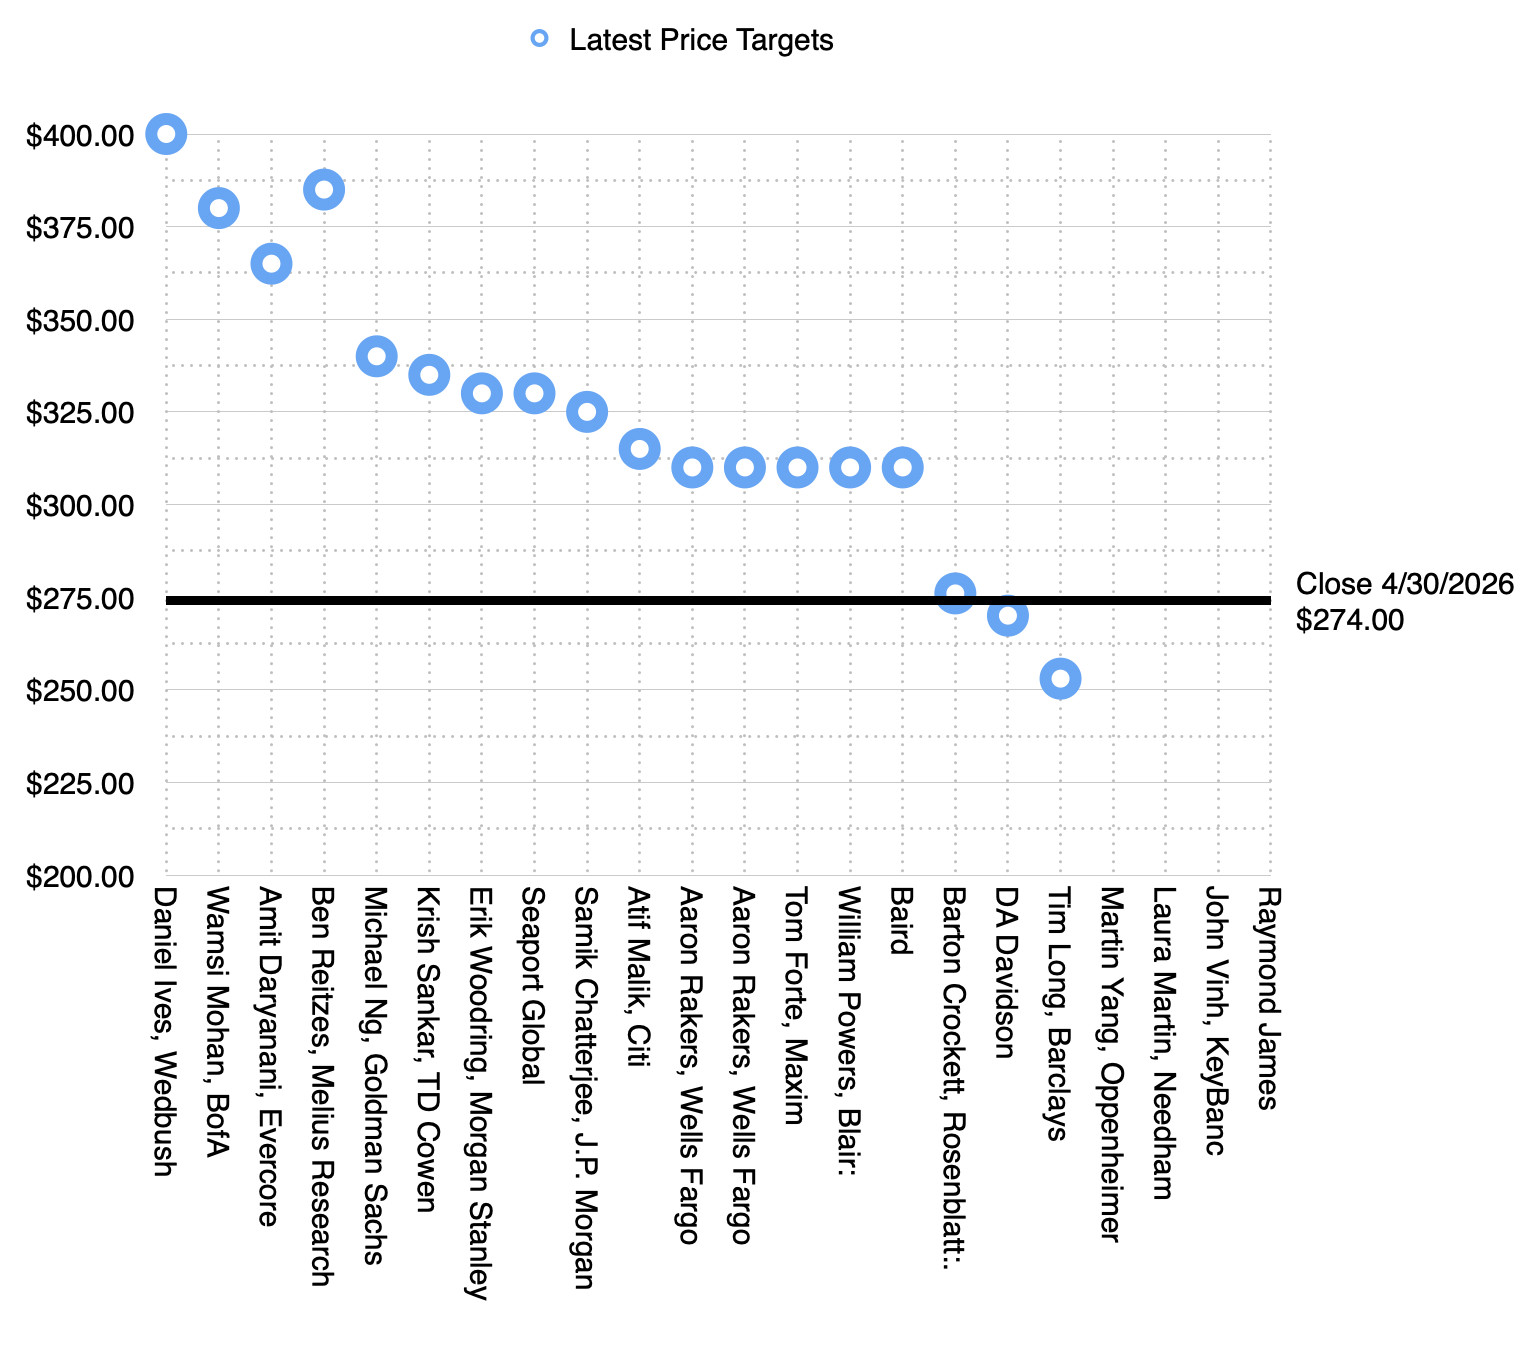
NB: Latest analyst targets are shown with Melius' stepping up. Analysts are coming round.
This upgrade follows Bank of America boosting its price target to $380 a share.
“In an agentic world, value accrues to the platform that controls user intent, personal context, app access, permissions, identity, authentication, payments, and trust,” said BofA’s senior equity research analyst Wamsi Mohan.
“Smartphone is the scaled consumer device where these factors already converge,” he added. “If AI assistants become the new front door…we think Apple should have meaningful leverage over model providers, app developers, merchants, advertisers, and payment networks.”
An agentic version of Siri could boost 2030 revenue by as much as $65 billion, Wamsi and his team estimated, adding up to $2 billion in incremental earnings over the next four years.
Reitzes sees the new Apple Siri as a stand-alone app that has the potential to replace ChatGPT for Apple's 2.5 billion installed devices, while proving to be “an agentic interface that can further differentiate the Apple ecosystem and ignite a level of excitement with developers not seen since the early days of the App store.”
But it’s also likely to establish Apple as the leader in consumer-use AI.
“If agentic AI shifts the market from answering questions to taking actions, the critical control point becomes centered around owning the endpoint,” Wamsi said. “Apple does not need to own the best frontier model if it owns the trusted interface that routes intent across local models, Apple-controlled cloud models, external models, and app actions.”
Reitzes at Melius sees that shift, which he describes as a “shot in the arm” for Apple’s app store, driving “a massive new product cycle that keeps iPhone growth going.”
He’s also observing that Apple’s architecture, with on-device models handling lighter workloads and its private cloud taking on the larger ones, makes it unique.
“No other consumer technology company has both legs of that architecture under a single trust model, and we think that gap becomes more visible, and more valuable, as agentic complexity scales,” he said.
“Agentic AI is a structural tailwind that will force consumers to get the latest and greatest Apple device because it will work better than other brands.”
Bank of America upped its price target on the tech giant, citing a potential boost from agentic artificial intelligence.
Shares rose 0.5% in premarket trading.
“In an agentic world, value accrues to the platform that controls user intent, personal context, app access, permissions, identity, authentication, payments, and trust,” analyst Wamsi Mohan wrote in a note to clients. “Smartphone is the scaled consumer device where these factors already converge. If AI assistants become the new front door to search, apps, commerce, scheduling, payments, and workflow completion, we think Apple should have meaningful leverage over model providers, app developers, merchants, advertisers, and payment networks.”
Mohan raised his price target to $380 from $330 and reiterated his Buy rating on Apple. Delving deeper, Mohan said that the company's benefit in agentic AI comes from its semiconductors and iOS, as Apple's silicon can dictate what happens on a devices (which is important for latency, reliability, privacy and costs) and iOS will determine how the AI is used by the user. “Our analysis around token usage suggests Apple will need to rely on distributed compute (on device), Private Cloud Compute and third-party compute to deliver a robust AI experience,” Mohan added. “Removing the net cash neutral target, in our opinion, is a reflection of a new period of AI-driven investments to enable this agentic era.”
As such, Mohan believes that the coming Siri redesign needs to be integrated into the iPhone and make it an agent that is capable of understanding intent, retrieving context, bringing up apps, and completing workflows. If this were to happen, an agentic version of Siri could boost fiscal 2030 revenue between $15B and $30B, or as much as $40B to $65B if users really became acclimated to it.
Why the most common measure for valuation is inadequate in an age of AI
Software and services companies like Google, Microsoft, Amazon, Meta are spending on Capital Expenditures at the rate of heavy industry manufacturing. This defies their description as "asset light" business models which depend on services, distribution or platform economics.
The problem isn't just semantic. It is that for their entire existence, these companies were valued for their profitability and measured in terms of a P/E ratio and earnings growth. The situation has changed dramatically. Their revenues are up, the earnings are up and growth is up and share prices are way up. But not their P/E ratios. Why is this?
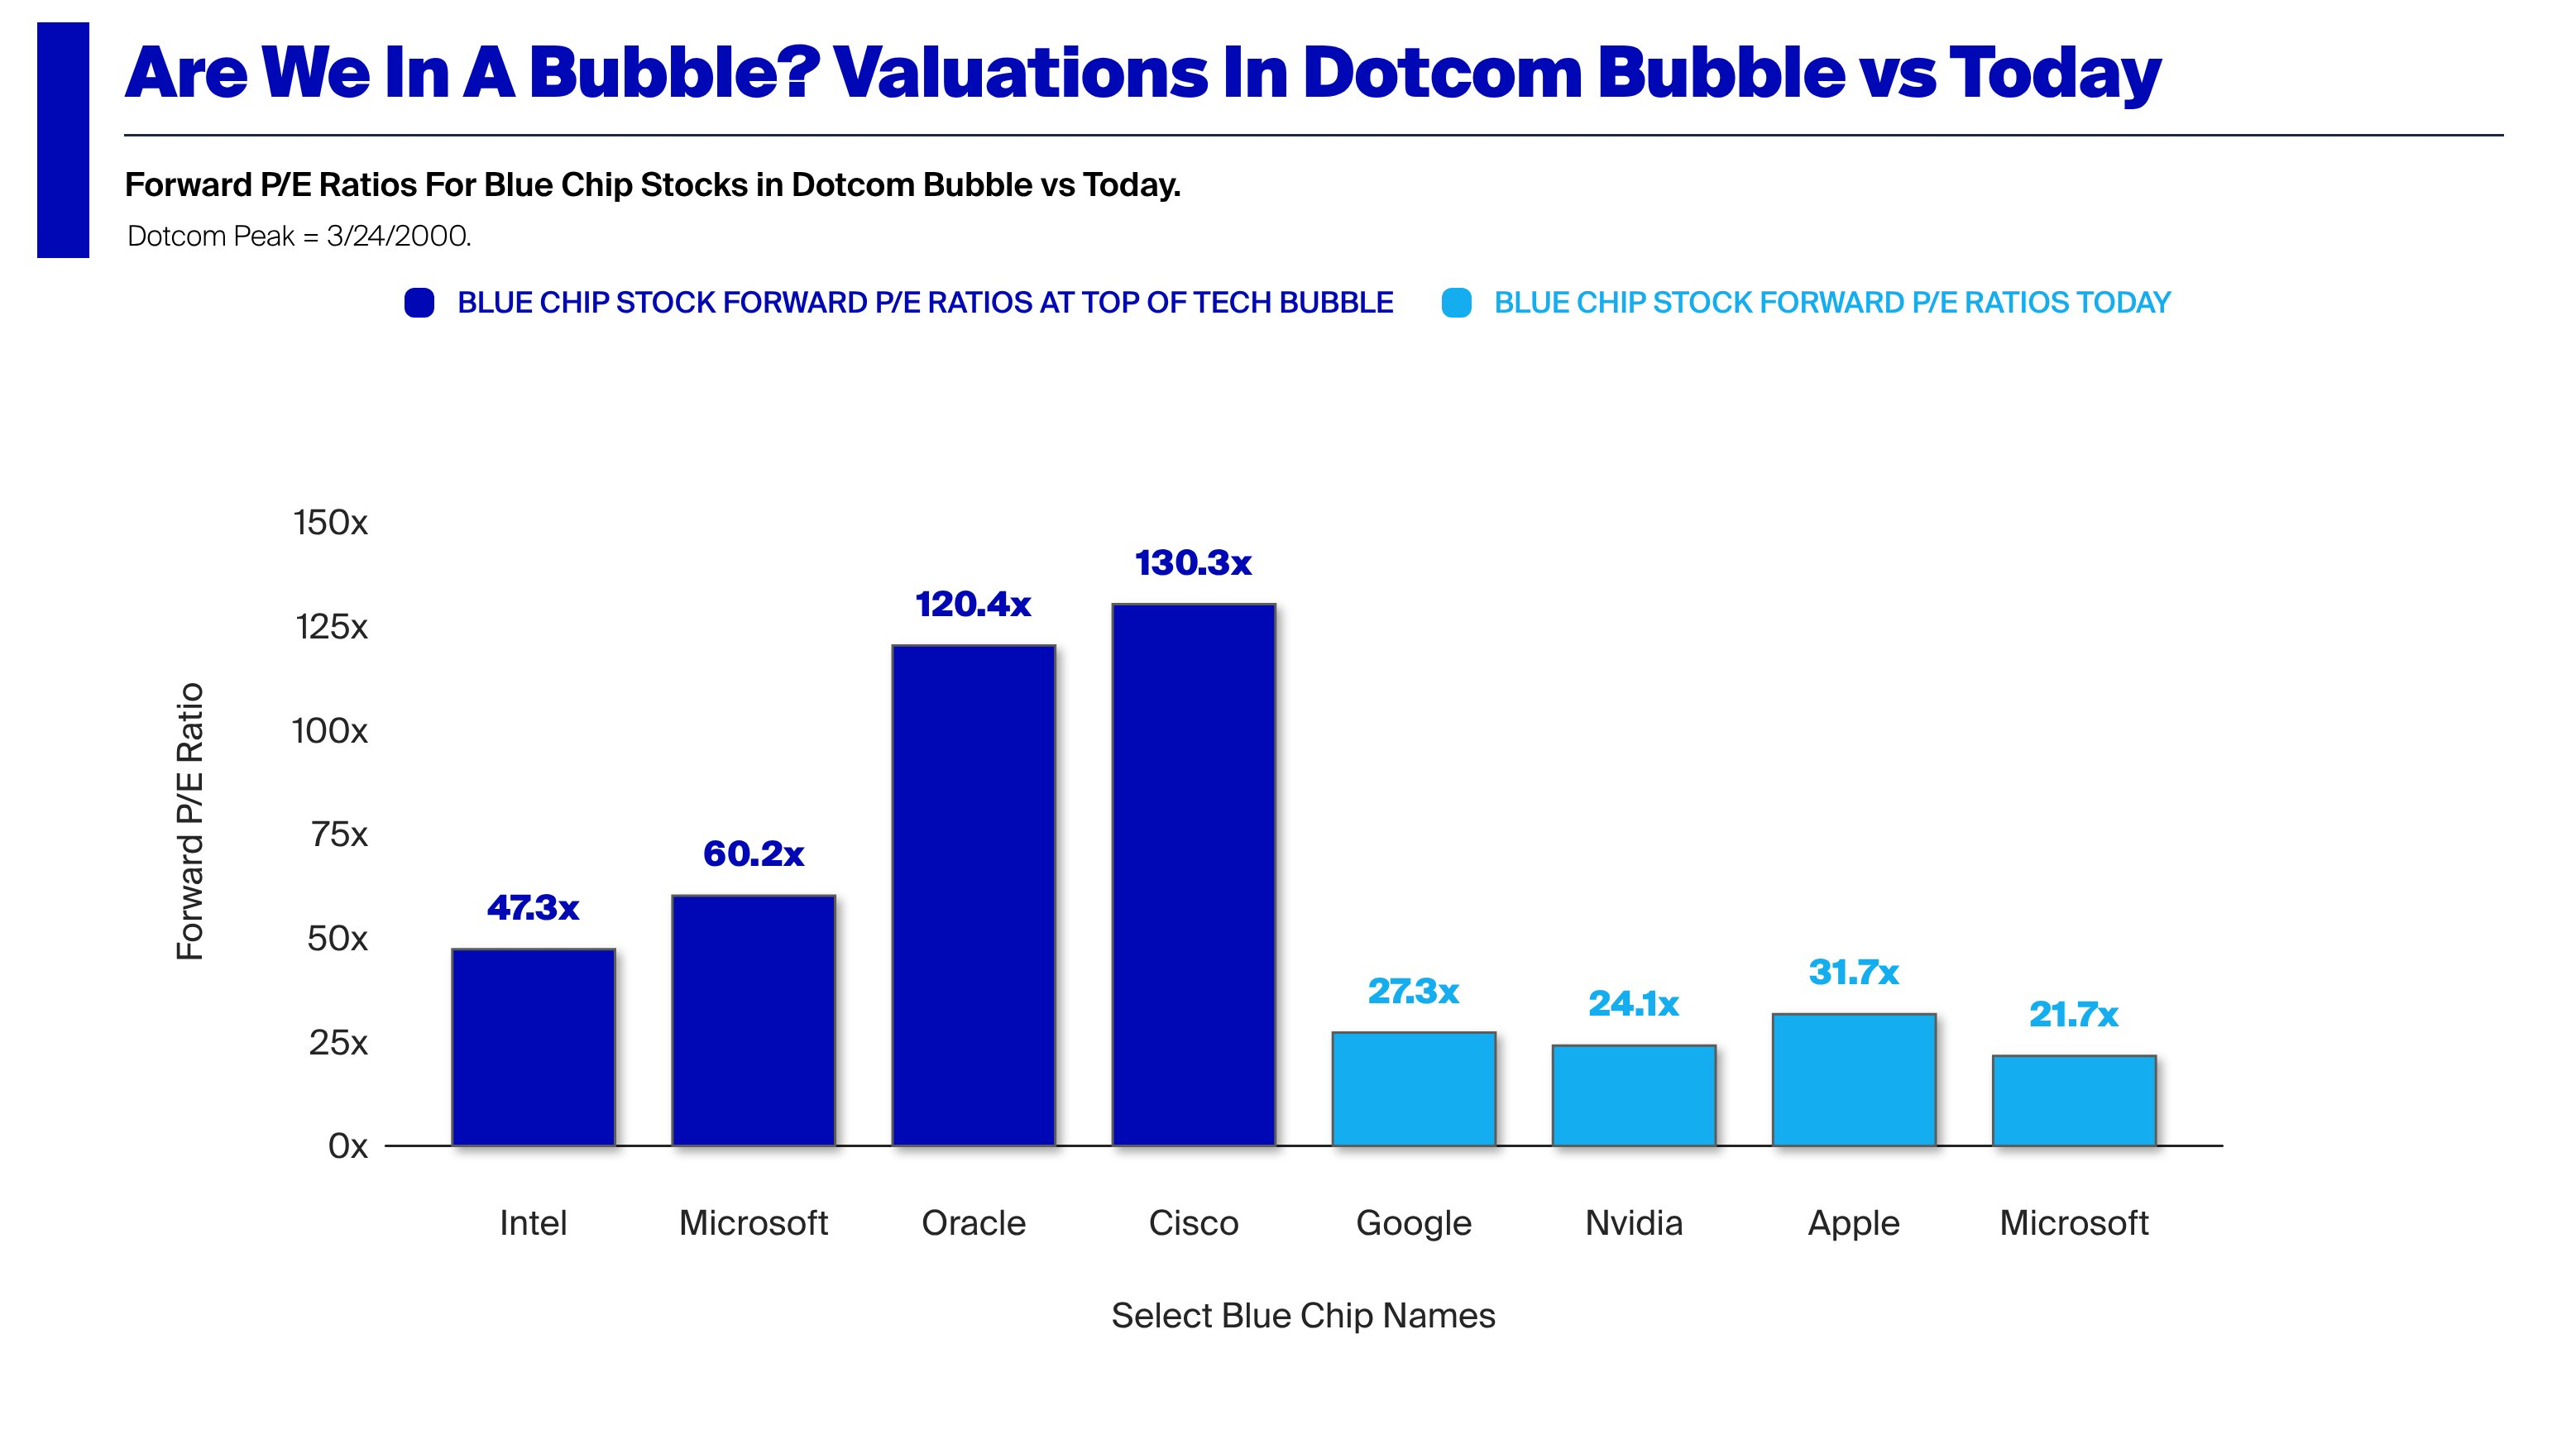
Consider the graph below showing the (forward) P/E ratios of the Dot Com market leaders vs. the market leaders today.
This even as share prices and value concentration have risen even faster than in the Dot Com era. Seen from the P/E basis, it does not look like we are in a bubble. Earning growth is way up so the share prices are not outrageous on that basis. That is contrary to 1999 when P/E ratios in the hundreds were considered normal. Expectations of an internet fueled boom were speculative. Expectation of an AI earnings boom seem well founded.
But these companies could still be over-valued. The P/E ratio is not the full picture. It is in fact a simplifying shortcut which ignores significant pockets and omissions of value.
For this analysis I'll use a sample including some of the largest market caps in the world with two exceptions. The exceptions are Lilly (LLY), Berkshire Hathaway (BRK-B) which are on the list but not in the top 10 (though in top 15) and Saudi Aramco and Broadcom which are in the top 10 but not on the list[1].
Company
Market Cap
NVDA
$5,709,746,405,376
AAPL
$4,379,916,369,920
GOOG
$4,811,891,146,752
MSFT
$3,041,424,048,128
AMZN
$2,874,514,866,176
TSM
$2,166,463,135,744
TSLA
$1,664,912,326,656
META
$1,569,837,154,304
BRK-B
$1,044,046,610,432
LLY
$897,716,060,160
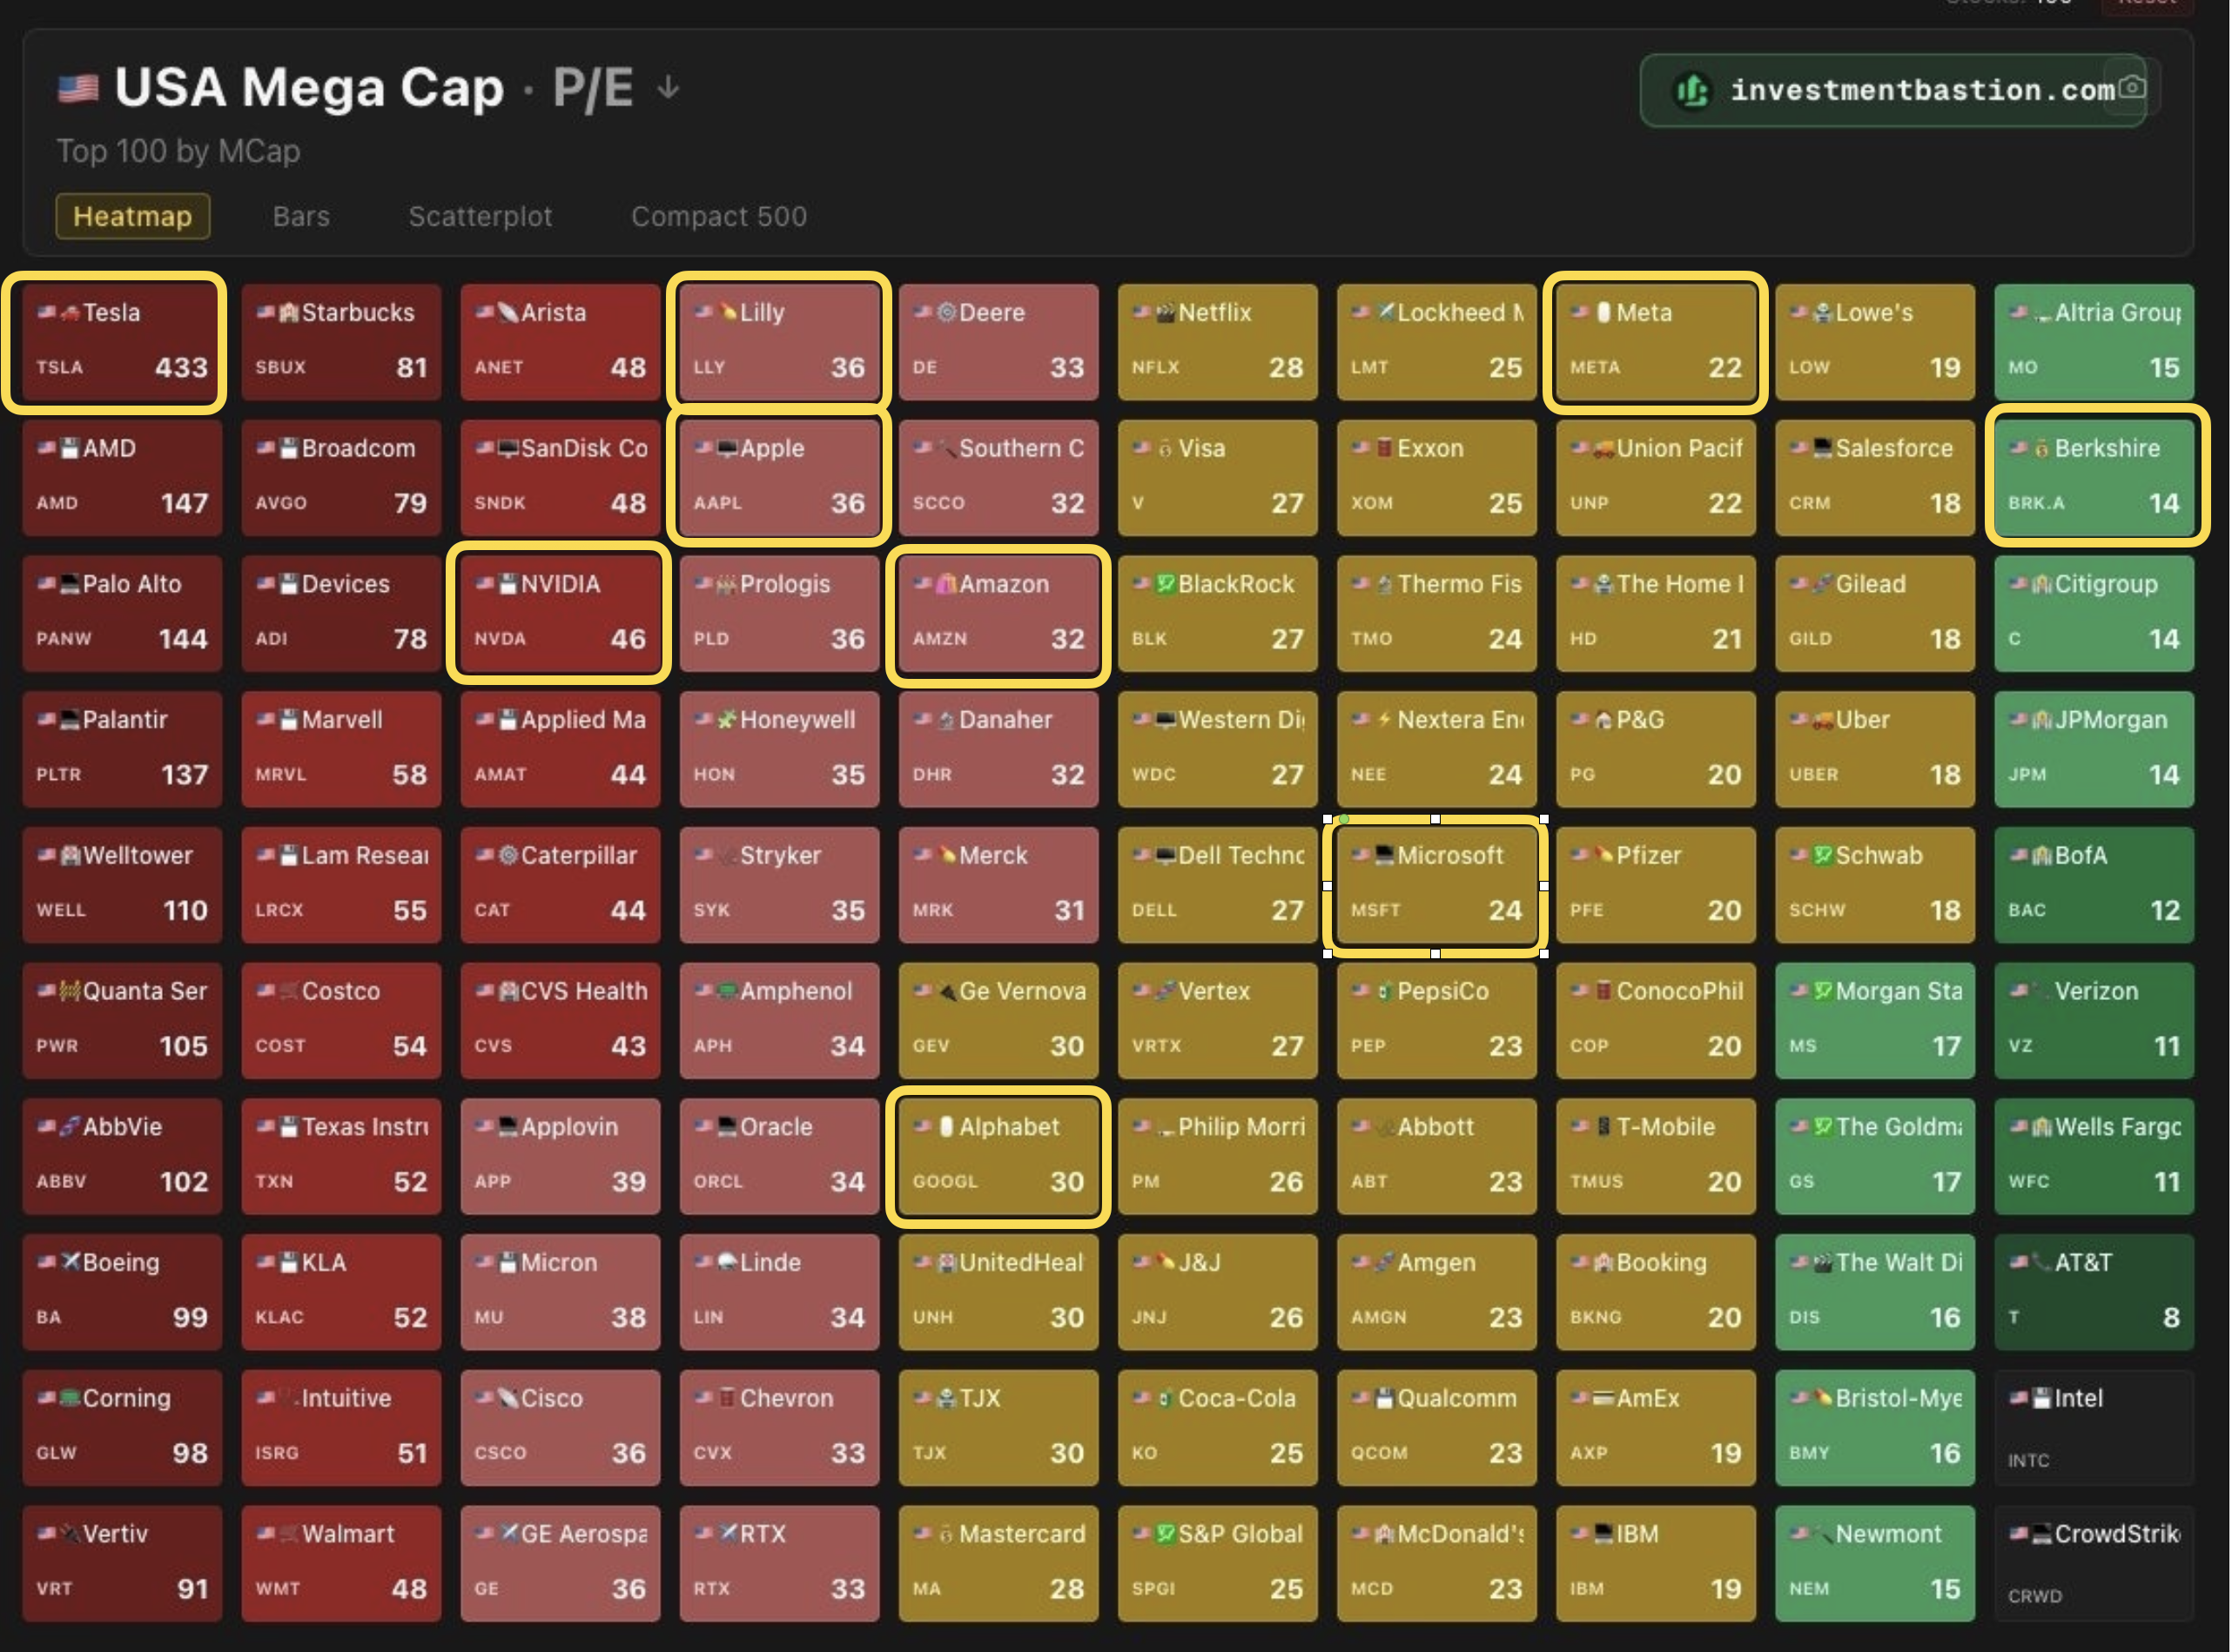
The following diagram shows the P/E ratios of the sample relative to the top 100 US market caps[2]. Note that, with one exception, the companies are not in the dark red zone with above P/E of 60. The exception is, of course, Tesla, which, at P/E of 400+ is 14x the average multiple.
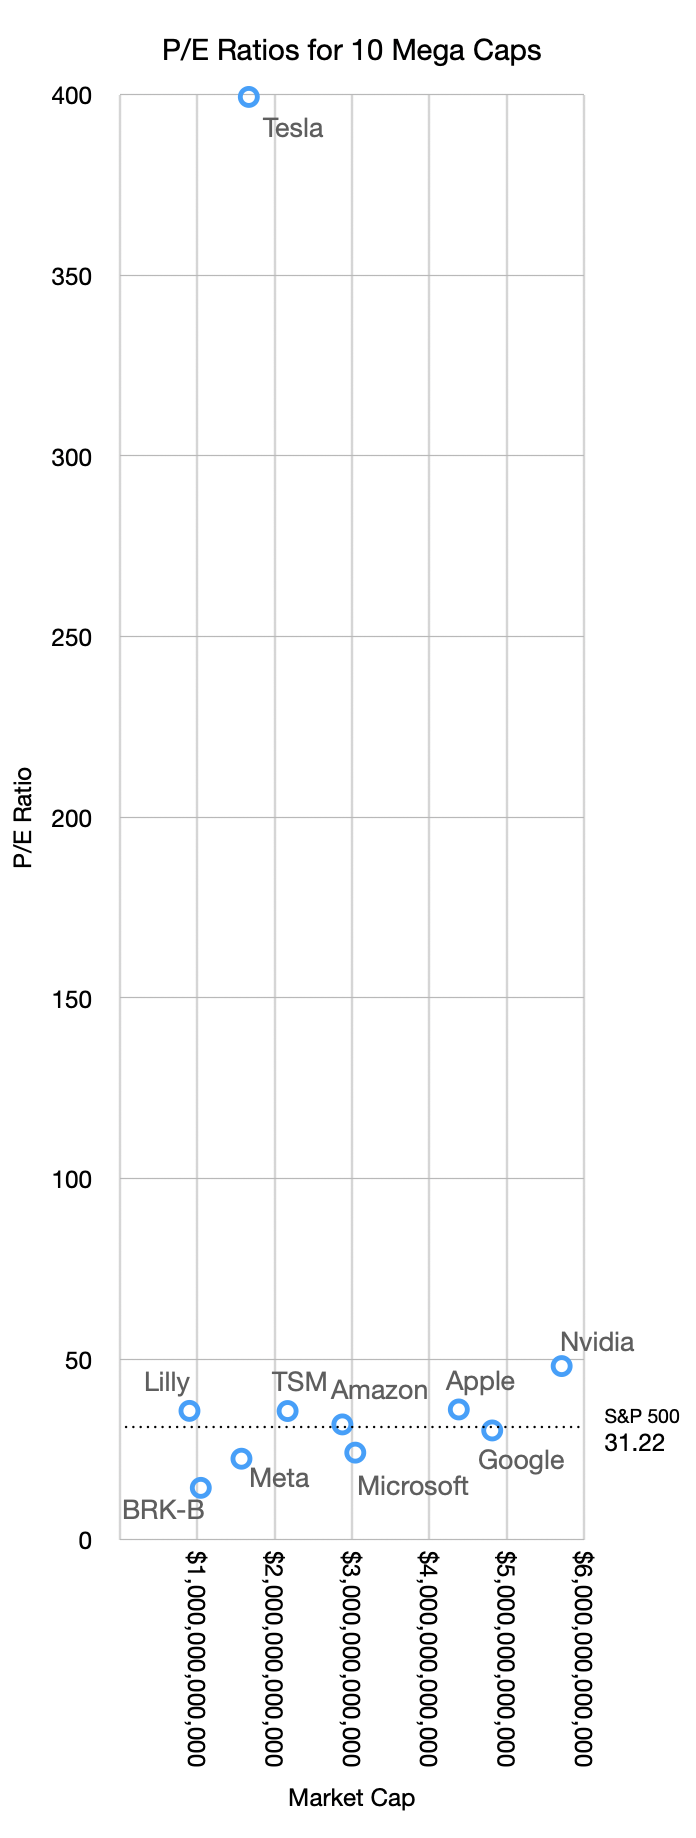
Moreover, compared with the S&P 500, these P/E ratios are in-line with the median. The following graph shows the sample set with P/E ratio vs. Market Cap.
Excluding the one anomaly the relationship seen is that higher market caps roughly correspond to higher P/Es. Nvidia has a market cap over $5.7 trillion with a P/E of 48 while Meta has a market cap of $1.5 trillion and a P/E of 22.5.
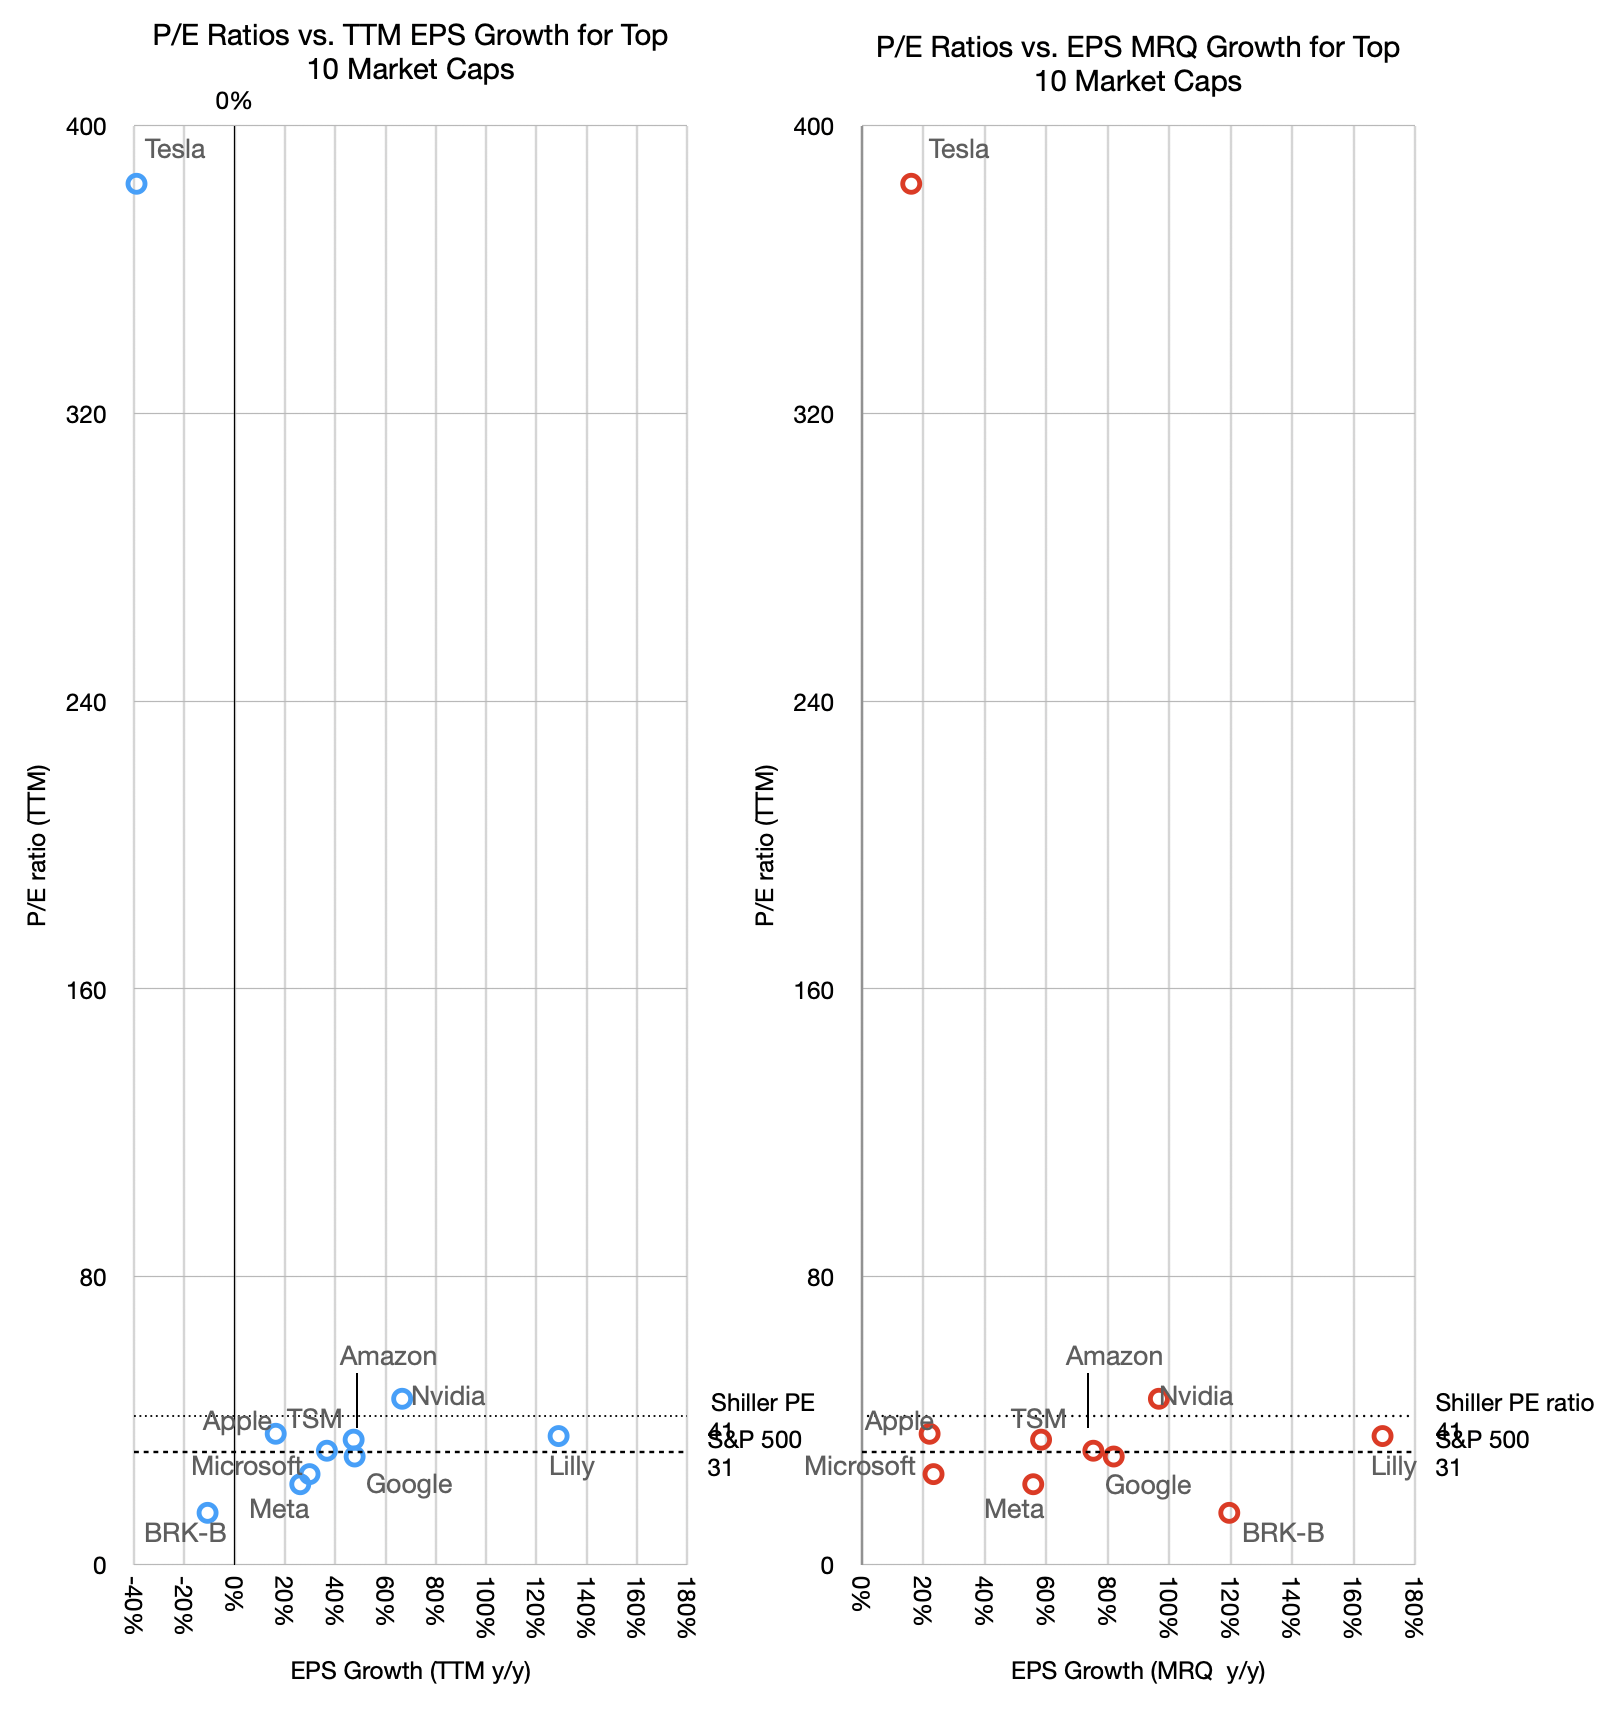
Higher P/Es should also correspond to higher growth rates. The graph below shows the relationship between P/E and growth, both in the most recent quarter (MRQ) and trailing twelve months (TTM).
There is a loose relationship between P/E and TTM growth but not with last quarter's growth. The one anomaly is even more prominent as it shows negative growth with exceptional valuation. Fundamentally however the relationship between P/E and growth is weak. Companies having widely divergent growth show similar P/E ratios. Alphabet for example has seen its P/E ratio in the 20s with growth in the 80s TTM and 50s MRQ.
This might sound familiar. From 2008 to 2020 Apple was trading at a P/E ratio in the teens and low 20s while growing as fast as 80%. The logic was captured by my analogy of the goose that lays the golden eggs. Apple was able to create extraordinary products but the market considered such hits fleeting. It valued consistency over heroism. Getting on base vs. home runs. And so the P/E began to rise only once Services became more prominent. Regardless of how foreseeable this pattern was, it took a decade and is still ongoing for the pricing to catch up.
But the situation with AI companies (that is, all the big tech companies but Apple) is that their earnings today are somewhat an illusion.
An old maxim that says "earnings are an opinion while cash flow is a fact.[3]"
This is because Net income can be manipulated by accounting abstractions, whereas cash flow is based on bank transactions.
To wit: Net income (earnings) is calculated using accrual accounting, which relies heavily on judgment calls rather than bank balances. Companies recognize revenues the moment a contract is signed, even if the cash won't be collected for months. Or they can dial in a delay as they desire.
Because of varying accounting policies, two identical companies with the exact same physical business can report vastly different earnings figures.
Cash flow is objective and simply tracks the actual movement of money in and out of the business. Real dollars either enter the bank account or they don't. A company can look highly profitable on an income statement but still go bankrupt if its cash is trapped in unpaid invoices or unsold inventory.
Finally, cash flow can be strongly negative while earnings are strongly positive. This is because investment in capital equipment does not appear in the income statement.
Therefore true economic value is determined by the cash a company can actually distribute or reinvest rather than how it declares profitability based on accounting abstractions.
AI companies are not necessarily hiding behind suspect earnings but their extraordinary capital expenditures are draining their cash and thus what investors have access to.
Earnings seem to be soaring so the ratio P/E suggests a modest valuation. This is based on opinion or at least incompleteness.
We should look at a better indicator. It's the EV/FCF ratio. We will look at this next.
The top 10 ranking can change rapidly and it makes analysis difficult over longer time periods. The inclusion of LLY and BRK-B allow for visibility outside of the tech sector and they were in the list mid 2025. Saudi Aramco is in a completely different environment influenced by non-economic factors.
TSMC is absent from the table as it is US only companies. It is notable perhaps that of the top 15, three are not US companies (TSMC, Samsung and Saudi Aramco). Furthermore the top Chinese company, Tencent is 25th, valued at $532 billion and the top European company is ASML at 21st and $610 billion.
Takeshi Narabe • 06:41 So you also compared [Apple] with the Japanese companies. Actually Japanese companies are very keen on marketing and doing some anchors many times. And I think [historically] they didn't know what consumers want. But you mentioned that is also […] their advantage […] because they only made what [management] wanted. But on the other hand, Apple exceeds the consumer's expectation or make a new market.
Horace Dediu • 07:37 The story of Japanese innovation is fascinating and I hope you give me a little bit of time to reflect upon this because I think it is also part of the story of Apple. I have a great admiration for the history of Japanese innovation. And it was something that, again, Professor Christensen taught me and made me appreciate.
Of course, during the 1970s, and maybe even earlier, but at least from the 70s onward, Japanese innovation was the world leader. It was in consumer electronics, it was in automotive, it was in many heavy industries, it was phenomenal. And the reason a lot of that happened was because Japan was constrained. Japan didn't have access to as much capital or as much land or as much resources as a lot of the industrial nations at the time. And those constraints taught it to be lean and efficient and how to think about "just in time", the Toyota production system, etc. And that wisdom came from a constraint.
As a result, Japan [began to] teach the world during the 90s and onward about how to do better manufacturing. And they taught Apple. Apple at the time was in awe. Steve Jobs was in awe of Japan. Nobody could come close. Also, Sony was a phenomenon. In fact, in interviews with executives; I was just watching an interview with [Jon] Rubinstein, who was at the time heading the iPod.… He said they were absolutely paralyzed with fear that Sony would beat them at this game. Even though [Apple] were by far the market leader, […] it wasn't Microsoft, it wasn't Motorola, it was Sony that was the worry.
Now, what happened? I think one of the things that Christiansen doesn't say--[which I do] because I come from a software engineering background--one thing that I think Japan didn't understand starting in the late 90s was the power of software. And I think it's a cultural problem. Software has a different culture fundamentally. The software engineers in general are like cats. You know, managers want to manage dogs because dogs are predictable and they tend to follow the instructions. People who do software tend to be very much more independent, but they need to be coordinated.
So it's a very difficult management problem, and it doesn't fit so well, perhaps, with corporate culture in Japan, at least at the time we're speaking of. And so one of the aspects, I think, that was critical in the late 90s was this, I would say, cultural crisis. By the way, it's also a problem in Europe. One of the reasons Europe did not succeed with software was precisely because of the cultural aspects as well.
But that's one element and I think it's not the only element but you address the question of customer understanding and this is very crucial as well. I think the Japanese were for many decades thinking that if you build good things, especially as they were better than what was in the market, then customers will buy. Simply focus on quality and the customer will decide eventually to switch.
That's a very logical decision, a very logical plan. And you don't have to worry too much about marketing and branding and all of these aspects, which are again, perhaps a cultural difference. Or you could hire someone to do that for you, but fundamentally the management inside Japan couldn't think in the same kind of marketing ways that American marketers would think.
But as far as the customer discovery problem, this is true. And it is something even American companies don't know how to do, or European companies don't know how to do. […] The way Apple suggested they do it (this is what they've told us,) is that they have to talk amongst themselves. They talk to each other as they did about the iPhone and said: "What do we dislike about our phones? How can we make them so more usable?"
And this fundamentally is because they always had this inquiry internally about why are things hard to use? Why can't we make things easy? Some of that is evident in Japan, but I think it wasn't thought of through the lens of interfaces. It was thought of more like being compact, being portable, being good [to the touch]. But it wasn't as much about how do you interact visually with something. A lot of things go into that. Obviously, you have to have a different sensibility about the two-dimensional display and so on. [1]
And so my point is that the Japanese weren't stepping back enough and asking these, what Christiansen would call, jobs-to-be-done questions. "What do people really want to accomplish with products", even if we haven't yet envisioned what they are? How do we work, how do we think about these design questions. Designers, by the way, say "we don't just make things look good. We think about how they are to be used". You know that philosophy of deeply understanding the user behaviors that is part of the Jony Ive philosophy. But it wasn't just him. It was before him and after him. [Apple designers] have been thinking the same way.
So it's a design philosophy. It's a real introspection, asking yourself, how should the world be? How should we improve the lives of people? And that's hard to really be very concise about. So I apologize, I'm [going on] so long about it. But it is part of the decision, part of the culture, again, of Apple, where they are looking at themselves.
Famously, by the way, this is another anecdote about Apple. It is that they don't do focus groups. They don't obtain that [product] knowledge by surveys. They don't obtain it by asking even indirectly what the customer wants or gathering loads and loads of market data. Lots of [research] companies will sell you market data and tell you all kinds of insights, cutting everything into demographics, into segmentations of various kinds.
The theory of jobs[to be done] is that usually you need to ask [only] five people. You don't need a large sample. You don't need to survey 10,000 people to find out that there's a desperate need for companionship. Should a machine be a companion? That's a very basic question.
A question which is, by the way, answered by AI. A lot of AIs are just hired as companions. But you don't discover this by surveying what people own today or what they're buying today, [or] what they ask for. You observe and you maybe do a little bit of inquisition on the spot and you just tease the customer's intentions.
I said many times, many of the best [product] ideas are taboo[2]. [For instance] People do things on social media which were once considered not just impolite, but sinful. You know, the idea of being vain is a sin. The idea of bragging and being boastful is considered sinful or [at least impolite]. And I used to say that all the social media can be segmented on the seven deadly sins that were part of the [moral] conversation centuries ago.
It was the church who would say these are bad things you shouldn't do them. Gluttony or covet thy neighbor. Every single social media is positioned precisely on [one] sin. Now, the discovery of this wasn't because Facebook surveyed what people do as sinful and provided it to them. Rather, they gave options and then the algorithm discovered it in a way. Apple [by the way] chose, I think [wisely], to stay out of there.
But you can see how the discovery of social media didn't come from a process of surveying people, asking them what would they like. They would have said "I want to have communications" or "I want to have cheap communications." They wouldn't say I want to send selfies, (which by the way didn't exist,) of myself doing everything all day long.[3]
What I was trying to say here was that the Japanese approach to the display of two dimensional information is different due to the writing style. Japanese visual layouts are denser and more information-rich--some would argue more beautiful. There is less of an expectation by the consumer for simplicity which implies an acceptance or even appreciation of complexity.
By taboo I mean unspoken prohibition, something implicitly forbidden or embarrassing. To which nobody would admit to or request.
Narcissism is an observed behavior predating Christianity and the 7 sins. It was named after the Greek mythological figure Narcissus who fell in love with his own reflection, popularized at least by Ovid before 8 AD.
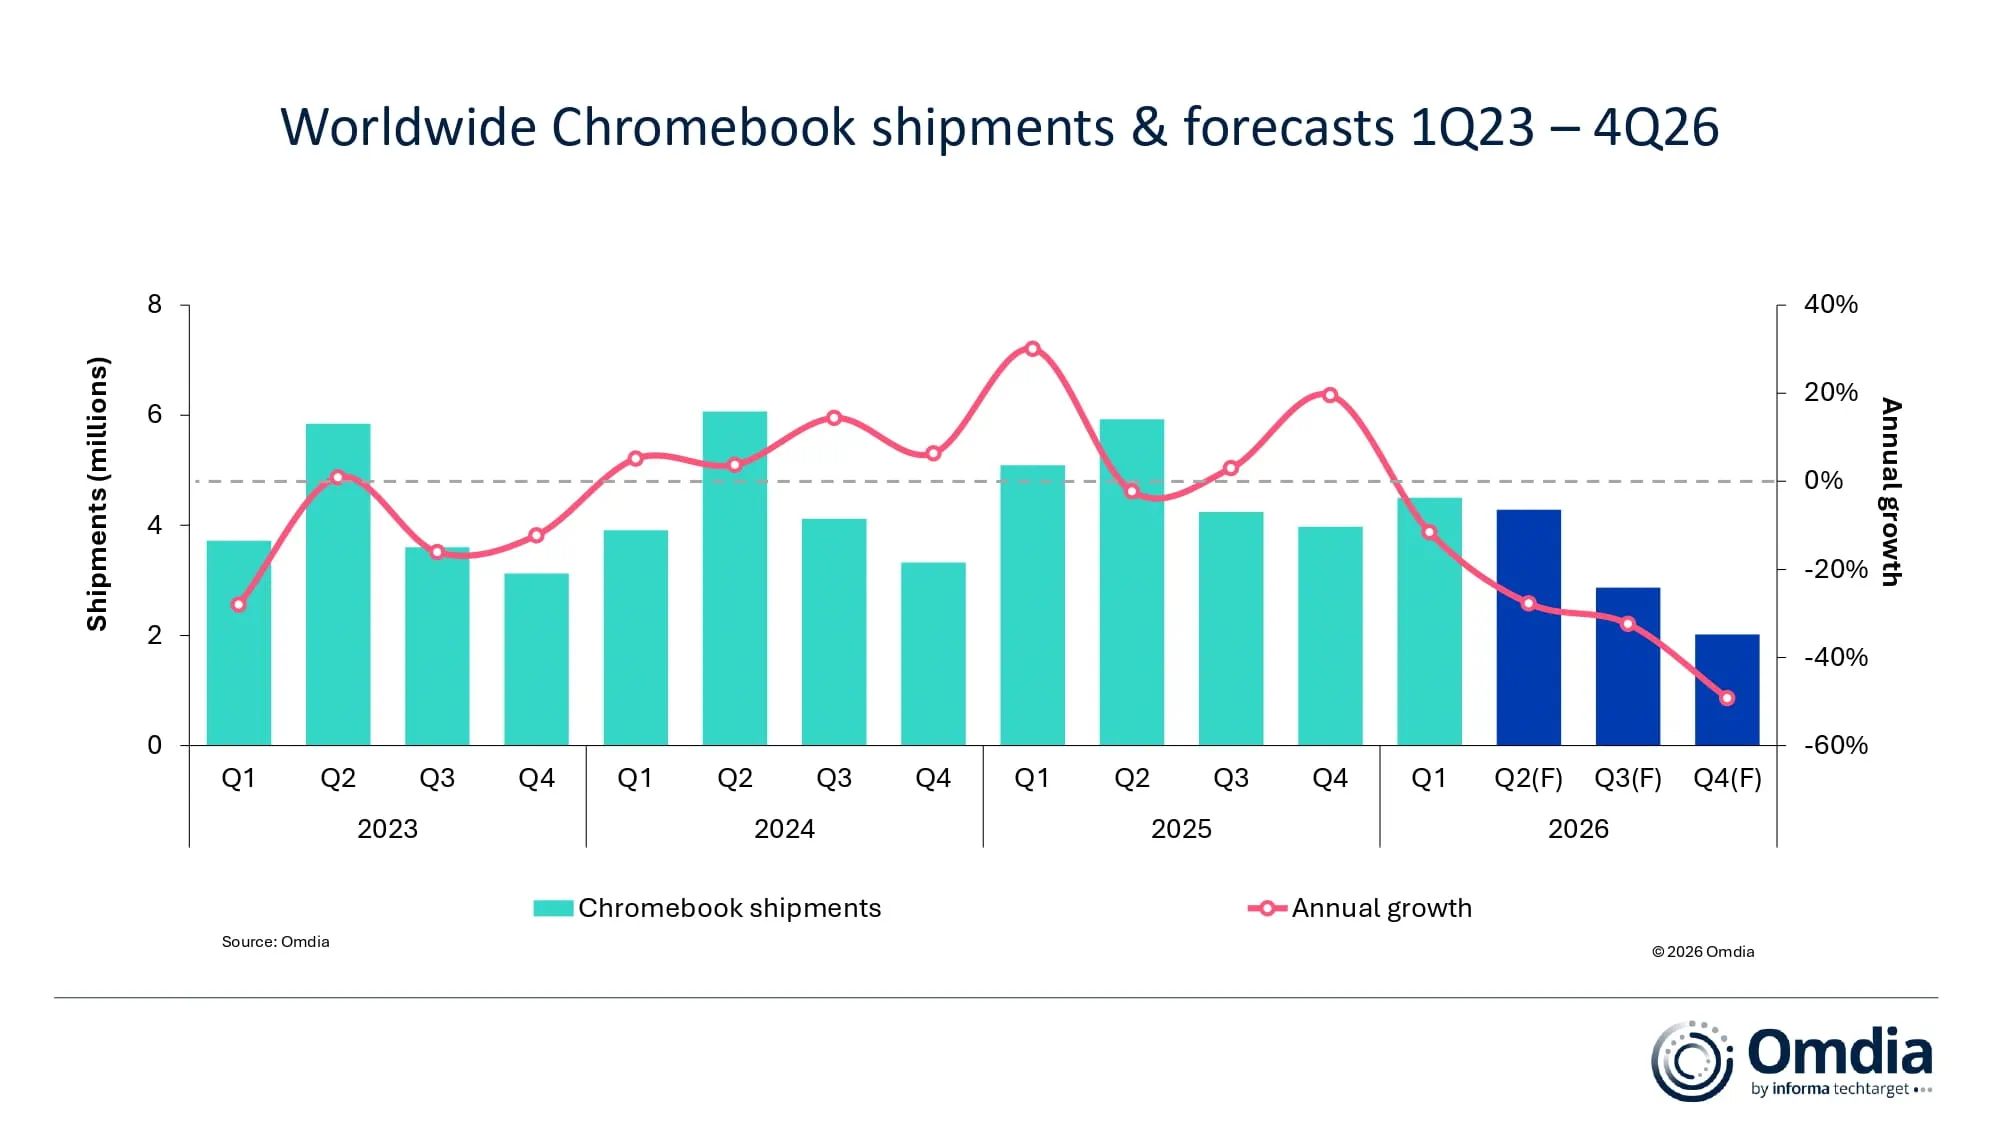
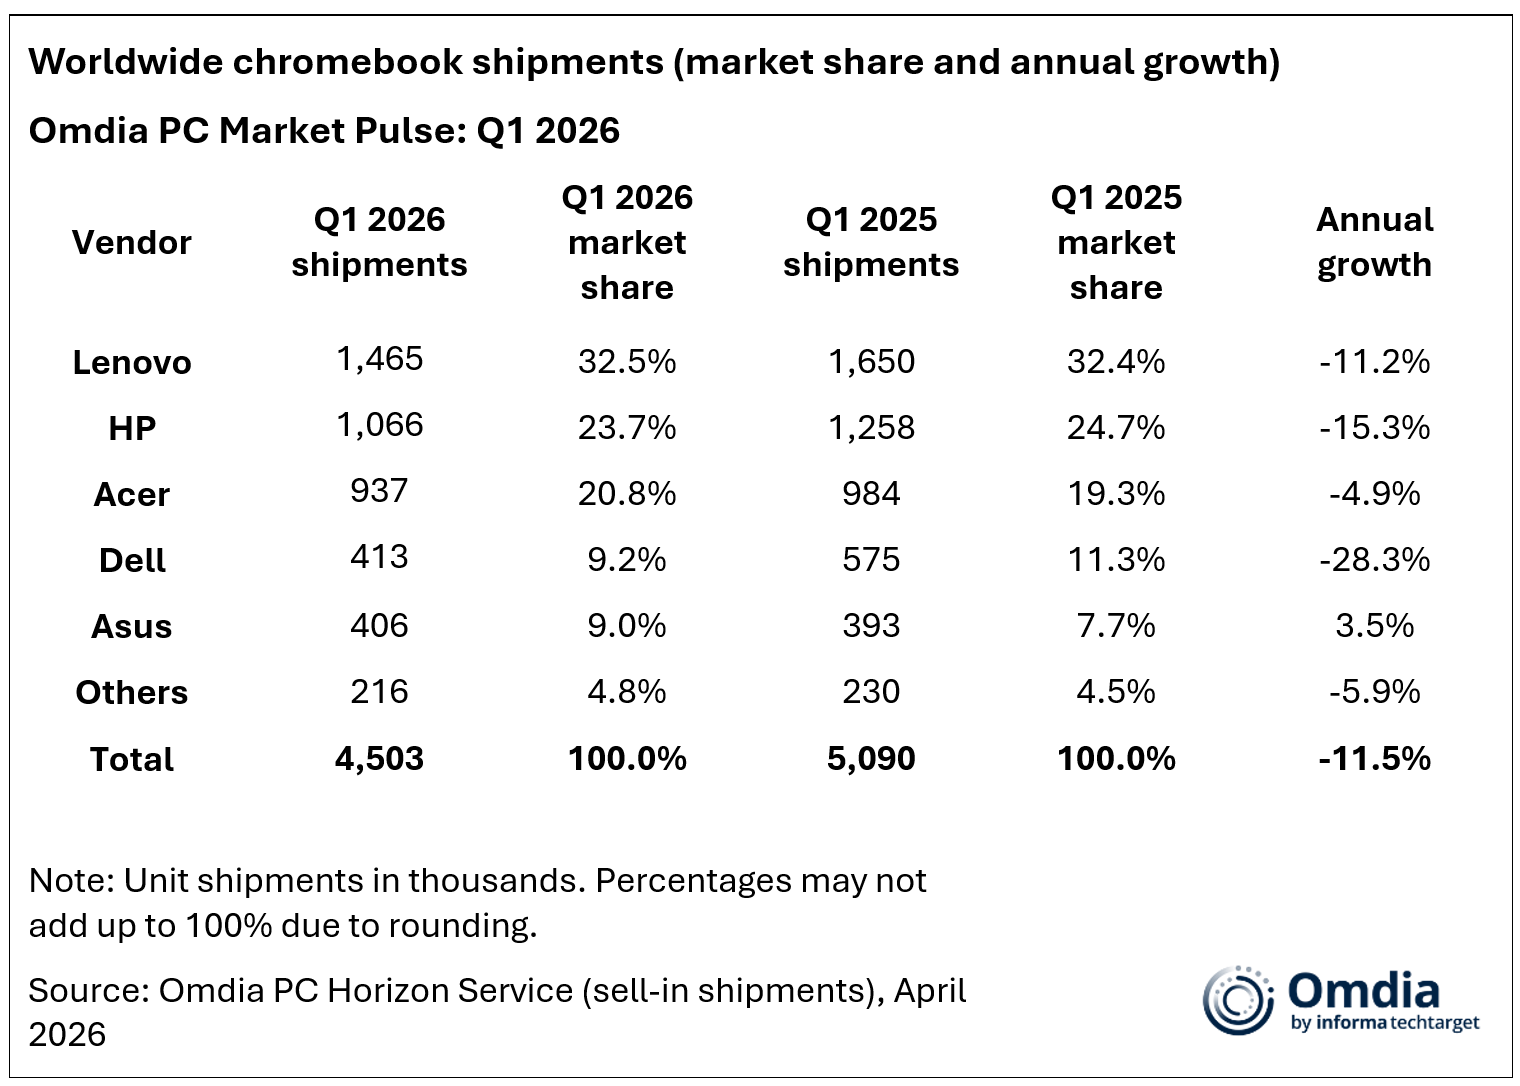
“Within the PC segment, Chromebooks are currently the most impacted category, with volumes declining significantly,” said Kieren Jessop, Principal Analyst at Omdia. “Production indicators point to a weak near-term outlook, and education-related deployments are increasingly being deferred until market conditions stabilize. Ongoing supply constraints are also expected to delay the second phase of Japan’s GIGA School Program 2.0. While the first phase - extended from end-2024 through end-2025 - was completed without major disruption, the current supply environment is likely to introduce delays in the next phase.”
All major Chromebook vendors faced challenges in Q1. Lenovo, which ranked first and was a key participant in Japan’s GIGA School Program alongside its subsidiary NEC, saw shipments decline 11.2% year on year to 1.5 million units as the first phase of deployments concluded. HP ranked second, shipping 1.0 million units, down 15.3% year on year. Acer placed third with 937K units, managing a relatively smaller decline supported by stable shipments in North America and increased shipments into APAC. Dell experienced the steepest decline among the top five vendors, with shipments falling 28.3% year-on-year to 413K units. ASUS, another key participant in Japan’s GIGA School Program 2.0, was the only vendor to record growth in Q1, with shipments rising 3.5% year on year to 406K units, accounting for a 9% market share.
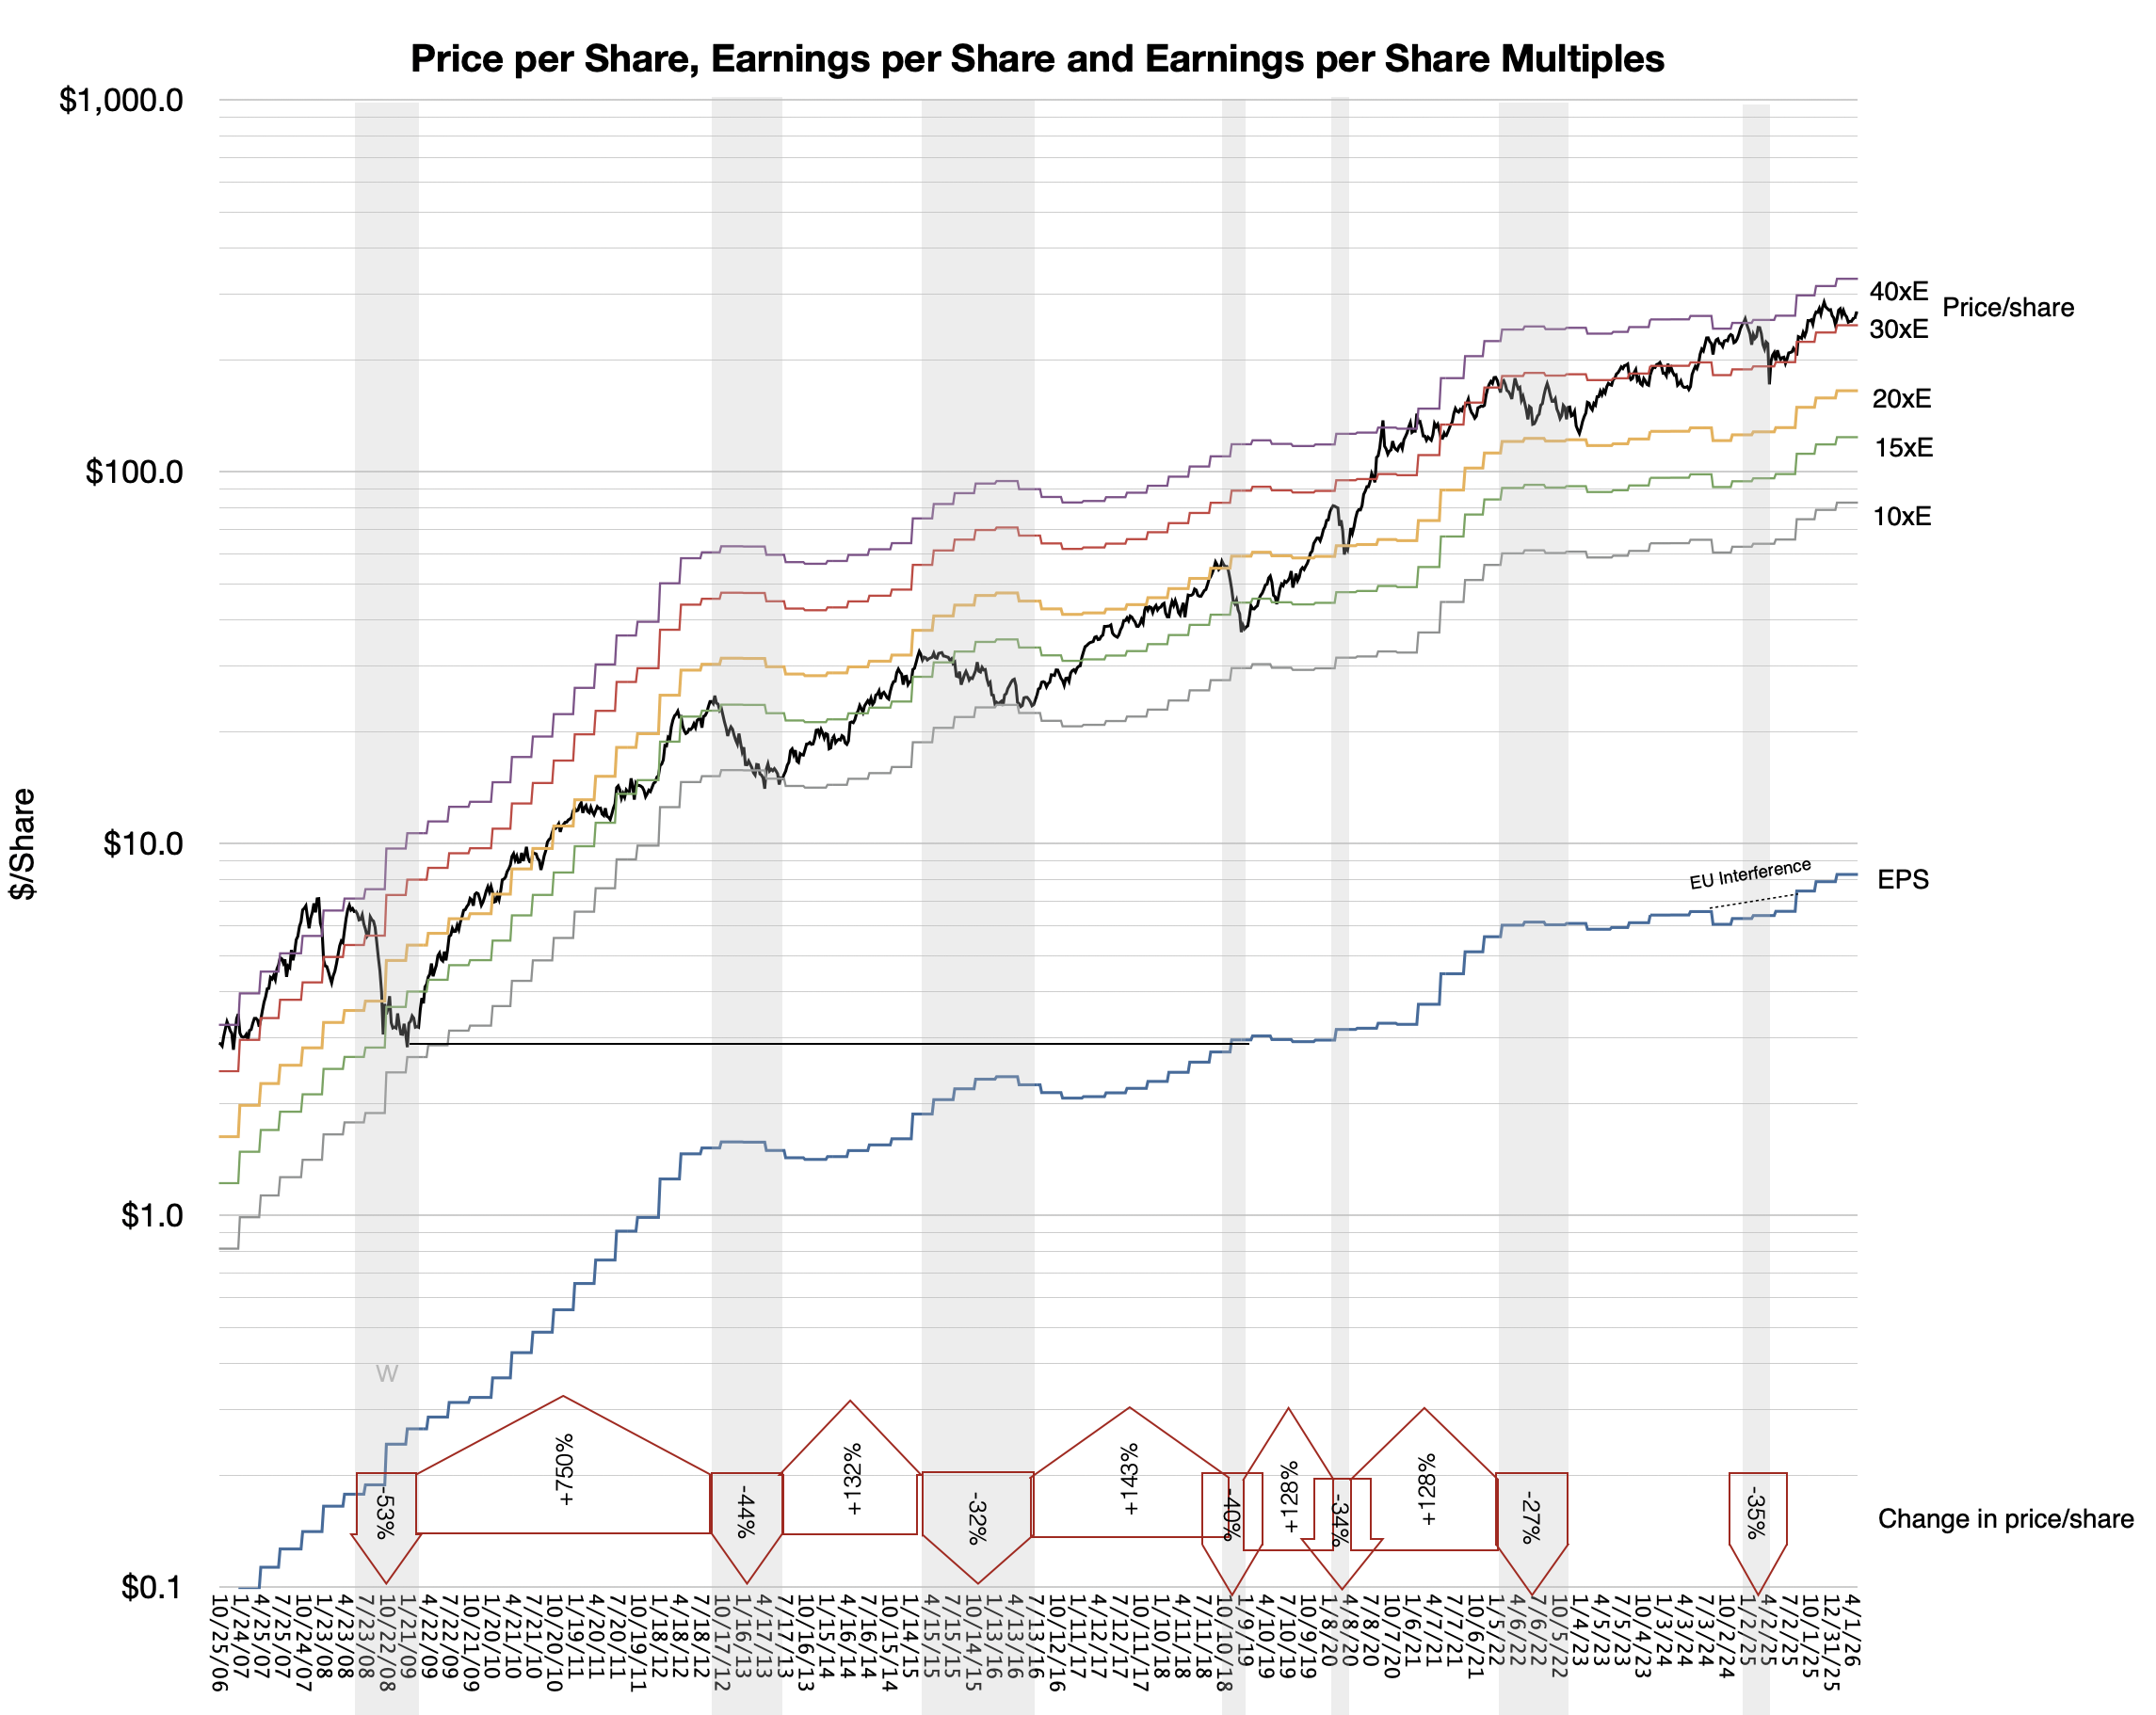
Apple recently hit an all-time high. Today the stock is trading at a P/E of 35. The P/E ratio is the current share price P divided by the last four quarters’ net earnings per share E. But we also have a pretty good idea of the earnings for the next quarter, ending June (now almost half-way completed). The guidance very clearly suggests that on a one Quarter forward basis the P/E ratio is 34.
I’ve maintained for at least 15 years that a reasonable multiple for Apple is 35. This was mainly because other large cap technology companies were also trading around that number. While at this ratio, if a company is growing at 22% it means that an investor will make their money back in about 10 years. Thereafter all free cash flows will go entirely to the investor’s pocket. That seems a reasonable return. It’s not a particularly risky bet to assume 20% growth for 10 years if you look at (a) history and (b) how many people in the world have not yet started using Apple products and (c) assess how well management is doing their job.
So by this measure, Apple seems to be reasonably priced. Historically it has not been reasonably priced but that is due to the disconnect between understanding the business and falling for the usual false tropes. The following graph shows the share price and where it fell between the bands of Earnings multiples. The grey areas represent periods of significant share price decline.
But much of the volatility of the stock is also due to overall sentiment collapse. That has happened on many occasions, most notably the 2008 financial crisis and “great recession.” (Another was the Covid crisis.) In these cases, regardless of underlying strength, the shares were available very cheaply.
Today perhaps we should ask if a bubble is forming due to exuberance around AI which is inflating the market in unsustainable ways.
There are four reasons why the current asset value explosion is different.
First, it is highly concentrated in a handful of names.
2005 S&P 500 top 10
% of the S&P index
2026 S&P 500 top 10
% of the S&P index
Exxon
3.1%
NVDA
7.8%
MSFT
2.5%
GOOG
7.3%
Citigroup
2.2%
AAPL
6.4%
GE
2.0%
MSFT
4.6%
Walmart
1.7%
AMZN
4.4%
BoA
1.6%
Broadcom
3.0%
J&J
1.6%
TSLA
2.4%
Pfizer
1.4%
META
2.3%
Intel
1.3%
Walmart
1.6%
AIG
1.3%
Berkshire Hathaway
1.5%
Total
18.7%
41.3%
Second it is fueled by equity not debt. Third, it involves disproportionate capital expenditure rather than M&A. Fourth it is accompanies by sharply growing revenues (though not as sharp as investment growth.)
In other words, whereas the equity value is growing rapidly, so is income and investment without leverage. This is a low-debt with high income scenario. Previous crises were high income with high debt (2008) or low income with low debt. (Dot Com).
That’s not to say that we have uniform fair equity values. We need to do quite a bit more due diligence to determine the state of the valuations precisely because we have unusual capital allocation strategies.
To cover this topic I’ll will break the analysis into multiple posts. They are:
Why the most common metrics for valuation are insufficient — the problem with the P/E ratio
What are the alternatives that into consideration exceptional cash and capital expenditures — The EV/FCF ratio
How does the P/E ratio differ from EV/FCF and what does it mean if they diverge one way or another
How do the Mag 7 et. al. appear on these Metrics
How to complement snapshots like valuation ratios with the time series of fundamentals
Why payback measures are the ultimate measure of valuation
What are the current payback measures for the Mag 7 et.al.
Compare Apple to its peer group
Finally assess whether a collapse in confidence is imminent
Please return to these pages in the next few days to read these posts.
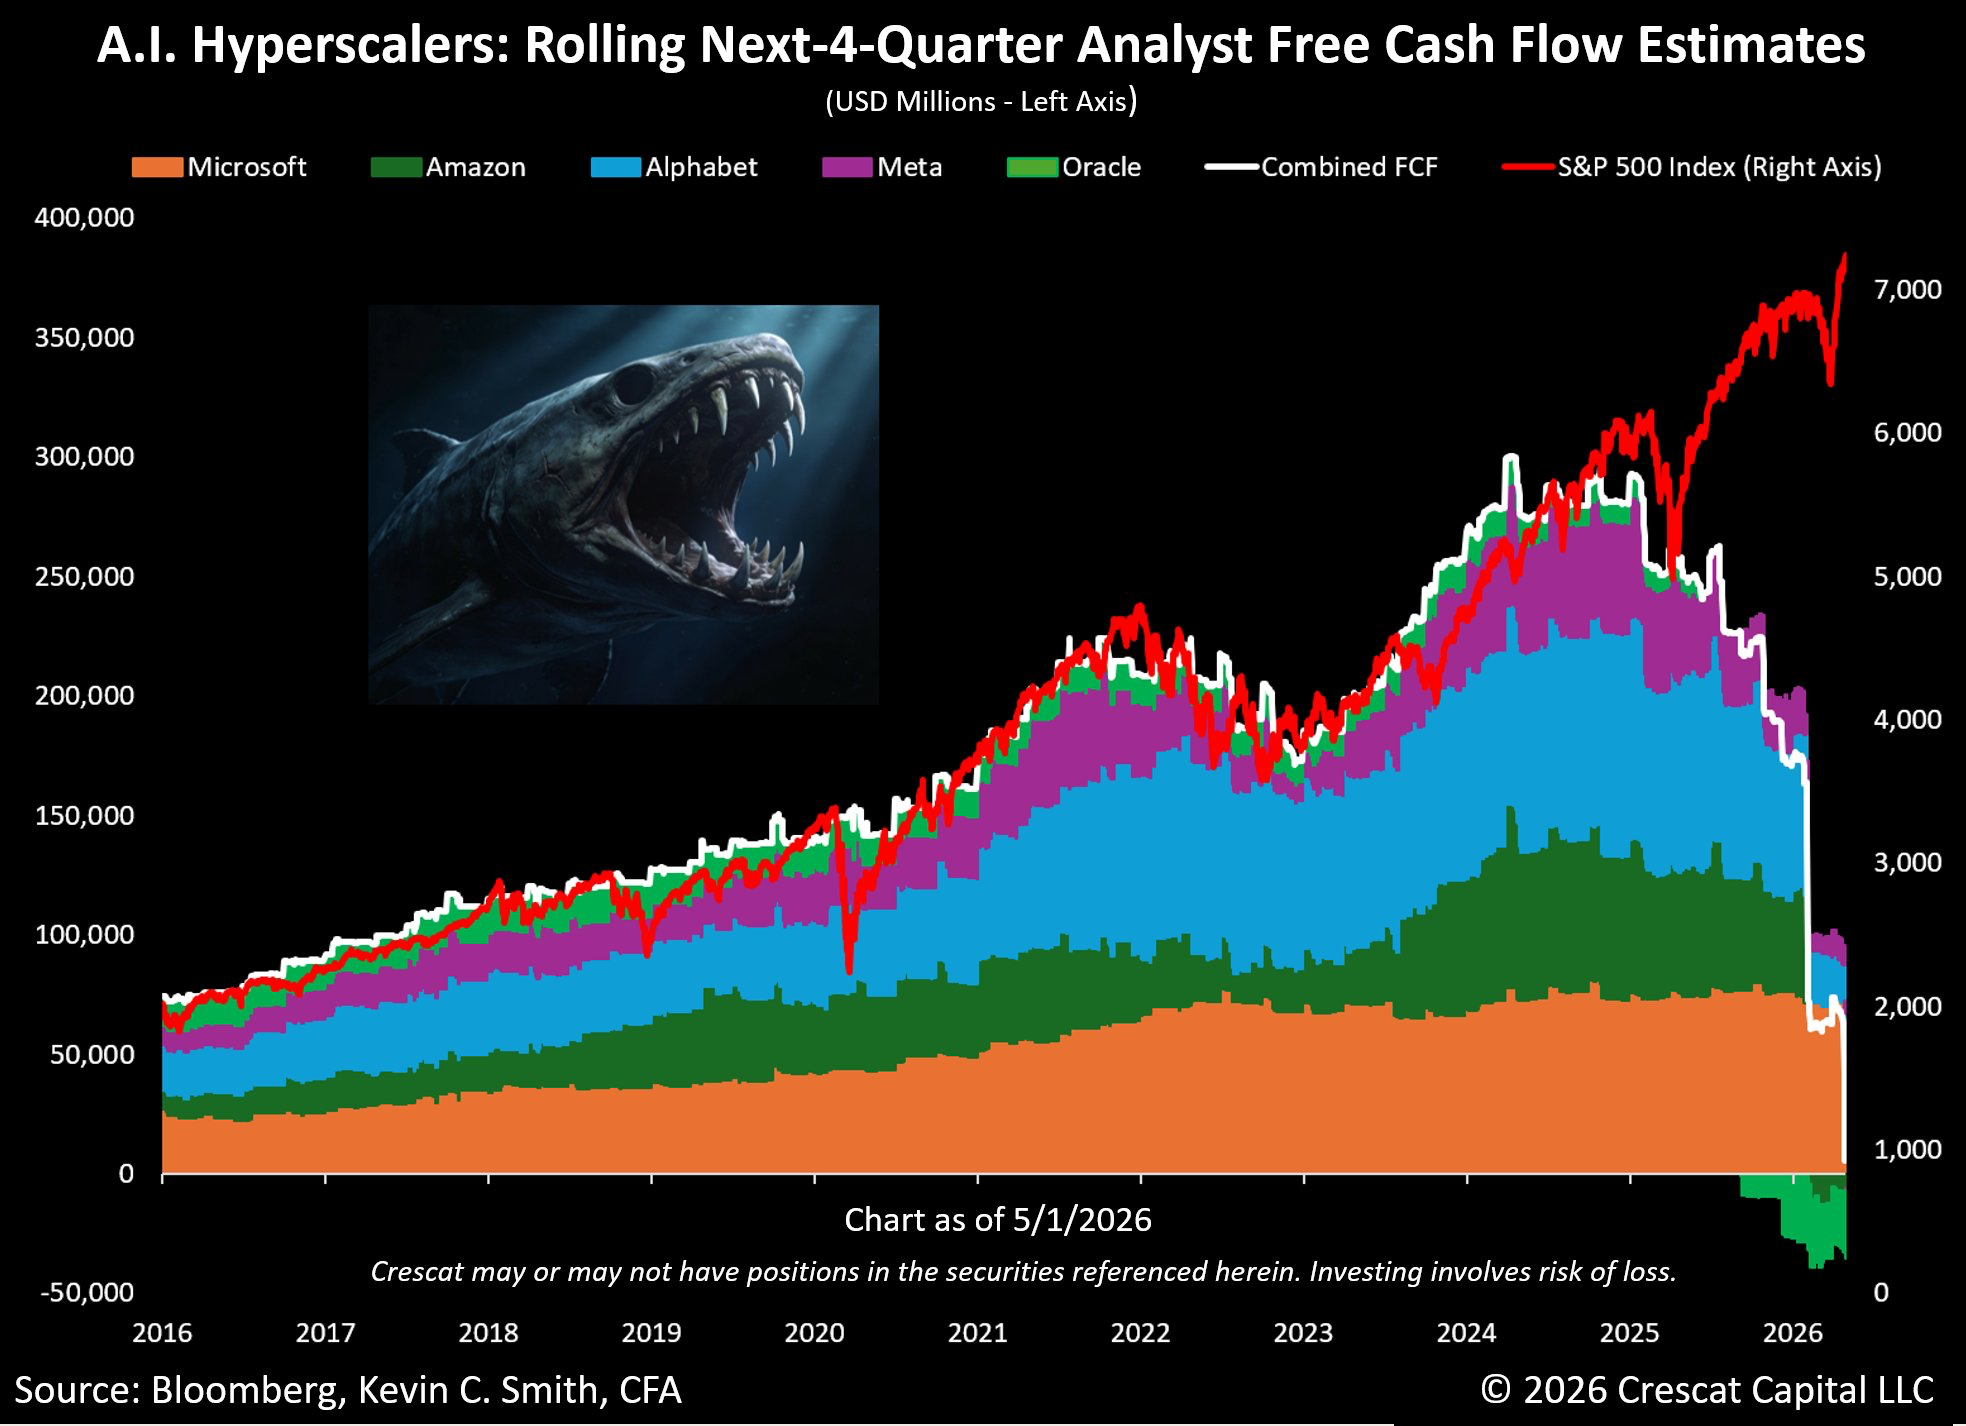
Alphabet generated $73.266 billion in free cash flow in FY2025, which sounds enormous until you look at what's coming. CEO Sundar Pichai has guided for 2026 capital expenditures in the range of $175 to $185 billion. For context, Alphabet's FY2025 operating cash flow was $164.713 billion. If capex hits the midpoint of that guidance range, it consumes essentially all operating cash the business generates.
The trajectory has been accelerating hard. In 2023, Alphabet spent $32.3 billion on capex. In 2024, that rose to $52.5 billion. In 2025, it hit $91.4 billion, a 74% year-over-year increase. The proposed jump to $175-185 billion in 2026 would be another near-doubling. Q4 2025 alone saw capex grow 95% year-over-year to $27.9 billion.
This dynamic is playing out across the peer group. Amazon already lived this story in 2025: FY2025 free cash flow collapsed 65.95% year-over-year to $11.194 billion as capex hit $131.8 billion. CEO Andy Jassy has guided for approximately $200 billion in capital expenditures across Amazon in 2026.
Meta and Microsoft are spending aggressively too. Meta's FY2025 free cash flow declined 19.39% year-over-year to $43.6 billion against 2026 capex guidance of $115 to $135 billion. Microsoft's Q2 FY2026 capex alone was $29.9 billion, up 89% year-over-year.
Patel's broader point is that tech insiders understand the technology better than financial markets, and that returns on AI infrastructure will ultimately justify the spend. The businesses backing these bets are not struggling — Alphabet posted Google Cloud revenue of $17.7 billion in Q4 2025, up 48% year-over-year, with a 31.6% operating margin at the Alphabet level. Full detail is in Alphabet's SEC filing.
Whether it's applied enough is exactly what Patel is questioning. If you believe AI infrastructure is a winner-take-most game and Alphabet and Amazon are positioned to win it, the FCF compression looks like the price of admission. If you think the returns won't materialize at the scale management expects, zero free cash flow at a $1.7 trillion market cap is a very different conversation.
NB: Even before these future investments are considered, for the trailing twelve months Alphabet's EV/FCF has his 73 vs. a P/E ratio of 29. If FCF goes to zero…
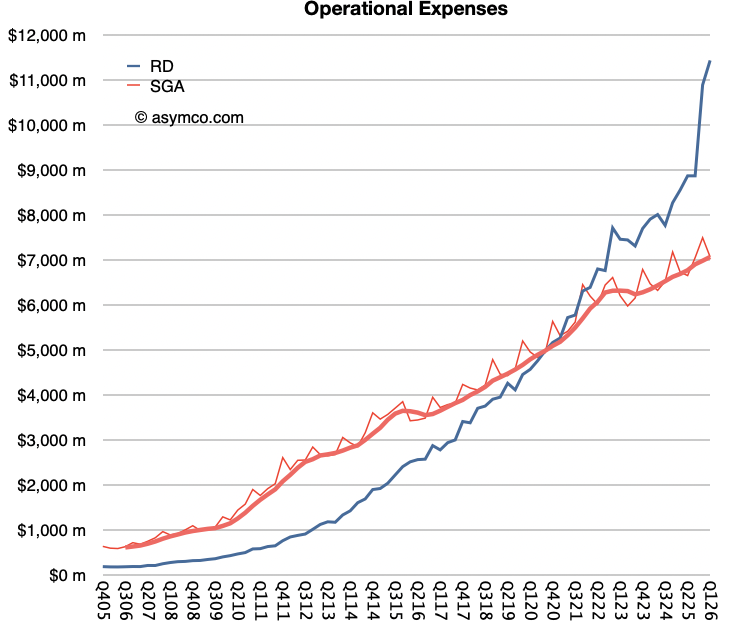
Apple’s R&D spending hit 10.3% of revenue in the March quarter, as the the tech giant ramps up investments in artificial intelligence.
The increase puts Apple closer to the rest of megacap tech on R&D, though the iPhone maker is still taking a very different approach when it comes to capital expenditures, according to CNBC. R&D spending was up from 7.6% in the prior period and 9% in the same quarter a year earlier. While sales jumped 17%, the fastest rate of growth for any quarter since 2021, R&D climbed twice as quickly, increasing almost 34% from a year prior, according to CNBC.
“That’s a sign that Apple is seeing a sense of urgency around new AI products,” said Gene Munster, managing partner at Deepwater Asset Management.”
Horace Dediu, founder of Asymco, agreed that a major question is where all that spending is going. Much of the increase, he said, is likely tied to talent, teams and experiments in training and modeling, rather than the kind of large-scale data center deployment underway at the hyperscalers. But he also said Apple is pushing across hardware, investing in silicon, optics, batteries, materials, sensors and smaller form factors.”
"AI is an obvious candidate, but R&D is not capex," Dediu said.
NB: Apple has been increasing its R&D spending from around 2% to 9% of sales on a 4-trailing quarter basis. It has overtaken SG&A which has remained around 7% since 2011.